
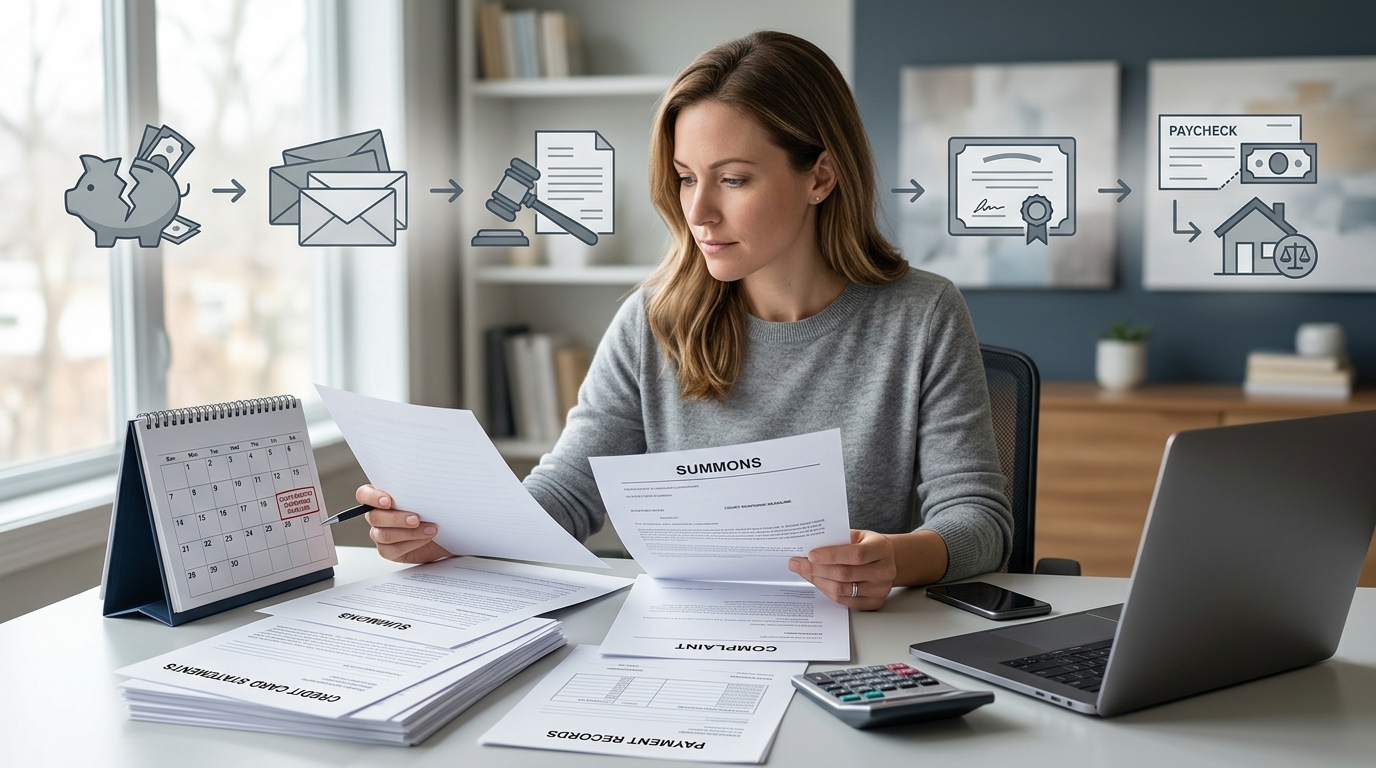
The honest answer is that debt collectors and debt buyers can sue consumers in appropriate circumstances. Whether they can legally pursue a particular debt, whether they actually choose to file a lawsuit, and what happens afterward depends on factors such as the age of the debt, applicable state law, the documentation available, and whether you respond to the lawsuit.
If you have actually been served with a lawsuit, the most important step is to read the court papers carefully and respond by the deadline stated in them. The Consumer Financial Protection Bureau (CFPB) explains that responding does not mean you are admitting that the debt is valid. It gives you an opportunity to raise defenses and protect your rights.
Yes, Debt Collectors Can Legally Sue You
For a debt that is still within the applicable statute of limitations, a debt collector or debt buyer may have the legal ability to file a lawsuit seeking a court judgment. The exact rules depend on the state and type of debt involved.
A lawsuit is therefore a real collection tool—not simply an empty threat in every situation. However, that does not mean every unpaid account ends up in court.
Debt collectors may first use letters, phone calls, settlement offers, payment plans, or other collection efforts. The CFPB notes that ignoring collection attempts can eventually lead to a lawsuit, so receiving collection communications should not automatically be treated as harmless.
If you are dealing with a collection account, it can also help to understand how a debt validation letter works before deciding what to do next.
Why Not Every Unpaid Debt Results in a Lawsuit
Lawsuits require time, money, documentation, and court procedures. As a result, collectors generally have to decide whether pursuing litigation makes economic and practical sense.
The Size of the Debt
A larger balance may make litigation more economically attractive because the potential recovery may justify the cost of filing and pursuing the case.
Smaller balances may not always justify the same level of legal expense. However, there is no universal dollar amount below which you should assume a lawsuit cannot happen.
How Strong the Documentation Is
A collector or debt buyer pursuing a lawsuit generally needs to establish that the debt is valid, that you are the person responsible for it, that the amount claimed is accurate, and that the plaintiff has the legal right to pursue the debt.
This can become especially important when a debt has been sold multiple times. If you want to understand this issue, see our guide to debt buyers vs. collection agencies.
Whether the Debt Is Still Within the Statute of Limitations
State law generally limits how long a creditor or debt collector has to sue over an unpaid debt. This period is called the statute of limitations.
The length of the period and the rules for calculating it vary by state and debt type. The Federal Trade Commission (FTC) explains that some states may also have rules under which making a payment or acknowledging an old debt can affect the limitations period.
Because of these differences, do not assume that an old debt is automatically too old to sue over. You can learn more in our guide to the statute of limitations on debt.
Whether You Appear Able to Pay a Judgment
A collector may also consider whether a judgment would realistically produce a recovery. If someone has limited income and few non-exempt assets, obtaining a judgment may be less immediately useful to the collector.
However, financial circumstances can change, and a judgment may remain enforceable for a significant period depending on state law. Being unable to pay today does not necessarily make a lawsuit irrelevant.
What the Actual Debt Lawsuit Process Looks Like
If a collector decides to sue, the process generally moves from collection activity into the court system.
1. Filing and Service
The collector or a law firm representing the collector files a complaint with the appropriate court. You are then formally served with legal papers.
The documents commonly include a summons, which tells you that a case has been filed and provides information about how and when you must respond, and a complaint, which explains the claims being made against you.
2. Your Response Deadline
The deadline is one of the most important details in the entire lawsuit.
The exact deadline varies according to the court and applicable law. Do not rely on a generic number of days found online. Instead, look directly at your summons and other court documents to determine the deadline that applies to your case.
The CFPB specifically advises consumers who are sued by a debt collector to respond by the date specified in the court papers.
3. Filing an Answer
If you respond by filing an Answer, you can address the allegations made against you and raise applicable defenses.
The case may then proceed through additional stages, potentially including discovery, motions, settlement discussions, hearings, and—in some cases—a trial.
Responding does not necessarily mean admitting that you owe the money. The CFPB explains that when you respond, the collector still has to establish its claim in court.
4. Default Judgment If You Do Not Respond
If you fail to respond by the applicable deadline, the court may enter a default judgment against you.
This is one of the biggest risks of ignoring a lawsuit. A default can prevent you from presenting defenses you might otherwise have been able to raise.
The CFPB warns that ignoring a properly served debt collection lawsuit can result in a judgment and stronger collection tools.
What Happens If the Collector Wins—or You Default?
A court judgment can give a creditor or debt collector additional legal tools to collect, although the specific procedures and exemptions vary by state.
Wage Garnishment
A judgment may allow the creditor to seek an order directing an employer to withhold part of your wages to satisfy the judgment.
Federal and state laws can limit how much can be garnished, and certain income or benefits may receive legal protections. The CFPB’s wage-garnishment guidance explains that state and federal exemptions can apply.
For more information, read our detailed guide to wage garnishment.
Bank Account Levies
Depending on state law and the circumstances, a judgment creditor may be able to obtain an order allowing funds in a bank account to be seized.
However, exemptions can protect certain funds or amounts. Federal benefits such as Social Security and VA benefits can have specific protections when they are directly deposited, subject to applicable rules.
Property Liens
A judgment may also result in a lien against property in circumstances permitted by state law.
A lien can complicate a future sale or refinancing of property. The CFPB identifies property liens as one of the stronger collection tools that may become available after a judgment.
A judgment is not necessarily an instant transfer of money. Additional legal steps may be required before particular collection remedies can be used.
Your Realistic Defenses If You Are Sued
Being sued does not automatically mean the collector will win. The appropriate defenses depend on the facts of the case and the law governing it.
The Statute of Limitations Has Expired
If the debt is genuinely time-barred under the applicable state law, that may provide an important defense.
However, do not assume that the court will automatically recognize an expired statute of limitations without you raising it. The FTC advises consumers who are sued over time-barred debt not to ignore the lawsuit and to tell the court that the statute of limitations has expired.
Before making a payment or acknowledging an old debt, review our guide on why making a payment on old debt can sometimes backfire.
The Plaintiff Cannot Adequately Prove Ownership or the Amount Owed
This can be particularly relevant when the plaintiff is a debt buyer.
The collector may need to establish that the debt belongs to you, that the amount is accurate, and that the plaintiff has the legal right to collect it. The FTC similarly explains that in a lawsuit the collector must establish that you are the person who owes the debt, that the amount is accurate, and that you owe the debt to that party.
The Debt Has Already Been Paid or Settled
If you previously paid or settled the account, keep documentation showing what happened.
Bank statements, settlement agreements, payment confirmations, letters, and other records can be important when challenging a claim that you still owe the balance.
The Debt Isn’t Yours
A lawsuit involving a debt that does not belong to you should be taken seriously.
The problem could involve identity theft, mistaken identity, incorrect account information, or another data error. If this applies to you, review our guide on what to do if you’re contacted about a debt that isn’t yours.
Procedural Problems
There can also be technical issues involving service, jurisdiction, documentation, or how the lawsuit was filed.
These issues can be highly dependent on state and court rules, so legal assistance can be especially useful when you believe something about the lawsuit itself was improper.
Should You Get an Attorney?
If you have actually been sued, consider speaking with a consumer-law attorney or legal-aid organization if one is available to you.
The potential consequences of a judgment can include additional collection tools, so understanding your legal position before the response deadline can be valuable.
The CFPB recommends contacting a lawyer if you are sued or if a judgment has already been entered against you. It also notes that consumers may be able to negotiate a compromise or settlement before a court enters judgment.
If you cannot afford private legal representation, check whether your court provides self-help resources or whether a nonprofit legal-aid organization in your state can assist.
Can You Negotiate a Settlement Even After Being Sued?
Yes. A lawsuit does not necessarily eliminate the possibility of negotiating a settlement.
Settlement discussions may occur before or after litigation begins. If you decide to negotiate, make sure you understand exactly what the agreement says before sending money.
Get the settlement terms in writing and pay particular attention to what happens to the lawsuit itself.
If a settlement is supposed to resolve the lawsuit, the written agreement should clearly address the status of the case and the remaining balance. Depending on the circumstances and the agreement, you may want legal advice about whether a dismissal should be with prejudice.
You can also read our guide on how to negotiate with a debt collector without getting taken advantage of.
What If You Genuinely Can’t Afford to Pay, Even If You Lose?
If a judgment is entered and you have very limited income or assets that can legally be reached, your practical ability to pay may be limited.
However, this should not be treated as a reason to ignore a lawsuit.
Financial circumstances can change, and judgments may remain enforceable for years depending on state law. Interest and other lawful amounts may also apply.
If your debts are broader than a single collection account, consider discussing your situation with a consumer-law attorney, nonprofit credit counselor, or qualified bankruptcy professional to understand your available options.
How Long After a Debt Becomes Delinquent Can a Collector Still Sue You?
The answer depends primarily on the applicable statute of limitations.
The limitation period varies by state and by the type of debt. The FTC explains that the period can also depend on the law applicable to the debt agreement, and in some states certain actions involving an old debt may affect the limitations period.
Because the rules differ, do not rely on a universal “three years,” “six years,” or “seven years” rule.
Read our complete guide to the statute of limitations on debt for more information.
Can You Be Sued for a Debt That Has Fallen Off Your Credit Report?
Potentially, yes.
The credit-reporting period and the statute of limitations for filing a lawsuit are separate legal concepts.
Negative information generally has a limited reporting period under federal credit-reporting law, but the expiration of the credit-reporting period does not automatically answer whether a lawsuit is legally permitted under state law.
That means you should not assume that a debt is legally unenforceable simply because it no longer appears on your credit report.
You can learn more about checking your credit history in our guide on how to read a credit report.
Does Getting Sued Automatically Mean Your Wages Will Be Garnished?
No.
A lawsuit by itself does not automatically mean your employer will begin withholding money from your paycheck.
Generally, a creditor seeking ordinary debt-collection garnishment first needs a judgment and then must follow the applicable procedures for obtaining and enforcing a garnishment order. Federal and state laws can also limit garnishment amounts and provide exemptions.
This is one reason why receiving a lawsuit is serious—but it is not the same thing as immediately having your wages taken.
Can a Debt Collector Sue You in a State Where You Don’t Currently Live?
Jurisdiction and venue rules determine where a lawsuit can properly be filed. The answer can depend on where you live, where the underlying agreement was made, the terms of the agreement, and applicable state law.
If you receive court papers from a jurisdiction that seems unrelated to you or the debt, do not simply ignore them. Consider getting legal advice about whether the court has proper jurisdiction and whether the filing location is appropriate.
What If You Ignore the Lawsuit Because You Can’t Afford an Attorney?
Not being able to afford a lawyer does not eliminate the importance of responding.
Ignoring a properly served lawsuit can result in a default judgment even when you may have had a legitimate defense.
The FTC advises consumers not to ignore debt collection lawsuits and to follow the instructions and deadlines contained in the legal papers.
Depending on your location, the court may provide self-help materials, Answer forms, legal-aid referrals, or other resources for people representing themselves.
You can also review our guide on what happens if you ignore a debt collection lawsuit.
A Realistic Timeline From Missed Payment to Lawsuit
A debt lawsuit usually does not appear out of nowhere.
A typical sequence may look something like this:
- Missed payment: The account becomes delinquent.
- Continued delinquency: The creditor attempts to collect.
- Charge-off: For many credit-card accounts, charge-off may occur after an extended period of nonpayment.
- Collection: The account may be placed with or sold to a collection company or debt buyer.
- Collection attempts: Calls, letters, settlement offers, and payment discussions may continue.
- Potential lawsuit: If the collector decides litigation is appropriate and the legal requirements are satisfied, a lawsuit may be filed.
- Service: You receive a summons and complaint.
- Response deadline: You must respond according to the court’s instructions.
- Further proceedings: The case may involve motions, discovery, settlement discussions, or trial.
- Judgment or resolution: The case may end through settlement, dismissal, a judgment, or another court resolution.
This is only a general sequence. Individual cases can move much faster or slower, and the exact process depends on state and court rules.
What Does a Summons and Complaint Actually Look Like?
If you are served with a lawsuit, the legal terminology can initially be confusing.
The Summons
The summons is the document that formally notifies you that a lawsuit has been filed and tells you how to respond and, generally, when your response is due.
The Complaint
The complaint describes the plaintiff’s allegations. In a debt collection lawsuit, it may identify the original creditor, the alleged account, the amount claimed, and the legal basis for the lawsuit.
Read both documents carefully. Write down every deadline and follow the instructions provided by the court.
How Court Self-Help Resources Can Help If You Can’t Afford an Attorney
Many courts provide information for people who represent themselves.
Depending on your state and county, resources may include self-help centers, simplified forms, legal clinics, court navigators, or referrals to legal-aid organizations.
Start with the official website of the court listed on your summons. You can also contact the clerk’s office to ask what self-help resources are available.
Do not assume that you must hire a private attorney simply to find out how to submit your response. At the same time, if you have a complicated defense or substantial financial exposure, professional legal advice may be appropriate.
Does the Amount of Debt Affect Whether You Should Take a Lawsuit Seriously?
Even a relatively small lawsuit deserves attention.
There is no universal dollar threshold below which ignoring a lawsuit becomes safe. A default judgment can still create legal and financial consequences even when the original balance is relatively small.
The appropriate response is therefore to follow the court’s instructions and deadline regardless of the amount claimed.
Can a Collector Sue You While You Are Disputing the Debt With the Credit Bureaus?
Yes, a credit-report dispute and a debt collection lawsuit are separate processes.
Disputing information with Equifax, Experian, or TransUnion does not automatically prevent a collector from pursuing a lawsuit over the underlying debt.
However, documentation from your dispute may potentially be relevant to your case if it concerns the accuracy, ownership, or amount of the debt.
If you need to challenge inaccurate information, see our guide on how to dispute credit report errors.
If a Debt Buyer Sues You, Is It Harder for Them to Win?
Not automatically.
However, a debt buyer may need to establish both the validity of the underlying debt and its legal ownership of the particular account.
This can make documentation particularly important when a debt has been sold or transferred multiple times.
Read more about how debt gets resold to multiple companies and how ownership can become an important issue in collection disputes.
Is Small Claims Court Different From a Standard Debt Collection Lawsuit?
Some debt collection cases, particularly those involving smaller balances, may be filed in small claims court.
Small claims procedures are often designed to be simpler and less expensive than ordinary civil litigation, but the exact rules vary significantly by state and court.
Even in small claims court, the same basic principles remain important: read the paperwork, understand the deadline, appear or respond as required, and raise any legitimate defenses.
Respond vs. Ignore: What Changes?
| Issue | If You Respond | If You Ignore the Lawsuit |
|---|---|---|
| Ability to raise defenses | You generally preserve the opportunity to raise applicable defenses. | You risk losing the opportunity to present defenses through a default judgment. |
| Collector must prove its case | The collector must establish its claim in court. | A default judgment may be entered without the same opportunity for you to contest the claim. |
| Settlement leverage | You may still have an opportunity to negotiate. | Your position may become weaker after a judgment. |
| Weak documentation | You may be able to challenge insufficient proof. | A default can prevent you from presenting those arguments. |
| Potential cost | You may have filing costs, legal expenses, or other case-related costs. | A judgment may add lawful interest, fees, costs, or collection consequences. |
The central point is simple: responding preserves options. Ignoring a lawsuit can result in a default judgment and make the situation more difficult to address later. The CFPB and FTC both advise consumers not to ignore debt collection lawsuits.
What Debt Collectors Say About Litigation as a Collection Tool
Litigation is one of several tools available to creditors and debt collectors. It requires a formal court process and creates costs and risks for both sides.
That means a threat of litigation should not automatically be interpreted as proof that a lawsuit has already been filed. At the same time, it should not automatically be dismissed as a bluff.
If you receive an actual summons and complaint, the situation has moved beyond an ordinary collection call. Treat the court documents as a legal matter and follow the response instructions.
If a Lawsuit Is Dismissed, Is the Debt Gone Forever?
Not necessarily.
The effect of a dismissal depends on the reason for the dismissal and whether it is with prejudice or without prejudice.
A dismissal without prejudice may allow a plaintiff to pursue the matter again in circumstances permitted by law. A dismissal with prejudice generally prevents the same claim from being refiled.
Because the consequences depend on the specific order and applicable law, review any dismissal carefully and consider legal advice if the debt remains disputed.
Can More Than One Company Sue You for the Same Debt?
A debt should have a legitimate current owner or party entitled to enforce it, but debt transfers and recordkeeping problems can sometimes create confusion.
If you receive collection demands or legal papers from more than one company concerning the same debt, preserve all documentation.
If you have already paid, settled, or defended a lawsuit involving the account, those records may be particularly important.
You can also read our article on how the same debt can be resold between different companies.
Does Settling After Being Sued Affect Your Credit?
Settling a debt does not automatically erase its history from your credit report.
The credit-reporting treatment of a collection account or judgment can depend on the account’s reporting status, applicable federal law, and the information furnished by the creditor or collector.
Before making a payment or settlement, get the agreement in writing and understand exactly what the payment resolves.
If your primary concern is an inaccurate account appearing on your credit reports, learn how to dispute credit report errors rather than assuming payment alone will correct inaccurate information.
What Should You Do If a Debt Collector Is Threatening to Sue You?
If a collector is threatening legal action but you have not received court papers, start by determining exactly what stage you are in.
- Ask for information identifying the debt.
- Review your records and credit reports.
- Determine whether the debt is yours.
- Check whether the amount claimed appears accurate.
- Review the age of the debt and the applicable statute of limitations.
- Be careful about making payments or acknowledging very old debts before understanding the applicable state law.
- Keep copies of letters, emails, statements, and other communications.
- If you receive actual court papers, follow the court’s deadline rather than treating the threat as an ordinary collection call.
If you are dealing with collection harassment, you can also read our guide to debt collector harassment and the FDCPA.
What Should You Do If You Have Already Been Served?
If you already have a summons and complaint, prioritize the court deadline.
- Read every page. Identify the court, plaintiff, case number, response deadline, and instructions.
- Do not ignore the papers. A default judgment can result if you fail to respond.
- Gather your records. Look for statements, payments, settlement agreements, correspondence, and evidence concerning ownership or identity.
- Review the allegations. Compare what the plaintiff claims with your records.
- Consider legal help. A consumer-law attorney or legal-aid organization may be able to help.
- Consider settlement carefully. If settlement is appropriate, obtain the terms in writing and understand what happens to the lawsuit.
- Follow the court’s instructions. Do not rely solely on general online advice because procedural rules vary by jurisdiction.
The CFPB’s guidance emphasizes that responding to the lawsuit gives you an opportunity to defend yourself and does not by itself mean you admit that the debt is valid.
The Bottom Line
Yes, debt collectors can genuinely sue you. A debt collection lawsuit is a real legal process with potentially significant consequences, particularly if you ignore the court papers.
But being sued is not the same as automatically losing, and receiving a lawsuit is not the same as having your wages immediately garnished or your bank account immediately seized.
The most important thing to remember is the response deadline. If you receive a summons and complaint, read it carefully and respond according to the court’s instructions. The CFPB and FTC both emphasize the importance of responding rather than ignoring a debt collection lawsuit.
Depending on your situation, you may have defenses involving the validity of the debt, ownership, the amount claimed, prior payment or settlement, the statute of limitations, identity, or procedural issues.
If you are unsure what to do, consider obtaining advice from a qualified consumer-law attorney or legal-aid organization in your state.
Need Help Reviewing Your Credit Report?
If a debt collector is contacting you or a collection account is appearing on your credit report, understanding exactly what is being reported is an important first step. Review your credit reports for inaccurate, outdated, duplicate, or unfamiliar information.
Contact Credit Repair Services to discuss your credit situation →
Frequently Asked Questions
Can a debt collector really sue me?
Yes. A debt collector or debt buyer may sue when legally permitted, including when the debt is within the applicable statute of limitations. Whether a collector actually files a lawsuit depends on the circumstances.
Can a debt collector sue me for an old debt?
It depends on the applicable statute of limitations and state law. An old debt may be time-barred from litigation, but the rules vary. Do not assume that simply being old makes a debt legally unenforceable.
Can I be sued after a debt falls off my credit report?
Potentially. Credit reporting periods and lawsuit limitation periods are separate concepts.
What happens if I don’t respond to a debt lawsuit?
The court may enter a default judgment against you. That judgment can give the creditor or collector stronger legal collection tools, depending on state law.
Can a debt collector garnish my wages without suing me?
For ordinary consumer debts, creditors generally need a court judgment before using wage garnishment, although exceptions exist for certain government debts and other obligations.
Can I settle a debt after being sued?
Yes. Settlement may still be possible after litigation begins. If you settle, get the terms in writing and make sure you understand what happens to the lawsuit and remaining balance.
What if the debt isn’t mine?
Do not ignore the lawsuit. Gather documentation showing that the debt is not yours and raise the issue through the appropriate legal process. You can also review our guide on debt that isn’t yours.
What if the debt collector is threatening to sue but hasn’t filed anything?
A threat to sue is different from an actual lawsuit. However, it should not automatically be dismissed as a bluff. Review the debt, understand your rights, and take actual court papers seriously if they arrive.
Does a credit-bureau dispute stop a debt lawsuit?
Not automatically. A credit-report dispute and a court lawsuit are separate processes.
Should I hire an attorney if a debt collector sues me?
Consider consulting a consumer-law attorney, especially if the debt is disputed, the amount is significant, the statute of limitations may have expired, or you are concerned about defenses or collection consequences. Legal-aid resources may also be available if you cannot afford private counsel.
Where can I learn more about debt collection rights?
The Consumer Financial Protection Bureau’s debt-collection resource provides information about judgments, validation notices, garnishment, harassment, and other debt-collection issues.