
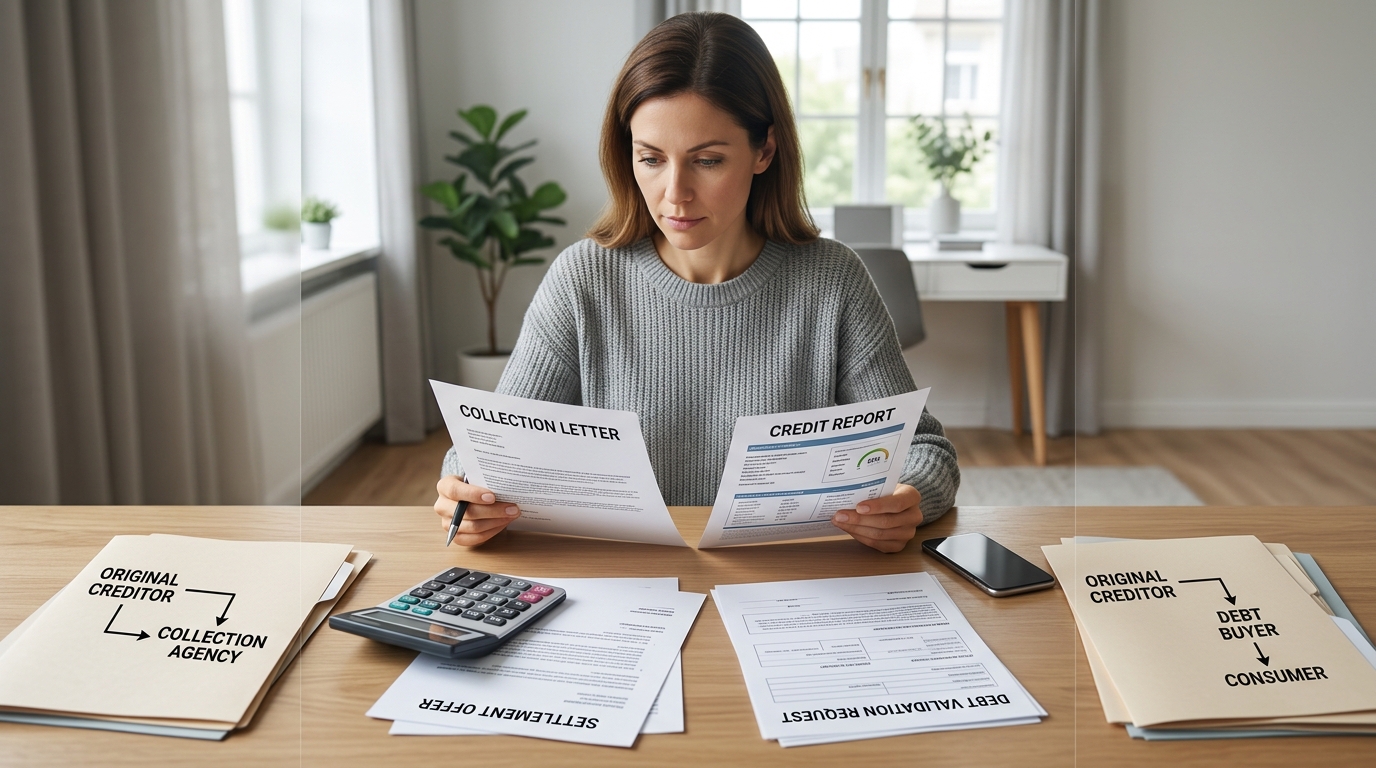
Both may contact you about the same type of debt, and both may be described generally as debt collectors, but their business models are different.
The key distinction is who owns the debt. That difference can affect who you negotiate with, what documentation may be relevant, and how the debt may move through the collection process.
This guide explains the difference between debt buyers and collection agencies, how to determine which one you are dealing with, how debt can move from one to the other, and what you should understand before negotiating or disputing an account.
The Core Difference Between a Debt Buyer and a Collection Agency
A collection agency generally works for the original creditor. The original creditor retains ownership of the debt while the collection agency attempts to recover the money on the creditor’s behalf.
A debt buyer, by contrast, purchases the debt from the original creditor or, in some cases, from another debt buyer. Once the sale is completed, the debt buyer becomes the current owner of the account.
| Collection Agency | Debt Buyer |
|---|---|
| Usually collects on behalf of the original creditor | Purchases the debt and becomes the current owner |
| Usually receives a fee or contingency-based compensation | Keeps amounts it collects after purchasing the account |
| Original creditor generally retains ownership | Original creditor generally no longer owns the sold account |
| Settlement authority may depend on creditor authorization | May have different settlement authority because it owns the account |
| May return an unsuccessful account to the creditor | May continue collection or resell the account |
This ownership distinction is the foundation for many of the practical differences between the two.
How Collection Agencies Work
A collection agency is generally hired by a creditor to collect an account that the creditor still owns.
The Agency Does Not Usually Own the Debt
The collection agency is acting as an agent or service provider for the original creditor.
For example, suppose you have an unpaid credit-card account with a bank. The bank may send the account to a collection agency rather than immediately selling it.
The collection agency then contacts you and attempts to recover the balance, but the bank remains the owner of the underlying debt.
How Collection Agencies Are Compensated
Collection agencies commonly operate under arrangements in which they receive compensation based on the amounts they successfully collect.
This creates an incentive to recover as much of the outstanding balance as possible.
However, the agency may not have unlimited authority to accept a substantial reduction in the balance because it is collecting on behalf of another company.
How Much Negotiating Flexibility Does a Collection Agency Have?
A collection agency may offer payment plans or settlement options, but the extent of its authority can depend on the agreement it has with the original creditor.
If the agency cannot resolve the account, the original creditor may decide to:
- Continue collection internally
- Send the account to another collection agency
- Take legal action where permitted
- Sell the debt to a debt buyer
If you are dealing with an agency, it can be useful to ask what settlement or payment options the agency is authorized to offer.
How Debt Buyers Work
A debt buyer operates under a different model.
Instead of simply collecting for the original creditor, the debt buyer purchases the debt.
The Debt Buyer Owns the Account
Once a debt has been sold, the buyer generally becomes the current owner of that debt.
The buyer may have purchased the account directly from the original creditor or from another debt buyer.
This means a debt can sometimes move through a chain such as:
Original Creditor → Debt Buyer A → Debt Buyer B → Debt Buyer C
Our article on how debt can be resold to multiple companies explains why the same account may eventually generate collection attempts from several different companies.
Why Do Debt Buyers Purchase Debt?
Debt buyers often purchase portfolios of charged-off accounts for substantially less than the total face value of the debt.
The buyer is effectively making a calculated investment: it pays a discounted price for a portfolio and attempts to recover more than it paid.
The exact price paid for an individual account may not be separately determined because debt is often purchased in large portfolios containing hundreds or thousands of accounts.
Debt Buyers Keep What They Collect
Because a debt buyer purchased the account, the buyer generally keeps the money it collects rather than sharing the recovery with the original creditor under a traditional collection-agency contingency arrangement.
This difference can affect the company’s approach to settlement negotiations.
Debt Buyer vs. Collection Agency: Why the Difference Matters
Knowing who owns the debt can help you understand who actually has authority over the account.
Negotiating With a Collection Agency
If a collection agency is working on behalf of the original creditor, you can ask what settlement or payment options the agency is authorized to provide.
Depending on the circumstances, you may also want to determine whether the original creditor remains involved in the account.
A useful question is:
“Are you collecting this debt on behalf of the original creditor, or does your company own the debt?”
Negotiating With a Debt Buyer
A debt buyer has purchased the account and therefore may have different authority over settlement terms.
Because the account was purchased rather than simply assigned for collection, the buyer may have more flexibility to evaluate a settlement based on what it believes can realistically be recovered.
However, there is no universal settlement percentage that every debt buyer will accept. Your financial circumstances, the age and type of debt, the company’s policies, and the specific account can all affect negotiations.
Our guide on how to negotiate with a debt collector without getting taken advantage of provides additional guidance on preparing for these conversations.
How to Find Out Which One You Are Dealing With
You do not have to guess whether the company contacting you is a debt buyer or a collection agency.
Ask the Company Directly
Ask:
“Does your company own this debt, or are you collecting it on behalf of the original creditor?”
The answer can help establish the company’s role.
Request Debt Validation
If you receive a debt validation notice, review the information carefully.
Depending on the circumstances and applicable law, the information provided can help you determine the creditor or current owner of the debt and understand the basis of the collection claim.
Our debt validation letter guide explains how consumers can approach the validation process.
Check Your Credit Report
Your credit report may provide clues about who is reporting the account.
You may see:
- The original creditor
- A collection account
- A debt buyer’s company name
- Multiple entries associated with the same underlying account
However, the credit report alone should not be treated as definitive proof of ownership. When ownership matters, review the documentation provided by the company and the account history.
You can also learn how to read a credit report so you can better understand collection accounts and account histories.
Research the Company’s Business Model
Some companies primarily operate as collection agencies, while others primarily operate as debt buyers.
Some companies may operate in more than one capacity.
For that reason, researching the company can provide useful background, but confirming the role of the company with respect to your specific account is more important than relying solely on the company’s general business model.
Why a Debt Can Involve Both a Collection Agency and a Debt Buyer
A single debt can move through both models during its lifetime.
For example:
- A consumer stops making payments on a credit-card account.
- The original creditor attempts to collect the balance.
- The creditor places the account with a collection agency.
- The collection agency attempts to recover the money on the creditor’s behalf.
- The agency is unsuccessful.
- The original creditor eventually sells the account to a debt buyer.
- The debt buyer becomes the current owner.
- The buyer attempts to collect from the consumer.
This progression explains why a person may hear from multiple companies about what appears to be the same debt.
It does not necessarily mean that the consumer owes multiple separate debts.
Do Debt Buyers and Collection Agencies Have the Same Legal Protections?
The legal protections that apply depend on the company’s role, the type of debt, and the applicable federal and state laws.
The Fair Debt Collection Practices Act (FDCPA) generally applies to covered debt collectors collecting debts owed or allegedly owed to another. The law establishes protections involving issues such as harassment, false or misleading representations, and certain collection practices.
Not every entity involved in debt collection is covered in exactly the same way. For example, an original creditor collecting its own debt generally is not treated the same as a third-party debt collector under the FDCPA.
The Consumer Financial Protection Bureau provides an overview of the federal debt collection rules and consumer protections. Review the CFPB’s debt collection resources.
You can also learn more about FDCPA protections against collection harassment.
Which Is Easier to Dispute: a Debt Buyer or Collection Agency?
The answer depends on the facts of the account, but ownership documentation can become particularly important when dealing with a debt buyer.
A debt buyer may need to establish not only the underlying account information but also its legal ownership of the debt.
If the account has been sold multiple times, documentation connecting the original account to the current owner can become an important issue.
A collection agency that is collecting on behalf of the original creditor may instead rely primarily on the original creditor’s account records and its authority to collect.
This does not mean that every dispute against a debt buyer will succeed or that every collection agency has perfect records. The specific documentation and facts matter.
Debt Buyer vs. Collection Agency Comparison
| Issue | Collection Agency | Debt Buyer |
|---|---|---|
| Who owns the debt? | Usually the original creditor | The debt buyer |
| How are they compensated? | Typically through a fee or contingency arrangement | Generally keeps what it collects after purchasing the debt |
| Settlement flexibility | May be limited by the original creditor’s authorization | May have greater flexibility because it owns the account |
| Documentation | Original account and collection authority | Original account information plus documentation of ownership transfer may become relevant |
| Can you contact the original creditor? | Potentially, because the creditor may still own the account | Usually the debt buyer is the party you need to deal with after the sale |
| Credit report | May appear through collection reporting and/or information associated with the original account | The buyer’s name may appear as a collector or current creditor depending on the reporting arrangement |
What Happens if a Debt Buyer Cannot Prove Ownership?
If you formally dispute a debt and the collector cannot adequately establish the basis for its collection claim, the dispute can become significant.
Ownership documentation may be particularly relevant where a debt has been sold multiple times.
However, inability to immediately produce a particular document does not automatically mean that the underlying debt never existed or that the consumer can simply disregard every future collection attempt.
If a dispute escalates into litigation, the parties may have different evidentiary requirements under the applicable law and court procedures.
For credit-reporting issues, inaccurate information can also be disputed with the applicable credit reporting company and furnisher.
See our guide on how to dispute credit report errors.
Do Debt Buyers Have to Tell You When They Purchase Your Debt?
There is not one universal federal rule requiring every debt buyer to proactively contact a consumer immediately when a debt is purchased.
However, when a covered debt collector begins collection activity, federal debt collection rules can require specific information to be provided through the validation notice and related procedures.
If you receive a collection notice from an unfamiliar company, review it carefully and determine who the current creditor is and why the company claims authority to collect.
Can a Collection Agency Later Become a Debt Buyer?
Some companies operate multiple parts of the debt-collection business.
A company might act as a collection agency for one creditor while a separate division or related entity purchases debt portfolios.
For a specific account, what matters is the company’s actual role at the time it is contacting you.
Ask whether the company is collecting on behalf of someone else or owns the account itself.
What Happens When a Debt Buyer Resells the Debt?
A debt buyer may eventually sell an account to another debt buyer.
When this happens, the new buyer becomes the current owner and may need to establish its ownership of the account.
The new buyer may also have a different approach to negotiation than the previous owner.
If you receive a new collection notice from a different company concerning the same debt, do not assume that your previous communications with the former owner automatically resolve the new owner’s claim.
Review the new notice and verify the new company’s authority to collect.
Our article on zombie debt and old debts that come back to life covers this issue in more detail.
How Debt Portfolios Are Sold
Debt is often sold in portfolios rather than as isolated individual accounts.
A bank or credit-card issuer may bundle hundreds or thousands of charged-off accounts based on factors such as debt type, age, and balance.
The entire portfolio is then sold to a debt buyer for a negotiated price.
The buyer does not necessarily know exactly how much it will recover from each individual account. Instead, the buyer evaluates the portfolio using expected recovery rates and other historical data.
This helps explain why settlement decisions can vary from one account to another even when the accounts are owned by the same debt buyer.
What Happens to the Original Creditor After Selling the Debt?
When a creditor sells an account outright, the buyer becomes the new owner of that debt.
The original creditor generally no longer has the same ownership interest in the account.
This differs from a collection-agency arrangement, where the original creditor retains ownership while another company attempts collection on its behalf.
As a result, once a debt has been sold, resolving the account generally requires dealing with the current owner or its authorized collection representative rather than returning to the original creditor as though the account had never been sold.
Why Companies Choose Different Collection Models
The collection-agency and debt-buyer models involve different financial risks and rewards.
Collection Agency Model
A collection agency generally does not have to spend its own capital purchasing the debt. Instead, it receives compensation for successfully collecting on behalf of its client.
This can provide a more predictable business model while limiting the agency’s ownership-related risk.
Debt Buyer Model
A debt buyer spends money to acquire a portfolio before knowing exactly how much it will recover.
If recoveries are higher than expected, the buyer can potentially earn a significant return. If recoveries are lower than expected, the buyer bears the financial loss.
These different risk structures help explain why the two business models can approach settlement and collection differently.
What Happens to the Credit Report When You Pay a Collection Agency?
If a collection agency is working on behalf of the original creditor, payment information should generally be reflected appropriately in the account’s reporting.
However, reporting errors and delays can occur.
After resolving an account, review your credit reports to confirm that the information has been updated accurately.
If you identify inaccurate information, learn how to dispute the error.
Can Debt Buyers Have Incomplete Records?
Documentation can become more complicated when an account has been sold multiple times.
Older portfolios may contain records that were transferred between companies, and information may not always be perfectly preserved.
This is one reason debt validation can be particularly important when an unfamiliar debt buyer contacts you.
If you do not recognize the debt, you can also review our guide on what to do when a debt isn’t yours.
Can You Ask a Debt Buyer How Much It Paid for Your Debt?
You can ask, but a debt buyer generally is not required to disclose the specific purchase price it paid for your individual account simply because you request it.
Debt is often purchased in large portfolios, making the exact purchase price attributable to one account difficult to determine.
Understanding that debt buyers may purchase portfolios at a discount can nevertheless provide useful context when evaluating settlement negotiations.
Negotiation Scripts for Each Type of Company
If You Are Dealing With a Debt Buyer
You might say:
“I understand your company purchased this account. I would like to discuss a settlement for the account. Please let me know what settlement options you are authorized to offer, and I would like any agreement to be provided to me in writing before I make a payment.”
This approach focuses on confirming ownership and obtaining clear written settlement terms rather than assuming that the buyer must accept a particular percentage.
If You Are Dealing With a Collection Agency
You might say:
“Since you are collecting on behalf of the original creditor, I would like to understand what settlement or payment-plan options you are authorized to offer. Please also confirm who currently owns the account.”
Neither approach guarantees a particular outcome. The goal is to match the conversation to the company’s actual role.
Frequently Asked Questions
Is a debt buyer the same thing as a collection agency?
No. A collection agency generally collects on behalf of the creditor that owns the debt. A debt buyer purchases the debt and becomes the current owner.
Does it matter whether a debt buyer or collection agency contacts me?
It can matter for practical reasons, particularly when determining who owns the account, who has settlement authority, and what documentation may be relevant. Your legal rights depend on the applicable federal and state laws and the company’s role.
Can a debt buyer negotiate a lower settlement?
A debt buyer may have authority to negotiate settlement terms, but there is no guaranteed settlement percentage. The amount offered and accepted depends on the company, account, debt age, financial circumstances, and other factors.
If a debt buyer cannot prove ownership, do I automatically not have to pay?
Not necessarily. A documentation problem may affect the buyer’s ability to establish its claim, but it does not automatically prove that the underlying debt never existed.
If you dispute the account, follow the applicable validation and dispute procedures and keep records of your communications.
Do debt buyers have to notify me when they purchase a debt?
There is no single universal federal rule requiring every debt buyer to immediately notify every consumer simply because a purchase occurred. However, applicable debt-collection rules can require information when collection activity begins.
Are debt buyers more aggressive than collection agencies?
There is no reliable basis for assuming that one category is inherently more aggressive. Collection practices vary substantially from company to company.
Can a collection agency eventually become the owner of a debt?
Some companies operate multiple business lines, so it is possible for a company or related entity to operate as a collector in one situation and a debt buyer in another. What matters is the company’s role with respect to your specific account.
Can a debt buyer sell my debt again?
Yes. A debt buyer may resell an account to another debt buyer. If a new company contacts you, verify the new company’s identity and authority to collect.
Can nonprofit credit counselors work with both debt buyers and collection agencies?
Nonprofit credit counseling organizations may work with debts involving original creditors, collection agencies, or debt buyers depending on the circumstances and the type of debt-management program involved.
How can I check whether a debt collector is legitimate?
You can request validation information, check the company’s identity and contact information, review your credit reports, and check applicable state licensing or registration records where available.
Debt Buyer vs. Collection Agency: What Should You Do First?
If an unfamiliar company contacts you about a debt, start with the basics.
- Identify the company. Find out its legal name and contact information.
- Ask who owns the debt. Determine whether the company owns the account or is collecting for someone else.
- Request validation information. Review the information provided about the account and current creditor.
- Check your records. Compare the claim with your statements, payment records, and previous collection correspondence.
- Review your credit report. Look for the account and compare the reported information with the collection company’s claim.
- Check the account’s age. If the debt is old, research the applicable statute of limitations before making a payment or acknowledgment.
- Decide how to proceed. Depending on the circumstances, you may dispute inaccurate information, negotiate, pay, or seek legal advice.
If the account is already affecting your credit report, you can also review our guide on disputing credit report errors.
The Bottom Line
The fundamental difference between a debt buyer and a collection agency is ownership.
A collection agency generally works on behalf of the original creditor, while a debt buyer purchases the debt and becomes its current owner.
That difference can affect:
- Who you are negotiating with
- Who has authority over the account
- What documentation may be relevant
- How the debt may move through the collection system
- What you should verify before making a payment
If you are unsure which type of company is contacting you, ask directly and request validation information. Do not assume that an unfamiliar company automatically owns the debt simply because it is calling you.
Understanding who owns the account is an important first step before negotiating, disputing, or making a payment.
Need Help Reviewing a Collection Account?
If you are dealing with a debt buyer, collection agency, or unfamiliar collection account on your credit report, reviewing the account information carefully can help you understand what is being reported and whether inaccurate information may be present.
Contact Credit Repair Services to discuss your credit situation and learn about available credit-repair options.