
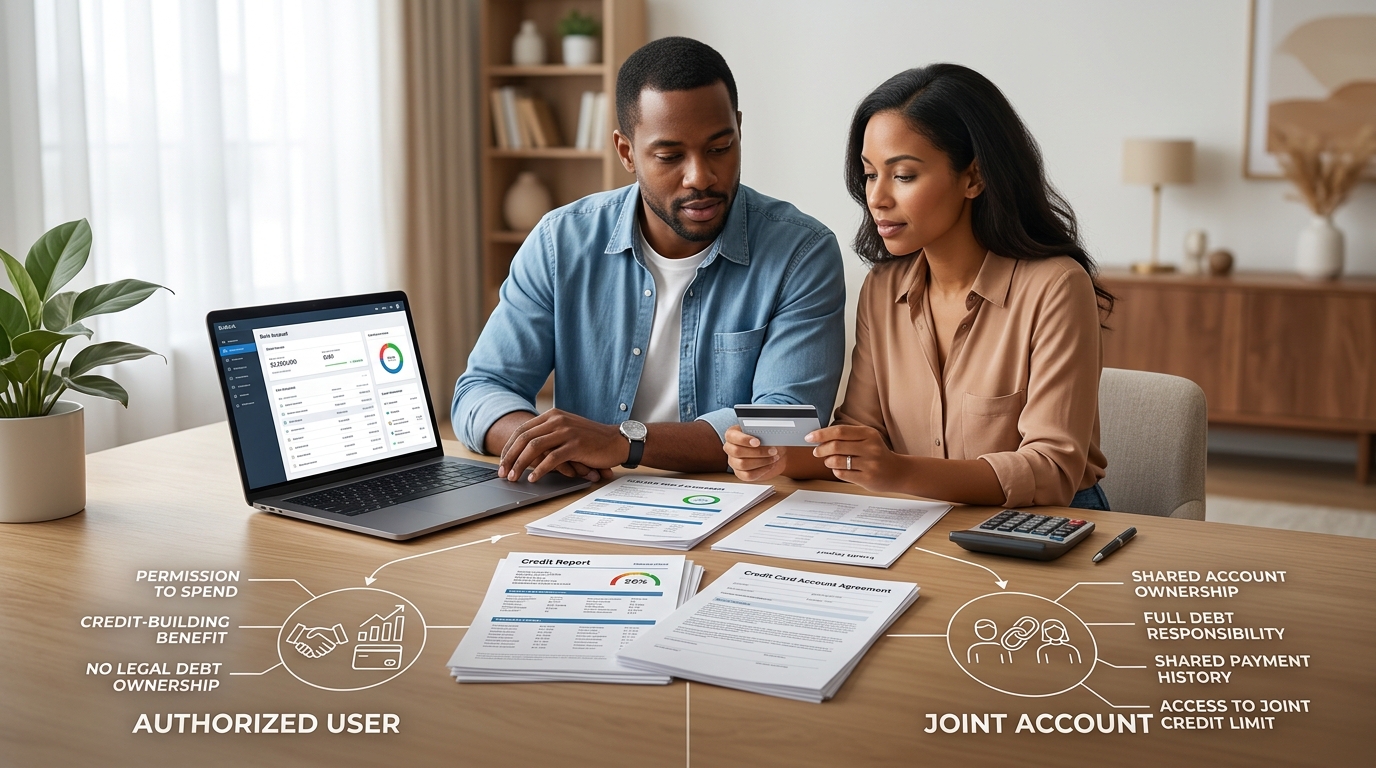
They may sound similar because both involve two people connected to one account. But the financial and legal reality behind each arrangement is very different.
The distinction can affect your credit report, credit-building opportunities, control over the account, and responsibility for debt.
This guide explains exactly what separates an authorized user from a joint account holder, when each arrangement may make sense, and the mistakes people make when they assume the two are interchangeable.
The Short Version
An authorized user is someone who has been given permission to use a credit card account that legally belongs to someone else. They can generally make purchases using the card, and the account’s history may appear on their credit report if the issuer reports authorized-user activity. However, an authorized user generally has no legal obligation to pay the account balance and does not own the account.
A joint account holder is a co-owner of the account. Both people are legally responsible for the debt and generally have account-management rights associated with ownership.
That distinction—legal responsibility for the debt—is the single most important difference between the two arrangements.
If you are trying to build credit, it is also important to understand how credit scores are calculated, because the effect of an account depends on the information being reported and the scoring model being used.
Authorized Users Explained
How an Authorized User Arrangement Works
The primary cardholder—the person who owns the account—can request that the card issuer add another person as an authorized user.
The issuer may request information such as the person’s name, date of birth, and, depending on its policies, Social Security number or other identifying information.
Unlike opening a new credit account, adding an authorized user typically does not require the same type of credit application and approval process for the person being added.
The authorized user may receive a physical card connected to the same account and credit limit.
What Authorized Users Can Do
Depending on the card issuer’s policies, an authorized user may be able to:
- Make purchases using the authorized card.
- Use the account’s available credit.
- View certain account information.
- Request a replacement card or report a card as lost or stolen.
The exact permissions can vary by issuer, so the account holder should confirm the specific rules before adding another person.
What Authorized Users Generally Cannot Do
An authorized user generally does not have the same legal rights as the account owner.
Depending on the issuer and account agreement, an authorized user generally cannot:
- Take legal ownership of the account.
- Become legally responsible for the account balance simply by being an authorized user.
- Change the overall credit limit.
- Add other authorized users.
- Make major account-level decisions reserved for the account owner.
- Close the account as an owner.
The precise rules vary by card issuer, so the account agreement remains important.
How Being an Authorized User Can Affect Your Credit
This is one of the main reasons people consider becoming authorized users.
Many major credit card issuers report authorized-user accounts to the credit bureaus. When they do, information associated with the account can appear on the authorized user’s credit report.
That may include information such as:
- Account age.
- Payment history.
- Credit limit.
- Reported balance.
- Utilization information.
For example, imagine that a parent has maintained a credit card for many years with a strong payment history and relatively low utilization. If the issuer reports the account for the authorized user, that established account may become part of the authorized user’s credit profile.
This can be particularly relevant for someone with a thin or relatively new credit file.
However, authorized-user status is not automatically beneficial.
If the primary account holder carries high balances, misses payments, or otherwise has negative information reported on the account, those details may also affect the authorized user’s credit file when the issuer reports them.
The authorized user therefore receives potential benefits from someone else’s account behavior—but may also be exposed to the consequences of that person’s account management.
For additional credit-building strategies, see our guide on how to improve your credit score.
Joint Account Holders Explained
How a Joint Account Works
A joint account involves two people who are legally responsible for the account.
Both individuals generally apply for the account together and are evaluated according to the lender or card issuer’s approval requirements.
Joint credit card arrangements are less common today than authorized-user arrangements with many issuers, so the availability of joint accounts depends heavily on the specific financial institution.
What Joint Account Holders Can Do
Because joint holders are co-owners, they generally have substantially greater rights than authorized users.
Depending on the account agreement, joint holders may be able to:
- Make purchases.
- View and manage the account.
- Request certain account changes.
- Manage account settings allowed under the agreement.
- Exercise ownership rights associated with the account.
The precise authority available to each joint holder depends on the financial institution and the account agreement.
What Joint Account Holders Are Responsible For
Here is the critical difference:
Joint account holders can be legally responsible for the entire balance, regardless of who made the individual purchases.
Suppose two people share a credit card and one person charges $8,000 but then stops making payments.
The other joint holder may still be responsible for the full balance under the account agreement. Joint liability does not necessarily mean that each person is responsible for only half of the debt.
This is why joint accounts require a significantly higher level of financial trust and communication.
How Joint Accounts Affect Credit
Because both people are legal account holders, the account can appear on both individuals’ credit reports.
Positive information can help both credit profiles, while negative information can hurt both.
If payments are missed or balances become excessively high, both joint holders can potentially experience negative credit consequences.
This is different from an authorized-user relationship because the joint holder is also legally responsible for the underlying debt.
Authorized User vs. Joint Account: Side-by-Side Comparison
| Feature | Authorized User | Joint Account Holder |
|---|---|---|
| Legal ownership | Generally no | Yes |
| Legal responsibility for debt | Generally none solely from authorized-user status | Generally full responsibility |
| Credit check | Usually no separate credit application | Typically yes when opening the account |
| Can use the card | Generally yes | Yes |
| Can manage the account | Limited | Generally much broader rights |
| Can close the account | Generally no | Ownership rights may allow account management, subject to issuer rules |
| Appears on credit report | Often, but issuer-dependent | Generally yes |
| Affected by negative account activity | Potentially yes | Yes |
| Debt liability | Generally no legal liability | Generally full legal liability |
| Removal | Often relatively straightforward, depending on issuer | Generally more complicated |
When Being an Authorized User May Make Sense
An authorized-user arrangement may make sense in several situations.
Helping Someone Build Credit
A parent or family member may want to help someone with a thin credit file establish positive credit history.
A well-managed account with a long history and low utilization may provide useful credit-report information if the card issuer reports authorized-user activity.
However, the account holder should understand that the authorized user may be affected by the account’s reported activity.
Providing Spending Access Without Shared Legal Ownership
An authorized-user arrangement can provide another person with card access while keeping ownership and primary responsibility with the account holder.
For example, a parent may add a teenager or young adult to a credit card for emergencies or controlled spending.
The primary cardholder retains control of the underlying account.
Using a More Reversible Arrangement
Authorized-user status can generally be removed without closing the entire credit account, although the exact process depends on the issuer.
This can make the arrangement less permanent than establishing a joint account.
When a Joint Account May Make Sense
A joint account may make sense when both people genuinely intend to share ownership and responsibility.
Shared Household Expenses
Couples or long-term partners who manage household finances together may choose an arrangement in which both people have legal responsibility and account-management rights.
Equal Financial Responsibility
If both people want the account to represent a shared financial obligation, joint ownership can reflect that arrangement more directly.
Shared Financial Planning
Joint accounts can also be considered when two people are intentionally building a shared financial life and both understand the consequences of the account.
The important point is that joint ownership comes with genuine financial liability—not simply shared access.
The Risks You Should Take Seriously
Risks for an Authorized User
An authorized user’s primary risk is that their credit profile may be affected by someone else’s account management.
If the primary cardholder:
- Misses payments.
- Uses a very high percentage of the available credit.
- Allows the account to become delinquent.
- Accumulates other negative information.
the authorized user’s credit report may potentially reflect that information if the issuer reports it.
The authorized user may have little or no control over correcting the underlying account because they are not the legal owner.
Risks for a Joint Account Holder
The risk is more direct for a joint holder.
If the other joint holder spends heavily and does not pay the balance, the other joint holder may remain legally responsible for the entire debt.
That means a disagreement over spending can become a serious financial and credit problem.
Relationship Risk in Both Arrangements
Both arrangements require trust and communication.
Problems can arise when:
- One person spends more than expected.
- Payment responsibilities are unclear.
- The relationship ends.
- One person becomes financially irresponsible.
- Neither person has clearly defined an exit plan.
Before linking your credit to another person, discuss the rules and expectations in advance.
How to Remove Yourself From an Authorized User Arrangement
Removing an authorized user is generally simpler than separating from a joint account.
An authorized user may be able to request removal directly from the card issuer, or the primary cardholder can generally request that the authorized user be removed.
The exact procedure varies by issuer.
After removal, the account’s future reporting may no longer appear as an authorized-user account on the person’s credit file. The treatment of historical information can depend on the credit bureau, issuer, and circumstances.
If you are using authorized-user status as part of a broader credit-building strategy, it is important to have other accounts or positive credit activity rather than relying entirely on someone else’s account.
How to Remove Yourself From a Joint Account
Removing yourself from a joint account can be considerably more complicated.
Simply agreeing with the other person that you are no longer responsible does not necessarily release you from your legal obligation to the creditor.
Depending on the account and issuer, separating the financial relationship may require:
- Paying off the existing balance.
- Closing the joint account.
- Opening a new account in one person’s name.
- Refinancing or transferring the obligation where available.
- Working directly with the creditor to determine available options.
This is particularly important after a divorce or separation.
A private agreement between two former partners does not necessarily change the terms of the creditor’s account agreement.
What Happens When Someone Dies?
The two arrangements can also differ when one account holder dies.
Authorized User
An authorized user generally is not legally responsible for the deceased primary cardholder’s credit card debt merely because they were an authorized user.
The account and any outstanding debt may instead be handled according to the primary cardholder’s estate and applicable law.
Joint Account Holder
A surviving joint account holder generally remains responsible for the account’s outstanding balance because they are also a legal account holder.
The exact treatment of an account after death can depend on the account agreement and applicable law, so anyone dealing with a deceased account holder’s debts should confirm the specific circumstances.
Authorized User vs. Co-Signer: A Third Important Difference
Authorized users and joint account holders are also different from co-signers.
A co-signer agrees to be legally responsible for a debt if the primary borrower does not meet their obligation.
A co-signer may not have the same day-to-day access to the account that an authorized user or joint account holder has.
In terms of financial liability, however, a co-signer can have significant responsibility for the debt.
Because the exact structure varies by loan and lender, it is important to read the specific agreement rather than assuming that “co-signer,” “joint holder,” and “authorized user” mean the same thing.
Frequently Asked Questions
Will an authorized-user account appear on my credit report?
It may. Many issuers report authorized-user accounts to the credit bureaus, but reporting practices vary by issuer. If credit building is the reason for adding an authorized user, confirm the issuer’s reporting policy first.
Can an authorized user be responsible for the credit card debt?
Simply being an authorized user generally does not make the person legally responsible for the underlying balance. The primary account holder remains responsible for the debt under the account agreement.
Can a joint account holder be responsible for the entire balance?
Generally, yes. Joint account holders can be legally responsible for the entire balance rather than only the portion associated with their own purchases.
Is an authorized user the same as a joint account holder?
No. An authorized user generally has permission to use someone else’s account without becoming a legal owner. A joint account holder is a co-owner with legal responsibility for the account.
Can an authorized user close the account?
Generally, no. An authorized user does not normally have the same account-ownership rights as the primary account holder.
Can a joint account holder close the account?
Account-management rights depend on the specific issuer and account agreement. A joint holder generally has substantially greater rights than an authorized user, but the exact process for closing or changing an account should be confirmed with the issuer.
Can I become an authorized user without providing my Social Security number?
It depends on the card issuer. Some issuers may require limited information, while others may request additional identifying information so they can accurately report the account.
Is being an authorized user good for building credit?
It can be useful when the account is well managed and the issuer reports authorized-user activity to the credit bureaus. However, it should not be treated as a guaranteed score increase, because the impact depends on the account information and the scoring model.
For a broader look at credit-building strategies, visit our guide to improving your credit score.
Can I build credit by being an authorized user and also having my own account?
Yes. These approaches are not mutually exclusive. An authorized-user account can potentially add established credit history, while your own accounts give you credit relationships that you control directly.
Can a joint account holder be added after an account is opened?
This depends on the financial institution. Some institutions may allow changes to account ownership, while others do not offer joint credit card accounts or require a new application.
Can my ex-spouse remove me from a joint account?
The process depends on the account and issuer. Because joint holders have legal responsibility for the debt, simply asking to be removed does not necessarily release you from the creditor’s claim.
If you are separating finances, contact the creditor directly and determine what options are available for closing, transferring, or restructuring the account.
A Real-World Example: Helping a College Student Build Credit
Imagine a parent wants to help a college-age child establish credit.
There are two possible approaches:
- Add the child as an authorized user on an established credit card.
- Open a joint credit account together, if the issuer offers that structure.
Authorized User Approach
The parent remains the legal owner of the account.
The child can potentially benefit from the account’s reported history if the issuer reports authorized-user activity.
The parent maintains control over the account and can generally remove the authorized user if circumstances change.
The downside is that the child does not have the same legal ownership or control as a joint holder.
Joint Account Approach
The child becomes a legal co-owner of the account.
This creates a more direct shared financial relationship, but it also means both people can be responsible for the account balance.
If the child makes large purchases and does not pay, the parent may remain legally responsible for the debt as a joint account holder.
The choice therefore depends on whether the goal is primarily credit-building with limited shared liability or genuine shared ownership and responsibility.
How Scoring Models Treat Authorized-User Accounts
Authorized-user accounts can influence credit scoring, but the exact impact depends on the scoring model and the information reported.
Credit-scoring models have evolved over time, including changes related to the treatment of authorized-user accounts.
This matters because simply becoming an authorized user does not guarantee a particular score increase.
The account’s age, payment history, utilization, and other information can all matter.
Be Careful With “Tradeline Renting”
Some companies and individuals have promoted arrangements in which strangers are paid to add consumers as authorized users to established credit accounts.
This is different from a genuine family or trusted-person relationship.
Consumers should be cautious about paying for credit-report access through an unrelated person’s account, particularly when a company promises a guaranteed score increase.
Legitimate credit building should focus on accurate credit information and responsible financial behavior rather than relying on questionable arrangements designed solely to manipulate a credit profile.
What to Discuss Before Setting Up Either Arrangement
Before adding someone as an authorized user or opening a joint account, have a clear conversation about expectations.
How Much Can Be Spent?
Agree on whether the authorized user or joint holder will have a specific spending limit or informal spending rules.
Who Will Make the Payments?
Make the payment responsibility clear before spending begins.
This is especially important for joint accounts because both people can remain legally responsible for the debt.
How Will You Monitor the Account?
Decide whether both people will review balances, purchases, and payment activity regularly.
What Is the Exit Plan?
Discuss what happens if the arrangement needs to end.
For an authorized user, that may mean removing the person from the account.
For a joint account, the process may involve paying the balance, closing the account, or establishing a new arrangement with the creditor.
Frequently Asked Questions About Authorized Users and Joint Accounts
Does adding an authorized user cost money?
Many card issuers do not charge a fee for adding an authorized user, although some premium cards may charge additional-user fees. Check the specific card’s terms before adding someone.
Does an authorized user get a separate credit limit?
Generally, no. An authorized user’s card is typically connected to the same overall credit limit as the primary account.
What happens if a joint account holder files bankruptcy?
The bankruptcy of one joint holder does not automatically erase the other person’s legal responsibility for the joint debt. If you are a joint holder, you may remain responsible for the balance even if the other person’s obligation is affected by bankruptcy.
Because bankruptcy law is highly fact-specific, anyone facing this situation should obtain advice specific to their circumstances.
Can an authorized user account be converted into a joint account?
There is generally no universal conversion process. If both people want genuine joint ownership, the issuer may require a new application or another formal account process.
Do all credit card companies report authorized users?
No. Reporting practices vary by issuer. If credit building is the primary reason for the arrangement, verify directly with the issuer that authorized-user activity is reported.
How Divorce Can Complicate Joint Accounts
Joint accounts can become especially complicated during divorce.
A divorce agreement may assign responsibility for a particular debt to one spouse, but that agreement does not necessarily change the creditor’s original contract with both joint account holders.
For example, if a divorce agreement says that one spouse will pay a joint credit card, the creditor may still be able to pursue both joint account holders if the debt remains jointly owed under the account agreement.
This is why separating joint financial obligations during a divorce requires careful coordination with the creditors involved.
Simply relying on a private agreement between former spouses may not be enough to remove a person’s liability to the creditor.
What Happens If an Authorized User Is Removed?
Removing an authorized user can affect the person’s credit profile if the account was contributing to their reported credit history.
If the account is no longer reported as an authorized-user account, the person’s credit profile can change depending on how important that account was to their overall history, utilization, and credit mix.
For someone who relies heavily on one authorized-user account, losing it may have a noticeable effect.
This is another reason to build independent credit accounts rather than relying entirely on someone else’s account.
Can Business Credit Cards Have Joint Account Holders?
Business credit cards can have different structures from personal credit cards.
Businesses may have an owner or authorized employee users, while the underlying business entity and individual guarantors can have different responsibilities depending on the issuer and agreement.
Do not assume that business-card terminology works exactly like personal joint-account terminology.
Can an Authorized User Affect Your Mortgage Application?
Potentially, depending on the lender’s underwriting policies.
Some mortgage underwriting processes may consider information associated with an authorized-user account when evaluating a borrower’s credit profile or debt obligations.
If you are relying heavily on authorized-user accounts before applying for a mortgage, ask the lender how it treats those accounts under its underwriting guidelines.
The Bottom Line
The difference between an authorized user and a joint account holder comes down primarily to one question:
Who is legally responsible for the debt?
An authorized user generally receives permission to use someone else’s account without becoming the legal owner or assuming responsibility for the underlying debt solely because of that status.
A joint account holder is a legal co-owner and can be fully responsible for the account balance, regardless of who actually made the purchases.
Both arrangements can affect credit reports, but they create very different levels of control and legal responsibility.
Before choosing either arrangement, consider:
- Who owns the account?
- Who is legally responsible for the balance?
- Will the account be reported to the credit bureaus?
- How will spending be controlled?
- What happens if payments are missed?
- What happens if the relationship ends?
- How easy will it be to exit the arrangement?
If your goal is to build or rebuild credit, you can also explore our guides on how to fix your credit and credit repair tips.
Need Help Reviewing Your Credit Profile?
If you’re trying to determine whether an authorized-user account, joint account, or another credit issue is affecting your credit profile, reviewing your reports carefully is an important first step.
Contact Credit Repair Services for help with your credit situation →