
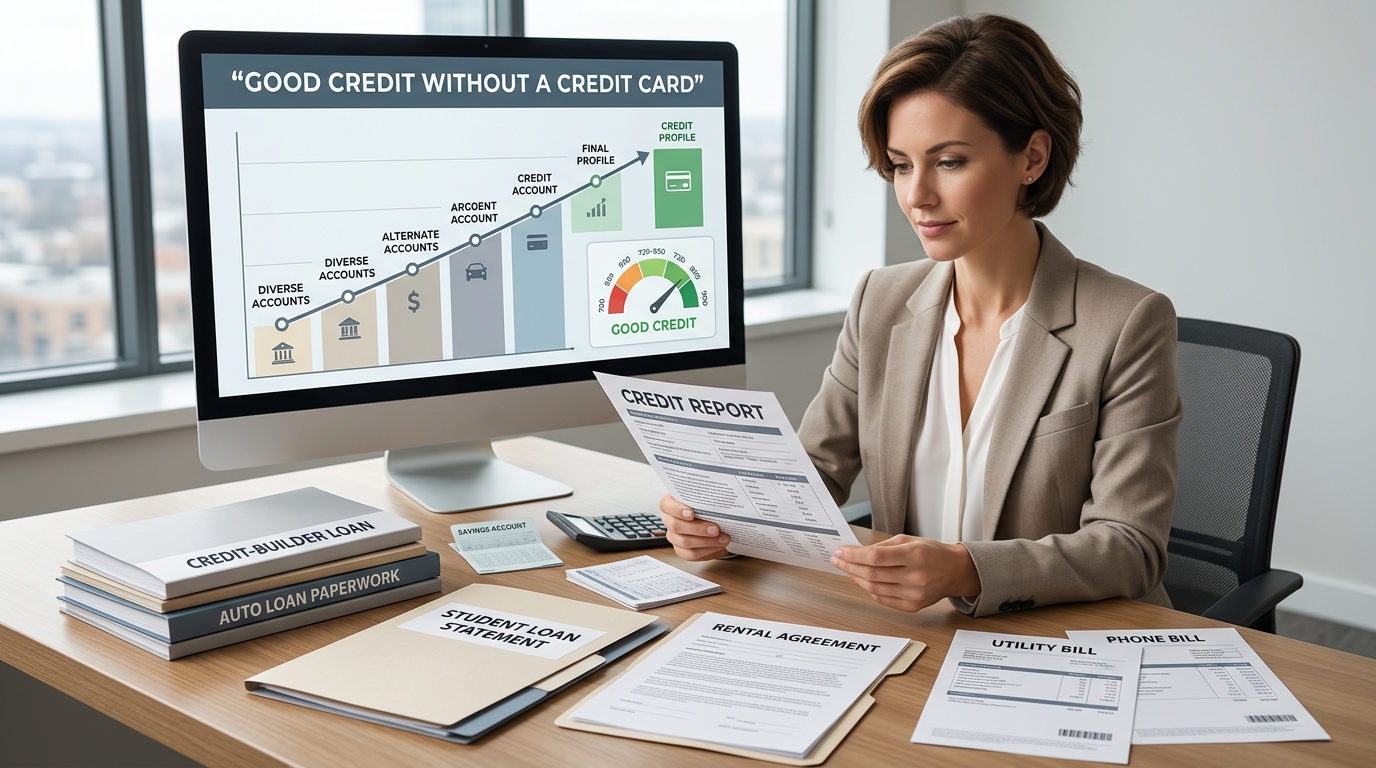
It’s an understandable assumption, since credit cards are among the most commonly discussed credit-building tools. But it’s not entirely accurate.
Good credit without a credit card is genuinely possible. However, it requires a more deliberate approach than the default path many people follow.
This guide explains how credit scoring can work without a credit card, which alternative tools can help build credit, what the major tradeoffs are, and how you can create a strong credit profile without relying on revolving credit cards.
Why This Question Even Comes Up
Some people avoid credit cards for genuinely personal reasons.
For example, someone may have experienced credit card debt in the past and not want to repeat it. Others may prefer simpler cash-based spending, have personal or religious objections to interest-based debt, or simply want to avoid the temptation of having readily available revolving credit.
Whatever the reason, the concern is legitimate:
If credit cards are one of the most common ways people build credit, does avoiding them permanently damage your financial life?
The answer is nuanced.
It is absolutely possible to build and maintain good credit without a credit card. However, you generally cannot build a strong traditional credit profile with literally zero credit activity.
Credit-scoring models need information to evaluate.
The distinction that matters is therefore “no credit card” versus “no credit at all.”
If you are starting with little or no credit history, you may also want to read our guide on how to improve your credit score.
How Credit Scoring Actually Works
Credit scores are calculated using information contained in your credit reports.
Those reports track your history with different types of credit accounts. Importantly, “credit accounts” does not mean only credit cards.
Credit scoring models consider multiple aspects of your credit profile, including factors such as:
- Payment history.
- Credit utilization.
- Length of credit history.
- Credit mix.
- New credit and recent applications.
Payment History
Payment history is not limited to credit cards.
If you have a reported installment loan and consistently make your payments on time, those payments can contribute to your credit history.
Credit Utilization
Credit utilization is different.
It primarily concerns revolving credit, such as credit cards and lines of credit, and measures balances relative to available credit limits.
This is one of the more difficult aspects of a traditional credit profile to develop without a credit card.
Length of Credit History
You do not necessarily need a credit card for an account to establish a history over time.
An installment account that remains open and is managed responsibly can contribute to the age and history of your credit file.
Credit Mix
Credit mix considers the different types of credit accounts in your profile.
Having installment accounts can therefore contribute to the variety of credit types represented in your file.
New Credit
New credit considers recent applications, new accounts, and associated inquiries.
This factor is not exclusively about credit cards.
Alternative Credit-Building Tools That Don’t Require a Credit Card
If you intentionally want to avoid credit cards, you still have several potential credit-building options.
Installment Loans
Installment loans have a fixed amount, a defined repayment schedule, and a set number of payments.
Examples include:
- Auto loans.
- Personal loans.
- Student loans.
- Mortgages.
When these accounts are reported to the credit bureaus, making payments on time can help establish positive payment history.
For example, someone with a student loan or auto loan may already be building credit without owning a credit card.
Credit-Builder Loans
A credit-builder loan is specifically designed to help consumers establish or strengthen credit history.
These products are often offered by credit unions and some financial institutions.
Instead of receiving the loan proceeds immediately, the borrowed amount may be placed into a secured savings account while you make scheduled payments.
The payments may be reported to the credit bureaus.
After the loan is completed, the funds are generally released according to the product’s terms.
Because the structure is specifically designed around building payment history, a credit-builder loan can be an option for someone who does not want a credit card.
Secured and Share-Secured Loans
Some credit unions offer secured or share-secured loans backed by money held in a savings account or another form of collateral.
These loans can be easier to qualify for in some circumstances because the lender has collateral supporting the obligation.
If the lender reports the account, responsible payments can help establish positive credit history.
Rent Reporting
Rent is one of the largest recurring expenses for many consumers, but traditional credit reports have not historically captured every rent payment.
Some rent-reporting services and participating landlords can report rental payment information to one or more credit bureaus.
If your rent payments are reliably made on time, rent reporting can potentially turn an existing financial habit into additional credit history.
The exact bureaus covered, eligibility requirements, and fees vary by service, so review the terms carefully.
Utility and Phone Bill Reporting
Some services allow consumers to use eligible utility, phone, or other recurring bill payments to add information to a credit file.
One example is Experian Boost, which is a service offered by Experian that can consider eligible recurring payments for its credit file.
However, it is important to understand the limitation: a tool that affects an Experian credit file does not automatically add the same information to Equifax and TransUnion.
Being an Authorized User
Another possibility is becoming an authorized user on someone else’s well-managed credit card.
This does not require you to open a credit card in your own name.
However, it is technically still an arrangement involving a credit card account, so someone who wants to avoid credit cards entirely may not consider this a true card-free strategy.
It is also important to understand that authorized-user reporting practices vary by issuer.
The Utilization Problem: The One Factor That’s Harder Without a Credit Card
There is one genuine challenge with avoiding credit cards entirely: credit utilization.
Credit utilization measures revolving balances relative to available revolving credit.
Credit cards are the most common form of revolving credit available to consumers.
Installment loans do not work the same way.
For example, the remaining balance on an auto loan is not treated like a credit card balance compared with a credit limit.
As a result, someone who has no revolving credit account may have less information in this particular part of their credit profile.
That does not mean that the person cannot have good credit.
Someone with strong installment-loan payment history, reported rent payments, and an otherwise clean credit file can still establish a solid credit score without a credit card.
However, the absence of revolving credit may make it more difficult to maximize certain scoring factors compared with an otherwise identical consumer who responsibly manages a revolving account.
A Realistic Path to Good Credit Without a Credit Card
If avoiding credit cards is your goal, you can take a deliberate approach.
1. Start With an Installment-Type Account
A credit-builder loan can be one option because it is specifically designed to establish positive payment history.
Before opening any account, compare the fees, interest rate, reporting practices, and total cost.
2. Add Rent Reporting If You Rent
If you already pay rent consistently, rent reporting may allow those payments to contribute to your credit profile.
Compare providers carefully and confirm which credit bureaus receive the information.
3. Consider Eligible Bill-Payment Reporting
Services such as Experian Boost may allow eligible recurring bills to contribute information to an Experian credit file.
This can be useful for someone who is already paying those bills regularly.
4. Consider a Secured Installment Loan
If you have savings and your credit union offers a suitable share-secured loan, this may provide another installment account that can contribute to your payment history and credit mix.
5. Be Patient
Building credit without a credit card can require patience.
A good credit profile is generally built through consistent, responsible management over time rather than a single financial product.
A solid credit score can be achievable without a credit card, although the exact score and timeline will depend on the individual’s credit history and the scoring model being used.
Is It Actually a Good Idea to Avoid Credit Cards Entirely?
This is a separate question from whether it is technically possible.
There are legitimate reasons someone may choose not to use credit cards.
Reasons Someone May Avoid Credit Cards
Someone with a history of credit card debt may prefer not to have access to revolving credit.
Others may prefer spending only money they already have available.
Personal, ethical, or religious beliefs may also influence the decision.
For those individuals, avoiding credit cards can be a deliberate financial choice rather than a credit-building mistake.
Tradeoffs of Going Card-Free
Credit cards can provide access to revolving credit, which is relevant to the utilization portion of many scoring models.
They may also provide rewards, cash-back opportunities, emergency payment flexibility, and certain consumer protections.
Some consumers who want to minimize risk choose a middle-ground option, such as a secured credit card with a small limit.
However, a secured credit card is still a credit card and therefore does not meet the strict definition of avoiding credit cards altogether.
Common Misconceptions About Credit Without a Credit Card
“You Need a Credit Card to Have Any Credit Score.”
False.
Credit scores can be generated using information from different types of reported credit accounts.
Installment loans can contribute to a credit history even when a consumer has never opened a credit card.
“Debit Cards Build Credit Like Credit Cards.”
False.
Using a debit card generally does not create the same type of credit account or revolving credit history as a credit card.
Debit card purchases draw from money already held in your bank account rather than extending credit.
Therefore, simply using a debit card responsibly does not normally establish traditional credit history.
“You Can Never Get a Mortgage Without a Credit Card.”
Not necessarily.
Mortgage lenders evaluate an applicant’s overall financial and credit profile.
Installment loan history, rental payment history where considered, income, assets, debt obligations, and other factors can all matter.
However, a consumer with a thin credit file may encounter different underwriting requirements than someone with a longer and more diverse credit history.
Frequently Asked Questions
Can I get a good credit score using only a credit-builder loan?
It is possible to establish credit with a credit-builder loan, but relying on one account can limit the breadth of your credit profile.
Depending on your situation, combining responsible installment credit with other legitimate reporting sources may create a more developed credit history.
Does having zero revolving credit actively hurt my score?
The absence of revolving credit does not automatically mean that your credit score will be poor.
However, it means scoring models may have less information about your management of revolving credit and utilization.
This can limit your ability to maximize certain scoring factors.
If I eventually want a credit card, will building credit without one help?
An established history of responsible credit management can give a lender more information about your creditworthiness than having no credit history at all.
Whether that makes approval easier depends on the lender’s underwriting requirements and your overall credit profile.
Is a secured credit card considered a credit card?
Yes.
A secured credit card is still a revolving credit account. The deposit provides security for the issuer, but the account functions as a credit card for credit-reporting purposes.
How long does it take to build good credit without a credit card?
There is no universal timeline.
The time required depends on the accounts you use, whether they are reported to the credit bureaus, the age of your existing history, and how consistently you make payments.
Building a meaningful credit history generally requires months and often years of responsible management.
A Closer Look at Experian Boost and Similar Tools
Experian Boost is one of the better-known tools for potentially adding eligible recurring payment information to an Experian credit file.
The service can connect to eligible bank accounts or use other supported methods to identify qualifying payments such as certain utility, phone, and streaming bills.
However, there is an important limitation.
Experian Boost applies to an Experian credit file.
It does not automatically add the same information to Equifax and TransUnion.
That means someone who relies heavily on Experian Boost should understand that a lender reviewing another bureau may not see the same information.
It is therefore better viewed as a supplement to a broader credit-building strategy rather than a complete replacement for traditional credit accounts.
How Lenders May Evaluate You Without a Traditional Credit Profile
Someone can have responsible financial habits and still have a relatively thin credit file.
A lender may sometimes use alternative underwriting methods when traditional credit information is limited.
Depending on the lender and product, alternative evaluation may include:
- Bank-account information.
- Income consistency.
- Rental payment history.
- Utility payment history.
- Employment information.
- Alternative credit data.
- Manual underwriting.
Not every lender offers these options.
If you have repeatedly been denied because your credit file is too thin, you can ask the lender whether it offers an alternative underwriting process.
A Sample 12-Month Plan for Building Credit Without a Credit Card
Month 1
Consider opening a credit-builder loan through a reputable credit union or financial institution after comparing costs and reporting practices.
If you rent, investigate whether a legitimate rent-reporting service is available to you.
Months 1–3
Make every payment on time.
Confirm that the credit-builder loan is being reported correctly and, if applicable, that your rent-reporting service has begun reporting payments.
Month 3
Consider whether an eligible service such as Experian Boost fits your situation.
If you use such a service, understand which credit bureau receives the information.
Months 3–6
Continue making all payments on time.
Review your credit reports to confirm that your accounts are being reported accurately.
If you find inaccurate information, learn more about how to dispute credit report errors.
Month 6
Depending on your financial situation, you could consider whether another appropriate installment account makes sense.
Do not open unnecessary debt solely for the purpose of increasing your credit score.
Months 6–12
Continue responsible payment management and monitor your credit periodically.
Focus on consistency rather than trying to create rapid score changes.
Month 12 and Beyond
After a year of consistent management, review your overall credit profile and determine whether your current strategy is meeting your goals.
If you eventually decide that a credit card is appropriate, an established credit history may provide a stronger starting point than applying with no credit history at all.
Frequently Asked Questions About Building Credit Without a Credit Card
Does paying off a credit-builder loan early hurt my credit?
Paying off an installment loan early does not erase the positive payment history that has already been reported.
However, paying it off early ends the future monthly reporting that would have occurred while the loan remained open.
If your primary purpose for the account is credit building, compare the financial cost of the loan with the potential benefit of keeping it open according to its original schedule.
Is my credit mix incomplete if I only have installment loans?
Not in a way that automatically prevents you from having good credit.
However, scoring models can consider the variety of credit accounts in your profile, so an otherwise identical profile with both installment and revolving accounts may have different scoring results.
Can I build credit through a mortgage if it is my only credit account?
Yes. A mortgage is an installment loan, and its reported payment history can contribute to your credit profile.
Because mortgages can remain on a credit report for many years, responsible mortgage payments can become an important part of a homeowner’s credit history.
Can Someone Without a Credit Card Have a Higher Score Than Someone With One?
Absolutely.
Having a credit card does not automatically produce a good credit score.
For example, someone with a maxed-out credit card and a history of late payments can have substantially weaker credit than someone who has no credit card but maintains a clean history of reported installment payments.
The important issue is not simply whether a particular account exists.
How responsibly the accounts are managed matters enormously.
Why Some Financial Professionals Still Recommend Having a Credit Card
Even though good credit without a credit card is possible, there are practical reasons some financial professionals recommend having access to one.
Emergency Flexibility
A credit card can provide another payment option during an emergency when cash savings may not immediately cover a large expense.
However, relying on credit for emergencies can also create debt, so an emergency fund remains an important part of financial planning.
Fraud Protection
Credit cards and debit cards have different legal and practical protections for unauthorized transactions.
Consumers should understand the applicable rules and promptly report unauthorized transactions to their financial institution.
Building Revolving Credit History
As discussed earlier, revolving credit is the main area that is difficult to replicate without a credit card.
A responsibly managed credit card can therefore provide information about revolving-credit management that installment loans cannot provide in the same way.
Travel and Rental Holds
Some hotels and rental-car companies may place security holds or have policies that make credit cards more convenient or, in some circumstances, specifically required.
Someone who chooses to remain entirely credit-card-free should check payment requirements before traveling.
These practical considerations do not change the central point: you can build good credit without a credit card.
Frequently Asked Questions About Going Completely Card-Free
Does closing my only credit card hurt my credit?
It can affect your credit profile, particularly if the account is old or has a meaningful credit limit.
Closing a credit card can eliminate its available revolving credit and may affect utilization calculations depending on how your remaining accounts are reported.
If you already have a card and are considering closing it, evaluate the consequences before making the decision.
Our guide to how credit scores are calculated can help you understand the relevant factors.
Are credit-builder loans available everywhere?
Availability varies by location and financial institution.
Credit unions and community financial institutions may offer credit-builder products, but terms, fees, interest rates, and credit-bureau reporting practices vary.
Compare several options before opening an account.
Will lenders think it is suspicious if I have no credit card?
Not necessarily.
A lender generally evaluates the overall credit profile rather than automatically treating the absence of a credit card as suspicious.
However, a limited or thin credit file may provide less information for traditional underwriting.
The Bottom Line
Yes, you can have good credit without a credit card.
But there is an important distinction: you generally cannot build a strong traditional credit profile without any credit activity.
Installment loans, credit-builder loans, mortgages, eligible rent reporting, and certain bill-reporting services can all provide alternative paths to establishing credit history.
The main tradeoff is credit utilization.
Because utilization specifically concerns revolving credit, it is harder to develop that part of your credit profile without a revolving account.
That may make reaching the highest scoring tiers more difficult in some circumstances, but it does not prevent you from developing solid credit.
If avoiding credit cards is an intentional personal or financial choice, it does not have to mean giving up on good credit.
The key is to be deliberate about the other credit-building tools you use, make every payment on time, avoid unnecessary debt, and periodically review your credit reports for accuracy.
If you are working to establish or rebuild your credit, explore our credit repair tips and our guide on how to fix your credit.
Need Help Understanding Your Credit Profile?
If you are building credit without a credit card or trying to understand why your score is not where you want it to be, reviewing your credit reports is an important first step.
Contact Credit Repair Services to discuss your credit situation →