
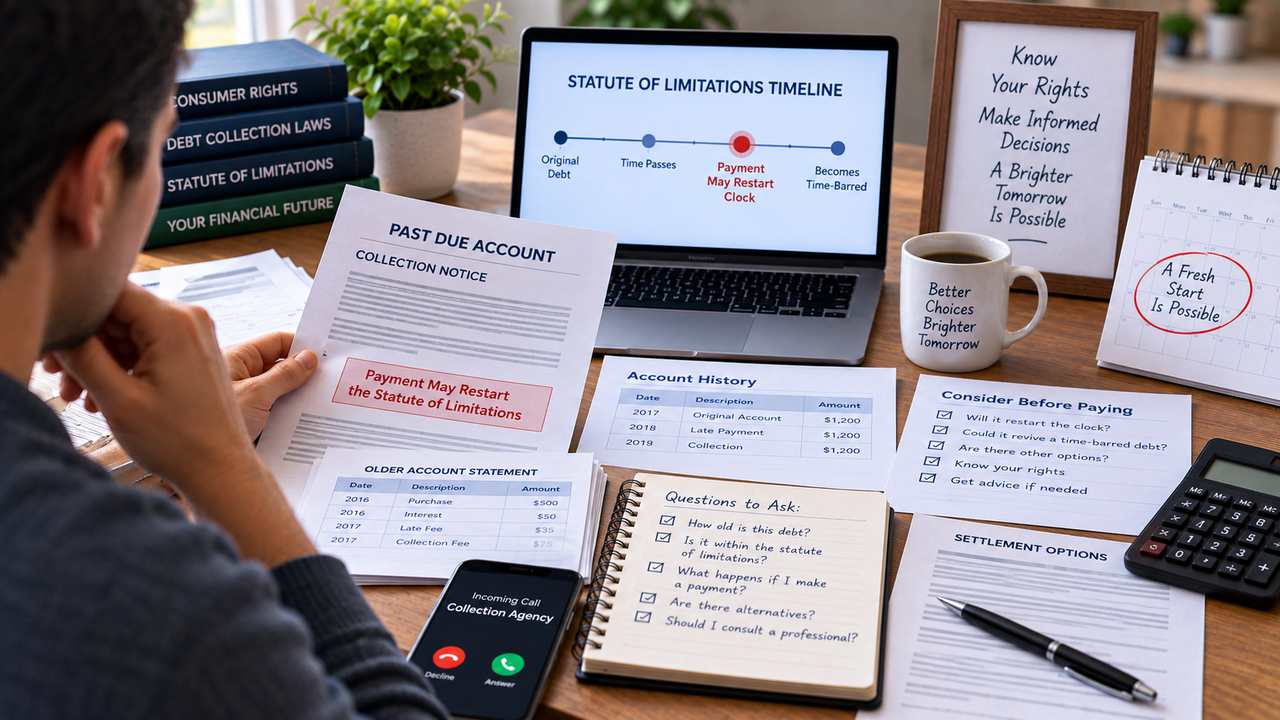
The Core Issue: Restarting the Statute of Limitations
Every state has a statute of limitations — a legal deadline within which a creditor or debt collector can sue you to collect a debt through the court system. Once this window closes, the debt is generally still technically “owed” in an informal sense, but it becomes what’s called “time-barred,” meaning it can no longer be successfully enforced through a lawsuit, even though a collector might still legally contact you and ask for payment.
The Consumer Financial Protection Bureau (CFPB) explains that the statute of limitations depends on factors such as the type of debt, applicable state law, and potentially the law specified in a credit agreement. The CFPB also warns that, in some states, a partial payment or acknowledgment of an old debt can restart the limitations period.
Here’s the part that catches people off guard: in many states, taking certain actions related to an old debt — including making even a partial payment, or in some states simply acknowledging in writing that you owe it — can legally restart that statute of limitations clock. This means a debt that was previously safely outside the window for a lawsuit can become newly, fully enforceable again, simply because you made what felt like a reasonable, responsible gesture toward resolving it.
Why This Rule Exists
This isn’t an arbitrary trap — the underlying legal logic is that a new payment or acknowledgment represents a fresh recognition of the debt’s validity, which many states’ laws treat as functionally similar to a new promise to pay, restarting the clock much the way a brand-new debt agreement would. From the law’s perspective, if you’re actively engaging with and partially paying an old debt, it makes some sense to treat that as reviving the creditor’s ability to pursue the remainder through legal means, rather than treating the payment as happening in some kind of legal vacuum separate from the underlying obligation’s enforceability.
Whether or not this reasoning feels fair from a consumer’s perspective, understanding that it exists — and that debt collectors are often well aware of exactly how it works — is essential before making any decision about an old debt.
The CFPB’s current consumer guidance specifically notes that making a partial payment or acknowledging an old debt may restart the limitations period in some states.
How This Gets Exploited by Some Debt Collectors
This isn’t a hypothetical, rarely-relevant technicality. Some debt collectors, aware of exactly how this rule works, specifically target very old, otherwise time-barred debt with settlement offers designed to look attractive and low-pressure — “pay just a small amount to resolve this old account” — precisely because getting you to make even a token payment can revive their ability to pursue the remaining balance through litigation, something they couldn’t have done the day before you made that payment. This is exactly the kind of practice consumer protection cases and regulatory guidance (including a notable federal case specifically addressing misleading settlement letters on time-barred debt) have scrutinized, since it can mislead consumers who don’t understand the legal mechanics at play into inadvertently creating new legal exposure.
Federal rules also matter here. Under Regulation F, 12 CFR § 1006.26, a debt collector generally may not bring or threaten to bring a legal action against a consumer to collect a time-barred debt. However, whether a debt has become time-barred and whether a payment or acknowledgment can revive the right to sue are matters that can depend on state law.
If you’re dealing with aggressive collection activity, you may also want to read our guide on collection agency harassment and the FDCPA.
How to Know If This Risk Applies to Your Specific Debt
- Determine roughly how old the debt actually is, measured from either your last payment or the date the account first became delinquent (the specific starting point varies by state and debt type).
- Look up your state’s specific statute of limitations for the type of debt involved (credit card, personal loan, medical debt, and other categories sometimes have different rules even within the same state).
- Compare the debt’s age against that statute of limitations period. If the debt is already older than your state’s limitations period, it’s likely time-barred, meaning this restart risk is directly relevant to any decision about making a payment.
- If you’re not certain, treat it as a live risk rather than assuming it doesn’t apply. Given how much is potentially at stake (renewed lawsuit exposure on a debt that was otherwise safely past the legal window), erring toward caution — verifying with certainty, or consulting a consumer law attorney, before making any payment on genuinely old debt — is the more prudent approach.
The Federal Trade Commission’s debt collection guidance similarly explains that the limitations period depends on the type of debt and applicable state law and recommends checking the relevant state rules before deciding how to handle an old debt.
You can also review our guide on the statute of limitations on debt for additional information about how these deadlines can affect collection activity.
What Specifically Can Restart the Clock, Beyond Just Payment
Depending on your state’s specific law, several actions beyond a direct payment can potentially have the same restarting effect:
- Making any payment, even a small, partial one.
- Signing a new payment agreement or settlement letter, even without making an actual payment yet, in some states.
- Verbally acknowledging the debt in a way that could be interpreted as a new promise to pay, in some jurisdictions, though this is generally harder for a collector to prove without a payment or written acknowledgment to point to.
- In some states, simply making a payment on a different, unrelated debt to the same creditor can, in rare and specific circumstances, be argued to have implications for a separate old debt with that same creditor, though this is a more unusual and state-specific scenario worth confirming with an attorney if it seems potentially relevant to your situation.
Given this range of potentially triggering actions, and the fact that specific rules vary meaningfully by state, a cautious approach — avoiding any of these actions on genuinely old, time-barred debt until you’ve either decided you’re comfortable with the risk or confirmed it doesn’t meaningfully apply to your situation — is generally the wiser path.
What to Do Instead If You Want to Address Old, Time-Barred Debt
Get written confirmation of the debt’s status before doing anything. If you’re considering paying off an old debt anyway (for personal peace of mind, or because you believe it’s affecting your credit report, though a genuinely time-barred debt this old should typically already be off your report under the separate seven-year rule), consider requesting written confirmation from the collector that they won’t pursue any further legal action, and specifically that they acknowledge the debt is time-barred, before sending any payment.
Consult a consumer law attorney if the amount at stake is significant. Given the real legal complexity and the meaningful stakes involved (restarting exposure to a lawsuit, potential garnishment, or a lien), a brief consultation — often free or low-cost for this kind of question — can provide clarity specific to your state and situation that generic guidance can’t fully replace.
If you decide not to pay, consider sending a written statement noting your understanding that the debt is time-barred, and requesting the collector cease further contact, which is a request they’re generally required to honor under the FDCPA, even without you paying anything.
The CFPB’s debt collection rights guidance explains that consumers can request that a debt collector stop contacting them, although doing so does not necessarily prevent other legal collection methods when a debt remains legally enforceable.
Don’t confuse the credit reporting window with the statute of limitations. These are two entirely separate legal concepts — the seven-year credit reporting rule (governed by federal law, the FCRA) and your state’s statute of limitations for lawsuits (governed by state law) don’t automatically align, and a debt can be off your credit report while still theoretically within a longer statute of limitations period, or vice versa, depending on your specific state’s rule and the debt’s actual timeline.
The CFPB explains that most negative credit information can generally be reported for up to seven years, while bankruptcy can remain on a credit report for up to ten years. These credit-reporting periods are separate from state statutes of limitations for lawsuits.
For more information about the distinction between credit reporting and legal enforceability, see our guide on how to read a credit report.
What If You’ve Already Made a Payment Without Realizing the Risk?
If you’ve already made a payment on old debt without understanding this dynamic, it’s worth knowing this doesn’t necessarily doom your situation entirely — the specific legal consequences depend on your state’s exact rule (some states have more nuanced standards than a blanket “any payment restarts everything” rule) and the specific circumstances of your payment. Consulting a consumer law attorney at this point can help you understand exactly where you stand, rather than assuming the worst-case interpretation automatically applies without professional guidance specific to your situation.
A Common Point of Confusion: Does This Apply to Debt You’re Actively, Currently Paying On Schedule?
This restart risk specifically concerns debt that’s already gone delinquent and aged toward or past the statute of limitations — it doesn’t apply to normal, current, on-schedule payments on a loan or credit card you’re actively and appropriately managing. If you’re making regular payments on time on a current account in good standing, there’s no meaningful statute of limitations concern at all, since the debt was never delinquent or approaching that legal window in the first place. This distinction matters because the guidance in this article is specifically about old, already-delinquent debt, not a caution against ever making any payment on any debt whatsoever.
Frequently Asked Questions
Does this restart risk apply the same way to a formal, written settlement agreement as it does to an informal payment?
Generally yes, and in some ways a formal written settlement agreement can be even more clearly interpreted as a new acknowledgment of the debt, since it typically involves explicit written terms — which is exactly why getting confirmation of the debt’s time-barred status, and understanding the specific implications, before signing anything is worth doing regardless of whether you’re making an informal payment or entering a formal agreement.
If a collector tells me the debt isn’t time-barred, should I take their word for it?
Not without independent verification — collectors don’t always have accurate information about your specific state’s law or the exact original delinquency date, and in some documented cases, collectors have been found to misrepresent a debt’s time-barred status, whether through error or deliberate practice. Independently researching your state’s rule, or consulting an attorney, is a more reliable approach than relying solely on the collector’s own characterization.
Does making a payment on old debt in one state have different consequences than in another?
Yes, potentially significantly different — since statute of limitations rules and the specific actions that restart them vary meaningfully by state, the exact same payment behavior could have very different legal consequences depending on which state’s law applies to your specific debt.
If the debt is already off my credit report due to the seven-year rule, does the statute of limitations risk even matter anymore?
Yes, it can still matter — being off your credit report only affects your credit score and report visibility; it has no bearing on whether the debt remains legally enforceable through a lawsuit, which is governed entirely separately by your state’s statute of limitations, a period that can be shorter or longer than seven years depending on your specific state and debt type.
Is there ever a good reason to intentionally make a payment on time-barred debt, understanding the restart risk?
Some people choose to do this anyway, for reasons like wanting genuine peace of mind, feeling a personal moral obligation to pay debt they acknowledge owing regardless of legal enforceability, or believing (sometimes correctly, sometimes not) that resolving it will meaningfully help their credit situation. This is a legitimate personal choice, but it should be made with full understanding of the restart risk, ideally with written confirmation from the collector about their intentions going forward, rather than as an uninformed default reaction to a collection call or letter.
A State Categorization Framework (General Patterns, Not Legal Advice)
While the exact rule genuinely varies by state and you should verify your own state’s specific law, most states fall into roughly one of a few general categories worth knowing about as a starting framework:
- States where any payment clearly restarts the clock, treating a partial payment as an unambiguous new acknowledgment of the debt, restarting the full original statute of limitations period from the date of that payment.
- States with a more nuanced standard, sometimes requiring a written acknowledgment specifically (not just a payment alone) to restart the clock, or applying a shorter “renewed” period rather than a full restart in some cases.
- States where the effect depends significantly on how the payment is characterized, such as whether it was made as part of a formal settlement agreement versus a more informal, ambiguous partial payment.
Because this genuinely varies and the specific legal nuances matter, this general framework is meant only to illustrate that “any payment always restarts everything everywhere” is an oversimplification — the actual rule in your specific state could be more or less strict than that blanket assumption, which is exactly why direct verification matters rather than relying on a generic rule of thumb.
The CFPB confirms that statutes of limitations and revival rules can vary by state and debt type, which is why consumers should verify the applicable law before making decisions about old debt.
How This Interacts With Settlement Negotiations You’re Actively Pursuing
If you’ve determined a debt is genuinely old and potentially time-barred, but you still want to negotiate a settlement (perhaps because you want to resolve it for personal reasons, or because you’re unsure of your state’s exact rule and want to proceed cautiously anyway), a few practical safeguards can help protect your position:
- Negotiate the full settlement terms in writing before making any payment, rather than making a partial “good faith” payment during the negotiation process itself.
- Consider requesting the collector’s written acknowledgment that the debt is outside the statute of limitations, as part of the settlement documentation, which at least creates a record of the collector’s own position on the matter, even though this alone may not fully eliminate the legal restart risk in every state.
- If possible, have any settlement structured as a single, immediate, final payment rather than a payment plan extending over time, since a payment plan involves multiple, ongoing acknowledgments of the debt spread across a longer period, potentially compounding the restart risk with each subsequent payment.
Before entering a settlement arrangement, you can also review our guide explaining how pay-for-delete agreements work and our guide on how to negotiate a pay-for-delete with a collection agency. These are separate issues from the statute-of-limitations question, so the legal status of the debt should be considered first.
Frequently Asked Questions, Continued
Does this restart risk apply to debts owed to the government, like taxes or court fees, the same way it applies to private consumer debt?
Government debt often follows different, sometimes more favorable-to-the-government rules than standard consumer debt statute of limitations, and some government debts (certain federal tax debt, for example) may not have the same kind of enforceable time limit at all. If you’re dealing with old government debt specifically, the general private consumer debt framework in this article may not directly apply, and researching the specific rules for that particular type of government obligation is worth doing separately.
If I dispute a debt rather than pay it, does disputing itself have any restart effect?
Generally, no — formally disputing a debt as inaccurate or unverified is different from acknowledging you owe it, and disputing shouldn’t itself restart the statute of limitations clock, since a dispute is essentially the opposite of an acknowledgment; you’re contesting the debt’s validity, not affirming it.
If the account contains inaccurate information, see our guide on how to dispute credit report errors before taking action based solely on a collector’s claim.
Can an attorney help me negotiate a time-barred debt without triggering the restart risk?
Yes, this is exactly the kind of situation where an attorney’s specific knowledge of your state’s law can be valuable — they can help structure any negotiation or payment (if you choose to proceed) in a way that’s informed by the specific legal nuances of your state, potentially including specific language or documentation that manages this risk more carefully than you might on your own.
A Realistic Scenario Walking Through the Decision
Imagine a $3,000 credit card debt that went delinquent five years ago, in a state with a four-year statute of limitations for this type of debt. This means the debt is already time-barred — a collector could not successfully sue you over it at this point. A debt buyer who recently acquired the account sends a letter offering to “settle” for $600, phrased in a way that sounds like a simple, low-cost way to resolve an old obligation.
Without understanding the restart risk, paying that $600 might feel like an easy win — a small payment to make an old problem disappear. But in a state where any payment restarts the clock, that $600 payment could restart the four-year statute of limitations from scratch, meaning the collector (or a subsequent buyer) would now have a fresh four years during which they could sue you for the remaining $2,400, something they couldn’t have done the day before that payment.
A more cautious approach in this scenario: verify the debt is genuinely time-barred (through your own research or an attorney), then either decline to pay at all (understanding they can still contact you but not successfully sue), or, if you do want to resolve it, get written confirmation of the time-barred status and a clear, final settlement agreement — ideally structured in a way your attorney has reviewed — before sending any payment.
Frequently Asked Questions, Continued Further
Is there a way to pay off part of an old debt without it counting as a full “acknowledgment” under the law?
This is highly state-specific and genuinely uncertain territory in many jurisdictions — some legal theories distinguish between a payment made with an explicit reservation of rights (stating in writing that the payment isn’t intended as an acknowledgment of a legally enforceable debt) versus an unqualified payment, but whether this distinction actually protects you depends entirely on your specific state’s case law and statutes, making this exactly the kind of nuanced question worth an attorney’s direct input rather than general guidance.
Does the restart risk apply differently to debt that’s already resulted in a judgment, as opposed to debt that hasn’t been sued on at all?
Yes — a debt that’s already resulted in a court judgment operates under different rules entirely, since the judgment itself typically has its own separate enforceability period (often longer than the original debt’s statute of limitations, and in many states, renewable by the creditor), which is a different legal framework than the pre-judgment statute of limitations discussed throughout this article.
If I’m unsure whether my state’s specific rule treats my situation as restarting the clock, what’s the safest default assumption?
Given the genuine uncertainty and the potentially significant consequences, the safest default is to assume payment could restart the clock unless you’ve specifically confirmed otherwise for your state and situation — treating this as a real risk rather than a remote technicality is the more protective approach when you’re not certain.
The Bottom Line
Making a payment on old debt can genuinely backfire by restarting your state’s statute of limitations clock, converting a debt that was safely time-barred (unenforceable through a lawsuit) back into one that’s newly vulnerable to legal action. This isn’t true of all debt — it specifically concerns old, already-delinquent debt approaching or past your state’s legal window — but for debt in that category, understanding this risk before making any payment, verbal acknowledgment, or signed agreement is essential. When in doubt about whether a specific old debt falls into this risky category, verifying your state’s specific rule or consulting a consumer law attorney before taking any action is a small investment of time that can prevent a genuinely costly legal mistake.
Need Help Understanding Your Credit Report?
If an old collection account or other negative item is appearing on your credit reports, the first step is understanding exactly what is being reported and whether the information is accurate and verifiable.
Request a Credit Audit to review your credit situation and discuss potential next steps.