
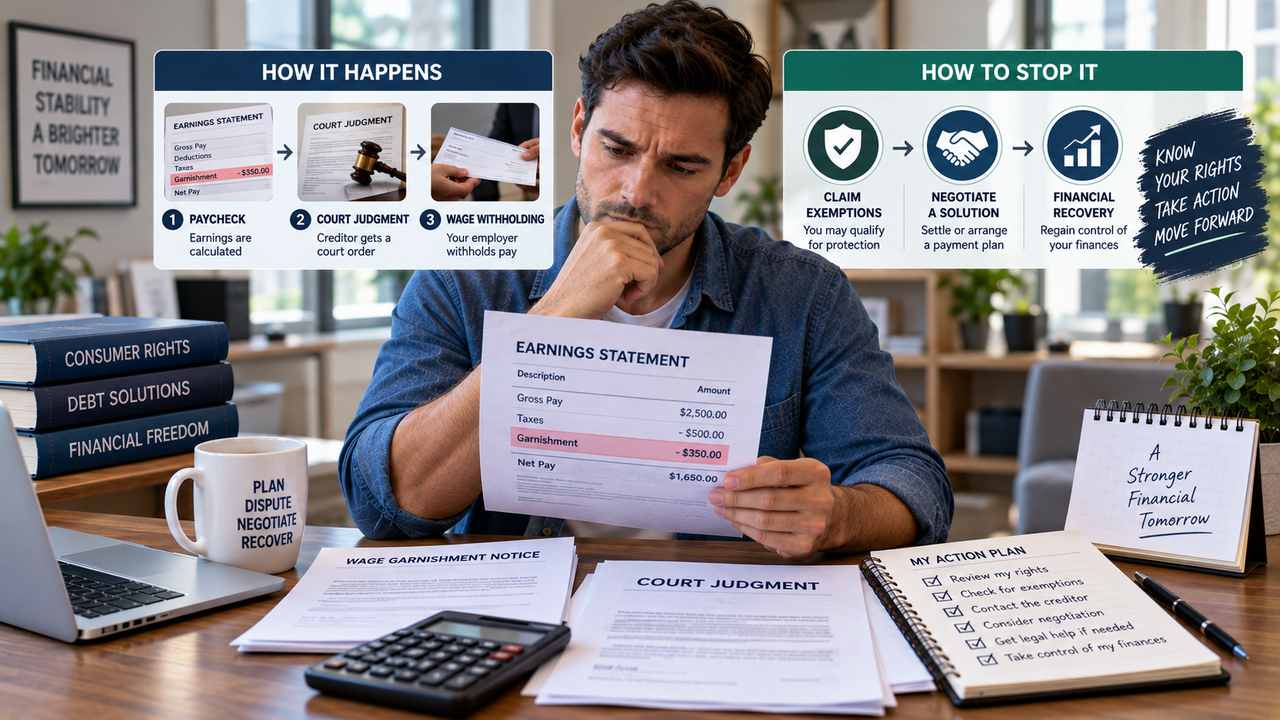
Understanding how wage garnishment works, what limits protect you, and the specific options available to stop or reduce it can make an intimidating process easier to navigate.
This guide explains how wage garnishment typically works, federal limits, protected income, exemptions, hardship claims, negotiation options, bankruptcy, and what you can do if you believe too much is being withheld from your paycheck.
What Is Wage Garnishment?
Wage garnishment is a legal process in which a portion of your paycheck is withheld by your employer and sent directly to a creditor to satisfy a debt instead of being paid to you.
Wage garnishment does not happen automatically simply because you owe money. For most private consumer debts—such as credit cards, medical bills, and personal loans—a creditor generally must first obtain a court judgment before pursuing wage garnishment.
There are important exceptions. Certain debts, including some federal student loans, unpaid taxes, and child support obligations, are governed by separate federal or state collection procedures and may allow wage withholding without the same type of court judgment required for ordinary consumer debt.
If you are already dealing with collection activity, it can also help to understand your rights when dealing with debt collectors and how to request debt validation.
How the Wage Garnishment Process Typically Works
For ordinary consumer debt, the process commonly follows several stages:
- A creditor obtains a judgment. This may happen because you lost a lawsuit or because a default judgment was entered after you failed to respond.
- The creditor seeks a garnishment order. Depending on the applicable procedure, the creditor requests an order that allows wages to be withheld and may provide your employer’s information if known.
- Your employer receives the order. Once properly served, the employer generally must comply with the applicable garnishment order.
- Wages begin to be withheld. A specified portion of future paychecks is withheld and sent toward the debt.
- You may have challenge or exemption rights. Depending on state law and the type of debt, you may receive information about claiming an exemption or challenging the garnishment.
- The garnishment continues. It generally continues until the debt and applicable interest, fees, and costs are satisfied or the garnishment is otherwise stopped or modified.
The Consumer Financial Protection Bureau explains that most creditors generally need a court judgment before garnishing wages or certain benefits, although federal and state laws establish exemptions and limitations. Learn more from the CFPB.
If you have received a lawsuit or court papers, do not assume that ignoring them will make the problem disappear. You can also read our guide on what happens if you ignore a debt collection lawsuit.
Federal Limits on Wage Garnishment
Federal law establishes limits on how much of an employee’s earnings may generally be garnished for ordinary consumer debts.
Under the Consumer Credit Protection Act (CCPA), ordinary garnishments are generally limited to the lesser of:
- 25% of disposable earnings, or
- The amount by which disposable earnings exceed 30 times the federal minimum hourly wage.
The federal minimum wage used in this calculation is currently $7.25 per hour. The U.S. Department of Labor explains that these limits apply to ordinary garnishments and that state law may provide greater protection when it results in a lower amount being garnished.
See the U.S. Department of Labor’s current wage garnishment guidance.
What Are Disposable Earnings?
The federal calculation is based on disposable earnings, rather than simply your gross paycheck.
Disposable earnings are generally the amount left after legally required deductions. These can include federal, state, and local taxes and required Social Security, Medicare, and certain other legally required deductions.
Voluntary deductions generally are not treated the same way when calculating disposable earnings under the federal garnishment limits.
Federal Garnishment Examples
For a weekly pay period, the federal baseline currently works as follows for ordinary consumer debt:
| Weekly Disposable Earnings | General Federal Maximum |
|---|---|
| $217.50 or less | No garnishment under the general CCPA formula |
| More than $217.50 but less than $290 | Amount above $217.50 |
| $290 or more | Maximum 25% |
These are federal baseline calculations for ordinary garnishments. Your specific situation may be governed by additional state or federal rules.
Different Types of Debt Have Different Garnishment Rules
Not every type of debt is treated the same way.
| Debt Type | Typical Federal Treatment | Court Judgment First? |
|---|---|---|
| Most consumer debt, such as credit cards, medical bills, and personal loans | Generally subject to the CCPA limits, including the 25%/30-times-minimum-wage formula | Generally yes |
| Federal student loans | Administrative wage garnishment can generally reach up to 15% of disposable pay, subject to applicable federal rules | Not necessarily |
| Unpaid federal taxes | Subject to separate IRS levy rules and formulas | Not necessarily |
| Child support or alimony | Higher federal limits can apply, depending on circumstances | Separate administrative/family-law procedures may apply |
The Department of Labor notes that ordinary consumer garnishments, federal debts, support obligations, and tax-related garnishments are subject to different rules. Review the Department of Labor’s detailed explanation.
How Much Can Be Garnished for Child Support?
Child support and certain alimony obligations are treated differently from ordinary consumer debt.
Under the federal CCPA, up to 50% of disposable earnings may generally be garnished when the employee is supporting another spouse or child, or up to 60% when the employee is not supporting another spouse or child. An additional 5% may apply when support payments are more than 12 weeks in arrears.
Because state rules and the specific circumstances of a support order can affect the calculation, anyone facing support-related wage withholding should review the applicable order and state requirements carefully.
What Income Is Protected From Garnishment?
Certain types of income and benefits receive protections under federal or state law. The exact protection depends on the type of debt, the source of the money, and the applicable jurisdiction.
Examples can include:
- Some Social Security benefits for ordinary private debts, subject to important exceptions.
- Certain retirement funds and accounts, depending on the account type and applicable law.
- Certain public benefits and needs-based assistance programs.
The CFPB notes that federal and state laws establish exemptions and limitations protecting wages, benefits, and money held in bank accounts from certain collection actions.
If you believe protected income is being targeted, it is important to identify the exact source of the funds and the debt involved before assuming that the garnishment is valid.
How to Stop or Reduce a Wage Garnishment
Having wages garnished does not necessarily mean that you have no options. Depending on the circumstances, several potential paths may exist.
1. Respond to the Original Lawsuit Before Garnishment Begins
The best opportunity to prevent a judgment-based wage garnishment is often before the judgment is entered.
If you receive a debt collection lawsuit, responding within the applicable deadline can give you an opportunity to raise defenses, challenge inaccurate information, negotiate a resolution, or otherwise address the claim before enforcement becomes possible.
Our guide on how to file a credit dispute can help when the underlying account information is inaccurate, while our article on the statute of limitations on debt explains why the age of a debt can matter.
2. File a Claim of Exemption
If garnishment has already begun—or is about to begin—your state may provide a process for claiming that some or all of your income is protected.
An exemption may be available because the income comes from a protected source or because the applicable law provides a hardship or other exemption.
Exemption procedures are highly dependent on state law, so check the instructions that accompany the garnishment order and consider obtaining legal assistance when necessary.
3. Claim a Financial Hardship
Some states provide a process for requesting relief when a garnishment, even if otherwise within the normal legal limits, would prevent you from meeting basic living expenses.
A hardship process may require documentation showing your:
- Income
- Housing expenses
- Utilities
- Food costs
- Transportation expenses
- Medical expenses
- Other essential living expenses
Depending on the jurisdiction, you may need to file a specific claim with the court and attend a hearing.
4. Negotiate Directly With the Creditor
A judgment or garnishment does not necessarily eliminate the possibility of negotiating.
Some creditors may be willing to consider a lump-sum settlement or structured payment arrangement instead of continuing the garnishment process.
Before making an offer, understand exactly what you owe and who currently owns or collects the debt. Our guides on debt validation and negotiating with a debt collector without getting taken advantage of can help you prepare.
If you reach an agreement, get the terms in writing before sending money.
5. Challenge the Underlying Judgment
If you believe the judgment was improperly obtained—for example, because you were not properly served, the debt was inaccurate, or you had a valid defense that you never had an opportunity to present—you may have grounds to ask the court to set aside or vacate the judgment.
This is a procedural legal issue and can be complicated. Because the requirements vary by jurisdiction, legal advice may be appropriate before attempting to challenge an existing judgment.
6. Consider Bankruptcy When Debt Is Overwhelming
For people dealing with severe, overwhelming debt, bankruptcy may be another legal option to evaluate.
Filing bankruptcy generally triggers an automatic stay that stops many collection actions, including many wage garnishments, while the bankruptcy case proceeds. Whether the underlying debt can ultimately be discharged depends on the type of debt and the applicable bankruptcy rules.
You can learn more about the differences between Chapter 7 and Chapter 13 bankruptcy before discussing your situation with a qualified bankruptcy professional.
Can a Creditor Garnish Your Wages Without Going to Court?
For most private consumer debt, a creditor generally needs a court judgment before it can garnish wages.
However, some debts operate under different systems. Federal student loans and certain tax obligations, for example, may be subject to administrative wage garnishment or levy procedures without the same type of court judgment required for an ordinary credit card debt.
The CFPB confirms that most creditors can generally garnish wages or certain benefits only after a court issues a judgment, while federal and state laws establish exceptions and protections.
Read the CFPB’s guidance on wage garnishment.
What Happens if Garnishment Causes Serious Financial Hardship?
If the amount being withheld makes it impossible for you to cover basic living expenses, investigate whether your state provides a hardship procedure.
A hardship request commonly requires evidence showing your income and essential expenses. The court may evaluate whether the garnishment should be reduced or whether another payment arrangement is appropriate under the applicable law.
Do not assume that simply telling the creditor that you are experiencing financial hardship will automatically stop the garnishment. Follow the formal process required by the court or agency handling the garnishment.
Can Your Employer Fire You Because of Wage Garnishment?
Federal law provides employment protection in connection with a single garnishment for one debt.
The Department of Labor explains that the CCPA generally prohibits an employer from discharging an employee because the employee’s earnings have been subject to garnishment for any one debt.
However, the federal protection does not generally extend in the same way to a second or subsequent debt. State law may provide broader protections.
See the Department of Labor’s garnishment and employment protections.
What Happens if You Have Multiple Garnishments?
Multiple garnishment orders can make the situation more complicated.
Different garnishments may have different priorities under state or federal law. Support obligations, tax debts, consumer judgments, and other obligations may not be treated equally.
The federal CCPA establishes limits on the amount that can generally be garnished from disposable earnings, while priority between different garnishments may be determined by other federal or state laws.
If you are facing multiple garnishments at the same time, consider getting professional legal advice so you can understand which order has priority and how the combined deductions should be calculated.
Worked Example of the Federal Garnishment Calculation
The federal limit for ordinary consumer debt uses two calculations. The lower amount generally controls.
Suppose your disposable weekly earnings are $500, and the federal minimum wage is $7.25 per hour.
Thirty times the federal minimum wage is:
30 × $7.25 = $217.50
Calculation One: 25% Method
25% of $500 is:
$500 × 25% = $125
Calculation Two: Amount Above the Threshold
Subtract $217.50 from your $500 disposable earnings:
$500 − $217.50 = $282.50
The lower of the two calculations is $125.
Therefore, under the general federal formula for an ordinary consumer debt, the maximum garnishable amount in this example would be $125 for that weekly pay period.
The Department of Labor provides additional examples showing how the federal formula works across different pay periods and circumstances.
What to Do if Your Employer Is Garnishing More Than Allowed
If you believe the amount being deducted from your paycheck exceeds the applicable legal maximum, address the issue promptly.
Start by requesting a detailed breakdown from your employer’s payroll or HR department showing how the garnishment was calculated.
Then compare the calculation with:
- The garnishment order
- Your disposable earnings
- The applicable federal limit
- Your state’s garnishment rules
- Any other garnishment orders affecting your paycheck
If a payroll calculation error is confirmed, the employer should correct the withholding going forward. Depending on the circumstances and applicable law, improperly withheld amounts may also require additional corrective action.
Wage Garnishment vs. Voluntary Wage Assignment
A formal wage garnishment should not be confused with a voluntary wage assignment.
A wage garnishment generally involves a legal process requiring an employer to withhold earnings to satisfy a debt.
A voluntary wage assignment is an agreement in which you authorize deductions from your wages to repay a debt.
The Department of Labor specifically distinguishes voluntary wage assignments from wage garnishments covered by the CCPA’s garnishment provisions.
If a creditor or lender asks you to sign a wage assignment agreement, read the terms carefully before agreeing to this payment method.
Does Bankruptcy Permanently Stop Wage Garnishment?
Bankruptcy can immediately stop many collection actions through the automatic stay, including many wage garnishments.
However, the long-term result depends on whether the underlying debt is dischargeable.
If the debt is ultimately discharged, collection on that discharged debt generally cannot continue. If the debt is not dischargeable, collection activity may potentially resume after the bankruptcy case ends, depending on the circumstances.
Bankruptcy is a significant financial and legal decision. If you are considering it, review our Chapter 7 vs. Chapter 13 guide and consider consulting a qualified bankruptcy attorney.
Can a Creditor Garnish a Joint Bank Account?
A bank account levy is different from wage garnishment.
Instead of taking money directly from your paycheck, a creditor or government agency may attempt to seize money held in a bank account through the applicable legal process.
Joint accounts can create additional complications because state law determines how ownership interests and exemptions are treated.
If you are concerned about a joint account being levied because of one account holder’s debt, review the specific state rules before assuming that all funds are protected or all funds are collectible.
What Happens When the Debt Is Fully Paid?
When a judgment debt has been fully satisfied, the garnishment should generally end through the appropriate legal process.
The creditor is typically responsible for taking the steps necessary to terminate the garnishment order, but you should not simply assume that the payroll deduction will stop automatically.
Once you believe the debt has been satisfied, follow up with your payroll department and, where appropriate, the creditor or court to confirm that the garnishment has been formally released.
Can You Negotiate a Lower Garnishment Amount?
In some circumstances, a creditor may agree to accept an alternative payment arrangement instead of continuing to collect through the maximum available garnishment.
This could involve a settlement, lump-sum payment, or structured payment plan.
Whether such an arrangement is available depends on the creditor, debt, judgment, state law, and your financial circumstances.
If you negotiate, make sure the agreement clearly states the amount you will pay, payment dates, what happens to the remaining balance, and how the garnishment will be released.
For more information, see our guide on how to negotiate with a debt collector without getting taken advantage of.
Does Wage Garnishment Appear on Your Credit Report?
The garnishment itself is generally an enforcement action rather than a separate credit-report entry.
The underlying debt, collection account, or judgment may have separate credit-reporting implications depending on what information is being reported and the applicable reporting rules.
If you believe your credit report contains inaccurate information related to the debt, you can learn how to dispute credit report errors.
You can also review your reports through AnnualCreditReport.com, the federally authorized source for free credit reports.
What If You Change Jobs?
Changing jobs does not permanently eliminate a valid garnishment.
The garnishment does not necessarily transfer to a new employer automatically. However, a creditor may take steps to identify the new employer and serve the appropriate order or notice once the new employment is discovered.
For that reason, changing jobs should not be viewed as a permanent solution to a wage garnishment.
Can Self-Employed People Have Their Wages Garnished?
Self-employed individuals can face different collection mechanics because there may not be a traditional employer available to receive a wage-garnishment order.
Depending on the circumstances, creditors may instead pursue other collection methods, including a bank account levy or other lawful enforcement mechanisms.
If you are self-employed and facing a judgment, consider reviewing the applicable collection procedures in your state.
What If You Get a Raise While Being Garnished?
Because ordinary garnishment limits are generally based on disposable earnings, an increase in income can affect the amount withheld from your paycheck.
The exact result depends on the applicable garnishment formula, pay period, and type of debt.
A higher paycheck does not automatically mean that the creditor can take any amount it wants. The applicable federal and state limits still apply.
Can You Keep Your Garnishment Private From Coworkers?
Wage garnishment necessarily involves your employer or payroll department because the employer must process the withholding.
However, coworkers generally do not need to know the details of your personal debt or garnishment.
If you have concerns about workplace privacy, you can speak directly with your HR or payroll department about how sensitive payroll information is handled.
Frequently Asked Questions About Wage Garnishment
Can a debt collector garnish my wages without ever going to court?
For most private consumer debt, a court judgment is generally required before wage garnishment can occur. Federal student loans, certain tax debts, and child support are examples of obligations governed by different collection procedures.
Can I negotiate a settlement after wage garnishment has already started?
Yes. A garnishment does not necessarily prevent you from negotiating. Depending on the creditor and circumstances, you may be able to negotiate a settlement or alternative payment arrangement.
Can I challenge a wage garnishment?
Potentially. Depending on state law and the circumstances, you may be able to claim an exemption, request hardship relief, challenge the underlying judgment, or raise another legal objection.
Can I check whether a judgment exists before my wages are garnished?
Many states provide online court-record systems that allow you to search for civil cases and judgments. Checking court records can sometimes help you identify a judgment before additional enforcement action occurs.
Does bankruptcy stop wage garnishment?
Filing bankruptcy generally triggers an automatic stay that stops many collection actions, including many wage garnishments. However, exceptions exist and the underlying debt may or may not be dischargeable.
Can a creditor garnish a joint bank account?
A bank account levy is different from wage garnishment. Whether and how much of a joint account can be levied depends heavily on state law and the ownership of the funds.
What if my employer is withholding too much?
Ask payroll or HR for the calculation and compare it with the applicable garnishment order and federal and state limits. If the amount appears incorrect, address the issue promptly with the employer and, when appropriate, the court or agency that issued the order.
The Bottom Line
Wage garnishment is a serious consequence of unresolved debt, but it does not necessarily mean that you have no options.
For most private consumer debt, a creditor generally needs a court judgment before wages can be garnished. Federal law also establishes limits on ordinary consumer-debt garnishments, while state law may provide additional protections.
If you are facing garnishment, potential options may include:
- Responding to the underlying lawsuit
- Claiming an applicable exemption
- Requesting hardship relief
- Negotiating directly with the creditor
- Challenging an improperly obtained judgment
- Considering bankruptcy when appropriate
The rules can differ substantially depending on your state and the type of debt involved. Before taking action, identify the type of debt, determine whether a judgment exists, review the garnishment order, and understand the exemptions and limits that apply to you.
If inaccurate debt or credit-report information is part of the problem, you can also review our guides on disputing credit report errors, removing collection accounts, and how to read your credit report.
Need Help Reviewing Your Credit Situation?
If wage garnishment is connected to collection accounts, inaccurate information, or other credit problems, understanding exactly what is being reported can be an important first step.
Contact Credit Repair Services to discuss your credit situation and learn about the available credit-repair options.