Category: Credit Repair

  • Does a 7-Day Late Payment Affect Your Credit Score?

    Does a 7-Day Late Payment Affect Your Credit Score?

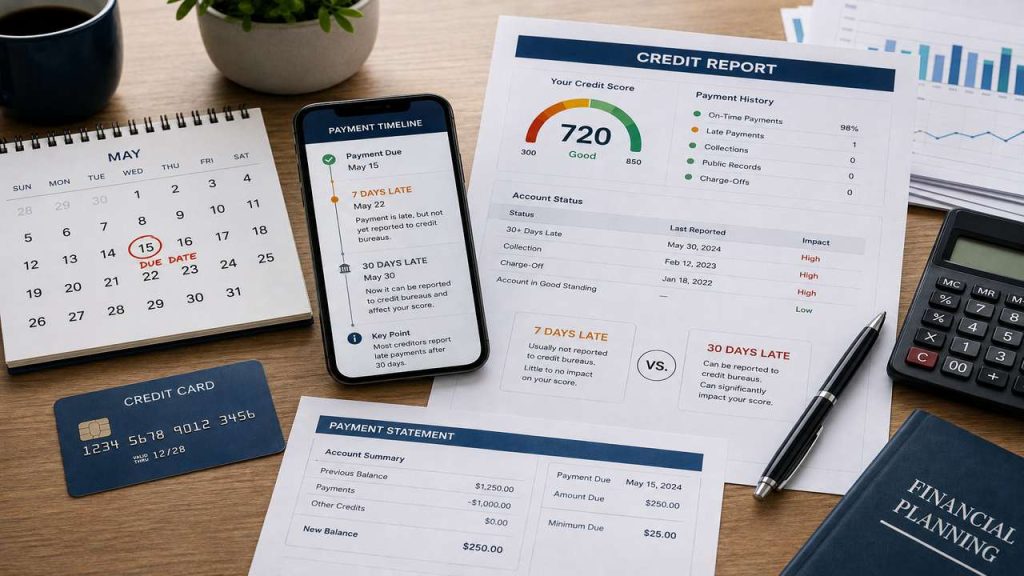
    If you’ve missed a payment due date by a week, the anxious question that follows is almost always the same: is this going to show up on my credit report and tank my score? The short answer is reassuring for most people: a payment that’s late by seven days almost never gets reported to the credit bureaus at all, and in most cases won’t affect your credit score directly. But there’s real nuance here worth understanding, because “almost never” isn’t “never,” and the fees and other consequences of a short late payment are still worth taking seriously even when your score isn’t at risk.

    This guide explains exactly how late payment reporting works, why the 30-day mark is the real threshold that matters, what does happen during that first week even if your score is unaffected, and the specific situations where a short delay can still cause a problem.

    The 30-Day Rule: Why It’s the Number That Actually Matters

    Credit card companies, mortgage servicers, auto lenders, and virtually all other creditors that report to the major credit bureaus (Equifax, Experian, and TransUnion) follow a standard convention: a payment isn’t reported as “late” to the bureaus until it’s at least 30 days past the due date. This isn’t just an industry courtesy — it’s baked into how the reporting fields in the credit bureau data systems (following the Metro 2 reporting format used industry-wide) are structured, with late payment statuses defined in 30-day increments: 30, 60, 90, 120+ days past due.

    This means a payment made 7 days late, while genuinely late from your creditor’s internal perspective, falls well short of the threshold that triggers a report to the credit bureaus. In the vast majority of cases, a payment made within that first 30-day window — even if it’s technically past the stated due date — will not appear on your credit report as a late payment at all, and will have zero effect on your credit score.

    What Actually Happens During Those First 7 Days, Even If Your Score Is Safe

    Even though your score is very likely unaffected, a payment that’s a week late isn’t consequence-free. Here’s what’s actually happening behind the scenes with most creditors during that window:

    A late fee is typically charged, often in the range of $25 to $40 for credit cards, though this varies by issuer and is subject to certain regulatory caps under the CARD Act for credit cards specifically. Other loan types (mortgages, auto loans, personal loans) have their own late fee structures defined in your original loan agreement.

    Your interest rate could be affected on some credit cards. Many credit card agreements include an “penalty APR” clause that can be triggered once a payment is 60 days late (again, past the 30-day reporting threshold, but worth knowing the escalation path), so a single 7-day late payment alone typically won’t trigger this, but it’s a reminder of what’s at stake if a short delay turns into a longer one.

    Your grace period for new purchases may be affected. If you’re carrying a balance and miss your due date, even briefly, some card issuers will begin charging interest on new purchases immediately rather than extending the usual grace period, until you’ve paid your balance in full again.

    Internal account flags may be set. Even if nothing reaches the credit bureaus, your creditor’s internal system now shows a late payment on your account history with them specifically, which they can reference for their own purposes — such as evaluating you for a credit limit increase, a retention offer, or future account decisions — even though this internal note isn’t visible to other lenders or reflected in your credit score.

    When a 7-Day Late Payment CAN Still Cause a Problem

    While the 30-day reporting threshold covers the vast majority of situations, there are a few specific scenarios where a short delay can still matter:

    If it happens repeatedly

    A pattern of consistently paying a few days late, even if each individual instance stays under the 30-day reporting threshold, can eventually lead a creditor to take other actions — closing your account for risk management reasons, declining to extend a credit limit increase, or, in some subscription or utility contexts, canceling the service — even without any single late payment ever reaching your credit report.

    If your specific due date and the 30-day window overlap in an unusual way

    In rare cases involving certain loan servicers or unusual billing cycles, the exact timing of when a “30 days late” status gets calculated and reported can vary slightly. If you’re right at the edge of that window due to a payment processing delay, a mailed check, or a bank transfer that took longer than expected, it’s worth confirming directly with your creditor exactly when your account will be considered officially delinquent for reporting purposes, rather than assuming the standard convention applies exactly.

    If it’s a rent payment, and your landlord uses rent-reporting

    Some landlords and property managers use services that report rent payments to the credit bureaus, and these services don’t always follow the same 30-day convention as traditional lenders — some report payment timeliness on a more granular basis. If your lease specifies rent reporting, it’s worth checking the specific service’s policy on late payment reporting thresholds.

    If your account was already delinquent from a previous missed payment

    If a 7-day-late payment is actually the second consecutive missed payment on an account where the first one was never fully caught up, the cumulative delinquency could already be approaching or past the 30-day mark from the original missed due date, in which case the “7 days late” framing understates how far behind the account actually is.

    Certain non-traditional or specialty lenders may report differently

    Some smaller lenders, certain buy-now-pay-later services, or specialty financing products don’t always follow the standard Metro 2 reporting conventions used by major banks and credit unions, and some report payment status on a more frequent or different schedule. If you’re using a newer or less traditional lending product, it’s worth directly confirming their specific reporting practices rather than assuming the standard 30-day rule applies.

    What to Do If You’re About to Be a Few Days Late

    Contact your creditor before the due date if you already know you’ll be late. Many creditors, especially for a customer with an otherwise good payment history, will work with you — extending the due date slightly, waiving the late fee, or at minimum confirming exactly when a payment would need to post to avoid any issue.

    Make the payment as soon as possible, even if it’s already past the due date. The sooner you pay, the sooner any grace period effects or reporting risk resolve, and this also minimizes any additional late fees or interest that might accrue with additional delay.

    Set up autopay for at least the minimum payment going forward, even if you prefer to manually pay in full each month. This creates a safety net so that a forgotten manual payment doesn’t accidentally cross the 30-day threshold due to being overlooked for weeks rather than days.

    Double check whether your specific creditor’s grace period differs from the standard. While 30 days is the near-universal convention for credit bureau reporting, individual account-level grace periods (for late fees, interest, or promotional rate forfeiture) can be shorter, and it’s worth knowing your specific account’s terms, usually found in your cardholder agreement or loan documents.

    If You Discover a 7-Day-Late Payment Was Incorrectly Reported

    Although rare, reporting errors do happen — a creditor’s system glitch, a misapplied payment, or an administrative mistake can occasionally result in a payment being reported as late to the credit bureaus even when it was actually made within the standard grace window. If you find what you believe is an inaccurately reported late payment on your credit report:

    Gather your proof first

    Bank statements, payment confirmations, or screenshots showing the exact date and time your payment was made or posted are essential for a successful dispute.

    Contact the creditor directly before filing a formal dispute

    Many disputes can be resolved faster by calling the creditor’s customer service line directly, explaining the discrepancy, and asking them to correct their reporting to the bureaus — this is often faster than the formal bureau dispute process, though it doesn’t replace your right to file a formal dispute if the creditor doesn’t cooperate.

    File a formal dispute with the credit bureau if needed

    If the creditor won’t correct an error you can document, file a dispute directly with whichever bureau (or bureaus) shows the incorrect information, including your supporting documentation. Under the FCRA, the bureau is required to investigate, typically within 30 days.

    How to Think About the Distinction Between “Late” and “Reported Late”

    It’s worth internalizing this distinction clearly, since it resolves a lot of unnecessary anxiety: being “late” in the everyday sense — missing your stated due date by any amount of time — has real consequences (fees, interest, and potentially account-level flags with that specific creditor), but it is meaningfully different from being “reported late” to the credit bureaus, which is the thing that actually affects your credit score and appears on your report for other lenders to see. A short delay puts you in the first category without typically crossing into the second, but treating the two as identical leads either to unnecessary panic over a minor delay, or, in the opposite direction, to complacency about repeatedly paying just a few days late without recognizing the compounding fee costs and creditor-relationship risk that come with it, even absent any credit score impact.

    Frequently Asked Questions

    Will a 7-day late payment show up if I check my credit report immediately?

    No, assuming your creditor follows the standard 30-day reporting convention, a payment made within that window — even after the due date — won’t generate a late payment entry on your report at all, regardless of when you check.

    Does this apply to mortgages the same way it applies to credit cards?

    Generally yes, mortgage servicers also follow the standard 30-day reporting convention for credit bureau purposes, though mortgage late fees and specific account-level consequences (which can include escalating notices well before the 30-day mark) are governed by your specific loan agreement and can differ from credit card terms.

    If I’m late by 7 days every single month, will that eventually catch up with my score?

    Not through credit bureau reporting directly, as long as each individual instance stays under 30 days. However, a consistent pattern like this carries real risk of other consequences — a creditor closing your account, declining future credit limit increases, or in some cases reporting the account differently if they determine the pattern represents a heightened risk, so it’s worth addressing the underlying cause of consistently paying late even if your score isn’t directly affected yet.

    What’s the safest number of days to consider a hard deadline?

    Given the standard is 30 days, but grace periods, fees, and account-specific terms all vary, a reasonable personal rule of thumb is to treat any missed due date as requiring payment within a few days at most, both to avoid unnecessary fees and interest, and to build in a safety margin against any variation in how a specific creditor calculates and reports delinquency.

    Can a 7-day late payment affect a mortgage application I’m currently in the middle of?

    If it doesn’t get reported to the credit bureaus, it generally won’t show up on a credit report pulled during underwriting. However, some mortgage lenders request recent bank statements as part of underwriting, and a pattern of late payments or overdrafts visible in those statements (separate from your credit report) could still raise questions during the underwriting process, even without a formal late payment report.

    How Different Types of Accounts Handle a Short Delay

    Account type Credit bureau reporting threshold Late fee risk in first 7 days Other early consequences
    Credit card 30 days (standard) High — often charged after just 1 day late Grace period on new purchases may be lost
    Mortgage 30 days (standard) Varies by servicer, often after a short window (commonly 10-15 days per loan terms) Servicer may send early notices well before 30 days
    Auto loan 30 days (standard) Varies by lender, sometimes after just a few days Some loans allow repossession proceedings to begin surprisingly early per contract terms, even without credit reporting yet
    Personal loan 30 days (standard) Varies by lender agreement Some online lenders use non-standard reporting schedules — worth confirming directly
    Rent (if reported) Varies by rent-reporting service Governed by lease terms and state/local law Some services report more granularly than the standard 30-day convention
    Student loans (federal) 90 days for federal loans specifically Grace period varies by loan type Federal loans have a notably longer reporting grace period than most other credit types

    This table highlights something important: federal student loans are a notable exception to the general 30-day rule, with a longer 90-day window before being reported as delinquent to the credit bureaus. This doesn’t mean a short delay on a federal student loan is risk-free — interest continues accruing and other consequences can apply — but it does mean the credit-reporting risk specifically is even more limited than with most other account types.

    Understanding What “Day One” of Lateness Actually Means

    A subtle point that trips people up: your due date itself is not a late day. If your payment is due on the 15th, a payment made on the 15th is on time, and a payment made on the 16th is one day late — not the “first day of your grace period” in some interpretations, but genuinely one day past due from your creditor’s perspective, even though (as covered above) it won’t be reported to the credit bureaus until it reaches 30 days past that due date. Some people mistakenly believe there’s an automatic few-day cushion built into every due date; while some individual account terms do include an explicit grace period for fees specifically (common with mortgages, for example, which often have a 10-to-15-day grace period before a late fee is charged, separate from the 30-day credit bureau threshold), this isn’t universal, and it’s worth checking your specific account terms rather than assuming a cushion exists.

    A Practical Autopay Setup Guide to Prevent This Entirely

    Given how much of the risk here comes down to timing rather than an inability to pay, setting up a reliable autopay system is one of the highest-value, lowest-effort things you can do. A few specifics worth getting right:

    • Choose “pay in full” rather than “minimum payment only” if your cash flow reliably supports it. This avoids carrying a balance and paying interest, while still providing the safety net against a missed due date.
    • If your income is variable, consider autopay for the minimum payment only, with manual additional payments when you have extra funds. This ensures you never technically miss a due date (avoiding the fee and reporting risk entirely) while giving you flexibility on the rest.
    • Verify your payment method on file is current, especially before it expires. An expired card or a closed bank account linked to autopay is one of the most common reasons a payment silently fails despite autopay being “set up,” precisely the kind of surprise that can turn into an unintentional multi-week delay if you’re not checking your statements regularly.
    • Set a backup calendar reminder a few days before each due date anyway. Autopay failures do happen — due to a bank processing delay, an issuer’s system error, or an account status change — and a simple manual check a few days early catches this before it becomes a genuine problem.
    • Consider aligning due dates across multiple accounts to a schedule that matches your pay cycle. Many creditors will let you request a specific due date; aligning several bills to fall shortly after payday reduces the chance of a payment failing due to insufficient funds at the moment it’s scheduled.

    What a Short Late Payment Does to Your Relationship With a Creditor, Beyond the Score

    Even when your credit score is completely unaffected, it’s worth remembering that your creditor’s internal records are a separate thing entirely, and they do track your payment behavior over time for their own purposes. A card issuer deciding whether to offer you a credit limit increase, a lower interest rate, or a retention bonus when you consider closing an account will often reference their own internal history with you — which does include every late payment, regardless of whether it was ever reported to the bureaus. This is a good reason to treat on-time payment as a broader habit worth maintaining consistently, not simply a box to check only when the credit-bureau reporting threshold is at stake.

    does-a-7-day-late-payment-affect-credit-score-under-100kb

    Frequently Asked Questions, Continued

    Does a 7-day late payment affect my ability to get a new credit card while it’s outstanding?

    If it isn’t reported to the credit bureaus (the typical case), it won’t appear on the credit report a new card issuer would review, so it generally wouldn’t affect a new application. If the payment is still outstanding at the time you apply, though, it’s better practice to resolve it first regardless, both for the late fee and to keep your account in good standing with your existing creditor.

    If I pay 7 days late but the creditor charges a late fee, does that fee itself ever get reported to credit bureaus?

    No, fees themselves aren’t reported as a line item to credit bureaus. What matters for reporting purposes is your payment status (on time vs. a specific number of days past due), not fees assessed on the account.

    Can a creditor choose to report a late payment sooner than 30 days if they want to?

    While the 30-day convention is a strong industry norm tied to the standardized Metro 2 reporting format, technically nothing legally requires every creditor to use exactly that threshold. In practice, virtually all major banks, credit unions, and mainstream lenders follow it, but it’s worth being aware that a small number of alternative or non-traditional lenders could theoretically report differently, which is why checking your specific creditor’s stated policy is a reasonable extra precaution if you’re ever genuinely unsure.

    Is there a difference between “late” and “past due” on my account statement?

    These terms are often used interchangeably by creditors and generally mean the same thing: a payment hasn’t been received by the stated due date. Neither term on its own indicates whether the account has crossed the 30-day credit-bureau reporting threshold — you’d need to check the specific number of days past due to know that.

    Why This Reporting Standard Exists in the First Place

    It’s worth understanding the reasoning behind the 30-day convention, since it isn’t arbitrary. Credit reporting exists to help lenders assess long-term repayment reliability, not to penalize every minor timing slip a person makes in daily financial life. Bills get missed for all kinds of ordinary reasons — a bank holiday delaying a transfer, a forgotten due date during a busy week, a temporary mail delay for a paper check — that have little to do with someone’s actual ability or willingness to repay debt. A reporting standard that flagged every single-day delay would generate enormous noise in the credit system and would punish minor administrative slip-ups as harshly as genuine payment difficulty, making credit scores far less useful as a signal of real risk.

    The 30-day threshold represents an industry-wide judgment that a delay of less than a month is common enough, and generally recoverable enough, that it doesn’t yet indicate meaningful credit risk on its own. Once a payment crosses that threshold, it starts to represent a more genuine signal — the person either can’t currently pay, is actively avoiding payment, or has lost track of the obligation entirely — which is the kind of information a future lender genuinely benefits from knowing about.

    A Note on Buy Now, Pay Later Services

    Buy Now, Pay Later (BNPL) services like Klarna, Afterpay, and Affirm have grown enormously in recent years, and their credit reporting practices are still evolving and vary significantly between providers. Some BNPL providers don’t report to the major credit bureaus at all under normal circumstances, only doing so if an account becomes seriously delinquent or is sent to collections. Others have begun reporting more routinely, including for on-time payments, as the industry moves toward more standardized practices. If you use these services regularly, it’s worth checking the specific provider’s current reporting policy directly, since the general 30-day guidance for traditional credit doesn’t necessarily map cleanly onto every BNPL provider’s practices, and this is an area where policies have been changing faster than most other parts of consumer credit reporting.

    Frequently Asked Questions, Continued Further

    Does my bank see a late payment on my checking account the same way a credit late payment works?

    No — an overdraft or low balance on a checking account is an entirely separate matter from credit reporting and doesn’t follow the same 30-day convention. Overdrafts are typically tracked through a different system (sometimes ChexSystems, used for banking history rather than credit history) and can affect your ability to open new bank accounts, separate from your credit score.

    If I’m 7 days late on one card but current on all my others, does that isolated instance affect my overall creditworthiness in any lender’s eyes?

    Since it’s very unlikely to be reported to the credit bureaus, it generally won’t be visible to other lenders reviewing your credit report. The one exception is if that specific creditor is later asked directly by another party (which is uncommon) or if you disclose it yourself during an application process that asks about your payment history in detail.

    Can I ask my creditor to simply not report this if it does end up crossing 30 days?

    In rare cases, particularly for a longtime customer with an excellent payment history and a clearly explainable one-time circumstance (a documented medical emergency, for example), some creditors will agree to a “goodwill” non-reporting or later removal of an isolated late payment, though this is entirely at their discretion and not something you’re legally entitled to request.

    The Bottom Line

    A payment that’s seven days late almost always falls safely under the 30-day threshold that triggers credit bureau reporting, meaning your credit score is very unlikely to be directly affected. That said, late fees, potential interest rate consequences, and the risk of an escalating pattern with your creditor are all real considerations even when your score is untouched. The safest approach is simple: treat every due date as a genuine deadline, set up autopay as a backstop, and if you do end up a few days late, pay as soon as possible and don’t hesitate to contact your creditor proactively if you know a delay is coming.

    Get a Credit Audit

    If you’re dealing with a late payment or want to review your credit reports for inaccurate or negative information, you can request a credit audit or quote.

    Request a Credit Audit or Quote

  • Why Did My Credit Score Drop 20 Points? Common Causes Explained

    Why Did My Credit Score Drop 20 Points? Common Causes Explained

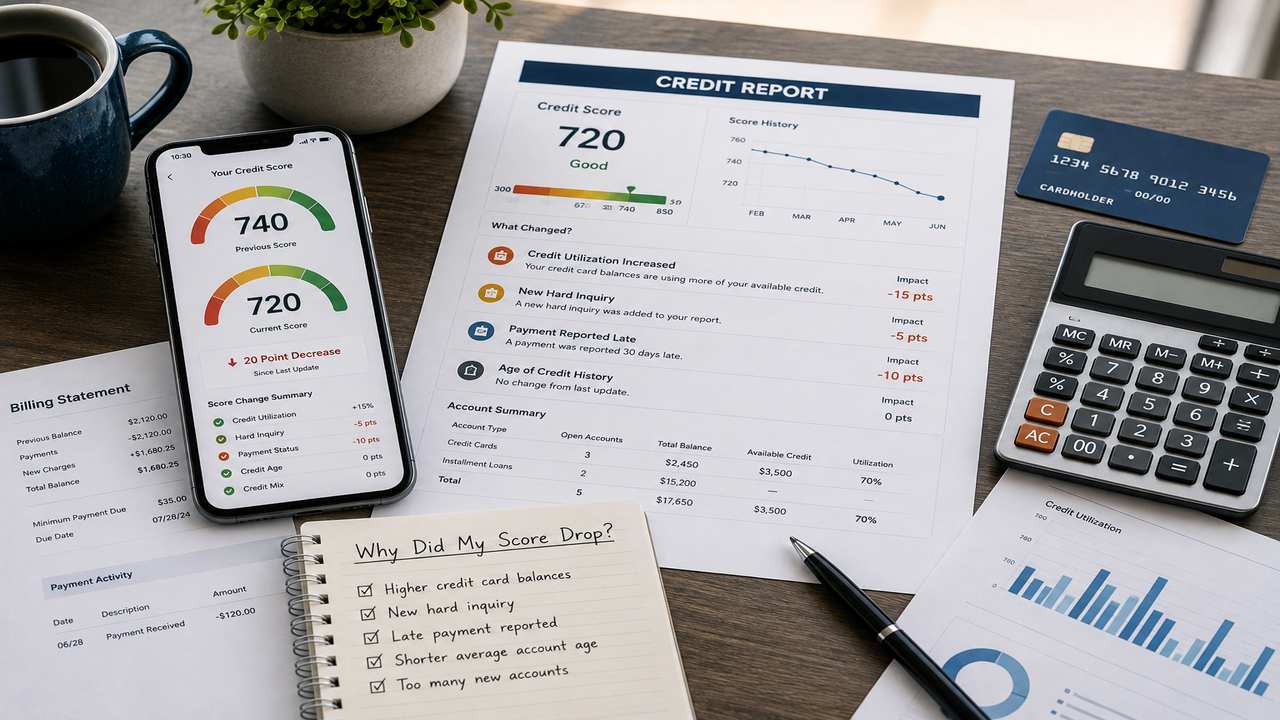
    Opening a credit monitoring app and seeing your score has dropped by 20 points, seemingly out of nowhere, is unsettling. Twenty points is enough to notice, enough to potentially move you into a different lending tier, and often confusing enough that you can’t immediately connect it to anything you remember doing. The good news is that a 20-point drop is almost always explainable once you know where to look, and it’s rarely the sign of a catastrophic problem.

    This guide walks through the most common causes of a moderate score drop like this, how to identify which one applies to you, and what to do about it.

    Start With Your Credit Report, Not Just Your Score

    Your score is a single number, but it’s calculated from the detailed information in your credit report. Before guessing at causes, pull your current reports from all three bureaus (free at AnnualCreditReport.com) and compare them to what you remember from before the drop. Most monitoring apps and services also show you the specific factors contributing to a recent score change, sometimes explicitly, which is the fastest way to identify the cause without guesswork.

    The Most Common Causes of a 20-Point Drop

    A New Hard Inquiry

    Applying for any new credit — a credit card, an auto loan, a personal loan, sometimes even a new phone plan or apartment application that includes a credit check — generates a “hard inquiry” on your report. A single hard inquiry typically causes a drop of somewhere in the range of 5 to 10 points, though it can be more for someone with a shorter credit history or fewer total accounts, where each new data point carries relatively more weight.

    If you recently applied for anything requiring a credit check, this is the first and most likely explanation to check. Multiple applications close together compound this effect, though many scoring models group similar inquiries (like rate shopping for a mortgage or auto loan within a short window) as a single inquiry for scoring purposes.

    A Increase in Credit Utilization

    If your reported balance on one or more cards went up relative to your limit — even due to normal spending rather than a new charge-off or missed payment — your utilization ratio increases, and this is one of the more common drivers of a moderate score change. Remember that your card issuer reports your balance on your statement closing date, not in real time, so a temporarily higher balance from a large purchase, holiday spending, or a big one-time expense can show up on your report even if you plan to pay it off in full before interest accrues.

    A jump from, say, 10% utilization to 40% utilization on a card can easily account for a drop in this range, especially if that card carries a meaningful portion of your total available credit.

    A Late Payment

    Even a single payment reported 30 days late can cause a drop in this range or larger, particularly if your credit was otherwise in very good standing beforehand (counterintuitively, a strong existing credit history tends to make each new negative mark relatively more impactful, since the scoring model has less “room” to reassess a previously excellent payment record). Double-check your accounts for any payment that might have been processed late, even by a day or two past the grace period, due to a forgotten autopay, an expired card on file, or a bank holiday delaying a transfer.

    An Account Was Closed

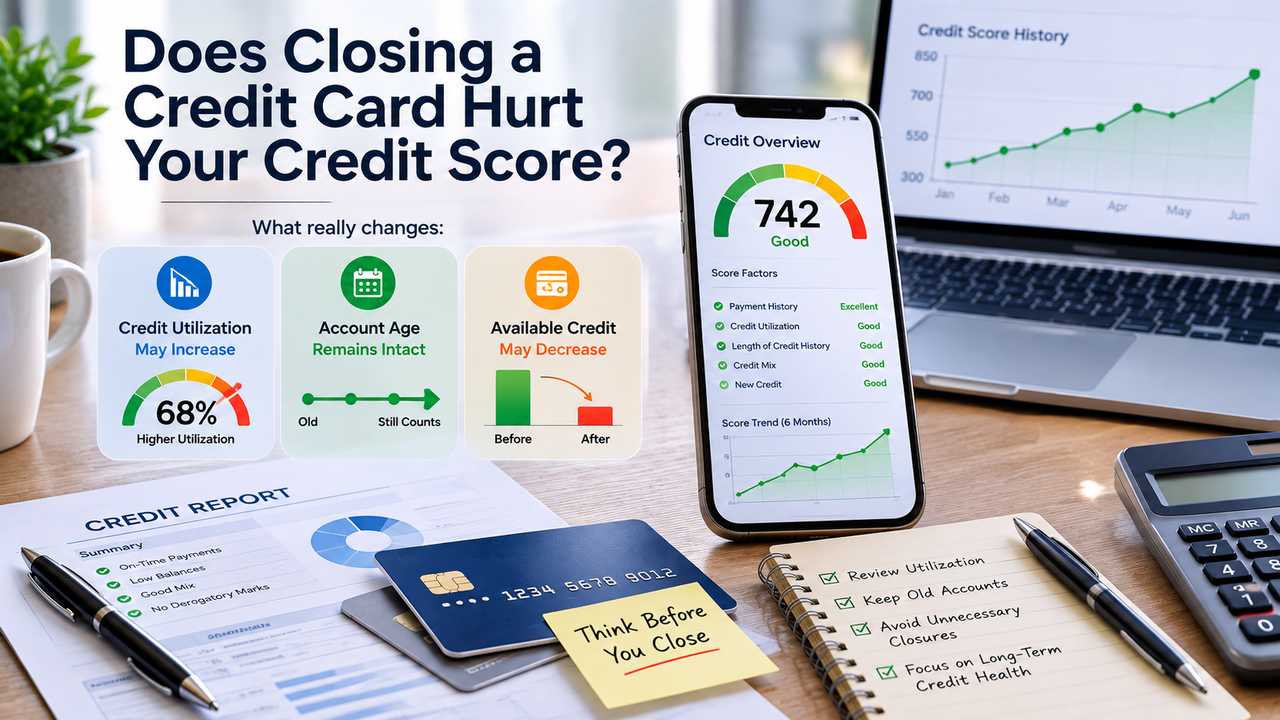
    Closing a credit card — whether you did it deliberately or the issuer closed it for inactivity — can affect your score in two ways: it reduces your total available credit, which raises your overall utilization ratio even if your spending hasn’t changed, and if it was one of your older accounts, it can eventually reduce your average account age once it fully drops off your report (closed accounts in good standing typically remain on your report and continue counting toward your history for up to ten years, but they’ll eventually age out, and in the meantime the loss of available credit is the more immediate effect).

    A Change in Your Credit Mix

    If you paid off and closed your only installment loan (like a car loan reaching its final payment), your remaining credit mix skews more heavily toward revolving credit alone, which can have a modest negative effect on the “credit mix” component of your score, even though paying off a loan is, in every other sense, a positive financial event.

    An Authorized User Account Changed

    If you were an authorized user on someone else’s credit card and that person’s account status changed — they missed a payment, their utilization spiked, or they closed the card — it can affect your score too, since authorized-user accounts contribute to your file the same way your own accounts do. This is easy to overlook because the change wasn’t something you did yourself.

    A New Collection or Public Record

    A medical bill, unpaid parking ticket sent to collections, gym membership dispute, or library fine (yes, some of these genuinely do get reported) that you may not have even known about can appear as a new negative item and cause a noticeable drop. These are often small-dollar items that catch people completely off guard because they never received a bill or didn’t realize an old dispute had escalated.

    Normal Scoring Model Fluctuation

    Sometimes a score genuinely shifts by a small amount for reasons that aren’t tied to any single dramatic event — simply the natural month-to-month recalculation as your account ages, balances shift slightly, and the relative weighting of different factors in the algorithm responds to the overall combination of your file. This is less common as an explanation for a full 20-point move (which usually does have an identifiable cause) but can be a contributing factor alongside one of the more specific reasons above.

    How to Diagnose Your Specific Cause

    Compare report dates. Pull the date of your last known good score and the date of the drop, then look specifically at what changed on your credit report in that window: new accounts, new inquiries, updated balances, or new negative marks.

    Check each account’s reported balance against what you remember. A surprising number of moderate score drops trace back to one card’s balance being higher than expected on its specific statement date, even if your overall spending habits haven’t meaningfully changed.

    Look for anything genuinely unfamiliar. A new inquiry you don’t recognize, a new account you didn’t open, or a collection for a debt you’ve never heard of could indicate identity theft or an error, both of which require a formal dispute rather than simply waiting for the score to recover on its own.

    Check whether an authorized-user account changed. If applicable, ask the primary cardholder whether anything changed on their end recently.

    What to Do Once You’ve Identified the Cause

    If it’s a new hard inquiry: No action needed beyond patience. The impact fades within a few months and disappears from scoring calculations entirely after 12 months, even though the inquiry itself remains visible on your report for 24 months.

    If it’s increased utilization from normal spending: Pay down the balance, and consider paying before your statement closing date going forward if you want tighter control over what gets reported each month. The score typically recovers within one to two billing cycles once the balance is reduced.

    If it’s a late payment: Bring the account current immediately if it isn’t already, and consider calling the creditor to request a “goodwill adjustment” — some creditors, especially for a first-time late payment on an account with an otherwise clean history, will agree to remove the late mark as a customer service gesture, though this isn’t guaranteed and isn’t a right you can demand.

    If it’s a closed account: There’s not much to reverse after the fact, but going forward, consider keeping no-annual-fee cards open even if unused, specifically to preserve your available credit and account age.

    If it’s an unfamiliar item that shouldn’t be there: File a dispute with the credit bureau reporting it, and if it appears to be identity theft, place a fraud alert or credit freeze and file a report with the FTC at IdentityTheft.gov.

    why-did-my-credit-score-drop-20-points-under-100kb

    When a 20-Point Drop Is Actually Nothing to Worry About

    It’s worth putting this in perspective: a 20-point fluctuation, especially one tied to routine causes like a single hard inquiry or a temporarily elevated statement balance, is a completely normal part of how credit scores work, not a sign your credit is in trouble. Scores move up and down in small to moderate increments constantly as your file updates each month. The number that matters most for actual lending decisions is your score trend over months and years, not any single month’s fluctuation, and most lenders also look at the underlying report details, not just the headline number, when evaluating an application.

    When It’s Worth Digging Deeper

    If you’ve ruled out all the common explanations above and genuinely can’t identify a cause, or if the drop is part of a larger, ongoing decline rather than an isolated one-time event, it’s worth a closer, line-by-line review of your full credit report from all three bureaus, since scores can sometimes differ between bureaus if only one of them received updated (or inaccurate) information. Persistent unexplained drops, especially across multiple months, are also a reasonable trigger to consider a credit freeze or monitoring service if you haven’t already, simply as a precaution against undetected fraud.

    Frequently Asked Questions

    How long does it take for a score to recover after a 20-point drop from a hard inquiry?

    Typically within a few months, as the inquiry’s impact diminishes with time even before it fully drops off your report at 24 months and stops counting toward scoring entirely after 12 months.

    Can checking my own credit score cause a 20-point drop?

    No. Checking your own score or report is always a soft inquiry and never affects your score, regardless of how often you check.

    Why did my score drop even though I didn’t do anything unusual that month?

    The most common overlooked cause is a higher-than-usual statement balance being reported on a normal billing cycle, an authorized-user account changing, or a small collection account you weren’t aware of. A careful review of your full report, not just the score, usually reveals the specific cause.

    Is a 20-point drop the same across all three bureaus?

    Not necessarily. Since Equifax, Experian, and TransUnion don’t always receive identical information from every creditor at the same time, your score can differ between them, and a drop reported by one monitoring service pulling from a single bureau might not exactly match what you’d see from a different service.

    Should I be worried about a 20-point drop before applying for a mortgage?

    It’s worth understanding the cause before applying, since even a modest score difference can occasionally shift you into a different mortgage rate tier depending on where you fall relative to lender thresholds. If the cause is a routine hard inquiry or a temporarily elevated balance, allowing a couple of months for it to settle before applying, if your timeline allows, is a reasonable precaution.

    Why FICO and VantageScore Can React Differently to the Same Event

    If you’re tracking your score through more than one app or service, you may notice they don’t always move by the same amount, or even in the same direction, after the same event. This is because FICO and VantageScore — the two major scoring model families — weight certain factors slightly differently, and even different versions within each family (FICO 8 versus FICO 9 versus FICO 10, for example) handle specific situations differently.

    A notable example: older FICO models treat all collection accounts similarly regardless of amount, while newer FICO models and VantageScore 3.0/4.0 ignore paid collections and treat small-dollar or medical collections more leniently. Similarly, how heavily a single new hard inquiry is weighted can vary slightly between model versions and depending on the overall thickness of your file. This is why two people can experience the exact same event — say, opening one new credit card — and see meaningfully different point drops, and why your own score might show a 12-point drop on one app and a 25-point drop on another for what appears to be the same underlying change.

    Rather than treating any single app’s number as the absolute truth, it’s more useful to watch the general trend across your monitoring tools and to understand the underlying reason for a change, since the reason matters more than the exact point value assigned to it by any one model.

    A Month-by-Month Example Scenario

    To illustrate how a 20-point drop can quietly build from more than one small factor at once, consider this composite (illustrative, not calculated from any specific real scoring formula) scenario:

    Early in the month

    You apply for a new rewards credit card to take advantage of a sign-up bonus. This generates a hard inquiry, contributing an estimated 6-point dip.

    Mid-month

    You put a larger-than-usual purchase — a plane ticket for an upcoming trip — on an existing card, planning to pay it off in full when the bill arrives. Your statement closes before you’ve paid it down, reporting a utilization jump on that card from around 8% to 35%, contributing an estimated 10-point dip.

    Later in the month

    A subscription service you forgot about attempts to charge an expired card on file, the payment fails, and after a couple of follow-up attempts, it gets reported 30 days past due before you notice and resolve it, contributing an estimated additional dip on top of the other two factors.

    Individually, none of these would necessarily be alarming, and none represents a change in your actual overall financial reliability. Together, though, they can combine into a drop in the 20-point range within a single reporting cycle, which is why a moderate drop often has more than one small contributing cause rather than a single dramatic one.

    Things That Do NOT Directly Affect Your Score (Common Misconceptions)

    Your income.

    Income isn’t a factor in credit scoring at all — it’s not reported to the credit bureaus by employers or otherwise, though lenders may separately ask for it during a loan application.

    Your savings account balance.

    Bank account balances aren’t part of your credit file or score calculation.

    Checking your own credit report or score.

    As mentioned above, this is always a soft inquiry with zero score impact, no matter how often you do it.

    Marital status or a spouse’s credit history, unless you have joint accounts together or you cosign for something specific.

    Getting married doesn’t merge two individual credit files into one.

    Being denied credit.

    The denial itself doesn’t affect your score; only the hard inquiry generated by the application does, and that impact is small and temporary regardless of the outcome of the application.

    Age, employment history, or where you live.

    None of these are part of the scoring formula, though some lenders do independently consider factors like employment and income during underwriting, separate from the credit score itself.

    A Prevention Checklist to Avoid Future Unexplained Drops

    1. Set up balance alerts with your card issuer so you’re notified if a balance crosses a threshold you set, helping you catch a utilization spike before your statement closes.
    2. Keep at least one payment method’s expiration date updated everywhere it’s saved, particularly for recurring subscriptions, to avoid an accidental missed payment from an expired card.
    3. Space out credit applications rather than applying for several products in a short window, unless you’re specifically rate-shopping for a mortgage or auto loan, where similar inquiries within a short period are often grouped together by scoring models.
    4. Review your full credit report, not just your score, every few months, since the report shows the specific line items that drive any score change, while the score alone doesn’t explain itself.
    5. Set a calendar reminder to check accounts you rarely use, such as a card you keep open but don’t actively use, to catch any unexpected activity, fees, or issuer-initiated changes.
    6. Consider a credit freeze if you’re not planning to apply for new credit soon, which prevents new accounts from being opened in your name without your explicit unlocking of the freeze first.

    Frequently Asked Questions, Continued

    Can a credit limit decrease from my card issuer cause a score drop even if I didn’t do anything?

    Yes. If your issuer reduces your credit limit — sometimes done unilaterally due to their own risk assessment, unrelated to anything you did — your utilization ratio increases immediately even with an unchanged balance, which can cause a moderate score drop you had no direct control over.

    Does paying my credit card multiple times a month help prevent these drops?

    It can help, particularly if you make a payment before your statement closing date to ensure a lower balance gets reported that cycle, rather than waiting until the due date, by which point the higher balance may have already been reported.

    Why did my score drop even though my report shows no new negative items?

    Sometimes a shift in utilization or a hard inquiry is the entire explanation and doesn’t require any “negative item” in the traditional sense — an inquiry and a balance increase are both neutral factual changes, not derogatory marks, but they still influence the score calculation.

    Is there a way to see exactly which factor caused my score change?

    Many free credit monitoring services and card issuer apps provide a breakdown of the top factors influencing your current score, and some explicitly flag month-over-month changes with a stated reason. This is usually the fastest way to pinpoint a cause without manually comparing full reports.

    How Lenders Interpret a Recent Score Drop

    It’s natural to worry that a lender reviewing your application will see a recent drop and treat it as a red flag on its own. In practice, most lenders only see your score at the moment they pull it — they generally don’t see a graph of your recent history the way you might in a monitoring app, unless they specifically request a more detailed report. What they do see, if they review your full report rather than just the score, is the same underlying detail you’d see: a new inquiry, an elevated balance, or a payment status.

    A single new inquiry from a recent application is a completely normal and expected part of a credit file and isn’t treated as suspicious on its own — lenders extend credit to millions of people who have applied for other things recently. An elevated utilization ratio is more likely to be weighed as a genuine risk factor if you’re applying for new credit at the same time, since it can suggest reliance on available credit, which is worth being mindful of if you’re planning a major application in the near future. A late payment is the one factor genuinely worth proactively addressing (through a goodwill letter, or simply time and a clean record afterward) before applying for something significant, since it’s viewed as a more direct signal of payment reliability.

    Hard Inquiries vs. Soft Inquiries: A Closer Look

    Because hard inquiries come up so often as an explanation for a moderate score drop, it’s worth understanding exactly what triggers one versus what doesn’t, since the distinction isn’t always obvious from a consumer’s perspective.

    Triggers a hard inquiry

    Applying for a credit card, auto loan, mortgage, personal loan, a new cell phone plan requiring a credit check, and some rental applications and utility setups that specifically pull a full credit report as part of the approval decision.

    Does not trigger a hard inquiry (soft inquiry only)

    Checking your own score through any app or service, a credit card issuer checking your file to offer you a pre-approved offer, an existing lender periodically reviewing your account (called an “account review,” common practice for credit card issuers), and most employment background checks (which typically use a modified version of your report that doesn’t include your score and is coded as a soft inquiry).

    If you’re ever unsure whether a specific application will trigger a hard or soft inquiry, it’s reasonable to ask directly before proceeding, particularly for financial products where multiple similar applications close together could compound the score impact more than a single one would.

    Building a Buffer So Small Drops Don’t Feel Alarming

    Part of what makes a 20-point drop feel unsettling is not knowing whether it’s routine or a sign of a bigger problem. A practical way to build confidence here is to establish a personal baseline: check your score and full report at the same time each month for a few months, noting the typical range your score moves within during ordinary financial activity. Once you have that baseline, a routine fluctuation becomes recognizable as exactly that, rather than a surprise each time it happens, and a genuinely unusual move (a much larger drop, or one with no identifiable cause after reviewing your full report) becomes easier to distinguish and take seriously when it does occur.

    Frequently Asked Questions, Continued Further

    Will my score automatically bounce back to where it was before?

    In most cases, yes, once the underlying cause resolves — the inquiry ages out of scoring relevance, the balance is paid down, or enough time passes after a late payment with continued on-time payments afterward. There’s no fixed guaranteed timeline, since it depends on the specific cause and your overall file, but routine causes typically resolve within a few months.

    Does disputing an item on my credit report cause a temporary score drop while it’s under investigation?

    No. Filing a dispute itself doesn’t lower your score. If the dispute results in a negative item being corrected or removed, your score can only stay the same or improve as a result, never worsen from the dispute process itself.

    Can two people with a joint credit card see different score impacts from the same activity?

    Generally no, for the joint account itself — both cardholders’ reports reflect the same account status and balance information identically, since it’s a shared account, not an authorized-user arrangement. However, each person’s overall score can still differ due to their other, separate accounts and credit history.

    I paid my card in full and on time, so why did my utilization still show up higher this month?

    This traces back to the statement closing date issue covered earlier — your issuer reports the balance as of a fixed date each cycle, which may not be zero even if you always pay in full, simply because you had a balance on that specific day before your payment posted.

    The Bottom Line

    A 20-point credit score drop almost always has an identifiable, usually unremarkable cause: a new hard inquiry, a higher reported balance, a late payment, a closed account, or a change tied to an authorized-user account. Pulling your full credit report rather than fixating on the score alone is the fastest way to find the specific reason, and most causes at this scale resolve themselves naturally within a few months of continued responsible credit management.

    Need Help Reviewing Your Credit?

    If you’re dealing with an unexplained credit score drop or want to identify inaccurate or negative information on your credit reports, you can request a credit audit to review your situation.

    Request a Credit Audit or Quote

  • How to Start Credit at 18: A Complete Beginner’s Guide

    How to Start Credit at 18: A Complete Beginner’s Guide

    Turning 18 comes with a long list of new responsibilities, and one of the most overlooked is credit. Nobody hands you a manual for it. There’s no class in most high schools that walks you through what a credit score actually measures, how it’s calculated, or why a number you’ve never seen before can end up deciding whether you get approved for an apartment, a car loan, or even a cell phone plan without a hefty deposit.

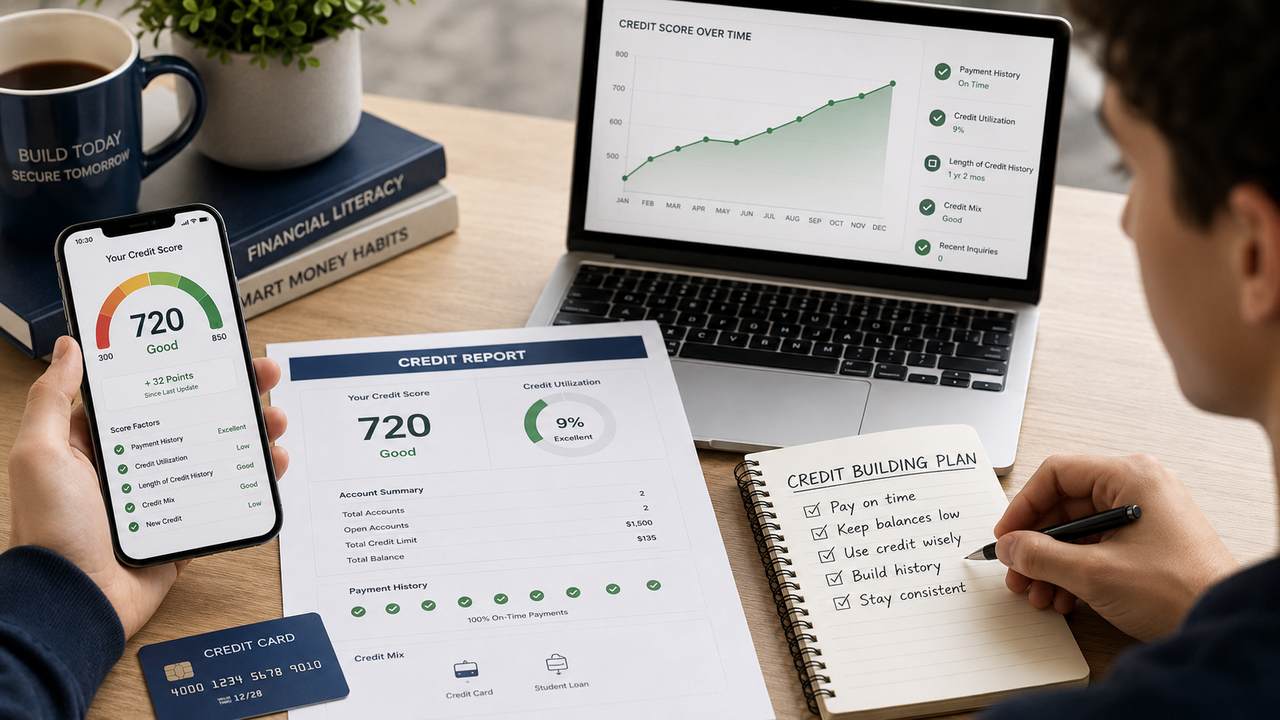
    The good news is that starting credit at 18 is one of the easiest financial advantages you can give yourself, precisely because you’re starting from zero rather than trying to undo years of mistakes. This guide walks through exactly how credit works, the specific tools available to someone just starting out, the order in which to use them, and the mistakes that trip up most first-timers.

    Why Starting Early Actually Matters

    Credit scoring models reward length of history. One of the core factors in your score is simply how long your accounts have been open. Someone who opens their first credit card at 18 and manages it responsibly will, all else being equal, have a real structural advantage over someone who waits until 25 or 30 to start — not because they’re smarter with money, but because their file is older.

    Think of it like planting a tree. A tree planted today and given basic care will be bigger in ten years than an identical tree planted five years from now, no matter how well you care for the second one later. Credit history works the same way. The clock only starts once you have an account, so the earliest possible responsible start is the biggest single edge a young adult can build in.

    There’s a second reason it matters: many of the biggest financial milestones in your twenties — renting your first apartment without a cosigner, buying a car, getting approved for a decent credit limit, even some job applications — quietly depend on having a credit history at all. Not a perfect one. Just one that exists.

    What a Credit Score Actually Measures

    Before building credit, it helps to understand what you’re actually building. In the United States, the most widely used scoring models are FICO and VantageScore, both of which pull from the same three major credit bureaus: Equifax, Experian, and TransUnion. Your score is a three-digit number, typically ranging from 300 to 850, that estimates how likely you are to repay debt on time based on your past behavior.

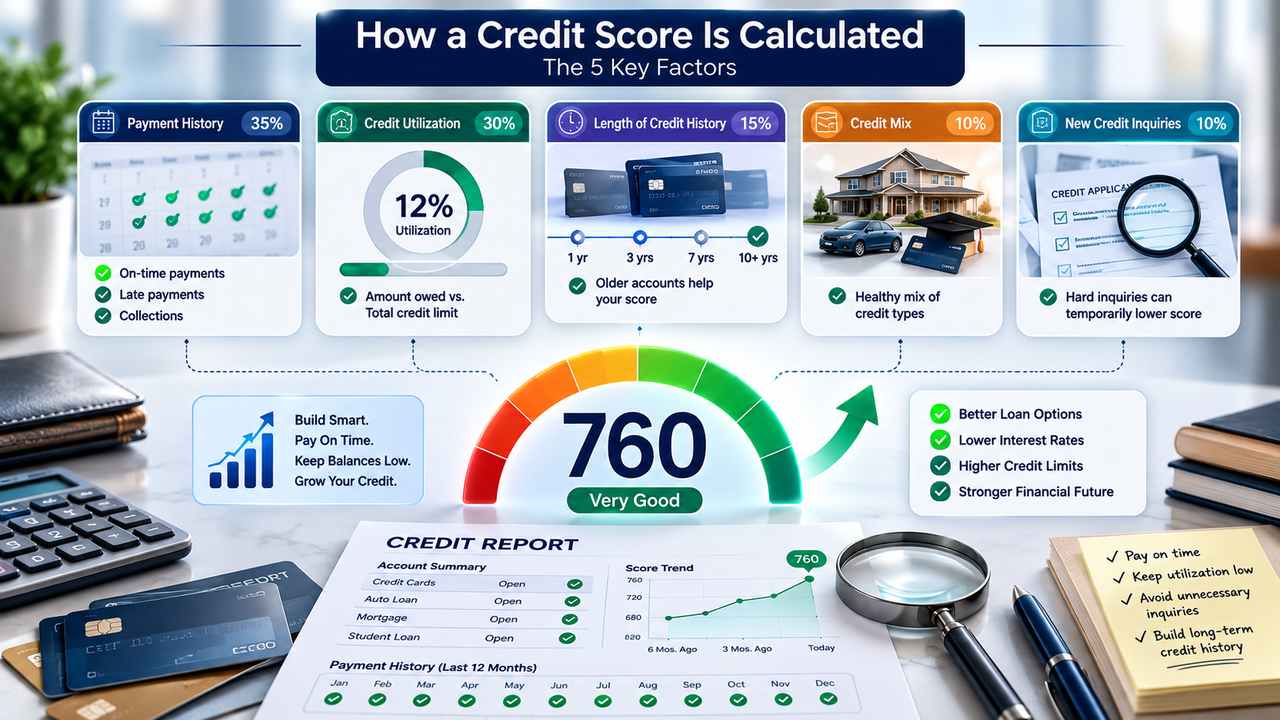
    The score is built from five main ingredients, weighted roughly as follows:

    • Payment history (about 35%). This is simply whether you’ve paid your bills on time. It’s the single heaviest factor, and it’s also the simplest to control: pay everything by the due date, every time.
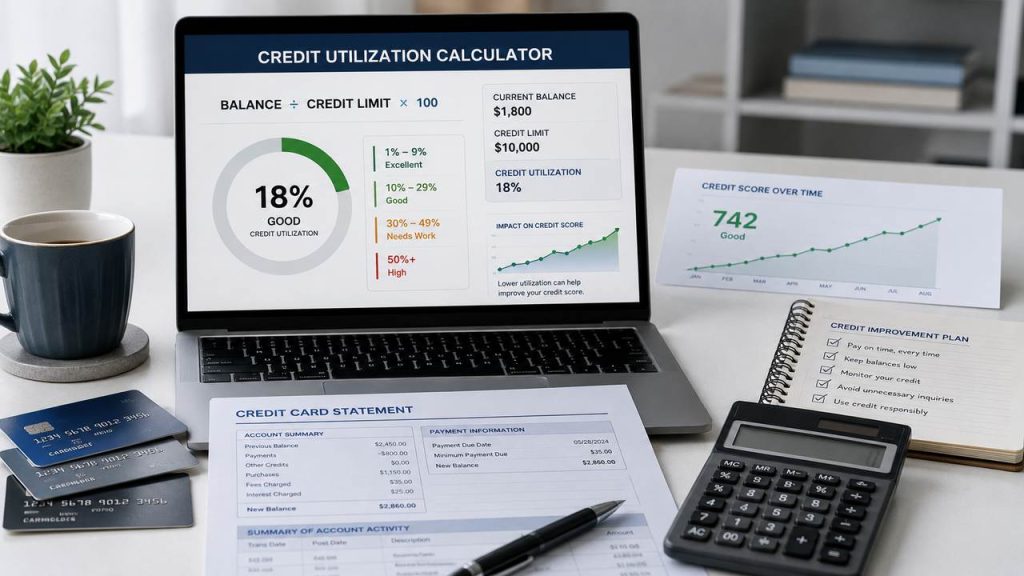
    • Credit utilization (about 30%). This measures how much of your available credit you’re actually using. If you have a card with a $1,000 limit and you’re carrying a $800 balance, your utilization is 80%, which scoring models read as a red flag, even if you plan to pay it off in full. Lower is better — many experts suggest staying under 30%, and under 10% is ideal if you can manage it.
    • Length of credit history (about 15%). This looks at the age of your oldest account, your newest account, and the average age across all your accounts. This is the factor that most rewards starting early.
    • Credit mix (about 10%). This considers the different types of credit accounts you have, such as revolving credit and installment loans.
    • New credit (about 10%). This considers recent applications for credit and hard inquiries. Opening too many accounts in a short period can make you look risky to lenders and temporarily lower your score.

    The percentages are approximate and can vary by scoring model and the specific version being used. But the general hierarchy is consistent: pay on time, keep balances low, keep accounts open, and don’t apply for everything at once.

    How to Start Credit at 18: The Step-by-Step Plan

    You don’t need five credit cards, a car loan, and a mortgage to start building credit. In fact, doing too much too soon can backfire. The goal is to establish one or two accounts, manage them perfectly, and let time do the rest.

    Step One: Get Your First Credit Account

    For most 18-year-olds, there are three realistic starting points:

    • A secured credit card
    • An authorized-user account
    • A student credit card, if you qualify

    Each has a different level of control, risk, and accessibility.

    Secured Credit Cards

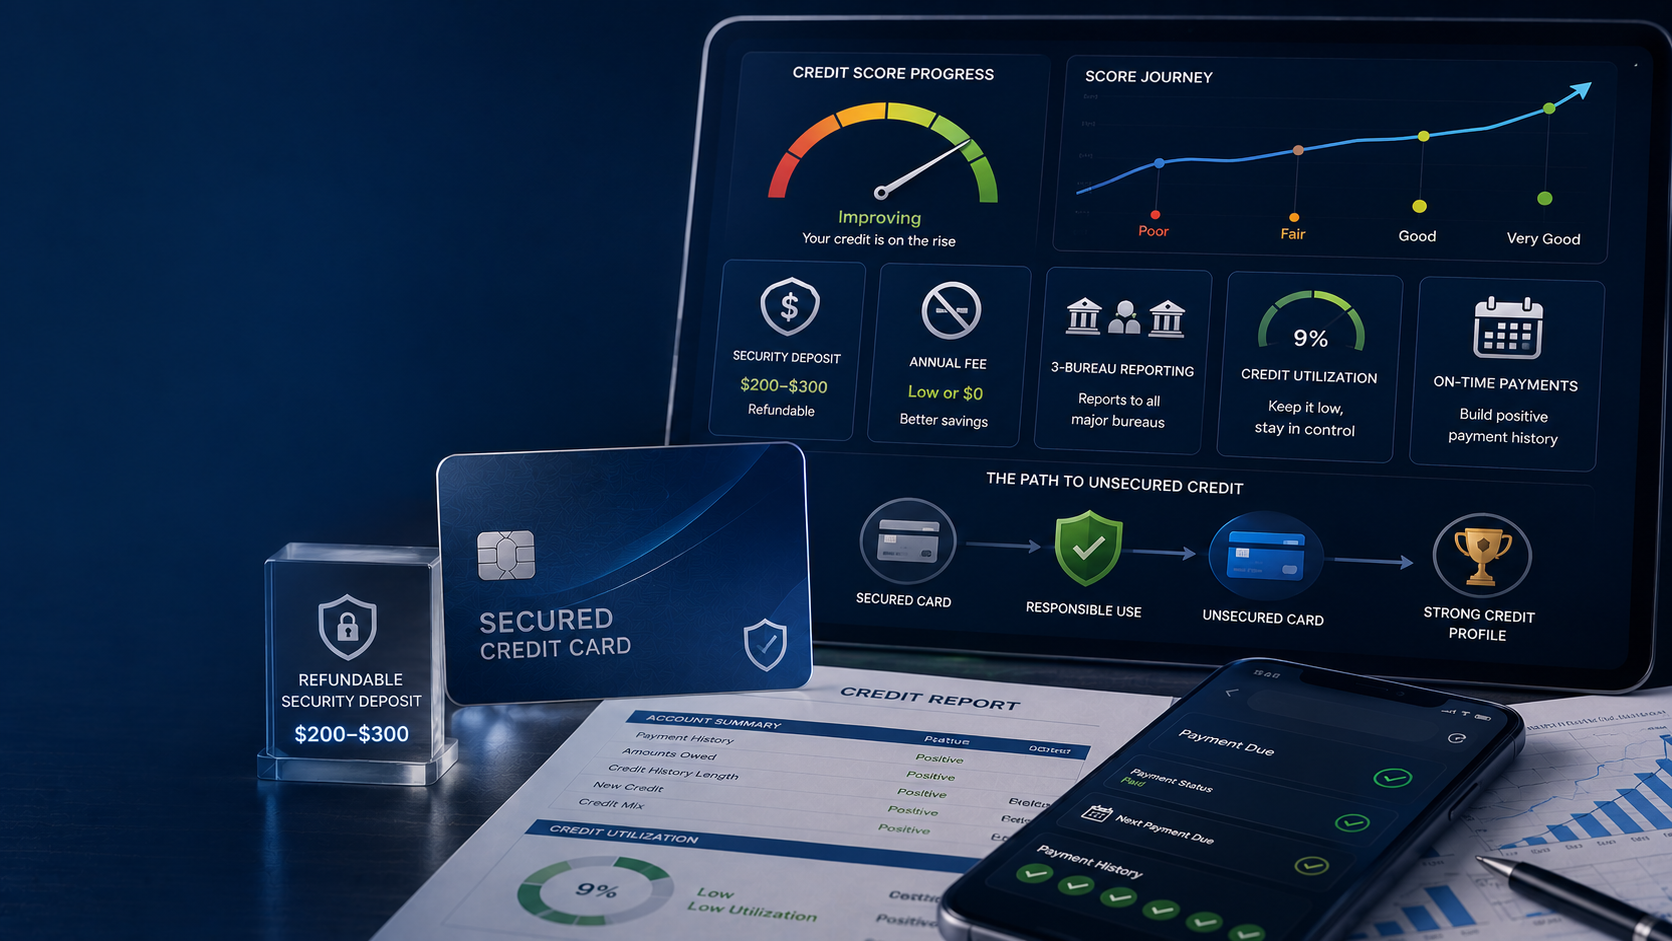
    A secured credit card is often the simplest first credit account for someone with no credit history. You provide a refundable security deposit — commonly $200 to $500 — and that deposit typically becomes your credit limit.

    You then use the card like a normal credit card. The issuer reports your payment activity to the credit bureaus, and you build a credit history by making payments on time.

    The deposit is not a payment toward your balance. It is collateral for the account. If you eventually close the card in good standing or graduate to an unsecured card, the deposit can generally be returned.

    When choosing a secured card, look for:

    • Reporting to all three major credit bureaus
    • Low or no annual fee
    • No unnecessary monthly maintenance fees
    • A clear path to graduating to an unsecured card
    • A reputable issuer

    Become an Authorized User

    If you have a parent, guardian, or another trusted family member with an established credit card that has a long history of on-time payments and low utilization, becoming an authorized user can be an effective way to establish credit history.

    When an issuer reports the authorized-user account to the credit bureaus, the account’s history may appear on your credit reports. This can give you access to positive payment history, account age, and available credit without requiring you to qualify for the primary account yourself.

    This can be particularly powerful for someone starting from zero because you may effectively inherit years of account history.

    But there is an important caveat: the account needs to be healthy. If the primary cardholder carries a very high balance or misses payments, those negative characteristics may also appear on your credit reports.

    Only become an authorized user on an account belonging to someone who manages credit responsibly.

    Student Credit Cards

    If you’re attending college, a student credit card can be another excellent starting point.

    Student cards are designed for people with limited or no credit history and are often easier to qualify for than traditional rewards cards. They can provide an unsecured credit line without requiring a security deposit.

    They’re offered by most major issuers (Discover it Student, Capital One SavorOne Student, Chase Freedom Student, Bank of America Travel Rewards for Students, etc.).

    Why they’re worth it

    • No security deposit required — you get a real unsecured card with no money down.
    • Lower APRs than store cards (though still higher than prime cards).
    • Often include rewards — cash back on dining, groceries, or gas, which secured cards typically don’t offer.
    • Reports to all three bureaus like any unsecured card.
    • Many have a graduation path — after you finish school and build history, the issuer may upgrade you to a standard unsecured rewards card.

    What to know

    • You must be 21+ to apply without a co-signer or proof of independent income. Under 21, the CARD Act requires you to show ability to repay (income) or have a co-signer. Student income from part-time work can qualify — don’t assume you need a full-time job.
    • Credit limits are modest (often $500–$1,500), but higher than most secured cards.
    • Use it for one small recurring charge (a streaming subscription, a textbook purchase) and pay it in full monthly.
    • Don’t use student status as an excuse to carry a balance. The APR on a student card is typically 18–25%. A carried balance wipes out any rewards you earn.

    If you’re a student, apply for a student card before a secured card. No deposit, better terms, and a cleaner path to an unsecured rewards card down the line.

    Consider a Credit-Builder Loan

    Credit-builder loans are designed specifically for people building or rebuilding credit. Unlike a traditional loan, you don’t receive the money upfront. Instead:

    • The lender holds the loan amount in a secured savings account.
    • You make monthly payments (which are reported to the credit bureaus).
    • When the loan is paid off, you receive the money.

    This builds positive installment credit history and forces you to save money at the same time. Many credit unions and community banks offer credit-builder loans, and there are also online lenders specializing in this product. Look for one that reports to all three bureaus and has reasonable fees.

    Give It Time

    Rebuilding credit is a marathon, not a sprint. The length of your credit history and the age of your accounts are factors you can’t rush. What you can do is start now, be consistent, and let time work in your favor. Every month of on-time payments, every statement cycle with low utilization, and every year of account aging adds up.

    Your 6-Month Plan: No Score to First FICO

    Here’s the concrete, step-by-step plan we walk clients through. Follow it in order and you’ll have a scorable FICO by month 6 and a foundation that compounds from there.

    Month 1: Lay the Foundation

    Week 1:

    • Pull your free reports from AnnualCreditReport.com (you’re entitled to free weekly reports from each bureau). Confirm you’re truly starting from scratch — sometimes there’s a surprise account (a store card a parent opened in your name, a student loan you forgot) that’s already aging on your file.
    • If there are errors or accounts you don’t recognize, document them. (This is where a credit repair professional can help — identify what’s already on your file before you start building.)

    Week 2:

    • Apply for one secured credit card from a major issuer that reports to all three bureaus and charges no annual fee. If you can, fund a $500 deposit (the higher limit helps with utilization).
    • If you have a trusted family member or partner with a clean, long-standing credit card, ask them to add you as an authorized user. Emphasize that they don’t have to give you the card.

    Week 3–4:

    • Once your secured card arrives, set up one small recurring charge on it — a $10–15 streaming subscription or similar. This keeps your balance tiny and your utilization negligible.
    • Set up auto-pay for the full statement balance every month. This is the single most important habit you’ll build. No exceptions.
    • If you rent, sign up for a rent reporting service that reports to all three bureaus and can back-report up to 24 months of past on-time payments.

    Month 2: Add the Second Tradeline

    • Apply for a credit-builder loan with a 12-month term and a small monthly payment ($25–$50).
    • Do not apply for another credit card yet.
    • Continue using your first card lightly and paying the statement balance in full.
    • Check that your secured card is appearing on your credit reports.

    Month 3: Build the Habit

    • Keep your credit card utilization below 10% whenever possible.
    • Continue making every payment on time.
    • Do not open additional accounts simply because you now have a credit score.
    • Review your reports for errors and confirm that your accounts are reporting correctly.

    Months 4–6: Let the History Build

    • Keep your accounts open.
    • Continue making every payment on time.
    • Keep utilization low.
    • Avoid unnecessary hard inquiries.
    • Monitor your reports for unexpected changes.

    By around six months, many people with their first account may become scoreable under commonly used FICO models, although the exact timing depends on the scoring model and the information being reported.

    A Closer Look: How Utilization Actually Gets Calculated

    Credit utilization is one of the easiest factors to misunderstand.

    Suppose your first card has a $300 limit. You spend $280 during the month, but you pay the entire $280 before the due date.

    You might think your utilization is zero because you paid the balance in full.

    That is not necessarily what the credit bureaus see.

    Most credit card issuers report balances around the statement closing date. If the statement closes while you owe $280, the bureau may receive a $280 balance against your $300 limit.

    That means the reported utilization could be about 93% even though you paid the card in full afterward.

    The solution: Make a payment before the statement closes if necessary, or keep your spending low enough that the statement balance remains a small percentage of the limit.

    For a $300 limit:

    • 10% utilization = $30
    • 20% utilization = $60
    • 30% utilization = $90
    • 50% utilization = $150
    • 90% utilization = $270

    For a beginner, keeping the reported balance under $30–$90 is a simple way to keep utilization low.

    Comparing Your First-Card Options Side by Side

    Feature Secured Card Student Card Authorized User
    Security deposit Usually required Usually not required None
    Credit check Varies by issuer Usually required Usually not for the AU
    Account in your name Yes Yes No — primary account belongs to someone else
    Builds payment history Yes Yes Depends on issuer reporting
    Builds utilization history Yes Yes Yes, if reported
    Control over account High High Low
    Best for People with no or limited credit Students with qualifying income/status People with a trusted primary cardholder

    For many young adults, the strongest approach is not choosing only one. A trusted authorized-user account can provide age and positive history, while a secured or student card establishes an account that you personally control.

    A Realistic First-Year Budget Example

    Imagine you’re 18, working part-time and earning $1,500 per month. You have a secured credit card with a $500 limit.

    You decide to use the card only for:

    • $25 streaming subscription
    • $40 gas
    • $35 groceries

    Your normal monthly charges are $100.

    Your utilization is:

    $100 ÷ $500 = 20%

    If you make a payment before the statement closes and the reported balance is $40, your reported utilization would be:

    $40 ÷ $500 = 8%

    You then pay the entire statement balance by the due date.

    There is no reason to spend $500 simply because you have a $500 credit limit. The purpose of the account is to establish a record of responsible credit management — not to give you permission to spend money you don’t have.

    A Short Glossary for First-Timers

    Credit Limit

    The maximum amount a revolving credit account allows you to borrow at one time.

    Statement Balance

    The balance shown on your credit card statement for a particular billing cycle.

    Current Balance

    The amount currently owed on the account, which may differ from the statement balance because additional transactions may have occurred.

    Credit Utilization

    The percentage of your available revolving credit that you are using.

    Hard Inquiry

    A credit check associated with an application for new credit that can affect your credit score.

    Soft Inquiry

    A credit check that generally does not affect your credit score, such as checking your own credit or receiving certain prequalification offers.

    Tradeline

    An individual credit account appearing on your credit report.

    Authorized User

    A person added to another individual’s credit card account who may be able to use the account but is generally not responsible for the debt as the primary account holder is.

    Secured Credit Card

    A credit card backed by a refundable security deposit that typically determines the credit limit.

    Credit-Builder Loan

    A loan product designed to establish positive payment history while the borrowed funds are held until the loan is paid off.

    A Simple First-90-Days Checklist

    • Pull all three credit reports.
    • Check for accounts you don’t recognize.
    • Choose one primary credit-building account.
    • Confirm the account reports to all three bureaus.
    • Set up autopay.
    • Use the account for one or two predictable expenses.
    • Keep utilization low.
    • Pay the full statement balance every month.
    • Avoid unnecessary applications.
    • Monitor your reports regularly.
    • Never miss a payment.
    • Do not close your first account simply because you receive another card.

    If you follow this checklist consistently, you will have accomplished the most important thing: you will have started building a positive credit history without taking on unnecessary debt.

    Myths About Starting Credit Young

    Myth 1: You Need to Carry a Balance

    You do not need to carry a balance or pay interest to build credit.

    Paying your full statement balance every month is generally the better strategy because you avoid interest while still establishing positive payment history.

    Myth 2: More Cards Mean More Credit

    More accounts do not automatically mean a higher score.

    For someone just starting out, one well-managed card is usually enough. Adding multiple accounts before you have established good habits creates unnecessary complexity and additional hard inquiries.

    Myth 3: You Need a Car Loan

    You do not need an auto loan to build credit.

    Never take on thousands of dollars of debt simply because someone told you installment credit is necessary for a strong credit score.

    Myth 4: Checking Your Own Credit Hurts Your Score

    Checking your own credit report is a soft inquiry and does not hurt your score.

    You should actually monitor your reports regularly, especially when you are building credit for the first time.

    Myth 5: You Need a 700 Score Immediately

    You don’t.

    At 18, your first objective is not to hit a specific number. It is to establish a clean, positive history that can grow over time.

    How Lenders Actually View a Thin File at 18

    When a lender sees an 18-year-old with six months of credit history, they are not expecting the same profile they would see from someone who has been borrowing for 20 years.

    What they want to see is evidence that you can manage the credit you have.

    That means:

    • No late payments
    • Low utilization
    • Stable accounts
    • No excessive recent applications
    • Growing account age
    • Consistent financial behavior

    A thin file is not necessarily a bad file. It simply means there is not much information yet.

    Your job is to give the scoring models and lenders a clean track record to evaluate.

    When to Bring in Outside Help

    Starting credit at 18 is usually something you can manage yourself. But there are situations where professional guidance can make sense.

    For example, you may want help if:

    • You discover accounts on your report that you never opened.
    • Your credit report contains inaccurate information.
    • You are already dealing with late payments or collections.
    • You are unsure how to dispute inaccurate information.
    • You need help understanding your three credit reports.
    • You are preparing for a major financial goal and want a detailed credit review.

    The important thing is to work with legitimate professionals who explain the process clearly and do not promise impossible results.

    Frequently Asked Questions

    1. How fast can I realistically build credit from scratch?

    With consistent, responsible use of a secured card (and ideally an authorized user account), you can expect your first FICO score in about 6 months, typically in the 670–720 range. Reaching 700+ usually takes 12–18 months, and 740+ takes 18–24 months. There is no legal, legitimate way to build a strong score in 30 days — anyone promising that is either misinformed or selling something that violates the FCRA.

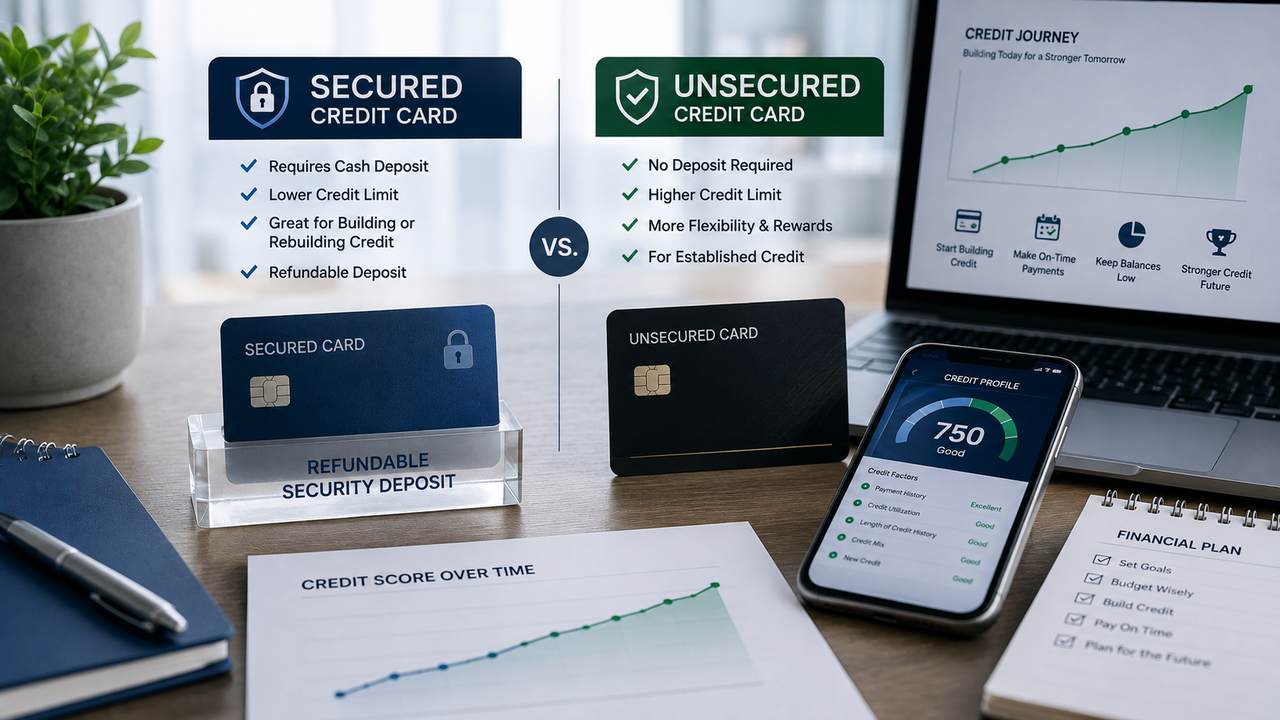
    2. What’s the difference between a secured and unsecured credit card?

    A secured card requires a refundable security deposit (usually $200–$500) that becomes your credit limit. An unsecured card requires no deposit and grants you a credit limit based on your creditworthiness. Both report to the bureaus and build credit identically. Secured cards are designed for people with no or poor credit; unsecured cards typically require an established credit history.

    3. Do I need to pay interest to build credit?

    No. This is a common myth. Paying your full statement balance every month builds your score just as fast as carrying a balance — and it costs you nothing in interest. The bureaus see your on-time payment and your reported balance; they don’t see whether you paid interest. Paying in full is the optimal strategy.

    4. Can I build credit without a credit card?

    Yes, but it’s slower and less effective. Rent reporting, credit-builder loans, and authorized user status can all build credit without you personally holding a credit card. However, revolving credit (credit cards) is the most heavily weighted type of account in FICO scoring, so if you’re able to manage a secured card responsibly, it’s the single fastest tool.

    5. Will being an authorized user hurt the primary cardholder?

    No. Adding an authorized user doesn’t affect the primary cardholder’s credit score — your separate credit activity doesn’t touch their file. The only risk to the primary cardholder is financial: they’re responsible for any charges made on the AU’s card. They can eliminate this risk by adding you as an AU but never giving you the physical card.

    6. How many credit cards should I have to build credit?

    For the first 12 months, one is plenty. After that, 2–3 revolving accounts is optimal for most people — enough to show you can manage multiple lines, but not so many that you risk missed payments or high utilization. Don’t open more than one or two new accounts per year to avoid lowering your average account age.

    7. What credit score do I need to rent an apartment?

    It varies by landlord and market, but most rental applications look for 620–680+. Higher-end buildings and competitive markets may require 700+. If you don’t yet have a score, some landlords will accept alternative evidence of financial responsibility — bank statements, employment verification, previous landlord references, or a larger security deposit. Rent reporting services can help you build toward the score threshold while you search.

    8. Can credit-repair.com help me if I’m starting from scratch?

    Yes — and this is a point worth emphasizing. Credit repair isn’t only for people with negative items to dispute. If you’re starting from zero, we can pull your three-bureau reports to confirm you’re truly starting clean (sometimes there are surprise accounts), help you identify the fastest combination of credit-building tools for your specific situation, set up rent reporting and bureau monitoring, and build you a custom repair-and-build plan that maps your path from no score to 740+. Our process is FCRA-compliant and attorney-backed, which means every step is legal, ethical, and designed for long-term success — not quick fixes.

    Start With a Free Credit Audit

    Building credit from scratch is a marathon, not a sprint. But it’s a marathon with a clear course, mile markers, and a finish line you can see. The hardest part is the first six months — the stretch where you’re doing everything right and the system hasn’t started rewarding you yet. Once that first FICO appears, the compounding begins: every month of clean history adds value, every account ages, every on-time payment strengthens the 35% of your score that matters most.

    You don’t have to figure out the path alone. At credit-repair.com, we start every new client — including those with no credit history at all — with a free three-bureau credit audit. We pull your reports from Equifax, Experian, and TransUnion, identify what’s already on your file (including any errors or surprise accounts you may not know about), and build you a custom credit-building plan tailored to your goals, timeline, and budget.

    Our approach is attorney-backed and FCRA-compliant, which means every recommendation we make is grounded in federal credit law and designed for measurable, long-term progress — not quick fixes or empty promises. We educate you on the process as we go, so you understand why each step works and can maintain strong credit long after you’ve reached your target score.

    Get your free credit audit at credit-repair.com →

    Whether you’re 18 with your first job, a recent immigrant establishing a U.S. credit file, or someone who simply never needed credit until now — the fastest way to build credit is the legitimate way, done right, starting today. We’ll walk it with you.

    Disclaimer: This article is for educational purposes and does not constitute legal or financial advice. Individual credit outcomes vary based on personal financial behavior and history. credit-repair.com operates in full compliance with the Fair Credit Reporting Act (FCRA) and all applicable federal credit laws. We do not guarantee specific score outcomes or timelines.

    Get a free credit audit.


  • Collection Agency Harassment: Your Rights Under the FDCPA

    Collection Agency Harassment: Your Rights Under the FDCPA


    If your phone rings at 7:45 a.m. with a number you don’t recognize, and by the third call of the day you’ve stopped answering altogether, you are not alone. Millions of Americans deal with collection agency harassment every year — and the majority of them don’t realize they have a federal law on their side that puts hard limits on what a debt collector can say, when they can call, and how far they can push before the law pushes back.

    The Fair Debt Collection Practices Act (FDCPA) is a federal statute that has protected consumers since 1978. It is specific, it is enforceable, and it gives you real remedies — including the ability to sue a debt collector in federal court and recover money damages. You do not need to be a lawyer to use it. You do not need to pay a lawyer up front to use it. You need to understand what the rules are, document what’s happening to you, and take the right steps in the right order.

    This guide walks you through every layer of the FDCPA in plain language: what the law covers, what collectors cannot do, how to stop the calls, how to validate or dispute a debt, how to file complaints with the right agencies, and how to take legal action when a collector crosses the line. We also explain how FDCPA protections connect to the Fair Credit Reporting Act (FCRA) and your broader credit repair strategy — because the two laws work together, and understanding both gives you leverage that neither one provides alone.

    We are a San Diego-based, attorney-backed credit repair firm that helps clients nationwide. We don’t make quick-fix promises. We help you understand your rights, enforce them, and build the kind of long-term credit health that holds up after the dispute is over. If you want a free credit audit after you finish reading, you’ll find the link at the bottom. But first, let’s get you the knowledge you need.

    What the FDCPA Is and Who It Covers

    The Fair Debt Collection Practices Act was passed by Congress in 1978 as part of the Consumer Credit Protection Act. Its purpose, stated plainly in the law itself, is “to eliminate abusive debt collection practices by debt collectors, to insure that those debt collectors who refrain from using abusive debt collection practices are not competitively disadvantaged, and to promote consistent State action to protect consumers against debt collection abuses.”

    In simpler terms: Congress recognized that a segment of the debt collection industry was using intimidation, deception, and harassment to extract payments from people who often didn’t owe the money, owed less than claimed, or were already in financial distress. The FDCPA set a federal floor — a baseline of conduct that every debt collector in the country must meet, regardless of what state they operate in.

    Who counts as a “debt collector” under the FDCPA

    This is the single most important distinction in the entire law, and it trips people up constantly. The FDCPA applies to third-party debt collectors — not to the original creditor you borrowed from.

    What does that mean in practice?

    • If you have a credit card with a bank and you fall behind, and the bank’s own internal collections department calls you, the FDCPA does not apply to that call. The bank, as the original creditor, is generally exempt.
    • If that same bank hires an outside collection agency to collect the debt on its behalf, or sells the debt to a debt buyer who then tries to collect it, the FDCPA applies. Once a third party enters the picture, the federal protections kick in.
    • The FDCPA also applies to debt buyers — companies that purchase charged-off debt portfolios for pennies on the dollar and then attempt to collect the full balance. These are some of the most common sources of consumer complaints, and they are squarely covered by the law.
    • Debt collection attorneys are covered when they regularly attempt to collect debts. A lawyer who files a collection lawsuit against you is generally acting as a debt collector under the FDCPA if they regularly engage in collection activity.

    There’s a specific threshold in the law: a “debt collector” is someone whose principal business is collecting debts, or who regularly collects debts owed to another. The 2010 amendment and subsequent court interpretations have clarified that debt buyers — entities that purchase debts and collect them in their own name — are also covered, though some nuances remain depending on when the debt was acquired and whether the collector used the original creditor’s name.

    What counts as a “debt” under the FDCPA

    The FDCPA defines a debt as “any obligation or alleged obligation of a consumer to pay money arising out of a transaction in which the money, property, insurance, or services which are the subject of the transaction are primarily for personal, family, or household purposes.” The key phrase is personal, family, or household. Business debts are not covered by the FDCPA. If you took out a loan for a small business and the lender sends it to collections, the FDCPA does not apply to that collection activity — though state laws might.

    Covered debts include:

    • Credit card debt
    • Medical bills sent to collections
    • Personal loans
    • Auto loans (the deficiency balance after repossession, typically)
    • Payday loans
    • Student loans (private student loans are covered; federal student loans are collected by the government and its servicers, which are generally not “debt collectors” under the FDCPA, though some private collectors hired by the Department of Education may be)
    • Utility bills and cell phone bills in collections
    • Overdrawn bank accounts

    Who is NOT covered

    • Original creditors collecting on their own debts, using their own name (your credit card company calling you directly)
    • Internal collection departments of the original creditor, as long as they use the creditor’s name
    • Government employees collecting government debts
    • Process servers serving legal papers
    • Mortgage servicers in some contexts (though mortgage foreclosures have their own regulatory framework)

    State laws may extend protection

    This is critical and often overlooked: even if the FDCPA doesn’t cover your situation — say, because you’re dealing with an original creditor’s internal collection department — your state may have its own debt collection law that covers original creditors. States like California (with the Rosenthal Fair Debt Collection Practices Act), New York, Florida, Massachusetts, and many others have laws that mirror or expand the FDCPA and apply it to original creditors as well. We cover this in more detail in the State Debt Collection Laws section below.

    The bottom line: if a collector is a third party collecting a personal, family, or household debt, the FDCPA applies to them — and you have enforceable rights. If they’re not covered by the FDCPA, check your state law before assuming you have no protection.

    Your Rights Under the FDCPA

    The FDCPA gives you a specific, enumerated set of rights. These are not suggestions. They are federal law, and violating them can cost the collector money — money that can end up in your pocket. Here is the full breakdown.

    Your FDCPA Rights at a Glance

    Right What It Means FDCPA Section
    No calls before 8 a.m. or after 9 p.m. Collectors cannot call outside 8:00 a.m. – 9:00 p.m. local time § 1692c(a)(1)
    No calls at work if prohibited If your employer doesn’t allow personal calls, collectors can’t call you at work § 1692c(a)(3)
    No harassment or abuse No threats of violence, profanity, or repeated calls meant to harass § 1692d
    No false or misleading statements No lying about the debt, the consequences, or who they are § 1692e
    No publishing your name Cannot publish a “shame list” of debtors § 1692e(d)
    Must identify themselves Must state they are a debt collector and that information will be used to collect a debt § 1692e(11)
    Must send a validation notice Within 5 days of first contact, must send written notice of the debt and your rights § 1692g
    Right to dispute the debt You have 30 days to dispute the debt in writing § 1692g(a)(3)
    Right to request collector’s name and address You can demand the original creditor’s name and the amount owed § 1692g(a)(2)
    No contact if you have an attorney If you’re represented by an attorney, the collector must contact them, not you § 1692c(a)(2)
    Right to stop all contact You can send a cease and desist letter demanding no further contact § 1692c(c)

    No calls before 8 a.m. or after 9 p.m.

    A debt collector cannot call you before 8:00 a.m. or after 9:00 p.m. local time — your local time, not theirs. A collector in New York cannot call you in Los Angeles at 9:30 a.m. their time and claim it’s within bounds, because that would be 6:30 a.m. your time. The standard is the consumer’s time zone.

    If a collector calls you at 7:15 a.m., that is a violation. If they call you at 9:30 p.m., that is a violation. If they call you repeatedly at 8:01 a.m. every single day for two weeks, the time-of-day rule may not be violated, but the harassment provision (§ 1692d) likely is.

    No calls at work if prohibited

    If your employer prohibits you from receiving personal calls at work, and the collector knows or should know this, they cannot call you at work. The key is that the collector must be on notice. You can put them on notice by telling them directly: “My employer does not allow me to receive personal calls at work. Do not contact me here.” Once you’ve said that, any further call to your workplace is a violation.

    No harassment, threats, or profanity

    The FDCPA prohibits harassment or abuse in connection with the collection of any debt. The law lists specific examples:

    • Threats of violence or physical harm — to you, your family, or your property
    • Profane or abusive language — swearing, name-calling, racial slurs, demeaning language
    • Repeated or continuous calls intended to annoy, abuse, or harass
    • Publication of a list of consumers who allegedly refuse to pay debts (the “shame list” prohibition)
    • Telephone calls without meaningful disclosure of the caller’s identity — anonymous calls designed to intimidate

    The harassment standard is about intent and effect. A single call that uses profane language is a violation. A pattern of 15 calls in one day is a violation even if the collector is polite on each call, because the volume itself constitutes harassment. Courts look at the totality of the conduct.

    No false or misleading statements

    This is one of the broadest and most powerful provisions of the FDCPA. A debt collector may not use any false, deceptive, or misleading representation or means in connection with the collection of any debt. The law lists 16 specific prohibited false statements, including:

    • Falsely claiming to be an attorney or that the communication is from an attorney
    • Falsely claiming the debt is legally owed when it isn’t, or misstating the amount
    • Falsely threatening arrest or imprisonment — you cannot be jailed for failing to pay a debt (more on this below)
    • Falsely claiming to be a government representative or affiliated with any government agency
    • Threatening to take action that cannot legally be taken or that the collector doesn’t actually intend to take (e.g., threatening to garnish wages when they have no judgment and no intention to sue)
    • Falsely claiming nonpayment will result in seizure of property unless they have the legal right to do so
    • Misrepresenting the legal status of the debt — claiming it’s a judgment when it isn’t, or claiming it’s within the statute of limitations when it isn’t
    • Using a false business name or a name that misleads you about who is calling
    • Falsely claiming that documents are legal process when they aren’t, or that documents are not legal process when they are

    This provision is why so many FDCPA lawsuits succeed. Collectors routinely make statements that cross the line — “we’re going to garnish your wages next week” (when they can’t), “this will go on your criminal record” (it won’t), “we’re attorneys and we’re preparing a lawsuit” (they aren’t). Each false statement is a separate violation.

    Must identify themselves

    Every debt collector must, in the initial communication with you, state clearly that they are attempting to collect a debt and that any information obtained will be used for that purpose. This is the so-called Mini-Miranda warning. It must appear in the first written communication and, if the first contact is by phone, must be stated during that call.

    If a collector calls you and says “this is John from the processing department” without identifying themselves as a debt collector, that’s a violation. If they send you a letter that looks like a legal notice but never says “this is an attempt to collect a debt,” that’s a violation.

    Must send a written validation notice

    Within five days of their initial communication with you (whether that communication is a phone call or a letter), a debt collector must send you a written notice containing:

    1. The amount of the debt
    2. The name of the creditor to whom the debt is owed
    3. A statement that unless you dispute the debt within 30 days, the collector will assume the debt is valid
    4. A statement that if you notify the collector in writing within 30 days that you dispute the debt, the collector will obtain verification of the debt and mail it to you
    5. A statement that if you request the name and address of the original creditor within 30 days, the collector will provide it

    This notice is your gateway to challenging the debt. We cover it in detail in the Validation Notice section.

    Right to be represented by an attorney

    If you hire an attorney to represent you regarding the debt, the collector must stop contacting you directly and must communicate only through your attorney. This is one of the fastest ways to get the calls to stop — and it’s why working with an attorney-backed credit repair firm can be so effective. Once the collector knows you’re represented, they have to go through your representative.

    How to Stop Collection Calls

    You have several tools to stop a debt collector from calling you. They range from informal to formal, and the right approach depends on your situation and your goals.

    Option 1: Tell them to stop calling

    The simplest step is to tell the collector, on the phone, to stop calling you. This is not as legally powerful as a written cease and desist letter, but it does create a record. Say something like: “I am requesting that you stop calling this number. All future communication must be in writing.” Note the date, time, and the name of the person you spoke with.

    Option 2: Send a written cease and desist letter

    This is the most powerful tool you have for stopping contact short of hiring a lawyer. Under FDCPA § 1692c(c), if you notify a debt collector in writing that you refuse to pay the debt or that you wish the collector to cease further communication, the collector must stop communicating with you — with very limited exceptions.

    Once the collector receives your written cease and desist letter, they can only contact you to:

    1. Advise you that further collection efforts are being terminated
    2. Notify you that specific remedies (like a lawsuit) may be invoked
    3. Notify you that specific remedies will be invoked

    That’s it. No more calls. No more letters. No more texts. If they contact you for any other reason, that is a violation of the FDCPA — and you can sue for it.

    Cease and desist letter template

    Here is a template you can adapt and send. Send it by certified mail with return receipt so you have proof of delivery. Keep a copy for your records.

    [Your Name]
    [Your Address]
    [Your City, State, ZIP]
    [Your Phone Number]
    [Your Email]

    [Date]

    [Collection Agency Name]
    [Collection Agency Address]
    [City, State, ZIP]

    Re: Account # [Account or Reference Number]
    Original Creditor: [Original Creditor Name, if known]
    Amount Claimed: $[Amount, if known]

    To Whom It May Concern:

    I am writing in response to your attempts to collect a debt that you claim I owe. Pursuant to my rights under the Fair Debt Collection Practices Act (15 U.S.C. § 1692c(c)), I hereby request that you CEASE AND DESIST all communication with me regarding this alleged debt.

    This means you are not to contact me by telephone at my home, at my place of employment, on my cell phone, or at any other number. You are not to contact me by mail, by email, by text message, or through any third party. The only exceptions permitted by law are:

    1. To advise me that your collection efforts are being terminated.
    2. To notify me that you may invoke specified remedies.
    3. To notify me that you intend to invoke a specified remedy, such as filing a lawsuit.

    Please be advised that I am aware of my rights under the Fair Debt Collection Practices Act and under applicable state law. I am also aware that if you fail to comply with this request, you may be subject to liability for statutory damages, actual damages, and attorney’s fees under 15 U.S.C. § 1692k.

    In addition, I dispute the validity of this debt and request that you provide verification of the debt as required by 15 U.S.C. § 1692g, including:

    – The name and address of the original creditor
    – The amount of the alleged debt
    – Proof that you are authorized to collect this debt
    – A copy of any judgment or other documentation establishing the debt

    Until you have provided this verification, you are prohibited by law from collecting this debt or reporting it to any credit reporting agency.

    Sincerely,

    [Your Signature]
    [Your Printed Name]

    Important caveats about cease and desist letters

    A cease and desist letter stops communication, but it does not make the debt go away. The collector can still:

    • Report the debt to the credit bureaus (unless you also dispute the debt and they cannot verify it)
    • File a lawsuit against you to collect the debt (in fact, some collectors sue after receiving a cease and desist letter, because litigation is one of the permitted “specified remedies”)
    • Sell the debt to another collector, who is also bound by the FDCPA and to whom you can send another cease and desist letter

    So a cease and desist is powerful, but it’s not a silver bullet. It buys you peace and it creates a record, but it doesn’t resolve the underlying debt. For that, you need to address the debt itself — through validation, dispute, settlement, or, if appropriate, bankruptcy.

    Option 3: Hire an attorney

    When you hire an attorney to handle the debt, the collector must stop contacting you and deal only with your attorney. This is often the cleanest solution because it puts a professional between you and the collector, and because an FDCPA attorney will often take your case on contingency — meaning you pay nothing up front, and the attorney collects their fee from the collector if you win.

    Option 4: File for bankruptcy

    If you’re overwhelmed by multiple debts, bankruptcy triggers the automatic stay, which stops virtually all collection activity immediately. This is a major step with long-term consequences, and it’s beyond the scope of this article — but it is a legal tool that stops collection calls cold. If you’re considering bankruptcy, consult a bankruptcy attorney.

    The Validation Notice and Your 30-Day Right

    The validation notice is one of the most important protections in the FDCPA, and it’s the one most consumers misunderstand. Here’s how it works.

    The five-day rule

    Within five days after a debt collector first contacts you (whether by phone, letter, or other means), they must send you a written notice containing the validation information described above: the amount of the debt, the name of the creditor, your right to dispute, your right to request the original creditor’s name and address, and the 30-day deadline.

    Your 30-day window

    From the date you receive that validation notice, you have 30 days to take one of several actions:

    • Dispute the debt in writing — if you dispute the debt, the collector must cease collection until they obtain verification of the debt (or a copy of the judgment, if applicable) and mail it to you
    • Request the original creditor’s name and address — if you request this in writing, the collector must provide it
    • Do nothing — if you do nothing within 30 days, the collector may presume the debt is valid and continue collection efforts

    The 30-day period is not a statute of limitations on disputing the debt. You can dispute a debt at any time. But within the 30-day window, the collector must stop collecting and verify the debt if you dispute it. Outside the window, they are not legally required to stop collecting while they respond, though they still cannot make false statements or harass you.

    What “verification” means

    The FDCPA does not define exactly what “verification” requires, and courts have split on how thorough it must be. At minimum, the collector must:

    • Confirm with the original creditor that the amount is correct
    • Obtain and send you some documentation supporting the debt — at least a copy of a judgment if one exists, or basic information confirming the debt

    Some courts require more — particularly for debt buyers, who may need to provide a chain of assignment showing they actually own the debt. If a debt buyer cannot produce documentation that they own the debt and that the amount is accurate, they may not be able to verify it, and continued collection could violate the FDCPA.

    What happens if they can’t verify

    If a collector cannot verify the debt, they must stop collecting it. That means:

    • No more calls
    • No more letters
    • No more lawsuits
    • No reporting to credit bureaus (under the FDCPA, continued reporting without verification can be a violation, and under the FCRA, reporting inaccurate information is a separate violation)

    This is where the FDCPA and the FCRA work together — and where an attorney-backed credit repair strategy can be especially effective. If a collector reports a debt to the credit bureaus without verifying it after you’ve disputed it, you may have claims under both laws.

    What “verification” does NOT mean

    Verification is not the same as validation in the credit reporting sense. The collector does not have to produce a mountain of documentation. They do not have to prove every detail of the debt in a court of law at this stage. The standard is relatively low — but it is a real standard, and collectors who skip it or ignore a timely dispute are violating the law.

    Disputing after the 30-day window

    You can dispute a debt at any time, even years later. The 30-day window gives you the strongest legal leverage (because it forces the collector to stop collecting until they verify), but you always have the right to:

    • Dispute directly with the credit bureaus under the FCRA
    • Request verification from the collector (though they’re not required to stop collecting if you’re outside the 30-day window)
    • Demand validation as part of defending a collection lawsuit

    If a collector sues you, you can raise the failure to validate as a defense and can also counterclaim for FDCPA violations.

    What Debt Collectors Cannot Do

    Beyond the time-of-day and harassment rules, the FDCPA specifically prohibits a range of conduct. Here’s a plain-language list of what collectors absolutely cannot do.

    1. Threaten arrest or imprisonment

    You cannot be jailed for failing to pay a debt. Debt is a civil matter, not a criminal one. A collector who threatens you with arrest, claims a warrant is out for you, or says you’ll be sent to prison is violating the FDCPA. The only exception is in extremely rare cases of criminal contempt related to court orders — and even then, it’s not the debt itself that triggers arrest, it’s a violation of a court order. A collector claiming “we’ll have you arrested tomorrow if you don’t pay” is lying, and that lie is illegal.

    2. Lie about the debt

    A collector cannot:

    • Claim you owe more than you do
    • Add unauthorized fees or interest
    • Claim the debt is a judgment when no lawsuit has been filed
    • Claim the debt is within the statute of limitations when it’s time-barred
    • Claim they’ve already sued you when they haven’t
    • Misrepresent the legal consequences of nonpayment

    3. Contact third parties about your debt

    Except to locate you, a collector cannot contact third parties about your debt. This means:

    • No calling your family members to tell them about your debt
    • No calling your employer to discuss your debt (they can call once to verify your employment, but cannot discuss the debt)
    • No calling your friends, neighbors, or coworkers to discuss your debt
    • No calling your spouse in some circumstances (though spouses may be contacted in certain states and situations)

    The exception: a collector may contact third parties once to obtain your location information (your address, phone number, place of employment) — but they cannot mention the debt, and they cannot contact that third party again unless the third party agrees to help or the collector reasonably believes the information was false.

    4. Call repeatedly to harass

    While the FDCPA doesn’t set a specific number of calls that constitutes harassment, courts have found that repeated calls — multiple calls per day, calls every day for weeks, calls after being told to stop — can violate the harassment prohibition. The standard is whether the calls are intended to annoy, abuse, or harass. If a collector calls you 10 times in a single day, a court is likely to find that harassing. If they call once a day for a week after you’ve told them you can’t pay, that may also cross the line.

    5. Use obscene or profane language

    Any profanity, racial slurs, name-calling, or abusive language is prohibited. A collector who calls you a “deadbeat,” uses profanity, or makes demeaning comments is violating the FDCPA.

    6. Threaten actions they cannot or will not take

    A collector cannot threaten to:

    • Garnish your wages without first obtaining a judgment (in most states, wage garnishment requires a court judgment — there are exceptions for federal student loans, taxes, and child support)
    • Seize your property without a legal right to do so
    • File a lawsuit they have no intention of filing
    • Have you arrested (as noted above)
    • Take any action that is illegal or that they don’t actually intend to take

    7. Deposit a postdated check early

    If you give a collector a postdated check, they cannot deposit it early without your consent. They also cannot accept a postdated check from you without disclosing their intent to deposit it early.

    8. Collect amounts not authorized

    A collector cannot collect any amount — interest, fees, charges — unless it’s expressly authorized by the agreement that created the debt or permitted by law. Many old debts are “time-barred” (past the statute of limitations), and collecting interest or fees on a time-barred debt can be a violation.

    9. Communicate by postcard

    A collector cannot communicate with you about a debt by postcard, because a postcard can be read by anyone who handles the mail — which would disclose your debt to third parties.

    10. Use any envelope with markings that indicate a debt collection

    The envelope of any communication from a debt collector cannot have any language or symbol (other than the collector’s name and address) that indicates the communication is about debt collection. This is why legitimate collection letters come in plain envelopes.

    11. Contact you if you’re represented by an attorney

    If the collector knows you have an attorney representing you regarding the debt, they must contact the attorney, not you — unless the attorney fails to respond within a reasonable time.

    12. Call you at inconvenient times or places

    Beyond the 8 a.m. – 9 p.m. rule, a collector cannot call you at any time or place they know (or should know) is inconvenient for you. If you tell them “don’t call me on Sundays” or “don’t call me during my lunch hour,” they must respect that.

    What to Do When You’re Harassed

    If a debt collector is violating the FDCPA, you have a clear path to fight back. Here’s the step-by-step process, in order.

    Step 1: Document everything

    This is the most important step. Without documentation, you have no case. With documentation, you have leverage — and potentially a lawsuit worth real money.

    Start a collection log immediately. For every contact, record:

    • Date and time of the contact
    • Phone number the call came from (or the address on the envelope)
    • Name of the collector and the collection agency
    • What was said — as close to verbatim as you can remember
    • Any threats, profanity, or false statements made
    • Witnesses who were present (if any)
    • Your emotional state and any distress you experienced

    Save every voicemail. Save every text message. Save every letter and envelope. Do not delete anything. If the calls are coming to your cell phone, take screenshots of the call log. If you can, record the calls — but check your state’s recording law first. In “one-party consent” states (the majority), you can record without telling the collector. In “two-party consent” states (like California, Florida, Illinois, and others), you must inform the other party that the call is being recorded.

    Step 2: Send a cease and desist letter

    Use the template above. Send it by certified mail with return receipt. Keep the receipt — it’s your proof that the collector received it. Once they have it, any further contact (other than the three permitted exceptions) is a violation.

    Step 3: Dispute the debt in writing

    If you don’t believe you owe the debt, or you believe the amount is wrong, dispute it in writing within 30 days of receiving the validation notice. This forces the collector to verify the debt and stops collection activity until they do. Use a dispute letter that specifically requests:

    • Verification of the debt
    • The name and address of the original creditor
    • Proof that the collector is authorized to collect the debt
    • A copy of any judgment (if applicable)

    Step 4: File a complaint with the CFPB

    The Consumer Financial Protection Bureau (CFPB) is the federal agency that enforces the FDCPA. You can file a complaint online at consumerfinance.gov. The CFPB will forward your complaint to the collector and require them to respond. The CFPB tracks complaint patterns and can take enforcement action against collectors with widespread violations.

    What to include in your CFPB complaint:

    • The collection agency’s name and contact information
    • The debt information (amount, original creditor, account number)
    • A description of the violation(s), with dates
    • Any documentation you have (letters, call logs, voicemails)
    • What you want (e.g., the calls to stop, the debt verified, damages)

    Step 5: File a complaint with the FTC

    The Federal Trade Commission (FTC) also accepts complaints about debt collectors at ftc.gov. While the CFPB is now the primary enforcer of the FDCPA, the FTC still plays a role, and filing with both agencies creates a more complete record.

    Step 6: File a complaint with your state attorney general

    Many state attorneys general have consumer protection divisions that handle debt collection complaints. Some states have their own debt collection laws (covered below) that the AG can enforce. Filing with your state AG can trigger state-level action that complements the federal process.

    Step 7: Consult an FDCPA attorney

    If you have documented violations, talk to a consumer protection attorney who handles FDCPA cases. Most FDCPA attorneys offer a free initial consultation and take cases on contingency — meaning they get paid by the collector if you win, not out of your pocket. The FDCPA specifically provides for attorney’s fees to be paid by the losing collector, which is why attorneys can take these cases without charging you upfront.

    An attorney can:

    • Evaluate the strength of your case
    • Send a formal demand letter to the collector
    • Negotiate a settlement (which may include the debt being removed from your credit report)
    • File a lawsuit in federal court if the collector won’t settle
    • Help you recover statutory damages up to $1,000 plus actual damages and attorney’s fees

    You don’t have to wait until you’ve been harassed to consult an attorney. If a collector is making your life miserable, an attorney can step in immediately and take over all communication — which, as we noted, the collector must respect.
    collection-agency-harassment-fdcpa-under-100kb

    How to Sue Under the FDCPA

    If a debt collector has violated the FDCPA, you have the right to sue them in federal court. You can also sue in state court, but federal court is the more common venue for FDCPA cases. Here’s what you need to know.

    Who can sue

    Any consumer who has been subjected to a prohibited collection practice can sue. You do not need to have actually paid the debt. You do not need to have suffered financial loss. The FDCPA provides statutory damages — a fixed amount — for any violation, regardless of whether you lost money.

    What you can recover

    Under 15 U.S.C. § 1692k, you can recover:

    1. Statutory damages — up to $1,000 per lawsuit (not per violation). This is a flat amount that you’re entitled to if the collector violated the FDCPA, even if you can’t prove any specific financial harm. Some courts and state laws allow more.
    2. Actual damages — compensation for any concrete harm you suffered. This can include:
      • Emotional distress (anxiety, sleep loss, stress, humiliation)
      • Out-of-pocket costs (e.g., the cost of changing your phone number, medical bills for stress-related treatment)
      • Lost wages (if collection calls caused you to miss work)
      • Damage to your credit (if false reporting caused you to be denied credit)
    3. Attorney’s fees and costs — the collector must pay your attorney’s fees and court costs if you win. This is what makes FDCPA cases feasible on contingency.

    In class action lawsuits, the statutory damages cap is the lesser of $500,000 or 1% of the collector’s net worth.

    The statute of limitations

    You must file an FDCPA lawsuit within one year of the violation. The clock starts running on the date of the violation. If a collector called you in violation on March 15, 2025, you have until March 15, 2026 to file. If they made multiple violating calls over several months, each call may be a separate violation, but the one-year clock runs from each individual violation.

    This deadline is strict. If you miss it, you lose your right to sue under the FDCPA — though you may still have claims under state law, which often has a longer statute of limitations. Don’t wait. If you think you have a case, talk to an attorney as soon as possible.

    What you have to prove

    To win an FDCPA case, you generally need to show:

    1. The defendant is a “debt collector” under the FDCPA (they regularly collect debts owed to others)
    2. The debt is a “consumer debt” (personal, family, or household purpose)
    3. You are a “consumer” under the FDCPA
    4. The collector violated a specific provision of the FDCPA
    5. You suffered damages (statutory damages don’t require proof of specific harm, but actual damages do)

    For most violations, you don’t need to prove the collector intended to violate the law. The FDCPA is a strict liability statute — the collector is liable for violations even if they didn’t mean to break the law. However, there is a “bona fide error” defense: if the collector can show the violation was unintentional, resulted from a bona fide error, and was not part of a pattern, they may avoid liability. This defense is narrow and rarely succeeds.

    The process

    1. Consult an attorney (or decide to proceed pro se — on your own — which is possible but not recommended)
    2. File a complaint in federal court
    3. The collector responds (usually by answering the complaint or filing a motion to dismiss)
    4. Discovery — both sides exchange information and evidence
    5. Settlement negotiations — most FDCPA cases settle before trial
    6. Trial (if no settlement is reached)

    Most FDCPA cases settle. Collectors don’t want to go to trial because the attorney’s fees provision makes losing expensive, and because bad publicity and CFPB scrutiny can follow. A typical settlement may include:

    • A cash payment to you (often more than the $1,000 statutory minimum)
    • Waiver or reduction of the underlying debt
    • Deletion of the tradeline from your credit report
    • An injunction requiring the collector to stop the prohibited conduct

    Do you need an attorney?

    You can file an FDCPA lawsuit without an attorney (pro se), but it’s not advisable. FDCPA law has procedural nuances, federal court rules are complex, and collectors will have attorneys. Because the FDCPA provides for attorney’s fees, consumer protection attorneys take these cases on contingency — meaning you pay nothing upfront, and the attorney’s fee comes from the collector if you win. There’s almost no downside to at least consulting one.

    How This Ties to Credit Repair

    The FDCPA and the Fair Credit Reporting Act (FCRA) are two halves of a complete consumer protection framework. The FDCPA governs how collectors can collect from you. The FCRA governs how collectors can report about you. Understanding how they interact is the key to effective credit repair.

    The connection

    When a debt goes to collections, the collector typically reports it to the three major credit bureaus — Equifax, Experian, and TransUnion — as a collection account. This collection tradeline can drop your credit score by 50 to 100 points or more and stays on your report for seven years from the date of the original delinquency.

    Here’s how the two laws work together:

    1. You dispute the debt with the collector under the FDCPA (within 30 days of the validation notice). The collector must verify the debt or stop collecting. If they can’t verify, they should also stop reporting — because reporting without verification can be a false or misleading representation under the FDCPA.
    2. You dispute the tradeline with the credit bureaus under the FCRA. The bureaus must investigate within 30 days (generally) and must provide the results to you. If the collector cannot verify the debt, the tradeline should be removed or corrected.
    3. If the collector reports inaccurate information — wrong amount, wrong dates, wrong original creditor, or reports a debt you’ve disputed without noting the dispute — that’s a violation of the FCRA. And if the collector continues to report after failing to verify a disputed debt, that can be a violation of both the FCRA and the FDCPA.
    4. If the collector sues you, you can raise FDCPA violations as counterclaims and can also challenge the FCRA reporting as part of your defense.

    The strategy

    An effective credit repair strategy uses both laws:

    • FDCPA tools — cease and desist letters, validation disputes, documentation of violations, lawsuits — to stop harassment and force collectors to verify or back off
    • FCRA tools — bureau disputes, requests for reinvestigation, method-of-verification requests — to challenge inaccurate, incomplete, or unverifiable information on your credit reports
    • Attorney backing — to enforce your rights under both laws and to escalate when collectors or bureaus don’t comply

    Why attorney backing matters

    A debt collector who knows you’re working with an attorney thinks differently. They know that violations could cost them money in court. They know that an attorney-backed dispute is not a “nuisance” dispute that they can ignore. They know that continued reporting without verification could trigger an FCRA claim on top of the FDCPA claim.

    This is why our firm is attorney-backed. We don’t just send dispute letters and hope. We work alongside experienced attorneys who understand both the FDCPA and the FCRA, who know how to document violations, and who can escalate to litigation when necessary. The combination of legal knowledge, strategic dispute filing, and attorney oversight gives our clients leverage that pure “credit repair” companies — who just send form letters — cannot match.

    What we do

    Our process includes:

    1. A free credit audit — we pull and review your credit reports from all three bureaus and identify collection accounts, errors, and potential violations
    2. A customized repair plan — tailored to your specific debts, goals, and timeline
    3. FDCPA-based disputes — validation requests to collectors, documentation of violations, cease and desist letters when appropriate
    4. FCRA-based disputes — bureau disputes, method-of-verification requests, follow-up on inaccurate reporting
    5. Attorney coordination — when a collector crosses the line or a bureau fails to correct an error, we work with attorneys who can take legal action
    6. Client education — we teach you how to maintain strong credit long after the process is complete, because credit health is a long-term commitment

    We do not guarantee specific outcomes, and we do not make quick-fix promises. What we do is use the full scope of federal and state consumer protection law — applied strategically and backed by attorneys — to give you the best possible chance of removing inaccurate, unverifiable, or unlawfully reported items from your credit reports.

    State Debt Collection Laws

    The FDCPA is a federal floor, not a ceiling. Many states have their own debt collection laws that provide additional protections or extend coverage to situations the FDCPA doesn’t reach. Here’s what you need to know.

    States that extend FDCPA protections to original creditors

    The FDCPA only covers third-party collectors. But several states have laws that apply the same (or similar) protections to original creditors collecting their own debts. The most notable is:

    • California — the Rosenthal Fair Debt Collection Practices Act extends FDCPA-like protections to original creditors, debt buyers, and attorneys. If you’re dealing with a bank’s internal collection department in California, the Rosenthal Act likely applies.

    Other states with broader coverage include:

    • New York — the state’s debt collection regulations (via the Department of Financial Services) impose FDCPA-like requirements on creditors and collectors
    • Florida — has a state Consumer Collection Practices Act that covers original creditors
    • Massachusetts — has regulations covering unfair debt collection practices
    • Pennsylvania, Connecticut, North Carolina, Texas, and others — have various state-level protections

    States that require collectors to be licensed

    Many states require debt collectors to be licensed before they can collect from residents. If a collector is unlicensed in a state that requires licensure, their collection attempts may be illegal — and you may have grounds to dispute the debt and prevent reporting. States with licensure requirements include:

    • California, New York, Florida, Texas, Illinois, Pennsylvania, New Jersey, and many others

    If you’re unsure whether a collector is licensed in your state, you can check with your state’s department of finance, banking, or consumer affairs. An unlicensed collector is a significant red flag — and a potential defense if they sue you.

    State statutes of limitations on debt

    Every state has a statute of limitations — a time limit on how long a creditor or collector has to sue you for a debt. These vary widely:

    • Oral contracts: 2–6 years depending on the state
    • Written contracts: 3–10 years
    • Open accounts (credit cards): 3–6 years in most states

    Once a debt is past the statute of limitations, it is time-barred — a collector cannot legally sue you to collect it. However, the debt still exists, and a collector can still attempt to collect it voluntarily (by calling or writing). What they cannot do is threaten to sue or actually file suit on a time-barred debt — that’s an FDCPA violation.

    If a collector sues you on a time-barred debt, you can raise the statute of limitations as a defense and likely get the case dismissed. You may also have an FDCPA counterclaim for threatening action they cannot legally take.

    How to find your state’s laws

    • Check your state attorney general’s website — most have a consumer protection section with debt collection information
    • Look up your state’s statute of limitations for the type of debt in question
    • Consult a local consumer protection attorney who knows your state’s specific laws

    State law can be more powerful than the FDCPA in some situations — especially when dealing with original creditors or when your state offers higher damage awards or longer statutes of limitations for filing suit.

    Common Mistakes to Avoid

    Even when people know their FDCPA rights, they often make mistakes that weaken their position or forfeit their claims entirely. Here are the most common ones — and how to avoid them.

    1. Not documenting the violations

    Without a record, you don’t have a case. If a collector calls you 20 times in a week and you don’t log the calls, save the voicemails, or note what was said, you have no evidence. Start documenting the moment you realize you’re being harassed. Keep a dedicated log. Save everything.

    2. Sending a cease and desist letter without proof of delivery

    If you send a cease and desist by regular mail and the collector claims they never received it, you have no proof. Always send by certified mail with return receipt. The receipt is your evidence that the letter was delivered.

    3. Missing the 30-day validation window

    The 30-day window is your strongest tool for forcing a collector to verify a debt. If you miss it, you can still dispute — but the collector isn’t required to stop collecting while they respond. Dispute in writing within 30 days of receiving the validation notice whenever possible.

    4. Disputing verbally instead of in writing

    A verbal dispute over the phone is hard to prove. A written dispute — sent by certified mail — creates a paper trail. Always dispute in writing.

    5. Admitting to the debt on a recorded call

    Collectors record their calls. If you admit the debt is yours, that admission can be used against you. You are not obligated to admit or deny a debt on a call. You can say: “I dispute this debt and request validation in writing. Please send me the validation notice.”

    6. Ignoring a lawsuit

    If a collector files a lawsuit against you, do not ignore it. Ignoring a lawsuit leads to a default judgment — which allows the collector to garnish your wages, levy your bank account, or place a lien on your property. Respond to the lawsuit, raise your defenses (including FDCPA violations), and consult an attorney immediately.

    7. Paying a time-barred debt without understanding the consequences

    Making a payment on an old, time-barred debt can restart the statute of limitations in some states — turning a debt the collector can no longer sue over into one they can. Before paying any old debt, understand your state’s rules on restarting the clock. A partial payment, in some states, is enough to restart it.

    8. Believing a collector who says “you’ll go to jail”

    You will not go to jail for a debt. This is a lie, and it’s an FDCPA violation. Do not let fear of arrest drive you to pay a debt you can’t afford or don’t owe.

    9. Failing to check if the collector is licensed

    If your state requires debt collectors to be licensed and the collector is unlicensed, their collection activity may be illegal. Check licensure — it’s a simple step that can dramatically change your leverage.

    10. Not consulting an attorney

    FDCPA cases are almost always taken on contingency. You pay nothing upfront. The collector pays your attorney’s fees if you win. There is no downside to at least consulting an attorney. People who try to handle FDCPA violations alone often leave money and leverage on the table.

    11. Settling for too little

    If you have documented violations, you may be entitled to more than you think. A collector may offer to waive the debt as a “settlement” — but if they violated the FDCPA, you may be entitled to the debt being waived plus a cash payment to you. Don’t accept the first offer without understanding the full value of your claims.

    12. Forgetting about credit reporting

    Stopping the calls is only half the battle. If the collector is still reporting the debt to the credit bureaus, the tradeline is still dragging down your score. Address both the collection conduct and the credit reporting — they’re separate issues under separate laws (FDCPA and FCRA).

    Frequently Asked Questions

    Can a debt collector call my family or employer?

    A debt collector can contact third parties once to obtain your location information (address, phone number, place of employment) — but they cannot mention the debt, and they cannot contact that person again unless they agree to help or the collector believes the information was false. They cannot discuss your debt with your family, friends, neighbors, or employer. If a collector tells your mother you owe money, that’s a violation. If they call your boss to discuss the debt, that’s a violation.

    Can I go to jail for not paying a debt?

    No. Debt is a civil matter, not a criminal one. You cannot be imprisoned for failing to pay a debt. If a collector threatens you with arrest or imprisonment, they are violating the FDCPA. The only rare exception involves criminal contempt of court orders — and even then, the arrest is for contempt, not for the debt itself.

    Can a debt collector garnish my wages without suing me?

    In most cases, no. A collector must first file a lawsuit, win a judgment, and then obtain a court order for wage garnishment. The major exceptions are federal student loans (which can be administratively garnished without a court order), federal taxes (IRS levy), and child support (which can be garnished through administrative processes). If a collector threatens to garnish your wages without a judgment, that’s an FDCPA violation.

    What is the statute of limitations on debt in my state?

    It varies by state and by the type of debt. Credit card debt (an “open account”) is typically 3–6 years; written contracts are 3–10 years. You can find your state’s statute of limitations on your state attorney general’s website or by consulting a local consumer protection attorney. Once a debt is past the statute of limitations, it is “time-barred” — a collector cannot sue you for it, though they can still attempt voluntary collection. Be careful: making a payment on a time-barred debt can restart the clock in some states.

    How much can I recover if I sue a debt collector?

    Under the FDCPA, you can recover statutory damages up to $1,000 (a flat amount per lawsuit, regardless of the number of violations), actual damages (for emotional distress, out-of-pocket costs, lost wages, credit damage), and attorney’s fees and court costs. In class actions, the cap is the lesser of $500,000 or 1% of the collector’s net worth. Many cases settle for more than the statutory minimum, especially when actual damages are documented.

    What should I do if a debt collector sues me?

    Do not ignore the lawsuit. Respond to the complaint (usually within 20–30 days, depending on your state). Raise any defenses you have, including the statute of limitations, lack of standing (if it’s a debt buyer who can’t prove they own the debt), and FDCPA violations as counterclaims. Consult a consumer protection attorney immediately — many will defend collection lawsuits for free on contingency because they can recover their fees from the collector if they win.

    Does the FDCPA cover medical bills?

    Yes. Medical bills are personal debts, and if they are placed with a third-party collection agency or sold to a debt buyer, the FDCPA applies. Medical debt is one of the most common types of debt sent to collections, and medical collectors are subject to the same rules as any other debt collector — no harassment, no false statements, no calls outside 8 a.m. – 9 p.m., validation notices required.

    Can I dispute a debt after the 30-day window?

    Yes. You can dispute a debt at any time. The 30-day window (from the validation notice) gives you the strongest leverage — the collector must stop collecting until they verify the debt. Outside the window, the collector isn’t required to stop collecting while they respond, but you can still dispute with the credit bureaus under the FCRA, and you can still raise the dispute as a defense if the collector sues you. Don’t let the 30-day deadline stop you from acting — it just changes the specific procedural leverage you have.

    Free Credit Audit

    If you’re dealing with collection agency harassment, inaccurate credit reporting, or both, you don’t have to handle it alone. Our San Diego-based, attorney-backed credit repair firm helps clients nationwide understand and enforce their rights under the FDCPA, the FCRA, and applicable state laws.

    We offer a free credit audit — a thorough review of your credit reports from all three major bureaus — to identify:

    • Collection accounts that may be inaccurate, unverifiable, or unlawfully reported
    • Potential FDCPA violations by collectors contacting you
    • FCRA reporting errors that may be dragging down your score
    • Time-barred debts that should not be reported as collectible
    • Opportunities to dispute, validate, and remove items that don’t belong on your report

    We don’t make quick-fix promises. We don’t guarantee specific outcomes. What we do is apply the full scope of federal and state consumer protection law — strategically, transparently, and backed by experienced attorneys — to give you the strongest possible path to cleaner credit and lasting financial health.

    Get your free credit audit at credit-repair.com →

    When you work with us, you gain a long-term financial partner — not just a one-time service. We educate you on your rights, we empower you to maintain strong credit long after the process is complete, and we operate with full compliance with federal law, including the FCRA. Transparent pricing, no hidden fees, no misleading claims.

    Your rights under the FDCPA are real. Your credit is worth protecting. Let’s get to work.

    Disclaimer: This article is for educational purposes and does not constitute legal advice. Your individual situation may vary based on your state’s laws, the specifics of your debt, and the conduct of the collector involved. For advice tailored to your circumstances, consult a licensed attorney in your jurisdiction.

    Related reading:
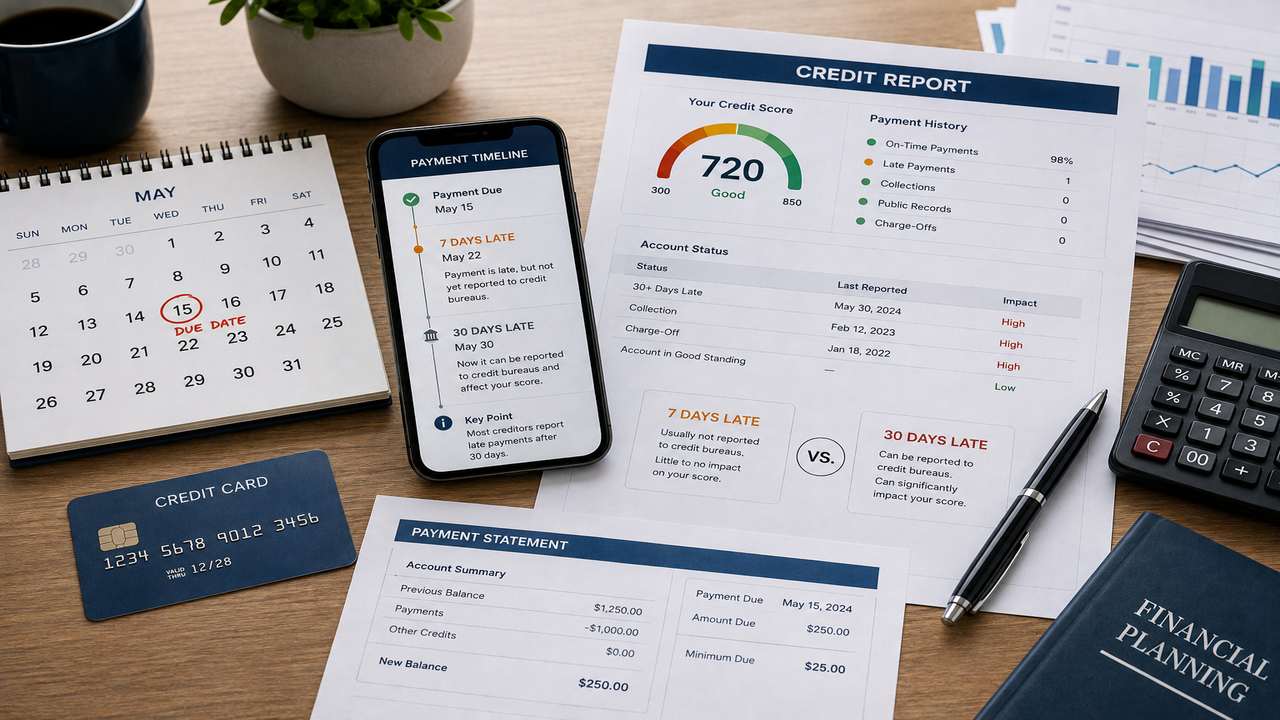
     

  • Credit Score Ranges Explained: Where Do You Stand?

    Credit Score Ranges Explained: Where Do You Stand?

    If you have ever applied for a credit card, financed a car, or shopped for a mortgage, you have run into the three-digit number that can quietly open doors or close them: your credit score. Lenders use it to decide whether to approve you, what interest rate to offer, and sometimes whether to trust you with an apartment lease or a cell phone plan. Yet most people are never taught what the credit score ranges actually mean, where the cut-offs sit, or how to climb from one tier to the next.

    That knowledge gap is costly. A score in the fair credit range instead of the good credit range can add tens of thousands of dollars in extra interest over the life of a mortgage. A score in the poor credit range can keep you from being approved at all. The good news is that credit scores are not fixed stars. They move in response to how you manage credit, and understanding the ranges is the first step to moving yours in the right direction.

    This guide breaks down the credit score ranges for both major scoring models in the United States — FICO and VantageScore — explains what each tier means for your wallet, and gives you a practical, tier-by-tier plan for climbing higher. We keep things honest: no “secret tricks,” no overnight-fix promises. What you will get instead is the transparent, legally grounded guidance we give every client at our San Diego-based, FCRA-compliant, attorney-backed credit repair firm.

    What Credit Score Ranges Are

    A credit score range is the spread of possible numerical values a scoring model can assign to a consumer, divided into named bands or credit score tiers. Each tier corresponds to a level of credit risk: the higher the score, the lower the perceived risk to a lender, and the better the terms you are likely to be offered.

    Think of a credit score range as a ladder. The bottom rung represents the highest risk and the worst borrowing terms; the top rung represents the lowest risk and the best terms. Most consumers land somewhere in the middle, which is why the “good” and “fair” tiers get so much attention — they are where the majority of Americans live, and they are also where the most dramatic improvement is usually possible.

    Why do ranges matter? Because lenders rarely quote a single interest rate to everyone. They price risk. A borrower in the excellent credit range might qualify for a 6.5% APR on a personal loan, while a borrower in the fair range might be quoted 15% or higher for the exact same loan from the exact same lender. Over a five-year repayment, that gap can mean thousands of dollars.

    Ranges also matter because they set the mental benchmarks consumers use when setting goals. “I want to hit 700” is a common target because 700 sits solidly in the good tier for most models and unlocks meaningfully better offers. “I just need to get above 620” is another common goal because 620 is the rough threshold many mortgage lenders use for conventional loan eligibility. Knowing the ranges helps you set a goal that is tied to a real-world outcome, not just an arbitrary number.

    The Basic Structure of a Credit Score Range

    Both major U.S. scoring models use a 300 to 850 scale for their general-purpose scores. That means the lowest possible score is 300 and the highest is 850. Within that span, each model defines its own tier cut-offs:

    • Poor (or Very Poor / Deep Subprime)
    • Fair (or Subprime)
    • Good (or Prime)
    • Very Good (or Superprime, in VantageScore terminology)
    • Exceptional (or Excellent)

    The exact numerical boundaries differ slightly between FICO and VantageScore, which is why we cover each separately below. Some industry-specific scores (auto, bankcard) use different scales, which we address in the industry-specific section.

    Why Two Models Exist

    The credit scoring industry is dominated by two competitors. FICO (developed by the Fair Isaac Corporation) is the older and more widely used model, especially in mortgage lending. VantageScore (developed jointly by the three major credit bureaus — Equifax, Experian, and TransUnion) is newer and is often the score you see in free credit-monitoring apps and on credit card statements.

    Because the two models weigh factors slightly differently and sometimes use different tier boundaries, a consumer can have a FICO score of 712 (good) and a VantageScore of 698 (also good, but on a different boundary). Both are “real” scores; neither is more correct than the other. What matters is knowing which model a given lender uses — and understanding the ranges for both.

    The Two Main Scoring Models: FICO and VantageScore

    Before we get into the tier-by-tier breakdown, it helps to understand how each model is built. The ranges are only meaningful once you know what moves the number inside them.

    FICO: The Mortgage Standard

    FICO is the scoring model you will encounter most often in high-stakes lending. When you apply for a conventional mortgage, a FHA loan, an auto loan, or a new credit card, there is a strong chance the lender is pulling a FICO score — often a specific FICO variant tailored to that product.

    FICO’s base scoring factors (roughly weighted):

    • Payment history — 35%: whether you have paid past credit accounts on time. This is the single biggest lever.
    • Amounts owed — 30%: how much of your available credit you are using, especially revolving credit. This is your credit utilization ratio.
    • Length of credit history — 15%: how long your accounts have been open, including the age of your oldest account and the average age of all accounts.
    • Credit mix — 10%: the variety of account types you manage (revolving, installment, mortgage).
    • New credit — 10%: how many recent inquiries and new accounts you have. Too many in a short window signals risk.

    FICO updates its models periodically (FICO 8, FICO 9, and the newer FICO 10/T are all in circulation), but the 300–850 scale and the five-tier structure have remained stable across recent generations.

    VantageScore: The Bureau-Built Alternative

    VantageScore was created by the three credit bureaus to compete with FICO and to produce a score even when a consumer has a thinner credit file. The current generation in wide use is VantageScore 4.0, which also uses the 300–850 scale.

    VantageScore’s scoring factors (roughly weighted):

    • Payment history — ~40%: the dominant factor, similar to FICO.
    • Credit utilization and balances — ~20%: how much you owe relative to your limits.
    • Credit mix and experience — ~20%: the variety of account types and how long you have managed them.
    • Credit age — ~15%: the age of your accounts.
    • Recent credit behavior — ~5%: inquiries and new accounts.

    VantageScore tends to be more forgiving of thin credit files and can produce a score with fewer accounts than FICO requires. It also treats certain negative items (like paid collections and medical collections) more leniently in its newer generations, which can push a consumer up a tier relative to their FICO score.

    Which Score Will a Lender See?

    There is no universal answer. A mortgage lender will typically pull a tri-merge of FICO scores — one from each bureau, using a FICO model specifically designed for mortgage risk (often FICO 2, FICO 4, or FICO 5, depending on the bureau). An auto lender might pull an auto-enhanced FICO that weights your past auto-loan behavior more heavily. A credit card issuer might use FICO 8 or FICO Bankcard. A free credit app is probably showing you a VantageScore.

    This is why your “score” can differ by 20, 40, or even 60 points depending on who is looking. The ranges below give you the framework to interpret any of them.

    FICO

    Score Ranges: A Detailed Breakdown

    FICO’s base scores (FICO 8 and FICO 9 are the most common) use the following tier boundaries. These are the ranges most lenders and consumers reference when they talk about “your FICO score.”

    FICO Tier Score Range Share of U.S. Consumers (approx.)
    Exceptional 800–850 ~21%
    Very Good 740–799 ~25%
    Good 670–739 ~21%
    Fair 580–669 ~18%
    Poor 300–579 ~15%

    Exceptional (800–850)

    An exceptional FICO score tells a lender you are an extremely low risk. You have a long, spotless payment history, low utilization, a mature credit mix, and no recent negative marks. At this level, you are effectively at the front of the line for the best offers a lender has. Denial is almost unheard of for new credit unless there is an income or fraud issue. Interest rates are typically the lowest the lender publishes.

    Very Good (740–799)

    A very good FICO score still puts you in the top tier for most practical purposes. The difference between 740 and 800 is usually invisible at the cash register — both qualify you for the best advertised mortgage rates and top-tier credit card offers. The main benefit of climbing from very good to exceptional is psychological and marginal: a little more cushion if a negative event (a late payment, a new hard inquiry) ever lands on your file.

    Good (670–739)

    A good FICO score means you are a solid, acceptable risk. You will be approved for most credit cards and auto loans, and you will generally qualify for conventional mortgage financing (most conventional mortgage programs use a 620–640 floor, so 670 clears it comfortably). Your interest rates, however, will be noticeably higher than what an exceptional borrower pays. This is the tier where many consumers first notice that “good” is not quite “great” when the monthly payment is calculated.

    Fair (580–669)

    A fair FICO score is the tier where borrowing starts to get uncomfortable. You may still qualify for credit, but the terms tighten: higher APRs, lower credit limits, and more denials. A 580 score is the minimum for an FHA mortgage with the standard 3.5% down payment, so consumers in the lower half of this tier often rely on government-backed loan programs rather than conventional financing. Credit card offers in this tier tend to come with annual fees, high APRs, and smaller credit lines — and secured cards become a realistic rebuilding tool.

    Poor (300–579)

    A poor FICO score reflects significant credit risk in the eyes of a lender. This tier is commonly associated with recent late payments, accounts in collections, high utilization, charged-off accounts, or a combination of these. Traditional unsecured credit is very difficult to obtain at this level. Consumers in the poor range are often limited to secured credit cards, credit-builder loans, or subprime auto financing with very high rates. The encouraging news: this is also the tier where disciplined, structured repair produces the fastest absolute point gains, because removing even one or two negative marks can move a score up by dozens of points.

    VantageScore Ranges: A Detailed Breakdown

    VantageScore 3.0 and 4.0 use the same 300–850 scale as FICO but draw the tier boundaries at slightly different points. The names also differ: VantageScore uses “Superprime” instead of “Exceptional,” for example.

    VantageScore Tier Score Range Share of U.S. Consumers (approx.)
    Superprime 781–850 ~45%
    Prime 661–780 ~22%
    Near Prime 601–660 ~13%
    Subprime 500–600 ~13%
    Deep Subprime 300–499 ~7%

    Superprime (781–850)

    A superprime VantageScore is the top tier and signals very low risk. Consumers here enjoy the best rates and the broadest approval odds across product types. Because VantageScore’s superprime band starts lower than FICO’s exceptional band (781 vs. 800), a consumer can be “superprime” by VantageScore standards while sitting in FICO’s “very good” tier. This is a common source of confusion when comparing scores across models.

    Prime (661–780)

    A prime VantageScore is a healthy, lender-friendly score. Consumers in this band are generally approved for credit cards, auto loans, and mortgages, and qualify for competitive — though not always the absolute lowest — interest rates. The 661 lower boundary is meaningfully lower than FICO’s 670 “good” boundary, which is why a VantageScore often looks a few points more favorable than a FICO score for the same consumer.

    Near Prime (601–660)

    A near prime VantageScore corresponds roughly to the upper half of FICO’s fair tier. Borrowers here may qualify for credit but typically at higher rates and with smaller limits. This is a transitional band — consumers in near prime are usually only a few good habits (and a few months) away from crossing into prime, where terms improve noticeably.

    Subprime (500–600)

    A subprime VantageScore maps to the lower half of FICO’s fair tier and the upper portion of FICO’s poor tier. Borrowers in this band face real headwinds: higher APRs, more denials, and a heavier reliance on secured products and government-backed loan programs. Like FICO’s poor tier, this is a band where structured repair work can produce meaningful gains.

    Deep Subprime (300–499)

    A deep subprime VantageScore reflects the highest perceived risk. Borrowers in this band typically have multiple serious negative items — recent late payments, collections, charge-offs, public records, or a combination. Traditional credit is largely unavailable, and the path forward usually starts with secured credit products and a deliberate, multi-month rebuilding plan.

    FICO vs. VantageScore Ranges: Side-by-Side Comparison

    Because the two models use the same 300–850 scale but draw boundaries differently, it is easy to misread your standing if you do not know which score you are looking at. The table below places the two sets of tiers side by side so you can compare directly.

    Risk Level FICO Tier FICO Range VantageScore Tier VantageScore Range
    Lowest risk Exceptional 800–850 Superprime 781–850
    Low risk Very Good 740–799 Superprime 781–850
    Moderate-low risk Good 670–739 Prime 661–780
    Moderate risk Fair 580–669 Near Prime 601–660
    Higher risk Fair / Poor (border) 580–669 Subprime 500–600
    Highest risk Poor 300–579 Deep Subprime 300–499

    A Few Patterns Are Worth Noting

    • VantageScore’s top tier starts earlier. A 785 is superprime under VantageScore but only “very good” under FICO. If a free app shows you a 790 VantageScore, do not assume your FICO is also in the exceptional band — it may sit at 760.
    • VantageScore draws the prime line lower than FICO draws the good line. A 665 is prime under VantageScore but only fair under FICO. This is a frequent reason consumers feel “better” looking at their VantageScore than their FICO.
    • The lower boundary differs. FICO’s poor tier starts at 579 and below; VantageScore’s deep subprime starts at 499 and below. A consumer at 540 is “poor” under FICO but “subprime” (one tier higher) under VantageScore.

    The practical takeaway: when a lender tells you their minimum score requirement, always ask which model and which generation they use. A “620 minimum” almost always refers to a FICO score in mortgage lending; a “660 minimum” on a credit card pre-qualification tool may well reference VantageScore.

    What Each Tier Means for Borrowing, Rates, and Approvals

    Knowing the range is only half the picture. The other half is understanding what each tier actually buys you in the real world — what lenders will approve, what rates they will quote, and what you will pay over time. Below we translate each tier into concrete borrowing outcomes.

    Exceptional / Superprime (Top Tier)

    • Mortgages: You qualify for the lowest advertised rates. On a conventional 30-year mortgage, the difference between a top-tier rate and a good-tier rate can be 0.25% to 0.75%. On a $400,000 loan, that is roughly $60–$180 per month — and $20,000–$65,000 over the life of the loan.
    • Auto loans: You qualify for the manufacturer’s advertised promotional APRs, often 0%–3.99% for well-qualified buyers.
    • Credit cards: You receive pre-qualified offers for premium rewards cards, low ongoing APRs, large credit limits, and sign-up bonuses.
    • Approvals: Near-certain for any standard product, assuming income supports the debt.

    Very Good (FICO) / Upper Superprime (VantageScore)

    • Mortgages: You still qualify for the best or near-best rates. The practical difference from exceptional is minimal.
    • Auto loans: You qualify for top-tier promotional rates.
    • Credit cards: Premium cards remain well within reach.
    • Approvals: Very high. Denial is rare and usually tied to income or a recent negative item rather than the score itself.

    Good / Prime

    • Mortgages: You qualify for conventional financing. Rates run a quarter to half a point above the best available.
    • Auto loans: You are approved, but the lowest promotional APRs may be just out of reach. Expect rates a point or two above top-tier offers.
    • Credit cards: You qualify for most mid-tier rewards cards. The most competitive premium cards may be borderline depending on the issuer.
    • Approvals: High, but you may face smaller credit limits and slightly more scrutiny on income and debt-to-income ratio.

    Fair / Near Prime

    • Mortgages: Conventional loans become difficult. FHA loans (minimum 580 FICO for 3.5% down) are the typical path. You may face higher mortgage insurance costs.
    • Auto loans: You are approved, but rates climb sharply — often 8% to 15% or higher depending on the lender and the vehicle.
    • Credit cards: Unsecured cards are available but come with higher APRs, lower limits, and possible annual fees. Secured cards are a strong rebuilding option.
    • Approvals: Mixed. You will be approved by some lenders and declined by others, especially for premium products.

    Poor / Subprime / Deep Subprime

    • Mortgages: Traditional conventional and FHA financing is generally out of reach until the score improves. Specialized programs (manual underwriting, certain non-prime lenders) may exist but at significantly higher rates.
    • Auto loans: Subprime auto financing is available but rates can exceed 20%. Down payments are usually required.
    • Credit cards: Unsecured cards are largely unavailable. Secured credit cards and credit-builder loans are the primary tools for rebuilding.
    • Approvals: Limited. Expect denials on most standard credit products and a reliance on secured or alternative lenders.

    How to Move Up from One Tier to the Next

    This is where most consumers want the “secret.” There is no secret — but there is a reliable, repeatable process. The same factors that pull a score down are the levers that push it up. Below is tier-by-tier, actionable guidance for climbing the ladder.

    From Poor to Fair

    If you are in the poor credit range (FICO 300–579, VantageScore 300–600), your score is being held down by specific, identifiable items — not by some abstract “bad luck.” The priority is removing or neutralizing those items.

    1. Pull all three bureau reports. You are entitled to a free report from each bureau every week at AnnualCreditReport.com. Pull Equifax, Experian, and TransUnion so you can see the full picture.
    2. Audit for errors. According to a Federal Trade Commission study, roughly one in five consumers has an error on at least one credit report serious enough to affect their score. Look for accounts that are not yours, incorrect late-payment notations, outdated balances, and duplicate entries. Every error you successfully dispute is a potential score gain.
    3. Dispute inaccurate negative marks under the FCRA. The Fair Credit Reporting Act gives you the right to dispute any item you believe is inaccurate, incomplete, or unverifiable. The bureaus must investigate within 30 days (45 in some cases) and remove anything they cannot verify. This is the legal backbone of credit repair.
    4. Address legitimate negative items. For accurate negative marks, explore options: pay-for-delete agreements with creditors on smaller collections, goodwill letters asking a long-standing creditor to remove a one-time late payment, and negotiated settlements on charged-off accounts.
    5. Open a secured credit card. A secured card (with a $200–$500 deposit) reports to the bureaus just like an unsecured card. Using it for a small recurring charge and paying it in full each month establishes a fresh positive payment record.
    6. Consider a credit-builder loan. These small installment loans hold the borrowed funds in a savings account while you make payments, building both payment history and an installment account in your credit mix.

    The combination of removing negative items and adding positive payment history is the fastest reliable path out of the poor tier. Many of our clients see meaningful movement within 60–90 days of starting structured repair work, though individual results vary and no specific outcome can be guaranteed.

    From Fair to Good

    Once you are in the fair credit range, the heavy negative items are usually fewer, and the levers shift toward utilization and consistency.

    1. Drive down credit card balances. Utilization is recalculated every time a new balance is reported — usually monthly. Paying a card from 80% utilized to under 30% can produce a noticeable score increase the next cycle.
    2. Aim for under 10% utilization on each card. The biggest utilization gains come from getting each individual card below 10%, not just the aggregate. If one card is maxed and others are at zero, that one card still drags the score.
    3. Never miss a payment. At this tier, a single 30-day late mark can undo months of progress. Set auto-pay for at least the minimum on every account.
    4. Avoid new hard inquiries unless necessary. Each hard inquiry can cost a few points. In the fair tier, you want every point working in your favor.
    5. Keep old accounts open. Closing an older card shortens your average account age and reduces your total available credit — both of which can lower your score.

    From Good to Very Good

    Moving from good to very good is a matter of refinement. The big levers have already been pulled; now you are optimizing.

    1. Maintain long-term low utilization. Keep your reported balances consistently under 10%.
    2. Let your accounts age. Time is a scoring factor you cannot rush, but you can protect it by avoiding unnecessary new accounts and keeping your oldest cards open and lightly used.
    3. Diversify your credit mix thoughtfully. If you only have revolving credit, a well-managed installment loan (auto, personal, or mortgage) can add points over time. Do not take on debt you do not need just for the mix — but if you are already financing a car, that installment account is helping.
    4. Pay down installment loans. For installment loans, paying down the principal reduces the “original loan amount vs. current balance” ratio, which VantageScore and newer FICO models reward.

    From Very Good to Exceptional

    The jump from very good to exceptional is the slowest and least urgent. The practical benefits are marginal — you already qualify for top-tier offers. The remaining gains come from patience: continued perfect payments, aging accounts, and avoiding any new negative marks. Most consumers who reach exceptional do so by simply maintaining very good habits for several more years.

    credit-score-ranges-explained-under-100kb

    How Long It Takes to Climb Between Tiers

    There is no universal timeline, because every credit file is different. But general patterns hold, and setting realistic expectations helps you stay motivated.

    Poor to Fair: 2–6 months

    This is often the fastest tier-to-tier climb, especially if your poor score is driven by a small number of correctable items. Successful disputes, pay-for-delete agreements, and the establishment of a single new positive account (a secured card) can move a score from the 500s to the low 600s within a few reporting cycles. If the file has extensive, recent negative items (a recent bankruptcy, multiple fresh collections), the climb takes longer — often 12–24 months.

    Fair to Good: 6–18 months

    This climb is steadier. It usually involves paying down balances to consistently low utilization and accumulating 6–12 months of flawless payment history. If a single significant negative item (like a 30-day late from a year ago) is still aging, expect the climb to accelerate once that item crosses the 12- or 24-month mark.

    Good to Very Good: 12–24 months

    This is a patience tier. You are optimizing, not rescuing. Continued low utilization, no new negatives, and the slow aging of your accounts produce gradual upward movement. Most consumers reach very good by simply maintaining good habits for another year or two.

    Very Good to Exceptional: 2–5 years

    This is the slowest transition and is largely a function of account age and the total absence of negative marks. Consumers who reach exceptional typically have 7–10+ years of credit history and zero recent derogatory items. There is no shortcut — only consistency.

    Special Case: Bankruptcy

    A Chapter 7 bankruptcy stays on your report for 10 years; a Chapter 13 for 7 years. The score impact is most severe in the first two years, after which it gradually lessens. Many consumers see their scores recover into the fair and then good range within 3–5 years post-discharge, provided they establish new positive credit and avoid new negative marks. This is a marathon, not a sprint, and it is one of the situations where professional, FCRA-compliant guidance is most valuable.

    What Pulls You Down a Tier

    Understanding the downward forces is just as important as knowing the upward ones. Here are the most common reasons consumers drop from one tier to the next.

    Late Payments

    A single 30-day late payment can drop a good score by 60–80 points, especially if your history was previously spotless. The higher your score, the bigger the drop from a first late. A 60- or 90-day late is more severe and lingers longer in the scoring models.

    High Credit Utilization

    Utilization is the second-biggest factor, and it is dynamic — it updates with each monthly balance report. Maxing out a card (or coming close) can drop a score 20–40 points in a single cycle, even with no late payments. The good news: bringing the balance back down restores the score just as quickly.

    Collections and Charge-Offs

    An account sent to collections or charged off by the original creditor is a serious negative mark. Even a small medical bill sent to collections can cost 50–100 points depending on your starting score. Newer scoring models (FICO 9, VantageScore 4.0) discount paid collections and smaller medical collections, but older models still in wide use (FICO 8) do not.

    New Hard Inquiries in Clusters

    A single hard inquiry typically costs 1–5 points and fades in 12 months. But a cluster of inquiries in a short window — say, applying for four credit cards in two months — signals risk and can compound the score impact, especially for thinner files.

    Closing Old Accounts

    Closing an older card does not immediately remove it from your report (it continues to age for up to 10 years), but it does reduce your total available credit immediately, which can spike your utilization ratio and lower your score.

    Applying for Too Much New Credit

    A burst of new accounts lowers your average account age and adds inquiries, both of which can pull a score down temporarily. The effect is usually modest and recovers within 6–12 months, but it can be enough to nudge you across a tier boundary at exactly the wrong moment — like right before a mortgage application.

    Public Records

    A civil judgment or tax lien (when still reportable — standards have tightened in recent years) is a serious negative mark. Bankruptcies, as noted above, are the most impactful and longest-lasting.

    Industry-Specific Scores: Auto-Enhanced and Bankcard Scores

    The 300–850 ranges we have covered apply to general-purpose credit scores. But many lenders use industry-specific scores that are tuned for the product they are underwriting. These scores have their own ranges — sometimes the same 300–850, sometimes different.

    FICO Auto Scores

    FICO Auto Scores are used by many auto lenders. They weigh your past auto-loan and auto-lease history more heavily than a base FICO score would. If you have always paid your car loan on time but had some credit card stumbles, your Auto Score may be higher than your base score.

    • Range: 250–900 (wider than the base 300–850 range)
    • Use case: Auto loan origination and refinancing
    • What it means for ranges: The tiers are roughly shifted. A “good” Auto Score might sit around 660–720, slightly different from the base FICO good tier. Always ask the dealer which score they are pulling.

    FICO Bankcard Scores

    FICO Bankcard Scores are used by credit card issuers. They weigh your history with revolving credit more heavily.

    • Range: 250–900
    • Use case: Credit card underwriting and limit assignment
    • What it means for ranges: As with Auto Scores, the tier boundaries are shifted relative to the base score. A Bankcard Score of 680 may correspond to a slightly different risk band than a base FICO of 680.

    VantageScore Industry Scores

    VantageScore also offers industry-specific variants for auto and credit card lending, though these are less commonly discussed than FICO’s. The same principle applies: the score is tuned for the product, and the tier boundaries may not line up exactly with the general-purpose VantageScore ranges.

    Mortgage Scores

    Mortgage lending deserves special mention. Most conventional and FHA lenders pull a tri-merge of older FICO models — typically FICO Score 2 (Experian), FICO Score 4 (TransUnion), and FICO Score 5 (Equifax). These older models use the 300–850 scale but can produce scores somewhat different from FICO 8 or 9, particularly because they treat certain credit mix and utilization factors differently.

    If you are planning a major purchase — a home, a car, a balance-transfer credit card — it is worth asking the prospective lender which specific score they will pull. That way you can focus your preparation on the model that actually matters for that decision.

    Common Myths About Credit Score Ranges

    A surprising amount of bad advice circulates about credit scores. Here are the myths we hear most often, and the reality behind each.

    Myth 1: “Checking my credit score lowers it.”

    False. Checking your own score or pulling your own report is a soft inquiry, which has zero impact on your score. Only hard inquiries — those initiated by a lender evaluating you for new credit — can affect your score, and even then only slightly.

    Myth 2: “Closing a paid-off card helps my score.”

    Usually false. Closing a card reduces your total available credit, which can raise your utilization ratio and lower your score. It also eventually shortens your account-age history. In most cases, it is better to keep a paid-off card open and use it occasionally for a small charge you pay in full.

    Myth 3: “Carrying a small balance builds credit faster.”

    False. You do not need to carry a balance or pay interest to build credit. The scoring models reward on-time payments and low utilization — both of which are achieved by paying your statement balance in full each month. Carrying a balance only costs you interest and, if the balance is high relative to your limit, can actually hurt your score.

    Myth 4: “My income is part of my credit score.”

    False. Credit scoring models do not consider income, salary, or net worth. Lenders consider income separately, as part of their underwriting (debt-to-income ratio, ability to repay). Your score reflects how you have managed credit, not how much money you make.

    Myth 5: “Negative items fall off after seven years — automatically.”

    Mostly true, with caveats. Most negative items (late payments, collections, charge-offs) fall off after seven years; Chapter 7 bankruptcies after ten. But they do not always disappear on schedule — a creditor may re-report, or a collection may be re-aged if mishandled. It is worth checking your reports periodically to confirm old items have been removed.

    Myth 6: “Paying off a collection instantly removes it from my report.”

    Usually false. Paying or settling a collection updates the balance to zero, but the collection record typically remains on your report for up to seven years from the original delinquency date. The newer scoring models (FICO 9, VantageScore 4.0) ignore paid collections, so paying can help your score under those models — but the item may still be visible on your report. A pay-for-delete agreement, where the collector agrees to remove the item in exchange for payment, is the way to actually clear the item from the report.

    Myth 7: “Credit repair is illegal.”

    False. Credit repair is a legal, regulated activity under the Credit Repair Organizations Act (CROA), which sets rules for how credit repair companies must operate. Legitimate, FCRA-compliant credit repair — disputing inaccurate, incomplete, or unverifiable items — is your right under federal law. What is illegal is a company promising guaranteed results or asking you to misrepresent information to the bureaus.

    Myth 8: “A higher salary moves you into a higher tier.”

    False, for the same reason as Myth 4. Tiers are determined by your credit behavior, not your income. A high earner with missed payments can sit in the poor tier; a modest earner with long, flawless credit history can sit in the exceptional tier.

    Frequently Asked Questions

    1. What is the difference between a credit score and a credit report?

    Your credit report is a detailed record of your credit history — every account, its status, your payment history, balances, inquiries, and public records. Your credit score is a three-digit number calculated from the information in your report. The report is the underlying data; the score is a summary of the risk that data represents. You can have different scores from different models, all calculated from the same underlying report.

    2. Which credit score range matters most?

    The one your prospective lender uses. For mortgages, that is almost always a FICO score (and often an older FICO model). For many credit cards and free monitoring apps, it is a VantageScore. For auto loans, it may be a FICO Auto Score. Knowing the product you are shopping for tells you which score to focus on.

    3. Can I have a score above 850?

    On the standard base FICO and VantageScore scales, no — 850 is the ceiling. Some industry-specific scores (FICO Auto, FICO Bankcard) go up to 900, but those are different scales used only for specific products. For general-purpose credit, 850 is the maximum.

    4. How often does my credit score change?

    Potentially every time a new piece of information is reported to the bureaus — which for most active accounts means once a month. If you pay down a credit card balance, your score can move the next time that card reports. If a late payment lands, your score can drop the next reporting cycle. Scores are dynamic, not static.

    5. Does the credit score range I am in affect my insurance rates?

    In many states, yes. Insurers in many jurisdictions use a credit-based insurance score — derived from credit report data but calculated with a different model — to help set auto and home insurance premiums. A lower score can mean higher premiums in states where the practice is permitted. Several states (California, Hawaii, Massachusetts, and others) restrict or prohibit the practice for certain insurance types.

    6. What is a “good” credit score for a mortgage?

    For a conventional mortgage, most lenders look for a FICO score of at least 620, though some programs accept lower. For an FHA loan, the minimum is 580 for the standard 3.5% down payment (or 500 with a 10% down payment in some cases). To get the best advertised mortgage rates, you generally need a FICO score of 740 or higher.

    7. Will disputing an error on my report hurt my score?

    No. Filing a dispute does not affect your score. While an item is under investigation, it remains on your report. If the bureau verifies the item, it stays and your score is unchanged. If the bureau cannot verify it and removes it, your score may go up. There is no downside to disputing items you genuinely believe are inaccurate.

    8. How long do hard inquiries stay on my report?

    Hard inquiries remain on your report for two years, but their scoring impact fades after about 12 months. Most consumers see the point impact disappear entirely within a year. Rate-shopping for a single product (a mortgage or auto loan) within a focused window — typically 14–45 days depending on the model — is usually treated as a single inquiry for scoring purposes, so shopping around does not multiply the impact.

    Take the Next Step With a Free Credit Audit

    Knowing the credit score ranges is the first step. Knowing where you stand — and exactly what is holding your score where it is — is the step that actually changes things.

    At our San Diego-based, FCRA-compliant, attorney-backed credit repair firm, we start every relationship with a free, no-obligation three-bureau credit audit. We pull your reports from Equifax, Experian, and TransUnion, walk you through every item line by line, identify inaccuracies and negative marks that may be dragging your score down, and give you a clear, honest picture of where you stand and what is possible.

    You do not have to figure this out alone, and you do not have to settle for a score that is costing you money every month in higher interest rates. Whether you are working toward a mortgage, refinancing a car, or simply want to stop overpaying for credit, the path starts with knowing your numbers.

    Schedule your free credit audit at credit-repair.com — no pressure, no quick-fix promises, just a transparent, legally grounded plan for moving your score where it needs to be.

    Disclaimer: This article is provided for educational purposes only and is not legal or financial advice. Individual credit outcomes vary based on the specifics of each credit file. No specific score improvement or timeline is guaranteed. Our services operate in full compliance with the Fair Credit Reporting Act (FCRA) and the Credit Repair Organizations Act (CROA).

  • Credit Utilization Calculator: Find Your Ideal Balance

    Credit Utilization Calculator: Find Your Ideal Balance

    If you’ve ever stared at a credit card statement and wondered, “How much of my credit limit should I actually be using?” — you’re asking exactly the right question. That single number, your credit utilization ratio, is the second-most influential factor in your credit scores (behind payment history alone). It can swing your scores by dozens of points in either direction, and yet most people have never calculated it for themselves.That’s the gap this guide closes. Below, you’ll find a complete, plain-language explanation of what credit utilization is, the exact formula for calculating it, step-by-step worked examples for single cards, multiple cards, and mixed-balance scenarios, a fill-in worksheet you can use by hand, interpretation of your results, a target-balance lookup table for common credit limits, mid-cycle payment strategies, the math behind credit limit increases, the most common calculation mistakes, and a full FAQ. By the end, you’ll be able to calculate your utilization in under two minutes — and, more importantly, know exactly what to do with that number.This is the same guidance we walk every client through during a free credit audit at credit-repair.com. We’re a San Diego-based, FCRA-compliant, attorney-backed credit repair firm, and we believe the best results come from understanding the mechanics — not from quick fixes or empty promises. Everything below is grounded in how the credit reporting system actually works.

    What Is Credit Utilization — and Why Calculating It Matters

    Credit utilization is the percentage of your available revolving credit that you’re currently using. “Revolving credit” means credit cards and lines of credit — accounts where the balance goes up and down as you borrow and repay. Installment loans (auto loans, mortgages, student loans) are not part of utilization, because those balances only go down over a fixed term.

    Think of it as a ratio: how much you owe divided by how much you’re allowed to borrow. If you have a $10,000 credit limit and you carry a $2,000 balance, you’re using 20% of your available credit. That 20% is your utilization ratio.

    Why does this number matter so much? Because it’s one of the few parts of your credit profile you can change within a single billing cycle. Payment history takes years to build. Age of accounts only grows with time. New inquiries stay on your report for two years. But utilization updates every time your card issuer reports your balance to the credit bureaus — usually once a month, shortly after your statement closes. Drop your balance, and your utilization (and often your scores) can improve within 30 days.

    The two utilization numbers you need to know

    There are actually two utilization figures that influence your credit:

    • Overall utilization — your total balances across all revolving accounts, divided by your total credit limits across all revolving accounts. This is the headline number most people refer to.
    • Per-card utilization — the balance on a single card divided by that card’s limit. Each card has its own ratio, and scoring models look at both the aggregate and the individual card-level numbers.

    A common surprise: you can have a healthy overall utilization but still be penalized because one card is maxed out. If you have three cards each with a $5,000 limit and you carry a $4,500 balance on one while the other two sit at zero, your overall utilization is 30% ($4,500 / $15,000) — which looks okay at a glance — but that one card is at 90%, and most scoring models will dock you for it. This is why calculating both figures matters.

    Why a “calculator” approach beats guessing

    People guess at their utilization constantly, and they’re usually wrong in one of two ways:

    • They use their current balance (what they see in the app today) instead of the statement balance that actually gets reported to the bureaus. More on this distinction in the mid-cycle payment section — it’s a big deal.
    • They forget about cards they rarely use. A $0 balance on a card still counts toward your total available credit, which lowers your overall utilization. But if that card is closed or the issuer reduces the limit, your ratio jumps overnight. Knowing your real denominator — the sum of every revolving limit — requires actually listing every account.

    A calculator approach forces you to gather the real numbers. That’s the value. You’re not estimating; you’re measuring. And once you’ve measured, you can plan.

    The Credit Utilization Formula, Explained Step by Step

    The formula is simple. The discipline is in gathering the inputs.

    The core formula

    Credit Utilization (%) = (Total Balance ÷ Total Credit Limit) × 100

    In words: divide what you owe by what you’re allowed to borrow, then multiply by 100 to express it as a percentage.

    Step 1: Gather your balances

    Log in to every revolving credit account you have — every credit card, every store card, every personal line of credit. For each one, note the current balance. If you’re trying to predict what will be reported to the bureaus (which is what affects your scores), use the statement balance — the balance on the day your statement closes — rather than the balance you happen to see mid-cycle. We’ll cover this distinction in depth later, but for now: use the most recent statement balance for each card if you want to estimate what’s on your credit report.

    Sum these balances. That’s your Total Balance.

    Step 2: Gather your credit limits

    For each of those same accounts, note the credit limit — the maximum amount you’re approved to borrow. For charge cards that have no preset spending limit (certain American Express cards, for example), this gets nuanced; most scoring models use your highest recent balance or a “preset” limit the issuer reports, and some exclude these cards from utilization entirely. For simplicity, include only cards that report a definite credit limit.

    Sum these limits. That’s your Total Credit Limit — your denominator.

    Step 3: Divide and convert

    Divide Total Balance by Total Credit Limit. You’ll get a decimal (0.20, for instance). Multiply by 100 to get a percentage (20%).

    Step 4: Repeat per card

    To get your per-card utilization, run the same formula on each card individually: that card’s balance divided by that card’s limit, times 100. Don’t sum across cards for this step — you want one ratio per account.

    A note on rounding

    Credit scoring models don’t care whether your utilization is 19.7% or 20.1% — they bucket you into ranges. So don’t obsess over decimal places. Round to the nearest whole percent. The buckets that matter are explained in the What Your Result Means section below.

    How to Calculate Per-Card and Overall Utilization

    The best way to learn the formula is to see it worked through real examples. Below are three worked scenarios of increasing complexity, each shown as a table so you can follow the arithmetic.

    Worked Example A: A Single Credit Card

    Let’s start with the simplest case — one card, one balance, one limit.

    Item Value
    Credit card balance $640
    Credit card limit $4,000
    Calculation $640 ÷ $4,000 = 0.16
    Utilization 16%

    In this example, you’re using 16% of your available credit on this single card. Because there’s only one card, your per-card utilization and your overall utilization are identical — both are 16%.

    What this means: 16% falls in the “good” range (10–29%). It’s not hurting your scores meaningfully, but it’s not optimal either. Bringing it under 10% — a balance below $400 on this card — would likely give you a small bump. We’ll come back to this in the interpretation section.

    Worked Example B: Multiple Cards, Evenly Used

    Now let’s look at three cards, each used at a similar rate. This is where per-card versus overall becomes interesting.

    Card Balance Credit Limit Per-Card Utilization
    Card A $300 $3,000 10%
    Card B $500 $5,000 10%
    Card C $1,000 $10,000 10%
    Totals $1,800 $18,000 —
    Overall utilization — — 10%

    Every card is at exactly 10%, and the overall is also 10%. This is a clean, symmetric scenario — and it’s the kind of profile scoring models reward. No single card is a problem; the aggregate is in the excellent-to-good boundary.

    What this means: 10% overall with no card exceeding 10% is about as good as utilization gets for most people. Pushing lower (under 5%, or even reporting $0 on some cards) may add a few more points, but the gains shrink rapidly below 10%. The much bigger leaps come from moving out of the 30%+ and 50%+ ranges, which we’ll cover shortly.

    Worked Example C: Mixed Balances and Limits

    Real life is messier. Here’s a scenario with uneven usage — a couple of cards lightly used, one carrying a larger balance, and a store card with a low limit that’s nearly maxed.

    Card Balance Credit Limit Per-Card Utilization
    Card A (primary rewards card) $1,200 $12,000 10%
    Card B (travel card) $2,400 $8,000 30%
    Card C (store card) $850 $1,000 85%
    Card D (backup, rarely used) $0 $5,000 0%
    Totals $4,450 $26,000 —
    Overall utilization — — 17.1% ≈ 17%

    This is the scenario that trips people up. The overall utilization looks fine at 17% — comfortably in the “good” range. But look at the per-card column: Card C is at 85%, which most scoring models treat as a maxed-out card. Card B is at 30%, right on the threshold. Only Card A and Card D are healthy.

    What this means: Even though the headline number looks okay, this profile is likely suppressing your scores. Scoring models (FICO and VantageScore both) evaluate per-card utilization in addition to overall. A maxed-out store card is a known red flag, partly because low-limit cards are easy to max out and partly because maxed-out behavior correlates with financial stress. The fix here isn’t necessarily to pay down everything — it’s to prioritize Card C first. Bringing Card C under 30% (below $300) would likely produce a noticeable score improvement even if the overall utilization barely moves.

    This is why a calculator that shows per-card numbers is so much more useful than a single overall figure. The overall number can hide problems that the per-card breakdown reveals.

    A Fill-In Worksheet to Calculate Utilization By Hand

    You don’t need a spreadsheet or a fancy tool. A pen and the table below will get you there in a few minutes. Print this out or copy it into a notebook, then fill in your own numbers.

    Step 1: List every revolving account

    For each credit card or line of credit, fill in the card name, your most recent statement balance, and your credit limit. Then calculate per-card utilization (balance ÷ limit × 100).

    Card Name Statement Balance Credit Limit Per-Card Utilization (Balance ÷ Limit × 100)
    _______________ $________ $________ ______%
    _______________ $________ $________ ______%
    _______________ $________ $________ ______%
    _______________ $________ $________ ______%
    _______________ $________ $________ ______%
    _______________ $________ $________ ______%

    Step 2: Sum the columns

    Add up all the balances. Add up all the credit limits.

    Value
    Total Balance $________
    Total Credit Limit $________

    Step 3: Calculate overall utilization

    Divide Total Balance by Total Credit Limit, then multiply by 100.

    Step 4: Scan the per-card column

    Look down the per-card utilization column. Flag any card above 30% — those are your priority targets for paydown, regardless of what the overall number says. If everything is under 30% and your overall is under 10%, you’re in excellent shape.

    Step 5: Note the date

    Write today’s date at the top of the worksheet. Utilization is a snapshot — it changes every statement cycle. Recalculate monthly, or any time you make a large purchase, open a new card, or close an account. Tracking it over time is how you see progress.

    What Your Utilization Result Means

    Once you have your numbers — both overall and per-card — here’s how to interpret them. The ranges below are widely accepted across FICO and VantageScore scoring models, though exact thresholds vary slightly by model and by the rest of your credit profile.

    Overall utilization ranges

    Utilization Range Rating What It Means for Your Scores
    Under 10% Excellent This is the sweet spot. You’re using credit lightly and responsibly. Most people see their best utilization-based scores here. Going lower (under 5%, or $0 on some cards) may add a couple more points, but returns diminish.
    10% – 29% Good You’re in solid territory. Scores are generally not being suppressed much by utilization. Aim to dip below 10% if you’re applying for something soon.
    30% – 49% Fair / Needs Work You’ve crossed the threshold where scoring models start to penalize. Dropping below 30% typically produces a measurable score increase — often 10–20 points or more, depending on your profile.
    50% – 74% Poor Scores are being meaningfully suppressed. Improvement from this range can be substantial once you pay down.
    75% – 99% Very Poor You’re approaching or effectively maxed out. This is a serious drag on your scores and a signal of financial strain to lenders.
    100%+ (over limit) Critical Being over your credit limit is a major red flag. Some issuers will decline new transactions, report you as over-limit, or even reduce your limit. Address this immediately.

    Per-card utilization: the hidden second grade

    The table above applies to both your overall ratio and each individual card. A common guideline:

    • No single card should be above 30% — even if your overall is low.
    • Ideally, no card above 10% for maximum scores.

    The scoring reasoning is behavioral. Someone who spreads spending evenly across several cards looks like someone who manages credit comfortably. Someone who concentrates nearly all their debt on one card — especially one that’s near its limit — looks like someone scrambling for capacity. The overall ratio tells part of the story; the per-card ratios tell the rest.

    The “0% myth”

    A quick clarification, because this comes up constantly: carrying a small balance does not help your credit scores. There is no scoring bonus for owing money. The idea that you need to carry a balance to “build credit” is one of the most persistent credit myths out there. You can pay your statement balance in full every month — pay zero interest — and still achieve excellent utilization (because the statement balance is what’s reported, before you pay it). We cover the mechanics in the mid-cycle payment section.

    The one nuance: reporting $0 on every card can sometimes be marginally worse than reporting a small balance on one card. Scoring models like to see some activity. The common advice — and it’s sound — is to let one card report a small balance (under 10%) and pay the rest to $0 before the statement closes. But this is fine-tuning. The big wins come from getting out of the 30%+ ranges, not from micro-optimizing between 0% and 8%.

    How to Use Your Result to Plan Paydown

    Knowing your utilization is only useful if you do something with it. Here’s a practical paydown framework that uses your numbers directly.

    Priority 1: Address any card above 30%

    If one or more cards are above 30% per-card utilization, those are your top priority — even if your overall utilization looks fine. As the Worked Example C showed, a maxed-out store card on an otherwise healthy profile can quietly suppress your scores.

    For each card above 30%, calculate how much you’d need to pay to bring it under the 30% threshold:

    Example: Card C from Worked Example C had an $850 balance on a $1,000 limit. To get under 30%: $850 − (0.30 × $1,000) = $850 − $300 = $550 of paydown needed. Once you pay $550, that card drops from 85% to 30%.

    If you can’t get it under 30% in one payment, aim for the biggest reduction you can manage. Every drop helps, but the 30% threshold is where the biggest scoring impact typically lands.

    Priority 2: Bring overall utilization under 30%

    If your overall utilization is above 30%, that’s your second target. Calculate the paydown needed:

    Example: If your total balance is $9,000 and your total credit limit is $20,000, you’d need to pay down $9,000 − (0.30 × $20,000) = $9,000 − $6,000 = $3,000 to reach 30% overall.

    Priority 3: Push toward 10% or below

    Once everything is under 30%, the next goal is 10% or below — the “excellent” range. Same formula, swap 0.10 for 0.30:

    This is where scores tend to peak. If you’re applying for a mortgage, auto loan, or any major credit product, getting under 10% in the 30–60 days before application is one of the highest-leverage moves you can make.

    A paydown strategy note: avalanche vs. utilization

    There’s a tension between two sensible goals: paying down your highest-interest debt first (the avalanche method, which saves you the most money) and paying down high-utilization cards first (which helps your scores the most). They don’t always point the same direction.

    A reasonable approach: make minimum payments on everything to stay current, then direct extra cash to whichever card is both above 30% utilization and has your highest interest rate. Once that card is under 30%, move to the next card meeting both criteria.

    credit-utilization-calculator-under-100kb

    Target Balance Table for Common Credit Limits

    To make planning faster, here’s a lookup table. Find your credit limit, and the table shows the maximum balance you can carry to stay under the 10% (excellent) and 30% (good-to-fair) thresholds.

    Per-card target balances

    Credit Limit Stay Under 10% (Excellent) Stay Under 30% (Good) 50% Threshold Max (100%)
    $500 Under $50 Under $150 Under $250 $500
    $1,000 Under $100 Under $300 Under $500 $1,000
    $2,000 Under $200 Under $600 Under $1,000 $2,000
    $2,500 Under $250 Under $750 Under $1,250 $2,500
    $3,000 Under $300 Under $900 Under $1,500 $3,000
    $5,000 Under $500 Under $1,500 Under $2,500 $5,000
    $7,500 Under $750 Under $2,250 Under $3,750 $7,500
    $10,000 Under $1,000 Under $3,000 Under $5,000 $10,000
    $15,000 Under $1,500 Under $4,500 Under $7,500 $15,000
    $20,000 Under $2,000 Under $6,000 Under $10,000 $20,000
    $25,000 Under $2,500 Under $7,500 Under $12,500 $25,000
    $50,000 Under $5,000 Under $15,000 Under $25,000 $50,000

    How to use this table

    • Find your card’s credit limit in the leftmost column.
    • The second column tells you the balance to stay under for excellent utilization (under 10%). If you’re preparing for a major credit application, aim here.
    • The third column is the threshold to stay out of penalty territory (under 30%). If you’re above this number on any card, that card is your paydown priority.
    • For overall utilization, sum your limits, find the closest row, and apply the same thresholds to your total balance.

    A quick example

    You have three cards with limits of $1,000, $5,000, and $10,000. Looking up the table:

    • The $1,000 card should stay under $100 (for 10%) or $300 (for 30%).
    • The $5,000 card should stay under $500 (for 10%) or $1,500 (for 30%).
    • The $10,000 card should stay under $1,000 (for 10%) or $3,000 (for 30%).

    Your total limit is $16,000. The closest row is $15,000, so for overall utilization you’d target under $1,500 (for 10%) or under $4,500 (for 30%). If you want to be precise, just use the formula: 10% of $16,000 = $1,600; 30% of $16,000 = $4,800.

    The Mid-Cycle Payment Strategy

    Here’s something that catches nearly everyone off guard: the balance that matters for your credit scores is not the balance you see when you log in to your card app. It’s the balance your card issuer reports to the credit bureaus — and that almost always happens once a month, on or shortly after your statement closing date, not your due date.

    Why this distinction matters

    Suppose your statement closes on the 15th of each month, and your payment is due on the 12th of the following month. If you charge $2,000 during the billing period and pay it in full on the due date, you pay no interest — great. But on the 15th, when the statement closes, your issuer reports that $2,000 balance to the bureaus. Even though you’re about to pay it off, your credit reports show a $2,000 balance for that cycle. If your limit is $5,000, the bureaus see 40% utilization — squarely in the penalty range — for that month.

    This is why people who pay in full every month can still have high utilization on their credit reports. They’re not carrying debt, but they’re using a lot of their limit during the cycle, and that’s what gets reported.

    The mid-cycle payment fix

    The fix is straightforward: make a payment before your statement closes, in addition to the payment you make by the due date. Here’s the sequence:

    1. Find your statement closing date for each card. It’s usually printed on your statement and visible in your online account. It’s typically the same date each month, give or take a day for weekends.
    2. A few days before the statement closes — say, 3–5 days prior — log in and pay down most or all of your current balance. This brings the balance that will be reported to the bureaus down to whatever you choose.
    3. Let the statement close with the reduced balance (or $0 if you paid in full). That’s the number that gets reported.
    4. Pay any remaining statement balance by the due date to avoid interest.

    Worked example

    You have a $5,000 limit. Your statement closes on the 20th. By the 15th, you’ve charged $2,500 this cycle (50% utilization if reported as-is). You pay $2,000 on the 16th. The statement closes on the 20th with a $500 balance. The issuer reports $500 — that’s 10% utilization, in the excellent range. You then pay the remaining $500 by the due date. No interest paid, and your credit report shows a healthy 10% utilization instead of 50%.

    Why this works

    You’re not changing how much you spend or how much interest you pay. You’re only changing the snapshot the bureaus see. Because utilization is calculated from the balance reported at statement close, timing your payment to land just before that snapshot gives you direct control over the number — without changing your spending habits.

    This is one of the fastest, lowest-cost credit score improvements available. For many people, a single cycle of mid-cycle payments can move scores noticeably, because utilization updates on the next bureau report (usually within a few days of statement close).

    A note on timing precision

    You don’t need to be exact to the day. Most issuers report within a few days after the statement closes. Paying 3–5 days before the statement close date gives a comfortable buffer. If you’re not sure when your statement closes, call your issuer and ask — they’ll tell you, and some will let you change your statement closing date to something more convenient.

    How Credit Limit Increases Change the Math

    A credit limit increase is the other major lever you have. Because your credit limit is the denominator of the utilization formula, increasing it lowers your utilization — without requiring you to pay down a single dollar of balance.

    The math

    If you carry a $2,000 balance on a $5,000 limit, your utilization is 40%. If your issuer raises your limit to $8,000 and your balance stays at $2,000, your new utilization is $2,000 ÷ $8,000 = 25%. You’ve dropped from the “needs work” range to the “good” range just by getting a higher limit — no paydown required.

    Two ways to get a limit increase

    1. Automatic increases — many issuers review accounts periodically and raise limits on their own, especially if you’ve had the card for a while, pay on time, and have rising income. These usually don’t result in a hard inquiry on your credit report.
    2. Requesting an increase — you can ask your issuer for a higher limit through your online account or by calling. Some issuers do this with no hard inquiry (a soft pull); others will do a hard inquiry, which can ding your scores a few points temporarily. Ask before you request whether the increase will require a hard inquiry. Many issuers will tell you upfront.

    The risk: spending creep

    A higher limit only helps your utilization if your balance stays roughly the same. If a higher limit tempts you to spend more — a well-documented behavioral pattern — your utilization can end up not improving at all, and you’ll carry more debt. The math is only on your side if you treat the new limit as capacity you don’t use.

    A combined strategy

    The most powerful approach is combining both levers: pay down balances AND secure limit increases. Each makes the other more effective. A paydown of $1,000 lowers your numerator; a limit increase of $3,000 raises your denominator. Together, they compress your utilization faster than either alone.

    Example: You start at $3,000 balance on a $5,000 limit — 60% utilization. You pay down $1,000 (to $2,000) and get a limit increase to $8,000. New utilization: $2,000 ÷ $8,000 = 25%. You’ve gone from 60% to 25% in one move, which would typically produce a solid score improvement.

    What about new cards?

    Opening a new credit card also increases your total credit limit (the denominator), which can lower overall utilization. But new cards come with trade-offs: a hard inquiry, a new account that lowers your average age of accounts, and the temptation to spend. For short-term score optimization (next 6 months), a new card is usually a wash or a slight negative — the inquiry and age factors offset the utilization benefit. For longer-term optimization (12+ months out), a new card can help because the inquiry impact fades and the account ages. Think carefully before opening a card purely for utilization reasons, especially if you’re applying for a mortgage soon.

    Common Credit Utilization Calculation Mistakes

    Even with the formula in hand, people make predictable errors. Here are the most common ones — and how to avoid them.

    1. Using current balance instead of statement balance

    This is the most frequent mistake. The balance you see in your card app changes every time you make a charge or a payment. The balance that matters for your credit scores is the one reported at statement close. If you calculate utilization using your current balance on a random day, you may be over- or under-estimating what’s actually on your credit report. Use your most recent statement balance for an accurate estimate.

    2. Forgetting about a card you rarely use

    That store card you opened for a discount three years ago and haven’t touched since? It still has a limit, and that limit still counts toward your total available credit. Forgetting to include it means your denominator is wrong, which means your overall utilization calculation is wrong. List every revolving account, even ones with $0 balances.

    3. Including installment loans in the calculation

    Auto loans, mortgages, student loans, and personal loans are installment debt, not revolving debt. They are not part of utilization. Mixing them in inflates both your numerator (balances) and your denominator (limits, which installment loans don’t have in the same way) — and gives you a meaningless number. Only include revolving accounts: credit cards and lines of credit.

    4. Ignoring per-card utilization

    Calculating only the overall number and calling it a day is tempting, but as Worked Example C showed, you can have a healthy overall ratio with a maxed-out card hiding in the mix. Always compute per-card ratios and scan for any card above 30%.

    5. Treating charge cards as regular credit cards

    Some cards — notably certain American Express charge cards — have no preset spending limit. They don’t report a traditional credit limit, so they may be excluded from utilization calculations or handled with a substitute figure (like your highest recent balance). Including them as if they had a normal limit distorts your math. Check your credit report to see what’s actually being reported for each account.

    6. Closing cards to “clean up” your credit

    Closing a card doesn’t remove its history from your report immediately (the account stays on your report for up to 10 years if closed in good standing), but it does remove its credit limit from your utilization denominator the moment it closes. If you close a card with a $10,000 limit and your other cards total $15,000 in limits, your total available credit just dropped from $25,000 to $15,000. If you carry a $4,500 balance, your utilization jumps from 18% to 30% overnight — a significant downgrade. Think twice before closing cards, especially older ones with high limits.

    7. Counting a credit limit increase as a guarantee

    If you request a limit increase and the issuer does a hard inquiry but denies the increase, you’ve taken a small score hit for no benefit. Ask about the inquiry policy before requesting. And if your income has dropped or you’ve missed payments recently, an increase may be unlikely — consider focusing on paydown instead.

    8. Confusing “due date” with “statement closing date”

    Your due date is when your payment must arrive to avoid interest. Your statement closing date is when the billing cycle ends and the balance is reported. They’re typically 3–4 weeks apart, and they serve completely different purposes. Mid-cycle payments (discussed above) hinge on knowing the closing date, not the due date. Mixing them up is the most common reason mid-cycle payment strategies fail.

    9. Overlooking balance reporting frequency

    Most issuers report once per month, but not all. Some report more frequently, and a few report on irregular schedules. If you’re being precise about timing — say, for a mortgage application — check your credit report to see when each issuer last reported. A mid-cycle payment won’t help if the issuer has already reported for that cycle.

    10. Forgetting that authorized-user cards count

    If you’re an authorized user on someone else’s card, that card’s limit and balance typically appear on your credit report and factor into your utilization. This can help (if the primary user keeps it low) or hurt (if it’s maxed). When listing your accounts for the worksheet, include authorized-user cards — and if one is dragging your utilization down, ask the primary user if they can pay it down or, in extreme cases, remove you as an authorized user.

    Frequently Asked Questions

    1. What is a credit utilization calculator?

    A credit utilization calculator is a tool — whether a spreadsheet, an online form, or a manual worksheet like the one in this guide — that computes the percentage of your available revolving credit you’re currently using. You input your balances and credit limits, and the calculator applies the formula (balance ÷ limit × 100) to show both your overall utilization and your per-card utilization. The value isn’t in the arithmetic itself, which is simple; it’s in forcing yourself to gather accurate inputs for every account and see both the aggregate and per-card numbers at once.

    2. How much of my credit limit should I use?

    For optimal credit scores, aim to keep your overall utilization under 10% and no individual card above 30% — ideally under 10% per card as well. For everyday health (not preparing for a specific application), staying under 30% overall and under 30% per card keeps you out of penalty territory. You do not need to carry a balance to build credit — paying your statement balance in full each month avoids interest entirely while still reporting a healthy utilization based on your statement balance.

    3. Does paying my card in full every month mean my utilization is 0%?

    No — and this is a common point of confusion. If you pay your statement balance in full by the due date, you pay no interest, but the statement balance is still what gets reported to the bureaus at statement close (before your due date). So if you charge $2,000 during a cycle on a $5,000 limit card, your credit report will show 40% utilization for that month — even though you pay it off and owe no interest. This is why mid-cycle payments (paying before the statement closes) are the key to controlling the reported number.

    4. Is per-card utilization or overall utilization more important?

    Both matter, and scoring models evaluate both. As a general rule, overall utilization carries somewhat more weight, but a maxed-out individual card can still suppress your scores even when your overall ratio looks fine. The safest approach is to manage both: keep the overall ratio under 10% if possible, and keep every individual card under 30%. Use the worked examples and worksheet in this guide to track both numbers.

    5. How fast does utilization update on my credit report?

    Most card issuers report to the three major bureaus (Equifax, Experian, TransUnion) once per month, shortly after your statement closes. Once the new balance is reported, your utilization on your credit report updates immediately, and your scores typically reflect the change within a few days to a couple of weeks (depending on when lenders pull your scores). This is why utilization is one of the fastest score levers available — you can change it meaningfully within a single billing cycle.

    6. Will requesting a credit limit increase hurt my credit score?

    It depends on whether the issuer does a hard inquiry (a “hard pull”) on your credit report. Some issuers grant increases with only a soft pull, which doesn’t affect your scores. Others do a hard inquiry, which can cause a small, temporary dip (usually a few points) that fades over 12 months. Always ask the issuer whether an increase will require a hard inquiry before you request it. Many issuers will tell you upfront.

    7. Should I close a credit card I don’t use anymore?

    Generally, no — at least not without weighing the utilization impact. Closing a card removes its credit limit from your total available credit, which can raise your overall utilization even if you don’t change your spending. If the card has no annual fee, consider keeping it open and using it for a small recurring charge (like a streaming subscription) that you pay off each month, to keep the account active and the limit in your denominator. If it has an annual fee you can’t justify, weigh the cost against the potential utilization impact — and consider asking the issuer to convert it to a no-fee version instead of closing it.

    8. What utilization ratio is best for buying a house?

    If you’re applying for a mortgage, aim for overall utilization under 10% and ideally under 5% in the 30–60 days before your lender pulls your credit. Mortgage lenders are particularly sensitive to utilization, and even small reductions can improve the rate you’re offered. This is also a time to avoid opening new cards, closing existing cards, or taking on new installment debt — keep your profile stable and your utilization low. Mid-cycle payments are especially valuable here, because they let you control exactly what balance is reported when your lender pulls your scores.

    Get a Free Credit Audit

    Calculating your utilization is a great first step — but it’s only one piece of your credit picture. If you want a full, professional review of your credit reports across all three major bureaus, we can help.

    At credit-repair.com, we offer a free credit audit that includes:

    • A line-by-line review of your reports from Equifax, Experian, and TransUnion
    • Identification of inaccuracies, outdated information, and negative marks that may be dragging down your scores
    • A clear explanation of what each item is and whether it’s disputable under the Fair Credit Reporting Act (FCRA)
    • A customized repair plan tailored to your specific goals — whether that’s buying a home, refinancing, or simply getting your scores into the excellent range
    • An honest assessment of what’s achievable and a realistic timeline, with no guarantees or quick-fix promises

    We’re San Diego-based, FCRA-compliant, and we work alongside experienced attorneys to ensure every dispute we file is grounded in federal law. We serve clients in cities nationwide, and we’re committed to educating you throughout the process — so you leave us not just with better credit, but with the knowledge to keep it strong for life.

    Ready to see where you stand? Request your free credit audit at credit-repair.com. We’ll walk through your reports together, answer your questions, and give you a clear, honest plan — no pressure, no hidden fees, no obligation.

    Disclaimer: This article is for educational purposes and does not constitute legal or financial advice. Your individual credit situation is unique. For personalized guidance, request a free credit audit at credit-repair.com. We do not guarantee specific score improvements; results vary based on individual circumstances and the information on your credit reports.

  • How Your Credit Score Is Calculated: The 5 Factors Explained

    How Your Credit Score Is Calculated: The 5 Factors Explained

    You check your credit score, see a three-digit number, and immediately wonder: where did that number actually come from?

    It is a fair question. Your credit score can decide whether you get approved for a mortgage, what interest rate you pay on a car loan, whether a landlord rents to you, and in some cases whether a potential employer offers you a job. Yet most people never receive a clear explanation of how the score is built. They are handed the result without ever seeing the formula.

    That stops here. In this guide, we are going to walk through exactly how your credit score is calculated — the five factors that feed into it, the percentage weight each one carries, what helps and hurts each factor, and what you can do starting today to strengthen the ones you control. No jargon, no quick-fix promises, just a clear, honest breakdown from a team that does this work every day.

    If you have ever felt like your credit score was handed down from a black box, this article is for you. By the end, you will understand the mechanics well enough to look at your own credit report and know — with real confidence — which levers to pull and which ones to leave alone.

    The 30-Second Version

    If you only have a minute, here is the whole system in one breath:

    Your credit score is calculated from five factors drawn from your credit report. Payment history carries the most weight at 35 percent — have you paid on time? Credit utilization (how much of your available credit you are using) comes next at 30 percent. Length of credit history — how long your accounts have been open — is 15 percent. Credit mix — the variety of account types you manage — is 10 percent. And new credit inquiries — how often you are applying for new credit — rounds it out at 10 percent.

    Those five factors, in roughly those proportions, are how FICO — the scoring model used in roughly 90 percent of lending decisions — converts the information on your credit report into a single three-digit number that lenders use to gauge risk.

    That is the skeleton. Now let us put muscle on the bones.

    Payment History — 35% (The Heavyweight)

    Payment history is the single most influential factor in your credit score. At 35 percent of the FICO scoring formula, it carries more weight than any other category. The logic is simple and ruthless: if a lender wants to know whether you will repay a future loan, the best evidence they have is whether you have repaid past ones.

    How it is measured

    Payment history looks at whether you have paid your credit accounts on time and in full. But it is not a simple yes-or-no checkbox. The scoring model digs into several layers of detail:

    • On-time vs. late payments. A payment is generally reported as “on time” if it is received by the due date or within the grace period your creditor allows. Once a payment is 30 days late, it can be reported to the credit bureaus as delinquent, and that negative mark begins dragging on your score.
    • Severity of lateness. A 30-day late payment hurts, but a 60-day late payment hurts more, and a 90-day late payment is far more damaging. The deeper the delinquency, the harder the hit and the longer it lingers.
    • Recency of delinquency. A late payment from two years ago weighs less than one from two months ago. Time heals, but slowly.
    • Frequency. One late payment is a blemish. A pattern of repeated late payments signals a systemic problem and is scored accordingly.
    • Account type. Late payments on a mortgage or auto loan — larger, more structured obligations — can carry more weight than a late payment on a store credit card, though any delinquency is damaging.
    • Public records. Bankruptcies, foreclosures, lawsuits, and tax liens (where still reportable) are severe negative items that fall under payment history and can suppress a score for years.
    • Collections and charge-offs. If an account is sent to collections or written off as a loss by the creditor, it is recorded here and is one of the most damaging entries possible.

    What helps

    • Paying every bill on time, every time. This is the single most powerful credit-building habit you can develop. Consistency matters more than amount.
    • Setting up autopay or payment reminders. Most late payments are not about lack of money — they are about lack of attention. Automation removes that risk.
    • Paying at least the minimum. If you cannot pay in full, always pay at least the minimum by the due date. Interest accrues, but the account stays current.
    • Catching up on past-due accounts. If you have slipped, getting current stops the bleeding. A late payment that is now 30 days old is less damaging than one that ages into 60 or 90 days.
    • Time. As late payments age, their impact fades. A single 30-day late payment from four years ago has a fraction of the effect of one from last month.

    What hurts

    • Any payment reported 30 or more days late. This is the line that, once crossed, shows up on your report and starts pulling your score down.
    • Serious delinquencies — 60, 90, or 120 days late — which escalate the damage sharply.
    • Accounts sent to collections. Even small balances (a forgotten utility bill, an unpaid medical copay) can end up here and do outsized damage.
    • Charge-offs, where the creditor has given up on collecting and written the debt off as a loss.
    • Bankruptcies, foreclosures, and repossessions. These are the most severe negative items and can suppress a score for 7 to 10 years.
    • Settled-for-less-than-full amounts. Settling a debt for less than you owe may resolve the obligation, but the account history still reflects that you did not pay as agreed.

    How to optimize it

    Payment history is the factor you cannot fast-track, but you can protect it ruthlessly:

    1. Automate at least the minimum payment on every account. This single step eliminates the most common cause of late payments — forgetting.
    2. Review your statements monthly. Catch billing errors, unauthorized charges, or due-date changes before they become a problem.
    3. If you fall behind, get current as fast as possible and stay current. A brief lapse followed by years of perfect payments tells a better story than a lapse that deepens.
    4. Communicate with creditors early. Many offer hardship programs, payment plans, or due-date adjustments that can keep a late payment off your report if you reach out before the due date passes.
    5. Dispute inaccurate late payments. If a payment is incorrectly reported as late, you have the right under the Fair Credit Reporting Act (FCRA) to dispute it with the credit bureaus. Incorrect reporting is more common than most people realize.

    Credit Utilization — 30% (The Silent Power Broker)

    If payment history is the heavyweight, credit utilization is the silent power broker. At 30 percent of your score, it is the second-largest factor — and unlike payment history, it is one you can change quickly. For people with otherwise solid payment habits, utilization is very often the difference between a good score and an excellent one.

    How it is measured

    Credit utilization measures how much of your available revolving credit you are using. It is expressed as a percentage:

    If you have two credit cards with combined limits of $10,000 and your combined balances are $2,500, your utilization is 25 percent.

    Key details:

    • Revolving accounts only. Utilization looks at credit cards, store cards, and lines of credit — not installment loans like mortgages, auto loans, or student loans.
    • Overall and per-card utilization. The scoring model looks at utilization both across all revolving accounts combined and on each individual card. Maxing out one card even if your overall utilization is low can still hurt.
    • Statement date, not due date. Utilization is typically calculated based on the balance reported to the bureaus — which is usually your statement balance, the snapshot taken when your billing cycle closes. Paying your card off in full after the statement posts does not change what was reported. To influence the reported number, you need to pay before the statement closing date.

    What helps

    • Keeping utilization low. The general guidance is to stay below 30 percent, but the real target is below 10 percent for top-tier scores. People with the highest scores tend to use a small fraction of their available credit.
    • Paying before the statement closes. If you use your card heavily for rewards or cash flow but want a low reported balance, make a payment before the statement closing date so the reported balance is small.
    • Asking for credit limit increases. A higher limit with the same spending lowers your utilization ratio. Just confirm the creditor will not do a hard inquiry for the increase — many will do a soft pull instead.
    • Keeping cards open even when you stop using them.
    • Multiple small payments during the month. If one big payment before the statement date feels risky, several smaller payments throughout the cycle keep the running balance low.

    What hurts

    • Maxing out cards — utilization near or at 100 percent is one of the fastest ways to sink a score, even with a flawless payment history.
    • Carrying high balances relative to limits, even if you pay on time. A $2,000 balance on a $3,000 limit card (67 percent utilization) is far more damaging than $2,000 spread across a $20,000 limit (10 percent).
    • Closing old cards. Closing a card removes its credit limit from your utilization calculation, which can cause your ratio to jump even if your spending has not changed.
    • Consolidating balances onto one card. Moving several balances onto a single low-limit card can spike that card’s per-card utilization even if the overall picture looks the same.

    How to optimize it

    Utilization is the factor where small, deliberate moves can produce visible score changes within a billing cycle:

    1. Find out your statement closing dates for every card. These are the dates that matter, not the due dates.
    2. Pay down balances before the statement closes — not just before the due date — to control what gets reported.
    3. Target under 10 percent utilization on each card and overall for the strongest scores.
    4. Request credit limit increases on cards you have held responsibly for a while. More room with the same spending instantly lowers the ratio.
    5. Think twice before closing cards. If a card has no annual fee, keeping it open preserves your available credit. If it has a fee you cannot justify, weigh the score impact before closing.
    6. Spread spending across cards rather than loading one. This keeps per-card utilization low even if overall utilization is the same.

    Length of Credit History — 15% (The Long Game)

    At 15 percent of your score, length of credit history is a mid-weight factor. You cannot accelerate it quickly — it is, by definition, a function of time — but understanding how it works helps you avoid common mistakes that accidentally shorten it.

    How it is measured

    Length of credit history looks at the age of your credit accounts. Specifically, the model considers:

    • Age of your oldest account. How long has your earliest credit account been open?
    • Age of your newest account. How recently did you open new credit?
    • Average age of all accounts. This is the most influential single figure within this category. It is calculated as the sum of the ages of every account on your report, divided by the number of accounts.
    • How long specific account types have been open. How long ago did you first get a credit card, a mortgage, an auto loan, and so on.
    • How long since those accounts were active. Inactivity on an old account can reduce its contribution to this factor over time.

    What helps

    • Keeping your oldest account open. Your oldest account anchors your credit age. Closing it can shorten your average age and remove a long, positive history from the calculation.
    • Keeping older accounts active. A small recurring charge — a streaming subscription, a phone bill — paid off each month keeps an old card from being closed by the issuer for inactivity.
    • Opening new credit sparingly. Every new account lowers your average age. The impact is temporary, but spacing out applications minimizes it.
    • Being an authorized user on a long-standing account. If a family member adds you as an authorized user to a card they have held for many years, that account’s age can show up on your report and lengthen your history. (Be sure the primary holder has a clean payment record on that card — their negatives come too.)

    What hurts

    • Closing your oldest card. This can shorten your credit history and raise your utilization simultaneously — a double hit.
    • Opening several new accounts at once. This lowers your average account age and can make you look like a sudden credit seeker, which also affects the new credit factor.
    • Long stretches with no credit activity. Some creditors will close inactive accounts, which removes that history from your report and can shorten your average age.

    How to optimize it

    Length of credit history rewards patience, but you can protect it:

    1. Never close your oldest credit card unless there is a compelling reason (high annual fee, serious fraud, etc.). Even if you rarely use it, keeping it open preserves your history.
    2. Keep old cards active with a small, automatic charge every month that you pay off.
    3. Think carefully before applying for new credit. Each application has a place, but a burst of new accounts compresses your average age.
    4. If you are new to credit, start now. The clock starts when your first account is reported. The sooner you have a single account reporting on-time payments, the sooner you begin building history.
    5. Consider an authorized-user arrangement if you are starting out or rebuilding and have a trusted family member with a long, clean credit history.

    Credit Mix — 10% (The Well-Rounded Profile)

    Credit mix accounts for 10 percent of your FICO score.

    Credit mix looks at the variety of credit accounts you manage. The scoring models generally distinguish between revolving credit, such as credit cards, and installment credit, such as mortgages, auto loans, student loans, and personal loans.

    What helps

    • Having both revolving and installment accounts, when those accounts are appropriate for your financial situation.
    • Managing different types of credit responsibly.
    • Allowing naturally occurring accounts to age and remain in good standing.

    What hurts

    • Having a very limited credit profile with little variety of account types.
    • Opening unnecessary loans solely to improve your credit mix.
    • Taking on debt you do not need or cannot comfortably afford.

    How to optimize it

    Credit mix is a “let it happen” factor. You should not force it:

    1. Do not take out a loan just to improve your mix. The 10 percent weight is not worth the cost, risk, or hard inquiry.
    2. When you naturally need an installment loan — a car, a home, education — that addition will gradually improve your mix as long as you pay it on time.
    3. If you only have installment loans (say, a student loan and a car loan), responsibly opening a single credit card and paying it in full each month can round out your profile.
    4. For thin or new files, a secured credit card or a credit-builder loan can establish both account types without requiring strong credit to qualify.

    New Credit and Inquiries — 10% (The Caution Flag)

    The final 10 percent of your score comes from new credit and inquiries. This factor rewards restraint — it measures how aggressively you have been seeking new credit, and it penalizes patterns that suggest risk.

    How it is measured

    The new credit factor looks at:

    • Hard inquiries. When you apply for credit — a card, a loan, a mortgage — the lender pulls your credit report. That pull is recorded as a hard inquiry and can affect your score.
    • Number of recently opened accounts. How many new accounts have you opened in the recent past (typically the last 6–12 months)?
    • Proportion of accounts that are new. If a large share of your accounts are recently opened, it signals you are taking on new credit rapidly.
    • Time since the most recent inquiry or account opening. The older your newest inquiry or account, the less it weighs.
    • Rate shopping windows. For certain loan types — mortgages, auto loans, student loans — multiple inquiries within a short window (typically 14 to 45 days, depending on the scoring model version) are treated as a single inquiry for scoring purposes, recognizing that you are shopping for one loan, not opening many accounts.

    Hard vs. soft inquiries — know the difference

    This distinction matters more than almost any other in this factor:

    • Hard inquiries result from you applying for credit. They appear on your report, they can affect your score, and they remain visible for up to two years (though the score impact typically fades after about one year).
    • Soft inquiries result from checks that are not tied to a credit application — your own review of your credit, creditor pre-approval screenings, employer background checks, account monitoring by your existing creditors. Soft inquiries never affect your score.

    Checking your own credit is a soft inquiry. It will not lower your score, no matter how often you do it. This is one of the most persistent myths we encounter, and it is worth stating clearly: you can check your own credit as often as you like without any scoring penalty.

    What helps

    • Applying for credit only when you genuinely need it. Spontaneous applications for store cards at checkout, or for cards offering modest sign-up bonuses, generate inquiries that can dent your score for marginal benefit.
    • Rate shopping within a short window. For mortgages and auto loans, clustering applications within the 14-to-45-day window means multiple pulls are scored as one.
    • Letting inquiries age. A hard inquiry’s effect diminishes over time and typically disappears from your score after about a year, even though it remains visible on your report for two years.
    • Keeping your overall pace of new credit modest. One or two new accounts over several years is a healthy pattern.

    What hurts

    • Multiple hard inquiries in a short period, especially across different credit types — this signals risk-seeking behavior.
    • Opening several new accounts quickly, which lowers your average account age (affecting the length of history factor) and raises the proportion of new accounts (affecting this factor).
    • Applying for credit repeatedly after denials. Each application adds another hard inquiry, and a string of them compounds the damage.
    • Responding to every pre-approval offer. Pre-approvals are based on soft inquiries, but if you act on them and formally apply, that application becomes a hard inquiry.

    How to optimize it

    1. Space out credit applications. A good rule of thumb: no more than one new credit application every six months unless you are rate-shopping a specific loan.
    2. When rate-shopping a mortgage or auto loan, do all your applications within a 14-day window to ensure they are scored as a single inquiry.
    3. Check your own credit freely. Use free services or annualcreditreport.com — these are soft inquiries and have no score impact.
    4. Be selective with store cards. The discount at checkout is usually not worth the inquiry and new account, especially if you will not use the card regularly.
    5. If you have been denied, find out why before applying again. Repeated applications without addressing the underlying issue just stack inquiries.

    Summary Table: The 5 Factors at a Glance

    Factor Weight What It Measures Speed of Change
    Payment History 35% Whether you have paid past credit accounts on time Slow — months to years of consistent on-time payments
    Credit Utilization 30% How much of your available revolving credit you are using Fast — can change within a single billing cycle
    Length of Credit History 15% The age of your credit accounts, oldest and average Very slow — purely a function of time
    Credit Mix 10% Variety of revolving and installment account types Slow — develops naturally as you finance major purchases
    New Credit and Inquiries 10% How many recent credit applications and new accounts you have Moderate — inquiries fade in about a year

    The weights above are the FICO percentages — the model used in the overwhelming majority of lending decisions in the United States. VantageScore, the other major model, weights factors differently, which we cover in the next section.

    FICO vs. VantageScore: How the Scoring Models Differ

    When people talk about “your credit score,” they are usually referring to a FICO score. FICO (Fair Isaac Corporation) has been the dominant credit scoring model in the U.S. since the late 1980s, and its scores are used in an estimated 90 percent of consumer lending decisions.

    But FICO is not the only model. VantageScore, developed jointly by the three major credit bureaus (Equifax, Experian, and TransUnion), is an alternative that has gained traction, particularly in free credit monitoring services and some lending decisions. Both models analyze the same underlying data — your credit report — but they weight the factors differently and have some structural differences worth understanding.

    How the weights differ

    Factor FICO Weight VantageScore Weight (approx.)
    Payment History 35% ~40% (extremely influential)
    Credit Utilization 30% ~20% (highly influential)
    Length of Credit History 15% ~21% (moderately influential)
    Credit Mix 10% ~13% (moderately influential)
    New Credit and Inquiries 10% ~5% (less influential)
    Recent Credit Behavior / Available Credit — included in the above categories

    VantageScore tends to place even more emphasis on payment history and somewhat less on new credit inquiries than FICO. It also treats available credit (the total dollar amount of unused credit lines) as a distinct consideration, whereas FICO folds that into utilization.

    Other key differences

    • Scoring ranges. FICO scores generally range from 300 to 850. VantageScore 3.0 and 4.0 also use a 300 to 850 range, though earlier VantageScore versions used a different 501–990 scale.
    • Minimum credit history. FICO traditionally requires at least one account that is six months old and at least one account reported to the bureaus within the last six months. VantageScore can generate a score with a thinner file, making it useful for people new to credit or rebuilding.
    • Paid collections. VantageScore 3.0+ ignores paid collections entirely. FICO 9 also ignores paid collections, but FICO 8 — still widely used — does not. This means a paid collection can still affect a FICO 8 score even after it is settled.
    • Trended data. VantageScore 4.0 uses trended data — the trajectory of your balances over time — to assess whether you are paying down debt or accumulating it. FICO has been incorporating similar data in newer versions.
    • Medical collections. Both newer FICO and VantageScore models give more favorable treatment to medical collections than other types, recognizing that medical debt often results from circumstances outside a consumer’s control.

    What this means for you

    In practice, the two models usually tell a similar story. A person with strong payment history, low utilization, and a long, diverse credit profile will score well under both. A person with recent late payments and maxed-out cards will score poorly under both. The differences show up at the margins — particularly for people with thin files, paid collections, or a lot of recent rate shopping.

    If you are preparing for a specific lending decision (a mortgage, an auto loan), ask the lender which scoring model they use. For mortgages, the answer is almost always a specific FICO model (often FICO 2, 4, or 5, depending on the bureau). Knowing which model matters can help you focus your effort on the factors that model emphasizes.

    What Is NOT in Your Credit Score

    Understanding what is in your score is only half the picture. It is equally important to understand what is not in it — because a surprising number of factors that people assume affect their score do not.

    By federal law — specifically the Equal Credit Opportunity Act (ECOA) — credit scoring models in the United States are prohibited from considering certain personal characteristics. The law is designed to prevent discrimination in lending, and it shapes the boundary of what a score can and cannot reflect.

    What is NOT considered

    • Your income. Your credit score does not know how much you earn. A high salary does not produce a high score, and a low salary does not produce a low one. Income matters to lenders separately — they consider it as part of their own underwriting, in the debt-to-income ratio — but it is not part of the score itself.
    • Your employment history. Whether you are employed, unemployed, self-employed, or retired is not in your score. Lenders may ask, but the scoring model does not see it.
    • Your age. The ECOA prohibits credit scoring from considering age as a factor. (A related factor — the age of your credit accounts — is included, but your chronological age as a person is not.)
    • Your race, color, religion, national origin, or sex. These are explicitly prohibited by the ECOA. The scoring model does not have access to them and cannot use them.
    • Your marital status. Whether you are single, married, divorced, or widowed does not appear in your score.
    • Where you live. Your address is on your report for identification, but geography does not factor into the score.
    • Whether you receive public assistance. Participation in public assistance programs is not considered.
    • Your interest rates on existing accounts. The rates you pay on your current loans are not part of the score. (The accounts themselves are, but not the cost of borrowing on them.)
    • Child support or family obligations in most cases, unless they have been reported as a delinquent debt or collection.
    • Your occupation. Your job title and field are not scored.
    • Participation in credit counseling — by itself — does not appear as a negative item. The individual accounts within a counseling program may be reported, but the counseling itself is not a score factor.

    Why this matters

    Two practical takeaways:

    1. A high income does not protect your score. If you earn $300,000 a year but pay late and carry maxed-out cards, your score will suffer the same as anyone else’s. The score measures behavior on credit accounts, not financial capacity.
    2. The score is behavior-based, not identity-based. By design, it cannot discriminate on the basis of who you are. It only reflects how you have managed credit. That is both its limitation — it cannot see your full financial picture — and its fairness.

    This is also why two people with the same income can have wildly different scores, and why someone with a modest income can have an excellent score while someone with a high income has a poor one.

    How Scoring Models Turn Your Report Into a Number

    We have covered the five factors and their weights. But how does the scoring model actually combine them into a single three-digit number? Here is a simplified, plain-English walkthrough of the process.

    Step 1: Data collection

    Each of the three major credit bureaus — Equifax, Experian, and TransUnion — maintains a credit file on you. That file is populated by reports from your creditors: banks, card issuers, auto lenders, mortgage servicers, student loan servicers, and collection agencies. Each creditor reports your account status, balance, credit limit, payment history, and dates typically once a month.

    Step 2: Building the report

    The bureaus assemble this data into your credit report — a structured document with sections for personal identifying information, account histories, public records, and inquiries. Your report at each bureau may differ slightly, because not every creditor reports to every bureau, and timing can vary.

    Step 3: Applying the scoring model

    When a lender requests your score, a scoring model (FICO or VantageScore) is applied to the data in your report at that bureau. The model:

    1. Extracts the relevant data points — payment history, balances, limits, account ages, inquiry counts, account types.
    2. Categorizes and weights them according to the factor percentages (35/30/15/10/10 for FICO).
    3. Compares you to the statistical behavior of millions of other consumers with similar profiles, drawing on historical data about which behaviors have correlated with repayment or default.
    4. Produces a score — a three-digit number that predicts the likelihood that you will become seriously delinquent on a credit obligation in the next 24 months.

    Step 4: The score reaches the lender

    The lender receives the score along with key report data and uses both — along with their own underwriting criteria, your income, your debt-to-income ratio, and other factors — to make a lending decision. The score is a risk indicator, not a verdict. It tells the lender the statistical likelihood of future default; it does not tell them whether you personally are a good borrower.

    Why your score can differ between bureaus

    Because your three bureau reports may contain slightly different data — a creditor that reports to only one or two bureaus, a timing difference in when a balance updates, a discrepancy in how an account is coded — your FICO score at each bureau can vary, often by a few points and sometimes by more. This is normal. Lenders who pull a “tri-merge” report see all three and typically use the middle value for mortgage underwriting.

    Why your score can change day to day

    Your score is a real-time reflection of the data in your report at the moment it is pulled. Because creditors report updates throughout the month, and because inquiries are added when you apply, your score can shift between pulls even if your behavior has not obviously changed. Small movements — five to ten points — are noise. Larger, sustained movements usually reflect a meaningful change: a new late payment, a paid-down balance, a new account, or a dropped negative item.

    how-credit-score-is-calculated-under-100kb

    A Worked Example: Walking Through a Hypothetical Profile

    To make this concrete, let us walk through a hypothetical person and see how the five factors combine. We will call her Maria.

    Maria’s credit profile

    • Total revolving credit limits: $15,000 across three credit cards
    • Total revolving balances: $4,200
    • Overall utilization: $4,200 / $15,000 = 28 percent
    • Payment history: One 30-day late payment on a store card three years ago; otherwise perfect on all accounts.
    • Accounts:
      • Credit card A — opened 9 years ago, $5,000 limit, $1,200 balance
      • Credit card B — opened 6 years ago, $7,000 limit, $2,000 balance
      • Store card C — opened 4 years ago, $3,000 limit, $1,000 balance (the one with the old late payment)
      • Auto loan — opened 3 years ago, paying on time
    • Average age of accounts: roughly 5.5 years
    • Credit mix: revolving (cards) + installment (auto loan) — a decent mix
    • Recent inquiries: one hard inquiry six months ago (the auto loan); no others in the past two years
    • New accounts: the auto loan, opened six months ago

    How the factors stack up

    Payment history (35%): Maria has a single late payment from three years ago, now well aged, and years of otherwise perfect payments. This factor is strong but not flawless — the old late payment still appears, though its impact has faded significantly. She is in the upper tier on this factor.

    Credit utilization (30%): At 28 percent overall, Maria is just under the 30 percent threshold most people cite, but well above the 10 percent target for top scores. Her per-card utilization is also a concern — card B is at 29 percent, store card C is at 33 percent. This factor is likely the biggest thing holding her score back. If she paid her balances down to under $1,500 total (under 10 percent), she could see a meaningful score increase within a billing cycle.

    Length of credit history (15%): Her oldest account is 9 years old and her average age is around 5.5 years — solid but not exceptional. This factor is moderately positive and will only improve with time, as long as she keeps her old accounts open.

    Credit mix (10%): With revolving cards and an installment auto loan, Maria has a reasonable mix. This factor is fine and will strengthen as the auto loan continues to age.

    New credit and inquiries (10%): One hard inquiry from six months ago and one new account (the auto loan) is a modest, justifiable level of new credit activity. The inquiry’s effect is already fading and will disappear from the score at the one-year mark.

    What Maria should do

    If Maria came to us for a credit audit, here is what we would tell her:

    1. Pay down your revolving balances. This is the single highest-leverage move available to her. Dropping overall utilization to under 10 percent and bringing each card under 30 percent could produce a visible score increase quickly.
    2. Keep all three cards open. Her oldest card anchors her credit age and contributes to her total available credit. Closing any of them would hurt both the length of history and utilization factors.
    3. Keep paying on time. The one late payment is aging off; adding another would reset the damage. Continued perfect payments will keep strengthening the most heavily weighted factor.
    4. Avoid new applications for the next 12 months. She has had one recent inquiry and one new account. Letting those age will let the new credit factor recover fully.
    5. Let time do its work. The late payment will fall off her report at the seven-year mark. Her account ages will continue to grow. Both will gently lift her score if she maintains her current habits.

    This is a realistic, honest picture. Maria is not in trouble, but she is leaving points on the table — primarily in the utilization factor, which she can change quickly. That is the kind of insight a credit audit is designed to surface.

    Which Factors You Can Change Fast vs. Slow

    One of the most useful ways to think about your credit score is by how quickly each factor responds to your actions. This helps you prioritize effort, especially if you are preparing for a specific lending decision on a known timeline.

    Fast (weeks to a single billing cycle)

    • Credit utilization. Paying down balances before your statement closing date can change your reported utilization — and your score — within one billing cycle. This is the fastest meaningful lever in the entire scoring system.
    • Credit card balances in general, for the same reason.
    • Disputing errors. If an account, late payment, or collection is reporting inaccurately and you successfully dispute it, the correction can be reflected in your score within 30 to 45 days — the time it takes the bureau to investigate and the creditor to update.

    Moderate (a few months to a year)

    • New credit inquiries. Hard inquiries fade from your score impact at around the one-year mark, so the effect of past applications naturally diminishes.
    • Recent account aging. New accounts lower your average age initially, but that effect lessens as they cross the one-year and two-year thresholds.
    • Establishing a first credit account. If you are starting from no credit, opening a secured card or credit-builder loan and paying it on time will begin generating a score within about six months under FICO, sooner under VantageScore.

    Slow (years)

    • Payment history. You cannot erase a legitimate late payment quickly. The only remedies are time (it ages and eventually falls off at seven years for most late payments) or a goodwill removal request to the creditor, which is not guaranteed.
    • Length of credit history. This is purely a function of time. You can protect it by keeping old accounts open, but you cannot accelerate it.
    • Credit mix. This develops as you take on installment loans for real needs — a car, a home, education. Forcing it with unnecessary debt is counterproductive.
    • Major negative items. Bankruptcies remain for 7 to 10 years. Foreclosures, repossessions, and collections remain for up to 7 years. Their impact fades with time, but the timeline is set by law and reporting rules, not by your behavior.

    The practical takeaway

    If you have a specific goal — buying a house in six months, refinancing a car next quarter — focus first on the fast factors: pay down revolving balances, dispute any reporting errors, and avoid new applications. Then let the slower factors continue their work in the background.

    If you have no immediate goal, focus on building the durable factors: perfect payment history, keeping old accounts open, and letting time compound. The fast factors will be there when you need them.

    Common Misconceptions About Credit Scoring

    A lot of what people “know” about credit scoring is wrong. Here are the misconceptions we hear most often, and the truth behind each one.

    Misconception 1: “Checking my credit lowers my score.”

    False. Checking your own credit is a soft inquiry and has zero impact on your score, no matter how often you do it. Only hard inquiries — which result from you applying for credit — can affect your score. You can and should check your credit regularly.

    Misconception 2: “Carrying a balance on my credit card builds my score faster.”

    False. There is no scoring benefit to carrying a balance. Paying in full each month — so no interest accrues — is just as good for your score as carrying a balance, and it saves you money. The score cares about your reported balance and your payment history, not whether you paid interest.

    Misconception 3: “Closing an old card I don’t use helps my score.”

    False — and often the opposite. Closing an old card can shorten your credit history and reduce your total available credit, which raises your utilization. Both effects can lower your score. Unless the card has a fee you cannot justify, keeping it open is usually the better move.

    Misconception 4: “My income affects my credit score.”

    False. Your income is not in your credit score. Lenders consider income separately, in their own underwriting, but the scoring model does not see it. A high income does not produce a high score; a low income does not produce a low one.

    Misconception 5: “Paying off a collection immediately removes it from my report.”

    False, under most scoring models in common use. Paying or settling a collection updates the status to “paid,” but the collection can remain on your report for up to seven years from the original delinquency. FICO 9 and VantageScore 3.0+ ignore paid collections in scoring, but FICO 8 — still widely used — does not. Paying it is the right thing to do, but it may not produce an immediate score jump.

    Misconception 6: “A high credit limit hurts my score.”

    False. A higher credit limit, all else equal, helps your score by lowering your utilization ratio. The risk is behavioral — if a higher limit tempts you to spend more, that is a problem you create, not one the scoring model imposes.

    Misconception 7: “Credit repair companies can remove accurate negative items.”

    Be skeptical. Under the FCRA, you have the right to dispute inaccurate information, and the bureaus must investigate. But accurate negative items — a late payment you really made, a collection you really owe — cannot be legally removed before their reporting expiration just because you pay someone to challenge them. If a company promises to remove accurate negative items, that promise is not one they can keep honestly. Legitimate credit repair focuses on verifiable inaccuracies, incomplete reporting, and items past their reporting window — not on erasing accurate history.

    Misconception 8: “All debt is bad for your credit score.”

    False. The score measures how you manage credit, not whether you have it. Responsibly managed installment debt (a mortgage, an auto loan, student loans) contributes positively to your payment history and your credit mix. The issue is not whether you have debt; it is whether you pay it on time and keep your revolving balances low relative to your limits.

    Frequently Asked Questions

    1. How often is my credit score updated?

    Your score is not updated on a fixed schedule. It is recalculated each time a lender requests it, based on the data in your credit report at that moment. Because creditors report to the bureaus throughout the month — typically once per billing cycle — your report changes continuously, and so does the score that would be produced from it. In practice, meaningful changes usually appear within 30 to 45 days of a change in your credit behavior, as that is the typical reporting cycle for most creditors.

    2. What is a “good” credit score?

    Under the FICO 300–850 scale, score ranges are generally categorized as:

    • 300–579: Poor
    • 580–669: Fair
    • 670–739: Good
    • 740–799: Very good
    • 800–850: Exceptional

    A score of 670 or above is generally considered good and will qualify you for most mainstream credit products. A score of 740 or above typically unlocks the best interest rates and terms. That said, every lender sets its own thresholds, and a “good” score for one product (say, a mortgage) may differ from a “good” score for another (a rewards credit card).

    3. How long does a late payment stay on my credit report?

    A late payment can remain on your credit report for up to seven years from the date of the delinquency. Its impact on your score fades over time — a late payment from five years ago weighs far less than one from five months ago — but it remains visible on the report for the full reporting period. If a late payment is reported inaccurately, you have the right under the FCRA to dispute it.

    4. Does shopping for a mortgage hurt my credit?

    If you cluster your mortgage applications within a short window — typically 14 to 45 days, depending on the scoring model version — the multiple inquiries are scored as a single inquiry for scoring purposes. This is designed to let you shop for the best rate without penalty. The single inquiry may have a small, temporary effect on your score, but it is far less than the cumulative effect of several separate inquiries would be.

    5. Can I get a mortgage with a less-than-perfect credit score?

    Yes. Many mortgage programs accept scores well below the “exceptional” range. FHA loans, for example, can accept scores as low as 580 (and sometimes lower with a larger down payment). Conventional loans typically require a minimum of 620, though better rates come with higher scores. VA loans and USDA loans have their own guidelines. If your score is not where you want it to be, a credit audit can help you identify the specific moves that will get you over the threshold for the loan you want.

    6. Will my credit score be the same at all three bureaus?

    Often not exactly. Your three bureau reports may contain slightly different data — because not every creditor reports to every bureau, and reporting timing varies — so the scores generated from each can differ. Differences are usually small (a few points), but can be larger if an account appears at one bureau and not another. For mortgages, lenders typically pull all three and use the middle score.

    7. How can I rebuild my credit after a major negative event like bankruptcy?

    Rebuilding takes time, but it is absolutely possible. The path generally involves:

    1. Making sure the bankruptcy is reported accurately and that accounts included in it are marked as discharged or included, not as open and delinquent.
    2. Establishing a new positive credit line — often a secured credit card — as soon as you are able.
    3. Paying every new obligation on time, every time. Recent positive behavior begins to offset the older negative item.
    4. Keeping utilization low on any new revolving accounts.
    5. Being patient. A Chapter 7 bankruptcy remains on your report for up to 10 years; a Chapter 13 for up to 7 years. The impact diminishes well before it falls off, especially if you build a strong recent history.

    The timeline is real, but so is the path forward. Many people see meaningful improvement within two to three years of disciplined rebuilding, even before the bankruptcy is fully removed.

    8. Does paying off my auto loan early help my credit score?

    Not directly, and it can sometimes cause a small, temporary dip. Paying off an installment loan closes the account, which can slightly reduce your credit mix (if it was your only installment account) and shorten your average account age. The on-time payment history remains on your report and continues to help.

    Financially, paying off a loan early is usually smart if it saves you interest — but do not expect a score boost from it, and be aware it may cause a brief, small decrease.

    Ready to See Where You Stand?

    Understanding how your credit score is calculated is the first step. The next is seeing how those five factors are playing out in your actual credit profile — and knowing exactly which moves will move the needle for your specific situation.

    That is what a credit audit is for. A thorough audit examines your reports across all three major bureaus, identifies inaccuracies, flags items that may be disputable under the FCRA, evaluates each of the five factors against your personal profile, and maps out a realistic, prioritized plan for improvement — no quick-fix promises, no generic advice, just an honest assessment and a clear path forward.

    If you are preparing for a major purchase, recovering from a setback, or simply want to understand your credit better, we would be glad to help. We are a San Diego-based, attorney-backed credit repair firm operating in full compliance with federal credit law, serving clients nationwide. We do not just work on your credit — we equip you with the knowledge to keep it strong for the long term.

    Get your free credit audit at credit-repair.com →

    No pressure, no obligation. Just a clear picture of where you stand and what your options are.

    This article is for educational purposes and does not constitute legal or financial advice. Your individual credit situation is unique. For a personalized review, request a credit audit and speak with a qualified professional.

  • Does Closing a Credit Card Hurt Your Score? (The Real Answer)

    Does Closing a Credit Card Hurt Your Score? (The Real Answer)

    You’ve probably heard the advice a hundred times: “Never close a credit card it’ll tank your score.”

    It’s one of the most repeated rules in personal finance. It’s also one of the most misunderstood.

    Here’s the truth: closing a credit card can hurt your credit score but not always, not always by much, and not for the reason most people think. In some cases, closing a card is genuinely the right move for your financial health, and the credit-score impact is small and temporary.

    In this guide, we’ll walk through what actually happens to your score when you close a card, when it matters most, when it doesn’t, and how to close a card the right way if you decide it’s time. No scare tactics, no quick-fix promises just a clear, honest breakdown so you can make the call with confidence.

    The Short Answer

    Does closing a credit card hurt your score? It can but the real answer depends on two things: your credit utilization and the age of your other accounts.

    When you close a credit card, you lose that card’s credit limit. If you carry balances on other cards, your overall utilization ratio (how much of your available credit you’re using) can go up and that’s the change that most commonly drags your score down. Utilization is one of the most heavily weighted factors in your credit score, accounting for about 30% of your FICO Score.

    The second common worry that closing a card shortens your credit history is mostly a myth in the short term. A closed account in good standing stays on your credit report for up to 10 years, and it continues to count toward your average age of accounts during that time. So the length-of-history impact is delayed, not immediate.

    So:

    • If the card has a high credit limit and you carry balances elsewhere, closing it can raise your utilization and lower your score sometimes noticeably.
    • If the card has a small limit, or you pay your balances in full each month, the impact may be minimal or even unmeasurable.
    • If it’s your only or oldest card, closing it carries more risk because you’re shrinking your credit profile and, eventually, your average account age.
    • If you have several other older accounts in good standing, closing one card is unlikely to do meaningful damage.

    The decision isn’t “never close a card.” It’s “close the right card, at the right time, the right way.” Let’s look at the mechanics.

    The Two Main Impacts of Closing a Card

    When you close a credit card, two parts of your credit score can be affected: credit utilization and length of credit history. Let’s take each one apart.

    Impact #1: Credit Utilization (The One That Usually Matters Most)

    Credit utilization is the percentage of your available credit that you’re currently using. It’s calculated both per card and across all your cards combined.

    For example, say you have two cards:

    Card Credit Limit Balance Utilization
    Card A $10,000 $2,000 20%
    Card B $5,000 $0 0%
    Total $15,000 $2,000 13.3%

    Your overall utilization is 13.3% well within the healthy range (most experts recommend keeping it under 30%, and under 10% is even better for top-tier scores).

    Now suppose you close Card B because you never use it. Your available credit drops from $15,000 to $10,000. Your balance stays at $2,000. Your new utilization:

    New utilization = $2,000 ÷ $10,000 = 20%

    That’s a jump from 13.3% to 20% still under 30%, but higher. Your score may dip a little.

    Now consider a more dramatic example. Same two cards, but you carry more debt:

    Card Credit Limit Balance Utilization
    Card A $10,000 $4,500 45%
    Card B $5,000 $0 0%
    Total $15,000 $4,500 30%

    Close Card B, and your available credit falls to $10,000 while your balance stays at $4,500:

    New utilization = $4,500 ÷ $10,000 = 45%

    You’ve gone from 30% to 45% — crossing well above the 30% threshold that FICO treats as a yellow flag. That kind of jump can produce a meaningful score drop, sometimes 20–50 points or more depending on the rest of your profile.

    Why this matters so much: Utilization is evaluated instantaneously. Unlike payment history, which builds over time, your utilization is recalculated every time a card issuer reports your balance to the credit bureaus (usually once a month, on your statement closing date). That means a utilization change from closing a card can show up on your score within a single billing cycle.

    The key takeaway: The utilization impact from closing a card depends entirely on whether you carry balances on other cards and how large the closed card’s limit was relative to your total credit.

    • No balances anywhere? Closing a card typically has little to no utilization impact.
    • Carrying balances? Closing a high-limit card can push your utilization up and your score down.

    Impact #2: Length of Credit History (The One People Get Wrong)

    This is where most of the confusion lives.

    A lot of people believe that the moment you close a credit card, it disappears from your credit report and your “credit age” resets. That’s not how it works.

    Here’s what actually happens:

    • When you close a credit card that’s in good standing (no late payments, not charged off), the account stays on your credit report for up to 10 years from the date of closure.
    • During that entire period, the closed account continues to be factored into your average age of accounts (AAoA) and your oldest-account age two metrics that influence the “length of credit history” portion of your score (about 15% of your FICO Score).
    • Only after the account finally falls off your report roughly a decade later does it stop contributing to your credit history length.

    So if you close a 12-year-old card today, it keeps helping your average account age until you’re 22 years out. By then, your other accounts will have aged considerably, softening the impact.

    This is the nuance most people miss: The length-of-history impact from closing a card isn’t immediate. It’s delayed by years, often a decade. The thing that does hit quickly is utilization.

    There’s one important exception: if the closed card was your only credit account or your oldest by a wide margin, the eventual drop-off matters more because you’ll have less depth to absorb it. We’ll cover that in the next section.

    The key takeaway: Don’t close a card out of fear that your credit history will vanish overnight. It won’t. A closed account in good standing keeps working for you for years. The urgency around “never close a card” is mostly about utilization, not history.

    When Closing a Card Hurts Most

    Not every closure carries the same risk. Closing a card is most likely to hurt your score when one or more of the following is true.

    1. It’s your only credit card (or one of very few)

    Credit scoring models reward a diverse, established credit profile. If you only have one or two credit cards, closing one shrinks your credit picture significantly.

    With fewer open accounts, your utilization becomes more volatile (one balance can swing the ratio dramatically), and your file looks thinner to lenders.

    If you’re going to close your only card, it’s worth opening a replacement first (or exploring alternatives like a product change — more on that below) so you don’t end up with no revolving credit at all.

    2. It’s your oldest credit account

    Your oldest account age is a anchor point for your credit history. Closing your oldest card doesn’t erase it immediately — remember, it stays on your report for up to 10 years — but when it eventually falls off, your credit age could shorten noticeably if you haven’t added other long-standing accounts in the meantime.

    If your oldest card is your only old account, think twice. If you have several other accounts that are also 10+ years old, closing one is much lower risk.

    3. It has a large credit limit and you carry balances elsewhere

    This is the classic utilization trap. If the card you’re closing carries a big chunk of your total available credit and you maintain balances on other cards, closing it will push your overall utilization up — sometimes significantly.

    Before closing a high-limit card, do the math:

    If that number lands above 30%, expect a score dip. If it lands above 50%, expect a more noticeable one.

    4. You’re planning to apply for a major loan soon

    If you’re within 3–6 months of applying for a mortgage, auto loan, or any other major credit product, avoid unnecessary changes to your credit profile. Even small score movements can affect the interest rate you’re offered. A difference of 20 points on a mortgage can translate to thousands of dollars over the life of the loan.

    In this window, keep your credit picture stable: don’t close cards, don’t open new cards, don’t miss payments, and keep utilization low.

    5. The card has a long clean payment history you’d lose

    If the card has years of on-time payments and it’s one of your few accounts with a spotless record, closing it (and eventually losing it from your report) removes a piece of positive payment history. Payment history is the single biggest factor in your score at about 35%, so a long clean track record is worth preserving when you can.

    That said — remember the 10-year rule. The payment history doesn’t vanish the day you close the card. It keeps contributing for years. The concern is mainly about the long-term picture, not the immediate impact.

    When Closing a Card Makes Sense

    For all the talk about keeping cards open, there are absolutely situations where closing a card is the right financial decision — even if it causes a small, temporary score dip. Your credit score is a tool that serves your financial life, not the other way around.

    Here are the scenarios where closing makes good sense.

    1. You’re paying an annual fee you don’t use

    This is the most common and most defensible reason to close a card. If you’re paying $95, $250, or $450 a year for a card whose perks you no longer use, that’s pure cost with no benefit.

    Before closing, check whether the issuer offers a product change to a no-annual-fee version of the card (more on this below). A product change lets you keep the account open — preserving your credit limit and account age — while dropping the fee. If that’s not available or appealing, closing is reasonable.

    Do the math honestly: if the annual fee is $250 and you’re not getting $250 worth of value from the card, closing it saves you real money. A temporary score dip of 10–20 points is usually worth $250 a year.

    2. The card tempts you to overspend

    This one is underrated. If having a particular card in your wallet leads you to spend more than you should — maybe it’s a store card that pulls you toward impulse purchases, or a travel card that encourages trips you can’t really afford — the financial damage of overspending will far outweigh any credit-score impact from closing it.

    Credit scores don’t measure your overall financial health. They measure how you manage borrowed money. If a card is actively working against your financial goals, closing it is a legitimate choice.

    3. You have plenty of other old accounts

    If you have several other credit cards that are older than or comparable in age to the one you’re considering closing, the impact on your average account age (both now and when the closed card eventually falls off) is minimal. In this case, the length-of-history concern is mostly a non-issue, and as long as utilization is managed, closing is low risk.

    4. You’re simplifying your financial life

    Every open credit account is one more thing to monitor for fraud, one more statement to review, one more due date to track, one more potential source of missed-payment damage. If you’re consolidating your finances — maybe after a life change like marriage, divorce, or a move — closing a card or two to reduce complexity is a reasonable choice. Just be thoughtful about which cards you close.

    5. The card has poor terms and a better option exists

    If you’re holding onto a card with a high APR, a low credit limit, poor customer service, or no upgrade path, and you’ve already been approved for a better card, there’s little reason to keep the old one on life support. This is especially true if the old card’s limit is small enough that closing it won’t meaningfully change your overall utilization.

    6. A joint account situation needs resolving

    After a divorce or business partnership dissolution, you may need to close joint credit accounts to protect yourself from the other person’s spending or payment behavior. In these cases, closing is often necessary regardless of the score impact. Work with the issuer to close the account properly, and consider opening a new individual account to replace it.

    How to Close a Credit Card the Right Way

    If you’ve decided closing a card is the right move, do it carefully. A sloppy closure can create problems that are entirely avoidable. Here’s the step-by-step process.

    Step 1: Pay the balance down to zero

    You generally cannot close a card while it carries a balance — and even if the issuer allows it, it’s a bad idea. A closed account with a balance can continue to accrue interest, and you lose the ability to make new purchases to help manage cash flow.

    Pay the balance in full, or transfer it to another card with a balance transfer offer if needed. Confirm the payoff includes any pending interest charges (call the issuer to get a precise payoff amount if you’re unsure).

    Step 2: Redeem or transfer your rewards

    If the card earns cash back, points, or miles, redeem them before closing. Most issuers forfeit any unredeemed rewards the moment the account is closed. Some cards let you transfer points to another card with the same issuer or to a travel partner — check the rules for your specific card.

    Don’t leave money on the table. Even $25 in cash back is worth claiming before you shut the door.

    Step 3: Redirect recurring charges and auto-pays

    This is the step people forget — and it causes the most headaches.

    Go through your last 6–12 months of statements and identify every recurring charge on the card: subscriptions (Netflix, gym, software), utilities, insurance premiums, auto-pays, mobile phone billing, streaming services, and any memberships.

    Move each one to a different card (or to a debit card if you prefer) before closing. Then watch the next billing cycle carefully to confirm nothing slips through. A missed auto-pay on a closed card can result in a late payment or a service interruption — both of which create more headaches than the closure itself.

    Pro tip: some people keep a dedicated “bills card” that they never close and never carry a balance on, specifically to centralize recurring charges and avoid this chore in the future.

    Step 4: Call the issuer and confirm the payoff

    Ask them to confirm the account is eligible for closure and whether there are any pending transactions or fees that might post after closure.

    This phone call is worth the five minutes. It prevents the surprisingly common scenario of a tiny residual interest charge generating a balance on a closed account, which can then trigger late fees and a negative mark on your credit report if it goes unpaid.

    Step 5: Request closure in writing (or via a documented channel)

    Close the account through the issuer’s official channel — usually by phone, secure message, or online chat. Ask for written confirmation of the closure, including the date and the fact that the account was closed at your request (not by the issuer).

    The distinction matters: an account “closed by creditor” can look slightly worse to future lenders than one “closed by consumer.” Make sure your credit report reflects that you initiated the closure. If it doesn’t, you have the right to dispute it with the credit bureaus under the FCRA.

    Step 6: Keep your oldest card open

    If the card you’re closing isn’t your oldest, make sure your oldest credit card stays open and active. This preserves the anchor of your credit history and protects your average account age over the long term.

    If your oldest card has an annual fee you don’t want to pay, ask the issuer about a product change to a no-fee version (see below). Keeping the account open in some form is almost always better than closing your oldest card outright.

    Step 7: Monitor your credit report after closure

    Pull your credit report 30–60 days after closing to confirm the account is showing as “closed” and “paid” or “current” with a $0 balance. You’re entitled to a free report from each of the three bureaus every week at AnnualCreditReport.com — take advantage of it.

    If the account is still showing as open, or if it’s incorrectly reported as “closed by creditor” with a balance, file a dispute with the bureau reporting the error. Under the FCRA, inaccurate information must be corrected or removed, typically within 30 days.

    Step 8: Watch your utilization on remaining cards

    After closure, keep your balances low on your remaining cards for at least one billing cycle so the utilization change doesn’t bite harder than it needs to. If you can pay balances down before the statement closing date (not just the due date), you’ll keep the reported utilization as low as possible.

    does-closing-credit-card-hurt-score-under-100kb

    Alternatives to Closing a Card

    Before you close a card, it’s worth checking whether one of these alternatives gets you what you want without the downsides.

    Product change

    A product change is when you switch your current card to a different card within the same issuer’s portfolio — for example, converting a $95-annual-fee travel card to a no-annual-fee cash-back card from the same bank.

    Why this is often better than closing:

    • The account stays open, so your credit limit and account age are preserved.
    • No hard inquiry — product changes typically don’t require a new credit pull.
    • You keep the payment history and the account’s contribution to your credit profile.
    • You drop the fee (or get a card that better fits your spending).

    Almost every major issuer offers product changes. Call the number on the back of your card and ask: “I’m considering closing this card because of the annual fee. Can I product-change to a no-annual-fee option?” They’ll often have several choices.

    Downgrade to a no-fee card

    This is essentially a product change focused specifically on eliminating the annual fee. Many premium cards have a no-fee sibling in the same family. For example, a premium travel card might downgrade to a basic rewards card with no annual fee and fewer perks but the same credit limit and account history.

    Keep the card open but inactive

    If the card has no annual fee, you don’t actually have to use it regularly for it to help your credit. You can keep it open with a small recurring charge (like a single subscription) set to autopay in full each month. This keeps the account active, prevents the issuer from closing it for inactivity, and preserves your credit limit and account age — all without requiring you to carry the card or think about it.

    A warning on inactivity: issuers can close accounts for inactivity, typically after 12–24 months of no usage. An involuntary closure for inactivity looks the same on your credit report as a closure by the creditor and can still affect your utilization. So if you’re keeping a card open for credit-building purposes, put one small recurring charge on it and set it to autopay. Set it and forget it.

    Request a credit limit increase on another card first

    If your reason for hesitation is the utilization impact, you can ask for a credit limit increase on another card before closing the one you want to drop. If approved, the new limit can offset the limit you’re losing, keeping your overall utilization roughly the same.

    This does sometimes involve a hard inquiry, so check with the issuer about whether they’ll do a soft-pull increase (many will if you ask). A soft pull has no impact on your score.

    Open a new card before closing the old one

    If the card you’re closing has a meaningful credit limit and you want to preserve your total available credit, you can open a new card with a comparable limit first, then close the old one. Your total available credit stays about the same, and your utilization is unchanged.

    The trade-off: the new card will come with a hard inquiry and will lower your average account age slightly. But if the new card has better terms, no annual fee, and a similar limit, this can be a net positive. Just avoid doing this if you’re planning to apply for a mortgage or auto loan in the next 6 months.

    How to Offset the Utilization Hit

    If closing a card will push your utilization up, here are concrete ways to soften or eliminate the impact.

    Pay down balances on your other cards

    This is the most direct and effective method. Since utilization is a ratio — balances divided by available credit — lowering the numerator (your balances) offsets losing credit limit from the denominator.

    For example, if closing a card will move you from $15,000 to $10,000 in available credit, and you currently carry $3,000 in balances, your utilization would jump from 20% to 30%. But if you pay down $1,000 before closing, your new utilization would be:

    $2,000 ÷ $10,000 = 20%

    You’ve neutralized the impact entirely. Paying down debt is also the single best thing you can do for your overall financial health, so this is a win-win.

    Ask for credit limit increases on your remaining cards

    As mentioned above, you can request limit increases on your other cards to replace the limit you’re losing. Many issuers will grant these with a soft credit pull (no score impact) if your account is in good standing and you haven’t had a recent increase.

    Call or use the issuer’s online portal to request an increase. If they ask whether they can do a hard pull, you can decline and try again later or with a different issuer.

    Time the closure strategically

    If you have the flexibility, time your card closure around your billing cycles. Wait until right after your statements close and balances are reported as low (or zero), then close the card. This gives you a window where your reported utilization is already favorable, and any dip from the closure is less likely to be compounded by a high balance reporting at the same time.

    Open a new card (with caution)

    Opening a new card adds available credit, which can offset the loss from closing another. But be aware:

    • The new application triggers a hard inquiry (small, short-term score impact, usually 1–5 points).
    • The new account lowers your average account age temporarily.
    • You’ll need good enough credit to be approved.

    If you were planning to get a new card anyway, doing it around the same time as closing an old one can be a smart move — the new limit replaces the old one, and you end up with a card that better fits your needs.

    Use the “AZEO” method before a major application

    If you’re closing a card and also planning to apply for a major loan soon, consider the AZEO (All Zero Except One) strategy: pay all your cards to $0 except one, and let that one report a small balance (under 10% of its limit). This produces the lowest possible utilization score and can offset the impact of a recent closure. Just be sure to execute this at least 30–60 days before your loan application so the low balances have time to report.

    Common Myths About Closing Credit Cards

    Let’s clear up some of the most persistent misconceptions.

    Myth 1: “Closing a card immediately removes it from your credit report.”

    False. A closed account in good standing stays on your report for up to 10 years and continues to contribute to your average account age and payment history during that time. Only negative-information accounts (like charge-offs or accounts closed by the creditor with a balance) drop off sooner — typically after 7 years.

    Myth 2: “Closing a card always hurts your score.”

    Not always. If you pay your balances in full every month and have several other older accounts, closing a card may have a negligible impact — sometimes zero measurable change. The score effect depends on your utilization, your overall credit profile, and which card you’re closing.

    Myth 3: “You should never close your oldest card.”

    Mostly true, but not absolute. Your oldest card is valuable because it anchors your credit history length. But if it has an annual fee, poor terms, and you have other accounts that are nearly as old, the math may favor closing it — especially if you can product-change it to a no-fee version instead. The blanket rule oversimplifies a decision that should be based on your full profile.

    Myth 4: “Closing a card erases the payment history on it.”

    False. The payment history — including all those years of on-time payments — stays on your report along with the account for up to 10 years after closure. You don’t lose the positive history the day you close the card.

    Myth 5: “Closing a card helps your score because it shows you’re being responsible.”

    False. Credit scoring models don’t interpret closure as a signal of responsibility or irresponsibility. They simply recalculate your score based on the updated data — utilization, account ages, payment history, and so on. Closing a card doesn’t earn you any “good behavior” credit.

    Myth 6: “A closed account stops aging your credit history.”

    False. A closed account in good standing continues to age while it’s on your report. A card you’ve had for 8 years and then close will show as 9, 10, 11 years old in subsequent years, right up until it falls off at the 10-year mark.

    Myth 7: “Store cards don’t matter if you close them.”

    False. Store cards are real credit accounts reported to the bureaus. Closing one affects your utilization and account age just like any other card. The main difference is that store cards often have lower limits, so the utilization impact per card is usually smaller — but they still count.

    Myth 8: “You can close a card online and it’s done instantly with no consequences.”

    Partially true, but risky. You can often initiate closure online, but you still need to handle the pre-closure checklist: pay to zero, redeem rewards, redirect auto-pays, and confirm the $0 balance. Skipping these steps can leave you with residual balances, lost rewards, or missed recurring charges that turn into late payments.

    Frequently Asked Questions

    Q1: How many points will my score drop if I close a credit card?

    There’s no fixed number — it depends on your full credit profile. If you pay your balances in full and have several other old accounts, the drop may be 0–10 points or unmeasurable. If closing the card pushes your utilization from under 30% to over 50%, you could see a drop of 20–50 points or more. The biggest factor is almost always the change in your utilization ratio, not the closure itself.

    Q2: Should I close my oldest credit card?

    Usually no — your oldest card anchors your credit history length, and keeping it open preserves that anchor for as long as the account stays on your report (up to 10 years after closure, but keeping it open keeps it on your report indefinitely). If the card has an annual fee, try a product change to a no-fee version first. If that’s not possible and the fee isn’t worth it, closing may be justified — but explore alternatives before you do.

    Q3: Does closing a credit card with a zero balance hurt your score?

    It can, but usually less than closing one with a balance. The main risk is the utilization impact from losing the credit limit. If you have no balances on any of your cards, closing a zero-balance card has minimal score impact because your utilization is already 0%. If you carry balances elsewhere, losing the limit can still raise your overall utilization even though the closed card itself had a zero balance.

    Q4: How long does a closed credit card stay on my credit report?

    A closed account in good standing stays on your report for up to 10 years from the date of closure. A closed account with negative information (late payments, charge-off) stays for up to 7 years from the date of the first delinquency. During the time it’s on your report, a good-standing closed account continues to contribute positively to your payment history and average account age.

    Q5: Is it better to close a card or just stop using it?

    If the card has no annual fee, it’s usually better to stop using it (or use it for one small recurring charge) rather than close it. This keeps your credit limit, account age, and payment history intact. If the card has an annual fee you don’t use, closing it (or product-changing to a no-fee version) makes more sense. For cards with no fee that you simply don’t want to carry, put a single small subscription on it and set it to autopay — this prevents the issuer from closing it for inactivity while keeping your credit profile strong.

    Q6: Can I close a credit card with a balance?

    Technically you can, but it’s almost always a bad idea. The balance continues to accrue interest, you lose the ability to make new purchases, and some issuers may raise your APR or demand payment in full. You also can’t redirect the credit limit elsewhere. Pay the balance to zero first, or transfer it to a balance transfer card, then close.

    Q7: Will closing a credit card affect my ability to get new credit?

    It can, indirectly. A lower credit score from a utilization increase may affect approval odds or the interest rates you’re offered. Additionally, if closing a card leaves you with very few open accounts, lenders may see your file as thin. However, if you have a strong overall profile with several open accounts and a solid payment history, closing one card is unlikely to meaningfully affect your ability to get new credit.

    Q8: Does closing a card hurt your score more if you have bad credit?

    Generally yes. If your credit profile is already thin or has some negative marks, any change — including a utilization increase from closing a card — tends to have a bigger relative impact. People with long, diverse credit histories and high scores have more “buffer” to absorb small changes. If you’re working to rebuild your credit, it’s usually best to keep accounts open and focus on paying down balances and making on-time payments.

    When to Get Professional Help

    If you’re reading this because you’re trying to improve your credit and you’re not sure which cards to keep, which to close, or what your next move should be — that’s exactly where a professional credit review can help.

    A credit audit looks at your full profile across all three major bureaus — Experian, Equifax, and TransUnion — and identifies:

    • Accounts that are helping or hurting your score
    • Inaccuracies that may be dragging your score down (and that you have the right to dispute under the FCRA)
    • Opportunities to optimize your utilization, account mix, and payment strategy
    • A clear, personalized plan for improving your credit over time

    At credit-repair.com, we’re a San Diego-based, attorney-backed credit repair firm that helps individuals and families nationwide take control of their financial future. We don’t make empty promises or sell quick fixes. We do honest, results-driven work: in-depth credit audits, disputes of inaccurate information, negotiations with creditors, and customized repair plans tailored to your goals — all in full compliance with federal credit laws, including the Fair Credit Reporting Act (FCRA).

    Whether you’re trying to figure out if closing a card is the right move, dealing with inaccurate negative marks on your report, or just want a clear picture of where your credit stands and how to improve it, a free credit audit is the best place to start.

    Get your free credit audit at credit-repair.com →

    You’ll get a clear, no-pressure review of your credit profile and a straightforward plan for what to do next — no hidden fees, no misleading claims, no unnecessary services. Just honest guidance from a team that treats your financial future like their own.

    The Bottom Line

    The old advice — “never close a credit card” — is too simple to be useful. The real question isn’t whether closing a card hurts your score; it’s whether closing this card, in your situation, at this time, makes sense.

    Here’s the framework to use:

    1. Check your utilization. If closing the card will push your overall utilization above 30%, expect a score dip. Pay down balances or increase limits elsewhere to offset it.
    2. Check your account age. If it’s your oldest or only card, think twice. If you have several other old accounts, the length-of-history impact is minimal — and delayed by up to 10 years anyway.
    3. Check the fee. If you’re paying an annual fee for perks you don’t use, closing (or product-changing) is usually worth a temporary score dip.
    4. Check your timeline. If you’re applying for a major loan in the next 3–6 months, hold off on changes. Keep your profile stable.
    5. Close it the right way. Pay to zero, redeem rewards, redirect auto-pays, confirm the $0 balance, get written confirmation, and monitor your report afterward.

    Your credit score is a tool. It exists to serve your financial life — not the other way around. When you understand how closing a card actually works, you can make the decision with confidence instead of fear.

    And if you want a second set of eyes on your full credit picture before you make a move, that’s exactly what we’re here for.

    Start with a free credit audit at credit-repair.com →

    Disclaimer: This article is for educational purposes only and does not constitute legal or financial advice. Your individual credit situation is unique. For personalized guidance, request a free credit audit or consult with a qualified financial advisor.

  • Unsecured vs. Secured Credit Cards: Which Is Right for You?

    Unsecured vs. Secured Credit Cards: Which Is Right for You?

    If you’re working to build or rebuild your credit, one of the first decisions you’ll face is whether to apply for a secured credit card or an unsecured credit card. It’s a choice that affects your upfront costs, your approval odds, your monthly payments, and the speed at which your credit score climbs. And unfortunately, the marketing around both types is often confusing, vague, or designed to push you toward a product that may not serve your long-term goals.

    That’s why we wrote this guide. We’re a San Diego-based, attorney-backed credit repair firm, and every day we help people across the country understand exactly how credit works — not in hype-driven snippets, but in plain, honest language. We believe that the more you understand about the tools in front of you, the better decisions you’ll make for your financial future. No quick fixes. No false promises. Just the facts, the trade-offs, and a clear path forward.

    This article walks you through everything you need to know about secured and unsecured credit cards: what each one is, how they differ, who they’re designed for, how they affect your credit score, and how to move from one to the other when the time is right. By the end, you’ll have a confident answer to the question: which is right for you?

    What Is a Secured Credit Card?

    A secured credit card is a credit card that requires you to put down a refundable cash deposit before you’re approved. That deposit becomes your credit limit in most cases — so if you deposit $300, your card will typically have a $300 spending limit. If you deposit $500, your limit is usually $500.

    The word “secured” refers to the fact that the card issuer is protected by your deposit. If you stop paying your bill, the lender can keep your deposit to cover the outstanding balance. This arrangement lowers the lender’s risk, which is why secured cards are available to people who might not qualify for other types of credit.

    Here’s the most important thing to understand: a secured card is still a real credit card. It functions like any other credit card in day-to-day use:

    • You make purchases with it at stores, online, and anywhere credit cards are accepted.
    • You receive a monthly statement showing your balance, minimum payment, and due date.
    • You’re expected to pay your bill on time each month.
    • Your payment activity is reported to the three major credit bureaus — Equifax, Experian, and TransUnion.

    That last point is the key. The purpose of a secured card isn’t really to give you a line of credit — it’s to give you a credit-building tool. Every on-time payment you make is reported to the bureaus and helps establish a positive payment history, which is the single most important factor in your credit score.

    Your deposit is not a fee. It’s held in a separate account by the card issuer, usually interest-bearing (though the interest is minimal). As long as you manage the card responsibly — paying on time, keeping your balance low, and not defaulting — you’ll get that deposit back when you close the account or upgrade to an unsecured card with the same issuer.

    Most secured cards require a minimum deposit between $200 and $300, and many allow you to deposit more to increase your credit limit. Some issuers let you add to your deposit over time, gradually raising your limit as your financial situation improves. A growing number of secured cards also offer a feature called a credit limit increase without an additional deposit after a period of on-time payments, which can be a helpful stepping stone.

    One common point of confusion: a secured credit card is not the same as a prepaid debit card. With a prepaid card, you load money onto the card and spend it down — there’s no credit being extended, no monthly bill, and no reporting to the credit bureaus. A prepaid card does nothing for your credit score. A secured credit card, by contrast, involves a real line of credit that you borrow against and repay, and your activity is reported to the bureaus just like any other credit card.

    If you’re starting from scratch no credit history at all or if you’re rebuilding after financial setbacks like missed payments, collections, or a bankruptcy, a secured card is often the most accessible and lowest-risk way to begin establishing positive credit.

    What Is an Unsecured Credit Card?

    An unsecured credit card is what most people picture when they hear the phrase “credit card.” It’s a traditional credit card that does not require a cash deposit. The card issuer extends you a line of credit based on your creditworthiness — your credit history, credit score, income, and overall financial profile — and trusts you to repay what you borrow.

    The word “unsecured” means the lender has no collateral backing the loan. If you don’t pay, they can’t seize a specific asset the way a lender could repossess a car or foreclose on a house. Instead, they rely on the strength of your credit profile and their ability to pursue repayment through collections, charge-offs, or, in extreme cases, legal action. Because the lender is taking on more risk, they’re more selective about who qualifies.

    An unsecured credit card works like this:

    • You’re approved for a credit limit based on your credit profile and income — this could be anywhere from $500 to $25,000 or more.
    • You make purchases up to your credit limit.
    • Each month, you receive a statement and can choose to pay the full balance, a portion of it, or the minimum payment.
    • If you carry a balance, you’re charged interest at the card’s APR (annual percentage rate).
    • Your payment activity is reported to all three major credit bureaus.

    Unsecured cards come in a wide range of tiers, from basic “starter” unsecured cards designed for people with fair credit to premium rewards cards aimed at those with excellent credit scores (typically 740 and above). The features, benefits, interest rates, and fees vary dramatically across these tiers:

    • Entry-level unsecured cards may have low credit limits, higher APRs, and few or no rewards. Some carry annual fees.
    • Mid-tier unsecured cards often offer modest cash back or points programs, moderate APRs, and perks like no foreign transaction fees.
    • Premium unsecured cards may offer generous sign-up bonuses, travel benefits, airport lounge access, and premium purchase protections — but they typically require excellent credit and may charge higher annual fees.

    Because an unsecured card doesn’t require a deposit, it’s more accessible from a cash-flow perspective — you don’t need to tie up hundreds of dollars upfront. But the approval bar is higher. Lenders want to see a track record of responsible credit use before they’ll extend an unsecured line.

    The unsecured credit card is the goal for most people who are building or rebuilding credit. It represents a level of trust from the financial system, offers more flexibility and purchasing power, and typically comes with better terms than a secured card. But it’s not where everyone starts — and that’s okay. The journey from a secured card to an unsecured one is a normal, expected part of building strong credit.

    Secured vs. Unsecured Credit Cards: The Key Differences

    Now that you understand what each type of card is, let’s put them side by side. The table below summarizes the most important differences between secured and unsecured credit cards so you can compare them at a glance.

    Feature Secured Credit Card Unsecured Credit Card
    Deposit required? Yes — typically $200–$300 minimum, refundable No deposit required
    Credit limit Usually equals your deposit (some issuers allow increases over time) Set by the issuer based on creditworthiness; can range from $500 to $25,000+
    Approval requirements Low — designed for bad or no credit; income verification may be required Moderate to high — requires fair to excellent credit depending on the card
    Risk to the lender Low — deposit acts as collateral Higher — no collateral backing the line of credit
    Interest rates (APR) Often higher than standard unsecured cards, though varies widely Varies widely — from low-teens for excellent credit to high-20s for subprime unsecured cards
    Annual fees Common, usually $25–$50; some no-fee options exist Varies — many no-annual-fee cards available; premium cards may charge $95–$500+
    Rewards and perks Rare; a few secured cards offer modest cash back Common — cash back, travel points, sign-up bonuses, purchase protections
    Reports to credit bureaus? Yes — all three major bureaus (confirm before applying) Yes — all three major bureaus
    Effect on credit score Same as unsecured — bureaus don’t distinguish between secured and unsecured in scoring Same as secured — payment history and utilization matter most
    Path to upgrade Many issuers allow graduation to unsecured after consistent on-time payments N/A — already unsecured; may qualify for better terms as credit improves
    Best for Building or rebuilding credit from a low starting point People with fair to excellent credit who want flexibility, rewards, and no deposit

    Let’s unpack a few of these differences in more detail, because the nuance matters.

    Deposit and Cash Flow

    The deposit is the most visible difference between the two card types. With a secured card, you need to have cash on hand to fund the deposit — usually $200 to $300 at minimum. That money is tied up for as long as you keep the card open. With an unsecured card, no deposit is required, so your cash stays available for other uses. For people living paycheck to paycheck, this is a meaningful distinction.

    Approval Odds

    Secured cards are designed for people who are building or rebuilding credit. Issuers are generally willing to approve applicants with thin credit files, past delinquencies, or even recent bankruptcies (though some require the bankruptcy to be discharged). Unsecured cards have stricter approval standards. Entry-level unsecured cards may accept applicants with fair credit (typically 580–669), but the best terms go to those with good or excellent credit.

    Fees and APR

    Secured cards often carry annual fees, though several reputable issuers now offer no-annual-fee secured cards. Their APRs tend to be on the higher side — often in the mid-20s — because the issuer is lending to higher-risk borrowers. However, if you pay your balance in full each month, the APR doesn’t matter; you won’t be charged interest.

    Unsecured cards span a wider range. No-annual-fee options are plentiful for people with good credit, and APRs can be quite competitive. Premium cards may charge annual fees but offer benefits that can offset them if you use the card enough. Subprime unsecured cards — those marketed to people with bad credit — can carry exorbitant fees and APRs, which we’ll discuss in detail later.

    Credit Limit and Purchasing Power

    A secured card’s credit limit is constrained by your deposit. If you can only afford a $300 deposit, your limit is $300 — which limits both your purchasing power and your ability to keep your credit utilization low (more on that in the credit score section). An unsecured card’s limit is set by the issuer and can grow over time as you demonstrate responsible use, giving you more flexibility.

    Rewards and Benefits

    Most secured cards don’t offer rewards. A handful provide modest cash back on certain categories, but these are the exception. Unsecured cards, especially mid-tier and premium options, offer rewards programs that can return 1–5% of your spending in cash, points, or miles. For people who use credit cards for everyday spending and pay the balance in full, these rewards add real value.

    The bottom line: a secured card is a stepping stone, not a destination. It’s a tool to help you build the credit profile you need to qualify for an unsecured card with better terms. An unsecured card is the destination — but it’s a destination that’s earned through consistent, responsible credit use over time.

    Who Should Get a Secured Credit Card?

    A secured credit card isn’t for everyone, but for certain situations, it’s the single best tool available for building or rebuilding credit. Here’s how to know if a secured card is the right choice for you.

    You Have No Credit History

    If you’re young, new to the country, or have simply never used credit before, you may have a “thin” credit file — meaning the credit bureaus don’t have enough information about you to generate a score. Lenders see thin files as risky because they have no evidence of how you handle credit. A secured card is one of the most reliable ways to build that history from nothing. Because the deposit reduces the lender’s risk, approval standards are low, and you can start establishing a payment record immediately.

    You Have Bad Credit

    If your credit score is below 580 — often referred to as the “poor” range — you may have difficulty qualifying for most unsecured cards. A secured card gives you a way to rebuild positive credit history while demonstrating to future lenders that you can manage a credit account responsibly. Every on-time payment is a data point that pushes your score in the right direction.

    You’re Recovering From a Major Financial Setback

    Bankruptcy, foreclosure, repossession, significant collections, or a period of missed payments can devastate your credit score. Recovering from these events takes time, and a secured card can be part of a deliberate rebuilding strategy. Many secured card issuers will approve applicants with a discharged bankruptcy, and some don’t even require a credit check — they use alternative data like income and banking history to make approval decisions.

    You Want to Build Credit Without the Temptation of a Large Credit Line

    Because a secured card’s limit equals your deposit, it naturally constrains your spending. For people who are working on financial discipline and don’t want the temptation of a large credit line, this can be a feature, not a bug. You can build a positive payment history with small, manageable purchases — a tank of gas, a recurring subscription, a grocery run — and pay them off each month.

    You Want Guaranteed Approval (Almost)

    While no credit card offers truly guaranteed approval, secured cards come close. The deposit eliminates most of the lender’s risk, so issuers are far more lenient. If you can fund the deposit and verify your identity and income, your odds of approval are very high — even with a rocky credit past.

    What to Look For in a Secured Card

    Not all secured cards are created equal. When choosing one, look for:

    • Reports to all three bureaus. This is non-negotiable. If a card doesn’t report to Equifax, Experian, and TransUnion, it won’t help your credit. Confirm this before applying.
    • Low or no annual fee. There are excellent secured cards with no annual fee. Avoid cards that charge high annual or monthly maintenance fees.
    • A reasonable minimum deposit. $200 is standard. Avoid cards that require unusually high deposits for low limits.
    • A path to graduation. Some issuers will review your account after 6–12 months of on-time payments and offer to upgrade you to an unsecured card, returning your deposit. This is a valuable feature.
    • No application or processing fees. Reputable secured cards don’t charge these. If a card does, it’s a red flag.

    A secured card is a means to an end. Use it consistently, pay on time every month, keep your balance low, and let it do its job: building the credit history you need to move on to better products.

    Who Should Get an Unsecured Credit Card?

    An unsecured credit card is the right choice when your credit profile is strong enough to qualify for one with reasonable terms. Here’s how to know if you’re ready.

    You Have Fair Credit or Better

    If your credit score is 580 or above — and especially if it’s 670 or above (the “good” range) — you’re likely a candidate for an unsecured card. Entry-level unsecured cards may accept scores in the 580–669 range, while better terms and rewards become available as your score climbs into the 700s.

    You Don’t Want to Tie Up Cash in a Deposit

    If you’d rather keep your cash available for emergencies, savings, or everyday expenses, an unsecured card’s no-deposit structure is a clear advantage. You get the credit-building benefits of a credit card without locking up $200–$500 in a refundable deposit.

    You Want Rewards or Better Terms

    If you use a credit card for regular spending and pay the balance in full each month, an unsecured rewards card can put money back in your pocket. Cash back, travel points, and sign-up bonuses have real value when you’re not paying interest. Unsecured cards also tend to offer lower APRs, better purchase protections, and perks like extended warranties and travel insurance.

    You’ve Already Built a Positive Payment History

    If you’ve had a secured card (or another credit account) for 6–12 months with consistent on-time payments, you may have built enough positive history to qualify for an unsecured card. This is the natural next step, and many secured card issuers will proactively offer to graduate you to an unsecured product.

    You Need a Higher Credit Limit

    If your secured card’s limit is too low to be practical — or too low to keep your credit utilization in a healthy range without obsessively micromanaging your balance — an unsecured card can provide a higher limit that gives you more breathing room. Higher limits, used responsibly, can actually help your credit score by lowering your utilization ratio.

    You Have Stable Income and Manageable Debt

    Lenders evaluate unsecured card applications based on both your credit score and your debt-to-income ratio. If you have a stable income and your existing debt obligations are manageable, you’re in a strong position to qualify for an unsecured card with good terms.

    What to Look For in an Unsecured Card

    When shopping for an unsecured card, consider:

    • No annual fee unless the rewards or benefits clearly justify it.
    • A competitive APR — though if you pay in full each month, this matters less.
    • Rewards that match your spending — cash back on groceries and gas, travel points, or flat-rate cash back on everything.
    • A sign-up bonus if you can meet the spending requirement naturally.
    • No hidden fees — watch for late fees, foreign transaction fees, and over-limit fees.
    • A grace period — at least 21 days from the statement closing date to the payment due date, during which you won’t be charged interest if you pay in full.

    An unsecured card is a privilege you earn by building a track record. If you’re not quite there yet, that’s fine — a secured card will get you there faster than you might think.

    Can You Get an Unsecured Card With Bad Credit?

    This is one of the most common questions we hear, and the honest answer is: yes, but you need to be very careful.

    There are unsecured cards marketed specifically to people with bad credit. They’re sometimes called “credit-building” or “credit-rebuilder” cards, and they don’t require a security deposit. On the surface, this sounds appealing — you get an unsecured card without tying up cash in a deposit. But the reality is that many of these cards come with terms that can make your financial situation worse, not better.

    The Warning Signs of Predatory Unsecured Cards

    Here’s what to watch out for when you encounter an unsecured card for bad credit:

    Exorbitant fees

    Some subprime unsecured cards charge an application fee, a processing fee, an annual fee, a monthly maintenance fee, and even a fee for requesting a credit limit increase. When you add it all up, you could pay $100–$200 or more in fees in the first year alone — before you’ve even made a purchase. Some cards charge fees that consume a significant portion of your credit limit before you ever use the card, leaving you with very little actual purchasing power.

    Very high APRs

    Subprime unsecured cards often carry APRs of 29.99% or higher. If you carry a balance, the interest charges can quickly spiral, making it harder to pay down the principal and increasing your overall debt load.

    Low credit limits

    These cards often start with very low limits — $300 to $500 — similar to what you’d get with a secured card, but without the security of a deposit. And because some of the fees are charged to the card immediately upon approval, your available credit can be dramatically less than the stated limit.

    No grace period

    Some predatory cards start charging interest from the day you make a purchase, with no grace period at all. This means even if you pay your balance in full each month, you’re still paying interest.

    No path to better terms

    Many of these cards don’t offer credit limit increases, rewards, or any upgrade path. You’re stuck with the same poor terms for as long as you hold the card.

    The Honest Recommendation

    If you have bad credit and you’re choosing between a predatory unsecured card and a reputable secured card, the secured card is almost always the better choice. Here’s why:

    • A secured card from a reputable issuer typically has lower fees — many have no annual fee at all.
    • Your deposit is refundable. Fees on a predatory unsecured card are gone forever.
    • A secured card often has a path to graduation — after 6–12 months of on-time payments, you may be upgraded to an unsecured card with your deposit returned.
    • The credit-building effect is the same. Both types report to the credit bureaus, and the bureaus don’t treat secured cards differently in scoring.

    There are a small number of legitimate unsecured cards for people with fair credit — cards from reputable issuers with reasonable fees and transparent terms. These can be a good option if you’re on the border between bad and fair credit and you don’t want to put down a deposit. But read the fine print carefully. If a card’s fee structure seems designed to extract money from you rather than help you build credit, walk away.

    A Note on “No Credit Check” Cards

    Some unsecured cards advertise “no credit check” approval. These are often catalog cards or store-specific cards that can only be used at certain retailers and may not report to all three bureaus. They often charge membership fees and carry high interest rates. Read the terms very carefully before applying, and confirm that the card reports to all three major credit bureaus. If it doesn’t, it won’t help you build credit.

    The bottom line: an unsecured card with bad credit is possible, but the terms are often designed to profit from your situation rather than help you improve it. A secured card from a reputable issuer is usually the safer, smarter, and cheaper path to the same destination.

    secured-vs-unsecured-credit-cards-under-100kb

    How to Graduate From a Secured to an Unsecured Card

    One of the most rewarding moments in a credit-building journey is the transition from a secured card to an unsecured one. This is often called “graduating,” and it represents tangible evidence that your credit profile has improved enough for a lender to trust you without a deposit.

    Here’s how to make that transition happen as smoothly and quickly as possible.

    Step 1: Use Your Secured Card Consistently

    Don’t let your secured card sit idle. Make small, regular purchases — a subscription, a gas fill-up, a grocery run — so there’s activity on the account each month. Activity generates statements, and statements generate payment reports to the credit bureaus. A card that’s never used produces no positive payment history.

    Step 2: Pay On Time, Every Time

    This is the single most important thing you can do. Payment history accounts for 35% of your credit score — more than any other factor. A single missed payment can set your progress back significantly. Set up autopay for at least the minimum payment, and consider paying the full balance each month to avoid interest charges and keep your utilization low.

    Step 3: Keep Your Balance Low

    Aim to keep your balance below 10% of your credit limit, and never exceed 30%. If your secured card has a $300 limit, try to keep your statement balance under $30, and certainly under $90. Credit utilization accounts for 30% of your credit score, and lower is always better. If you need to make a larger purchase, consider paying it down before the statement closing date so the reported balance stays low.

    Step 4: Wait 6 to 12 Months

    Most issuers want to see at least 6–12 months of consistent on-time payments before they’ll consider upgrading you. Some issuers review accounts automatically; others require you to request a review. Check your card’s terms or contact customer service to find out the policy.

    Step 5: Monitor Your Credit Score

    Track your credit score over time using a free credit monitoring service. You should see steady improvement as your positive payment history accumulates. If your score has climbed into the fair or good range (620+), you’re likely a candidate for an unsecured card — either through an upgrade with your current issuer or by applying for a new unsecured card from a different issuer.

    Step 6: Request an Upgrade or Apply for an Unsecured Card

    When your score has improved and you have 6–12 months of on-time payments, you have two options:

    Option A: Request an upgrade with your current issuer. Many secured card issuers will review your account and, if you’ve demonstrated responsible use, upgrade you to an unsecured card. This is the smoothest path because it doesn’t require a new credit application (which would result in a hard inquiry on your credit report). Your deposit is returned, your account history stays intact, and you continue building credit on the same account.

    Option B: Apply for a new unsecured card. If your current issuer doesn’t offer an upgrade path, or if you want a card with better terms or rewards, you can apply for an unsecured card from a different issuer. This will result in a hard inquiry on your credit report, which may cause a small, temporary dip in your score, but the long-term benefit of a better card usually outweighs the short-term impact.

    Step 7: Handle Your Secured Card Properly

    If you upgrade with your current issuer, they’ll return your deposit and convert the account to unsecured — no need to close anything. If you apply for a new unsecured card and are approved, you’ll need to decide what to do with your secured card. We cover this decision in detail in the next section.

    Graduating from a secured to an unsecured card is a milestone worth celebrating. It means your credit-building efforts are working, and the financial system is recognizing your progress. Keep the same habits that got you there — on-time payments, low balances, consistent activity — and your credit will continue to strengthen.

    Should You Close a Secured Card After Graduating?

    This is a more important question than most people realize, and the answer isn’t always what you’d expect. The short version: think carefully before closing a secured card, because it can affect your credit score in ways you might not anticipate.

    Let’s break down why.

    The Impact on Credit Utilization

    Credit utilization — the percentage of your available credit that you’re using — accounts for 30% of your credit score. It’s calculated across all your credit card accounts, both individually and in aggregate. When you close a secured card, you lose that card’s credit limit, which reduces your total available credit.

    Here’s an example. Suppose you have a secured card with a $500 limit and a new unsecured card with a $1,000 limit. Your total available credit is $1,500. If you typically carry a balance of $150 across both cards, your utilization is 10% — a healthy range.

    Now suppose you close the secured card. Your total available credit drops to $1,000. That same $150 balance now represents 15% utilization — still okay, but higher than before. If your balance were $300, closing the secured card would push your utilization from 20% to 30% — a significant jump that could negatively affect your score.

    If closing a secured card would push your utilization above 30%, it’s better to keep it open — at least until your new unsecured card’s limit is high enough to absorb the difference.

    The Impact on Average Age of Accounts

    The length of your credit history accounts for 15% of your credit score, and a key component is the average age of your accounts. Older accounts help your score because they demonstrate a longer track record of credit use.

    When you close a credit card, the account remains on your credit report for up to 10 years and continues to contribute to your average age of accounts during that time. However, once it falls off your report, your average account age could decrease, which may cause a dip in your score.

    If your secured card is one of your oldest accounts, closing it could eventually shorten your credit history. If it’s your only other account, the impact could be more noticeable.

    When It Makes Sense to Close a Secured Card

    There are situations where closing a secured card is the right call:

    • The card charges an annual fee and you no longer use it. If you’ve graduated to an unsecured card and the secured card is sitting unused while charging you $35–$50 per year, the cost may not be worth the credit score benefit. Consider whether the fee is worth paying to keep the account open.
    • Your utilization won’t be significantly affected. If your new unsecured card has a high enough limit that closing the secured card won’t push your utilization above 30%, the impact on your score will be minimal.
    • You have other older accounts. If you have multiple credit accounts with long histories, closing one secured card won’t dramatically shorten your average account age.
    • You want your deposit back and don’t qualify for an upgrade. If your issuer doesn’t offer an upgrade path and you need the deposit returned for other financial priorities, closing the card may be the practical choice.

    When It Makes Sense to Keep a Secured Card Open

    • The card has no annual fee. If it costs you nothing to keep open, there’s no financial downside, and the account continues to contribute to your credit history and available credit.
    • Closing it would push your utilization too high. Keep it open until your other credit limits grow enough to absorb the difference.
    • It’s one of your oldest accounts. Preserving long-standing accounts helps your average age of accounts over time.
    • You can use it for a small recurring charge. Put a single small subscription on the card and set up autopay. This keeps the account active with minimal effort and cost.

    A Practical Approach

    If your secured card has no annual fee, the simplest strategy is to keep it open, use it occasionally for a small purchase, and let it continue contributing to your credit profile. If it has an annual fee, weigh the cost against the credit score benefit. In many cases, it’s worth paying a modest annual fee for a year or two until your other accounts have aged and your credit limits have grown — then close it when the impact will be minimal.

    There’s no single right answer for everyone. The decision depends on your specific credit profile, your other accounts, your financial priorities, and the terms of your secured card. If you’re unsure, a credit professional can help you evaluate the trade-offs in the context of your overall credit strategy.

    How Each Card Affects Your Credit Score

    One of the most persistent myths about credit cards is that secured cards are somehow “lesser” or treated differently by the credit scoring system. This is not true. From a credit scoring perspective, secured and unsecured credit cards are identical. The major credit scoring models — FICO and VantageScore — do not distinguish between the two. They evaluate both based on the same factors:

    Payment History (35%)

    This is the most important factor in your credit score, regardless of which type of card you have. Every on-time payment is reported to the credit bureaus and contributes positively to your score. Every missed or late payment is reported and contributes negatively. A secured card and an unsecured card contribute to this factor in exactly the same way.

    If you make on-time payments on a secured card for 12 months, the positive impact on your score is the same as it would be for 12 months of on-time payments on an unsecured card. The bureaus see payment activity — not the type of card behind it.

    Credit Utilization (30%)

    Your credit utilization ratio is the amount of credit you’re using divided by the amount you have available. If you have a $500 limit and a $50 balance, your utilization is 10%. Lower utilization is better for your score, and the scoring models look at both individual card utilization and your overall utilization across all cards.

    Because secured cards typically have lower limits, it can be harder to keep utilization low. A $300 limit means a $90 balance already puts you at 30% — the upper end of the recommended range. With an unsecured card that has a $2,000 limit, the same $90 balance is only 4.5% utilization. This is one practical advantage of unsecured cards: higher limits make it easier to maintain low utilization without constantly micromanaging your balance.

    That said, you can keep utilization low on a secured card by making small purchases and paying them down before the statement closes. The scoring impact is the same.

    Length of Credit History (15%)

    The age of your accounts matters. Older accounts help your score, and a longer average account age is better. Both secured and unsecured cards contribute to this factor equally. An account opened today — whether secured or unsecured — starts contributing to your credit history immediately and continues to age over time.

    Credit Mix (10%)

    The scoring models like to see a mix of different types of credit — revolving accounts (like credit cards) and installment accounts (like auto loans, mortgages, or personal loans). Having both secured and unsecured credit cards contributes to your credit mix in the same way, since both are revolving accounts. The scoring models don’t give extra points for having one type over the other.

    New Credit and Inquiries (10%)

    When you apply for any credit card — secured or unsecured — the lender performs a hard inquiry on your credit report, which can cause a small, temporary dip in your score (usually 1–5 points). Multiple hard inquiries in a short period can have a compounding effect, so it’s wise to space out applications. This applies equally to both types of cards.

    The Bottom Line on Scoring

    The credit scoring system doesn’t care whether your card is secured or unsecured. It cares whether you pay on time, keep your balances low, maintain a long and diverse credit history, and apply for new credit sparingly. Both types of cards give you the opportunity to build positive credit in all of these areas.

    The practical difference is that secured cards typically have lower limits, which makes low utilization harder to maintain, and they may lack the rewards and benefits of unsecured cards. But from a pure credit-building standpoint, a secured card used responsibly is just as effective as an unsecured card used responsibly — and far more accessible if your credit is damaged or nonexistent.

    Pros and Cons of Secured Credit Cards

    Let’s summarize the advantages and disadvantages of secured credit cards so you can weigh them clearly.

    Pros

    • Accessible approval. Designed for people with bad or no credit. If you can fund the deposit, your approval odds are very high.
    • Effective credit building. Reports to all three major bureaus, just like an unsecured card. On-time payments build positive credit history.
    • Refundable deposit. Your money isn’t gone — it’s held in an account and returned when you close the card or upgrade.
    • Controlled spending. The deposit-based limit naturally constrains your spending, which can help if you’re working on financial discipline.
    • Path to graduation. Many issuers offer a clear upgrade path to an unsecured card after a period of responsible use.
    • No risk of overspending beyond your means. You can’t spend more than your deposit (in most cases), which provides a built-in safety valve.
    • Equal scoring treatment. The credit bureaus treat secured cards identically to unsecured cards in scoring.

    Cons

    • Requires upfront cash. You need $200–$300 (or more) to fund the deposit, which may be difficult if money is tight.
    • Low credit limits. Your limit is tied to your deposit, which can make it harder to keep utilization low and limits purchasing power.
    • Higher APRs. Interest rates are often in the mid-20s or higher, though this only matters if you carry a balance.
    • Annual fees are common. While no-fee options exist, many secured cards charge $25–$50 per year.
    • Few or no rewards. Most secured cards don’t offer cash back, points, or other rewards programs.
    • Less flexibility. You can’t increase your limit without adding to your deposit (unless your issuer offers increases based on payment history).

    Pros and Cons of Unsecured Credit Cards

    Pros

    • No deposit required. Your cash stays available for other uses — no need to tie up hundreds of dollars upfront.
    • Higher credit limits. Limits are set by the issuer based on your creditworthiness and can grow over time, giving you more purchasing power and making low utilization easier to maintain.
    • Rewards and benefits. Many unsecured cards offer cash back, travel points, sign-up bonuses, purchase protections, extended warranties, travel insurance, and other perks.
    • Lower APRs (for qualified applicants). If you have good or excellent credit, you can qualify for APRs in the low-to-mid teens, and some cards offer 0% introductory APR periods.
    • No-annual-fee options. Many excellent unsecured cards charge no annual fee, making them free to carry.
    • Greater flexibility. Higher limits and better terms give you more room to manage your finances strategically.

    Cons

    • Harder to qualify. Requires fair to excellent credit. If your score is below 580, most reputable unsecured cards will be out of reach.
    • Risk of overspending. Without the natural constraint of a deposit-based limit, it’s easier to charge more than you can afford to repay.
    • Interest charges can compound. If you carry a balance, high APRs (especially on subprime unsecured cards) can lead to rapidly growing debt.
    • Temptation of rewards. The prospect of earning cash back or points can encourage spending beyond your means if you’re not disciplined about paying the balance in full.
    • Hard inquiry on application. Each application results in a hard inquiry, which can cause a small, temporary score dip.
    • Predatory subprime options. Unsecured cards marketed to people with bad credit often carry exorbitant fees and terms that can worsen your financial situation.

    Common Mistakes to Avoid

    Whether you’re using a secured or an unsecured credit card, certain mistakes can undermine your credit-building efforts and cost you money. Here are the most common ones — and how to avoid them.

    1. Missing Payments

    A single missed payment can stay on your credit report for up to seven years and can cause a significant score drop, especially if your credit history is short. Set up autopay for at least the minimum payment on every credit card you hold. If you prefer to pay manually, set calendar reminders for at least a week before each due date.

    2. Carrying High Balances

    Even if you pay on time, carrying a high balance relative to your credit limit hurts your score. Aim to keep your statement balance below 10% of your limit, and never above 30%. If you need to make a large purchase, consider paying it down before the statement closes so the reported balance stays low.

    3. Applying for Too Many Cards at Once

    Each credit card application results in a hard inquiry on your credit report. Multiple inquiries in a short period can signal to lenders that you’re desperate for credit, which can lower your score and reduce your approval odds. Space out applications by at least 6 months when possible.

    4. Choosing a Card Without Reading the Fine Print

    Before applying for any credit card, read the terms and conditions carefully. Look for annual fees, monthly maintenance fees, application fees, processing fees, APR, grace period, and foreign transaction fees. If the fee structure seems designed to extract money rather than help you build credit, look elsewhere.

    5. Confusing a Secured Card With a Prepaid Card

    A prepaid debit card is not a credit card. It doesn’t report to the credit bureaus and doesn’t help you build credit. If your goal is to build or rebuild credit, make sure the card you’re applying for is specifically a credit card — secured or unsecured — and that it reports to all three major bureaus.

    6. Closing Your Oldest Card Too Soon

    Closing your oldest credit card can shorten your credit history and reduce your available credit, both of which can negatively affect your score. Think carefully before closing any older account, and consider keeping it open with a small recurring charge if it has no annual fee.

    7. Not Using Your Card at All

    A credit card that sits in a drawer doesn’t build credit. Issuers may close inactive accounts after a period of inactivity (typically 12–24 months), which can reduce your available credit and shorten your credit history. Make at least one small purchase each month to keep the account active.

    8. Only Paying the Minimum

    While paying the minimum keeps your account in good standing, it means you’re carrying a balance and paying interest. Over time, interest charges can make your purchases significantly more expensive and make it harder to pay down the principal. Aim to pay your balance in full each month. If you can’t, pay as much above the minimum as you can afford.

    9. Ignoring Your Credit Report

    Your credit report contains the information that determines your score. Errors on your report — accounts you don’t recognize, incorrect payment statuses, outdated information — can drag down your score unfairly. You’re entitled to a free copy of your credit report from each of the three major bureaus every 12 months through AnnualCreditReport.com. Review them regularly and dispute any inaccuracies.

    AnnualCreditReport.com

    10. Falling for “Guaranteed Approval” Schemes

    No legitimate credit card offers guaranteed approval. Cards that make this claim often have hidden fees, don’t report to all three bureaus, or are catalog cards with limited utility. Stick with cards from reputable issuers — major banks and credit unions — and verify their terms before applying.

    Avoiding these mistakes doesn’t require perfection. It requires awareness and consistent good habits. Pay on time, keep your balances low, read the terms, and monitor your credit. Do these things reliably, and your credit score will reflect your effort.

    Frequently Asked Questions

    1. Is a secured credit card better than an unsecured credit card?

    Neither is inherently “better” — they serve different purposes at different stages of your credit journey. A secured card is the right choice when you’re building credit from scratch or rebuilding after financial setbacks, because it’s accessible and effective for establishing positive payment history. An unsecured card is the right choice when your credit is strong enough to qualify for one with good terms, because it offers higher limits, rewards, and no deposit requirement. The best card for you is the one that matches your current credit profile and financial goals.

    2. How long does it take to graduate from a secured to an unsecured card?

    Most issuers review secured card accounts for potential upgrades after 6–12 months of consistent on-time payments. Some may take longer — 12–18 months — depending on your starting credit profile and how quickly your score improves. You can speed up the process by paying on time every month, keeping your utilization low, and avoiding new credit applications during this period.

    3. Do secured credit cards build credit the same as unsecured cards?

    Yes. The credit bureaus and scoring models (FICO and VantageScore) do not distinguish between secured and unsecured cards. Both report payment activity, utilization, account age, and other factors in the same way. A secured card used responsibly builds credit just as effectively as an unsecured card used responsibly. The key is consistent on-time payments and low balances.

    4. Can I get an unsecured card with no deposit and bad credit?

    Yes, but you should proceed with caution. Unsecured cards for bad credit exist, but many come with high fees, high APRs, low limits, and no upgrade path. Some are outright predatory. Before applying, read the terms carefully, compare the total first-year fees to what you’d pay for a secured card, and confirm the card reports to all three major bureaus. In most cases, a secured card from a reputable issuer is the safer and cheaper option for building credit with bad credit.

    5. What happens to my deposit when I upgrade from a secured to an unsecured card?

    If your issuer upgrades your secured card to an unsecured card, your deposit is refunded — usually as a statement credit or a check. The account remains open with the same history, so there’s no impact on your credit age. If you close the secured card instead of upgrading, your deposit is also refunded after the final balance is paid.

    6. Will closing a secured card hurt my credit score?

    It can. Closing any credit card reduces your total available credit, which can increase your utilization ratio — and higher utilization can lower your score. Closing an older account can also eventually shorten your average account age, though the account remains on your credit report for up to 10 years after closing. If your secured card has no annual fee, consider keeping it open with a small recurring charge to preserve the credit limit and account age.

    7. How many credit cards should I have to build credit?

    There’s no magic number, but most credit experts recommend having 2–3 credit cards once your credit is established. This provides enough active accounts to build a strong payment history and gives you enough total credit limit to keep utilization low. However, more cards aren’t always better — each application results in a hard inquiry, and managing multiple cards requires discipline. Start with one card, build a solid payment history, and add cards gradually as your credit improves and your financial situation warrants.

    8. What credit score do I need for an unsecured credit card?

    It depends on the card. Entry-level unsecured cards may accept scores in the 580–669 range (fair credit). Cards with better terms, rewards, and no annual fees typically require scores of 670 or above (good credit). Premium rewards cards with the best perks usually require scores of 740 or above (excellent credit). If your score is below 580, a secured card is generally your best option for building the credit you need to eventually qualify for an unsecured card.

    Take the Next Step Toward Stronger Credit

    Choosing between a secured and an unsecured credit card is just one piece of a larger credit-building strategy. If you’re dealing with negative items on your credit report — late payments, collections, charge-offs, inaccuracies, or errors — having the right card can help you build positive history, but it won’t address the underlying issues holding your score down.

    That’s where we come in. At credit-repair.com, we offer a comprehensive, attorney-backed approach to credit repair that goes beyond surface-level fixes. Our process includes:

    • A thorough credit audit across all three major bureaus to identify errors, inaccuracies, and disputable negative items.
    • Disputing inaccuracies under the Fair Credit Reporting Act (FCRA), with the support of experienced attorneys who ensure every step is ethical, accurate, and legally compliant.
    • Negotiating with creditors to resolve outstanding debts and explore options for removing negative marks.
    • A customized repair plan tailored to your specific credit profile, goals, and timeline.
    • Ongoing education and support so you understand not just what we’re doing, but why — and how to maintain strong credit long after our work is done.

    We operate with full transparency. No hidden fees. No misleading claims. No guarantees of specific outcomes, because no legitimate credit repair firm can honestly guarantee a particular score increase. What we can guarantee is that we’ll work diligently, ethically, and in full compliance with federal law to give your credit the best possible chance to improve.

    Ready to see where you stand? Start with a free credit audit at credit-repair.com. We’ll review your credit reports from all three major bureaus, identify what’s helping and what’s hurting your score, and give you a clear, honest picture of your options — with no obligation.

    Your credit journey doesn’t have to be a guessing game. With the right tools, the right information, and the right team in your corner, you can take control of your financial future — one step at a time.

    This article is for educational purposes only and does not constitute legal or financial advice. Your individual credit situation is unique, and results vary based on your specific circumstances. Credit repair is a process that requires time, consistency, and compliance with applicable federal laws, including the Fair Credit Reporting Act (FCRA).

  • Best Secured Credit Cards to Rebuild Your Score in 2026

    Best Secured Credit Cards to Rebuild Your Score in 2026

    If your credit score has taken a hit — whether from late payments, a collections account, a bankruptcy, or simply a thin credit file you never had the chance to build — you’ve probably been told the same thing over and over: “Get a secured credit card.”That advice is sound. A secured card is one of the most reliable, legally protected tools for rebuilding credit in the United States. But here’s what most guides won’t tell you: the “best” secured card is not a single product. It’s the card that fits your specific situation, your budget, and your long-term plan.That’s why this article does something different. Instead of pushing you toward a handful of branded cards (whose terms can change at any time), we’re going to give you a criteria-based framework — a way to evaluate any secured card you come across and decide whether it deserves a place in your wallet. We’ll walk through the seven factors that actually matter, describe what to look for in each major category, and give you a comparison table you can fill in as you shop around.We’ll also show you how to apply without dinging your score, how to use whichever card you pick so it actually moves the needle, and the red flags and common mistakes that trip people up along the way.No quick fixes. No guarantees. Just a clear, honest path forward — the same approach we take with every client at credit-repair.com.

    What Makes a Secured Card “the Best”?

    A secured credit card is a regular credit card backed by a refundable cash deposit. That deposit becomes your credit line in most cases — put down $300, and you get a $300 spending limit. The deposit protects the issuer if you stop paying, which is why they’re willing to approve people with damaged or limited credit.

    Here’s the key point: a secured card is not a prepaid card, and it is not a debit card. When you make a purchase with a secured card, the issuer lends you the money, you owe them a balance, and — this is the part that matters — they report your payment activity to the credit bureaus. That reporting is what rebuilds your score.

    So what makes a secured card “the best”? It’s not the flashiest marketing or the biggest sign-up bonus. The best secured card for you is the one that:

    • Reports to all three major bureaus (Equifax, Experian, and TransUnion) so your good behavior actually shows up everywhere a lender might look.
    • Costs you as little as possible in fees, because every dollar you spend on fees is a dollar not going toward your deposit, your balances, or your life.
    • Has a realistic path to graduate to an unsecured card — meaning the issuer will eventually review your account and, if you’ve handled it well, return your deposit and upgrade you to a regular card.
    • Fits your deposit budget without forcing you to tie up money you can’t afford to lock away.
    • Is issued by a reputable lender that operates within the Fair Credit Reporting Act (FCRA) and other federal consumer protections.

    A card can be perfect on paper but wrong for you if the deposit is too high, the fees eat you alive, or the issuer doesn’t report to all three bureaus. That’s why we evaluate cards against criteria, not against brand names.

    The 7 Selection Criteria That Actually Matter

    When you’re comparing secured cards, these are the seven factors worth your time. Everything else is marketing.

    1. Annual Fee

    The annual fee is what the issuer charges you simply for having the card, regardless of whether you use it. This is the single most important cost to watch.

    Some secured cards charge $0. Others charge anywhere from $25 to $50 per year. A few charge more, or sneak in monthly “maintenance” fees on top. Because secured cards rarely come with sign-up bonuses or rewards that offset costs, an annual fee is money out of your pocket from day one — before you’ve even made a single purchase.

    What to look for: A card with no annual fee, or an annual fee under $35 if a no-fee option isn’t available to you.

    2. Bureau Reporting

    This is non-negotiable. A secured card that doesn’t report to all three major credit bureaus is not rebuilding your credit — it’s just a spending tool.

    Your FICO and VantageScore scores are calculated from the information in your credit reports at Equifax, Experian, and TransUnion. If a card only reports to one or two bureaus (or worse, none), your on-time payments only show up in some of the places lenders might look. That means your rebuilt credit may not be visible when you apply for an apartment, a car loan, or a mortgage.

    What to look for: Explicit confirmation — in the card’s terms or FAQ — that the issuer reports to all three major bureaus: Equifax, Experian, and TransUnion.

    Don’t assume. Some issuers only report to one or two, and some smaller or newer issuers may not report at all unless you miss a payment.

    Why it matters: Rebuilding credit is hard enough. Don’t do the work and then have it invisible to two-thirds of the system that’s supposed to reward you.

    3. Deposit Required

    The deposit is the money you lock up to secure the card. It’s refundable — you get it back when you close the card in good standing or graduate to an unsecured card — but while it’s locked, you can’t use it for anything else.

    Typical minimum deposits run from $49 to $300, and most cards let you deposit more to get a higher credit line. Some issuers offer flexible deposit options based on your credit profile, where you might qualify for a $200 credit line with a $49, $99, or $200 deposit.

    What to look for: A minimum deposit you can comfortably afford to lock away for 12 to 24 months. For most people starting out, that’s $200 or less. If cash is tight, look for issuers that offer partial security deposits (where a smaller deposit unlocks a larger line) or no-deposit secured options that use your banking history instead of an upfront deposit.

    Why it matters: If the deposit stretches your budget so thin that you can’t pay your other bills, the card is creating a new financial problem while trying to solve an old one. Rebuilding credit should not require choosing between your deposit and your groceries.

    4. APR (Annual Percentage Rate)

    The APR is the interest rate you pay if you carry a balance from month to month. Secured card APRs tend to be high — often 25% to 30% or more — because issuers are taking on riskier borrowers.

    Here’s the honest truth: if you pay your statement balance in full every month, the APR doesn’t matter. You won’t be charged interest. But if there’s any chance you’ll carry a balance — even occasionally — a lower APR will save you real money.

    What to look for: First, commit to paying in full every month. Second, as a safety net, look for a card with an APR at the lower end of the secured-card range. Treat a high APR as a deterrent, not a dealbreaker — but don’t pretend it doesn’t exist.

    5. Graduation Path

    A graduation path means the issuer can eventually upgrade your secured card to an unsecured card after you demonstrate responsible account management.

    Graduation can allow you to receive your security deposit back and potentially receive a higher credit limit without opening a completely new account.

    What to look for: A documented graduation policy, automatic account reviews, and clear information about when your account becomes eligible.

    6. Credit Line Increase

    A secured card that allows you to increase your credit line by adding to your deposit can become more useful as your financial situation improves.

    A higher credit limit can also make it easier to keep your utilization ratio low, assuming your spending does not increase along with the limit.

    What to look for: The ability to add deposits in increments, clear credit-line increase rules, and no unnecessary hard inquiry for an increase that is funded by an additional deposit.

    7. Fees and Perks

    Once the major fundamentals are covered, look at secondary features such as rewards, free credit monitoring, cell phone protection, foreign transaction fees, and other cardholder benefits.

    Treat everything else as a bonus.

    Why it matters: Free credit score monitoring keeps you informed as you rebuild. A small cash-back reward offsets some of your normal spending. Neither of these is the reason to choose a card, but both make a good card better.

    The Secured Card Comparison Framework

    Use this table to evaluate any secured card you’re considering. Print it out, copy it into a spreadsheet, or just fill it in mentally as you read terms and reviews. The goal is to compare cards side by side on the factors that actually determine whether they’ll help you rebuild.

    Criteria Card A Card B Card C What to Aim For
    Annual fee $0, or under $35
    Reports to all 3 bureaus? Yes — Equifax, Experian, TransUnion
    Minimum deposit $200 or less
    Maximum credit line $2,000+ (via added deposit)
    APR Lower is better, but only matters if you carry a balance
    Graduation path? Yes — automatic review after 6–12 months
    Credit line increase by deposit? Yes
    Monthly maintenance fees? None
    Application pull type Soft pull or pre-qualification first
    Rewards / perks Free credit score access; 1–2% cash back is a bonus
    Foreign transaction fee 0% if you travel
    Late payment fee Check terms — know the cap
    Issuer reputation Reputable bank or credit union; FCRA-compliant

    A few notes on how to fill this in:

    • Read the card’s terms and conditions (T&C) and FAQ page directly. Marketing pages emphasize the positives. The T&C is where the fees and limitations live.
    • Cross-reference recent reviews from independent financial publications and real cardholders. Terms change, and a review from two years ago may not reflect current reality.
    • Call the issuer if anything is unclear. A reputable issuer will answer direct questions about bureau reporting, graduation, and fees. If they won’t, that’s a red flag.

    Categories: How to Find the Right Card for Your Situation

    There’s no single “best secured card” — there are best cards for specific situations. Below, we describe what to look for in each category so you can match the card to your needs.

    Best for No Annual Fee

    If you’re rebuilding on a tight budget, every dollar matters. A no-annual-fee secured card lets you keep the card open for as long as you need without paying for the privilege.

    What to look for:

    • A $0 annual fee, clearly stated in the terms.
    • No monthly maintenance fees, program fees, or setup fees hiding in the fine print.
    • Reporting to all three bureaus (some no-fee cards skip a bureau — verify before you apply).
    • A reasonable APR, since no-fee cards sometimes compensate with higher interest rates.

    Who this is best for: Anyone who wants to minimize out-of-pocket costs while rebuilding, especially if you expect to carry the card for 18 to 24 months before graduating. It’s also the right choice if you’re juggling multiple rebuilding tools (like a credit-builder loan) and want to keep fixed costs low.

    Watch out for: Some “no annual fee” cards charge a one-time setup fee or monthly fees after the first year. Read the full fee schedule, not just the headline.

    Best for Low Deposit

    If you don’t have $200 to lock away, a low-deposit secured card can get you started with as little as $49 to $99. Some issuers offer partial security deposits — your credit profile determines whether you qualify for a $200 line with a $49, $99, or $200 deposit.

    What to look for:

    • A minimum deposit of $49 to $100, or a flexible deposit model that adjusts based on your profile.
    • A credit line that’s at least 2x to 4x your deposit if you qualify for a partial deposit (this is common with major issuers).
    • Clear terms on when and how you get the deposit back.
    • No requirement to deposit the full credit line amount if you don’t want to.

    Who this is best for: Anyone whose cash flow is tight — if you’re recovering from a financial setback and can’t afford to tie up $200+, this category gets you in the game without straining your budget.

    Watch out for: Low-deposit cards sometimes come with annual fees. Calculate the total cost over a year (deposit locked + fees paid) and compare it to a higher-deposit no-fee card. Sometimes the no-fee card is cheaper even though it requires more upfront.

    Best for Graduation (Unsecured Upgrade Path)

    A graduating secured card is one where the issuer proactively reviews your account and, if you’ve paid on time and kept your balance manageable, upgrades you to an unsecured card and returns your deposit — without a new application or hard credit pull.

    This is the category most people should care about, because graduation is the moment your rebuilding transitions into long-term credit health.

    What to look for:

    • A documented graduation policy (stated in the terms, FAQ, or confirmed by the issuer directly).
    • Automatic account reviews, typically starting at 6 to 12 months of responsible use.
    • No application or hard pull required to graduate.
    • A track record of actually graduating cardholders — check independent reviews and forum discussions to confirm the issuer follows through.

    Who this is best for: Anyone who wants a clear bridge from secured to unsecured credit without reapplying. If you’re serious about rebuilding and want the deposit back as soon as you’ve proven yourself, prioritize this category.

    Watch out for: Some issuers advertise graduation but rarely upgrade in practice. Reviews and user forums are your best signal for whether an issuer actually delivers. If you can’t find evidence of real graduations, treat the “path” as theoretical.

    Best for High Credit Limit

    If you want to keep your utilization ratio low — which is one of the fastest ways to improve your score — a card that allows a high credit line through additional deposits is valuable. With a $2,000 limit, a $200 balance is just 10% utilization. With a $300 limit, that same balance is 67% — which will drag your score down even if you pay it off every month.

    What to look for:

    • A maximum credit line of $2,000 to $5,000 or more, reachable by adding to your deposit over time.
    • The ability to add deposits in increments (not just one lump sum at opening).
    • No hard credit pull required to increase your limit by deposit.
    • Clear terms on how quickly additional deposits are reflected in your credit line.

    Who this is best for: People who spend moderately on their card each month and want to keep utilization under 10% without micromanaging every purchase. It’s also good for anyone whose score is being held back by high utilization on existing cards — adding a high-limit secured card can dilute your overall utilization.

    Watch out for: Don’t deposit more than you can afford to lock away. A high limit only helps if you can access your cash again when you need it. Remember: the deposit is refundable, but not on demand — you get it back when you close the card or graduate.

    Best for No Credit Check or Soft-Pull Approval

    If you’re worried that a hard credit inquiry will further damage your score (each hard pull can drop your score by a few points, and the inquiry stays on your report for two years), look for a card that offers pre-qualification with a soft pull or no credit check at all.

    What to look for:

    • A pre-qualification tool on the issuer’s website that uses a soft pull (which doesn’t affect your score) to show you which cards you’re likely to be approved for before you formally apply.
    • Cards that use banking history instead of a credit check to determine eligibility.
    • Clear disclosure that the pre-qualification step is a soft pull, not a hard one.

    Who this is best for: Anyone with a score so low that even a single hard inquiry feels risky, or anyone who wants to shop around without accumulating inquiries. It’s also useful if you’ve been denied recently and want to avoid another ding.

    Watch out for: Pre-qualification is not a guarantee of approval. When you formally apply, some issuers will still do a hard pull. Read the fine print to understand when the hard pull happens — ideally only after you’ve been pre-qualified and decide to proceed.

    Best with Rewards and Perks

    A growing number of secured cards offer cash back, free credit score monitoring, cell phone protection, travel benefits, or rent reporting. These perks used to be reserved for unsecured cards, but competition has pushed them into the secured market.

    What to look for:

    • 1% to 2% cash back on all purchases or on specific categories like dining and gas.
    • Free monthly credit score access so you can track your progress.
    • No foreign transaction fees if you travel outside the U.S.
    • Cell phone protection or extended warranty as a cardholder benefit.
    • Rent and utility reporting — a few secured cards (and some credit-builder products) report your rent and utility payments to the bureaus, which adds positive payment history without additional spending.

    Who this is best for: Anyone who has narrowed down their options to a few cards with similar fees and terms and wants a tiebreaker. Rewards should never be the primary factor in choosing a secured card, but they’re a legitimate differentiator when everything else is equal.

    Watch out for: Don’t pay an annual fee just to earn cash back. Do the math: if a card charges $35/year and earns you 1% cash back, you’d need to spend $3,500 per year just to break even on the fee. A no-fee card with no rewards is usually a better deal for a rebuilder.

    How to Apply Without Hurting Your Score

    One of the most common fears we hear from clients is: “Won’t applying for a credit card hurt my score?”

    It’s a fair concern. A hard credit inquiry can lower your score by a few points, and it stays on your report for two years (though the impact fades after about 12 months). But there’s a smart way to apply that minimizes or eliminates that impact.

    Step 1: Use Pre-Qualification Tools First

    Many major issuers offer a pre-qualification or pre-approval tool on their website. You enter some basic information — name, address, income — and the issuer does a soft pull of your credit to show you which cards you’re likely to qualify for.

    A soft pull does not affect your credit score. You can use as many pre-qualification tools as you want without accumulating inquiries.

    Use pre-qualification to:

    • Compare offers from multiple issuers without risk.
    • Identify cards where your approval odds are strongest.
    • Avoid unnecessary hard inquiries.
    • Compare fees, deposits, credit limits, and graduation policies before applying.

    Step 2: Submit Only One Formal Application

    Once you’ve compared your options and identified the card that fits your situation, submit one formal application rather than applying for several cards at once.

    A formal application typically results in a hard inquiry. Multiple applications in a short period can create multiple inquiries and make your credit profile look riskier to lenders.

    Step 3: Fund Your Deposit

    If you’re approved, fund the security deposit according to the issuer’s instructions. Remember that this money is generally held as security and is not available for everyday spending.

    Only deposit an amount you can comfortably afford to have tied up for the foreseeable future.

    Step 4: Set Up Autopay Immediately

    Set up automatic payments as soon as your account is active. At minimum, make sure the minimum payment is automatically paid before the due date.

    If your budget allows it, pay the statement balance in full each month.

    Step 5: Check Your First Statement

    Review your first statement carefully. Confirm the payment due date, credit limit, fees, interest rate, and other terms.

    Also confirm that the account is reporting correctly to the credit bureaus once reporting begins.

    How to Use Whichever Card You Pick the Right Way

    Choosing a good secured card is only half the process. What you do with it afterward determines whether it actually helps you rebuild.

    Rule 1: Never Miss a Payment

    One missed payment can undo months of progress.

    Set up autopay for at least the minimum payment, and set a calendar reminder to review your statement each month. Treat the due date as non-negotiable.

    Rule 2: Pay in Full If You Can

    Paying in full means you never carry a balance and never pay interest. It also keeps your utilization low. If you can’t pay in full, pay as much as you can — always more than the minimum.

    Rule 3: Keep Your Utilization Under 10%

    Utilization is the second biggest factor in your score, after payment history. Aim to keep your statement balance below 10% of your credit limit. On a $300 card, that means a statement balance under $30. On a $1,000 card, under $100.

    If you need to spend more than 10% in a given month, you have two options:

    • Make a mid-month payment to bring the balance down before the statement closes.
    • Add to your deposit to raise your credit line, which lowers your utilization ratio automatically.

    Rule 4: Use the Card Every Month

    A card that sits in a drawer doesn’t generate payment activity. Make at least one small purchase each month — a subscription, a tank of gas, a grocery run — and pay it off. This creates a steady stream of positive payment history.

    Rule 5: Don’t Close the Card Too Early

    Closing a secured card can reduce your available credit and shorten your average account age — both of which can temporarily lower your score. Keep the card open until you’ve either graduated to an unsecured card or opened another unsecured card with a comparable limit. If you must close it to get your deposit back, do so only after you have other positive accounts reporting.

    Rule 6: Track Your Progress

    Use the free credit score monitoring that comes with your card (or a free service) to watch your score trend over time. You should see gradual improvement within 3 to 6 months of consistent on-time payments, with more noticeable gains at the 12-month mark.

    Best secured credit cards to rebuild credit in 2026

    Red Flags to Avoid

    The secured card market includes some products that exist to extract money from people who are desperate to rebuild. Here’s what to watch for.

    1. High Annual or Monthly Fees

    If a card charges an annual fee above $50, or any monthly maintenance fee (some charge $5 to $12 per month — that’s $60 to $144 per year), walk away. There are reputable no-fee or low-fee options.

    2. No Bureau Reporting

    If you can’t confirm in writing that the card reports to all three major bureaus, skip it. A card that doesn’t report is not rebuilding your credit — it’s just a spending tool with your own money locked behind it.

    3. Application Fees

    Legitimate secured cards do not charge an application fee. If a card asks for money before you’re even approved, that’s a warning sign.

    4. “Credit Repair” Cards That Are Actually Catalog Cards

    Some products marketed as “credit repair cards” are actually catalog cards or merchant cards — they only let you buy goods from a specific catalog or store, and they may only report to one bureau (or none). These are almost never worth it. A real secured card is a Visa, Mastercard, American Express, or Discover card accepted anywhere those networks are accepted.

    5. Predatory APRs Above 30%

    While secured card APRs are generally high, anything above 30% is a signal that the issuer is pricing for default and isn’t interested in a long-term relationship. If you ever carry a balance, the interest will eat you alive.

    6. No Clear Path to Get Your Deposit Back

    If the issuer doesn’t clearly explain how and when you get your deposit returned — either through graduation or by closing the account in good standing — treat that as a red flag. Your deposit is your money, and you should know exactly how to reclaim it.

    7. Pressure to Buy Add-On Services

    Some issuers push add-ons like credit insurance, identity protection, or “credit accelerator” programs during the application process. These are rarely worth the cost. Decline them and focus on the fundamentals: on-time payments and low utilization.

    Common Mistakes That Slow Your Progress

    Even with the right card, people make mistakes that delay their recovery. Here are the most common ones we see.

    Mistake 1: Not Using the Card

    If you open a secured card and never use it, the issuer may eventually close it for inactivity — which can reduce your available credit and shorten your account history. Make at least one purchase per month, even if it’s a $5 charge.

    Mistake 2: Maxing Out the Card

    Using your full credit limit — even if you pay it off — can hurt your score if the balance is reported before you pay. The bureaus see your statement balance, not your payment timing. Keep your statement balance under 10% of your limit.

    Mistake 3: Missing a Payment

    One 30-day late payment can drop your score by 60 to 80 points or more, depending on your starting score. On a secured card — where the whole point is to build positive history — a late payment is especially damaging because it contradicts the story you’re trying to tell lenders. Set up autopay for at least the minimum.

    Mistake 4: Applying for Multiple Cards at Once

    Each application is a hard inquiry. Multiple inquiries in a short window signal risk and compound the score impact. Apply for one card, get approved, use it responsibly for 6+ months, then consider adding another if needed.

    Mistake 5: Closing the Card Too Soon

    If you close a secured card after just 3 or 4 months, you’ve cut short the payment history you were building. Keep the card open for at least 12 months, ideally until you graduate or have other positive accounts well-established.

    Mistake 6: Ignoring the Rest of Your Credit

    A secured card is one tool, not a complete strategy. If you have negative items on your report — late payments, collections, charge-offs, inaccurate information — those items are still dragging your score down. Pair your secured card with a proper credit repair plan that addresses errors and negotiates with creditors. This is exactly what we do at credit-repair.com: a comprehensive audit, disputes with all three bureaus, and a customized plan that works alongside tools like secured cards.

    Mistake 7: Expecting Overnight Results

    Credit rebuilding is a marathon, not a sprint. Most people see meaningful improvement in 6 to 12 months with consistent effort, and significant improvement in 18 to 24 months. Anyone promising faster results is either misleading you or using tactics that don’t last.

    Frequently Asked Questions

    1. Can a secured card really rebuild my credit?

    Yes — if the card reports to all three major bureaus and you use it responsibly (on-time payments, low utilization). A secured card generates payment history and contributes to your credit utilization ratio, both of which are major factors in your credit score. However, a secured card alone won’t fix negative items on your report. For the best results, pair it with a credit repair plan that addresses inaccuracies and negative marks.

    2. How much deposit do I need for a secured card?

    Most secured cards require a minimum deposit between $49 and $300. Some issuers offer partial security deposits where a smaller deposit unlocks a larger credit line, based on your credit profile. The deposit is refundable — you get it back when you close the card in good standing or graduate to an unsecured card.

    3. Will applying for a secured card hurt my credit score?

    The formal application typically involves a hard credit inquiry, which can lower your score by a few points. However, many issuers offer pre-qualification with a soft pull that doesn’t affect your score — use that first to check your odds. A single hard inquiry is minor and temporary; the positive history from the new card will outweigh it within a few months.

    4. How long does it take to graduate from a secured to an unsecured card?

    It depends on the issuer and your behavior. Some issuers review accounts automatically at 6 to 12 months; others may take longer or require you to request the upgrade. Graduation typically returns your deposit and may increase your credit limit. Not all issuers offer a graduation path — verify before you apply.

    5. What credit score do I need to get a secured card?

    Most secured cards are designed for people with bad credit or no credit, so the approval threshold is generally low. Some issuers don’t have a minimum score at all — they use your deposit as the qualifying factor. That said, a recent bankruptcy or active collections may affect approval with certain issuers. Pre-qualification tools will tell you where you stand before you formally apply.

    6. Can I have more than one secured card?

    Yes, but it’s usually best to start with one, use it responsibly for 6 to 12 months, then consider adding a second if you want to increase your total available credit. Applying for multiple cards at once generates multiple hard inquiries and signals risk. Two well-managed cards can improve your utilization ratio and diversify your credit profile, but only after you’ve proven you can handle one.

    7. Do secured cards build credit as fast as unsecured cards?

    Yes — the scoring models treat secured and unsecured cards the same way. What matters is your payment history, utilization, account age, and the fact that the card reports to the bureaus. The deposit behind the card is invisible to the scoring algorithm. The speed of your progress depends on your behavior and what else is on your report, not on whether the card is secured.

    8. What happens to my deposit if the issuer goes out of business?

    Your deposit is typically held in a separate, FDIC-insured account and should be returned to you even if the issuer fails. That said, always verify that the issuer is a reputable, regulated bank or credit union before applying. If you’re working with a smaller or newer issuer, ask directly where your deposit is held and how it’s protected.

    Next Steps: Pair Your Card With a Real Credit Plan

    A secured credit card is one of the best tools available for rebuilding your credit — but it works best as part of a broader strategy. If your credit report contains inaccuracies, outdated negative items, or accounts that could be disputed or negotiated, those items are holding your score down no matter how responsibly you use your new card.

    That’s where we come in.

    At credit-repair.com, we help individuals and families across the country take control of their financial future through honest, attorney-backed credit repair. Our process includes:

    • A comprehensive credit audit across all three major bureaus — Equifax, Experian, and TransUnion.
    • Disputing inaccuracies under the Fair Credit Reporting Act (FCRA), with the backing of experienced attorneys.
    • Negotiating with creditors to resolve legitimate negative items where possible.
    • A customized repair plan built around your specific goals and timeline.
    • Ongoing education so you understand how credit works and how to keep it strong for life.

    We don’t make empty promises or offer quick fixes. We believe in transparency, legal compliance, and measurable progress — the same values you should look for in a secured card.

    Ready to see where you stand? Get your free credit audit at credit-repair.com. We’ll review your reports from all three bureaus, identify what’s holding your score back, and build a plan that works alongside tools like your secured card to get you where you want to go.

    Your credit isn’t broken forever. With the right card, the right habits, and the right plan, you can rebuild — and we’re here to help you do it.

    This article is for educational purposes and does not constitute legal or financial advice. Credit outcomes vary based on individual circumstances. Sintra and credit-repair.com do not guarantee specific score improvements.