
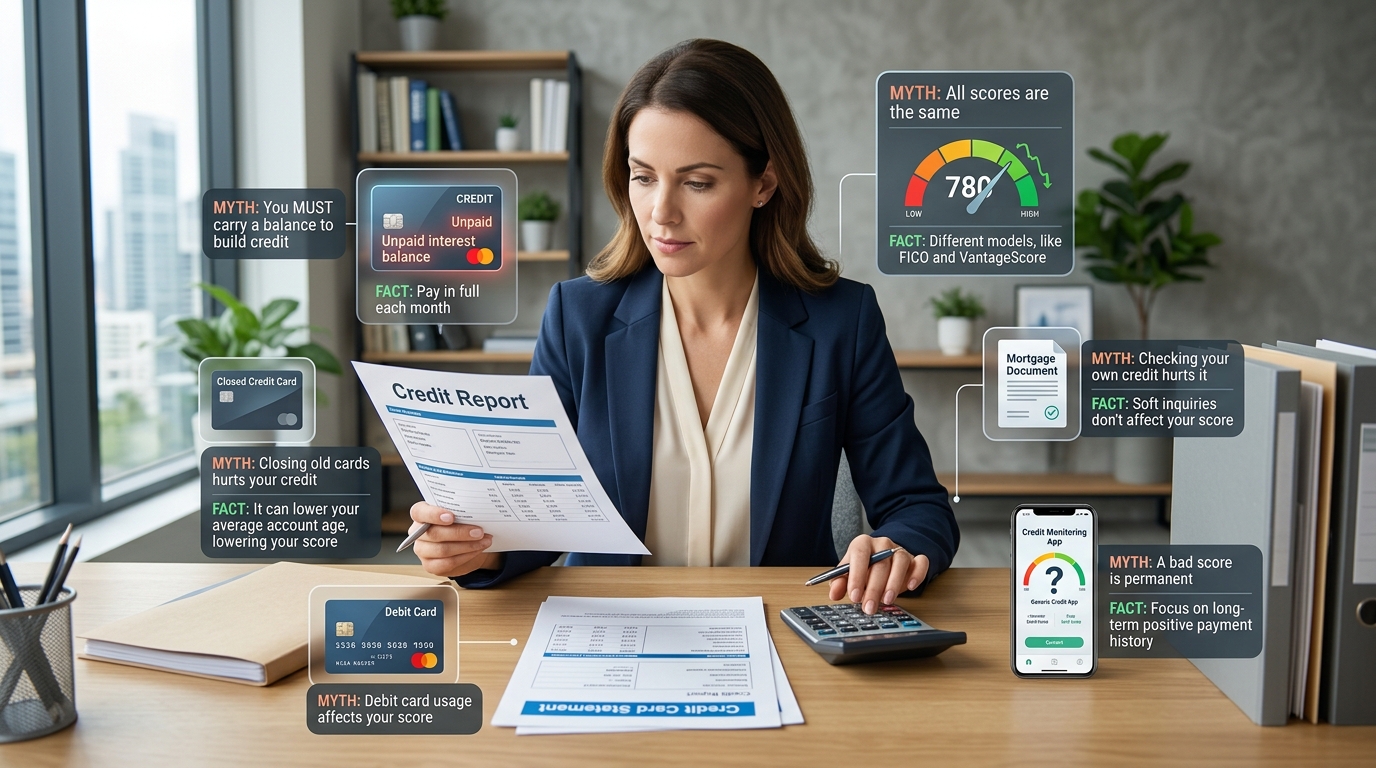
Some of these ideas were once true under specific circumstances and have since become outdated as credit scoring models evolved. Others were never true at all.
Either way, acting on bad credit advice can cost you money, slow your progress, or lead you to make decisions that do not actually help your credit profile.
This guide breaks down some of the most persistent credit score myths and explains what is actually true.
Myth: You Need to Carry a Balance to Build Credit
This is one of the most damaging and widespread credit myths because following the advice can cost you real money.
You do not need to carry a balance from month to month to build credit.
Carrying a balance means you may pay interest on your purchases. It does not create a special credit-building benefit simply because you allowed debt to remain unpaid after the statement due date.
What matters for your credit profile includes factors such as payment history and the amount of revolving credit you are using relative to your available limits.
You can therefore use a credit card, have activity reported to the credit bureaus, and then pay your statement balance in full.
The Consumer Financial Protection Bureau (CFPB) provides consumer guidance on using credit cards and managing balances. ([consumerfinance.gov](https://www.consumerfinance.gov/consumer-tools/credit-cards/?utm_source=chatgpt.com))
Bottom line: Carrying interest-bearing debt is not a requirement for building credit.
Myth: Checking Your Own Credit Score Hurts It
Checking your own credit report or score does not hurt your credit score.
When you request your own credit information, it is generally treated as a soft inquiry. Soft inquiries do not affect your credit score.
This is different from a hard inquiry, which can occur when a lender checks your credit in connection with an application for credit.
The CFPB explains the difference between hard and soft inquiries and notes that checking your own credit report does not hurt your score. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/does-checking-my-own-credit-report-hurt-my-credit-score-en-1331/?utm_source=chatgpt.com))
You can also check your official credit reports through AnnualCreditReport.com.
Myth: Closing a Credit Card You Don’t Use Helps Your Score
Closing an unused credit card does not automatically improve your credit score.
In some circumstances, closing a card can actually make certain scoring factors less favorable.
For example, closing a revolving account removes its available credit from your total available revolving credit. If your balances stay the same, your overall utilization ratio can increase.
Account age can also matter. A closed account in good standing may continue appearing on your credit reports for years, but eventually it may no longer contribute to the same extent once it falls off the report.
That does not mean you should keep every credit card open forever. Annual fees, security concerns, poor terms, or personal financial goals can all be legitimate reasons to close an account.
Before closing an account, consider how the change could affect your overall credit profile.
Read our guide on how credit scores are calculated for more context.
Myth: You Only Have One Credit Score
There is no single universal credit score attached permanently to your name.
Credit scores can vary because different scoring models can use different formulas, versions, and credit-report data.
FICO and VantageScore are two major scoring systems, and each has multiple versions.
Scores can also differ depending on which credit bureau’s information is being used.
This is why the score you see through one financial app may not be identical to the score a lender uses for a particular application.
The CFPB explains that consumers can have multiple credit scores because lenders and scoring companies may use different models and different credit-report information. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/why-is-my-credit-score-different-from-the-score-i-see-online-en-1797/?utm_source=chatgpt.com))
Myth: A Debit Card Builds Credit Just Like a Credit Card
A debit card does not build traditional credit history in the same way a credit card does.
When you use a debit card, the transaction generally draws money directly from your bank account.
Ordinary debit-card purchases are not reported to the credit bureaus as credit-account payment history.
Credit cards, installment loans, and certain specialized reporting services can contribute information to credit reports when the relevant company reports that information.
This is one reason why someone can responsibly use a debit card for years and still have little or no traditional credit history.
Myth: Being Married Automatically Merges Your Credit With Your Spouse’s
Marriage does not automatically create one shared credit report or one combined credit score.
Each spouse generally has an individual credit file.
Simply getting married, sharing a last name, or living at the same address does not merge the two credit reports.
Credit can become connected when spouses actually share financial obligations—for example, through a joint credit account or when one spouse becomes an authorized user on the other’s account.
If both spouses apply jointly for credit, the lender may review information from both individuals.
Myth: Paying Off a Collection Immediately Removes It From Your Credit Report
Paying a collection does not automatically mean the collection account disappears from your credit report.
Depending on the account and reporting practices, paying a collection may update the account’s status to show that it has been paid or settled.
That is different from deleting the collection entirely.
There are important exceptions and changes in how certain medical debt is treated. The three nationwide credit reporting companies announced that paid medical collections would be removed from consumer credit reports, and unpaid medical collections below $500 were also removed under their announced policy. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/how-does-medical-debt-affect-my-credit-report-en-1851/?utm_source=chatgpt.com))
For other types of collection accounts, payment does not necessarily result in automatic deletion.
Before paying an account, understand exactly how the payment is expected to affect the account and whether you have any dispute concerning its accuracy.
Learn more about removing collections from your credit report.
Myth: You Should Avoid Credit Entirely to Protect Your Score
Avoiding credit entirely does not create a perfect credit score.
If you have no credit accounts or very little reported history, lenders may simply have limited information with which to evaluate your creditworthiness.
Having no credit history is different from having excellent credit history.
If you eventually need a mortgage, auto loan, apartment, or other service where credit information is considered, having an established record of responsible credit management can be useful.
The CFPB recommends establishing a credit history and using credit responsibly rather than avoiding credit altogether. ([consumerfinance.gov](https://www.consumerfinance.gov/consumer-tools/credit-reports-and-scores/how-to-rebuild-your-credit/?utm_source=chatgpt.com))
Myth: A High Income Means a High Credit Score
Income itself is not one of the standard factors used to calculate a FICO or VantageScore credit score.
Someone earning a high salary can still have a low score if they have missed payments, high credit utilization, defaults, or other negative information.
Likewise, someone with a more modest income can have a strong credit profile if they consistently manage their credit accounts responsibly.
Income does matter in a different part of the lending process. A lender may ask about income when determining whether you can afford a loan or credit line.
But income and credit score are not the same thing.
Myth: Credit Repair Companies Can Remove Any Negative Item, Accurate or Not
No legitimate credit repair process can lawfully erase accurate negative information simply because a consumer wants it removed.
Credit repair can involve identifying information that is inaccurate, incomplete, outdated, or unverifiable and disputing it through the appropriate process.
Consumers can generally dispute inaccurate information themselves without paying a credit repair company.
The CFPB explains that consumers have the right to dispute inaccurate information on their credit reports. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/how-do-i-dispute-an-error-on-my-credit-report-en-314/?utm_source=chatgpt.com))
The FTC’s Credit Repair Organizations Act guidance also addresses prohibited practices, including misleading claims and certain advance-payment arrangements. ([ftc.gov](https://www.ftc.gov/business-guidance/resources/credit-repair-organizations-act-compliance-guide?utm_source=chatgpt.com))
Be particularly skeptical of companies promising to remove accurate negative information or guaranteeing a specific score increase.
Read our guide to whether credit repair companies work before hiring a company.
Myth: Once You Reach 850, You’re “Maxed Out” and Should Stop Worrying
850 is the top of the standard FICO score range, but reaching the maximum possible score is not necessary for every lending situation.
Different lenders use different underwriting criteria and scoring models, and the practical difference between very high scores can depend on the specific product and lender.
Once your credit is already strong, continued responsible management generally matters more than obsessing over every possible point.
The important objective is not simply to reach a particular number. It is to maintain a healthy credit profile that gives you access to appropriate financial products and terms.
Myth: Opening Several New Accounts at Once Builds Credit Faster
Opening several accounts quickly does not necessarily accelerate credit building.
New credit applications can result in hard inquiries, and newly opened accounts can reduce the average age of your accounts.
Opening multiple accounts can therefore produce short-term effects that are the opposite of what you intended.
The CFPB recommends applying for new credit only when needed and notes that multiple applications can affect your credit reports and scores. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/how-does-applying-for-a-credit-card-affect-my-credit-score-en-1119/?utm_source=chatgpt.com))
A smaller number of well-managed accounts can be a more sensible approach than rapidly accumulating new credit.
Myth: Your Score Resets to Zero If You Don’t Use Credit for a While
Your credit score does not simply reset to zero because you stop using credit for a period.
However, extended inactivity can create complications.
An issuer may eventually close an inactive credit card, which can affect your available credit. Also, some scoring models require recent account activity before a score can be generated.
The practical lesson is not that you need to constantly borrow money. It is that completely abandoning your credit accounts can sometimes create unintended consequences.
If you have a credit card with no annual fee, responsible occasional use may help keep the account active, but you should never create debt you cannot comfortably manage simply to generate activity.
Myth: Renting an Apartment or Paying Utilities Automatically Builds Credit
Paying rent and utility bills on time is financially responsible, but those payments do not automatically appear on every traditional credit report.
Some landlords, utility companies, and specialized reporting services may report payment information, but reporting practices vary.
This is why rent-reporting services exist: they can potentially convert eligible rental payment history into information reported to participating credit reporting companies.
Before paying for a reporting service, check which bureaus receive the information and what fees or limitations apply.
Myth: A Cosigner’s Credit Doesn’t Matter Once the Loan Is Approved
A cosigner’s responsibility does not end when the loan is approved.
A cosigner can remain legally responsible for the debt according to the terms of the agreement.
If the primary borrower fails to make payments, those missed payments can affect the cosigner as well.
This is why cosigning should be treated as a serious financial commitment rather than simply a favor that helps someone get approved.
Myth: You Should Never Apply for New Credit Right Before a Major Purchase
This advice contains a grain of truth but is too broad.
It is generally wise to avoid unnecessary new credit applications immediately before a major application such as a mortgage.
However, rate shopping for certain types of loans is treated specially by many scoring models. Multiple inquiries for a mortgage, auto loan, or student loan made within a defined shopping period may be treated as a single inquiry for scoring purposes.
The exact treatment depends on the scoring model and type of credit involved.
The CFPB recommends shopping around for loans while being aware that applications can result in credit inquiries. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/how-will-shopping-for-an-auto-loan-affect-my-credit-en-763/?utm_source=chatgpt.com))
Myth: All Debt Is Equally Bad for Your Credit
The existence of debt itself is not automatically damaging to your credit score.
What matters is how the debt is managed and how the account is reported.
For example, a credit card that is used responsibly and paid on time can contribute to a positive credit history.
A mortgage or installment loan with a consistent payment history can also contribute to your overall credit profile.
Problems arise when debt is mismanaged through missed payments, excessive revolving utilization, defaults, collections, charge-offs, or other negative events.
See our guide to how credit scores are calculated for more information about the factors involved.
Myth: Your Score Determines Whether You Get a Job or Apartment on Its Own
A credit score is not automatically a universal pass-or-fail test for employment or housing.
However, credit information can sometimes be considered in screening decisions, depending on the situation and applicable law.
For employment, employers that use consumer reports must comply with the Fair Credit Reporting Act and obtain the required permissions and disclosures. Employment-related credit reports are not simply identical to the score a lender uses.
For housing, landlords can use tenant screening reports and may consider credit information along with income, rental history, references, and other factors.
The key point is that credit score alone does not necessarily determine every employment or rental decision.
Myth: Paying Off Your Mortgage Early Always Improves Your Score
Paying off a mortgage can be an important financial achievement, but it does not guarantee an immediate increase in your credit score.
Once an installment loan is paid off, your credit profile can change because that account is no longer an active installment account.
Depending on the rest of your credit profile and scoring model, your score could move slightly.
That does not mean paying off a mortgage is financially harmful. Eliminating interest and reducing debt can provide significant financial benefits that have nothing to do with your credit score.
The broader lesson is that credit score optimization should not automatically override sound financial planning.
Myth: You Can’t Get Approved for Anything With a Low Score
A low credit score can make borrowing more difficult and expensive, but it does not necessarily mean that every financial product is unavailable.
Depending on the lender, consumers with lower scores may still qualify for products such as secured credit cards, credit-builder loans, or other products designed for people with limited or damaged credit.
The tradeoff may include higher interest rates, lower limits, security deposits, or other less favorable terms.
Improving your credit over time can expand your options.
For practical strategies, see our guide on how to improve your credit score.
Myth: Your Score Only Considers the Last Few Months of Activity
Recent activity matters, but your credit score is not based exclusively on the last few months.
Depending on the scoring model, factors can include payment history, amounts owed or utilization, length of credit history, credit mix, and new credit.
Your older account history can therefore continue to matter.
A recent late payment may be important, but it does not automatically erase years of positive history from the scoring equation.
Myth: Every Hard Inquiry Has the Same Impact
There is no universal rule saying that every hard inquiry lowers every person’s score by exactly the same number of points.
The effect can depend on the consumer’s overall credit profile and the scoring model being used.
Hard inquiries can have a greater relative effect on someone with a thin credit file than on someone with a long-established profile, although the actual impact varies.
That is another reason why generic statements such as “one inquiry always costs exactly X points” should be treated skeptically.
Myth: You Need Perfect Credit to Ever Get a Mortgage
You do not necessarily need perfect credit to qualify for a mortgage.
Different mortgage programs have different eligibility requirements.
For example, the Federal Housing Administration (FHA) provides mortgage-insurance programs that can accommodate borrowers who do not have perfect credit, subject to applicable requirements.
The U.S. Department of Housing and Urban Development provides current information about FHA credit requirements and mortgage programs. ([hud.gov](https://www.hud.gov/hud-partners/single-family-fha-loan-origination?utm_source=chatgpt.com))
However, qualifying for a mortgage and receiving the most favorable possible terms are different questions.
Myth: Having Too Many Credit Cards Automatically Hurts Your Score
The number of credit cards you have is not, by itself, a universal scoring penalty.
What matters more is how the accounts affect factors such as payment history, utilization, account age, and new credit.
Someone with several well-managed cards can have a strong credit profile, while someone with only one card can have a poor score if that account is consistently maxed out or paid late.
However, opening many cards in a short period can create hard inquiries and lower average account age, so rapidly accumulating accounts can still have consequences.
Myth: Credit Unions Give You Better Credit Scores Than Banks
There is no inherent credit-score bonus simply because a credit card or loan comes from a credit union rather than a bank.
Credit unions and banks can both furnish information to the major credit reporting companies.
Your score is primarily determined by the information in your credit reports and the scoring model being used, not by whether the institution happens to be structured as a bank or credit union.
Myth: Student Loan Debt Is Automatically Treated More Harshly Than Other Debt
Student loans are not automatically assigned a special “bad debt” penalty simply because they are student loans.
Credit scoring models consider factors such as payment history, account status, balances, and other characteristics of the credit file.
A student loan paid consistently according to its terms is very different from a student loan with serious delinquencies or defaults.
Myth: You Should Max Out a Credit Card Once to Prove You Can Pay It Off
This is bad credit advice.
Maxing out a credit card can cause your reported utilization to become very high.
High revolving utilization can negatively affect credit scores, even if you later pay the balance in full.
There is no general scoring bonus for temporarily maxing out a card to “prove” that you can repay it.
If your goal is to build or maintain strong credit, responsible use and manageable balances are generally much more useful than deliberately creating a high utilization ratio.
Myth: Your Score Drops Permanently After Your First Missed Payment
A missed payment can have a significant negative effect, particularly when it is reported as a serious delinquency.
But the effect does not remain exactly the same forever.
As time passes and you establish a longer record of on-time payments, the impact of the old late payment can diminish.
Negative payment information can generally remain on a credit report for up to seven years, but that does not mean the score is permanently frozen at the level it reached when the late payment occurred.
If you have late payments, see our guide to goodwill letters for late payments.
Myth: Credit Monitoring Apps Eventually Flag You for Checking Too Often
Checking your own credit information through a legitimate monitoring service does not create a special “suspicious activity” penalty on your credit score.
Consumer-initiated checks are generally soft inquiries and do not lower the score.
Monitoring your credit regularly can actually help you identify inaccurate or unfamiliar information sooner.
You can learn more about monitoring options in our guide to the best credit monitoring services.
Myth: Employers See Your Actual Credit Score During a Background Check
When an employer obtains a consumer report for employment purposes, the report is not necessarily the same product or score used by a lender.
Employment-related credit reports generally do not provide the employer with a standard numerical credit score in the same way a lender receives a credit score for a credit application.
Employers also must comply with applicable federal requirements when using consumer reports for employment decisions.
The FTC’s Fair Credit Reporting Act resources provide information about employer use of consumer reports. ([ftc.gov](https://www.ftc.gov/legal-library/browse/rules/fair-credit-reporting-act?utm_source=chatgpt.com))
Myth: Switching Banks or Credit Unions Resets Your Credit History
Changing your checking or savings bank does not reset your credit history.
Your credit history is maintained through credit reporting companies and is associated with your individual identifying information and reported accounts.
If you close a checking account and open another at a different bank, your credit cards, loans, and other reported accounts do not simply disappear.
Where These Credit Score Myths Actually Come From
Credit myths often survive because they contain a small piece of truth wrapped inside an overly broad statement.
Some advice comes from older scoring models or rules that have changed over time.
Some comes from individual experiences. Someone may take an action and then see their score rise, incorrectly assuming that the action itself caused the increase.
Other myths survive because they are repeated so frequently that repetition begins to feel like proof.
Online credit content can contribute to the problem when articles copy one another without checking primary sources.
That is why it is useful to compare credit advice against information from sources such as the CFPB, FTC, U.S. government agencies, and official credit reporting or scoring organizations.
A Practical Test for Evaluating Credit Advice
When you encounter a new credit tip online, ask a few basic questions.
Does It Connect to an Actual Credit-Scoring Factor?
For many widely used scoring models, major factors include payment history, amounts owed or utilization, length of credit history, credit mix, and new credit.
If a piece of advice claims that something completely unrelated to your reported credit activity will magically increase your score, be skeptical.
Does It Make Sense Given How Credit Reporting Works?
Creditors and other furnishers report account information to credit reporting companies. Scoring models then calculate scores using the information available in the relevant credit report.
There is no secret mechanism where a lender awards points because you followed an arbitrary credit ritual.
Can You Verify It With Independent Sources?
Look for information from multiple reputable sources rather than relying on a single social-media post, influencer, or blog.
The CFPB’s credit-report and score resources are a useful starting point. ([consumerfinance.gov](https://www.consumerfinance.gov/consumer-tools/credit-reports-and-scores/?utm_source=chatgpt.com))
Does It Promise a Guaranteed or Dramatic Result?
Be especially skeptical of claims that a single trick will increase your score by a guaranteed number of points.
Credit improvement generally comes from changes in actual account information and financial behavior.
Myth: You Can’t Dispute the Same Credit Report Item Twice
You are not necessarily limited to one dispute forever.
If you have additional evidence or a legitimate new basis for disputing information, you may be able to submit another dispute.
However, repeatedly submitting identical disputes without new information is unlikely to produce a different result.
If you are disputing an error, keep copies of your supporting documents and previous correspondence.
See our guide on how to dispute credit report errors.
Myth: A Bankruptcy Permanently Caps Your Credit Score
A bankruptcy can have a substantial effect on your credit history while it remains on your credit reports.
But there is no permanent invisible “credit score ceiling” that remains forever after a bankruptcy disappears from your credit reports.
Once negative information is no longer part of the report used by the scoring model, it generally cannot continue affecting that score merely because it existed in the distant past.
Bankruptcy reporting periods can differ by type of bankruptcy and applicable reporting rules.
If you are dealing with bankruptcy-related credit issues, see our guide to Chapter 7 vs. Chapter 13 bankruptcy.
Myth: All Forms of Credit Repair Are Scams
This is more nuanced than simply saying “true” or “false.”
Credit repair itself is a real process. Consumers can review their reports, identify inaccurate information, dispute errors, and exercise rights provided by federal law.
Consumers can also hire companies to assist with certain credit-repair activities.
What is misleading is the idea that a company has a secret legal ability to erase accurate negative information or guarantee a particular credit score.
The FTC warns consumers about credit-repair companies that make deceptive promises or engage in prohibited practices. ([ftc.gov](https://consumer.ftc.gov/articles/credit-repair-how-helpful?utm_source=chatgpt.com))
Before hiring a company, understand what it can legitimately do and what you can do yourself for free.
Frequently Asked Questions
Does carrying a credit card balance improve your credit score?
No. You do not need to carry interest-bearing debt from month to month to build credit. Responsible use and on-time payments matter, while paying your statement balance in full can help you avoid unnecessary interest.
Does checking your own credit lower your score?
No. Checking your own credit report or score is generally a soft inquiry and does not lower your credit score. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/does-checking-my-own-credit-report-hurt-my-credit-score-en-1331/?utm_source=chatgpt.com))
Does closing a credit card hurt your credit?
It can, depending on your overall credit profile. Closing an account can reduce available revolving credit and potentially increase utilization.
Does having a high income give you a higher credit score?
No. Income is not a standard credit-scoring factor. Lenders may consider income separately when deciding whether to approve an application.
Does paying a collection delete it from your credit report?
Not automatically. Payment may update the account’s status, but most collection accounts are not automatically deleted simply because they are paid.
Does marriage combine two credit scores?
No. Spouses generally maintain separate credit reports and scores. Joint accounts and authorized-user relationships can connect credit activity, but marriage alone does not merge credit files.
Does a debit card build credit?
Ordinary debit-card transactions generally do not build traditional credit history because they use money already held in your bank account.
Can you have more than one credit score?
Yes. Different scoring models and different credit-report data can produce different legitimate scores.
Does opening several credit cards build credit faster?
Not necessarily. Multiple applications can produce hard inquiries and new accounts can lower the average age of your credit accounts.
Does renting automatically build credit?
No. Rent generally needs to be reported through a participating landlord or rent-reporting service to appear as credit history.
Does a cosigner’s credit matter after the loan is approved?
Yes. A cosigner can remain legally responsible for the debt and can be affected if the borrower fails to make payments.
Can a low credit score prevent you from getting every type of credit?
No. Some products are specifically designed for consumers with limited or damaged credit, although the terms may be less favorable.
Do you need an 850 credit score to get the best financial opportunities?
Not necessarily. Lenders use different underwriting standards and scoring models, and many financial products do not require a perfect score.
Do you need perfect credit to qualify for a mortgage?
No. Mortgage programs have different requirements, and some programs accommodate borrowers with less-than-perfect credit. ([hud.gov](https://www.hud.gov/hud-partners/single-family-fha-loan-origination?utm_source=chatgpt.com))
Can a bankruptcy permanently damage your score?
Bankruptcy can significantly affect your credit while it is reported, but there is no permanent invisible score cap that continues indefinitely after the bankruptcy information is no longer part of the credit report.
Can accurate negative information be removed through credit repair?
A legitimate credit-repair process cannot lawfully guarantee removal of accurate, verifiable negative information simply because a consumer wants it gone. Credit repair focuses on inaccurate, incomplete, outdated, or unverifiable information and applicable consumer rights.
The Bottom Line
Credit score myths persist because they sound plausible, get repeated informally, and are rarely checked against how credit reporting and scoring actually work.
The common thread behind most of these myths is simple: your credit profile is based on actual reported account information and financial behavior—not credit superstitions.
Payment history, credit utilization or amounts owed, length of credit history, credit mix, and new credit are much more useful concepts to understand than rules such as “always carry a balance” or “never check your score.”
When you hear a new piece of credit advice, ask what actual credit-report information it changes and which scoring factor it affects.
If the advice promises a secret trick, guaranteed score increase, or immediate removal of accurate negative information, be particularly cautious.
For more practical guidance, explore our credit repair tips or learn how to fix your credit step by step.
Need Help Reviewing Your Credit Report?
If you are unsure whether information on your credit report is accurate, reviewing the actual accounts and identifying potential errors is a useful starting point.
Contact Credit Repair Services to discuss your credit situation →