Category: Credit Repair

  • How to Negotiate With a Debt Collector Without Getting Taken Advantage Of

    How to Negotiate With a Debt Collector Without Getting Taken Advantage Of

    Negotiating with a debt collector is one of those situations where the other side has done this thousands of times, and you’re probably doing it for the first time. That imbalance in experience is real, but it doesn’t mean you’re powerless — understanding the actual mechanics of how these negotiations work, what leverage you genuinely have, and the specific mistakes that put people at a disadvantage levels the playing field considerably.

    This guide walks through exactly how to negotiate effectively while protecting yourself throughout the process.

    Before negotiating, it is also important to understand how debt validation works and make sure you are dealing with an account that is actually yours and accurately documented.

    Understand Your Leverage Before You Start

    Many people enter a debt negotiation assuming they have no power at all — they owe the money, so what room is there to negotiate? In reality, you have more leverage than this assumption suggests, particularly if you’re dealing with a debt buyer rather than the original creditor.

    If it’s a debt buyer, they purchased your debt for a fraction of its face value — often somewhere between a few cents and twenty cents on the dollar. This means even a settlement at 30-40% of the balance likely represents a substantial profit relative to what they paid, giving you real room to negotiate below the full amount.

    However, the price a debt buyer paid for an account does not automatically determine the amount you legally owe or guarantee that a particular settlement percentage will be accepted.

    If the debt is old, approaching or past your state’s statute of limitations, the collector’s legal options are limited or nonexistent, which changes the power dynamic significantly, even though this requires careful handling given the payment-restarts-the-clock risk covered elsewhere.

    Before making a payment on old debt, review our guide to the statute of limitations on debt.

    If the debt is poorly documented, particularly after being resold multiple times, the collector may have genuine gaps in their ability to prove the debt is accurately yours and accurately calculated, giving you dispute leverage separate from settlement negotiation.

    Your own ability and willingness to pay something (even if not the full amount) is itself leverage, since collectors generally prefer recovering something over nothing, particularly for older or harder-to-collect accounts.

    Verify Before You Negotiate Anything

    Before entering any negotiation, request formal debt validation. Negotiating a settlement on a debt you haven’t verified is inaccurate, or that isn’t actually yours, means potentially paying for something you didn’t need to resolve at all.

    This step costs you nothing but a short delay and protects you from negotiating away money unnecessarily.

    The Consumer Financial Protection Bureau recommends confirming that you owe the debt before negotiating and explains that validation information can help you determine whether the debt is yours and how much is claimed. See the CFPB’s guidance on negotiating a settlement with a debt collector.

    If the information is inaccurate, you may need to dispute the account rather than immediately negotiate payment. You can also review our guide on how to dispute credit report errors.

    Set Your Own Numbers Before the Conversation, Not During It

    Determine the maximum you’re genuinely willing and able to pay, as a firm ceiling, before any conversation begins — negotiating under pressure, in real time, without a predetermined limit is exactly how people end up agreeing to more than they intended.

    Determine a reasonable opening offer, below your actual ceiling, giving yourself room to negotiate upward if needed.

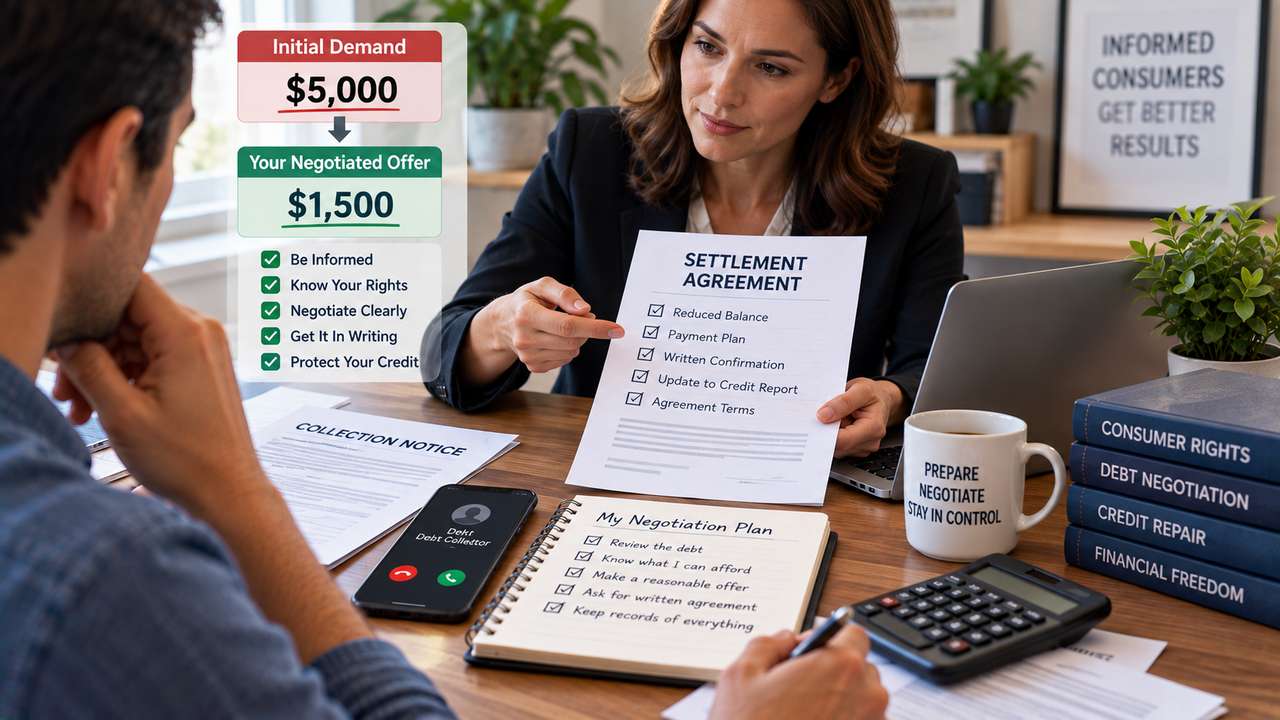
    For debt buyer accounts specifically, an opening offer in the 20-30% range of the claimed balance isn’t unreasonable, given how cheaply these accounts are often acquired. However, this is a negotiation strategy rather than a guaranteed industry rule, and there is no universal settlement percentage that every collector will accept.

    Decide whether a lump sum or a payment plan better fits your actual financial situation, and be clear with yourself about which structure you’re aiming for before the conversation, rather than deciding on the spot.

    The CFPB similarly recommends calculating a realistic repayment amount and considering your income, expenses, and ability to maintain payments before making a proposal. Review the CFPB’s negotiation guidance.

    Tactics Collectors Use That You Should Recognize

    Artificial Urgency

    “This offer is only available today” is a common pressure tactic. Legitimate debt doesn’t expire within a single phone call, and a collector genuinely interested in resolving the account will typically still be willing to negotiate tomorrow, or after you’ve had time to think.

    You should not feel obligated to make a financial commitment simply because a representative creates a sense of urgency.

    Anchoring High

    Collectors often open with a settlement offer at a relatively high percentage of the balance (sometimes 70-80%), hoping you’ll negotiate down from there rather than up from a lower starting point.

    Don’t treat their opening number as the realistic ceiling of what’s negotiable — treat it as their opening position, exactly as your own opening offer is yours.

    Implying You Have No Other Option

    Some collectors frame settlement as your only path forward, without mentioning alternatives like disputing the debt, exploring your state’s statute of limitations, or simply taking more time to consider your options.

    Your options depend on the specific debt and your circumstances, but you generally do not have to make a decision during a single phone call.

    Requesting Payment Information Before Terms Are Finalized

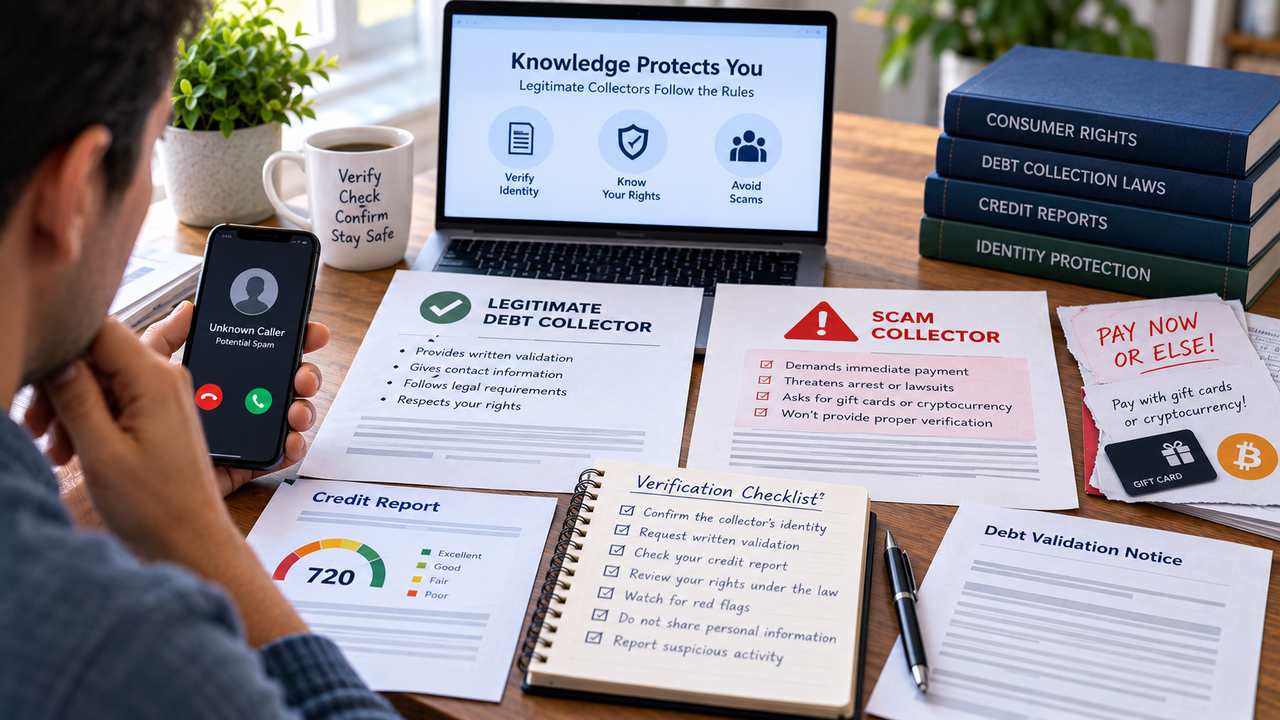
    Never provide bank account or card information until you’ve actually agreed on final terms and have them in writing — a request for payment details before an agreement is finalized is a red flag regardless of how routine it’s framed as being.

    The CFPB specifically recommends getting a repayment or settlement agreement and the collector’s promises in writing before making a payment. See the CFPB’s recommendations for documenting settlement agreements.

    How to Actually Structure the Negotiation Conversation

    Start by Confirming the Debt

    Start by confirming the debt has been validated and you’re negotiating based on accurate information.

    State Your Offer Clearly

    State your opening offer clearly and calmly, without over-explaining or apologizing extensively for your financial situation — a clear, confident offer tends to be taken more seriously than an anxious, over-justified one.

    Expect Some Back-and-Forth

    Expect and allow for some back-and-forth. It’s normal for the collector to counter your initial offer, and for the final agreed amount to land somewhere between your opening offer and theirs.

    This is a completely standard part of the process, not a sign anything has gone wrong.

    Do Not Feel Forced to Agree Immediately

    Don’t feel obligated to agree during this call. If you need time to think, or want to run numbers by someone you trust, it’s entirely reasonable to say you’ll call back with a decision, rather than committing to something in the moment because you feel pressured to resolve it immediately.

    Getting the Agreement in Writing — The Single Most Important Protection

    Regardless of what’s agreed to verbally, never send payment until you have the specific terms in writing.

    This should include:

    • The exact amount agreed upon.
    • Explicit confirmation that this payment constitutes full and final settlement of the debt (not a partial payment toward a larger remaining balance, unless that’s genuinely your intended structure).
    • How the account will be reported to the credit bureaus once payment is made (paid, settled, or, if you’ve specifically negotiated it, deleted — though deletion agreements are far from guaranteed and shouldn’t be assumed without explicit written confirmation).
    • A specific payment method and timeline.

    If a collector is unwilling to put the agreed terms in writing before you send payment, this is a significant warning sign, and reasonable grounds to pause and reconsider before proceeding.

    The CFPB explicitly advises consumers to get settlement or repayment plans and the collector’s promises in writing before making a payment. Read the CFPB’s settlement documentation guidance.

    Common Mistakes That Put People at a Disadvantage

    Confirming Personal or Financial Details Before Validating the Debt

    Providing sensitive information early, before you’ve verified anything, gives the collector information they can potentially use, without you having gained any corresponding verification in return.

    Agreeing to a Payment Plan Without Understanding the Consequences

    Some settlement agreements include provisions where missing even one payment voids the entire settlement, reverting you to owing the full original balance — understanding this specific risk before agreeing to a payment plan (versus a single lump-sum payment) is important.

    Read the agreement carefully before committing to a structured payment arrangement.

    Not Asking About the Tax Implications of a Large Settlement

    If more than $600 of debt is forgiven as part of your settlement, the creditor may be required to issue a Form 1099-C, which can create a tax obligation on the forgiven amount — worth knowing about in advance, not discovering unexpectedly during tax season.

    The IRS states that applicable creditors generally must file Form 1099-C when $600 or more of debt is canceled, and canceled debt may generally be taxable income unless an exception or exclusion applies. See the IRS information on Form 1099-C.

    The tax treatment depends on your individual circumstances, so consider speaking with a qualified tax professional before finalizing a large settlement.

    Making a Payment on Old Debt Without Checking the Statute of Limitations

    Making a payment on old debt without checking the statute of limitations first can potentially create legal complications, depending on the state and circumstances.

    The CFPB advises consumers to find out the applicable statute of limitations before making a payment or agreeing to a payment plan on an old debt. Review the CFPB’s guidance on old debt.

    Negotiating From Shame or Panic

    Negotiating from a place of shame or panic rather than calm, methodical decision-making can make the process harder.

    It’s completely understandable to feel emotional about debt, but negotiating effectively requires treating the conversation as a business transaction, separate from any feelings of guilt or embarrassment about the underlying circumstances that led to the debt.

    What a Fair Settlement Typically Looks Like

    While every situation varies, general industry patterns can help calibrate your expectations.

    For debt buyer-owned accounts specifically, settlements in the 30-50% range of the claimed balance are commonly reported as achievable, particularly for older accounts or accounts where you can demonstrate genuine financial hardship.

    For debt still with the original creditor or an agency working on their behalf, the range may run somewhat higher, since their own flexibility is more constrained.

    These are general patterns, not guarantees — your specific outcome depends on the particular company, the debt’s age and documentation, and how the negotiation itself unfolds.

    Rather than relying on a particular percentage as a guaranteed target, use your own budget and ability to pay to establish a maximum amount you can responsibly afford.

    Frequently Asked Questions

    Should I tell the collector I’m negotiating with multiple debts at once, or keep that information private?

    This is generally worth keeping to yourself during negotiation — while it might seem like disclosing broader financial hardship could help your case, it can also be used by the collector to argue you need to prioritize this specific debt, and it doesn’t typically strengthen your negotiating position to volunteer this kind of comprehensive financial picture.

    Is it better to negotiate over the phone or in writing?

    Both have advantages — phone negotiation allows real-time back-and-forth that can move the conversation along efficiently, while written negotiation (letters or email, where the collector’s policies allow it) creates an automatic documented record.

    Many people use a hybrid approach: negotiating verbally, then insisting on written confirmation before finalizing anything, combining the efficiency of real-time discussion with the protection of documentation.

    Can I negotiate a settlement without disclosing exactly how much I can afford?

    Yes — you’re not obligated to reveal your full financial picture or a specific maximum amount during negotiation; stating your offer and negotiating from there, without explaining in detail why that’s your limit, is a reasonable and common approach.

    What if the collector refuses to negotiate at all and insists on the full balance?

    This does happen, particularly with some original creditors or agencies with limited authorized flexibility.

    If this occurs, it’s worth asking directly whether a payment plan (even at the full balance) is available, or considering whether disputing any inaccuracies, or simply taking more time before deciding how to proceed, makes more sense than accepting their full, non-negotiated demand under pressure.

    Is it worth hiring a debt settlement company to negotiate on my behalf?

    Many people successfully negotiate directly without paying a third party, since the core skills involved (verification, patience, getting things in writing) don’t necessarily require professional intervention.

    A debt settlement company or attorney becomes more valuable if you’re managing multiple debts simultaneously, facing active litigation, or simply want professional guidance and don’t feel confident handling the negotiation yourself.

    The CFPB cautions that debt settlement companies can carry risks and fees and recommends considering alternatives such as negotiating directly or working with a nonprofit credit counselor. Review the CFPB’s guidance on debt relief programs.

    A Complete Sample Negotiation Script

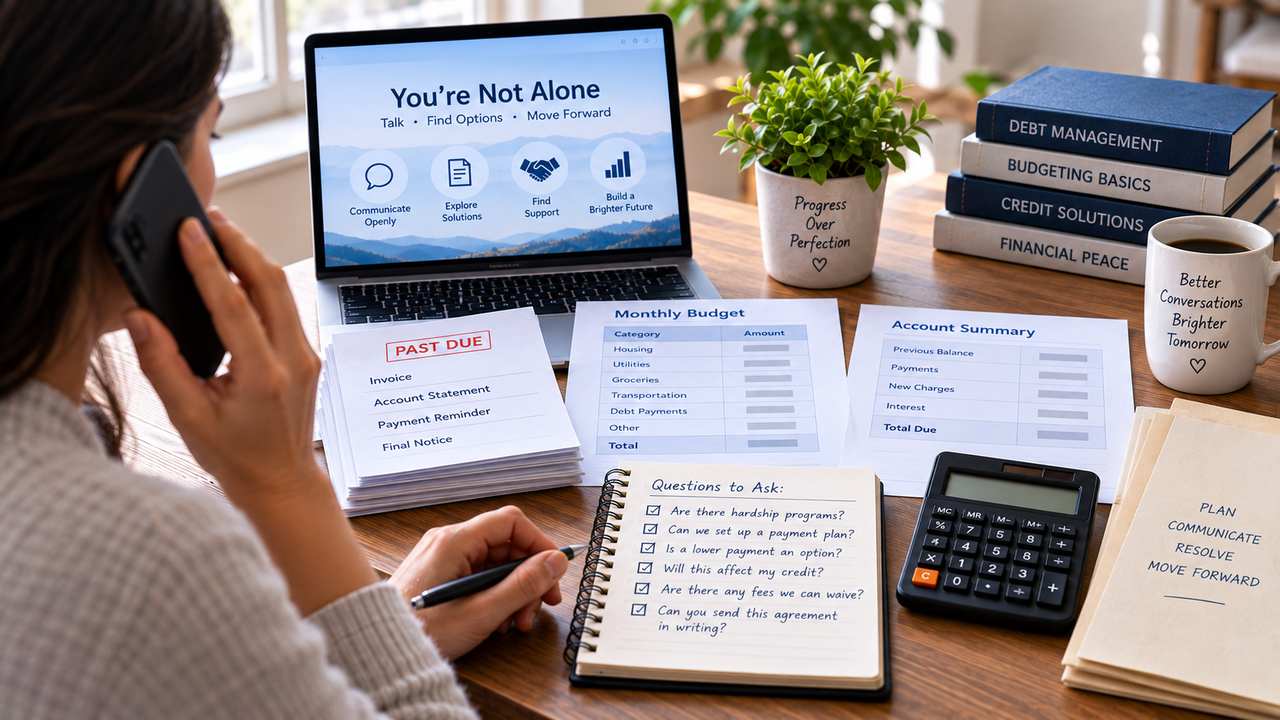
    Having language prepared in advance removes much of the anxiety from an unfamiliar negotiation. Here’s a full script you can adapt:

    Opening

    “I’m calling regarding account [number]. I’ve reviewed the validation information you sent, and I’d like to discuss resolving this account.”

    Making Your Offer

    “I’m able to pay [X amount] as a lump sum, which would represent full and final settlement of this account. Is that something your company can agree to?”

    If They Counter With a Higher Amount

    “I understand, but [X amount] is genuinely what I’m able to offer right now. Would you be able to accept [a slightly higher amount, if you have room] as a final resolution?”

    Before Agreeing to Anything

    “Before I send any payment, I’ll need this agreement in writing — specifically the settlement amount, confirmation this resolves the account in full, and how it will be reported to the credit bureaus.”

    If Pressured for Immediate Payment Information

    “I’m not able to provide payment details until I’ve received the written confirmation we discussed. Once I have that, I’ll be able to move forward promptly.”

    This script keeps the conversation focused, professional, and protected at each key decision point, without requiring you to improvise under pressure.

    How to Handle a Collector Who Becomes Aggressive or Pushes Back Hard on Your Written-Confirmation Request

    If a collector resists providing written confirmation before payment, insisting it’s unnecessary or that you should “just trust” the verbal agreement, this is worth treating as a significant red flag rather than a minor inconvenience.

    A legitimate company negotiating in good faith has no real reason to refuse a request as basic as putting agreed-upon terms in writing — this is standard practice across the debt collection and settlement industry, and a collector’s resistance to it should increase, not decrease, your caution about proceeding with payment.

    The CFPB likewise advises consumers to get repayment or settlement terms in writing before making a payment. Review the CFPB’s consumer guidance.

    Understanding the Difference Between “Settled” and “Paid in Full” for Your Credit Report

    As part of your negotiation, it’s worth understanding this distinction, since it affects how the resolved account will appear on your credit report.

    “Paid in full” means you paid the entire original balance, and this designation is generally viewed most favorably.

    “Settled” or “paid, less than full balance” means you paid a negotiated, reduced amount, and while this is still considerably better than an unpaid balance, some scoring models and some future lenders manually reviewing your file view a “settled” status very slightly less favorably than “paid in full.”

    This is a difference worth knowing about but generally not enough, by itself, to justify paying substantially more than you can responsibly afford simply to secure a “paid in full” label instead of a well-negotiated settlement.

    If you are reviewing how collection accounts appear on your credit report, see our guide on how to read a credit report.

    Frequently Asked Questions, Continued

    Is it ever worth making a counteroffer that’s lower than what I’d actually be willing to pay, to leave room for negotiation?

    Yes, this is a standard and reasonable negotiation tactic — opening below your actual ceiling gives you room to make concessions during back-and-forth while still landing at or below what you were genuinely willing to pay, similar to how the collector’s own opening offer is typically higher than their actual floor.

    Should I negotiate differently if I’m dealing with a company I know has a history of consumer complaints?

    It’s worth being even more diligent about documentation and written confirmation with a company that has a known pattern of complaints, though the core negotiation principles remain the same — verify, know your numbers, and never pay without written terms, regardless of which specific company you’re dealing with.

    If you believe a collector is violating your rights, you can learn more in our guide to collection agency harassment and the FDCPA.

    Can I ask for a longer period to pay a lump sum, like 30 or 60 days, rather than paying immediately?

    Yes, this is a reasonable request, particularly if you need time to gather funds — many collectors are willing to hold a negotiated settlement offer open for a specific period, though it’s worth getting this timeline confirmed in writing along with the rest of the agreement’s terms.

    If I negotiate a settlement and later realize I could have gotten a better deal, is there any way to reopen the negotiation?

    Once a settlement is finalized and paid, it’s generally considered closed and binding, so this isn’t typically an option after the fact — this is exactly why taking your time, not feeling rushed, and being confident in your offer before finalizing anything matters more than trying to renegotiate after the fact.

    A Comparison of Negotiation Approaches by Debt Type

    Debt Type Typical Negotiating Room Special Considerations
    Debt buyer-owned credit card debt High (often 30-50% achievable) Purchased at steep discount; often most flexible
    Original creditor still holding the debt Moderate Constrained by internal policy; sometimes hardship programs available
    Medical debt Often high Providers frequently prefer resolution over prolonged collection; nonprofit hospitals sometimes have charity care programs
    Very old, potentially time-barred debt Variable Verify statute of limitations before any payment; restart-the-clock risk applies
    Debt already in litigation Real, but time-sensitive Settlement can still occur, but responding to the lawsuit itself remains essential regardless

    This table is a general guide, not a guarantee — actual outcomes depend heavily on the specific company, your documented circumstances, and how the negotiation itself unfolds, but it’s useful for calibrating your expectations and opening offer strategy based on which category your specific debt falls into.

    how-to-negotiate-with-a-debt-collector-under-100kb-v2

    Frequently Asked Questions, Continued Further

    Does negotiating a settlement affect my ability to negotiate other unrelated debts in the future?

    No — each debt and each negotiation is independent; successfully or unsuccessfully negotiating one account has no bearing on your standing or leverage with a completely separate creditor or collector for a different debt.

    Is it reasonable to ask the collector why they’re unwilling to go lower than a certain amount during negotiation?

    You can ask, though they’re not obligated to explain their internal reasoning or authorization limits — if they hold firm at a number that doesn’t work for you, it’s reasonable to either continue negotiating, take time to consider, or decide that particular offer doesn’t meet your needs and explore your other options (dispute, payment plan structured differently, or simply not proceeding immediately).

    Should my approach differ if I’m negotiating on behalf of a family member rather than my own debt?

    The same core principles apply, though you’d generally need proper authorization to negotiate on someone else’s behalf (verified by the collector), and it’s worth being clear about your role and relationship to the account from the outset of the conversation to avoid confusion about who’s actually agreeing to any final terms.

    The Bottom Line

    Negotiating with a debt collector without getting taken advantage of comes down to a few consistent principles: verify the debt before negotiating anything, know your own numbers before the conversation starts, recognize common pressure tactics for what they are, and never send payment without the final terms in writing.

    You have more genuine leverage than the power imbalance might initially suggest, particularly with debt buyers who acquired your debt at a steep discount — approaching the negotiation calmly, methodically, and with your own predetermined boundaries turns what can feel like an intimidating conversation into a manageable, controllable process.

    Related Credit & Debt Resources

    Need Help Reviewing Your Credit Situation?

    If you are dealing with collection accounts, inaccurate balances, repeated collection activity, or accounts that may have changed ownership, reviewing your credit situation can help you understand what appears on your reports and what issues may need attention.

    Request a Credit Audit

    Important: This article provides general educational information and is not legal or tax advice. Debt-collection laws, statutes of limitations, settlement practices, credit-reporting rules, and tax consequences can vary depending on the debt and your circumstances. If you are facing a lawsuit, a time-barred debt issue, or significant tax consequences from canceled debt, consider consulting a qualified attorney or tax professional.
  • Can Debt Collectors Contact Your Employer or Family?

    Can Debt Collectors Contact Your Employer or Family?

    One of the more anxiety-inducing fears people have about unpaid debt is the possibility of a collector calling their boss, or telling family members about their financial troubles. This fear is understandable, but it’s also based on a significant misunderstanding of what debt collectors are actually allowed to do. Federal law places firm, specific limits on this kind of contact, and knowing exactly where those limits sit puts you in a much stronger position if it ever comes up.

    If you are dealing with collection activity, it can also help to understand your rights under the FDCPA and how improper collection practices may be challenged.

    The Short Answer: Very Limited Contact Is Allowed, and Almost Never What You’re Afraid Of

    Under the Fair Debt Collection Practices Act, a debt collector is permitted to contact third parties — including your employer, family members, neighbors, or anyone else — for exactly one narrow purpose: to obtain your location information, such as a current address or phone number, if the collector doesn’t already have accurate contact information for you.

    Beyond that single, narrow purpose, they generally cannot discuss the debt itself, disclose that you owe money, or reveal any details about your financial situation to a third party.

    The Consumer Financial Protection Bureau explains that federal debt-collection rules restrict how collectors communicate with people other than the consumer and include specific requirements regarding third-party communications. Review the CFPB’s Regulation F rules on third-party communications.

    What Collectors Can Legally Ask a Third Party

    • Your current address.
    • Your current phone number.
    • Your place of employment, if they don’t already know it and need it solely for the purpose of correctly contacting you (not for the purpose of contacting your employer about the debt itself).

    That’s essentially the full scope of what’s legally permitted when contacting a third party. The FDCPA is specific and restrictive here precisely because Congress recognized how damaging and embarrassing it would be for collectors to be able to freely discuss someone’s debt with employers, family, or acquaintances.

    For more information about federal debt-collection protections, you can also review the CFPB’s debt collection consumer resources.

    What Collectors Cannot Do When Contacting a Third Party

    • They cannot state or imply that you owe a debt. The conversation is legally supposed to be limited to location information, not disclosure of the underlying financial matter.
    • They cannot contact the same third party more than once, unless they have a reasonable belief the earlier information was incorrect or incomplete, or the third party specifically requests a follow-up contact.
    • They cannot use any language or symbol on an envelope indicating they’re a debt collector, if sending written correspondence to a third party for location purposes, and generally cannot identify their employer as a debt collection company unless specifically asked.
    • They cannot discuss the amount owed, the nature of the debt, or any other financial details with anyone other than you (or your spouse, or your attorney, if applicable) without your explicit consent.

    These restrictions are part of the federal rules governing covered debt collectors. The exact application can depend on the circumstances and the relationship of the person being contacted.

    What About Calling Your Workplace Directly to Reach You (Not Your Employer About the Debt)?

    This is a different scenario worth distinguishing clearly: a collector calling your workplace phone number specifically to reach you (not to discuss the debt with your employer or coworkers) is generally permitted, unless you’ve told them not to contact you at work, or unless they know or have reason to know your employer prohibits you from receiving such calls.

    Once you inform a collector — verbally or in writing — that you cannot receive calls at work, they’re legally required to stop contacting you there, and this request is straightforward and something you’re fully entitled to make at any time.

    For additional information about controlling communications from collectors, see our guide to cease-and-desist letters for debt collectors.

    Can They Tell Your Employer You Owe Money, to Pressure You Into Paying?

    No — this would be a clear FDCPA violation. Some particularly aggressive or illegitimate collectors have, historically, attempted this kind of pressure tactic (sometimes explicitly threatening to “call your boss” if you don’t pay), but this crosses a firm legal line.

    If a collector does this, or explicitly threatens to do this, it’s a serious violation worth documenting and reporting.

    The Federal Trade Commission explains that the FDCPA prohibits covered debt collectors from using unfair, deceptive, or abusive collection practices. Review the FTC’s debt collection guidance.

    Can Debt Collectors Garnish Wages Without Involving Your Employer?

    This is a related but distinct question worth addressing, since wage garnishment does necessarily involve your employer, but through an entirely different legal process than informal debt collection contact.

    If a collector obtains a court judgment against you and then legally pursues wage garnishment, your employer will be formally notified through a legal garnishment order, which is a legitimate court process, not the kind of informal “calling your boss to pressure you” scenario this article is otherwise addressing.

    Your employer is legally required to comply with a valid garnishment order once issued, and while this is understandably still uncomfortable, it’s a fundamentally different, legally structured process than a collector simply calling your workplace to disclose your debt informally.

    Federal and state rules governing garnishment can vary. The CFPB provides additional information about how wage and benefit garnishment can work and why consumers should understand applicable protections. See the CFPB’s garnishment guidance.

    If you are already dealing with a lawsuit over a collection account, our guide on what happens if you ignore a debt collection lawsuit may also be helpful.

    What About Family Members — Can They Be Told You Owe Money?

    The same core restriction applies: a collector generally cannot disclose the existence or details of your debt to family members, beyond the narrow location-information exception discussed above.

    There is one specific exception worth knowing: if you’re married, a collector may be permitted to discuss the debt with your spouse specifically, depending on your state’s laws (particularly relevant in community property states, where a spouse may have some legal responsibility for certain debts incurred during the marriage), and in some cases with a parent if you’re a minor.

    Beyond these specific, limited exceptions, siblings, adult children, parents (of an adult), roommates, or other family members generally cannot be told about your debt by a collector.

    The CFPB’s Regulation F includes specific rules governing communications with people other than the consumer. Review the federal third-party communication rules.

    What to Do If a Collector Violates These Rules

    Document Everything

    Document everything. Note the date, time, what was said, and to whom, if you become aware that a collector improperly contacted your employer or a family member and disclosed information about your debt.

    Keep copies of collection letters, emails, text messages, voicemails, and any other communications that may help establish what occurred.

    Send a Written Complaint or Cease-and-Desist Request

    Send a written complaint or cease-and-desist request if the behavior continues, formally noting the violation and your understanding of the law.

    Our guide to credit repair letters can help you understand how written correspondence can be organized when addressing credit and collection issues.

    File a Complaint With the CFPB

    File a complaint with the CFPB. This creates a formal record and requires the company to respond, which can be an effective way to hold them accountable, particularly for clear, documented violations like this.

    You can submit a consumer complaint through the CFPB.

    Consider Consulting a Consumer Law Attorney

    Consider consulting a consumer law attorney. FDCPA violations like improper third-party disclosure can support a legal claim, including statutory damages, and this is exactly the kind of clear violation that attorneys handling these cases are often willing to take on, sometimes on a contingency basis.

    The FDCPA contains specific provisions concerning civil liability and the time period for bringing private actions. Because deadlines and legal remedies can be important, legal advice should come from a qualified attorney familiar with your circumstances and state.

    What If Your Employer Finds Out About Your Debt Some Other Way?

    It’s worth distinguishing a collector improperly disclosing your debt from other, unrelated ways an employer might become aware of a financial matter — for example, if a wage garnishment order is legitimately issued following a court judgment, your employer will necessarily become aware of it as part of complying with that legal order, which is different from a collector informally telling your boss you owe money to pressure you.

    Similarly, some background checks (particularly for certain financial industry jobs or security clearance positions) may include a review of your credit history as part of legitimate employment screening, which is a separate process from debt collection contact and governed by its own specific rules under the Fair Credit Reporting Act, requiring your consent before such a check can be conducted.

    The Federal Trade Commission provides information about employment background checks and consumer rights under the FCRA. Learn more about employer background checks and your rights.

    Frequently Asked Questions

    Can a debt collector call my workplace’s general number if they don’t have my direct extension?

    Yes, this is generally permitted if they’re trying to reach you specifically (not disclose the debt to whoever answers), though once you inform them you can’t receive calls at work, they must stop, regardless of which specific number at your workplace they were previously using.

    Does the “no discussing the debt with third parties” rule apply to roommates who might answer my phone?

    Yes — if a roommate answers a call intended for you, the collector should limit the conversation to leaving a message asking you to call back or confirming they’ve reached the right number, not disclosing debt details to the roommate, similar to the restriction on other third parties.

    Can a collector send a letter to my workplace address if that’s the only address they have for me?

    This can happen if it’s genuinely your only known address, though the letter should not indicate on the envelope that it’s from a debt collector, and if you inform them not to send mail to your workplace, they should honor that request going forward, similar to the phone contact restriction.

    Is there a difference in these rules for a collection agency versus a debt buyer contacting third parties?

    No — these FDCPA restrictions apply to third-party debt collectors broadly, whether they’re a traditional collection agency or a debt buyer, since both are typically classified as “debt collectors” under the law’s definition when collecting debt owed to someone else (including debt they’ve purchased).

    The precise application of the FDCPA’s definition can depend on the collector’s role and circumstances. For background, see the CFPB’s explanation of what constitutes a debt collector.

    What if I actually want a family member to help me deal with a debt collector — can I authorize that?

    Yes — you can specifically authorize a collector to discuss your debt with a particular person (a family member helping you manage the situation, for example), which is different from a collector unilaterally disclosing the debt without your consent; this kind of authorization should ideally be provided in writing to create a clear record of your consent.

    A Sample Cease-and-Desist Letter for Improper Third-Party Contact

    If a collector has improperly contacted your employer or a family member, a written response documenting the violation is a strong first step:

    [Your Name]
    [Your Address]
    [Date]

    [Collector Name and Address]

    Re: Improper Third-Party Contact — Account [Reference Number, if known]

    To Whom It May Concern:

    I am writing to formally notify you that on [date], your company contacted [name/relationship of third party — e.g., “my employer” or “my sister”] and disclosed information regarding an alleged debt. This contact violated my rights under the Fair Debt Collection Practices Act, which permits contact with third parties solely for the purpose of obtaining location information, not for disclosing the existence or details of a debt.

    I am requesting that you cease any further contact with third parties regarding this matter, and that all future communication be directed to me directly, in writing, at the address above.

    Please be advised that I am documenting this violation and reserve the right to pursue further action if it continues.

    Sincerely,
    [Your Name]

    Send via certified mail with return receipt requested, and keep a copy along with your documentation of the original incident.

    For more information about written communication with collectors, see our cease-and-desist letter guide.

    Why This Protection Exists: The History Behind It

    Understanding the reasoning behind this specific rule helps clarify why it’s taken so seriously. Before the FDCPA was enacted in 1977, it was a documented, common practice among some collectors to deliberately embarrass debtors into paying by publicizing their debts to employers, neighbors, and family members — sometimes even posting notices in public places or contacting an employer specifically hoping the debtor would be fired or pressured by workplace embarrassment into paying faster.

    Congress specifically identified this kind of third-party shaming as an abusive practice warranting explicit legal prohibition, which is why the location-information exception is drawn so narrowly, and why violations of this specific provision are treated seriously under the law.

    The FTC provides historical and consumer-oriented information about the FDCPA and prohibited debt-collection practices. Review the text of the Fair Debt Collection Practices Act.

    What Legitimate Reasons Might Explain Workplace Contact That Feel Alarming But Aren’t Violations

    Not every collector contact involving your workplace is necessarily improper. A few scenarios worth distinguishing:

    • A collector calling your work number specifically to reach you (not disclosing anything to whoever answers) is permitted unless you’ve asked them to stop.
    • A formally issued wage garnishment order, following an actual court judgment, necessarily involves your employer as part of a legitimate legal process, different from informal collection pressure.
    • If you yourself provided your workplace as a contact method on an original credit application or account, a collector using that legitimately provided contact information to reach you (again, not to disclose debt details to a third party) isn’t itself a violation, even though it might still feel uncomfortable.

    Frequently Asked Questions, Continued

    If a collector calls my workplace and a coworker answers, is that automatically a violation?

    Not automatically — if the collector simply asks to speak with you or leaves a generic callback message without disclosing any information about a debt, this typically doesn’t violate the third-party disclosure rule; the violation specifically occurs if they disclose the nature or existence of the debt to that coworker.

    Can a debt collector show up at my workplace in person?

    This is less common than phone or written contact but isn’t explicitly prohibited by the FDCPA itself, though the same restrictions on disclosing debt information to third parties would still apply to any in-person contact at your workplace, and repeated or harassing in-person visits could potentially constitute harassment under the broader FDCPA provisions.

    Does this protection apply if the debt collector is actually my employer?

    This is a more complex, less common scenario — if your employer is also your original creditor (such as certain employer-sponsored loan programs), the dynamics are different since there’s no true “third party” disclosure issue in the same sense, though other consumer protections and your specific loan agreement’s terms would still likely apply.

    Is there a specific timeframe within which I should report a third-party contact violation?

    There’s no strict deadline for reporting to the CFPB or filing a complaint, though the FDCPA itself has a one-year statute of limitations for filing a private lawsuit based on a violation, so if you’re considering legal action specifically, acting within that window matters, even though administrative complaints can generally be filed at other times as well.

    Because legal deadlines can be important, consider consulting a consumer-law attorney promptly if you believe a violation occurred.

    How This Interacts With Co-Signers and Joint Account Holders

    It’s worth clarifying a related but distinct scenario: if someone is a co-signer or joint account holder on the specific debt in question, they’re not really a “third party” in the same sense — they’re independently, legally responsible for the debt themselves, meaning a collector can legitimately discuss the debt directly with them, since they’re a party to the obligation, not an outside person being contacted merely for location information.

    This is different from, say, a parent who didn’t co-sign anything but is being told about their adult child’s unrelated credit card debt, which would fall under the more restrictive third-party rules discussed throughout this guide.

    A Broader Perspective on Why Understanding This Matters Beyond the Legal Technicalities

    Beyond the legal protections themselves, understanding exactly what collectors can and cannot do regarding your employer and family tends to meaningfully reduce the anxiety that debt collection situations often produce.

    A significant portion of the fear people feel isn’t really about the debt itself — it’s about the imagined social consequences, the fear of a boss or a parent finding out and judging them.

    Knowing concretely that the law specifically and firmly restricts this kind of disclosure can help separate the legitimate financial matter (which does need to be addressed) from an exaggerated fear of public exposure that, in the vast majority of legitimate collection situations, simply isn’t a realistic risk given these protections.

    Frequently Asked Questions, Continued Further

    If I list a family member as an emergency contact on a credit application, does that give the collector permission to discuss my debt with them later?

    No — providing someone as an emergency contact is typically understood as being for location or contact purposes only, not as blanket authorization for a collector to discuss the substance of your debt with that person; the same restrictions on third-party disclosure would still apply.

    Can a collector contact my landlord instead of my employer for location information?

    Yes, a landlord could similarly be contacted solely for location-verification purposes under the same narrow exception, with the same restriction against disclosing details about the debt itself to the landlord.

    Does reporting a violation to the CFPB actually result in any consequence for the collector, or is it mostly symbolic?

    CFPB complaints require a company response and become part of the public complaint database, which can carry real reputational and, in aggregated patterns, regulatory consequences for repeat offenders — while a single complaint may not immediately halt improper behavior, it’s a legitimate, documented step that contributes to broader enforcement patterns and creates a record that can support further action if needed.

    File a complaint with the CFPB if you believe a covered debt collector has violated your rights.

    The Bottom Line

    Debt collectors are significantly more restricted in contacting your employer or family than most people assume — they can generally only reach out to third parties to obtain your location information, not to discuss the debt itself or pressure you through disclosure to people in your life.

    Calling your workplace to reach you directly is different and generally permitted unless you’ve asked them to stop, but disclosing your debt to your employer or family members without your consent is a clear violation of your rights.

    If this happens to you, documenting it and filing a complaint — with the CFPB, or through a consumer law attorney — is a legitimate and often effective response to a genuine violation of protections specifically designed to prevent exactly this kind of embarrassment and pressure.

    Related Credit & Debt Resources

    Need Help Reviewing Your Credit Situation?

    If you are dealing with collection accounts, inaccurate information, repeated collection contacts, or other credit-report problems, a review of your credit situation can help you understand what appears on your reports and what steps may be available.

    Request a Credit Audit

    Important: This article is for general educational purposes and is not legal advice. Federal and state laws can vary, and the FDCPA does not apply to every type of creditor or collection activity. If you believe a debt collector has violated your rights, consider consulting a qualified consumer-law attorney about your specific circumstances.

  • How Debt Gets Resold to Three Different Companies

    How Debt Gets Resold to Three Different Companies

    It’s one of the more disorienting experiences in dealing with debt: you get a collection letter from a company you’ve never heard of, and then, months later, a different company entirely contacts you about what appears to be the exact same debt. Neither is necessarily lying to you — this is actually a common, structurally built-in feature of how the debt collection industry operates. Understanding how and why debt gets resold, sometimes multiple times, clears up a lot of confusion and helps you respond correctly each time it happens.

    If you are dealing with multiple collection companies, it is also useful to understand how credit repair works and how collection accounts can affect your credit history.

    Why Debt Gets Sold in the First Place

    When you stop paying a credit card or similar unsecured debt, your original creditor eventually reaches a point (commonly around 180 days of nonpayment) where they’re required to “charge off” the account — an accounting move that classifies it as a loss rather than an asset they still expect to collect. At this point, the creditor has a few options: continue trying to collect internally, hire a third-party collection agency to work the account for a commission, or sell the debt outright to a debt buyer.

    Selling is often the most immediately attractive option from the creditor’s perspective — it converts an uncertain, resource-intensive collection process into an immediate (if heavily discounted) cash recovery, allowing the creditor to move on rather than continuing to dedicate staff and resources to chasing an account that’s already fairly deep into delinquency.

    If you want to understand what happens to an account after serious delinquency, see our guide to charge-offs versus collections.

    The Debt-Buying Marketplace

    Debt buyers purchase these charged-off accounts, typically in large bundled portfolios containing hundreds or thousands of individual accounts, for a price that’s a small fraction of the total original balance — often reported to range from a few cents to around twenty cents on the dollar, depending on the debt’s age, type, and how much supporting documentation accompanies the sale. Once purchased, the buyer becomes the new legal owner and attempts to collect, keeping whatever they recover.

    The fact that a debt buyer paid only a fraction of the original balance does not automatically mean that the consumer’s claimed balance is reduced by the same percentage. What the buyer paid for the account and what the consumer allegedly owes are separate questions.

    Why the Same Debt Can Change Hands Multiple Times

    Here’s where the “three different companies” scenario actually originates. A debt buyer who purchases a portfolio doesn’t necessarily succeed in collecting every account within it — some accounts turn out to be harder to collect than the buyer initially projected, whether due to the debtor being genuinely unable to pay, the debt being harder to verify or document than expected, or simply the debtor being difficult to locate or reach.

    Rather than continuing to invest resources indefinitely into accounts that aren’t producing results, many debt buyers periodically resell their less successful accounts to yet another debt buyer, at an even steeper discount than they themselves originally paid, essentially cutting their losses on that specific account while still recovering some value from the original bulk purchase.

    This second buyer might have more success (sometimes simply because a different, later collection attempt happens to land at a moment when the debtor is more able or willing to resolve it), or they too might eventually resell the account to a third buyer if their own efforts also fail.

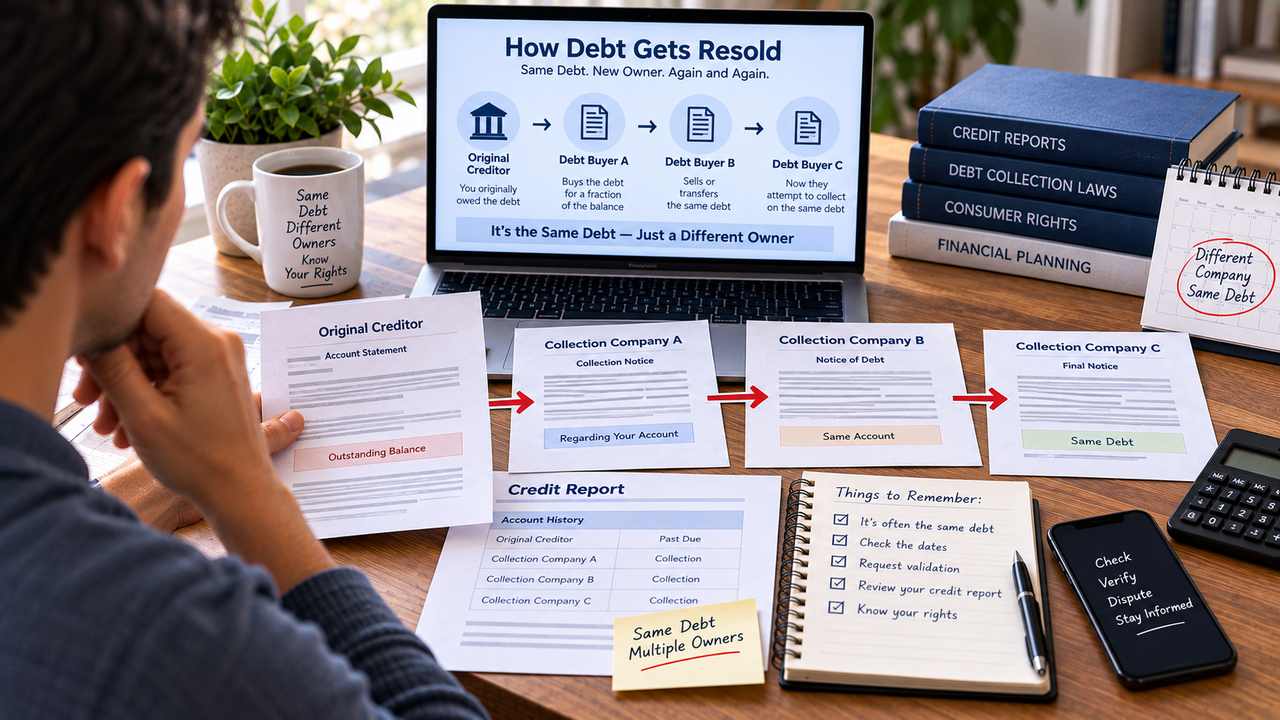
    This is exactly how a single, original debt can pass through the hands of multiple different companies over time — each one representing a different stage of this resale chain, not separate, unrelated debts you actually owe multiple times over.

    What This Means for You Practically

    You only owe the debt once, to whoever currently, legitimately owns it. Even though multiple companies might contact you about what was originally the same debt, at any given point in time only the current legal owner has the right to actually collect it — a previous owner who’s already resold the account no longer has any legitimate claim.

    Each new owner should be able to validate their current ownership if you request it.

    Since ownership is what actually matters, not the debt’s history of prior owners, the current company contacting you should be able to demonstrate — if you formally request debt validation — that they legitimately purchased and now own the account.

    Federal rules generally require debt collectors to provide validation information about the debt, including information that helps a consumer identify the creditor and amount claimed. The CFPB explains that consumers generally have a 30-day validation period for disputing a debt after receiving the required validation information. Learn more about debt validation requirements from the CFPB.

    You should never end up paying more than one company for the same debt. If you’ve already resolved the debt with a previous owner (through payment or a settlement), and a subsequent “owner” contacts you claiming you still owe it, this is exactly the kind of situation where your own documentation of the prior resolution becomes critical, since it’s your strongest evidence that the current claim is invalid.

    If a collection account appears inaccurate, you can also review our guide on how to dispute credit report errors.

    How to Tell If a New Contact Represents a Genuinely Different Debt, or a Resold Version of One You Already Know About

    Compare the Original Creditor Listed

    Formal debt validation should specify the name of the original creditor the debt traces back to — if two different collection contacts, months or years apart, both point back to the same original creditor and roughly the same account details (approximate original balance, approximate account opening date), this strongly suggests it’s the same underlying debt, now with a new current owner.

    The CFPB notes that validation information can include the name of the creditor, account information, the current amount of the debt, and information explaining how to dispute the debt. Review the CFPB’s explanation of required validation information.

    Compare the Claimed Balance

    Compare the claimed balance, accounting for any legitimately accrued interest or fees.

    While the exact figure might shift somewhat between different collection attempts (due to permitted interest accrual, or different rounding or fee calculations), a wildly different balance for what’s supposedly the same original account is worth specifically questioning.

    Ask Directly

    Ask directly. A simple, direct question to the new company — “Is this the same debt originally owed to [original creditor], previously being collected by [prior company you dealt with]?” — is a reasonable, direct way to clarify the situation, and a legitimate company should be able to answer this based on their own account records.

    For a more formal approach, see our guide to debt validation letters.

    Why This System Can Create Documentation Problems (That Work in Your Favor)

    Every time a debt is resold, there’s an opportunity for record-keeping to become less complete or accurate than the original account documentation was. A debt that’s been resold two or three times may have a current owner whose actual proof of the account’s history, the original agreement terms, and the accurate current balance is less robust than what the original creditor would have had readily available.

    This is exactly why formal debt validation becomes increasingly valuable and increasingly likely to reveal genuine gaps the more times a specific debt has changed hands — if a current owner genuinely can’t produce adequate documentation connecting the debt back to you and confirming their own legitimate ownership, this is a real, potentially successful basis for disputing their claim, separate from any question of whether the debt was ever legitimately owed to the original creditor in the first place.

    Federal debt-collection rules provide consumers with specific validation and dispute rights. The CFPB’s current Regulation F explains the federal requirements for validation notices. See the CFPB’s current Regulation F validation rule.

    What to Do Each Time a “New” Company Contacts You About What Might Be an Old Debt

    Request Formal Debt Validation

    Request formal debt validation every time, even if you’ve already gone through this process with a previous owner of what appears to be the same debt. Each new owner needs to independently establish their own legitimate claim; your prior dealings with a previous owner don’t automatically transfer or bind the new one.

    For practical guidance on challenging collection accounts, you can also review how to file a credit dispute.

    Check Whether You Already Resolved the Debt

    Check whether you already resolved this specific debt with a previous owner. If you have documentation showing you already paid or settled with a prior company for this same original account, this is your strongest and most direct response — providing this documentation to the new company (and disputing the claim if they continue pursuing it despite this evidence) rather than starting the negotiation process over as if it were a fresh, unresolved debt.

    The CFPB specifically provides guidance for consumers contacted about debts they believe they already paid or do not owe. See the CFPB guidance on already-paid or disputed debts.

    Check Your State’s Statute of Limitations

    Check your state’s statute of limitations, since the resale itself doesn’t reset this clock.

    A common misconception is that a new owner means a “fresh start” on the legal timeline — it doesn’t. The statute of limitations is tied to the original delinquency date, regardless of how many times the debt has subsequently been resold.

    However, statute-of-limitations rules can vary by state and by the circumstances of the debt. Our guide to the statute of limitations on debt provides additional context.

    Keep Thorough Records

    Keep thorough records of every interaction, regardless of which specific company is currently involved. Given how confusing multiple resales can become, maintaining your own organized file — dates, company names, amounts claimed, any payments or agreements — protects you regardless of how many additional companies might eventually become involved with this same underlying debt.

    Frequently Asked Questions

    If I paid off a debt with the first company that contacted me, why would a second company later claim I still owe it?

    This can happen due to a records error (the payment wasn’t properly recorded or communicated during a subsequent resale), or, less commonly, through improper or fraudulent conduct by a subsequent buyer. Either way, your own payment documentation is critical evidence in disputing this kind of claim.

    Does the debt’s dollar amount typically increase or decrease as it gets resold multiple times?

    The amount a buyer paid to acquire it typically decreases with each resale (since previously unsuccessful accounts sell for less), but the amount they claim you owe generally doesn’t decrease correspondingly — you’d still generally be pursued for something close to the full remaining balance (potentially plus additional accrued interest, depending on what’s legally permitted), regardless of how cheaply the current owner acquired the account.

    Can I ask a company how many times my specific debt has been resold?

    You can ask, though they may not have complete visibility into the debt’s full ownership history before they themselves acquired it, and they’re not generally obligated to volunteer this information even if they do have it — formal debt validation, focused on establishing their own current legitimate ownership, is generally a more productive request than asking for a complete historical accounting of every prior owner.

    Is there a limit to how many times a single debt can be resold?

    There’s no specific legal limit on the number of times a debt can be resold, though practically, debt tends to become less valuable and less frequently resold as it ages and accumulates a longer history of unsuccessful collection attempts by multiple prior owners, eventually reaching a point where it’s simply written off entirely rather than resold again.

    If a debt is resold after I’ve already disputed it successfully with a previous owner, does the new owner need to honor that prior successful dispute?

    This is a nuanced situation worth discussing with a consumer law attorney if it arises — in principle, if you successfully demonstrated the debt was inaccurate or unverifiable with a previous owner, this is strong evidence a new owner would also need to grapple with, though the new owner isn’t automatically bound by an agreement or resolution reached with an entirely different, prior company simply because the debt is the same.

    A Visual Walkthrough of a Typical Resale Chain

    To make this concrete, here’s how a single credit card debt might realistically travel through several owners over a period of years:

    Time What Happens
    Year 1 You stop paying a credit card with a $2,500 balance. After 180 days, the original bank charges it off and sells it, bundled with thousands of other accounts, to Debt Buyer A for roughly 10 cents on the dollar.
    Year 1–2 Debt Buyer A attempts collection — calls, letters, maybe a settlement offer — without success, whether because you were unreachable, unable to pay, or disputed the debt without full resolution.
    Year 2 Debt Buyer A resells the account, along with other unsuccessful accounts from that original portfolio, to Debt Buyer B, this time for perhaps 3–4 cents on the dollar, reflecting the lower expected recovery odds for an account that’s already proven difficult to collect once.
    Year 3 Debt Buyer B has similarly limited success and resells the account to Debt Buyer C for an even smaller amount.
    Year 3–4 Debt Buyer C contacts you — this is potentially the third different company name you’ve seen associated with what is, underneath it all, the exact same original $2,500 credit card debt from Year 1.

    Throughout this entire chain, your actual legal obligation never multiplied — you owed $2,500 (plus any permitted interest) at the start, and you still owe that same underlying amount to whichever company currently, legitimately holds it, not three separate $2,500 debts to three separate companies.

    How This Pattern Connects to the “Zombie Debt” Phenomenon

    This resale pattern is directly related to zombie debt, covered in more detail elsewhere — very old debt that resurfaces years later often does so precisely because it’s completed one or more rounds of this resale cycle, eventually landing with a buyer willing to make a fresh attempt long after the debt first went unpaid.

    Understanding the resale mechanism explains why zombie debt exists at all: it’s not that anyone deliberately waited years to contact you: it’s that the debt spent that time moving through this ownership chain, with gaps of inactivity between different owners’ respective collection attempts.

    If you are dealing with older debt, it is especially important to review the statute of limitations on debt before making decisions.

    Frequently Asked Questions, Continued

    Does each new owner in the resale chain have to notify me directly when they acquire my debt, before attempting collection?

    There’s no strict, universal requirement for proactive notification immediately upon purchase in every circumstance, though you’re generally entitled to validation information, including confirmation of current ownership, once they begin attempting to actually collect and you request it.

    Federal rules require debt collectors to provide validation information in connection with collection communications. The exact requirements can depend on the circumstances, so consumers should review the notice they receive and the applicable rules. See Regulation F from the CFPB.

    If I successfully negotiate a “pay for delete” with one owner in the chain, but the debt gets resold before I complete payment, is that agreement still valid?

    This depends on the specific terms and timing — if you have a written agreement and haven’t yet fulfilled the payment, a subsequent sale could complicate enforcement of that specific agreement with the new owner, which is exactly why completing any negotiated agreement promptly, rather than delaying, is generally advisable once terms are reached.

    Learn more about the concept in our guide to pay-for-delete agreements.

    Can I proactively find out if my debt has been resold before a new company contacts me?

    Not directly in most cases — there’s no consumer-facing registry tracking individual debt resales, so you’d typically only become aware of a resale when the new owner actually initiates contact or, in some cases, when your credit report updates to reflect a new company’s name associated with the debt.

    Does the interest rate or terms change when a debt is resold to a new owner?

    Generally, the new owner is bound by the same underlying terms and legal limits that applied to the original debt agreement (or whatever’s legally permitted under your state’s law), rather than being able to impose entirely new, different terms simply because they’ve acquired the account — though it’s still worth verifying the specific accrued amount claimed through the validation process, since errors and improper additional fees do sometimes occur through this resale process.

    Why Debt Buyers Are Willing to Purchase Accounts That Have Already Failed Once or Twice

    It might seem strange that anyone would want to purchase a debt that one or even two previous professional collection companies already tried and failed to collect. The economics make more sense once you understand the pricing involved: since each subsequent resale happens at a progressively steeper discount, a third or fourth buyer might pay only a tiny fraction of a cent per dollar of face value, meaning even a very low success rate — collecting from just a small percentage of a large bulk portfolio of previously-unsuccessful accounts — can still be profitable.

    Some companies specifically specialize in this later-stage, deeply discounted segment of the market, sometimes using different collection strategies (a different tone, a different settlement offer structure, sometimes simply better timing relative to your current financial situation) than earlier attempts used, on the theory that a different approach or a different moment might succeed where prior attempts didn’t.

    What This Means for Your Long-Term Financial Record-Keeping

    Given how often this resale pattern occurs, it’s worth building a habit of keeping documentation for any debt you resolve — payment confirmations, settlement agreements, written correspondence — for considerably longer than might feel intuitively necessary.

    A debt you settled five or even ten years ago could theoretically resurface through this resale chain, and having your own records readily available to prove the resolution is far more useful than trying to reconstruct that history from memory or from a company that may no longer exist or be reachable by the time a dispute arises.

    Frequently Asked Questions, Continued Further

    Is there a way to tell from a collection letter alone how many times a debt has already been resold?

    Not always directly, though sometimes a letter’s language (“we recently acquired your account”) or an unusually low-sounding settlement offer relative to the claimed balance can be an informal signal that you’re dealing with a later-stage buyer in a longer resale chain, though formal validation remains the more reliable way to understand the debt’s actual history and current status.

    Does a debt lose any of its original terms or protections as it moves through multiple owners?

    Your underlying legal protections (FDCPA rights, your state’s statute of limitations, the standard credit reporting rules) remain constant regardless of how many times the debt has been resold — what can become less reliable through repeated resale is the completeness of the documentation supporting the debt’s specific details, not your fundamental consumer protections themselves.

    The Federal Trade Commission explains that the FDCPA prohibits covered debt collectors from using deceptive, unfair, or abusive practices when collecting consumer debts. Review the FTC’s debt collection guidance.

    The Bottom Line

    Debt gets resold because it’s often financially efficient for both original creditors and debt buyers who’ve had limited success — rather than pursuing a difficult account indefinitely, selling it (even at a steep additional discount) recovers some value while passing the ongoing collection effort to a new owner.

    If you’re contacted by multiple different companies over time about what appears to be the same original debt, this resale pattern is very likely the explanation, not a sign that you somehow owe the debt multiple times over.

    The practical response remains consistent regardless of how many times the debt has changed hands: request formal validation from whoever is currently contacting you, verify their claim against your own records and any prior resolution documentation, and never pay more than once for the same underlying obligation.

    Related Credit & Debt Resources

    Need Help Reviewing Your Credit Report?

    If you are dealing with collection accounts, duplicate accounts, inaccurate information, or debts that appear to have changed ownership multiple times, reviewing the information on your credit reports can help you identify potential inconsistencies.

    Get in touch with our team to learn more about your credit situation.

    Request a Credit Audit

    Important: This article provides general educational information about debt collection and credit reporting. Laws and procedures can vary by state and by the circumstances of a particular debt. It is not legal advice. If you are facing a lawsuit, judgment, or a complex dispute over debt ownership, consider consulting a qualified consumer-law attorney in your state.

  • What Happens If You Ignore a Debt Collection Lawsuit

    What Happens If You Ignore a Debt Collection Lawsuit

    Of all the mistakes people make when facing a debt collection lawsuit, ignoring it entirely is by far the most costly, and it’s also, understandably, one of the most common. Legal paperwork is intimidating, the language is unfamiliar, and it’s tempting to hope the whole thing simply goes away if left unaddressed. It won’t. This guide walks through exactly what happens, step by step, when a debt collection lawsuit is ignored, and why understanding these consequences in advance is one of the most motivating reasons to respond instead.

    The Consumer Financial Protection Bureau’s guidance on debt collection lawsuits recommends responding to a lawsuit by the deadline specified in the court papers. The exact deadline and procedure depend on the court and applicable state law.

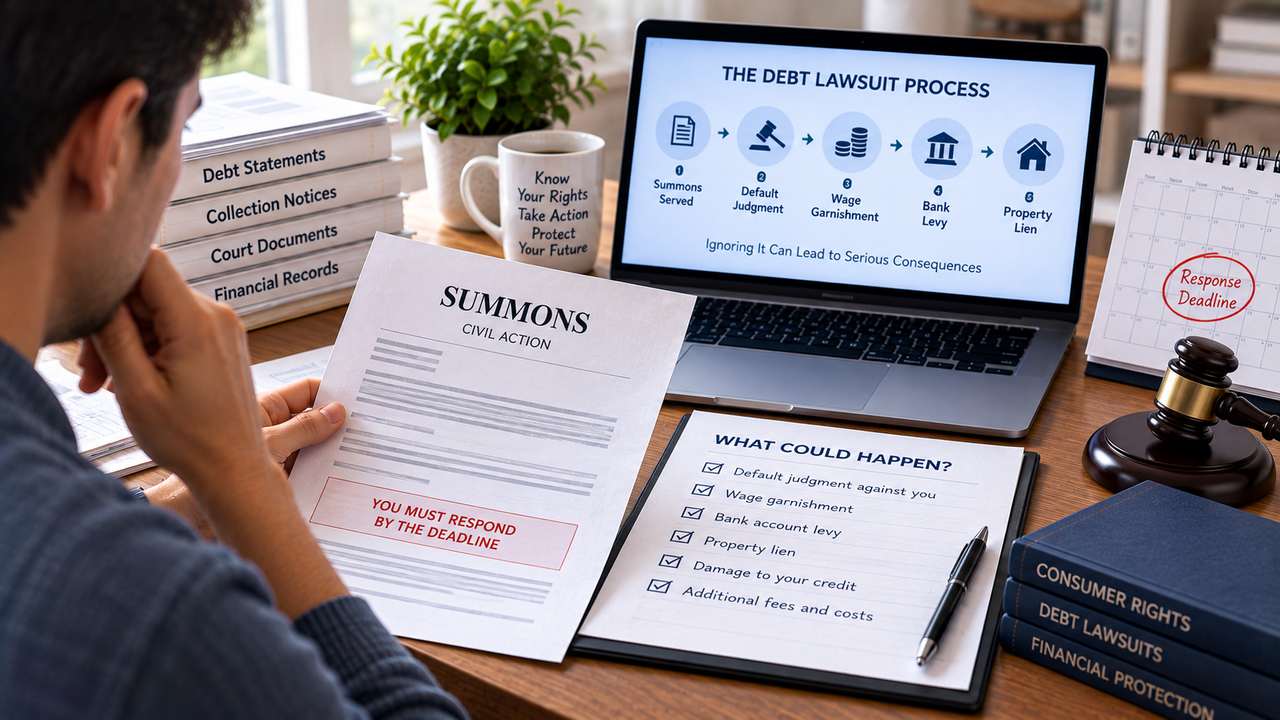
    Step One: The Default Judgment

    If you don’t file a formal response (typically called an “Answer”) by the deadline specified in your court papers — commonly somewhere between 14 and 30 days from when you were served, depending on your state and court — the plaintiff (the debt collector or their attorney) can request that the court enter a default judgment against you. This means the court rules in the collector’s favor automatically, without you ever presenting any defense, evidence, or argument on your own behalf, simply because you didn’t show up or respond in the required timeframe.

    The exact response deadline is not universal. Read the summons and complaint carefully and follow the deadline stated by the court. In federal civil cases, for example, the general answer period can be 21 days after service, subject to exceptions and different rules.

    This is true even if you had a completely valid defense available — an expired statute of limitations, inadequate documentation proving the debt is actually yours, or evidence you already paid it off. None of that matters if you never formally raise it, because the court has no way of knowing these defenses exist if you don’t present them.

    The CFPB similarly explains that responding does not necessarily mean you agree that you owe the debt. Responding gives you an opportunity to require the collector to establish its claim and preserve potential defenses.

    If you are dealing with a collection account before it reaches the lawsuit stage, our guide on how to file a credit dispute may also help you understand the difference between a credit-report dispute and a court case.

    What a Default Judgment Actually Means for You

    Once a default judgment is entered, the collector has a formal, legally enforceable court order confirming you owe the debt (plus, often, court costs and sometimes attorney’s fees, depending on your state and the original credit agreement’s terms). This judgment gives them access to legal collection tools they didn’t have before filing the lawsuit:

    Wage Garnishment

    In most states, once a judgment is entered, the creditor can request a wage garnishment order, requiring your employer to withhold a portion of your paycheck (subject to federal and state limits on the maximum percentage) and send it directly to satisfy the judgment.

    Garnishment rules and exemptions vary significantly. The CFPB’s guidance on wage and benefit garnishment explains that state and federal protections may apply to different types of income.

    Bank Account Levies

    A judgment can allow the creditor to freeze and seize funds directly from your bank account, though certain types of funds — Social Security income, in many states, and sometimes other specific protected categories — are generally exempt from this kind of seizure.

    The specific exemptions depend on federal and state law. If you believe protected funds have been frozen or taken, prompt legal advice may be important.

    Property Liens

    If you own real estate, a judgment can result in a lien being placed against the property, which typically must be resolved (paid off) before you can sell or refinance that property in the future.

    Continued Interest Accrual

    Many judgments continue accruing interest at a legally set rate until fully paid, meaning the total amount owed can continue growing over time even after the judgment is entered, sometimes substantially, especially for a judgment that remains unpaid for years.

    The CFPB explains that judgments can include the amount claimed plus lawful additional costs, interest, and attorney fees where applicable.

    The Judgment Doesn’t Just Disappear Over Time

    Unlike credit report entries, which follow the standard seven-year reporting rule, a court judgment can remain legally enforceable for a much longer period, and in many states, creditors can formally renew a judgment before it expires, extending its enforceability for additional years, sometimes indefinitely through repeated renewals. This means an ignored lawsuit and resulting default judgment isn’t a problem that simply resolves itself with the passage of time the way some other financial issues eventually do — it can remain a live, growing, actively enforceable obligation for a very long time if left unaddressed.

    The exact duration of a judgment and whether it can be renewed are matters of state law. Do not assume that a judgment will automatically disappear after a particular number of years.

    This is also different from the federal credit-reporting rules. The CFPB explains the federal time limits that generally apply to negative information on consumer credit reports, which are separate from the legal enforceability of a court judgment.

    How This Affects Your Credit and Broader Financial Life

    While federal civil judgments were removed from standard credit reports several years ago as part of an industry-wide policy change, the practical downstream effects of an unresolved judgment — wage garnishment showing up in your pay records, a bank levy disrupting your finances, a property lien complicating a future home sale — can still create significant, visible financial disruption even though the judgment itself may not appear as a distinct line item on your credit report the way it once did. Additionally, the underlying debt that led to the lawsuit likely already appears (or previously appeared) on your credit report as a collection or charge-off, separate from the judgment itself, continuing to affect your score through that more standard reporting mechanism.

    If you want to understand what is currently being reported, you can obtain your credit reports through AnnualCreditReport.com, the official federally authorized source for free credit reports.

    Our guide on how to read a credit report can help you understand the different sections and account information you may see.

    Can a Default Judgment Be Undone?

    In some circumstances, yes, though it’s a considerably harder and more uncertain process than simply responding to the original lawsuit on time would have been. Courts can sometimes vacate (undo) a default judgment if you can demonstrate a valid legal reason — commonly, that you were never properly served with the lawsuit in the first place, or that you had a legitimate, excusable reason for missing the response deadline (a serious illness, for example) combined with a genuine defense you would have raised had you responded in time.

    This process typically requires filing a specific motion with the court, often within a limited timeframe after learning of the default judgment, and successfully arguing your case for why the judgment should be set aside — which is considerably more complex and uncertain than simply filing a timely Answer would have been from the start. If you discover a default judgment has already been entered against you, consulting a consumer law attorney promptly about whether vacating it is a realistic option for your specific situation is worth pursuing, though the earlier you act after discovering the judgment, the better your chances typically are.

    Federal Rule 60 provides procedures for seeking relief from certain federal-court judgments, but state courts have their own rules and deadlines. For that reason, the U.S. Courts rules and procedures resources are useful for understanding federal cases, while state-specific cases should be reviewed under the applicable state rules.

    Why People Ignore Lawsuits, and Why It’s Almost Always the Wrong Choice

    • Fear and avoidance. Legal paperwork is intimidating, and avoidance is a natural, if ultimately counterproductive, emotional response to something frightening and unfamiliar.
    • Belief the debt isn’t legitimate, and therefore doesn’t need a response. Ironically, if you genuinely believe the debt is inaccurate, too old, or improperly pursued, responding is even more important, since these are exactly the kinds of defenses that get automatically forfeited by not responding — ignoring a lawsuit over an illegitimate debt doesn’t win you anything; it guarantees you lose by default regardless of how valid your underlying objection might have been.
    • Assuming there’s no point since you can’t afford to pay anyway. Even if you ultimately can’t pay the full amount, responding preserves your ability to potentially negotiate a more favorable settlement or structured payment arrangement, and to ensure the judgment amount (if one is ultimately entered) is accurate rather than inflated by unchallenged claims.
    • Not understanding what’s actually at risk. Many people simply don’t realize how serious the consequences of a default judgment can be until it’s already happened, which is exactly why understanding this process in advance — before you’re facing an actual deadline under stress — is so valuable.

    The CFPB specifically notes that responding to a lawsuit can preserve the opportunity to challenge the debt or amount claimed and may allow settlement discussions before a judgment is entered.

    What Responding Actually Requires

    Responding doesn’t necessarily require hiring an expensive attorney, though consulting one is worthwhile if accessible to you. Many courts provide simplified, fillable Answer forms specifically designed for debt collection cases, and various legal aid organizations and court self-help centers offer free guidance for exactly this situation. At minimum, responding requires: reading your court papers carefully to identify your specific deadline, filling out and filing whatever response form your specific court requires (addressing each claim made against you and raising any defenses that apply), and following your court’s specific filing process (which may include a fee, though fee waivers are often available based on income).

    The LawHelp legal-aid directory can help consumers locate legal assistance and legal-aid resources in their state. Availability and eligibility vary.

    What Happens After You Respond

    Once you’ve filed a timely Answer, the case moves into further stages rather than an automatic default. This typically includes a discovery phase (where you can request the plaintiff produce documentation supporting their claim), potential settlement discussions (many cases resolve this way, without ever reaching trial), and, in a minority of cases, an actual trial where both sides present their case. Throughout this process, you retain the ability to negotiate a settlement, challenge inadequate documentation, or raise legitimate defenses — none of which remain available once a default judgment has already been entered.

    If you’re considering settlement, our guide on negotiating with creditors when you’re genuinely struggling provides general information about creditor negotiations.

    Remember that negotiating with the collector does not necessarily replace the requirement to file a formal court response by the deadline. The CFPB recommends responding to the lawsuit according to the court’s requirements even if you are also discussing settlement.

    Frequently Asked Questions

    If I can’t afford the court filing fee to respond, does that mean I have no choice but to let the case default?

    No — many courts offer fee waivers for those who qualify based on income, and it’s worth specifically asking the court clerk about this option rather than assuming the fee is an absolute barrier to responding.

    Does ignoring a lawsuit affect anyone else, like a spouse or family member?

    If the debt was solely yours, generally only your own finances and credit are directly affected, though in community property states, a spouse’s assets or income could potentially be implicated depending on specific state law and the nature of the debt — this is worth clarifying with an attorney if you’re in a community property state and concerned about this specific issue.

    How Would I Know If a Default Judgment Has Been Entered?

    You may receive formal notice of the judgment itself, separate from the original lawsuit papers, or you might first become aware of it when a garnishment or levy actually begins affecting your paycheck or bank account — periodically checking your state’s online court records system (many states now offer this) for your name is one proactive way to check whether any judgments exist against you, particularly if you’re unsure whether a prior lawsuit you may have missed resulted in one.

    Do not rely solely on your credit report to determine whether a judgment exists. Court records and credit reports serve different purposes.

    Is it too late to negotiate a settlement once a default judgment has already been entered?

    Not necessarily too late, though your negotiating position is considerably weaker than it would have been before the judgment, since the collector has already secured their legal win and the tools that come with it. Some creditors remain willing to negotiate a payoff even post-judgment, particularly if they recognize collection through garnishment or levy might be slow or difficult, but you’re negotiating from a position of less leverage than you’d have had earlier in the process.

    Can I still be sued again for the same debt if the case is dismissed due to my failure to appear at a required hearing, separate from the initial Answer deadline?

    This depends on how exactly the dismissal is characterized by the court (with or without prejudice) and the specific circumstances — missing a later required hearing, even after initially filing an Answer, can also lead to negative consequences, which is why staying engaged with the case throughout its entire duration, not just at the initial response stage, matters if you choose to contest a lawsuit.

    A Timeline of What Actually Unfolds After You Ignore a Lawsuit

    Days 1-30 (varies by state): The response window

    After being served, this is your window to file an Answer. If it passes with no response, the plaintiff becomes eligible to request a default judgment.

    Following the Missed Deadline: The Default Judgment Motion

    The plaintiff’s attorney files a motion or request asking the court to enter judgment in their favor by default, typically a relatively quick, administrative process since there’s no opposition to consider.

    Judgment Entry

    Once the court grants the default judgment, it becomes an official court order, generally including the original debt amount plus any court costs and, depending on the original agreement and state law, sometimes attorney’s fees and additional interest.

    Post-Judgment Collection Actions

    The creditor generally must take additional legal steps to actually enforce the judgment — filing for a wage garnishment order, requesting a bank levy, or recording a property lien — each of which typically involves its own separate legal process and paperwork, meaning there’s often some additional time (weeks to months) between the judgment being entered and actual collection action beginning, though this varies by state and the specific creditor’s approach.

    Ongoing Enforcement and Potential Renewal

    If the judgment isn’t satisfied, the creditor can continue pursuing collection through these tools for an extended period, and depending on your state, can formally renew the judgment before its enforceability period expires, extending their ability to collect for additional years.

    Why Some People Mistakenly Believe Ignoring It Is a Viable Strategy

    A few misconceptions specifically fuel this mistake. Some people assume that since they have no significant assets or garnishable wages right now, a judgment against them is essentially meaningless — but financial circumstances change, and a judgment doesn’t expire simply because you’re currently judgment-proof; it can sit dormant, waiting to be enforced later if your situation improves, or be renewed to remain enforceable indefinitely. Others assume that because the underlying debt itself feels illegitimate or unfair, a court will somehow recognize this even without them formally raising it — but courts generally rule based on what’s actually presented and argued, not on an independent investigation into fairness; your defense, however valid, needs to actually be raised to matter.

    The CFPB likewise warns that ignoring a lawsuit can result in a judgment even when you believe you do not owe the debt.

    Frequently Asked Questions, Continued

    If I move to a different state after a default judgment is entered against me, does the judgment follow me?

    Generally, yes — a valid judgment doesn’t simply disappear because you’ve moved, though the creditor may need to take additional legal steps (sometimes called “domesticating” the judgment) to enforce it in your new state specifically, which adds some complexity but doesn’t eliminate their underlying right to pursue collection.

    Does a default judgment show a different amount than what was originally claimed in the lawsuit?

    It can, since courts sometimes add court costs, and depending on the terms of your original agreement and state law, potentially additional interest or attorney’s fees beyond the base amount originally claimed — meaning the total judgment amount is sometimes higher than what you initially saw referenced in the lawsuit paperwork itself.

    Is there a difference between a default judgment and a judgment entered after I actually participated but lost the case?

    Practically, once entered, both types of judgments generally carry the same enforcement tools (garnishment, levy, lien) — the meaningful difference is in how they can potentially be challenged afterward, since a default judgment (where you never had a chance to present your case) is sometimes easier to argue should be vacated than a judgment entered after a full, contested proceeding where you did participate but simply didn’t prevail.

    The Real Cost Comparison: Responding vs. Ignoring

    Responding to the Lawsuit Ignoring It
    Time investment: Filing an Answer, possibly attending hearings Time investment: Minimal upfront, but potentially years of consequences later
    Cost: Possible filing fee (often waivable), possible attorney consultation Cost: No immediate cost, but judgment amount plus accruing interest over time
    Ability to negotiate: Strong — collector faces litigation uncertainty Ability to negotiate: Weak — collector has already won
    Defenses available: All applicable defenses can be raised Defenses available: All forfeited automatically
    Long-term risk: Resolved through settlement, judgment, or dismissal Long-term risk: Judgment can persist and be renewed for years

    This comparison makes clear why, even accounting for the very real time and stress involved in responding to a lawsuit, ignoring it is rarely the lower-cost option once the full picture — including years of potential judgment enforcement and renewal — is taken into account.

    Frequently Asked Questions, Continued Further

    If the debt collector’s lawyer contacts me directly after I’ve been served, should I respond to them or only to the court?

    Both matter, but they serve different purposes — responding formally to the court (filing your Answer by the deadline) is the legally required action that prevents default, while any direct communication with the plaintiff’s attorney is a separate, optional channel for settlement discussions that doesn’t substitute for your formal court filing.

    Can a default judgment affect my ability to rent an apartment or get a job later, beyond the credit and financial impacts already discussed?

    Court records, including judgments, are often part of the public record and can sometimes appear in background checks used by landlords or employers, depending on the specific screening service and what it searches, adding another potential downstream consequence beyond the direct financial enforcement tools already covered.

    If I successfully get a default judgment vacated, does that mean the lawsuit is dismissed entirely?

    Not automatically — vacating a default judgment typically reopens the case to the point before the judgment was entered, meaning you’d then need to actually respond and defend the case going forward, rather than the lawsuit being entirely dismissed as a result of successfully vacating the earlier default.

    Related Debt & Credit Resources

    If you are facing a lawsuit over an old debt, the CFPB’s debt collection resources provide additional information about debt validation, collection practices, judgments, and consumer rights.

    The Bottom Line

    Ignoring a debt collection lawsuit doesn’t make it go away — it can result in a default judgment against you, potentially without any opportunity to present a defense you might have genuinely had. That judgment can then open the door to wage garnishment, bank levies, and property liens, and can remain legally enforceable and renewable for years, continuing to accrue interest the entire time. Whatever your specific circumstances or beliefs about the debt’s validity, responding to the lawsuit by your deadline — even if you ultimately can’t fully resolve the underlying debt — preserves your legal options rather than forfeiting them through inaction.

    The CFPB’s guidance is straightforward: if you are sued by a debt collector or creditor, respond by the date specified in the court papers, either personally or through an attorney.

    Need Help Understanding Your Credit Situation?

    If a debt collection lawsuit has also resulted in collection accounts, inaccurate information, or other credit-report concerns, reviewing your credit reports can help you understand what is currently being reported.

    Request a Credit Audit to discuss your credit situation and potential next steps.

  • Building Back Up From Financial Rock Bottom: A Realistic Timeline

    Building Back Up From Financial Rock Bottom: A Realistic Timeline

    Financial rock bottom looks different for everyone — a bankruptcy, a foreclosure, maxed-out debt with no clear path forward, or simply reaching a point where every month feels like triage.

    Wherever the specific starting point, the process of rebuilding follows a reasonably predictable arc, even though the exact pace varies by individual circumstances. This guide lays out a realistic timeline, phase by phase, so you know roughly what to expect and can measure your own progress against a genuine framework rather than either unrealistic optimism or unwarranted despair.

    Phase One: Stabilization (Roughly the First 1-3 Months)

    The immediate priority after hitting rock bottom isn’t rebuilding — it’s stopping the bleeding and establishing a baseline of stability. This phase typically involves:

    • Getting a complete, honest picture of your situation — every debt, every account, your actual income, and your actual essential expenses, without avoidance or minimization.
    • Addressing any acute crises first — an eviction risk, a utility shutoff notice, a wage garnishment already in progress — since these time-sensitive issues need immediate attention before longer-term planning becomes productive.
    • Establishing basic stability in housing, income, and essential needs, even if imperfect, since you can’t effectively rebuild from a state of ongoing acute crisis.
    • Deciding on your major strategic path, if applicable — bankruptcy, debt settlement, a debt management plan, or simply an aggressive but conventional payoff plan — since this decision shapes much of what follows.

    One practical first step is reviewing your current credit reports so you know exactly which accounts and negative items are being reported. AnnualCreditReport.com is the federally authorized source for obtaining your credit reports from Equifax, Experian, and TransUnion.

    You can also learn more about how to read a credit report so you can identify accounts, balances, payment history, collections, and other information that may require attention.

    Phase Two: Structural Resolution (Roughly Months 3-12)

    Once immediate stabilization is achieved, this phase focuses on actually resolving the structural issues that led to or resulted from rock bottom:

    • If pursuing bankruptcy, this phase often includes the actual filing process and, for Chapter 7, typically concludes with discharge within this window; for Chapter 13, this phase marks the beginning of a longer repayment plan period.
    • If pursuing debt settlement, this phase involves the actual negotiation and resolution of individual debts, which can take several months to over a year depending on how many debts are involved and how negotiations unfold.
    • If pursuing a debt management plan, this phase involves establishing and beginning the structured repayment plan through your credit counseling agency.
    • Regardless of path, this phase typically includes beginning to rebuild a minimal emergency fund (even just $500-1,000 as an initial buffer), establishing or re-establishing a working budget, and addressing any remaining acute issues (health insurance gaps, essential but deferred expenses) that stabilization alone didn’t fully resolve.

    If bankruptcy is part of the situation, the U.S. Courts bankruptcy resources explain the federal bankruptcy process and the different bankruptcy chapters available to individuals. Bankruptcy can have significant legal and financial consequences, so professional legal advice may be appropriate for someone considering filing.

    If you are negotiating with creditors because of financial hardship, our guide on how to negotiate with creditors when you’re genuinely struggling covers hardship requests, payment accommodations, documentation, and creditor conversations.

    The Consumer Financial Protection Bureau’s credit counseling guidance also explains how credit counseling organizations can help with budgeting, debt management plans, and money-management issues.

    Phase Three: Foundation Building (Roughly Year 1-2)

    With the acute crisis resolved and major structural decisions implemented, this phase focuses on building a genuine financial foundation:

    • Credit rebuilding begins in earnest — secured credit cards, credit-builder loans, and consistent on-time payment on any remaining obligations, working toward a genuinely improved credit score, which most people see meaningful progress on within this timeframe.
    • Emergency fund growth continues, working toward a more substantial cushion (commonly one to three months of essential expenses as an interim goal, before eventually working toward the more standard three-to-six-month recommendation).
    • Sustainable budgeting habits solidify, moving from crisis-mode financial management toward a more normal, sustainable approach to income and spending.
    • Any remaining debt from before or during the crisis continues being addressed, whether that’s completing a Chapter 13 repayment plan, finishing out settlement negotiations on remaining accounts, or paying down debt that wasn’t part of a formal restructuring process.

    As you begin rebuilding, regularly reviewing your credit reports can help you identify inaccurate or outdated information. The CFPB’s explanation of credit reports provides an overview of the information commonly contained in consumer credit reports.

    For practical steps, see our guide on how to improve your credit score and our broader credit repair tips.

    Phase Four: Genuine Rebuilding (Roughly Year 2-4)

    This phase is where the effects of rock bottom become increasingly a part of your history rather than your present reality:

    • Credit scores for many people reach a genuinely good range within this window, assuming consistent management through the previous phases — commonly a score in the high 600s to 700s range, sometimes higher, depending on individual circumstances.
    • Larger financial goals become realistic again — qualifying for a mortgage (if that’s a goal and enough time has passed for any bankruptcy or foreclosure waiting period requirements), a car loan on reasonable terms, or other significant financial milestones that would have been difficult or impossible immediately after rock bottom.
    • The emergency fund reaches a more complete, standard target, providing genuine protection against future disruption rather than just a minimal buffer.
    • Retirement savings, if paused or reduced during the crisis period, typically resume more fully during this phase, as other priorities stabilize and free up capacity for longer-term goals.

    If foreclosure was part of your financial crisis, our guide on what foreclosure actually means and how to avoid it provides additional information about foreclosure stages and possible alternatives.

    For homeowners dealing with mortgage distress, HUD-approved housing counseling resources can provide information about mortgage delinquency, foreclosure, budgeting, and housing-related financial issues.

    Phase Five: Beyond Recovery (Year 4+)

    By this point, for most people who’ve consistently worked through the previous phases, the financial rock-bottom period becomes primarily a part of their financial history rather than an ongoing constraint:

    • Credit history, while still technically showing the historical negative event (bankruptcy remaining for up to 10 years, for example), carries progressively less weight in lending decisions as it moves further into the past and is increasingly outweighed by the more recent years of positive management.
    • Financial goals that felt impossible during rock bottom — homeownership, comfortable retirement saving, general financial security — become genuinely achievable, assuming continued consistent management.
    • The emotional and psychological relationship with money often continues evolving during this phase too, sometimes taking longer to fully process than the technical financial recovery itself.

    Why This Timeline Varies So Much Between Individuals

    • The specific path chosen (bankruptcy versus settlement versus a conventional payoff plan) affects the pace and shape of recovery differently.
    • Income trajectory during the recovery period matters enormously — someone whose income grows significantly during this window generally rebuilds faster than someone whose income remains flat or declines further.
    • The severity and specific nature of the original crisis — a single significant setback (a major medical event, a job loss) often resolves faster than an extended period of chronic financial strain with multiple compounding issues.
    • Support systems, both financial (family who can help in specific ways) and emotional (people who provide encouragement and accountability through a genuinely difficult, multi-year process) meaningfully affect both the pace and the experience of rebuilding.

    If your financial crisis began after losing employment, our guide on how to rebuild your finances after a job loss provides additional practical context.

    Common Emotional Patterns During This Process

    It’s worth naming that the emotional experience of rebuilding often doesn’t move in a straight line alongside the technical financial progress. Many people experience a specific kind of anxiety even as their numbers genuinely improve — a lingering fear of another setback, difficulty trusting that progress is “real” or permanent, or a tendency toward either excessive caution or, in the opposite direction, a kind of reactive overspending once things start to feel stable again. None of these patterns are unusual, and giving yourself both patience and, if it would genuinely help, professional support (a financial therapist, or simply a supportive community) for this dimension of recovery, alongside the purely technical financial steps, tends to produce more sustainable, complete recovery than focusing exclusively on the numbers.

    How to Measure Your Own Progress Realistically

    Rather than comparing your specific timeline to someone else’s, or to an idealized version of how fast recovery “should” happen, more useful benchmarks include: are you moving in a positive direction over each several-month period, even if slowly? Are you meeting the specific milestones relevant to your chosen path (settlement negotiations progressing, a Chapter 13 plan being maintained, credit score showing gradual improvement)? Is your day-to-day financial stress meaningfully lower than it was during the acute crisis phase, even if long-term goals still feel distant? These kinds of process-oriented measures tend to be more useful and more encouraging than fixating purely on a specific target date or comparing your situation to a generic timeline that may not reflect your specific starting point or circumstances.

    Frequently Asked Questions

    Is it normal to feel like recovery is taking longer than this general timeline suggests?

    Yes, completely normal — this is a general framework, not a guarantee, and individual circumstances (income changes, unexpected new setbacks, the specific severity of the original situation) can meaningfully extend any of these phases; the framework is meant to provide realistic general expectations, not a rigid schedule to feel discouraged about falling behind.

    Should I avoid all new credit during the stabilization and structural resolution phases?

    Generally, yes, avoiding new debt during these earliest phases is wise, focusing instead on resolving existing issues — new credit becomes more relevant and appropriate once you’re moving into the foundation-building phase, with a clearer, more stable financial base to build from.

    Does everyone need to go through all five of these phases, or can some be skipped?

    The specific content of each phase varies based on your situation (someone who didn’t need bankruptcy skips that specific element, for example), but the general progression — stabilization, structural resolution, foundation building, genuine rebuilding, and eventual full recovery — tends to apply in some form to most significant financial recovery situations, even if the specific tools used within each phase differ.

    How do I stay motivated during the slower, less dramatic middle phases of this process?

    Many people find it helpful to track specific, concrete milestones (a certain debt fully resolved, a specific credit score threshold reached, a certain emergency fund amount saved) rather than only the more abstract, harder-to-feel overall progress — celebrating these specific, achieved milestones along the way helps sustain motivation through what can otherwise feel like a long, undifferentiated period of gradual improvement.

    Is professional financial counseling worth it throughout this entire process, or just at the beginning?

    This varies by individual — some people benefit most from intensive support during the early stabilization and structural resolution phases, then transition to more independent management; others find ongoing periodic check-ins throughout the full multi-year process valuable for accountability and continued guidance, particularly if their situation involves any ongoing complexity.

    A Visual Summary of the Full Timeline

    Phase Approximate timing Primary focus
    1. Stabilization Months 1-3 Stop acute crises, get a full honest picture, choose a strategic path
    2. Structural resolution Months 3-12 Execute the chosen path (bankruptcy, settlement, DMP), begin minimal emergency fund
    3. Foundation building Year 1-2 Credit rebuilding, sustainable budgeting, growing emergency fund
    4. Genuine rebuilding Year 2-4 Good credit score achieved, larger goals become realistic, fuller emergency fund
    5. Beyond recovery Year 4+ Historical event carries less weight, full financial goals achievable

    Keeping a visual reference like this can help during the harder middle stretches, when day-to-day progress can feel invisible — seeing where you are within this broader arc provides useful context that a single month’s numbers alone don’t capture.

    A Note on Setbacks Within the Recovery Process Itself

    It’s worth acknowledging directly that recovery from financial rock bottom isn’t always a smooth, uninterrupted climb — a new unexpected expense, a temporary income disruption, or simply a harder month can occur even while you’re generally moving in the right direction. This doesn’t mean you’re back at rock bottom, and it doesn’t erase the progress already made. Treating a temporary setback within the recovery process as exactly that — temporary, and separate from your overall trajectory — rather than as evidence that the whole effort has failed, is an important mental framing that helps sustain the multi-year effort this kind of recovery genuinely requires.

    How to Know You’ve Genuinely Moved Into the Next Phase

    Since these phases don’t have hard, universal boundaries, it can help to have some general markers for recognizing your own transition points: moving from stabilization to structural resolution often coincides with having chosen and begun executing your specific strategic path, rather than still primarily reacting to crises. Moving from structural resolution to foundation building often coincides with your major restructuring process (bankruptcy discharge, completed settlements, an established debt management plan) being substantially complete, shifting your primary focus toward forward-building activities rather than resolving past issues. These aren’t rigid checkpoints, but noticing this kind of shift in your own primary focus can help you recognize genuine progress even when it doesn’t feel dramatic in the moment.

    Frequently Asked Questions, Continued

    Does having dependents (children, or other family members relying on you financially) significantly extend this timeline?

    It can, simply given the additional financial demands and reduced flexibility that supporting dependents often involves, though it doesn’t fundamentally change the general phase structure — it may mean each phase takes somewhat longer, or that certain foundation-building priorities (like building a larger emergency fund) become even more important given the additional people depending on your financial stability.

    Is there a risk of feeling perpetually behind if I keep comparing myself to this general timeline?

    This is worth being mindful of — the timeline is meant to provide general, encouraging structure, not a source of additional pressure; if you find comparing your specific situation to this general framework is generating more anxiety than helpful structure, it’s completely reasonable to set the comparison aside and simply focus on your own month-to-month progress instead.

    Should my approach to investing change across these different phases?

    Generally, investing beyond basic retirement account contributions (if your employer offers a match, which is often worth prioritizing even during recovery, given the immediate return the match itself represents) becomes more relevant in the later foundation-building and genuine-rebuilding phases, once emergency savings and debt resolution are more established — this isn’t a universal rule, but reflects the general principle of building a stable foundation before layering in additional financial goals.

    How to Handle Comparisons to Others’ Faster or Slower Recovery Stories

    Especially in an age of readily shared personal finance content, it’s easy to encounter stories of people who seemingly recovered from a serious financial setback in a fraction of the time this general framework describes. It’s worth remembering that these stories rarely capture full context — differing income levels, differing severity of the original crisis, family financial support that isn’t always disclosed, or simply survivorship bias in which stories get shared publicly in the first place. Using your own specific starting point and circumstances as your reference, rather than a curated success story from someone whose full situation you don’t actually know, leads to more realistic expectations and less unnecessary discouragement along the way.

    building-back-up-financial-rock-bottom-timeline-under-100kb

    Frequently Asked Questions, Continued One More Time

    Does remarrying or a significant relationship change during this recovery process complicate the timeline?

    It can add complexity, particularly around merging or keeping separate finances, and potentially around how a new partner’s own financial situation interacts with your ongoing recovery — this is worth navigating thoughtfully and honestly with a partner, since financial transparency about an ongoing recovery process tends to support a healthier long-term relationship than concealment.

    Is there a specific point where I should consider my “rock bottom” period officially over?

    This is ultimately a personal determination rather than a specific technical milestone — some people mark it at debt discharge or full settlement completion, others at reaching a specific credit score, and still others simply notice a shift in their day-to-day relationship with money feeling meaningfully less anxious and more stable; whichever marker feels meaningful to you personally is a valid way to recognize this transition.

    The Bottom Line

    Rebuilding from financial rock bottom follows a reasonably predictable arc — stabilization, structural resolution, foundation building, genuine rebuilding, and eventual full recovery — typically unfolding over two to four years for most people, though this varies considerably based on the specific path chosen, income trajectory, and the original situation’s severity. Understanding this general timeline helps set realistic expectations, both preventing the discouragement of comparing your progress to an unrealistic faster timeline, and providing genuine hope grounded in a real, achievable framework rather than vague reassurance — financial rock bottom is genuinely recoverable, and the path forward, while requiring real time and sustained effort, is a well-understood one that many people successfully navigate.

    Related Credit & Financial Recovery Resources

    For additional consumer guidance, you can also review the Consumer Financial Protection Bureau, which provides educational resources about credit reports, debt collection, credit counseling, and managing debt.

    Need Help Understanding Your Credit Situation?

    If financial hardship has left you dealing with inaccurate information, negative accounts, collections, or other credit-report concerns, a professional credit review can help you understand what is currently appearing on your reports and what steps may be available.

    Request a Credit Audit to discuss your credit situation and potential next steps.

  • How to Tell a Legitimate Debt Collector From a Scam

    How to Tell a Legitimate Debt Collector From a Scam

    Debt collection scams have become sophisticated enough that distinguishing a real collector from a fraudulent one isn’t always obvious just from a gut feeling. Scammers know the same terminology real collectors use, sometimes even referencing accurate personal details obtained through data breaches, and they’re specifically designed to create urgency that discourages the careful verification that would otherwise expose them. This guide walks through the concrete, reliable signs that separate a legitimate debt collector from a scam, and exactly how to verify which one you’re dealing with.

    The Core Red Flags of a Scam

    Demands for payment through gift cards, wire transfers, cryptocurrency, or prepaid debit cards. This is one of the most reliable scam indicators across virtually all types of fraud, not just debt collection. Legitimate debt collectors accept standard, traceable payment methods — checks, standard bank transfers, credit or debit card payments — and have no legitimate reason to insist specifically on these harder-to-trace, harder-to-reverse payment forms.

    The Federal Trade Commission’s guidance on gift card scams specifically warns consumers that anyone who demands payment by gift card is displaying a major fraud warning sign.

    Extreme urgency and pressure to pay immediately. Real debt, however old, doesn’t expire in the next few hours. A caller insisting you must pay today, right now, before you have any chance to research or verify anything, is exhibiting a classic pressure tactic scammers rely on specifically because it works against careful, rational decision-making.

    Threats of immediate arrest or law enforcement action. Unpaid consumer debt in the United States is a civil matter, not a criminal one. No legitimate debt collector can have you arrested for an unpaid credit card, medical bill, or personal loan. Any threat of imminent arrest for unpaid debt is a clear, reliable sign of either a scam or a company operating illegally.

    Refusal to provide written validation when requested. Legitimate collectors are legally required to provide this upon request, and while a real collector might sometimes be slow or need a follow-up reminder, an outright refusal or evasiveness about this basic legal obligation is a significant warning sign.

    The Consumer Financial Protection Bureau’s Regulation F guidance explains requirements concerning information debt collectors must provide to consumers, including validation information in covered collection communications.

    Inability or unwillingness to identify the specific company and provide verifiable contact information. A legitimate collector should be able to tell you their company name, provide a callback number, and give you a mailing address — vague or evasive answers to these basic questions are cause for real skepticism.

    Requests for sensitive information beyond what’s needed to identify the account. A legitimate collector generally already has enough information to confirm they’ve reached the right person and doesn’t need you to read out your full Social Security Number, bank account numbers, or similar sensitive details over an unverified phone call.

    How Scammers Make Themselves Sound Legitimate

    Understanding their tactics helps you stay skeptical even when something initially sounds convincing:

    • Using real personal information, obtained through data breaches. Scammers sometimes have access to genuine personal details (your name, address, even partial account information) obtained through data breaches, which they use to sound credible and knowledgeable, even though this doesn’t mean the underlying debt claim itself is legitimate.
    • Adopting official-sounding company names. Scam operations sometimes choose names deliberately similar to real, well-known companies or government agencies, hoping the similarity alone will discourage close scrutiny.
    • Referencing real debts you may have had at some point, even if the debt has already been paid, discharged in bankruptcy, or is being fraudulently claimed by an unrelated party, betting that the general familiarity of “yes, I did have a debt like that once” will short-circuit your careful verification instinct.
    • Using caller ID spoofing to make an incoming call appear to come from a legitimate-looking or even local number, which has become increasingly technically easy to fake and shouldn’t be relied on as a verification method on its own.

    The FTC’s consumer guidance on caller ID spoofing explains why the number displayed on your phone should not be treated as proof of who is calling.

    How to Actually Verify Legitimacy

    Ask for everything in writing before engaging further. A legitimate collector should be willing and able to send you written information about the debt, including formal validation if you request it, without needing to resolve everything on the initial call.

    Hang up and call back using independently sourced contact information. Rather than trusting a number the caller gives you, or a callback number from an incoming call, look up the company’s official contact information yourself — through their official website, or, if they claim to represent a specific original creditor, by contacting that original creditor directly to confirm whether they’ve actually placed or sold your account with this specific company.

    Check your own credit report. If a legitimate debt exists and has been placed with a collector, it will very often (though not always, particularly for very recent placements) show up on your credit report, giving you independent confirmation the account exists, separate from whatever the caller is telling you.

    You can obtain your credit reports through AnnualCreditReport.com, the official federally authorized source for free credit reports.

    If you need help understanding what you find, see our guide on how to read a credit report.

    Search the company name alongside terms like “scam,” “complaints,” or “reviews.” While not a perfectly reliable method on its own (legitimate companies can have complaints too, and sophisticated scammers sometimes create fake positive reviews), a pattern of widespread, consistent scam reports is a meaningful warning sign worth taking seriously.

    Check whether the company is registered or licensed in your state, if your state requires this. Many states require debt collectors to register or obtain a license to operate, and some maintain publicly searchable databases through the state’s department of financial regulation, providing another verification avenue.

    What a Legitimate Collector Will and Won’t Do

    Will: provide written validation upon request, identify themselves and their company clearly, accept standard payment methods, honor a request to communicate only in writing, and generally allow you time to verify information before demanding immediate payment.

    Won’t (if operating legally): threaten arrest for unpaid civil debt, demand payment exclusively through gift cards or cryptocurrency, refuse to provide any written information about the debt, or use genuinely abusive, threatening, or harassing language.

    The CFPB’s debt collection resources explain consumer rights and restrictions that apply to covered debt collectors under federal law.

    What to Do If You Suspect a Scam

    Don’t provide any payment or sensitive personal information. If something feels off, it’s always reasonable to simply end the call or not respond to a suspicious message, taking time to verify before engaging further.

    Report it. The Federal Trade Commission’s ReportFraud.gov and the Consumer Financial Protection Bureau complaint system both accept complaints about suspected debt collection scams, and reporting helps build the case against repeat offenders even if it doesn’t resolve your individual situation immediately.

    Alert your bank if you’ve already provided any financial information, so they can monitor for and help protect against unauthorized activity.

    Consider a fraud alert or credit freeze if you believe your personal information has been compromised in a way that could lead to further fraudulent activity beyond just this one contact attempt.

    Our guide on identity theft protection covers additional steps you can take if you believe your personal information has been compromised.

    You can also learn about the difference between a credit freeze and a fraud alert before deciding which protection is appropriate for your situation.

    What If the Debt Is Real, But the Specific Collector Contacting You Isn’t Legitimate?

    This is a genuinely tricky and increasingly common scenario: you might have a real debt, but be contacted by a scammer who’s somehow aware of it (through a data breach, or by impersonating a legitimate collector who does actually own the account) attempting to collect fraudulently, separate from any legitimate collection effort. In this case, the appropriate response is the same — don’t pay or provide information to the suspicious contact — but it’s also worth proactively contacting the actual, verified original creditor or a legitimately identified current debt owner (found independently, not through the suspicious contact) to address the real underlying debt through proper channels.

    A Practical Verification Checklist

    1. Did they demand an unusual, hard-to-trace payment method? If yes, treat with strong suspicion.
    2. Did they threaten arrest or immediate legal action within hours? If yes, this is not legally accurate for consumer debt and is a red flag.
    3. Were they willing to provide written information and a verifiable company name and contact information? If no, or if evasive, be skeptical.
    4. Have you independently verified the company’s legitimacy — through your own research, your credit report, or contacting the claimed original creditor directly? If not yet, do this before any further engagement.
    5. Are they pressuring you to decide and pay within an unreasonably short window? If yes, this urgency tactic is a common scam indicator, even when the rest of the interaction seems otherwise plausible.

    Frequently Asked Questions

    Can a scammer know real details about my actual debts?

    Yes, unfortunately — data breaches affecting banks, retailers, and other companies have exposed enormous amounts of personal and financial information over the years, and scammers sometimes purchase or otherwise obtain this data, using genuine details to make fraudulent contact attempts sound more credible than they actually are.

    Is it a scam if the caller has my correct Social Security Number?

    Not necessarily proof either way — having your SSN doesn’t confirm they’re legitimate (this information can be obtained through breaches or other illegitimate means) nor does it necessarily mean they’re a scam. Legitimacy needs to be verified through the broader checklist in this guide, not through any single piece of information they happen to have.

    Should I ever give my debit or credit card number to a debt collector over the phone?

    This is generally not recommended as a first step, even with a collector you believe is legitimate — it’s safer to request written validation first, verify the company independently, and then make any payment through a method and channel you’ve independently confirmed, such as calling back using a number you looked up yourself, rather than providing card details during an unsolicited or unverified call.

    What if the “collector” claims to be a law firm rather than a standard collection agency?

    Some legitimate law firms do handle debt collection, particularly once a matter has progressed toward or into litigation, but this claim should be verified the same way as any other — checking the firm’s actual bar registration and legitimate contact information independently, rather than assuming the “law firm” framing alone confirms legitimacy or increases urgency.

    Is there a specific government database I can check to verify a debt collector’s legitimacy?

    The CFPB’s consumer complaint database allows you to search for complaints against specific companies, and many state financial regulatory agencies maintain licensing databases — while neither is a perfect, complete verification tool on its own, both provide useful additional data points when combined with the other verification steps in this guide.

    A Deeper Look at Common Debt Collection Scam Variants

    Understanding the specific patterns scammers commonly use helps you recognize them faster in the moment, rather than needing to work through a full checklist each time.

    The “phantom debt” scam, where the caller claims you owe a debt that doesn’t actually exist at all — sometimes for a payday loan you never took out, or an old debt that’s already been paid or discharged, betting that the general anxiety and confusion the call creates will lead to a quick payment without careful verification.

    The “fake law firm” scam, where callers claim to represent a law firm, sometimes threatening an imminent lawsuit or even claiming a lawsuit has already been filed, when no such legal action actually exists, designed to create heightened urgency and fear beyond what a standard collection call might produce.

    The “government impersonation” scam, where callers falsely claim to represent a government agency (sometimes referencing the IRS, a court, or law enforcement) in connection with an alleged debt, leveraging the added authority and fear associated with government contact to pressure faster, less-questioned compliance.

    The “debt relief” scam, somewhat different in structure, where a company falsely claims to be able to negotiate or eliminate your real debts in exchange for upfront fees, sometimes instructing you to stop paying your actual creditors while they supposedly negotiate on your behalf — a pattern that can leave you both out the upfront fee and further behind on your actual, real obligations.

    Before working with any company offering debt relief or credit-related services, it is worth understanding how credit repair works and what legitimate services can and cannot do.

    What to Do If You’ve Already Sent Money to a Scammer

    If you’ve already made a payment before recognizing the scam, acting quickly matters, though options vary by payment method. If you paid by credit card, contact your card issuer immediately to dispute the charge, which offers the strongest built-in consumer protection among common payment methods. If you paid via bank transfer, contact your bank immediately, since some transfers can potentially be reversed if caught quickly enough, though this becomes less likely the more time has passed. If you paid via gift card or wire transfer, unfortunately, recovery is often very difficult or impossible, though reporting to the FTC and the gift card issuer (some companies have specific fraud reporting processes) is still worth doing, both for your own records and to support broader enforcement efforts against the scammer.

    If you believe a fraudulent credit-card transaction occurred, our guide on how to dispute a fraudulent credit card charge explains the basic dispute process.

    The FTC’s guidance on what to do after being scammed provides additional steps for reporting fraud and protecting your accounts.

    How Legitimate Companies Sometimes Get Mistaken for Scams

    It’s worth acknowledging the reverse situation too: legitimate debt collectors sometimes get flagged as suspicious simply because collection calls are inherently unwelcome and anxiety-inducing, leading people to assume the worst even when the company is operating entirely within legal bounds. A legitimate collector calling from an unfamiliar number, discussing an old debt you’d genuinely forgotten about, using standard industry terminology that sounds unfamiliar to you, isn’t automatically a scam simply because it’s uncomfortable or unexpected. The verification checklist in this guide is designed to help you distinguish between “unfamiliar and uncomfortable” (which legitimate collection calls often are) and “actually fraudulent” (which requires the specific red flags covered throughout this guide), rather than treating every unexpected collection contact as automatically suspicious.

    Frequently Asked Questions, Continued

    Can I ask a caller to prove their legitimacy on the spot, during the call itself?

    You can ask, but be aware that a sophisticated scammer may have prepared answers to common verification questions — the more reliable approach remains independent verification after the call (calling back using information you look up yourself, checking your credit report, contacting the claimed original creditor directly) rather than relying solely on what the caller tells you during the conversation itself.

    Is it a scam if I don’t recognize the original creditor they mention?

    Not automatically — as covered in guides about zombie debt and debt resale, legitimate old debt can genuinely trace back to a creditor you’ve forgotten about, or the account may have originated with a company that’s since merged, been renamed, or is otherwise less immediately recognizable. This alone isn’t proof of a scam, though it does warrant the same careful verification process as any other collection contact.

    Do scammers ever send physical mail, or is this primarily a phone-based scam?

    Scammers do send physical mail as well, sometimes designed to look official or urgent, so the same verification principles apply regardless of the contact method — don’t respond with payment or sensitive information based solely on an unverified letter any more than you would an unverified phone call.

    Should I report a suspected scam even if I didn’t lose any money?

    Yes — reporting suspected scam attempts, even unsuccessful ones, to the FTC and CFPB helps regulators identify patterns and take action against repeat offenders, potentially protecting others who might be more vulnerable to a similar attempt in the future.

    A Comparison Table: Legitimate Collector vs. Scam Indicators

    Behavior Legitimate Collector Scam Red Flag
    Payment methods accepted Checks, cards, standard bank transfer Insists on gift cards, crypto, wire only
    Response to validation request Provides in writing, may take time Refuses or stalls indefinitely
    Urgency Willing to let you research and respond Demands payment within hours
    Legal threats Accurate — civil consequences only Threatens arrest for unpaid debt
    Company identification Clear name, verifiable address/number Vague, evasive, or unverifiable
    Willingness to communicate in writing Yes, upon request Avoids written communication

    Keeping this comparison in mind during any unexpected collection contact gives you a fast, practical way to assess the situation in the moment, before deciding how — or whether — to engage further.

    Frequently Asked Questions, Continued Further

    Do scam debt collectors typically target specific demographics more than others?

    Unfortunately, yes — scammers often specifically target populations perceived as more vulnerable or less likely to push back, including elderly individuals, recent immigrants less familiar with U.S. debt collection norms, and people already under significant financial stress who may feel less equipped to carefully scrutinize a stressful call. Being aware of this pattern is useful both for your own vigilance and for watching out for family members who might be more susceptible to this kind of targeting.

    Can text message or email debt collection attempts be scams too, not just phone calls?

    Yes, absolutely — as legitimate debt collection has expanded to include email and text communication (subject to specific consent and opt-out requirements under updated FDCPA regulations), scammers have adapted the same tactics to these channels, making the same verification principles just as relevant to a suspicious text or email as to a phone call.

    Is it worth blocking a number after a suspected scam call, or does that not accomplish much given how easily numbers can be spoofed?

    Blocking a specific number provides some benefit even though spoofing means a scammer could call again from a different number — it at least prevents repeat contact from that exact number and takes only a moment, making it a reasonable low-effort step even if it’s not a complete, permanent solution against a persistent scammer using multiple spoofed numbers.

    The Bottom Line

    Distinguishing a legitimate debt collector from a scam comes down to a consistent set of reliable warning signs — demands for untraceable payment methods, threats of arrest, extreme urgency, and refusal to provide written validation or verifiable company information — combined with proactive, independent verification on your part rather than simply trusting whatever the caller tells you. Legitimate collectors are ultimately fine with you taking time to verify and respond in writing; scammers depend on you not doing so. When in doubt, slow down, hang up, verify independently, and never provide payment or sensitive information based purely on pressure from an unverified contact.

    Need Help Reviewing Your Credit Report?

    If you’ve received a suspicious collection notice or found an unfamiliar collection account on your credit report, reviewing the account details can help you determine what information is being reported and whether there are potential inaccuracies.

    Request a Credit Audit to discuss your credit situation and potential next steps.

  • How to Talk to Creditors When You Can’t Pay

    How to Talk to Creditors When You Can’t Pay

    Picking up the phone to tell a creditor you can’t pay is one of those tasks that feels harder in anticipation than it usually is in practice — but the anticipation itself often causes people to delay the call, which is precisely the wrong instinct. This guide focuses specifically on the conversation itself: what to actually say, how to structure it, and how to handle the range of responses you might get.

    Why This Conversation Is Worth Having, Even When It Feels Pointless

    It’s a common assumption that calling a creditor when you can’t pay accomplishes nothing — after all, you still can’t pay, so what’s the point of the conversation? In reality, this conversation can accomplish several concrete things: it can access hardship programs not offered proactively, it can prevent a missed payment from being reported as severely as it might be if handled reactively after the fact, it creates a documented record of your good-faith effort, and it sometimes simply buys you a short amount of additional time through an agreed extension.

    Preparing Before You Call

    Know Your Specific Numbers

    Have a clear sense of what you can realistically pay, if anything, right now, and what a sustainable payment might look like going forward if your hardship is ongoing rather than a single-month gap.

    Gather Relevant Documentation

    Gather relevant documentation, even if you don’t end up needing to send it during the initial call — a layoff notice, reduced pay stubs, or a general summary of your situation.

    Decide What You’re Specifically Asking For

    Decide what you’re specifically asking for. A short extension? A reduced payment plan? A pause? Having a specific ask, even if you’re flexible about the details, makes the conversation more productive than an open-ended “I can’t pay, what do we do.”

    A Basic Conversation Structure

    Open Directly

    “I’m calling about my account because I’m not going to be able to make my full payment this month, and I want to discuss options.”

    Briefly Explain Why

    Briefly explain why, without over-explaining. “I lost my job on [date]” or “I had an unexpected medical expense” is sufficient — you don’t need to justify your situation extensively.

    State What You’re Asking For

    State what you’re asking for. “I’m hoping we can arrange a short extension” or “I’d like to know if a reduced payment plan is available.”

    Listen and Ask Clarifying Questions

    Listen to what they offer, and ask clarifying questions about anything unclear — specifically whether interest continues accruing, what happens if the arrangement isn’t sustained, and how this will affect your account status and credit reporting.

    Confirm the Next Steps

    Confirm next steps and request written confirmation of whatever is agreed to before the call ends.

    How to Handle Common Responses

    If They Offer a Specific Hardship Program

    Ask for full details in writing before agreeing, and make sure you understand exactly what’s required of you and what happens at the end of the program period.

    If They Say No Formal Program Is Available

    Ask directly whether any informal accommodation is possible — sometimes representatives have some discretion even without a named “program,” particularly for a customer with a strong prior payment history.

    If They Push for a Payment Amount You Can’t Afford

    It’s okay to say clearly, “I’m not able to commit to that amount right now” rather than agreeing to something you know you can’t sustain, which would likely just result in a second, compounding problem shortly afterward.

    If the Representative Seems Unhelpful or Inflexible

    Politely ask if there’s a supervisor or a specific hardship/loss mitigation team you can be transferred to, since front-line representatives don’t always have full visibility into every available option.

    What to Avoid Saying or Doing

    • Don’t make a promise you’re not confident you can keep, simply to end an uncomfortable conversation. An unfulfilled promise can damage your credibility for future negotiations and sometimes voids whatever accommodation was extended based on that promise.
    • Don’t provide payment information before you’ve agreed on final terms. If asked for a card or bank account number before the specifics are settled, it’s reasonable to say you’ll provide payment details once the arrangement is confirmed in writing.
    • Don’t let embarrassment stop you from asking clarifying questions. If something isn’t clear — how interest works during a pause, what happens if you miss the new arrangement — ask directly rather than nodding along without understanding.

    When to Put It in Writing Instead of (or in Addition to) Calling

    Some situations are better suited to a written request from the start — if you want a clear, documented record from the very beginning, if you find phone conversations more stressful and prefer time to compose your thoughts, or if a specific creditor’s process specifically directs hardship requests through a written or online form rather than a phone call. A hybrid approach — calling first to understand your options, then following up in writing to formally request and confirm — combines the efficiency of real-time conversation with the protection of documentation.

    How This Conversation Differs Depending on Who You’re Talking To

    Original Creditor

    An original creditor’s customer service or hardship team generally has the most flexibility and the clearest institutional incentive to keep you as a paying customer, making this often the most productive version of this conversation.

    Collection Agency

    A collection agency working on behalf of a creditor has somewhat less flexibility, constrained by what the original creditor authorizes, though the same core conversation structure still applies.

    Debt Buyer

    A debt buyer who already owns defaulted debt is a different conversation entirely (covered in more detail in guides specifically about negotiating with debt collectors), since by this point you’re generally discussing settlement of an already-defaulted debt rather than hardship accommodation on a current account.

    If you are dealing with a collection account, you may also want to review our guide on how to remove collections from your credit report and learn about debt validation letters.

    Practicing the Conversation Before You Make the Call

    If phone conversations like this feel especially daunting, it can genuinely help to write out or even say aloud what you plan to say beforehand, almost like a brief script. This isn’t about sounding rehearsed or robotic — it’s about reducing the anxiety of needing to improvise difficult content in the moment, so you can focus on actually listening to and engaging with the representative’s response rather than being preoccupied with figuring out what to say next.

    Frequently Asked Questions

    Is it better to call during a specific time of day to reach a more helpful representative?

    This isn’t generally a reliable strategy — call quality and representative helpfulness vary by individual, not predictably by time of day, though calling when you’re not rushed and can give the conversation full attention (rather than squeezed into a quick break) tends to produce a more productive conversation regardless of the specific hour.

    Should I mention that I’m considering bankruptcy as leverage in this conversation?

    This is generally not an effective negotiating tactic and can sometimes work against you — creditors may become less willing to offer flexible accommodation if they believe you’re likely to discharge the debt entirely through bankruptcy regardless of what they offer, since it reduces their incentive to extend favorable terms.

    What if I get a different answer from two different representatives at the same company?

    This does happen, given some variability in how individual representatives understand or apply policy — if you receive information that seems inconsistent, it’s reasonable to call back and ask to speak with someone else, or specifically request supervisor-level clarification, rather than simply accepting whichever answer happened to come first.

    Is texting or emailing a creditor an acceptable alternative to calling if I find phone calls too stressful?

    Many creditors do offer written communication channels (secure messaging through an online account portal, for example) as an alternative to phone calls, and this can be a completely legitimate way to have this conversation if it genuinely reduces your stress and helps you communicate more clearly — the core content and goals of the conversation remain the same regardless of the specific channel used.

    Does it help to mention I’ve been a loyal customer for a long time?

    This can be a reasonable, honest point to include, since account tenure and history genuinely do factor into how some creditors evaluate hardship requests, though it shouldn’t be the centerpiece of your request — leading with the factual situation and your specific ask, with tenure as supporting context, tends to be more effective than leading with loyalty alone.

    A Full Sample Call Script From Start to Finish

    Having a complete script — not just fragments — can make the actual call feel far more manageable:

    You: “Hi, I’m calling about my account ending in [last 4 digits]. I want to be upfront that I’m not going to be able to make my full payment this month due to [brief reason]. I’d like to understand what options might be available.”

    Representative: [Asks for account verification, may ask follow-up questions about your situation]

    You: “That’s right. I’m hoping we can work out either a short extension or a temporarily reduced payment — whatever might be possible on your end.”

    Representative: [Offers a specific option, or says none is available]

    If offered something: “That sounds workable. Can you send me written confirmation of the terms — the amount, the timeline, and how this affects my account status — before we finalize it?”

    If nothing is offered: “I understand. Is there anyone else I could speak with, or any other option I should know about, given my situation?”

    Closing: “Thank you for your help today. I’ll watch for that written confirmation, and please let me know if you need anything further from me.”

    This kind of complete, natural script — reviewed once or twice beforehand — removes much of the anxiety of needing to think on your feet, while still leaving room to adapt naturally to how the actual conversation unfolds.

    Understanding Representative Incentives Can Help You Navigate the Call

    It can help to remember that most customer service representatives handling these calls are measured on some combination of call resolution and customer retention, not purely on collecting the maximum amount possible in the moment. This means a representative genuinely may be motivated to help you find a workable path forward, since a customer who successfully navigates a hardship and remains an account holder is generally a better outcome, from the company’s own perspective, than one who defaults entirely. This isn’t true universally at every company, but keeping this general dynamic in mind can help you approach the conversation as a collaborative problem-solving exercise rather than an adversarial one, which often produces better results for both sides.

    how-to-talk-to-creditors-when-you-cant-pay-under-100kb

    What to Do Immediately After the Call

    • Write down what was discussed while it’s fresh — the date, the representative’s name if provided, and a summary of what was offered or agreed to.
    • Follow up promptly if written confirmation doesn’t arrive within the timeframe discussed, rather than assuming it’s being processed indefinitely without checking.
    • Calendar any key dates — when a temporary accommodation period ends, when a modified payment is first due — so you’re not caught off guard by a transition back to standard terms.

    Frequently Asked Questions, Continued

    If I’m nervous and the conversation doesn’t go as smoothly as I’d hoped, can I call back and try again?

    Yes — there’s no rule against calling back, whether to clarify something you didn’t fully understand the first time, to speak with a different representative, or simply because you want another attempt at a conversation that didn’t go how you’d hoped; creditors field these calls regularly and a second call isn’t unusual or penalized.

    Should I record the call for my own records?

    Recording laws vary by state (some require only one party’s consent, others require all parties’ consent), so it’s worth knowing your specific state’s rule before recording without informing the other party — many companies also record calls on their end for quality purposes, which you can sometimes reference later if there’s a dispute about what was discussed, even without your own separate recording.

    Is there a specific department name I should ask for to get to the most helpful team fastest?

    This varies by company, but terms like “hardship department,” “loss mitigation,” “financial assistance program,” or “customer assistance team” are common names worth asking for specifically, rather than assuming general customer service is your only option.

    Why Written Follow-Up Matters Even After a Positive Phone Conversation

    Even when a phone conversation goes well and a representative seems genuinely helpful and clear about what’s being offered, verbal agreements are inherently harder to enforce or even simply remember accurately weeks later. This is true regardless of how trustworthy the representative seems in the moment — it’s not about doubting their sincerity, but about protecting yourself against the very real possibility of a processing error, staff turnover, or simple miscommunication that written confirmation guards against. Treating “get it in writing” as a non-negotiable step, not an optional extra precaution, protects you regardless of how well any individual conversation goes.

    Frequently Asked Questions, Continued One More Time

    If English isn’t my first language, are there resources to help with this conversation?

    Many major creditors offer multilingual customer service lines or translation services — it’s worth asking directly whether service in your preferred language is available, and if not through the creditor directly, a nonprofit credit counseling agency serving your community may be able to provide language support or even directly assist with the negotiation on your behalf.

    Does it matter if I’m slightly emotional or upset during this call?

    This is a completely human, understandable reaction to financial stress, and representatives who handle these calls regularly are generally not put off by some visible emotion — that said, if you feel too overwhelmed to communicate clearly in the moment, it’s reasonable to say so directly (“I’m finding this difficult to discuss right now, can I call back”) and try again once you feel more composed, rather than pushing through a conversation that isn’t productive.

    The Bottom Line

    Talking to a creditor when you can’t pay is a conversation worth having directly and proactively, structured around a clear, factual explanation of your situation and a specific request for accommodation. Preparing your numbers and documentation in advance, listening carefully to what’s offered, asking clarifying questions rather than agreeing to unclear terms, and getting everything confirmed in writing all meaningfully improve the outcome of this conversation compared to avoiding it out of discomfort or assuming in advance that nothing productive will come from it.

    For additional guidance, see our related article on how to negotiate with creditors when you’re struggling.

    Need Help Reviewing Your Credit Situation?

    If missed or late payments have already affected your credit reports, a professional credit review can help you understand what information is being reported and whether there are inaccurate items that may need attention.

    Request a Credit Audit

  • Foreclosure: What It Actually Means and How to Avoid It

    Foreclosure: What It Actually Means and How to Avoid It

    Foreclosure is one of the most feared words in personal finance, and for good reason — losing a home is a genuinely severe outcome. But foreclosure is also a legal process with specific stages, specific timelines, and, importantly, specific points along the way where intervention can still prevent the worst outcome. Understanding exactly how the process works demystifies it and clarifies where your real opportunities to act actually are.

    What Foreclosure Actually Is

    Foreclosure is the legal process through which a mortgage lender repossesses and sells a property after the borrower has defaulted on their mortgage payments, using the sale proceeds to recover what’s owed on the loan. It’s the lender’s enforcement mechanism for the security interest they hold in the property, since a mortgage loan is secured by the home itself as collateral.

    How the Process Typically Unfolds

    Missed Payments and Early Delinquency

    The process generally begins with a missed payment, followed by increasingly serious notices as delinquency continues.

    Default Notice

    After a specific period of continued nonpayment (commonly around 90-120 days, though this varies by state, lender, and loan type), the lender formally declares default and often sends a formal notice, sometimes called a “Notice of Default,” which is often the first clearly foreclosure-specific document a borrower receives.

    Pre-Foreclosure Period

    Depending on your state, there’s often a period between formal default notice and an actual foreclosure sale during which specific rights and options may apply, including a right to “cure” the default by catching up on missed payments plus fees.

    Foreclosure Filing or Notice of Sale

    Depending on your state’s specific process (judicial foreclosure, which goes through the court system, versus non-judicial foreclosure, which follows a specific out-of-court process defined by state law and your original loan documents), formal foreclosure proceedings begin.

    Foreclosure Sale

    The property is sold, typically at a public auction, with proceeds going toward the outstanding loan balance, fees, and costs.

    Eviction, if Necessary

    If you’re still occupying the home at the time of sale, a separate eviction process typically follows to formally remove you from the property.

    Judicial vs. Non-Judicial Foreclosure

    Judicial Foreclosure

    Judicial foreclosure requires the lender to file a lawsuit and obtain a court order to foreclose, generally providing more procedural protections and time for the borrower, since it goes through the full court process.

    Non-Judicial Foreclosure

    Non-judicial foreclosure, used in many states, follows a specific process outlined in state law and your original mortgage documents (specifically the “power of sale” clause many deeds of trust include), generally proceeding faster than judicial foreclosure since it doesn’t require a separate court lawsuit.

    Which process applies to you depends entirely on your state’s law, and this significantly affects your realistic timeline and specific procedural rights, making it worth understanding which type applies in your specific state early in any foreclosure concern.

    The Critical Window: Options Available Before Foreclosure Sale

    Reinstatement

    Paying the full past-due amount (plus fees and costs) to bring your loan current, stopping foreclosure and returning to your normal payment schedule. This is often available, though sometimes only up to a specific point in the process defined by your state’s law.

    Forbearance

    A temporary reduction or pause in payments, agreed to by the lender, typically for a defined period, with a plan for how the paused amount will eventually be addressed (added to the end of the loan, a repayment plan, or in some cases as part of a broader modification).

    Loan Modification

    A more permanent restructuring of your loan terms — potentially a lower interest rate, extended term, or other changes — to make your payment more sustainable going forward.

    Repayment Plan

    An agreement to pay your regular payment plus an additional amount over a defined period specifically to catch up on the missed payments.

    Short Sale

    Selling the home for less than the remaining mortgage balance, with the lender’s approval, avoiding foreclosure while still resulting in the loss of the home, but generally with less severe credit and financial consequences than an actual foreclosure.

    Deed in Lieu of Foreclosure

    Voluntarily transferring the property back to the lender to avoid the formal foreclosure process, again resulting in loss of the home but sometimes with somewhat less severe consequences than a completed foreclosure, depending on the specific circumstances and lender.

    Why Contacting Your Servicer Early Matters So Much

    Similar to other hardship situations, the earlier you engage with your mortgage servicer, the more options remain realistically available. Many of the options above — forbearance, modification, repayment plans — are far more accessible when requested proactively or early in delinquency than once foreclosure proceedings have formally begun. Federal regulations actually require mortgage servicers to make good-faith efforts to contact borrowers and discuss loss mitigation options before initiating formal foreclosure in many circumstances, but proactively reaching out yourself, rather than waiting for the servicer to initiate contact, generally puts you in a stronger position.

    For more guidance on communicating with creditors during financial hardship, see our guide on how to negotiate with creditors when you’re struggling.

    Specific Protections for Federally Backed Loans

    If your mortgage is backed by the FHA, VA, USDA, Fannie Mae, or Freddie Mac (a very large portion of U.S. mortgages fall into one of these categories), you have access to specific, more standardized hardship and loss mitigation programs than a purely private, non-backed loan might offer. Finding out which category your loan falls into (your servicer can confirm this, or you can often check through Fannie Mae’s or Freddie Mac’s own loan lookup tools) is a valuable early step, since it clarifies which specific programs and protections apply to your situation.

    Working With a HUD-Approved Housing Counselor

    The U.S. Department of Housing and Urban Development (HUD) certifies housing counseling agencies that provide free or low-cost foreclosure prevention counseling, helping you understand your options, communicate with your servicer, and sometimes directly assist in negotiating a resolution. This is a genuinely valuable, often underused resource — working with a HUD-approved counselor is free and can meaningfully improve your ability to navigate a complex, high-stakes process.

    What Happens to Your Credit After Foreclosure

    A completed foreclosure is a serious negative item, generally remaining on your credit report for up to seven years from the date of the first missed payment that led to the foreclosure. This significantly affects your ability to qualify for a new mortgage for a period (commonly several years, depending on the specific loan program you’d apply for in the future), though — similar to bankruptcy — many people who go through foreclosure rebuild their credit and can qualify for a new mortgage again within a few years of consistent, responsible financial management afterward.

    If you are working to recover from negative credit information, our guides on how to improve your credit score and how to fix your credit provide additional information.

    What Happens If the Sale Doesn’t Cover the Full Loan Balance?

    If your home sells for less than what you owed (a “deficiency”), some states allow lenders to pursue you for this remaining deficiency balance through a separate legal action, while other states have specific anti-deficiency laws limiting or eliminating this possibility for certain types of loans (commonly purchase-money mortgages on a primary residence, though rules vary considerably). Understanding your specific state’s deficiency rules is an important part of understanding your full financial exposure if foreclosure does ultimately occur.

    Frequently Asked Questions

    How long does the entire foreclosure process typically take, from first missed payment to actual sale?

    This varies enormously by state and specific circumstances, ranging anywhere from a few months in some non-judicial foreclosure states to well over a year in judicial foreclosure states with more extended court processes — there’s no single universal timeline, making it important to understand your specific state’s typical process.

    Can I sell my home myself to avoid foreclosure, even if I owe more than it’s worth?

    Yes, through a short sale, though this requires your lender’s approval since they’re agreeing to accept less than the full amount owed — this process takes some time to negotiate and complete, so it’s most viable if pursued before you’re extremely close to an actual scheduled foreclosure sale date.

    Does forbearance mean I don’t have to pay anything, or does the paused amount still need to be addressed eventually?

    Forbearance pauses your required payment temporarily, but the paused amount generally still needs to be addressed eventually — through a lump-sum repayment, a repayment plan spread over time, or, sometimes, being added to the end of your loan term through a modification, depending on what your specific lender and program allow.

    Is bankruptcy an option to stop a foreclosure that’s already in progress?

    Yes — filing for bankruptcy triggers the automatic stay, which immediately halts foreclosure proceedings, at least temporarily, while your bankruptcy case is active; whether this provides a lasting solution depends on your specific situation and which type of bankruptcy you file, making this worth discussing with a bankruptcy attorney if foreclosure feels imminent and other options haven’t resolved the situation.

    For additional information, see our guide explaining Chapter 7 and Chapter 13 bankruptcy.

    Should I keep making partial mortgage payments if I can’t afford the full amount, or does that not help?

    This depends on your specific servicer’s policies — some servicers will not accept and simply return partial payments, since they’re not the full contractual amount due, which can actually leave you appearing to have made no payment at all; it’s worth directly asking your servicer how they’d prefer you handle a partial payment situation before assuming it’s automatically helpful.

    A Realistic Timeline Comparison: Judicial vs. Non-Judicial States

    To make the practical difference more concrete: in a typical non-judicial foreclosure state, the process from initial notice of default to an actual foreclosure sale might take roughly 3-6 months, following a specific statutory timeline with defined notice periods. In a judicial foreclosure state, where the lender must file and win a lawsuit, the same process — accounting for court scheduling, potential borrower response and defense, and standard litigation timelines — might take a year or considerably longer. This difference matters enormously for how much time you realistically have to pursue alternatives once formal proceedings begin, which is exactly why identifying which type of process applies in your state early on helps you calibrate your own sense of urgency and timeline for pursuing loss mitigation options.

    What a Notice of Default Should Include, and Why Reading It Carefully Matters

    If you receive a formal Notice of Default, this document typically specifies the exact amount needed to cure the default (reinstate your loan), any applicable deadline for doing so, and often information about foreclosure prevention resources and your right to request a meeting or discussion with the servicer about alternatives. Reading this document carefully — rather than setting it aside out of anxiety, which is an understandable but costly response — gives you the specific facts and deadlines you need to act effectively, including the exact reinstatement amount and timeline, which is often more precise and actionable than general assumptions about your situation.

    How a HUD-Approved Counselor Session Typically Unfolds

    For anyone hesitant about what working with a HUD-approved housing counselor actually involves: a typical session includes a comprehensive review of your income, expenses, and mortgage details, an explanation of which specific loss mitigation options you likely qualify for given your loan type and circumstances, help preparing any documentation your servicer might require, and sometimes direct assistance communicating with your servicer on your behalf or alongside you. This service is genuinely free (funded through HUD, not charged to you), and counselors are specifically trained in foreclosure prevention, making this one of the highest-value, lowest-cost resources available if you’re facing this situation — finding a HUD-approved counselor near you is possible through HUD’s own website or by phone.

    Frequently Asked Questions, Continued

    Does a foreclosure affect only my credit, or does it show up anywhere else beyond my credit report?

    Beyond your credit report, a completed foreclosure is generally part of the public record (since it typically involves a legal filing or recorded document, depending on judicial vs. non-judicial process), meaning it could theoretically be found through a public records search, separate from and in addition to its credit report impact.

    Can I still apply for a HELOC or refinance while behind on my current mortgage?

    Generally, no — most lenders require your existing mortgage to be current to approve a new loan against the same property, meaning refinancing typically isn’t a viable path once you’re already behind, though it may have been a reasonable option to explore earlier, before delinquency began, if you’d anticipated difficulty.

    If my home is foreclosed on, do I get any of the sale proceeds if it sells for more than I owed?

    In most cases, yes — if a foreclosure sale generates proceeds exceeding the total amount owed (principal, interest, fees, and costs), the excess is generally required to be returned to the former homeowner, though the specific process for claiming this varies by state and isn’t always straightforward, sometimes requiring you to actively file a claim rather than receiving it automatically.

    How Property Taxes and Insurance Factor Into Foreclosure Risk

    It’s worth knowing that falling behind on property taxes or homeowners insurance, separate from your actual mortgage payment, can also create serious risk, even if your mortgage payments themselves are current. Many mortgage agreements require you to maintain insurance and stay current on property taxes, and a lapse can trigger the lender to force-place expensive insurance on your behalf (added to your loan balance) or, in the case of significant tax delinquency, potentially even trigger a separate tax lien or tax foreclosure process entirely independent of your mortgage lender. Keeping both of these obligations current, even during a period of mortgage-specific hardship negotiation, protects against this additional layer of risk.

    Frequently Asked Questions, Continued One More Time

    Does a completed foreclosure ever get removed from my credit report early, before the standard seven years?

    Generally, no — like most negative credit items, a foreclosure follows the standard reporting period tied to the original delinquency date, and there’s no standard early-removal mechanism simply based on time passing faster than expected or your subsequent good financial behavior, though disputing any inaccuracy in how it’s reported remains available if genuine errors exist.

    If you believe your credit report contains inaccurate foreclosure-related information, you can learn more about how to dispute credit report errors.

    Is it possible to negotiate a repayment plan that includes both catching up on missed payments and a permanent rate reduction simultaneously?

    Yes, some loan modification programs combine elements of both — addressing past-due amounts while also permanently adjusting terms going forward — though the specific structure available depends heavily on your loan type, investor requirements (for loans backed by Fannie Mae, Freddie Mac, FHA, VA, or USDA specifically), and your servicer’s particular programs, making this worth discussing comprehensively with your servicer or a HUD-approved counselor rather than assuming only one type of solution is available.

    The Bottom Line

    Foreclosure is a formal legal process with distinct stages, and the further along that process you are, the fewer options typically remain available — which is exactly why understanding the process and reaching out to your servicer (and, ideally, a free HUD-approved housing counselor) as early as possible in any payment difficulty gives you access to the widest range of potential solutions: reinstatement, forbearance, modification, or, if keeping the home genuinely isn’t feasible, a short sale or deed in lieu that generally results in less severe consequences than letting the process run its full course to a completed foreclosure sale.

    Need Help Reviewing Your Credit Situation?

    If foreclosure or mortgage hardship has affected your credit report, reviewing your credit history can help you identify inaccurate or potentially disputable information as you work toward financial recovery.

    Request a Credit Audit

  • How to Negotiate With Creditors When You’re Genuinely Struggling

    How to Negotiate With Creditors When You’re Genuinely Struggling

    How to Negotiate With Creditors When You’re Genuinely Struggling? There’s a meaningful difference between negotiating a settlement on old, charged-off debt and negotiating with a creditor while you’re still current, or only slightly behind, but genuinely struggling to keep up. This earlier-stage conversation has its own dynamics, its own available tools, and its own strategic considerations — and getting it right can prevent a temporary hardship from escalating into a much larger, harder-to-resolve problem. This guide focuses specifically on this earlier-stage negotiation.

    Why Timing Matters More Than Almost Anything Else

    The single biggest factor determining your negotiating leverage and options is how early you engage. A creditor is generally far more willing to offer meaningful accommodation to a customer who reaches out before missing a payment, or immediately after a first missed payment, than to one who’s already deep into delinquency or default. Early engagement signals reliability and good faith, and it also means you’re working with the creditor directly rather than a third-party collector or debt buyer with different incentives and less flexibility.

    What to Actually Say When Reaching Out

    Be direct and factual about your situation. “I’m experiencing a temporary financial hardship due to [brief, honest reason — job loss, medical expense, reduced hours] and I want to discuss options before this affects my account status.”

    State what you’re hoping for, even if approximately. “I’m hoping to explore a temporarily reduced payment, a short deferment, or another accommodation that might be available.”

    Ask directly what programs exist, rather than assuming you know your only options. “What hardship programs does your company offer for a situation like mine?”

    The Range of Accommodations Creditors Commonly Offer

    Temporary Payment Reduction

    Temporary payment reduction, often for a defined period (three to six months is common), after which your payment returns to the standard amount.

    Interest Rate Reduction

    Interest rate reduction, sometimes temporary, sometimes for the remainder of the loan, reducing the total cost of carrying the balance even if the payment structure doesn’t dramatically change.

    Deferment or Forbearance

    Deferment or forbearance, pausing payments entirely for a period, though it’s important to understand whether interest continues accruing during this pause, since this affects the total cost.

    Loan Modification

    Loan modification, more substantial restructuring (common with mortgages specifically), potentially extending the loan term or otherwise permanently adjusting terms to make payments more sustainable going forward.

    Fee Waivers

    Fee waivers, less significant individually but worth asking about, particularly late fees that might otherwise accumulate during a difficult stretch.

    What Documentation to Have Ready

    Creditors often require some documentation supporting your hardship claim before approving formal accommodation:

    • Proof of income change — a layoff notice, reduced pay stubs, or similar documentation.
    • Medical documentation, if a health issue is the underlying cause, though detailed medical records typically aren’t required — a general confirmation is often sufficient.
    • A basic budget or hardship letter, outlining your income, essential expenses, and why the requested accommodation would help you remain current going forward.

    Having this ready before you call, rather than scrambling to produce it after being asked, speeds up the process and demonstrates preparedness.

    How to Negotiate Different Types of Creditors

    Mortgage Servicers

    Mortgage servicers often have the most formalized hardship processes, particularly for federally backed loans (FHA, VA, USDA, Fannie Mae, Freddie Mac), which have specific, sometimes mandated forbearance and modification programs. Contact your servicer’s loss mitigation department specifically, rather than general customer service, for the most direct path to these programs.

    Credit Card Issuers

    Credit card issuers vary considerably in their formal hardship program structure, though most major issuers do have some options — asking specifically for their “hardship department” or “financial assistance program” often gets you to the right team faster than general customer service.

    Auto Lenders

    Auto lenders may offer deferment (pushing a missed payment to the end of the loan term) or a temporary modified payment, though flexibility varies more by individual lender than with mortgages, given less standardized federal program involvement.

    Utility Companies

    Utility companies often have their own hardship and payment plan programs, sometimes combined with state or local assistance program eligibility, worth asking about directly if utility payments are part of your broader struggle.

    how-to-negotiate-with-creditors-under-100kb

    What If the Creditor’s Initial Response Isn’t Sufficient?

    Ask if there’s a supervisor or specialized hardship team you can be escalated to, since front-line representatives sometimes have less authority or flexibility than a dedicated hardship or loss mitigation team.

    Consider whether a formal, written hardship request (rather than only a phone conversation) might receive more serious consideration, particularly for larger creditors with formal review processes.

    Explore nonprofit credit counseling if you’re struggling across multiple creditors simultaneously, since a credit counselor can sometimes negotiate more favorable terms across your full financial picture than you might achieve creditor-by-creditor on your own, and can help you develop a comprehensive plan rather than addressing each account in isolation.

    Common Mistakes in This Type of Negotiation

    • Waiting until you’ve already missed several payments before reaching out, which significantly narrows your available options compared to earlier engagement.
    • Not asking specifically about hardship programs, assuming none exist simply because they weren’t offered proactively — many creditors don’t advertise these programs prominently, requiring you to ask directly.
    • Agreeing to an accommodation without fully understanding the terms, particularly whether interest continues accruing during a payment pause, or what happens if your hardship extends beyond the accommodation’s defined period.
    • Not getting the agreed terms in writing, which protects you if any confusion or dispute arises about what was actually agreed to.
    • Feeling too embarrassed to reach out at all, which is an understandable but ultimately costly instinct to give in to — creditors deal with hardship requests constantly and generally aren’t judging you personally; they’re simply processing a routine (if individually significant to you) business request.

    What Happens After Your Accommodation Period Ends

    Have a plan for what happens once a temporary accommodation concludes — if your hardship is genuinely resolved by then, you’d simply resume standard payments. If it’s not fully resolved, proactively reaching back out before the accommodation ends, rather than waiting to see what happens once it expires, gives you the best chance of extending or modifying your arrangement rather than falling back into default status once the temporary measure concludes.

    Frequently Asked Questions

    Does requesting a hardship accommodation appear on my credit report or affect my score?

    Simply requesting or being granted an accommodation generally doesn’t directly harm your score — what matters for your credit is whether you’re actually making the agreed payments under the modified terms, which, if maintained, should continue reporting as current rather than delinquent.

    Can I negotiate hardship terms if I’m not yet behind, just concerned I might fall behind soon?

    Yes, and this is actually the ideal time to reach out — creditors are often most flexible and accommodating for a customer who’s still current but proactively addressing an anticipated difficulty, compared to one who’s already delinquent.

    Is there a limit to how many times I can request a hardship accommodation from the same creditor?

    There’s no universal legal limit, though creditors do have discretion, and a pattern of repeated hardship requests may be viewed differently than a single, isolated one — this varies by creditor and specific program, making it worth understanding your specific creditor’s policy if you anticipate needing this kind of accommodation more than once.

    Should I prioritize which creditors to negotiate with first if I’m struggling across multiple accounts?

    Yes — prioritizing based on consequence severity (as covered in related guides — housing and secured debts generally first, given the more severe consequences of falling behind on these specifically) is a reasonable approach if you need to focus your limited time and energy on the negotiations most likely to prevent the most serious outcomes.

    Is it better to negotiate hardship terms myself, or work with a nonprofit credit counselor from the start?

    Many people successfully negotiate directly, particularly for a single creditor or a straightforward situation — a nonprofit credit counselor becomes more valuable when you’re managing hardship across multiple creditors simultaneously, or when you want professional guidance navigating options you’re not confident evaluating on your own.

    A Complete Sample Hardship Request Letter

    For creditors that accept or prefer written hardship requests, having a template ready streamlines the process:

    [Your Name]
    [Your Address]
    [Date]

    [Creditor Name]
    Re: Account [Number]

    To Whom It May Concern:

    I am writing to request assistance due to a financial hardship. [Brief explanation — e.g., “I was laid off from my position on [date] and am currently seeking new employment while managing reduced income from unemployment benefits.”]

    I have been a customer in good standing since [year/date if known], and I want to remain current on this account. I am requesting information about any hardship programs available, including temporary payment reduction, deferment, or interest rate adjustment.

    I can provide documentation supporting my situation, including [income documentation, layoff notice, etc.], and I’m happy to discuss my situation further by phone.

    Thank you for your consideration.

    Sincerely,
    [Your Name]
    [Account Number]
    [Phone Number]

    Send this via whatever channel the creditor prefers (mail, secure online messaging through your account portal, or as a follow-up after an initial phone call), and keep a copy for your records.

    How Creditors Internally Evaluate Hardship Requests

    Understanding roughly what a creditor’s internal review considers can help you present a stronger request. Most look at: your account tenure and payment history (a longer, cleaner history generally supports more favorable consideration), the nature and apparent temporariness of your hardship (a clearly temporary situation, like a specific medical event or job loss with an active search underway, is often viewed more favorably than an open-ended, unclear situation), and your overall relationship value to the institution (larger balances or additional products with the same institution sometimes receive more attention, simply reflecting the creditor’s own risk exposure). None of these factors are things you can necessarily change quickly, but understanding them helps you present your specific situation in the most relevant, complete light.

    The Difference Between Asking for Help and Asking for Forgiveness

    It’s worth framing this type of negotiation clearly in your own mind: you’re generally asking for temporary accommodation to get through a difficult period while remaining a paying customer, not asking the creditor to forgive or reduce what you ultimately owe (which is a different kind of negotiation, more relevant to already-defaulted debt with a debt buyer, covered in other guides). This framing matters both for how you present your request and for realistically calibrating what’s likely to be offered — creditors are often considerably more willing to adjust timing and short-term terms than to reduce the fundamental amount owed on a current, still-performing account.

    If you are dealing with older collection accounts instead of a current account, see our guide on how to remove collections from your credit report and learn about debt validation letters.

    Frequently Asked Questions, Continued

    Does my credit score itself affect how much flexibility a creditor is willing to offer during hardship negotiation?

    It can be a factor, since a strong existing credit history and payment record on that specific account generally supports a stronger case for accommodation, though creditors also specifically design hardship programs anticipating that people using them are, by definition, going through a difficult period, so a temporarily strained situation doesn’t automatically disqualify you.

    Can I negotiate hardship terms on behalf of an aging parent or family member?

    This is possible but generally requires proper authorization — either being an authorized representative on the account, having power of attorney, or the account holder participating directly in the conversation to provide consent for the creditor to discuss their account details with you.

    Is it worth negotiating hardship terms even for a very small remaining balance?

    Even a small balance is worth addressing if maintaining it in good standing genuinely matters to you (for your credit history, or your ongoing relationship with that specific creditor for future needs), though the time and effort involved should reasonably scale with the stakes involved — a very small balance might not warrant the same intensive negotiation effort as a significant one.

    What to Do If a Creditor’s Hardship Program Feels Insufficient

    Sometimes the accommodation offered genuinely doesn’t fully solve your situation — perhaps the reduced payment is still more than you can manage, or the deferment period is shorter than your anticipated hardship. In this case, it’s worth being honest about this gap during the conversation itself, rather than accepting an insufficient arrangement and risking a second, compounding default shortly after. Asking directly, “Is there anything beyond this that might work better for my situation?” or requesting to explore a different type of accommodation than what was initially offered, keeps the conversation open rather than prematurely closing it around an option that isn’t actually going to work.

    Frequently Asked Questions, Continued One More Time

    Does it help to have a specific end date in mind for my hardship when negotiating, even if I’m not entirely certain?

    Yes, having even an approximate expected timeline (based on your job search progress, a medical recovery timeline, or similar) helps a creditor structure an appropriate accommodation — open-ended requests without any sense of duration can be harder for a creditor to accommodate with a specific, time-bound program.

    Can I negotiate hardship terms over email or written request if I genuinely prefer not to call?

    Many creditors do accept written hardship requests through their online portal, secure messaging, or in some cases traditional mail, as an alternative to a phone call — this is a completely legitimate approach if it better fits your communication preference, though response times may be somewhat slower than a real-time phone conversation.

    The Bottom Line

    Negotiating with creditors while you’re still current, or only recently behind, offers meaningfully more flexibility and better options than negotiating after a debt has been charged off or sold to a collector. Reaching out proactively and early, being direct about your situation, specifically asking what hardship programs exist, and getting any agreed terms in writing are the core principles that consistently improve outcomes in this earlier-stage negotiation — turning what could become a much larger, harder-to-resolve problem into a manageable, temporary accommodation that gets you back to stable footing.

    For additional guidance on protecting and improving your credit during financial hardship, explore our credit repair tips or learn how to fix your credit.

    Need Help Reviewing Your Credit Situation?

    If financial hardship has already resulted in negative or inaccurate information on your credit reports, a professional credit review can help you understand what may need attention.

    Request a Credit Audit

  • Bankruptcy Explained: What Chapter 7 and Chapter 13 Actually Mean

    Bankruptcy Explained: What Chapter 7 and Chapter 13 Actually Mean

    Bankruptcy carries a lot of stigma and misunderstanding, often based on outdated or incomplete information. For the right situation, it’s a legitimate, legally structured tool for resolving overwhelming debt — not a sign of personal failure, but a formal legal process specifically designed to give people a genuine fresh start. Understanding how the two most common types, Chapter 7 and Chapter 13, actually work helps you evaluate whether either might be relevant to your situation and have a more informed conversation with an attorney if you pursue it further.

    The Core Difference Between Chapter 7 and Chapter 13

    Chapter 7, often called “liquidation bankruptcy,” involves selling (liquidating) your non-exempt assets to pay creditors, after which most remaining qualifying debt is discharged (legally eliminated). This process is relatively quick, typically completed within a few months.

    Chapter 13, often called “reorganization bankruptcy,” doesn’t involve liquidating assets in the same way. Instead, you propose a court-supervised repayment plan, typically lasting three to five years, paying back some or all of your debt according to that plan, after which any remaining qualifying debt is discharged.

    Do You Qualify for Chapter 7?

    Chapter 7 eligibility is determined through a means test, comparing your income against your state’s median income for a household of your size. If your income is below the median, you generally qualify for Chapter 7. If it’s above the median, a more detailed calculation (accounting for certain allowed expenses) determines whether you still qualify, or whether you’d instead need to pursue Chapter 13.

    What Happens to Your Assets in Chapter 7

    Not everything you own is automatically sold — federal and state law provide exemptions, protecting certain assets up to specific value limits (which vary by state) from liquidation. Common exemptions often include some equity in your primary home, a vehicle up to a certain value, essential household goods, retirement accounts, and tools of your trade. Assets exceeding these exemption limits, or that don’t qualify for an exemption at all, can be sold by the bankruptcy trustee to pay creditors, though in practice, many Chapter 7 filers have few or no assets exceeding their state’s exemptions, resulting in what’s sometimes called a “no-asset” case, where nothing is actually liquidated.

    If you are also dealing with credit-report problems related to debt, you may want to review our guide on how to read a credit report and learn more about credit report errors.

    What Debt Gets Discharged in Chapter 7

    Most unsecured debt — credit cards, medical bills, personal loans, and old utility bills — is generally dischargeable. Some debt types are generally not dischargeable, including most federal and many private student loans (absent a separate, harder-to-obtain “undue hardship” finding), most tax debt, child support and alimony obligations, and debts arising from fraud or certain willful misconduct.

    How Chapter 13 Works in Practice

    You propose a repayment plan, based on your income and expenses, which must be approved by the bankruptcy court. This plan typically requires paying certain “priority” debts (like recent tax debt) in full, while other unsecured debt might be paid back partially or, in some cases, very minimally, depending on your specific financial circumstances and what the plan calls for.

    You make plan payments for three to five years, generally through a court-appointed trustee who distributes the funds to your creditors according to the approved plan.

    Once the plan is successfully completed, any remaining qualifying unsecured debt covered by the plan is discharged, similar to Chapter 7, though the process to get there is considerably longer.

    Why Someone Might Choose Chapter 13 Over Chapter 7 (Even If They’d Qualify for Chapter 7)

    To catch up on and keep a house or car that’s in danger of foreclosure or repossession. Chapter 13 allows you to include past-due secured debt payments in your repayment plan, potentially letting you keep property that might otherwise be lost through a Chapter 7 liquidation process or continued default outside of bankruptcy.

    To protect non-exempt assets that would otherwise need to be liquidated under Chapter 7, since Chapter 13 doesn’t involve the same liquidation process.

    Because they don’t qualify for Chapter 7 based on the means test, making Chapter 13 the only available bankruptcy path for their situation.

    The Automatic Stay: An Immediate Benefit of Filing Either Type

    The moment you file for either Chapter 7 or Chapter 13, an automatic stay takes effect, immediately halting most collection activity — including lawsuits, wage garnishment, and collection calls — while your bankruptcy case proceeds. This immediate relief is often one of the most significant practical benefits of filing, providing breathing room from active or threatened collection actions right away, even before the ultimate discharge is determined.

    If collection activity is affecting your credit situation, you can also learn about collection agency harassment and FDCPA protections and the cease and desist process for debt collectors.

    The Impact on Your Credit

    Both types of bankruptcy appear on your credit report as a serious negative item — Chapter 7 for up to 10 years from the filing date, Chapter 13 for up to 7 years, reflecting the different processes involved. This is a significant, long-lasting credit impact, though many people who file bankruptcy were already experiencing serious credit damage from the underlying debt situation that led them to consider bankruptcy in the first place, meaning the actual marginal impact is sometimes less dramatic than the “10 years” figure might suggest in isolation.

    Rebuilding Credit After Bankruptcy

    Contrary to some assumptions, credit rebuilding after bankruptcy can begin relatively quickly, sometimes even during a Chapter 13 repayment period. Secured credit cards, credit-builder loans, and consistent on-time payment on any remaining or new obligations can meaningfully rebuild your score over time, and many people see a genuinely good credit score within two to four years post-discharge, particularly since bankruptcy itself, once filed, removes the ongoing negative reporting from all the individual accounts that led to it, replacing many separate negative marks with one (admittedly serious) bankruptcy notation.

    For additional guidance, see our guide on how to improve your credit score and our practical credit repair tips.

    The Process of Actually Filing

    Credit Counseling Requirement

    Before filing, you’re generally required to complete credit counseling from an approved agency, which reviews your financial situation and alternatives to bankruptcy.

    Filing the Petition and Required Documentation

    Filing the petition and required documentation, including detailed financial disclosures, generally with an attorney’s assistance, though self-representation (“pro se”) is technically possible, if not commonly advisable given the complexity involved.

    The Meeting of Creditors

    The meeting of creditors (“341 meeting”), a relatively brief, generally straightforward hearing where the trustee (and potentially creditors, though they rarely attend in practice) can ask questions about your financial situation.

    Completion of the Second Required Course

    Completion of a second required course, a debtor education course, before your discharge is finalized.

    Discharge

    Discharge, the formal legal order eliminating your qualifying debt, typically issued within a few months for Chapter 7, or at the successful completion of your repayment plan for Chapter 13.

    Common Misconceptions About Bankruptcy

    “Bankruptcy erases all debt.”

    As covered above, several categories of debt generally aren’t dischargeable, including most student loans, recent taxes, and child support.

    “You lose everything you own.”

    Exemptions protect meaningful assets in most cases, and many Chapter 7 filers retain everything they own, particularly if their assets are modest relative to their state’s exemption limits.

    “Bankruptcy means you’ll never get credit again.”

    As covered above, credit rebuilding, while requiring deliberate effort, is genuinely achievable within a few years for most people who file.

    “Filing is simple enough to always do without an attorney.”

    While technically possible, the complexity of exemptions, means testing, and procedural requirements makes attorney guidance genuinely valuable for most people, and many bankruptcy attorneys offer free initial consultations specifically to help you understand whether bankruptcy makes sense for your situation before committing to the cost of filing.

    Frequently Asked Questions

    How much does it cost to file for bankruptcy?

    Court filing fees are a few hundred dollars (varying slightly by district), and attorney fees vary considerably by location and case complexity, though many bankruptcy attorneys offer payment plans, and fee waivers for the court filing fee itself are sometimes available for very low-income filers.

    Can I file for bankruptcy more than once in my lifetime?

    Yes, though there are specific waiting periods between filings and between different chapter types (for example, a waiting period before you can receive another Chapter 7 discharge after a previous one), which an attorney can clarify based on your specific prior filing history if relevant.

    Will everyone find out I filed for bankruptcy?

    Bankruptcy filings are part of the public record, technically searchable, though in practice, most people don’t actively search public bankruptcy records, and your employer generally wouldn’t be notified directly unless a specific circumstance (like wage garnishment being addressed through the case) required their involvement.

    Does bankruptcy affect a spouse who didn’t file, if we have joint debts?

    If you file individually while married, your spouse’s own credit and individual liability aren’t directly affected by your filing, except for any jointly held debts, where their liability for that specific joint debt generally remains intact even if your portion is discharged through your individual bankruptcy.

    Is there a difference in how bankruptcy affects a home you own versus rent?

    Homeownership introduces more complexity, particularly around whether you want to keep the home (relevant to the Chapter 7 vs. 13 decision and exemption planning) — renters generally have simpler considerations, primarily around whether any past-due rent or a related judgment is part of the dischargeable debt being addressed.

    A Side-by-Side Comparison

    Category Chapter 7 Chapter 13
    Basic structure Liquidation of non-exempt assets 3-5 year repayment plan
    Typical duration A few months 3-5 years
    Eligibility Means test based on income Available to those with regular income, including those who don’t qualify for Chapter 7
    Best for Limited non-exempt assets, no property to save from foreclosure Behind on mortgage/car payments you want to keep, or don’t qualify for Chapter 7
    Credit report duration Up to 10 years Up to 7 years
    Discharge timing Relatively soon after filing Only after completing the full repayment plan

    This comparison highlights why the “right” choice depends heavily on your specific circumstances rather than one option being universally better — someone with few assets and no property at risk of foreclosure often finds Chapter 7 the more efficient path, while someone specifically trying to catch up on a mortgage or car loan to avoid losing that property often needs Chapter 13’s structure to accomplish that goal.

    bankruptcy-explained-chapter-7-vs-13-under-100kb

    What “Non-Exempt Assets” Actually Looks Like in Practice

    Since the concept of exemptions can feel abstract, a concrete example helps. Imagine you own a car worth $8,000, and your state’s motor vehicle exemption protects up to $5,000 in vehicle equity. If you own the car outright (no loan), you’d have $3,000 in non-exempt equity — the trustee could potentially require you to either pay the trustee $3,000 (sometimes called “buying back” the non-exempt equity) or, in some cases, the car could be sold with you receiving your exempt portion back. In practice, many filers work with their attorney specifically to plan around these thresholds, sometimes timing a filing or making certain decisions in advance to minimize non-exempt exposure, which is exactly the kind of strategic planning a bankruptcy attorney’s specific knowledge of your state’s exemptions genuinely adds value to.

    How the Means Test Actually Works

    The means test isn’t simply “is your income below the median” — for filers above the median, a more detailed calculation follows, subtracting IRS-standardized allowed expenses (and some actual expenses) from your income to determine your “disposable income.” If this calculation shows insufficient disposable income to meaningfully repay creditors, you may still qualify for Chapter 7 despite an above-median income; if it shows you do have meaningful repayment capacity, you’d generally need to pursue Chapter 13 instead. This calculation involves enough nuance and specific IRS-standardized figures that working through it with an attorney, rather than attempting it entirely independently, is generally advisable for anyone whose income is close to or above their state’s median.

    Frequently Asked Questions, Continued

    Can I choose Chapter 13 even if I’d qualify for the faster Chapter 7 process?

    Yes — the means test determines Chapter 7 eligibility, but choosing Chapter 13 instead, even when you qualify for Chapter 7, remains an available choice, commonly made specifically to protect property from foreclosure or repossession, as discussed above.

    What happens if I can’t keep up with my Chapter 13 payment plan partway through?

    Depending on the specific circumstances, options can include modifying the plan (if your income has genuinely changed), converting to Chapter 7 if you now qualify, or in some cases, the case being dismissed if payments aren’t maintained and no alternative arrangement is reached — this is exactly the kind of situation where staying in close communication with your bankruptcy attorney throughout the plan’s multi-year duration matters considerably.

    Does bankruptcy discharge debt owed to family members or friends the same as debt owed to a bank?

    Generally, yes, informal personal loans from family or friends can be discharged the same as other unsecured debt, assuming they don’t fall into a specific non-dischargeable category, though the personal and relational dimension of this kind of debt is obviously a separate, non-legal consideration worth thinking through as well.

    The Role of the Bankruptcy Trustee

    In both chapters, a trustee is appointed to oversee your case, though their role differs between the two. In Chapter 7, the trustee’s primary job is reviewing your assets for anything non-exempt that could be liquidated to pay creditors, and reviewing your filing for accuracy and completeness. In Chapter 13, the trustee’s role is more ongoing — collecting your monthly plan payments and distributing them to creditors according to your approved plan throughout the multi-year repayment period, essentially administering the plan from start to finish.

    Frequently Asked Questions, Continued One More Time

    Can creditors object to my bankruptcy filing or proposed Chapter 13 plan?

    Yes — creditors have the right to object to certain aspects of a case, such as disputing whether a specific debt should be discharged (particularly for debts alleged to involve fraud), or objecting to a Chapter 13 plan’s terms if they believe it doesn’t adequately account for your actual income and ability to pay; these objections are resolved through the bankruptcy court process, often with your attorney representing your position.

    Does filing bankruptcy affect a professional license or security clearance?

    This varies by profession and the specific licensing or clearance body’s own rules — some professions have reporting requirements or review processes triggered by a bankruptcy filing, making this worth researching specifically for your field or discussing with your bankruptcy attorney if you hold a professional license or security clearance that might be affected.

    The Bottom Line

    Chapter 7 and Chapter 13 bankruptcy serve different purposes: Chapter 7 offers a faster process built around liquidating non-exempt assets (often minimal or none in practice) to discharge qualifying debt, while Chapter 13 offers a structured, multi-year repayment plan, often chosen specifically to protect property like a home or car from foreclosure or repossession. Both provide immediate relief from collection activity through the automatic stay upon filing, and both carry significant but not permanent credit consequences, with genuine rebuilding achievable within a few years for most filers. Given the complexity involved — means testing, exemptions, and which specific debts qualify for discharge — consulting a bankruptcy attorney, often through a free initial consultation, is a valuable step in understanding whether either path makes sense for your specific financial situation.

    Need Help Understanding Your Credit Situation?

    Bankruptcy can address qualifying debt, but understanding what remains on your credit reports and identifying inaccurate information can still be an important part of your financial recovery. If you’re dealing with credit-report issues, consider getting a professional review of your situation.

    Request a Credit Audit