Author: admin

  • Best Credit Monitoring Services in 2026 (Free and Paid)

    Best Credit Monitoring Services in 2026 (Free and Paid)

    If you have ever checked your credit score, exhaled, and then wondered whether it would still look that way next month, you already understand the case for credit monitoring. Your credit report is not a static document. It moves. Accounts open and close, balances rise and fall, inquiries appear, and — sometimes — something lands on your file that you never authorized. A credit monitoring service is how you keep eyes on all of that without having to manually pull your report every week.

    This guide breaks down what credit monitoring actually does, how free and paid services compare, why 3-bureau coverage matters more than most people realize, and how to choose a service (or combination of services) that fits your life and your goals. We will keep it honest: for many people, a well-built free setup is more than enough. For others — especially anyone actively repairing their credit or recovering from identity theft — a paid service earns its keep. We will help you tell the difference.

    Whether you are just starting to pay attention to your credit or you are deep into a repair plan and want to track every point of progress, this is the framework you need.

    What Is Credit Monitoring, Really?

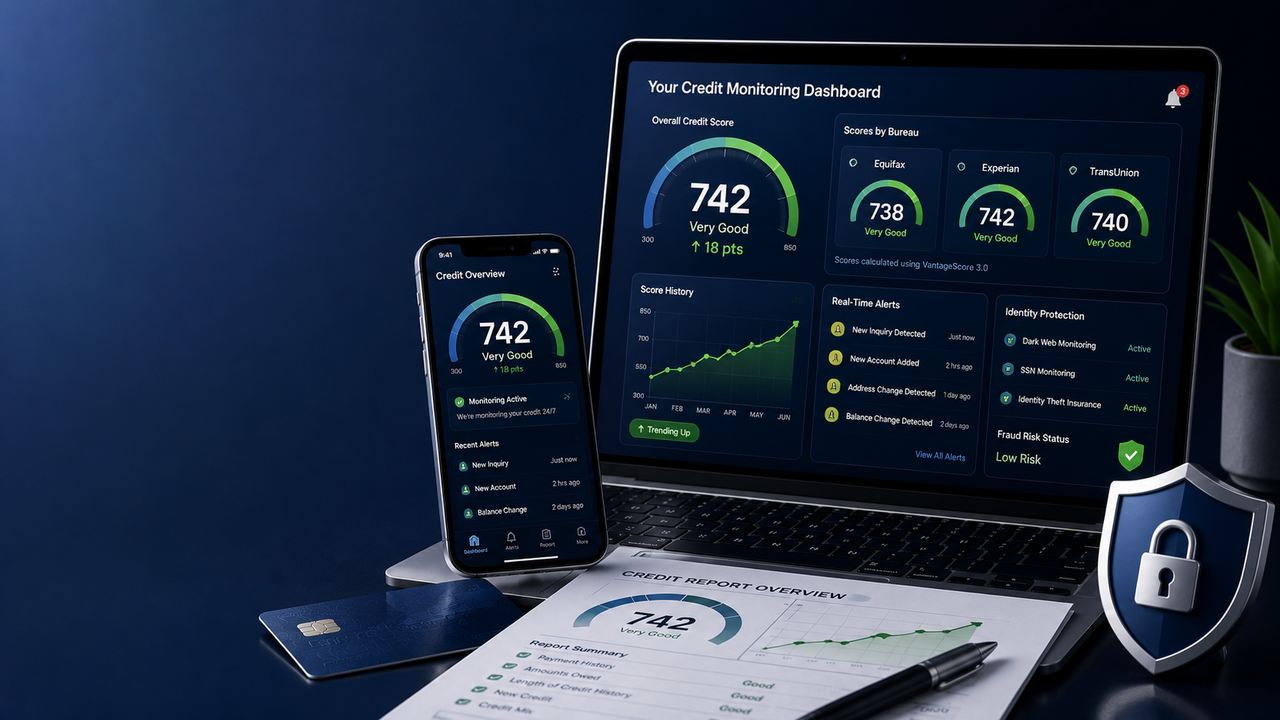
    Credit monitoring is the ongoing, automated tracking of your credit reports and credit scores across one or more of the three major credit bureaus — Equifax, Experian, and TransUnion. Instead of pulling your report manually once a year and hoping nothing changes in between, a monitoring service watches your file for you and tells you when something happens.

    Think of it as a motion detector for your credit profile. The moment a new account opens, a balance jumps, an address changes, an inquiry hits, or a late payment gets reported, the service sends you an alert. Some services also track your credit score over time so you can see the trend — up, down, or flat — and connect those movements to real events in your financial life.

    Here is the important distinction that gets lost in a lot of marketing copy: credit monitoring is not credit repair, and it is not identity theft prevention.

    Monitoring does not stop someone from opening an account in your name. It tells you, quickly, that it happened. That early warning is valuable — incredibly valuable — but it is a detection tool, not a lock. (A credit freeze is the lock. We will come back to that.)

    What monitoring does do well:

    • Detects unauthorized activity early, often within 24 hours of it appearing on your report.
    • Tracks your progress when you are actively building or repairing credit, so you can see whether your efforts are moving the needle.
    • Surfaces reporting errors — accounts that are not yours, payments marked late that were actually on time, balances that are wrong — so you can dispute them before they do more damage.
    • Keeps you informed about changes that are legitimate but still matter, like a credit card balance increase that drops your score, or a closed account that shortens your credit history.

    In short, credit monitoring turns your credit report from something you check into something that checks in with you. That shift — from reactive to proactive — is the whole point.

    Internal link placeholder: [What Is a Credit Report?] — a beginner explainer on what’s actually inside your three bureau reports.

    Why Credit Monitoring Matters: Three Core Benefits

    Let’s look more closely at the three reasons most people sign up for monitoring, and why each one matters for your financial life.

    1. Early Fraud Detection

    This is the headline benefit, and it deserves the attention. When a fraudster opens a credit card, takes out a loan, or applies for utilities in your name, that activity eventually lands on your credit report at one (or more) of the three bureaus. Without monitoring, you might not find out until months later — when a collection notice arrives, when you are denied credit, or when you pull your annual report and see accounts you do not recognize.

    By then, the damage can be significant: multiple fraudulent accounts, tanked scores, collections, and hours of paperwork to unwind it all.

    With monitoring, you can get an alert within a day of a new account or hard inquiry appearing on your report. That gives you a window to act fast — contact the creditor, place a fraud alert, freeze your credit, and file an identity theft report with the FTC at IdentityTheft.gov — before the fraud compounds.

    The math is simple: the sooner you know, the less there is to clean up.

    2. Tracking Your Progress

    If you are working to build credit for the first time, or rebuild it after a setback, monitoring gives you something rare in the credit world: visible, measurable feedback. You pay down a credit card, and a week or two later your score ticks up. You add an authorized-user tradeline, and you watch the effect. You let a balance creep back up, and you see the dip.

    This is not vanity. Tracking your score over time is how you learn which behaviors actually move your number — and which do not. It is how you confirm that a dispute you filed actually resulted in a negative mark being removed. It is how you stay motivated when the process feels slow, because credit repair is rarely a straight line.

    A good monitoring service will show you a score history chart and, ideally, flag the events that correspond to each change. That context is what turns a number into insight.

    3. Spotting Reporting Errors

    Here is a fact that surprises a lot of people: a meaningful share of credit reports contain errors. The Federal Trade Commission has studied this repeatedly over the years, and the findings have been consistent — mistakes happen. Accounts get mixed up between consumers with similar names. Payments get misreported as late. Paid-off balances linger as “open.” Closed accounts stay listed as active. Collection accounts get re-aged to look newer than they are.

    Some of these errors are minor. Some can cost you dozens of points, a better interest rate, or an approval altogether. Monitoring surfaces these discrepancies early, while they are still small problems — before you are sitting in a lender’s office wondering why your score is 40 points lower than you thought.

    When you spot an error through monitoring, your next step is a dispute — with the bureau that is reporting it and, often, with the furnisher (the creditor or collector that sent the information). That is a process with its own rules under the Fair Credit Reporting Act (FCRA), and it is exactly the kind of work a credit repair firm can help you navigate.

    Internal link placeholder: [How to Dispute Credit Report Errors Under the FCRA] — step-by-step dispute guide.

    Free vs. Paid Credit Monitoring: The Real Difference

    The credit monitoring market splits cleanly into two tiers: free and paid. Understanding what you get — and what you give up — at each tier is the foundation of choosing well.

    What Free Monitoring Gives You

    Free credit monitoring has gotten genuinely good. A decade ago, “free” mostly meant a gimmick — a trial that rolled into a monthly charge. Today, several major services offer legitimately free, ongoing monitoring with no credit card required. Here is what the best free options typically include:

    • Monitoring of one bureau’s report (usually TransUnion or Experian, depending on the service) with alerts when key changes hit.
    • A credit score, updated regularly — often weekly, sometimes daily. The score may be a VantageScore rather than a FICO score, and it may come from only one bureau.
    • Basic identity monitoring — alerts if your email, phone number, or other personal info shows up in places it should not, like data breach dumps.
    • Educational tools — simulators, tips, and recommendations tailored to your profile.

    For a lot of people, that is enough. If your credit is stable, you do not have high fraud risk, and you just want to know if something unexpected happens, free monitoring does the job.

    What Free Monitoring Usually Lacks

    • Only one bureau is monitored. This is the big one. If a fraudulent account gets reported to Experian but your free service only watches TransUnion, you will not get an alert. We will dig into why this matters in the next section.
    • No or limited identity theft insurance. If you are the victim of identity theft, a paid service might cover up to $1 million in expenses (legal fees, lost wages, stolen funds). Free services rarely offer this.
    • No dedicated restoration help. Recovering from identity theft is paperwork-intensive and frustrating. Paid services often include a specialist who guides you through it. Free services point you to resources and leave you to do the walking.
    • Score models and refresh frequency may be limited. You might see a VantageScore from one bureau updated weekly, rather than FICO scores from all three updated daily.

    What Paid Monitoring Adds

    Paid services — typically $15 to $40 per month depending on features and family coverage — layer on the things free services leave out:

    • 3-bureau monitoring with alerts from all three bureaus, often with daily refreshes.
    • Identity theft insurance, usually ranging from $500,000 to $1 million in coverage.
    • Identity restoration assistance, including a dedicated case manager.
    • Dark web monitoring that scans for your Social Security number, email, passport, and other sensitive data being traded or sold.
    • Family or child monitoring plans that cover minors, who are frequent targets of identity theft because no one is checking their credit.
    • More frequent score updates and, often, access to FICO scores from all three bureaus (the scores most lenders actually use).

    The question is not whether paid services offer more — they clearly do. The question is whether you need the extra coverage. We will get to a framework for answering that a few sections down.

    Single-Bureau vs. 3-Bureau Monitoring

    This is the single most important technical distinction in credit monitoring, and it is the one most people get wrong when they sign up for a free service and assume they are covered.

    The Three-Bureau Reality

    Your credit life is not managed by one company. Three independent, competing credit bureaus — Equifax, Experian, and TransUnion — each maintain their own version of your credit report. Lenders and creditors choose which bureau(s) to report to, and they do not all report to all three. Some report to only one. Some report to two. Some report to all three.

    The result is that your three reports are not identical. A credit card account might appear on your Equifax and Experian reports but not your TransUnion report. A collection account might show up at only one bureau. A hard inquiry from a recent credit application might land at just one or two.

    This means that if your monitoring service is watching only one bureau, you are seeing only a slice of your credit picture — typically about a third of it, give or take. A fraudster who opens an account that gets reported to a bureau you are not monitoring will fly completely under your radar. You will feel safe because you have monitoring, but you will not actually be covered.

    Why 3-Bureau Monitoring Is Stronger

    3-bureau credit monitoring watches all three of your reports simultaneously. When a new account, inquiry, address change, public record, or other key item appears on any of your three files, you get an alert. That is meaningfully different protection, and for anyone with elevated fraud risk, it is the floor we would recommend — not the ceiling.

    Here is a way to think about it: single-bureau monitoring is like a security camera on your front door. It is better than nothing, and it might catch a problem. 3-bureau monitoring is like cameras on every entrance. You still are not invulnerable, but you are not blind to two-thirds of the possible entry points either.

    Does Everyone Need 3-Bureau Monitoring?

    No. And we want to be straight with you about that, because a lot of paid services will tell you otherwise.

    If your credit is stable, your fraud risk is average, and you are using monitoring as a basic early-warning system, a free single-bureau service combined with a credit freeze at all three bureaus gives you solid protection for zero monthly cost. The freeze blocks new accounts from being opened in your name (the thing monitoring cannot do), and the single-bureau monitor gives you a reasonable heads-up if something changes on that one report.

    Where 3-bureau monitoring clearly wins:

    • You are at higher risk of identity theft — you have been in a data breach, your wallet or Social Security number was lost or stolen, or you have already been a victim.
    • You are actively repairing your credit and you want to see disputes resolve across all three bureaus, not just one.
    • You are about to make a major purchase (home, car) and you need a complete, accurate view of what every lender will see.
    • You want peace of mind and the monthly cost is not a financial strain.

    For everyone else, the free-plus-freeze approach is a genuinely smart, frugal setup. Do not let anyone — including us — talk you into a monthly bill you do not need.

    Internal link placeholder: [Credit Freeze vs. Credit Lock: Which Protects You Better?] — comparison guide.

    What a Good Credit Monitoring Service Includes

    Whether you are comparing free options or weighing a paid service, here are the features that separate a useful monitoring product from a marketing wrapper. Not every service will have all of these, and that is fine — but you should know what you are getting and what you are not.

    1. Real-Time (or Near Real-Time) Alerts

    The value of monitoring drops sharply if you find out about a fraudulent account two weeks after it appears. A good service sends alerts within 24 hours of a change hitting your report — and ideally faster for high-severity events like new accounts or hard inquiries. Look for services that offer push notifications or email alerts, not just a dashboard you have to remember to check.

    2. 3-Bureau Coverage

    As we just covered, monitoring all three bureaus gives you a complete view instead of a partial one. For paid services, 3-bureau coverage should be table stakes. For free services, it is the main feature you are trading away.

    3. Score Tracking Over Time

    A single score snapshot is interesting. A score history is useful. You want to see the trend line — is your score trending up, down, or sideways — and ideally, annotations that show what events correspond to each change (a new account, a late payment, a dispute resolution). This is the feature that turns monitoring from a fraud detector into a progress tracker.

    Pay attention to which score model the service provides. FICO scores are used by the vast majority of lenders. VantageScore is a competing model that is useful for tracking trends but may not match the number a lender pulls. Both have their place, but if you are preparing for a major application, FICO is the one that matters.

    4. Report Refresh Frequency

    How often does the service pull fresh data from the bureaus? Daily pulls are the gold standard. Weekly is solid for most people. Monthly is the bare minimum and, frankly, borderline for fraud detection. A service that refreshes your score daily but your full report only monthly is telling you about some changes quickly and others slowly — know which is which.

    5. Dark Web and Identity Monitoring

    Beyond your credit report, the best services scan the dark web, data breach databases, and public records for your personal information — your Social Security number, email addresses, phone numbers, passport number, driver’s license, and more. If your data shows up somewhere it should not, you get an alert. This is often the earliest signal that you have been compromised, sometimes before any credit fraud has occurred.

    6. Identity Theft Insurance

    If the worst happens, insurance helps cover the costs of recovery — legal fees, lost wages while you sort it out, fraudulent fund reimbursement, and sometimes the cost of re-filing taxes. Look for coverage of at least $500,000, and read the fine print on what is actually covered and what the deductibles are.

    7. Restoration Help

    This is the human feature that is easy to overlook until you need it. Identity restoration assistance means a dedicated specialist walks you through the recovery process: contacting creditors, placing fraud alerts, filing FTC reports, disputing fraudulent accounts, and handling the paperwork. After identity theft, this is the difference between a guided path and a maze.

    8. Family and Child Coverage

    Children are frequent identity theft targets because their credit files are clean and no one is checking them. A family plan that covers your children (and sometimes other household members) adds a layer of protection that individual plans miss. If you have kids, this is worth specifically looking for.

    The Best Free Credit Monitoring Options in 2026

    Let’s walk through the strongest free options and be clear about what each one does well — and where each one falls short. We are describing categories and tools rather than pushing you toward any specific paid upgrade, because for a lot of people the free tier is the right answer.

    Credit Karma

    Credit Karma is probably the most widely used free credit monitoring service, and for good reason. It offers:

    • Free credit scores and reports from TransUnion and Equifax, updated weekly.
    • VantageScore 3.0 scores from both bureaus.
    • Credit monitoring alerts when key changes hit your TransUnion or Equifax file.
    • A credit score simulator that lets you model the impact of actions like paying down debt or opening a new card.
    • Basic identity monitoring that alerts you if your info appears in breach databases.

    What it does well: Two-bureau coverage (better than most free services), a clean interface, genuinely useful educational tools, and no credit card required.

    Where it falls short: No Experian coverage. VantageScore rather than FICO. No identity theft insurance or restoration help. The interface is ad-supported, and Credit Karma makes money by recommending credit products — so take the “recommended for you” cards with a grain of salt.

    Experian Free Membership

    Experian offers a free tier that includes:

    • Your Experian credit report and a FICO Score 8, updated periodically.
    • Experian Boost, which lets you get credit for on-time utility, telecom, and streaming payments that normally would not count toward your score.
    • Monitoring of your Experian file with alerts on key changes.
    • Dark web scan of your email.

    What it does well: Gives you a FICO score (the one lenders actually use), not a VantageScore. Experian Boost can genuinely help people with thin credit files. The dark web scan is a nice free addition.

    Where it falls short: Only one bureau (Experian). The free tier is, predictably, a lead-in to Experian’s paid CreditWorks product. Limited score refresh frequency compared to the paid version.

    Discover Credit Scorecard

    Discover’s free offering is open to everyone — you do not need to be a Discover customer. It provides:

    • A FICO Score 8 based on your Experian credit report.
    • Score history so you can see the trend.
    • Alerts when something on your Experian report changes.

    What it does well: A clean, simple FICO score from Experian. No ads, no hard sell. Good for people who want a straightforward number and alerts without a dashboard full of credit card recommendations.

    Where it falls short: Single bureau (Experian). Limited features compared to Credit Karma or Experian’s full free tier. Not a full monitoring solution on its own, but a good complement.

    Bank and Credit Card Issuer FICO Scores

    Many major banks and credit card issuers now include a free FICO score in their app or online dashboard — often updated monthly. Common examples include issuers that provide FICO Score 8 (or a bankcard-specific FICO variant) based on one bureau’s data.

    What this does well: It is the score from the institution you already use, so you see the same number your lender sees when you log in. No separate app to manage.

    Where it falls short: Monthly refresh is too slow for fraud detection. Single bureau. No monitoring alerts — just a score snapshot. Use this as a supplement, not your primary monitoring.

    AnnualCreditReport.com — The Foundation

    This is not a monitoring service, but it belongs in every credit-conscious person’s toolkit. AnnualCreditReport.com is the official, federally authorized site where you can get free copies of your full credit reports from all three bureaus.

    Historically you were entitled to one free report from each bureau per year. In recent years, the bureaus have made weekly access available — meaning you can pull your full reports from all three bureaus, for free, far more often than annually. This is the place to get your actual full reports (not just summaries), which is what you need if you are disputing errors or want to see everything that is on file.

    What it does well: The only authorized source for your full, free reports from all three bureaus. No scores, no fluff — just the raw reports.

    Where it falls short: No monitoring, no alerts, no scores. You have to pull the reports yourself. But paired with a free monitoring service, it gives you the depth the monitoring service lacks.
    best-credit-monitoring-services-2026-under-100kb

    A Strong Free Setup

    If you want genuinely good protection at zero monthly cost, here is a combination that works:

    1. Credit Karma for TransUnion + Equifax monitoring alerts and weekly scores.
    2. Experian’s free tier for Experian monitoring, a FICO score, and Experian Boost.
    3. AnnualCreditReport.com to pull your full reports from all three bureaus regularly — every few months, or anytime you are about to dispute something.
    4. A credit freeze at all three bureaus to block new-account fraud — the one thing monitoring cannot do.

    That stack gives you alerts from all three bureaus, a mix of VantageScore and FICO, full report access, and a lock on new account openings — all for free. For many people, that is the right answer, and there is no shame in it.

    How to Evaluate Any Credit Monitoring Service

    Whether you are looking at a free service, a paid service, or trying to compare two side by side, here is a framework you can use to cut through the marketing and see what you are actually getting.

    The Evaluation Table

    Feature Why It Matters Free Tier Paid Tier
    Bureau coverage Determines how much of your credit picture you can see. One bureau = partial; three = complete. Usually 1–2 bureaus All 3 bureaus
    Refresh frequency How fast you learn about changes. Daily is best; monthly is the floor. Weekly to monthly Daily
    Alert types New accounts, inquiries, address changes, public records, late payments, balance changes — the more, the better. Key changes only Comprehensive
    Score model FICO is what most lenders use; VantageScore is useful for trend tracking but may differ from lender pulls. Often VantageScore Usually FICO
    Score history Lets you see trends and connect events to score changes — critical for progress tracking. Often included Included
    Dark web / identity monitoring Early warning that your personal info is compromised, often before credit fraud occurs. Basic or none Comprehensive
    Identity theft insurance Covers recovery costs — legal fees, lost wages, stolen funds — if the worst happens. Rarely included $500K–$1M typical
    Restoration help A specialist who guides you through recovery from identity theft. Enormous peace of mind. Not included Included
    Family / child coverage Protects minors and household members, who are often overlooked targets. Not included Often available
    Price The bottom line. Know what you are paying and whether the features justify it for your situation. $0 $15–$40/mo

    Questions to Ask Before You Sign Up

    Beyond the table, ask yourself:

    • What am I actually trying to protect against? Fraud? Errors? Tracking repair progress? Your answer changes what matters.
    • Is my fraud risk elevated? If yes, 3-bureau daily monitoring and insurance are worth more. If no, free plus a freeze is plenty.
    • Am I about to apply for a major loan? If yes, you want FICO scores from all three bureaus and full reports, not just VantageScore from one.
    • Do I have kids? If yes, look for family plans with child monitoring.
    • Will I actually use the alerts? Monitoring only works if you read the alerts and act on them.

    Do You Actually Need Paid Credit Monitoring?

    This is where a lot of articles get vague. We are going to be direct, because that is what a trusted advisor should do.

    Most People Are Fine With Free Monitoring Plus a Credit Freeze

    If you are an average consumer — stable credit, no recent identity theft, no elevated fraud exposure, no major purchase on the immediate horizon — a free monitoring setup combined with a credit freeze at all three bureaus is more than enough.

    The freeze does the heavy lifting on prevention (it blocks new accounts from being opened in your name), and the free monitoring gives you a reasonable early-warning system for changes on your report. You can always pull your full reports from AnnualCreditReport.com for depth when you need it.

    This is not a compromise or a “starter” setup. It is a genuinely strong, financially smart protection plan that costs you nothing.

    Paid Monitoring Makes Sense When

    • You have been a victim of identity theft. After the first time, your risk of being targeted again is elevated. The insurance and restoration help alone justify the cost.
    • Your personal data has been exposed in a major breach involving your Social Security number, and you want active 3-bureau daily monitoring while you assess the damage.
    • You are actively repairing your credit and you want to see disputes resolve across all three bureaus in near real time, not just one.
    • You are preparing for a major purchase (mortgage, auto loan) in the next 6–12 months and you need accurate FICO scores from all three bureaus, plus alerts on anything that could move your number.
    • You have children and want to monitor their credit files for fraudulent activity.
    • You run a business, have a public profile, or are otherwise a higher-value target for identity thieves.
    • You simply value the peace of mind and can comfortably afford the monthly cost. That is a legitimate reason. Peace of mind has value.

    Paid Monitoring Is Probably Overkill If

    • Your credit is stable and you are not actively working on it.
    • You have no recent fraud history and no elevated risk.
    • A $20–$40 monthly bill would create financial pressure.
    • You already have a freeze in place and check your reports periodically.
    • You are signing up out of fear after seeing an ad, not because you have assessed your actual risk.

    If any of those describe you, start with the free setup described earlier. You can always upgrade later if your situation changes. The free options are not a trap — they are genuinely useful, and for most people they are the right long-term answer.

    How Credit Monitoring Fits Into a Credit Repair Plan

    If you are working on repairing your credit — whether on your own or with help from a firm like ours — credit monitoring is not optional. It is how you know whether the work is working.

    Here is how monitoring fits into each phase of a typical credit repair plan.

    Phase 1: The Audit

    Before any disputes are filed, you (or your credit repair team) need a complete picture of what is on all three of your reports. AnnualCreditReport.com gives you the full reports. A monitoring service — especially one with 3-bureau coverage — gives you the ongoing view as the plan unfolds.

    At this stage, monitoring establishes your baseline: your starting scores at each bureau, the negative items that are dragging them down, and the positive items that are keeping them afloat. Everything from here forward is measured against that baseline.

    Phase 2: Disputes and Interventions

    Under the FCRA, you have the right to dispute any information on your credit report that is inaccurate, incomplete, or unverifiable. When you (or your credit repair firm) file a dispute, the bureau has typically 30 days to investigate and respond. If the disputed item cannot be verified, it must be removed or corrected.

    Monitoring tells you the moment that removal or correction hits your report. You do not have to wonder whether the dispute worked. You see the score change, you see the item disappear, and you can confirm that all three bureaus updated — not just the one you disputed with. This matters because disputes do not always propagate across all three bureaus automatically. If an item is removed at TransUnion but still shows at Experian, monitoring is how you catch it.

    Phase 3: Building and Rebuilding

    Repair is only half the work. The other half is building positive credit history — new accounts, on-time payments, low utilization, responsible account aging. Monitoring tracks the impact of each of those moves in real time. You see a new tradeline report. You see your utilization drop as you pay down balances. You see your score climb as on-time payments accumulate.

    This feedback loop is what keeps the rebuilding phase on track. Without it, you are making good decisions in the dark, hoping they add up. With it, you can see what is working and adjust what is not.

    Phase 4: Long-Term Maintenance

    Once your credit is where you want it, monitoring becomes your early-warning system. A surprise late payment, a fraudulent account, a reporting error — any of these can undo months of work. Monitoring catches them while they are still small, so you can address them before they become big.

    This is also where a credit freeze becomes your long-term preventive tool. Freeze your credit at all three bureaus, keep monitoring in place, and you have a strong, low-cost defense that will catch problems fast while blocking most new-account fraud from happening in the first place.

    Internal link placeholder: [The Credit Repair Process: Step-by-Step] — full walkthrough of a compliant, attorney-backed repair plan.

    Common Credit Monitoring Mistakes to Avoid

    Even with the right service in place, people make predictable mistakes that undercut the protection monitoring is supposed to provide. Here are the ones we see most often.

    1. Confusing Monitoring With Prevention

    Monitoring tells you something happened. It does not stop it from happening. If you want to actually block new-account fraud, you need a credit freeze — not a monitoring service, and not a “credit lock” that a paid service is trying to upsell you. The freeze is free by federal law at all three bureaus. Use it.

    2. Ignoring the Alerts

    A monitoring service only works if you read the alerts and act on them. If your inbox is full of unread monitoring emails, you have the illusion of protection, not the reality. Treat alerts the way you would treat a smoke alarm — read them immediately, and act if something looks wrong.

    3. Relying on a Single-Bureau Service and Calling It Done

    If your free service only monitors TransUnion, you are not monitoring your credit — you are monitoring one-third of it. Either stack free services to cover all three bureaus (as described above) or move to a paid 3-bureau service. Do not let “I have monitoring” lull you into false confidence.

    4. Fixating on the Score Number Instead of the Report

    Scores are useful, but the report is the source of truth. A score can drop for reasons that have nothing to do with fraud or error (a balance increase, a new inquiry, an account closure). The report tells you why. If you only look at the score and never pull the full report, you will miss the actual problems.

    5. Paying for a Service You Do Not Need

    A lot of people end up on a $25/month paid plan because they signed up during a moment of worry — after a data breach, after a news story about identity theft, after a friend’s horror story — and then never reassessed. If your situation has not changed and your risk is not elevated, the free setup is fine. Revisit your decision once a year.

    6. Not Monitoring Children’s Credit

    Children are prime identity theft targets because their credit files are clean and no one checks them. A child’s Social Security number can be used to open accounts for years before anyone notices — usually when the child turns 18 and applies for their first credit card or student loan and finds a wrecked credit history they did not create. If you have kids, look for a service with child monitoring or at minimum freeze their credit at all three bureaus (which is free).

    7. Assuming One Service Covers Everything

    No single service — free or paid — is a complete solution. The strongest setups combine monitoring (for alerts), a freeze (for prevention), and periodic full report pulls (for depth). Do not treat any one service as a complete defense. Layer your protection.

    Frequently Asked Questions

    Is free credit monitoring actually free, or is it a trial?

    The services we described — Credit Karma, Experian’s free tier, Discover Scorecard — are genuinely free, ongoing services, not trials. You do not need a credit card to sign up, and you will not be charged after a period. They make money through advertising (showing you credit card and loan recommendations) or by upselling you to paid tiers. The free monitoring itself is real and ongoing.

    How often should I check my credit report?

    With monitoring in place, you do not need to pull your full reports constantly — the alerts will tell you when something changes. But it is wise to pull your full reports from all three bureaus via AnnualCreditReport.com at least a few times a year, and anytime you are about to dispute an item, apply for a major loan, or suspect fraud. The monitoring dashboard shows summaries and scores; the full report shows everything.

    Does credit monitoring hurt my credit score?

    No. Monitoring uses soft inquiries, which do not affect your credit score. Only hard inquiries — the kind a lender makes when you apply for credit — can lower your score, and only slightly and temporarily. Checking your own credit, through any service, never counts against you.

    What is the difference between a credit freeze and a credit lock?

    Both block new creditors from accessing your credit file, which effectively prevents new accounts from being opened in your name. A credit freeze is a free, federally protected right at all three bureaus. A credit lock is a voluntary, service-managed feature (often bundled with paid monitoring) that does essentially the same thing but through an app, with faster lock/unlock toggling. For most people, a freeze is the better choice because it is free and legally protected. A lock is fine if it comes with a service you are already paying for and you value the convenience.

    Can credit monitoring prevent identity theft?

    No — and any service that implies otherwise is being misleading. Monitoring detects identity theft early. It does not prevent it. To prevent new-account fraud, you need a credit freeze. To protect existing accounts, you need strong passwords, two-factor authentication, and vigilance against phishing. Monitoring is one layer in a broader defense, not the whole defense.

    Should I pay for credit monitoring if I am already working with a credit repair firm?

    It depends on your situation. If you are in an active repair plan, 3-bureau monitoring is genuinely useful for tracking dispute outcomes and score progress across all three bureaus. That said, a good credit repair firm should be pulling and reviewing your reports as part of the process, so you may not need a separate paid service if your firm provides that visibility. Talk to your firm about what they include. If they do not provide 3-bureau monitoring, a free stack (Credit Karma + Experian free) plus periodic full report pulls is a strong, zero-cost complement to your repair plan.

    What should I do if I get an alert about an account I do not recognize?

    Act immediately. First, do not assume it is fraud — sometimes a legitimate account shows up under an unfamiliar creditor name (a store card backed by a bank you do not recognize, for example). Look up the creditor and confirm whether it is yours. If it is not yours:

    1. Contact the creditor directly and tell them the account is fraudulent.
    2. Place a fraud alert at one of the three bureaus (it will propagate to the other two).
    3. Freeze your credit at all three bureaus if you have not already.
    4. File a report with the FTC at IdentityTheft.gov.
    5. Dispute the account with the credit bureau(s) reporting it.
    6. If you have identity theft insurance or restoration help through a monitoring service, call them — they will guide you through the process.

    Speed matters. The faster you act, the less damage there is to undo.

    Is it worth monitoring my child’s credit?

    Yes. Child identity theft is a real and growing problem because children’s credit files are clean and no one is watching them. A child’s Social Security number can be used to open accounts for years before the theft is discovered — often not until the child applies for their first credit card, student loan, or apartment lease and finds a damaged credit history they did not create. You can freeze your child’s credit for free at all three bureaus (the process is a bit more involved than freezing an adult’s credit but worth it) and use a monitoring service with child coverage if you want ongoing alerts.

    Next Steps: Take Control of Your Credit

    Credit monitoring is one piece of a larger picture. If you want a clear, honest, attorney-backed review of your full credit profile across all three bureaus — including a breakdown of what is helping your score, what is hurting it, and what can be disputed under the FCRA — we can help.

    At credit-repair.com, we offer a free credit audit that walks you through your reports, identifies errors and negative items that may be dragging your score down, and lays out a customized repair plan grounded in federal credit law. No quick-fix promises. No hidden fees. Just a clear path forward and a team that treats your financial future like their own.

    Start your free credit audit at credit-repair.com →

    Your credit score is not a verdict. It is a snapshot, and snapshots change. With the right monitoring, the right protections, and the right plan, you can watch it move in the direction you want — and know exactly what is moving it.
  • Balance Transfer Cards to Pay Off Debt: A Smart Move or Trap?

    Balance Transfer Cards to Pay Off Debt: A Smart Move or Trap?

    If you’re carrying a balance on a high-interest credit card, you already know the math is brutal. A typical card charges somewhere between 22% and 29% APR these days. On a $5,000 balance, making minimum payments, you can easily spend five years and thousands of dollars in interest just to pay down the principal. It’s a slow drain, and most of your monthly payment is going to the bank — not your debt.

    That’s where a balance transfer credit card enters the conversation. The pitch is simple: move your existing balance to a new card with a 0% introductory APR for 12 to 21 months, and every dollar you pay during that window goes straight to principal. No interest. Just progress.

    Sounds great, right? And it can be. A balance transfer, done carefully, is one of the most effective tools for paying down credit card debt without taking out a loan. But it can also go sideways — fast. We’ve seen people transfer a balance, feel relief, then run the old card right back up and end up owing twice as much. We’ve seen people miss the end of the intro window and get hit with deferred interest they didn’t know was coming. We’ve seen people apply for a transfer, get denied, and take a hard inquiry hit on a score they were trying to rebuild.

    So is a balance transfer credit card a smart move or a trap? The honest answer is: it depends entirely on how you use it. The same tool that frees one person buries another. This guide walks you through both sides — what these cards do well, where they bite, and the specific rules that make the difference.

    We’re a San Diego-based credit repair firm, and we talk to people every day who are weighing this exact decision. Our job isn’t to sell you on a balance transfer. It’s to help you understand the full picture, in plain language, so you can make the call that’s right for your situation — and your credit.

    Get a free credit audit or request a quote.

    What Is a Balance Transfer Credit Card?

    A balance transfer credit card is a card designed to let you move an existing balance from one (or more) credit cards onto it, usually at a promotional interest rate — most commonly 0% APR — for a set period. The goal is to stop paying interest on your existing debt so your payments actually reduce what you owe.

    Here’s the mechanics in plain terms. Say you have a $4,000 balance on a card charging 26% APR. You apply for a balance transfer card offering 0% intro APR for 18 months. If approved, the new card issuer pays off your old card (or you do it yourself with a transfer check or online tool), and that $4,000 now lives on the new card — with no interest accruing for 18 months, assuming you follow the rules.

    You can typically transfer balances from:

    • Other credit cards (the most common scenario)
    • Store cards and retail cards
    • Gas cards
    • Some personal loans (card-dependent)
    • Sometimes medical debt or other installment loans — though this varies by issuer

    What you usually can’t transfer is a balance from another card issued by the same bank. Chase won’t let you transfer a balance from one Chase card to another Chase card. Same with Citi, Bank of America, Discover, and the rest. You’ll need to move the debt to a different issuer.

    There’s also a limit to how much you can transfer. The new card comes with a credit limit, and most issuers cap the transfer amount at some percentage of that limit — often 70% to 95%. If you get approved for a $10,000 limit, you may be able to transfer somewhere between $7,000 and $9,500, depending on the issuer. You won’t know the exact cap until you’re approved and see the limit, which is one of the frustrations of the process — you may be counting on transferring a specific amount and end up short.

    The transfer itself usually happens one of three ways:

    1. Direct transfer — you provide the old card details when you apply (or right after approval), and the new issuer pays the old card directly. This is the cleanest method.
    2. Transfer checks — the new issuer mails you checks drawn on the new card account. You write one to your old card issuer. Takes longer, and some issuers treat check-initiated transfers differently than direct ones.
    3. Online transfer tool — once your new card is active, you log into the new issuer’s portal and initiate the transfer there.

    Each method has timing considerations. Direct transfers typically process in 7 to 14 days, though some issuers say up to 6 weeks. During that window, you still need to make at least the minimum payment on your old card — if you don’t, you risk a late payment, which is the last thing you need when you’re trying to clean up your credit.

    How the 0% Intro APR Actually Works

    The headline feature of any balance transfer credit card is the 0% introductory APR. “Intro APR” just means the interest rate the card charges for a limited time after you open the account. For balance transfers, that intro rate is almost always 0%, and the window usually lasts somewhere between 12 and 21 months.

    During that intro period, no interest accrues on the balance you transferred. This is the entire value proposition. If you transfer $5,000 and pay it off in full before the intro period ends, you pay zero interest on that debt. Every dollar you send the card company goes to principal.

    There are a few things to understand clearly, because the marketing doesn’t always spell them out:

    The 0% rate may not apply to new purchases

    The 0% rate applies to the balance you transferred — not necessarily to new purchases. Many balance transfer cards also offer a 0% intro APR on purchases, but not all do. Some cards give you 0% on balance transfers for 18 months but charge the regular purchase APR from day one.

    If you’re planning to use the card for new spending, check whether purchases are covered by the intro offer — and honestly, if you’re transferring a balance to pay off debt, you probably shouldn’t be making new purchases on the card anyway.

    The intro clock starts when you open the account

    The intro period starts when you open the account, not when you complete the transfer. This matters more than people realize. If your intro period is 15 months and it takes you 6 weeks to actually complete the transfer because of processing time or mailing checks, you’ve already burned more than a month of your interest-free window. The clock starts the day you’re approved, so initiate the transfer as quickly as possible.

    Missing a payment can destroy the benefit

    The 0% rate is conditional on making your minimum payments. If you miss a payment during the intro period, most issuers will immediately cancel the promotional rate and kick you up to the standard APR — sometimes even higher, in the form of a penalty APR that can reach 29.99% or more. One late payment can undo the entire reason you did the transfer. This is why automating your payments is non-negotiable.

    Intro APR is not the same as “no interest ever”

    Once the intro window closes, any remaining balance starts accruing interest at the card’s standard ongoing APR. That ongoing rate is typically in the 19% to 29% range depending on your credit and the card. There is no extension. There is no grace. The day after the intro period ends, interest starts calculating on whatever’s left.

    Watch for deferred interest

    Some cards — and this is critical to watch for — use deferred interest instead of true 0% intro APR. Deferred interest means the interest is calculated every month but not charged to your account — as long as you pay off the full balance before the promo ends. If you don’t pay it all off, all that accrued interest gets added to your balance retroactively, as if the 0% never existed.

    This is more common with store cards (like those offered by retailers and medical financing companies) than on major credit cards, but always read the terms to know which you’re getting. True 0% intro APR means no interest accrues during the period. Deferred interest means interest accrues in the background and gets waived only if you cross the finish line in time.

    Typical Terms: 12 to 21 Months, Then the Real APR Kicks In

    When you’re shopping for a balance transfer credit card, the intro period length is one of the two most important variables (the other being the balance transfer fee). Here’s how the landscape typically looks:

    Intro Period What It Means for You Common Cards in This Range
    12 months Tight but workable for smaller balances. You need a clear payoff plan. Many entry-level balance transfer cards
    15 months A solid middle ground. Gives breathing room for balances in the $3,000–$8,000 range. Several mid-tier offers
    18 months Strong. Comfortable window for most payoff plans. Popular cards from major issuers
    21 months The longest commonly available. Best for larger balances or if you want a safety margin. A small number of top-tier cards

    The longer the intro period, the more flexibility you have — and the lower your monthly payment needs to be to clear the balance in time.

    Here’s a quick illustration:

    Intro Period Monthly Payment to Pay Off in Full Total Interest Paid
    12 months ~$417 $0 (plus transfer fee)
    15 months ~$334 $0 (plus transfer fee)
    18 months ~$278 $0 (plus transfer fee)
    21 months ~$238 $0 (plus transfer fee)

    That table assumes you make equal payments and pay it off exactly at the end of the intro period. Real life is messier — you might pay more some months and less others — but the point is clear: a longer intro period means a lower required monthly payment, which means more room in your budget and less risk of falling short.

    What happens after the intro period?

    Once the promotional window closes, the card’s ongoing APR applies to any remaining balance. This rate is determined when you’re approved and is based on your credit profile. Current typical ranges:

    • Excellent credit (760+): around 19%–23%
    • Good credit (670–759): around 22%–26%
    • Fair credit (640–669): around 25%–29%
    • Below that: you’re unlikely to be approved for most balance transfer cards

    If you still have, say, $1,500 left on the card when the intro period ends and your ongoing APR is 24%, you’ll start paying about $30/month in interest on that remaining balance. That’s not catastrophic, but it defeats the purpose — you did the transfer to stop paying interest, and now you’re paying interest again, just on a smaller amount.

    This is why the single most important number to calculate before you transfer a balance is: can I realistically pay this off before the intro period ends? If the answer is “probably not,” a balance transfer may not be the right tool — or you may need a longer intro period than you originally planned for.

    Can you extend the intro period?

    Generally, no. The intro period is set when you open the account and doesn’t renew or extend. Some issuers have occasionally offered to let customers transfer a new balance at a promotional rate after the first one is paid off, but this is not something to count on. The intro period you sign up for is the one you get.

    One option that exists: if you’ve paid off your first transfer and your credit is still in good shape, you can apply for a second balance transfer card with a new intro period and transfer any remaining balance (or a new balance) there. This is sometimes called “balance transfer surfing” or “churning.” It can work, but it has real downsides — each application is a hard inquiry, each new account lowers your average account age, and issuers are increasingly wise to the pattern and may deny you if they see you’ve done it recently. We don’t recommend this as a primary strategy, though it’s an option in specific situations.

    The Balance Transfer Fee: Usually 3% to 5%

    The 0% APR is the headline. The balance transfer fee is the fine print. Almost every balance transfer card charges a fee to move your debt over, and it’s almost always a percentage of the amount transferred.

    The standard range is 3% to 5%, with 3% being the most common on competitive cards and 5% showing up on some less generous offers. The fee is typically added to your new card balance — it’s not a separate charge you pay out of pocket.

    Example: You transfer $5,000 to a card with a 3% balance transfer fee. The fee is $150. Your starting balance on the new card is $5,150. That $150 is the cost of doing the transfer, and it’s rolled into the balance you’ll pay off during the intro period.

    A few important details:

    • The fee is charged per transfer. If you transfer balances from three different cards, you pay the fee three times — once on each amount.
    • Some cards cap the fee. A few issuers charge “3% of the amount transferred, with a minimum of $5” — the minimum matters only for very small transfers. Most don’t have a maximum cap, which means on a large transfer, the fee can be substantial (5% of $15,000 = $750).
    • A small number of cards waive the fee entirely. These are rare and usually require excellent credit. When they exist, they’re worth looking at — but the intro period is sometimes shorter on no-fee cards, so you have to weigh the tradeoff.
    • The fee is almost always non-negotiable. You can’t call up and ask them to waive it (though there’s no harm in asking — occasionally a retention specialist will have some flexibility, especially if you’re an existing customer).

    How to factor the fee into your decision

    The fee is the upfront cost of the transfer. The 0% APR is the ongoing benefit. To know if the transfer is worth it, you compare the fee to the interest you’d pay if you left the balance where it is.

    Rough rule of thumb: if the interest you’d pay on your current card during the intro period is more than the balance transfer fee, the transfer saves you money. If the fee is more than the interest you’d pay, it doesn’t.

    We’ll do the full math in the next section, but here’s the quick version:

    • You have a $4,000 balance at 26% APR.
    • Over 12 months, you’d pay roughly $1,040 in interest if you made minimum payments (this is approximate — actual interest depends on your payment pattern).
    • A 3% transfer fee on $4,000 is $120.
    • You save about $920 by transferring.

    That’s a clear win. But flip the numbers:

    • You have a $1,000 balance at 22% APR.
    • Over 12 months, you’d pay roughly $220 in interest at minimum payments.
    • A 3% transfer fee on $1,000 is $30.
    • You save about $190.

    Still a win, but a smaller one — and if your payoff timeline is short (say you’ll have it paid off in 3 months either way), the math might not work. On a 3-month payoff, you’d pay about $55 in interest on the old card, and the transfer fee is $30 — so the transfer saves you only $25, which may not be worth the hassle, the hard inquiry, and the new account on your credit report.

    The bottom line on fees: they’re the price of admission. They’re usually worth it for balances you’ll need more than a few months to pay off, and usually not worth it for small balances you can knock out quickly. Always calculate before you commit.

    What Credit Score Do You Need? (The Honest Answer)

    This is where the conversation gets uncomfortable, and we’re not going to sugarcoat it.

    Balance transfer credit cards are generally designed for people with good to excellent credit. The typical approval threshold is a FICO score of 670 or higher, with the best offers (longest intro periods, lowest fees, highest credit limits) reserved for scores of 740 and above.

    But your score isn’t the only thing the issuer looks at. They also consider:

    • Credit utilization — if your existing cards are maxed out or near their limits, it signals financial strain.
    • Income — issuers want to see that you have the means to pay back what you transfer.
    • Payment history — recent late payments, even if your score has recovered, can be a red flag.
    • Age of credit history — a longer history with multiple accounts in good standing helps.

    If you apply and get denied, you’ll receive a letter explaining why. Read it — it’s useful information. If the reason was “insufficient credit score” or “high utilization,” those are things you can work on. If it was “too many recent inquiries,” waiting a few months before reapplying can help.

    Should you apply if you’re not sure you’ll be approved?

    This is a judgment call. Every application is a hard inquiry, which typically drops your score by a few points (usually 1–5, recovering within a few months). If you’re borderline and get denied, you’ve taken the hit with no benefit. On the other hand, if you don’t apply, you definitely won’t get the transfer.

    A few ways to reduce the risk:

    • Check for prequalification. Some issuers and card comparison sites offer a prequalification tool that does a soft pull (no score impact) to tell you whether you’re likely to be approved. This isn’t a guarantee, but it’s a good signal.
    • Check your credit reports first. Know where you stand before you apply. You can get free reports from all three bureaus at AnnualCreditReport.com.
    • Apply for the card you’re most likely to get. Don’t shoot for the 21-month intro card if your score is 680 — target a card whose approval range includes your score.

    How a Balance Transfer Can Help You

    Now let’s talk about the upside — because when a balance transfer works, it works remarkably well. Here’s what it does for you:

    1. The Interest Pause Lets Your Principal Drop Fast

    This is the big one. On a normal high-interest card, a large chunk of your monthly payment goes to interest, not principal. The result: your balance barely moves, even when you’re paying every month. It’s demoralizing, and it’s by design — the card issuer profits from you carrying the balance.

    When you transfer to a 0% intro APR card, that dynamic flips. Every dollar you pay (minus the minimum payment on any new fees) goes to principal. Your balance drops visibly, month over month. You can see the progress, and that psychological effect matters — people who see their debt shrinking are more likely to keep paying it down.

    Concrete example: You have a $6,000 balance at 24% APR. Your minimum payment is about $180/month, and roughly $120 of that goes to interest. Only $60 goes to principal. After a year of minimum payments, your balance has dropped from $6,000 to about $5,280. You paid $2,160 and knocked off $720. Brutal.

    Transfer that to a 0% APR card with an 18-month intro. Now your entire $180 payment goes to principal. After 12 months at $180/month, your balance is $3,840 — you’ve knocked off $2,160 instead of $720. Three times the progress, same payment. That’s the power of the interest pause.

    2. It Can Lower Your Credit Utilization

    Credit utilization is the percentage of your available revolving credit that you’re using. It’s calculated both per-card and overall. The lower your utilization, the better, with most scoring models rewarding utilization below 30% and especially below 10%.

    A balance transfer can help utilization in a specific way: if you transfer a balance from a card that’s near its limit to a new card with a higher limit, you spread your debt across more available credit. Say you have a card with a $5,000 limit and a $4,500 balance (90% utilization — very bad for your score). You transfer that balance to a new card with a $10,000 limit. Now your old card is at $0 (0% utilization) and your new card is at $4,500 (45% utilization). Your overall utilization dropped from 90% to 30%. That can meaningfully help your score.

    There’s a catch, though — and it’s important. This benefit depends on you not closing the old card and not running it back up. More on both in the next section.

    3. It Simplifies Your Payments

    If you’re juggling balances on three or four cards, each with its own due date and minimum payment, consolidating them onto one balance transfer card means one payment, one due date, one account to track. This reduces the chance of missing a payment (which would be disastrous — remember, a missed payment can cancel your intro APR) and makes budgeting cleaner.

    4. It Creates a Defined Payoff Timeline

    When you’re paying down a regular card at 24% APR, there’s no natural endpoint — you can make minimum payments forever, and the issuer is fine with that. A balance transfer card with an 18-month intro period creates a deadline. You know exactly when the 0% window closes, and that creates a natural forcing function: you need to be done by then. This helps people who do better with a clear target than an open-ended grind.

    5. It Can Be a Stepping Stone to Better Credit

    If you handle the balance transfer well — pay on time every month, pay down the balance steadily, don’t run up other cards — you’re building a positive payment history on a new account and improving your utilization. Both of those help your score. By the time the intro period ends, your score may be meaningfully higher, which gives you more options (better cards, better loan rates, better insurance rates in many states) going forward.

    How a Balance Transfer Can Hurt You

    Here’s the other side. A balance transfer is a tool, and like any tool, it can cause damage if used wrong. Here’s what can go wrong:

    1. The Hard Inquiry and New Account

    When you apply for a balance transfer card, the issuer does a hard inquiry on your credit report. This typically drops your score by a few points and stays on your report for two years (though the scoring impact fades after about 6–12 months).

    Then, when you’re approved and open the account, you have a new account on your report. This lowers your average age of accounts — another factor in your credit score. If your credit history is short (say, you only have one other card that’s two years old), adding a brand-new account can drop your average age significantly. If your history is long, the impact is smaller.

    These two effects — the hard inquiry and the new account — typically cause a small, temporary score dip. For most people, it’s 5 to 15 points, recovering within 6 to 12 months if you manage the new account well. But if you’re already on the credit score bubble, even a small dip can matter.

    2. Closing the Old Card Can Raise Your Utilization

    We mentioned earlier that a balance transfer can help your utilization by spreading debt across more credit. The flip side: if you close the old card after transferring the balance, you lose its credit limit from your utilization calculation.

    Example: You have two cards. Card A has a $5,000 limit and a $4,000 balance. Card B (new) has a $10,000 limit and you transfer the $4,000 to it. If you keep Card A open:

    • Card A: $0 balance / $5,000 limit = 0% utilization
    • Card B: $4,000 balance / $10,000 limit = 40% utilization
    • Overall: $4,000 / $15,000 = 27% utilization — good

    If you close Card A:

    • Only Card B counts: $4,000 / $10,000 = 40% utilization — worse

    Closing Card A also removes it from your average age calculation eventually (closed accounts stay on your report for up to 10 years if in good standing, but they stop contributing to your active credit picture). The general rule: don’t close the old card after a transfer. Keep it open, let it report a $0 balance, and maybe put a small recurring charge on it (like a streaming subscription) that you pay off every month to keep it active.

    3. The Deferred-Interest Trap

    We covered this briefly above, but it deserves emphasis. If your card uses deferred interest rather than true 0% intro APR, and you don’t pay off the entire transferred balance before the promo period ends, you get hit with all the interest that accrued during the promo period — retroactively, as if the 0% never existed.

    This is more common with store cards and medical financing offers than with major credit cards, but always check. If the terms say “no interest if paid in full within X months,” that’s deferred interest. If they say “0% intro APR for X months,” that’s true intro APR. The difference matters enormously.

    4. The New Card’s Terms May Not Be What You Expected

    The offer you saw online may not be the offer you get. Issuers sometimes advertise a range — “0% intro APR for 15 or 18 months, depending on creditworthiness” — and you don’t find out which you got until after approval. Same with the credit limit: you might apply expecting to transfer $8,000 and get approved for a $5,000 limit, leaving you with $3,000 still on the old card. Now you’re making payments on two cards, which is exactly the complication you were trying to avoid.

    5. The Temptation to Spend

    This is the biggest behavioral risk, and we’ll dedicate the next section to it. A balance transfer card arrives in the mail with a $0 balance (after the transfer processes) or a low balance, and a fresh credit limit. For someone who has been living with maxed-out cards, that empty credit line can feel like breathing room — and the temptation to use it can be overwhelming.

    balance-transfer-credit-cards-under-100kb

    The Math: When the Fee Is Worth It vs. When It’s Not

    Let’s get into the actual numbers. The decision to do a balance transfer comes down to a calculation: does the fee cost less than the interest you’d otherwise pay?

    Here’s a worked example with the key variables:

    Scenario A: Large balance, long payoff, high APR

    • Current balance: $8,000
    • Current APR: 26%
    • Transfer fee: 3% ($240)
    • New card intro period: 18 months at 0%
    • Your planned monthly payment: $450

    Without transfer (staying on the 26% card):

    Month Payment Interest Principal Remaining Balance
    1 $450 $173 $277 $7,723
    6 $450 $151 $299 $6,541
    12 $450 $126 $324 $5,247
    18 $450 $97 $353 $3,793

    After 18 months, you’ve paid $8,100 total and still owe $3,793. Roughly $1,893 of your payments went to interest.

    With transfer (0% intro APR for 18 months, $240 fee):

    Month Payment Interest Principal Remaining Balance
    1 $450 $0 $450 $7,790 (after fee)
    6 $450 $0 $450 $5,590
    12 $450 $0 $450 $2,890
    18 $450 $0 $450 $190

    Starting balance on new card: $8,000 + $240 fee = $8,240. After 18 months at $450/month ($8,100 paid), you owe $190. You’ve nearly paid it off entirely.

    Savings: In the no-transfer scenario, you still owe $3,793 after 18 months. In the transfer scenario, you owe $190. The difference is about $3,600 — the interest you didn’t have to pay, minus the $240 fee. Net savings: roughly $3,360.

    This is a clear, decisive win for the balance transfer.

    Scenario B: Small balance, short payoff

    • Current balance: $1,500
    • Current APR: 22%
    • Transfer fee: 3% ($45)
    • New card intro period: 15 months at 0%
    • Your planned monthly payment: $500 (you can afford to pay this off fast)

    Without transfer:

    You pay $500/month on the $1,500 balance at 22%. Month 1: $27.50 interest, $472.50 principal, balance $1,027.50. Month 2: $18.84 interest, $481.16 principal, balance $546.34. Month 3: $10.01 interest, $489.99 principal, balance $56.35. Done in about 3.5 months. Total interest paid: roughly $60.

    With transfer:

    You pay $500/month on $1,545 ($1,500 + $45 fee) at 0%. Month 1: balance $1,045. Month 2: balance $545. Month 3: balance $45. Done in about 3.1 months. Total interest: $0. Total fee: $45.

    Savings: You save about $60 in interest but pay $45 in fees. Net savings: about $15.

    This is technically a win, but barely. For $15, it’s not worth the hard inquiry, the new account on your credit report, and the administrative hassle. If you can pay off a small balance in 3–4 months, just pay it off — don’t bother with a transfer.

    The Trap: Running Up the Old Card Again

    The danger feels gone. But the danger hasn’t gone anywhere; it’s just moved to a new card. And the underlying spending patterns that created the debt in the first place haven’t been addressed.

    We see this in our work regularly. People come to us with two cards, both carrying balances, and one of them is a balance transfer card they used to consolidate debt six months ago. They meant well. They intended to pay it down. But the old card crept back up, and now they’re in worse shape than before.

    How to avoid the trap:

    1. Cut up the old card. Not close the account — you want to keep it open for credit score reasons (utilization and account age). But physically destroy the card so you can’t use it. Remove it from your digital wallets and online payment profiles. If you can’t physically get to it, some issuers let you “lock” the card so it can’t be used for new charges while still reporting as open.
    2. Do not carry the old card with you. Out of sight, out of wallet. If it’s not in your pocket, you can’t swipe it.
    3. Address the spending that created the debt. A balance transfer moves the debt; it doesn’t fix the cause. If you don’t have a budget, make one. If you don’t know where your money goes, track it for a month. If there’s an income problem (not just a spending problem), that needs a different solution — possibly one of the alternatives we’ll discuss below.
    4. Consider keeping the new card for the transfer only. Don’t use it for purchases. Don’t carry it either, if you can help it. Treat it as a debt payoff tool, not a spending tool. Some people literally tape the card to a piece of paper with their payoff plan written on it and stick it in a drawer.
    5. Be honest with yourself about your patterns. If you’ve done a balance transfer before and ended up with more debt, another transfer is probably not the right move. The pattern is telling you something. A debt management plan (which we’ll cover below) might be a better fit because it includes structure and accountability.

    The people who succeed with balance transfers treat them as a one-time intervention — a reset button, not a recurring strategy. The people who struggle treat them as a recurring strategy. Know the difference.

    Rules to Make a Balance Transfer Work

    If you’ve decided a balance transfer is right for your situation, here are the rules that separate the people who succeed from the people who end up worse off. These aren’t suggestions — they’re the operating manual.

    Rule 1: Pay Off the Balance Before the Intro Period Ends

    This is the whole point. Calculate your required monthly payment (balance including fee, divided by months in intro period) and pay at least that every month. If the intro period is 18 months and your transferred balance (with fee) is $5,200, your number is $289/month. Pay that or more, every month, without exception.

    Build in a buffer. If you can afford $325/month, pay $325. That gives you a cushion for months when money is tight and ensures you finish early rather than right at the deadline.

    Rule 2: Stop Using the Old Cards

    See the previous section. Cut them up, lock them, remove them from your wallet and digital wallets.

    The only reason to keep the accounts open is for your credit score — not for spending.

    Rule 3: Automate Your Payments

    Set up automatic payments for at least the minimum (ideally your full planned payment amount) from your bank account. This ensures you never miss a payment, which is critical — a missed payment can cancel your intro APR and trigger a penalty rate. Automate it the day you open the account. Don’t wait.

    If you’re worried about overdrawing your checking account, set the auto-pay for a few days after payday, and set up low-balance alerts with your bank.

    Rule 4: Read the Fine Print on Which Balances Qualify

    Not all balances are eligible for transfer, and not all transfers qualify for the 0% intro APR. Common restrictions:

    • Same-issuer transfers are usually blocked. You can’t transfer from one Citi card to another Citi card.
    • Some issuers exclude certain types of debt. Business card balances, for instance, may not qualify for a personal card transfer.
    • The promo rate may only apply to transfers initiated within a specific window — often 60 to 120 days from account opening. If you initiate a transfer six months in, it may be charged the standard APR, not 0%.
    • Transfer limits. You can only transfer up to your credit limit (minus the fee), and some issuers cap transfers at a percentage of the limit.

    Read the terms before you apply, and confirm the details after you’re approved before initiating the transfer.

    Rule 5: Don’t Make New Purchases on the Transfer Card

    This is both a behavioral rule and a financial one. Behaviorally, using the transfer card for purchases puts you back in the spending mindset you’re trying to escape. Financially, it complicates your payoff plan — purchases may or may not be covered by the 0% intro APR, and even if they are, they add to the balance you’re trying to pay down.

    If you need a card for everyday spending, use a different one — ideally one you pay off in full every month. The transfer card is for debt payoff, not for spending.

    Rule 6: Keep Making Minimum Payments on the Old Card During the Transfer Window

    The transfer isn’t instant. It can take 7 to 14 days (sometimes longer) for the new issuer to pay off your old card. During that window, you still owe the old card, and you need to make at least the minimum payment. If you don’t, you risk a late payment — which hits your credit score and can stay on your report for up to seven years.

    Once the transfer posts and the old card shows $0, you can stop making payments on it (though you should verify the balance is actually $0 — don’t assume).

    Rule 7: Watch for the End of the Intro Period

    Mark the date on your calendar — the exact month the intro APR expires. If you have a balance remaining, decide in advance what you’ll do: pay it off with savings, transfer it to a new card, or accept the ongoing APR. Don’t get surprised by it.

    Rule 8: Don’t Apply for Multiple Transfer Cards at Once

    Each application is a hard inquiry. Multiple hard inquiries in a short period signal to issuers that you’re scrambling for credit, which makes them less likely to approve you and dings your score. Apply for one card, see what you get, and work with it. If you need to consolidate multiple balances and the credit limit isn’t high enough, focus on paying down what you transferred first — then consider a second transfer later if needed.

    Balance Transfer vs. Personal Loan vs. Debt Management Plan

    A balance transfer card is one of three common tools for consolidating and paying down credit card debt. It’s not always the best one. Here’s how the three compare:

    Balance Transfer Credit Card

    Best for: People with good to excellent credit (670+) who can pay off the balance within the intro period (12–21 months) and are confident they won’t run up the old cards.

    Pros:

    • 0% intro APR means all payments go to principal
    • Potential for large interest savings
    • Can improve credit utilization

    Cons:

    • Requires good credit to qualify
    • Balance transfer fee (3%–5%)
    • Intro period is limited — after that, ongoing APR kicks in
    • Risk of running up old cards
    • Hard inquiry and new account affect credit score

    Personal Loan (Debt Consolidation Loan)

    Best for: People who want a fixed payoff timeline and fixed monthly payment, and whose credit may not qualify for the best balance transfer cards.

    How it works: You take out a personal loan for the amount of your credit card debt, use it to pay off the cards, and then repay the loan in fixed monthly installments over a set term (typically 2–7 years) at a fixed interest rate.

    Pros:

    • Fixed rate and fixed payment — you know exactly when you’ll be done
    • Rates can be lower than credit card APRs (especially for good credit), often 8%–18%
    • No “intro period” deadline — the rate is the rate for the whole term
    • May be easier to qualify for than a top-tier balance transfer card
    • Simplifies payments to one monthly amount

    Cons:

    • Interest rate is not 0% — you’re paying interest the whole time
    • Origination fees (1%–8% of the loan amount on some loans)
    • Loan amount may not cover all your debt
    • Still requires decent credit for good rates
    • Doesn’t address the spending behavior that caused the debt

    Debt Management Plan (DMP)

    Best for: People who are struggling to make minimum payments, whose credit may not qualify for balance transfers or personal loans at good rates, or who want structured support and accountability.

    How it works: You work with a nonprofit credit counseling agency (look for one affiliated with the National Foundation for Credit Counseling). They negotiate with your creditors to lower your interest rates and waive certain fees, and you make one monthly payment to the agency, which distributes it to your creditors. Plans typically last 3–5 years.

    Pros:

    • Can significantly lower interest rates (often to 6%–10%, sometimes lower)
    • One monthly payment
    • Structured timeline and counseling support
    • Credit score doesn’t need to be good — the plan is based on your situation, not your score
    • Creditors may waive late fees and over-limit fees
    • Forces you to stop using the cards (they’re typically closed as part of the plan)

    Cons:

    • You usually have to close the credit cards included in the plan — this can lower your score in the short term
    • Not all creditors participate
    • You can’t use the cards while on the plan (which is partly a pro and partly a con)
    • Some scam operators pose as credit counselors — always verify you’re working with a legitimate nonprofit
    • The plan is noted on your credit report, which some lenders view cautiously (though it doesn’t directly affect your FICO score)

    Which should you choose?

    There’s no one-size answer. The right choice depends on your credit score, your discipline, your balance size, and your timeline. Here’s a rough decision framework:

    Your Situation Consider
    Good credit, can pay off in 12–18 months, confident about discipline Balance transfer card
    Good credit, want a fixed timeline, prefer predictable payments Personal loan
    Fair credit, struggling with minimums, want support and structure Debt management plan
    Below fair credit, limited options DMP or work on credit repair first, then reassess
    Large balance that won’t fit on one transfer card Personal loan or DMP

    And there’s a fourth option we should mention: directly negotiating with your creditors. You can call your card issuer and ask for a lower APR, a hardship program, or a payment plan. They won’t always say yes, but they sometimes will — especially if you’ve been a long-time customer and you explain that you’re trying to avoid defaulting. This doesn’t require good credit, doesn’t involve a new application, and can provide real relief. It’s not a consolidation tool, but it’s worth trying before you commit to any of the above.

    Common Mistakes to Avoid

    We’ve touched on most of these throughout the guide, but let’s consolidate them into a checklist you can refer back to:

    1. Not Having a Payoff Plan Before You Transfer. Transferring a balance without knowing how you’ll pay it off is like starting a road trip without a map. Before you apply, calculate: total balance (including fee), divided by months in intro period, equals your required monthly payment. If you can’t afford that payment, the transfer may not be the right tool — or you need a longer intro period.
    2. Missing a Payment. One missed payment can cancel your 0% intro APR and trigger a penalty APR. Automate your payments. We can’t say this enough.
    3. Closing the Old Card. This hurts your utilization and your average account age. Keep the old card open with a $0 balance. If you’re worried about temptation, cut up the card or lock it — but don’t close the account.
    4. Using the Transfer Card for New Purchases. This adds to the balance you’re trying to pay down and blurs the line between debt payoff and spending. Keep the transfer card for the transfer only.
    5. Ignoring the Balance Transfer Fee. The fee is real money, added to your balance. Factor it into your calculations. A 5% fee on a $10,000 transfer is $500 — that’s not trivial.
    6. Applying for the Wrong Card. If your credit is at 680, don’t apply for the card that typically approves at 750+. You’ll get denied, take a hard inquiry hit, and get nothing. Check for prequalification, know your score, and target realistically.
    7. Not Reading the Fine Print on Deferred Interest. If your card uses deferred interest instead of true 0% intro APR, you need to know — because the consequences of not paying it off in time are much worse. Read the terms.
    8. Transferring Too Little. If you transfer part of a balance and leave the rest on a high-APR card, you’re now managing two payments. This is sometimes unavoidable (if your credit limit won’t cover the full balance), but it’s not ideal. If you can only transfer part, focus your payoff efforts on the remaining high-APR balance first.
    9. Applying for Multiple Cards Simultaneously. Each application is a hard inquiry. Multiple inquiries in a short window look desperate to issuers and compound the score impact. Apply for one, see what you get, proceed from there.
    10. Not Addressing the Root Cause. A balance transfer moves debt. It doesn’t fix the spending or income patterns that created the debt. If you don’t address those, you’ll be back here in a year — possibly worse. Budgeting, spending tracking, and (if needed) financial counseling are part of the solution. The transfer is a tool, not a cure.

    Frequently Asked Questions

    1. Does a balance transfer hurt your credit score?

    In the short term, yes — slightly. The hard inquiry from your application typically drops your score by a few points, and the new account lowers your average account age. However, if you manage the new card well (on-time payments, steady payoff, low utilization), your score usually recovers within 6–12 months and can end up higher than before, thanks to improved utilization and added payment history.

    2. Can I transfer a balance from the same bank?

    Generally, no. Most issuers won’t let you transfer a balance from one of their own cards to another of their cards. You need to move the debt to a different issuer. If you have a Chase card, you’d need to transfer to a Citi, Discover, Bank of America, Wells Fargo, or other non-Chase card.

    3. What happens if I don’t pay off the balance before the intro period ends?

    Any remaining balance starts accruing interest at the card’s ongoing APR — typically 19%–29%. There’s no penalty beyond the interest itself (for true 0% intro APR cards). For deferred-interest cards, the terms are much worse: all the interest that accrued during the promo period gets added to your balance retroactively. Know which type you have.

    4. Can I do multiple balance transfers?

    Yes, but each one is a separate application with a separate hard inquiry. Doing several in a short period can hurt your score and make issuers wary. A better approach: transfer what you can to one card, pay it down, and only apply for a second transfer if needed after you’ve made progress.

    5. Is there a limit to how much I can transfer?

    Yes. You can generally transfer up to your credit limit (or a percentage of it, often 70%–95%) minus the balance transfer fee. You won’t know the exact limit until you’re approved and see your credit limit. This is one reason it’s hard to know in advance exactly how much you’ll be able to move.

    6. Are there balance transfer cards with no fee?

    Yes, but they’re rare and typically require excellent credit. No-fee transfer cards sometimes have shorter intro periods, so you have to weigh the fee savings against the shorter payoff window. If a no-fee card offers 12 months at 0% and a 3% fee card offers 18 months at 0%, the longer period may save you more than the fee costs — do the math.

    7. Can I transfer balances other than credit card debt?

    It depends on the issuer. Some allow transfers from personal loans, auto loans, student loans, or other installment loans. Some allow medical debt. The specifics vary by card, so check the terms or call the issuer before applying if you’re hoping to transfer a non-credit-card balance.

    8. Should I use a balance transfer or a personal loan?

    It depends on your credit, your payoff timeline, and your preference for structure. A balance transfer saves you more money if you can pay it off during the intro period, but it requires discipline and good credit. A personal loan has a higher rate than 0% but gives you a fixed timeline and fixed payment, which some people find easier to stick to. If your credit is fair rather than good, a personal loan may be easier to qualify for at a reasonable rate. See the comparison section above for more detail.

    Improving Your Score First Unlocks Better Offers

    Here’s something we want you to take away from this guide, especially if you’ve read this far and realized your credit isn’t quite where it needs to be for a balance transfer: you don’t have to stay where you are.

    The offers you qualify for are directly tied to your credit score. A score of 680 gets you decent balance transfer cards. A score of 740 gets you the best ones — longer intro periods, lower fees, higher limits. The difference between “decent” and “best” can be thousands of dollars in interest savings on a large balance.

    That’s where we come in. At credit-repair.com, we help people improve their credit scores through a process that’s honest, legally compliant, and built for the long term. Here’s what that looks like:

    • A full credit audit across all three major bureaus — Experian, Equifax, and TransUnion. We look at everything: accounts, balances, payment history, inquiries, public records, and personal information.
    • Disputing inaccuracies under the Fair Credit Reporting Act (FCRA). If something on your report is wrong, outdated, or unverifiable, you have the legal right to dispute it, and we handle that process for you.
    • Working with creditors and negotiating where appropriate — sometimes directly with the original creditor or collection agency to resolve outstanding items.
    • Building a customized repair plan based on your specific goals. If your goal is to qualify for a balance transfer card in six months, we build the plan around that timeline and those requirements.
    • Educating you along the way — because the score improvement only sticks if you understand how credit works. We don’t just fix things; we teach you how to keep them fixed.

    We’re attorney-backed and FCRA-compliant, which means every step we take is within the bounds of federal law. We don’t make promises we can’t keep, and we don’t use tricks or shortcuts. We use the legal process the way it was designed — to make sure your credit report is accurate, fair, and verified.

    Why this matters for balance transfers specifically:

    If you’re at a 640 score and you improve to a 700, you cross the threshold from “probably won’t be approved” to “likely will be approved.” If you’re at 700 and improve to 760, you go from “decent offers” to “best offers.” Every point you gain opens doors — not just for balance transfers, but for personal loans, mortgages, auto loans, insurance rates, and even job applications (in states where employment credit checks are legal).

    A free credit audit is the starting point. It gives you a clear picture of where you are, what’s on your report, and what we can do about it. There’s no obligation, no pressure, and no cost to find out. You’ll talk with a real person who will walk you through your report in plain language and explain your options.

    Visit credit-repair.com to request your free credit audit. Whether you’re planning a balance transfer next month or next year, knowing where you stand — and having a plan to improve it — puts you in control.

    The Bottom Line

    A balance transfer credit card is a powerful tool. It can save you thousands in interest, accelerate your debt payoff, and help you build better credit — if you use it right. The mechanics are straightforward: move your balance to a 0% intro APR card, pay it off before the intro period ends, don’t run up the old cards, and automate your payments so you never miss one.

    But it’s not a magic solution. It requires a credit score that not everyone has yet. It comes with a fee. It has a deadline. And most importantly, it doesn’t fix the underlying behaviors that created the debt in the first place. If you transfer a balance and then run the old card back up, you’ll end up in a deeper hole than the one you started in.

    The smart move is to use a balance transfer as part of a broader plan — one that includes a budget, a payoff timeline, and a strategy for improving your credit so you have better options going forward. The trap is to use it as a quick fix that masks the real problem.

    We’re here to help you build the plan, not just move the debt. If your credit isn’t where it needs to be for the best offers, let’s fix that first.

    Request a free credit audit or quote.

    Disclaimer: This article is for educational purposes only and does not constitute legal or financial advice. Individual results vary based on credit history, lender requirements, account terms, and other factors. No credit repair organization can guarantee the removal of accurate, verifiable information from a credit report.

  • What’s the Average Credit Score in America (and How Do You Compare?)

    What’s the Average Credit Score in America (and How Do You Compare?)

    If you’ve ever pulled your credit score and immediately wondered, “Is that good?” — you’re not alone. It’s one of the most common questions we hear at credit-repair.com, and it’s a fair one. A number on its own doesn’t tell you much. What you really want to know is where you stand relative to everyone else, what that number unlocks (or blocks) for you, and whether you have room to move up.

    That’s exactly what this guide is about. We’ll walk through the average credit score in America right now, how it’s shifted over the past decade, how it breaks down by age and state, and — most importantly — what those numbers actually mean for your borrowing power, your monthly costs, and your financial future. We’ll also get honest about why the “average” is useful context but not the whole story, especially when credit reports contain errors that quietly drag scores down.

    No hype. No “raise your score 100 points overnight” promises. Just a clear, trustworthy picture of where things stand and what you can realistically do about it.

    The Current Average Credit Score in America

    As of recent data, the average FICO score in the United States sits around 715 to 718. We say “around” deliberately, because the number shifts slightly from quarter to quarter and depends on which scoring model and which bureau’s data you’re looking at. FICO and VantageScore use slightly different scales and pull from slightly different data, so you’ll see figures hovering anywhere in that 715–718 band depending on the source.

    Here’s the important framing: that average lands squarely in the “good” credit range. FICO’s official score ranges look like this:

    Score Range Rating
    300–579 Poor
    580–669 Fair
    670–739 Good
    740–799 Very Good
    800–850 Exceptional

    So the average American, statistically speaking, has good credit — not great, not poor. They can qualify for most loans and credit cards, but they’re not getting the very best rates lenders reserve for the 740+ and 800+ crowds. That’s a meaningful distinction we’ll come back to, because the difference between “good” and “very good” can translate into thousands of dollars over the life of a loan.

    A Quick Note on Where These Numbers Come From

    FICO scores are calculated using data from the three major credit bureaus — Equifax, Experian, and TransUnion. The average we’re referencing comes from FICO’s periodic publications based on millions of consumer credit files. VantageScore, the competing model created jointly by the three bureaus, tends to report a similar average (usually within a few points). When you see a headline like “the average credit score hit 715,” it’s almost always FICO data.

    Your own score will vary a bit depending on which bureau’s data was used and which scoring model the lender pulls. It’s completely normal to see a 10- or 20-point swing between, say, your Experian FICO 8 and your TransUnion FICO 8. That’s not a glitch — it’s because not every creditor reports to every bureau, and reporting timing can differ. We’ll dig into this more in the FAQ.

    How the Average Has Trended Up Over the Past Decade

    Here’s something that might surprise you: the average credit score in America has been climbing steadily for years. A decade ago, the national average FICO score was sitting closer to 695. Today it’s around 715–718. That’s roughly a 20-point gain over ten years — not a dramatic leap, but a clear, sustained upward drift.

    What’s Driving the Rise?

    Several factors have pushed scores upward:

    • Greater access to credit information. Free credit score services, credit-monitoring apps, and lender-provided scores on monthly statements have made consumers far more aware of their credit than they were a generation ago. Awareness drives behavior.
    • The pandemic effect. During 2020 and 2021, stimulus checks, paused student loan payments, reduced spending on travel and dining, and forbearance programs gave many households room to pay down debt. Average scores jumped noticeably during this period — one of the few silver linings of a difficult time.
    • Improved consumer protections. Changes like the removal of certain tax liens and civil judgments from credit reports, and agreements to wait longer before reporting medical collections, removed negative marks from many files.
    • A shift toward longer credit histories. As the population ages and older adults maintain accounts longer, average credit history length — a factor in scoring — has nudged upward.
    • Better financial education. Schools, employers, and nonprofits have invested more in financial literacy, and a lot of that education focuses on the mechanics of credit building.

    But the Average Doesn’t Tell the Whole Story

    Here’s the honest caveat: a rising average doesn’t mean everyone’s doing better. The distribution matters. What’s really happened is that a lot of people moved from “fair” into “good,” and a meaningful chunk moved from “good” into “very good.” But a significant portion of the population — roughly 1 in 6 Americans — still has a score below 580. The average can go up while a lot of people stay stuck, and that’s exactly what’s happened.

    We’ll come back to this point throughout the article, because it’s the core reason we encourage people to look beyond the headline number. Your goal isn’t to match the average. Your goal is to understand your own file, fix what’s holding it back, and build from there.

    Average Credit Score by Age Group

    This is where the data gets genuinely interesting, because credit scores follow a remarkably predictable pattern: they rise with age. That’s not because older people are somehow “better” with money. It’s because the scoring model rewards things that accumulate over time — longer credit histories, more accounts paid on time, and lower credit utilization as people pay down debt and earn more.

    Here’s a breakdown of average credit scores by age group based on recent FICO data:

    Age Group Generation Average FICO Score Range Rating
    18–25 Gen Z ~679 Fair to Good
    26–41 Millennials ~690 Good
    42–57 Gen X ~709 Good
    58–76 Boomers ~745 Very Good
    77+ Silent Generation ~760 Very Good

    Why Younger Americans Score Lower

    If you’re in your twenties or early thirties and your score feels lower than you’d like, there’s a structural reason for that. Credit scoring models favor history.

    The length of your credit history accounts for about 15% of your FICO score, and the age of your oldest account, your newest account, and the average across all accounts all factor in. A 23-year-old simply hasn’t had time to build a 15-year track record.

    Younger consumers also tend to have:

    • Thinner credit files — fewer accounts means less data for the scoring model to work with, and one missed payment can swing the score more dramatically.
    • Higher credit utilization — younger people often have lower credit limits, so even modest balances use up a bigger percentage of available credit.
    • Student loan debt — which, while not inherently bad for credit, adds to overall debt load and can hurt if payments are missed.
    • Newer accounts — every time you open a new card or loan, it temporarily lowers the average age of your accounts.

    Why Older Americans Score Higher

    Boomers and the Silent Generation tend to score well because they’ve had decades to:

    • Build long, clean payment histories (payment history is 35% of your score — the single biggest factor).
    • Pay down mortgages and other installment loans.
    • Accumulate multiple accounts in good standing.
    • Establish high credit limits with low balances, which means low utilization.

    This isn’t about moral virtue or financial wisdom. It’s about the math of the scoring model. Time is a legitimate credit-building tool, and older adults have more of it working in their favor.

    The Takeaway for Every Age

    If you’re young, don’t panic. Your score has more upward potential than any other group’s, and small habits — paying on time, keeping balances low, avoiding unnecessary new accounts — compound quickly. If you’re middle-aged and feeling stuck, that’s often the signal of a specific issue dragging your score down (a collection, a high-utilization card, an error on your report). And if you’re older, your job is mostly preservation: keep accounts open, keep utilization low, and watch for errors that can quietly chip away at hard-earned scores.

    Average Credit Score by State

    Credit scores also vary geographically, and the patterns reveal something important: scores correlate heavily with local economic conditions — income levels, cost of living, housing markets, and access to traditional banking. States with higher median incomes and stronger job markets tend to have higher average scores, while states with more economic hardship tend to sit lower.

    The General Picture

    Based on recent data from Experian and FICO, here’s how the country shakes out:

    Higher-average states (typically in the 730–740+ range) tend to include:

    • Minnesota
    • Vermont
    • New Hampshire
    • Massachusetts
    • Washington
    • North Dakota
    • South Dakota

    Lower-average states (typically in the 680–695 range) tend to include:

    • Mississippi
    • Louisiana
    • Alabama
    • Texas
    • Georgia
    • Nevada
    • Oklahoma

    Most states cluster somewhere in the 700–720 band, which lines up with the national average.

    Why the Regional Spread?

    A few structural factors explain most of the variation:

    1. Income and employment. States with higher median incomes tend to have lower credit utilization, fewer missed payments, and better access to financial tools. It’s not that wealthy people are more responsible — it’s that they have more margin.
    2. Cost of living versus wages. In states where housing and basics eat up a larger share of income, people are more likely to carry higher balances and occasionally miss payments. That directly lowers scores.
    3. Medical debt. States with higher uninsured rates tend to have more medical collections on credit reports, which can significantly drag down averages. (Recent rule changes have removed many medical collections from credit reports, but the legacy effect persists.)
    4. Access to credit. “Credit deserts” — areas with few traditional banks and credit unions — push people toward higher-cost alternative financial services that don’t build credit the same way.
    5. Cultural and educational factors. Regions with stronger financial education infrastructure tend to see better credit outcomes over time.

    What This Means for You

    Your state’s average is interesting context, but it doesn’t determine your score. We’ve worked with clients in so-called “low-average” states who have 800+ scores, and clients in “high-average” states who are fighting to break 600. Your score is about your file, not your zip code. That said, if you live somewhere with thinner financial infrastructure, it’s worth being proactive about building credit deliberately — we’ll cover how in a later section.

    What “Average” Means for Your Borrowing Power

    Here’s where the rubber meets the road. A credit score isn’t a trophy — it’s a key that unlocks (or restricts) access to financing, and the terms you get can vary enormously based on where you land on the scale. Let’s get concrete about what average credit score actually buys you.

    Credit Cards

    • Below 580: You’ll mostly qualify for secured cards (which require a cash deposit) or subprime cards with high fees and low limits. Rewards and cash-back cards are generally out of reach.
    • 580–669 (Fair): You can get unsecured cards, but APRs will be high (often 25–30%+) and limits modest. Some entry-level rewards cards become available at the top of this range.
    • 670–739 (Good — the average zone): Most mainstream cards open up, including many rewards and cash-back cards. APRs are still on the higher side, and premium travel cards may require 700+.
    • 740–799 (Very Good): You’ll qualify for most cards, including premium travel and rewards cards, with better APRs and higher limits.
    • 800+ (Exceptional): You get the best offers lenders have — lowest APRs, highest limits, premium card approvals, and often pre-approved offers with generous sign-up bonuses.

    Mortgages

    This is where the score really hits your wallet. Conventional mortgage rates are tiered, and even small differences compound over a 30-year loan. As a rough framework:

    • 760+ unlocks the best available rates.
    • 700–759 gets very competitive rates, typically within 0.25% of the top tier.
    • 680–699 sees a noticeable bump in rate.
    • 620–679 may still qualify for conventional loans (FHA loans go lower), but rates and mortgage insurance costs climb.
    • Below 620 generally means non-prime or FHA territory, with higher costs.

    To put that in real terms: on a $350,000 30-year mortgage, the difference between a rate available at 760+ and a rate available at 660 can add up to tens of thousands of dollars in additional interest over the life of the loan. That’s not a hypothetical — it’s the actual cost of a lower score.

    Auto Loans

    Auto lenders also tier their rates, and the spread is significant:

    • 750+ typically gets the advertised promotional rates (sometimes 0% financing offers on new cars).
    • 700–749 gets competitive rates, usually within 1–2 percentage points of the best.
    • 600–699 sees rates climbing — often 2–5 points higher than the best offers.
    • Below 600 can mean rates of 15%+ or difficulty qualifying without a co-signer.

    On a $30,000 car loan over 60 months, the difference between a 5% APR and a 15% APR is roughly $8,500 in extra interest. That’s real money that comes straight out of your monthly budget.

    Insurance, Rentals, and Employment

    Credit scores also influence things beyond borrowing:

    • Auto and home insurance — in most states, insurers use credit-based insurance scores to set premiums. Lower scores can mean higher premiums.
    • Rentals — landlords routinely check credit. A lower score may require a larger deposit or a co-signer, or get your application passed over entirely.
    • Employment — certain employers (especially in finance and government) check credit reports as part of background checks. They don’t see your score, but they see the underlying report.
    • Utility and cell phone accounts — lower scores may trigger security deposit requirements.

    The Bottom Line on Borrowing Power

    If you’re sitting at the national average of around 715, you’re in decent shape. You can get a mortgage, qualify for good cards, and access most mainstream financial products. But you’re not getting the best terms — those are reserved for 740 and above. Moving from 715 to 760 can be one of the highest-ROI financial moves you make, because it compounds across every loan and card you open for years to come.

    Why Comparing Yourself to the Average Is Useful — But Not the Whole Story

    We give you all these averages because context matters. Knowing the national average, your age group’s average, and your state’s average gives you a rough sense of where you stand. But we want to be clear: the average is a starting point, not a finish line.

    Averages Hide the Distribution

    The average might be 715, but that doesn’t mean most people are clustered right around 715. The actual distribution is wide — there are millions of Americans at 550 and millions at 800. The average just tells you where the center of mass is, not where you personally need to be. Two people with very different files can both be “above average” or “below average” for entirely different reasons.

    Averages Don’t Account for Your Specific Goals

    If your goal is to buy a house in the next year, the relevant threshold isn’t the national average — it’s whatever score your target lender requires for the rate you can afford. If you’re trying to refinance credit card debt, the relevant number is whatever the consolidation lender wants. Your goal should be tied to your specific milestone, not a national statistic.

    Averages Mask Individual Errors

    This is the big one, and it’s core to our work at credit-repair.com. The average is calculated across millions of credit files, including ones with errors. If a meaningful percentage of those files contain inaccuracies — a duplicate account, a misreported late payment, a collection that shouldn’t be there — then the average is being pulled down by problems that are fixable. Your score might be lower than it should be not because of anything you did, but because of something someone else reported incorrectly. We’ll dig into this more in a dedicated section below.

    Averages Don’t Reflect Your Trajectory

    A 680 score that’s been climbing steadily for two years is in a very different place than a 680 that just dropped from 720. The direction matters as much as the number. Lenders sometimes look at trends, and more importantly, you should look at trends — a dropping score is a signal to investigate, even if the number still looks “okay.”

    How to Use the Average Well

    Here’s the healthy way to use these numbers:

    • As a sanity check. If you’re 100 points below your age group’s average, it’s worth understanding why. That gap usually points to something specific.
    • As a goal-setting reference. If you’re at 660 and your age group averages 705, that gives you a concrete, realistic target.
    • As motivation, not shame. Being below average doesn’t mean you’ve failed. It means there’s room to improve, and often that improvement is very achievable.

    How to Improve From Below Average to Above Average

    This is the section most people come for. The good news: credit scores are not fixed. They update as new information flows into your credit report, which means the habits you build today start moving the needle within weeks, not decades. Here’s a practical, grounded approach — no magic, just the mechanics of how scoring actually works.

    1. Pay Every Bill on Time, Every Time

    Payment history is 35% of your FICO score — the single largest factor. One late payment (30+ days past due) can drop a good score by 80 to 100 points, and it stays on your report for up to seven years. The flip side: a long, clean payment history is the most powerful score-builder there is.

    Practical steps:

    • Set up automatic payments for at least the minimum on every account.
    • Use payment reminders or calendar alerts for anything that can’t be auto-paid.
    • If you miss a payment, catch it up within 30 days — many creditors don’t report until you’re 30 days late.
    • If you have a good history with a creditor and slip up once, call and ask for a goodwill removal. Many will remove a first-time late payment as a courtesy.

    2. Lower Your Credit Utilization

    Credit utilization — how much of your available credit you’re using — is about 30% of your score, making it the second-biggest factor and the fastest one to move. The scoring model looks at utilization both per-card and overall.

    The targets:

    • Below 30% is the widely cited threshold, but lower is better.
    • Below 10% is where you see the biggest score benefit.
    • 0% isn’t ideal — a small balance that you pay off monthly shows active use.

    Practical steps:

    • Pay down balances, and pay them before the statement closing date (that’s when balances get reported to the bureaus, not when your bill is due).
    • Ask for credit limit increases — more available credit with the same balance lowers your utilization. (Just don’t use the new limit as a license to spend.)
    • If you have a big purchase coming up, consider paying it off immediately rather than carrying the balance.
    • Spread balances across multiple cards rather than maxing one out — per-card utilization matters too.

    3. Don’t Open Unnecessary New Accounts

    Every new credit application triggers a hard inquiry, which can ding your score 5–10 points. New accounts also lower the average age of your credit history. This isn’t a reason to never open new credit — strategic new accounts can help over time — but avoid opening several cards in a short window, especially if you’re planning to apply for a mortgage or auto loan soon.

    4. Keep Old Accounts Open

    The age of your accounts matters. Closing your oldest card shortens your credit history and reduces your total available credit, both of which can lower your score. If a card has no annual fee, keep it open and use it for a small recurring charge (like a streaming subscription) to keep it active.

    5. Build a Credit Mix

    About 10% of your score comes from having a mix of credit types — revolving (cards) and installment (loans). If you only have credit cards, adding an installment loan (a personal loan, a credit-builder loan, or even a car loan you were planning anyway) can give your score a small lift over time. Don’t take on debt just for the sake of mix, but if you’re going to borrow anyway, it helps.

    6. Deal With Collections and Charge-Offs

    If you have accounts in collections, they’re dragging your score down significantly. Options:

    • Validate the debt. Collectors must prove the debt is yours and the amount is correct. If they can’t, you can dispute it.
    • Negotiate a pay-for-delete. Some collectors will remove the item from your report in exchange for payment (get any agreement in writing).
    • Pay in full vs. settle. Paid collections still hurt your score but less than unpaid. Newer FICO models (FICO 9, VantageScore 3 and 4) ignore paid collections entirely, though many lenders still use FICO 8, which counts them.

    7. Dispute Inaccuracies on Your Report

    This is where the biggest, fastest gains often hide. If your report contains errors — and a lot of them do — those errors may be the single thing holding your score down. We’ll cover this in depth in the next section.

    average-credit-score-under-100kb

    What Below-Average Scores Actually Cost You

    A below-average credit score isn’t just a number you see on an app. It can translate directly into higher borrowing costs, fewer choices, and larger deposits.

    Credit Card Costs

    Below-average scores can mean higher APRs, lower credit limits, fewer rewards options, and fewer balance-transfer opportunities. Even when you’re approved, the difference between a low APR and a high APR can become expensive if you carry a balance.

    Mortgage Costs

    Mortgage rates are particularly sensitive to credit score tiers because the loan amounts are large and the repayment period is long. A lower score can mean a higher interest rate and potentially higher mortgage insurance costs.

    Auto Loan Costs

    Auto lenders also tier their rates, and the spread is significant:

    • 750+ typically gets the advertised promotional rates (sometimes 0% financing offers on new cars).
    • 700–749 gets competitive rates, usually within 1–2 percentage points of the best.
    • 600–699 sees rates climbing — often 2–5 points higher than the best offers.
    • Below 600 can mean rates of 15%+ or difficulty qualifying without a co-signer.

    On a $30,000 car loan over 60 months, the difference between a 5% APR and a 15% APR is roughly $8,500 in extra interest. That’s real money that comes straight out of your monthly budget.

    Insurance, Rentals, and Other Costs

    Lower credit can also affect insurance premiums, rental approvals, security deposits, utility accounts, and other financial opportunities.

    How Averages Hide Credit Report Errors Pulling Scores Down

    This is the section we care about most, and it’s the heart of why we do what we do at credit-repair.com.

    Here’s a fact that doesn’t get enough attention: a meaningful percentage of credit reports contain errors. Various studies and Federal Trade Commission reports over the years have found that roughly 1 in 5 consumers have a material error on at least one of their credit reports — meaning an inaccuracy significant enough to affect their score or their ability to get credit.

    That means millions of Americans are walking around with scores lower than they deserve because of something they didn’t do. And here’s the kicker: those errors get averaged into the national “average credit score.” The headline number you see is being pulled down by fixable problems across millions of files.

    Common Types of Credit Report Errors

    Errors come in several flavors:

    • Identity errors — accounts that belong to someone with a similar name or Social Security number showing up on your report.
    • Account status errors — payments reported as late when they were on time, accounts marked as open when they’re closed (or vice versa), or accounts showing as active that you never opened.
    • Data errors — incorrect credit limits (which can artificially inflate your utilization), wrong balances, or duplicated accounts that make it look like you have more debt than you do.
    • Outdated information — negative items that should have aged off after seven years still lingering on your report.
    • Mixed files — a more serious form of identity error where two consumers’ credit histories get merged, which can drag in someone else’s collections, late payments, or bankruptcies.
    • Re-aging errors — a collection or negative account whose “date of last activity” gets incorrectly updated, making it look newer than it is and resetting the seven-year clock.
    • Furnisher errors — a creditor reporting information incorrectly to the bureaus, whether by mistake or because of sloppy record-keeping.

    Why This Matters for the Average

    When these errors pull individual scores down, they also pull the national average down. If we could wave a wand and correct every error tomorrow, the average credit score in America would almost certainly jump. That’s not a number we can quantify precisely, but given that 1 in 5 reports have material errors and many of those errors are score-lowering, the effect is real.

    This is why we say the average is “useful but not the whole story.” It includes people whose scores are artificially depressed by someone else’s mistake. Your job isn’t to beat the average — it’s to make sure your score is based on accurate information. If you’re below average and you don’t know why, an error is one of the first things to rule out.

    Your Rights Under the FCRA

    The Fair Credit Reporting Act (FCRA) is the federal law that gives you the right to an accurate credit report. Under the FCRA:

    • You have the right to see your reports from all three bureaus — free, once a year, at AnnualCreditReport.com (and currently, you can access them weekly at no cost).
    • You have the right to dispute any information you believe is inaccurate.
    • The bureaus are required to investigate your dispute, usually within 30 days.
    • If information can’t be verified, it must be corrected or removed.
    • You have the right to add a statement to your report if a dispute isn’t resolved in your favor.

    This is where attorney-backed credit repair becomes valuable. While you can dispute errors on your own, the process can be slow, frustrating, and repetitive — especially when creditors and bureaus push back. Having legal professionals who understand the FCRA, the Fair Debt Collection Practices Act (FDCPA), and the nuances of how furnishers and bureaus are required to respond can make a real difference in outcomes. It’s not about doing something you can’t do yourself — it’s about having experienced advocates who know the system and don’t get deterred by the first “verified” response.

    How to Check for Errors Yourself

    If you haven’t reviewed your three-bureau credit report recently, that’s the place to start:

    1. Pull your reports from all three bureaus (Equifax, Experian, TransUnion) via AnnualCreditReport.com.
    2. Review each one carefully. Don’t assume they’re identical — they often aren’t. Look for accounts you don’t recognize, late payments you don’t remember, balances that look wrong, and any personal information errors.
    3. Dispute inaccuracies in writing with the bureau reporting the error. Be specific: include the account name, the error, and why it’s wrong. Attach supporting documentation if you have it.
    4. Follow up. If the bureau says the item is “verified” but you know it’s wrong, you can dispute again with additional documentation, file a complaint with the Consumer Financial Protection Bureau (CFPB), or get professional help.
    5. Repeat periodically. Errors can reappear or new ones can surface. An annual review at minimum is wise; more frequent monitoring catches problems sooner.

    The Bottom Line on Errors

    If your score is lower than you’d expect — especially if you’ve been responsible with credit and can’t point to a reason — an error is a likely culprit. Don’t accept a low score as a verdict until you’ve confirmed your report is accurate. This is the single highest-leverage thing many people can do for their credit, because correcting an error can produce a faster, bigger jump than any behavioral change.

    Frequently Asked Questions

    1. What is the average credit score in America in 2026?

    The average FICO score in the U.S. is currently around 715 to 718, depending on the quarter and data source. It’s been hovering in that band for a couple of years after rising steadily through the 2010s and early 2020s. VantageScore reports a similar national average. The number fluctuates slightly as new data comes in, which is why you’ll see slightly different figures from different sources — they’re all pointing at roughly the same reality.

    2. Is a 700 credit score good?

    Yes. A 700 lands in the “good” range (670–739). You’ll qualify for most credit cards, many mortgages, and most auto loans. You’re right around the national average. That said, you’re not yet in the “very good” tier (740+) where the best rates live, so there’s meaningful room to improve — and the financial payoff of moving from 700 to 760 can be substantial, especially on mortgages and auto loans.

    3. What credit score do I need to buy a house?

    It depends on the loan type:

    • Conventional loans: typically 620+, though some lenders want 660+.
    • FHA loans: as low as 580 with 3.5% down (some lenders accept 500–579 with 10% down).
    • VA loans: no official minimum, but most lenders want 580–620+.
    • USDA loans: typically 640+.

    But qualifying and getting a good rate are different things. For the best conventional mortgage rates, you generally want 760 or higher. If you’re below that, improving your score before applying can save you a lot over the life of the loan.

    4. How fast can I raise my credit score?

    It depends on what’s holding it down:

    • High utilization — paying down balances can produce a noticeable jump within 30–60 days, because utilization updates when bureaus receive new balance information (usually monthly).
    • A recent late payment — its impact fades over time, but a goodwill removal can help immediately if the creditor agrees.
    • An error or unauthorized account — disputing and removing it can produce a jump within 30–45 days, once the bureau completes its investigation.
    • Thin credit file — building new positive history takes 6–12 months to show meaningful movement.

    Realistic expectation: most people can move 20–60 points in a few months with focused effort. Bigger gains (100+ points) usually take longer and depend on what’s on the report. Be wary of anyone promising fast, huge gains.

    5. Does checking my own credit score lower it?

    No. When you check your own score or pull your own report, it’s a “soft inquiry,” which has no effect on your score. Only “hard inquiries” — when a lender pulls your credit as part of an application — can affect your score, and even then, a single hard inquiry typically drops your score by only a few points and fades within a year. Checking your own credit is free, safe, and something you should do regularly.

    6. Why are my three credit scores different?

    Because your three credit reports aren’t identical. Not every creditor reports to all three bureaus, and even when they do, the timing of updates can differ. Since your FICO score is calculated from whatever data is in that specific bureau’s file, the scores will vary. A 10–30 point difference between bureaus is normal. If the difference is much larger, it’s a sign that something is being reported to one bureau but not the others — or that there’s an error on one report. Worth investigating.

    7. How long do negative items stay on my credit report?

    Here are the standard timeframes under the FCRA:

    • Late payments: 7 years from the missed payment date.
    • Collections: 7 years from the original delinquency date.
    • Charge-offs: 7 years from the date of the first missed payment.
    • Chapter 7 bankruptcy: 10 years.
    • Chapter 13 bankruptcy: 7 years.
    • Civil judgments: no longer reported (removed in 2017–2018 reforms).
    • Paid tax liens: no longer reported (removed in 2018 reforms).
    • Hard inquiries: 2 years (impact fades after about 12 months).

    Positive information stays much longer — often 10 years or more — which is why keeping old accounts in good standing helps your score long-term.

    8. Can credit repair actually remove accurate negative items?

    Only inaccurate, unverifiable, or outdated items can be removed through disputes — and that’s what legitimate credit repair focuses on. If a negative item is accurate, verified, and within the reporting window, it generally can’t be removed through the dispute process. What legitimate credit repair can do is make sure everything on your report meets that standard — accurate, verified, and within the time limit — and push back when it doesn’t. Be very cautious of anyone who promises to remove accurate negative items; that’s a red flag. The FCRA-compliant approach is about accuracy and verification, not erasure.

    Ready to See Where You Stand?

    Here’s our honest take: the average credit score in America is useful context, but your score is what actually shapes your financial life — and your score is based on your specific credit file, not a national statistic. The most important question isn’t “how do I compare to the average?” It’s “is my credit report accurate, and is there anything on it holding me back that shouldn’t be?”

    That’s where we come in. At credit-repair.com, we offer a free credit audit across all three major bureaus — Equifax, Experian, and TransUnion. We’ll review your reports for inaccuracies, identify items that may be pulling your score down, and walk you through what we find in plain language. No pressure, no quick-fix promises, no hidden fees. Just a clear picture of where you stand and what, if anything, is worth addressing.

    We’re a San Diego-based credit repair firm that operates in full compliance with the FCRA and works alongside experienced attorneys to make sure every step of the process is ethical, accurate, and effective. We serve clients in cities nationwide, and our approach is built on transparency and client education — because we don’t just want to help you fix your credit, we want to equip you with the knowledge to keep it strong for life.

    Start your free credit audit at credit-repair.com →

    Whether you’re above average and looking to optimize, below average and not sure why, or somewhere in between and just want a second set of eyes on your report — we’re here to help. Your credit score isn’t a verdict. It’s a snapshot, and snapshots change.

    Disclaimer: This article is for educational purposes and does not constitute legal or financial advice. Credit scores and averages cited are based on publicly available data and change over time. Individual results vary. Credit Repair is a San Diego-based, FCRA-compliant credit repair firm. We do not guarantee specific score improvements or the removal of accurate, verifiable items from your credit report.

  • How to Read a Credit Report: A Step-by-Step Guide

    How to Read a Credit Report: A Step-by-Step Guide

    If you’ve ever pulled your credit report and felt your eyes glaze over, you’re not alone. Credit reports were designed by lenders, for lenders — which means they’re packed with abbreviations, codes, and rows of data that feel like a foreign language the first time you see them. But here’s the truth: once you know what each section does, reading a credit report is surprisingly straightforward. And more importantly, it’s one of the highest-leverage things you can do for your financial life.Your credit report is the foundation everything else is built on. Lenders use it to decide whether to approve you for a mortgage, a car loan, a credit card, or an apartment lease. Insurance companies, utility providers, and even some employers look at it. The three-digit credit score you hear about in commercials? It’s calculated entirely from the information inside your credit report. So if your report contains errors — and roughly one in four reports do — those errors can quietly cost you thousands of dollars in higher interest rates, larger deposits, and missed opportunities.

    This guide walks you through every part of a credit report in plain language. You’ll learn what each section means, what to look for, what to do when something looks wrong, and how the three major bureaus differ in how they present your information. By the end, you’ll be able to pick up any credit report and read it with confidence.

    What a Credit Report Actually Is

    A credit report is a detailed record of your credit history — essentially, a financial dossier that tracks how you’ve borrowed and repaid money over time. It’s maintained by the three major credit reporting bureaus in the United States: Equifax, Experian, and TransUnion. These bureaus collect information from creditors (banks, credit card issuers, auto lenders, mortgage companies), public records sources, and collection agencies, and compile it into a standardized report.

    Your report contains identifying information, a list of every credit account you’ve opened (past and present), your payment history on each one, public records like bankruptcies or tax liens, inquiries made by lenders when you’ve applied for credit, and any accounts that have been sent to collections. It does not contain your credit score — that’s a separate calculation derived from the report’s data. It also doesn’t include your salary, bank account balances, retirement savings, or criminal history. Credit reports are specifically about borrowing behavior.

    Under federal law — specifically the Fair Credit Reporting Act (FCRA) — you have the right to see what’s in your report. You’re entitled to one free report from each bureau every 12 months through AnnualCreditReport.com, and since the pandemic, the bureaus have generally made weekly access available as well. You can also get a free report if you’ve been denied credit, insurance, or employment based on your credit, or if you suspect fraud.

    The reason understanding your report matters so much: everything flows from it. A single inaccurate late payment, a mixed file with someone who shares your name, or a collections account that was already paid can drag down your score for years. And because lenders report to the bureaus voluntarily and on their own timelines, mistakes happen more often than most people realize.

    Credit Report vs. Credit Score: The Key Difference

    People often use “credit report” and “credit score” interchangeably, but they’re two different things — and understanding the difference is the first step to reading your report effectively.

    Your credit report is the raw data. It’s the document — pages of account entries, dates, balances, and status codes. Think of it as the answer sheet.

    Your credit score is a number — usually between 300 and 850 — that’s calculated from the information in your report. It’s a summary grade. The most common scoring model is FICO, but VantageScore is also widely used. Both analyze the same underlying report data and produce a three-digit number that tells lenders, at a glance, how risky you are as a borrower.

    Here’s why this matters when you’re learning how to read a credit report: you can’t fix a score directly. You fix the report, and the score follows. If your score is lower than you’d like, the reason lives inside your report — and the only durable way to raise that score is to correct, dispute, or strategically manage what’s on the report itself.

    The five factors that most influence your FICO score, and where they live in your report:

    Factor Weight Where to Find It in Your Report
    Payment history 35% The payment history grid on each trade line
    Amounts owed (utilization) 30% Balances and credit limits on revolving accounts
    Length of credit history 15% Date opened on your oldest accounts
    Credit mix 10% Variety of account types in trade lines
    New credit / inquiries 10% The inquiries section

    So when you read your report, you’re not just looking for errors — you’re looking for opportunities. Every section tells you something about what’s helping or hurting your score.

    The Five Main Sections of a Credit Report

    While the three bureaus format their reports differently, all three organize your information into the same five core sections. Once you recognize the structure, you can navigate any report regardless of which bureau produced it.

    1. Personal Information

    This section sits at the top of your report and identifies you. It typically includes:

    • Full legal name (and any variations or aliases you’ve used on credit applications)
    • Current and previous addresses
    • Date of birth
    • Social Security number (usually partially masked, showing only the last four digits)
    • Current and former employers (reported by lenders when you list employment on an application)
    • Phone numbers associated with your file

    What to look for that’s wrong:

    Personal information errors are more common than most people think, and they can cause serious problems. A misspelled name, a wrong address, or an employer you never worked for might seem harmless, but these details are how the bureaus match you to credit data. If your file gets mixed with someone who has a similar name or lived at an address you once used, their accounts and payment history can end up on your report — a problem known as a “mixed file.”

    Check every entry carefully:

    • Are there names you’ve never used? Variations are normal (a married name, a nickname), but a completely unfamiliar name is a red flag.
    • Are all the addresses yours? An address you’ve never lived at could indicate identity theft or a mixed file.
    • Is your Social Security number correct? Even a single transposed digit can cause matching problems.
    • Are the employers listed actually places you’ve worked? Employers sometimes stay on your report long after you’ve left, which is fine — but one you’ve never heard of is not.

    Small variations (like “Jon” vs. “Jonathan”) are generally harmless and don’t need disputing. But anything that’s clearly not you should be flagged for correction.

    2. Credit Accounts (Trade Lines)

    This is the heart of your credit report. Trade lines — also called account history or credit items — are individual records for every credit account you’ve ever had. Each trade line is a mini-profile of one account, showing who the creditor is, what type of account it is, when it was opened, your current balance, your credit limit or original loan amount, and your complete payment history.

    There are two main categories of trade lines:

    Revolving accounts — credit cards, store cards, and lines of credit. These stay open indefinitely (until you or the issuer closes them) and have a credit limit you can borrow against repeatedly. Your balance fluctuates month to month.

    Installment accounts — mortgages, auto loans, student loans, and personal loans. These have a fixed original loan amount, a set repayment term, and a balance that decreases as you pay it down.

    Each trade line also has a status that tells the bureau (and anyone reading the report) what state the account is in:

    Status What It Means
    Open / Current Account is active and payments are up to date
    Pays as agreed Payments are being made on time per the contract
    30 / 60 / 90 / 120 days late Payments are past due by that many days
    Collection Account was turned over to a collection agency
    Charge-off Creditor wrote the debt off as a loss (usually after 180 days delinquent)
    Closed Account is no longer active (can be closed by you or the creditor)
    Settled You paid less than the full balance to resolve the debt
    Included in bankruptcy Account is part of a bankruptcy filing

    What to look for that’s wrong:

    Trade line errors are the most consequential mistakes on a credit report because they directly impact your payment history (35% of your score) and utilization (30%). Watch for:

    • Accounts that don’t belong to you — possibly identity theft or a mixed file
    • Late payments you believe were made on time
    • Accounts marked as open when you’ve closed them (or vice versa)
    • Balances that are significantly higher than what you actually owe
    • Credit limits reported incorrectly (a lower-than-actual limit makes your utilization look worse)
    • Duplicate accounts — the same debt listed twice
    • Accounts showing as charge-offs or collections when you’ve already paid or settled them
    • A date opened that’s wrong — this affects your average age of accounts

    We’ll go deeper into how to read each field inside a trade line in the next section.

    3. Public Records

    Public records are legal filings related to your finances that have been reported by courts or government agencies. The three types that appear on credit reports are:

    • Bankruptcies — Chapter 7 (liquidation) and Chapter 13 (reorganization) filings
    • Tax liens — unpaid tax debts claimed by a government entity (note: as of recent policy changes, the bureaus have largely removed tax liens from reports, but older reports may still show them)
    • Civil judgments — court-ordered debts resulting from lawsuits (also largely removed under recent bureau policy changes)

    Public records are among the most damaging items on a credit report. A Chapter 7 bankruptcy stays on your report for 10 years from the filing date; a Chapter 13 stays for 7 years. Tax liens and judgments, when they do appear, typically remain for 7 years.

    What to look for that’s wrong:

    • A bankruptcy that was discharged but is still showing as active
    • A bankruptcy that belongs to a family member or someone with a similar name
    • A public record that’s past the reporting window and should have fallen off
    • A tax lien or judgment that was vacated, satisfied, or dismissed but still shows as open
    • Duplicate entries for the same filing

    Public records come from court data, not from creditors, so the path to correcting them often involves both the court and the bureau. If a record is inaccurate, you’ll need documentation from the court showing the correct status.

    4. Credit Inquiries

    Inquiries are records of who has looked at your credit report. There are two types, and the distinction matters a lot:

    Hard inquiries (also called “hard pulls”) occur when a lender checks your credit in response to an application you’ve submitted — for a credit card, mortgage, auto loan, personal loan, or other credit product. Hard inquiries can affect your credit score, typically by a few points, and they stay on your report for 2 years (though FICO only factors them into your score for the first 12 months).

    Soft inquiry (also called “soft pulls”) occur when you check your own credit, when a lender sends you a pre-approved offer, when an existing creditor monitors your account, or when an employer or insurance company checks your credit with your permission. Soft inquiries do not affect your credit score at all, and they’re only visible to you on your report — not to lenders who pull it.

    We’ll cover how to read the inquiries section in detail below.

    5. Collections

    When an account becomes severely delinquent — usually 180 days past due — the original creditor may close the account, write it off as a loss (a charge-off), and either assign or sell the debt to a collection agency. That collection agency then reports the debt to the bureaus as a separate entry, creating a collections item on your report.

    Collections can also appear for medical bills, utility bills, unpaid gym memberships, apartment lease breakages, and other debts that weren’t originally traditional credit accounts. These are sometimes called “non-account collections” or “collection items without an associated trade line.”

    Collections are serious: they can drop your score by 60 to 100+ points depending on your starting score and the rest of your profile. They remain on your report for 7 years from the date of the original delinquency (the date you first missed a payment with the original creditor, before the account went to collections).

    What to look for that’s wrong:

    • A collection for a debt you’ve already paid or settled
    • A collection for a debt that isn’t yours
    • A collection that’s past the 7-year reporting window
    • Duplicate collections — the same debt reported by multiple agencies (this happens when a debt is sold from one collector to another and both report it)
    • A collection with a wrong balance or wrong original creditor
    • Medical collections that should have been removed under the recent policy changes (medical collections under $500 are generally no longer reported, and paid medical collections are removed)

    How to Read Each Account Entry

    Now let’s zoom in on a single trade line. Understanding each field is what allows you to actually audit your report rather than just skim it.

    A typical trade line on your report will include these fields:

    Creditor Name and Account Number

    The name of the lender and a partially masked account number (usually showing only the last four digits). Verify the creditor is one you recognize and the account number matches your records.

    Account Type

    Whether the account is revolving (credit card, line of credit) or installment (mortgage, auto loan, student loan). This affects how the account factors into your credit mix.

    Date Opened

    The month and year the account was opened. This is important for two reasons: it contributes to your length of credit history, and it’s a common source of errors. If a date opened is later than it should be, your account appears younger than it is, which can lower your average age of accounts.

    Date of First Delinquency (DOFD)

    This is one of the most important — and most overlooked — dates on your report. The DOFD is the date you first missed a payment on an account, before it went into default. It’s the clock that starts the 7-year reporting period for negative items. After 7 years from the DOFD, the negative item (late payments, charge-off, collection) must be removed from your report.

    Many people don’t know about the DOFD, and collectors sometimes re-age debts by reporting a more recent DOFD to keep the item on your report longer. This is illegal under the FCRA, and it’s one of the most valuable things to check when you’re auditing a negative account.

    Date of Last Activity

    The most recent date any activity occurred on the account — a payment, a charge, or a credit. This can sometimes be confused with the DOFD, but they’re different. Understanding both helps you calculate when negative items should age off.

    Credit Limit or Original Loan Amount

    For revolving accounts, this is your credit limit. For installment loans, it’s the original amount you borrowed. A revolving account with an incorrectly low limit makes your utilization ratio look higher than it is, which can hurt your score even if you pay in full each month.

    Balance

    The amount you currently owe. For revolving accounts, this is the balance as of the creditor’s last reporting date — it may not reflect payments you’ve made since. If a balance is dramatically wrong, it could be a reporting lag or an error worth disputing.

    Monthly Payment

    For installment loans, your scheduled monthly payment. For revolving accounts, this may show your minimum payment or the most recent payment amount.

    Account Status

    Whether the account is open, closed, current, delinquent, in collections, charged off, included in bankruptcy, or settled. Verify the status matches what you know to be true.

    Payment History Grid

    This is a series of symbols (usually a grid of squares or a list of codes) showing your payment status for each month the account has been reported. A clean payment history shows a string of “OK” or green marks. Late payments show up as 30, 60, 90, or 120, indicating how many days past due you were that month.

    This grid is one of the first places to look for errors. A single misreported late payment can cost you 60 to 80 points, and it’s surprisingly easy for a creditor’s reporting system to glitch and mark an on-time payment as late. Cross-reference any late marks against your own bank statements or payment confirmations.

    Responsibility

    Whether the account is individual (just you), joint (you and someone else), or authorized user (someone else’s account you have permission to use). Authorized user accounts affect your score but aren’t your legal responsibility to repay.

    Remarks

    Free-text notes from the creditor or bureau. These might say “Account closed at consumer’s request,” “Lost or stolen card,” or “Payment deferred.” Remarks can provide useful context but can also contain errors.

    The most common trade line errors, ranked by score impact:

    1. Late payments that were actually on time (highest impact — 35% of score)
    2. Incorrect credit limits inflating your utilization (30% of score)
    3. Accounts that don’t belong to you (possible identity theft or mixed file)
    4. Duplicate accounts doubling your reported debt
    5. Charge-offs or collections that have been paid but still show as unpaid
    6. Wrong date opened artificially shortening your credit history

    How to Read the Inquiries Section

    The inquiries section lists every entity that has pulled your credit report. Reading it correctly comes down to distinguishing hard from soft inquiries and knowing what each one means.

    Hard Inquiries

    Each hard inquiry entry will show:

    • The name of the company that pulled your report
    • The date of the inquiry
    • The type of inquiry (usually labeled “credit application” or similar)

    Hard inquiries happen when you apply for credit. They’re initiated by your action. Common triggers:

    • Applying for a credit card
    • Applying for a mortgage or refinancing
    • Applying for an auto loan
    • Applying for a personal loan or student loan
    • Requesting a credit limit increase (sometimes — depends on the issuer)
    • Applying for an apartment rental (sometimes)
    • Opening a utility or cell phone account (sometimes)

    Rate shopping protection: If you’re shopping for a mortgage, auto loan, or student loan, multiple inquiries for the same type of credit within a short window (typically 14 to 45 days, depending on the scoring model) are usually counted as a single inquiry for scoring purposes. This is designed so you can compare rates without each application dinging your score separately. So if you’re buying a car and apply at three different banks in two weeks, it counts as one inquiry on your score — though all three will still show up individually on your report.

    What to look for that’s wrong:

    • Hard inquiries from companies you don’t recognize and didn’t apply with — this could be identity theft
    • Duplicate inquiries from the same lender on the same day (these can sometimes be consolidated)
    • Inquiries older than 2 years that haven’t fallen off

    If you see a hard inquiry you didn’t initiate, it’s worth investigating. Start by contacting the company that made the inquiry to find out what application triggered it. If it was fraudulent, you can dispute it and consider placing a fraud alert or security freeze on your file.

    Soft Inquiries

    Soft inquiries show up in a separate section of your report. They include:

    • Your own credit checks (when you pull your own report)
    • Pre-approved offer screenings by lenders
    • Account monitoring by your existing creditors
    • Insurance or employment checks (with your permission)
    • Public-record database updates

    Soft inquiries never affect your credit score. You can have dozens of them and it won’t matter. They’re listed for your information so you can see who’s been looking at your file, but they’re not a cause for concern unless you see something truly unfamiliar — which could indicate someone is accessing your credit information without authorization.

    How to Read Public Records

    Public records are the most severe items that can appear on your credit report, and reading them correctly requires understanding what each type means and how long it should stay.

    Bankruptcies

    A bankruptcy entry will typically show:

    • The court where the filing was made
    • The filing date
    • The case number
    • The chapter (Chapter 7 or Chapter 13)
    • The disposition (filed, dismissed, or discharged)
    • The discharge or dismissal date

    Reporting timelines:

    • Chapter 7: 10 years from the filing date
    • Chapter 13: 7 years from the filing date
    • Dismissed Chapter 13: 7 years from the dismissal date
    • Dismissed Chapter 7: 10 years from the filing date (dismissed means the case was thrown out, not completed)

    What to look for: A bankruptcy that’s past its reporting window should be removed automatically, but it doesn’t always happen. If yours is older than the limit, dispute it. Also verify the chapter is correct — a Chapter 13 mistakenly reported as Chapter 7 would stay on your report three years longer than it should.

    Tax Liens and Civil Judgments

    Due to policy changes implemented by all three bureaus between 2017 and 2018, most tax liens and civil judgments have been removed from credit reports. The bureaus made this change because the data was often incomplete or mismatched to the wrong person. However, it’s still worth checking your report for any lingering entries, especially if you’re looking at an older report or one that includes supplemented data.

    If you do see a tax lien or judgment:

    • Verify it’s actually yours
    • Check whether it’s been satisfied, vacated, or dismissed
    • Confirm the date — if it’s more than 7 years old, it should be removed
    • If it’s been satisfied but still shows as open, dispute it with supporting documentation

    What the Codes and Abbreviations Mean

    Credit reports use a standardized set of codes to keep things compact. Different bureaus may use slightly different formats, but the underlying meanings are consistent. Here are the most common ones you’ll encounter.

    Payment Status Codes

    Code Meaning
    0 or OK Pays as agreed, account current
    30 30 days past due
    60 60 days past due
    90 90 days past due
    120 120 days past due
    150 150 days past due
    C Current
    X No reportable activity for that month
    – Not rated / no data available

    Account Type Codes

    Code Meaning
    R Revolving account (credit card, line of credit)
    I Installment account (auto loan, mortgage, personal loan)
    O Open account (charge account, typically due in full each month)
    M Mortgage

    Account Status Codes

    Code Meaning
    1 Pays as agreed
    2 30+ days past due
    3 60+ days past due
    4 90+ days past due
    5 120+ days past due or collections/charged off
    7 Included in bankruptcy
    8 Foreclosure
    9 Charge-off

    Other Common Abbreviations

    Abbreviation Meaning
    DOFD Date of First Delinquency
    DOLA Date of Last Activity
    DOLP Date of Last Payment
    CL Credit Limit
    HC High Credit (highest balance ever reported)
    TLA Total Loan Amount (original amount borrowed)
    ECOA Equal Credit Opportunity Act code (indicates who’s responsible for the account)
    ARD Account Review Date
    FR Fraud alert

    The ECOA code is worth knowing because it tells you who’s legally responsible for the account:

    ECOA Code Meaning
    I Individual
    J Joint
    A Authorized user
    C Co-signer
    S Shared
    T Terminated
    U Undesignated

    If you’re an authorized user on someone else’s account, it should show an “A” — the account affects your score but you’re not responsible for the debt. If an account you thought was an authorized user shows up as joint or individual, that’s an error worth correcting.

    Understanding these codes turns your report from a wall of abbreviations into a readable document. When you see “R1” next to an account, you know it’s a revolving account that pays as agreed. When you see “I5,” you know it’s an installment account that’s 120+ days past due or in collections — a serious issue that needs attention.

    Section-by-Section Audit Checklist

    When you’re ready to actually audit your report, work through each section methodically. Here’s a checklist you can follow for every credit report you pull.

    1. Personal information: Verify every name, alias, address, employer, and date of birth listed. Flag anything you do not recognize. Wrong personal data is both an error in itself and a leading cause of mixed files.
    2. Account history: Verify the account name and number, open date, account status, credit limit or original loan amount, balance, monthly payment, payment history, date of last activity, and responsibility.
    3. Public records: Check for bankruptcies, civil judgments, and tax liens. Verify each is actually yours, was reported correctly, and is within its reporting window.
    4. Inquiries: Scan hard inquiries for any you do not recognize. An unrecognized hard inquiry may be an error or a sign of identity theft.
    5. Collections: Verify each collection is yours, that the amount is correct, and that the original delinquency date is accurate. If a collection was paid or settled and is still showing an unpaid balance, that is an error.

    credit-report-how-to-read-under-100kb

    How the Three Bureaus’ Reports Differ

    The three credit bureaus — Equifax, Experian, and TransUnion — maintain separate databases, so the information on your reports will not necessarily be identical.

    This means an account might appear on your Equifax and Experian reports but not your TransUnion report — and that’s normal, not necessarily an error.

    Differences also arise from:

    • Reporting timing: Each creditor sends updates on their own schedule, so the same account may show a slightly different balance or status depending on when each bureau last received an update.
    • Data formatting: Each bureau formats its reports differently. Field names, section order, and code displays vary, so the same account looks different on each report.
    • Public record sourcing: Each bureau obtains public records from slightly different sources and at different intervals.
    • Dispute resolution: When you dispute an item, the correction happens at the bureau you disputed with. If you dispute an error only with Equifax, it remains on your Experian and TransUnion reports until you dispute it with them too.

    Format differences between the bureaus

    While the underlying data structure is the same (personal info, trade lines, public records, inquiries, collections), each bureau presents it differently:

    Equifax tends to present trade lines in a structured list with clear field labels. Inquiries are split into separate sections for hard and soft. The format is generally considered the most straightforward to read for beginners.

    Experian groups accounts by type (mortgage, installment, revolving, collections) and uses a detailed payment history grid. It also includes a “potentially negative items” summary at the top that flags items the bureau considers harmful to your score.

    TransUnion uses a more narrative format with accounts grouped by status. It often includes more employer and address history than the other two. The layout can feel denser, but it also surfaces a lot of detail.

    What this means for you

    The practical takeaway: you need to check all three reports. Reviewing only one leaves blind spots. An error on your TransUnion report that’s costing you 50 points won’t show up on your Equifax report, and a lender that pulls TransUnion will see the error even if your other two reports are clean.

    This is also why, when you dispute an error, you generally need to dispute it with each bureau separately. The FCRA requires each bureau to investigate disputes independently — correcting one doesn’t automatically correct the others.

    If pulling and reviewing three separate reports feels overwhelming, that’s exactly the kind of work a credit repair service handles for you. A reputable firm pulls all three reports, audits each one line by line, identifies errors across all three, and manages the dispute process with each bureau simultaneously.

    What to Do When You Spot an Error

    Finding an error on your credit report is frustrating, but the FCRA gives you a clear, legally backed process for correcting it. Here’s how it works.

    Step 1: Gather your documentation

    Before you dispute anything, collect evidence that supports your claim. This might include:

    • Bank or credit card statements showing on-time payments
    • A letter from a creditor confirming an account was closed, paid, or settled
    • Court documents showing a bankruptcy discharge, a vacated judgment, or a dismissed case
    • A police report or FTC Identity Theft Report if the error is the result of fraud
    • Your own records of the account’s correct balance, credit limit, or date opened

    The stronger your documentation, the more likely the dispute succeeds quickly.

    Step 2: Dispute with the credit bureau(s)

    You can dispute errors online, by phone, or by mail with each bureau. Many consumer advocates recommend submitting disputes by mail with certified mail return receipt, because it creates a paper trail and forces the bureau to respond within a specific legal timeframe. However, online disputes are faster and are now widely accepted.

    Under the FCRA, the bureau must investigate your dispute within 30 days (sometimes 45 days if you submit additional information during the investigation). They must forward your dispute to the creditor that furnished the information, and that creditor must review and respond. If the creditor can’t verify the information, or doesn’t respond in time, the bureau must remove or correct the item.

    Important: Dispute the error with each bureau that’s reporting it. Correcting it with one doesn’t correct it with the others.

    Step 3: Dispute with the creditor (furnisher)

    If the bureau’s investigation comes back “verified” and you believe the information is still wrong, you can dispute directly with the creditor that furnished the information — known as the furnisher. Under FCRA Section 623, furnishers have an obligation to investigate disputes and correct inaccurate information. Send them the same documentation you sent the bureau, along with a clear statement of what’s wrong and what you want corrected.

    Step 4: Add a statement of dispute

    If the dispute is resolved in the creditor’s favor and the item remains, you have the right to add a 100-word statement of dispute to your credit file. This statement doesn’t change your score, but anyone who pulls your report will see your side of the story. In practice, this rarely helps with automated lending decisions, but it can matter for manual reviews — like a mortgage underwriter or a landlord reading your report.

    Step 5: Escalate if necessary

    If the bureau and the furnisher both refuse to correct a genuine error, you have additional options:

    • File a complaint with the Consumer Financial Protection Bureau (CFPB). The CFPB forwards complaints to the company and tracks their response. This often gets attention that individual disputes don’t.
    • File a complaint with your state attorney general’s office.
    • Consult a consumer protection attorney. The FCRA allows consumers to sue for actual damages, statutory damages, and attorney’s fees when a bureau or furnisher willfully or negligently violates the law.

    For a deeper dive into the dispute process, including templates and timelines, see our guide to disputing credit report errors.

    What not to do

    A few common mistakes to avoid:

    • Don’t dispute everything at once. Filing a dozen disputes simultaneously can cause the bureau to flag your disputes as frivolous, which lets them dismiss them without investigating. Prioritize the most impactful errors first.
    • Don’t dispute accurate information. If a late payment is real, disputing it won’t remove it (and repeated disputes on the same accurate item can get your future disputes ignored).
    • Don’t close accounts in response to errors. Closing an account to “get rid of it” can shorten your credit history and increase your utilization. Dispute the error instead.
    • Don’t pay a collection just to make it disappear. Paying a collection updates the balance to zero but doesn’t remove the entry from your report (unless you negotiate a “pay-for-delete” agreement in writing beforehand). The collection still shows for 7 years from the DOFD — it just shows as paid rather than unpaid. Whether paying helps your score depends on the scoring model; newer FICO and VantageScore models ignore paid collections, but older models still count them.

    Frequently Asked Questions

    How often should I check my credit report?

    At minimum, pull all three reports once a year through AnnualCreditReport.com. Many people benefit from staggering them — pulling Equifax in January, Experian in May, and TransUnion in September — so you’re checking a fresh report every four months. If you’re actively repairing your credit, monitoring for fraud, or preparing for a major purchase like a home, check more frequently. The bureaus currently allow weekly pulls at no cost.

    Will checking my own credit report hurt my score?

    No. When you pull your own report, it’s a soft inquiry and has zero impact on your score. This is true whether you use AnnualCreditReport.com, a credit monitoring service, or your bank’s free credit dashboard. You can check your own report as often as you like without any penalty.

    What’s the difference between a credit report and a credit monitoring service?

    A credit report is the document itself — the full record of your credit history from a specific bureau. A credit monitoring service is a tool that watches your credit file and alerts you to changes (new inquiries, new accounts, status changes, score movements). Monitoring services are useful for catching fraud early and tracking progress, but they’re not a substitute for sitting down and reading your full report carefully at least once a year.

    How long do negative items stay on my credit report?

    The general rule is 7 years from the date of first delinquency (DOFD) for most negative items — late payments, collections, charge-offs, foreclosures, and settled accounts. Chapter 13 bankruptcy stays for 7 years from the filing date; Chapter 7 stays for 10 years. Unpaid tax liens, when they do appear, can stay indefinitely until paid, then 7 years from the payment date — though, again, most liens have been removed under current bureau policy. Positive accounts can stay on your report indefinitely and are helpful to your score, so there’s no need to worry about old good accounts.

    What if an error keeps coming back after I dispute it?

    Sometimes a creditor re-reports the same inaccurate information after a bureau removes it. If this happens, dispute again with updated documentation and include a note explaining that the item was previously removed. If the furnisher continues to report information they can’t verify, you may have an FCRA claim worth discussing with a consumer protection attorney. Filing a CFPB complaint at the same time often accelerates a resolution.

    Can I remove accurate negative items from my report?

    You can’t legally force the removal of accurate, verifiable negative information before its reporting window expires. If a credit repair company promises to remove accurate items, be skeptical — this is one of the most common signs of a scam. What you can do is build positive credit history alongside the negative items, so the impact diminishes over time. Negative items hurt less the older they get, and a strong recent payment pattern can outweigh older mistakes. The one legitimate path to early removal is a goodwill letter — asking the creditor directly to remove a late payment as a courtesy, which sometimes works for long-time customers with otherwise clean records.

    Do all three bureaus have the same information on me?

    No. Not all creditors report to all three bureaus, so your reports can differ in which accounts appear, what balances are shown, and even what personal information is listed. This is why it’s important to check all three — an error or a fraudulently opened account might appear on only one report.

    How can a credit repair firm help me with my credit report?

    A reputable, FCRA-compliant credit repair firm handles the audit and dispute process for you. That means pulling all three bureau reports, reviewing every trade line, public record, inquiry, and collection for accuracy and compliance with reporting rules, preparing and submitting disputes with the appropriate documentation, following up when disputes are verified or re-reported, and escalating to furnishers, the CFPB, or attorneys when needed. The best firms also educate you on how to build positive credit going forward so you’re not just fixing the past but strengthening the future. The key is choosing a firm that’s transparent about pricing, operates within the law, and doesn’t make guarantees about specific outcomes — because no one can promise a particular score increase or removal of accurate items.

    Get a Free Credit Audit

    Reading your credit report is one thing. Auditing all three — line by line, code by code, checking every DOFD and status flag against what’s legally allowed — is another. It’s detailed work, and it’s easy to miss something when you’re not sure what you’re looking at.

    That’s where we come in. At credit-repair.com, we offer a free credit audit that covers all three bureau reports — Equifax, Experian, and TransUnion. We’ll pull your reports, walk through every section with you, identify errors, outdated items, and anything that shouldn’t be there, and give you a clear picture of where your credit stands and what’s holding it back.

    We’re a San Diego-based, attorney-backed credit repair firm that operates in full compliance with the Fair Credit Reporting Act. We don’t make empty promises or sell quick fixes. What we do is the careful, legal, evidence-based work of correcting what’s wrong on your report and equipping you with the knowledge to keep your credit strong for the long term.

    Every client gets:

    • A full tri-bureau credit audit
    • A personalized repair plan tailored to your specific goals
    • Dispute management with all three bureaus and with original creditors
    • Ongoing education so you understand your credit and how to protect it
    • Transparent, affordable pricing with no hidden fees

    Your credit report shouldn’t be a mystery, and the errors on it shouldn’t cost you. Let us read it with you — all three — and help you take control of your financial future.

    Get your free credit audit at credit-repair.com.

    This article is for educational purposes only and does not constitute legal or financial advice. Individual credit situations vary. No credit repair company can guarantee a specific score increase or removal of accurate, verifiable information.
  • Is Credit Karma Accurate? What You Need to Know About Free Scores

    Is Credit Karma Accurate? What You Need to Know About Free Scores

    You pulled up Credit Karma, saw a solid 742, and felt a wave of relief. A week later, the mortgage lender pulls your credit and tells you the number is 689. Your stomach drops. Did Credit Karma lie to you? Is the free score you have been tracking for months completely wrong?

    The short answer is no — Credit Karma did not lie, and your score is not wrong. But it is also not the score your lender used. And that gap between what you see and what a lender sees is one of the most common — and most frustrating — sources of confusion in the credit world.

    Credit Karma accuracy is a nuanced topic. The platform shows real, legitimate credit scores generated from real credit report data. Those scores are calculated by established scoring models and pulled directly from two of the three major credit bureaus. Nothing about them is fake, inflated, or fabricated. But the specific scoring model Credit Karma uses is different from the scoring model most lenders use, and that single difference can produce a 20, 30, even 60-point gap depending on your credit profile.

    This guide walks you through exactly what Credit Karma shows you, why it so often differs from what a lender pulls, when you can trust it, when you should look elsewhere, and how to get the actual number that matters for your next loan or credit application. We have spent years helping people across the country understand the difference between educational credit scores and the scores lenders rely on, and the single most important thing we can tell you up front is this: accuracy depends on context.

    What Credit Karma Is and How It Works

    Credit Karma launched in 2007 with a straightforward premise: give people free access to their credit scores and credit reports, without requiring a credit card or a paid subscription. At the time, most credit monitoring services charged $15 to $30 a month, and pulling your own score meant navigating a maze of trial offers and cancellation deadlines. Credit Karma disrupted that model by making money through targeted advertising and credit product recommendations instead of charging the consumer.

    The platform is free to use. You create an account, verify your identity, and in return you get ongoing access to two credit scores and two credit reports, updated on a regular basis. You also get credit monitoring alerts, simulated tools that show how certain actions might affect your score, and recommendations for credit cards and loans you might qualify for.

    How does Credit Karma get your data?

    When you sign up, you provide personal information — your name, address, date of birth, and Social Security number. Credit Karma uses that information to pull your credit file from TransUnion and Equifax, two of the three major credit bureaus in the United States. (The third, Experian, is not part of Credit Karma’s core offering.) It then runs your credit file data through a scoring model to generate a three-digit score, and displays that score alongside a summary of your credit report.

    The key thing to understand is that Credit Karma is not a credit bureau. It does not maintain its own database of your credit history. It is a consumer-facing platform that retrieves data from the bureaus and presents it to you in a user-friendly way. The data itself — your accounts, balances, payment history, inquiries, and public records — comes directly from TransUnion and Equifax. The score is calculated by applying a specific scoring formula to that data.

    This is where a lot of the confusion starts. There is not one single credit score. There is not even one single FICO score. There are dozens of scoring models, each developed by different companies, each weighing credit data slightly differently, and each producing a different number from the same underlying information. Credit Karma chose to use one particular family of scoring models. Most lenders chose a different one. And that is the root of almost every “my score was different” story you have ever heard.

    The Scores Credit Karma Shows — VantageScore, Not FICO

    This is the most important section in this entire article, so read it carefully.

    Credit Karma shows VantageScore 3.0 credit scores, not FICO scores.

    VantageScore is a credit scoring model created in 2006 as a joint venture by the three major credit bureaus — TransUnion, Equifax, and Experian. It was designed as an alternative to FICO, which has been the dominant credit scoring model since the 1980s. VantageScore 3.0, released in 2013, was a significant update that adopted the same 300-to-850 score range that FICO uses, making it easier for consumers to compare the two — but the two models are not interchangeable.

    Here is why that matters: FICO and VantageScore weigh credit data differently. They use the same underlying information from your credit report — payment history, credit utilization, length of credit history, credit mix, and new credit — but they apply different formulas to that information.

    How VantageScore 3.0 Weighs Your Credit

    VantageScore 3.0 uses this approximate breakdown:

    • Payment history (40%) — whether you have paid your accounts on time
    • Credit utilization (20%) — how much of your available credit you are using
    • Credit balances (11%) — your total outstanding debt
    • Depth of credit (11%) — the age and variety of your credit accounts
    • Recent credit (11%) — new accounts and hard inquiries
    • Available credit (7%) — the total amount of credit you have access to

    How FICO Weighs Your Credit

    The classic FICO scoring model uses this breakdown:

    • Payment history (35%) — the single biggest factor
    • Amounts owed / utilization (30%) — your balances relative to your credit limits
    • Length of credit history (15%) — how long your accounts have been open
    • Credit mix (10%) — the variety of credit types you manage
    • New credit (10%) — recent applications and new accounts

    The percentages are similar but not identical, and the differences underneath are more significant than they look.

    For example, VantageScore 3.0 can score people with thinner credit files who might not be scoreable by traditional FICO models. VantageScore also treats paid collections more leniently than some FICO versions and ignores certain types of medical collections that have been paid. FICO, depending on the version, may treat these differently.

    There are also newer versions of each model. VantageScore 4.0 was released in 2017 and is used by some lenders, though Credit Karma still primarily displays VantageScore 3.0. FICO has gone through many iterations — FICO 8, FICO 9, FICO 10, and the industry-specific scores like FICO Auto Score and FICO Bankcard Score, each tuned for a particular type of lending.

    The result of all this is that you can take the exact same credit report, run it through VantageScore 3.0 and FICO 8, and get two different numbers. Sometimes the gap is small — 5 to 10 points. Sometimes it is substantial — 30 to 60 points or more. Neither score is “wrong.” They are just different interpretations of the same data, using different formulas with different priorities.

    Does Credit Karma Show VantageScore 4.0?

    As of the most recent updates, Credit Karma primarily displays VantageScore 3.0 scores from both TransUnion and Equifax. The platform has historically been slow to adopt newer VantageScore versions, and even if it did update, the core issue would remain: VantageScore, in any version, is not the same as FICO, and FICO is what the vast majority of lenders use.

    Credit Karma TransUnion and Equifax: Two Scores, Not One

    Another common point of confusion: Credit Karma shows you two different scores, not one. One is based on your TransUnion credit file, and the other is based on your Equifax credit file. These two scores are often different from each other, even though they are both calculated using the same VantageScore 3.0 model.

    Why? Because your credit file at TransUnion and your credit file at Equifax are not identical.

    Credit bureaus are independent companies. They each maintain their own database of consumer credit information. Lenders and creditors do not always report to all three bureaus. Some report to all three, some report to only two, and some report to only one. This means:

    • An account might appear on your TransUnion report but not on your Equifax report
    • A late payment might be recorded at one bureau but not another
    • A balance might be reported to one bureau on a different day than another, showing a different utilization ratio
    • A hard inquiry from a credit application might show up at one bureau but not the others

    When the underlying data is different, the score calculated from that data will be different too. So when you log into Credit Karma and see a 738 from TransUnion and a 725 from Equifax, that is not a mistake. It simply reflects the fact that the two bureaus have slightly different pictures of your credit history.

    This is also why a lender might pull a score that does not match either of your Credit Karma numbers. If the lender pulls your FICO 8 score from Experian — a bureau that Credit Karma does not even show you — then the data behind that score could be entirely different from what you are seeing on your phone.

    Why You Have Three Credit Reports, Not One

    It is worth pausing to reinforce this point, because it surprises a lot of people: you do not have one credit report. You have three. TransUnion, Equifax, and Experian each maintain a separate report on you, and while they often contain similar information, they are rarely identical. Any credit score — whether from Credit Karma, your bank, or a lender — is calculated from one bureau’s report at a time, using one scoring model. Change the bureau, change the data. Change the scoring model, change the formula. Change either one, and the number changes.

    This is why the question “is Credit Karma accurate” does not have a simple yes or no answer. The right question is: accurate compared to what?

    Why Your Credit Karma Score Often Differs From What a Lender Pulls

    Now we get to the heart of the matter. When you apply for a mortgage, auto loan, credit card, or personal loan, the lender pulls your credit. The number they see is very often different from what Credit Karma showed you. Here are the four main reasons why:

    1. Different Scoring Model

    This is the biggest factor. As we covered, Credit Karma shows VantageScore 3.0. Most lenders — roughly 90% of them, according to industry analyses — use some version of FICO. Specifically:

    • Mortgage lenders almost universally use FICO 2, FICO 4, or FICO 5 (older, mortgage-specific FICO models) pulled from all three bureaus
    • Auto lenders often use FICO Auto Scores, which are industry-specific FICO variants
    • Credit card issuers typically use FICO 8 or FICO Bankcard Scores
    • Personal loan lenders generally use FICO 8

    When a lender uses FICO 8 and Credit Karma shows you VantageScore 3.0, you are comparing two different scoring formulas applied to your credit data. The numbers will not match, and depending on your credit profile, the gap can be significant.

    2. Different Bureau

    Credit Karma shows you TransUnion and Equifax scores. Many lenders pull from Experian — the one bureau Credit Karma does not show you. If the lender pulls your Experian FICO 8 score, they are using a different bureau’s data and a different scoring model. Two variables have changed at once, and the resulting number could be quite different from either of your Credit Karma scores.

    Even when a lender pulls from TransUnion or Equifax (the same bureaus Credit Karma uses), they are still applying FICO to that bureau’s data, not VantageScore. So the bureau might be the same, but the model is different.

    3. Different Timing

    Credit scores are snapshots, not fixed numbers. They change every time new information is added to your credit report — a new balance reported by a creditor, a new inquiry, a late payment, an account closing, or even just the passage of time as your average account age increases.

    Credit Karma updates its scores on a regular schedule — typically once a week, though the exact timing depends on when the bureaus provide updated data. Between the time Credit Karma last updated your score and the time a lender pulls your credit, your report may have changed. A credit card statement may have closed, pushing your utilization up or down. A new account may have reported. A hard inquiry from another application may have appeared. Any of these can shift your score by the time the lender sees it.

    4. Industry-Specific Score Adjustments

    Some lenders use industry-specific FICO scores that are tuned for the type of lending they do. FICO Auto Scores, for example, weigh your history with auto loans more heavily. FICO Bankcard Scores weigh your credit card history more heavily. These specialized scores can be higher or lower than your standard FICO 8 score, and they are never what Credit Karma shows you.

    Putting It All Together

    When you combine all four factors — different model, different bureau, different timing, and industry-specific adjustments — it is entirely normal for a lender’s score to be 20 to 50 points different from your Credit Karma score. In some cases, the gap can be even larger, especially for people with thin credit files, recent negative marks, or high credit utilization.

    The key takeaway: a different score does not mean Credit Karma is inaccurate. It means Credit Karma is showing you a different score than the lender is using. Both scores are real. Both are calculated from real credit data. They are just not the same score.

    Is the Information Accurate? Score vs. Report Data

    To answer the question “is Credit Karma accurate” properly, we need to separate two things: the score and the report data.

    The Score Is Real, But It Is a Different Model

    As we have established, the VantageScore 3.0 scores Credit Karma shows are legitimate, real credit scores. They are calculated by VantageScore Solutions, a company jointly owned by the three credit bureaus, using a well-established and widely used scoring formula. These scores are used by some lenders — particularly in the personal loan and fintech space. They are not fake, not estimated, and not “educational only” in the way that some bank-provided scores are.

    However, they are not FICO scores, and FICO is what most lenders use. So the score is accurate for what it is, but it may not be accurate for your purpose. If you want to know whether you will qualify for a mortgage, your VantageScore is not the number the mortgage lender will use. If you want a general sense of where your credit stands and whether it is improving or declining over time, VantageScore is perfectly adequate for that.

    The Report Data Should Match the Bureau

    The credit report information Credit Karma displays — your accounts, balances, payment history, inquiries, and public records — comes directly from TransUnion and Equifax. This data should be identical to what you would see if you pulled your reports directly from those bureaus. If Credit Karma shows a credit card with a $2,500 balance and a perfect payment history, that same information should appear on your TransUnion and Equifax reports.

    But errors do happen. Credit report errors are common — studies by the Federal Trade Commission have found that roughly one in five consumers has an error on at least one of their credit reports that could affect their score. These errors are not Credit Karma’s fault; they originate at the creditor or bureau level. A creditor might report a late payment that was actually made on time. A collection account might appear that belongs to someone with a similar name. A balance might be reported incorrectly due to a data processing error.

    Credit Karma is actually a useful tool for spotting these errors, because it gives you regular, free access to your TransUnion and Equifax report data. If you see something that looks wrong — an account you do not recognize, a late payment you know you made on time, a balance that seems off — you should investigate it.

    You can dispute errors directly with the credit bureau, and under the Fair Credit Reporting Act (FCRA), the bureau is required to investigate and correct or remove inaccurate information, typically within 30 to 45 days.

    The Distinction That Matters

    So when someone asks “is Credit Karma accurate,” the most precise answer is:

    • The scores are real VantageScore 3.0 scores — accurate representations of your credit standing under that specific model, but not the same model most lenders use
    • The report data comes directly from TransUnion and Equifax — it should match what the bureaus have on file, and any errors are bureau-level errors, not Credit Karma errors
    • Neither the score nor the report data reflects what a lender will see if they pull Experian — Credit Karma does not show you Experian data at all

    Understanding this distinction is the difference between using Credit Karma as a helpful monitoring tool and being blindsided when a lender’s number does not match yours.

    When Credit Karma Is Useful

    Credit Karma is not the right tool for every situation, but it is genuinely excellent for several things. Here is where it shines:

    This is Credit Karma’s single greatest strength. Because it updates your scores regularly and shows you a history of how your score has moved over weeks, months, and years, it is an outstanding tool for tracking the direction of your credit. Is your score going up? Going down? Holding steady? What happened around the time it dropped 15 points — did a new account report, did a balance increase, did a late payment appear?

    For trend tracking, the specific scoring model matters less than the consistency of measurement. As long as Credit Karma keeps using VantageScore 3.0 from the same two bureaus, month over month, you can see whether your credit is improving. If your VantageScore goes from 680 to 720 over six months, your FICO score has almost certainly gone up too — maybe not by the exact same amount, but the direction is the same.

    Spotting Errors and Fraud Early

    Because Credit Karma monitors your TransUnion and Equifax reports and sends you alerts when something changes — a new account, a new inquiry, a new public record, a balance change — it can serve as an early warning system for identity theft and credit report errors. If a credit card you never opened shows up on your Credit Karma dashboard, you will know about it quickly and can take action.

    Monitoring Credit Utilization

    Credit Karma shows you your credit card balances and credit limits, making it easy to monitor your utilization ratio — one of the most important factors in your credit score. If you see your utilization creeping above 30%, you know it is time to pay down some balances before your score takes a hit.

    Getting Free Credit Reports

    Under federal law, you are entitled to one free credit report per year from each of the three bureaus through AnnualCreditReport.com. But once a year is not enough for many people. Credit Karma gives you ongoing access to your TransUnion and Equifax reports at no cost, which means you can check them whenever you want without waiting for your annual entitlement.

    Preparing for Major Financial Moves (With a Caveat)

    If you are planning to apply for a mortgage or auto loan in the coming months, Credit Karma can help you gauge whether your credit is in good shape generally. If your VantageScore is in the 500s, you know you have work to do before applying for anything. If it is in the mid-700s, you are probably in decent shape — though you still need to verify your FICO scores before assuming you will get the best rates.

    The caveat: use Credit Karma as a directional indicator, not a precise predictor of what a lender will see. It tells you whether you are in the ballpark, not exactly where you will land.

    When Credit Karma Is Misleading

    There are specific situations where relying on Credit Karma can lead you astray. Here are the most common ones:

    Mortgage Applications

    This is the number one scenario where Credit Karma misleads people. Mortgage lenders use older, specific FICO models — FICO 2 (Experian), FICO 4 (TransUnion), and FICO 5 (Equifax). These are not the same as FICO 8, let alone VantageScore 3.0. The older mortgage FICO models are stricter in some ways and can produce scores that are 20 to 60 points lower than what Credit Karma shows.

    We have seen clients walk into a mortgage pre-approval expecting a 760 Credit Karma score to translate into the best possible rate, only to learn their mortgage FICO scores are in the low 700s. That is the difference between an excellent rate and a good rate, which over a 30-year loan can mean tens of thousands of dollars.

    If you are applying for a mortgage, do not rely on Credit Karma. Get your actual mortgage FICO scores. (We cover how to do this later in this article.)

    Auto Loans

    Auto lenders often use FICO Auto Scores, which weigh your auto loan history more heavily than a standard FICO score. If you have a strong auto loan payment history, your FICO Auto Score might be higher than your standard FICO, and both might differ significantly from your VantageScore. If you have a repossession or late auto payments in your past, your FICO Auto Score could be lower than either your VantageScore or your standard FICO.

    When Your Scores Are Borderline

    If your Credit Karma score is sitting right at a lender’s cutoff — say, 680 for a personal loan that requires a 670 — the difference between VantageScore and FICO could push you above or below that threshold. You might think you qualify when you do not, or vice versa. In borderline situations, you need the exact score the lender will use, not an approximation.

    When You Are Rebuilding Credit

    People in the process of rebuilding credit after financial setbacks — late payments, collections, charge-offs, bankruptcies — are often the most motivated to track their progress. Credit Karma can be encouraging in these situations, because VantageScore 3.0 is sometimes more forgiving than FICO. Paid collections, for instance, may not impact your VantageScore as severely as they impact certain FICO models. You might see your Credit Karma score climb while your FICO scores lag behind, giving you an overly optimistic picture of where you stand in a lender’s eyes.

    When Experian Data Matters

    If your Experian report contains different information than your TransUnion or Equifax reports — a different balance, a different account, a different error — then any score based on Experian will differ from what Credit Karma shows. And since Credit Karma does not show Experian data at all, you could be completely unaware of something on your Experian report that is dragging down a lender’s score.

    Credit Karma vs FICO: A Side-by-Side Comparison

    Feature Credit Karma (VantageScore 3.0) FICO Scores
    Scoring model VantageScore 3.0 FICO 8, 9, 10, plus industry-specific variants
    Score range 300–850 300–850 (most models)
    Bureaus shown TransUnion and Equifax All three (depends on who pulls it)
    Used by lenders Some, primarily fintech and personal loan lenders ~90% of top lenders
    Mortgage lending Not used FICO 2, 4, 5 are standard
    Auto lending Rarely used FICO Auto Score commonly used
    Cost Free Varies — often paid through myFICO or lender
    Update frequency Typically weekly Varies by provider
    Thin file scoring Can score more consumers Requires more credit history
    Paid collections More lenient treatment Varies by FICO version
    Best for Trend tracking, monitoring, error spotting Knowing what lenders will actually see

    The comparison makes it clear: these are two different tools for two different purposes. Credit Karma is a monitoring and educational tool. FICO scores are the scores that actually determine whether you get approved for credit and at what interest rate. Both have value. Neither replaces the other.

    The Pros and Cons of Free Score Apps

    Credit Karma is the most popular free score app, but it is not the only one. Experian, Credit Sesame, NerdWallet, WalletHub, and many banks and credit card companies offer free scores too. Before you rely on any of them, it is worth understanding the general pros and cons.

    Pros

    • Free — No subscription, no credit card required, no trial period to cancel
    • Regular access — You can check your score and report data whenever you want
    • Alerts — Most apps send notifications when your score changes or new accounts appear
    • Educational tools — Simulators and articles help you understand how credit works
    • Early error detection — Regular monitoring means you catch mistakes and fraud sooner
    • Trend tracking — Seeing your score move over time is motivating and informative

    Cons

    • Not FICO (usually) — Most free apps show VantageScore, not the FICO scores lenders use
    • Advertising-driven — Free apps make money by recommending credit products, which can create a conflict of interest
    • Not all three bureaus — Most apps show one or two bureaus, not all three
    • Can create false confidence — Seeing a high VantageScore can make you assume your FICO is equally strong
    • Data lag — Scores may not reflect very recent changes to your credit report
    • Identity verification friction — Some people struggle to verify their identity, especially if they have a thin file or recently moved

    Is Credit Karma accurate showing Credit Karma score compared with FICO

    The Healthy Way to Use Free Score Apps

    Use free score apps as a monitoring layer, not as your definitive credit score. Check them regularly for:

    • Sudden score drops that signal a problem
    • New accounts or inquiries you did not initiate
    • Changes in utilization or balances
    • General upward or downward trends

    When you are preparing for a specific financial decision — a mortgage, auto loan, or major credit card application — go beyond the free app and get the actual FICO score that the relevant lender type will use.

    Other Free Score Sources Worth Knowing About

    Credit Karma is not your only option for free credit scores. Here are other sources worth knowing about, each with its own strengths:

    Discover Scorecard

    Discover offers a free FICO 8 score based on your Experian credit report, available to everyone — not just Discover cardholders. This is one of the few free sources of an actual FICO score (not VantageScore). If you want to see a real FICO 8 number without paying, Discover Scorecard is one of the best options available.

    You are limited to one score from one bureau, but it is a genuine FICO.

    Experian Free Account

    Experian offers a free consumer account that includes your FICO 8 score based on your Experian report, updated regularly. This is valuable because it gives you both Experian data and a FICO score — two things Credit Karma does not provide. Experian also offers a free credit report and credit monitoring. The free tier is genuinely useful; the paid tier adds more features but is not necessary for basic monitoring.

    Your Bank or Credit Card Provider

    Many banks and credit card issuers now provide free credit scores to their customers. Some show FICO 8 scores (Chase, Discover, Citibank, Bank of America, and others), while others show VantageScore. Check your bank’s app or website — you may already have access to a FICO score without realizing it. These are typically updated monthly and are based on the bureau the bank partners with.

    myFICO

    myFICO is FICO’s official consumer product. It is not free, but it is the most comprehensive way to see your FICO scores from all three bureaus, including industry-specific scores like FICO Auto and FICO Bankcard. If you are preparing for a major loan and want to see exactly what lenders will see, myFICO is the gold standard. There are different subscription tiers, and you can often cancel after one month if you only need a one-time snapshot.

    AnnualCreditReport.com

    This is the only federally authorized source for free credit reports from all three bureaus. You are entitled to one free report from each bureau per year (and currently, you can access them weekly). AnnualCreditReport.com does not give you scores — just reports — but seeing all three bureau reports is essential for understanding the full picture.

    Which Should You Use?

    For most people, a combination of two or three free sources is ideal:

    1. Credit Karma — for VantageScore trend tracking and TransUnion/Equifax monitoring
    2. Experian’s free account or Discover Scorecard — for an actual FICO 8 score based on Experian data
    3. Your bank or credit card’s free score — for another FICO data point, if available

    This combination gives you VantageScore trends, at least one FICO 8 score, and visibility into all three bureaus (TransUnion and Equifax through Credit Karma, Experian through the other sources). It is not a complete picture of every score a lender might use, but it is far more comprehensive than relying on Credit Karma alone.

    How to Get the Score Lenders Actually See

    If you are about to apply for a mortgage, auto loan, or other significant credit product, you want to know the actual number the lender will see — not an approximation. Here is how to get as close as possible:

    For Mortgages

    Mortgage lenders use FICO 2, FICO 4, and FICO 5 — one from each bureau. These are older FICO models, and they are not available through most free score sources. Your options:

    1. Go to myFICO.com and subscribe to a plan that includes mortgage scores from all three bureaus. This is the most direct way to see your actual mortgage FICO scores.
    2. Talk to a mortgage lender or broker about getting pre-qualified. They will pull your credit, and you can ask them to share the scores they see. This does involve a hard inquiry, so do it when you are serious about moving forward.
    3. Work with a credit repair professional who has access to tri-bureau FICO pulls and can help you understand exactly where you stand before you apply.

    For Auto Loans

    Auto lenders commonly use FICO Auto Scores, which are specialized versions of FICO that emphasize your auto loan payment history. To see these:

    1. myFICO offers FICO Auto Scores from all three bureaus as part of certain subscription tiers.
    2. Some auto dealers and lenders will tell you your score when you apply for pre-approval.

    For Credit Cards

    Credit card issuers typically use FICO 8 or FICO Bankcard Scores. FICO 8 is the most widely used general-purpose FICO model, and it is the one you are most likely to find for free (through Discover Scorecard, Experian’s free account, or your bank). If your FICO 8 score is strong, you are generally in good shape for credit card applications.

    For Personal Loans

    Personal loan lenders usually use FICO 8. The same free FICO 8 sources mentioned above will give you a solid estimate of what a personal loan lender will see.

    A Practical Strategy

    If you want a comprehensive picture without spending a fortune:

    1. Get your free VantageScore from Credit Karma for trend tracking
    2. Get your free FICO 8 from Discover Scorecard or Experian
    3. Get your free credit reports from all three bureaus at AnnualCreditReport.com
    4. If you are applying for a mortgage soon, subscribe to myFICO for one month to see your actual mortgage scores, then cancel
    5. If anything on your reports looks wrong, dispute it — or work with a credit repair professional who can help you navigate the dispute process under the FCRA

    Common Myths About Credit Karma

    There is a lot of misinformation floating around about Credit Karma. Let us clear up some of the most common myths.

    Myth 1: Credit Karma Scores Are Fake

    False. The scores are real VantageScore 3.0 scores calculated from real TransUnion and Equifax credit data. They are not estimates, not approximations, and not invented numbers. They are simply generated by a different scoring model than most lenders use.

    Myth 2: Checking Credit Karma Lowers Your Score

    False. Checking your own credit through Credit Karma is a soft inquiry, which does not affect your credit score. Only hard inquiries — which occur when a lender checks your credit as part of an application — can impact your score, and even then the effect is usually small and temporary.

    Myth 3: Credit Karma Gives You a Higher Score on Purpose So You Apply for More Cards

    Partially misleading. Credit Karma does make money from credit product recommendations, and it does show you offers you might qualify for. But it does not inflate your VantageScore to trick you into applying. The score it shows is the score the VantageScore model produces from your bureau data. The advertising model creates a potential conflict of interest in what products are recommended to you, but not in the score itself.

    Myth 4: Credit Karma and Your Lender Should Show the Same Score

    False. They use different scoring models and often different bureaus. A gap of 20 to 50 points is common and does not indicate an error on either side.

    Myth 5: Credit Karma Shows All Three Credit Bureaus

    False. Credit Karma shows TransUnion and Equifax only. Experian is not included. This means you are seeing two-thirds of your credit picture, not the full picture.

    Myth 6: If Credit Karma Shows a 750, You Will Get the Best Rate on Everything

    False. A 750 VantageScore does not guarantee a 750 FICO. And for mortgages, the relevant FICO models are older and stricter. You could have a 750 on Credit Karma and still not qualify for the best mortgage rate. Always verify your FICO scores before major applications.

    Myth 7: Credit Karma Created VantageScore to Compete with FICO

    False. VantageScore was created by the three credit bureaus (TransUnion, Equifax, and Experian) as a joint venture. Credit Karma simply chose to display VantageScore scores because they are available at lower cost than FICO scores, allowing the platform to remain free for consumers.

    Myth 8: You Should Only Check One Score Source

    False. Relying on a single score source gives you a limited view. Checking multiple sources — Credit Karma for VantageScore trends, Experian or Discover for FICO 8, your bank for another FICO data point — gives you a much more complete understanding of your credit standing.

    Frequently Asked Questions

    Is Credit Karma accurate for mortgage applications?

    No, not for mortgage applications specifically. Mortgage lenders use FICO 2, FICO 4, and FICO 5 — older FICO models that are stricter and often produce lower scores than VantageScore 3.0. If you are preparing to apply for a mortgage, check your actual mortgage FICO scores through myFICO or a mortgage lender. A 20 to 60 point gap between your Credit Karma score and your mortgage FICO scores is common.

    Why is my Credit Karma score higher than my FICO score?

    There are several reasons. VantageScore 3.0 and FICO weigh credit data differently — VantageScore gives more weight to payment history and is sometimes more lenient with paid collections and thin credit files. If your credit profile happens to be one that VantageScore treats more favorably (for example, you have a strong payment history but high utilization, which VantageScore weighs slightly less heavily), your VantageScore will be higher than your FICO. Different bureau data and timing differences can also contribute.

    Does Credit Karma show FICO scores?

    No. Credit Karma shows VantageScore 3.0 scores from TransUnion and Equifax. It does not display FICO scores in any form. If you want to see a FICO score for free, use Discover Scorecard or Experian’s free account, or check your bank or credit card issuer’s app.

    Can I trust Credit Karma for tracking my credit score over time?

    Yes. For trend tracking — watching whether your score is going up, down, or staying stable — Credit Karma is reliable. The key is to compare VantageScore to VantageScore over time, not to compare VantageScore to a FICO score at a single point. As long as you are consistent in what you are measuring, the trends will be meaningful.

    Why are my TransUnion and Equifax scores different on Credit Karma?

    Because your credit files at TransUnion and Equifax are not identical. Not all creditors report to both bureaus, balances may be reported on different days, and some accounts or inquiries may appear on one bureau’s report but not the other. Since the underlying data is different, the VantageScore 3.0 calculated from each bureau’s data will also be different. A gap of 10 to 30 points between the two is normal.

    How often does Credit Karma update my score?

    Credit Karma typically updates your scores and reports once a week, though the exact timing depends on when TransUnion and Equifax provide updated data. You may see updates more or less frequently depending on your account activity and the bureaus’ reporting schedules. You can manually refresh your reports within the app if you want to check for recent changes.

    Does checking Credit Karma hurt my credit?

    No. Checking your own credit through Credit Karma is a soft inquiry, which has no impact on your credit score. You can check as often as you like without any negative effect. Only hard inquiries — which happen when a lender checks your credit as part of an application — can lower your score, and even then the impact is usually small (a few points) and temporary.

    What should I do if my Credit Karma score does not match my lender’s score?

    First, do not panic — a difference is normal and expected. Ask your lender which scoring model and bureau they used. If they used a FICO model (which is likely), the difference is simply the model gap we have discussed throughout this article. If you suspect an error on your credit report is causing the discrepancy, pull your reports from all three bureaus at AnnualCreditReport.com and review them carefully. If you find errors, dispute them with the relevant bureau. If the errors are complex or you are not sure how to dispute them, consider working with a credit repair professional who can guide you through the process under the protections of the Fair Credit Reporting Act.

    See What Lenders See — Free Credit Audit

    If you have read this far, you understand the difference between the score Credit Karma shows you and the scores lenders actually use. You know that VantageScore and FICO are different models, that different bureaus produce different numbers, and that the score you see on your phone is not necessarily the score that determines whether you get approved — or at what interest rate.

    But understanding the difference is only the first step. The next step is seeing where you actually stand, across all three bureaus, with the scoring models that matter for your financial goals.

    That is where we come in.

    At credit-repair.com, we offer a free credit audit that pulls your credit reports from all three major bureaus — TransUnion, Equifax, and Experian — and gives you a clear, honest picture of where you stand. We do not just hand you a number. We walk you through what is on your reports, what is helping your scores, what is hurting them, and whether there are errors, outdated information, or negative marks that can be disputed under the Fair Credit Reporting Act.

    Our approach is attorney-backed and fully FCRA-compliant. That means every dispute we file, every negotiation we conduct with creditors, and every step of our process is grounded in federal credit law. We do not make empty promises or offer quick fixes — we have seen too many of those companies come and go. What we offer is transparent, legally sound, and focused on measurable progress.

    We also believe in education. We do not just fix your credit and send you on your way. We equip you with the knowledge and tools to maintain strong credit for the long term, so you are never again surprised by a gap between what you think your score is and what a lender tells you it is.

    Here is what the free audit includes:

    • A full tri-bureau credit report review (TransUnion, Equifax, and Experian — not just two)
    • An explanation of the difference between your VantageScore and FICO scores
    • Identification of errors, inaccuracies, or disputable negative items
    • A personalized repair plan tailored to your specific credit goals
    • No obligation, no hidden fees, no pressure

    Whether you are preparing for a mortgage, an auto loan, or just want to understand your credit better, the free audit is the best place to start. It is the difference between guessing and knowing.

    Visit credit-repair.com to request your free credit audit today.

    See what lenders see. Understand the numbers that actually matter. And take control of your financial future with a team that has your back — every step of the way.

    Request a credit audit or quote.

    Disclaimer: This article is for educational purposes only and does not constitute legal or financial advice. Individual credit situations vary, and results from credit repair services are not guaranteed. Credit Karma is a trademark of Credit Karma, LLC. FICO is a registered trademark of the Fair Isaac Corporation. VantageScore is a registered trademark of VantageScore Solutions, LLC. This article is not affiliated with, endorsed by, or sponsored by any of these entities.

  • Debt Settlement vs. Debt Consolidation: Which Is Better for Your Credit?

    Debt Settlement vs. Debt Consolidation: Which Is Better for Your Credit?

    If you’re staring down a pile of credit card balances, medical bills, and personal loans, you’ve probably run into two words that sound similar but mean very different things: settlement and consolidation. They’re both pitched as “debt relief.” They both promise to make your situation more manageable. But under the hood, they work in completely opposite ways — and they leave very different marks on your credit report.Here’s the short version before we go deep:

    Debt consolidation combines multiple debts into one new loan or balance transfer, ideally at a lower interest rate, so you make a single monthly payment and pay off what you owe in full. Done right, it can help your credit over time.

    Debt settlement negotiates with your creditors to accept less than the full amount you owe — usually after you’ve stopped paying them. It can slash your total debt, but it does serious, long-lasting damage to your credit.

    Neither one is a magic eraser. Both have trade-offs, costs, and risks that the late-night commercials don’t always mention. And the “right” choice depends less on which one sounds better and more on your actual financial situation: your income, your credit standing, your hardship, and your goals.

    This guide walks you through both options in plain language — how they work, what they do to your credit, what they cost, what the IRS has to do with any of it, and how to tell which one fits your life. We’ll be honest about the downsides, because the last thing you need is another promise that sounds too good to be true.

    What Is Debt Consolidation?

    <a name=“what-is-debt-consolidation”></a>

    Debt consolidation is the process of taking out a single new loan — or opening a new credit card with a balance transfer offer — and using it to pay off multiple existing debts at once. Instead of juggling five minimum payments to five different creditors at five different interest rates, you end up with one monthly payment, one due date, and (ideally) one lower interest rate.

    The key word is ideally. Consolidation doesn’t reduce what you owe — you still pay back the full principal. What it changes is the structure of your debt: fewer moving parts, a single rate, and a defined payoff timeline.

    The Main Forms of Consolidation

    There are several ways to consolidate, and they work differently:

    • Personal consolidation loan. An unsecured installment loan from a bank, credit union, or online lender. You receive a lump sum, use it to pay off your existing balances, and then repay the loan in fixed monthly installments over a set term (typically 2–7 years). Interest rates vary widely based on your credit — anywhere from around 6% for strong credit to 30%+ for weaker credit profiles.
    • Balance transfer credit card. A new card that offers a low or 0% promotional APR for a set period (often 12–21 months). You transfer existing credit card balances onto it and use the interest-free window to pay down principal. Once the promo period ends, the regular APR kicks in — which can be high.
    • Home equity loan or HELOC. If you own a home with equity, you can borrow against it to pay off unsecured debts. These typically offer lower rates because the loan is secured by your house — which means if you can’t repay, you’re putting your home at risk.
    • 401(k) loan. Some employer retirement plans let you borrow from your own account. There’s no credit check, and you pay interest back to yourself — but if you leave your job, the loan may come due quickly, and unpaid balances can become taxable withdrawals with penalties.
    • Debt management plan (DMP). Offered through nonprofit credit counseling agencies, a DMP isn’t technically a loan. The agency negotiates lower rates and fees with your creditors, you make one monthly payment to the agency, and they distribute it to your creditors. It usually takes 3–5 years to complete and often requires you to close your credit card accounts.

    What Consolidation Does Not Do

    It’s important to be clear about what consolidation doesn’t accomplish:

    • It does not reduce the principal you owe. You still pay back every dollar.
    • It does not erase negative marks already on your credit report from late payments or defaults.
    • It does not fix the spending habits that got you into debt in the fIRSt place. If you consolidate and then run your old cards back up, you’ll end up worse off than before — with the consolidation loan and new balances.

    Consolidation is a tool for reorganizing debt into a more manageable, less expensive structure. It works best for people who have a steady income, can qualify for a lower rate than what they’re currently paying, and are committed to not adding new debt while they pay the old debt down.

    How Debt Consolidation Affects Your Credit

    <a name=“how-debt-consolidation-affects-your-credit”></a>

    Here’s where a lot of people get confused — and understandably so. Consolidation affects your credit in both positive and negative ways, sometimes simultaneously. The net effect depends on how you manage the new loan and your existing accounts.

    The Short-Term Impact (Slight Dip)

    When you apply for a consolidation loan or balance transfer card, the lender pulls your credit report. That’s a hard inquiry, which typically causes a small, temporary dip in your score — usually fewer than 5 points, and it fades over 12 months (dropping off your report entirely after 24 months).

    Opening a new account also lowers the average age of your accounts, which is a factor in your credit score. If your credit history is short, this can have a modest negative effect. If you have a long, established history, the impact is minimal.

    So yes, in the fIRSt few weeks after consolidating, your score might tick down slightly. That’s normal and expected.

    The Medium-Term Impact (Potential for Real Improvement)

    Here’s the good news — and it’s genuinely good if you play it right. After consolidation, several things can start working in your favor:

    • Credit utilization drops. If you take out a personal loan to pay off credit cards, those card balances go to zero. Credit utilization — the percentage of your available credit you’re using — is one of the biggest factors in your score, and dropping it from, say, 85% to under 10% can produce a meaningful score increase. (Note: this only holds if you keep the card balances low. Running them back up erases the gain.)
    • Payment history improves. A single, manageable monthly payment is easier to make on time than five scattered ones. Payment history is the single most important factor in your credit score, and consistent on-time payments on your consolidation loan build it steadily.
    • Credit mix diversifies. If your report was all revolving credit (cards) and you add an installment loan, that mix can help slightly — scoring models like to see that you can handle different types of credit responsibly.

    The Long-Term Impact (Depends Entirely on You)

    Over the full life of the consolidation loan — whether it’s a 3-year personal loan or a 36-month DMP — the effect on your credit is almost entirely a function of your behavior:

    • Pay on time every month, keep old card balances near zero, and don’t apply for unnecessary new credit → your score generally improves, sometimes substantially.
    • Miss payments on the consolidation loan, let old card balances creep back up, or take on new debt → your score drops, and you’re in a worse position than before you consolidated.

    A consolidation loan is a piece of equipment. It doesn’t fix your credit on its own — but in the hands of someone committed to paying on time and not re-accumulating debt, it’s one of the more credit-friendly debt relief options available.

    One Caution: Closing Old Accounts

    After paying off cards with a consolidation loan, many people want to close those accounts to remove temptation. It’s a reasonable impulse — but be aware that closing old cards can lower your score in two ways: it reduces your total available credit (which can raise your utilization ratio if you carry any balances), and it shortens your average account age. In most cases, it’s better for your credit to keep the accounts open, use them sparingly for small recurring charges, and pay them in full each month. That said, if leaving them open creates a real risk of running up debt again, closing them may be the wiser personal choice — the credit score hit is recoverable, and financial stability matters more than a number.

    What Is Debt Settlement?

    <a name=“what-is-debt-settlement”></a>

    Debt settlement is fundamentally different from consolidation. Instead of paying back everything you owe under new terms, you negotiate with your creditors to accept a lump-sum payment that is less than the full balance — and in exchange, they consider the debt “settled” and close the account.

    A creditor might accept 40–60% of what you owe, for example, and forgive the rest. That sounds appealing on the surface, and it can be the right move in genuine hardship situations — but the process is harder, slower, and more damaging to your credit than most people realize.

    How the Process Usually Works

    Here’s what typically happens in a debt settlement process:

    • You stop paying your creditors. This is the part the commercials gloss over. Most creditors won’t negotiate a reduced payoff while you’re current on your payments — there’s no incentive for them to accept less than you owe if you’re paying as agreed. So settlement, whether you do it yourself or through a company, usually requires you to stop making payments and let accounts go delinquent.
    • You save up money instead. Instead of paying creditors, you set money aside — often into a dedicated savings or escrow account — to build a lump sum you can eventually offer as a settlement. This phase can take many months to several years.
    • Your accounts go delinquent, then into default. As months pass without payment, your accounts are reported as 30, 60, 90, 120+ days late. Eventually, the creditor may charge off the debt — declaring it unlikely to be collected and writing it off their books. (A charge-off does not mean the debt is gone. You still owe it, and it remains on your credit report.)
    • Negotiation begins. Once the debt is seriously delinquent or charged off — or sometimes once it’s been handed to a collections agency — you (or the settlement company) approach the creditor with a lump-sum offer. If they accept, you pay the agreed amount and the account is marked as “settled” or “settled for less than the full balance.”
    • The remaining balance is “forgiven.” The difference between what you owed and what you paid is considered forgiven — which, as we’ll cover, can create a tax obligation.

    What Settlement Does Not Do

    • It does not happen while you’re current on payments. You have to fall behind to create the leverage that makes settlement possible.
    • It does not guarantee a specific result. Creditors are not obligated to negotiate, and some may refuse entirely or sue you instead.
    • It does not remove the negative marks from your credit report. The late payments, charge-off, and “settled” notation stay on your report for up to seven years.
    • It does not stop interest and fees from accruing while you’re not paying. Your balances can actually grow during the months or years you’re building your settlement fund.

    Who Typically Pursues Settlement

    Debt settlement is generally considered an option of last resort before bankruptcy. It’s most appropriate for people who:

    • Cannot afford their monthly payments at all
    • Have already fallen significantly behind
    • Are facing accounts going to collections or lawsuits
    • Have a lump sum (or can build one) to offer creditors
    • Are genuinely considering bankruptcy as the alternative

    If you’re still current on payments and your main concern is high interest rates or the inconvenience of multiple payments, settlement is almost certainly the wrong path — consolidation is what you’re looking for.

    How Debt Settlement Affects Your Credit

    <a name=“how-debt-settlement-affects-your-credit”></a>

    This is where settlement and consolidation diverge most sharply. While consolidation can help your credit over time, settlement does significant, lasting damage — and that damage starts before any settlement is actually reached.

    The Credit Score Drop

    Let’s be direct: debt settlement typically causes a substantial drop in your credit score. The exact number depends on where your score started and how many accounts are involved, but it’s not unusual to see scores fall by 100 points or more — sometimes much more if you started with good credit.

    Here’s why the drop happens and why it’s so severe:

    • Late payments pile up. Every month you don’t pay, a new late-payment mark is added to your report. Payment history is 35% of your FICO score — the single largest factor — and a string of 90- or 120-day lates is devastating.
    • Accounts are charged off. A charge-off is one of the most serious negative items on a credit report. It signals to future lenders that you failed to repay a debt as agreed.
    • Accounts go to collections. Charged-off debts are often sold to collection agencies, which creates additional negative entries and can lead to collection accounts appearing on your report.
    • The “settled” notation. Even after a settlement is reached, the account is not marked “paid in full.” It’s marked “settled” or “settled for less than the full balance.” Future lenders viewing your report see this and understand that you did not repay the full amount you owed. It remains a negative mark.

    The Seven-Year Reporting Window

    Under the Fair Credit Reporting Act (FCRA), most negative information — including late payments, charge-offs, and settled accounts — can remain on your credit report for up to seven years from the date of the original delinquency. That’s a long time. During that window, the negative items affect your ability to qualify for new credit, the interest rates you’re offered, and sometimes your ability to rent housing, get certain jobs, or obtain insurance at favorable rates.

    The impact lessens over time — a charge-off from four years ago hurts less than one from four months ago — but the marks are present and visible for the full seven-year period.

    What Settlement Does Not Mean for Your Report

    A common misconception is that once you settle, the negative history disappears. It does not. Settling the debt changes the account status from “unpaid” or “charged off” to “settled,” but the history of late payments and the charge-off remain. The account is updated, not erased.

    Some settlement companies advertise that they’ll “remove negative items” as part of the process. Be very cautious with this claim. Accurate, verifiable negative information that is within its reporting window generally cannot be removed simply because the debt was settled — and a company that promises otherwise may be setting you up for disappointment or steering you toward disputing accurate information, which is a different (and often futile) process.

    Can You Rebuild After Settlement?

    Yes — and this is important to emphasize. A settled account is better for your credit than an unsettled charged-off account that’s still outstanding. Settling stops the bleeding: no more late payments accumulate, the balance is resolved, and the clock on the seven-year reporting window starts counting down from the original delinquency.

    From that point forward, the path to rebuilding is the same as after any major credit event:

    • Make every remaining payment on time, every time.
    • Keep any remaining credit accounts in good standing.
    • Keep utilization low on any open cards.
    • Consider a secured credit card or credit-builder loan to establish new positive history.
    • Be patient. The negative items age out, and new positive history gradually outweighs them.

    Settlement is a serious hit, but it is not permanent — and for some people in genuine hardship, the hit is worth it to resolve debts they truly cannot pay and get a fresh start.

    Debt Settlement vs. Consolidation: Side-by-Side Comparison

    <a name=“side-by-side-comparison”></a>

    Here’s a detailed comparison so you can see how the two options stack up across the dimensions that matter most.

    Dimension Debt Consolidation Debt Settlement
    What it does Combines multiple debts into one new loan or transfer; you repay the full amount owed under new terms Negotiates with creditors to accept a lump sum that is less than the full amount owed; the rest is forgiven
    Effect on total debt No reduction in principal — you still owe the full amount Reduces total debt — you pay back a fraction of what you owe
    Credit impact (short term) Small, temporary dip from hard inquiry and new account Severe — late payments begin immediately as you stop paying creditors
    Credit impact (long term) Generally positive if you pay on time and keep utilization low Significant negative marks for up to 7 years; “settled” notation remains
    Timeline to complete Typically 2–7 years (loan term or DMP length) Typically 2–4 years to negotiate and fund settlements, plus up to 7 years of reporting impact
    Monthly payment One fixed payment to the new lender or DMP agency Money set aside into a savings/escrow account instead of paying creditors; no set payment to creditors during the process
    Interest Ideally lower than what you were paying; fixed on personal loans Interest and fees continue accruing on unpaid debts until settlement is reached — balances can grow
    Upfront cost Possibly origination fees or balance transfer fees (usually 3–5%); no upfront cost for DMPs Settlement companies typically charge 15–25% of enrolled debt, often built into your monthly program payment
    Tax implications None — no debt is forgiven Forgiven debt over $600 may be reported as taxable income via Form 1099-C
    Creditor relations Creditors are paid in full; accounts closed in good standing or kept open Creditors receive partial payment; accounts marked “settled,” relationship often severed; some may sue during the process
    Risk of lawsuits Low — you’re paying as agreed Moderate to high — creditors may sue during the months you’re not paying and before settlement is reached
    Who it’s for People with steady income, decent credit, and ability to qualify for a lower rate People in genuine hardship who cannot afford payments and are considering bankruptcy
    Do you need to be behind? No — you typically need to be current to qualify Usually yes — creditors rarely negotiate while you’re current
    Effect on future credit access Minimal — a consolidation loan is a standard credit product Significant — “settled” status and charge-offs make new credit harder and more expensive to obtain for years

    When Debt Consolidation Is the Better Choice

    <a name=“when-consolidation-is-better”></a>

    Consolidation tends to be the better path when you have the means to repay your debts in full and the main problem is structure — high rates, scattered payments, or a payoff timeline that feels endlessly out of reach. Here are the signs that consolidation is likely the right fit:

    You Have a Steady Income

    Consolidation doesn’t reduce what you owe — it reorganizes it. That means you need a reliable income stream to make the new single payment month after month for the full term. If your income is stable and you can comfortably afford a consolidated payment (even if it’s tighter than you’d like), consolidation lets you trade chaos for a clear finish line.

    Your Credit Is Good Enough to Qualify for a Better Rate

    The whole point of consolidation is to lower your cost of borrowing. If your credit score qualifies you for a personal loan or balance transfer card at a significantly lower APR than what you’re currently paying, consolidation makes mathematical sense. If your credit has already deteriorated to the point where the only loans you qualify for carry rates as high as — or higher than — your current cards, consolidation may not save you money, and you should think carefully before adding a new high-rate loan on top of existing debt.

    You Want to Preserve and Build Your Credit

    If protecting your credit score is a priority — because you plan to buy a home, refinance, finance a car, or simply maintain financial flexibility — consolidation is the far more credit-friendly option. A consolidation loan is a standard, respectable credit product. On-time payments build your history. Utilization drops when card balances are paid off. There are no charge-offs, no “settled” notations, no seven-year negative reporting window. For most people who have a choice, this matters enormously.

    You’re Current (or Close to Current) on Your Payments

    Consolidation works best as a proactive move — you see the problem coming and reorganize before things spiral. If you’re still current or only slightly behind, you can likely qualify for decent rates and prevent the cascade of late payments and charge-offs that settlement requires.

    You’re Committed to Not Accumulating New Debt

    This is the make-or-break factor. Consolidation succeeds when you pay off the old debt and don’t replace it. It fails when you consolidate, then gradually run the old cards back up — leaving you with the consolidation loan plus new balances, which is a deeper hole than where you started. If you’re ready to change the spending patterns that created the debt, consolidation gives you a clean, structured runway to become debt-free.

    You Have Equity You’re Willing to Leverage (With Caution)

    If you own a home with equity, a home equity loan or HELOC can offer substantially lower rates than unsecured consolidation loans — potentially saving you thousands in interest. But this comes with a serious caveat: you’re converting unsecured debt into debt secured by your home. If you can’t repay, you risk foreclosure. This option is appropriate only for disciplined borrowers who are certain they can make the payments and who treat the home equity loan as a tool to eliminate debt, not a license to take on more.

    When Debt Settlement Is the Better Choice

    <a name=“when-settlement-is-better”></a>

    Settlement is not a “deal” or a shortcut. It’s a hardship remedy — the right option when the math of repaying your debts in full simply doesn’t work and the alternatives are worse. Here’s when settlement may be the more appropriate path:

    You’re Experiencing Genuine Financial Hardship

    Settlement exists for situations where repayment in full is not realistically possible: a job loss, a medical crisis, a divorce, a business failure, or a combination of setbacks that has made your debt load genuinely unaffordable. If you’ve cut expenses to the bone and still can’t cover minimum payments — or can only cover them by taking on new debt — you’re in the territory where settlement is worth considering.

    You’ve Already Fallen Significantly Behind

    If your accounts are already 90+ days delinquent, in collections, or charged off, the credit damage of settlement has largely already occurred. In that situation, the question is no longer “how do I protect my credit?” — it’s “how do I resolve these debts and stop the bleeding?” Settlement can close out accounts that are already in default and prevent judgments, wage garnishment, or further legal action.

    You Can’t Afford Monthly Payments Even After Consolidation

    Sometimes people look into consolidation, run the numbers, and realize that even with a lower rate and a single payment, they still can’t afford it. If a consolidated payment would still consume more than you can sustainably pay each month, consolidation is just delaying the inevitable. Settlement — by reducing the principal — may be the only option that brings the required payment within reach.

    You’re Considering Bankruptcy

    Settlement is often described as a “step before bankruptcy” — and that’s an accurate framing. If you’re seriously weighing bankruptcy because you see no other way out, settlement is worth exploring fIRSt. It can resolve debts for less than full balance without the long-term legal and credit consequences of a bankruptcy filing, which stays on your report for 7–10 years and has broader financial implications.

    That said, if your debts are truly unmanageable, your income is too low to fund settlements, and you have no assets to protect, Chapter 7 bankruptcy may actually be a faster, more complete remedy — and it’s worth consulting a bankruptcy attorney to compare. Don’t assume settlement is always better than bankruptcy; in some situations, bankruptcy is the cleaner, quicker reset.

    You Have (or Can Build) a Lump Sum

    Settlement usually requires a lump-sum offer — or at minimum, the ability to make a few large payments over a short period. If you’ve received a tax refund, an inheritance, an insurance settlement, a bonus, or the sale of an asset, and you can direct that money toward resolving delinquent debts, settlement becomes feasible. Without a lump sum, you’re relying on months of savings while your accounts deteriorate further — a slower, riskier path.

    You Understand and Accept the Credit Consequences

    This is non-negotiable. If you choose settlement, you must go in with eyes open: your credit score will drop significantly, negative marks will remain for up to seven years, and new credit will be harder and more expensive to obtain during that period. If you’ve accepted that reality and decided that resolving unaffordable debt is worth the credit hit — because the alternative is ongoing default, lawsuits, or bankruptcy — then settlement may be the pragmatic choice.

    The 1099-C Tax Issue: When Forgiven Debt Becomes Taxable Income

    <a name=“the-1099-c-tax-issue”></a>

    This is one of the most commonly overlooked aspects of debt settlement — and it can turn a “deal” into a surprise bill from the IRS.

    The Basic Rule

    When a creditor forgives $600 or more of your debt, they are generally required to send you (and the IRS) a form called Form 1099-C, Cancellation of Debt. The amount of forgiven debt is then treated as taxable income on your federal tax return for the year the forgiveness occurred.

    Here’s how that plays out. Say you owe $20,000 on a credit card and you settle for $8,000. The creditor forgives $12,000. At tax time, you receive a 1099-C showing $12,000 of canceled debt. You must report that $12,000 as income on your return — which could push you into a higher tax bracket and result in a tax bill of hundreds or thousands of dollars, depending on your overall income and bracket.

    This doesn’t mean settlement is a bad idea. But it means the real cost of settlement is higher than just the settlement amount — you need to factor in the tax impact when comparing it to other options. A $12,000 forgiveness at a 22% marginal rate means an additional $2,640 in taxes. That’s real money, and it should be part of your math.

    Exceptions and Exclusions

    There are several situations in which forgiven debt is not taxable:

    • Insolvency exclusion. If you were insolvent — meaning your total liabilities exceeded the fair market value of your total assets — immediately before the debt was canceled, you can exclude the forgiven debt from income up to the amount of your insolvency. You file Form 982 to claim this exclusion. This is the most common and important exclusion for people going through settlement, because many people in hardship situations are, by definition, insolvent.
    • Bankruptcy. Debts discharged through bankruptcy are not considered taxable income.
    • Qualified principal residence indebtedness. Historically, forgiven mortgage debt on a primary residence had a special exclusion, though this provision has expired and been extended multiple times by Congress. Check the current status with a tax professional.
    • Qualified farm or business indebtedness. Specific exclusions apply to certain farm and business debts.
    • Gifts and certain other exclusions. If the forgiveness is structured as a gift or falls under specific IRS exclusions, it may not be taxable.

    What This Means in Practice

    Before you commit to a settlement, estimate the tax impact. Add the likely tax bill to the settlement amount and compare the total to what you’d pay under a consolidation plan. In many cases — especially for people who qualify for the insolvency exclusion — settlement still comes out ahead. But for people with moderate income who don’t qualify for any exclusion, the tax bill can eat into the savings significantly.

    We strongly recommend talking to a tax professional or CPA before finalizing a settlement, especially if a large amount of debt is being forgiven. The rules around insolvency, Form 982, and the timing of the 1099-C can be nuanced, and getting it wrong on your tax return can create problems down the line.

    Debt settlement vs debt consolidation comparison

    The Risks of For-Profit Debt Settlement Companies

    <a name=“risks-of-for-profit-debt-settlement-companies”></a>

    If you decide settlement is the right path, you’ll face a choice: do it yourself or hire a for-profit debt settlement company. The for-profit settlement industry has a checkered history, and it’s important to understand the risks before signing up.

    High Fees

    Debt settlement companies typically charge fees of 15–25% of the total debt you enroll — not a percentage of what they save you, but a percentage of what you owe. On $30,000 of enrolled debt, a 20% fee is $6,000. That fee is often built into your monthly program payment, which means a meaningful portion of the money you’re setting aside each month is going to the company, not to your settlement fund.

    Federal rules under the Telemarketing Sales Rule (TSR) prohibit for-profit debt settlement companies from collecting upfront fees before at least one of your debts has been successfully settled. This is a meaningful consumer protection — but it doesn’t make the fees small. It just means they’re collected after settlements are reached, not before.

    The Escrow Account

    Most settlement companies instruct you to stop paying creditors and instead deposit money into a dedicated escrow or savings account each month. Over time, that account builds a balance the company can use to make lump-sum settlement offers.

    The risks here are real:

    • During the savings period, you’re not paying creditors. Late payments accumulate, credit scores plummet, and accounts move toward charge-off and collections. The company isn’t protecting you from this — it’s the expected process.
    • Creditors may sue you during the savings period. You might be 18 months into a program, have $5,000 in your escrow account, and get served with a lawsuit from a creditor who’s tired of waiting. Settlement companies generally do not represent you in court, and a judgment can lead to wage garnishment or bank levies.
    • The escrow account is yours, but it’s under your control. Under the TSR, the account must be held at an insured financial institution, in your name, and you must be able to withdraw from it at any time without penalty. Be wary of any company that asks you to send money directly to them rather than to an account in your name.

    No Guarantee of Results

    Creditors are not obligated to negotiate with settlement companies — and some refuse entirely. There is no guarantee that every enrolled debt will be settled, or that the settlements reached will match the “typical” 40–60% savings the company advertised. Some creditors may demand a higher percentage; some may sell the debt to a collection agency that’s harder to negotiate with; some may sue.

    A reputable settlement company will be honest about this uncertainty. A less reputable one will promise specific savings percentages and timelines — which is a red flag.

    Credit Damage Is Inevitable and Substantial

    Some settlement companies downplay the credit impact or frame it as temporary. The reality is that stopping payments on your debts — which is the core mechanism of settlement — will produce severe, multi-year negative marks on your credit report regardless of whether a company is handling the process or you’re doing it yourself. The company cannot shield your credit from the consequences of non-payment.

    “New Fees” and Other Red Flags

    Be cautious of settlement companies that:

    • Charge upfront fees before any debt is settled (this violates the TSR)
    • Pressure you to enroll immediately without reviewing your full financial picture
    • Tell you to stop communicating with creditors without explaining the consequences
    • Promise to remove accurate negative items from your credit report (they generally can’t)
    • Claim to be a government program or use official-sounding names to imply government affiliation
    • Guarantee specific savings amounts or percentages (no one can guarantee what a creditor will accept)

    A Word About Nonprofit Credit Counseling

    There is an important distinction between for-profit debt settlement companies and nonprofit credit counseling agencies. Nonprofit agencies — the kind affiliated with the National Foundation for Credit Counseling (NFCC) — do not negotiate settlements for reduced principal. Instead, they offer debt management plans (DMPs), which consolidate your payments and negotiate lower interest rates and waived fees, with the goal of paying your debts in full over 3–5 years.

    A DMP is a form of consolidation, not settlement. It’s generally a safer, more transparent option than for-profit settlement, and initial consultations with nonprofit agencies are typically free. If you’re weighing your options, a conversation with a nonprofit credit counselor is a good fIRSt step — they can help you assess whether consolidation, a DMP, or (in genuine hardship) settlement is the right path.

    DIY vs. Hiring a Company

    <a name=“diy-vs-hiring-a-company”></a>

    For both consolidation and settlement, you have the option of handling it yourself or working with a company. Here’s how the choice breaks down.

    DIY Debt Consolidation

    Consolidation is fairly straightforward to do on your own: you shop for a personal loan or balance transfer card, compare offers, apply, and use the funds to pay off your existing balances. There’s no need to pay a middleman — the process is between you and the lender.

    A debt management plan through a nonprofit counseling agency is the one form of consolidation where working with an organization adds real value: they negotiate the rate reductions and fee waivers with your creditors and manage the payment distribution. The fees are typically modest and the structure provides accountability.

    DIY Debt Settlement

    Settling debts yourself is possible and saves you the 15–25% company fee — but it requires time, persistence, negotiation skill, and emotional resilience. Here’s what the DIY path involves:

    • Stop paying the accounts you intend to settle. (This is unavoidable — settlement requires delinquency.)
    • Save the money you would have paid toward minimums into a separate account.
    • Wait until accounts are seriously delinquent or in collections — creditors usually won’t discuss settlement until then.
    • Contact each creditor (or collection agency) and offer a lump-sum settlement. Start low — many DIY settlers begin by offering 25–30% of the balance and negotiate up.
    • Get every agreement in writing before paying. Never send money based on a verbal agreement. The settlement letter should state the amount, that it settles the account in full, and that the creditor will report it as “settled” to the credit bureaus.
    • Pay the settlement and keep the letter forever. You’ll need proof if the debt resurfaces later or if a different collection agency comes after you for the remaining balance.
    • Watch for the 1099-C and handle the tax implications.

    The DIY route can work well if you have a small number of accounts, decent negotiation skills, and the discipline to manage the process over many months. It becomes harder with many creditors, large balances, or if you’re uncomfortable confronting collectors.

    When a Company Adds Value

    A settlement company can add value when:

    • You have many accounts and don’t want to manage multiple negotiations
    • You’re intimidated by dealing with collectors and creditors
    • You want a structured program that handles the escrow and offer process
    • You’re willing to pay the fee for the convenience and support

    Just go in with realistic expectations: the company cannot guarantee results, cannot prevent credit damage, and cannot stop lawsuits. Their value is in handling the logistics, not in achieving outcomes you couldn’t achieve yourself.

    How Each Path Interacts With Credit Repair

    <a name=“how-each-path-interacts-with-credit-repair”></a>

    This is where our particular perspective comes in. As a credit repair firm, we spend our days looking at credit reports and helping people address inaccurate, outdated, or unverifiable negative items. Here’s how consolidation and settlement interact with the credit repair process:

    Credit Repair and Consolidation

    Consolidation is largely credit-neutral to credit-positive, which means credit repair work and consolidation work well in parallel:

    • If you have inaccurate negative items on your report — accounts that aren’t yours, incorrect late-payment dates, duplicated collection entries, outdated information past its reporting window — credit repair addresses those independently of your consolidation. Removing inaccurate items can improve your score and even help you qualify for a better consolidation rate.
    • Consolidation itself doesn’t create disputes. It’s a straightforward financial transaction. The new loan appears on your report as a legitimate account, and there’s nothing to dispute about it.
    • As you make on-time payments on your consolidation loan, you’re building positive payment history while any credit repair work runs its course. The two efforts complement each other.

    Credit Repair and Settlement

    Settlement creates a more complex relationship with credit repair:

    • The late payments, charge-offs, and “settled” notations that result from settlement are, in most cases, accurate — they reflect what actually happened. Credit repair cannot remove accurate, verifiable negative information that’s within its reporting window. If a creditor verifies that the late payments and charge-off are accurate, those items remain.
    • However, there are situations where credit repair does help after settlement:
    • If a settled account is reported inaccurately — for example, showing an incorrect balance, wrong date of fIRSt delinquency, or a status that doesn’t match the settlement agreement — those errors can be disputed.
    • If a collection agency reports a settled debt as still owed, or if a debt buyer tries to collect on the forgiven portion, that’s a reporting error that can be challenged.
    • If negative items are older than seven years from the date of fIRSt delinquency and are still appearing, they can be disputed as outdated.
    • If the original creditor or collection agency fails to verify an item when it’s disputed, the credit bureaus may remove it — even if the underlying event was real. (This is a function of the FCRA’s verification process, not a “loophole.”)
    • The timing of credit repair relative to settlement matters. If you’re still in the settlement process — still not paying, still negotiating — it’s generally not the right moment to dispute the late payments, because they’re ongoing and accurate. Credit repair is more effective after settlement is complete, when you’re rebuilding and addressing any reporting errors or outdated items.

    The Rebuilding Phase

    Regardless of which path you choose, the period after you’ve completed consolidation or settlement is when credit repair and rebuilding efforts are most valuable. That’s when you:

    • Dispute any remaining inaccurate or outdated items
    • Establish new positive credit history with a secured card or credit-builder loan
    • Keep utilization low and payments on time
    • Monitor your report for re-aging, duplicate reporting, or other errors
    • Let time do its work — negative items age and eventually fall off

    A credit repair firm can’t undo the legitimate consequences of your debt relief choices. But it can ensure your report is accurate, that nothing is being reported erroneously, and that you’re positioned to rebuild as quickly and effectively as possible.

    Common Mistakes to Avoid

    <a name=“common-mistakes-to-avoid”></a>

    Whatever path you choose, certain mistakes trip people up repeatedly. Here are the ones we see most often:

    1. Choosing Based on the Commercial, Not Your Situation

    The debt relief industry spends heavily on marketing, and the messaging is designed to make whatever they’re selling sound like the answer. A settlement commercial makes settlement sound like a clean slate. A consolidation ad makes consolidation sound like a fresh start. Neither is inherently right for you. Choose based on your income, your credit, your hardship level, and your goals — not on which ad was more persuasive.

    2. Consolidating Without Changing Spending Habits

    This is the single most common — and most damaging — mistake. You consolidate, the card balances go to zero, and over the following months, you gradually use the cards again. By the time the consolidation loan is half paid off, the cards are loaded up again, and you’re making payments on both. The fix is behavioral, not financial: before consolidating, create a budget, identify the spending patterns that created the debt, and commit — genuinely — to not using the old cards for anything you can’t pay off in full each month.

    3. Expecting Settlement to Be Quick or Painless

    Settlement is a multi-year process that involves months of non-payment, damaged credit, collection calls, and the constant possibility of lawsuits. People who enter it expecting a fast, clean resolution often become frustrated and abandon the process midway — at which point their credit is damaged, no settlements have been reached, and they’re worse off than when they started. Go in with a realistic timeline: 2–4 years, with meaningful hardship throughout.

    4. Not Getting Settlement Terms in Writing

    If you settle a debt — whether through a company or on your own — get the terms in writing before you pay a cent. A verbal agreement over the phone is not sufficient. The written settlement letter should specify the settlement amount, that payment settles the account in full, and how the creditor will report to the credit bureaus. Without this, you may pay the agreed amount and later discover the creditor is pursuing you for the remaining balance or reporting the account differently than promised.

    5. Ignoring the Tax Implications of Settlement

    As we covered, forgiven debt over $600 can generate a 1099-C and a tax bill. Too many people are surprised by this at tax time. If you’re settling, estimate the tax impact before you agree, keep records of your assets and liabilities in case you qualify for the insolvency exclusion, and talk to a tax professional.

    6. Paying Upfront Fees to a Settlement Company

    Under the federal Telemarketing Sales Rule, for-profit debt settlement companies cannot collect fees before settling at least one of your debts. If a company asks for upfront payment, walk away — it’s a violation, and it’s a strong sign the company is not operating in your best interest.

    7. Not Exploring Nonprofit Credit Counseling First

    Before signing up with any for-profit debt relief company, talk to a nonprofit credit counseling agency. An initial consultation is typically free, and a certified counselor can help you understand whether a debt management plan, consolidation, or (in genuine hardship) settlement is appropriate for your situation. It’s an objective, low-pressure way to get professional guidance before committing to a paid program.

    8. Waiting Too Long to Act

    Debt problems rarely resolve themselves. The earlier you act — whether that means consolidating, entering a DMP, or settling — the more options you have and the less damage you typically sustain. People who wait until they’re already being sued or until every account is charged off have fewer and harder choices. If you’re struggling, take a step now, even if it’s just a free consultation.

    Frequently Asked Questions

    <a name=“faq”></a>

    Is debt settlement or debt consolidation better for my credit score?

    Consolidation is significantly better for your credit. It can cause a small, temporary dip when you apply for the new loan, but consistent on-time payments and lower credit utilization generally improve your score over time. Settlement, by contrast, requires you to stop paying creditors, which leads to late payments, charge-offs, and a “settled” notation — all of which can stay on your report for up to seven years and cause a substantial score drop.

    Can I consolidate debt if my credit score is already low?

    It depends on how low. Many lenders offer consolidation loans to people with fair credit (mid-600s and up), but the interest rates may be higher — and if your score is below the 600 range, you may struggle to qualify for a rate that’s actually better than what you’re currently paying. In that case, a debt management plan through a nonprofit credit counseling agency may be a better option, as DMPs don’t rely on your credit score for enrollment.

    Will debt settlement remove the negative items from my credit report?

    No. Settling a debt changes the account status from unpaid to “settled,” but the history of late payments, the charge-off, and the “settled” notation remain on your report for up to seven years from the original delinquency. Accurate, verifiable negative information within its reporting window generally cannot be removed simply because the debt was settled. Credit repair can address inaccurate or outdated items, but it cannot erase the legitimate record of a settled debt.

    How much can I save with debt settlement?

    There’s no set amount. Creditors may accept anywhere from 30% to 80% of the balance, depending on the creditor, the age of the debt, whether it’s been charged off, and whether it’s with the original creditor or a collection agency. For-profit settlement companies often advertise “typical” savings of 40–60%, but individual results vary widely, and there’s no guarantee any particular creditor will negotiate. You should also subtract the company’s fees (15–25% of enrolled debt) and any tax liability on forgiven debt from your “savings.”

    Do I have to pay taxes on settled debt?

    Often, yes. If a creditor forgives $600 or more of your debt, they typically issue a Form 1099-C, and the forgiven amount is generally treated as taxable income. However, if you were insolvent (your debts exceeded your assets) at the time of forgiveness, you may be able to exclude some or all of the forgiven amount using Form 982. Bankruptcy-discharged debts are also not taxable. Because the rules are nuanced, we recommend consulting a tax professional before settling.

    Can I be sued while in a debt settlement program?

    Yes. Creditors are not obligated to wait while you save up money to offer a settlement, and some may file lawsuits during the months you’re not paying. Settlement companies generally do not provide legal representation. If you’re sued, you may need to respond to the lawsuit, negotiate directly with the creditor’s attorney, or consult a consumer law attorney. This is one of the most significant risks of the settlement process.

    How long does each option take?

    Consolidation typically takes 2–7 years, depending on the term of your consolidation loan or debt management plan. Settlement typically takes 2–4 years to negotiate and fund all settlements, and the negative credit impact lasts up to 7 years from the date of fIRSt delinquency on each account. In both cases, the timeline depends on how much debt you have, your income, and how consistently you stick to the plan.

    Should I talk to a professional before deciding?

    Yes — ideally, before you commit to any program. A free consultation with a nonprofit credit counseling agency can help you understand your options without a sales pitch. If you’re considering settlement, a conversation with a consumer law attorney can help you understand the legal risks in your state. And if you’re trying to understand where your credit stands and what’s helping or hurting it, a credit audit from a reputable credit repair firm can give you a clear picture of your report and a realistic plan for improvement.

    Which Path Fits You?

    <a name=“which-path-fits-you”></a>

    There’s no universally right answer to the settlement vs. consolidation question — there’s only the answer that fits your situation. The framework is straightforward:

    • If you can repay your debts in full and the problem is high rates, scattered payments, or an endless timeline → consolidation is almost certainly your better choice. It protects your credit, simplifies your life, and gives you a clear path to debt-free.
    • If you genuinely cannot afford to repay your debts and you’re facing default, collections, or bankruptcy → settlement may be the more realistic option, despite the credit damage. It’s a hardship remedy, not a deal, and it’s appropriate when repayment in full isn’t possible.
    • If you’re somewhere in between — struggling but not yet in crisis — start with nonprofit credit counseling. A free consultation can help you figure out whether a debt management plan, consolidation, or a harder conversation about settlement is the right next step.

    And whatever you choose, remember that the debt itself is only part of the picture. Your credit report tells the story of your financial life — and making sure that story is told accurately, with any errors or outdated items addressed, is part of putting yourself in the strongest possible position going forward.

    We Can Help You See the Full Picture

    At , we offer a free credit audit that gives you a clear, honest look at what’s on your report across all three major bureaus — what’s accurate, what might be inaccurate or outdated, and what a realistic improvement plan looks like for your specific situation.

    We’re not here to sell you a quick fix, because quick fixes don’t exist in credit repair. What we do is grounded in the Fair Credit Reporting Act and the legal right every consumer has to an accurate, verifiable credit report. We work alongside experienced attorneys, we operate in full compliance with federal credit laws, and we help you understand not just what’s on your report, but what to do about it.

    Whether you’re consolidating, settling, rebuilding, or just trying to figure out where you stand, a free audit is a good place to start.

    Get your free credit audit at credit-repair.com →

    Disclaimer: This article is for educational purposes and does not constitute legal, tax, or financial advice. Debt settlement and debt consolidation have significant financial and credit implications. We recommend consulting with a qualified financial advisor, tax professional, or attorney before making decisions about your debt. Credit repair services cannot guarantee the removal of accurate, verifiable negative information from your credit report. Individual results vary.

  • How Many Hard Inquiries Is Too Many?

    How Many Hard Inquiries Is Too Many?

    If you’ve ever applied for a credit card and then watched your score dip a few points, you already know the sting of a hard inquiry. But what you might not know is when those little dents turn into a real problem — and when they’re nothing to worry about.

    One of the most common questions we hear from clients is some version of: “How many hard inquiries is too many?” It’s a fair question, and the honest answer is more nuanced than a single magic number. The credit scoring system doesn’t draw a hard line in the sand. Instead, it weighs the recency, clustering, and type of inquiries to judge how much risk you represent.

    This guide walks you through everything you need to know — what a hard inquiry actually is, how many points it typically costs, when lenders start raising eyebrows, how the rate-shopping window works, how different scoring models treat inquiries, and what to do if you’ve already accumulated more than you’d like. No quick-fix promises, no scare tactics — just a clear, honest breakdown so you can make confident decisions about your credit.

    What Is a Hard Inquiry (and How Is It Triggered)?

    A hard inquiry (sometimes called a “hard pull”) is a formal review of your credit file that occurs when you actively apply for new credit. It’s the lender’s way of saying: “This person is asking to borrow money — let’s look at their full credit picture before we decide.”

    Hard inquiries are triggered when you apply for:

    • A new credit card
    • An auto loan or auto refinance
    • A mortgage or mortgage refinance
    • A personal loan or installment loan
    • A student loan
    • A business credit card or loan (when it requires a personal credit check)
    • An apartment rental (in some cases, depending on the screening service)
    • A utility account or cell phone contract (sometimes — varies by provider)
    • A credit limit increase on an existing card (with some lenders)

    The key distinction is your permission. A hard inquiry can only happen with your consent — usually buried in the fine print of the application you sign or click “I agree” on. You won’t get a hard pull from a lender just looking at your file for marketing purposes, or from you checking your own credit.

    Hard vs. Soft Inquiries

    It’s worth clarifying the difference, because people confuse these all the time:

    Feature Hard Inquiry Soft Inquiry
    Triggered by Your application for credit Your own credit check, lender pre-approval offers, existing account reviews, employer background checks
    Affects credit score Yes (temporarily) No
    Visible to lenders on your report Yes No (visible only to you)
    Requires your permission Yes Not always

    A soft inquiry (or “soft pull”) has zero impact on your score. Checking your own credit through a free app or annualcreditreport.com, receiving pre-approved card offers in the mail, or having an existing creditor review your account for account management — none of these hurt you. Only hard inquiries do.

    What Triggers a Hard Pull (and What Doesn’t)

    This is where a lot of confusion lives. Here’s a quick reference:

    Will trigger a hard inquiry:

    • Submitting a credit card application
    • Applying for any loan (auto, mortgage, personal, student)
    • Requesting a credit limit increase with certain lenders (Chase and Discover are known for hard-pulling on some increase requests; others, like American Express, often use soft pulls)
    • Opening a new bank account that requires a credit check (varies by institution)
    • Applying for a retail store card at checkout

    Will NOT trigger a hard inquiry:

    • Checking your own credit score through any monitoring service
    • Receiving pre-qualified or pre-approved offers in the mail
    • A landlord running a “soft” rental screening (some do hard, some don’t — ask first)
    • An employer conducting a background credit check
    • A creditor you already have an account with reviewing your file for account maintenance

    When in doubt, ask the company directly before you apply: “Will this result in a hard or soft pull on my credit?” Reputable lenders will tell you.

    How Many Points Does a Hard Inquiry Cost?

    Here’s the good news that surprises most people: a single hard inquiry typically costs you only 1 to 5 points on your FICO score. For most people, it’s closer to the lower end of that range.

    That’s a pretty small dent. If you have a 740 score and apply for a new credit card, you might drop to 737 or 738. Not catastrophic. Within a few months of responsible use, you’ll usually recover those points — and if the new card adds to your total available credit (lowering your utilization), your score can actually rise over time despite the inquiry.

    Why the Range Varies

    The exact point impact depends on several factors:

    • Your current score level. Someone with an 800 score has more to lose from a new inquiry than someone with a 620 score, because the scoring model is more sensitive to changes at higher score ranges.
    • Your overall credit profile. A long, thick credit file with multiple established accounts absorbs an inquiry more easily than a thin file with just one or two accounts.
    • How recent your other inquiries are. A new inquiry on top of five others from the last six months costs more than a new inquiry on a file with no recent activity.
    • The type of inquiry. The model distinguishes between a single credit card application and a cluster of auto loan inquiries — more on that in the rate-shopping section.

    The Real Damage Isn’t Usually the Points

    Here’s the thing most people miss: the point cost of an inquiry is usually not the real problem. One inquiry costing 3 points is noise. The actual risk shows up when:

    • Inquiries accumulate (six applications in six months tells a different story than one every two years)
    • Inquiries cluster in a short window (suggesting you’re scrambling for credit)
    • Inquiries are recent (a hard pull from last month weighs more than one from 18 months ago)
    • The new accounts those inquiries produced lower your average age of accounts

    The scoring model is smart enough to look at the pattern, not just the count. Which brings us to the question you actually came here for.

    So, How Many Hard Inquiries Is Too Many?

    We’ll give you the honest, nuanced answer — but first, the number most people are looking for:

    There is no fixed, official threshold. FICO and VantageScore have never published a specific number of inquiries that automatically disqualifies you or triggers a score cliff. The scoring formula treats inquiries as one factor among many, weighted alongside payment history, utilization, age of accounts, and credit mix.

    That said, based on how the scoring models and lender underwriting guidelines actually behave in practice, here’s a practical frame:

    Inquiries in the last 2 years Typical impact What lenders see
    1–2 Minimal Normal credit use — most adults have this many
    3–5 Modest Generally fine, especially if spread out and for legitimate purposes
    6+ Notable Starts raising flags — lenders may ask questions or tighten terms
    10+ Significant Red flag — suggests credit-seeking behavior or financial stress

    A reasonable rule of thumb: six or more hard inquiries within a 24-month period is when you should start paying attention. It’s not an automatic denial, but it’s the zone where lenders — especially manual underwriters — begin to look more carefully at the story behind the applications.

    The Recency Principle

    Here’s the part that matters more than the raw count: one recent inquiry can hurt more than five old ones.

    Hard inquiries affect your FICO score for 12 months, but they remain visible on your credit report for 24 months. After the 12-month mark, they carry zero scoring weight. So:

    • Five inquiries from 18 months ago = zero score impact
    • One inquiry from three weeks ago = small but real score impact

    If you’re trying to figure out whether your inquiry count is “too many,” the better question is: how many do you have in the last 12 months? That’s the window that actually affects your score. Inquiries older than 12 months are just history — lenders can see them, but the scoring formula has stopped counting them.

    What “Too Many” Really Means

    When a lender sees a high inquiry count, they’re not thinking about the 3 points you lost. They’re thinking about the story the inquiries tell:

    • Is this person taking on too much new debt at once?
    • Are they being denied and reapplying repeatedly (a sign of desperation)?
    • Are they credit-seeking across many categories (cards, personal loans, auto) simultaneously?
    • Or are they just rate-shopping for one mortgage, which is normal and expected?

    The pattern matters more than the number. Six inquiries for one auto loan over two weeks is fine. Six inquiries for six different credit cards over two months is a different signal entirely.

    Why Recency and Clustering Matter More Than the Raw Count

    If you remember one thing from this article, let it be this: the scoring model cares more about when your inquiries happened and how they cluster than about the total number.

    Recency: Newer Hurts More

    The FICO scoring formula applies a deduplication logic that essentially weights inquiries on a decay curve. An inquiry from last month is treated as a stronger risk signal than one from six months ago, which is stronger than one from 11 months ago. At 12 months, it drops off the scoring formula entirely.

    This makes intuitive sense. If you applied for three cards last year but have been quiet since, you’ve demonstrated that you weren’t actually desperate for credit — you just had a burst of applications and then stopped. That’s recoverable. But if you applied for three cards in the last three weeks, the model sees active credit-seeking behavior right now, which is a higher-risk signal.

    Clustering: Spread Out Looks Better Than Bunched Up

    Clustering refers to how bunched-together your inquiries are. Consider two scenarios:

    • Scenario A: One inquiry in January, one in May, one in September. Spread across nine months.
    • Scenario B: Three inquiries in October, all within a two-week period.

    Even though both profiles have three inquiries in a year, Scenario B is actually treated more favorably if those three inquiries are for the same loan type (like an auto loan). Why? Because the rate-shopping logic recognizes that you’re shopping for one loan, not opening three separate credit lines. We’ll dig into this in the next section.

    But if those three October inquiries are for three different credit cards, that’s a cluster that looks like impulse credit-seeking — and the model treats it less kindly.

    The Pattern Lenders Read

    When a human underwriter reviews your file (which happens with mortgages, some auto loans, and any manual review), they’re looking at the pattern of inquiries as a narrative:

    • Clean file, one recent inquiry: “Normal person applying for normal credit.”
    • Several inquiries for the same loan type in a short window: “Smart consumer rate-shopping. Non-issue.”
    • Inquiries across multiple credit types (card, personal loan, auto) in a short period: “Possibly overextending. Worth a closer look.”
    • Many inquiries, many denials, rapid reapplications: “Credit stress signal. Higher risk.”
    • Old inquiries, nothing recent: “Past burst of applications, now stable. Low concern.”

    The takeaway: if you’re going to apply for credit, be intentional about it. A planned, purposeful application is read very differently than a scattered, reactive one.

    The Rate-Shopping Window: FICO’s Built-In Protection

    Here’s where a lot of the fear around “too many inquiries” falls apart. FICO does not penalize you for shopping around for the best rate on a single loan.

    When you’re looking for a mortgage, auto loan, student loan, or personal loan, it’s expected — and financially smart — to compare offers from multiple lenders. FICO recognizes this and applies a deduplication rule for rate shopping.

    How the Deduplication Works

    Here’s the rule, in plain terms:

    Multiple hard inquiries for the same type of loan within a 14-to-45-day window are counted as a single inquiry for scoring purposes.

    So if you apply with five auto lenders over two weeks to compare rates, your FICO score treats those five pulls as one inquiry — not five. You get the benefit of comparison shopping without the penalty of five separate dings.

    The Window Length Depends on the Model

    The exact window varies by scoring model version:

    Scoring Model Rate-Shopping Window Loan Types Covered
    Older FICO models (e.g., FICO 8) 14 days Auto, mortgage, student loans
    Newer FICO models (FICO 9, FICO 10T) 45 days Auto, mortgage, student loans
    VantageScore 3.0 & 4.0 14 days Auto, mortgage, student loans

    Because you don’t always know which model a lender will use, the safest approach is to concentrate all your rate-shopping applications within a 14-day window. That way, you’re protected regardless of which model is checking.

    What Counts as “Same Loan Type”

    The deduplication only applies when the inquiries are for the same type of financing. The categories the models recognize are:

    • Mortgage (purchase, refinance, home equity loan)
    • Auto loan (new, used, refinance)
    • Student loan
    • Personal loan / installment loan

    If you apply for a mortgage and an auto loan in the same week, those are two different categories — you’ll get two inquiries on your score, not one. The deduplication is within-category, not across-category.

    What Does NOT Get Deduplicated

    Credit card applications are not covered by rate-shopping logic. Each credit card application counts as a separate hard inquiry, period. If you apply for three different cards in a week, that’s three inquiries on your score.

    This is an important distinction. The scoring model assumes that when you’re shopping for a mortgage or auto loan, you’re getting one loan — you’re just comparing lenders. But when you apply for three credit cards, the model assumes you might actually open three separate accounts, which represents more potential new debt.

    The Bottom Line on Rate Shopping

    If you’re buying a car or a house:

    • Do your research first — know your target lenders before you start applying.
    • Concentrate applications within 14 days — this ensures deduplication under every scoring model.
    • Don’t worry about the inquiry count — if you stay within the window, five auto loan applications count as one.
    • Be aware that the inquiries still appear on your report — they’re visible to lenders for 24 months, but the scoring formula treats them as one.

    This is one of the most misunderstood parts of the credit system. You should never avoid shopping around for a major loan because you’re worried about inquiry count. The system is specifically designed to let you do this.

    How Different Scoring Models Count Inquiries

    Not all credit scores treat inquiries identically. The model a lender uses affects how your inquiries are weighed, how long they matter, and how rate shopping is handled.

    FICO 8 (The Most Widely Used)

    FICO 8 is still the workhorse of the lending world, used in the majority of credit card and auto loan decisions. Key inquiry facts:

    • Inquiries affect your score for 12 months
    • Rate-shopping window: 14 days for auto, mortgage, student loans
    • Inquiries contribute to the “new credit” category, which is about 10% of your total FICO score
    • A single inquiry typically costs 1–5 points

    FICO 9

    FICO 9 is gentler in several ways — it’s more forgiving of paid collections and gives more weight to rental history. On inquiries:

    • Rate-shopping window expanded to 45 days
    • Otherwise treats inquiries similarly to FICO 8

    FICO 10T (The Newest FICO)

    FICO 10T introduces trended data — it looks at your credit behavior over time, not just a snapshot. On inquiries:

    • Rate-shopping window: 45 days
    • May weigh recent inquiry clusters slightly more heavily because it can see the trajectory of your credit activity over the past 24+ months
    • Increasingly used by mortgage lenders, though adoption is still growing

    VantageScore 3.0 and 4.0

    VantageScore is the model created by the three credit bureaus (Equifax, Experian, TransUnion) as an alternative to FICO. It’s used by some lenders and by many free credit score apps.

    • Inquiries affect your score for 12 months (VantageScore 3.0) or 14 months (VantageScore 4.0)
    • Rate-shopping window: 14 days
    • Inquiries are weighted as part of the “recent credit” factor, which is about 10–12% of the score
    • VantageScore tends to be slightly more sensitive to recent inquiries than FICO, but the difference is small

    Which Model Matters for You?

    You can’t control which model a lender uses, but here’s the practical takeaway:

    • For credit cards and auto loans: Assume FICO 8 — 14-day rate-shopping window for auto.
    • For mortgages: Increasingly FICO 10T or FICO 9 — 45-day window, but ask your lender which model they pull.
    • For monitoring your own score: The free score from your card issuer or a monitoring app is usually FICO 8 or VantageScore — a useful benchmark, but not always identical to what a specific lender will see.

    The inquiry behaviors that help across all models are the same: avoid unnecessary applications, concentrate rate shopping into a short window, and let time do its work.

    How Lenders View Inquiry Patterns

    So far we’ve talked about how the scoring formula treats inquiries. But there’s a second layer: how human lenders interpret your inquiry pattern when they’re deciding whether to approve you.

    This matters most in situations involving manual underwriting — where a person, not just an algorithm, reviews your application. Manual review is common with:

    • Mortgages (almost always involve human review)
    • Some auto loans (especially from credit unions or smaller lenders)
    • Business loans
    • Any application that’s borderline — if your score is right at the approval cutoff, a human may look at the details

    What Underwriters Look For

    A manual underwriter reviewing your credit file sees every inquiry from the last 24 months (even though only the last 12 affect your score). They’re looking for patterns that tell a story about your financial behavior:

    Green flags:

    • A single inquiry for a mortgage, followed by on-time payments on the new loan
    • Rate shopping for an auto loan concentrated in a 2-week window (shows responsible comparison)
    • Inquiries spread out over time with new accounts showing good payment history
    • A clean inquiry record overall

    Yellow flags (may prompt questions):

    • 3–5 inquiries in the last 6 months across different credit types
    • Recent inquiries without corresponding new accounts (suggests you applied and were denied)
    • A pattern of applying for credit right before major life events

    Red flags:

    • 6+ inquiries in the last 6 months, especially across multiple credit categories
    • Inquiries from subprime or high-interest lenders (payday loan inquiries, certain subprime card issuers)
    • Rapid-fire applications suggesting you’re trying to access as much credit as possible before something changes
    • Inquiries that coincide with late payments or rising balances on existing accounts

    The “Inquiries Without New Accounts” Pattern

    This is one underwriters watch closely. If your report shows five inquiries in the last year but only one new account, the underwriter knows you applied for credit four times and were either denied or declined the offer. That pattern reads as credit-seeking under pressure — you’re trying to get approved and not succeeding.

    By contrast, five inquiries that all resulted in new accounts (and those accounts are in good standing) tells a different story: you’re actively building credit, and multiple lenders have deemed you creditworthy.

    Lender-Specific Tolerances

    Different lenders have different internal thresholds for inquiry count:

    • Major credit card issuers (Chase, Amex, Citi) often have internal rules — Chase’s unofficial “5/24 rule” denies applicants who have opened 5+ cards across all banks in 24 months, regardless of score.
    • Mortgage lenders are generally more tolerant of rate-shopping clusters but may ask for a letter of explanation for any inquiry in the last 120 days.
    • Auto lenders understand rate shopping well and rarely penalize clustered auto inquiries.
    • Credit unions tend to take a more holistic, relationship-based view and may be more forgiving of inquiry count if your overall profile is strong.

    If you’re planning a major application (especially a mortgage), it’s worth pulling your own report first and reviewing the inquiry section. If there’s anything that might prompt a question, you can prepare a brief, honest explanation in advance.

    When Inquiries Signal Risk vs. Normal Shopping

    Let’s crystallize the difference between an inquiry pattern that signals risk and one that reflects normal, healthy credit behavior.

    Normal, Healthy Inquiry Patterns

    • One credit card application every year or two to take advantage of a rewards program or balance transfer offer
    • Rate shopping for a single auto loan or mortgage within a 2-week window
    • Occasional applications when legitimate financial needs arise (a new car, a home purchase, a needed personal loan for home repair)
    • A student loan refinance once or twice over a lifetime
    • Applying for a store card once in a while for a major purchase discount (though we’d generally advise caution here — store cards often have high APRs)

    These patterns tell lenders: “This person uses credit deliberately and for clear purposes.”

    Risk-Signaling Inquiry Patterns

    • Multiple credit card applications in a short period (3+ cards in 3 months)
    • Applying for credit after being denied at another lender, repeatedly
    • Inquiries across many credit categories simultaneously (a card, a personal loan, and an auto loan all in the same month)
    • Applications to subprime or high-fee lenders (payday lenders, high-interest installment loans, fee-heavy subprime cards)
    • Inquiries that coincide with rising balances on existing accounts or any late payments
    • A sudden burst of applications after a long period of no credit activity
    • Applying for cash advances or high-fee credit products

    These patterns tell lenders: “This person may be experiencing financial stress or building up debt rapidly.”

    The Gray Zone

    Most people fall somewhere in the middle. You might have applied for two cards in six months because you were rebuilding after a divorce, or you might have an old auto loan inquiry and a recent mortgage inquiry that look close together but are for completely legitimate reasons.

    If you’re in the gray zone, the best thing you can do is be ready to explain. When you apply for a mortgage and the underwriter asks about the inquiry from six months ago, a one-sentence explanation — “That was a balance transfer card I used to consolidate higher-interest debt, and I’ve paid it down since” — resolves the question cleanly. Lenders don’t expect perfection; they expect coherence.

    How to Minimize Inquiries When Rate Shopping

    If you’re planning to apply for credit, a little strategy goes a long way. Here’s how to keep your inquiry count low while still getting the best terms.

    1. Concentrate Applications in a Short Window

    For auto loans, mortgages, and student loans, do all your applications within a 14-day period. This guarantees that every scoring model treats them as a single inquiry.

    Plan your approach:

    • Research lenders first — identify 4–6 you want to compare before you apply to any.
    • Get your documents ready — pay stubs, W-2s, bank statements, ID — so you can apply to all of them quickly.
    • Apply within the same week if possible. Two weeks is the safe maximum.
    • Don’t stretch shopping over a month. If you apply to one lender in week one and another in week four, older FICO models will count those as two separate inquiries.

    2. Use Pre-Qualification and Pre-Approval Tools (Soft Pulls)

    Many lenders offer pre-qualification tools that use a soft pull to show you the rates and terms you’d likely qualify for — without a hard inquiry. This lets you shop and compare before you commit to a formal application.

    • Credit cards: Most major issuers (Chase, Amex, Citi, Capital One, Discover) offer pre-qualification pages on their websites. Bankrate, NerdWallet, and Credit Karma also aggregate pre-qualified offers using soft pulls.
    • Auto loans: Many online lenders (LightStream, Capital One Auto, Carvana) offer pre-qualification with a soft pull. You can see your rate before you apply formally.
    • Personal loans: Pre-qualification is widely available from online lenders.
    • Mortgages: Pre-qualification exists but is less meaningful than a full pre-approval (which does involve a hard pull). For mortgages, a pre-approval is worth the inquiry because it strengthens your offer to sellers.

    The strategy: use pre-qualification to narrow your options, then submit formal applications only to your top 1–3 choices.

    3. Don’t Apply Speculatively

    Avoid the “let me just see if I get approved” approach. Every speculative application is a hard inquiry that costs points — and if you’re denied, you have nothing to show for it but a ding on your score.

    Instead:

    • Check pre-qualification first to gauge your odds.
    • Review the lender’s stated credit requirements (many publish minimum score ranges).
    • Only apply when you have a reasonable expectation of approval.

    4. Be Strategic About Credit Card Applications

    Since credit card inquiries aren’t deduplicated, each one counts. If you’re interested in multiple cards:

    • Prioritize — apply for the one you want most first.
    • Space them out — wait at least 6 months between card applications if possible.
    • Be aware of issuer-specific rules — Chase’s 5/24 rule, for example, will deny you for many Chase cards if you’ve opened 5+ cards from any issuer in 24 months.
    • Consider the value — a sign-up bonus is only worth it if you’ll use the card long-term, not just for the bonus.

    5. Freeze Your Credit If You’re Not Actively Applying

    If you know you won’t be applying for credit in the near future, a credit freeze with all three bureaus (Equifax, Experian, TransUnion) prevents new hard inquiries entirely. It’s free, doesn’t affect your score, and you can unfreeze temporarily when you do want to apply. This is also excellent protection against identity theft and fraudulent applications.

    How Long Inquiries Affect Your Score and Stay on Your Report

    Two different timelines to keep straight:

    Timeline What It Means
    12 months How long a hard inquiry affects your FICO score. After 12 months, it carries zero scoring weight. (VantageScore 4.0 uses 14 months.)
    24 months How long a hard inquiry remains visible on your credit report. Lenders can see it, but it no longer affects your score after the first year.

    After 12 Months: Score Recovery

    Once a hard inquiry crosses the 12-month mark, it stops affecting your FICO score. You don’t need to do anything — the scoring formula automatically stops counting it. Any points you lost from that inquiry should have already been recovered by then (most people recover inquiry-related points within 6–12 months of responsible credit use).

    After 24 Months: Removal From Your Report

    At 24 months, the inquiry falls off your credit report entirely. It’s no longer visible to lenders or to you. You don’t need to request removal — the bureaus drop it automatically.

    Can You Remove Inquiries Early?

    In general, no — legitimate hard inquiries stay on your report for 24 months. There is no legitimate way to remove an accurate inquiry early. Any service promising to “remove hard inquiries fast” is either:

    • Filing disputes on your behalf and hoping the bureau can’t verify the inquiry (which sometimes works for undocumented or fraudulent inquiries but is not reliable for legitimate ones), or
    • A scam

    The one exception: if an inquiry is inaccurate or fraudulent — for example, someone applied for credit in your name without permission, or a lender pulled your credit without authorization — you can dispute it with the credit bureaus. Legitimate disputes for fraudulent or unauthorized inquiries can result in removal. But accurate, authorized inquiries are there for the full 24 months.

    How to Check Your Inquiries

    You can see every hard inquiry on your file by pulling your free credit reports from annualcreditreport.com (you’re entitled to one free report from each bureau per week under current federal law). Review the inquiry section and make sure every pull listed is one you recognize. If you see an inquiry you don’t recognize, dispute it — it could be a sign of identity theft.

    How to Bounce Back After Too Many Inquiries

    If you’ve accumulated more hard inquiries than you’d like — whether from a period of credit rebuilding, a difficult financial stretch, or just not knowing how the system worked — here’s the honest, practical path forward.

    1. Stop Applying for New Credit

    This is the single most important step. The clock starts ticking the day you stop applying. Every month that passes without a new inquiry moves you further from the “recent” window that matters most.

    Commit to a hard pause — no new credit applications for at least 6 months, ideally 12. Use this time to let your existing accounts age and your most recent inquiries fade toward the 12-month mark.

    2. Focus on the Factors You Can Control

    Inquiries are a small part of your score (about 10% in FICO). The bigger factors — payment history (35%) and credit utilization (30%) — are where you have real leverage.

    • Pay every bill on time, every month. A single 30-day late payment costs far more than any hard inquiry.
    • Keep your credit card balances low. Aim to use less than 10% of your available credit on each card and overall. If you have a $10,000 limit across all cards, try to keep your total reported balance under $1,000.
    • Pay down balances before the statement closing date — that’s when most card issuers report to the bureaus, not the due date.

    3. Let Your Accounts Age

    The average age of your accounts is about 15% of your FICO score. As your existing accounts get older and your recent inquiries age past 12 months, your score will naturally recover and grow. Don’t close old accounts (unless they have annual fees you can’t justify) — keeping them open preserves your credit history length and your total available credit.

    4. Dispute Any Inaccurate Inquiries

    Pull your reports from all three bureaus and review the inquiry section carefully. If you see any inquiry you don’t recognize or didn’t authorize, dispute it. The bureau must investigate within 30 days. If the inquiry can’t be verified, it gets removed — which can help your score if it was within the 12-month scoring window.

    5. Be Patient and Consistent

    Credit recovery is not a 30-day project. It’s a 6-to-24-month process of consistent good behavior. The good news: the scoring model rewards steady, responsible use. Within a year of stopping new applications, paying on time, and keeping utilization low, most people see meaningful score improvement — even with a heavier inquiry history.

    6. Consider a Professional Review

    If your credit situation is complex — multiple negative marks alongside the inquiries, accounts in collections, or errors across bureaus — a professional credit audit can identify the specific factors dragging your score and a clear, prioritized plan to address them. At , we offer a free credit audit that reviews all three bureau reports and maps out a tailored recovery plan. No quick fixes — just a clear-eyed assessment of where you stand and what to do next.

    Common Myths About Hard Inquiries

    Let’s clear up some of the most persistent misconceptions we hear from clients.

    Myth 1: “Checking my own credit score hurts my score.”

    False. Checking your own credit — through a monitoring app, your bank’s free score feature, or annualcreditreport.com — is a soft inquiry and has zero impact on your score. You can check your own credit every single day without consequence.

    Myth 2: “Every inquiry drops your score by 10 points.”

    False. A single hard inquiry typically costs 1–5 points, and the impact depends on your overall profile. The “10 points per inquiry” idea is a myth that makes people far more anxious than they need to be.

    Myth 3: “Rate shopping for a car loan will wreck your score.”

    False. FICO specifically deduplicates multiple auto loan inquiries within a 14-day (or 45-day, depending on the model) window. Five auto loan applications in two weeks count as one inquiry for scoring purposes. You should never avoid shopping around for a major loan because of inquiry concerns.

    Myth 4: “You can pay a service to remove legitimate hard inquiries.”

    False. Legitimate, authorized hard inquiries stay on your report for 24 months — period. Any service promising to remove accurate inquiries is either filing baseless disputes (which rarely work for legitimate inquiries) or is a scam. The only inquiries that can be removed are inaccurate or fraudulent ones, which you can dispute yourself for free.

    Myth 5: “Inquiries stay on your report forever.”

    False. Hard inquiries fall off your report automatically after 24 months. They stop affecting your score after 12 months. You don’t need to do anything — they age out on their own.

    Myth 6: “A pre-approval offer means a hard pull already happened.”

    False. Those pre-approved credit card offers you get in the mail are based on a soft inquiry from a list the lender purchased from the credit bureaus. No hard pull has occurred. If you actually apply in response to the offer, that’s when the hard pull happens.

    Myth 7: “Closing a credit card removes the inquiry from your report.”

    False. Closing a card does not remove the original application inquiry — that inquiry stays on your report for 24 months regardless. Closing the card may actually hurt your score by reducing your available credit and shortening your average account age.

    Myth 8: “All credit scores treat inquiries the same way.”

    False. FICO 8, FICO 9, FICO 10T, and VantageScore all have slightly different inquiry rules — different rate-shopping windows, different lengths of scoring impact, different weightings. The behaviors that help are the same across all of them, but the exact point impact can vary.

    Frequently Asked Questions

    How many hard inquiries is too many for a credit card application?

    There’s no official cutoff, but as a general guideline: 6+ inquiries in the last 12 months starts to raise concerns for many lenders. Some card issuers have stricter internal rules — Chase’s 5/24 rule, for example, counts new accounts (not just inquiries) across all banks. If you’re applying for a premium card, aim for no more than 2–3 inquiries in the last 6 months.

    Does applying for multiple credit cards in one day hurt your score more?

    Each credit card application is a separate hard inquiry — they are not deduplicated like rate-shopping inquiries for loans. So applying for three cards in one day means three separate inquiries on your score. However, they’ll all hit your report around the same time, and the scoring impact (typically 3–15 points total for three inquiries) will be concentrated. The bigger concern is that rapid card applications signal credit-seeking behavior to lenders.

    Can I remove a hard inquiry before 24 months?

    Only if the inquiry is inaccurate or fraudulent. If you didn’t authorize the application or the inquiry is listed in error, you can dispute it with the credit bureau, and it must be investigated within 30 days. Legitimate, authorized inquiries cannot be removed early — they remain for the full 24 months.

    Do hard inquiries affect your score for 12 or 24 months?

    12 months for scoring purposes, 24 months for visibility. After 12 months, a hard inquiry no longer affects your FICO score (VantageScore 4.0 uses 14 months). It remains visible on your credit report for the full 24 months, so lenders can see it, but it carries zero scoring weight after the first year.

    Will rate shopping for a mortgage hurt my credit?

    No — as long as you concentrate your mortgage applications within a 14-to-45-day window, FICO treats them as a single inquiry. You can and should shop around for the best mortgage rate. Mortgage lenders expect this and the scoring model is designed to accommodate it. Just be aware that each lender’s inquiry will still appear on your report individually (even though they count as one for scoring), and a mortgage underwriter may ask you to explain any inquiries during the application process.

    How many points does one hard inquiry cost?

    Typically 1 to 5 points for a single inquiry. The exact impact depends on your overall credit profile, your current score, and how many other recent inquiries you have. People with higher scores and thicker credit files tend to lose fewer points per inquiry.

    Do soft inquiries affect my credit score at all?

    No. Soft inquiries — from checking your own credit, receiving pre-approved offers, existing account reviews, or employer background checks — have zero impact on your credit score. They’re not visible to lenders and aren’t included in the scoring formula.

    Should I freeze my credit to prevent hard inquiries?

    A credit freeze is a good idea if you’re not actively applying for credit. It prevents new hard inquiries (including fraudulent ones) and has no effect on your score. It’s free with all three bureaus. When you do need to apply, you can temporarily lift the freeze for a specific lender or a specific time period. A freeze is also one of the best protections against identity theft and fraudulent credit applications.

    Take Control of Your Credit

    Hard inquiries are a small part of your credit picture, but they’re a part worth understanding. The key takeaways:

    • One or two inquiries are nothing to worry about — that’s normal credit use.
    • Six or more in 24 months is the zone to watch — not an automatic problem, but worth attention.
    • Recency matters more than count — one recent inquiry can outweigh five old ones.
    • Rate shopping is protected — concentrate auto, mortgage, and student loan applications within 14 days and they count as one.
    • Time heals — inquiries stop affecting your score after 12 months and fall off your report after 24.

    If you’re concerned about your inquiry count — or if inquiries are just one piece of a credit picture that needs attention — we can help. At , we offer a free credit audit that pulls and reviews all three of your bureau reports, identifies every factor affecting your score (not just inquiries), and maps out a clear, personalized plan to improve your credit health.

    We’re a San Diego-based, attorney-backed credit repair firm that operates in full compliance with the Fair Credit Reporting Act (FCRA). We don’t make quick-fix promises — we believe in honest, transparent, results-driven work that equips you with the knowledge to keep your credit strong for life.

    Ready to see where you stand? and take the first step toward credit clarity.

    This article is for educational purposes and does not constitute legal or financial advice. Your individual credit situation is unique. For a personalized review, request a free credit audit at .

    Related reading:

  • How to Remove Late Payments From Your Credit Report

    How to Remove Late Payments From Your Credit Report

    If you have ever checked your credit report and felt your stomach drop at the sight of a late payment, you are not alone. A single missed payment can knock dozens of points off your credit score, and it can sit there, quietly costing you money on every loan and credit card, for up to seven years. The good news is that you have options — real, legal, FCRA-compliant options — to address late payments on your report.Here is the honest part, though: not every late payment can be removed early. If the late payment is accurate, verifiable, and recent, no credit repair company or letter can guarantee its deletion. Anyone who promises otherwise is not telling you the truth. What we can do — and what we help our clients do every day — is pursue every legitimate path to removal, dispute what should not be there, and build a long-term credit strategy that minimizes the damage while you wait out the clock.

    In this guide, we walk you through what a late payment actually is, how much it hurts, how long it stays, and the five legitimate paths to getting it off your report. We include step-by-step instructions and sample letters you can adapt and send yourself.

    What Is a Late Payment?

    A late payment is a payment on a credit account — a credit card, auto loan, mortgage, student loan, personal loan, or other installment account — that was not made by the due date listed in your agreement with the lender. Creditors generally report your payment status to the three major credit bureaus (Equifax, Experian, and TransUnion) every month, and that status becomes part of your credit history.

    Not every payment that is a day late shows up on your report. Most creditors have a small grace period (often 10 to 15 days for credit cards, longer for mortgages) before they consider a payment officially delinquent and before they report it. The key threshold is 30 days past due. Once a payment crosses that 30-day mark, the creditor can — and almost always will — report it to the bureaus as a 30-day late payment.

    That is the moment a late payment enters your credit file and starts affecting your score. Before 30 days, you may still owe a late fee to the creditor, but the bureaus typically do not know about it. After 30 days, it becomes a matter of public record on your credit report — visible to any lender who pulls your file.

    A late payment on your report includes several pieces of information:

    • The creditor’s name (the furnisher who reported it)
    • The account number (often truncated)
    • The date the late payment occurred (the month and year)
    • The severity (30, 60, 60, or 90+ days late)
    • The current status (whether the account is now current, still delinquent, or charged off)

    Understanding each of these fields matters because, when you dispute a late payment, you are asking the bureau to verify the accuracy of these specific details. A wrong date, a wrong severity code, or a furnisher that cannot back up the entry are all openings for removal.

    ()

    30, 60, and 90-Day Late Payments — How Severity Differs

    Not all late payments are created equal. The credit reporting system uses a sliding scale of severity, and the further behind you fall, the more damage each mark does.

    30-Day Late Payment

    A 30-day late payment is the first tier of delinquency. It means a payment was not made within 30 days of the due date. This is the most common type of late payment and the one most people encounter at some point in their lives — a forgotten bill, a payment that got lost in the mail, a temporary cash-flow crunch.

    A 30-day late is the least severe of the lates, but it is still a late payment, and it still hurts. On a good credit score, a single 30-day late can drop you 60 to 80 points. On a score that is already mid-range, the hit is smaller but still meaningful.

    60-Day Late Payment

    A 60-day late payment means the payment is now two billing cycles behind. This is more serious. By the time you reach 60 days, the creditor has usually sent you multiple notices, possibly called you, and may have restricted your account. A 60-day late signals to lenders that this was not a one-off oversight but a sustained inability to keep up.

    The score impact of a 60-day late is larger than a 30-day, and it stays a red flag for longer in the eyes of manual underwriters even after the score itself has recovered.

    90-Day Late Payment

    A 90-day late payment is the most serious of the commonly reported lates, and it is often the threshold at which a creditor considers the account in default. At 90 days, many creditors will charge off the account (write it off as a loss), send it to a collection agency, or, for secured loans, begin repossession or foreclosure proceedings.

    A 90-day late is treated by the scoring models as a major delinquency. It can drop a good score by 100 points or more, and its effect lingers. From a lender’s perspective, a 90-day late is a strong signal of financial distress, and it is the hardest type of late payment to explain away.

    120, 150, and 180-Day Lates

    Some accounts report even higher delinquency tiers — 120, 150, and 180 days — before charge-off. These behave much like 90-day lates in terms of scoring impact: they are major delinquencies, and the damage is severe. If you have lates at this level, they are almost always accompanied by a charge-off or collection, which means the path to resolution usually involves the account itself, not just the late-payment mark.

    Why the Distinction Matters for Removal

    The severity of the late payment matters for two reasons. First, it tells you how hard the mark will be to remove. A 30-day late on an otherwise perfect account is a candidate for a goodwill letter; a 90-day late on a charged-off account is not. Second, it tells you how much the mark is hurting you right now, which helps you prioritize which items to go after first when you are working through a credit repair plan.

    How Much a Late Payment Hurts Your Score

    The impact of a late payment depends on three things: how recent it is, how severe it is, and what your score was before it happened. Of the three, recency matters the most.

    Recency Is the Biggest Factor

    The FICO and VantageScore models weight recent negative information more heavily than old negative information. A late payment from three months ago hurts you far more than an identical late payment from three years ago. This is why people often see their score drop sharply right after a late reports, and then slowly recover over the following years even if the late payment itself never comes off.

    This also means that the first year after a late payment is the most painful. If you can get through that first year with on-time payments on everything else, you will have absorbed most of the damage and your score will begin to stabilize.

    Severity Amplifies the Hit

    As we covered above, a 30-day late is less damaging than a 90-day late. But the scoring models do not treat each additional 30 days as a linear increase — the jump from 30 to 60 is meaningful, and the jump from 60 to 90 is even bigger because 90 crosses into major-delinquency territory.

    Your Starting Score Changes Everything

    Here is a wrinkle that surprises people: the higher your score was before the late payment, the more points you will lose. Someone with an 800 score who gets a 30-day late might drop to 680 — a 120-point swing. Someone with a 620 score who gets the same 30-day late might only drop to 600 — a 20-point swing.

    This feels unfair, but it makes sense in the context of risk modeling. A high score says you have a long, clean history, so a new late payment is a strong signal that something has changed. A lower score already reflects some risk, so a new late is less of a surprise.

    A Rough Point-Range Guide

    These are estimates, not guarantees — your actual score change depends on your full profile:

    • Single 30-day late, previously clean file: 60–110 point drop
    • Single 60-day late: 70–130 point drop
    • Single 90-day late: 90–150+ point drop
    • Multiple late payments on the same account: the impact compounds, and the account can start dragging your score down in a way that does not fully reverse until the account itself is resolved

    The takeaway: a late payment is not a minor blemish. It is a significant event, and it is worth fighting to remove if you have a legitimate basis to do so.

    How Long Late Payments Stay on Your Report

    Under the Fair Credit Reporting Act (FCRA), most negative information — including late payments — can stay on your credit report for up to seven years. The clock starts from the date of the original delinquency — that is, the date the late payment first occurred, not the date the account was closed or the date the late was reported.

    The Seven-Year Rule

    Seven years is the maximum. The bureaus are required to remove the late payment automatically once that seven-year period ends. You do not have to request it (though it is a good idea to check that it actually comes off — bureaus occasionally miss the deadline).

    When the Clock Starts

    This is one of the most misunderstood parts of credit reporting. The seven-year clock does not start when you close the account, when you pay off the debt, or when the late payment was reported. It starts on the date of the first delinquency that led to the late being reported.

    For a single isolated late payment, this is straightforward: the clock starts the month the payment was due and you missed it. For an account that went delinquent and stayed delinquent (leading to a charge-off), the clock starts on the date of the first missed payment in that delinquent streak — not the date of the charge-off.

    State Laws Can Shorten the Window

    Some states have laws that require negative information to come off sooner than seven years for certain types of data. California, for example (where we are based), has consumer protection provisions that interact with the FCRA. It is worth knowing your state’s rules, but the FCRA’s seven-year cap is the federal baseline that applies everywhere.

    What Does Not Reset the Clock

    A common myth is that making a payment, disputing the account, or acknowledging the debt resets the seven-year clock. It does not. The date of original delinquency is fixed. Making a partial payment on an old account does not restart the reporting clock (though it may restart the statute of limitations for being sued — a separate legal concept you should understand before you act on an old debt).

    How to Check When a Late Payment Will Fall Off

    Your credit report typically includes a “scheduled to remain on report until” date for each negative item. Pull your free reports from all three bureaus at AnnualCreditReport.com and look for that date. If a late payment is older than seven years and is still showing, you have a clear-cut dispute: the bureau is required to remove it.

    ()

    The Five Legitimate Paths to Late Payment Removal

    There is no single magic method for removing a late payment. There are five legitimate paths, and the right one depends on whether the late is accurate, how old it is, and whether there is an open collection or charge-off attached to it.

    Let’s walk through each.

    Path 1: Dispute an Inaccurate or Unverifiable Late Payment

    Best for: late payments that are wrong in any detail — wrong date, wrong severity, not yours, or already paid on time.

    This is the strongest and most straightforward path. Under the FCRA, you have the right to dispute any information on your credit report that is inaccurate, incomplete, or unverifiable. When you file a dispute, the bureau is required to investigate (usually within 30 days) by going back to the furnisher (the creditor that reported the late) and asking them to verify the details. If the furnisher cannot verify it, or does not respond in time, the bureau must delete the late payment.

    Grounds for disputing a late payment include:

    • The payment was actually made on time (you have proof)
    • The date of the late is wrong
    • The severity is wrong (it says 60 days but you were only 30)
    • The account is not yours (identity theft or mixed file)
    • The account was in deferment or forbearance at the time
    • The late was already resolved and should be reporting as current
    • The furnisher no longer exists or cannot verify the details

    Step-by-Step: How to Dispute an Inaccurate Late Payment

    • Pull all three credit reports. Get your reports from Equifax, Experian, and TransUnion. The late may appear on one, two, or all three — and you need to dispute it with each bureau that is reporting it. Use AnnualCreditReport.com for your free copies.
    • Gather your evidence. Bank statements, payment confirmations, canceled checks, correspondence with the creditor, deferment letters — anything that proves the late is wrong or supports your version of events. The stronger your documentation, the better your odds.
    • File the dispute with each bureau reporting the late. You can dispute online, by phone, or by mail. Mail is slower but creates a paper trail and lets you include copies of your evidence. We recommend mail for anything complicated.
    • Send the dispute to the furnisher too. Under the FCRA, you can also dispute directly with the creditor that reported the late. This is often overlooked. Send them the same documentation and ask them to correct or withdraw the reporting.
    • Wait for the investigation. The bureau has 30 days (sometimes 45, if you send additional information during the investigation) to complete their review. They will contact the furnisher, who must verify the details.
    • Review the results. The bureau sends you the outcome in writing. If the late is deleted, great. If it is verified and remains, you move to the next path.
    • If deleted, confirm it across all three bureaus. A deletion at one bureau does not automatically delete at the others. Pull your reports again in 30–60 days to confirm.

    What If the Furnisher Does Not Respond?

    If the furnisher fails to respond to the bureau’s verification request within the 30-day window, the bureau is required to delete the late payment. This happens more often than you might think, especially with older accounts where the furnisher has archived the records or the original creditor has been acquired or dissolved.

    This is why disputing is worth doing even when you are not 100% certain the late is wrong — if the furnisher cannot back it up, the late comes off. But do not dispute items you know are accurate just hoping the furnisher skips the response; that strategy backfires, and bureaus can flag repeat, frivolous disputes.

    Path 2: Send a Goodwill Letter for an Isolated or Old Late

    Best for: a late payment that is accurate but was a one-time mistake on an otherwise solid account, or a late that is several years old and you have been current ever since.

    A goodwill letter is exactly what it sounds like: a polite, honest letter to the creditor asking them, as a matter of goodwill, to remove a late payment from your report. You are not disputing the accuracy — you are acknowledging the mistake and asking for leniency.

    This works because creditors have the discretion to remove accurate negative reporting if they choose to. There is no law requiring them to keep it on, and no law preventing them from taking it off. It is entirely up to the human (or algorithm) on the other end.

    When Goodwill Letters Work Best

    Goodwill letters are most effective when:

    • The late was a one-time event on an account with years of on-time payments before and after
    • The late is older — at least a year or two in the past
    • You are still a customer in good standing (or were for a long time)
    • There was a genuine hardship — a job loss, medical emergency, divorce, death in the family — that you can briefly and honestly explain
    • Your account is current and has been for a while

    When Goodwill Letters Rarely Work

    • The late is recent (within the last few months)
    • You have multiple late payments on the same account
    • The account went to collections or was charged off
    • You closed the account angrily or defaulted on a settlement
    • The creditor is a large bank with an automated policy against goodwill removals (some are more flexible than others)

    Step-by-Step: How to Write and Send a Goodwill Letter

    • Identify the right recipient. Send the letter to the creditor’s customer service or executive resolution office, not the general payment address. For larger banks, search for the office of the president or the executive customer relations team.
    • Be honest and specific. State the account number, the date of the late payment, and the reason it happened. Do not over-explain or make excuses — a few honest sentences are more effective than a long, dramatic story.
    • Emphasize your positive history. Mention how long you have been a customer, how many on-time payments you have made, and any steps you have taken to make sure it does not happen again (autopay, emergency fund, etc.).
    • Make a clear, polite ask. Request that they remove the late payment as a goodwill gesture. Do not demand, threaten, or cite laws — this is a favor, not a legal right.
    • Send by mail if possible. A physical letter on paper gets more attention than an email or a portal message. Keep a copy and send it with tracking.
    • Follow up if you do not hear back. Wait 30–45 days. If no response, send a second letter. If still nothing, try a different contact path (executive office, social media, regulator complaint as a last resort).
    • Be patient and realistic. Goodwill removals are not guaranteed. Creditors say no far more often than they say yes. But the cost of trying is a stamp and a few minutes, so it is almost always worth a shot for a late that is genuinely an outlier.

    ()

    Path 3: Pay-for-Delete When a Collection Is Tied to the Late

    Best for: situations where the late payment has escalated into a collection account or a charge-off, and you have the ability to pay (or settle) the underlying debt.

    Pay-for-delete is an arrangement where you negotiate with a collection agency (or sometimes the original creditor) to have the negative item removed from your credit report in exchange for paying the debt. This is not a dispute and not a goodwill request — it is a negotiated settlement.

    The Important Caveat

    Pay-for-delete works primarily with collection agencies, not with original creditors reporting late payments directly. If your late payment is simply a 30/60/90-day mark on an open account that is still with the original creditor, pay-for-delete is usually not on the table. It becomes relevant when the account has been sent to collections or charged off, and a collection agency is now reporting a separate collection item.

    In those cases, paying the collection (or settling it) in exchange for deletion of the collection entry can indirectly clean up the credit file — and sometimes, with the right negotiation, the original late-payment marks too.

    Step-by-Step: How to Negotiate Pay-for-Delete

    • Confirm the debt is yours and the amount is correct. Do not negotiate until you have validated the debt. Send a debt validation letter first if you have any doubts.
    • Decide what you can pay. Full payment is ideal, but many collection agencies will accept a settlement for less than the full balance (often 40–70%). Decide your ceiling before you start negotiating.
    • Get the agreement in writing before you pay. This is the most important step. Never pay on a verbal promise. The agency must send you a written agreement stating that, upon receipt of your payment, they will request deletion of the collection (and any related negative reporting) from all three bureaus.
    • Pay only after the written agreement is in hand. Use a method that gives you a receipt — check, money order, or tracked payment. Keep proof forever.
    • Follow up to confirm deletion. Give it 30–60 days after payment, then pull your reports. If the collection is still showing, send a dispute to the bureaus with your pay-for-delete agreement and proof of payment attached.

    Honest Limitations

    Not all collection agencies agree to pay-for-delete. Some have policies against it, and some credit bureaus have pushed back on the practice. But many still do it, especially for full payment. And even if you cannot get a deletion, paying a collection is still better for your credit than leaving it open — paid collections are scored more favorably than unpaid ones under newer FICO and VantageScore models, and many lenders treat a paid collection very differently than an unpaid one in manual underwriting.

    Path 4: Wait Out the Seven-Year Clock

    Best for: accurate late payments that cannot be removed any other way, especially older ones that are already close to the seven-year mark.

    This is the path no one wants to hear, but it is the most reliable one. If a late payment is accurate, has been verified, and the creditor will not grant goodwill removal, it comes off your report automatically after seven years from the date of the original delinquency. No letter, no dispute, no payment required.

    Make the Wait Less Painful

    While you wait, the late payment’s impact shrinks every year. The scoring models weight recency, so a late that is five years old barely affects your score even though it is still on your report. Here is how to make the waiting period work for you:

    • Pay everything on time, every time. The single best thing you can do for your score while waiting out a late is to build a long, unbroken streak of on-time payments. New positive history dilutes the old negative.
    • Keep your credit utilization low. Stay under 30% on your credit cards, ideally under 10%. This is the second-biggest scoring factor after payment history.
    • Do not close old accounts. Account age helps your score. Closing a long-standing account can shorten your average age of accounts and lower your score.
    • Add positive accounts if you need to. A secured credit card or a credit-builder loan, used responsibly, adds new positive history to your file.
    • Monitor the deletion date. Set a reminder for the month the late is scheduled to come off. If it does not disappear on its own, dispute it as obsolete.

    Disputing as Obsolete

    If a late payment is older than seven years and is still on your report, you have an absolute right to have it removed. File a dispute with each bureau stating that the item is obsolete — older than the FCRA’s seven-year reporting period — and must be deleted. Include the date of the original delinquency if you have it. The bureau must remove it. This is one of the easiest disputes to win.

    Path 5: Negotiate Directly With the Furnisher

    Best for: situations where you have a relationship with the creditor and some leverage — for example, you are current on a modified payment plan, you are settling a charged-off account directly with the original creditor, or you are a long-standing customer with a single blemish.

    Sometimes the fastest path is a direct conversation with the creditor that reported the late. This is different from a goodwill letter (which is written) and different from pay-for-delete (which is about a collection). This is picking up the phone or sending a message and asking, person to person, whether they will update the reporting as part of a broader arrangement.

    Scenarios Where This Works

    • You are settling a charged-off account. As part of the settlement, ask the creditor to report the account as “paid as agreed” or “current” instead of “settled” or “charged off.” Some will do this; many will not, but it is worth asking.
    • You are entering a hardship or modification program. Some creditors will agree to suppress negative reporting while you are on a modification plan, or to remove prior lates once you complete the plan successfully.
    • You are a long-time customer with a single late. A phone call to the retention or executive customer service line can sometimes accomplish what a goodwill letter cannot, especially if you are considering moving your business elsewhere.

    How to Approach the Conversation

    • Call the customer service line and ask to be transferred to a supervisor or the retention/executive resolutions team. Front-line reps often do not have the authority to change credit reporting.
    • Be calm, clear, and specific. State what you want (removal of a specific late payment, re-reporting as current, suppression of future lates during a plan). Have your account number and the date of the late in front of you.
    • Offer something in return if you can. If you are settling, offer a higher settlement percentage in exchange for better reporting. If you are a long-time customer, mention your history and your desire to stay.
    • Get any promise in writing. If they agree, ask them to send you a letter or email confirming what they will report. Verbal promises are not enforceable, and front-line reps sometimes misstate what they can actually do.
    • Follow up on your reports. Give it 30–60 days and check whether the reporting has actually changed. If it has not, call back with your written confirmation in hand.

    How to remove late payments from a credit report

    Sample Dispute Letter for an Inaccurate Late Payment

    Below is a template you can adapt when disputing a late payment you believe is inaccurate or unverifiable. Replace everything in brackets with your own information, and include copies (not originals) of any supporting documents.

    [Your Name] [Your Address] [City, State ZIP] [Your Phone Number] [Your Date of Birth] [Your Social Security Number — last 4 only, e.g., XXX-XX-1234] [Date] [Credit Bureau Name — Equifax, Experian, or TransUnion] [Bureau Address] RE: Dispute of Inaccurate Late Payment Reporting To Whom It May Concern: I am writing to dispute a late payment that is appearing on my credit report from [Bureau Name]. I believe this information is inaccurate and should be removed. Account Information: – Creditor: [Creditor Name] – Account Number: [Account Number] – Late Payment Date Reported: [Month/Year] – Severity Reported: [30/60/90 days late] – Reason for Dispute: [Choose one: The payment was made on time / The date is incorrect / The severity is incorrect / This account is not mine / The account was in forbearance at the time / Other — explain briefly] Supporting Facts: [In 2–4 sentences, state plainly what happened and why the reporting is wrong. Example: “My bank records show the payment for the December 2024 billing cycle was initiated on December 18, 2024, and posted to the creditor on December 20, 2024 — four days before the due date. The late payment reporting for January 2025 is therefore incorrect.”] Enclosed are copies of the following documents supporting my dispute: – [List each document, e.g., “Bank statement showing payment initiation on 12/18/2024”] – [Creditor’s payment confirmation email dated 12/20/2024] – [Any other evidence] Under the Fair Credit Reporting Act (15 U.S.C. § 1681i), I am requesting that you investigate this dispute within 30 days, contact the furnisher to verify the accuracy of the reporting, and delete this late payment from my credit file if it cannot be verified or is found to be inaccurate. Please send me the results of your investigation in writing, along with an updated copy of my credit report reflecting the deletion if applicable. Thank you for your prompt attention to this matter. Sincerely, [Your Signature] [Your Printed Name] Enclosures: [Number] pages

    A few tips on using this letter:

    • Send it by certified mail with return receipt so you have proof of delivery and the date it was received.
    • Keep a copy of everything you send.
    • Send a separate letter to each bureau that is reporting the late. Do not assume they will share the dispute with each other.
    • Send a separate dispute to the furnisher (the creditor) at the same time. The FCRA gives you the right to dispute directly with furnishers, and doing both at once increases your chances.

    Sample Goodwill Letter for a Legitimate Late Payment

    Below is a template for a goodwill letter — use this when the late payment is accurate but you are asking the creditor to remove it as a courtesy. Be honest, be brief, and be specific about your positive history.

    [Your Name] [Your Address] [City, State ZIP] [Your Phone Number] [Date] [Creditor Name] Attn: Customer Service / Executive Resolutions [Creditor Address] RE: Goodwill Request for Removal of Late Payment Account Number: [Account Number] Dear [Creditor Name] Team, I am writing to respectfully request a goodwill adjustment to remove a late payment reported on my account in [Month/Year of the late]. I have been a customer with [Creditor Name] since [Year you opened the account], and I value our relationship. In [Month/Year], I missed a payment due to [brief, honest reason — e.g., “an unexpected medical emergency that kept me out of work for three weeks” / “a job transition that caused a temporary disruption in my income” / “an oversight while traveling for a family emergency”]. I take full responsibility for the missed payment. Since that time, I have brought the account current and have made [number] consecutive on-time payments. I have also enrolled in autopay to ensure this does not happen again. My account is in good standing. This single late payment is the only blemish on an otherwise strong history with your company, and it is currently preventing me from [specific goal — e.g., “qualifying for a mortgage” / “refinancing my auto loan at a better rate” / “securing a business loan for my small business”]. I am hoping you will consider, as a gesture of goodwill, removing this late payment from my credit report. I understand this is a request and not a requirement, and I appreciate your time in considering it. Thank you for being a company I have trusted with my financial business for [number] years. Sincerely, [Your Signature] [Your Printed Name]

    Tips for goodwill letters:

    • Address it to a real person or office if you can find a name. LinkedIn and executive contact databases can help.
    • Keep it to one page. Long letters get skimmed, not read.
    • Do not cite the FCRA or threaten legal action. This is a favor, not a fight.
    • Send it by mail. Email works sometimes, but a physical letter signals effort and seriousness.
    • If you get a no, wait two to three months and try again, perhaps to a different contact within the company.

    What to Do If the Late Payment Is Verified

    So you disputed the late payment, the bureau investigated, and the furnisher verified it. The late is staying. Now what?

    First, do not panic. A verified late payment is not the end of your credit journey. Here is the playbook for living with — and ultimately moving past — a verified late.

    1. Request a Method of Verification

    Under the FCRA, you have the right to ask the bureau how they verified the item — what process they used, who they contacted, and what evidence the furnisher provided. Send a written request for the method of verification within 15 days of receiving the dispute results. Sometimes the bureau’s “investigation” is nothing more than a database check with the furnisher, and if they cannot produce a meaningful answer, you have grounds to push harder.

    2. Dispute Directly With the Furnisher

    If the bureau’s investigation was cursory, go directly to the creditor. Send them a dispute letter under FCRA Section 623, which requires furnishers to investigate disputes about information they reported. Include your evidence and ask them to correct or withdraw the reporting. Some furnishers are more responsive to direct disputes than to bureau-forwarded ones.

    3. Add a Consumer Statement to Your File

    Under the FCRA, you have the right to add a 100-word consumer statement to your credit report explaining the circumstances behind a negative item. This does not change your score, but it can be seen by lenders who manually review your report, and it gives you a chance to tell your side of the story. This is a small, often-overlooked tool.

    4. File a Complaint if There Is a Real Error

    If you have strong evidence that the late is wrong and the bureau and furnisher are both stonewalling, you can file a complaint with the Consumer Financial Protection Bureau (CFPB) and your state attorney general’s office. The CFPB forwards complaints to the company and requires a response within 60 days. This is not a guarantee of resolution, but it puts pressure on the furnisher and creates a paper trail that can support a future legal claim if one becomes necessary.

    5. Talk to an Attorney

    If a furnisher is knowingly reporting inaccurate information and refuses to correct it, you may have a claim under the FCRA. The FCRA allows consumers to sue for actual damages, statutory damages, and attorney’s fees. This is where the attorney-backed part of what we do matters — having legal counsel review a stubborn, inaccurate reporting situation can change the furnisher’s calculus quickly. Not every case warrants a lawsuit, but some do, and you should know your options.

    6. Focus on What You Can Control

    While you work the dispute, keep building positive credit. On-time payments, low utilization, and new positive accounts all help your score recover even while the late payment sits there. Do not let one verified late payment make you give up on the rest of your credit profile.

    How Late Payments Age and Hurt Less Over Time

    Here is something that often gets lost in the stress of a late payment: the damage shrinks as the late gets older. A late payment does not hurt you the same amount in year one as it does in year six.

    The Recency Curve

    The scoring models are built to care most about what you have done lately. A late payment from two months ago is a strong signal of current trouble. A late payment from four years ago is a much weaker signal — you have had four years to demonstrate that it was an anomaly, not a pattern.

    A rough way to think about the curve:

    • Year 1 (0–12 months): Full impact. The late is hurting you as much as it ever will.
    • Year 2 (12–24 months): Meaningful but softening. Your score has likely recovered some if the rest of your file is clean.
    • Years 3–4: Noticeably less impact. Many people see their scores return to pre-late levels by this point, assuming no new negatives.
    • Years 5–6: Minimal impact. The late is still on your report, but it is barely moving your score.
    • Year 7: The late falls off entirely, and you get whatever small boost remains.

    Why This Matters

    This matters because it tells you where to focus. If you have a late payment from five years ago and a high credit card balance from this month, paying down the balance will help your score more than chasing the old late payment. The recency-weighted scoring means your energy is best spent on the most recent factors first.

    It also means that time is on your side. Every month that passes with on-time payments, the late payment hurts a little less. This is why we encourage clients not to obsess over a single old late at the expense of building strong current habits. The old late is fading; the new habits compound.

    Single 30-Day Late vs. 90-Day Late — The Impact Difference

    People often ask: does it matter whether it was a 30-day late or a 90-day late? The answer is yes — a lot.

    The 30-Day Late

    A single 30-day late on an otherwise clean account is the most survivable negative item on a credit report. It hurts, especially in the first year, but it is the kind of thing lenders see regularly and are willing to overlook with context. A goodwill letter has a real chance of working. A year of on-time payments afterward recovers most of the lost score. Two years out, it is mostly a footnote.

    The 90-Day Late

    A 90-day late is a different animal. It is classified as a major delinquency, and it tells lenders that the missed payment was not a one-time oversight but a sustained period of nonpayment. The score drop is larger, the recovery is slower, and goodwill removals are far less likely because the creditor has a harder time justifying the deletion internally.

    A 90-day late also frequently comes with downstream consequences: the account may be closed by the creditor, the interest rate may be jacked up to a penalty APR, and the account may be charged off and sent to collections. When that happens, you are not dealing with one negative item — you are dealing with a late payment, a charge-off, and a collection, all stemming from the same event.

    The Practical Takeaway

    If you have a choice about which late to address first — say, you have a 30-day late on one account and a 90-day late on another — go after the 90-day late first if there is any chance of removal or settlement, because it is doing more damage. But also know that the 90-day late is harder to remove and that managing the underlying account (settling it, paying it, negotiating reporting) is usually more productive than disputing the late mark in isolation.

    Compound Lates

    If a single account has a 30, then a 60, then a 90 — a streak of escalating lates — the scoring impact compounds. The account looks like it slid into delinquency and stayed there. In these cases, the most effective strategy is usually to address the account as a whole (bring it current, settle it, or negotiate a resolution) rather than trying to pluck individual late marks off one at a time.

    Common Mistakes That Sabotage Removal Attempts

    In our work with clients, we see the same mistakes over and over. Avoiding these will save you time, money, and frustration.

    1. Disputing Everything Hoping Something Sticks

    Filing disputes on accurate items you know are correct, just hoping the furnisher does not respond, is a bad strategy. Bureaus can flag your disputes as frivolous under the FCRA, which lets them refuse to investigate. Once you are flagged, even legitimate disputes become harder. Dispute only items you have a genuine reason to question.

    2. Using Aggressive or Threatening Language

    Whether you are writing a dispute, a goodwill letter, or a negotiation, angry, threatening, or legalistic language backfires. The people reading these are humans with discretion, and a hostile tone makes them less inclined to help. Be firm, be clear, and be polite.

    3. Not Keeping Records

    Every letter you send, every response you receive, every date and every name — keep it all. Disputes and negotiations often come down to who can prove what happened and when. If you cannot show the bureau received your dispute on a specific date, you cannot enforce the 30-day investigation deadline.

    4. Sending Originals Instead of Copies

    Never send original documents to a bureau or furnisher. Send copies. Documents get lost, and if you send your only proof, you may never see it again.

    5. Paying a Collection Without a Written Deletion Agreement

    If you are pursuing pay-for-delete, get the agreement in writing before you pay. Paying first and then asking for deletion almost never works — once they have your money, they have no incentive to help you.

    6. Closing Accounts After a Late Payment

    Closing the account where the late happened does not remove the late from your report, and it can hurt your score by shortening your average account age and reducing your available credit. Keep the account open, keep it current, and let the positive history rebuild.

    7. Believing “Guaranteed Removal” Promises

    Any company that guarantees they can remove accurate, verified late payments is lying. The FCRA does not allow for guaranteed removal of accurate information, and no legitimate credit repair firm — ours included — will promise that. We can pursue every legitimate path, and we do, but we will not lie to you about the odds.

    8. Ignoring the Underlying Debt

    If a late payment is tied to an unpaid debt, chasing the late mark without addressing the debt is a losing game. The debt can be sold, re-reported, and turned into a collection that does far more damage than the original late. Deal with the debt first, then deal with the reporting.

    9. Disputing Online When You Should Dispute by Mail

    Online disputes are fast, but they often ask you to waive certain rights and they limit how much documentation you can attach. For complicated disputes, mail is better — it creates a full paper trail and lets you include everything.

    10. Giving Up After One “No”

    A no from a bureau or a creditor is not always final. Goodwill letters can be sent again to a different contact. Disputes can be reframed with new evidence. Furnishers can be contacted directly. Persistence — within reason and within the rules — pays off.

    Frequently Asked Questions

    Can I remove a late payment that is accurate?

    It is possible but not guaranteed. The most common path for an accurate late payment is a goodwill letter asking the creditor to remove it as a courtesy. Creditors are not required to say yes, and many do not, but some do — especially for isolated lates on accounts with long, otherwise clean histories. If there is an open collection tied to the late, a pay-for-delete negotiation may also be an option.

    How long does a late payment stay on my credit report?

    Up to seven years from the date of the original delinquency, under the FCRA. The late payment should be removed automatically once that period ends. If it is still showing after seven years, you can dispute it as obsolete and the bureau must delete it.

    Will one late payment ruin my credit?

    No. A single 30-day late payment will hurt your score — especially in the first year — but it is not catastrophic, and the impact fades over time. With consistent on-time payments afterward, most people see substantial score recovery within 12 to 24 months. A 90-day late is more serious and takes longer to recover from.

    Can I dispute a late payment online?

    Yes, all three bureaus offer online dispute portals. However, for complicated disputes or ones that require documentation, we recommend disputing by mail with certified delivery. This creates a stronger paper trail and lets you include copies of all your supporting evidence. Online disputes sometimes limit what you can attach and may include arbitration clauses you do not want to agree to.

    Does paying a late payment remove it from my report?

    Not automatically. Paying the overdue amount brings your account current and stops new lates from reporting, but the existing late payment mark stays on your report for up to seven years. To try to remove the mark itself, you would need to dispute it (if it is inaccurate), send a goodwill letter, or negotiate pay-for-delete if a collection is involved.

    What is a goodwill letter and does it work?

    A goodwill letter is a written request to a creditor asking them to remove an accurate late payment from your credit report as a courtesy. It works sometimes — not always. It is most effective for a one-time late on an account with a long, positive history, especially if there was a genuine hardship. Creditors are not obligated to grant goodwill removals, and many have internal policies against it, but the cost of trying is low and the upside is real.

    Can a credit repair company remove late payments?

    A legitimate credit repair company can help you identify inaccurate or unverifiable late payments, file disputes on your behalf, send goodwill letters, and negotiate with creditors and collectors. What a legitimate company cannot do is guarantee the removal of accurate, verified information. If a company promises guaranteed removals, that is a red flag. We pursue every legitimate path, but we will be honest with you about the odds.

    Should I hire a lawyer to remove a late payment?

    For most late payments, a lawyer is not necessary — the dispute and goodwill processes are things you can do yourself or with a credit repair firm. However, if a furnisher is knowingly reporting inaccurate information and refuses to correct it, you may have a claim under the FCRA, and an attorney can help you pursue it. The FCRA allows for actual damages, statutory damages, and attorney’s fees, which means legal representation may be available at no out-of-pocket cost to you depending on the case. This is one of the advantages of working with an attorney-backed credit repair firm.

    How much does a late payment affect my credit score?

    It depends on your starting score, the severity of the late, and how recent it is. A single 30-day late can drop a strong score (780+) by 60 to 110 points. A 90-day late can drop a strong score by 100 to 150 points or more. If your score is already lower, the point drop is smaller. The impact fades each year, and by years 5–6 the late is barely affecting your score even though it is still on your report.

    What is the difference between a late payment and a collection?

    A late payment is a mark on an existing account showing that a payment was overdue by 30, 60, or 90+ days. The account is still open and being reported by the original creditor. A collection is a separate account that appears when the original creditor gives up on collecting the debt and either sells it to a collection agency or hires one to collect on their behalf. A collection is a more serious negative item and typically appears in addition to, not instead of, the late payments that led up to it.

    Get a Free Credit Audit

    A late payment on your credit report is not something you have to figure out alone. Whether the late is inaccurate and needs to be disputed, accurate and needs a goodwill request, or tied to a collection that needs to be negotiated, we can help you map out the right path and walk it with you.

    At credit-repair.com, we offer a free, no-obligation credit audit across all three major bureaus. We will review your reports, identify every late payment and negative item, tell you honestly which ones have a real chance of removal and which ones do not, and lay out a plan tailored to your situation and goals. We are San Diego-based, FCRA-compliant, attorney-backed, and we serve clients nationwide.

    We do not promise quick fixes because quick fixes do not exist. What we promise is transparency, legal compliance, and a genuine partnership focused on your long-term credit health — not just getting one late off your report, but building the knowledge and habits that keep your credit strong for life.

    Request your free credit audit at credit-repair.com →

    Disclaimer: This article is for educational purposes and is not legal advice. Your individual situation may vary. The FCRA provides specific rights and remedies for consumers dealing with inaccurate credit reporting; an attorney can advise you on whether your situation warrants legal action.

  • Debt Validation Letter: Your Right to Make Collectors Prove a Debt

    Debt Validation Letter: Your Right to Make Collectors Prove a Debt

    A debt collector contacts you out of nowhere about a debt you barely recognize — or one you’re certain you already paid. They say you owe $4,200. They reference an account number that looks vaguely familiar. They want payment, and they want it now.

    Here’s what most people don’t know: you have a legal right to make that collector prove the debt exists, that it’s yours, and that the amount is correct — before you pay a single cent. That right lives in a federal law called the Fair Debt Collection Practices Act (FDCPA), and the tool that exercises it is called a debt validation letter.

    A debt validation letter is a written request that forces a collector to stop all collection activity and produce proof of the debt. If they can’t — or won’t — they have to stop collecting. In many cases, they also have to stop reporting the debt to the credit bureaus.

    This guide walks you through every part of the process: what validation is, when to send the letter, what it must contain, what happens after you send it, and what to do when a collector fails to respond. We’ve included a full template you can adapt, a breakdown of how validation interacts with your credit reports, and answers to the questions we hear most often from clients at credit-repair.com.

    Whether you’re dealing with your first collection notice or you’ve been wrestling with an old debt for years, understanding debt validation is one of the most practical, empowering tools in the credit repair process.

    What Is a Debt Validation Letter?

    A debt validation letter is a written notice you send to a debt collector requesting that they prove a debt is legitimate before they continue trying to collect it. It is a formal, legally recognized request that triggers specific obligations under the FDCPA.

    When you send a validation letter, you’re asking the collector to produce evidence that:

    • The debt actually exists — there’s a real underlying obligation, not a fabricated or mistaken entry.
    • The debt belongs to you — it’s tied to your identity, your account, and your signature (or other proof of obligation).
    • The amount is accurate — the balance, fees, and interest have been calculated correctly and legally.
    • The collector has the authority to collect it — they either own the debt or have been authorized by the original creditor to collect on it.

    Think of it as the collector’s homework assignment. You’re not refusing to pay. You’re saying, “Before I hand over money to a stranger who called me on a Tuesday afternoon, I need you to show me the paperwork.”

    This matters more than most people realize. Debts change hands constantly. An original creditor sells a portfolio of accounts to a debt buyer, who sells it to another, who assigns it to a collection agency. With each transfer, records degrade. Account numbers get transposed. Balances get inflated with questionable fees. Sometimes the same debt gets sold to two different collectors, and both come after you.

    A validation letter forces clarity into a process that is otherwise opaque and one-sided.

    Debt validation letter vs. debt verification notice

    People often use “validation” and “verification” interchangeably, but under the FDCPA they refer to different things — and the distinction matters.

    • A validation notice (sometimes called a validation letter or dunning notice) is what the collector sends to you within five days of their first contact. It tells you how much they claim you owe, who the original creditor is, and that you have 30 days to dispute the debt.
    • A debt validation letter is what you send to the collector within that 30-day window. It’s your request for proof. In everyday conversation and in this guide, when we say “debt validation letter,” we mean the letter you send to request validation.

    We’ll dig into what the law requires collectors to produce in .

    Your Right to Validate Under the FDCPA

    The Fair Debt Collection Practices Act (FDCPA) is a federal law passed in 1978 that regulates how third-party debt collectors operate. Its core purpose is to eliminate abusive, deceptive, and unfair debt collection practices — and one of the most important protections it gives consumers is the right to request validation of a debt.

    The specific provision is 15 U.S.C. § 1692g, and here’s what it says in plain terms:

    If a debt collector contacts you about a debt, they must send you a written notice (either with the first contact or within five days of it) that includes:

    That third and fourth point are the heart of your validation right. The collector’s notice must explicitly tell you that you have 30 days to dispute the debt in writing, and that if you do, they have to verify it.

    Who is covered by the FDCPA?

    The FDCPA applies to third-party debt collectors — collection agencies, debt buyers, and attorneys who regularly collect debts. It does not apply to original creditors collecting their own debts (like a credit card company calling you about its own account). However, many states have their own laws that extend similar protections to original creditors, and the Fair Credit Reporting Act (FCRA) provides separate protections for how debts are reported.

    This is a distinction worth understanding: if Chase calls you about a Chase credit card, the FDCPA may not apply. If a collection agency calls you about that same Chase account, the FDCPA absolutely applies.

    What counts as “in writing”?

    The FDCPA requires that your dispute or validation request be made in writing. A phone call is not enough. This is why sending a formal debt validation letter — and keeping proof of mailing — is essential.

    Some collectors may accept disputes electronically, but to preserve your full legal rights, a written letter sent via certified mail with return receipt is the gold standard. We’ll cover this in detail in .

    The 30-Day Validation Window

    The FDCPA gives you a specific window to request validation: 30 days from the date you receive the collector’s initial validation notice.

    Here’s how the timeline works:

    • First contact — A collector contacts you for the first time (by phone, letter, or other means).
    • Validation notice — Within five days of that first contact, the collector must send you a written validation notice containing the information described above.
    • 30-day clock — The 30-day period begins when you receive the notice. If you receive it on March 1, your 30 days run through March 31.
    • Your validation request — You send your debt validation letter within those 30 days.
    • Collection must pause — Once the collector receives your written dispute, they must cease all collection activity until they obtain and mail you verification of the debt.

    What happens if you miss the 30-day window?

    This is one of the most common — and most consequential — misunderstandings about debt validation.

    If you miss the 30-day window, the collector is allowed to assume the debt is valid and continue collection efforts. However — and this is critical — you do not lose the right to request validation. You can still send a validation letter after the 30 days have passed.

    The difference is in the effect:

    • Within 30 days: The collector is legally required to cease collection activity and verify the debt before resuming. They cannot sue you, report to credit bureaus, or continue calling while validation is pending.
    • After 30 days: The collector is not legally required to cease collection activity in response to your request. They can continue collecting while they respond — or they can ignore your request entirely. Many will still respond, especially if the request is well-written, but the FDCPA’s automatic cease-collection requirement no longer applies.

    This is why timing matters so much. If you’re within 30 days of first contact, send the letter. If you’re outside the window, you can still send it — but understand that the legal leverage is weaker, and you may need to combine it with other strategies (like FCRA disputes or state-law claims) to achieve the same result.

    How to know if you’re within the window

    If you received a written notice from the collector, check the date on it. The 30-day clock starts from when you received it, not the date printed on it. If you’re not sure when it arrived, err on the side of acting quickly. If the first contact was a phone call and you never received a written notice, the collector may have violated the FDCPA by failing to send one — and you can still send a validation letter, noting that you never received the required notice.

    Validation vs. Verification: What the Law Actually Requires

    Here’s where things get nuanced — and where a lot of consumers (and even some practitioners) get confused.

    The FDCPA says that if you dispute a debt within 30 days, the collector must obtain “verification of the debt” and mail it to you. But the law doesn’t precisely define what “verification” means. Over the years, courts have interpreted this requirement, and the results vary by jurisdiction.

    The minimal interpretation

    In the landmark case Marshall v. Medina (2003), the court held that verification can be minimal — the collector confirming the debtor’s name, the amount, and that they have records from the original creditor. Under this interpretation, a collector can satisfy the FDCPA by sending you a simple letter that says, “We have confirmed with the original creditor that you owe $X for account Y.”

    This is frustrating for consumers because it feels like the collector just… said the same thing again. But under this minimal standard, that may be technically sufficient.

    The more demanding interpretation

    Other courts have taken a broader view. In Chaudhry v. Gallerizzo (1997), the court suggested that verification requires the collector to obtain confirming information from the creditor and share enough detail that the consumer can meaningfully identify the debt and dispute it if it’s wrong.

    And in 2021, the Consumer Financial Protection Bureau (CFPB) issued Regulation F, which clarified and modernized FDCPA requirements. Under Reg F, when a collector responds to a validation request, they must provide:

    • The amount of the debt at charge-off (if different from the current balance)
    • The amount of interest, fees, and other charges added since charge-off
    • The current balance
    • The name of the original creditor (if requested)
    • If the debt was sold or transferred, information about the current creditor

    This is significantly more than the old “we confirm you owe $X” standard. It gives you a fighting chance to see whether the amount has been inflated, whether fees are legitimate, and whether the chain of ownership is intact.

    What “validation” should look like in practice

    At a minimum, proper validation should include:

    • The original creditor’s name and address
    • The original account number
    • The amount owed at charge-off
    • An itemization of interest, fees, and charges added since
    • The current balance
    • The name of the current creditor (if the debt was sold)
    • Some documentation connecting you to the debt — ideally a signed application, account statements, or a contract

    If a collector sends you a one-line letter that says “We verified your debt of $4,200 with [Creditor],” that may technically satisfy the FDCPA in some jurisdictions — but it’s weak validation, and there are ways to push back. We cover those in .

    The practical takeaway

    The law sets a floor, not a ceiling. A well-written validation letter requests specific documents — account agreements, statements, proof of assignment — rather than just asking the collector to “verify” the debt. This puts the burden on the collector to either produce real documentation or admit they don’t have it.

    Why Debt Validation Matters

    You might be wondering: if collectors can sometimes satisfy validation with a minimal letter, what’s the point of sending one at all?

    The answer is that debt validation serves several critical purposes, and the letter itself is a tool that does more than just trigger the FDCPA’s verification requirement.

    1. It forces the collector to prove the debt — or stop collecting

    The most powerful effect of a timely validation letter is the cease-collection requirement. Once the collector receives your written dispute within the 30-day window, they must stop all collection activity until they verify the debt. That includes:

    • Phone calls and letters
    • Lawsuits
    • Credit reporting (more on this below)
    • Garnishment proceedings

    If the collector can’t produce verification, they cannot legally resume collection. For many debts — especially older ones that have been sold multiple times — the collector simply doesn’t have the documentation. The original creditor’s records are gone. The chain of assignment is broken. In these cases, the debt effectively becomes uncollectible.

    2. It surfaces errors and inaccuracies

    Debts are transferred, sold, and re-sold. At each step, information degrades. We regularly see:

    • Wrong amounts — fees and interest added that weren’t authorized in the original agreement
    • Wrong consumer — debts mixed up due to similar names, shared addresses, or data entry errors
    • Duplicate debts — the same account placed with two different collectors
    • Already-paid or settled debts — accounts that were resolved but resurface in collection
    • Identity theft — accounts opened fraudulently in the consumer’s name
    • Time-barred debts — debts past the statute of limitations being collected as if they’re still enforceable

    A validation letter forces these issues into the open. If the collector’s records don’t match reality, the validation process exposes that.

    3. It creates a paper trail

    Every communication you send via certified mail creates a documented record. If you later need to prove that you disputed the debt, that the collector failed to validate, or that the collector continued collection activity illegally, your paper trail is your evidence.

    This matters for two reasons:

    • FCRA enforcement — If a collector reports a debt to the credit bureaus after you’ve disputed it and they haven’t validated, they may be violating the FCRA. Your validation letter and certified mail receipts are the proof.
    • FDCPA lawsuits — If a collector violates the FDCPA (continues collecting without validating, sues you during the validation period, etc.), you may have grounds for a lawsuit. Statutory damages under the FDCPA can be up to $1,000 per violation, plus actual damages and attorney’s fees.

    4. It puts you in control

    Most collection interactions are one-directional: the collector demands, the consumer pays (or panics). A validation letter flips that dynamic. You’re not refusing to pay — you’re exercising a legal right and requiring the collector to do their homework before you write a check.

    This shift in control is significant. It moves the conversation from “pay up” to “prove it,” and it gives you time and information to make a good decision.

    When to Send a Debt Validation Letter

    The best time: within 30 days of first contact

    If a debt collector contacts you and you receive their validation notice, send your debt validation letter as soon as possible — and absolutely within 30 days. This is when you have the strongest legal rights.

    Within the 30-day window:

    • The collector must cease all collection activity upon receiving your letter
    • The collector must obtain verification and mail it to you
    • The collector cannot sue you while validation is pending
    • The collector generally should not report the debt to credit bureaus during the validation period

    There is no advantage to waiting. The moment you receive the validation notice, the clock is running. Send the letter promptly.

    What counts as “first contact”?

    First contact can be:

    • A phone call from the collector (they must follow up with a written notice within five days)
    • A letter in the mail
    • An email or text message (under Reg F, collectors can use electronic communications, but they must still provide the validation notice)
    • A message left on your answering machine (though this raises separate FDCPA concerns about third-party disclosure)

    If you received a phone call and no written notice followed within five days, the collector may have violated the FDCPA. You can still send a validation letter, and you should note in the letter that you never received the required written notice.

    After the 30-day window: you can still request validation

    If you’re past the 30-day window, you have not lost your right to ask for validation. You can still send the letter. The difference is that the collector is not legally required to cease collection while they respond.

    That said, sending a validation letter after the window is still worthwhile for several reasons:

    • Many collectors will still respond — especially if the request is specific and well-written. They know that ignoring a written request looks bad if the matter ends up in court.
    • It creates a paper trail — documenting that you asked for proof and what the collector did (or didn’t) provide.
    • It supports FCRA disputes — if you dispute the debt with the credit bureaus, having a validation request on record strengthens your position.
    • It may reveal FDCPA violations — if the collector continues collection activity without validating, that may be actionable even outside the 30-day window in certain circumstances.

    When you should always send a validation letter

    Regardless of timing, you should send a validation letter when:

    • You don’t recognize the debt — you have no memory of the account or the creditor
    • The amount seems wrong — it’s higher than you remember, or includes fees you don’t understand
    • You believe the debt was already paid or settled
    • You suspect identity theft — the account may have been opened in your name fraudulently
    • The collector is aggressive or threatening — you want to shift to written communication and create a record
    • The debt is old — it may be time-barred or past the credit reporting window
    • You’re considering bankruptcy or settlement — you need to know exactly what you owe and to whom before making decisions

    When you might not need to send one

    If you know the debt is yours, the amount is correct, you have the means to pay it, and your goal is simply to resolve it — you may choose to negotiate directly rather than validate. But even then, a validation letter can be a useful opening move: it pauses collection activity, giving you breathing room to negotiate from a calmer position.

    What Must Be in Your Validation Letter

    A debt validation letter doesn’t need to be written in legal language or follow a rigid format. But it does need to be clear, specific, and sent in writing. Here are the elements every effective validation letter should include.

    1. Your identifying information

    Include your full name, current address, and (optionally) the last four digits of your Social Security number. This helps the collector match your letter to the right account. Do not include your full SSN — the last four are sufficient.

    2. The collector’s information

    Address the letter to the specific collection agency, using the name and address from their validation notice.

    3. A clear statement that you are disputing the debt

    Your letter must explicitly state that you are disputing the debt and requesting validation. Use those words. Do not say “I’d like more information” or “Can you send me details?” — that may not be treated as a formal dispute under the FDCPA.

    4. Reference to the specific debt

    Include the account number, the original creditor’s name (if known), and the amount the collector claims you owe. This comes from their validation notice. If you don’t have all of this information, include what you do have.

    5. Specific requests for documentation

    This is where a good validation letter goes beyond the minimum. Don’t just ask for “verification.” Ask for specific documents:

    • A copy of the original signed contract or application
    • Account statements showing the charges and payments
    • The date of the last payment and the charge-off date
    • An itemization of all fees, interest, and charges added since charge-off
    • Proof that the collector owns the debt or has authority to collect it (chain of assignment)
    • The original creditor’s name and address

    6. A demand to cease collection activity

    State clearly that under the FDCPA, the collector must cease all collection activity until validation is provided. This includes phone calls, letters, lawsuits, and credit reporting.

    7. A request for communication preferences

    You can specify how you want the collector to communicate with you. Many people request that all communication be in writing only — no phone calls. Under the FDCPA, collectors must honor a written request to cease communication (though this is a separate request under § 1692c).

    8. Your signature and the date

    Sign the letter and date it. Keep a copy for your records.

    9. Proof of mailing

    This isn’t part of the letter itself, but it’s essential: send the letter via certified mail with return receipt requested. The return receipt is your proof that the collector received your letter and when. Without it, a collector can claim they never got your dispute, and you’ll have no way to prove otherwise.

    The return receipt costs a few dollars at the post office. It is one of the best investments you can make in the credit repair process.

    Sample Debt Validation Letter Template

    Below is a template you can adapt for your own use. Replace the bracketed information with your specific details. This template is designed to be thorough — it requests specific documents and clearly invokes your FDCPA rights.

    This template is for educational purposes and is not legal advice. Your situation may have nuances that require professional guidance. If you’re working with an attorney, follow their instructions.

    [Your Full Name] [Your Current Address] [Your City, State, ZIP] [Your Phone Number] [Last 4 digits of SSN: XXXX] [Date] [Collector/Agency Name] [Collector Address] [Collector City, State, ZIP] RE: Dispute of Debt and Request for Validation Account Number: [Account number from validation notice] Original Creditor: [Name from validation notice, if known] Amount Claimed: $[Amount from validation notice] To Whom It May Concern: I am writing in response to your [letter / phone call] dated [date], regarding the above-referenced account. I do not recall this debt and am disputing it in its entirety. Pursuant to my rights under the Fair Debt Collection Practices Act (FDCPA), 15 U.S.C. § 1692g, I am requesting that you validate this debt. Specifically, I am requesting that you provide me with the following: 1. The name and address of the original creditor and the account number associated with this debt. 2. A copy of the original signed contract, application, or other agreement that created the underlying obligation. 3. Account statements from the original creditor showing the charges, payments, and the charge-off date. 4. The date of my last payment to the original creditor. 5. A complete itemization of the debt, including: – The balance at the time of charge-off – All interest, fees, and charges added since charge-off, with the basis for each – The current balance you are attempting to collect 6. Proof that you currently own this debt or have been authorized by the creditor to collect it, including any applicable chain of assignment or transfer of ownership from the original creditor to your agency. 7. Confirmation of whether this debt is within the applicable statute of limitations for enforcement in my state. Please be advised that under 15 U.S.C. § 1692g(b), you must cease collection of this debt — including all phone calls, letters, credit reporting, and legal action — until you have obtained verification of the debt and mailed it to me. I also request that all future communication regarding this matter be conducted in writing only. Do not contact me by telephone at home or at work. If you cannot provide the documentation requested above, I expect that you will cease all collection activity, notify me in writing that you are unable to validate this debt, and remove any information you have reported about this debt to the credit reporting agencies. I expect a response within 30 days of your receipt of this letter. Sincerely, [Your Signature] [Your Printed Name]

    Tips for using this template

    • Send it certified mail with return receipt. Keep the receipt and the returned postcard in a safe place.
    • Keep a copy of the signed letter. You may need it later.
    • Do not admit to the debt. The letter says “I do not recall this debt” — that’s a dispute, not an admission.
    • Customize the requests. If you know the debt is yours but the amount is wrong, focus your requests on the itemization and charge-off details. If you suspect identity theft, emphasize the request for the signed application.
    • Be accurate. Don’t claim you don’t recognize the debt if you do. You can still dispute the amount or request validation without denying the debt exists.

    What Happens After You Send the Letter

    Once the collector receives your validation letter (and you have the return receipt to prove it), several things happen — or should happen.

    The collector must cease collection activity

    Under FDCPA § 1692g(b), if you dispute the debt in writing within the 30-day window, the collector must cease collection of the debt until they obtain verification and mail it to you.

    “Collection activity” is broadly defined. It includes:

    • Phone calls and letters demanding payment
    • Filing or pursuing a lawsuit against you
    • Reporting the debt to credit bureaus (more on this in )
    • Garnishing wages or levying bank accounts
    • Any other act intended to collect the debt

    If the collector continues any of these activities after receiving your letter and before validating, they may be violating the FDCPA. Document every contact — save voicemails, keep letters, note dates and times of calls.

    The collector must obtain verification

    The collector must obtain verification of the debt (or a copy of a judgment, if the debt is based on one) and mail it to you. There is no specific deadline in the FDCPA for how long the collector has to respond — the law says they must do it, but it doesn’t say “within X days.”

    In practice, most collectors respond within 30–60 days. But some take longer, and some never respond at all. If a collector doesn’t respond, the cease-collection requirement remains in effect — they cannot resume collection without validating.

    What if the collector sues you during the validation period?

    If a collector files a lawsuit against you after you’ve sent a timely validation letter and before they’ve validated, that is generally a violation of the FDCPA. If this happens:

    • Respond to the lawsuit. Do not ignore a court summons, even if the collector is violating the FDCPA. File an answer with the court asserting your validation rights as a defense.
    • Contact an attorney. An FDCPA violation may give you a countersuit for statutory damages, actual damages, and attorney’s fees.
    • Document everything. Your certified mail receipt, the date the lawsuit was filed, and any other communications are all evidence.

    What if the collector sells the debt to another agency?

    Sometimes, instead of validating, a collector will sell the debt to another agency. This is not a violation per se — but the new collector becomes subject to the same FDCPA requirements. When the new collector contacts you, a new 30-day validation window begins, and you can send another validation letter.

    This is frustrating, but it’s also an opportunity. Each time a debt changes hands, the documentation chain weakens. The further a debt travels from the original creditor, the harder it is for any collector to validate it.

    Debt validation letter template and FDCPA debt collection rights

    What Proper Validation Looks Like

    When a collector responds to your validation request, the quality of their response matters enormously. Here’s what proper, thorough validation should include — and what weak validation looks like.

    Strong validation

    A collector who has solid documentation should be able to provide:

    • A copy of the original agreement or application showing your signature
    • Account statements from the original creditor showing the transaction history
    • The charge-off date and balance at charge-off
    • A clear itemization of interest, fees, and charges added since charge-off, with the contractual or legal basis for each
    • Proof of ownership or assignment — documentation showing the debt was transferred from the original creditor to the current collector, including the chain of transfers if the debt was sold multiple times
    • The current creditor’s name and address

    If you receive all of this, the debt is well-documented. Your next steps depend on your goals — you might negotiate a settlement, set up a payment plan, or, if the documentation reveals errors, dispute specific aspects of the debt.

    Weak validation

    Weak validation looks like:

    • A one-paragraph letter stating “We have verified that you owe $X to [Creditor]” with no supporting documents
    • A printout from the collector’s own database (not from the original creditor)
    • A statement that says “We have confirmed the debt with the original creditor” but includes no account statements, no contract, and no itemization
    • A response that includes the original creditor’s name but nothing else

    Under the minimal interpretation of the FDCPA (the Marshall v. Medina standard), weak validation may technically satisfy the collector’s obligation. But it doesn’t mean you’re out of options.

    What to do with weak validation

    If you receive weak validation:

    • Send a follow-up letter. Acknowledge their response and state that it is insufficient. Request the specific documents listed in your original letter — the signed agreement, account statements, itemization, and proof of assignment. State that their response does not constitute adequate validation and that you continue to dispute the debt.
    • Dispute with the credit bureaus. If the debt is on your credit reports, file disputes with Equifax, Experian, and TransUnion. Under the FCRA, if a furnisher cannot verify a debt, it must be removed. We cover this in .
    • Consider the FCRA angle. If the collector is reporting the debt to the bureaus but can’t produce real documentation, there may be a tension between their FDCPA obligation and their FCRA obligation. A collector who can’t validate a debt to you arguably can’t verify it to the bureaus either.
    • Consult a professional. If the amount is significant or the collector is aggressive, an attorney who specializes in FDCPA and FCRA cases can help. Many offer free consultations and work on contingency.

    What to Do If They Don’t Respond or Send Weak Validation

    Non-response and weak response are two of the most common outcomes — and both can work in your favor if you handle them correctly.

    If the collector doesn’t respond at all

    If you sent your validation letter certified mail within the 30-day window and the collector never responds:

    • The cease-collection requirement remains in effect. The collector cannot legally resume collection activity. If they do — by calling, writing, suing, or reporting to the bureaus — they are violating the FDCPA.
    • Document any continued collection activity. Save every letter, voicemail, and note every phone call. If they sue you, respond to the lawsuit and raise the validation defense.
    • Send a follow-up letter. Note that they have not responded to your validation request and that collection activity must continue to cease. Request that they confirm in writing that they cannot validate the debt and that they will close the account and remove any credit reporting.
    • Dispute with the credit bureaus. File disputes with all three bureaus. When the bureaus contact the collector to verify the debt, the collector’s failure to validate to you makes it harder for them to verify to the bureaus. If they can’t verify, the debt must be removed.
    • Consider legal action. If the collector continues collection activity without validating, you may have an FDCPA claim. Statutory damages are up to $1,000 per violation, plus actual damages and attorney’s fees. Many consumer protection attorneys offer free consultations.

    If the collector sends minimal or weak validation

    As discussed above, weak validation may technically satisfy the FDCPA in some jurisdictions. But it doesn’t end the story:

    • Send a follow-up letter stating that their response is insufficient and requesting the specific documents you originally asked for.
    • Dispute with the credit bureaus under the FCRA. The FCRA requires that reported information be accurate and verifiable. If the collector can’t produce real documentation, the bureaus may not be able to verify it.
    • Request a method of verification (MOV) from the credit bureaus after they “verify” the debt. The bureau must provide a description of the procedure they used to verify. If the verification was cursory, this can support further disputes.
    • Look for other violations. Collectors who send weak validation sometimes also violate other FDCPA provisions — failing to send the initial validation notice, calling at prohibited times, misrepresenting the debt, or adding unauthorized fees.

    If the collector claims they’ve already validated

    Sometimes a collector will claim that the initial letter they sent you (the validation notice) is the validation. This is incorrect. The validation notice is the notice of your right to validate — it is not itself validation. Validation must be obtained after you dispute, and it must come from the original creditor or from the collector’s own records obtained from the original creditor.

    If a collector makes this claim, respond in writing clarifying that their initial notice is not validation and that you are still awaiting the documentation you requested.

    How Validation Interacts With Credit Reporting

    This is one of the most important — and most overlooked — connections in credit repair: debt validation under the FDCPA and credit reporting under the FCRA are linked. Understanding how they interact can help you remove invalid debts from your credit reports.

    The FDCPA side

    Under FDCPA § 1692g(b), once you dispute a debt in writing within 30 days, the collector must cease collection activity until they validate. The CFPB and many courts have taken the position that reporting a debt to credit bureaus is a form of collection activity. Therefore, if a collector is required to cease collection, they should also cease reporting — or at minimum, report the debt as “disputed.”

    The FCRA side

    Under the FCRA (15 U.S.C. § 1681s-2), when a furnisher (the collector) reports information to a credit bureau, and the consumer disputes that information directly with the bureau, the bureau must notify the furnisher. The furnisher must then:

    • Conduct a reasonable investigation
    • Review all relevant information provided by the bureau
    • Report the results to the bureau
    • If the information is inaccurate or cannot be verified, modify or delete the item

    Additionally, under FCRA § 1681s-2(a)(3), if a consumer disputes a debt directly with the furnisher (which is what your validation letter does), the furnisher must:

    • Note that the debt is disputed when reporting it to the bureaus
    • Conduct an investigation
    • If the information cannot be verified, delete it

    The practical intersection

    Here’s how these two laws work together:

    • You send a validation letter to the collector (FDCPA). The collector must cease collection — including reporting the debt as “owed” without noting the dispute.
    • The collector should report the debt as “disputed” on your credit reports. This doesn’t remove the debt, but it signals to anyone viewing your report that the debt is contested.
    • If the collector can’t validate, they should not continue to report the debt. Continuing to report a debt you’ve disputed, without being able to verify it, may violate both the FDCPA and the FCRA.
    • You can also dispute directly with the credit bureaus (FCRA). The bureau contacts the collector. If the collector can’t verify, the bureau must remove the debt.
    • If the bureau “verifies” despite the collector’s inability to validate, you can request a method of verification and escalate.

    A strategic approach

    At credit-repair.com, we often recommend a two-pronged strategy:

    • Send the validation letter to the collector (FDCPA) — this creates the legal obligation and the paper trail.
    • File disputes with the credit bureaus (FCRA) — this triggers the bureau’s verification process.

    If the collector can’t validate to you, they may also fail to verify to the bureaus. If they verify to the bureaus but can’t validate to you, that inconsistency can be used to challenge the reporting.

    This is where professional help can make a real difference. The interplay between the FDCPA and FCRA is technical, and collectors and bureaus don’t always follow the rules. An experienced credit repair professional — especially one working alongside attorneys — can navigate this intersection effectively.

    Debt Validation vs. Credit Bureau Disputes

    People often confuse debt validation with credit bureau disputes. They’re related but distinct tools, and understanding the difference helps you use both effectively.

    Debt validation (FDCPA)

    • Who you contact: The debt collector
    • What you’re doing: Demanding that the collector prove the debt is legitimate before they continue collecting
    • Legal basis: Fair Debt Collection Practices Act (FDCPA)
    • Effect: The collector must cease collection activity until they validate
    • Best for: Stopping collection calls, preventing lawsuits, forcing the collector to produce documentation, challenging the existence or accuracy of the debt at the source

    Credit bureau dispute (FCRA)

    • Who you contact: The credit reporting agencies (Equifax, Experian, TransUnion)
    • What you’re doing: Telling the bureaus that information on your credit report is inaccurate or unverifiable and asking them to investigate
    • Legal basis: Fair Credit Reporting Act (FCRA)
    • Effect: The bureau contacts the furnisher (the collector or original creditor). If the furnisher can’t verify, the item is removed from your credit report
    • Best for: Removing inaccurate, unverified, or obsolete information from your credit reports

    How they work together

    These two tools are most powerful when used together:

    • Send a validation letter to the collector. This forces them to produce documentation or cease collecting.
    • File disputes with the credit bureaus for the same debt. The bureau asks the collector to verify.
    • If the collector can’t validate (to you) and can’t verify (to the bureau), the debt may be removed from your credit reports AND the collector may have to stop collecting.
    • If the collector validates (produces real documentation), you can review it for accuracy. If it contains errors, you can dispute those specific errors with the bureaus.
    • If the collector verifies to the bureau but sends you weak or no validation, you can challenge the inconsistency — request a method of verification from the bureau, file a complaint with the CFPB, or consult an attorney.

    The key difference in one sentence

    Validation makes the collector prove the debt. Disputes make the credit bureaus check the reporting. Both are necessary for comprehensive credit repair.

    Common Mistakes to Avoid

    Over years of helping clients navigate credit repair, we’ve seen the same mistakes crop up again and again. Here are the most common — and how to avoid them.

    1. Waiting too long to respond

    The 30-day validation window is short, and life is busy. Many people set the collector’s letter aside, intending to deal with it later, and the window closes. Send your validation letter as soon as you receive the collector’s notice. Even if you’re not sure what to do about the debt, preserving your validation rights buys you time and options.

    2. Calling the collector instead of writing

    A phone call does not preserve your FDCPA rights. The law requires a written dispute. You can call to get information, but follow up immediately with a written validation letter sent certified mail.

    3. Not sending certified mail

    If you send a validation letter by regular mail and the collector claims they never received it, you have no proof. Always use certified mail with return receipt. The few dollars it costs are trivial compared to the value of the proof it provides.

    4. Admitting to the debt

    Be careful with your language. If you’re not sure the debt is yours, say “I do not recall this debt and am disputing it.” Don’t say “I think I might owe this but I’m not sure” — that can be treated as an admission. You can always acknowledge the debt later if validation confirms it. You cannot un-say an admission.

    5. Sending a vague letter

    “I dispute this debt” is technically sufficient, but it’s weak. A letter that requests specific documents — the signed contract, account statements, itemization, proof of assignment — puts more pressure on the collector and makes it harder for them to satisfy validation with a one-line response.

    6. Ignoring the debt after sending the letter

    Sending a validation letter is not the end of the process — it’s the beginning. If the collector validates, you need to review the documentation. If they don’t, you need to follow up, dispute with the credit bureaus, and document any continued collection activity. Stay engaged.

    7. Failing to document everything

    Keep copies of every letter you send and receive, every certified mail receipt, every voicemail, and a log of every phone call. If you ever need to prove an FDCPA or FCRA violation, your documentation is your evidence.

    8. Believing the debt will just disappear

    Sometimes a collector can’t validate and the debt goes away. But sometimes they validate, sell the debt, or continue collecting in violation of the FDCPA. Don’t assume silence means victory. Follow up, and if the debt persists, get professional help.

    9. Paying a debt you’re disputing without a written agreement

    If you decide to settle or pay the debt after validation, get the terms in writing first. “If you pay $X, we will report the account as paid in full and remove it from your credit report” should be in writing before you send money. Verbal promises from collectors are notoriously unreliable.

    10. Not knowing your state’s statute of limitations

    Each state has a statute of limitations on debt — the time period during which a collector can sue you to enforce the debt. These range from 3 to 10 years depending on the state and the type of debt. If a debt is time-barred, a collector can still attempt to collect (in most states), but they cannot sue you. Making a payment or even acknowledging the debt in writing can restart the clock. Before you do anything with an old debt, find out if it’s time-barred.

    Scams and Pitfalls to Watch For

    The debt collection world attracts bad actors. Here are scams and pitfalls to be aware of.

    Phantom debt collection

    Some scammers contact consumers about debts that don’t exist — fabricated account numbers, fictitious creditors, and threats of legal action. They rely on fear and confusion. Signs of phantom debt collection:

    • The collector can’t or won’t provide an address
    • They demand immediate payment by wire transfer, gift cards, or prepaid cards
    • They threaten arrest or jail (debt is a civil matter, not criminal)
    • They refuse to send a validation notice
    • The debt doesn’t appear on your credit reports

    If you suspect phantom debt collection, request validation in writing and report the collector to the CFPB and the Federal Trade Commission (FTC).

    Debt collection without proper licensing

    Many states require debt collectors to be licensed. If a collector is unlicensed in your state, they may be violating state law, and their ability to collect may be legally impaired. Your state attorney general’s office or department of consumer affairs can tell you whether a collector is licensed.

    “Pay for delete” scams

    Some companies promise to remove negative items from your credit report in exchange for payment. While pay-for-delete arrangements do exist (and can work when done correctly with the original creditor or collector), be wary of companies that:

    • Guarantee removal (no one can guarantee this)
    • Demand payment before providing any service
    • Won’t put the arrangement in writing
    • Are not a legitimate, established business

    Credit repair scams

    Be cautious of any credit repair company that:

    • Promises to remove accurate, verifiable information (they can’t — it’s illegal to claim this)
    • Demands payment before providing services (the Credit Repair Organizations Act prohibits this)
    • Advises you to dispute accurate information or create a “new” credit identity
    • Won’t provide a written contract

    Legitimate credit repair firms — like those that operate in compliance with the FCRA and work alongside attorneys — are transparent about what they can and cannot do. They don’t guarantee specific outcomes, they explain the process, and they charge fees that are clearly disclosed.

    Restarting the statute of limitations

    As mentioned above, making a payment — or in some states, even acknowledging the debt in writing — can restart the statute of limitations clock on an old debt. If you have an old debt that’s approaching or past the statute of limitations, talk to a professional before taking any action.

    Frequently Asked Questions

    1. Does a debt validation letter hurt my credit?

    No. Sending a debt validation letter does not directly affect your credit score. The debt may already be on your credit report (which does affect your score), but the act of requesting validation doesn’t add a negative mark. In fact, if the collector cannot validate and the debt is removed from your credit reports, your score may improve. While the dispute is being processed, the debt should be reported as “disputed” — which is a neutral marker, not a negative one.

    2. Can I send a debt validation letter for a debt that’s already on my credit report?

    Yes. A debt can be on your credit report and still subject to validation. In fact, if you see a collection account on your credit report that you don’t recognize or believe is inaccurate, sending a validation letter to the collector and filing a dispute with the credit bureaus is the recommended approach. The two processes work together under the FDCPA and FCRA respectively.

    3. What if the 30-day window has already passed — is it too late?

    No. You can still send a validation letter after the 30-day window. The difference is that the collector is not legally required to cease collection activity while they respond. However, many collectors will still respond, and the letter creates a paper trail that supports credit bureau disputes and any potential legal claims. The 30-day window gives you the strongest rights, but it’s not the only opportunity to request validation.

    4. Can a collector still sue me if I send a validation letter?

    If you send the letter within the 30-day window, the collector must cease collection activity — including lawsuits — until they validate. If they sue you anyway, that’s generally an FDCPA violation, and you should respond to the lawsuit and contact an attorney. If you send the letter after the 30-day window, the collector is not required to cease collection, and they may proceed with a lawsuit. However, if they can’t produce documentation, you can use that in your defense.

    5. How long does the collector have to respond to my validation letter?

    The FDCPA does not specify a deadline. It says the collector “shall cease collection” until they obtain verification and mail it to you. In practice, most collectors respond within 30–60 days. If they don’t respond, they cannot resume collection. There’s no point at which the law says “the collector took too long, so the debt is void” — but the longer they go without validating, the harder it is for them to justify continued collection or credit reporting.

    6. What if the collector validates but the information is wrong?

    If the collector provides documentation but it contains errors — wrong amount, wrong dates, fees you didn’t agree to — you can dispute the specific inaccuracies with both the collector and the credit bureaus. Under the FCRA, if the furnisher cannot verify the accuracy of the information, it must be corrected or removed. Review the validation carefully and identify any discrepancies. This is where professional help can be valuable — an experienced credit repair professional or attorney can spot errors you might miss.

    7. Do I need an attorney to send a debt validation letter?

    No. You can send a validation letter on your own — the template in this guide gives you a starting point. However, if the debt is large, the collector is aggressive, or you suspect FDCPA or FCRA violations, consulting an attorney who specializes in consumer protection law is wise. Many offer free consultations and work on contingency for FDCPA cases. At credit-repair.com, we work alongside experienced attorneys to ensure every step of the process is legally sound.

    8. Will validating a debt reset the statute of limitations?

    This depends on your state. In most states, simply disputing a debt or requesting validation does not reset the statute of limitations clock. However, making a payment, entering a payment agreement, or in some states, acknowledging the debt in writing can reset the clock. This is why it’s important to be careful with your language and to consult a professional if you’re dealing with an old debt. Your validation letter should dispute the debt — not acknowledge it.

    Take the Next Step

    A debt validation letter is one of the most powerful tools available to consumers dealing with collection accounts. It forces collectors to play by the rules, surfaces errors and inaccuracies, and creates a documented record that supports every other step in the credit repair process.

    But validation is just one piece of a larger picture. Comprehensive credit repair involves auditing your reports from all three bureaus, disputing inaccuracies, negotiating with creditors, and building positive credit history over time. It’s a process that benefits from experience, attention to detail, and a thorough understanding of the laws that protect you.

    At credit-repair.com, we help individuals and families take control of their financial future through honest, results-driven credit solutions. Our process starts with a free credit audit — a thorough review of your reports from all three major bureaus to identify inaccuracies, outdated information, and items that may be disputable. We’ll explain what we find, answer your questions, and outline a customized plan based on your goals.

    We operate in full compliance with the Fair Credit Reporting Act and work alongside experienced attorneys to ensure every step is ethical, accurate, and effective. We don’t make empty promises or offer quick fixes. We provide transparency, legal compliance, and measurable progress — so you can see the work being done and the results it produces.

    Ready to see where you stand? Visit to request your free credit audit. There’s no obligation, no pressure, and no cost to get started. You’ll gain a clear picture of your credit situation and a practical plan for moving forward — whether that involves debt validation, credit bureau disputes, or a combination of strategies tailored to your circumstances.

    Your credit health is too important to leave to chance. Let’s take the first step together.

    Disclaimer: This article is for educational purposes only and does not constitute legal advice. The information provided is based on federal law (the FDCPA and FCRA) as of the date of writing. State laws may provide additional protections. Your individual situation may involve factors not addressed in this article. For advice specific to your circumstances, consult a qualified attorney or contact credit-repair.com for a free consultation.

  • How Being an Authorized User Affects Your Credit Score

    How Being an Authorized User Affects Your Credit Score

    If you’ve ever been added to someone else’s credit card — maybe a parent pulled you onto their oldest card to help you start building credit, or a spouse added you for convenience — you’ve been an authorized user. It’s one of the oldest and most misunderstood tools in the credit-building playbook. Done well, it can meaningfully strengthen a thin credit file. Done carelessly, it can drag down your score or saddle someone you love with debt they didn’t expect to be responsible for.

    This guide breaks down what actually happens to your credit score when you become an authorized user, which cards report that history, how the scoring models treat it differently, the real risks on both sides of the relationship, and how to add or remove an authorized user the right way. We’ll also be honest about where this strategy stops working — including the murky world of paid “tradelines” — so you can make a clear-eyed decision.

    What Is an Authorized User?

    An authorized user (often abbreviated AU) is someone who is permitted to use another person’s credit card account but is not legally responsible for paying the debt. The primary cardholder — the person who opened the account and signed the credit agreement — remains fully on the hook for every charge made on the card, including charges made by the authorized user.

    Here’s what being an authorized user does and does not give you:

    • You can make purchases with a card issued in your name on the primary account.
    • You can build credit history — if the card issuer reports authorized user activity to the credit bureaus.
    • You cannot be held legally responsible for the balance.
    • You cannot change the account terms, request credit limit increases, or close the account.
    • You cannot remove the primary cardholder or other authorized users.

    This is a one-way street of permission and liability. The primary cardholder extends a privilege and bears all the legal risk. You, as the authorized user, get the convenience of using the card and — critically — the potential benefit of the account’s history landing on your credit report.

    The arrangement is common between family members: a parent adds a teenager or young adult child to a long-standing card; a spouse adds a partner who is rebuilding credit after a divorce or bankruptcy; sometimes a trusted friend sponsors someone working to recover from past credit mistakes. It is one of the few ways a person with no credit history at all can begin to establish one without opening their own account and risking a hard inquiry or a denial.

    Why the strategy exists at all

    Credit scoring models reward two things above almost everything else: a long history of on-time payments and low credit utilization. For someone with a thin file — a young adult, a recent immigrant, someone who has avoided credit for years — those two ingredients are exactly what they lack. You can’t build payment history without an account, and you can’t get an account without some history. Authorized user status is the most common workaround: it lets you “inherit” the positive history of an established account without having to qualify for it yourself.

    This is why the strategy is sometimes called piggybacking — you ride on the back of someone else’s good credit. When it’s done between family members with honest intentions, it’s a legitimate and widely recommended credit-building tool. When it’s commercialized and sold to strangers (more on that below), it enters a gray area that the credit bureaus and scoring models have spent years trying to police.


    Authorized User vs. Co-Signer vs. Joint Account Holder

    People often use these three terms interchangeably, but they are legally and financially distinct — and the differences matter a lot for your credit and your liability.

    Authorized user

    As described above, an authorized user has no legal responsibility for the debt. Your name appears on a card tied to the primary account, and the account may show up on your credit report, but the creditor cannot come after you for the balance. If the primary cardholder stops paying, your credit may suffer (if the account is reporting on your file), but you won’t be sued or sent to collections for that debt.

    Co-signer

    A co-signer is someone who signs the credit agreement alongside the primary borrower and agrees to be fully responsible for the debt if the primary borrower fails to pay. Co-signers are common on loans for young borrowers, people with limited credit, or people rebuilding credit — auto loans, private student loans, and sometimes credit cards.

    The key difference from an authorized user: a co-signer is legally on the hook. If the primary borrower defaults, the lender can pursue the co-signer for the full balance, report the default on the co-signer’s credit, and take the co-signer to court. The loan appears on both parties’ credit reports from the start, and both are equally exposed to the consequences of missed payments.

    Joint account holder

    A joint account holder (or joint applicant) co-owns the account with equal rights and equal responsibility. Both parties applied for the account together, both can use it, both can make changes to it, and both are fully liable for the balance. Joint accounts are more common on credit cards from credit unions and some smaller issuers; the major national banks have largely moved away from offering them.

    Feature Authorized User Co-Signer Joint Account Holder
    Can use the card Yes No (usually) Yes
    Legally responsible for debt No Yes (if primary defaults) Yes (always)
    Account reports on their credit Sometimes (issuer-dependent) Yes Yes
    Can request changes to account No No Yes
    Can close the account No No Yes (usually)
    Risk to their credit if payments are late Possible (if reporting) Yes Yes
    Risk of being sued for the debt No Yes Yes

    The practical takeaway: if someone asks you to “help them build credit” and you’re trying to decide which role to take, understand what you’re signing up for. Being an authorized user is low-risk for the person being added. Co-signing or opening a joint account is high-risk for the person doing the helping — you’re putting your own credit and your own assets on the line.

    How Being an Authorized User Affects Your Credit

    When everything lines up correctly, being an authorized user can help your credit score in several specific ways. But “when everything lines up correctly” is doing a lot of work in that sentence — so let’s unpack what actually happens under the hood.

    The mechanism: account history lands on your file

    When you’re added as an authorized user to a credit card, the card issuer has the option to report the account to the three major credit bureaus — Equifax, Experian, and TransUnion — under your name as well as the primary cardholder’s name. If the issuer does report it, the entire history of that account (not just the period after you were added) typically appears on your credit report as if you had been associated with the account all along.

    That means if the primary cardholder opened the card ten years ago, has never missed a payment, and keeps the balance low, your credit report may suddenly show a ten-year-old account in perfect standing — even if you were added last week and have never made a single charge.

    This matters because credit scoring models weight several factors that this account can influence:

    • Payment history (the single biggest factor in most scoring models, roughly 35% under FICO 8). An account with years of on-time payments boosts this category.
    • Length of credit history (about 15% under FICO 8). An old account raises your average age of accounts, which is one of the hardest metrics to improve quickly on your own.
    • Credit utilization (about 30% under FICO 8). A card with a high credit limit and a low balance improves your overall utilization ratio.
    • Credit mix (about 10% under FICO 8). An additional revolving account can modestly help if your file is thin on revolving credit.

    What shows up on your report

    When an authorized user account reports on your credit file, it typically displays:

    • The account type (revolving credit card)
    • The date opened (the original opening date, not the date you were added)
    • The credit limit and current balance
    • The payment history for the life of the account
    • Your relationship to the account (authorized user)
    • The account status (open, current, etc.)

    The reporting relationship is usually clearly marked as “authorized user,” which is important because it tells anyone reading the report (including scoring models) that you are not the primary account holder.

    When it helps most

    Authorized user status helps most for people with:

    • A thin credit file — few or no open accounts, short or nonexistent credit history
    • No credit score at all — a completely “unscorable” file because there isn’t enough data
    • A damaged score being rebuilt — where adding a clean, old positive account can help offset past negatives
    • Limited revolving credit — where adding one more healthy revolving account improves utilization and credit mix

    For someone who already has a thick file, multiple established cards, and a strong score (say, 760+), adding an authorized user account typically produces a much smaller — sometimes imperceptible — change. The marginal value of one more good account diminishes as your file gets richer.

    When it does not help

    Being an authorized user does not help your credit when:

    • The issuer does not report authorized user accounts to the bureaus (see the next section).
    • The primary account has late payments, high utilization, or other negative marks — those can hurt you, not help you.
    • You already have stronger accounts of your own and the new AU account doesn’t add anything.
    • The scoring model being used to evaluate you strips out or downweights authorized user accounts (more on this below).


    The Catch: Not Every Issuer Reports Authorized Users

    Here’s the part that trips people up: not all credit card issuers report authorized user accounts to all three credit bureaus. If the issuer doesn’t report the AU relationship, then as far as your credit report is concerned, being an authorized user changes nothing. You can use the card, but it won’t help your credit at all.

    Which issuers report, and to whom?

    Reporting practices vary by issuer and can change over time. As a general rule:

    • Most major national issuers (American Express, Bank of America, Capital One, Chase, Citi, Discover, Wells Fargo, and others) do report authorized users to all three bureaus — but there are caveats.
    • Some issuers require the authorized user to have a Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN) on file before they’ll report. Without one, the account may not land on the AU’s credit file.
    • A few issuers report to only one or two bureaus rather than all three.
    • Store cards and co-branded cards sometimes have different reporting practices than the issuer’s general-purpose cards.

    Because these practices shift, the most reliable approach is to call the issuer directly and ask: “Do you report authorized users to all three credit bureaus — Equifax, Experian, and TransUnion? Do you require a Social Security Number for the authorized user to be reported?” Get the answer in writing if you can (some issuers will note it in chat transcripts), and confirm before you rely on the arrangement for credit-building.

    The scoring model wrinkle

    Even when the issuer does report the AU account, the scoring model that eventually evaluates your credit file has to actually consider it. The two major scoring model families handle authorized users differently:

    FICO 8 and later — FICO has stated that its models are designed to prevent “abuse” of authorized user status, a response to the paid tradeline industry (more on that below). In practice, FICO 8 does still consider authorized user accounts for most consumers, but it applies logic meant to isolate suspicious patterns — for example, a sudden spike in newly added AU accounts on a single primary card may be treated differently than a long-standing family arrangement. For ordinary consumers being added to a family member’s card, FICO 8 generally counts the AU history.

    VantageScore 3.0 and 4.0 — VantageScore has historically taken a more skeptical view of authorized user accounts. Earlier versions of VantageScore stripped out AU accounts entirely in some cases. VantageScore 3.0 and 4.0 do consider authorized user tradelines, but the models have been tuned to reduce the weight of AU-only history relative to primary accounts. If a lender pulls a VantageScore to evaluate you, the AU account may help less than it would under FICO 8.

    FICO 9, FICO 10, and FICO 10T — These newer models continue to consider authorized user accounts but include refinements to the abuse-detection logic. FICO 10T, which uses trended data (looking at your balances over time rather than a single snapshot), may weight the primary cardholder’s utilization patterns differently when they appear on your file as an AU.

    Industry-specific scores — Auto-enhanced and bankcard-enhanced FICO scores may treat AU accounts somewhat differently from the base scores used for most general lending decisions.

    The practical implication: the same authorized user account can help your score a lot under one model and barely move it under another. Since you don’t control which model a lender uses, the best you can do is make sure the account is reporting to all three bureaus and is in good standing — then let the models do what they do.

    What you should verify

    Before you count on authorized user status to build credit, confirm three things:

    • The issuer reports AU accounts to all three bureaus. Call and ask.
    • The issuer has the AU’s identifying information (SSN or ITIN, date of birth, legal name) so the bureaus can match the account to the AU’s file.
    • The account is in good standing — no late payments, low utilization, not in dispute or hardship status.

    If any of those three are missing, the strategy may quietly do nothing — or worse, do something harmful.

    How Much Does It Actually Help?

    Let’s be honest about the upside, because there’s a lot of hype online that suggests becoming an authorized user is a magic credit-score boost. It isn’t. It’s a useful tool in the right circumstances, and a near-irrelevant one in the wrong circumstances.

    For a thin or new credit file: meaningful

    If you have no credit history at all — no cards, no loans, no score — being added as an authorized user to a single old, clean, low-utilization account can be enough to generate a FICO score where none existed before. We’ve seen cases where a previously “unscorable” consumer becomes scorable within one or two billing cycles of being added to the right card.

    For someone with one or two young accounts and a short history, adding a ten-year-old AU account can raise their average age of accounts significantly, which can nudge the score up by a meaningful number of points — sometimes 20 to 50 points depending on the rest of the file. This is the sweet spot for the strategy.

    For a damaged file being rebuilt: modest and conditional

    If you have negative marks (late payments, collections, charge-offs), a positive AU account can help, but it won’t erase the damage. Payment history dominates the scoring models, and a single clean AU account can’t outweigh a recent 90-day late payment or an active collection. The AU account helps by adding positive history and improving utilization, which can support gradual recovery — but the timeline is driven by when the negative items age off your report (typically seven years for most late payments and collections).

    For an established, strong file: minimal

    If you already have several cards in good standing, a long average age of accounts, and a score in the mid-700s or above, adding one more authorized user account will usually produce a change so small it’s within the normal month-to-month fluctuation of your score. There’s no harm in it, but there’s also little reason to expect a meaningful bump.

    For someone with no credit accounts but a long AU history: model-dependent

    Some people have only authorized user accounts on their file — no primary accounts of their own. Whether this produces a usable score depends on the model. FICO 8 can generate a score from AU-only history in some cases, but the score may be weaker and less predictive than one built on primary accounts. VantageScore may handle AU-only files differently. Lenders that manually review the report will see that the history is all “authorized user” and may discount it.

    The honest summary

    • Best case (thin file, great primary card): can take you from no score to a solid score, or from a limited score to a meaningfully better one.
    • Typical case (average file, decent primary card): a modest bump, maybe 10–30 points.
    • Worst case (thick file, or a primary card with problems): little to no help, or actual harm.

    No one can guarantee a specific point increase, and you should be skeptical of anyone — including a credit repair company — who promises one. The outcome depends on the totality of your credit file, the specific account you’re attached to, and the scoring model the lender uses.

    Choosing the Right Primary Cardholder

    If you’re the one being added, the quality of the primary account matters more than almost anything else. A great authorized user arrangement can help you; a bad one can hurt you. Here’s what to look for in the account you’re attaching yourself to.

    1. Long account history

    Older is better. An account opened 10, 15, or 20 years ago contributes a long payment history and raises your average age of accounts. A brand-new account — even a perfectly managed one — adds almost nothing to your length of history and may actually lower your average age briefly. If you have a choice between being added to a card your parent opened in 2008 and a card your sibling opened last year, pick the 2008 card.

    2. Spotless payment history

    This is non-negotiable. A single 30-day late payment on the primary account can show up on your credit report as an authorized user and damage your score. Look for an account that has never been late — not once, not for a month, not during a hardship. If the primary cardholder has had any payment issues on that card, even years ago, consider a different account.

    3. Low credit utilization

    Utilization — the ratio of the current balance to the credit limit — is one of the most powerful levers in credit scoring. The primary card should ideally report a balance below 10% of its limit, and certainly below 30%. A card with a $10,000 limit that routinely reports a $4,000 balance (40% utilization) can hurt your score, not help it, even if it’s never been late.

    Be aware that utilization is typically reported based on the statement balance — the balance on the day the statement closes — not the balance you carry month to month. A cardholder who pays in full every month but has high statement balances can still report high utilization. Ask the primary cardholder about their typical statement balance relative to the limit.

    4. High credit limit (for utilization spillover)

    A card with a high limit helps your overall utilization across all your accounts. If you have a $500 limit card of your own with a $200 balance (40% utilization on that card), and you’re added to a $20,000 limit AU card with a $500 balance, your total utilization drops from 40% to about 3.4% — a significant improvement.

    5. Stability

    Avoid accounts that are in active hardship programs, frequently disputed, or at risk of closure. An account that gets closed while you’re an authorized user loses its ongoing contribution to your file (though the history may remain for up to 10 years on FICO scores). An account that gets sent to collections is far worse.

    6. An issuer that reports AUs

    As discussed above, confirm the issuer reports authorized users to all three bureaus. There’s no point in being added to a perfect account if it never shows up on your credit report.

    Quick checklist for the ideal AU card

    • Opened at least 5–10 years ago (older is better)
    • Never a late payment
    • Statement balance usually under 10% of the limit
    • High credit limit
    • Stable, active, not at risk of closure
    • Issuer reports AUs to all three bureaus

    If the primary cardholder ticks all those boxes, you’ve found a strong candidate. If they tick only some, weigh the trade-offs — and remember that a single late payment or sustained high utilization can flip a “helpful” AU card into a “harmful” one overnight.

    How being an authorized user affects your credit score

    Risks to the Authorized User

    Being added to someone else’s card is not risk-free for you, even though you’re not legally responsible for the debt. The risks are all about what lands on your credit report.

    1. Their late payments become your late payments

    If the primary cardholder misses a payment on the account — 30 days late, 60 days late, 90 days late — that late payment can be reported on your credit file as an authorized user. A 90-day late mark is one of the most damaging single items that can appear on a credit report, and it can tank your score by 100 points or more depending on your starting point. You didn’t make the late payment. You may not have even known about it. But it shows up on your report nonetheless.

    This is the single biggest risk of being an authorized user, and it’s why you should only be added to an account you trust completely — one where the primary cardholder has a long, clean payment record and the financial discipline to keep it that way.

    2. High utilization on the card hurts your score

    Even if the primary cardholder never misses a payment, if they run the balance up near the limit, your utilization — as reflected on your credit report — goes up with it. A sudden spike in utilization (say, from 10% to 85% because of a large purchase or an emergency expense) can cause an immediate score drop, sometimes 30–60 points, until the balance is paid down.

    3. Account closure removes the benefit

    If the primary cardholder closes the account, or if the issuer closes it (for inactivity, default, fraud, or any other reason), the account may stop contributing to your active credit picture. The closed account’s history may remain on your report for up to 10 years (under FICO scoring), which softens the blow — but your “open revolving accounts” count drops, and if this was your oldest or only account, the impact can be noticeable.

    4. Disputed or charged-off accounts are catastrophic

    If the account goes into default, gets charged off, or is sent to collections, those severe negative marks can appear on your credit report as an authorized user. A charge-off is nearly as damaging as a 90-day late payment and stays on your report for seven years.

    5. You have no control

    As an authorized user, you cannot log in and pay the bill (unless the primary cardholder gives you access), you cannot request a credit limit increase, you cannot dispute inaccuracies on the account as the primary party, and you cannot close the account. You are entirely dependent on the primary cardholder to keep the account in good standing. If your relationship with the primary cardholder deteriorates — a divorce, a family estrangement, a falling-out — you may find it difficult to get yourself removed quickly.

    How to protect yourself

    • Only join accounts you trust. The primary cardholder should have a years-long clean payment record.
    • Monitor your credit. Pull your reports from all three bureaus at AnnualCreditReport.com at least once a year, and consider a free credit monitoring service so you’ll see changes quickly.
    • Ask to be removed immediately if the account goes sideways. The faster you’re removed, the faster the account stops updating on your file. (More on removal below.)
    • Remember that removal stops future reporting but doesn’t erase past negatives. If a late payment already hit your file as an AU, removing yourself prevents new ones but doesn’t delete the old one. You may need to dispute it (with help from a credit repair professional if necessary) on the basis that you were not the responsible party.

    Risks to the Primary Cardholder

    The risks run the other direction too — and they’re more severe, because the primary cardholder is the one with legal liability.

    1. You are responsible for every charge the AU makes

    This is the core risk and the one most often underestimated. If the authorized user runs up $15,000 in charges on your card, you owe the $15,000. The card issuer will come after you, not the AU, for payment. If you don’t pay, your credit is the one that gets destroyed — not theirs. You could sue the AU in small claims court to recover the money, but that’s a long, uncertain, relationship-destroying process.

    This is why the most common advice is: if you add an authorized user, don’t give them the physical card. Many issuers let you add an AU for credit-reporting purposes without ever issuing a card in their name. The AU gets the credit-building benefit, and you get zero risk of them making charges you didn’t authorize.

    2. AU charges can push up your utilization

    Even if the AU is responsible and only uses the card for agreed-upon expenses, their charges still count toward your balance and your utilization. If you keep a tight utilization strategy (paying down balances before the statement closes to report a low number), AU charges can disrupt that if you’re not coordinating closely.

    3. Your credit is exposed if you add the wrong person

    If the AU has a history of financial irresponsibility — and you give them a card — you’re handing a loaded financial instrument to someone who may not use it wisely. The AU’s past credit problems don’t directly affect your credit (their negatives don’t migrate to your file), but their future behavior on your card absolutely does.

    4. Relationship risk

    Mixing family or friendship with shared credit can strain even strong relationships. Disagreements about what was “agreed,” what charges were authorized, and who was supposed to pay can turn into lasting rifts. Set clear expectations in advance — ideally in writing — about whether the AU will use the card, for what, and how repayment will work.

    How to protect yourself as the primary cardholder

    • Add the AU for credit-building only — don’t issue a card. This is the safest arrangement and is available from most major issuers.
    • If you do issue a card, set spending limits. Some issuers let you set a per-card spending limit for authorized users. Use it.
    • Monitor the account. Set up alerts for every transaction. Review the statement every month.
    • Have a clear agreement. If the AU will use the card, agree in advance on what’s allowed and how and when they’ll reimburse you. Put it in writing.
    • Be ready to remove the AU and destroy the card. If the arrangement isn’t working, act quickly. You can remove an AU at any time, and the sooner you do, the sooner you stop the bleeding.

    How to Add or Remove an Authorized User

    The mechanics of adding and removing an authorized user are straightforward, but there are some details worth getting right.

    Adding an authorized user

    • Log in to your online account or call the issuer’s customer service line. Most issuers have an “Add an Authorized User” option in the account management section.
    • Provide the AU’s information. You’ll typically need their full legal name, date of birth, and Social Security Number (or ITIN). Some issuers allow you to add an AU without an SSN, but as discussed, providing one improves the likelihood that the account will report on the AU’s credit file.
    • Decide whether to issue a card. You can usually choose to have a physical card mailed in the AU’s name, or to add them without issuing a card. For pure credit-building purposes, adding without a card is the safest option.
    • Set spending limits if available. If the issuer supports per-AU spending limits and you’re issuing a card, set one that reflects your comfort level.
    • Confirm reporting. Within one to two billing cycles, check the AU’s credit report (via AnnualCreditReport.com or a monitoring service) to confirm the account is appearing on their file at all three bureaus. If it isn’t, call the issuer to verify their reporting settings.

    Removing an authorized user

    Removing an AU is just as easy — sometimes easier:

    • Log in or call. Most issuers let you remove an AU online; some require a phone call.
    • Request removal. You’ll need the AU’s name. Some issuers may ask for a reason, but you’re not obligated to provide a detailed one.
    • Destroy the AU’s card if one was issued. Cutting it up is the simplest approach. The issuer may also deactivate the card on their end.
    • Confirm the removal stops reporting. After removal, the account should stop updating on the AU’s credit file. The historical entries (positive or negative) that already reported while the AU was on the account generally remain on the AU’s report — removal doesn’t retroactively erase them.

    If you’re the AU and want to be removed

    As the authorized user, you generally cannot remove yourself from an account through the issuer — only the primary cardholder can remove you. However, you have another option: you can dispute the account directly with the credit bureaus. File a dispute with Equifax, Experian, and TransUnion stating that you are an authorized user, not a responsible party, and that you want the account removed from your credit report. The bureaus will typically remove authorized user accounts at the consumer’s request, since you have no legal obligation on the account.

    This is a useful escape hatch if the primary cardholder is unresponsive, unreachable, or uncooperative — for example, in a difficult divorce or family estrangement.

    A note on timing

    If the account has already damaged your credit as an AU (late payments, high utilization), removing yourself or being removed stops future reporting but doesn’t fix the past. For that, you may need to dispute the negative items with the bureaus, arguing that as an authorized user you were not the responsible party. This is one of the situations where working with a reputable, FCRA-compliant credit repair firm can help — the dispute process has specific legal requirements, and doing it wrong can waste time or even backfire.


    Does Being an Authorized User Still Work in 2026?

    Yes — with caveats. Authorized user status remains a legitimate and widely used credit-building tool in 2026. The major issuers still report AU accounts (though always confirm with your specific issuer), FICO and VantageScore models still consider them, and lenders still recognize AU history on consumer credit reports.

    But the landscape has evolved in ways worth understanding:

    Stricter abuse detection in scoring models

    FICO has been refining its authorized user handling since FICO 8, which introduced logic to detect and limit “piggybacking” abuse — specifically, the practice of selling authorized user slots on strong accounts to strangers. FICO 10 and FICO 10T continue this trend. The models are designed to let legitimate family AU relationships count while limiting the impact of suspicious, commercially motivated AU additions. For ordinary consumers being added to a family member’s long-held card, the models generally still give full credit. But the models are less generous with patterns that look like tradeline brokering.

    Trended data changes the utilization picture

    FICO 10T, which has been gaining adoption among lenders, uses trended data — it looks at your balance and payment patterns over time, not just a single snapshot. This means that if the primary cardholder has a history of running up high balances and paying them down (even if they’re never late), that pattern may be visible to the model and could reduce the benefit of the AU account. Under trended-data scoring, the ideal AU card is one with consistently low balances, not one that swings between high and zero.

    Bureau-level AU handling

    The credit bureaus themselves have tightened some of their processes around AU reporting over the years, partly in response to regulatory scrutiny and partly to combat tradeline brokering. This has not stopped legitimate family AU reporting, but it has made it slightly more important to ensure the AU’s identifying information is accurate and complete when they’re added.

    Lender discretion

    Even when an AU account helps your credit score, some lenders — particularly mortgage lenders — may look at your credit report manually and treat AU accounts differently. A mortgage underwriter might ask you to provide a letter explaining your relationship to the primary cardholder, or might discount AU accounts when calculating your effective credit history. This doesn’t make AU status useless, but it means that for major lending decisions (like a home purchase), the AU benefit may be less than your credit score alone suggests.

    The bottom line for 2026

    Authorized user status still works as a credit-building tool. It is most effective for thin files, still useful for average files, and least useful for thick files or for scoring models that downweight AU history. It is not a shortcut to an 800 credit score, and anyone who tells you it is — is selling you something. Use it as one tool in a broader credit-building strategy that includes opening and responsibly managing your own accounts over time.

    Piggybacking and Paid Tradelines: The Scammy Side

    This is the part of the authorized user conversation that gets shady, and we want to be direct about it because we’ve seen too many clients get burned.

    What is “piggybacking” in the commercial sense?

    In its innocent form, “piggybacking” just means being added as an authorized user to a family member’s card to build credit — exactly what we’ve been describing throughout this article. That’s legitimate.

    In its commercial form, “piggybacking” refers to a for-profit industry where brokers sell authorized user slots on strangers’ credit card accounts. The arrangement works like this:

    • A person with a strong, old credit card agrees to sell authorized user slots on their account.
    • A broker connects that cardholder with buyers who want a credit boost.
    • The buyer is added as an authorized user (usually without ever receiving a card).
    • The account’s positive history reports on the buyer’s credit file.
    • After a billing cycle or two, the buyer is removed, and the slot is sold to the next customer.

    Why it’s problematic

    • It may violate the cardholder’s agreement with the issuer. Most issuers prohibit using their cards for commercial arrangements like this. If caught, the cardholder’s account can be closed — which damages both the cardholder and every AU currently on the account.
    • It’s designed to game the credit scoring models. FICO has explicitly built abuse-detection logic to limit the effectiveness of this practice. A sudden burst of AU additions on a single account, especially with no apparent family relationship, can trigger the model to discount or ignore those AU tradelines.
    • The boost is temporary. Because the AU is removed after a short period, the benefit disappears as soon as the account stops reporting — unless the buyer is simultaneously building their own primary credit, the score will drift back down.
    • It’s expensive. Brokers typically charge hundreds to thousands of dollars per tradeline, for a benefit that may last only a billing cycle or two.
    • There are scams. Some tradeline brokers take payment and never add the buyer to any account. Others use stolen or synthetic identities to create the “primary” accounts being sold — which means the AU history on your report is tied to a fraudulent account that can collapse at any time, potentially dragging your score down or flagging you for fraud.

    What we recommend

    Don’t buy tradelines. If you want the benefit of authorized user status, do it the legitimate way:

    • Ask a trusted family member with a strong, old, clean credit card to add you as an authorized user. Most people are surprised at how willing a parent or spouse is to help when they understand it doesn’t put them at risk (as long as they don’t issue you a card).
    • Make sure the issuer reports AU accounts.
    • In parallel, start building your own primary credit — a secured card, a credit-builder loan, a student card, or a starter card from a bank you already have a relationship with. Your own accounts are the foundation; the AU account is a supplement, not a substitute.

    If you’ve already bought tradelines and you’re worried about what’s on your credit report, pull your reports from all three bureaus and review them carefully. If you see accounts you don’t recognize, or accounts that look like they may be tied to a broker, consider working with an FCRA-compliant credit repair firm to dispute and remove them. Cleaning up the aftermath of a tradeline scheme can take time, but it’s absolutely possible.

    A clear warning

    Be especially skeptical of any company that guarantees a specific score increase from adding tradelines, that requires large upfront payments, or that pressures you to act quickly. These are classic signs of a credit repair scam. Under the federal Credit Repair Organizations Act (CROA), a legitimate credit repair company cannot charge you in advance for work that hasn’t been done, and cannot make guaranteed claims about outcomes.


    Common Mistakes to Avoid

    Over years of working with clients on credit repair and credit building, we see the same handful of authorized user mistakes over and over. Here are the most common — and how to avoid them.

    1. Being added to the wrong account

    Not all accounts are created equal. Being added to a card that’s two years old, carries a 60% utilization, and had a late payment last year will hurt you, not help you. Before you’re added, evaluate the account against the checklist in the “Choosing the Right Primary Cardholder” section above.

    2. Not confirming the issuer reports AUs

    This is the most common reason the strategy “doesn’t work.” You get added, you wait, you check your credit, and nothing has changed. Nine times out of ten, the issuer doesn’t report authorized users (or doesn’t report without an SSN on file). Confirm before you commit.

    3. Being added to too many accounts at once

    Adding multiple AU accounts in a short window can look suspicious to the scoring models — especially if the accounts have no apparent relationship to you. If you’re going to use the strategy, add one strong account and let it season. Adding three or four at once is more likely to trigger abuse-detection logic than to triple your benefit.

    4. Issuing a card when you don’t need to

    If the goal is credit building, the primary cardholder doesn’t need to give you a physical card. Not issuing a card eliminates essentially all the risk to the primary cardholder while preserving the credit-reporting benefit for you. If you do need a card for convenience (a spouse, a business partner), set spending limits and clear expectations.

    5. Ignoring the account after you’re added

    Credit reports aren’t set-and-forget. Once you’re an AU, the account affects your credit every month it reports. If the primary cardholder runs up the balance, misses a payment, or closes the account, your score can move — and not in a good direction. Monitor your credit and stay in communication with the primary cardholder.

    6. Staying on an account that’s gone bad

    If the primary cardholder starts missing payments or maxing out the card, remove yourself (by dispute with the bureaus if necessary) as soon as possible. Every month the account reports negatively is another month of damage. Don’t wait and hope it gets better.

    7. Relying on AU status alone

    Authorized user history is a supplement, not a foundation. If your entire credit file is AU accounts, your score is fragile — it depends entirely on someone else’s behavior, and lenders may discount it. Build your own primary accounts alongside the AU arrangement so that, over time, your credit stands on its own.

    8. Buying tradelines

    As discussed above, this is expensive, temporary, potentially fraudulent, and increasingly ineffective as scoring models get better at detecting it. Use the legitimate family version instead.

    9. Forgetting to remove an AU after a relationship ends

    If you go through a divorce, a breakup, or a family estrangement and you were the primary cardholder, remove the AU promptly. If you were the AU, get yourself removed (by dispute if necessary). Lingering AU connections after a relationship ends can lead to surprises — sometimes years later — when the primary cardholder’s behavior on the account shifts.

    10. Expecting a guaranteed point increase

    No legitimate credit professional can guarantee a specific score increase from an authorized user arrangement. The outcome depends on your full file, the specific account, and the scoring model. If someone promises you “50 points in 30 days” from becoming an AU, walk away.

    Frequently Asked Questions

    1. Does being an authorized user help your credit score?

    It can, under the right conditions. If the card issuer reports authorized user accounts to the credit bureaus, and the primary account is in good standing (long history, no late payments, low utilization), the account’s positive history can appear on your credit report and improve your score. It helps most for people with thin or no credit history, and less for people who already have strong, established files. It does not help at all if the issuer doesn’t report AU accounts, or if the primary account has negative marks.

    2. Will my credit be affected if the primary cardholder misses a payment?

    Yes, potentially. If the issuer reports authorized user accounts, a late payment on the primary account can show up on your credit report as an authorized user and damage your score. This is the biggest risk of being an AU. If this happens, you can dispute the late payment with the credit bureaus (arguing that you were not the responsible party) or ask the primary cardholder to remove you from the account to stop future negative reporting.

    3. Can I remove myself as an authorized user?

    You generally can’t remove yourself through the card issuer directly — only the primary cardholder can do that. However, you can file a dispute with each of the three credit bureaus (Equifax, Experian, TransUnion) requesting that the authorized user account be removed from your credit report. Because you have no legal responsibility for the debt, the bureaus will typically honor this request. This is a useful option if the primary cardholder is unavailable or uncooperative.

    4. Do all credit card companies report authorized users to the credit bureaus?

    No. Most major issuers do report authorized users, but practices vary — some issuers require a Social Security Number for the AU before reporting, some report to only one or two bureaus, and some don’t report AU accounts at all. Before relying on the strategy, call the issuer and ask specifically whether they report authorized users to all three bureaus and what information they require.

    5. Does being an authorized user hurt your credit?

    It can, if the primary account has problems. Late payments, high utilization, charge-offs, or collections on the primary account can appear on your credit report as an AU and lower your score. The strategy only helps when the primary account is in excellent standing. Being added to a problem account is worse than not being added at all.

    6. How long does it take for an authorized user to show up on your credit report?

    If the issuer reports AU accounts, you can usually expect the account to appear on your credit file within one to two billing cycles — typically 30 to 60 days after you’re added. If it hasn’t appeared after 60 days, confirm with the issuer that they’re reporting and that they have your correct identifying information (name, date of birth, SSN or ITIN).

    7. Is buying authorized user tradelines safe or effective?

    We don’t recommend it. Paid tradelines — where brokers sell AU slots on strangers’ credit cards — are expensive, the benefit is temporary, the practice may violate the cardholder’s agreement with the issuer, and the scoring models have built-in logic to detect and limit their effectiveness. Some tradeline operations are outright scams, and some involve fraudulent “primary” accounts that can collapse and damage your credit. The legitimate alternative is being added to a family member’s card, which is free, safe, and recognized by the scoring models.

    8. What’s the difference between an authorized user and a co-signer?

    An authorized user has no legal responsibility for the debt — they can use the card and may build credit from the account’s history, but the creditor cannot pursue them for the balance. A co-signer has full legal responsibility — if the primary borrower defaults, the co-signer can be pursued for the full balance, and the debt appears on the co-signer’s credit report with all the risk that entails. Co-signing is far riskier than adding an authorized user.

    Ready to Take Control of Your Credit?

    Being an authorized user is one useful tool in a broader credit-building strategy — but it’s not the whole strategy, and it works best when it’s part of a clear, compliant plan tailored to your specific situation.

    If your credit report has errors, outdated negative items, or accounts that don’t belong there, those problems can undermine even the best authorized user arrangement. That’s where we come in.

    At credit-repair.com, we help individuals and families across the country take control of their financial future through honest, attorney-backed, FCRA-compliant credit repair. We start with a free credit audit — a thorough review of your reports from all three major bureaus — to identify inaccuracies, disputable negative items, and opportunities to strengthen your file. From there, we build a customized plan tailored to your goals, with transparent pricing and no hidden fees.

    No quick fixes. No empty promises. Just a clear path forward, guided by people who know the system and care about your outcome.

    [Get your free credit audit at credit-repair.com →] (link placeholder to audit signup page)

    Have questions about authorized users, credit building, or anything else on your credit report? We’re here to help you understand your options — no pressure, no obligation, just straightforward answers from a team that’s on your side.