
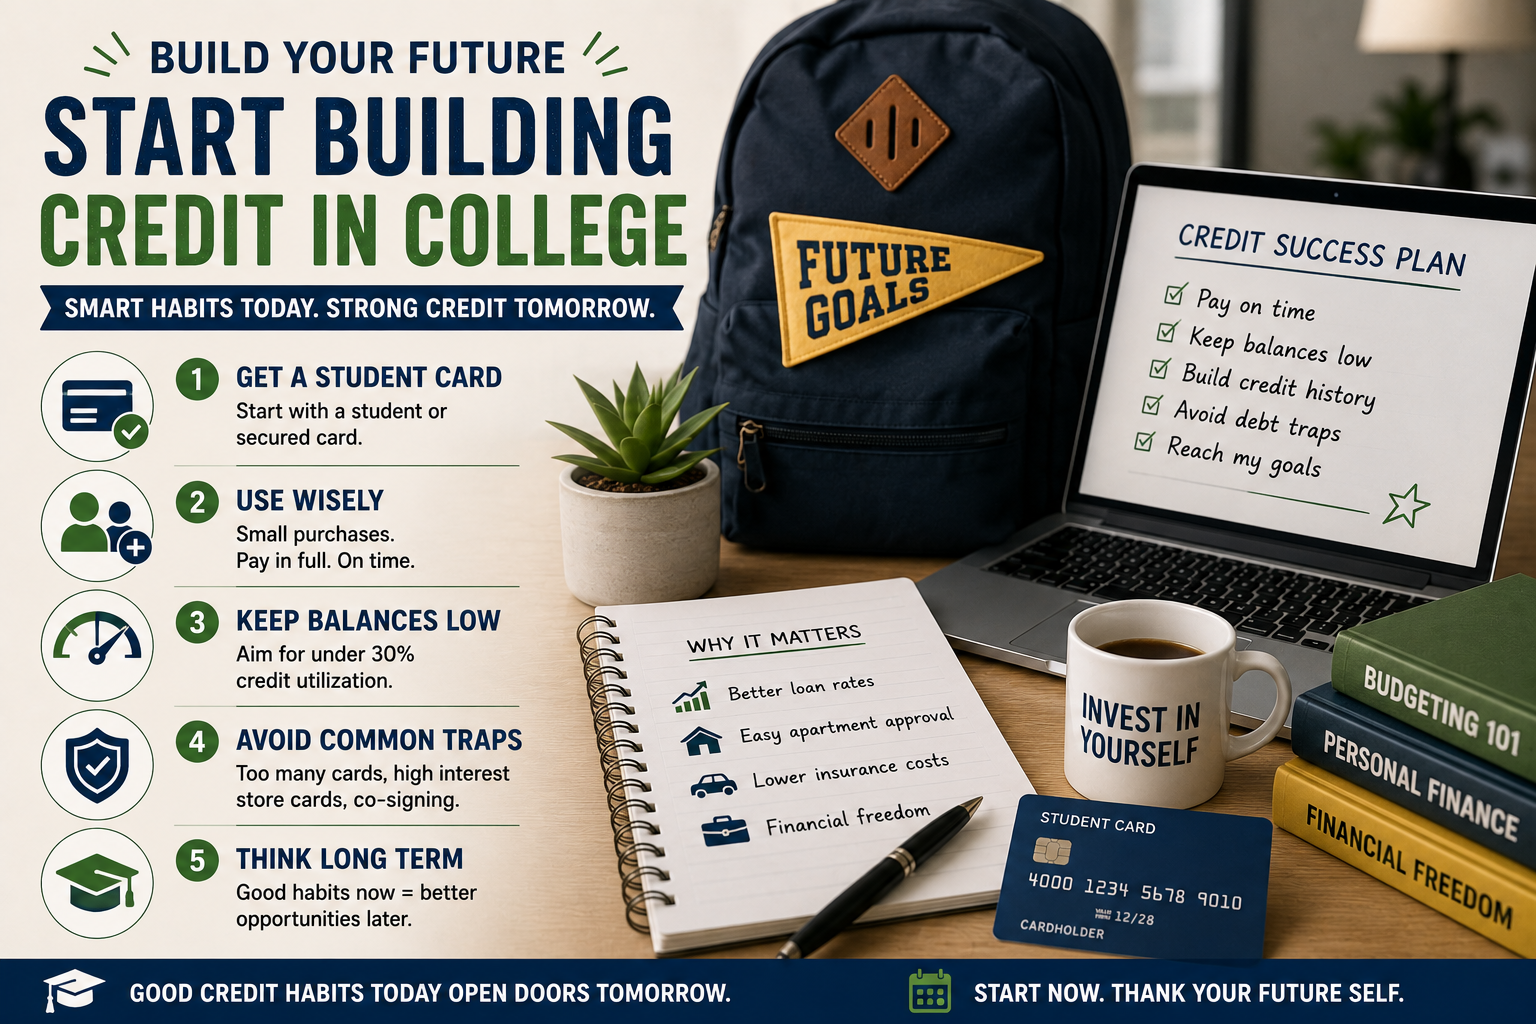
Starting to build credit in college puts you in an unusually good position, even if it doesn’t feel that way — you likely have relatively low financial obligations, time on your side before you need strong credit for a car loan or apartment lease, and (compared to graduating with no credit history at all) a genuine head start if you use these years intentionally. The mistakes that hurt college students financially are usually less about credit mechanics and more about a few specific, avoidable traps. Here’s how to do it right.
Why Starting in College Is a Genuine Advantage
Two of the biggest factors in your credit score — payment history and average account age — both reward time. An account opened at 19 and kept in good standing for years has a real structural advantage over one opened at 25, simply because it’s had longer to season and to establish a track record. Starting now, even modestly, compounds in your favor for years.
Step 1: Get a Student-Specific Credit Card
Many major issuers offer credit cards specifically designed for students with limited or no credit history, generally with:
– Lower credit limits (which is actually helpful for a first card — less room to overspend).
– More lenient approval criteria than standard unsecured cards.
– Sometimes modest rewards or cash-back structured around common student spending categories.
If you can’t qualify for a student card (some still require a minimum income or a co-signer), a secured card is a reliable fallback, requiring a cash deposit as collateral.
Step 2: Consider a Parent Co-Signer or Authorized User Status Carefully
Two different options here, worth distinguishing clearly:
**Co-signer**: you’re the primary account holder, but a parent’s signature helps you qualify, and they share legal responsibility for the debt. This builds credit in your own name from day one, but obligates your co-signer if you miss payments.
**Authorized user**: you’re added to a parent’s existing account, and their account history (potentially years of it) can appear on your credit report. This can be a faster way to establish a longer-looking credit history, but you have no independent control over the account, and if your parent’s usage becomes irresponsible, that reflects on your file too.
If a parent has excellent, long-standing credit, authorized user status can be a genuinely powerful head start — sometimes adding a decade or more of positive account history to a brand-new credit file. If a
parent’s credit is shakier, this can work against you instead, so it’s worth an honest conversation before pursuing it.
Step 3: Use the Card for Small, Predictable, Recurring Purchases
The goal isn’t to “use” the card in a way that demonstrates spending power — it’s to demonstrate reliability. A good pattern:
– Charge one small recurring expense (a streaming subscription, a set grocery budget) to the card each month.
– Pay it off in full before the due date, every time, without exception.
– Avoid using the card for large, unpredictable purchases that could tempt you into carrying a balance you can’t immediately pay off.
Step 4: Never Carry a Balance If You Can Avoid It
This is the single most important habit to establish early, and also the one most likely to be undermined by common (and sometimes actively predatory) advice aimed at students. You do **not** need to carry a balance and pay interest to build credit — this is a persistent myth. Paying your statement balance in full every month:
– Builds the exact same positive payment history as carrying a balance would.
– Costs you nothing in interest.
– Keeps your utilization ratio low, which is actively beneficial to your score, unlike a carried balance which pushes utilization higher.
If you’ve heard advice suggesting you should carry a small balance to “build credit faster,” that’s inaccurate — it’s a myth that mainly benefits card issuers collecting interest, not your credit-building goals.
Step 5: Watch Out for Common Student Credit Traps
**Store credit cards with aggressive marketing**, often pitched at checkout with a first-purchase discount. These frequently carry high interest rates and lower credit limits, and opening several in a short period (chasing the discounts) generates multiple hard inquiries that can drag down a thin, new credit file more noticeably than they would an established one.
**Campus-adjacent predatory lending** — payday-style loans or rent-to-own arrangements marketed near campuses, which generally don’t help build credit at all (many don’t report to bureaus in a positive way) and carry serious cost and risk.
**Co-signing for friends or a significant other.** Being asked to co-sign a lease, car loan, or credit card for someone else in college is common, but it makes you fully liable for their payment behavior on your own credit file — this is worth approaching with real caution, since it’s one of the more common ways college-age credit gets damaged by someone else’s decisions.
Step 6: Keep Student Loans in Mind as Part of Your Credit Picture
If you have student loans, they will eventually become part of your credit report and payment history once repayment begins (or immediately, for loans in active repayment during school). A few things worth understanding:
– **Loans in deferment while you’re enrolled generally don’t require payments yet**, but it’s worth confirming your specific loan terms rather than assuming.
– **Once repayment begins, on-time payments build meaningful positive history**, given the typically long repayment term of student loans, which contributes positively to your average account age over many years.
– **If you’re struggling to make payments after graduation**, addressing this proactively (income-driven repayment plans, deferment/forbearance options, direct communication with your loan servicer) is far better for your credit than letting a payment become late or default, which is a significantly more damaging outcome than a temporarily adjusted payment plan.
Step 7: Don’t Apply for Too Many Products at Once
It’s tempting, especially with frequent student-targeted card offers, to apply for several cards hoping one approves. Resist this — each hard inquiry has a modest negative effect, more noticeable on a thin file, and multiple recent inquiries can itself look like a red flag to future lenders evaluating your file, separate from the individual denials.
What a Strong Graduation-Day Credit Profile Looks Like
If you start early and follow these principles, by graduation you can realistically have:
– 2-4 years of on-time payment history on at least one card.
– Low utilization maintained consistently.
– A credit score often in the “good” range, sometimes higher, well ahead of peers who wait until after graduation to start.
This head start matters concretely — it can mean qualifying for a car loan at a meaningfully better interest rate, an apartment lease without needing a co-signer or larger deposit, or a first post-graduation credit card with genuinely competitive terms rather than another entry-level product.
The Bottom Line
College is one of the best windows to start building credit, precisely because the stakes are relatively low and time is on your side. A student or secured card, used lightly for small recurring purchases and paid off in full every month, combined with caution around co-signing and store card overextension, sets up a credit profile that will meaningfully outperform peers who wait until after graduation — not because of anything complicated, just because payment history and account age both reward starting early and staying consistent.