
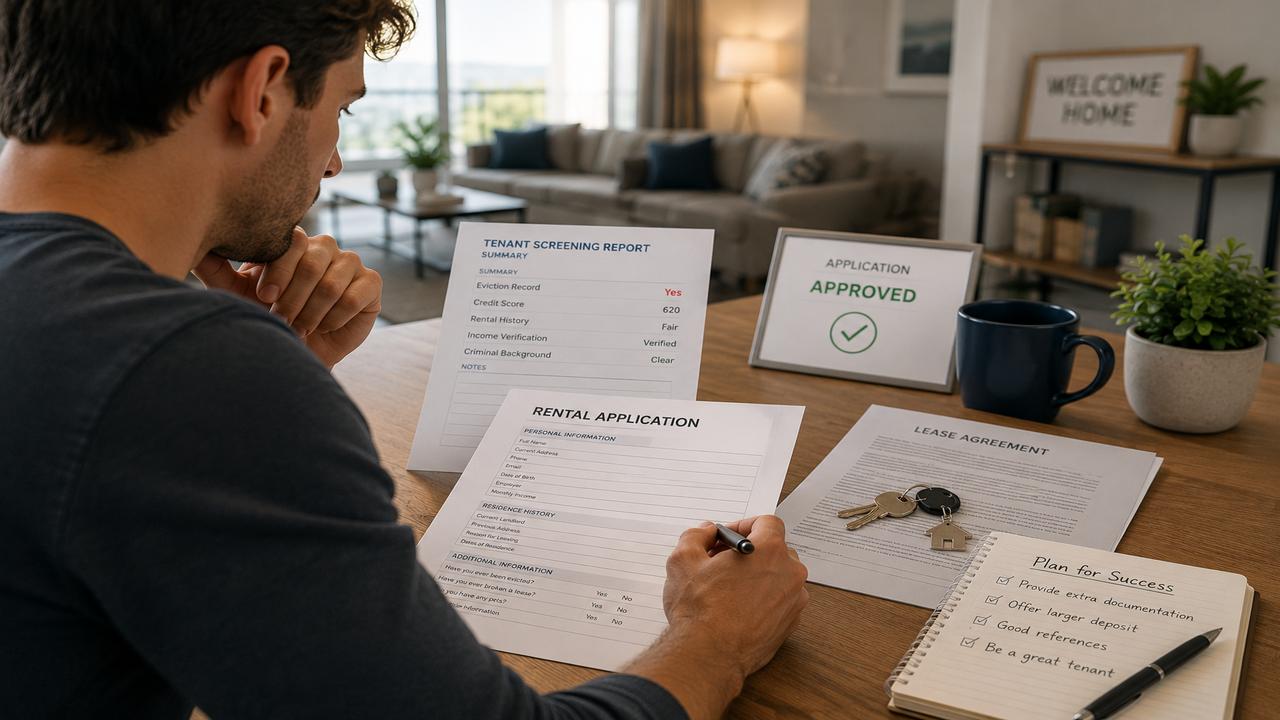
This guide covers how eviction records actually work, how long they stick around, how to challenge inaccurate ones, and the specific tactics that help renters with a real eviction history get approved anyway.
How Eviction Records Actually Work
An eviction, formally called an “unlawful detainer” action in many states, is a court case a landlord files to legally remove a tenant. Because it goes through the court system, it becomes part of the public record, separate from your credit report. This is an important distinction: an eviction filing shows up primarily through tenant screening companies that pull court records, not necessarily through Equifax, Experian, or TransUnion directly — though the debt from an eviction (unpaid rent, court-ordered judgments) can separately end up on your credit report if it’s sent to collections.
This means you can have a clean credit report and still fail a rental background check because of an eviction case, and vice versa. Property managers commonly use specialized tenant-screening services (like RentPrep, TransUnion SmartMove, or various regional court-record aggregators) that search county and state court databases directly for eviction filings, judgments, and sometimes even cases that were filed but later dismissed.
That last point matters enormously: in many states, an eviction filing can appear on a screening report even if you won the case, the landlord withdrew it, or it was settled and dismissed. The mere fact that a case was filed is what many screening services report, regardless of outcome. This is one of the more unfair aspects of the system, and it’s also one of the more fixable ones, which we’ll get to.
How Long an Eviction Stays on Your Record
There’s no single national answer, because eviction reporting isn’t governed the same way credit reporting is under the Fair Credit Reporting Act’s standard seven-year rule for most negative items. In practice:
- Court records of an eviction filing are often public indefinitely, though many tenant-screening companies limit how far back they report, commonly 7 years, sometimes less.
- A judgment (a formal court ruling against you, often for unpaid rent) can appear on tenant-screening reports for up to 7 years in most states, similar to other financial judgments.
- Collections debt stemming from an eviction, like unpaid rent sent to a collection agency, follows the standard credit-report rule and can appear for up to 7 years from the date of the original delinquency.
Some states have passed laws limiting how eviction records can be used or reported, particularly for cases that were dismissed, withdrawn, or resulted in the tenant prevailing. If you’re unsure what applies to your situation, checking your state’s specific tenant-screening and eviction-sealing laws is worth the time, since several states now allow eviction records to be sealed or expunged under certain conditions (often tied to case outcome, time elapsed, or the underlying reason for the eviction).
Step One: Get Your Actual Eviction Record
Before doing anything else, find out exactly what a landlord would see. Request your tenant screening report from a major screening company (many are required to provide this to you for free or a small fee under the FCRA, since tenant screening reports are considered consumer reports), or pull the court record directly from the county courthouse where the case was filed.
You want to know:
- The exact case outcome (dismissed, judgment for the landlord, judgment for you, settled)
- The amount, if any, that was awarded
- Whether it’s been paid, and if so, when
- Which screening companies are actually reporting it
Many people are surprised to find their eviction case was actually dismissed or resolved in their favor, yet a screening company is still reporting the filing itself as if it were a finding against them. This is exactly the kind of error worth disputing.
Step Two: Dispute Anything Inaccurate
If your screening report shows incorrect information — the wrong outcome, a debt that’s already been paid, or a case that doesn’t actually belong to you (which does happen, especially with common names) — you have the right to dispute it directly with the tenant screening company, the same way you’d dispute an error on a credit report. Under the FCRA, they’re required to investigate and correct verified inaccuracies.
This is also where sealing or expungement can help if your state allows it. If a case was dismissed, resulted in your favor, or is old enough to qualify, some states let you petition the court to seal the record, after which reputable screening companies should stop reporting it. This process varies significantly by state and sometimes by county, so check your local courthouse or a local tenant’s rights organization for the specific procedure.
Step Three: Pay Off Any Outstanding Balance
If the eviction resulted in a real debt you actually owe — back rent, court costs, damages — paying it off, even years later, does two things. First, it removes any risk of a fresh collections action or wage garnishment down the line. Second, it gives you something concrete to show future landlords: proof that even though something went wrong once, you ultimately made it right. A “paid” eviction judgment reads very differently to a landlord than an outstanding one.
If you can’t pay the full balance, contact the original landlord or the current debt holder (if it’s been sold to a collector) to negotiate a payment plan or a reduced lump-sum settlement. Get any agreement in writing before paying, and specifically request written confirmation once the balance is paid or settled.
Step Four: Build a Strong Rental Application Anyway
Even with an eviction in your past, a strong overall application changes how a landlord weighs that one red flag. A few things to prepare before you start applying:
A written explanation letter.
A short, honest, non-defensive explanation of what happened and what’s different now goes further than most renters expect. Landlords who deny eviction-record applicants automatically are often doing so out of a lack of context, not because every eviction is treated as unforgivable. If the eviction happened because of a job loss, a medical emergency, or a temporary hardship that has since resolved, say so plainly. Avoid blaming the previous landlord in detail, even if you feel justified — the goal is to demonstrate stability now, not relitigate the past.
Proof of current income and stability.
Pay stubs, an offer letter, or bank statements showing consistent income well above the rent (commonly landlords look for income at least three times the monthly rent) help offset the risk a landlord associates with the eviction.
References that speak to reliability.
A letter from a current or more recent landlord, even a shorter tenancy, showing on-time payment and good standing, can meaningfully counterbalance an older eviction. Employer references confirming stable employment help too.
A larger security deposit or advance rent, offered proactively.
Some landlords are legally capped on how much deposit they can require upfront, but where allowed, voluntarily offering additional deposit or even a few months of rent paid in advance can turn a “no” into a “yes” by directly addressing the landlord’s core financial concern.
A cosigner or guarantor.
If you have someone with strong credit and income willing to cosign, this shifts a significant amount of the landlord’s risk and can be the deciding factor, especially for a landlord who’s on the fence rather than firmly opposed to renting to anyone with an eviction history.
Step Five: Target the Right Kind of Landlord
Not every rental market screens applicants the same way. A few categories worth focusing your search on:
Independent landlords rather than large corporate property management companies.
Big management companies often use rigid, automated screening criteria with no room for context or explanation. An individual landlord renting out a property they own personally has more flexibility to consider your explanation, your references, and your current situation as a whole.
Second-chance or eviction-friendly rental listings.
In many cities, some landlords and property managers specifically advertise as open to applicants with eviction history, sometimes explicitly, sometimes signaled through phrases like “flexible screening” or “case-by-case basis.” Local tenant advocacy organizations, and even some dedicated online listing categories, can help identify these.
Properties that are harder to fill.
Units that have been vacant longer, or that are in a less competitive part of the rental market, put more negotiating leverage in your hands. A landlord who has had a unit sitting empty for two months is often more willing to work with an applicant who has a strong current income and a reasonable explanation, compared to a landlord fielding twenty applications for one unit.
Month-to-month or short-term arrangements first.
Some renters use a short-term lease, sublet, or room rental (which often has less formal screening) as a bridge, building a fresh, positive rental history for a year before applying somewhere with stricter screening.
What to Say (and Not Say) About Your Eviction
How you frame the conversation matters. A few principles:
Be upfront rather than hoping it won’t come up.
If a landlord discovers an undisclosed eviction during screening after you’ve implied a clean record, it damages trust more than the eviction itself would have. Bringing it up proactively, briefly, and with context shows confidence and honesty.
Keep the explanation short and factual.
One or two sentences on what happened, one sentence on what’s different now (steady job, savings buffer, resolved the underlying issue) is usually more effective than a long, emotional account.
Don’t over-apologize or seem desperate.
A landlord is assessing risk, not judging your character. A calm, matter-of-fact tone that focuses on your current stability tends to land better than an apologetic or defensive one.
When an Eviction Isn’t Actually Yours or Was Handled Unfairly
If you believe an eviction on your record is inaccurate, belongs to someone else, or was the result of an illegal action by a landlord (such as retaliation for reporting a habitability issue, or an eviction attempted without proper legal process), contact a local tenant’s rights organization or legal aid clinic. Many operate on a free or sliding-scale basis and can help you understand whether the case can be challenged, sealed, or removed from screening reports altogether. This is a meaningfully different situation from an eviction that legitimately occurred, and it’s worth pursuing seriously rather than assuming nothing can be done.
Frequently Asked Questions
Can a landlord legally deny me solely because of a past eviction?
In most states, yes — landlords generally have wide discretion in choosing tenants, and a past eviction is a legitimate factor they can weigh. Some cities and states have passed “fair chance” or “second look” housing laws that limit blanket denials based solely on eviction history, similar to fair-chance hiring laws for criminal records, so check your local regulations.
Does an eviction show up on a credit report?
Not directly, in most cases. The eviction case itself typically appears through tenant-screening services that search court records. However, any unpaid debt connected to the eviction (back rent, court-ordered judgments) can be reported to the credit bureaus if it’s sent to collections, and that portion would show up on a standard credit report.
How long do I need to wait before applying again after an eviction?
There’s no waiting period required by law in most places. Some renters find success reapplying immediately with a strong explanation and references; others spend six months to a year building savings, paying off any balance owed, and establishing a track record before applying somewhere more competitive.
Will paying off an old eviction judgment remove it from my record?
Paying it off typically updates the status to “paid” or “satisfied” rather than removing the record entirely, though a paid status is viewed far more favorably by landlords than an outstanding balance. Whether the underlying case can be sealed or removed depends on your state’s specific laws.
Should I use a professional eviction-removal or “credit repair for renters” service?
Be cautious. Legitimate options — disputing genuine inaccuracies, petitioning for sealing where your state allows it, negotiating a payoff — are all things you can typically do yourself for free or low cost. Be skeptical of any service promising to remove an accurate eviction record for a fee; if the underlying case is real and accurately reported, no legitimate service can simply make it disappear.
Sample Explanation Letter Template
Having a written explanation ready before you start applying saves you from scrambling to write one under pressure, and it also lets you refine the wording until it sounds calm and confident rather than defensive. A basic structure that works well:
Opening:
A brief, direct acknowledgment. “I want to be upfront that a past tenancy at [address/city] ended in an eviction filing in [year].”
Context:
One or two sentences on the cause, focused on facts rather than blame. “This happened after I lost my job unexpectedly and fell behind on rent for several months.”
Resolution:
What’s different now. “I’ve since resolved the balance in full and have been steadily employed at [company/type of role] for the past [length of time].”
Forward-looking close:
A short statement of reliability. “I’m happy to provide references from my current employer and landlord, and I’m glad to discuss any additional documentation that would be helpful.”
Keep the whole thing to a short paragraph. A landlord reading fifteen applications doesn’t need your full life story — they need enough context to feel confident saying yes, and a demonstration that you can address a difficult topic professionally.
Understanding Why the Eviction Happened Shapes Your Strategy
Not all evictions come from the same root cause, and the reason behind yours should shape how you present your situation.
Nonpayment of rent due to a temporary hardship
(job loss, medical emergency, unexpected expense) is generally the easiest to explain, because it’s a specific, resolvable event rather than an ongoing pattern. Landlords can usually understand a single hardship, especially if you can show the underlying cause has passed.
A dispute over property conditions or a landlord-tenant disagreement
that escalated to an eviction filing, especially one that was later dismissed or settled, is worth explaining clearly with documentation, since it reflects a specific conflict rather than an inability to pay rent or maintain a property.
Repeated late payments or lease violations
leading to eviction suggest a pattern a landlord will want more reassurance about — this is where strong recent references and proof of a genuinely different financial situation matter most.
An eviction tied to a former partner or roommate’s actions
where you were on the lease but not primarily responsible for the underlying issue, is worth explaining honestly, along with any documentation (police reports, court filings naming the other party specifically) that supports your account.
Being clear-eyed with yourself about which category your situation falls into helps you write a more convincing, specific explanation rather than a vague, generic one.
Alternatives and Workarounds Worth Knowing About
Rent guarantor or insurance services.
Companies like Insurent, TheGuarantors, and similar services will act as a guarantor for your lease in exchange for a fee (often equivalent to a portion of a month’s rent), backing your application financially the way a personal cosigner would. This can be a practical option if you don’t have a family member or friend able to cosign.
Corporate or extended-stay housing.
Furnished apartments and extended-stay properties sometimes have more flexible screening than traditional leases, since they’re often priced at a premium and cater to short-term or transitional renters. This can serve as a bridge while you rebuild a rental history.
Subletting or room rentals.
Renting a room in someone else’s home, or subletting from an existing tenant, often involves a much less formal screening process — sometimes just a conversation and a reference — and can be a practical way to secure housing and build a positive, recent rental reference for a future, more formal application.
Rent-reporting services.
Once you’re in a new lease, some services (like Rental Kharma, Boom, or your landlord directly, if they participate) will report your on-time rent payments to the credit bureaus, which builds a positive credit history independent of your rental screening file, and can help demonstrate reliability if you’re building back up after a rocky period.
Understanding Your Rights During the Screening Process
Because tenant screening reports are considered consumer reports under the Fair Credit Reporting Act, you have specific legal protections. If you’re denied housing based even partly on information in a screening report, the landlord is required to give you an “adverse action notice,” which must include the name and contact information of the screening company that provided the report. This is valuable because it tells you exactly where to go to pull your file and dispute anything inaccurate, rather than guessing which of several possible screening companies was involved.
You’re also entitled to a free copy of that specific report from the screening company if you request it within 60 days of the adverse action notice. Many renters don’t realize this and simply move on to the next application without ever seeing what actually triggered the denial — which means they keep hitting the same wall for a reason they never identified or corrected.
Frequently Asked Questions, Continued
Can I get an eviction removed just by asking the landlord to withdraw the report?
If the case is still pending or was recently filed, some landlords may be willing to withdraw the case (especially if the underlying balance gets paid), which would then reflect in court records as dismissed. Once a case is closed and reported by screening companies, you generally can’t simply ask a company to remove accurate information — you’d need to pursue sealing or expungement through the appropriate legal process if your state allows it.
Do all landlords use the same tenant screening company?
No. Different landlords and property management companies use different screening vendors, and each maintains its own database, sometimes with different lookback periods or reporting practices. This is part of why an eviction might show up on one application and not another — it’s worth requesting your report from whichever company was actually used, rather than assuming it’s the same one every time.
Is it worth hiring an attorney to fight tenant screening errors?
For a straightforward factual error (wrong outcome, mismatched identity, an unpaid balance that’s actually been paid), you can usually resolve it yourself through the dispute process at no cost. An attorney becomes more valuable for a genuinely contested legal question, such as whether a landlord’s original eviction action was retaliatory or otherwise improper, or if a screening company refuses to correct a documented error after a proper dispute.
How much does an eviction typically lower approval chances?
There’s no universal number — it depends heavily on the individual landlord, the local rental market’s competitiveness, how recent the eviction is, and how strong the rest of your application is. In a tight rental market with many applicants, any red flag can be disqualifying by default; in a slower market, or with an independent landlord, a well-explained eviction with strong current references is often manageable.
Eviction Sealing and Expungement Laws Are Changing
Over the past several years, a growing number of states and cities have recognized that eviction filings — as opposed to actual eviction judgments — can unfairly follow a tenant for years even when the case never resulted in a finding against them. In response, many jurisdictions have introduced or expanded laws that allow certain eviction records to be sealed from public view or removed from tenant screening reports under specific conditions.
Common qualifying conditions across different jurisdictions include: the case was dismissed or withdrawn, the tenant prevailed in court, a certain number of years have passed since the filing, the underlying issue was tied to a state of emergency (some jurisdictions passed specific protections for eviction filings during public health emergencies), or the debt has been paid in full and a set waiting period has elapsed.
Because these laws vary significantly by state — and sometimes even by county or city within a state — the most reliable way to find out what applies to you is to contact your local courthouse’s self-help center, a legal aid organization, or a tenant’s rights nonprofit in your area. Many of these organizations provide free consultations specifically for renters trying to understand and act on eviction-sealing eligibility, and some even help file the paperwork at no cost.
If you do successfully seal or expunge a record, it’s worth following up directly with any tenant-screening companies that previously reported it, since sealing a court record doesn’t always automatically and immediately update every private screening database — you may need to provide proof of the sealing order to have it corrected.
Building a Rental Resume
Just as a job resume presents your professional history in an organized, persuasive format, a “rental resume” does the same for your housing history, and it’s an underused tool for renters trying to overcome a past eviction. A simple one-page document that includes your current employment and income, a summary of your rental history (including the honest, brief explanation of the eviction), personal and professional references with contact information, and any relevant financial documentation (bank statements, proof of savings) gives a landlord a complete, organized picture upfront rather than forcing them to piece it together from a screening report alone.
Handing this to a landlord alongside your application, rather than waiting to explain the eviction only if asked, demonstrates initiative and honesty — two qualities that directly counter the concerns an eviction on your record might otherwise raise.
A Note on Emotional Resilience Through the Process
It’s worth naming directly: searching for housing with an eviction on your record can involve real rejection, sometimes repeatedly, and that’s genuinely discouraging. It’s easy to internalize each denial as a judgment on your character rather than what it usually is — a risk-averse screening policy applied broadly and impersonally. Keeping a level head through a string of “no” responses, while continuing to refine your application and explanation letter based on what you learn along the way, tends to produce results faster than either giving up on a search or becoming defensive and combative with prospective landlords. Every rejection is also information: if you’re consistently denied by large corporate management companies but getting further with independent landlords, that’s a useful signal about where to focus your energy going forward.
Frequently Asked Questions, Continued Further
What if the eviction was filed against a roommate, not me?
If your name wasn’t actually on the eviction case, it generally shouldn’t appear on your individual tenant screening report at all. If it does, that’s likely a case of mistaken identity or a data-matching error at the screening company, and it’s worth disputing directly, providing documentation such as the original lease showing only your roommate’s name on the case.
Can I rent an apartment under a different name to avoid the eviction showing up?
No — beyond being generally impractical, since leases and screening require accurate legal identification and often a Social Security number for the credit check portion, misrepresenting your identity on a rental application can constitute fraud and create far more serious legal problems than the eviction itself.
Does bankruptcy clear an eviction-related debt?
An eviction-related debt (like a court judgment for unpaid rent) can potentially be discharged in bankruptcy depending on the type of bankruptcy filed and the specific circumstances, but the eviction case itself, as a court record, is a separate matter from the debt and isn’t erased by a bankruptcy filing. If you’re considering bankruptcy for eviction-related debt, a consultation with a bankruptcy attorney can clarify what would and wouldn’t be affected in your specific situation.
How do I find eviction-friendly landlords in my area?
Local tenant’s rights organizations, some nonprofit housing assistance programs, and certain online rental platforms that cater to “second chance” renters are good starting points. Word of mouth and directly asking property managers about their screening flexibility during a phone inquiry, before submitting a formal application, can also save time by avoiding applications to landlords with rigid automatic denial policies.
The Bottom Line
An eviction makes renting harder, not impossible. The renters who move past it fastest tend to do three things: verify exactly what’s on their record and dispute anything inaccurate, resolve any outstanding balance so the record reflects a closed chapter rather than an open one, and build an application that gives a landlord real reasons to say yes — steady income, solid references, a straightforward explanation, and sometimes a larger deposit or a cosigner to offset the risk. None of this erases the past, but it consistently changes the outcome for renters willing to put in the extra groundwork.
Need Help Reviewing Your Credit?
If your eviction also resulted in collections, unpaid rent, or other negative information appearing on your credit reports, you can request a credit review to understand what is being reported and what options may be available.