
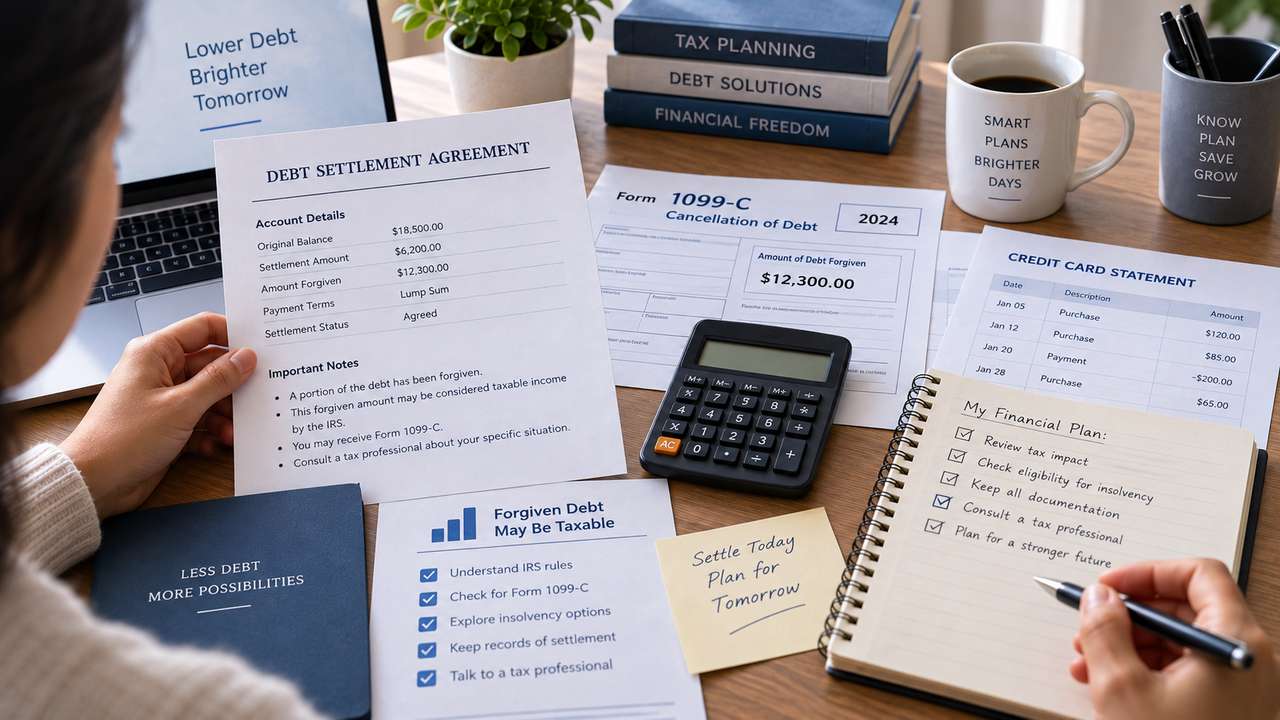
The Core Concept: Forgiven Debt Is Generally Taxable Income
Under U.S. tax law, when a creditor forgives $600 or more of debt you owed, the IRS generally treats that forgiven amount as taxable income to you — the theory being that the debt relief provided you with an economic benefit equivalent to receiving that amount in cash, since you’re no longer obligated to pay it. This applies to most types of settled consumer debt, including credit cards, personal loans, and similar unsecured debt.
For current IRS information about cancellation-of-debt income, see the IRS guidance on canceled debt and Form 1099-C.
The Form 1099-C: What It Is and Why You Might Receive One
When a creditor forgives $600 or more of debt, they’re generally required to file a Form 1099-C, “Cancellation of Debt,” with the IRS, and send you a copy as well. This form reports the amount of debt that was cancelled, which you’re then generally required to include as income on your tax return for that year, unless a specific exception or exclusion applies (covered below).
A concrete example: if you owed $5,000 on a credit card and settled it for $2,000, the forgiven $3,000 difference is the amount that would typically be reported on a 1099-C and treated as taxable income, potentially increasing your tax bill for that year, depending on your overall tax bracket and situation.
When This Applies to Debt Settlement Specifically
If you negotiate a settlement with a creditor or debt buyer — paying less than the full balance as full and final resolution — the forgiven portion is exactly the kind of cancelled debt this rule addresses. This is true whether you negotiated the settlement yourself, worked with a debt settlement company, or went through a formal debt management plan that resulted in a negotiated reduction (though debt management plans through nonprofit credit counseling more commonly focus on reduced interest rather than principal reduction, making this specific tax issue somewhat less common in that particular context compared to debt settlement’s typical structure).
Important Exceptions and Exclusions
The good news is that not everyone who has debt forgiven actually owes tax on it — several exceptions exist:
Insolvency Exception
If you were insolvent immediately before the debt was cancelled — meaning your total liabilities exceeded your total assets — you can potentially exclude some or all of the cancelled debt from your taxable income, up to the amount by which you were insolvent. This requires calculating your total assets and total liabilities at the specific time of the cancellation, which can be a meaningful calculation for someone in genuine financial distress at the time of a settlement, and often results in partial or complete exclusion of the tax liability that would otherwise apply.
Bankruptcy Exception
Debt discharged through bankruptcy is generally fully excluded from taxable income, regardless of your insolvency status — this is one of the more significant tax advantages of bankruptcy compared to an out-of-court settlement, since debt settled outside of bankruptcy doesn’t automatically receive this same blanket exclusion.
Certain Specific Debt Types
Some specific categories of forgiven debt have their own separate exclusion rules — certain qualified student loan forgiveness programs, and some mortgage debt forgiveness under specific historical relief programs, have had dedicated exclusions at various points, though these rules change over time and should be verified for current applicability to your specific situation.
How to Determine If You Qualify for the Insolvency Exception
This requires completing IRS Form 982, which involves calculating your total liabilities (all debts, not just the one being settled) against your total assets (bank accounts, property, retirement accounts, and other assets) as of immediately before the debt cancellation. If your liabilities exceeded your assets at that specific point, you were insolvent by that difference, and you can potentially exclude up to that amount of cancelled debt from taxation.
This calculation can be genuinely complex, particularly if you have multiple assets and debts to account for accurately, which is exactly why consulting a tax professional — even just for this specific calculation — is often worthwhile if you’ve received a 1099-C and believe insolvency might apply to your situation.
You can review the IRS information about Form 982 for additional information about exclusions related to cancellation of debt income.
What to Do Before Finalizing a Settlement
Factor the potential tax cost into your negotiation. If you’re settling a $5,000 debt for $2,000, and you don’t qualify for an exclusion, the $3,000 forgiven amount could add several hundred dollars or more to your tax bill (depending on your tax bracket), meaning the settlement’s true total cost is somewhat higher than the $2,000 payment alone.
Ask the creditor directly whether they intend to issue a 1099-C. While they’re generally required to for amounts of $600 or more, confirming this in advance helps you plan rather than being surprised months later during tax season.
Consider consulting a tax professional before finalizing a large settlement, particularly if you believe insolvency might apply, since this can meaningfully reduce or eliminate the tax consequence.
What to Do If You Receive a 1099-C
Don’t ignore it. The IRS receives a copy of the same form, and failing to report the income (if no exclusion applies) can result in a mismatch that triggers IRS notices or an audit down the line.
Determine whether an exclusion applies — insolvency being the most common for typical consumer debt settlement — and complete Form 982 if so.
Report the income on your tax return if no exclusion applies, understanding this may increase your tax liability for that year.
Consult a tax professional if your situation is complex, particularly involving multiple settled debts in the same year, or an uncertain insolvency calculation.
For official information about Form 1099-C, you can also review the IRS Form 1099-C information page.
A Common Point of Confusion: Does This Apply to a Charge-Off Alone, Without a Settlement?
This is worth clarifying, since it’s a frequent point of confusion: a charge-off by itself (the creditor’s internal accounting decision to write off a delinquent account) doesn’t automatically trigger a 1099-C — the debt has been charged off internally, but the creditor hasn’t necessarily formally cancelled or forgiven your legal obligation to pay it, and may still pursue collection or sell the debt to a buyer. A 1099-C is specifically tied to an actual determination that the debt has been cancelled or forgiven, which is a distinct, sometimes later event from the initial charge-off, most commonly triggered by an actual settlement, a formal debt forgiveness, or, in some cases, a creditor’s internal determination after an extended period that they’ve given up all further collection efforts.
What If You Receive a 1099-C for Debt You’re Still Being Asked to Pay?
This does happen, sometimes due to inconsistent internal processes at a creditor or a subsequent sale of the debt to a buyer who’s unaware it was already reported as cancelled. If you receive a 1099-C but are still being pursued for payment on what appears to be the same debt, this is worth addressing directly with both the company issuing the 1099-C and any company still attempting to collect, since you generally shouldn’t be both taxed on cancelled debt and still legally obligated to pay it — a genuine conflict here is worth resolving with documentation from both sides, and potentially with a tax professional’s or attorney’s guidance if it’s not straightforward to sort out.
Frequently Asked Questions
Does this tax rule apply to medical debt settlement the same way it applies to credit card debt?
Generally, yes, the same core principle applies to most forgiven consumer debt regardless of type, though the same exceptions (insolvency, bankruptcy) would apply equally, and medical debt settlements sometimes involve smaller forgiven amounts that may fall under the $600 reporting threshold, avoiding a 1099-C altogether for smaller settlements.
If multiple debts are settled in the same year, does each one need to exceed $600 separately, or do they combine?
Generally, the $600 threshold applies per creditor/cancellation event, meaning multiple separate settlements with different creditors, each individually under $600, might not individually trigger a 1099-C, even though your combined forgiven debt across all of them exceeds $600 — though the underlying tax principle about cancelled debt being potentially taxable can still technically apply even without a formal 1099-C being issued, which is worth discussing with a tax professional if this scenario applies to you.
Does settling debt through a nonprofit credit counseling debt management plan have the same tax implications as direct debt settlement?
Since debt management plans typically focus on reduced interest and fees rather than forgiving principal balance, this specific tax issue is less commonly triggered through this path compared to traditional debt settlement, though it’s worth confirming the specific structure of your particular plan with your credit counseling agency.
Is there a way to negotiate with a creditor to not issue a 1099-C as part of a settlement?
This isn’t generally something a creditor can simply agree to skip, since it’s a legal reporting requirement they’re obligated to follow for qualifying cancelled debt amounts — rather than trying to avoid the form itself, the more productive approach is understanding and applying any exclusions (like insolvency) you may legitimately qualify for.
Does forgiven debt from a foreclosure or repossession follow the same tax rules?
Generally yes, forgiven deficiency balances (the remaining amount owed after a foreclosure or repossession sale doesn’t cover the full loan) can similarly trigger a 1099-C and the same general tax treatment, subject to the same potential exclusions, including insolvency and, for certain historical mortgage relief programs, specific dedicated exclusions that have applied at various points.
A Worked Example of the Insolvency Calculation
To make the insolvency exception more concrete, imagine you settle a $6,000 credit card debt for $2,500, meaning $3,500 was forgiven. To determine whether the insolvency exception applies, you’d calculate your total assets and total liabilities immediately before the settlement:
- Assets: $1,200 in checking/savings, a car worth $4,000, and no other significant assets = $5,200 total assets.
- Liabilities: the $6,000 credit card debt itself (before settlement), plus $2,000 in other unpaid bills, plus a $3,000 remaining balance on the car loan = $11,000 total liabilities.
- Insolvency amount: $11,000 (liabilities) – $5,200 (assets) = $5,800.
Since your insolvency amount ($5,800) exceeds the forgiven debt amount ($3,500), you could potentially exclude the entire $3,500 from taxable income, since your insolvency more than covers the full forgiven amount. If your insolvency calculation had instead been smaller than $2,000 of insolvency, you’d be able to exclude that $2,000, but the remaining $1,500 of forgiven debt would still be taxable.
This example illustrates why the calculation matters so much and why it’s worth doing carefully (or with professional help) rather than assuming either that you automatically owe tax on the full forgiven amount, or that you’re automatically excluded — the actual answer depends entirely on your specific financial position at that specific moment.
How State Taxes May Differ From Federal Treatment
It’s worth knowing that state tax treatment of cancelled debt doesn’t always mirror federal rules exactly — some states follow federal exclusions (like insolvency) automatically, while others have their own separate rules or don’t offer the same exclusions at the state level, potentially creating a situation where forgiven debt is excluded from federal taxable income but still counted for state tax purposes, or vice versa. Checking your specific state’s treatment, or having a tax professional familiar with your state’s rules review your situation, is worth doing separately from the federal calculation, particularly for a larger settlement where the state tax difference could be meaningful.
Why Some People Choose to Proceed With a Settlement Despite the Tax Cost
Even accounting for a potential tax bill on forgiven debt, settling is often still financially advantageous compared to paying the full original balance or letting the debt continue accruing interest and fees indefinitely. A rough way to think about it: if you’re in a moderate tax bracket, the tax owed on forgiven debt is typically a fraction of the forgiven amount itself (since you’re taxed at your marginal rate, not required to pay back the full forgiven sum), meaning even with the tax cost factored in, a well-negotiated settlement usually still represents meaningful savings compared to the original obligation. Understanding the tax cost in advance simply allows you to make this comparison accurately, rather than being surprised by an unaccounted-for cost after the fact.
Frequently Asked Questions, Continued
Do I need to wait for the 1099-C to arrive before I can file my taxes, or can I estimate and file without it?
It’s generally best practice to wait for and use the actual 1099-C when filing, since it contains the official reported amount the IRS will also receive — filing based on your own estimate that doesn’t match the official form can create a mismatch that triggers IRS correspondence, even if your estimate was reasonably close.
If a creditor fails to send me a 1099-C despite forgiving $600 or more, am I still responsible for reporting the income?
Generally yes — the underlying tax obligation to report cancelled debt income exists independent of whether the creditor actually issues the form correctly; if you know debt was forgiven in an amount that should have triggered a 1099-C but never received one, it’s worth proactively addressing this with a tax professional rather than assuming the absence of the form means no tax obligation exists.
Does the insolvency exclusion reduce my tax bill dollar-for-dollar, or does it work differently?
The exclusion removes the qualifying amount from your taxable income entirely, meaning you don’t pay tax on that specific excluded portion at all — it’s not a tax credit or a partial reduction calculation, but a full exclusion up to your calculated insolvency amount.
A Second Worked Example Involving Multiple Debts Settled in the Same Year
Building on the earlier single-debt example, consider a more complex scenario: over the course of one year, you settle three separate debts — $2,000 forgiven on a credit card, $1,500 forgiven on a personal loan, and $800 forgiven on a medical bill. Each creditor individually exceeds the $600 threshold, so each would generally issue its own separate 1099-C, and for tax purposes, these combine into a total of $4,300 in potentially taxable cancelled debt income for that year. If your insolvency calculation at the time (using your total assets and liabilities immediately before each respective cancellation, which technically should be calculated separately for each event, though many people’s overall financial position doesn’t change dramatically within a single year) shows insolvency exceeding this combined amount, you could potentially exclude the full $4,300; if your insolvency is smaller, only that portion would be excluded, with the remainder still taxable. This kind of multi-debt scenario is exactly when consulting a tax professional becomes particularly valuable, given the added complexity of properly calculating and documenting insolvency across multiple cancellation events.
Frequently Asked Questions, Continued One Final Time
Does refinancing debt (rather than settling it) ever trigger similar tax consequences?
No — refinancing simply replaces one loan with another of a different structure or rate; no debt is actually forgiven in a standard refinance, so there’s no cancellation-of-debt income or 1099-C involved, unlike an actual negotiated settlement or forgiveness.
If I’m genuinely unsure whether I qualify for the insolvency exclusion, is it safer to just report the full amount as income and pay the tax?
This is a conservative approach some people take to avoid any risk of an IRS inquiry, but it can mean overpaying tax you weren’t actually required to pay if you did in fact qualify for some or all of the exclusion — given this tradeoff, a brief consultation with a tax professional to actually calculate your insolvency accurately is often worth the modest cost, particularly for a larger forgiven amount where the tax difference could be significant.
The Bottom Line
Debt settlement often carries a tax consequence that’s easy to overlook in the moment: forgiven debt of $600 or more is generally treated as taxable income, reported to you and the IRS via a Form 1099-C, unless a specific exclusion — most commonly insolvency, or a full bankruptcy discharge — applies to your situation. Before finalizing any significant settlement, it’s worth factoring this potential tax cost into your overall decision, and if you do receive a 1099-C, addressing it properly on your tax return, ideally with a tax professional’s help if your situation involves a meaningful insolvency calculation or any other complexity, rather than either ignoring the form or assuming the entire forgiven amount is automatically tax-free.
Need Help Reviewing Your Credit Report?
Debt settlement and tax consequences can be easier to understand when you have a clear picture of the accounts appearing on your credit report. Reviewing your credit profile can help you identify collection accounts, outstanding debts, and potentially inaccurate information that may need attention.
If you are working toward improving your credit after dealing with debt, a detailed credit report review can help you understand your current position and identify areas that may require further action.