
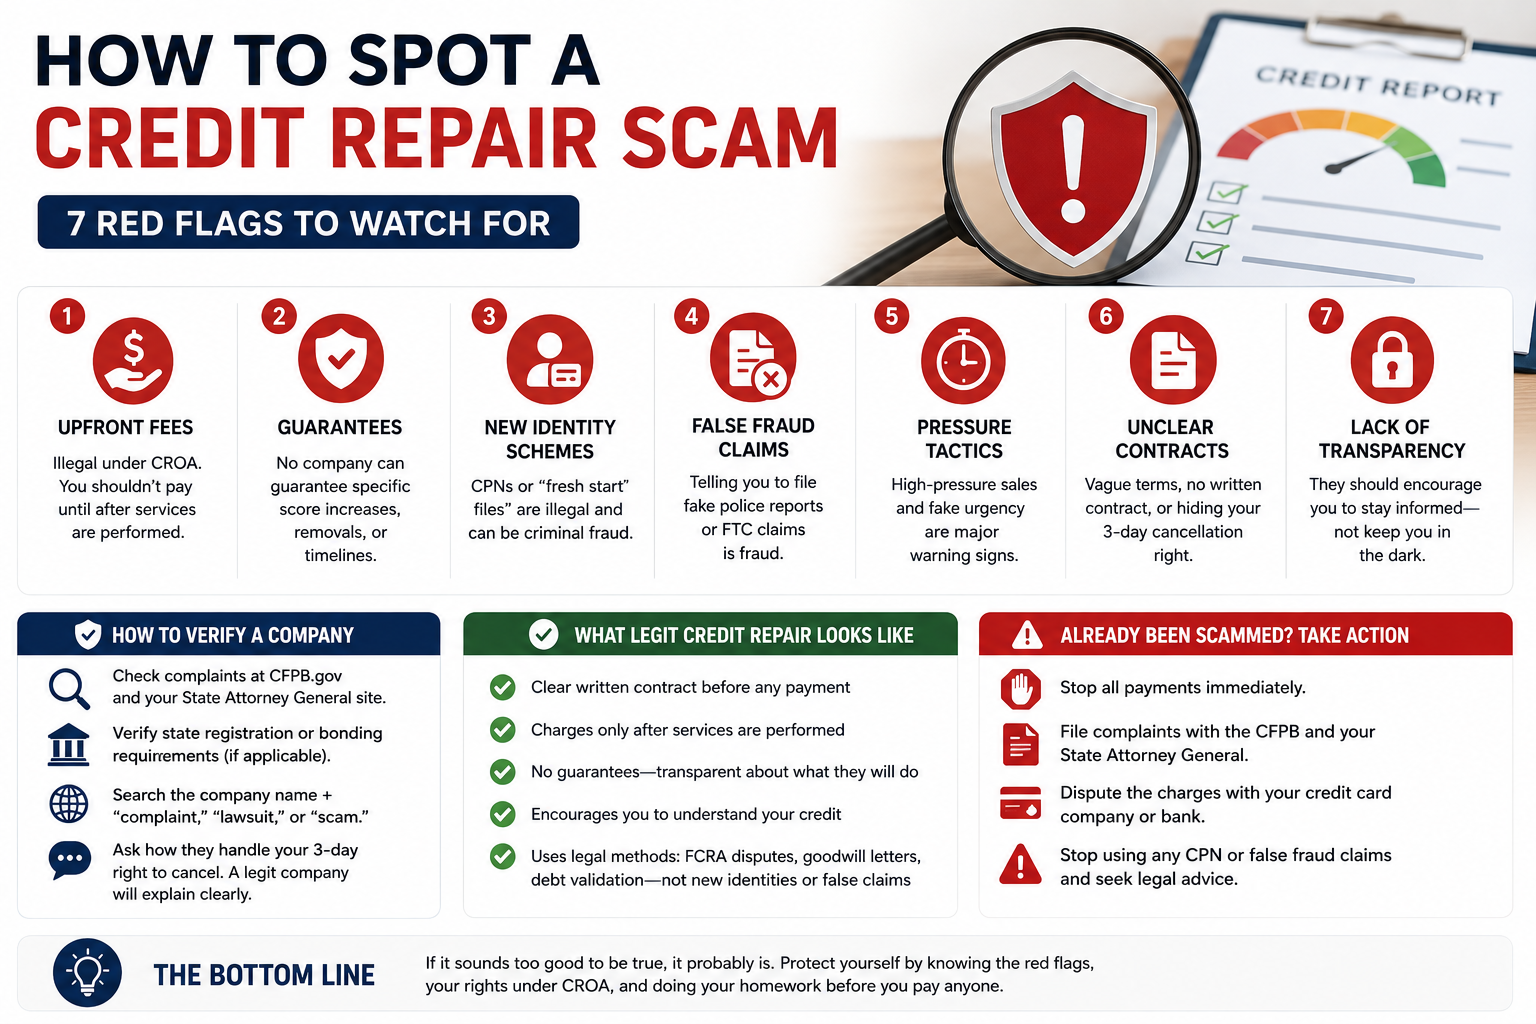
The credit repair industry has a genuinely useful, legitimate side, but it also has a well-documented history of scams and predatory operators, largely because desperate financial circumstances make people more vulnerable to promises that sound too good to be true. The good news: the law actually gives you specific, checkable red flags to look for, since the Credit Repair Organizations Act (CROA) spells out exactly what legitimate companies are and aren’t allowed to do.
Red Flag 1: Any Request for Payment Before Services Are Performed
This is the single most important, legally clear-cut red flag. Under CROA, credit repair companies are **prohibited from charging any fee before they’ve actually performed the promised services**. This isn’t a best practice or a suggestion — it’s federal law.
If a company asks for payment upfront, a “setup fee,” or any charge before disputes have actually been filed and results (or at least documented work) delivered, this is not just a red flag — it’s a company operating outside the law, regardless of how professional their marketing looks.
Red Flag 2: Guarantees About Specific Results
Any company promising a specific score increase (“we’ll raise your score by 100 points”), a guaranteed removal of specific negative items, or a guaranteed timeline for dramatic results is making a promise that’s both legally prohibited under CROA and practically impossible to honestly make — no legitimate company can guarantee the outcome of a dispute process that depends on the accuracy of your specific credit history and the response of individual furnishers, which are outside any company’s control.
Red Flag 3: Advice to Create a New Credit Identity
This is one of the more serious scams in the space, sometimes marketed as a “credit privacy number” (CPN) or a “fresh start” file. The pitch typically involves obtaining a new number (sometimes a real Employer Identification Number misused as if it were a personal identifier, sometimes an outright fabricated number) to use in place of your Social Security Number when applying for credit, effectively creating a synthetic new identity disconnected from your damaged credit history.
This is not a legal loophole — it’s **file segregation fraud**, a federal crime. Using any number other than your actual SSN to apply for credit, misrepresenting your identity to obtain credit, is illegal, and you — not just the company selling you the scheme — bear serious legal risk, including potential fraud charges, if you use one of these numbers. Any company suggesting this, however it’s framed, should be treated as an immediate, serious red flag.
Red Flag 4: Instructions to Dispute Accurate Information as Fraud
A related scam pattern involves instructing you to file police reports or FTC identity theft reports for debts that are actually yours, specifically to trigger the more aggressive removal protections available for genuine identity theft victims. This is fraud — falsely claiming identity theft to remove accurate, legitimately-owed debt is illegal, and doing so exposes you to potential legal consequences, separate from whatever the company itself faces.
Red Flag 5: Pressure Tactics and Urgency
Legitimate credit repair, whether DIY or through a reputable company, is inherently a multi-month process — there’s no legitimate reason for high-pressure “sign today” tactics, artificial urgency, or claims that a special rate or opportunity will disappear if you don’t commit immediately. This kind of pressure is a sales tactic designed to prevent you from doing the due diligence (reading reviews, checking complaint history, understanding the contract) that would otherwise reveal problems.
Red Flag 6: Vague or Unclear Contract Terms
Under CROA, legitimate credit repair companies are required to provide you with a written contract that clearly discloses:
– The specific services to be performed.
– The total cost and payment schedule.
– Your right to cancel within 3 business days without penalty.
– A specific timeline for when services will be completed.
If a company is vague about any of this, avoids putting terms in writing, or pressures you to sign without adequate time to review, that’s a serious warning sign, regardless of how legitimate other aspects of their pitch might seem.
Red Flag 7: They Discourage You From Contacting Bureaus or Creditors Directly
A legitimate company has no reason to discourage you from understanding or participating in your own dispute process — in fact, transparency about what’s being disputed and why is a hallmark of reputable operators. If a company is cagey about specifics, discourages you from checking your own credit report to verify their claimed progress, or asks you to route all communication exclusively through them without transparency, this warrants real skepticism.
How to Verify a Company Before Signing Anything
**Check their complaint history.** The CFPB’s public complaint database and your state Attorney General’s consumer complaint records are both searchable and free, and a pattern of unresolved complaints is a meaningful signal.
**Check state registration requirements.** Many states require credit repair companies to register or post a bond before operating — verify this directly with your state’s regulatory body if such a requirement applies where you live.
**Search the company name alongside terms like “complaint,” “lawsuit,” or “scam”** as a basic first-pass check, understanding that this isn’t foolproof (some complaints are unfounded, and some genuinely problematic companies have limited online complaint visibility) but is a reasonable starting point.
**Ask specifically how they handle the CROA-mandated cancellation right** — a legitimate company should have no hesitation explaining your 3-day right to cancel without penalty; hesitation or vagueness here is itself informative.
What Legitimate Credit Repair Actually Looks Like
To be fair to the reputable side of the industry, legitimate credit repair companies:
– Provide a clear written contract before any payment.
– Charge only after services are actually performed, often on a monthly basis tied to ongoing work.
– Make no guarantees about specific outcomes, while being transparent about what they will attempt and why.
– Encourage you to understand your own credit report and stay informed throughout the process.
– Operate within standard, legal dispute mechanisms — FCRA disputes, goodwill letters, legitimate debt validation and negotiation — nothing involving new identities or fraudulent claims.
What to Do If You’ve Already Been Scammed
If you’ve already paid a company that turned out to be operating illegally (charged upfront, made guarantees, or pushed a CPN scheme):
1. **Stop any further payments immediately.**
2. **File a complaint with the CFPB and your state Attorney General**, both of which take credit repair fraud seriously and have pursued enforcement actions against violators.
3. **Dispute the charges with your credit card company or bank** if payment was made electronically, citing the fraudulent or illegal nature of the services.
4. **If you were advised to use a CPN or file a false identity theft claim, stop using it immediately** and consult a consumer attorney about how to unwind any resulting complications, since continuing to use it compounds your own legal exposure.
The Bottom Line
The credit repair industry’s worst actors share a fairly consistent, checkable set of red flags: upfront payment demands, specific outcome guarantees, and — most seriously — any suggestion involving a new identity number or false fraud claims. CROA gives you real, enforceable legal protections against the first two, and the third category is simply illegal regardless of how it’s marketed. A few minutes of due diligence — checking complaint history, insisting on a clear written contract, and being appropriately skeptical of pressure and guarantees — filters out the vast majority of problematic operators before you ever hand over a payment.