
Buying a home is one of the biggest financial moves you’ll ever make. Long before you tour your first property or picture yourself in a new kitchen, one number quietly shapes the whole journey: your credit score.
Your credit score tells lenders how you’ve handled borrowed money in the past. It influences whether you get approved for a mortgage, what interest rate you’re offered, and even how large a down payment you’ll need. A strong score can save you tens of thousands of dollars over the life of a loan. A weaker one makes the path harder, though rarely impossible.
So what credit score do you actually need to buy a house? The honest answer is that it depends on the loan type, the lender, and the rest of your financial picture. Some loans let you qualify with a score in the 500s. Others reward scores above 740 with the best rates available.
This guide walks you through everything in plain language. You’ll learn the minimum credit score to buy a house for each major loan type, how your score affects mortgage rates, whether you can buy with bad credit, and exactly how to improve your credit before applying. By the end, you’ll know where you stand and what to do next.
Let’s get into it.
What You’ll Learn in This Guide
- What a credit score is and why lenders care so much about it
- The minimum credit score to buy a house by loan type
- FHA, conventional, VA, and USDA loan credit score requirements
- How your credit score affects your mortgage rate
- Whether you can buy a house with bad credit
- How debt-to-income ratio and down payment fit into approval
- Step-by-step ways to improve your credit before buying
- What first-time homebuyers should know
- Answers to the most common credit and mortgage questions
Read straight through, or jump to the section you need most.
What Is a Credit Score and Why Does It Matter for a Mortgage?
A credit score is a three-digit number that sums up how reliably you’ve borrowed and repaid money. Most scores range from 300 to 850. The higher the number, the less risky you look to a lender.
Think of it like a trust rating. When you apply for a mortgage, the lender is deciding whether to hand you a large sum of money for 15 or 30 years. Your credit score gives them a quick, data-backed way to gauge how likely you are to pay it back on time.
Two scoring models dominate the mortgage world: FICO and VantageScore. Mortgage lenders lean heavily on FICO scores, and they often pull versions from all three major credit bureaus—Equifax, Experian, and TransUnion. When your scores differ across bureaus, lenders typically use the middle number.
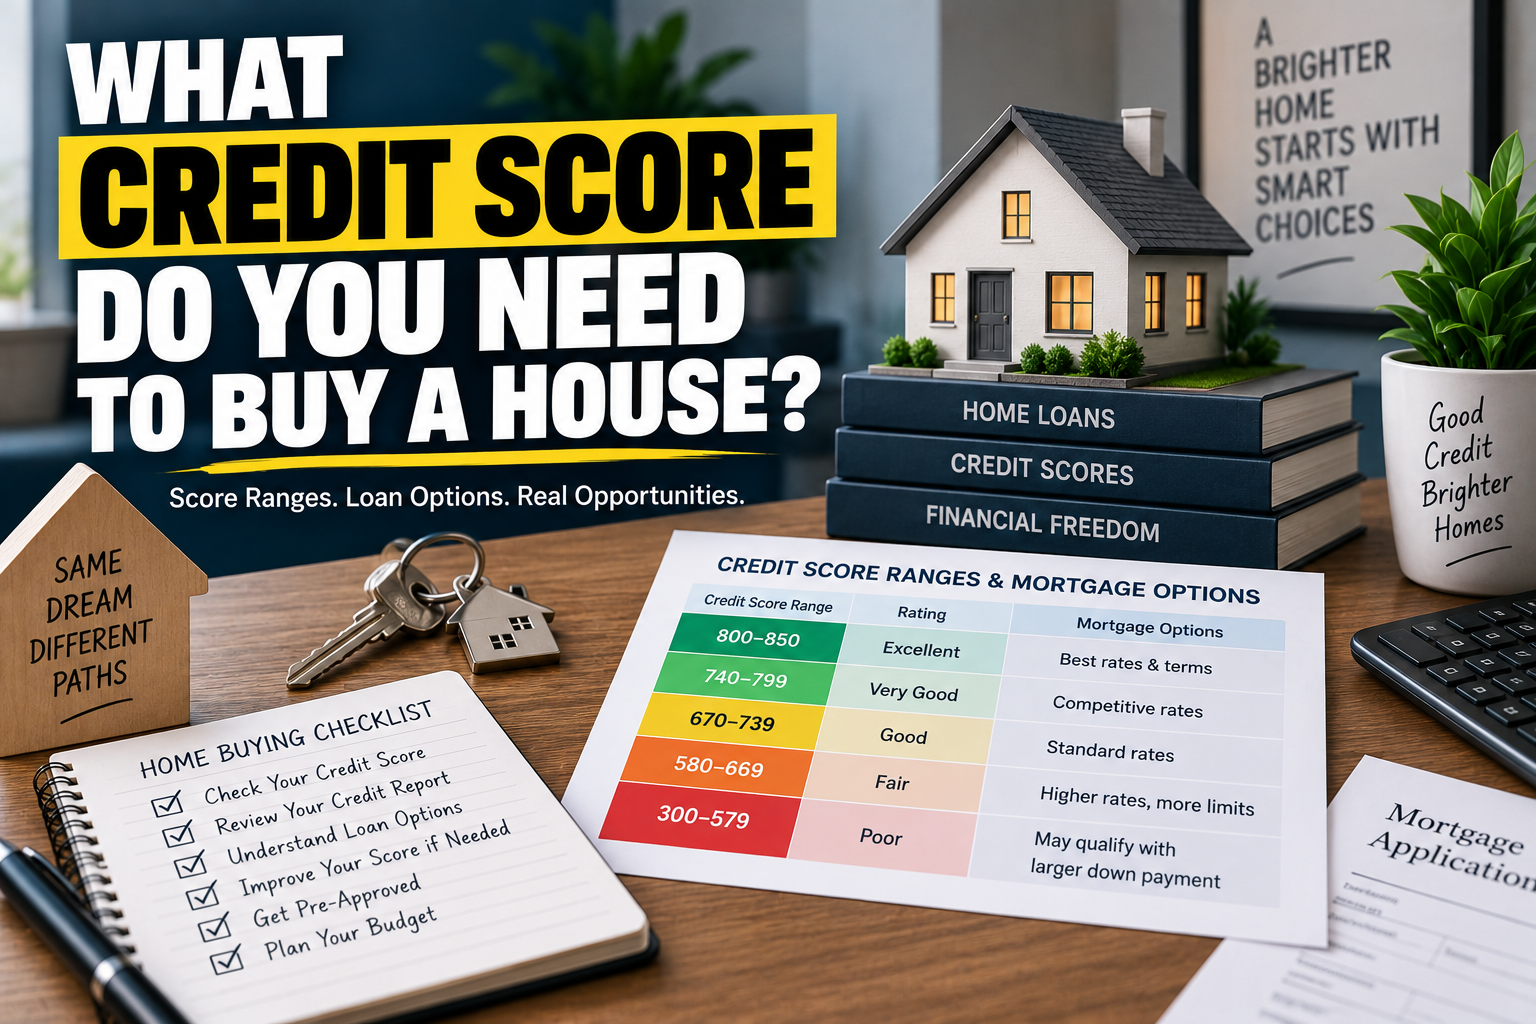
The Credit Score Ranges Lenders Use
Here’s a simple breakdown of how scores are generally grouped:
| Score Range | Rating | What It Means for a Mortgage |
| 800–850 | Exceptional | Access to the best rates and terms |
| 740–799 | Very Good | Strong approval odds, competitive rates |
| 670–739 | Good | Solid approval odds, decent rates |
| 580–669 | Fair | Approval possible, higher rates likely |
| 300–579 | Poor | Approval harder, limited loan options |
Notice that you don’t need a perfect score to buy a home. Plenty of buyers land mortgages with scores in the “good” or even “fair” range. The score simply changes which loans you qualify for and how much you’ll pay in interest.
Why Even a Few Points Can Matter
Here’s the part many first-time buyers miss. Lenders often set their pricing in tiers. Crossing from a 739 to a 740, for example, can bump you into a better rate bracket. A jump from 660 to 680 can do the same.
That means small improvements sometimes deliver outsized savings. Knowing where the thresholds sit helps you decide whether it’s worth waiting a few months to nudge your score higher before you apply.
The Minimum Credit Score to Buy a House by Loan Type
There’s no single magic number that unlocks a mortgage. Each loan program sets its own floor. Below is a quick reference, followed by a deeper look at each option.
| Loan Type | Typical Minimum Credit Score | Best For |
| FHA loan | 500–580 | Buyers with lower credit or smaller down payments |
| Conventional loan | 620 | Buyers with steady credit and finances |
| VA loan | No official minimum (often 580–620 in practice) | Veterans, service members, eligible spouses |
| USDA loan | No official minimum (often 640) | Buyers in eligible rural and suburban areas |
Keep in mind these are baseline figures. Individual lenders can set stricter requirements, known as “overlays.” One lender might approve an FHA loan at 580, while another wants 620 for the same program. Shopping around genuinely pays off.
FHA Loan Credit Score Requirements
FHA loans are backed by the Federal Housing Administration and are popular with first-time buyers and people rebuilding their credit. They’re known for flexible requirements.
Here’s how the credit score rules generally work:
- Score of 580 or higher:You may qualify with a down payment as low as 3.5%.
- Score between 500 and 579:You may still qualify, but typically need a 10% down payment.
That lower threshold makes FHA loans one of the most accessible paths to homeownership. The tradeoff is mortgage insurance. FHA loans require both an upfront mortgage insurance premium and an annual premium, which adds to your monthly cost.
FHA loans work well if your credit is still recovering or if you don’t have a large down payment saved. Just weigh the insurance costs against the easier approval.
Conventional Loan Credit Score Requirements
Conventional loans aren’t backed by the government. Instead, they follow guidelines set by Fannie Mae and Freddie Mac. They’re the most common type of mortgage in the country.
The typical minimum credit score for a conventional loan is 620. But the score does a lot of heavy lifting here:
- 620–679:Approval is realistic, though your rate may be higher.
- 680–739:You’ll usually see better pricing.
- 740 and above:You unlock the most competitive rates and terms.
Conventional loans also offer a nice perk. If you put down at least 20%, you can avoid private mortgage insurance (PMI) entirely. Even with less than 20% down, PMI on a conventional loan usually drops off once you build enough equity, unlike FHA insurance that often sticks around for the life of the loan.
If you have solid credit and reasonably stable finances, a conventional loan is often the most cost-effective choice over time.
VA Loan Credit Score Expectations
VA loans are a powerful benefit for veterans, active-duty service members, and certain surviving spouses. Backed by the Department of Veterans Affairs, they come with major advantages: no down payment requirement and no private mortgage insurance.
The VA itself doesn’t set a minimum credit score. However, the private lenders who issue these loans do. In practice, many look for a score around 580 to 620.
Because VA loans reduce a lender’s risk through the government guarantee, they’re often more forgiving on credit than conventional loans. If you’re eligible, a VA loan is frequently one of the best deals available. It’s worth exploring first if you’ve served.
USDA Loan Credit Score Expectations
USDA loans help buyers purchase homes in eligible rural and suburban areas. Backed by the U.S. Department of Agriculture, they offer another zero-down-payment option for those who qualify based on location and income.
Like VA loans, the USDA doesn’t publish a strict minimum score. Most lenders, though, look for around 640. A score at or above that level often streamlines approval, since it lets the lender use an automated underwriting system.
USDA loans can be a hidden gem if you’re open to living outside a major city. Many suburban neighborhoods qualify, so it’s worth checking whether your target area is eligible before you rule it out.
How Your Credit Score Affects Your Mortgage Rate
This is where your credit score turns into real dollars. Even a small difference in your interest rate can add up to a huge amount over 30 years.
Lenders price mortgages based on risk. A higher score signals lower risk, so you get a lower rate. A lower score signals higher risk, so you pay more to offset it.
A Simple Example
Imagine two buyers each borrow $300,000 on a 30-year fixed mortgage. One has excellent credit and secures a 6.5% rate. The other has fair credit and gets 7.5%.
- Buyer A (6.5%):Roughly $1,896 per month
- Buyer B (7.5%):Roughly $2,098 per month
That’s about $202 more per month for Buyer B. Over 30 years, that difference adds up to more than $72,000 in extra interest. Same house, same loan amount, dramatically different total cost.
This is exactly why improving your score before you apply can be one of the highest-return moves you make. A few months of focused effort can translate into savings that stretch across decades.
The Takeaway
You don’t just want to qualify for a mortgage. You want to qualify at the best rate you reasonably can. Treat your credit score as a tool that directly controls your monthly payment, not just a gatekeeper for approval.
Can You Buy a House With Bad Credit?
Yes, it’s possible to buy a house with bad credit. It’s just harder, and it usually costs more. But “bad credit” isn’t a locked door. It’s a hurdle you can often clear with the right strategy.
Here’s what buying with a lower score realistically looks like:
- FHA loans become your friend.With a score as low as 500, you may still qualify with a larger down payment.
- Expect higher interest rates.Lenders offset the added risk with pricing, so your monthly payment will likely be higher.
- A bigger down payment helps.Putting more money down reduces the lender’s risk and can strengthen your application.
- A co-signer or co-borrower may help.Adding someone with stronger credit can improve your odds, though it ties them to the loan.
When to Buy Now vs. Wait
Sometimes buying now with imperfect credit makes sense, especially if you plan to refinance later once your score improves. Other times, waiting a few months to raise your score is the smarter play, because it can lower your rate for the entire loan.
Run the numbers both ways. If a short delay could move you into a better rate tier, the wait often pays for itself many times over. If home prices or your rent are climbing fast in your area, buying sooner might still make sense. There’s no one-size-fits-all answer here.
It’s Not Just Your Credit Score: Other Factors Lenders Check
Your credit score is a major piece of the puzzle, but it’s not the whole picture. Lenders evaluate your full financial health before approving a mortgage. Two other factors deserve real attention.
Debt-to-Income Ratio (DTI)
Your debt-to-income ratio compares your monthly debt payments to your gross monthly income. It tells lenders how much room you have in your budget for a mortgage payment.
Here’s a quick way to picture it. If you earn $6,000 a month and your existing debts (car loan, student loans, credit cards, and the new mortgage) total $2,400, your DTI is 40%.
Most lenders prefer a DTI of 43% or lower, though some programs allow higher. The lower your DTI, the more comfortable a lender feels, and the easier approval becomes. Paying down debt before you apply improves both your DTI and, often, your credit score. It’s a double win.
Down Payment
Your down payment affects how much you need to borrow and how a lender views your risk. A larger down payment means:
- A smaller loan amount and lower monthly payments
- Better odds of approval
- Potentially a lower interest rate
- The chance to skip PMI on a conventional loan (with 20% down)
Common minimums vary by loan. Conventional loans can go as low as 3% down for qualified buyers. FHA loans start at 3.5% with a 580 score. VA and USDA loans can require nothing down for eligible buyers.
You don’t always need the classic 20%, but more down usually strengthens your position. Balance a healthy down payment against keeping enough savings for emergencies and closing costs.
How to Improve Your Credit Before Buying a Home
If your score isn’t where you want it, don’t worry. Credit is fixable, and you can often make meaningful progress in a matter of months. Here’s a practical, step-by-step plan.
Step 1: Check Your Credit Reports for Errors
Start by pulling your credit reports from all three bureaus. You’re entitled to free copies through the official federal source, and many services now offer free weekly access.
Read each report carefully and look for mistakes, such as:
- Accounts that aren’t yours
- Payments marked late that you actually paid on time
- Duplicate accounts
- Incorrect balances or credit limits
- Old negative items that should have aged off
Errors are more common than most people realize, and a single wrong entry can drag down your score. If you find one, dispute it with the bureau. Correcting a mistake is often the fastest way to boost your number.
Step 2: Pay Every Bill on Time
Payment history is the single biggest factor in your credit score, making up roughly 35% of it. One missed payment can cause real damage, especially close to a mortgage application.
Set up automatic payments or calendar reminders so nothing slips through. If you have any past-due accounts, bring them current as soon as you can. A clean stretch of on-time payments builds momentum quickly.
Step 3: Lower Your Credit Utilization
Credit utilization is the share of your available credit you’re using. It accounts for about 30% of your score. If your cards are close to maxed out, your score takes a hit.
Aim to keep utilization below 30%, and lower is even better. A few ways to get there:
- Pay down balances aggressively before you apply
- Make a mid-month payment to reduce your reported balance
- Ask for a credit limit increase without spending more
Lowering utilization is one of the quicker ways to see your score move upward.
Step 4: Avoid Opening or Closing Accounts
In the months before applying, keep your credit profile stable. Opening a new credit card or financing a car triggers a hard inquiry and shortens your average account age, both of which can ding your score.
Closing old accounts can backfire too, since it lowers your total available credit and shortens your history. Leave your old cards open, even the ones you rarely use.
Step 5: Don’t Apply for a Mortgage Too Early
Give your efforts time to show up. Credit changes often take a full billing cycle or two to appear on your report. If you can wait three to six months while practicing these habits, you’ll likely apply with a stronger score and land a better rate.
A Realistic Timeline
Here’s what improvement often looks like:
- Month 1:Fix report errors and set up on-time payments
- Months 2–3:Pay down balances and lower utilization
- Months 4–6:Keep habits steady and watch your score climb
Consistency wins. Small, steady moves compound into a noticeably higher score, which then translates into real savings on your mortgage.
What First-Time Homebuyers Should Know
If this is your first home, the process can feel like learning a new language. A little preparation goes a long way. Here are the essentials worth knowing before you dive in.
Get Pre-Approved Before You Shop
A mortgage pre-approval tells you exactly how much a lender is willing to loan you. It’s based on a real review of your credit, income, and finances. Pre-approval helps you shop with confidence and shows sellers you’re a serious buyer.
Try to get pre-approved before you fall in love with a home. It keeps your search realistic and speeds up the process once you make an offer.
Explore First-Time Homebuyer Programs
Many states and local agencies offer programs designed to help first-time buyers. These can include down payment assistance, lower interest rates, or reduced fees. Some have more flexible credit requirements too.
It’s worth researching what’s available in your area. These programs can meaningfully lower the upfront cost of buying and make homeownership reachable sooner than you expected.
Budget Beyond the Down Payment
The purchase price is just the start. First-time buyers are often surprised by the extra costs, such as:
- Closing costs, typically 2% to 5% of the loan amount
- Home inspection and appraisal fees
- Property taxes and homeowners insurance
- Moving expenses and immediate repairs
- Ongoing maintenance
Build these into your plan so you’re not caught off guard. Keeping a cushion of savings after closing protects you from surprises in those first few months of ownership.
Shop Around for Your Mortgage
Not all lenders offer the same rates or fees. Getting quotes from several lenders can save you a surprising amount. When you shop within a short window, usually 14 to 45 days, multiple mortgage inquiries typically count as a single hard inquiry, so comparison shopping won’t tank your score.
Compare the interest rate, the annual percentage rate (APR), and the closing costs. The lowest rate isn’t always the best deal once fees are factored in.
Verify Details and Protect Your Information
Applying for a mortgage means sharing a lot of sensitive personal and financial details. It also means depending on accurate records at every step, from your identity verification to the paperwork tied to the property and the people involved in the sale.
Before handing over your Social Security number or bank information, confirm that any lender or service you work with is legitimate. Stick with reputable, well-reviewed companies, look for secure websites, and keep your own copies of everything you submit. When accuracy and privacy come first, you move through the process with far more confidence.
Putting It All Together: A Sample Buyer Journey
Let’s tie the pieces together with a realistic example.
Meet Jordan, a first-time buyer with a 640 credit score, some credit card debt, and modest savings. Here’s how Jordan might approach the goal of buying a home:
- Pull all three credit reportsand spot a wrongly reported late payment. Jordan disputes it, and the correction lifts the score a few points.
- Pay down credit cardsfrom 55% utilization to under 30% over three months. The score climbs into the 680s.
- Hold off on a new car loanto keep the credit profile stable before applying.
- Calculate DTIand pay off a small loan to bring it under 43%.
- Get pre-approvedand discover eligibility for a conventional loan at a better rate than expected.
- Shop three lenderswithin two weeks and choose the one with the lowest total cost.
By taking a few months to prepare, Jordan moves from a borderline applicant to a confident buyer with a stronger rate. That’s the power of understanding how credit fits into the homebuying process.
You can follow a similar path. The exact steps depend on your starting point, but the principle holds: preparation pays.
Frequently Asked Questions
What credit score do you need to buy a house?
It depends on the loan. FHA loans can start as low as 500 with a larger down payment, while conventional loans usually require 620. To secure the best mortgage rates, aim for a score of 740 or higher. Even a fair score in the 580–669 range qualifies for many programs.
What is the minimum credit score to buy a house?
Around 500 is the lowest commonly accepted score, available through FHA loans with a 10% down payment. With 3.5% down, FHA typically requires 580. Conventional loans generally start at 620. VA and USDA loans set no official minimum, but lenders often look for 580 to 640.
What credit score do I need for an FHA loan?
You need a score of at least 580 to qualify for an FHA loan with the low 3.5% down payment. If your score falls between 500 and 579, you may still qualify, but lenders usually require a 10% down payment to offset the added risk.
What is the minimum credit score for a conventional loan?
620 is the typical minimum for a conventional loan. A score between 620 and 679 can get you approved, though at higher rates. Scores of 680 to 739 earn better pricing, and 740 or above unlocks the most competitive rates and terms available.
Do VA and USDA loans have a minimum credit score?
No official minimum is set by the VA or USDA. However, the private lenders who issue these loans do set their own thresholds. In practice, many look for a score around 580 to 620 for VA loans and about 640 for USDA loans.
Can you buy a house with bad credit?
Yes, but it’s harder and usually costs more. FHA loans allow scores as low as 500 with a bigger down payment. Expect higher interest rates to offset the risk. A larger down payment or a co-borrower with stronger credit can also improve your approval odds.
How does my credit score affect my mortgage rate?
Higher scores earn lower rates because they signal less risk to lenders. On a $300,000 loan, a single percentage point difference can add over $70,000 in interest across 30 years. Improving your score before applying can save you a significant amount over time.
How much of a down payment do I need to buy a house?
You don’t need 20%. Conventional loans can start at 3% down, and FHA loans at 3.5% with a 580 score. VA and USDA loans may require nothing down for eligible buyers. Putting 20% down does help you skip private mortgage insurance on a conventional loan.
What debt-to-income ratio do lenders want?
Most lenders prefer a debt-to-income (DTI) ratio of 43% or lower. Your DTI compares your monthly debt payments to your gross monthly income. Paying down debt before you apply lowers your DTI and often boosts your credit score at the same time.
How can I improve my credit score before buying a home?
Start by checking your credit reports for errors and disputing any you find. Then pay every bill on time, lower your credit card balances below 30% utilization, and avoid opening or closing accounts. Many buyers see meaningful progress within three to six months of steady effort.
Final Thoughts: Know Your Number, Then Take Action
So, what credit score do you need to buy a house? Enough to qualify for a loan that fits your situation, and ideally high enough to earn a competitive rate. For many buyers, that means a score of at least 580 to 620, with 740 and above unlocking the best deals.
But your score is only part of the story. Your debt-to-income ratio, your down payment, and your overall financial stability all play a role. The good news is that every one of these factors is something you can improve with a bit of planning.
Here’s your simple action plan:
- Check your credit reportsand fix any errors you find.
- Pay every bill on timeand lower your credit card balances.
- Reduce your debtto strengthen your debt-to-income ratio.
- Save for a down paymentand closing costs.
- Get pre-approvedand shop multiple lenders for the best deal.
Buying a home is a big step, but it’s far more manageable when you understand the numbers behind it. Take a little time to prepare, and you’ll walk into the process with confidence, clarity, and a real shot at the best possible mortgage. Your future home is worth it.