Author: Peter Krakue

  • How Long Does Credit Repair Actually Take?

    How Long Does Credit Repair Actually Take?

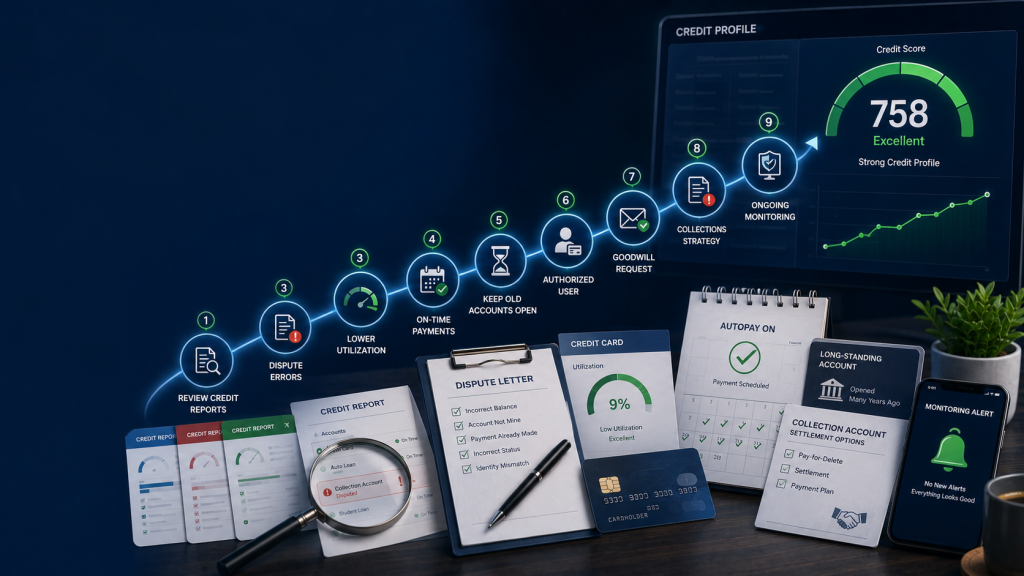
    While you wait, take action now: learn exactly how to file a credit dispute and what happens at each stage, use the fastest methods to build positive credit history in parallel, see our step-by-step credit repair process to know exactly what a professional does for you, and get 9 credit repair tips you can use today while the dispute process runs.

    If you’re working on your credit, one question probably comes up pretty quickly: how long does credit repair take? There isn’t a set answer. It really depends on what’s hurting your credit and how much needs to be fixed.

    Some credit report errors can be investigated and corrected within about 30 days. Improving a credit score after high balances, missed payments, or other legitimate negative information can take several months or longer. The key is understanding the difference between correcting credit report errors and rebuilding your credit history.

    How Long Does Credit Repair Take?

    For many people, credit repair is a process that takes a few months to see noticeable progress, while more serious credit problems can take much longer.

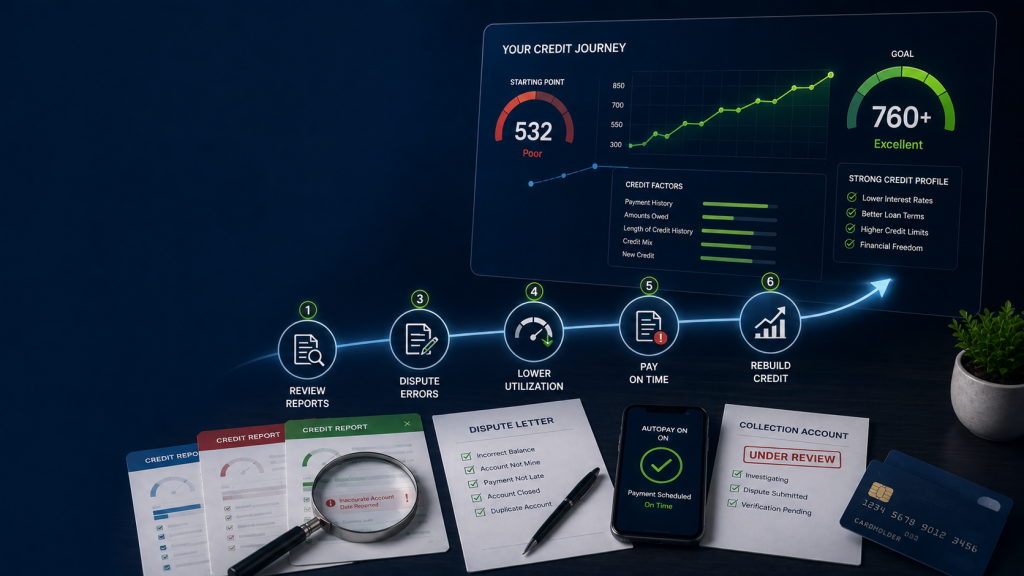
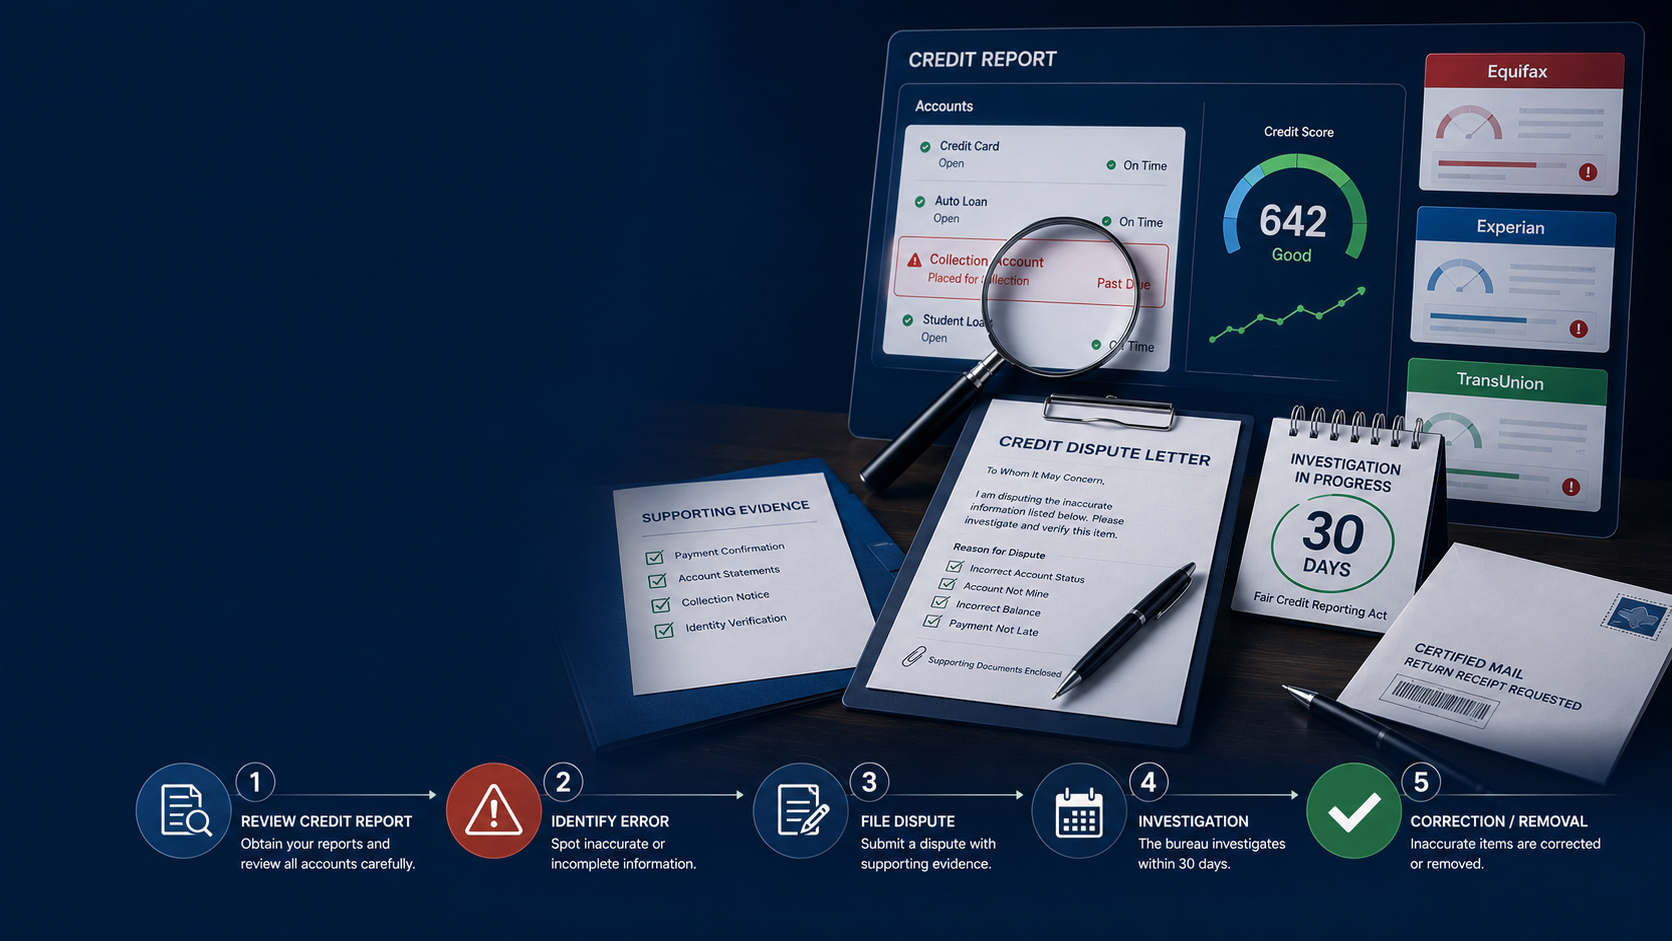
    If you are disputing inaccurate information, the process can move relatively quickly. Credit reporting companies generally have 30 days to investigate a dispute. In certain situations, the investigation can take up to 45 days.

    But correcting an error does not automatically mean your entire credit score will increase dramatically. Your score is based on multiple factors, including payment history, amounts owed, length of credit history, new credit, and credit mix.

    If your credit report is accurate but your score is low because of high balances or a history of missed payments, the timeline is different. You are rebuilding your credit rather than simply correcting an error.

    How Long Does It Take to Repair Credit Score?

    If you are wondering how long does it take to repair credit score, a realistic starting point is around three to six months for noticeable improvement, assuming you are consistently taking positive steps.

    FICO notes that people may begin seeing small score changes within three to six months, although significant improvements can take longer depending on the situation.

    Your timeline could be shorter if your main problem is high credit card utilization and you reduce your balances. It could be much longer if your report contains multiple late payments, collections, charge-offs, or other serious negative information.

    That is why a promise such as “we will increase your score by 100 points in 30 days” should be treated with caution.

    Read More: Can You Fix Your Own Credit for Free?

    Credit Repair Timeline: What to Expect

    The timeline usually depends on the type of problem you are trying to address.

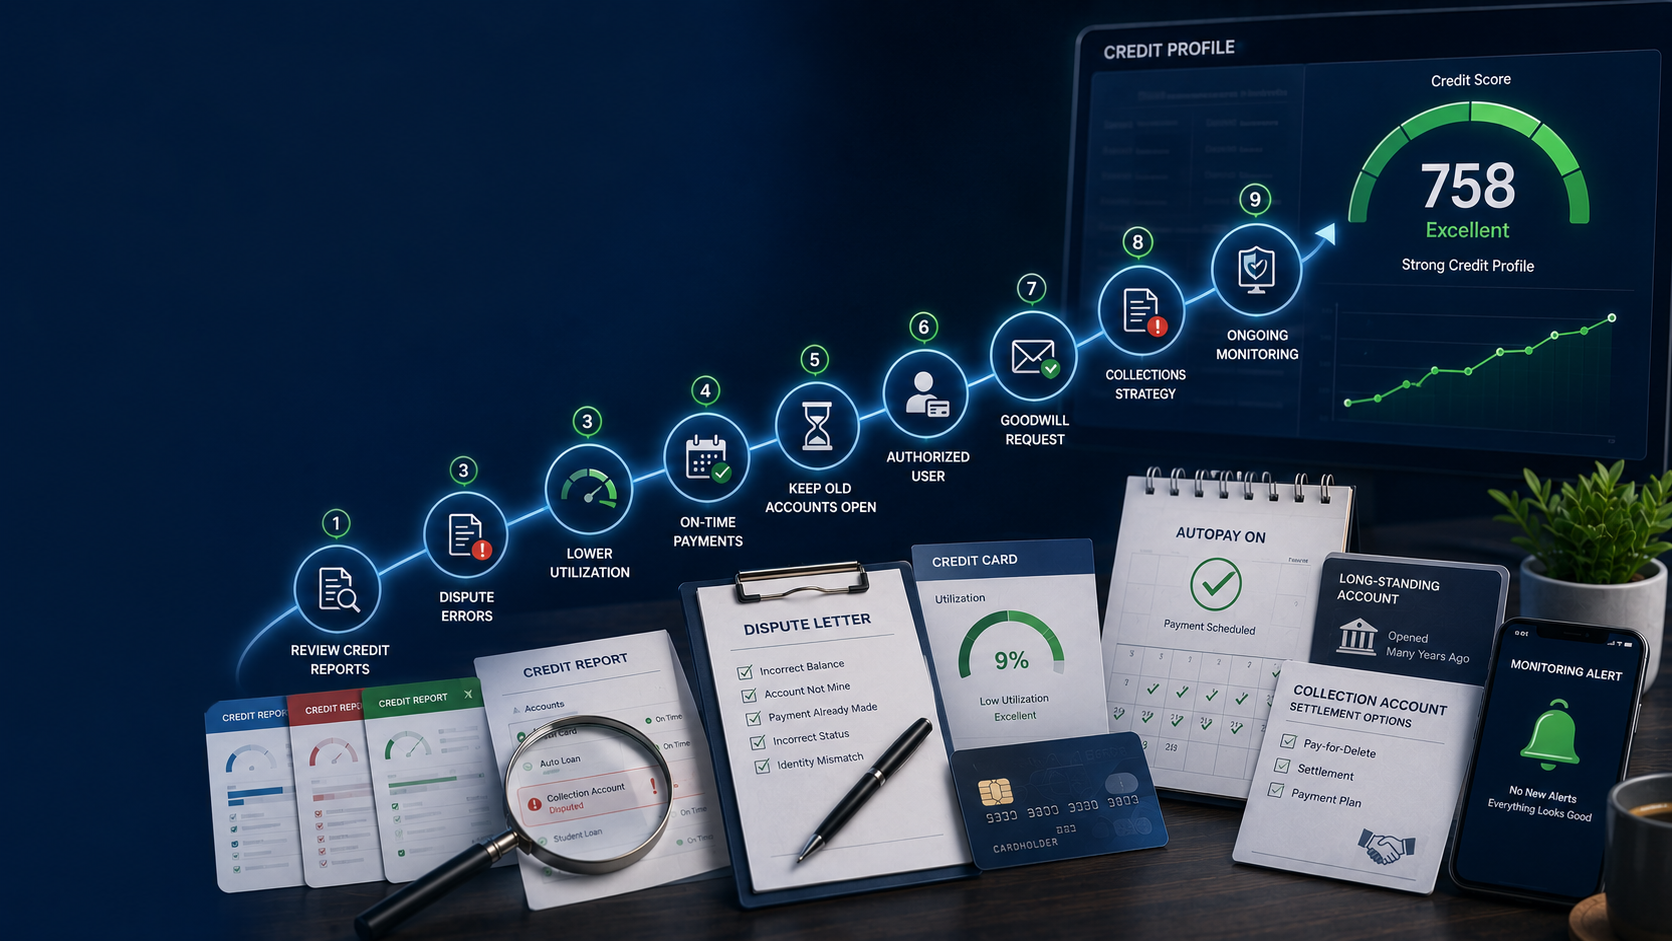
    1. Reviewing Your Credit Reports: A Few Days

    The first step is getting copies of your credit reports from the major credit reporting companies and reviewing them carefully.

    Look for incorrect personal information, accounts you do not recognize, duplicate accounts, inaccurate balances, incorrect payment history, and other information that does not belong on your report.

    This step can be completed fairly quickly, but finding every potential error may take more time.

    2. Disputing Credit Report Errors: About 30–45 Days

    If you find inaccurate information, you can dispute it with the credit reporting company and the company that furnished the information.

    Generally, a credit reporting company must investigate a dispute within 30 days. Some disputes can take up to 45 days, depending on the circumstances.

    If the information is found to be inaccurate, it should be corrected or removed. You should then review your updated report to make sure the change was properly reflected.

    3. Lowering Credit Card Balances: Potentially a Few Months

    High credit card utilization can affect your credit scores. Paying down revolving balances can help your score once the lower balances are reported.

    The exact improvement varies from person to person. Someone who is using most of their available credit may see a more noticeable change after reducing their balances, while someone with other major negative factors may need more time.

    The important part is consistency. Paying balances down once is helpful, but maintaining responsible credit use is what supports long-term improvement.

    4. Rebuilding After Late Payments: Several Months or Longer

    Late payments can be more difficult because accurate negative information generally cannot simply be removed.

    If a late payment is accurate, a legitimate credit repair company cannot legally erase it just because you want it gone. The FTC warns that companies cannot remove accurate and current negative information from your credit report.

    Instead, the focus should be on establishing a new pattern of on-time payments. As more positive payment history is reported, your overall credit profile can gradually improve.

    5. Recovering From Collections or Charge-Offs: Longer-Term

    Collections, charge-offs, and other serious negative accounts can make credit recovery more complicated.

    If the information is inaccurate, incomplete, duplicated, or does not belong to you, disputing it may lead to a correction. If the information is accurate, however, it generally cannot be legally removed simply because it hurts your score.

    Most accurate negative information can remain on a credit report for up to seven years, although the impact on your credit score can change over time.

    What Can Make Credit Repair Faster or Slower?

    The biggest factor is what needs to be repaired. Someone with one inaccurate collection account may have a much shorter timeline than someone with several years of missed payments and high balances.

    Your timeline can also depend on:

    • How many errors are on your credit reports
    • How quickly disputes are submitted
    • How quickly furnishers respond
    • Your current credit utilization
    • The number and age of negative accounts
    • Your payment history
    • How consistently you make payments going forward
    • How often your creditors report updated information

    This is why there is no universal answer to how long credit repair takes.

    Can Credit Repair Raise Your Score in 30 Days?

    It is possible to see a score change within 30 days in some situations, but that does not mean your credit has been fully repaired.

    For example, correcting a significant reporting error or lowering a high credit card balance may produce a relatively quick change. But rebuilding a damaged credit history generally requires more time.

    Be especially careful with companies that guarantee a specific score increase within a specific number of days. Legitimate credit repair cannot guarantee that an inaccurate item will be removed or that your score will increase by a certain number of points.

    The FTC specifically warns consumers about credit repair companies that make promises to remove accurate negative information or guarantee results.

    Read More: How much does credit repair cost

    How to Speed Up the Credit Repair Process

    You cannot control every part of the process, but you can avoid unnecessary delays. Start by reviewing all three credit reports and identifying the problems that are actually affecting your profile. Dispute legitimate inaccuracies with the appropriate credit reporting companies and furnishers, and keep copies of your documentation.

    At the same time, focus on the factors you can control. Pay every bill on time, reduce credit card balances, avoid unnecessary new applications, and monitor your reports regularly.

    The goal should not be to find a shortcut. It should be to correct genuine errors and build stronger credit habits that continue helping you after the initial repair process is finished.

    Is Credit Repair Worth It?

    Credit repair can be useful when your credit reports contain legitimate errors that need to be challenged. However, you do not necessarily need to hire a credit repair company to dispute inaccurate information.

    You have the legal right to dispute inaccurate information yourself, generally at no cost. The CFPB also notes that consumers can dispute inaccuracies directly with credit reporting companies and furnishers.

    If you decide to work with a credit repair company, look for transparency about what it can actually do. Avoid any company that asks you to dispute information you know is accurate, tells you to create a new credit identity, or promises to permanently erase accurate negative information.

    Read More: How does credit repair work

    How Long Does Credit Repair Actually Take?

    So, how long does credit repair take? For simple credit report errors, you may see results in roughly 30 to 45 days. For broader credit improvement, expect a longer process, often several months or more.

    The fastest approach is not chasing quick fixes. Review your reports, dispute legitimate errors, pay your bills on time, manage your balances, and give your credit history time to improve.

    Ready to take the first step? Start by reviewing your credit reports and identifying exactly what is holding your credit back.

  • Can You Remove a Foreclosure From Your Credit Report Early?

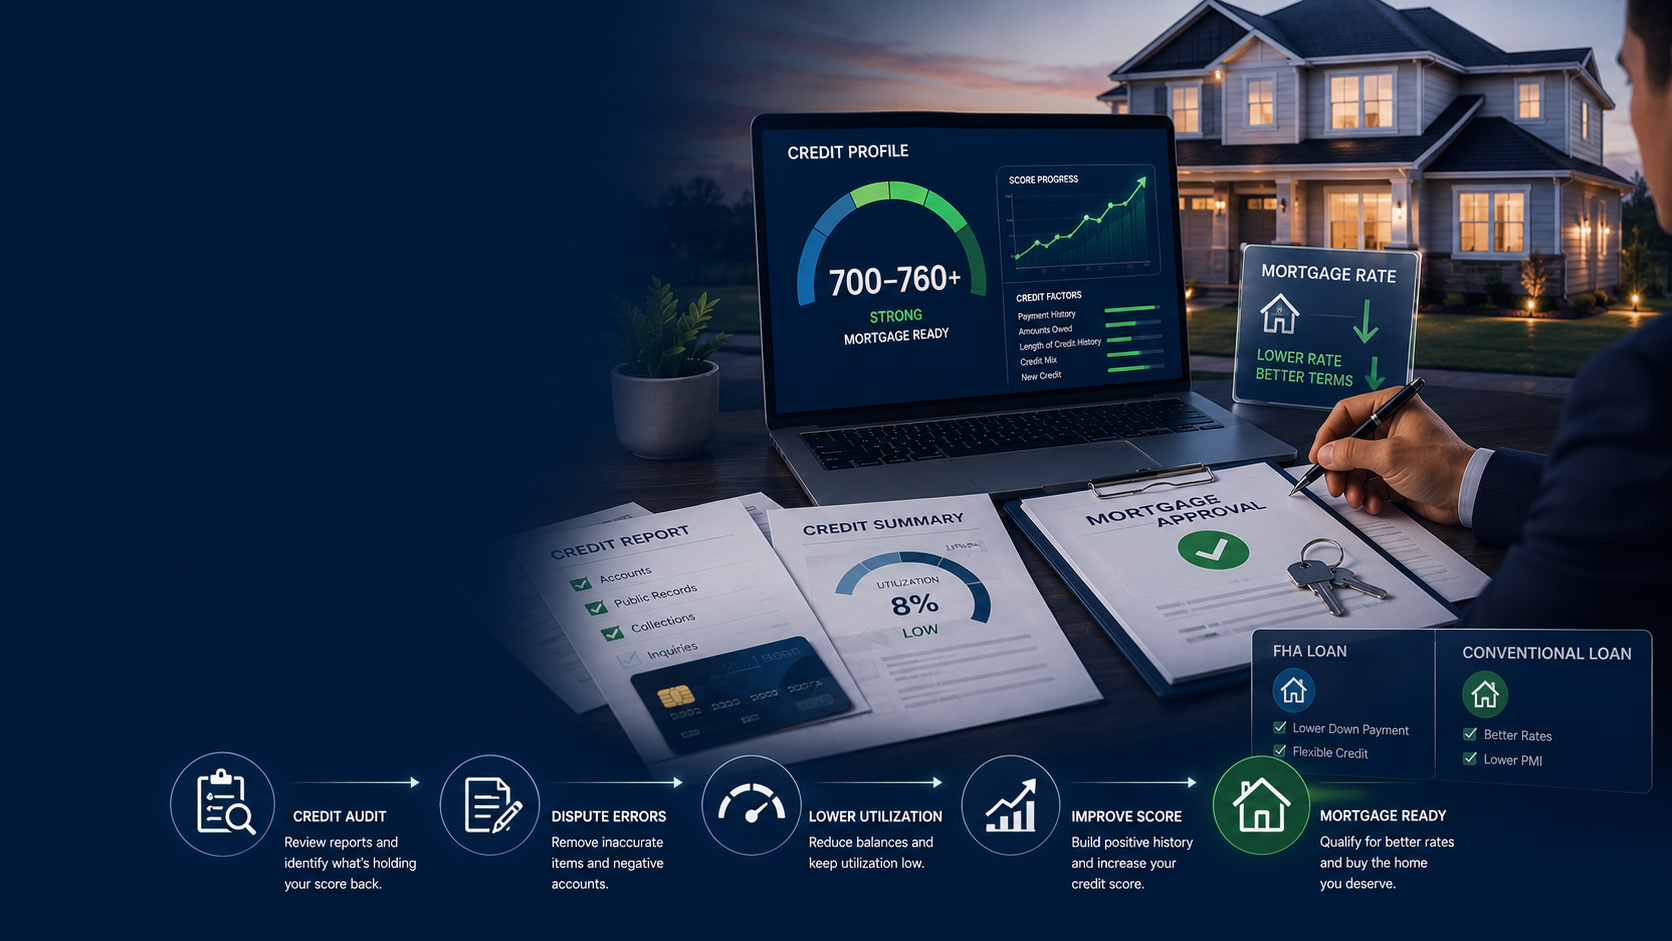
    Next steps: learn exactly how to file a credit dispute step by step, check if there are additional credit report errors on all three bureaus holding your score down, try a goodwill letter to address related late payment history, and see our guide on credit repair before applying for a mortgage if you’re working toward homeownership again.

    A foreclosure is one of the most severe marks a credit report can carry — heavier than almost any other negative item short of a bankruptcy — and it’s natural to want it gone as soon as possible. The honest answer is that removing it “early” in the sense of before its natural reporting window closes is difficult, but not impossible, and there are real strategies that can either shorten the practical impact or, in some cases, get the entry corrected or deleted outright. This article walks through what’s actually achievable and what isn’t.

    ## How Long a Foreclosure Normally Stays on Your Report

    A foreclosure is reported for seven years from the date of first delinquency on the mortgage that led to it — not from the date the foreclosure was finalized, and not from the date the home was sold at auction. This distinction matters enormously, because people often assume the clock starts at the foreclosure sale, when in reality it usually starts months or even a year or more earlier, back when the very first missed mortgage payment occurred.

    If you’re trying to figure out when a foreclosure will fall off your report, the first thing to do is identify that original delinquency date precisely — not the foreclosure filing date, not the sale date, not the date the deficiency was resolved.

    ## Why “Early Removal” Is Genuinely Hard

    Unlike some smaller negative items, a foreclosure is usually well-documented by the lender, with a clear paper trail: missed payments, notices of default, foreclosure filings, and often a public record component through the county court system. That combination of thorough documentation and public record backing makes it one of the harder items to dispute successfully on the grounds of “this shouldn’t be here” — because in most cases, factually, it should be.

    That said, “hard” doesn’t mean impossible. There are a few legitimate paths.

    ## Path 1: Dispute Factual Inaccuracies

    Even accurate foreclosures often have inaccurate details attached, and those details are disputable even when the underlying foreclosure itself isn’t:

    – **Incorrect date of first delinquency.** If the reported date is later than the actual first missed payment, it could be extending your reporting window illegally. Conversely, if it’s been misreported as later than it should be by the furnisher, you actually want that corrected too — but check carefully, because a later date benefits you (shorter remaining time) while an earlier true date might mean you’re closer to seven years than you thought.
    – **Incorrect balance or deficiency amount** reported after the sale.

    – **Duplicate reporting** — sometimes both the original mortgage servicer and the entity that eventually completed the foreclosure report separate, overlapping entries for what’s really one event.
    – **Reporting after a loan modification was actually granted** — if you were approved for a modification or forbearance that should have prevented foreclosure, and it proceeded anyway due to a servicer error, that’s a serious and disputable issue, and one that’s occurred often enough in mortgage servicing scandals over the past decade that documentation requests are taken seriously by regulators.

    ## Path 2: Goodwill Requests to the Servicer

    This is a long shot for foreclosures specifically — lenders are far less likely to grant goodwill removal on a foreclosure than on a smaller item like a single late payment, given the size of the loss involved. That said, it’s worth trying if:

    – The foreclosure was resolved through a **short sale or deed-in-lieu** rather than a full foreclosure auction, since those situations sometimes have more room for negotiated reporting outcomes if it wasn’t already agreed to at the time.
    – You have documentation of a **specific hardship** (major medical event, job loss tied to a mass layoff, a natural disaster affecting the property) and can show the lender didn’t offer or properly process available hardship assistance programs you were eligible for at the time.

    ## Path 3: Rebuilding Around the Foreclosure Rather Than Removing It

    For most people, the realistic strategy isn’t removal — it’s minimizing the foreclosure’s ongoing weight on your score while you wait out the clock. This matters because a foreclosure’s score impact isn’t static; it fades over time even while it’s still listed, and it fades faster the more positive, active credit history you build alongside it.

    Concrete steps that measurably help:

    – **Get a secured credit card and use it lightly, paying in full every month.** New, perfectly-managed accounts start outweighing older negative marks in most scoring models within about a year or two of consistent use.
    – **Become an authorized user on a family member’s long-standing, well-managed account**, if available — this can add years of positive history to your file relatively quickly.
    – **Avoid any new derogatory marks.** A foreclosure combined with subsequent late payments or collections resets the “recovery clock” scoring models effectively apply — lenders and scoring algorithms weight recent behavior heavily, so a completely clean record for the 12–24 months following a foreclosure does a lot of the recovery work.
    – **Keep credit utilization low** on whatever revolving credit you do have access to; this is one of the fastest-moving score factors and can meaningfully offset the drag from a foreclosure while you wait it out.

    ## What About FHA and Conventional Mortgage Waiting Periods?

    Separate from the credit report itself, most mortgage programs have specific waiting periods after a foreclosure before you’re eligible for a new loan — often three years for FHA loans and up to seven years for conventional loans, though these can be shortened with documented extenuating circumstances (job loss, medical crisis, divorce) under many lenders’ “extenuating circumstances” exception policies. If your goal is really “when can I buy a house again” rather than strictly “when does this come off my report,” it’s worth researching your target loan program’s specific waiting period and exception criteria directly, since those timelines don’t always match the seven-year credit reporting window.

    ## Statute of Limitations on Any Remaining Deficiency

    In states that allow deficiency judgments after foreclosure (not all do — some are non-recourse states where the lender can’t pursue you for the difference), that deficiency debt is subject to your state’s statute of limitations for written contracts, similar to other secured debt. If you’re being pursued for a deficiency balance, that’s a separate legal and credit-report issue from the foreclosure entry itself, and worth addressing with a consumer attorney if the amount is significant.

    ## When to Get Professional Help

    If you believe your foreclosure involved genuine servicer misconduct — wrongful foreclosure while a modification was pending, dual-tracking violations, improper notice — this moves beyond a standard credit dispute into potential legal claims against the servicer, and it’s worth consulting a consumer protection or foreclosure defense attorney rather than trying to resolve it purely through the credit bureau dispute process. Many such attorneys work on contingency or offer free consultations specifically because servicer violations during the post-2008 mortgage crisis era created a well-established body of case law and regulatory enforcement precedent.

    ## Realistic Timeline Expectations

    – **Factual disputes** (wrong dates, duplicate entries): standard 30-day bureau investigation window, though foreclosures often take the full window given the documentation involved.
    – **Goodwill requests**: no guaranteed timeline, and a low overall success rate compared to smaller negative items.
    – **Score recovery through rebuilding**: most people see meaningful score improvement within 12–24 months of consistent positive behavior post-foreclosure, even though the item itself remains listed for the full seven years.

    ## The Bottom Line

    True “early removal” of an accurate foreclosure is rare — the documentation trail behind most foreclosures is thorough enough that a dispute based purely on “please remove this” won’t succeed. Your realistic leverage points are factual errors in the reporting details, potential servicer misconduct if it applies to your situation, and — for most people — an active rebuilding strategy that reduces the foreclosure’s practical weight on your creditworthiness well before the seven-year mark actually arrives.

  • How to Dispute a Late Payment That Wasn’t Your Fault

    See also: if the late payment was legitimate, a goodwill letter may get it removed anyway; learn the full credit dispute process for when the payment truly wasn’t your fault; see every credit repair letter type and when to use each; and understand what score range you’re targeting after the removal.

    A single late payment can knock a surprising number of points off an otherwise strong credit score — sometimes more damage than a much larger negative item, simply because it signals a break in an otherwise reliable pattern. When that late payment happened because of something outside your control — a bank error, a lender’s processing delay, autopay that silently failed, a natural disaster — it’s worth fighting, and there are more paths to success than most people realize.

    ## Why “Not My Fault” Isn’t Enough on Its Own

    Credit bureaus and furnishers don’t remove accurate information just because there’s a sympathetic story behind it. A dispute needs to rest on one of a few concrete grounds:

    – The payment was **actually received on time** but processed or reported late by the lender.
    – There’s a **documented service disruption** (mail delay, bank system outage, natural disaster relief provisions).
    – The **due date itself was miscommunicated** — for example, a statement that arrived after the due date had already passed.
    – The account was in an **error state**, like an autopay that failed due to a bank system issue rather than insufficient funds.

    If your situation fits one of these, you have real leverage. If it’s simply “I forgot” or “I didn’t realize,” a goodwill letter — not a dispute — is the more honest and more effective route (more on that below).

    ## Step 1: Gather Proof of Timely Payment

    This is the single most important step. Before writing anything, pull together:

    – Bank statements or online banking screenshots showing the payment date and confirmation.
    – Any confirmation email or number from the payment itself.
    – If it was a check, proof of mailing date (postmark, if you have it) relative to the due date.
    – Screenshots of your account showing the due date at the time, especially if the lender later changed billing cycles.

    Without this, you’re asking the furnisher to take your word for it, which almost never results in removal.

    ## Step 2: Determine Whether to Dispute or Ask for Goodwill

    These are different tools for different situations:

    **Dispute** (formal, rests on factual inaccuracy):
    – Use when you have evidence the reporting itself is wrong — payment was on time, or the date reported is incorrect.

    – Goes through the formal FCRA dispute process with the credit bureau or directly with the furnisher.
    – The furnisher must investigate and respond within 30 days.

    **Goodwill adjustment** (informal, rests on your relationship and history):
    – Use when the late payment is accurate, but you have an otherwise strong payment history and a specific, honest explanation (illness, job loss, a one-time slip after years of on-time payments).
    – No formal investigation obligation — it’s entirely at the lender’s discretion.
    – Works best with original creditors you have an ongoing relationship with, not collection agencies.

    Trying to “dispute” something that’s actually accurate, hoping the furnisher won’t bother verifying it, sometimes works short-term but is a fragile strategy — accurate information that gets temporarily removed due to non-response can be re-added once the furnisher catches up, and a pattern of unfounded disputes can also get flagged.

    ## Step 3: File the Dispute (If You Have Grounds)

    Send your dispute in writing to both:

    1. **The furnisher directly** (the bank or lender) — under FCRA Section 623, furnishers have a legal obligation to investigate disputes sent directly to them, not just ones routed through a bureau.
    2. **Each credit bureau reporting the late payment.**

    Include:
    – The specific date in question and what the report currently shows versus what actually happened.
    – Your supporting documentation.
    – A clear, specific request: correction of the late payment status, not a vague “please fix my credit.”

    ## Step 4: Escalate If the Investigation Comes Back Wrong

    If the furnisher “verifies” the late payment despite your evidence — which happens more than it should, often because the investigation is a quick automated check rather than a human review — you have a few options:

    – **Request the method of verification.** Under FCRA, you can ask the bureau what specific method was used to verify the disputed information. A furnisher that can’t describe an actual investigation process is on shaky legal ground.
    – **File a complaint with the CFPB.** Consumer Financial Protection Bureau complaints go directly to the company and require a response, and they tend to get more serious attention than a standard dispute, especially for federally regulated banks.
    – **File a complaint with your state Attorney General’s consumer protection office**, particularly useful for state-chartered banks and credit unions not directly under CFPB’s primary jurisdiction.

    ## Step 5: If All Else Fails, Try a Goodwill Letter

    Even if a formal dispute doesn’t work, a goodwill letter is worth sending afterward. Keep it short, specific, and free of exaggeration:

    – State the account, the date, and your otherwise consistent payment history.
    – Briefly explain the circumstance (bank error, processing delay) without being adversarial — you’re asking for a courtesy, not arguing a legal case at this point.
    – Ask specifically for the late payment mark to be removed or adjusted, not for the whole account to be deleted.

    Goodwill letters have no guaranteed success rate and depend heavily on the individual lender’s policies — some have specific goodwill adjustment programs, others don’t entertain them at all — but they cost nothing to send.

    ## Special Case: Natural Disasters and Documented Emergencies

    If the late payment happened during a federally declared disaster area event, many lenders have specific disaster relief provisions that include suppressing negative credit reporting for affected accounts, sometimes automatically and sometimes only on request. Check whether your lender has a disaster relief program and whether your account should have already been covered — if it should have been and wasn’t, that’s a straightforward correction request, not really even a dispute in the adversarial sense.

    ## What to Expect for Timing

    – Standard FCRA disputes: bureaus have 30 days to investigate and respond (45 days if you submit additional information mid-investigation).
    – CFPB complaints: companies typically respond within 15 days, though full resolution can take longer.
    – Goodwill letters: no formal timeline — expect anywhere from a couple of weeks to no response at all.

    ## The Bottom Line

    A late payment that genuinely wasn’t your fault is fixable, but “wasn’t my fault” needs to translate into something concrete — proof of on-time payment, a documented system error, or a lender’s own disaster relief policy — before a dispute has real teeth. When you don’t have that kind of hard evidence, a goodwill request based on an honest, specific explanation and a track record of reliability is usually the better and more successful path than trying to force a formal dispute on accurate information.

  • How to Get a Repossession Removed From Your Credit Report

    Related guides: understand whether paying off a charge-off removes it (the same question applies to repo deficiency balances), learn how to remove the resulting collection account that often follows a repossession, see if pay-for-delete is an option with the collection agency, and dispute inaccuracies using our guide to filing a credit dispute.

    A repossession is one of the more complicated negative marks to deal with because it usually isn’t just one line item — it’s often a cluster: the repo itself, a “charged-off” balance for whatever the car didn’t cover when resold, and sometimes a separate collection account for that deficiency balance. Understanding how the pieces fit together is the first step to actually getting any of it removed.

    ## Understanding What’s Actually Being Reported

    When a vehicle (or other financed asset) is repossessed, several things typically happen to your credit file:

    1. The auto loan account is updated to show **”repossession”** as the status.
    2. The lender sells the vehicle at auction, usually for less than what’s owed.
    3. The **deficiency balance** (what’s left after the sale) either stays with the original lender as a charged-off amount, or gets sold to a collection agency.
    4. If sold, a **new collection account** may appear separately from the original auto loan tradeline.

    So it’s common to see what feels like the same debt reported twice — once as a repossessed auto loan, once as a collection account for the deficiency. That’s not automatically an error (it can be legitimate), but it’s worth checking for duplication or inconsistency between the two entries, since discrepancies there are a common and legitimate basis for dispute.

    ## Step 1: Determine Whether It Was Voluntary or Involuntary

    This matters for both practical negotiation and psychological framing, but not really for the credit report itself — both types report similarly and are equally damaging to your score. What it does affect is your leverage: if you voluntarily surrendered the vehicle and cooperated with the lender, you likely have a better relationship to work with when requesting a goodwill adjustment or negotiating a deficiency settlement.

    ## Step 2: Pull the Details and Check for Errors

    Look closely at:

    – **The date of first delinquency** — this is what starts the 7-year removal clock, not the repossession date itself, and not the date any deficiency balance was later sold to collections. A collector re-reporting the same debt with a new, later date is illegal re-aging and is one of the more common — and most disputable — errors in repo reporting.
    – **The reported balance** — does it reflect the actual deficiency after the sale, or is it inflated with fees that weren’t properly disclosed?
    – **Whether the loan and the collection account show consistent information** — same original creditor name, same original balance before any partial payments, same date of first delinquency.

    ## Step 3: Request Proof of Sale

    Under most state laws governing repossession, the lender is required to notify you of the sale and provide an accounting of how the sale proceeds were applied against your balance. If you never received this notice, or the lender can’t produce it now, that’s leverage — both for disputing the deficiency amount and, in some states, for challenging whether the deficiency is even collectible at all.

    Ask the lender or collector, in writing, for:

    – The date and method of sale (auction vs. private sale)
    – The sale price
    – An itemized accounting of fees added (repossession costs, storage, auction fees)
    – Proof that you were properly notified before the sale, per your state’s requirements

    If proper notice wasn’t given, many states either reduce or eliminate the deficiency balance entirely — which, if successful, gives you grounds to have the debt corrected or removed from your report.

    ## Step 4: Dispute Inaccuracies With the Bureaus

    Once you’ve identified something concrete — wrong dates, inflated balance, improper notice, duplicate reporting — file a dispute with each bureau reporting the item. As with other disputes, specificity wins: cite the exact discrepancy rather than a general “this isn’t right.”

    ## Step 5: Consider Goodwill for a Voluntary Repo With Good History

    If you had a strong payment history before the circumstances that led to repossession (job loss, medical emergency, etc.) and you’ve since paid off the deficiency, a goodwill letter to the original lender — not the collection agency — can occasionally result in the repo being removed as a courtesy. This is a long shot but costs nothing to try, and lenders you’ve had other accounts with (checking, savings, other loans) are more likely to accommodate it.

    ## What About Paying the Deficiency Balance?

    Same rule as with any charge-off: paying it changes the status to “paid,” which matters somewhat to manual underwriters and newer scoring models, but doesn’t remove the repossession or deficiency entry itself unless you negotiate a pay-for-delete arrangement in writing beforehand.

    If you’re going to pay, negotiate first. Deficiency balances after repossession are often sold to collectors for pennies on the dollar, which means there’s usually real room to settle for significantly less than the stated balance — and if you’re going to pay anything, it’s worth asking for removal as part of the deal rather than just a lower number.

    ## Statute of Limitations Considerations

    Repossession deficiency debt is subject to your state’s statute of limitations on debt collection, typically ranging from 3 to 6 years depending on the state and whether the original contract was written or oral (auto loans are written contracts, which usually get a longer statute of limitations than open-ended credit). If you’re outside that window, a collector can still ask you to pay, but generally can’t successfully sue you for it — though be careful, because making even a partial payment on time-barred debt can restart the clock in many states.

    ## Realistic Timeline

    – **Duplicate reporting or clear date errors**: resolvable in a standard 30-day dispute cycle.
    – **Improper notice disputes**: can take longer, especially if you need to formally request sale documentation from the lender first — budget 60–90 days.
    – **Goodwill requests**: no guaranteed timeline; some lenders respond in weeks, others take months or don’t respond at all.

    ## The Bottom Line

    A repossession is rarely a single clean fix — it usually involves checking two or three separate report entries against each other and against your state’s repossession notice requirements. The strongest angle isn’t emotional appeal, it’s procedural: lenders who skip proper notice steps, misreport dates, or double-report a debt give you concrete, disputable grounds, and that’s a much stronger position than simply asking for forgiveness.

  • Does Paying Off a Charge-Off Remove It From Your Credit Report?

    Next steps: negotiate removal by learning how pay-for-delete works with collectors, check the statute of limitations on the debt before deciding whether to pay, learn to remove the related collection account from your report, and see our full credit repair procedure if you want professional help addressing multiple negatives at once.

    This is one of the most common misconceptions in personal finance, and it trips up even people who are otherwise financially savvy: paying off a charged-off account does **not** automatically remove it from your credit report. It’s a distinction that matters a lot if you’re trying to decide how to spend limited money on debt repayment, so it’s worth understanding exactly what paying a charge-off does and doesn’t do.

    ## What a Charge-Off Actually Is

    A charge-off happens when a creditor decides an account is unlikely to be collected through normal means — typically after 180 days of non-payment — and writes it off as a loss for accounting purposes. This is an internal accounting decision by the creditor, not a legal forgiveness of the debt. You still owe the money. The creditor (or whoever they sell the debt to) can still pursue collection, and in most states, can still sue you for it within the statute of limitations.

    The charge-off itself gets reported to the credit bureaus as a status on the account, and it’s one of the more damaging marks on a credit report — second really only to a bankruptcy or foreclosure in terms of scoring impact.

    ## Why Paying It Off Doesn’t Erase It

    Here’s the part that surprises people: paying a charge-off changes the account’s **status** from “unpaid charge-off” to “paid charge-off,” but the charge-off itself — the fact that the account went unpaid long enough to be written off — remains on your report for seven years from the original date of delinquency.

    Think of it less like erasing a stain and more like changing the label on it. “Charge-off, paid” is better than “charge-off, unpaid,” but both say charge-off.

    That said, “paid” does matter in a few concrete ways:

    – **Lenders reviewing manually** (mortgage underwriters, for instance) generally view a paid charge-off more favorably than an unpaid one, even if the score impact is similar.
    – **Some newer scoring models** (FICO 9 and later, VantageScore 3.0 and later) treat paid collections and charge-offs somewhat less harshly than older models still used by some lenders.
    – **It stops the debt from being sold again.** An unpaid charge-off is often sold to a new collector, which can result in a fresh collection account appearing on your report — effectively re-aging the negative mark in the eyes of anyone glancing at your file, even though the legal reporting clock (7 years from original delinquency) doesn’t actually reset.

    ## When Paying Makes Sense — and When It Doesn’t

    **Paying makes sense if:**

    – You’re within the statute of limitations and want to avoid a lawsuit or wage garnishment.
    – You’re applying for a mortgage soon and the underwriter requires paid or resolved collections.
    – You can negotiate a pay-for-delete arrangement (see below) — this is the one scenario where payment can result in outright removal.
    – The debt is still with the original creditor and you want to preserve a relationship (e.g., a bank you want to keep doing business with).

    **Paying may not be worth it if:**
    – The debt is old and close to falling off your report naturally (within a year or so of the 7-year mark) — paying it now won’t change the fall-off date, and it might reset how recently the account shows activity in some models.
    – You’re outside the statute of limitations and the debt is unlikely to be collected on anyway. Paying could restart the clock on the statute of limitations in some states, actually increasing your legal risk.
    – You don’t have documentation confirming exactly who owns the debt and how much is owed — paying the wrong party doesn’t extinguish the original creditor’s claim.

    ## The One Way Paying Can Get It Removed: Pay-for-Delete

    A pay-for-delete arrangement is where you negotiate with the collector, in writing, before you pay: in exchange for payment, they agree to request the account’s removal from your credit report entirely, rather than just updating it to “paid.”

    A few important realities about pay-for-delete:

    – **It’s not guaranteed to work even after they agree.** The collector requests deletion from the bureau, but the bureau isn’t obligated to honor it, and increasingly, bureaus have started pushing back on pay-for-delete requests specifically because they’re seen as manipulating the accuracy of credit files.
    – **Get it in writing before you send money.** A verbal promise from a collections rep is worth nothing. Get the agreement on letterhead or in a formal email before you pay a cent.
    – **Not all collectors will agree.** Original creditors almost never do this since it involves under-the-table adjustment of a factual record; third-party collection agencies are more likely to negotiate since their only goal is recovering money.

    ## What Actually Removes a Charge-Off

    Outside of pay-for-delete, there are only a few legitimate paths to getting a charge-off off your report before the 7-year mark:

    1. **It’s inaccurate.** If the charge-off doesn’t belong to you, has the wrong balance, or has an incorrect date of delinquency (which affects when it falls off), you can dispute it directly.
    2. **The furnisher can’t verify it.** If you dispute and the creditor/collector doesn’t respond with adequate documentation within the bureau’s investigation window, it gets removed.

    1. **It naturally ages off.** Seven years from the original delinquency date, it comes off regardless of payment status.## A Practical Approach

      If you’re deciding what to do with a charge-off on your report, work through this order:

      1. **Check the date of first delinquency.** If it’s close to seven years old, you may be better off just waiting it out rather than paying, since payment won’t accelerate removal.
      2. **Verify accuracy.** Pull the account details and check the balance, dates, and creditor name against your own records.
      3. **If accurate and you want it gone, negotiate pay-for-delete in writing first**, then pay only after you have the agreement documented.
      4. **If pay-for-delete isn’t on the table**, weigh whether paying is worth it for the “paid” status improvement and to avoid collection/legal risk, understanding it won’t remove the item.

      ## The Bottom Line

      Paying a charge-off is often the right financial move, but don’t do it under the assumption it will clean your credit report. It changes the story the report tells — from “never paid” to “eventually paid” — which matters to some lenders and scoring models, but the mark itself sticks around for up to seven years unless you specifically negotiate its removal before paying, or successfully dispute it as inaccurate or unverifiable.

  • How to Fix Your Credit: A Step-by-Step Guide for 2026

    How to Fix Your Credit: A Step-by-Step Guide for 2026

    Go deeper on each step: learn how to find and fix credit report errors across all three bureaus, get the full playbook for removing collection accounts, see why lowering your credit utilization ratio is the fastest single move you can make, and follow the proven path to build positive history from scratch.

    If you’ve ever been denied a loan, offered sky-high interest rates, or felt that quiet knot in your stomach every time someone mentions a credit check, you already know how much your credit score shapes daily life. It affects the apartment you can rent, the car you can finance, the credit cards you qualify for, and sometimes even the jobs you can land. A low score doesn’t just cost you money — it limits your options.Here’s the good news: credit is not permanent. It’s not a life sentence. It’s a living, breathing record of your financial behavior, and that means it can be changed. Whether you’re dealing with errors on your reports, a history of missed payments, collections you’re not sure how to handle, or simply a thin credit file with not enough history, there are concrete, proven steps you can take to fix your credit — and keep it strong for the long haul.This guide is built to be the most thorough, practical, and honest resource on the internet for repairing and rebuilding credit in 2026. We’ll walk you through what “fixing your credit” actually means, how scores work, the three phases of credit improvement (repair, rebuild, protect), realistic timelines, your legal rights, how to choose a legitimate credit repair company if you decide you want help, and the myths and mistakes that trip people up along the way.

    We’re a San Diego-based, attorney-backed credit repair firm that operates in full compliance with the Fair Credit Reporting Act (FCRA). We believe in transparency, education, and measurable progress — not quick fixes or empty promises. Everything in this guide reflects that philosophy.

    What “Fixing Your Credit” Actually Means

    Most people use “fix my credit” as a catch-all phrase, but there are actually two distinct — and equally important — phases involved, and understanding the difference is the foundation of everything that follows.

    Phase 1: Credit Repair — This is the process of identifying and correcting what’s wrong on your credit reports. That includes disputing inaccurate information, addressing outdated items that should have fallen off, handling collections and charge-offs, and negotiating with creditors when appropriate. Think of repair as cleaning up the errors and negative marks that are dragging your score down unfairly or unnecessarily.

    Phase 2: Credit Rebuilding — This is the process of establishing and growing positive credit history. Even if your reports are perfectly clean, you won’t have a strong score without a track record of responsible borrowing. Rebuilding means making on-time payments, keeping your credit utilization low, maintaining a healthy mix of credit types, and letting your accounts age.

    Here’s the key insight that many people miss: you can’t just repair your way to a great score. If you successfully dispute and remove every error on your report but you have no open accounts, no recent on-time payments, and no active positive history, your score won’t magically climb. Likewise, you can open new accounts and pay them perfectly, but if your reports are full of inaccurate negative items, you’re fighting an uphill battle.

    The most effective approach tackles both phases together — cleaning up the past while building for the future. That’s why this guide is structured around three phases: Repair, Rebuild, and Protect. The third phase — protection and maintenance — is what keeps your hard-won progress from slipping away.

    A note on expectations: No legitimate credit repair professional, attorney, or company can guarantee a specific score increase or promise that a particular item will be removed within a specific timeframe. Anyone who does is not being honest with you. What we can do is make sure your reports are accurate (which is your legal right under the FCRA), help you build positive history strategically, and track measurable progress over time.

    How Credit Scores Work: The 5 Factors

    Before you can fix your credit effectively, you need to understand what actually determines your score. Most lenders in the United States use the FICO Score (currently the FICO 8 and FICO 9 models, with FICO 10 T gaining traction), while VantageScore (3.0 and 4.0) is also used by some lenders and many free credit monitoring services. While the exact algorithms are proprietary, both scoring models evaluate the same five core categories of information.

    Here’s the breakdown of the five factors that influence your FICO score, ranked by how much weight each one carries:

    Factor Weight What It Measures Quick Takeaway
    Payment History 35% Whether you’ve paid your credit accounts on time One late payment can drop your score significantly — this is the single most important factor
    Credit Utilization 30% How much of your available credit you’re using Keep balances below 30% of your limits, ideally below 10%
    Length of Credit History 15% The age of your oldest account, newest account, and average across all accounts Older accounts help your score — keep them open even if you don’t use them
    Credit Mix 10% The variety of credit types you have (revolving, installment, mortgage) A mix of credit cards and loans shows you can handle different responsibilities
    New Credit / Inquiries 10% How many recent hard inquiries and new accounts you have Space out applications — too many at once signals risk

    Let’s dig into each one.

    1. Payment History (35%) — The Big One

    Payment history is the single most influential factor in your credit score, and for good reason: lenders want to know that you’ll repay what you borrow. This factor looks at whether you’ve made payments on time across all your credit accounts — credit cards, auto loans, mortgages, student loans, personal loans, and other credit products.

    Here’s what matters within this category:

    • On-time payments build positive history. Every month you pay on time, you’re adding to the foundation of a strong score.
    • Late payments are reported in increments: 30 days late, 60 days late, 90 days late, 120+ days late. The later the payment, the more damage it does.
    • Recent late payments hurt more than older ones. A late payment from three years ago has far less impact than one from three months ago.
    • Charge-offs, collections, foreclosures, repossessions, and bankruptcies are severe negative marks that can stay on your report for 7 to 10 years.

    The takeaway: If you do nothing else, pay every bill on time, every month. Set up automatic payments or reminders. This one habit accounts for more than a third of your score.

    2. Credit Utilization (30%) — The Lever You Can Pull Quickly

    Credit utilization measures how much of your available revolving credit you’re currently using. If you have a credit card with a $10,000 limit and you carry a $3,000 balance, your utilization on that card is 30%.

    This factor is calculated both per-card and across all your revolving accounts combined. The scoring models look at the balances reported to the credit bureaus — which typically happens on your statement closing date, not your payment due date.

    Here’s the hierarchy of utilization and its impact:

    • Under 10% — Excellent. This is where the highest scores live.
    • 10% to 29% — Good. You’re in solid territory.
    • 30% to 49% — Fair. You’re using a lot of your available credit, which signals some risk.
    • 50% to 74% — Poor. Lenders see this as a sign of financial strain.
    • 75% or higher — Very poor. Maxed-out or near-maxed-out cards significantly depress your score.
    • 100% (maxed out) — Severe negative impact.

    The takeaway: Credit utilization is one of the fastest levers you can pull. Unlike payment history, which takes months to build, you can improve your utilization in a single billing cycle by paying down balances. If you can’t pay in full, aim to keep your statement balance below 10% of your limit.

    A pro tip: If you’re trying to optimize your score before applying for a major loan, consider making a payment before your statement closes, not just by the due date. This lowers the balance that gets reported to the bureaus, which is what the scoring models actually see.

    3. Length of Credit History (15%) — Time Is on Your Side

    This factor considers the age of your credit accounts. The scoring models look at:

    • The age of your oldest account
    • The age of your newest account
    • The average age of all your accounts

    Older accounts and a longer average age generally help your score because they demonstrate a longer track record of responsible credit use. This is why closing your oldest credit card can sometimes hurt your score — you’re shortening your credit history.

    The takeaway: Keep your oldest accounts open and active, even if you only use them for a small recurring charge (like a streaming subscription) that you pay off each month. This keeps the account reporting as active and preserves your credit history length.

    4. Credit Mix (10%) — Show You Can Handle Variety

    Credit scoring models like to see that you can manage different types of credit responsibly. The two main categories are:

    • Revolving credit — credit cards, store cards, lines of credit (you can borrow repeatedly up to a limit)
    • Installment credit — auto loans, mortgages, student loans, personal loans (fixed amount, fixed payments over a set period)

    Having only credit cards, or only installment loans, won’t necessarily tank your score, but having a healthy mix of both tends to give it a small boost. This factor carries the least weight of the five, so don’t take out a loan you don’t need just to improve your mix — but if you’re already considering an installment loan for a legitimate purpose, know that it can contribute to a stronger score over time.

    5. New Credit and Inquiries (10%) — Don’t Apply All at Once

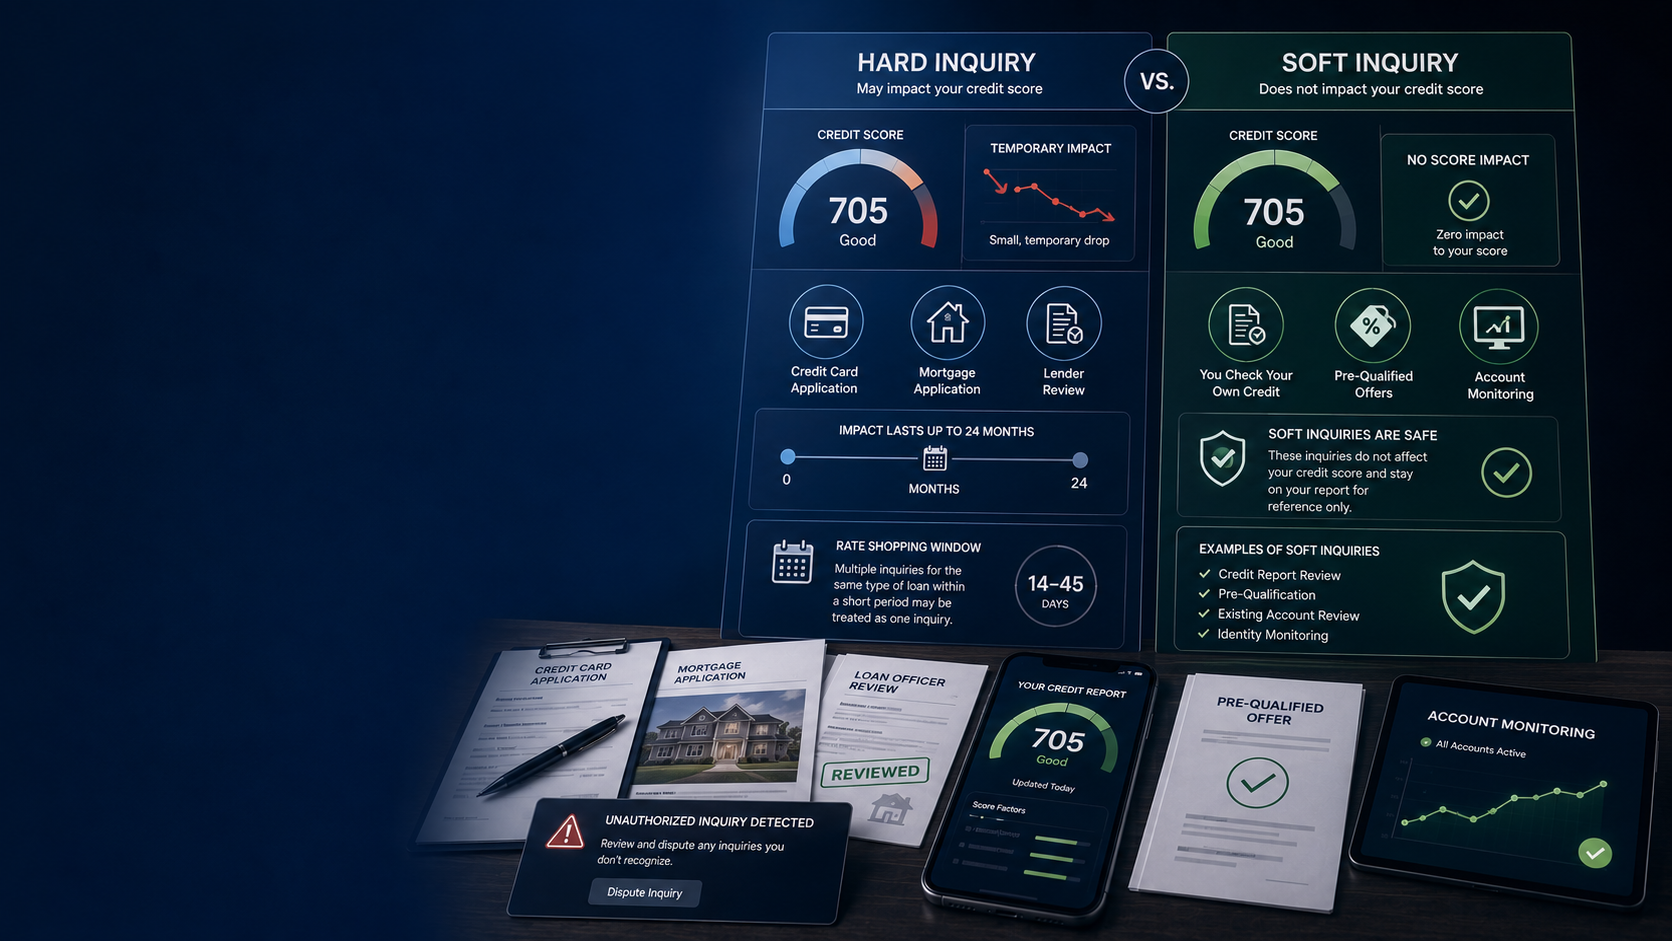
    Every time you apply for new credit, the lender performs a hard inquiry (also called a hard pull) on your credit report. A single hard inquiry typically causes a small, temporary dip in your score (usually 1-5 points). However, applying for multiple credit accounts in a short period signals risk to lenders and can have a more significant impact.

    Important distinctions:

    • Hard inquiries occur when you apply for credit. They’re visible to other lenders and can affect your score. They stay on your report for 2 years but only affect your FICO score for 12 months.
    • Soft inquiries occur when you check your own credit, when a lender pre-approves you, or when a current creditor monitors your account. These do not affect your score.
    • Rate shopping: The scoring models are smart enough to recognize rate shopping. If you’re shopping for a mortgage, auto loan, or student loan, multiple inquiries within a 14-45 day window (depending on the scoring model) are typically treated as a single inquiry for scoring purposes. So if you’re car shopping, get all your loan applications done within a couple of weeks.

    The takeaway: Space out credit applications. Don’t apply for five cards in a month. If you’re rate-shopping for a specific loan type, cluster those applications within a short window.

    Phase 1 — Repair: Fixing What’s Wrong

    Now that you understand what drives your score, it’s time to start the actual work. Phase 1 is all about identifying and correcting problems on your credit reports. This is where the legal protections of the Fair Credit Reporting Act (FCRA) come into play — you have the right to accurate, complete, and verifiable information on your reports, and you have the right to dispute anything that doesn’t meet that standard.

    Step 1: Pull All Three Credit Reports

    Your credit is reported by three major credit bureaus: Equifax, Experian, and TransUnion. They are separate companies with separate databases, and they don’t always have the same information. A creditor may report to one bureau but not another. An error may appear on your Equifax report but not your TransUnion report.

    This means you need to pull reports from all three.

    Your legal right to free reports: Under the FCRA, you’re entitled to one free credit report from each of the three bureaus every 12 months through AnnualCreditReport.com — the only federally authorized website for this purpose. In recent years, the bureaus have made free weekly reports available through this site as well, which is helpful if you’re actively working on your credit.

    You can also access your reports and scores through credit monitoring services (many of which are free), but be aware that these services often show VantageScore rather than FICO, and the report data may be a simplified version. For dispute purposes, you want the full, official reports directly from the bureaus.

    Step 2: Audit Your Reports for Errors

    Once you have all three reports, go through each one methodically. Credit report errors are remarkably common — various studies and regulatory investigations have found that a significant percentage of consumers have at least one error on their reports, and many of those errors are serious enough to affect credit decisions.

    Here’s what to look for:

    Personal information errors:

    • Wrong name, aliases you don’t recognize
    • Incorrect addresses
    • Inaccurate employer information
    • Mixed files — someone else’s accounts appearing on your report (this happens more often than you’d think, especially if you share a name with a relative)

    Account errors:

    • Accounts that don’t belong to you (potential identity theft or mixed file)
    • Incorrect account balances
    • Wrong credit limits (which can artificially inflate your utilization ratio)
    • Incorrect account status (showing open when it’s closed, or vice versa)
    • Late payments that were actually on time
    • Duplicate accounts (the same debt listed twice)
    • Accounts showing as charged off when they were settled or paid

    Outdated information:

    • Negative items older than 7 years (10 years for bankruptcies) that should have been removed
    • Collections that were paid and should be updated
    • Hard inquiries older than 2 years

    Fraud or identity theft:

    • Accounts you never opened
    • Inquiries you didn’t authorize
    • Addresses where you never lived

    Make a list of every error you find, organized by bureau. Note the specific item, the bureau reporting it, and why you believe it’s inaccurate. This documentation becomes the foundation of your disputes.

    Step 3: Dispute Inaccuracies the Right Way

    The FCRA gives you the right to dispute any information on your credit report that you believe is inaccurate, incomplete, or unverifiable. When you file a dispute, the bureau is required to investigate — typically within 30 days — and either verify, correct, or delete the disputed item.

    Here’s how to do it effectively:

    File disputes directly with the credit bureau(s) reporting the error. You can dispute online, by phone, or by mail. While online disputes are convenient, filing by certified mail with a return receipt creates a paper trail that can be valuable if you need to escalate later. Each bureau has a dedicated dispute process on their website.

    Also file disputes with the furnisher. Under the FCRA, you can also dispute directly with the creditor or collection agency that reported the information (the “furnisher”). This is called a direct dispute and it gives you a second avenue of accountability. If the furnisher can’t verify the information, they’re required to notify the bureaus to correct or remove it.

    Be specific and provide documentation. The more precise you are, the more likely the dispute will succeed. Don’t just say “this is wrong.” Say “this account shows a late payment in March 2024, but I have bank records showing the payment was made on March 12, 2024 — two days before the due date.” Attach copies of supporting documents (never send originals).

    Dispute one item at a time per letter. If you have multiple errors, it’s generally better to dispute them individually rather than batching them. Some consumer advocates argue that bureaus are more likely to dismiss batch disputes as frivolous. Whether or not that’s universally true, individual disputes are easier to track and follow up on.

    Keep records of everything. Copies of your dispute letters, certified mail receipts, bureau responses, and any correspondence with furnishers. If a dispute isn’t resolved and you later need legal help, this documentation is invaluable.

    What happens after you dispute: The bureau has 30 days to investigate (45 days if you dispute after receiving your free annual report). They contact the furnisher, who must verify the information. If the furnisher can’t verify it, or doesn’t respond within the investigation period, the item must be removed. You’ll receive the results in writing, along with a free updated copy of your report if changes were made.

    If the dispute comes back “verified” but you know it’s wrong: You can dispute again with additional documentation, file a complaint with the Consumer Financial Protection Bureau (CFPB), add a statement of dispute to your credit report (a brief explanation that appears on your report), or consult with a consumer law attorney. If the furnisher is reporting knowingly inaccurate information, you may have grounds for legal action under the FCRA.

    Step 4: Handle Collections Strategically

    Collections are one of the most stressful parts of credit problems, but there are effective strategies for dealing with them.

    First, verify the debt. Under the Fair Debt Collection Practices Act (FDCPA), you have the right to request debt validation within 30 days of being contacted by a collection agency. Send a written validation request, and the collector must provide proof that the debt is yours and that the amount is correct. If they can’t validate the debt, they must cease collection efforts and the credit bureaus should remove the collection if you dispute it.

    Understand the difference between original creditor and collection agency. When an account goes to collections, it may appear on your report twice — once as a charge-off from the original creditor and once as a collection from the collection agency. Both are negative, but paying or settling the collection doesn’t automatically remove the original creditor’s charge-off.

    Consider a pay-for-delete negotiation. Some collection agencies will agree to remove the collection from your credit report in exchange for payment. This isn’t guaranteed — many agencies have policies against it, and the bureaus technically discourage the practice — but it’s worth asking. Get any agreement in writing before you pay.

    The newer FICO and VantageScore models treat paid collections more favorably. FICO 9 and VantageScore 3.0/4.0 ignore paid collections entirely and give less weight to unpaid medical collections. However, many lenders still use older models (like FICO 8) where paid collections still impact your score. Paying a collection won’t necessarily boost your score immediately under older models, but it’s still the right thing to do — a paid collection looks better to lenders reviewing your report manually, and it prevents potential lawsuits.

    Medical collections have special rules. As of recent regulatory changes, medical bills under a certain threshold may not appear on your report, and there are extended waiting periods before medical debt can be reported. Always check whether medical collections on your report comply with current rules.

    Don’t reset the clock accidentally. Making a partial payment or acknowledging a debt in writing can, in some states, restart the statute of limitations on that debt — the time frame during which a creditor can sue you. Before you contact a collector about an old debt, understand your state’s statute of limitations.

    Step 5: Negotiate with Creditors

    If you have accounts that are past due but not yet in collections, or if you have charge-offs that you want to resolve, you can often negotiate directly with the original creditor. Common strategies include:

    Goodwill letters. If you have an otherwise solid payment history with a creditor but had a one-time late payment due to a specific hardship (medical emergency, job loss, natural disaster), you can write a goodwill letter asking the creditor to remove the late payment as a courtesy. This isn’t a legal right — it’s a request — but creditors sometimes grant it, especially for long-time customers with otherwise clean records.

    Pay-for-delete. Similar to the collection strategy, you can ask a creditor to remove a negative mark in exchange for payment. More commonly successful with collection agencies than original creditors, but worth attempting.

    Lump-sum settlements. If you owe a significant amount and can offer a lump-sum payment, creditors may accept less than the full balance (often 40-70% of what’s owed). Be aware that settled debt can still show on your report as “settled for less than full balance,” which is better than unpaid but not as good as “paid in full.”

    Payment plans. Some creditors will agree to updated payment plans and may even re-age your account (bringing it current) if you make a set number of on-time payments. This can stop further negative reporting.

    Get everything in writing. Any agreement you reach with a creditor should be documented in writing before you make a payment. Verbal agreements are difficult to enforce.

    Step 6: Deal with Outdated Items

    Negative information doesn’t stay on your credit report forever. Here are the time limits under the FCRA:

    Item Maximum Time on Report
    Late payments 7 years
    Collections 7 years from original delinquency date
    Charge-offs 7 years from original delinquency date
    Chapter 7 bankruptcy 10 years
    Chapter 13 bankruptcy 7 years
    Foreclosures 7 years
    Repossessions 7 years
    Civil judgments 7 years (or less, depending on state)
    Tax liens 7 years from paid date (unpaid liens may no longer appear)
    Hard inquiries 2 years (affect FICO score for 1 year)

    If you see negative items that are older than these limits, dispute them. The bureaus are required to remove outdated information. Note that the 7-year clock for collections and charge-offs starts from the date of the original delinquency — the first missed payment that led to the collection — not from the date the collection agency acquired the debt or the date you last made a payment.

    Phase 2 — Rebuild: Building Positive History

    Once you’ve addressed the errors and negative items on your reports, it’s time to focus on building the positive history that will lift your score. Even if you’ve removed everything negative, you need active, positive accounts to generate a strong score.

    Keep Making On-Time Payments

    This is worth repeating because it’s the foundation of everything: pay every bill on time, every month. Set up automatic payments for at least the minimum on all accounts. Use calendar reminders. Do whatever it takes to never miss a due date. Every on-time payment adds to your positive payment history, and over time, this is what will drive your score up the most.

    Keep Your Credit Utilization Low

    As we covered in the scoring factors section, utilization is the second-most-important factor and one of the fastest to improve. Here’s the strategy:

    • Keep balances below 30% of your credit limit on each card and across all cards combined.
    • Aim for under 10% for the best score impact.
    • Pay before the statement closes if you’re trying to optimize for a specific application — the balance reported to the bureaus is typically your statement balance.
    • Consider requesting credit limit increases — a higher limit with the same balance automatically lowers your utilization ratio. Just make sure the creditor won’t do a hard inquiry for the increase (many do soft inquiries for existing customers).

    Keep Old Accounts Open

    Your credit history length matters. When you pay off a credit card, don’t close the account — keep it open. A paid-off card with a $0 balance contributes positively to your utilization ratio (more available credit = lower utilization) and preserves your account age.

    If a card has an annual fee and you don’t want to keep paying it, ask the issuer if they can downgrade you to a no-fee version of the card. This keeps the account open and the history intact without the ongoing cost.

    If you absolutely must close an account, close a newer one — not your oldest card.

    Build a Healthy Credit Mix

    If you only have revolving credit (credit cards), adding an installment loan can give your score a small boost over time — but only if you genuinely need the loan and can afford the payments. Options include:

    • A small personal loan
    • A credit-builder loan (more on this below)
    • An auto loan if you’re already planning to buy a car
    • A share-secured loan from a credit union (backed by your savings)

    Don’t take on debt you don’t need just for credit mix. The 10% weight of this factor is not worth the financial risk.

    Use Secured Credit Cards

    If your credit is too damaged to qualify for regular (unsecured) credit cards, secured cards are one of the best rebuilding tools available. Here’s how they work:

    • You put down a refundable security deposit (typically $200-$500).
    • The deposit becomes your credit limit.
    • You use the card like a regular credit card — making purchases and paying them off each month.
    • Your activity is reported to the credit bureaus, building positive history.
    • After a period of responsible use (usually 6-12 months), many issuers will upgrade you to an unsecured card and refund your deposit.

    Tips for secured cards:

    • Choose a card that reports to all three bureaus (most do, but verify).
    • Look for cards with low or no annual fees.
    • Use the card for small purchases (gas, a recurring subscription) and pay the full balance each month.
    • Keep utilization low — if your limit is $300, don’t carry more than $30-$90.

    Become an Authorized User

    If you have a family member or close friend with a credit card that has a long history of on-time payments and low utilization, ask if they’ll add you as an authorized user. When you’re added as an authorized user, the account’s history is often reported on your credit report as well.

    This can be a powerful strategy because:

    • You inherit the account’s positive payment history.
    • The account’s age contributes to your credit history length.
    • The account’s limit contributes to your available credit, improving your utilization.

    Important caveats:

    • Not all card issuers report authorized user accounts to the bureaus. Check with the issuer first.
    • If the primary cardholder misses payments or runs up the balance, those negatives also appear on your report. Only do this with someone you trust to manage the account responsibly.
    • You don’t need to actually use the card — just being listed as an authorized user is enough.
    • The primary cardholder can keep the physical card; you never need to charge anything.

    Consider a Credit-Builder Loan

    Credit-builder loans are designed specifically for people building or rebuilding credit. Unlike a traditional loan, you don’t receive the money upfront. Instead:

    • The lender holds the loan amount in a secured savings account.
    • You make monthly payments (which are reported to the credit bureaus).
    • When the loan is paid off, you receive the money.

    This builds positive installment credit history and forces you to save money at the same time. Many credit unions and community banks offer credit-builder loans, and there are also online lenders specializing in this product. Look for one that reports to all three bureaus and has reasonable fees.

    Give It Time

    Rebuilding credit is a marathon, not a sprint. The length of your credit history and the age of your accounts are factors you can’t rush. What you can do is start now, be consistent, and let time work in your favor. Every month of on-time payments, every statement cycle with low utilization, and every year of account aging adds up.

    Phase 3 — Protect & Maintain

    Fixing your credit is an achievement. Protecting it is a lifelong habit. Phase 3 is about the systems and practices that keep your credit strong — and catch problems early when they do arise.

    Monitor Your Credit Regularly

    You should check your credit reports at least once a year from all three bureaus (via AnnualCreditReport.com), and more frequently if you’re actively rebuilding. In addition, set up ongoing credit monitoring:

    • Free monitoring services from banks, credit card issuers, and independent apps provide regular score updates and alerts when new accounts, inquiries, or changes appear on your report.
    • Paid monitoring services offer more comprehensive features like 3-bureau monitoring, identity theft insurance, and dark web scanning. Whether you need these depends on your risk level and preferences.
    • Identity theft alerts: If you see an account or inquiry you don’t recognize, act immediately. Contact the creditor, place a fraud alert on your credit file, and file a report with the FTC at IdentityTheft.gov.

    Consider a Credit Freeze or Fraud Alert

    A credit freeze (also called a security freeze) restricts access to your credit report. When your credit is frozen, lenders can’t pull your report, which means identity thieves can’t open new accounts in your name. You can temporarily lift the freeze when you need to apply for credit. Freezes are free under federal law and are the strongest protection against new-account identity theft.

    A fraud alert is a less restrictive option. It tells lenders to take extra steps to verify your identity before extending credit. Fraud alerts last for one year (or seven years for an extended fraud alert if you’ve filed an identity theft report with the FTC). You only need to place a fraud alert with one bureau — they’re required to notify the other two.

    Practice Good Financial Habits

    The habits that protect your credit are the same ones that built it:

    • Pay on time, every time. Automate at least the minimum payment on every account.
    • Keep utilization low. Check your balances mid-cycle and pay them down if needed.
    • Don’t close old accounts unless there’s a compelling reason.
    • Space out credit applications. Don’t apply for multiple cards or loans within a short period.
    • Maintain an emergency fund. Having savings prevents you from relying on credit cards when unexpected expenses arise, which keeps your utilization in check.
    • Review your statements monthly. Catch billing errors, unauthorized charges, and changes to terms early.

    Review Your Insurance and Utility Accounts

    Some insurance companies and utility providers use credit-based insurance scores or require credit checks. Maintaining good credit can lower your insurance premiums and eliminate deposit requirements for utilities, cell phones, and apartment leases. It’s a ripple effect — strong credit saves you money across many areas of life.

    Educate Yourself Continuously

    Credit laws, scoring models, and reporting practices evolve. Stay informed about your rights under the FCRA, FDCPA, and CROA. Follow reputable financial education resources. The more you understand about how credit works, the better equipped you’ll be to protect and grow your score over a lifetime.

    Realistic Timelines: What Improves and When

    One of the most common questions we hear is “How fast can I fix my credit?” The honest answer is: it depends on what’s on your report, what actions you take, and how consistently you maintain positive habits. But here’s a realistic framework for what you can expect at different milestones.

    Timeframe What Can Improve Realistic Score Impact
    30 days Dispute investigation results; rapid utilization improvement by paying down balances; removal of verified errors 10-40+ points if errors are removed or utilization drops significantly
    60-90 days Additional dispute rounds; goodwill letter responses; initial positive reporting from new secured cards or credit-builder loans 20-60+ points cumulative, depending on number and severity of items addressed
    6 months 6 months of on-time payments on new accounts; collection settlements updated; authorized user history accumulating; aging of recent inquiries 40-100+ points over baseline, depending on starting point and actions taken
    1 year 12 months of clean payment history; reduced impact from older negative items; account aging; improved credit mix 60-150+ points from a low starting score with consistent effort
    2+ years Significant aging of negative items; strong, diverse credit history; most recent negatives losing impact; approaching excellent score territory if habits are maintained 100-200+ points from a damaged starting point over a 2-year period of consistent positive behavior

    Important caveats:

    • These are general ranges, not guarantees. Your results depend on your specific credit profile.
    • If you have a bankruptcy or multiple serious delinquencies, recovery will take longer. A Chapter 7 bankruptcy, for example, stays on your report for 10 years and has a significant impact throughout that time — though the impact lessens as the bankruptcy ages and you build new positive history.
    • The fastest improvements come from fixing errors (removing items that shouldn’t be there) and lowering utilization. The slowest improvements come from building payment history and account age — these simply take time.
    • Consistency matters more than intensity. Six months of steady on-time payments and low utilization will help more than a burst of activity followed by a relapse.

    How to fix your credit and improve your credit score in 2026

    What Hurts Your Score Most (Ranked)

    Not all negative items are created equal. Here’s a ranking of what damages your credit score the most, from most severe to least:

    • Bankruptcy (Chapter 7 or 13) — The most damaging item. Can drop a good score by 100-200+ points and remains on your report for 7-10 years.
    • Foreclosure — A severe negative mark indicating default on a major secured loan. Stays on your report for 7 years.
    • Repossession — Similar to foreclosure but for auto loans. Indicates failure to repay a secured debt. 7 years.
    • Charge-off — When a creditor writes off your debt as a loss because they don’t expect you to pay. One of the most damaging account-level items. 7 years.
    • Collections — When your debt is sent to a collection agency. The impact is significant, though newer scoring models treat paid collections more leniently. 7 years.
    • Default (student loans) — Student loan default is a serious negative mark that can also lead to wage garnishment and tax refund seizure. 7 years.
    • Late payments (90+ days) — A 90-day late payment signals serious delinquency and has a major impact. 7 years.
    • Late payments (60 days) — Moderately damaging. 7 years.
    • Late payments (30 days) — The first level of delinquency. Damaging but less so than more severe lates. 7 years.
    • High credit utilization — Not a “negative mark” per se, but carrying high balances relative to your limits significantly depresses your score. Reversible quickly by paying down balances.
    • Hard inquiries — Minor impact individually (1-5 points), but multiple inquiries in a short period compound. Affect score for 1 year, visible for 2 years.
    • Closing old accounts — Indirect impact by reducing your available credit (raising utilization) and shortening your average account age.

    The severity of impact also depends on your starting score. If you have an excellent score (780+), a single 30-day late payment can drop your score by 90-110 points. If you have a fair score (680), the same late payment might only drop you by 60-80 points. Higher scores have further to fall.

    DIY Credit Repair vs. Hiring a Professional

    One of the biggest decisions you’ll face is whether to repair your credit yourself or hire a professional. Both paths are valid, and the right choice depends on your situation, time, and comfort level.

    The DIY Approach

    Pros:

    • It’s free (aside from postage and your time). The FCRA gives you the right to dispute errors yourself at no cost.
    • You have full control over what’s disputed and how.
    • You learn your credit inside and out — knowledge that serves you for life.
    • No risk of scams — you’re doing it yourself.

    Cons:

    • Time-consuming. Reviewing three reports, drafting dispute letters, following up on investigations, and tracking results takes significant time and organization.
    • Steep learning curve. Understanding FCRA rights, dispute processes, debt validation, and creditor negotiations requires research.
    • Less leverage. An individual dispute may not carry the same weight as one from an attorney or a professional firm that understands the legal framework and can escalate effectively.
    • Easy to make mistakes. Filing disputes incorrectly, missing deadlines, or accidentally resetting statutes of limitations can set you back.

    DIY is best for: People with a few minor errors, those who enjoy managing details, and those who have the time and patience to handle the process themselves.

    Hiring a Professional

    Pros:

    • Expertise and experience. A legitimate credit repair company or consumer law attorney knows the FCRA, FDCPA, and CROA inside and out. They understand what to dispute, how to frame disputes effectively, and when to escalate.
    • Saves time. They handle the paperwork, follow-ups, and tracking for you.
    • Attorney-backed firms can take legal action if your rights are violated — something no individual or non-attorney company can do.
    • Systematic approach. Professional firms have processes for ongoing dispute cycles, creditor negotiations, and monitoring that are difficult to replicate on your own.

    Cons:

    • Cost. Legitimate credit repair companies charge fees — typically a setup fee and monthly fees. You’re paying for expertise and convenience.
    • You still have to do the rebuilding. No company can build positive credit history for you — that requires your own on-time payments and responsible account management.
    • Scams exist. The credit repair industry has its share of bad actors. You must know how to identify and avoid them (covered in the next section).

    Professional help is best for: People with complex reports (many errors, collections, charge-offs), those who don’t have the time or confidence to DIY, those who suspect their rights have been violated and may need legal recourse, and those who want the peace of mind that comes with expert guidance.

    Your Rights Under the Credit Repair Organizations Act (CROA)

    The CROA is a federal law that protects consumers from deceptive practices by credit repair companies. Under the CROA, credit repair companies:

    • Cannot charge upfront fees before performing any services. A company that demands payment before doing any work is violating federal law.
    • Must provide a written contract that describes the services to be performed, the timeframe, and the total cost.
    • Must give you a 3-day right to cancel the contract without any charge.
    • Cannot make false claims about what they can do for your credit.
    • Cannot advise you to create a new credit identity (such as applying for an Employer Identification Number to use instead of your Social Security number) — this is illegal.
    • Must disclose your right to repair your own credit. A legitimate company will tell you that you can do this yourself for free.

    If a credit repair company violates any of these rules, that’s a red flag — and potentially a legal claim you can pursue.

    How to Choose a Legitimate Credit Repair Company

    If you decide to hire professional help, it’s critical to choose a company you can trust. Here’s what to look for — and what to run from.

    Green Flags (Signs of a Legitimate Company)

    • FCRA-compliant processes. The company works within the legal framework of the FCRA, FDCPA, and CROA.
    • Attorney involvement. Attorney-backed or attorney-staffed firms can provide legal analysis of your situation and take legal action if your rights are violated.
    • Transparent pricing. Clear, upfront pricing with no hidden fees. You should know exactly what you’ll pay before you sign anything.
    • Realistic expectations. They tell you that results aren’t guaranteed, that credit repair takes time, and that you have a role to play (making on-time payments, managing utilization).
    • Written contract. They provide a written agreement with a 3-day cancellation right, as required by the CROA.
    • Free consultation. They offer an initial review of your situation at no cost.
    • Educational resources. They help you understand your credit, not just “fix” it. A company that educates you is investing in your long-term success.
    • Clear dispute process. They explain exactly what they’ll dispute, how they’ll do it, and how they’ll track results.
    • Positive reviews and track record. Look for reviews on independent platforms, BBB ratings, and testimonials from real clients.

    Red Flags (Warning Signs to Avoid)

    • Upfront fees before any service is performed. This is illegal under the CROA. Walk away immediately.
    • Guaranteed results or specific score increases. No legitimate company can guarantee outcomes. Credit repair is a legal process, not a magic wand.
    • Promises to remove accurate, verifiable negative information. If the information is accurate and can be verified, it legally can remain on your report. A company promising to remove everything is either lying or planning to use illegal methods.
    • Advice to create a “new” credit identity. Using an EIN instead of your SSN, or applying for a new SSN, to start fresh is illegal and can result in federal prosecution.
    • Pressure to sign immediately. A legitimate company gives you time to review the contract and exercise your 3-day cancellation right.
    • No written contract. Verbal agreements are a sign of a company that doesn’t want to be held accountable.
    • Poor BBB rating or unresolved complaints. Check the Better Business Bureau and CFPB complaint database.
    • No physical address or verifiable business presence. A legitimate company has a real office and professional infrastructure.
    • Unwilling to explain their process. If they can’t or won’t tell you how they’ll repair your credit, they’re not trustworthy.

    Questions to Ask Before Signing

    • What exactly will you do, and what will you charge?
    • Are you attorney-backed? If so, in what capacity?
    • How long does the process typically take?
    • What happens if an item isn’t removed?
    • What is your cancellation policy?
    • Will you help me understand how to rebuild my credit, not just repair it?
    • Can you provide references or client testimonials?
    • What are my rights under the FCRA and CROA?

    A legitimate company will answer all of these questions clearly and patiently. If they’re evasive, move on.

    Common Credit Repair Myths Busted

    Myth 1: “Credit repair is illegal.”

    False. Credit repair is completely legal. The FCRA explicitly gives you the right to dispute inaccurate information on your credit reports, and you have the right to hire a professional to help you. The CROA regulates the credit repair industry to protect consumers, but it doesn’t make credit repair illegal. What is illegal is using fraudulent methods — like creating a new credit identity or lying on credit applications.

    Myth 2: “You can remove anything from your credit report.”

    False. You can dispute anything, but you can only get items removed if they’re inaccurate, incomplete, or unverifiable. If a negative item is accurate and the creditor can verify it, it has the right to remain on your report for the legal time limit (typically 7 years). Any company that promises to remove accurate, verifiable information is not being honest with you.

    Myth 3: “Paying off a collection immediately removes it from your report.”

    False. Paying a collection updates the status to “paid,” which is better than unpaid, but the collection itself remains on your report for up to 7 years from the original delinquency date. Under newer scoring models (FICO 9, VantageScore 3.0+), paid collections are ignored in scoring, but many lenders still use older models. A pay-for-delete agreement can sometimes remove the collection entirely, but it’s not guaranteed.

    Myth 4: “Closing a credit card improves your score.”

    False. Closing a credit card typically hurts your score. It reduces your available credit (raising your utilization ratio) and can shorten your average account age. Keep old accounts open unless there’s a compelling reason to close them (like an annual fee you can’t avoid and a card you never use).

    Myth 5: “Checking your own credit hurts your score.”

    False. Checking your own credit is a soft inquiry and has zero impact on your score. You can check your own credit as often as you want without any penalty. Only hard inquiries (when a lender checks your credit in response to an application) affect your score.

    Myth 6: “Your income affects your credit score.”

    False. Your income does not appear on your credit report and is not part of your credit score. Credit scores are based solely on your borrowing and repayment behavior. However, lenders consider your income separately when deciding whether to extend credit and at what terms — so income matters for lending decisions, just not for your score.

    Myth 7: “Carrying a balance improves your credit score.”

    False. You do not need to carry a balance (and pay interest) to build credit. Paying your statement in full each month builds the same positive payment history as carrying a balance, and it saves you money on interest charges. The ideal strategy is to use your cards regularly, pay the full balance by the due date, and never pay a cent in interest.

    Myth 8: “Credit repair happens overnight.”

    False. Dispute investigations take 30-45 days. Building positive history takes months. Aging out negative items takes years. Anyone who promises overnight results is either lying or using methods that won’t produce lasting, legitimate results. The most effective credit repair is methodical, persistent, and patient.

    Myth 9: “A credit repair company can do things you can’t do yourself.”

    Partially false. You have the same legal right to dispute information as any credit repair company. What a legitimate, experienced firm brings is expertise, efficiency, systematic processes, and — in the case of attorney-backed firms — the ability to take legal action if your rights are violated. They can’t do anything magical that you can’t, but they can often do it more effectively and with less of your time.

    Myth 10: “Once an item is removed, it can never come back.”

    Partially false. If an item is removed because the furnisher couldn’t verify it during the investigation, the furnisher can theoretically re-report it later if they subsequently obtain verification. However, if they do, the bureau is required to notify you within 5 days. In practice, items that are removed due to lack of verification rarely reappear, but it’s not impossible. Items that are removed because they’re outdated or demonstrably inaccurate should not return.

    Common Mistakes to Avoid

    Even with the best intentions, certain missteps can slow your progress or even make things worse. Here are the most common mistakes we see — and how to avoid them.

    1. Disputing Everything at Once Indiscriminately

    Some people try to dispute every negative item on their report, hoping something will stick. This can backfire. If you dispute items that are clearly accurate and verifiable, the bureaus may flag your disputes as frivolous — and they have the right to refuse to investigate if they determine your disputes are without merit. Focus on items that are genuinely inaccurate, outdated, or unverifiable.

    2. Missing Payments While Focusing on Repair

    It’s easy to get so caught up in the dispute process that you forget the basics: making your current payments on time. A single new late payment can undo months of repair progress. Set up automatic payments and make sure your current obligations are always met, even while you’re disputing old errors.

    3. Closing Accounts After Paying Them Off

    As we’ve discussed, closing accounts reduces your available credit and shortens your credit history. Keep paid-off accounts open, especially older ones.

    4. Applying for Multiple Credit Cards While Rebuilding

    Each application generates a hard inquiry and a new account, both of which can temporarily lower your score. If you’re rebuilding, apply for one secured card, use it responsibly for 6-12 months, and then consider adding a second account only if needed for credit mix.

    5. Ignoring the Root Causes

    If your credit problems stem from overspending, lack of budgeting, or a financial hardship that hasn’t been addressed, repairing your credit is like bailing water from a leaky boat without fixing the hole. Address the underlying financial habits alongside the credit repair, or you’ll end up back in the same situation.

    6. Falling for Quick-Fix Scams

    If a company promises to remove accurate negative items in 30 days, raise your score by 100 points guaranteed, or create a “new” credit identity — run. These are violations of the CROA and signs of a scam. Legitimate credit repair takes time and operates within legal boundaries.

    7. Not Keeping Documentation

    Every dispute letter, every creditor communication, every bureau response — keep copies of everything. If you need to escalate a dispute, file a CFPB complaint, or take legal action, your documentation is your evidence.

    8. Resetting the Statute of Limitations

    In some states, making a payment or even acknowledging a debt in writing can restart the statute of limitations — the time during which a creditor can sue you to collect. Before contacting a collector about an old debt, understand your state’s rules and consult with a professional if you’re unsure.

    9. Settling Debts Without Getting It in Writing

    If you negotiate a settlement or pay-for-delete agreement, get it in writing before you pay. A verbal agreement that the collector will remove the collection from your report is worthless if they don’t follow through.

    10. Giving Up Too Soon

    Credit repair and rebuilding take time. If you don’t see dramatic results in the first 30 days, don’t give up. The most meaningful improvements often come from consistent positive behavior over 6-12 months and beyond. Patience and persistence are your greatest assets.

    Frequently Asked Questions

    Q: How long does credit repair take?

    A: It depends on your specific situation. If you have a few errors that are successfully removed, you may see improvement within 30-60 days. If you have multiple collections, charge-offs, and a history of late payments, meaningful improvement typically takes 6-12 months of consistent effort. Serious cases involving bankruptcy or extensive negative history can take 2 or more years. No legitimate professional can guarantee a specific timeline.

    Q: Can I fix my credit for free?

    A: Yes. You have the legal right to dispute inaccurate information on your credit reports yourself at no cost (you can get free reports at AnnualCreditReport.com, and filing disputes is free). The cost of DIY repair is your time and effort. If you choose to hire a professional, there will be fees — but no company can charge you upfront before performing services, per the CROA.

    Q: Will paying off collections improve my score?

    A: It depends on the scoring model. Under FICO 9 and VantageScore 3.0/4.0, paid collections are ignored in scoring, so paying them can improve your score. Under older models (like FICO 8, which many lenders still use), paid collections still impact your score, though less than unpaid ones. Regardless of scoring impact, paying collections is generally the right move — it resolves the debt, stops collection activity, and looks better to lenders who review your report manually.

    Q: Can I dispute accurate negative items?

    A: You can dispute anything on your report, but the FCRA only requires the removal of items that are inaccurate, incomplete, or unverifiable. If an item is accurate and the furnisher can verify it, it will remain on your report for the legal time limit. Disputing accurate items hoping they won’t be verified is a strategy some people try, but bureaus may flag repeated disputes of the same verified item as frivolous.

    Q: How often should I check my credit?

    A: At minimum, pull your full reports from all three bureaus once per year via AnnualCreditReport.com. If you’re actively repairing or rebuilding, check more frequently. Set up free credit monitoring through a bank, credit card issuer, or independent service for ongoing alerts about changes to your reports.

    Q: Does becoming an authorized user actually help?

    A: Yes, if the primary account has a long history of on-time payments and low utilization, and if the card issuer reports authorized user accounts to the credit bureaus. Most major issuers do report authorized users. You inherit the account’s positive history, which can boost your score. Just make sure the primary cardholder manages the account responsibly — their negatives will also appear on your report.

    Q: What’s the difference between a credit report and a credit score?

    A: Your credit report is the detailed record of your credit history — accounts, payment history, inquiries, public records, and personal information. Your credit score is a three-digit number (typically 300-850) calculated from the information in your credit report. The report is the data; the score is the grade based on that data. You need to review both — the report for errors, and the score to track your overall progress.

    Q: Can a credit repair company guarantee results?

    A: No. Under the CROA, it is illegal for credit repair companies to guarantee specific results. Any company that promises a particular score increase or the removal of specific items is violating federal law. A legitimate company will set realistic expectations and focus on the legal dispute process, not guarantees.

    Q: Should I file for bankruptcy to fix my credit?

    A: Bankruptcy is a major legal and financial decision that should only be considered after consulting with a qualified bankruptcy attorney. While it can discharge certain debts and provide a fresh start, it also has severe and long-lasting credit consequences (7-10 years on your report). It’s not a “credit repair” strategy — it’s a legal remedy for overwhelming debt. If you’re considering bankruptcy, speak with a professional who can evaluate your full financial situation.

    Q: What if I’ve been a victim of identity theft?

    A: Act immediately. Place a fraud alert on your credit file with one bureau (they’ll notify the other two), review all three reports for accounts you didn’t open, file a report with the FTC at IdentityTheft.gov, and file a police report. Dispute all fraudulent accounts and inquiries. Consider a credit freeze to prevent further damage. If the damage is extensive, a professional (especially an attorney) can help you navigate the cleanup process and assert your rights under the FCRA’s identity theft provisions.

    Q: How do I get a free credit score?

    A: Many banks and credit card issuers provide free FICO or VantageScore access to their customers. You can also get free scores through credit monitoring services like Credit Karma, Experian Free, and others. These scores may not be the exact same model a lender will use, but they’re useful for tracking trends over time.

    Ready to Take the First Step?

    Fixing your credit is one of the most impactful things you can do for your financial future. A higher credit score means lower interest rates, better loan terms, more housing options, lower insurance premiums, and greater financial freedom. It’s not a quick fix — it’s a journey — but it’s a journey worth taking, and you don’t have to take it alone.

    At our San Diego-based credit repair firm, we offer a free, no-obligation credit audit to help you understand exactly what’s on your three credit reports, what’s helping and what’s hurting, and what steps would make the biggest difference for your specific situation.

    Here’s what sets us apart:

    • Attorney-backed — our process includes legal review and the ability to take action if your rights under the FCRA have been violated.
    • FCRA-compliant — every dispute we file operates within the full legal framework designed to protect you.
    • Transparent pricing — no hidden fees, no upfront charges, no misleading claims. You’ll know exactly what our services cost before you commit.
    • Education-focused — we don’t just repair your credit; we teach you how to keep it strong for life.
    • Nationwide service — we serve clients in cities across the country, not just in San Diego.

    Get a free credit audit.

    You can also call us at or explore more of our educational resources:

    • Understanding Credit Report Errors
    • How to Handle Collections
    • Credit Utilization Explained
    • Your Rights Under the CROA
    • Credit Monitoring Guide

    Your credit doesn’t define you. But improving it can open doors you might not even know are closed right now. Take the first step today — your future self will thank you.

    This article is provided for educational purposes and does not constitute legal or financial advice. Individual results vary based on your specific credit situation. We do not guarantee specific outcomes, score increases, or the removal of specific items from your credit report. Our services operate in full compliance with the Fair Credit Reporting Act (FCRA), the Fair Debt Collection Practices Act (FDCPA), and the Credit Repair Organizations Act (CROA).

  • Hard vs. Soft Inquiries: What’s the Difference and Which One Hurts Your Score?

    Hard vs. Soft Inquiries: What’s the Difference and Which One Hurts Your Score?

    Take action: if you have too many hard inquiries, learn how to remove hard inquiries from your report; see how a credit limit increase request can trigger a hard pull and how to avoid it; understand what score range you’re aiming for; and if you’re house-hunting, read our guide on credit repair before applying for a mortgage.

    You applied for a credit card last week. Today you checked your credit score and it dropped a few points. Your stomach drops with it. Did that application cost you? Will it get worse? And what about all those “pre-qualified” offers flooding your mailbox — are those quietly chipping away at your score too?These are the kinds of questions that keep people up at night, and for good reason. Credit inquiries are one of the most misunderstood parts of the credit system. The good news is that once you understand the difference between a hard inquiry and a soft inquiry, most of the anxiety melts away. The two have almost nothing in common when it comes to how they affect you.In this guide, we’ll walk you through everything you need to know — what each type of inquiry is, when it happens, who can see it, how many points it really costs, how long it stays on your report, the rate-shopping window that protects you when you’re mortgage or auto-loan shopping, how to dispute unauthorized pulls, and a whole section of myths we’re going to bust. By the end, you’ll have a clear, confident grasp of inquiries and exactly what to do (and not do) about them.

    What Is a Credit Inquiry?

    A credit inquiry is simply a record of someone looking at your credit report. That’s it at its core. Every time a party — whether it’s you, a lender, a landlord, or an employer — requests a copy of your credit file from one of the three major bureaus (Equifax, Experian, or TransUnion), an entry gets logged on that report noting who looked, when, and why.

    Credit bureaus track inquiries for a few important reasons. First, inquiries are a historical record of who has been evaluating your credit and when. That matters for transparency — you have a right to know who’s been poking around your financial life. Second, and more relevant to your score, inquiries are a signal. A sudden cluster of applications can suggest someone is scrambling for credit, which historically correlates with higher risk of default. Lenders want to see that pattern before they extend more credit themselves.

    But here’s where most of the confusion lives: not every inquiry is treated the same. The credit bureaus split inquiries into two categories — hard and soft — and the two categories have completely different rules, visibility, and scoring impact. Understanding that split is the whole ballgame.

    The distinction comes down to two questions: Did you give permission for this check as part of an application for new credit? And does this check show up on the version of your report that lenders see? If the answer to both is yes, it’s almost certainly a hard inquiry. If not, it’s soft. Let’s look at each in detail.

    Get a free credit audit.

    Hard Inquiries: The Basics

    A hard inquiry (also called a hard pull) is a credit check that happens when you apply for new credit — a credit card, a mortgage, an auto loan, a personal loan, a student loan refinance, and sometimes things like a new cell phone contract or an apartment rental application. The defining feature is that you initiated it by applying for something, and you gave the lender explicit permission to review your credit as part of that application.

    Here’s what you need to know about hard inquiries:

    They require your permission

    A lender cannot perform a hard pull on your credit without your authorization. When you apply for a credit card online and click “Submit,” buried in the terms you’re agreeing to is language granting the issuer permission to access your credit report. Same with a mortgage application — you sign a form authorizing the lender to pull your credit. If a hard inquiry appears on your report and you never applied for anything, that’s a problem worth disputing (more on that later).

    They show up on your report for two years

    A hard inquiry stays on your credit report for 24 months from the date it was made. That means anyone who pulls your report during that window — including you and any prospective lender — can see that inquiry listed, along with the name of the company that made it and the date.

    They only affect your score for 12 months

    This is the part most people get wrong. While the inquiry is visible on your report for two years, it only factors into your credit score for the first 12 months. After one year, the inquiry stops affecting your FICO and VantageScore numbers — even though it’s still printed on the report. After 24 months, it falls off entirely.

    Typical point impact: small

    A single hard inquiry typically lowers your credit score by 1 to 5 points. That’s it. For most people, the drop is barely noticeable and recovers within a few months of on-time payments. We’ll dig into the specifics — and debunk the “each inquiry costs 10 points” myth — in its own section below.

    Who can see them

    Hard inquiries appear on the version of your credit report that lenders see when you apply for new credit. They do not appear on the version used for marketing pre-screened offers (more on that when we get to soft inquiries). You can also see them on your own consumer disclosure.

    Why they affect your score at all

    The logic is straightforward: research shows that people who have recently applied for multiple new credit accounts are statistically more likely to fall behind on payments than people who haven’t. A hard inquiry is the credit system’s way of noting “this person just asked someone for credit.” One inquiry is barely a blip. A stack of them in a short window is a different story — and we’ll cover that in the red-flag section.

    The key takeaway: A hard inquiry is the cost of applying for credit. It’s small, it’s temporary, and for the vast majority of people, it’s nothing to worry about.

    Soft Inquiries: The Basics

    A soft inquiry (or soft pull) is a credit check that happens without you applying for new credit. The check still gets logged, but it doesn’t carry the scoring implications of a hard pull — and critically, it doesn’t show up on the version of your report that lenders see.

    Soft inquiries happen more often than most people realize. Here’s what you should know:

    They do not affect your credit score

    This is the big one. A soft inquiry has zero impact on your credit score. Not a point, not a fraction of a point. Zero. You can check your own credit every single day and your score will not move because of it. This is why the myth “checking your credit hurts your score” is so damaging — it discourages people from doing exactly the thing they should be doing.

    Only you can see them

    Soft inquiries appear only on the version of your credit report that you see — your consumer disclosure. They do not appear on the report a lender sees when you apply for credit. So a lender reviewing your application has no idea how many times you’ve checked your own credit, how many pre-approval offers you’ve been screened for, or whether your existing creditors have been monitoring your account.

    Common examples of soft inquiries

    • Checking your own credit — through AnnualCreditReport.com, your bank’s free credit monitoring, Credit Karma, Experian’s free app, or any similar service.
    • Pre-approval and pre-qualified offers — when a credit card company or lender screens your credit to decide whether to send you a promotional offer in the mail.
    • Existing creditor account reviews — your current credit card issuer or lender periodically checking in on your credit to see how you’re managing your overall debt load. This is routine and called “account review.”
    • Employer background checks — when a prospective employer checks your credit as part of a hiring decision (this requires your written permission under the FCRA, but it’s still a soft pull and doesn’t affect your score).
    • Insurance underwriting — when an insurer checks your credit to set your premium.
    • Utility and telecommunications checks — sometimes these are soft, sometimes hard (we’ll explain in the triggers section).

    Why they exist at all

    Soft inquiries serve two purposes. One, they let you monitor your own credit without penalty — which is good for consumers and encouraged by the FCRA. Two, they let lenders and other businesses screen large pools of consumers for marketing offers without dinging everyone’s credit. If every pre-screened mailing list check were a hard pull, no one’s credit would survive a single month of junk mail.

    The key takeaway: Soft inquiries are invisible to lenders and harmless to your score. They’re the credit system’s way of saying “this one is just for information, not for a decision about new credit.”


    Hard vs. Soft Inquiries: The Comparison Table

    Here’s a side-by-side breakdown on every dimension that matters. Bookmark this — it answers about 90% of the questions people have about inquiries.

    Dimension Hard Inquiry Soft Inquiry
    What triggers it You apply for new credit (card, mortgage, auto loan, personal loan, etc.) You check your own credit; a lender screens you for a pre-qualified offer; an existing creditor reviews your account; an employer runs a background check
    Requires your permission? Yes — always tied to a credit application you initiated No (with the exception of employer checks, which require written permission under the FCRA)
    Affects your credit score? Yes — typically 1–5 points per inquiry No — zero impact, ever
    How long it stays on your report 24 months Varies (often 12–24 months on your consumer disclosure, but irrelevant to scoring)
    How long it factors into your score 12 months Never
    Visible to lenders? Yes — appears on the report lenders see when you apply for credit No — appears only on the consumer version of your report that you see
    Visible to you? Yes — you can see it on your own report Yes — you can see it on your own report
    Can you dispute it? Yes — if it was unauthorized or inaccurate Generally no need (no score impact), but you can dispute factual errors
    Example You apply for a Chase Sapphire card; Chase pulls your credit You log into Credit Karma to check your score; Credit Karma does a soft pull
    Effect on rate shopping Multiple inquiries for the same loan type within the rate-shopping window count as one N/A — soft pulls don’t affect scoring
    Cost to you Small and temporary None

    That table is the single most useful thing to internalize. If you only remember one thing, remember this: if you didn’t apply for credit, it’s almost certainly a soft pull, and it can’t hurt your score.

    Common Hard Inquiry Triggers

    Hard inquiries are triggered specifically when you apply for new credit or, in some cases, when you sign up for a service where the provider checks your credit to assess risk. Here’s the full list of common triggers:

    1. Credit card applications

    Every time you apply for a new credit card — whether it’s a rewards card, a balance transfer card, a secured card, or a store card at the checkout counter — the issuer does a hard pull on at least one bureau (sometimes two, occasionally all three). This is the most common hard inquiry trigger, by far.

    2. Mortgage applications

    When you apply for a home loan, the lender pulls your credit from all three bureaus. That’s three inquiries right there — but as we’ll explain in the rate-shopping section, they’re typically treated as a single inquiry for scoring purposes if you’re shopping for a mortgage within a window.

    3. Auto loan applications

    Whether you’re financing through the dealership or applying directly with a bank or credit union, an auto loan application triggers a hard pull. Dealers may shop your application to multiple lenders, which can result in multiple inquiries — again, the rate-shopping window is designed to protect you here.

    4. Personal loan applications

    Personal loans from banks, credit unions, or online lenders (SoFi, Upstart, LendingClub, Marcus, etc.) all require a hard pull as part of the application. Some lenders offer a pre-qualification step that uses a soft pull first — we’ll cover that distinction in the pre-qualified vs. pre-approved section.

    5. Student loan refinancing

    Refinancing federal or private student loans through companies like SoFi, Earnest, or Laurel Road involves a hard credit pull at the formal application stage.

    6. Requesting a credit limit increase

    This one catches people off guard. Some credit card issuers do a hard pull when you request a credit limit increase, while others use a soft pull. The policy varies by issuer and sometimes by card product. If you’re going to request a limit increase, it’s worth checking the issuer’s policy first — or asking the rep directly whether it will be a hard or soft pull before you proceed.

    7. New utility or cell phone contracts (sometimes)

    Here’s where it gets nuanced. Some utility companies (electric, gas, water) and cell phone providers do a hard credit check when you open a new account; others use a soft check or no check at all. It depends on the provider and the state. If you’re asked for your Social Security number on a utility application, there’s a decent chance a credit check is coming — ask whether it will be hard or soft.

    8. Apartment rental applications (sometimes)

    Many landlords and property management companies run credit checks as part of a rental application. Some use a hard pull; some use a soft pull. The trend in recent years has been toward soft pulls or specialized tenant-screening reports that don’t ding your score, but hard pulls still happen. Read the application language carefully.

    9. Opening a bank account (sometimes)

    Some banks and credit unions do a hard pull (often through ChexSystems or one of the bureaus) when you open a checking account, especially if you’re requesting overdraft protection. Many use a soft pull or no pull. Again — ask first.

    The common thread: if the check is tied to you asking someone to extend you credit, credit-like risk, or a financial relationship where they’re evaluating whether to trust you with their money or service, it’s likely a hard pull. When in doubt, ask the company directly: “Will this credit check be a hard or soft pull?” It’s a fair question, and most companies will tell you.

    Common Soft Inquiry Triggers

    Soft inquiries happen quietly, often without you realizing it. Here’s where they come from:

    1. Checking your own credit

    This is the most important one to understand. Any time you check your own credit — through AnnualCreditReport.com, your bank’s free credit score feature, Credit Karma, Experian Boost, myFICO, or any similar service — it’s a soft pull. It does not affect your score. You can do it daily if you want. (You won’t, but you could.)

    2. Credit Karma and similar monitoring services

    Services like Credit Karma, Credit Sesame, Experian’s free monitoring, and your bank’s built-in credit score feature all use soft pulls. The bureaus know you’re checking your own credit, and they treat it accordingly — no score impact, no lender visibility.

    3. Pre-qualified and pre-approval screenings

    When a credit card company or lender sends you a “You’re pre-qualified!” offer in the mail, they got your name by screening your credit with a soft pull. This is called a “pre-screen” under the Fair Credit Reporting Act, and it doesn’t touch your score. Same for online pre-qualification tools — you put in some basic info, the lender does a soft pull to see if you’d likely qualify, and they show you offers. None of that costs you points.

    4. Account monitoring by existing creditors

    If you already have a credit card with, say, Capital One, Capital One will periodically check your credit — not because you applied for anything, but to monitor the overall health of your credit profile. They want to know if you’ve taken on a bunch of new debt elsewhere, which might affect your ability to pay them. This is called an account review inquiry, and it’s always a soft pull.

    5. Insurance underwriting

    When an auto or homeowners insurance company checks your credit to set your premium (in states where this is allowed), it’s typically a soft pull. Insurance credit checks don’t behave like lender credit checks.

    6. Employer background checks

    When a prospective employer runs a credit check as part of a hiring decision — common in financial services, government, and positions involving fiduciary responsibility — it’s a soft pull. It requires your written permission under the FCRA, but it doesn’t affect your score. And no, the employer doesn’t see your score — they see a modified version of your credit report.

    7. Soft pulls by debt collectors (in some cases)

    Some debt collectors use soft pulls to locate consumers or monitor their financial situation. This is regulated and doesn’t affect your score.

    The big-picture takeaway: soft inquiries are the credit system’s background noise. They’re everywhere, they’re harmless, and they exist to let you and certain businesses stay informed without penalizing you.

    The Rate-Shopping Window Explained

    This is one of the most important — and most misunderstood — features of how credit scoring handles inquiries. If you’re shopping for a mortgage, auto loan, or student loan refinance, pay close attention.

    The problem the rate-shopping window solves

    Without any protection, shopping for the best mortgage rate would be financially punishing. Lender A pulls your credit. Lender B pulls your credit. Lender C pulls your credit. The dealer shops your auto application to five different banks. Suddenly you have six or seven hard inquiries on your report, and your score tanks — even though you only ever intended to take out one loan.

    That’s clearly unfair, and the credit scoring models recognize it. The solution is the rate-shopping window.

    How it works

    When you apply for the same type of loan — a mortgage, an auto loan, or a student loan — from multiple lenders within a specific time window, the FICO and VantageScore models treat those inquiries as a single inquiry for scoring purposes. The logic is that you’re rate-shopping, not actually trying to open seven separate mortgages.

    Here are the specifics:

    • FICO’s window: 14 to 45 days, depending on which version of the FICO model is being used. Older FICO models use a 14-day window. Newer FICO models (FICO 8, FICO 9, FICO 10) use a 45-day window. To be safe, do your rate shopping within 14 days — that way you’re covered regardless of which FICO version the lender uses.
    • VantageScore’s window: 14 days. VantageScore 3.0 and 4.0 both use a 14-day window across all loan types.
    • Which loan types qualify: Mortgages, auto loans, and student loans. Credit cards and personal loans are NOT covered. Each credit card application is its own inquiry, period.
    • Same loan type only: The window applies when you’re shopping for one specific type of loan. If you apply for a mortgage and an auto loan in the same week, those are two separate inquiries — they don’t get bundled together.

    What this means in practice

    If you’re buying a car and you want to compare rates from three banks, a credit union, and the dealership’s financing arm, do it within a 14-day window. All those auto loan inquiries will count as one inquiry for scoring purposes. You’ll still see each individual inquiry listed on your credit report (they don’t disappear from view), but the scoring math treats them as one.

    Same with a mortgage — get your quotes from multiple lenders within 14 days, and the scoring impact is the same as if you’d only applied to one.

    Important caveats

    • The inquiries still show up on your report individually. A lender who manually reviews your report will see that you applied to five auto lenders. But the scoring models, which most lenders rely on for automated decisions, treat them as one.
    • Some older FICO models don’t recognize the 45-day window and stick with 14 days. Stick to 14 days when possible.
    • The rate-shopping window does NOT apply to credit cards. Apply for five credit cards in a week and you’ll have five separate hard inquiries on your report, each one counting toward your score.
    • The window applies to the same type of loan. Mixing auto and mortgage applications in the same window doesn’t bundle them.

    The smart move

    If you know you’re going to be shopping for a mortgage or auto loan, do your research first — identify 3–5 lenders you want to compare — and then submit all the applications within a focused 14-day period. That maximizes the rate-shopping protection and minimizes the scoring impact. Spreading applications out over a month or two defeats the purpose.


    How Many Points Does a Hard Inquiry Really Cost?

    This is the question we hear more than any other. And the answer, in most cases, is reassuringly small.

    The typical range: 1 to 5 points

    For most people, a single hard inquiry lowers your credit score by 1 to 5 points. The exact number depends on your overall credit profile — someone with a long, flawless credit history may see no measurable change at all, while someone with a thin or weaker file may see a slightly larger dip. But the range is narrow, and it’s almost always on the lower end.

    Why the impact is so small

    Inquiries make up only about 10% of your FICO score. The much bigger factors are payment history (35%), amounts owed / credit utilization (30%), and length of credit history (15%). A single inquiry is a small fraction of a small fraction of your score. It’s not nothing, but it’s nowhere near the catastrophe many people imagine.

    The recovery timeline

    Here’s the good news: your score typically recovers from a single hard inquiry within about 6 to 12 months, assuming you continue making on-time payments and don’t take on significant new debt. After 12 months, the inquiry stops affecting your score entirely, even though it remains visible on your report for the full 24 months.

    Busting the “10 points per inquiry” myth

    You’ll sometimes see people online claiming that each hard inquiry costs 10 points (or more), and that a few applications can wreck your score. That’s not how it works. The scoring models don’t deduct a fixed number of points per inquiry — they evaluate the pattern of inquiries as part of a broader risk assessment. One or two inquiries on an otherwise healthy profile are a rounding error. The models get concerned when the pattern signals distress (see the next section).

    When the impact can be larger

    There are a few situations where a hard inquiry can cost more than the typical 1–5 points:

    • You have a thin credit file. If you have only one or two accounts and a short history, a new inquiry represents a larger proportional change to your profile, and the scoring impact can be more noticeable.
    • You already have several recent inquiries. The marginal impact of each additional inquiry can grow as the pattern starts to look riskier.
    • You’re right on a scoring threshold. If you’re sitting at, say, 679 (top of the “Fair” range) and a hard inquiry drops you to 674, that 5-point swing can feel bigger because you’ve crossed a category boundary — even though the underlying score change is small.

    The bottom line

    For the vast majority of people, a single hard inquiry is a minor, temporary dip — not a financial emergency. Don’t avoid applying for a credit card you genuinely want or need because you’re worried about a 3-point drop. Apply strategically, understand the trade-off, and focus on the bigger factors that actually move your score: paying on time and keeping utilization low.

    When Hard Inquiries Become a Red Flag

    So far we’ve established that individual hard inquiries are no big deal. But there’s a point where the pattern of inquiries starts telling a story that lenders don’t like.

    What the scoring models are looking for

    Credit scoring models don’t just count inquiries — they look for patterns that statistically correlate with elevated risk of default. The pattern that worries them most is multiple inquiries in a short period of time. When someone applies for six credit cards in two months, the models interpret that as potential financial distress — someone scrambling for credit because they’re running low on cash, or someone about to take on a pile of new debt all at once.

    How many is “too many”?

    There’s no hard, published threshold, because the models consider your overall profile, not just the inquiry count. But as a general guideline:

    • 1–2 inquiries in the past 12 months: Completely normal. Not a concern.
    • 3–5 inquiries in the past 12 months: Starting to look active. May raise an eyebrow with some lenders, especially for new credit card applications, but usually not a dealbreaker if the rest of your profile is strong.
    • 6+ inquiries in the past 12 months: This is where lenders get genuinely nervous. It suggests you’re either in financial distress or aggressively seeking new credit, both of which elevate risk.
    • Multiple inquiries across different loan types in a short window: This can look worse than multiple inquiries for the same loan type (which, as we discussed, are bundled by the rate-shopping window).

    The “credit-seeking” signal

    Lenders have their own internal risk models on top of the standard FICO/VantageScore. Some banks will decline a new credit card application based on “too many recent inquiries” even if your score is still in the 700s. This is sometimes called the “velocity” rule — they don’t like seeing a high rate of new credit applications, regardless of the absolute score.

    What to do if you already have several inquiries

    If you’ve accumulated more inquiries than you’d like:

    • Stop applying for new credit for a while. The 12-month scoring window is your friend. Each inquiry that crosses the one-year mark stops affecting your score.
    • Focus on the bigger factors. On-time payments and low utilization matter far more than inquiries. A strong payment history will carry you through a period of elevated inquiry activity.
    • Let time pass. Inquiries age out. In 12 months, they’re scoring-neutral. In 24 months, they’re gone entirely.
    • Check your reports for unauthorized inquiries. Sometimes inquiries appear that you didn’t initiate. We’ll cover how to handle that next.

    Can You Remove Hard Inquiries?

    This is a question that gets asked constantly, and the honest answer is: only if the inquiry is unauthorized, inaccurate, or the result of identity theft. You cannot have a legitimate hard inquiry removed early just because you don’t like it being on your report.

    When removal is possible

    A hard inquiry can be disputed and removed from your credit report if any of the following are true:

    • You never authorized it. If an inquiry appears from a company you never applied to, it may be the result of identity theft or an error by the lender.
    • It’s a duplicate. Sometimes the same inquiry gets recorded twice due to a processing error. The duplicate can be removed.
    • It’s older than 24 months. Inquiries should fall off automatically after two years, but if one lingers, you can dispute it.
    • The lender’s name or the date is wrong. Factual errors in the inquiry listing can be corrected or removed.

    When removal is NOT possible

    If you applied for a credit card, got approved or denied, and a hard inquiry was logged — that inquiry is legitimate and it stays on your report for the full 24 months (12 months for scoring purposes). You cannot pay to have it removed, and no credit repair company can legitimately remove it early. Anyone who promises to remove a legitimate hard inquiry for a fee is either scamming you or planning to dispute it fraudulently (which can backfire).

    How to dispute an unauthorized hard inquiry

    If you spot a hard inquiry on your report that you didn’t authorize, here’s the process:

    • Pull all three credit reports. Go to AnnualCreditReport.com — you’re entitled to a free copy of each bureau’s report every week under current federal rules. Review all three, because an inquiry may appear on one bureau’s report but not the others.
    • Identify the unauthorized inquiry. Note the lender name, the date, and which bureau(s) it appears on.
    • File a dispute with the bureau. Each bureau (Equifax, Experian, TransUnion) has an online dispute process. You can also dispute by mail or phone. State clearly that you did not authorize the inquiry and that you’re requesting its removal.
    • File a dispute with the lender. Contact the company that made the inquiry directly. They are required under the FCRA to investigate. If they can’t produce proof that you authorized the pull, they must request that the bureau remove it.
    • Consider a fraud alert or credit freeze. If the unauthorized inquiry is part of a pattern of identity theft — multiple inquiries you didn’t initiate, accounts you didn’t open — place a fraud alert with one of the bureaus (it will notify the other two), or place a credit freeze on all three reports to prevent new hard pulls.
    • File an identity theft report. If identity theft is involved, file a report with the FTC at IdentityTheft.gov and with your local police department. This creates a paper trail that supports your disputes.
    • Follow up. Bureaus typically have 30 days to investigate disputes. If the inquiry isn’t removed and you have evidence it was unauthorized, you can escalate — including filing a complaint with the Consumer Financial Protection Bureau (CFPB).

    What a reputable credit repair firm does

    This is where our work comes in. A legitimate, FCRA-compliant credit repair firm — and we count ourselves in that category — will:

    • Pull all three bureau reports and identify every unauthorized, duplicate, or factually incorrect inquiry.
    • File formal disputes with each bureau and follow up persistently.
    • Work directly with the furnishing lender when necessary.
    • Help you place fraud alerts or freezes if identity theft is involved.
    • Never promise to remove legitimate inquiries, and never charge upfront fees for work not yet done.

    If you’re seeing inquiries on your reports that you don’t recognize, that’s exactly the kind of thing a is designed to surface.

    Get a free credit audit.

    Pre-Qualified vs. Pre-Approved: What’s the Real Difference?

    These two terms get thrown around almost interchangeably in credit card mailers and online lending offers, but there’s a meaningful distinction — and it ties directly back to the hard vs. soft inquiry distinction.

    “Pre-Qualified” — a soft pull, a preliminary screen

    When you see “You’re pre-qualified for this card” in your mail or in an online lender’s tool, it means the lender has done a soft pull on your credit (or purchased a pre-screened mailing list from a bureau using soft-pull criteria) and determined that you meet some basic initial eligibility requirements. This is a light screen — they’ve looked at broad factors and decided you’re in the ballpark.

    Crucially, a pre-qualified offer does NOT guarantee approval. When you actually submit the application, the lender will do a hard pull and review your full credit profile. You can still be denied at that stage.

    Pre-qualification tools — like the ones on Capital One’s, Discover’s, or American Express’s websites — typically use a soft pull to show you offers you’d likely qualify for. Using them costs you nothing in score points. It’s a smart first step before formally applying.

    “Pre-Approved” — a stronger soft-pull screen, still not a guarantee

    “Pre-approved” sounds more definitive, and it usually does represent a stronger initial screen than pre-qualified — the lender has done a more detailed soft-pull review and determined you meet more of their underwriting criteria. Some lenders use the term “pre-approved” to signal a higher likelihood of final approval.

    But — and this is important — “pre-approved” is still not a guarantee. The formal application still triggers a hard pull, and the lender can still decline you based on the full review. The language used in these offers is carefully hedged for legal reasons; the firm offer of credit you receive in a pre-screened mailing is conditional on your credit profile not having materially changed since the screening.

    What this means for you

    • Use pre-qualification and pre-approval tools before formally applying. They’re free, they’re soft pulls, and they give you a real sense of your approval odds before you take the hard-inquiry hit.
    • Don’t treat either as a guarantee. You can still be denied after a formal application. The only way to know for sure is to submit the application and let the lender do the hard pull.
    • A pre-qualified or pre-approved offer in the mail does not affect your score. The screening was a soft pull. Throwing the offer away or acting on it later doesn’t change that.
    • Responding to the offer by formally applying does trigger a hard pull. The pre-screen was soft; the application is hard. That’s the trade-off.

    A note on “firm offers of credit”

    Under the FCRA, when a lender uses a bureau’s pre-screening service to send you a pre-approved offer, they’re making what’s called a firm offer of credit. If you respond to the offer and your credit hasn’t materially changed, they’re generally obligated to extend the credit — though there are exceptions. This is a consumer protection built into the law. If you’re ever denied after responding to a firm offer, you have the right to ask why and to request the specific reasons.

    Hard vs soft inquiries and how they affect your credit score

    How to Minimize Inquiries When Shopping for a Loan

    If you’re planning to apply for a mortgage, auto loan, or personal loan, here’s how to keep your inquiry impact as small as possible:

    1. Use pre-qualification tools first

    Many lenders — especially for credit cards, personal loans, and auto loans — offer pre-qualification tools on their websites that use a soft pull. Use them. They’ll tell you whether you’re likely to qualify before you commit to a formal application. This lets you skip lenders who would probably deny you, saving the hard inquiries for lenders where your odds are real.

    2. Cluster your rate shopping in a 14-day window

    For mortgages, auto loans, and student loan refinancing, the rate-shopping window treats multiple inquiries for the same loan type as one — but only within the window. Do your homework first (identify your target lenders, gather your documents), then submit applications within a tight 14-day period to maximize the protection. Don’t spread them across two months.

    3. Don’t apply for credit cards while shopping for a loan

    A common mistake: someone is mortgage shopping and, in the middle of it, applies for a new rewards credit card or finances new furniture for the house they’re about to buy. That’s a separate hard inquiry outside the rate-shopping window for the mortgage, and worse, the new credit account changes your utilization and credit age — which can spook a mortgage underwriter. While a major loan is in underwriting, freeze your new credit applications entirely.

    4. Ask before you apply

    If you’re not sure whether a credit check will be hard or soft, ask. “Will opening this account trigger a hard or soft credit pull?” is a reasonable question that any reputable company should answer before you commit. This is especially relevant for utilities, cell phone contracts, bank accounts, and rental applications.

    5. Space out credit card applications

    Credit card inquiries don’t get bundled by the rate-shopping window, so each one counts. If you’re building a portfolio of cards (for rewards, for example), space applications out — generally at least 6 months between credit card applications is a sensible rule of thumb for most people, and many “chase” enthusiasts follow stricter guidelines.

    6. Be cautious with “apply now” buttons

    Online marketplaces — credit card comparison sites, lending marketplaces, rate-comparison tools — sometimes pass your information to multiple lenders, each of which may do a hard pull. Read the language carefully. Reputable comparison tools will tell you whether clicking through results in a hard or soft pull, and they’ll use soft pulls for the initial comparison stage.

    7. Monitor your reports

    Pull your reports from all three bureaus regularly (you can do this for free every week at AnnualCreditReport.com). Verify that every hard inquiry on there is one you authorized. If something looks wrong, dispute it immediately.


    Do Inquiries Matter If You’re Rebuilding Credit?

    If you’re working to rebuild a damaged credit profile, your relationship to inquiries is a little different. Here’s how to think about it.

    Inquiries still matter — but less than you might think

    The scoring models don’t treat someone rebuilding credit dramatically differently than someone with a strong profile when it comes to inquiries. A single hard inquiry still costs roughly 1–5 points, and it still stops affecting your score after 12 months. What changes is context — your score is already lower, so a 5-point drop represents a larger proportion of your available scoring headroom, and it can feel more significant.

    The bigger factors are still bigger

    If you’re rebuilding, the factors that move your score the most are still payment history (35% of FICO) and credit utilization (30%). A single missed payment costs you vastly more than a dozen hard inquiries. A maxed-out credit card costs you more than every hard inquiry on your report combined. If you’re choosing where to focus your energy, focus on on-time payments and paying down balances — not on avoiding every possible inquiry.

    But be strategic about new applications

    When you’re rebuilding, you should be more cautious about applying for new credit — not because of the inquiry itself, but because of what the application represents. Each new application is a chance to be denied (which doesn’t directly hurt your score, but wastes the inquiry), and each new credit account you open changes your credit age and utilization calculations. Be intentional. Apply only for credit you have a realistic chance of being approved for and a clear plan to manage well.

    Tools for rebuilding credit

    If you’re rebuilding, your best tools are:

    • A secured credit card — a card backed by a refundable deposit, designed for people rebuilding credit. Use it for small purchases, pay it in full each month, and let the on-time payment history build your score.
    • A credit-builder loan — offered by many credit unions and some online lenders, these hold the loan proceeds in a savings account while you make payments, building payment history without the risk of running up debt.
    • Authorized user status — being added as an authorized user on a trusted family member’s long-standing, well-managed credit card can import their positive payment history onto your report.
    • Consistent on-time payments — every single month, on every single account. This is the single most powerful thing you can do.

    Don’t let inquiry anxiety stop you from building

    One mistake we see sometimes: people who are rebuilding become so afraid of hard inquiries that they never apply for the credit-building tools they need. A secured card requires a hard pull. A credit-builder loan may require a hard pull. If you refuse every hard pull, you also refuse every opportunity to build the payment history that will actually help you. The smart play is to apply for the right tools strategically — one or two well-chosen applications — and then focus on the behavior that actually builds the score.

    How a credit repair firm fits in

    If you’re rebuilding and you have negative marks on your reports — late payments, collections, charge-offs, inaccuracies — a reputable credit repair firm can help you address those underlying issues, which will have a far larger impact on your score than worrying about inquiries. The inquiry question is small potatoes next to the question of “is everything on my report accurate and verifiable?”


    Common Myths About Credit Inquiries — Busted

    There’s a lot of bad information out there about credit inquiries. Let’s take down the most common myths one by one.

    Myth 1: “Checking your own credit hurts your score.”

    False. Checking your own credit is always a soft pull, and soft pulls have zero impact on your score. You can check your credit every day and your score won’t move because of it. In fact, regularly monitoring your credit is one of the smartest financial habits you can develop — it helps you catch errors, fraud, and unauthorized inquiries early. Please, check your own credit. Often.

    Myth 2: “Each hard inquiry costs you 10 points.”

    False. There is no fixed per-inquiry point deduction. A single hard inquiry typically costs 1–5 points, and the exact impact depends on your overall credit profile. The scoring models evaluate the pattern of inquiries, not a per-inquiry tariff. Ten points per inquiry is a myth that vastly overstates the reality.

    Myth 3: “All inquiries stay on your report for 7 years.”

    False. Hard inquiries stay on your report for 24 months and affect your score for only 12 months. Negative account information (late payments, collections, charge-offs) can stay for 7 years — and that’s probably where this myth comes from. But inquiries are a different category with a much shorter lifespan.

    Myth 4: “Credit Karma lowers your score.”

    False. Credit Karma uses soft pulls to show you your score and report. It cannot lower your score. What can confuse people is that Credit Karma shows VantageScore 3.0 scores, which may differ from the FICO scores a lender uses — so the number you see on Credit Karma might not match what a mortgage lender pulls. But that’s a scoring model difference, not a score impact from checking.

    Myth 5: “Pre-qualified offers hurt your credit.”

    False. The pre-screening that generates pre-qualified offers is a soft pull. Receiving a stack of pre-qualified credit card offers in the mail does not affect your score at all. Only when you formally apply does a hard pull occur.

    Myth 6: “A credit repair company can remove any hard inquiry.”

    False — and anyone who promises this is either scamming you or planning to file fraudulent disputes. Only unauthorized, inaccurate, or duplicate inquiries can be removed. A legitimate hard inquiry that resulted from an application you submitted stays on your report for the full 24 months. No legitimate credit repair firm will promise to remove it.

    Myth 7: “Rate shopping always hurts your score.”

    False. The rate-shopping window is specifically designed to protect you when shopping for a mortgage, auto loan, or student loan. If you cluster your applications within a 14-day window, the inquiries count as one for scoring purposes. Shop confidently for the best rate — that’s the smart financial move.

    Myth 8: “Inquiries are the biggest factor in your credit score.”

    False. Inquiries make up about 10% of your FICO score. Payment history (35%) and credit utilization (30%) dwarf inquiries in importance. If you want to improve your score, focus on paying on time and keeping your credit card balances low relative to your limits. Obsessing over inquiries while missing payments is putting your energy in exactly the wrong place.

    Myth 9: “You should avoid all hard inquiries.”

    False. Applying for credit is a normal, healthy part of building a credit profile. Without hard inquiries, you’d never open new accounts, and your credit file would stay thin. The goal isn’t to avoid inquiries entirely — it’s to apply strategically, only when you have a real need and a reasonable chance of approval.

    Myth 10: “Soft inquiries show up to lenders and make you look desperate for credit.”

    False. Soft inquiries appear only on the consumer version of your report — the one you see. Lenders do not see them. A lender reviewing your credit application has no idea how many times you’ve checked your own credit, how many pre-qualified offers you’ve been screened for, or whether your existing creditors have been reviewing your account. Those are all invisible to them.

    Frequently Asked Questions

    1. How long does a hard inquiry stay on my credit report?

    A hard inquiry stays on your credit report for 24 months from the date it was made. However, it only factors into your credit score for the first 12 months. After one year, the inquiry stops affecting your score; after two years, it falls off your report entirely.

    2. Does checking my own credit lower my score?

    No. Checking your own credit is always a soft pull, and soft pulls have zero impact on your credit score. You can check your credit as often as you like — through AnnualCreditReport.com, Credit Karma, your bank’s credit monitoring, or any similar service — without affecting your score.

    3. How many points does a hard inquiry cost?

    A single hard inquiry typically lowers your credit score by 1 to 5 points. The exact impact depends on your overall credit profile. The drop is usually small and temporary, with most scores recovering within 6 to 12 months as long as you keep making on-time payments.

    4. If I apply for five auto loans in two weeks, does that hurt my score five times?

    No. Thanks to the rate-shopping window, multiple inquiries for the same type of loan (auto, mortgage, or student loan) within a 14-day period are treated as a single inquiry for scoring purposes. The individual inquiries will still appear on your report, but the scoring math counts them as one. Note: this protection does NOT apply to credit cards — each credit card application is its own inquiry.

    5. Can I remove a hard inquiry from my credit report?

    Only if the inquiry is unauthorized, inaccurate, a duplicate, or older than 24 months. If you didn’t apply for credit with the company listed, you can dispute the inquiry with the credit bureau and the lender. Legitimate inquiries — ones that resulted from applications you actually submitted — cannot be removed early and will remain on your report for the full 24 months.

    6. What’s the difference between pre-qualified and pre-approved?

    Both are based on a soft pull and neither affects your credit score. “Pre-qualified” generally means the lender did a basic screen and you appear to meet initial criteria. “Pre-approved” typically means a more thorough screen and a stronger likelihood of approval. Neither is a guarantee. When you formally apply, the lender does a hard pull, and you can still be denied.

    7. Will requesting a credit limit increase hurt my score?

    It depends on the issuer. Some credit card companies do a hard pull when you request a limit increase; others use a soft pull. Before requesting an increase, ask the issuer’s customer service whether it will be a hard or soft inquiry. If it’s a hard pull and you’re worried about the small score impact, you can decline to proceed.

    8. What should I do if I see a hard inquiry I don’t recognize?

    Dispute it. Pull all three credit reports from AnnualCreditReport.com, identify the unauthorized inquiry, and file a dispute with the bureau(s) showing it. Also contact the company that made the inquiry directly — under the FCRA, they must investigate and provide proof you authorized the pull. If you suspect identity theft (multiple unauthorized inquiries, accounts you didn’t open), place a fraud alert with one bureau, consider a credit freeze, and file a report with the FTC at IdentityTheft.gov.

    Take Control of Your Credit Inquiries

    Here’s what we’ve covered, distilled to its essence:

    • Hard inquiries happen when you apply for new credit. They cost about 1–5 points, stay on your report for 24 months, and affect your score for only 12 months. They’re a small, temporary cost of doing business with the credit system.
    • Soft inquiries happen when you check your own credit, when lenders screen you for pre-qualified offers, when existing creditors monitor your account, or when an employer runs a background check. They have zero impact on your score and they’re invisible to lenders.
    • The rate-shopping window protects you when you’re shopping for a mortgage, auto loan, or student loan — cluster your applications within 14 days and they count as one inquiry.
    • Unauthorized inquiries can be disputed and removed, but legitimate ones cannot. Anyone who promises to remove a legitimate hard inquiry for a fee is not being honest with you.
    • The biggest factors in your score are payment history and credit utilization, not inquiries. Focus your energy there.
    • Checking your own credit is one of the smartest financial habits you can build. It does not hurt your score. Do it regularly.

    If you’re seeing inquiries on your credit reports that you don’t recognize — or if you just want a clear-eyed look at everything that’s currently on your three bureau reports — that’s exactly what our is for. As part of the audit, we’ll review all three bureau reports, flag any unauthorized or suspicious inquiries, identify any inaccurate negative marks, and walk you through a customized plan to address what we find.

    We’re a San Diego-based, FCRA-compliant, attorney-backed credit repair firm serving clients nationwide. We don’t make empty promises or sell quick fixes. We believe in transparency, legal compliance, and measurable progress — and we equip you with the knowledge to keep your credit strong long after the work is done.

    Ready to see where you stand? today.

    Get a free credit audit.

  • 9 Credit Repair Tips You Can Use Today (No Company Required)

    9 Credit Repair Tips You Can Use Today (No Company Required)

    Put these tips to work: master your credit utilization ratio for the fastest score boost, learn how to dispute credit report errors across all three bureaus, see whether a credit builder loan could accelerate your progress, and discover all the steps you can take with our guide to fixing your credit for free.

    If your credit score has been holding you back — from a better mortgage rate, an apartment approval, a new credit card, or even a job offer — you already know how heavy that number can feel. The good news is that credit repair is not a black box. It’s a process governed by federal law, and most of it is something you can do yourself, for free, without hiring anyone.The even better news: the most impactful credit repair tips don’t require special software, insider connections, or a paid service. They require understanding how the credit system works, knowing your rights, and applying consistent effort over time.This guide walks through nine actionable credit repair tips you can start using today — no company required. Every tip includes the why behind it, a step-by-step how, and an honest assessment of the impact and timeline you can expect. We’ll also cover the common mistakes that quietly undo progress, when DIY isn’t enough, your rights under the Credit Repair Organizations Act (CROA), and a FAQ section answering the questions we hear most often.A quick note before we begin: we are a San Diego-based, FCRA-compliant, attorney-backed credit repair firm. We’re sharing these tips because we believe an educated client is a successful client — whether you ever work with us or not. If you reach a point where you want professional help, we’re here. If not, this guide still gets you further than you are today.

    The Honest Expectation: Real Credit Improvement Takes Consistency, Not Tricks

    Let’s start with the truth that a lot of “credit repair” ads won’t tell you.

    There is no overnight fix. Anyone who promises to boost your score 100 points in 30 days is either lying, planning to do something illegal, or describing a narrow situation that won’t apply to most people. Real credit repair is built on three things:

    • Accuracy — making sure your credit reports reflect only true, verifiable, and legally reportable information.
    • Behavior — building a payment history and credit utilization pattern that scoring models reward.
    • Time — giving negative (but accurate) items room to age off your report naturally, while positive habits compound.

    The Fair Credit Reporting Act (FCRA) gives you the right to dispute anything on your report that is inaccurate, incomplete, or unverifiable. That’s a powerful lever, and it’s the backbone of DIY credit repair. But the FCRA does not give you the right to have accurate, verifiable negative information removed early. If a late payment actually happened, it can stay on your report for up to seven years. The same goes for collections, charge-offs, and most public records.

    So the realistic path looks like this: you remove what shouldn’t be there (inaccuracies, duplicates, outdated items, unverifiable accounts), you optimize what is there (utilization, payment history, account age), and you wait out the rest with a growing buffer of positive history.

    Most people who follow this process seriously see meaningful improvement within 3 to 6 months and significant improvement within 12 to 24 months. Some changes — like lowering your utilization — can move your score within weeks. Others, like aging out a collections account, are on a longer clock.

    If that timeline sounds daunting, here’s the encouraging part: the work itself is not complicated. It’s mostly free, it’s mostly yours to do, and the nine tips below cover the vast majority of what any credit repair company would do for you on the accuracy-and-behavior side.

    Let’s get into them.

    1. Pull All Three Credit Reports for Free First

    What it is

    Before you can fix anything, you need to see what’s on your credit reports — and yes, that’s “reports,” plural. You have three of them: one each from Experian, Equifax, and TransUnion. They are not identical. Lenders don’t always report to all three bureaus, so an account showing up on your Equifax report might be absent from your TransUnion report, and vice versa. A score pulled from one bureau can differ by 30, 50, or even 80+ points from a score pulled from another.

    Why it works

    You can’t dispute what you haven’t seen. You can’t spot identity theft if you don’t know what accounts are listed under your name. And you can’t prioritize which credit repair tips to apply first without a full picture of your current standing. Pulling all three reports is the single highest-value first step in any DIY credit repair effort — and it’s completely free.

    How to do it, step by step

    • Go to AnnualCreditReport.com. This is the only federally authorized website for free credit reports. Despite what the catchy jingle commercials suggest, many “free” credit report sites enroll you in paid monitoring after a trial. AnnualCreditReport.com does not.
    • Request all three reports. You are legally entitled to one free report from each bureau every 12 months — and since the COVID-19 pandemic, the bureaus have generally allowed weekly pulls for free. Take advantage.
    • Download or print each report as a PDF. You’ll want a stable copy to work from, annotate, and compare.
    • Review each report line by line. For every account listed, check:
    • Is this actually my account?
    • Is the balance correct?
    • Is the payment history accurate (especially any “late” or “missed” markers)?
    • Is the account status correct (open/closed, current/past due)?
    • Are there duplicate entries for the same debt?
    • Are there accounts from creditors you don’t recognize? (A red flag for identity theft or mixed files.)
    • Are there items older than the legal reporting window (typically 7 years for most negatives, 10 years for Chapter 7 bankruptcy)?
    • Make a list of every item you believe is inaccurate, incomplete, or unverifiable. This list becomes your dispute roadmap.
    • Note your personal information too. Incorrect names, addresses, or employers on your report can signal a mixed file (where someone else’s credit history has been merged with yours). These are worth disputing.

    Expected impact and timeline

    Pulling the reports doesn’t change your score directly — but it’s the prerequisite for every other action on this list. Expect to spend 30 to 60 minutes on a thorough review of all three reports. The disputes you file as a result (see Tip 2) can start moving your score within 30 to 45 days.

    Internal link placeholder: — Want a professional review of all three bureau reports? Our free credit audit flags inaccuracies, outdated items, and dispute opportunities in one pass. Get a free credit audit.

    2. Dispute Every Inaccuracy You Find (the FCRA Process)

    What it is

    Once you’ve identified errors on your credit reports, the FCRA gives you the legal right to dispute them — directly with the credit bureaus, directly with the furnisher (the creditor or collections agency that reported the information), or both. The bureaus are required to investigate your disputes (usually within 30 days), and if an item cannot be verified as accurate, it must be corrected or removed.

    Why it works

    Credit bureaus don’t verify the accuracy of every item they receive — they rely on furnishers to report accurately and on consumers to flag errors. Studies and regulator findings (including from the Consumer Financial Protection Bureau) have repeatedly shown that a meaningful percentage of credit reports contain errors serious enough to affect a consumer’s score. Some of those errors are small; some are big enough to cost someone a loan approval or a job.

    When you dispute an item, the bureau must contact the furnisher and ask them to verify it. If the furnisher can’t — because records are lost, because the account was sold, because the information was reported in error, or because the furnisher simply doesn’t respond within the investigation window — the item comes off your report. That’s the law.

    How to do it, step by step

    • Decide where to dispute. You can dispute with the credit bureau(s) showing the error, with the furnisher directly, or both. Disputing with the bureau is the more common starting point and tends to be simpler. Disputing with the furnisher can be useful when you have documentation that the furnisher’s records are wrong.
    • File the dispute in writing. While all three bureaus offer online dispute portals, written disputes sent by certified mail with return receipt give you a paper trail, a date stamp, and legal proof of delivery. This matters if you later need to escalate or take legal action.
    • Be specific. For each disputed item, identify:
    • The account name and account number (or at least a clear identifier).
    • The specific piece of information you’re disputing (the balance, the late-payment marker, the account status, etc.).
    • The reason for your dispute (not my account, never late, balance is wrong, account was discharged in bankruptcy, item is older than 7 years, etc.).
    • Any supporting documentation (a statement showing a $0 balance, a letter from the creditor, a bankruptcy discharge order, etc.).
    • Keep copies of everything. Your dispute letter, your attachments, your certified mail receipt, and the return receipt when it comes back.
    • Wait for the investigation. The bureau generally has 30 days to investigate (45 days if you sent additional information after pulling your free annual report). They must provide you with the results in writing, including a free updated copy of your report if the dispute resulted in a change.
    • If the item is verified and remains, evaluate next steps. You can dispute again with new information, dispute with the furnisher directly, file a complaint with the CFPB, or — for persistent, provable errors — consult an attorney about potential FCRA violations.
    • If the item is removed, great. Monitor your report in the following months to confirm it doesn’t reappear (sometimes called “reinsertion,” which has its own FCRA rules requiring the bureau to notify you within 5 days).

    What to dispute (common, legitimate targets)

    • Accounts that aren’t yours (identity theft or mixed file).
    • Late payments that didn’t happen.
    • Balances that are wrong (already paid off, wrong amount).
    • Accounts showing as open when they’re closed (or vice versa).
    • Duplicate accounts (same debt listed twice, sometimes under different furnishers).
    • Items older than the reporting window (7 years for most negatives, 10 for Chapter 7 bankruptcy).
    • Collections for debts you already paid or settled.
    • Public records that are inaccurate or outdated.

    What NOT to dispute

    Don’t dispute accurate, verifiable negative information just to “see if it sticks.” Frivolous disputes can be rejected by the bureaus, and repeat frivolous disputes can result in your disputes being flagged and ignored. Focus on items that are genuinely inaccurate, incomplete, or unverifiable.

    Expected impact and timeline

    Successful disputes can remove significant negative items, with score impact ranging from a few points (for a minor correction) to 30, 50, or even 100+ points (for removal of a major derogatory like a collections account or a charge-off that was reporting in error). The investigation process takes 30 to 45 days, and you’ll see the score impact once the updated report is reflected — usually within a week or two of the resolution.

    Internal link placeholder: — Our team handles FCRA-compliant disputes across all three bureaus, including escalations when furnishers refuse to verify.

    3. Lower Your Credit Utilization Immediately

    What it is

    Credit utilization is the percentage of your available revolving credit (credit cards, primarily) that you’re currently using. If you have $10,000 in total credit limits across your cards and you carry $3,000 in balances, your utilization is 30%.

    Utilization is one of the most influential factors in your credit score under both major scoring models (FICO and VantageScore). It falls under the “amounts owed” category, which is worth roughly 30% of your FICO score — making it the second-most-weighted factor after payment history.

    Why it works

    Scoring models interpret high utilization as a signal of financial stress. If you’re using most of your available credit, the models reason, you may be relying on credit to cover expenses — which raises the statistical risk that you’ll miss a payment or default. Conversely, low utilization signals that you’re managing credit comfortably.

    The conventional guidance is to stay below 30% utilization. But the truth is, the lower the better — people with the highest scores typically use less than 10% of their available credit. And here’s a detail many people miss: utilization is calculated both per-card and overall. A single maxed-out card can hurt your score even if your total utilization looks fine.

    How to do it, step by step

    There are three main levers, and you can combine them:

    Lever A: Pay down existing balances.

    • List every revolving account with its current balance and credit limit.
    • Calculate per-card utilization and total utilization.
    • Prioritize paying down the card(s) with the highest utilization first — bringing each card under 30%, then under 10% if possible.
    • If you can’t pay in full, pay as much as you can above the minimum.

    Lever B: Request credit limit increases.

    • Contact each credit card issuer (usually via the online account portal or by calling).
    • Ask for a credit limit increase. Many issuers have a soft-pull option that won’t ding your score with a hard inquiry.
    • Do not use the new credit. The goal is to lower your utilization ratio, not to give yourself more spending room. If a higher limit tempts you to spend more, skip this lever.
    • Be aware that some issuers do a hard pull for limit increases — ask before you confirm.

    Lever C: Make mid-cycle payments.

    • Most card issuers report your balance to the bureaus on your statement closing date — not on your payment due date.
    • If you pay your bill in full on the due date but you’ve been carrying a high balance during the billing cycle, the bureau may still see a high utilization when the statement closes.
    • To avoid this, make a payment a few days before your statement closing date to bring the reported balance down.
    • You can find your statement closing date on your statement or in your online account.

    Expected impact and timeline

    This is one of the fastest score-boosting levers in credit repair. Because utilization has no “memory” in most scoring models (it updates with each new reported balance), lowering your utilization can move your score within one billing cycle — often 30 to 45 days. The impact can be significant: dropping from 80% utilization to under 10% can lift a score by 30 to 60 points or more, depending on the rest of your profile.

    4. Never Miss Another Payment — Automate It

    What it is

    Payment history is the single most important factor in your credit score — worth about 35% of your FICO score. One missed payment can drop a good score by 60 to 80 points or more, and the later it is (30, 60, 90 days), the more damage it does. A 90-day late payment is treated by scoring models as a major derogatory, similar in impact to a collections account.

    The most reliable way to never miss another payment is to automate it.

    Why it works

    Human memory is unreliable. Life gets busy, statements get lost in the mail (or buried in the inbox), due dates slip, and suddenly you’re 30 days late on a card you’ve had for a decade. Automation removes the human error factor entirely. When at least your minimum payment is set to auto-pay, you guarantee that a missed payment due to forgetfulness becomes physically impossible.

    How to do it, step by step

    • Set up auto-pay for the minimum payment on every account. Log into each creditor’s online portal and enable automatic payments for at least the minimum due, drawn from your primary checking account on the due date (or a few days before).
    • If you can, set auto-pay for the full statement balance. This is ideal for cards you use regularly — it ensures you never carry a balance, never pay interest, and never miss a payment. Just make sure your checking account can absorb the monthly draw.
    • For accounts where you can’t auto-pay the full balance, set auto-pay for the minimum and then manually pay extra. This protects you from missing the due date while still letting you pay down principal faster.
    • Set payment alerts as a backup. Most banks and card issuers let you set text or email alerts for when a statement closes and when a payment is due. These are a useful secondary safety net even with auto-pay on.
    • Align due dates if possible. Some issuers let you change your payment due date. Grouping due dates around a predictable income deposit date (e.g., right after payday) reduces the chance of an overdraft on auto-pay.
    • Keep a buffer in your checking account. Auto-pay only works if the funds are there. Aim for at least one month’s worth of minimum payments as a floor balance.

    What if you’ve already missed payments?

    If you have recent late payments on your report, the damage is real but not permanent. Late payments stay on your report for up to 7 years, but their impact fades over time — a 2-year-old late payment hurts far less than a 2-month-old one. The most important thing is to stop the bleeding: get current, stay current, and let time do its work. See Tip 7 for a strategy that can sometimes remove one-time late payments earlier.

    Expected impact and timeline

    Preventing future missed payments doesn’t “raise” your score instantly — but it stops the single most damaging thing from happening to your credit. Over time, a clean payment history is the foundation that lets every other tip on this list reach its full impact. You’ll see the benefits compound over 6 to 24 months as your recent payment history becomes unblemished.

    If you’ve had a recent missed payment and you get current, the score recovery begins immediately — the “currently past due” status clears, and your score often ticks up within 30 to 60 days of getting back to current status.

    5. Keep Your Oldest Credit Card Open

    What it is

    The age of your credit accounts is a meaningful scoring factor — worth about 15% of your FICO score. Scoring models look at both the age of your oldest account and the average age of all your accounts. Generally, the older your credit history, the better your score.

    When you close an old credit card, two things happen:

    • That account eventually drops off your credit report (closed accounts in good standing typically stay for up to 10 years, but closed accounts with negative history can drop sooner).
    • Your total available credit decreases, which can raise your utilization ratio (see Tip 3).

    Why it works

    Keeping your oldest account open preserves the length of your credit history — both your oldest-account age and your average account age. It also keeps that account’s available credit in your total utilization calculation, which helps keep your utilization low.

    This is especially important for cards with no annual fee that you’ve had for many years. Even if you don’t use the card regularly, keeping it open costs you nothing and quietly supports your score.

    How to do it, step by step

    • Identify your oldest credit card. Check your credit reports for the “date opened” field on each account.
    • If it has an annual fee, evaluate the cost-benefit. A card with a $95 annual fee that you never use may not be worth keeping indefinitely. Options:
    • Ask the issuer to downgrade the card to a no-annual-fee version within the same product family. This usually preserves the account’s age and credit line.
    • If downgrade isn’t possible, weigh the annual fee against the score benefit. For a card you’ve had for 10+ years, paying $95/year to protect your score may be worth it until your other accounts have aged.
    • If it has no annual fee, keep it open. Period.
    • Keep the card active. An issuer may close an inactive account (which can hurt your score). To prevent this:
    • Put one small recurring charge on the card (a streaming subscription, a phone bill, etc.).
    • Set up auto-pay for that charge so it’s paid in full every month.
    • Check the card once a quarter to make sure it’s still active and no fraudulent charges have appeared.
    • Don’t worry about the card’s interest rate. If you’re paying the balance in full every month (which you should be), the APR is irrelevant.

    Expected impact and timeline

    This is a long-game tip. Keeping an old card open doesn’t produce an instant score bump, but it preserves a scoring factor that would otherwise erode. The benefit shows up over years, not weeks. Closing an old card, by contrast, can cause a small-to-moderate score drop — sometimes 10 to 20 points — both from the age reduction and the utilization increase, though the age impact is delayed.

    6. Become an Authorized User on a Trusted Family Member’s Card

    What it is

    An authorized user is someone added to another person’s credit card account. The authorized user gets a card in their name and can make purchases, but they are not legally responsible for the debt — the primary account holder is.

    Crucially, most credit card issuers report the account to the credit bureaus for both the primary holder and the authorized user. That means the authorized user’s credit report can inherit the account’s payment history, age, and utilization — as if it were their own.

    Why it works

    If you have a thin credit file, a short credit history, or a damaged score, being added as an authorized user to a well-managed, older account can give your score a quick and meaningful boost. You inherit:

    • The account’s age (which can improve your average age of accounts).
    • The account’s clean payment history (the most important scoring factor).
    • The account’s credit limit (which can lower your overall utilization).

    This strategy is sometimes called “piggybacking,” and when done with a trusted family member’s card, it’s entirely legal and legitimate.

    How to do it, step by step

    • Choose the right primary account holder. The ideal card has:
    • A long history (ideally 5+ years, the older the better).
    • A perfect or near-perfect payment history (no late payments).
    • A high credit limit and low utilization (under 10% is ideal).
    • A history of consistent, on-time payments.
    • Ask a trusted family member or spouse to add you. Be clear that you do not need physical access to the card — they can add you as an authorized user and simply not give you the card. This is a common arrangement and removes any spending-risk concern.
    • Confirm the issuer reports authorized users to all three bureaus. Most major issuers do, but it’s worth confirming. The primary holder can call the issuer and ask: “If I add an authorized user, will the account be reported on their credit report at all three bureaus?”
    • Be added and wait. Once you’re added, it typically takes one to two billing cycles for the account to appear on your credit reports.
    • Monitor your reports to confirm the account appears. If it doesn’t show up after 60 days, the issuer may not report authorized users — in which case, ask the primary holder to check with the issuer or consider a different card.

    Important caveats

    • You inherit the bad along with the good. If the primary holder misses a payment or maxes out the card, that negative history shows up on your report too. Choose someone whose credit habits you trust completely.
    • You can be removed. If the account starts hurting rather than helping, the primary holder can remove you as an authorized user. Once removed, the account typically stops reporting new activity to your file (though what was already reported may remain for a time).
    • Scoring models vary in how they treat authorized user accounts. FICO 8 and most VantageScore models do consider authorized user accounts. Some newer or industry-specific models may weight them differently. But for most consumers, the benefit is real.

    Expected impact and timeline

    This is one of the quickest legitimate score boosts available. Once the account appears on your report (usually within 30 to 60 days of being added), the impact can be significant — especially for people with thin files or short histories. Score increases of 15 to 40 points are common, and for someone with very limited credit, the jump can be even larger.

    7. Request Goodwill Deletions for One-Time Late Payments

    What it is

    A goodwill deletion (or “goodwill adjustment”) is a request you make directly to a creditor asking them to remove a late payment from your credit report as a courtesy — not because the late payment was inaccurate, but because it was an isolated mistake and you’ve otherwise been a good customer.

    This is different from a dispute. A dispute says “this is wrong.” A goodwill request says “this is right, but I’m asking you to remove it anyway as a gesture of goodwill.”

    Why it works

    Creditors are not obligated to grant goodwill requests, but many do — especially for long-term customers with a single late payment who have since returned to on-time payments. Creditors weigh the cost of keeping a negative mark (which may push you to close the account or stop using the card) against the benefit of keeping a loyal customer happy. For a one-time lapse on an otherwise strong account, the math often favors saying yes.

    How to do it, step by step

    • Identify the target. Look for accounts with a single late payment (30 or 60 days late) where you’ve otherwise paid on time. A 90-day late is much harder to get removed via goodwill.
    • Get current first. If you’re still past due on the account, get current before sending a goodwill request. Creditors are unlikely to grant goodwill to someone who’s still behind.
    • Write a goodwill letter. Address it to the creditor (not the credit bureau). Keep it brief, polite, and specific:
    • State your account number and the specific late payment you’re asking them to remove (include the date).
    • Briefly explain the circumstances — was it a medical emergency, a job transition, a postal issue, a one-time oversight? Be honest.
    • Emphasize your otherwise clean history with the account (e.g., “I’ve been a customer for 6 years and this is the only late payment on my record”).
    • Explicitly request that they remove the late payment from your credit report as a goodwill courtesy.
    • Thank them for considering the request.
    • Send it to the right place. Look for a correspondence address on your statement, the creditor’s website, or their credit bureau dispute department. Some creditors have a specific address for goodwill requests. Certified mail with return receipt is recommended for the paper trail.
    • Be patient. Creditors can take 30 to 60 days to respond. If you don’t hear back, follow up.
    • If denied, try again later. Some creditors have an informal internal policy of granting goodwill after a certain period of perfect payments post-late. A denial now doesn’t mean a denial in 6 months.

    What to expect

    Goodwill deletions are never guaranteed — creditors are within their rights to say no, and accurate late payments can legally remain on your report for up to 7 years. But when they work, the impact is immediate and clean: the late payment disappears, and your score can jump 20 to 50 points or more depending on how damaging the late was to your profile. Results typically show up within 30 to 60 days of the creditor granting the request.

    This tip is most effective when:

    • The late payment was isolated (one time, not a pattern).
    • You’ve had a long, otherwise-positive relationship with the creditor.
    • The late was recent enough to be hurting your score but old enough that you’ve demonstrated recovery.

    8. Handle Collections Strategically

    What it is

    A collections account appears on your credit report when an original creditor gives up on collecting a debt and either sells it to a collections agency or hires an agency to collect on their behalf. Collections are among the most damaging items on a credit report — a single new collection can drop a good score by 60 to 100 points.

    But not all collections are created equal, and how you handle them matters enormously. The three strategic options are: validate, negotiate, or wait it out.

    Why it works

    9 credit repair tips for improving your credit score

    Collections have a surprising amount of nuance:

    • Not every collections account is valid or verifiable.
    • Some collections can be negotiated down or removed entirely with the right approach.
    • All collections have a reporting lifespan — they must be removed after 7 years (measured from the original delinquency date, not the collection date).

    Option A: Validate the debt

    Under the Fair Debt Collection Practices Act (FDCPA), you have the right to request debt validation from a collections agency within 30 days of their first contact with you. This forces the agency to prove that:

    • The debt is actually yours.
    • The amount is correct.
    • They are legally authorized to collect it.
    • Send a debt validation letter (via certified mail) within 30 days of the collection agency’s first communication.
    • The agency must cease collection activity until they provide validation.
    • If they cannot validate the debt, they must stop collecting and the item should be removed from your credit report (or you can dispute it as unverifiable).
    • Even outside the 30-day window, you can still request validation — the agency isn’t legally required to stop collecting, but many will still respond, and if they can’t validate, you have grounds for a dispute.

    Option B: Negotiate (pay-for-delete or settlement)

    A pay-for-delete is an agreement where you pay the collections account (in full or in part) and the agency agrees to remove the item from your credit report. This is not guaranteed — the major bureaus have policies discouraging pay-for-delete because it undermines the accuracy of the credit file — but some smaller agencies still do it.

    • Offer a settlement. Collections are often negotiable. A debt of $1,000 might settle for $400–$600. Start low.
    • Get any agreement in writing before you pay. If an agency agrees to a pay-for-delete or a settlement for less than the full balance, get it in writing on their letterhead before you send a dime.
    • Pay only via a method that leaves a paper trail (check, money order, or bank transfer — never cash).
    • After payment, monitor your reports. If the agency agreed to delete, confirm the item is removed within 30–60 days. If they agreed to mark it “paid,” confirm the status updates.

    Note: Even without a pay-for-delete, paying a collection can help. Newer scoring models (FICO 9, VantageScore 3.0 and 4.0) ignore paid collections entirely. However, many lenders still use FICO 8 and older models, which count paid collections as negative. Paying doesn’t hurt, but it may help less than you hope with older models.

    Option C: Wait it out

    If the collection is old, close to the 7-year reporting limit, and you can’t get it validated or negotiated away, sometimes the best move is to wait.

    • Collections must be removed from your report 7 years from the original delinquency date (the date you first missed a payment with the original creditor — not the date the collection was placed).
    • If a collection is 6.5 years old, it may make more sense to wait 6 months than to pay it.
    • Do not make a payment or acknowledge the debt in writing if you’re planning to wait it out. In some states, making a payment or acknowledging the debt can reset the statute of limitations on collection lawsuits.

    Expected impact and timeline

    Removing a collections account (via validation, pay-for-delete, or aging off) can produce a significant score increase — often 30 to 80 points or more, depending on the rest of your profile and how recent the collection was. Validation can resolve in 30 to 45 days. Negotiation typically takes 30 to 60 days. Waiting it out, of course, takes however long remains on the 7-year clock.

    9. Monitor Your Credit Year-Round and Protect Against Identity Theft

    What it is

    Credit repair isn’t a one-time project — it’s an ongoing practice. Once you’ve done the hard work of cleaning up your reports and building positive habits, monitoring is what keeps your score safe and catches problems early.

    This includes:

    • Regularly reviewing your credit reports (not just once a year).
    • Monitoring your credit score for unexpected changes.
    • Protecting against identity theft, which can do severe, fast damage to your credit.
    • Placing fraud alerts or credit freezes if you suspect compromised information.

    Why it works

    Credit reports can change monthly. New accounts can appear, balances can update, old items can finally age off, and — if someone steals your identity — fraudulent accounts can show up overnight. The sooner you catch a problem, the easier it is to fix.

    A fraudulent account that’s been on your report for 6 months is harder to remove than one that’s been there for 6 days. A sudden 40-point score drop is easier to diagnose when you can see what changed this month versus last month.

    How to do it, step by step

    1. Set up free credit monitoring.

    • Several services offer free credit score monitoring with alerts: Credit Karma (TransUnion and Equifax), Experian’s free monitoring, your bank or credit card issuer (many now offer free FICO score access and alerts), and Discover’s Credit Scorecard (open to non-customers).
    • These services alert you when something changes on your report — a new account, a balance increase, a new inquiry, a missed payment, a change in personal information.
    • You don’t need to pay for credit monitoring. The free tools are sufficient for most people.

    2. Pull your full reports regularly.

    • Even with monitoring, pull all three full reports from AnnualCreditReport.com at least once a year — and ideally stagger them (e.g., Experian in January, Equifax in May, TransUnion in September) so you’re checking a full report every 4 months.

    3. Place a fraud alert if you suspect identity theft.

    • A fraud alert is a note on your credit report that tells lenders to take extra steps to verify your identity before extending credit. It lasts for 1 year (an extended 7-year alert is available for confirmed identity theft victims).
    • Contact any one bureau to place a fraud alert — they are required to notify the other two.
    • It’s free, and it doesn’t affect your score.

    4. Consider a credit freeze for stronger protection.

    • A credit freeze (also called a security freeze) locks your credit file so that no new creditor can access it — which means no one (including you) can open new credit in your name until you lift the freeze.
    • Freezes are free by federal law since 2018.
    • You must place a freeze with each bureau separately (Experian, Equifax, TransUnion).
    • You can temporarily lift a freeze when you apply for credit, then refreeze.
    • A freeze does not affect your score or your existing accounts.
    • For most people who aren’t actively applying for credit, a freeze is the single strongest identity-theft protection available.

    5. Review account statements monthly.

    • Catch unauthorized charges on existing accounts quickly. Many identity thieves start by testing small charges on an existing card before attempting to open new accounts.

    6. If you find identity theft, act immediately.

    • File a report with the Federal Trade Commission at IdentityTheft.gov — this creates an official identity theft report you can use with creditors and bureaus.
    • Place a fraud alert or freeze.
    • Dispute every fraudulent account with the bureaus, citing identity theft. The FCRA gives identity theft victims specific rights, including blocking of fraudulent information within 4 business days of receiving your identity theft report.

    Expected impact and timeline

    Monitoring itself doesn’t raise your score — but it protects the score you’ve built and catches issues that could otherwise quietly drag it down. The impact of catching a problem early versus late can be the difference between a 2-week fix and a 6-month battle. This tip is about risk reduction and early detection, and its value compounds over time.

    Quick Wins vs. the Long Game

    Not all credit repair tips operate on the same timeline. Some can move your score in weeks; others take months or years to fully pay off. Knowing which is which helps you set realistic expectations and sequence your effort effectively.

    Quick wins (30–60 days)

    Medium-term (3–6 months)

    Long game (6+ months to years)

    If you’re starting from a damaged score and want to move quickly, start with Tips 1, 2, 3, and 6 — they offer the fastest legitimate path to visible improvement. Layer in the others as you go.

    Common Mistakes That Undo Your Progress

    Credit repair is as much about what you don’t do as what you do. These are the mistakes we see most often — and they can quietly erase weeks of progress.

    1. Closing old cards “to clean up”

    We covered this in Tip 5, but it’s worth repeating because it’s so common. People pay off a card, feel good about it, and close the account to “get rid of it.” This can shorten your credit history and raise your utilization — both of which lower your score. Keep old, no-annual-fee cards open.

    2. Disputing everything hoping something sticks

    Submitting blanket disputes on every negative item — including accurate ones — is a fast way to get your disputes flagged as frivolous. Once a bureau decides you’re filing frivolous disputes, they can legally refuse to investigate future ones. Dispute only items you genuinely believe are inaccurate, incomplete, or unverifiable.

    3. Missing a payment while in the middle of repair

    It’s heartbreaking but common: someone is working hard on disputes and utilization, and then a single missed payment undoes months of progress. Automate your minimums (Tip 4) before you do anything else. Protect the floor before you raise the ceiling.

    4. Maxing out a card after a limit increase

    You requested a credit limit increase to lower your utilization (good), and then you used the new credit (bad). The increase only helps if your spending stays the same or lower. A higher limit is a tool for utilization, not a license to spend.

    5. Paying a collections account without negotiating first

    If you’re going to pay a collection, negotiate first — either for a pay-for-delete or for a settlement amount below the full balance. Paying the full amount without asking for anything in return leaves money on the table and doesn’t guarantee the item will be removed from your report.

    6. Ignoring the statute of limitations

    If you make a payment or acknowledge an old debt in writing, you may reset the statute of limitations on collection lawsuits in some states — potentially reviving a debt that was legally uncollectible. Before touching an old debt, understand your state’s statute of limitations and the potential consequences.

    7. Applying for new credit while repairing

    Every hard inquiry can ding your score by a few points, and new accounts lower your average account age. While you’re actively repairing your credit, avoid applying for new credit unless it’s part of your strategy (like a secured card to rebuild, or a consolidation loan with a clear plan).

    8. Falling for “credit repair” scams

    If a company guarantees specific score increases, promises to remove accurate negative information, asks for payment before providing any service (illegal under the CROA — see below), or tells you to create a “new” credit identity (a federal crime), walk away. We cover your CROA rights in the next section.

    When DIY Isn’t Enough — Bringing in a Professional

    We’ve been honest throughout this guide: most credit repair can be done yourself, for free. The FCRA gives you the same dispute rights that a credit repair company would exercise on your behalf. There is no special tool, no insider technique, and no legal loophole that a paid service can use that you cannot.

    So when does it make sense to bring in a professional?

    1. Complex, persistent errors

    If you’ve disputed an item once or twice and it keeps coming back verified — even though you know it’s wrong — the process of escalating can become time-consuming and legally intricate. A professional (especially an attorney-backed firm) can:

    • Escalate disputes with additional documentation and legal framing.
    • File CFPB complaints on your behalf.
    • Identify potential FCRA violations that could support legal action.
    • Pursue the furnisher directly with more formal legal pressure.

    2. Creditors that refuse to cooperate

    Some creditors and collections agencies are difficult to deal with — they ignore goodwill letters, refuse to validate debts, or report inaccurate information repeatedly. A professional can apply sustained, documented pressure that an individual consumer may struggle to maintain.

    3. Mixed files or identity theft with widespread damage

    If your credit file has been merged with another person’s (a “mixed file”) or if identity theft has resulted in multiple fraudulent accounts across all three bureaus, the cleanup process can be overwhelming. A professional can manage the volume of disputes, documentation, and follow-up required to restore your file.

    4. You simply don’t have the time

    Credit repair is not technically difficult, but it is time-consuming — pulling reports, writing letters, tracking responses, following up, documenting everything. If your work and family life don’t leave room for consistent effort, a professional can take that off your plate. That’s a legitimate reason, and it’s the one we hear most often from our own clients.

    5. You want the backup of attorney oversight

    The FCRA is a consumer protection law, and violations of it can carry statutory and actual damages. An attorney-backed credit repair firm can identify when a creditor or bureau has violated your rights and pursue legal remedies — something a non-attorney credit repair company legally cannot do. For consumers with provable, persistent errors, this can be the difference between a frustrating loop of disputes and a real resolution.

    What a reputable professional will and won’t do

    A reputable firm will:

    • Review your full credit picture before recommending action.
    • Dispute only items that appear inaccurate, incomplete, or unverifiable.
    • Provide a clear timeline and set realistic expectations.
    • Charge only for services performed (no upfront fees before work begins — required by the CROA).
    • Educate you on the process and your rights.
    • Offer a free initial consultation or audit.

    A reputable firm will not:

    • Guarantee specific score increases or the removal of specific items.
    • Tell you to dispute accurate information just to see if it sticks.
    • Suggest creating a new credit identity or Employer Identification Number (EIN) to start fresh.
    • Charge you before performing any work.
    • Promise results in a specific timeframe.

    Internal link placeholder: — If you’ve hit a wall with DIY credit repair, our free credit audit can tell you whether professional help makes sense for your situation. No obligation, no pressure. Get a free credit audit.

    Your Rights Under the CROA

    If you do decide to hire help, the Credit Repair Organizations Act (CROA) is the federal law that protects you. It applies to any company that offers to improve your credit report, history, or rating in exchange for payment.

    Here’s what the CROA gives you:

    The right to no upfront fees

    A credit repair company cannot charge you any fee before it has fully performed the services it promised. This means no “setup fee,” no “registration fee,” and no “retainer” before work is done. A company can charge you after it completes a service (e.g., after it files a dispute and obtains results), but not before.

    If a company asks for payment before doing anything, that’s a red flag and a CROA violation.

    The right to a written contract

    Before you pay or sign anything, the company must give you a written contract that includes:

    • The total cost of services.
    • A detailed description of the services to be performed.
    • The timeframe in which the services will be performed.
    • The company’s name and business address.
    • A statement of your right to cancel without charge within 3 business days of signing (a “cooling-off” period).

    The right to cancel

    You can cancel a credit repair contract without penalty within 3 business days of signing it. The company must inform you of this right in the contract.

    The right to honest claims

    A credit repair company cannot:

    • Make false claims about what they can do for your credit.
    • Advise you to make false statements to a credit bureau or creditor.
    • Advise you to dispute accurate information.
    • Suggest you create a “new” credit identity (using a new Social Security number or EIN — this is federal fraud).

    The right to enforcement

    If a credit repair company violates the CROA, you can sue them in federal court. You may be entitled to actual damages, statutory damages, punitive damages, and attorney’s fees.

    What this means for you

    The CROA exists because the credit repair industry has historically attracted bad actors. The law gives you a clear framework for evaluating any credit repair company: if they follow the CROA, they’re at least operating within the law. If they don’t — if they ask for money upfront, make guaranteed-result claims, or suggest anything that feels like a shortcut around the truth — they’re either scamming you or operating illegally, and you should walk away.

    At our firm, we operate in full compliance with the CROA and the FCRA. We don’t guarantee outcomes, we don’t charge upfront fees for services not yet performed, and we don’t ask you to do anything dishonest. We simply apply the legal rights you already have, professionally and persistently, with attorney oversight.

    Frequently Asked Questions

    Q1: Can I really repair my credit myself without paying a company?

    Yes. The FCRA gives you the same dispute rights that any credit repair company uses. You can pull your reports for free, dispute inaccuracies in writing, request goodwill deletions, validate debts, and manage your credit behavior — all without paying anyone. A professional can help when the process becomes complex, time-consuming, or legally contentious, but the core mechanics of credit repair are available to every consumer for free.

    Q2: How long does credit repair take?

    It depends on your starting point and your goals. Some changes — like lowering credit utilization or being added as an authorized user — can move your score within 30 to 60 days. Disputes resolve within 30 to 45 days under the FCRA. More significant repair, especially involving multiple negative items or complex errors, typically takes 3 to 6 months of consistent effort. Aging out accurate negative items can take years, but their impact fades over time.

    Q3: Is it illegal to pay a company to repair your credit?

    No. Hiring a credit repair company is legal, and the industry is regulated by the CROA. What’s illegal is when a company violates the CROA — charging upfront fees, making false guarantees, or advising you to commit fraud (like creating a new credit identity). A compliant, transparent credit repair firm is offering a legitimate service.

    Q4: Will disputing an item make it come back later?

    Sometimes. If a furnisher verifies an item during a re-investigation, it can remain on your report. If an item is removed but later verified by the furnisher and reinserted, the bureau must notify you within 5 business days of the reinsertion (under the FCRA). If you receive such a notice, you can evaluate whether to dispute again with new information or escalate to the CFPB or an attorney.

    Q5: Does paying off a collection remove it from my credit report?

    Not automatically. Paying a collection updates its status to “paid,” but the item can remain on your report for up to 7 years from the original delinquency date. That said, paid collections are treated more favorably than unpaid ones by newer scoring models (FICO 9, VantageScore 3.0+), which ignore paid collections entirely. To get a collection removed before the 7-year mark, you typically need a pay-for-delete agreement, successful debt validation, or to wait it out.

    Q6: How many points can I gain from credit repair?

    There’s no single answer — it depends entirely on your starting profile and what’s on your report. Someone removing a fraudulent collections account from an otherwise clean file might see a 60 to 100+ point jump. Someone lowering utilization from 85% to 8% might see 30 to 60 points. Someone whose only issue is a 3-year-old late payment on an otherwise strong file might see less dramatic movement. The people who see the biggest gains are usually those with multiple negative items that are genuinely inaccurate or unverifiable.

    Q7: Should I close a credit card I don’t use anymore?

    Usually no — especially if it’s one of your older accounts and has no annual fee. Closing it can shorten your credit history (once it eventually drops off) and raise your utilization by removing that card’s credit limit from your total. If the card has an annual fee, ask the issuer about downgrading to a no-fee version first. See Tip 5 for the full reasoning.

    Q8: What’s the difference between a fraud alert and a credit freeze?

    A fraud alert is a note on your credit report telling lenders to verify your identity before extending credit. It lasts 1 year (7 years for confirmed identity theft victims) and doesn’t block access to your credit file. A credit freeze completely locks your credit file so no new creditor can access it, preventing new accounts from being opened in your name until you lift the freeze. Both are free. A freeze is stronger protection; an alert is more convenient if you’re actively applying for credit. See Tip 9 for details.

    A Final Word

    Your credit score is not a measure of your worth, your intelligence, or your work ethic. It’s a statistical estimate of risk, built from a system that is imperfect, sometimes inaccurate, and fully regulated by laws that give you real power to correct it.

    The nine tips in this guide cover the core of what credit repair actually involves: see your reports, fix what’s wrong, optimize what’s in your control, and protect what you’ve built. You can do all of that yourself, for free, starting today. There is no secret technique that a paid service can use that you cannot — the FCRA gives you the same rights.

    If you work through these tips and reach a point where the errors are too complex, the creditors too stubborn, or the time too scarce to keep going alone — that’s exactly when a professional makes sense. And if that moment comes, we’re here.

    We offer a free credit audit at . We’ll review all three of your bureau reports, flag inaccuracies and dispute opportunities, and tell you honestly whether DIY is still your best path or whether professional help would add value. There’s no obligation, no pressure, and no cost for the audit itself.

    Whether you repair your credit on your own or with help, what matters is that you start. The sooner you pull your reports, the sooner you know what you’re working with. And the sooner you know that, the sooner your score starts moving in the right direction.

    This article is provided for educational purposes and does not constitute legal or financial advice. Your individual situation may vary. Credit outcomes are not guaranteed and depend on the specifics of your credit report and financial behavior.

    Ready for a free credit audit? Visit or to get started. Get a free credit audit.

  • Credit Repair to Buy a House: What You Need to Know Before Applying for a Mortgage

    Credit Repair to Buy a House: What You Need to Know Before Applying for a Mortgage

    Essential prep reading: understand how hard vs soft inquiries affect your score during mortgage shopping, know what score range qualifies you for the best rates, clear any collection accounts that could disqualify your application, and get help from our Denver credit repair team if you are buying in Colorado.

    There is a specific moment that stops a lot of would-be homeowners in their tracks. It’s not the open house, the offer, or even the down payment. It’s the moment a loan officer pulls their credit and says, “Your scores are a little lower than we’d like for this program.”Suddenly, the dream of owning a home — something you may have been building toward for years — feels like it’s slipping through your fingers. Maybe you know there are errors on your report. Maybe an old collection from a tough year is still dragging you down. Maybe you’ve just never had anyone explain, in plain language, what your credit actually needs to look like to get a mortgage.

    Here’s the good news: credit repair to buy a house is not a mystery, and it’s not a sprint. It’s a structured, legally grounded process that — done the right way — can move your scores meaningfully before you ever sit down with a lender. The key is starting early, understanding what mortgage lenders actually look at, and avoiding the traps that derail applications at the finish line.

    This guide walks you through every piece of that process: the minimum credit scores by loan type, what lenders examine beyond the number, how far in adVAnce to start, a step-by-step pre-mortgage credit plan, and the mistakes that quietly cost people their approvals. Whether you’re six months out or just starting to think about it, you’ll leave with a clear picture of what to do next.

    Why Your Credit Score Matters So Much for a Mortgage

    Your credit score is not a VAnity metric. When you apply for a mortgage, it is one of the single most important numbers in your financial life — and not just because it determines whether you get approved. It determines what you pay every month for the next 30 years.

    Mortgage lenders use your credit score to set your interest rate. The higher your score, the lower the rate. The lower the rate, the less you pay over the life of the loan. This is not a marginal difference. It is often the difference between tens of thousands of dollars.

    A Real Example: The Cost of 60 Points

    Let’s say you’re buying a $400,000 home with a 20% down payment ($80,000), which means you’re financing $320,000 on a 30-year fixed-rate mortgage. Here’s how a 60-point difference in your credit score might play out, using illustrative rate tiers based on typical industry pricing:

    Credit Score Range Approx. APR Monthly Payment (Principal + Interest) Total Interest Paid Over 30 Years
    760 – 850 (Excellent) 6.50% $2,022 $408,000
    700 – 759 (Good) 6.75% $2,075 $427,000
    680 – 699 (Fair-Good) 7.00% $2,129 $446,000
    620 – 679 (Below Average) 7.50% $2,238 $486,000

    Note: APRs shown are illustrative and fluctuate with market conditions. The relationship between score tiers and rates is what matters — the spread between tiers is consistent across rate environments.

    Look at the gap between the top tier and the bottom tier. A borrower with a score in the 620–679 range pays roughly $216 more per month than a borrower in the 760+ range — and over 30 years, that’s $78,000 more in interest alone. That’s a second car. That’s a child’s college tuition. That’s retirement money, redirected to a lender.

    Now narrow it to the 60-point swing in the title — say, moving from the 680–699 tier to the 700–759 tier. That single improvement saves roughly $54 per month and about $19,000 over the life of the loan. And moving from below-average to good can save over $40,000.

    This is why credit repair to buy a house is one of the highest-return investments you can make. Every point you responsibly add to your score before locking a rate compounds into real money over the life of your mortgage.

    Beyond the rate, your score also affects:

    Whether you qualify at all — most loan programs have hard minimums

    Your down payment requirements — lower scores often mean larger down payments

    PriVAte mortgage insurance (PMI) costs — which can add $100–$300+ per month

    Which loan programs are aVAilable to you — some won’t accept scores below a threshold

    The takeaway is simple: your credit score is the lever. Pull it in the right direction before you apply, and every other part of the mortgage process gets easier and cheaper.

    Get a free credit audit.

    Minimum Credit Scores by Loan Type

    One of the most common questions we hear is, “What credit score do I need to buy a house?” The honest answer is: it depends on the loan program. There is no single universal minimum. Different loan types — conventional, FHA, VA, USDA — each have their own requirements, and many lenders add their own “overlays” on top of the official minimums.

    Here’s an accurate breakdown of the major loan programs:

    Comparison Table: Minimum Credit Scores by Loan Type

    Loan Type Minimum Credit Score (Official) Typical Lender Minimum (Overlay) Down Payment Requirement Key Notes
    Conventional 620 620 – 640 As low as 3% (with PMI) Most common loan; stricter on credit history
    FHA Loan 580 (for 3.5% down) 580 – 620 3.5% down at 580+; 10% down at 500–579 Backed by the Federal Housing Administration; more forgiving of past credit issues
    VA Loan No official minimum set by the VA Typically 580 – 620 0% down (no down payment required) For eligible active-duty service members, veterans, and some surviving spouses
    USDA Loan 640 (per USDA guidance) 640+ 0% down (no down payment required) For eligible rural and suburban homebuyers meeting income limits

    Conventional Loans

    Conventional loans are not backed by a government agency. They follow guidelines set by Fannie Mae and Freddie Mac, the two government-sponsored enterprises that buy most conventional mortgages. The official minimum credit score is 620, but many lenders require 640 or higher — especially for borrowers putting less than 20% down. Conventional loans tend to have stricter standards around your overall credit history, debt-to-income ratio, and recent derogatory marks.

    FHA Loans

    FHA loans are insured by the Federal Housing Administration and are designed to help buyers with lower credit scores or limited down payment funds. The rules are split:

    Score of 580 or higher: You qualify for the minimum down payment of 3.5%

    Score of 500–579: You can still qualify, but you must put down at least 10%

    In practice, very few lenders approve FHA loans with scores below 580 — most set their overlay at 580 or even 620. But if you’re in the 500s and working to rebuild, FHA is your most realistic path. It’s also more forgiving of past bankruptcies (typically 2 years from discharge) and foreclosures (typically 3 years).

    VA Loans

    The Department of Veterans Affairs does not set an official minimum credit score — but individual lenders do. Most look for 580 to 620 or higher. VA loans are powerful: no down payment, no PMI, and competitive rates. If you’re eligible (active-duty, veteran, or qualifying spouse), this is often the best loan available, and the credit requirements are more lenient than conventional.

    USDA Loans

    The USDA Rural Development Guaranteed Loan Program requires a minimum score of 640, per USDA guidance. These loans are for homes in eligible rural and suburban areas and offer 0% down financing, but they also have household income limits. If you’re targeting a smaller community and your score is above 640, USDA is worth exploring.

    The Overlay Problem

    Here’s something most first-time buyers don’t realize: the official minimum is not always the minimum you’ll face. Lenders add their own requirements, called “overlays,” on top of the program minimums. A lender might require 640 for an FHA loan even though the FHA allows 580. This is why shopping between lenders matters — but only after your credit is in good shape, so you’re comparing real offers.

    What Mortgage Lenders Actually Look at Beyond the Score

    Your credit score is the headline, but it’s not the whole story. Mortgage underwriters look at the narrative behind the number. Two borrowers with the same 680 score can get very different outcomes depending on what’s in their file.

    Here’s what lenders examine beyond the three-digit score:

    1. Debt-to-Income (DTI) Ratio

    Your DTI is the percentage of your gross monthly income that goes toward debt payments — including the new mortgage. Most conventional loans want a DTI of 43% or lower, though some exceptions go up to 50% with strong compensating factors. FHA is more flexible, often allowing up to 50% with automated underwriting approVAl.

    DTI includes:

    Your new monthly mortgage payment (principal, interest, taxes, insurance, and HOA if applicable)

    Minimum credit card payments

    Auto loans

    Student loans

    Child support or alimony

    Any other recurring debt

    If your DTI is too high, even a great credit score won’t save you. Paying down balances before applying doesn’t just help your credit — it directly improves your DTI.


    2. Employment History and Income Stability

    Lenders want to see at least two years of steady employment in the same field. They’ll verify with W-2s, pay stubs, and tax returns. Job changes within the same industry are usually fine, but gaps in employment or a switch to a completely different field can raise questions. Self-employed borrowers face extra scrutiny — typically two years of business tax returns and profit-and-loss statements.

    Your payment history is the single largest factor in your credit score (about 35%), and lenders look at it closely. A recent 30-day late payment hurts far more than one from four years ago. Underwriters specifically look for:

    Late payments in the last 12 months — the most damaging

    Late payments on housing (previous mortgage or rent) — heavily weighted

    Patterns vs. one-time events — a single missed payment during a documented hardship is viewed differently than a pattern of missed payments

    4. Recent Derogatory Marks

    Recent bankruptcies, foreclosures, short sales, or judgments are significant red flags. Each loan type has waiting periods:

    Chapter 7 bankruptcy: 2 years for FHA, 4 years for conventional

    Chapter 13 bankruptcy: 1 year for FHA (with court approVAl and on-time payments), 2 years for conventional

    Foreclosure: 3 years for FHA, 7 years for conventional (though some programs allow 3–4 years with extenuating circumstances)

    The older the derogatory mark, the less impact — which is why starting credit repair well in adVAnce matters so much.

    5. Collections and Charge-Offs

    Collections are complicated. Whether they need to be paid before closing depends on the loan type, the lender, and the amount:

    Conventional: Typically, collections over a certain threshold (often $2,000 total, or individual accounts over $1,000) may need to be paid or have a payment plan in place

    FHA: More lenient, but lenders may still require resolution of larger or recent collections

    Medical collections: Often treated more leniently and may not need to be paid

    This is where working with both a credit repair firm and a loan officer helps — they can tell you exactly which collections matter for your specific loan and which can wait.

    6. Credit Utilization

    Even if your score is decent, high utilization on revolving accounts signals risk. Lenders (and scoring models) like to see credit card balances below 30% of the limit, and ideally below 10% for optimal scoring. If you’re at 80% utilization across your cards, paying those down can produce a fast, meaningful score increase — sometimes within a single billing cycle.

    7. Credit Mix and Account Age

    Lenders like to see a healthy mix of credit types (revolving accounts like credit cards plus installment loans like auto or student loans) and a long average account age. This is why closing your oldest accounts before applying is usually a mistake — it shortens your credit history and can drop your score.

    The Mortgage Credit Pull: Hard Inquiries and the Rate-Shopping Window

    A common fear we hear: “Won’t shopping around for a mortgage hurt my credit?” It’s a reasonable concern, but the system is actually designed to protect you — if you shop within the right window.

    How Hard Inquiries Work

    When a lender pulls your credit report as part of a loan application, it’s recorded as a hard inquiry. A single hard inquiry typically causes a small, temporary dip in your score — usually 1 to 5 points — and the impact fades within a few months. Hard inquiries stay on your report for two years but only affect your score for one year.

    The Rate-Shopping Window

    Here’s the key: credit scoring models treat multiple mortgage inquiries within a specific window as a single inquiry. This is designed so you can shop for the best rate without being penalized for it.

    FICO scoring models: Multiple mortgage, auto, and student loan inquiries within a 14- to 45-day window (depending on the scoring model version) count as one inquiry for scoring purposes

    Older FICO models: 14-day window

    Newer FICO models (FICO 8, FICO 9): 45-day window

    VantageScore: 14-day window

    The safest approach: do all your mortgage rate shopping within a 14-day period. This guarantees you’re covered regardless of which scoring model the lender uses.

    Two Important Distinctions

    Mortgage, auto, and student loan inquiries are deduplicated. Credit card inquiries are NOT. Applying for five credit cards in a month will show as five separate inquiries and will hurt your score.

    The deduplication only applies to the same type of loan. A mortgage pull and an auto loan pull in the same window are treated separately.

    When to Pull Your Own Credit

    Before you ever let a lender pull your credit, pull your own reports first. When you request your own credit report (through AnnualCreditReport.com or a monitoring service), it’s a soft inquiry — it does not affect your score at all. This lets you see exactly where you stand, identify errors, and start the repair process without any downside.

    We recommend pulling all three bureau reports (Equifax, Experian, TransUnion) at least 6–12 months before you plan to apply for a mortgage. That gives you time to address issues before a lender ever sees them.

    Timeline: How Far in Advance to Start Credit Repair Before House Hunting

    If there’s one piece of advice we want you to take from this entire article, it’s this: start early. Credit repair is not instantaneous. Disputes take time to investigate. Credit bureaus have legal windows to respond. Score improvements from paying down debt take billing cycles to reflect. And the older a negative mark is, the less it hurts — which means time itself is a tool.

    The Ideal Timeline: 6–12 Months

    We recommend starting credit repair 6 to 12 months before you plan to apply for a mortgage. Here’s why each phase of that timeline matters:

    12 months out — Foundation and Audit

    Pull all three credit reports

    Identify every error, outdated item, and disputable negative mark

    Begin formal disputes (bureaus have 30–45 days to investigate)

    Start paying down revolving balances

    Establish a perfect payment history from this point forward

    6–9 months out — Mid-Process Optimization

    Follow up on dispute outcomes; escalate unresolved items

    Continue utilization reduction

    Address collections and charge-offs (negotiate pay-for-delete or settlements where appropriate)

    Begin coordinating with a loan officer for pre-qualification guidance

    3–6 months out — Fine-Tuning

    Verify all dispute results have posted

    Check that scores have improved across all three bureaus

    Avoid any new credit applications, large purchases, or credit changes

    Get pre-approved (not just pre-qualified) with a lender

    1–3 months out — Lock-Down

    Do NOT open new credit accounts

    Do NOT make large purchases (furniture, cars, appliances)

    Do NOT close existing accounts

    Do NOT change jobs if avoidable

    Maintain perfect payment history

    Keep credit utilization low

    During underwriting and up to closing — Hold Steady

    Lenders often re-pull your credit right before closing

    Any new debt, new inquiries, or changed employment can derail the loan

    Treat the period between application and closing as sacred — nothing changes

    What If You Don’t Have 6–12 Months?

    Not everyone has the luxury of planning that far ahead. If you’re on a shorter timeline:

    3–6 months: Focus on the highest-impact items — disputing clear errors, paying down utilization, and resolving any collections that would block closing

    1–3 months: Prioritize paying down balances (fastest score impact) and addressing any lender-blocking items. Be realistic — some disputes won’t resolve in time

    Less than 1 month: Focus on utilization and avoiding any new negative marks. Work with a loan officer to identify which loan program fits your current scores. Don’t attempt aggressive disputes — they may not resolve before closing and could complicate underwriting

    The shorter your timeline, the more important it is to work with professionals who can prioritize effectively. This is where an attorney-backed credit repair firm can help you focus on what will actually move the needle in the time you have.

    Step-by-Step Pre-Mortgage Credit Plan

    Now let’s get into the actual work. Here is a structured, step-by-step plan for getting your credit mortgage-ready. Follow these in order, and don’t skip steps — each one builds on the last.

    Step 1: Pull All Three Reports and Audit for Errors

    Your credit reports from Equifax, Experian, and TransUnion are not identical. Different creditors report to different bureaus, and errors can appear on one report but not the others. You need all three.

    Where to get them:

    AnnualCreditReport.com — Free copies of all three reports, once per year (and currently more frequently due to expanded access)

    Your bank or credit card — Many offer free credit monitoring with report access

    A credit repair firm — Can pull consolidated reports and walk you through them

    What to audit for:

    Accounts you don’t recognize (potential identity theft or reporting errors)

    Incorrect account balances or credit limits

    Late payments that were actually on time

    Accounts listed as open that you closed (or vice versa)

    Duplicate accounts

    Negative marks older than 7 years (10 years for bankruptcies) that should have fallen off

    Incorrect personal information (wrong name, address, or employer)

    Studies have found that a significant percentage of credit reports contain errors — and some of those errors are serious enough to affect your score. Every error you find and dispute is a potential score increase.

    Step 2: Dispute Inaccuracies

    Under the Fair Credit Reporting Act (FCRA), you have the legal right to dispute any information on your credit report that you believe is inaccurate, incomplete, or unverifiable. Credit bureaus must investigate your dispute — typically within 30 days (up to 45 days in some cases) — and remove or correct any information they cannot verify.

    How to dispute:

    File disputes directly with each credit bureau (online, by mail, or by phone)

    Be specific: identify the exact item, explain why it’s wrong, and include supporting documentation

    Dispute with the original creditor as well — they are also required to investigate

    Keep records of every dispute, including dates and correspondence

    What can be disputed:

    Inaccurate account information (wrong balance, wrong dates, wrong payment status)

    Accounts that don’t belong to you

    Late payments that were actually on time

    Collections that were already paid but still show as unpaid

    Negative items older than the legal reporting limit

    Any item the creditor cannot verify

    Important: Only dispute items that are genuinely inaccurate or unverifiable. Filing frivolous disputes — disputing everything hoping something sticks — can result in the bureau flagging your disputes as frivolous and refusing to investigate. This is where professional guidance helps: an experienced credit repair firm knows which items are legitimately disputable and how to frame the dispute effectively.

    Step 3: Pay Down Balances and Optimize Utilization

    Credit utilization — the percentage of your aVAilable credit that you’re using — is the second-largest factor in your credit score (about 30%). And it’s the factor you can change fastest.

    Target utilization levels:

    Below 30%: Good — minimum threshold for most scoring improvement

    Below 10%: Optimal — produces the best scores

    0%: Also excellent, but having a small balance on one card (paid in full each month) can sometimes score slightly better than all cards at zero
    Credit repair to buy a house and get mortgage-ready

    Strategy:

    Pay down balances on all revolving accounts (credit cards, store cards, lines of credit)

    If you can’t pay everything down to 10%, prioritize getting each individual card below 30% — scoring models look at both overall utilization and per-card utilization

    Consider requesting credit limit increases (which improves utilization without paying down debt — but do NOT use the new aVAilable credit)

    Time your payments strategically: pay down balances before the statement closing date, not just the due date — that’s when balances are reported to the bureaus

    The impact of utilization changes can show up in your score within one to two billing cycles — often 30 to 60 days. This is the fastest lever you have for a meaningful score increase.

    Step 4: Handle Collections and Charge-Offs

    Collections and charge-offs are among the most damaging items on a credit report. But how you handle them depends on the type, age, and your specific loan program.

    Understand the two approaches:

    Pay for delete: You negotiate with the collection agency to have the item removed from your credit report in exchange for payment. Not all agencies will agree, but when they do, it’s the best outcome — the negative mark disappears entirely.

    Settle or pay in full: If a pay-for-delete isn’t possible, paying or settling the collection stops it from updating and, over time, reduces its impact. The collection will still appear on your report, but a paid collection is generally viewed more favorably than an unpaid one — and some newer scoring models (FICO 9, VantageScore 3.0+) ignore paid collections entirely.

    What lenders require:

    Conventional loans may require collections above certain thresholds to be paid or under a payment plan before closing

    FHA loans are more lenient but may still require resolution of larger or recent collections

    Some lenders require all collections in the last 24 months to be resolved

    Medical collections are often treated more leniently

    Strategy:

    Don’t pay or settle a collection without first checking whether it will actually help your specific loan situation — sometimes paying an old collection can actually cause a temporary score drop because it updates the date of last activity

    Negotiate. Collection agencies often settle for less than the full amount

    Get any agreement in writing before sending payment

    Work with a credit repair firm that knows which collections to prioritize and how to negotiate effectively

    Step 5: Avoid New Credit Applications and Big Purchases During the Process

    This is the step people underestimate — and it derails more mortgages than almost anything else.

    From the moment you start the mortgage process until the day you close, freeze your credit activity:

    No new credit card applications

    No auto loans

    No personal loans

    No “buy now, pay later” plans (these often involve credit checks)

    No co-signing loans for anyone

    No large purchases on existing credit cards that would spike your utilization

    No new furniture or appliance financing (even zero-interest offers involve credit pulls)

    Why this matters so much:

    Every new application generates a hard inquiry. Every new account lowers your average account age. Every new balance increases your utilization. And lenders often re-pull your credit just before closing — if they see new debt or inquiries that weren’t there when you were approved, they can deny the loan, even if you were already cleared.

    We’ve seen buyers get denied at the closing table because they financed a new couch the week before. Don’t let that be you.

    Step 6: Keep Your Oldest Accounts Open

    It’s tempting to close old credit cards you don’t use anymore, especially if they have annual fees. But doing so before a mortgage application can hurt your score in two ways:

    It shortens your average account age — a longer credit history generally means a higher score

    It reduces your total aVAilable credit — which increases your overall utilization ratio

    If you have an old card with an annual fee that you want to close, either do it well after your mortgage closes, or ask the issuer to downgrade it to a no-fee version instead of closing it. Keep the account open, make a small purchase on it every few months to keep it active, and pay it in full.

    Step 7: Don’t Open New Credit or Take on Debt Before Closing

    This is a repeat of Step 5 because it’s that important — and it extends all the way through closing, not just through application.

    The period between mortgage approVAl and closing is the most dangerous window. Lenders can and do re-verify your credit and employment just days before closing. Common last-minute mistakes include:

    Financing new furniture for the house

    Buying appliances on a store credit card

    Taking out an auto loan because you need a car for the new commute

    Opening a store credit card to get a discount on a purchase

    Co-signing a loan for a family member

    Making a large cash deposit that can’t be sourced

    Any of these can change your debt-to-income ratio, add hard inquiries, or trigger underwriting concerns — and cost you the loan. Wait until after closing. The couch can wait. The car can wait. Everything can wait until you have the keys.

    FHA vs. Conventional: Which Repairs Matter Most for Each

    Different loan programs care about different things. If you know which loan you’re targeting, you can focus your credit repair efforts where they’ll have the most impact.

    For FHA Loans: Focus on Recent Payment History and Utilization

    FHA loans are more forgiving of older credit issues — a bankruptcy from 3 years ago or a collection from 5 years ago is less likely to block you. What FHA lenders care most about:

    Recent payment history: The last 12–24 months are critical. Any late payments in this window are a significant red flag.

    Current utilization: High balances on existing cards signal financial stress.

    Active collections: Especially recent ones or large amounts.

    Documented hardship recovery: If you had a period of bad credit tied to a specific event (job loss, medical issue), documenting the recovery helps.

    FHA repair priorities:

    Establish 12+ months of perfect on-time payments

    Pay down credit card balances

    Address any recent collections

    Don’t worry as much about older, isolated negative marks

    For Conventional Loans: Focus on Overall Credit Profile and DTI

    Conventional loans are less forgiving overall but offer better terms for qualified borrowers. Conventional lenders care most about:

    Overall credit score: The 620 minimum is hard, and higher scores get meaningfully better rates

    Debt-to-income ratio: Conventional is stricter on DTI (typically 43%, though up to 50% with strong factors)

    Complete credit history: Older marks still matter more than they do for FHA

    Reserves: Some conventional programs want to see cash reserves after closing

    Conventional repair priorities:

    Maximize your score above 680 (and ideally 700+) for the best rates

    Reduce DTI by paying down existing debt

    Dispute and resolve any errors or outdated negative marks

    Build cash reserves — don’t use every dollar for the down payment

    Summary: Which Loan Is Right for You?

    Factor FHA Conventional
    Min. credit score 580 (official) 620 (official)
    Forgiveness of past issues More forgiving Less forgiving
    Down payment minimum 3.5% 3% (with PMI)
    PMI Required for life of loan (in most cases) Cancelable when equity reaches 20%
    DTI flexibility Higher (up to 50%) Lower (typically 43%)
    Best for Lower scores, limited down payment, past credit challenges Stronger credit, can put more down, wants to cancel PMI later

    If your score is below 620, FHA is likely your path. If you’re above 680 and can put 5–20% down, conventional may save you money long-term (due to cancelable PMI). A loan officer can help you run the numbers for your specific situation.

    Things That Will Derail a Mortgage Application

    We’ve touched on some of these already, but they deserve their own section because they are the most common reasons mortgages fall through — often after the buyer thought they were home free.

    1. Taking on New Debt Before Closing

    This is the number one killer of mortgage applications. A new car loan, a credit card, a personal loan, even a “buy now, pay later” plan — any of these can change your DTI or trigger underwriting concerns. Lenders frequently re-pull credit 1–3 days before closing.

    The rule: No new debt from the day you apply until the day you close. Period.

    2. Late Payments During Underwriting

    A single late payment — even on a small account — during the underwriting process can derail your loan. Underwriters look at your most recent payment history as a signal of your current financial stability.

    The rule: Set every account to autopay for at least the minimum, and check that payments go through. One missed $25 payment can cost you a $400,000 mortgage.

    3. Changing Jobs

    Lenders verify employment twice: once at application and again within days of closing. Changing jobs — even for a higher salary — can delay or derail your loan because underwriters want to see stability. This is especially true if you switch from salaried to commission-based, or to a different industry.

    The rule: If a job change is unavoidable, tell your loan officer immediately. They can advise whether it will affect your approVAl and how to document it.

    4. Large, Unexplained Bank Deposits

    Underwriters must verify that your down payment and closing funds come from legitimate, documented sources. A sudden $10,000 deposit that you can’t explain — even if it’s a gift from a family member — raises anti-money-laundering flags.

    The rule: Document every deposit. If family is helping with the down payment, get a gift letter from your lender’s format and have the donor document the source of the funds.

    5. Opening Store Credit Cards for Discounts

    The 10% off for opening a store card at checkout is not worth losing your mortgage. Every new application is a hard inquiry, a new account, and a shorter average account age.

    The rule: No new credit accounts of any kind until after closing.

    6. Making Large Purchases on Existing Credit

    Even if you don’t open new accounts, charging a large purchase (furniture, appliances, a trip) to an existing card increases your utilization and your monthly debt — both of which can affect your DTI and your score.

    The rule: Keep credit card spending flat from application through closing. Pay for any large purchases in cash from funds that aren’t part of your closing reserves.

    7. Closing Existing Credit Accounts

    Closing accounts reduces your aVAilable credit (raising utilization) and shortens your credit history. Both can lower your score right when you need it to be stable or improving.

    The rule: Don’t close any accounts before or during the mortgage process.

    8. Disputing Accounts During Underwriting

    This one surprises people. While disputing errors before you apply is smart, disputing accounts during underwriting can actually block your loan. Many lenders will not approve a mortgage while you have active disputes on your credit report — because the disputed item’s impact is temporarily excluded from your score, and the lender can’t get an accurate picture.

    The rule: Complete all disputes before you apply. If you discover a new issue during underwriting, talk to your loan officer before disputing anything.

    Why You Should NOT Do “Rapid Rescoring” Scams or Open New Accounts Right Before Applying

    When people get close to applying for a mortgage and realize their score isn’t quite where they want it, desperation can set in. That’s when they become vulnerable to two specific traps.

    Trap 1: “Rapid Rescoring” Scams

    Rapid rescoring is a legitimate process — but only when done through a mortgage lender. It allows a lender to quickly update your credit report with verified information (like a paid-down balance) so the new information is reflected in your score within days rather than waiting for the next billing cycle.

    The scam version works like this: a company that is NOT your mortgage lender claims they can “rapidly rescore” your credit for a fee. They may promise to remove accurate negative items, inflate your score, or “wipe” legitimate debts. These are not legitimate services. They are fraud.

    Red flags:

    Anyone who guarantees a specific score increase

    Anyone who claims they can remove accurate, verified negative information

    Anyone who asks for payment before performing services

    Anyone who is not working directly with your mortgage lender

    Anyone who suggests creating a “new” credit identity (this is illegal)

    The truth: Legitimate rapid rescoring can only verify and update factual information — it cannot remove accurate negative marks. And it can only be done through a lender with access to the credit bureaus’ rapid rescoring systems. If a standalone “credit repair” company offers rapid rescoring, they are either lying or planning to do something fraudulent.

    Trap 2: Opening New Accounts to “Build Credit” Right Before Applying

    The logic seems sound: “If I open a new credit card and use it responsibly, my score will go up.” And over the long term, that’s true. But in the short term — the 1–6 months before a mortgage application — opening new accounts can backfire:

    Hard inquiry: Immediate small score drop

    New account: Lowers your average account age

    New balance: Increases utilization if you carry a balance

    Unseasoned account: Lenders like to see accounts that have been open and managed well for at least 12 months

    Opening a new card 2 months before applying for a mortgage might lower your score at exactly the wrong time. The benefit of the new account won’t show up until months after you’ve already locked your rate.

    Better approach: If you need to build credit, start 12+ months before you plan to apply. If you’re already within 6 months of applying, don’t open new accounts — focus on optimizing what you already have (paying down balances, disputing errors, maintaining perfect payment history).

    What Actually Works

    Instead of these traps, focus on what genuinely moves your score:

    Pay down existing balances — fastest, most reliable improvement

    Dispute legitimate errors — removes items that shouldn’t be there

    Maintain perfect payment history — prevents new negative marks

    Let time work for you — older negative marks hurt less

    Work with a reputable, attorney-backed credit repair firm — professional guidance that operates within the law

    If anyone promises you a quick fix, a guaranteed score, or a “secret” method — walk away. The FCRA gives you real, legal tools to improve your credit. Use those tools, not shortcuts that put your mortgage at risk.

    Get a free credit audit.

    How Long After Fixing Credit Can You Buy a House

    One of the most common questions we get: “If I start credit repair now, when can I actually buy?” The answer depends on your starting point and your goals. Here are realistic timelines by scenario:

    Scenario 1: Minor Issues — A Few Errors and High Utilization

    Starting profile: Score in the mid-600s, a couple of reportable errors, credit card utilization above 50%, no recent late payments or major derogatory marks.

    Timeline to mortgage-ready: 2–4 months

    Disputes resolve in 30–45 days

    Utilization improvements show in 1–2 billing cycles

    Score improvement: potentially 40–80 points

    Target loan: Conventional (if score reaches 680+) or FHA

    Scenario 2: Moderate Issues — Collections, Some Late Payments

    Starting profile: Score in the low 600s, one or two collections, a late payment within the last year, utilization above 60%.

    Timeline to mortgage-ready: 4–8 months

    Disputes and collection negotiations: 60–120 days

    Utilization reduction: 2–3 billing cycles

    Establishing clean payment history: 6+ months

    Score improvement: potentially 50–100 points

    Target loan: FHA (more forgiving of recent issues) or conventional with strong improvement

    Scenario 3: Major Issues — Recent Bankruptcy, Foreclosure, or Multiple Collections

    Starting profile: Score in the 500s or low 600s, recent bankruptcy or foreclosure, multiple collections, significant derogatory history.

    Timeline to mortgage-ready: 12–24+ months

    Bankruptcy waiting periods: 2 years (FHA) to 4 years (conventional) from discharge

    Foreclosure waiting periods: 3 years (FHA) to 7 years (conventional)

    Rebuilding credit: 12–18 months of perfect payment history

    Score improvement: potentially 80–150+ points over time

    Target loan: FHA initially, potentially refinancing to conventional later

    Scenario 4: Rebuilding From Scratch — Thin or No Credit File

    Starting profile: Limited or no credit history, score in the 600s due to lack of data rather than negative marks.

    Timeline to mortgage-ready: 6–12 months

    Open a secured credit card or credit-builder loan

    Establish 6+ months of on-time payment history

    Add a second account for credit mix

    Keep utilization low

    Target loan: FHA or conventional with manual underwriting if needed

    The Pattern

    Across all scenarios, the same principles apply:

    Time is your ally — older negative marks hurt less, and longer clean payment histories help more

    Disputes take 30–45 days — plan for at least one round of disputes

    Utilization changes show in 30–60 days — the fastest lever

    New positive history needs 6+ months to have full impact

    Major derogatory events have hard waiting periods — no amount of credit repair shortens these

    Be honest with yourself about your starting point, set a realistic timeline, and work the plan. Trying to rush the process is how people end up making desperate decisions that backfire.

    Working With a Credit Repair Firm Alongside a Loan Officer

    One of the smartest things you can do when preparing to buy a house is coordinate between two professionals: a credit repair firm and a loan officer. They serve different roles, but when they work together, they can dramatically improve your outcome.

    The Loan Officer’s Role

    Your loan officer is your gateway to the mortgage. They:

    Assess your current credit and financial situation

    Tell you which loan programs you qualify for (or are close to qualifying for)

    Identify exactly what score and DTI you need for your target loan

    Let you know which specific items on your credit report are blocking approVAl

    Guide you through pre-approVAl, application, and underwriting

    The Credit Repair Firm’s Role

    A reputable credit repair firm (one that operates within the FCRA and works with attorneys) handles the credit-side work:

    Auditing all three credit reports for errors and disputable items

    Filing and managing formal disputes with the bureaus and creditors

    Negotiating with collection agencies (pay-for-delete, settlements)

    Advising on utilization optimization and payment strategy

    Tracking progress and updating you on score changes

    Coordinating with your loan officer on what’s being disputed and when

    How They Coordinate

    The most effective approach is when both professionals are working from the same playbook:

    You get pre-qualified with a loan officer first — they tell you where you stand and what you need

    You share that information with your credit repair firm — they target the specific items the lender flagged

    The credit repair firm works on disputes and negotiations — and avoids anything that would interfere with underwriting

    The loan officer monitors your progress — and re-eVAluates your readiness as your scores improve

    When your scores reach the target range, you formally apply — with a clean, optimized credit profile

    Important: Stop Disputes Before Application

    As mentioned earlier, having active disputes on your credit report during underwriting can block approVAl. Your credit repair firm should complete all disputes before you formally apply for the mortgage. This is a key coordination point — your loan officer should confirm that no disputes are active when they pull your credit for the application.

    Why Attorney-Backed Matters

    Credit repair that involves legal rights under the FCRA benefits from attorney oversight. Attorneys can:

    Ensure all disputes are filed correctly and within legal guidelines

    Escalate cases when bureaus or creditors violate your rights

    Pursue legal action if a creditor or bureau refuses to correct verified errors

    Provide an additional layer of accountability and compliance

    This is not about being adversarial — it’s about having the legal framework to enforce your rights when the system doesn’t work as it should. Most disputes resolve without legal action, but knowing you have that backing ensures the process is taken seriously.

    Common Mistakes to Avoid

    We’ve covered a lot of ground. Let’s consolidate the most common mistakes we see people make when trying to repair their credit to buy a house — so you can avoid every one of them.

    1. Starting Too Late

    The single biggest mistake. People start credit repair a month before they want to apply, then discover issues that take 3–6 months to resolve. Start 6–12 months out.

    2. Disputing Everything Hoping Something Sticks

    Filing disputes on accurate, verified information wastes time and can get your disputes flagged as frivolous — which means the bureau won’t investigate future disputes either. Only dispute items that are genuinely inaccurate, outdated, or unverifiable.

    3. Closing Old Accounts

    It feels responsible to close cards you don’t use, but it shortens your credit history and raises your utilization. Keep old accounts open, especially your oldest one.

    4. Paying Down the Wrong Balances First

    If you have limited funds, don’t spread payments evenly across all cards. Prioritize getting each card below 30% (and ideally 10%) of its limit. Per-card utilization matters, not just overall.

    5. Opening New Credit Right Before Applying

    New accounts, hard inquiries, and shorter average age — all at the worst time. No new credit within 6 months of applying (12 months is better).

    6. Making Big Purchases Before Closing

    Furniture, appliances, a car — even on existing cards, these purchases can change your utilization and DTI. Wait until after closing.

    7. Changing Jobs During the Process

    Even a promotion can complicate underwriting if it changes your compensation structure. Hold off on job changes until after closing if at all possible.

    8. Ignoring Non-Credit Factors

    Your credit score is one piece of the puzzle. DTI, employment history, down payment, and reserves all matter. Don’t optimize credit at the expense of other factors.

    9. Falling for Quick-Fix Scams

    Anyone who guarantees a specific outcome, promises to remove accurate information, or charges upfront fees is not legitimate. Use FCRA-compliant, attorney-backed credit repair only.

    10. Not Checking All Three Reports

    Errors can appear on one bureau’s report and not the others. If you only check one, you might miss something that a lender sees. Pull all three — Equifax, Experian, and TransUnion.

    11. Disputing During Underwriting

    Active disputes can block loan approVAl. Complete all disputes before you formally apply for the mortgage.

    12. Forgetting That Medical Bills Can Affect Credit

    Unpaid medical bills can end up in collections and on your credit report. While some scoring models treat medical collections more leniently, they still hurt — and lenders may still require resolution. Address medical collections proactively.

    13. Not Communicating With Your Loan Officer

    Your loan officer can’t help you navigate issues they don’t know about. If something changes — a new job, a large deposit, a missed payment — tell them immediately. Transparency gives them the chance to find a solution.

    14. Assuming Your Score Is The Same Across All Bureaus

    Scores VAry between bureaus because creditors report differently to each. A lender might pull a “tri-merge” report that shows all three, and they typically use the middle score (for conventional) or the lowest score (for some FHA lenders). Know all three of your scores, not just one.

    15. Neglecting Payment History While Focusing on Disputes

    The most important factor in your score is payment history. While you’re disputing errors and paying down balances, don’t let a single payment slip. One new late payment can undo months of repair work.

    FAQ

    1. Can I buy a house with a 580 credit score?

    Yes, potentially. The FHA allows loans with a minimum score of 580 for the 3.5% down payment option. However, individual lenders may require higher scores (often 620+), and a 580 score will mean higher interest rates and more limited loan options. If your score is at 580, working to raise it into the mid-600s before applying can significantly improve your terms.

    2. How fast can credit repair raise my score?

    It depends on what’s being addressed. Paying down high credit card utilization can produce score improvements within 30–60 days. Disputing and removing errors typically takes 30–45 days per dispute cycle. More significant improvements — from resolving collections, establishing payment history, or recovering from major derogatory events — take 6–12 months or more. Anyone promising specific results within a guaranteed timeframe is not being honest.

    3. Do I need to pay off all collections before getting a mortgage?

    Not necessarily. Whether collections need to be paid depends on the loan type, the lender’s overlays, the amount, and the age of the collection. Conventional loans may require larger or recent collections to be resolved. FHA is more lenient. Some lenders require all collections from the last 24 months to be paid. Work with your loan officer to determine which collections actually need to be addressed for your specific loan.

    4. Will shopping around for a mortgage hurt my credit score?

    No — not if you shop within the right window. Credit scoring models treat multiple mortgage inquiries within a 14- to 45-day period (depending on the model) as a single inquiry for scoring purposes. To be safe, do all your rate shopping within a 14-day window. This protection only applies to mortgage, auto, and student loan inquiries — not credit card applications.

    5. Should I close credit cards I don’t use before applying for a mortgage?

    No. Closing accounts can lower your score by reducing your aVAilable credit (which raises utilization) and shortening your average account age. Keep old accounts open, make a small purchase every few months to keep them active, and pay in full. If a card has an annual fee, ask the issuer about downgrading to a no-fee version instead of closing it.

    6. How long after bankruptcy can I buy a house?

    For a Chapter 7 bankruptcy, the waiting period is typically 2 years for an FHA loan and 4 years for a conventional loan from the date of discharge. For a Chapter 13 bankruptcy, FHA may allow approVAl after 1 year of on-time payments under the repayment plan (with court approval), while conventional typically requires 2 years after discharge. These are minimums — you’ll also need to have rebuilt your credit during that time.

    7. Can I do credit repair myself, or do I need a firm?

    You can absolutely do credit repair yourself. The FCRA gives you the right to dispute inaccurate information on your own, and there’s no legal requirement to use a firm. However, a reputable credit repair firm — especially one that’s attorney-backed — can help you navigate complex cases, ensure disputes are filed effectively, negotiate with collectors, and coordinate with your loan officer. For simple cases (one or two clear errors), DIY may be fine. For complex cases (multiple collections, mixed files, creditor disputes), professional help can save time and improve outcomes.

    8. What is the difference between pre-qualification and pre-approval?

    Pre-qualification is a preliminary estimate of what you might borrow, based on information you provide without a credit check or documentation. It’s informal and not a guarantee. Pre-approVAl is a formal process where a lender pulls your credit, verifies your income and assets, and gives you a conditional commitment for a specific loan amount. Pre-approval carries much more weight — sellers and real estate agents expect it, and it tells you exactly where you stand.

    Ready to Get Mortgage-Ready?

    If you’re planning to buy a house and you know your credit needs work, the best time to start was six months ago. The second best time is today.

    Every month you wait is a month that negative marks stay on your report, errors go unchallenged, and your score stays where it is instead of moving toward your target. And every point you add to your score before you lock a mortgage rate is money saved — month after month, year after year, for the life of your loan.

    At credit-repair.com, we help homebuyers get mortgage-ready through a process that’s transparent, legally compliant, and built around your specific goals. Here’s what sets us apart:

    Attorney-backed process — your disputes are handled with full legal oversight and FCRA compliance

    Three-bureau credit audits — we examine your Equifax, Experian, and TransUnion reports in detail to find every error and disputable item

    Custom repair plans — we build your plan around your target loan type, timeline, and the specific items blocking your approVAl

    Creditor negotiation — we work directly with creditors and collection agencies to resolve items effectively

    Long-term education — we don’t just fix your credit; we equip you with the knowledge to keep it strong long after you close on your home

    Coordination with your loan officer — we work alongside your lender so your credit repair aligns with your mortgage timeline

    Whether you’re a year out from house hunting or already in the process and hitting a credit roadblock, a free credit audit is the first step. We’ll review your reports, identify exactly what’s holding you back, and give you a clear, honest picture of what it will take to get mortgage-ready.

    [Get your free credit audit at credit-repair.com] Get a free credit audit.

    No pressure, no quick-fix promises — just a straightforward assessment of where you stand and a real plan to get you to closing.
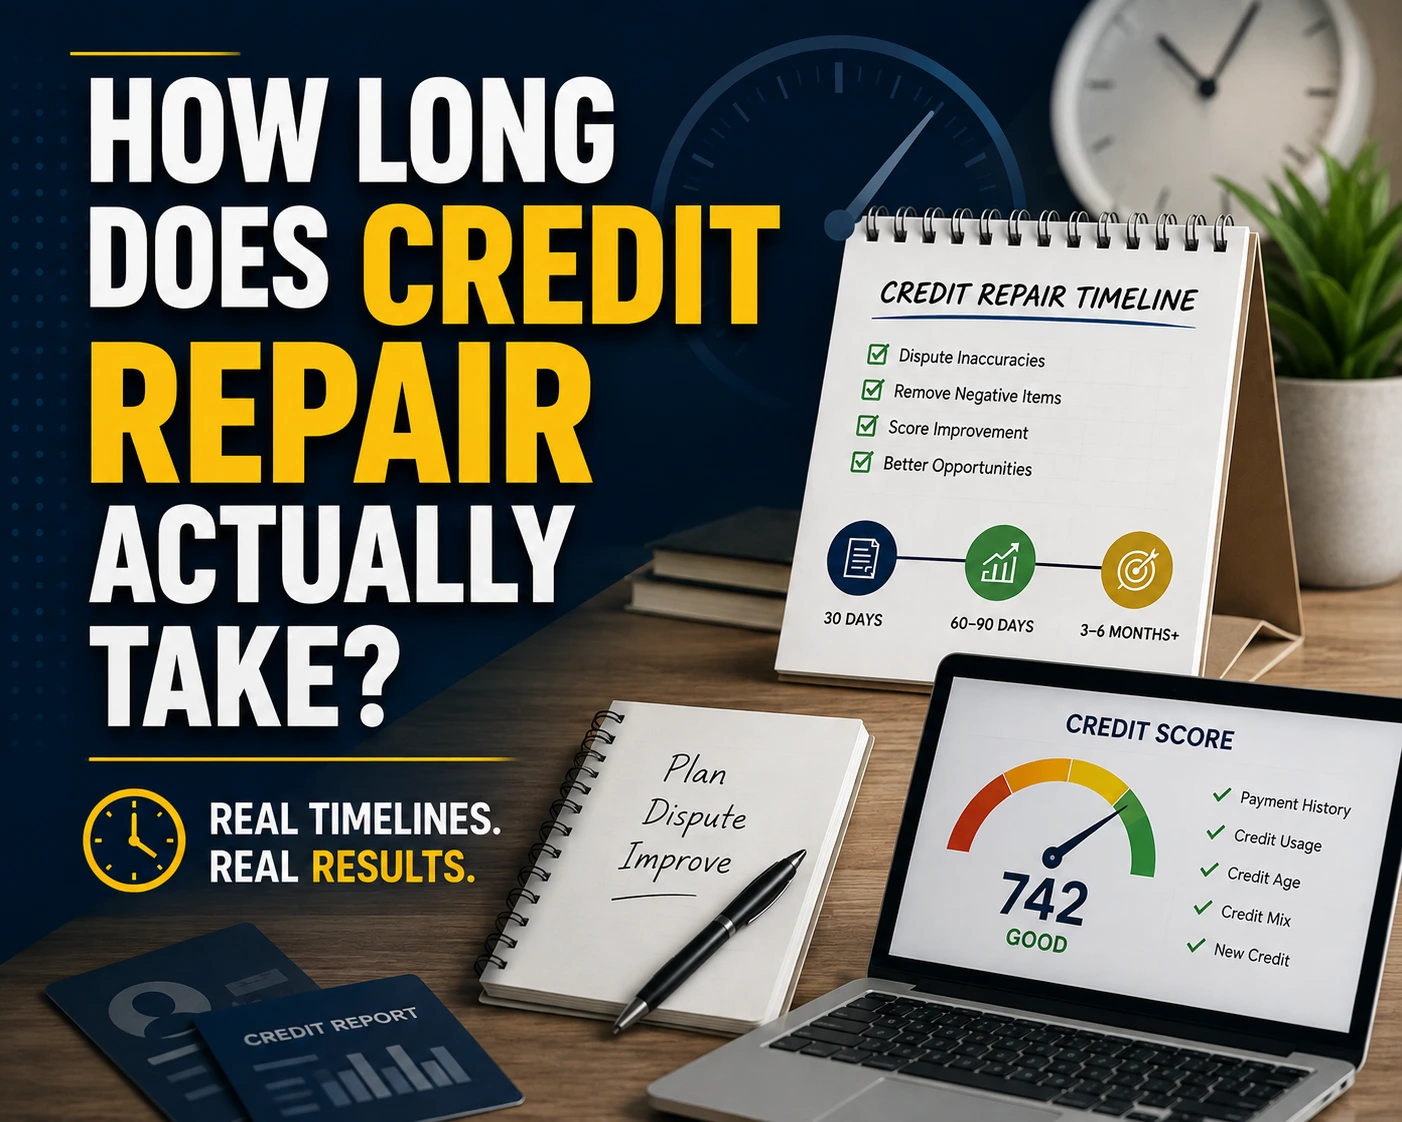
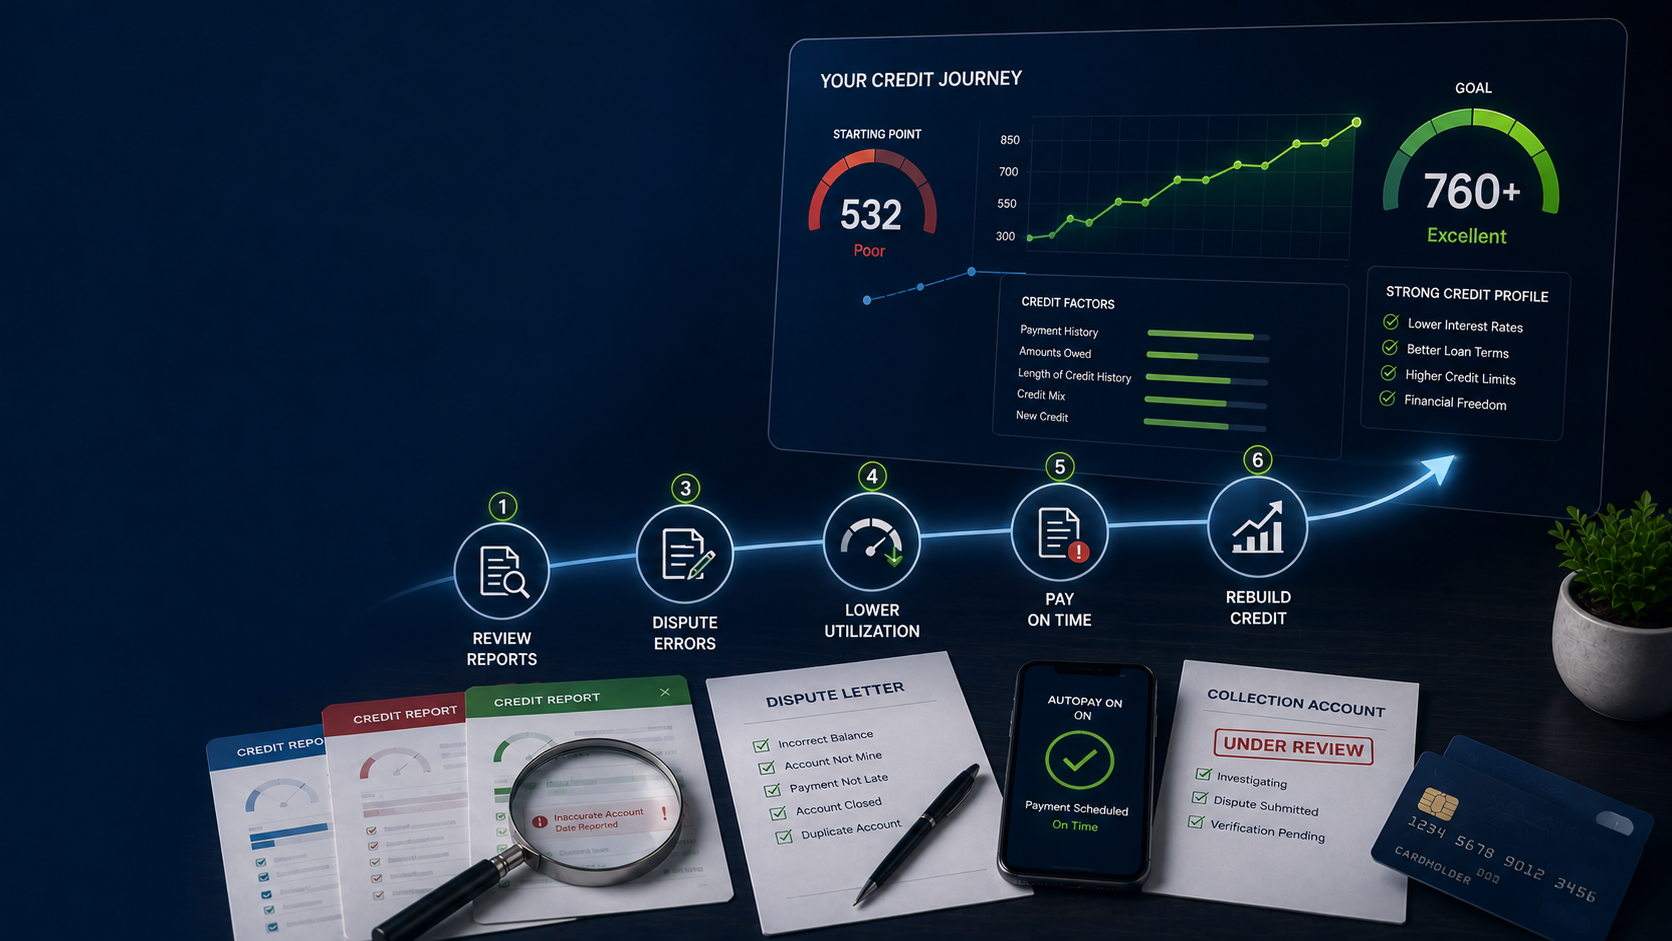
  • How to File a Credit Dispute (and What Happens Next)

    How to File a Credit Dispute (and What Happens Next)

    Your credit report is one of the most important financial documents attached to your name. It decides whether you get approved for a mortgage, what interest rate you pay on a car loan, whether a landlord will rent to you, and in some cases whether a job offer comes through. So when something on that report is wrong — a late payment you actually paid on time, a collection you’ve never heard of, an account that was never yours — the consequences can ripple through your life for years.The good news is that you have a legal right to challenge anything on your credit report that is inaccurate, incomplete, unverifiable, or outdated. That right is guaranteed by federal law under the Fair Credit Reporting Act (FCRA), and the credit bureaus are required by law to investigate your dispute — usually within 30 days — and remove anything they cannot verify. You don’t need to pay anyone to do this for you. You can file a credit dispute yourself, for free, and this guide will walk you through every step.That said, disputes can get complicated. Bureaus push back, furnishers “verify” items that are clearly wrong, and the process has a dozen small pitfalls that can get your dispute rejected before anyone even looks at it. We’ll cover all of that here too — including what to do when the system fails you and you need to escalate. If you’d rather have an attorney-backed team handle it, we’re here for that. But whether you do it yourself or work with us, you should understand how the process works. That’s what this article is for.

    Valid Reasons to Dispute an Item on Your Credit Report

    Not every dispute is a valid dispute. The FCRA gives you the right to challenge information that is inaccurate, incomplete, unverifiable, or outdated — and there’s a specific category for information that simply isn’t yours. Let’s break down each of these.

    1. Inaccurate information. This is the most common reason to file a credit dispute. Inaccurate means the information on your report doesn’t match what actually happened. Examples include:

    • A payment reported as late when you paid on time (and have the bank statements to prove it).
    • An account balance that’s wrong — say, a credit card showing $4,200 owed when you’ve paid it down to $800.
    • A loan amount or original credit limit that’s incorrect.
    • A payment history that shows missed payments in months you paid in full.
    • An account status reported as “charged off” when you’ve since settled it or paid it in full.

    2. Incomplete information. Sometimes an account is reported with missing context that makes it look worse than it is. Examples include:

    • A settled account that doesn’t show as “settled” — it still looks like an open collection.
    • A paid-off account still showing a balance.
    • A credit card that doesn’t report its credit limit, which can make your utilization look artificially high.
    • An account that was transferred or sold but only shows the original creditor’s entry as delinquent, without showing the transfer.

    3. Unverifiable information. This is one of the most powerful grounds for a dispute, and it’s often misunderstood. “Unverifiable” means the bureau, when they investigate, cannot get the furnisher to confirm that the information is accurate. This can happen for several reasons:

    • The original creditor has gone out of business or no longer has records of the account.
    • The furnisher doesn’t respond to the bureau’s investigation request within the required timeframe.
    • The furnisher’s records are incomplete or contradictory.
    • A collection agency can’t produce documentation proving they own the debt or that you owe it.

    You don’t have to know in advance that an item is unverifiable. You dispute it, the bureau investigates, and if the furnisher can’t back it up, the item gets removed. This is why it’s worth disputing older collection accounts — the documentation trail often doesn’t survive.

    4. Outdated information. The FCRA sets strict time limits on how long negative information can stay on your report. Most negative items — late payments, collections, charge-offs, foreclosures, and settled accounts — must be removed after seven years. A Chapter 7 bankruptcy can stay for ten years. If an item has passed its reporting time limit and is still showing up, you have a clear right to have it removed.

    A common outdated-information issue: a collection account that was sold and re-aged by a new collection agency, resetting the clock on the reporting period. That’s illegal. The seven-year clock starts from the original delinquency date with the original creditor — not from when a new collector bought the debt.

    5. Not yours (identity theft or mixed file). Sometimes information shows up on your report that has nothing to do with you. This can happen because of identity theft (someone opened accounts in your name) or because of a “mixed file” — where the bureau has merged your credit file with someone else’s, often someone with a similar name or Social Security number. Mixed files are shockingly common, especially among family members with similar names (Jr. vs. Sr., for example).

    If an account isn’t yours, dispute it immediately. For identity theft cases, you should also file a report with the Federal Trade Commission at IdentityTheft.gov and place a fraud alert or credit freeze with the bureaus.

    What You Can’t Dispute Away (and Why Honesty Matters)

    Here’s the part some credit repair companies won’t tell you, and it’s important: you cannot legally dispute accurate negative information that you legitimately owe. If you missed a payment, defaulted on a loan, or ran up a credit card and didn’t pay it, that negative mark has a right to be on your report for up to seven years — and no dispute letter, no matter how cleverly worded, is going to change that.

    Filing a dispute on an item you know is accurate is not just ineffective — it can actively work against you. Here’s why:

    • The bureau can flag your dispute as “frivolous.” Under FCRA Section 611, a bureau can refuse to investigate a dispute if they reasonably determine it’s frivolous or irrelevant. If you dispute every negative item on your report at once, with no specific reason, they’re likely to dismiss the whole batch — and that dismissal can make it harder to get legitimate disputes taken seriously later.
    • You’re training the furnisher to verify. Every time you dispute an accurate item, the furnisher gets pinged and confirms it. Now they’ve got their records pulled and organized. When you (or a credit repair company) dispute it again later, they’ve already done the homework — they verify faster the second time.
    • You may create a paper trail that hurts you. If you dispute something in writing and state “this is not my account” when it clearly is, that statement can come back to bite you in a lawsuit, a loan application, or any future proceeding where your credibility matters.

    So what can you do about accurate negative items you legitimately owe? A few honest paths:

    • Wait it out. Most negative items fall off after seven years. The impact on your score also fades over time — a late payment from five years ago hurts far less than one from last month.
    • Negotiate a pay-for-delete or goodwill deletion. Some creditors will remove a negative mark if you pay the debt (or settle it). Others will consider a “goodwill” removal if you’ve since rebuilt a positive payment history with them. This isn’t a dispute — it’s a negotiation. We do this for clients regularly.
    • Pay it and let time work. A paid collection is still a collection on your report, but many scoring models (including FICO 9 and VantageScore) treat paid collections more favorably than unpaid ones. And “paid in full” looks better to a manual reviewer than “unpaid.”
    • Rebuild with positive history. The single most powerful thing you can do for your credit score is to build new, positive payment history. A secured credit card, a credit-builder loan, or becoming an authorized user on a responsible family member’s card can start moving your score in the right direction even while old negatives are still on the report.

    The honest truth is that credit repair isn’t magic. It’s a legal process that works when there are actual errors on your report — and there very often are. But it’s not a tool for erasing legitimate debts, and anyone who tells you otherwise is either lying or putting you at legal risk.

    How to Prepare Before You File a Dispute

    Before you file a single dispute, do the preparation work. Skipping this step is one of the biggest reasons disputes get rejected. Here’s what you need to do.

    Step 1: Pull current reports from all three bureaus.

    Go to AnnualCreditReport.com — the only federally authorized source for free credit reports. You can pull all three bureau reports at once, or stagger them throughout the year. Since the bureaus made free weekly reports available, you can also check back regularly at no cost.

    Pull all three. Equifax, Experian, and TransUnion are separate companies with separate databases. An error on your Equifax report may not appear on your Experian report at all — and vice versa. Disputing with Equifax does nothing to fix an error on your TransUnion report. You need to see all three to know what you’re dealing with.

    Save copies as PDFs. Print hard copies if you can. You want a snapshot of your report as it exists right now, because the bureaus update reports constantly and you may need to prove what was showing on a specific date.

    Step 2: Go through each report line by line.

    This is tedious, but it’s the most important part of the process. For each report, check:

    • Personal information — name, current and previous addresses, Social Security number, date of birth, employer. Mixed files often show up here first. If you see an address you’ve never lived at or an employer you’ve never worked for, that’s a red flag.
    • Account list — every account, including creditor name, account number (often partially masked), account type, date opened, credit limit or original loan amount, current balance, payment status, and payment history.
    • Public records — bankruptcies, civil judgments, tax liens. (Note: most tax liens and civil judgments were removed from credit reports following a 2017 settlement, but bankruptcies still appear.)
    • Inquiries — both hard inquiries (which affect your score) and soft inquiries (which don’t). If you see a hard inquiry from a company you never applied with, that’s either a mixed file or identity theft.

    Step 3: Identify every error and categorize it.

    For each error you find, write down:

    • Which bureau it appears on (it may be on one, two, or all three).
    • The account name and account number.
    • What specifically is wrong (e.g., “shows 30 days late in March 2024, but payment was made on March 12, 2024 — see attached bank statement”).
    • What category of error it is: inaccurate, incomplete, unverifiable, outdated, or not mine.
    • What evidence you have to support the dispute.

    Step 4: Gather your evidence.

    This is where disputes succeed or fail. The more documentation you can provide, the harder it is for the bureau to dismiss your dispute. Useful evidence includes:

    • Bank or credit card statements showing payments were made on time.
    • Settlement letters or paid-in-full letters from creditors.
    • Billing statements showing the correct balance.
    • Identity theft reports from IdentityTheft.gov (for “not mine” disputes).
    • Police reports (for identity theft cases).
    • Previous correspondence with the creditor or collection agency.
    • Court documents showing a debt was discharged in bankruptcy.

    Make copies of everything. Never send originals. If you’re mailing your dispute, keep a copy of every document you send, plus the dispute letter itself, plus the certified mail receipt (more on that below).

    Step 5: Decide which items to dispute first.

    If you have multiple errors, prioritize. Start with the most damaging and most clearly wrong items — a collection that isn’t yours, a bankruptcy that’s past the ten-year mark, a charge-off that was actually settled. These are the disputes most likely to succeed and the ones that will move your score the most.

    Don’t file a dozen disputes at once unless they’re all clearly valid. Filing too many at once increases the chance the bureau flags the batch as frivolous. Pace yourself — three to five well-documented disputes at a time is a reasonable approach.

    How to File a Dispute With Each Bureau

    Each of the three credit bureaus has its own dispute process. You can file online, by mail, or by phone. We’ll cover all three methods for each bureau, plus what to include regardless of which method you use.

    No matter which bureau you’re disputing with, every dispute should include:

    • Your full name, current address, and any previous addresses relevant to the account.
    • Your Social Security number and date of birth (the bureaus use these to locate your file).
    • A clear identification of each item you’re disputing — creditor name, account number, and the specific information you believe is wrong.
    • The specific reason for each dispute — why you believe the information is inaccurate, incomplete, unverifiable, outdated, or not yours.
    • Any supporting documentation (copies, never originals).
    • A clear statement of what you want the bureau to do: “I am requesting that this item be removed” or “I am requesting that this information be corrected to reflect…”

    Equifax Dispute

    Equifax offers three ways to file a dispute.

    Online: Go to the Equifax dispute portal (equifax.com/personal/credit-report-services/credit-dispute). You’ll need to create an account or log in, then follow the prompts to select the item(s) you’re disputing and provide your reasons. You can upload supporting documents directly through the portal.

    By mail: Send your dispute letter and supporting documents to:

    Equifax Information Services LLC P.O. Box 740256 Atlanta, GA 30374-0256

    Include a copy of your Equifax credit report with the disputed items circled or highlighted, your dispute letter, and copies of supporting documentation. Send it via certified mail with return receipt so you have proof of delivery and the date it was received.

    By phone: Call Equifax’s dispute line at 1-866-640-2273. Have your credit report handy — the customer service rep will need the report number. Phone disputes are faster but harder to document, and you lose the paper trail. We recommend following up a phone dispute with a written letter for the record.

    Equifax typically completes investigations within 30 days and will send you the results in writing, including an updated copy of your credit report if changes were made.

    Experian Dispute

    Experian’s dispute process is similar.

    Online: Go to the Experian Dispute Center (experian.com/disputes). You’ll need to have your Experian credit report — either the one you pulled from AnnualCreditReport.com or a current one from Experian’s site. Enter the report number, select the items you want to dispute, provide your reasons, and upload supporting documents.

    Experian’s online portal is generally well-designed and lets you track the status of your dispute through your account. You’ll get updates as the investigation progresses.

    By mail: Send to:

    Experian P.O. Box 9701 Allen, TX 75013

    Include the same materials as for Equifax — a copy of your Experian report with disputed items marked, your dispute letter, and supporting documentation. Certified mail with return receipt.

    By phone: Call 1-866-200-5764. Have your Experian report number ready. As with Equifax, a phone dispute is quick but harder to document — follow up in writing if you can.

    Experian is often the fastest of the three to complete investigations, frequently finishing within 20–25 days, though they have the full 30.

    TransUnion Dispute

    TransUnion’s process mirrors the others.

    Online: Go to the TransUnion dispute portal (transunion.com/credit-disputes/dispute-your-credit). You can create a free account or use your existing TransUnion account to file and track your dispute. Upload supporting documents directly through the portal.

    By mail: Send to:

    TransUnion LLC Consumer Dispute Center P.O. Box 1000 Chester, PA 19022

    Same package: copy of your TransUnion report with disputed items marked, dispute letter, supporting docs, certified mail with return receipt.

    By phone: Call 1-800-916-8800. Have your TransUnion report number available.

    TransUnion generally completes investigations within the full 30-day window and sends results by mail.

    A note on dispute timing across all three bureaus: The 30-day clock starts when the bureau receives your dispute, not when you mail it. If you mail on the 1st and they receive it on the 5th, the 30 days runs from the 5th. This matters if you’re tracking deadlines — always use certified mail so you have proof of the receipt date.

    How to file a credit dispute with Equifax, Experian, and TransUnion

    Disputing With the Furnisher vs. the Bureau

    Most people only dispute with the credit bureaus. But the FCRA also gives you the right to dispute directly with the furnisher — the original creditor or collection agency that reported the information to the bureau. This is under FCRA Section 623, and it’s a separate, independent right from your right to dispute with the bureau.

    When to dispute with the bureau: Almost always. This is your primary path. The bureau has the legal obligation to investigate and remove unverifiable information, and they’re the ones who actually control what shows on your report.

    When to dispute with the furnisher directly:

    • When you have strong documentation that the furnisher’s reporting is wrong and you want them to correct it at the source.
    • When a bureau investigation “verified” the item but you know it’s wrong — a furnisher dispute creates a separate record and a separate legal obligation.
    • When you’re dealing with a collection agency that may not have the documentation to back up the debt.
    • When you want to build a paper trail for a potential FCRA lawsuit — direct furnisher disputes create their own set of legal obligations and potential liability for the furnisher.

    Why doing both can help: When you dispute with the bureau, the bureau contacts the furnisher and asks them to verify. If you’ve also sent a separate dispute letter to the furnisher directly, the furnisher now has two obligations: respond to the bureau’s investigation request AND respond to your direct dispute. If they fail on either front, you have grounds for removal — and potentially for legal action.

    To dispute directly with a furnisher, send a letter to the creditor or collection agency at the address listed on your credit report (or their correspondence address, if different). State clearly that you are disputing the accuracy of information they reported to the credit bureaus, identify the specific account and the specific information you believe is wrong, and include copies of any supporting documentation. Under FCRA Section 623, they are required to investigate, review the information, and report the results to you — and if they find the information is inaccurate, they must notify all the bureaus they reported to so the information can be corrected.

    Keep in mind: the furnisher dispute process has its own rules and timelines, and it’s slightly different from the bureau process. The furnisher must complete their investigation within roughly the same 30-day window. If you’re dealing with a stubborn furnisher, this is where having an attorney-backed credit repair firm can make a real difference — a letter from a law firm tends to get taken more seriously than a letter from a consumer. Get a free credit audit.

    What to Include in a Dispute Letter — Full Sample Template

    A good dispute letter is clear, specific, and well-documented. It doesn’t need to be long or use legal-sounding language — in fact, plain language is better. The bureaus’ dispute processing systems are largely automated, and clear, specific information gets processed faster than dense legal prose.

    Here’s a template you can adapt. Replace the bracketed information with your details.

    [Your Full Name]
    [Your Current Address]
    [Your Phone Number]
    [Your Email]
    [Your Date of Birth]
    [Your Social Security Number: XXX-XX-XXXX]
    
    [Date]
    
    [Credit Bureau Name — Equifax, Experian, or TransUnion]
    [Bureau Dispute Mailing Address]
    
    RE: Dispute of Inaccurate Information on My Credit Report
    Report Number: [Your report number, if available]
    
    To Whom It May Concern:
    
    I am writing to dispute the following information that appears on my credit report. I believe this information is inaccurate and should be investigated and corrected or removed.
    
    1. Item #1
       - Creditor: [Creditor Name]
       - Account Number: [Account Number or partial number as shown on report]
       - Disputed Information: [Describe what is wrong — e.g., "Account shows a 30-day late payment in March 2024"]
       - Reason for Dispute: [State why it's wrong — e.g., "Payment was made on time on March 12, 2024. I have attached a copy of my bank statement showing the payment."]
       - Requested Action: [e.g., "Remove the late payment notation" or "Delete this account entirely"]
    
    2. Item #2
       - Creditor: [Creditor Name]
       - Account Number: [Account Number]
       - Disputed Information: [Describe]
       - Reason for Dispute: [Explain]
       - Requested Action: [What you want]
    
    [Repeat for each disputed item.]
    
    I have attached the following supporting documentation:
    - [List each document — e.g., "Copy of bank statement dated March 2024," "Copy of settlement letter from XYZ Collections dated January 2024," etc.]
    
    Please investigate these disputed items in accordance with the Fair Credit Reporting Act, 15 U.S.C. § 1681i. If the information cannot be verified, please remove it from my credit report. Please send me the results of your investigation in writing, along with an updated copy of my credit report reflecting any changes.
    
    Thank you for your prompt attention to this matter.
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]
    
    Enclosures: [List number of enclosures]
    

    A few notes on using this template:

    • Be specific. “This account is wrong” doesn’t work. “This account shows a balance of $4,200 but was settled in full for $2,100 on January 15, 2024 — see attached settlement letter” does work.
    • Keep copies of everything you send. Keep the certified mail receipt and the return receipt when it comes back.
    • Don’t use this template to dispute items you know are accurate. Remember the frivolous-dispute rule — honesty matters here.
    • You can use the same letter format for all three bureaus; just change the mailing address and report number.
    • If you’re disputing identity theft, include a copy of your FTC Identity Theft Report and a police report. The FCRA gives identity theft victims additional rights, including blocking information from their report.

    Online Disputes vs. Mail Disputes — Pros and Cons

    You can file a credit dispute online or by mail (or by phone, but phone is the least documented option). Each method has trade-offs.

    Online disputes — pros:

    • Fast. You can file in 15–20 minutes from your computer.
    • Free and available 24/7 through each bureau’s dispute portal.
    • You can upload supporting documents directly.
    • You can track the status of your dispute through your account.
    • The bureaus’ systems are set up to process online disputes efficiently — they often move through the pipeline faster.

    Online disputes — cons:

    • The online forms may limit how much detail you can include or the types of documents you can upload.
    • You may inadvertently agree to the bureau’s terms of service, which in some cases include arbitration clauses that limit your right to sue. Read the fine print.
    • You don’t have the same physical paper trail you get with certified mail.
    • It’s harder to document exactly what you submitted and when.

    Mail disputes — pros:

    • You have a complete paper trail: a copy of your letter, copies of all supporting documents, the certified mail receipt proving you sent it, and the return receipt proving they received it.
    • You can include as much detail and as many documents as you want — no character limits or upload restrictions.
    • You avoid any online terms-of-service agreements and their arbitration clauses.
    • Certified mail with return receipt is legally compelling evidence if you ever need to prove the bureau received your dispute and failed to act on it.

    Mail disputes — cons:

    • Slower — you have to print, assemble, and mail the package, then wait for delivery.
    • Costs a few dollars for certified mail and return receipt.
    • You can’t track the investigation status online (though you’ll get results by mail).

    Our recommendation: For most disputes, mail with certified mail return receipt is the stronger option. The paper trail matters — especially if you end up needing to escalate to a CFPB complaint or a lawsuit. The bureaus are more careful when they know you have documented proof of every step. But for simple, clear-cut disputes (a misspelled name, an old address, a single clearly wrong late payment), the online portals are perfectly fine and faster.

    If you use online disputes, take screenshots of every page of the submission process, save PDFs of any confirmation emails, and keep a log of what you disputed and when. That’s your paper trail.

    The 30-Day FCRA Investigation Rule Explained

    The FCRA gives the credit bureaus 30 days to complete an investigation after receiving your dispute. This is the single most important deadline in the dispute process, and it’s worth understanding in detail.

    What the bureau must do within 30 days:

    • Review your dispute and all the information you provided.
    • Contact the furnisher (the creditor or collection agency that reported the information) and ask them to verify the accuracy of the disputed information.
    • Review the furnisher’s response and any evidence they provide.
    • Make a determination — is the information accurate, inaccurate, or unverifiable?
    • Notify you of the results in writing, usually within 5 days of completing the investigation.
    • Update your credit report if changes are required — removing deleted items, correcting updated information, etc.

    The 45-day extension: There’s an important exception to the 30-day rule. If you send additional information related to your dispute after you’ve already filed it, the bureau gets an extra 15 days — bringing the total to 45 days. This is meant to give them time to review the new information.

    Be careful with this. Some credit repair companies deliberately send additional information mid-investigation to trigger the 45-day extension, thinking more time helps. It usually doesn’t — it just delays the outcome. Only send additional information if it genuinely strengthens your dispute.

    What counts as “receiving” the dispute: The 30-day clock starts when the bureau receives your dispute, not when you mail it. This is why certified mail matters — it gives you proof of the receipt date. If you file online, the receipt date is usually the same day you submit.

    When the clock doesn’t start: If your dispute is missing required information (like your identity, the specific item you’re disputing, or the reason for your dispute), the bureau can request more information from you — and the 30-day clock doesn’t start until they have what they need. This is another reason to be thorough and specific in your initial dispute.

    What happens if they miss the deadline: If a bureau fails to complete the investigation within 30 days (or 45, if extended), they must delete the disputed item from your report. This is a hard rule. In practice, bureaus rarely miss the deadline — but if they do, you have a clear right to removal, and documented proof (certified mail receipt, screenshots of your online submission) makes enforcement straightforward.

    A note on frivolous disputes: The 30-day rule only applies to disputes the bureau considers legitimate. If they determine your dispute is frivolous — because you didn’t provide enough information, you’re disputing the same item repeatedly without new information, or you’re disputing everything on your report without specific reasons — they can refuse to investigate. They must notify you within 5 days of that determination and explain why. If you get a “frivolous” rejection, read the reason carefully, fix the deficiency, and refile with better documentation.

    What Happens During an Investigation

    When you file a dispute, here’s what goes on behind the scenes.

    1. Your dispute is logged and routed. The bureau enters your dispute into their system, assigns it a tracking number, and routes it to their dispute processing team. For online disputes, this happens almost instantly. For mailed disputes, it happens when the letter is received and opened.

    2. The bureau contacts the furnisher. Through an electronic system called e-OSCAR (Online Solution for Complete and Accurate Reporting), the bureau sends the furnisher a brief summary of your dispute — usually just a two-digit ” dispute code” and minimal context. This is a known weakness in the system: the furnisher often doesn’t see your actual dispute letter or supporting documents, just a compressed summary. This is one reason items that are clearly wrong sometimes get “verified” — the furnisher is responding to a generic code, not your specific evidence.

    3. The furnisher investigates. The furnisher is supposed to review their records, check whether the information they reported is accurate, and respond to the bureau. They can confirm, correct, or delete the information. In practice, many furnishers simply confirm what they originally reported without a thorough review — which is why furnisher disputes (see above) and documentation matter.

    4. The bureau makes a determination. Based on the furnisher’s response, the bureau decides whether to:

    • Delete the item (if the furnisher can’t verify it or agrees it’s wrong).
    • Update the item (if the furnisher provides corrected information).
    • Leave it as is (if the furnisher confirms the information is accurate).

    5. You’re notified of the results. The bureau sends you the results in writing, usually within 5 days of completing the investigation. If items were deleted or updated, you’ll receive an updated copy of your credit report.

    The whole process is designed to take 30 days, and it usually does. The weakness in the system is step 2 — the e-OSCAR summarization often strips out the nuance of your dispute, and the furnisher’s “investigation” can be cursory. This is why strong documentation and, in stubborn cases, direct furnisher disputes and escalation matter.

    Possible Outcomes: Deleted, Updated, Verified, Remains

    When the investigation is complete, you’ll get a results letter. Here are the possible outcomes for each disputed item.

    Deleted. The item is removed from your credit report entirely. This is the best outcome. It happens when the furnisher can’t verify the information, doesn’t respond within the timeframe, or agrees the information is wrong. A deleted item stops affecting your score immediately and is removed from all future reports.

    Updated. The information is corrected but the account remains on your report. For example, a late payment that was reported as 60 days late might be corrected to 30 days late, or a balance might be updated to reflect a payment you made. This can still help your score, depending on the nature of the update.

    Verified / Remains. The furnisher confirmed the information is accurate, and the item stays on your report as-is. This is the outcome no one wants, but it’s common — and it’s not the end of the road. If you still believe the item is wrong, you have escalation options (next section).

    Reinserted. Rarely, an item that was deleted can reappear on your report later if the furnisher subsequently certifies that the information is accurate. The FCRA requires the bureau to notify you within 5 days if an item is reinserted. If this happens, you have a right to dispute again, and the reinsertion itself can be challenged.

    For items that are verified and remain, you can also request that the bureau include a brief statement of your dispute on your credit report — a “consumer statement” that future creditors will see when they pull your report. This doesn’t change your score, but it gives context to anyone reviewing your file manually.

    What to Do if an Item Is “Verified” but Still Wrong

    Sometimes a bureau investigation comes back “verified” but you know — and can prove — the information is wrong. The furnisher confirmed it, but they’re wrong (or lying, or relying on incomplete records). This is frustrating, but it’s not the end of the line. Here’s the escalation path.

    Step 1: Request a reinvestigation. You have the right to request that the bureau reinvestigate, especially if you have new information or evidence that wasn’t considered in the first investigation. Send a new dispute letter with the additional evidence and a clear explanation of why the original verification was incorrect. Don’t just refile the same dispute — that’s likely to be flagged as frivolous. Add something new.

    Step 2: Dispute directly with the furnisher. As we covered earlier, FCRA Section 623 gives you the right to dispute directly with the furnisher. This creates a separate legal obligation. If the furnisher can’t substantiate the information, they must notify the bureaus to correct or remove it. A direct furnisher dispute also creates a record that can support a later legal claim.

    Step 3: File a complaint with the Consumer Financial Protection Bureau (CFPB). The CFPB is the federal agency that enforces the FCRA. You can file a complaint at consumerfinance.gov. The CFPB will forward your complaint to the bureau or furnisher and require them to respond, usually within 60 days. CFPB complaints get attention — they’re public, they’re tracked, and companies don’t want a pattern of complaints on their record. In many cases, filing a CFPB complaint prompts a more careful review and can result in items being removed.

    Step 4: Consult an attorney. If the item is clearly wrong, you’ve disputed it properly, and the bureau and furnisher still won’t fix it, you may have a case under the FCRA. The FCRA allows you to sue for:

    • Actual damages — money you’ve lost because of the error (higher interest rates, denied credit, denied housing, etc.).
    • Statutory damages — a set amount per violation, up to $1,000 per violation.
    • Punitive damages — in cases of willful violations.
    • Attorney’s fees and costs — the FCRA requires defendants to pay your attorney’s fees if you win, which means many FCRA attorneys take cases on contingency.

    This is one of the biggest advantages of working with an attorney-backed credit repair firm. If your case warrants legal action, you already have a lawyer in your corner who knows your file. Get a free credit audit.

    How Disputes Affect Your Credit Score

    One of the most common questions about credit disputes is whether filing one will affect your score. The short answer is: not directly, and usually not negatively.

    Filing a dispute does not affect your credit score. The act of disputing an item is not a scoring factor in any FICO or VantageScore model. Your score won’t drop because you filed a dispute.

    What can affect your score is the outcome. If an item is deleted, your score may go up — sometimes significantly, especially if the deleted item was a serious negative like a collection or charge-off. If an item is updated (say, a balance is corrected downward or a late payment is removed), your score may go up modestly. If the item remains, your score doesn’t change.

    The “soft pull” question. When you pull your own credit report — whether from AnnualCreditReport.com, a bureau’s website, or a credit monitoring service — it’s a soft inquiry (or “soft pull”). Soft inquiries do not affect your credit score. You can pull your own report as often as you like with no impact. Only hard inquiries — made when a lender pulls your credit to evaluate an application — affect your score, and even then the impact is usually small (typically 1–5 points) and temporary.

    The dispute comment. While an item is under dispute, it may show a “Account in Dispute” comment on your credit report. Some older scoring models temporarily excluded disputed items from certain calculations while the dispute was pending — which could cause a small, temporary score fluctuation. Under current FICO and VantageScore models, this is less common, but it’s worth knowing about. The comment is removed once the investigation is complete.

    Indirect effects. If you’re applying for a mortgage or other major loan while a dispute is pending, the lender may ask you to resolve the dispute before proceeding — some mortgage underwriters won’t approve a loan with open disputes on the file. This is a practical consideration, not a scoring one, but it’s worth timing your disputes around major credit applications if possible.

    In short: file disputes when you have real errors. Don’t worry about the dispute itself hurting your score — it won’t. Focus on the outcome.

    Common Mistakes That Get Disputes Rejected

    After walking through this process with thousands of credit reports, here are the mistakes we see most often — and how to avoid them.

    1. Disputing everything at once with no specific reasons. This is the number one way to get flagged as frivolous. If you send a dispute that says “everything on my report is wrong, please remove it all,” the bureau will reject it. Always be specific: identify each item, state what’s wrong, and explain why.

    2. Not providing enough detail. “This isn’t my account” with no further explanation is weak. “This account is not mine. I have never had an account with [Creditor]. I have attached a copy of my FTC Identity Theft Report and a police report documenting the identity theft” is strong. The more detail and documentation, the better.

    3. Not keeping a paper trail. If you file by mail and don’t use certified mail, you have no proof the bureau received your dispute. If they claim they never got it — and this happens — you have no recourse. Always use certified mail with return receipt for mailed disputes.

    4. Disputing accurate items. As we covered earlier, this trains the furnisher to verify and can get future legitimate disputes flagged as frivolous. Only dispute items you genuinely believe are wrong.

    5. Giving up after one “verified” result. A first dispute coming back “verified” is not the end. You can reinvestigate with new evidence, dispute with the furnisher directly, file a CFPB complaint, or consult an attorney. Many items that survive a first dispute come off after a second, better-documented attempt.

    6. Using a generic dispute letter with no customization. There are plenty of “credit dispute letter templates” online that promise magic results. They don’t work. A good dispute letter is specific to your situation, identifies your specific items, and includes your specific evidence. Copy-paste letters get poor results.

    7. Not pulling all three bureau reports. If you only dispute with Equifax because that’s the report you happened to pull, you’re missing errors on your Experian and TransUnion reports. Always check all three.

    8. Missing the 30-day follow-up. If the bureau’s 30-day window has passed and you haven’t heard back, follow up. They may have missed the deadline, which gives you grounds for removal. But if you don’t follow up, the item just sits there.

    9. Believing a “dispute” removes the underlying debt. A credit dispute challenges whether information should appear on your credit report. It does not erase the underlying debt. If you owe the money, you still owe it — even if the item is removed from your report because the furnisher couldn’t verify it. A creditor can still pursue collection, file a lawsuit, or resell the debt.

    The “Dispute Everything” Scam — A Warning

    If you’ve spent any time researching credit repair online, you’ve probably seen ads or social media posts promising to “remove all negative items from your credit report in 30 days” or “boost your score 100 points guaranteed.” These are almost always scams, and some of them can get you in legal trouble.

    Here’s how the “dispute everything” scam typically works:

    A company (or an individual on TikTok, YouTube, or Instagram) tells you to dispute every single negative item on your credit report — regardless of whether it’s accurate — using the theory that if the furnisher doesn’t respond within 30 days, the item has to be removed. They sell you a packet of dispute letters or a “credit sweep” service, take your money, and fire off disputes on everything.

    Why this is a bad idea:

    • It’s often illegal. If you knowingly dispute accurate information, you may be making false statements to the credit bureaus — which can be a violation of federal law. Some credit repair companies have been shut down and prosecuted for this exact practice.
    • It gets flagged as frivolous. The bureaus have seen this playbook a thousand times. A batch dispute of every negative item, with no specific reasons, is nearly always rejected as frivolous — and now you’ve made it harder to get legitimate disputes taken seriously.
    • It trains furnishers to verify. Every time a furnisher responds to a bogus dispute, they’re organizing their records. The next time the item is disputed — even for a legitimate reason — they verify it faster.
    • It wastes your time and money. Even if a few items get removed because a furnisher didn’t respond, they often get re-reported later when the furnisher updates their records. The removal is temporary, and you’ve paid for the privilege.
    • It can expose you to legal liability. If you sign a dispute letter stating “this is not my account” when it is, you’ve made a false statement in writing. That can come back to haunt you in a lawsuit, a loan application, or any proceeding where your credibility matters.

    The Credit Repair Organizations Act (CROA) is a federal law that regulates credit repair companies. Among other things, it prohibits credit repair companies from:

    • Charging upfront fees before they perform any services.
    • Making false or misleading claims about what they can do.
    • Advising you to make false statements to the credit bureaus.
    • Altering your identity to create a new credit file.

    If a credit repair company is doing any of these things, walk away. Legitimate credit repair firms — like ours — operate within the FCRA and CROA, only dispute items with valid grounds, and never promise guaranteed results or charge upfront fees for work not yet done.

    The honest version of credit repair is less sexy than “remove everything in 30 days” but it actually works: identify real errors, document them thoroughly, file specific disputes, follow up, and escalate when the system fails. It’s not magic, but it’s effective, legal, and lasting.

    Frequently Asked Questions

    How long does a credit dispute take?

    Under the FCRA, credit bureaus must complete their investigation within 30 days of receiving your dispute. If you send additional information during the investigation, they get an extra 15 days (45 days total). You’ll typically receive the results in writing within 5 days of the investigation being completed. In practice, many investigations finish in 20–25 days, but you should plan for the full 30.

    Will filing a dispute hurt my credit score?

    No. Filing a dispute does not directly affect your credit score. Only the outcome matters — if a negative item is deleted or corrected, your score may go up. If the item remains, your score is unchanged. Pulling your own credit report (to check for errors) is a soft inquiry and also doesn’t affect your score.

    Can I dispute a debt I actually owe?

    You have the right to dispute any information you believe is inaccurate, incomplete, unverifiable, or outdated. If you legitimately owe a debt but the information being reported about it is wrong (wrong balance, wrong date, wrong status), you can dispute the inaccurate details. But you cannot use the dispute process to remove accurate information about a debt you legitimately owe — and trying to do so can get your disputes flagged as frivolous and expose you to legal risk.

    Do I need to hire a credit repair company?

    No. You have the right to file disputes yourself for free. The FCRA gives you the tools, and this guide walks you through the process. That said, a legitimate, attorney-backed credit repair firm can help when disputes get complicated, when furnishers push back, or when you need to escalate to a CFPB complaint or lawsuit. If you choose to work with a firm, make sure they’re CROA-compliant, don’t charge upfront fees for unperformed services, and only dispute items with valid grounds. Get a free credit audit.

    What if the bureau says my dispute is frivolous?

    The bureau must notify you in writing within 5 days if they determine your dispute is frivolous, and they must explain why. Common reasons: not enough information, no specific reason for the dispute, or you’re disputing the same item repeatedly without new information. Read the reason, fix the deficiency, and refile with better documentation and more specific details. If the bureau continues to reject valid disputes, you can file a CFPB complaint or consult an attorney.

    Can I dispute an item that’s older than seven years?

    Yes — and you should. Most negative information must be removed from your credit report after seven years (bankruptcies after ten). If an item is still showing after its reporting period has expired, dispute it as outdated. The bureau must remove it. Check the “date of first delinquency” or “original delinquency date” on the account — that’s when the seven-year clock starts, not the date a collection agency bought the debt.

    What’s the difference between a credit freeze and a fraud alert?

    A credit freeze locks your credit report so no new creditor can access it (and therefore no new accounts can be opened in your name) until you unfreeze it. It’s free under federal law and is the strongest protection against identity theft. A fraud alert is a note on your report asking creditors to take extra steps to verify your identity before opening new accounts. It lasts for one year (or seven years for an extended fraud alert if you’ve filed an identity theft report). A freeze is stronger; an alert is more convenient if you’re actively applying for credit.

    Can I dispute an item that’s already been “verified” once?

    Yes. You can request a reinvestigation, especially if you have new evidence or information that wasn’t considered in the first investigation. You can also dispute directly with the furnisher under FCRA Section 623, file a CFPB complaint, or consult an attorney. A first “verified” result is not final — many items come off after a better-documented second dispute or an escalation.

    Ready to Get Your Credit Back on Track?

    Filing a credit dispute is one of the most powerful tools you have for protecting your financial reputation. The FCRA gives you the right, the process is something you can do yourself, and the outcomes — when the disputes are valid and well-documented — can meaningfully improve your credit score and your financial options.

    That said, we know the process can feel overwhelming, especially when you’re dealing with multiple errors across three bureaus, stubborn furnishers, or the aftermath of identity theft. You don’t have to do it alone.

    At credit-repair.com, we offer a free credit audit across all three bureaus — Equifax, Experian, and TransUnion. We’ll pull your reports, identify every error, and walk you through exactly what can be disputed and how. If you decide to work with us, our attorney-backed team handles the disputes, the furnisher negotiations, and any escalations — including CFPB complaints and legal action when warranted.

    We don’t make empty promises or guarantee results we can’t deliver. We operate in full compliance with the FCRA and the Credit Repair Organizations Act, we only dispute items with valid grounds, and we charge no hidden fees. What we do is give you a clear, honest picture of your credit, a plan to fix what’s wrong, and a team of attorneys and credit experts in your corner from start to finish.

    — Get your free 3-bureau credit audit today. Get a free credit audit.

    Your credit report shouldn’t be telling a story that isn’t true. Let’s fix it — the right way, the legal way, the way that lasts.