Author: Peter Krakue

  • Credit Utilization Ratio: The One Number That Moves Your Score Fastest

    Credit Utilization Ratio: The One Number That Moves Your Score Fastest

    If you could change just one number on your credit report and watch your score climb within weeks, which would you pick? Most people assume it’s payment history — and while paying on time matters enormously, it’s also the slowest lever to move because it takes months or years of spotless behavior to recover from a single missed payment. The fastest lever, by a wide margin, is your credit utilization ratio.Credit utilization is the amount of available credit you’re actually using, expressed as a percentage. It is recalculated every time your card issuers report your balances to the credit bureaus — usually once a month, right after your statement closes. That means a single well-timed payment can reshape your score before the next billing cycle even begins. No other scoring factor responds this quickly.In this guide, we’ll walk through exactly what credit utilization is, how it’s calculated, why it accounts for roughly 30% of your FICO score, and the practical, legally sound tactics you can use to lower it — and keep it low. We’ll also clear up some of the most damaging myths, including the “30% rule” that’s been repeated so often people mistake it for a target rather than a ceiling.This is the same framework we use with clients at our San Diego-based credit repair firm when we build customized repair plans. We don’t believe in quick fixes or guarantees. We believe in understanding the mechanics of your credit, making informed changes, and measuring the results. By the end of this article, you’ll have that same understanding — and a clear set of next steps.

    What Is Credit Utilization?

    Your credit utilization ratio (sometimes called your utilization rate) is the percentage of your available revolving credit that you’re currently using. “Revolving credit” means credit cards and lines of credit — accounts where the balance goes up and down as you borrow and repay. Installment loans like mortgages, auto loans, and student loans are not part of utilization. Those are scored separately, based on how much you still owe relative to the original loan amount.

    Here’s the key idea in plain terms: if you have a credit card with a $10,000 limit and you owe $2,000 on it, you’re using 20% of your available credit. That 20% is your utilization on that card. If you have three cards, each with its own limit and balance, you also have an overall utilization that combines all of them.

    Why does this matter so much? Because credit scoring models treat utilization as a proxy for risk. Someone using 5% of their available credit looks like a person who borrows modestly and pays it back comfortably. Someone using 85% looks like a person who may be stretching to make ends meet — even if they’ve never missed a payment. The scoring models don’t know your income or your savings. They only see the balances and limits that lenders report. Utilization is one of the clearest signals they have.

    This is also why utilization is the factor you can move fastest. Payment history is built over time. The age of your accounts only grows older. But utilization changes every month, based on what you charge and what you pay. If you understand the timing, you can influence what the bureaus see — and what the scoring models calculate — without waiting years.

    One important distinction: utilization is calculated from the balance your lender reports to the bureaus, not the balance you carry day to day. This is a subtle but critical point, and we’ll dig into it deeply in the section on the . For now, know this: you can pay your card in full every month, never pay a cent of interest, and still have a high utilization ratio if the wrong balance gets reported.

    The Credit Utilization Formula

    The formula itself is simple:

    That’s it. Divide what you owe by what you’re allowed to owe, then multiply by 100 to get a percentage.

    Per-card utilization uses the balance and limit of a single card:

    Overall utilization sums every card together:

    Both numbers matter. FICO and VantageScore scoring models look at utilization at both the individual-account level and the aggregate level. That means you can have a great overall utilization and still lose points if one card is maxed out. We’ll cover that in detail in the section.

    A few things to keep in mind about the inputs:

    • Balances are the amounts reported by your lender — typically your statement balance, which is the balance on your closing date. Some lenders report at other times, but statement closing is the most common.
    • Credit limits are your stated revolving limits. For charge cards that have no preset spending limit (certain American Express cards, for example), the scoring models use a different figure — often the highest balance you’ve ever carried or an internal limit the lender reports. This is handled automatically by the bureaus.
    • Closed accounts with balances can still factor in. If you closed a card but still owe a balance, that balance may still be reported and can affect your utilization depending on how the lender reports it. Be cautious about closing cards with outstanding balances.

    The simplicity of the formula is part of why utilization is so powerful: it’s transparent, it’s math you can do yourself, and it’s something you can influence directly. You don’t need to dispute anything, wait for a bureau investigation, or negotiate with a creditor to change it. You just need to change the numerator (your balances) or the denominator (your limits).

    Why Utilization Is 30% of Your Score

    Under the FICO 8 scoring model — still the most widely used model in lending decisions — your credit score is built from five categories:

    Scoring Factor Weight How Fast It Moves
    Payment history 35% Slow — months to years
    Amounts owed (utilization) 30% Fast — weeks to one billing cycle
    Length of credit history 15% Very slow — grows with time
    Credit mix 10% Slow — requires new accounts
    New credit / inquiries 10% Moderate — inquiries fade in 12 months

    Utilization is the second-largest factor, and it’s the only one of the top three that you can influence in a matter of weeks. That’s why we call it the fastest lever.

    Here’s why scoring models weight it so heavily. Decades of lender data show that as utilization rises, the likelihood of default rises too — and it rises non-linearly. Someone at 10% utilization is not just slightly less risky than someone at 30%; the risk gap is meaningful. Someone at 60% is meaningfully riskier than someone at 40%. The models bake this curve in, which is why even small drops in utilization can produce visible score gains when you’re starting from a high percentage.

    The “amounts owed” category (the official FICO label for the 30% bucket) includes more than just utilization. It also considers:

    • How many of your accounts carry balances at all
    • How much you owe on installment loans relative to the original amounts
    • The presence of any accounts in collection

    But utilization — both per-card and overall — is the dominant force inside that 30% bucket. For most people working to improve their credit, utilization is where the biggest, fastest gains live.

    A note on scoring model variations: FICO 9, VantageScore 3.0, and VantageScore 4.0 all treat utilization as a major factor, though the exact weightings differ. FICO 10T, the newer trended-data model, looks at your utilization over time rather than just a snapshot — we cover that in its own . The tactics in this article help across all of these models.

    The 30% Rule vs. the Truth

    If you’ve read anything about credit scores, you’ve heard the 30% rule: keep balances under 30 percent of your credit limits. It’s repeated in nearly every article, video, and forum thread about credit. Here’s the problem: 30% is not a target. It’s a ceiling — and a fairly loose one. The truth is more nuanced, and understanding the nuance is where real score gains come from.

    Where the 30% number comes from

    FICO has historically described utilization in broad tiers. The exact breakpoints aren’t published, but analysis of millions of scores — and FICO’s own public statements — have established a widely accepted tier structure:

    Utilization Range Score Impact
    0% Slight penalty — no active revolving use
    1% – 9% Best for scores — shows active, responsible use
    10% – 29% Very good — small, gradual point loss as you climb
    30% – 49% Fair — noticeable penalty begins around 30%
    50% – 74% Poor — meaningful penalty
    75% – 100% Very poor — near-maxed or maxed, large penalty

    The 30% threshold is where the penalty starts to become meaningful — not where scoring is optimal. Think of it as the speed limit on a highway: staying just under it won’t get you a ticket, but it also won’t get you the best fuel efficiency. The “best” zone for your score is well below 30%.

    Why under 10% is better

    People who keep their reported utilization under 10% — and ideally between 1% and 9% — consistently see the highest scores in the “amounts owed” category. At that level, you’re demonstrating that you use your credit cards but pay them down aggressively. That’s exactly the behavior scoring models reward.

    The difference between 28% and 8% utilization can be 20 to 40 points for some people, depending on the rest of their profile. That’s the difference between “approved at a decent rate” and “approved at a great rate” on a mortgage, or between “approved” and “denied” on a premium rewards card.

    Why 0% isn’t ideal — the “some activity” nuance

    This surprises a lot of people: a reported utilization of 0% is not optimal. If all your cards report a $0 balance every month, the scoring model sees no evidence that you’re actually using your revolving credit. From the model’s perspective, a dormant card tells it nothing about your ability to manage debt — so you may lose a few points compared to someone showing a small, paid-down balance.

    Here’s what’s really happening. Scoring models want to see some activity. They reward the pattern of: charge a small amount, let it report, pay it off. That cycle — use, report, repay — is the evidence the model uses to predict your future behavior. If you never let a balance report, there’s no evidence to score.

    This does not mean you should carry debt or pay interest. It means you should let a small balance appear on your statement (which happens naturally if you use the card for everyday purchases), and then pay it in full by the due date. The statement balance reports to the bureaus, the scoring model sees your responsible use, and you never owe a cent of interest because you pay in full during the grace period. This is the optimal pattern.

    The practical takeaway: aim for a reported utilization between 1% and 9% on each card and overall. That single digit above zero is your “some activity” signal. Anything from 10% to 29% is still good. Crossing 30% is where you want to pull back. And 0% across the board is a missed opportunity, not a victory.

    Per-Card vs. Overall Utilization

    This is one of the most under-explained topics in credit, and getting it wrong costs people points every month.

    Scoring models evaluate your utilization at two levels:

    • Overall (aggregate) utilization — your total balances across all revolving accounts, divided by your total credit limits across all revolving accounts.
    • Per-card (individual) utilization — the balance on each specific card, divided by that card’s specific limit.

    Both matter. A scoring model doesn’t just care that your overall utilization is healthy; it also looks at whether any single card is disproportionately loaded. This is because maxing out one card — even if your overall utilization is low — is a risk signal. It suggests you may be concentrated on one account, which can indicate cash flow stress on that particular line.

    A worked example

    Suppose you have three cards:

    Card Limit Balance Per-Card Utilization
    Card A $5,000 $1,500 30%
    Card B $5,000 $0 0%
    Card C $5,000 $0 0%

    Your overall utilization is $1,500 ÷ $15,000 = 10%. That’s in the good range. But Card A is at 30% — right at the ceiling. The scoring model sees both numbers and may dock you slightly for the per-card figure even though your overall is healthy.

    Now compare to this arrangement:

    Card Limit Balance Per-Card Utilization
    Card A $5,000 $500 10%
    Card B $5,000 $500 10%
    Card C $5,000 $500 10%

    Same total balance ($1,500), same overall utilization (10%). But now every card is at 10%, well under the 30% ceiling. This arrangement typically scores slightly better than the first, because no single card is loaded.

    Why this matters for your strategy

    The per-card vs. overall distinction changes how you should think about paying down debt. If you have extra cash to put toward your cards, don’t just throw it at the highest-interest card (though that’s still good advice for saving money). For score purposes, it often helps to pay down whichever card has the highest per-card utilization first, especially if that card is over 30%. Bringing one maxed-out card down to 30% can move your score more than bringing a moderately-used card down to 0%.

    This is also why the tactic of spreading balances across cards (covered below) can help — it smooths out per-card utilization even when the total balance stays the same. We’ll walk through that in the tactics section.

    How to Calculate Your Utilization (With Examples)

    Let’s run through a few scenarios so you can see exactly how the math works and apply it to your own situation.

    Example 1: Single card, simple case

    You have one credit card with a $8,000 limit. Your statement closes with a balance of $1,600.

    That’s in the good range — under 30%, though not quite in the optimal under-10% zone. To get into the optimal zone, you’d want your statement to close with a balance under $800.

    Example 2: Multiple cards, mixed utilization

    You have three cards:

    • Card A: $10,000 limit, $3,000 balance
    • Card B: $6,000 limit, $1,200 balance
    • Card C: $4,000 limit, $0 balance

    Per-card utilization:

    • Card A: $3,000 ÷ $10,000 = 30% (right at the ceiling)
    • Card B: $1,200 ÷ $6,000 = 20% (good)
    • Card C: $0 ÷ $4,000 = 0% (no activity — see the nuance above)

    Overall utilization:

    Overall, you’re at 21% — good. But Card A is at 30%, which the model will flag. If you had an extra $1,000 to put toward these balances, paying down Card A (bringing it to $2,000 and 20%) would help your score more than paying down Card B, because it removes the per-card ceiling violation.

    Example 3: The maxed-out card

    You have two cards:

    • Card A: $5,000 limit, $4,500 balance (90% — maxed out)
    • Card B: $15,000 limit, $0 balance

    Per-card:

    • Card A: 90% (very poor)
    • Card B: 0%

    Overall:

    Your overall utilization is 22.5%, which looks fine in isolation. But the scoring model will penalize you heavily for Card A being at 90%. This is a classic case where overall utilization hides a serious problem. If you’re applying for a loan and the lender manually reviews your report, a maxed-out card jumps out immediately.

    Example 4: The optimal setup

    Three cards, all lightly used:

    • Card A: $7,000 limit, $200 balance (2.9%)
    • Card B: $5,000 limit, $150 balance (3%)
    • Card C: $8,000 limit, $0 balance (0%)

    Overall:

    Overall at 1.75%, two cards showing small activity, one card dormant. This is close to the ideal pattern for most scoring models. You’re demonstrating active, responsible use without loading any single card.

    How to calculate your own

    • List every revolving account (credit cards, store cards, lines of credit). Skip installment loans.
    • For each card, note the current balance and the credit limit. You can find these on your most recent statement or by logging into your online account. For the most accurate picture, pull your credit report from AnnualCreditReport.com — the balances and limits there are what the bureaus currently have on file.
    • Calculate per-card utilization for each: balance ÷ limit × 100.
    • Add up all balances and all limits, then divide total balances by total limits × 100 for your overall utilization.
    • Check both numbers against the tier table in the . If either your overall or any single card is over 30%, that’s your first priority.

    One caution: the balances on your credit report may be slightly stale. Lenders report once a month, so the report shows the balance from your last statement date, not what you owe today. If you’ve made a large payment since then, your actual utilization is already lower than what the report shows — which is good news, but it means the score a lender pulls might still reflect the older, higher balance until the next reporting cycle.

    Tactics to Lower Your Utilization Fast

    These tactics are listed roughly in order of speed and impact. Most can be executed within a single billing cycle.

    1. Pay down balances before the statement closes

    This is the single most effective tactic, and it works immediately. Recall that the balance that matters for utilization is the one your lender reports — and most lenders report the balance as of your statement closing date. If you pay down your balance before the statement closes, the lender reports a lower number, and your utilization drops on the next bureau update.

    Here’s the timing to understand:

    • Statement closing date — the day your billing cycle ends and your statement is generated. The balance on this date is what gets reported.
    • Due date — about 21 to 25 days after the closing date. This is when your payment is due to avoid interest.

    Most people wait until the due date to pay. That’s fine for avoiding interest, but it does nothing for utilization because the balance was already reported weeks earlier at the statement closing date. To optimize utilization, you want to make a payment between the last day of your billing cycle and the statement closing date — or even just a few days before the statement closes.

    You don’t have to pay the whole balance. Even paying down to under 10% of the limit before the statement closes will land you in the optimal zone. Then pay off the remainder by the due date to avoid interest.

    2. Ask for a credit limit increase

    Remember the formula: utilization is balances ÷ limits. You can lower the ratio by shrinking the numerator (paying down) or by growing the denominator (raising your limits). A higher credit limit, with the same balance, instantly lowers your utilization.

    Most card issuers let you request a limit increase online — usually under an account settings or “card management” menu. Some increases can be granted instantly with a soft credit pull (which doesn’t affect your score). Others may require a hard inquiry, which causes a small, temporary score dip. Ask the issuer whether the request will be a soft or hard pull before you proceed.

    Important: A limit increase only helps if you don’t increase your spending. If you get a $5,000 limit bumped to $10,000 and then run the balance up to $5,000, your utilization is exactly where it was before — 50%. The tactic works only when the new limit gives you more headroom that you leave unused.

    A practical approach: request limit increases on your oldest, best-behaved cards every 6 to 12 months. Issuers are often willing to grant modest increases to customers with a track record of on-time payments and low balances relative to the current limit.

    3. Make mid-cycle payments

    If you use your card heavily during the month — for business expenses, reimbursable work charges, or just everyday spending — your balance may spike well above 30% mid-cycle, even if you pay it in full every month. If that spike happens to land on the statement closing date, you get dinged for utilization even though you’re a perfect payer.

    The fix: make a payment mid-cycle, before the statement closes. This brings the reported balance down. You can continue using the card for the rest of the cycle; just make another payment before the due date to clear the remainder.

    Some people who charge a lot each month make weekly payments to keep the balance low at all times. This is a perfectly legitimate strategy and is especially useful for people who put business expenses or large recurring bills on personal cards.

    4. Spread balances across multiple cards

    If you need to carry a balance (say, for a large purchase you’re paying off over a few months), spreading it across multiple cards can improve your per-card utilization even though your overall utilization stays the same.

    Compare:

    • Concentrated: One card at $4,500 / $5,000 (90%), another at $0. Overall: $4,500 / $20,000 = 22.5%. One card maxed.
    • Spread: Two cards at $2,250 / $5,000 each (45% each), one at $0. Overall: $4,500 / $20,000 = 22.5%. No card maxed, but both at 45%.

    The spread version still has both cards over 30%, so it’s not ideal — but it’s better than one card being at 90%. In a more moderate scenario, spreading a $3,000 balance across three $10,000-limit cards (10% each) versus concentrating it on one (30%) can produce a small but real score difference.

    This tactic has a caveat: it only helps if the cards you’re spreading to have similar interest rates. Moving a balance from a 0% promotional APR card to a 24% APR card to improve your utilization is a bad trade. If you’re carrying a balance, prioritize interest cost first, utilization second.

    5. Keep cards open — even paid-off ones

    When you pay off a card, the temptation is to close it. Resist that temptation if you care about your score. Here’s why: closing a card removes its credit limit from the denominator of your utilization calculation. If that card had a $10,000 limit and you close it, your total available credit drops by $10,000 — and your overall utilization jumps up accordingly, even though you didn’t spend a dime.

    Example: You have $20,000 in total limits and $4,000 in balances. Overall utilization: 20%. You pay off and close a card with a $10,000 limit. Now your total limits are $10,000, your balances are still $4,000, and your overall utilization is 40% — you just crossed the 30% ceiling by closing a card you didn’t owe anything on.

    Closed accounts in good standing can stay on your credit report for up to 10 years, which helps your average account age. But the credit limit comes off your utilization calculation immediately upon closure. This is one of the most common ways people accidentally hurt their scores.

    If a card has an annual fee you don’t want to pay, ask the issuer about a product change to a no-fee card instead of closing the account. That preserves the credit limit and the account history.

    6. Use a balance transfer strategically

    If you’re carrying high-interest debt, a balance transfer to a card with a 0% promotional APR can help in two ways: it reduces the interest cost (freeing up cash to pay down principal faster), and if the new card has a higher limit, it can improve your overall utilization. However, be aware that opening a new card generates a hard inquiry and lowers your average account age — both small, temporary score impacts. The utilization benefit usually outweighs these, but the math depends on your specific situation. Also watch out for balance transfer fees (typically 3% to 5%) and make sure you can pay off the balance before the promotional period ends.

    7. Become an authorized user on a responsible account

    If a family member or close friend has a long-standing credit card with a high limit and a low balance, being added as an authorized user can help your utilization. The card’s limit and history typically appear on your credit report as well, increasing your total available credit and potentially improving your average account age. Choose carefully: if the primary cardholder runs the balance up or misses payments, those negatives appear on your report too. This strategy works best when the primary holder is financially disciplined and you trust them completely.

    8. Open a new card — with caution

    A new credit card adds to your total available credit, which lowers your overall utilization (assuming you don’t carry a balance on the new card). But a new card also generates a hard inquiry, lowers your average account age, and adds a new account to your profile — all of which have small, temporary negative effects. For most people, the utilization benefit outweighs the drawbacks only if the new card meaningfully increases total available credit and you keep the balance at zero. If you’re already carrying high utilization on existing cards, adding a new card and running up its balance will only make things worse.


    The Statement-Balance Trap

    This is the single most common mistake we see, and it silently costs people 20 to 60 points every month without them realizing it.

    Here’s the scenario: You use your credit card for everything — groceries, gas, subscriptions, the works. You pay the statement balance in full every month by the due date. You’ve never paid a cent of interest. By every reasonable definition, you’re a perfect credit card customer. And yet, your credit score is stuck, and your reported utilization is high.

    What’s happening?

    The balance that gets reported to the credit bureaus is (for most issuers) your statement balance — the balance on the day your statement closes. That’s typically the peak of your monthly spending, because it’s the sum of everything you charged during the billing cycle. If you charged $3,000 during the cycle and your limit is $5,000, the statement balance is $3,000 — a 60% utilization — and that is what gets reported, even though you pay it off completely three weeks later.

    The scoring model never sees your payment. It only sees the reported balance. So from the model’s perspective, you’re at 60% utilization every month, even though you carry no debt.

    This is maddening for people who are doing everything “right.” But once you understand the timing, the fix is straightforward: pay down most of your balance a few days before the statement closes.

    The fix, step by step

    • Find your statement closing date. It’s on every statement. It’s usually the same date each month (for example, the 15th).
    • A few days before that date — say, the 12th or 13th — log in and pay your balance down to under 10% of your credit limit. If your limit is $5,000, pay it down to under $500.
    • Let the statement close with that small balance. The lender reports it to the bureaus. Your utilization looks excellent.
    • Pay the remaining small balance by the due date (about three weeks later) to avoid interest.

    You’re still paying in full every month. You’re still never paying interest. But now the bureau sees a low balance instead of a high one, and your score reflects that.

    This is the single highest-impact habit you can build for utilization. For people with high monthly card spend, it can be worth 30 to 60 points.

    How to confirm what’s being reported

    If you want to verify that this is working, pull your credit report from AnnualCreditReport.com (free, weekly during many periods, otherwise once per bureau per year) and check the balance listed for each card. Compare it to your statement balance — it should match. If it doesn’t, your lender may report on a different date than your statement closing date. In that case, call the issuer and ask when they report to the bureaus, and time your payment accordingly.
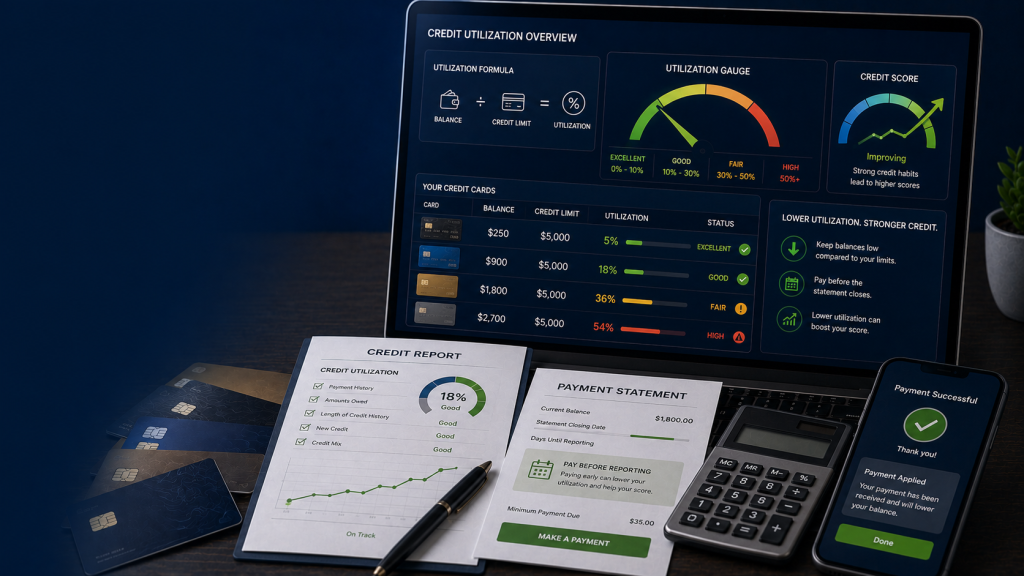
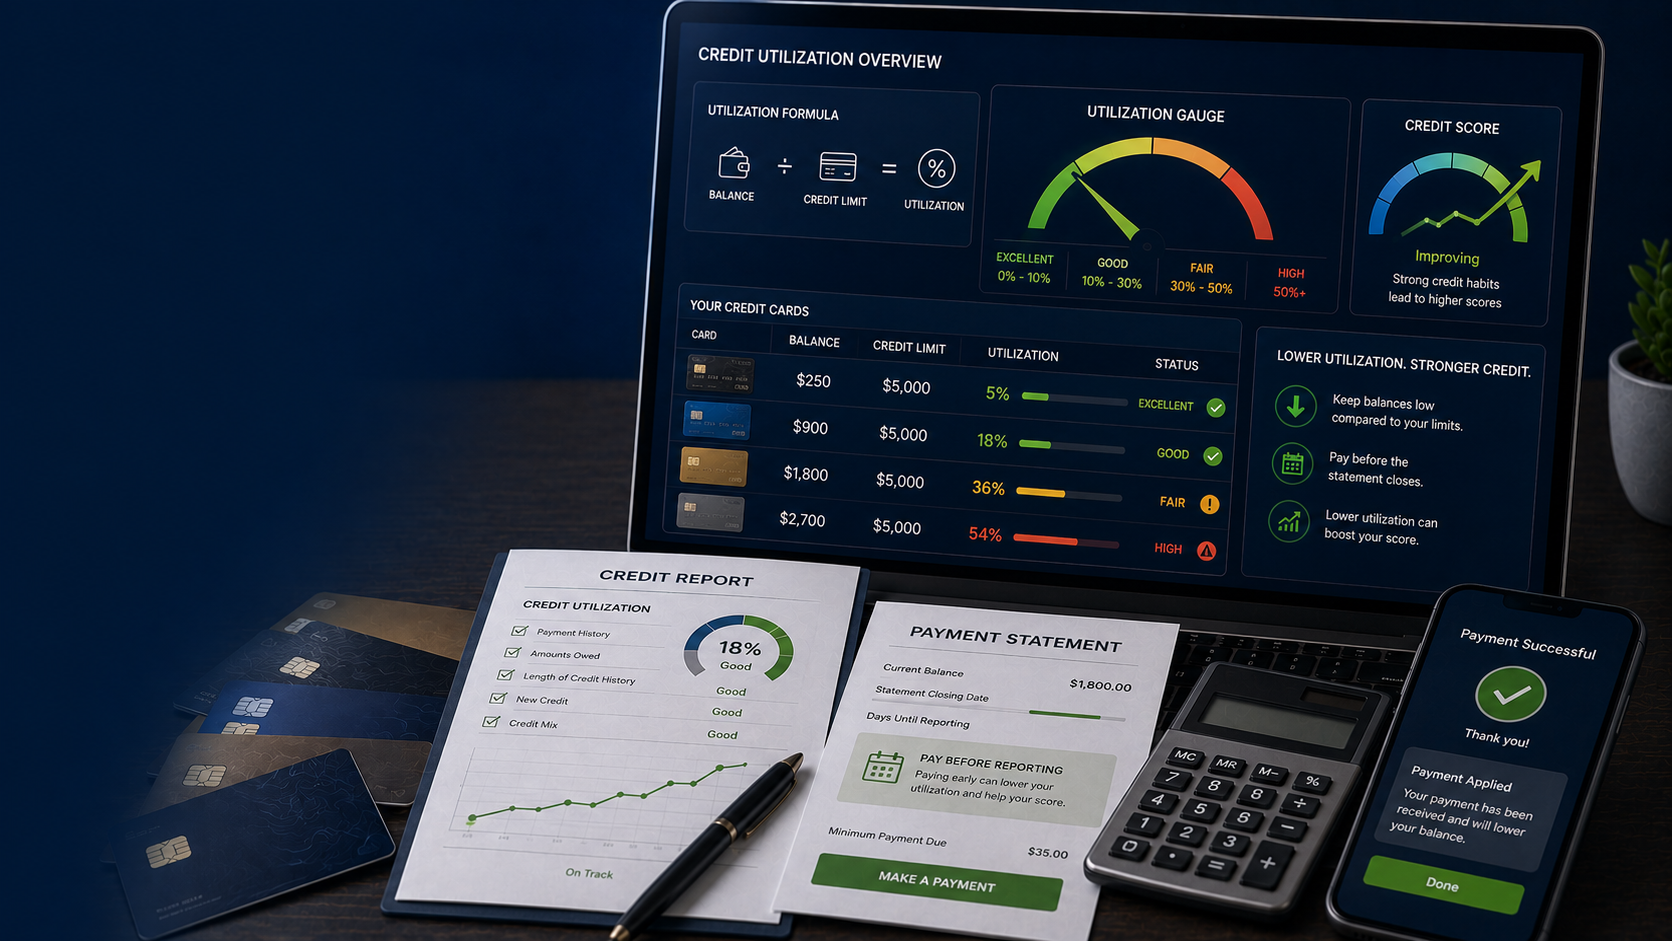
    Credit utilization ratio explained with credit card balances and limits

    FICO 8 vs. FICO 10T: Does Utilization Have a Memory?

    This is where the conversation gets interesting, because the newest scoring model changes a fundamental assumption that has guided credit advice for over a decade.

    FICO 8: Utilization has no memory

    Under FICO 8 — still the dominant model in mortgage lending and most consumer credit decisions — your utilization is scored as a snapshot. The model looks at the most recent balances and limits reported by your lenders and calculates your utilization from that single point in time. It doesn’t care what your utilization was last month, last year, or five years ago.

    This is why utilization is the “fast lever.” If you were at 60% last month and you pay down to 5% this month, the model scores you based on the 5% — and your score can jump in a single cycle. Your past high utilization is gone, as far as the model is concerned.

    This also means utilization “resets” every month. If you normally keep your utilization low but have one month where it spikes (say, a large purchase right before your statement closes), you may see a temporary score dip — but it will recover the following month when the next reported balance replaces the old one. There’s no lasting penalty.

    FICO 10T: Trended data

    FICO 10T, introduced in 2020 and being adopted gradually by lenders, uses trended data. Instead of a single snapshot, the model looks at your balances and utilization over the past 24 months or so. It can see whether your utilization has been trending up, trending down, or holding steady — and it factors that trend into your score.

    Under 10T, a sudden spike in utilization still matters, but it’s placed in context. If you’ve been steadily paying down for two years and have one high month, the model sees the broader trend and may not penalize you as heavily. Conversely, if you’ve been steadily climbing for two years — even if you’re still under 30% — the model may flag the upward trend as a risk signal.

    This changes the strategic emphasis. Under FICO 8, you can “game” utilization with a well-timed payment before a statement closes. Under 10T, that tactic still helps (because the most recent data point still matters), but the long-term trend matters too — so consistent, gradual paydown matters more than a one-month optimization.

    What this means for you

    • For now, most lending decisions still use FICO 8. Mortgages in particular are still underwritten against older FICO models (FICO 2, 5, and 4, which are similar to FICO 8 in their utilization treatment). The tactics in this article remain highly effective.
    • Over time, 10T adoption will grow. Building good utilization habits now — not just optimizing for a single month — positions you well for both models.
    • The best strategy works under both models: keep utilization consistently low (under 10% overall and per-card), make payments before statement closes when you have a high-spend month, and pay down debt over time rather than carrying it. That pattern looks great in a snapshot model and in a trended model alike.

    We monitor scoring model adoption for our clients and adjust repair plans as the landscape shifts. If you’re working with us, we’ll flag when a lender you’re targeting has moved to 10T and adjust your strategy accordingly.

    Utilization Across Multiple Cards

    When you have several credit cards, managing utilization gets more complex — but also gives you more tools. Here’s how to think about a multi-card portfolio.

    The aggregate is the headline, the per-card is the detail

    Your overall utilization is the number most people focus on, and it’s the one that moves the most points. But as we covered, scoring models also look at each card individually. A good rule of thumb: keep every card under 30%, and keep your overall under 10%. That combination consistently produces the best scores.

    If one card is over 30%, prioritize it

    When you have limited cash to put toward paydown, the order in which you pay cards matters for your score. Pay down the card that’s highest above 30% first. If two cards are both over 30%, prioritize the one with the higher per-card percentage. The scoring penalty for a 70% card is steeper than the penalty for a 40% card, so bringing the 70% card down first gives you more score movement per dollar.

    Once every card is under 30%, you can shift to paying down whichever card has the highest interest rate — that’s the financially optimal move once the score urgency is handled.

    Don’t close old cards to “simplify”

    We covered this in the tactics section, but it bears repeating in the multi-card context: closing an old, paid-off card removes its limit from your total available credit, which raises your overall utilization. If you’re carrying balances on other cards, this can push you over a scoring threshold even though you didn’t spend anything.

    If you have cards you don’t use, consider keeping them open with a small recurring charge (a subscription, a phone bill) that you pay off automatically each month. This keeps the card active, prevents the issuer from closing it for inactivity (which also removes the limit), and contributes a small, positive activity signal to your score.

    Store cards count too

    Store cards (Macy’s, Target, Home Depot, etc.) are revolving accounts and factor into utilization just like general-purpose credit cards. They often have lower limits than major cards, which means a modest balance can produce a high per-card utilization. A $300 balance on a $500 store card is 60% utilization on that card — a problem. Treat store cards with the same utilization discipline as any other card, or don’t carry balances on them at all.

    Common Mistakes That Quietly Tank Your Score

    Most utilization damage is self-inflicted, and most of it is avoidable. Here are the mistakes we see most often.

    1. Waiting until the due date to pay

    As we covered in the , paying on the due date is fine for avoiding interest but does nothing for utilization because the balance was already reported at the statement closing date. If you only change one habit, change this one: pay down before the statement closes, not just before the due date.

    2. Closing paid-off cards

    Removing a card’s limit from your total available credit raises your overall utilization. Keep old cards open, ideally with a small recurring charge to prevent inactivity closure.

    3. Maxing out one card to keep another at zero

    Some people concentrate spending on a single “rewards” card to maximize points, leaving other cards at zero. If that one card’s balance climbs above 30%, the per-card penalty can outweigh any rewards benefit. Spread spending or pay down mid-cycle.

    4. Ignoring store cards and smaller-limit accounts

    A $200 balance on a $500 store card is 40% utilization — a penalty. People often forget about store cards because the balances are small, but the limits are small too, so the percentage can be high. Track every revolving account, not just your main credit cards.

    5. Requesting limit increases with hard pulls unnecessarily

    A hard inquiry for a limit increase you might not get (and don’t urgently need) isn’t worth the small score dip. Ask issuers whether they can grant the increase with a soft pull first. Many can.

    6. Treating a limit increase as permission to spend more

    A higher limit helps your utilization only if your balance stays the same. If your spending rises with your limit, your utilization doesn’t improve — and you’ve taken on more debt. Treat a limit increase as headroom, not as spending power.

    7. Opening new cards to “dilute” utilization without a plan

    A new card raises your total available credit, which can lower overall utilization. But it also adds a hard inquiry, lowers your average account age, and creates the temptation to carry a balance. If you open a new card for utilization reasons, keep the balance at zero and don’t use it for anything you can’t pay off immediately.

    8. Assuming 0% utilization is perfect

    As we covered, 0% across the board misses the “some activity” signal the scoring models reward. Let a small balance report on at least one card, then pay it in full.

    9. Not checking what’s actually on your report

    The balances on your credit report may not match what you think you owe, especially if a lender reports on an unusual date or if a recent payment hasn’t cycled through yet. Pull your report periodically and verify that the balances and limits are accurate. If a limit is reported incorrectly (lower than it actually is), your utilization calculation is wrong — and you can dispute that.

    10. Carrying a balance to “build credit”

    This is a persistent myth. Carrying a balance and paying interest does not build your credit faster than paying in full every month. The scoring model doesn’t know or care whether you pay interest — it only sees the reported balance and your payment history. Paying in full every month builds credit just as effectively and costs you nothing.

    Summary Table: What to Do and What to Avoid

    Do Avoid
    Pay down balances before the statement closes Waiting until the due date to pay
    Aim for 1% – 9% reported utilization on each card and overall Treating 30% as a target instead of a ceiling
    Let a small balance report, then pay in full Carrying 0% across every card, every month
    Keep old, paid-off cards open Closing cards you don’t use (removes the limit)
    Request limit increases with soft pulls when possible Triggering hard pulls for increases you don’t urgently need
    Make mid-cycle payments during high-spend months Letting a big charge land on your statement date
    Spread balances across cards if you must carry debt Maxing out one card while others sit at zero
    Track store cards and small-limit accounts Forgetting that a $200 balance on a $500 card is 40%
    Pull your report and verify reported balances and limits Assuming the bureaus have your current balance right
    Pay in full every month to build credit at no cost Carrying a balance and paying interest to “build credit”

    Frequently Asked Questions

    1. What is a good credit utilization ratio?

    The best reported utilization is between 1% and 9% on each card and overall. This shows the scoring models that you actively use your revolving credit but pay it down aggressively. Anything under 30% is generally acceptable, and under 10% is optimal. A reported 0% is not ideal because it provides no evidence of active, responsible use.

    2. How fast can lowering my utilization raise my score?

    Under FICO 8, utilization has no memory — it’s scored from the most recent reported balances. That means if you pay down a high balance and the new lower balance is reported at your next statement closing date, your score can improve within that same cycle, typically within 30 to 45 days. The size of the improvement depends on how high your utilization was, how far you brought it down, and the rest of your credit profile. People moving from 70%+ to under 10% can see gains of 30 to 60 points or more.

    3. Should I close a credit card I don’t use anymore?

    Generally, no — not if you care about your score. Closing a card removes its credit limit from your total available credit, which can raise your overall utilization even though you didn’t spend anything. If the card has an annual fee, ask the issuer about switching to a no-fee version (a “product change”) so you keep the limit and the account history without the cost. If you must close it, try to do so when your overall utilization is already very low so the impact is minimal.

    4. Does asking for a credit limit increase hurt my score?

    It depends on whether the issuer does a soft or hard pull. A soft pull does not affect your score. A hard pull causes a small, temporary dip (usually a few points) that fades over 12 months. Ask the issuer before you request the increase whether it will be a soft or hard inquiry. Many issuers can grant increases with a soft pull, especially for existing customers in good standing.

    5. Is it better to pay my credit card before or after the statement closes?

    For utilization purposes, pay before the statement closes. The balance on your statement closing date is what most lenders report to the bureaus, so paying before that date lowers the reported balance. For interest purposes, pay by the due date (about three weeks after the statement closes). The optimal pattern is: pay down most of the balance before the statement closes, let a small balance report, then pay the remainder by the due date.

    6. Does utilization affect all credit scores the same way?

    No. Different models weight utilization differently, but all major models (FICO 8, FICO 9, FICO 10T, VantageScore 3.0 and 4.0) treat it as a significant factor. FICO 8 and most mortgage models score it as a monthly snapshot. FICO 10T uses trended data and looks at your utilization over the past 24 months, so long-term habits matter more under 10T. The safest approach is to keep utilization consistently low — which performs well under every model.

    7. Can I have a 0% utilization and still have a good score?

    Yes, but it may be a few points lower than it could be. A 0% reported utilization across all cards means no revolving activity is being scored, which can cost you a small number of points compared to showing a 1% – 9% balance. The fix is simple: use at least one card for a small purchase each month, let the statement close with that small balance, and pay it in full by the due date.

    8. What if my credit limit is reported wrong on my credit report?

    This is a disputeable error. If a lender is reporting a lower limit than you actually have, your utilization is being calculated higher than it should be — and your score is being unfairly penalized. Pull your report, identify the incorrect limit, and file a dispute with the bureau (online or by mail) asking them to correct it. You can also contact the lender directly and ask them to update their reporting. Under the Fair Credit Reporting Act (FCRA), bureaus are required to investigate disputes, typically within 30 days, and to correct or remove information that can’t be verified. This is one of the most common and impactful errors we help clients correct.

    Next Steps: Get a Free Credit Audit

    Understanding credit utilization is the first step. Acting on it is where your score starts to move.

    If you’ve read this far, you already know more about utilization than most people ever will. You know that 30% is a ceiling, not a target. You know to pay before the statement closes, not just before the due date. You know that per-card utilization matters alongside overall utilization, and that closing a paid-off card can backfire.

    The next step is to look at your actual credit report — your real balances, your real limits, your real per-card and overall utilization — and build a specific plan to optimize them. That’s where we come in.

    At our San Diego-based credit repair firm, we offer a free credit audit that covers all three major bureaus. We’ll pull your reports, identify any errors or inaccuracies that may be dragging your score down, calculate your current utilization, and give you a clear, honest assessment of where you stand and what’s realistically achievable. We work alongside experienced attorneys and operate in full compliance with the Fair Credit Reporting Act, so every step is ethical, accurate, and legally sound.

    We don’t promise overnight fixes, because credit doesn’t work that way. What we do promise is transparency: we’ll tell you exactly what we find, exactly what we recommend, and exactly what it costs — with no hidden fees and no services you don’t need.

    Get your free credit audit at credit-repair.com →

    Whether you work with us or take the DIY path using the tactics in this article, the most important thing is to start. Utilization is the fastest lever on your score, and the strategies in this guide can start moving the needle within a single billing cycle. The sooner you begin, the sooner your score reflects the responsible borrower you already are.

    This article is for educational purposes and is not legal or financial advice. Your individual credit situation is unique. For a personalized review, request a free credit audit at .

    Related reading:

    • How to Dispute Credit Report Errors Under the FCRA
    • Understanding Your FICO Score: The 5 Factors That Matter
    • How Long Does Credit Repair Take? A Realistic Timeline
    • The Ultimate Guide to Building Credit From Scratch
    • What to Do When a Credit Card Company Won’t Remove a Negative Mark

    To put this into action, explore how to ask for a credit limit increase without hurting your score, understand what a good credit score means, compare FICO vs VantageScore to know which model matters most, and follow our full guide on how to improve your credit score.
  • Credit-Builder Loans Explained: Do They Actually Work?

    Credit-Builder Loans Explained: Do They Actually Work?

    Related reading: learn the fastest way to build credit from scratch if you’re starting over, see how the Chime Credit Builder card compares as an alternative, understand what a good credit score means so you have a clear target, and see our credit repair process if you need professional help along the way.

    If you’ve ever tried to build credit from scratch — or rebuild it after a few hard years — you’ve probably run into the same frustrating loop that catches nearly everyone at some point. You need a loan or a credit card to build credit. But lenders want to see a credit history before they’ll approve you for one. So you’re stuck: no credit means no approvals, and no approvals means no way to build credit.It’s a perfectly designed catch-22, and it affects far more people than you might think. Recent immigrants who haven’t established a U.S. credit file yet. Young adults just starting out. People who spent years avoiding credit after a financial setback. Divorcees whose credit history was tied to a former spouse. People who simply never needed to borrow — until now.The credit builder loan was created specifically to break that loop. It’s a small, structured loan designed to do one thing very well: help you establish a positive payment history on your credit report without requiring you to already have good credit to qualify. No credit check for approval in most cases, no large deposit to lock up, and no complex application process.But here’s the honest question everyone eventually asks: does a credit builder loan actually work? And if it does, how well — and for whom?

    The short answer is yes, it can work, and the research backs that up. But the longer, more useful answer is that it works in a specific way, for specific reasons, and it has real limitations that the marketing copy from some providers tends to gloss over. Understanding those limitations before you sign up is the difference between a tool that genuinely helps you and one that leaves you frustrated a year later wondering why your score barely moved.

    This guide walks you through everything you need to know: what a credit-builder loan is, the unusual mechanic that makes it work, who it helps most, how to choose a good one, what to watch out for, and how it compares to the other credit-building options on the table. We’ll be straight with you about what it can and can’t do, because that’s what a trusted advisor should do.

    What Is a Credit-Builder Loan?

    A credit-builder loan is a small installment loan — usually between $300 and $1,000, sometimes up to $2,000 — designed specifically to help you build or rebuild your credit history. What makes it different from a traditional personal loan is that you don’t receive the money upfront.

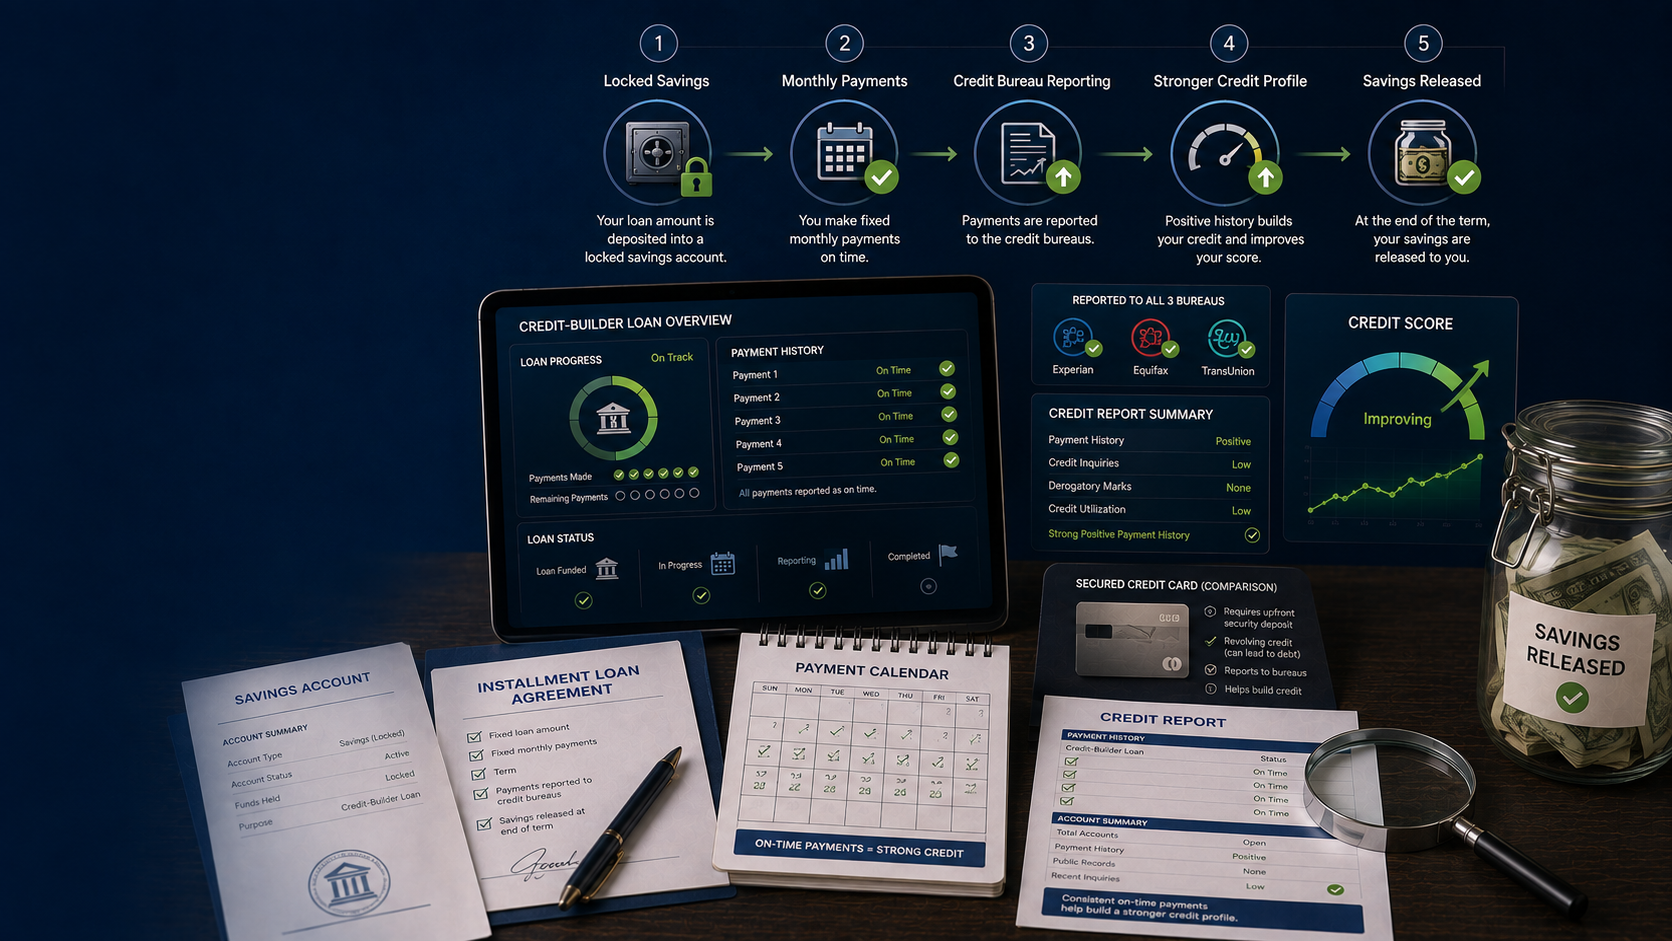
    Instead, the lender holds the loan amount in a locked savings account or certificate of deposit (CD) on your behalf. You make monthly payments — principal plus a modest interest charge or administrative fee — over a set term, typically 6 to 24 months. Each payment is reported to the credit bureaus as an on-time installment payment. Once you’ve paid the loan in full, the money in the savings account is released to you, minus any fees or interest charges.

    Think of it as a forced savings plan that also happens to build your credit. You’re not borrowing money to spend — you’re borrowing money to prove you can pay it back reliably. The “loan” is really the structure; the savings account is where your money lives until you’ve earned it back.

    This is why credit-builder loans are sometimes called “fresh start loans” or “savings-secured loans.” The structure is what matters. The lender isn’t taking a risk on whether you’ll repay, because they already hold the full amount. You’re not taking on debt in the traditional sense — you’re paying into your own savings while building a credit file.

    Where credit-builder loans come from

    Credit-builder loans are offered by a mix of institutions, and the provider you choose matters more than you might expect:

    • Community Development Financial Institutions (CDFIs) — These are Treasury Department-certified lenders (credit unions, community banks, nonprofit loan funds) whose mission includes serving low-income and underserved communities. A CDFI credit builder loan is often the most affordable option, with low or no fees and terms designed to set you up for success. Examples include Self-Help Credit Union, Latino Community Credit Union, and many local credit unions.
    • Credit unions — Many credit unions offer credit-builder loans as part of their member services, often at very low cost. You typically need to join the credit union to qualify, but membership is usually easy to obtain.
    • Fintech companies — Companies like Self (formerly Self Lender) and Credit Strong (a division of Austin Capital Bank) offer credit-builder loans that are available nationwide, often with an app-based experience. They’re convenient, but they tend to charge higher fees than community lenders.
    • Some community banks — A smaller number of community banks offer similar products, often branded as “credit building loans” or “savings-secured installment loans.”

    The key distinction isn’t the type of institution — it’s whether they report your payments to all three major credit bureaus (Equifax, Experian, and TransUnion). We’ll come back to that, because it’s the single most important factor in whether a credit-builder loan will actually help you.

    How a Credit Builder Loan Works: The Unusual Mechanic

    If you’re used to how normal loans work, the credit builder loan how it works question is worth slowing down for, because the mechanic is genuinely unusual.

    The traditional loan flow (what you’re used to)

    With a standard personal loan, the process goes:

    • You apply. The lender checks your credit, income, and debt-to-income ratio.
    • If approved, you receive the loan amount as a lump sum — deposited into your bank account or sent as a check.
    • You spend that money however you intended (debt consolidation, a car repair, whatever it was for).
    • You repay the lender over time, with interest.
    • Your on-time payments are reported to the credit bureaus and help build your credit.

    The lender is taking a real risk — they gave you money and they’re trusting you to pay it back. That’s why they check your credit first.

    The credit-builder loan flow (the flip)

    With a credit-builder loan, the flow is reversed:

    • You apply. The lender typically does not check your credit (or only does a soft check that doesn’t affect your score). They may verify your identity and your ability to make payments.
    • You do not receive the money. Instead, the loan amount is placed in a locked savings account or CD held by the lender (or a partner bank) in your name.
    • You make monthly payments — a portion goes toward the principal (your savings), and a portion covers interest or fees.
    • Each payment is reported to the credit bureaus as an on-time installment payment, building your payment history.
    • When the loan term ends and you’ve paid in full, the savings account is unlocked and the money is released to you — minus any fees or interest that was charged along the way.

    You never had access to the money during the loan. You were essentially paying yourSelf, with the lender acting as the structured middleman who reports your behavior to the credit bureaus.

    Why this structure exists

    This design solves two problems at once:

    For you: It removes the risk of spending borrowed money you can’t afford to repay. Because you never get the cash upfront, there’s no temptation to use it for something else and fall behind. You’re building the habit of making a monthly payment while simultaneously building savings.

    For the lender: It eliminates nearly all the credit risk. Since they hold the full loan amount in reserve, they don’t need to underwrite you the way they would for a traditional loan. This is why most credit-builder loans don’t require a credit check — the lender isn’t actually risking anything. They can approve you based on identity verification and a demonstrated ability to make the monthly payments, nothing more.

    This is also why credit-builder loans can exist at all for people with no credit or bad credit. The structure makes them possible. Without it, lenders would have no way to offer a credit-building product to people who can’t qualify for traditional credit.

    A concrete example

    Let’s say you take out a $1,000 credit-builder loan with a 12-month term. Here’s what the flow looks like:

    • The lender deposits $1,000 into a locked savings account in your name. You can’t touch it.
    • Your monthly payment is around $87 to $90, depending on the interest rate or fee structure. (We’ll get into the specifics of pricing in the .)
    • Each month, you pay that amount. The lender reports the on-time payment to Equifax, Experian, and TransUnion (assuming you chose a lender that reports to all three — which you should).
    • After 12 months, you’ve paid in roughly $1,050 to $1,080 total (the $1,000 principal plus $50–$80 in interest or fees).
    • The savings account unlocks. You receive approximately $1,000 — your accumulated principal payments. The lender kept the interest/fees.
    • Your credit report now shows 12 months of on-time installment payments, which is exactly what scoring models want to see.

    You essentially paid $50–$80 to build a year of credit history and walk away with $1,000 in savings. Whether that’s worth it depends on your situation — and we’ll get into that honestly below.

    How It Builds Your Credit

    To understand why a credit-builder loan works — and where it doesn’t — it helps to know what your credit score is actually made of. The FICO scoring model, which is used by the vast majority of lenders, weighs five categories:

    Factor Weight What It Measures
    Payment history 35% Whether you pay your bills on time
    Amounts owed / utilization 30% How much of your available credit you’re using
    Length of credit history 15% How long your accounts have been open
    Credit mix 10% The variety of credit types you have (revolving + installment)
    New credit / inquiries 10% How many recent applications and hard inquiries you have

    A credit-builder loan directly affects payment history, which is the single biggest factor. That’s the whole point. Each on-time monthly payment is a positive data point on your credit report, and over 12 to 24 months, those payments add up to a meaningful track record.

    Here’s how it touches each factor:

    Payment history (35%) — the main event

    This is where a credit-builder loan does its real work. Every month you pay on time, the lender reports a positive installment payment to the bureaus. After 12 months, you have 12 on-time payments on your report. After 24 months, you have 24. For someone starting with no credit history or a thin file, this is transformative — you go from having no payment data at all to having a solid, unbroken record of reliability.

    For someone rebuilding after negative marks (late payments, collections, charge-offs), the credit-builder loan adds a stream of positive payments that starts to dilute the impact of the older negatives. The negative marks don’t disappear — they stay on your report for up to seven years — but as they age and as you accumulate fresh positive history, their effect on your score weakens.

    Credit mix (10%) — a meaningful bonus

    Scoring models reward you for having a mix of credit types — specifically, a combination of revolving credit (credit cards, lines of credit) and installment credit (loans with fixed payments, like auto loans, mortgages, and personal loans). If your credit file only has credit cards, adding an installment loan can give your score a small bump by improving your credit mix.

    This is a modest effect — 10% of your score is a small slice — but for people with a thin file, every bit helps.

    Length of credit history (15%) — helps over time

    A credit-builder loan adds a new account to your report, which can temporarily shorten your average age of accounts (something we’ll discuss in the risks section). But as the loan ages over its 12- to 24-month term, it contributes to the overall length of your credit history. Once paid off, the account remains on your report for up to 10 years as a positive closed account, continuing to support your length of history.

    What it does NOT do

    Here’s the honest part that a lot of providers don’t emphasize enough:

    A credit-builder loan does not help with credit utilization (30% of your score). Utilization is a revolving-credit metric — it measures how much of your credit card limits you’re using. An installment loan doesn’t factor into utilization at all. If your credit cards are maxed out, a credit-builder loan won’t fix that problem. You’d need to pay down card balances or increase your credit limits to improve utilization.

    A credit-builder loan does not give you access to credit. During the loan term, you don’t have a usable credit line. If you need to make a purchase and finance it, the credit-builder loan doesn’t help with that — you still need a separate credit card or loan for actual borrowing needs.

    A credit-builder loan’s score gains are modest, not dramatic. We’ll cover this in detail in the next section, but it’s worth flagging now: if you see a provider promising “boost your score 100 points,” be skeptical. Real gains depend on your starting point and your overall credit profile, and for most people they’re in a more realistic range.

    Who a Credit-Builder Loan Is For

    A credit-builder loan isn’t for everyone, and pretending otherwise doesn’t serve you. Here’s an honest breakdown of who benefits most and who might want to look at other options.

    People with no credit history

    This is the sweet spot. If you’re starting from zero — no credit cards, no loans, no credit file at all — a credit-builder loan is one of the most accessible ways to start building. Most providers don’t require a credit check, so your lack of history isn’t a barrier. You’ll get an installment account on your report with 12 to 24 months of on-time payments, which gives scoring models something to work with and gives future lenders evidence that you can handle a fixed payment obligation.

    This group includes:

    • Young adults just entering financial independence who haven’t opened any credit accounts yet
    • Recent immigrants who are new to the U.S. and haven’t had time to establish a domestic credit file
    • People who’ve been unbanked or cash-only by choice or circumstance and now want to build credit
    • Divorcees or widows whose credit history was primarily or entirely tied to a former spouse

    People rebuilding after credit damage

    If you have negative marks on your credit report — late payments, a collection, a charge-off, a short sale — a credit-builder loan can help you rebuild by adding a clean, current stream of positive payment history. The old negatives don’t go away, but they age, and as they age their impact on your score diminishes. Meanwhile, your new on-time payments demonstrate that you’re back on track.

    This works best when the credit-builder loan is part of a broader rebuild plan that also includes:

    • Settling or paying off any outstanding collections or charge-offs
    • Bringing any current delinquent accounts current
    • Keeping all existing accounts in good standing going forward
    • Addressing any errors on your credit report (this is where a professional credit audit can help — more on that at the end)

    A credit-builder loan alone won’t undo serious credit damage, but as one tool in a larger effort, it’s a solid addition.

    People who can’t qualify for a secured credit card

    Secured credit cards — which we’ll compare in detail below — are another common credit-building tool, but not everyone can get one. Some secured cards require a minimum deposit of $200 or more, which is a real barrier if money is tight. Some require a credit check and have minimum score requirements. Some deny applicants with recent bankruptcies or certain negative marks on their file.

    A credit-builder loan can be a good alternative if a secured card isn’t accessible to you, because most credit-builder loan providers don’t pull your credit for approval. The monthly payment may also be lower than a secured card’s deposit, making it more manageable on a tight budget.

    People who struggle with credit card discipline

    Here’s a group that doesn’t get talked about enough: people who have tried credit cards before and ended up carrying balances they couldn’t pay off. If you know that having a revolving credit line tends to lead to overspending for you, a credit-builder loan offers the credit-building benefit without the temptation. You can’t spend the money — it’s locked away — so there’s no way to rack up a balance you can’t afford.

    For some people, this structural safeguard is exactly what they need to build credit without falling back into old patterns.

    Who might want a different approach

    A credit-builder loan may not be your best option if:

    • You already have good credit and an established mix of accounts. If you’ve got a couple of credit cards and an auto loan that you’re paying on time, a credit-builder loan won’t add much. Your score is already being driven by your existing history, and the loan’s impact would be minimal.
    • Your main credit problem is high utilization. If your cards are near their limits, paying down those balances will help your score far more than a credit-builder loan will. Utilization is 30% of your score, and an installment loan doesn’t touch it.
    • You can’t comfortably afford the monthly payment. A credit-builder loan only helps if you make every payment on time. If you’re already stretched thin and a missed payment is a real possibility, the loan could end up hurting you instead of helping. We’ll cover this in the risks section.
    • You need to borrow money right now. A credit-builder loan doesn’t give you access to funds during the term. If you need to finance a car repair, a medical bill, or an essential purchase, this product won’t solve that problem — you’d need a different loan or credit line.

    Does a Credit Builder Loan Actually Work? The Honest Answer

    This is the question that matters most, and it deserves a straight answer.

    Yes — a credit builder loan does work, in the specific sense that it reliably creates a positive payment history on your credit report, and that history tends to produce measurable score improvements for people who start with no credit or thin credit. The evidence on this is real, not just marketing.

    A widely cited study by the Consumer Financial Protection Bureau (CFPB) in 2020 examined the outcomes of credit-builder loan users and found that participants without existing debt saw an average score increase of roughly 60 points over the loan term. For participants with no credit score at the start, the majority became scoreable — meaning they went from having no credit file at all to having a FICO score that lenders could use.

    That’s a meaningful result, and it matches what we see in practice. For people starting from scratch, a credit-builder loan is one of the most reliable on-ramps to a credit score.

    But — and this is where the honesty comes in — the answer comes with important caveats that the advertising rarely mentions:

    The gains are biggest for people starting with no credit, smaller for everyone else

    The 60-point average in the CFPB study was driven largely by people who had no credit score at the outset. For people who already had a credit score and existing debt, the gains were much smaller — and in some cases, scores actually went down slightly. Why? Because opening a new account can temporarily lower your average age of accounts, and if you have existing debt, the new loan’s small benefit can be offset by that effect.

    So the honest framing is:

    • No credit history → credit-builder loan → big improvement. This is where the tool shines.
    • Bad credit with existing debt → credit-builder loan → modest improvement, possibly mixed. The loan helps with payment history, but if you’re also carrying high credit card balances, the utilization factor will keep your score suppressed regardless of what the loan does.
    • Already good credit → credit-builder loan → minimal or no benefit. You don’t need it, and the new-account penalty might offset any tiny gain.

    It builds payment history, not credit mix or utilization benefits

    We covered this above, but it’s worth restating in the context of “does it work.” A credit-builder loan affects one of the five scoring factors in a major way — payment history. It touches credit mix modestly. It doesn’t touch utilization at all, and utilization is nearly as important as payment history (30% vs. 35%).

    This means a credit-builder loan is most effective when paired with a revolving credit account (like a secured card) that you keep at low utilization. Used together, the two cover more of the scoring factors. Used alone, the loan is still helpful but leaves the 30% utilization factor entirely untouched.

    It works only if you pay on time every single month

    This cannot be overstated. The entire benefit of a credit-builder loan comes from on-time payments. A single late payment — especially one reported as 30 days late — can wipe out months of progress and leave a negative mark that stays on your report for seven years. The loan doesn’t have a grace period for credit reporting purposes the way some credit cards do. If the lender reports you late, it’s on your report.

    So “does it work” is really “does it work for you,” and the answer depends almost entirely on whether you can commit to making every payment on time for the full term. If you can, it works. If you can’t — if your income is irregular, your budget is already stretched, or you’re not confident you can make a payment every single month — then the tool can backfire, and you should consider whether the risk is worth it.

    The score gains are real but not dramatic for most people

    For someone starting with no credit, going from “no score” to “a score in the mid-600s” over 12–18 months is genuinely life-changing — it’s the difference between being denied for everything and being approved for entry-level credit products. In that context, the credit-builder loan absolutely works.

    For someone starting with a 580 who wants to reach 700, a credit-builder loan alone will likely get them part of the way there — maybe into the low-to-mid 600s — but not all the way. Closing that gap usually requires a combination of tools and time: the credit-builder loan for payment history, a secured card for utilization, removal of any errors or inaccurate negative marks, and simply the passage of time as old negatives age.

    If a provider tells you a credit-builder loan will “boost your score by 100 points,” treat that as a red flag. The honest version is: it will help, the amount depends on your starting point and your full credit picture, and it’s most effective as part of a broader plan rather than a standalone fix.

    Pros and Cons of Credit-Builder Loans

    Let’s lay it out plainly.

    Pros

    • No credit check required for approval at most providers. This is the feature that makes credit-builder loans accessible to people who can’t get any other credit product. You’re approved based on identity verification and ability to pay, not your credit history.
    • Builds a positive payment history. This is the single most important factor in your credit score (35%), and a credit-builder loan delivers it reliably — 12 to 24 on-time installment payments on your report.
    • Forces savings. Because the money is locked away and you’re paying toward it each month, you end the term with a lump sum — often $300 to $1,000 — that you might not have saved otherwise. For people who struggle with savings discipline, this is a genuine secondary benefit.
    • Low monthly payments. Depending on the loan size and term, payments often fall in the $25–$90 range, which is manageable for many budgets.
    • No risk of overspending. You can’t charge up a balance you can’t pay off, because there’s no usable credit line. The temptation problem that sinks many credit card users doesn’t exist here.
    • Adds to your credit mix. If your file only has revolving accounts, adding an installment loan gives scoring models evidence that you can handle both types.
    • Available from mission-driven lenders. CDFIs and many credit unions offer these loans at low cost because their mission includes serving underserved communities. You’re not just building credit — you’re often working with an institution that’s structured to support you.

    Cons

    • You don’t get the money until the end. Unlike a traditional loan, you can’t use the funds during the term. If you need to borrow for an immediate expense, this product doesn’t serve that need.
    • You pay fees and/or interest, so you end up paying more than you receive. The total cost of a credit-builder loan — the interest or administrative fees — means you get back less than you paid in. You’re paying for the credit-building service, not getting a free lunch.
    • Late payments are reported and can hurt your score. The same mechanism that helps you when you pay on time can damage you when you don’t. A 30-day late mark on a credit-builder loan is just as harmful as one on any other account.
    • No impact on credit utilization. If your main score problem is high credit card balances, the loan won’t address it. Utilization is 30% of your score, and installment loans don’t factor in.
    • Limited score gains for people with existing credit. If you already have a couple of accounts in good standing, the marginal benefit of adding a credit-builder loan is small.
    • Short-term new-account penalty. Opening the loan creates a hard inquiry (at providers that pull credit) and shortens your average age of accounts, both of which can cause a small, temporary dip in your score in the first few months.
    • Some providers only report to one or two bureaus. If your lender only reports to, say, Equifax and Experian but not TransUnion, your TransUnion file won’t benefit. This is a common and avoidable mistake — always confirm all-bureau reporting before signing up.

    Credit-Builder Loan vs. Secured Card vs. Authorized User

    A credit-builder loan is one of three common tools for building or rebuilding credit. The other two — secured credit cards and becoming an authorized user on someone else’s account — work differently and have different trade-offs. Here’s how they compare.

    The comparison table

    Feature Credit-Builder Loan Secured Credit Card Authorized User
    How it works You pay monthly toward a locked savings account; lender reports payments You put down a refundable deposit (usually $200+) that becomes your credit limit; you use the card and pay it off Someone adds you to their existing credit card as an authorized user; their account history appears on your report
    Credit check for approval? Usually no Usually yes (soft or hard) No (the primary cardholder was checked when they applied)
    Upfront cost First month’s payment + any setup fee Security deposit (typically $200–$500) None
    Ongoing cost Interest or admin fees ($15–$60 over the full term, depending on provider) Annual fee (varies; some have none) + interest if you carry a balance None (unless the primary cardholder asks you to chip in)
    Do you get access to credit? No — money is locked until the end Yes — you can use the card up to your limit Yes — you can use the card if the primary holder gives you a card
    What it builds on your report Installment payment history Revolving account history + utilization Revolving account history (the primary holder’s)
    Affects utilization? No Yes — keeping your balance low relative to your limit helps your score Yes — the account’s utilization appears on your report
    Risk of overspending None — no usable credit line Real — you can carry a balance and accrue interest Real — but the primary holder is ultimately responsible
    Risk from late payments A late payment hurts your score A late payment hurts your score and may trigger fees + APR increase Your late payments hurt both your score and the primary holder’s score
    Speed of score impact Gradual over 6–24 months Can be faster — utilization changes show up within a billing cycle Immediate if the account has a long, clean history
    Best for No credit, thin credit, people who want forced savings, people who can’t manage a card People who want a usable card while building credit, people who can manage a low balance People with a trusted family member or friend who has a long, clean credit history on a card
    Weakness Doesn’t help utilization, modest gains for people with existing credit Requires a deposit upfront, temptation to overspend, some have fees Depends entirely on the primary holder keeping the account in good standing

    Which should you choose?

    The honest answer from a trusted-advisor perspective: it depends on your situation, and you can use more than one.

    • If you’re starting from zero and want the simplest, lowest-risk entry point, a credit-builder loan is hard to beat. No credit check, no deposit to scrape together, no temptation to overspend. You build payment history and savings at the same time.
    • If you want a usable credit card while you build, a secured card is the better fit — but only if you’re confident you can keep the balance low (ideally under 10% of the limit) and pay it off in full every month. The utilization factor is powerful, and a secured card lets you work it.
    • If you have a trusted family member with a long, clean credit card history, becoming an authorized user is the fastest and cheapest option. Their account’s positive history appears on your report immediately. But it’s not in your control — if they later miss a payment or run up the balance, your score takes the hit too.
    • For the best results, combine tools. A credit-builder loan for installment payment history plus a secured card kept at low utilization for revolving history covers more of the scoring factors than either one alone. This is what we often recommend to clients who are serious about building credit as efficiently as possible.

    How to Choose the Right Credit-Builder Loan

    Not all credit-builder loans are created equal, and choosing a poor one can mean paying more than you need to or getting less credit-building benefit than you expected. Here are the factors that actually matter, in order of importance.

    1. Reports to all three credit bureaus — non-negotiable

    This is the single most important criterion. Your credit score is calculated separately by each of the three major bureaus — Equifax, Experian, and TransUnion — and lenders don’t all pull from the same one. A mortgage lender might pull all three. An auto lender might pull one. A credit card issuer might pull another.

    If your credit-builder loan only reports to one or two bureaus, your credit file at the non-reporting bureau(s) won’t show the loan at all. You could complete a 12-month loan, pay on time every month, and still have a thin file at one bureau — which means a lender pulling from that bureau would see no benefit.

    Before you sign up, confirm in writing (or in the provider’s FAQ) that they report to all three bureaus. Reputable providers state this clearly. If a provider is vague about which bureaus they report to, that’s a red flag — look elsewhere.

    2. Low fees and reasonable interest

    The cost of a credit-builder loan varies significantly by provider. A CDFI credit builder loan from a community credit union might charge no fees and a very low interest rate (sometimes under 6% APR, sometimes a flat administrative fee of $10–$25 total). A fintech provider might charge an administrative fee of $9–$15 upfront plus a monthly fee of $5–$10, or an APR of 15% or more.

    Over a 12-month term, the difference adds up:

    • A low-cost CDFI loan: you might pay $15–$30 total above the principal
    • A higher-cost fintech loan: you might pay $60–$150 total above the principal

    That’s not necessarily a deal-breaker — if the fintech loan is the only one available to you or the convenience is worth it, the cost is still modest in absolute terms. But all else being equal, you should prefer the lower-cost option. Why pay $120 for something you could get for $25?

    3. Reasonable term length

    The typical credit-builder loan term is 6 to 24 months. The term you choose affects two things:

    • The monthly payment amount — a longer term means lower monthly payments, which is easier on a tight budget
    • The amount of payment history you build — a longer term means more on-time payments on your report, which is better for your score

    For most people, a 12-month term is a good balance: long enough to build meaningful history, short enough that you’re not locked in for years. If your budget is very tight, an 18- or 24-month term with lower payments may be more sustainable. If you’re confident in your ability to pay and want to build history faster, a 6-month term works but gives you fewer data points.

    Avoid terms shorter than 6 months — there’s not enough time to build a meaningful track record.

    4. CDFI or credit union vs. fintech — the trade-off

    This is a genuine decision point, not a clear-cut one.

    CDFI credit builder loans and credit union loans:

    • Usually the lowest cost
    • Often come with financial education and counseling resources
    • May require membership (which is typically easy to get but is an extra step)
    • May have less polished digital experiences
    • May have geographic limitations (some serve specific regions or communities)
    • The mission-driven structure means they’re genuinely invested in your success

    Fintech credit-builder loans (Self, Credit Strong, etc.):

    • Available nationwide, usually with no membership requirement
    • App-based, easy to manage from your phone
    • Often faster to apply and get approved
    • Tend to charge higher fees than community lenders
    • Some offer additional features like credit monitoring included in the fee

    There’s no wrong choice here — both can build your credit effectively if they report to all three bureaus. But if you have access to a good CDFI or credit union option, the cost savings and the access to human support are real advantages. If convenience and speed matter more to you, a fintech like Self or Credit Strong is a perfectly reasonable choice.

    5. Payment flexibility and autopay

    Look for a provider that offers autopay — automatic monthly payments from your linked bank account. Autopay is the single best safeguard against the worst risk of a credit-builder loan (a missed payment), because it removes the need to remember and manually make the payment each month.

    Also check the provider’s policy on early payment or extra payments. Can you pay ahead if you have a good month? Can you pay off the loan early without penalty? Most credit-builder loans allow early payoff, but some don’t — and if you might want to finish early, confirm this before committing.

    6. What happens if you miss a payment

    Read the fine print on late payments. Key questions:

    • Is there a grace period before a late payment is reported to the bureaus?
    • Is there a late fee, and how much?
    • Does the loan go into default if you miss a certain number of payments, and what does that mean for the money in the savings account?
    • Can you pause payments (forbearance) if you hit a financial rough patch?

    A provider that reports a late payment to the bureaus after just one day past due is riskier than one with a 30-day grace period. This matters — know the policy before you sign up.

    7. Whether interest is earned on the savings portion

    Some providers pay interest on the savings account holding your loan proceeds while you’re paying the loan off. It’s usually a small amount (savings rates aren’t high), but it partially offsets the cost of the loan. It’s a minor factor, but worth checking — a provider that pays interest on your savings is returning a bit of value to you.

    Credit-builder loan explained and how it helps build credit

    Typical Terms and Costs

    Let’s get concrete about what you can expect to pay and what terms you’ll see in the market. These are typical ranges — actual offers vary by provider.

    Loan amounts

    • Small: $300–$500 — lowest monthly payments, good for tight budgets, builds less savings
    • Medium: $500–$1,000 — the most common range, balances payment affordability with meaningful savings at the end
    • Large: $1,000–$2,000 — higher monthly payments, more savings at the end, available from some providers

    Term lengths

    • 6 months — fast, lower total cost, fewer payment data points
    • 12 months — the standard, good balance of cost and history
    • 18–24 months — lower monthly payments, more payment history, higher total cost over the term

    Interest rates and fees

    Provider Type Typical APR or Fee Structure Total Cost on a $1,000 / 12-month Loan
    CDFI credit builder 5–10% APR or flat $10–$25 admin fee $25–$60
    Credit union 5–12% APR, sometimes no fees $30–$70
    Fintech (Self) $9 admin fee + $5–$10/month, or ~15% APR equivalent $70–$130
    Fintech (Credit Strong) Varies by plan; administrative fee + interest, ~15%+ APR equivalent $80–$150

    These are estimates — actual costs depend on the specific product, state, and term. The point is that the cost range across providers is meaningful: a low-cost CDFI loan might cost you $30 to build a year of credit history, while a premium fintech product might cost $130 for the same outcome. Both work; one is noticeably cheaper.

    Example payment schedules

    $500 loan, 12-month term, low-cost CDFI (no fee, 6% APR):

    • Monthly payment: ~$43
    • Total paid: ~$516
    • Amount you receive at end: ~$500
    • Net cost: ~$16

    $1,000 loan, 12-month term, fintech ($9 admin + $10/month):

    • Monthly payment: ~$92 ($83 principal + $9 monthly fee, plus initial $9 admin fee)
    • Total paid: ~$1,120
    • Amount you receive at end: ~$1,000
    • Net cost: ~$120

    $1,000 loan, 24-month term, credit union (8% APR):

    • Monthly payment: ~$45
    • Total paid: ~$1,083
    • Amount you receive at end: ~$1,000
    • Net cost: ~$83

    As you can see, the longer term lowers the monthly burden but increases the total cost slightly due to more interest accrual. The fintech option is meaningfully more expensive but offers convenience and app-based management.

    Step-by-Step: Using a Credit-Builder Loan

    If you’ve decided a credit-builder loan makes sense for you, here’s a clear walkthrough of how to use one effectively.

    Step 1: Check your current credit situation

    Before you apply, pull your credit reports from all three bureaus. You’re entitled to free reports at AnnualCreditReport.com. Review them for:

    • Errors or inaccurate negative marks — if there’s something wrong on your report, a credit-builder loan won’t fix it. Disputing errors first (or working with a professional credit repair firm) gives you a cleaner foundation to build on.
    • Existing accounts — know what’s already on your report so you can see how the credit-builder loan fits in.
    • Your current score (if you have one) — this gives you a baseline to measure progress against.

    If you find errors or significant negative marks, consider addressing those first or alongside the credit-builder loan.

    Step 2: Choose a provider that reports to all three bureaus

    Use the criteria in the . Confirm all-bureau reporting, compare costs, and pick a provider that fits your budget and preferences. If you have access to a local CDFI or credit union, start there — the cost savings are worth the extra step of joining.

    Step 3: Pick a loan amount and term you can afford

    Be honest with yourSelf about what monthly payment you can sustain for the full term. A smaller loan with a longer term and a $25–$40 monthly payment is a safer choice than a larger loan with a $90 payment that you’ll struggle to make in a bad month. The goal is 12–24 months of unbroken on-time payments — choose a payment level that makes that realistic.

    Step 4: Set up autopay before the first payment

    This is the single most important step after choosing the loan. Set up automatic payments from your primary bank account so that you never have to remember to make a payment manually. Verify the payment date works with your cash flow — if you get paid on the 15th, schedule the payment for the 16th or later, not the 10th.

    If your provider doesn’t offer autopay, set a recurring calendar reminder for at least five days before each due date, and make the payment manually as soon as you see the reminder.

    Step 5: Make every payment on time

    This is where the credit-building actually happens. Every on-time payment is a positive mark on your report. Every late payment is a negative mark that can undo months of progress. Treat the payment like rent or utilities — non-negotiable, paid before anything optional.

    If you see a rough month coming, contact the lender before the payment is due. Some providers offer forbearance or payment arrangements if you reach out proactively. They’re far less flexible after a payment is already late.

    Step 6: Monitor your credit along the way

    Check your credit score periodically (many banks and credit card issuers offer free score monitoring, and some credit-builder loan providers include it). You’re looking for:

    • Steady, gradual improvement over the loan term
    • The new installment account appearing on all three bureau reports
    • No unexpected drops that might indicate a reporting error or identity issue

    If the loan isn’t showing up on one of your bureau reports, contact the lender — it may be a reporting issue they can correct.

    Step 7: Receive your savings at the end

    When the loan term ends and you’ve paid in full, the lender releases the savings account balance to you. This is usually paid via ACH transfer to your bank account or by check. Take a moment to acknowledge what you’ve accomplished — you’ve built a year or more of positive credit history and you’ve saved a meaningful lump sum at the same time.

    Step 8: Decide what to do with the savings

    You have a choice here, and it matters for your long-term financial health:

    • Keep it as an emergency fund. If you don’t already have one, this is an excellent use. An emergency fund is the single best protection against the kind of financial setbacks that damage credit in the first place.
    • Use it as a secured credit card deposit. If you’ve been building credit with the loan and want to add a secured card for the utilization factor, your newly saved lump sum can serve as the deposit. This is a smart next step that covers more of the scoring factors.
    • Roll it into a new savings goal. If your emergency fund is already in place, keep the momentum going — move the money into a dedicated savings account for a specific goal.
    • Avoid spending it on non-essentials. The discipline you built during the loan term is a habit worth keeping. Don’t let the lump sum evaporate on a purchase that doesn’t serve your bigger financial picture.

    What Happens at the End of the Loan

    The end of a credit-builder loan is a moment worth understanding clearly, because it’s where the “forced savings” aspect pays off — literally.

    The payout

    When your final payment posts and the loan is paid in full, the lender releases the savings account balance to you. The amount you receive is the total of your principal payments — the money you paid in that went toward the loan amount, not toward interest or fees. For example:

    • On a $1,000 loan where you paid $1,080 total (with $80 in interest/fees), you receive $1,000.
    • On a $500 loan where you paid $530 total (with $30 in fees), you receive $500.

    The payout typically arrives within 7–14 days of the final payment, via ACH transfer or check, depending on the provider.

    What stays on your credit report

    The loan account doesn’t disappear from your credit report when it’s paid off. A paid installment loan remains on your report as a positive closed account for up to 10 years. During that time, it continues to contribute to your:

    • Payment history — the 12–24 months of on-time payments stay on your report as evidence of reliable repayment
    • Length of credit history — the account’s age continues to support your average age of accounts
    • Credit mix — the closed installment account still counts toward your mix of credit types

    This is a quiet but important benefit. The work you did during the loan term keeps paying off for years after the loan is gone.

    What to do next

    Once the loan is paid off, think about your next credit-building move:

    • If you don’t have a revolving credit account yet, consider opening a secured credit card (using part of your payout as the deposit, if needed). This starts building the utilization factor that the loan didn’t cover.
    • If you already have a credit card, keep its balance low and pay it in full each month. This maintains the utilization factor in your favor.
    • If your score has improved enough, you may now qualify for an unsecured credit card with better terms than a secured one. Check pre-qualification offers (which use soft inquiries) to see what’s available without adding a hard inquiry.
    • If you have older negative marks on your report, review whether any are due to age off soon or whether any are inaccurate and could be disputed.

    The credit-builder loan was a foundation. What you build on it next is where the bigger gains come from.

    Risks to Understand Before You Start

    A credit-builder loan is one of the safer credit-building tools available, but “safer” doesn’t mean “risk-free.” Here are the real risks to understand before you commit.

    Risk 1: Late payments damage your credit

    This is the biggest risk, and it bears repeating. If you miss a payment and the lender reports it as 30 days late to the bureaus, that negative mark stays on your credit report for up to seven years. The same mechanism that builds your credit when you pay on time can damage it when you don’t.

    A single 30-day late payment can drop a good credit score by 60–80 points. For someone building from scratch, it can mean going from a fledgling 650 back down to a 580 or lower — undoing months of careful work.

    Mitigation: Set up autopay. Choose a payment amount you can sustain even in a bad month. Contact the lender proactively if you see trouble coming.

    Risk 2: Fees can be higher than expected

    Some fintech credit-builder loans have fee structures that aren’t immediately obvious — monthly maintenance fees, administrative fees, early closure fees, payment processing fees for certain payment methods. Read the full fee schedule before you commit, not just the headline APR.

    Mitigation: Compare total cost across the full term, not just the monthly payment. Prefer CDFIs and credit unions where the fee structure is typically simpler and lower.

    Risk 3: The new account temporarily lowers your score

    When you open any new credit account, two things happen that can cause a small, temporary dip in your score:

    • A hard inquiry appears on your report (if the provider pulls credit — many don’t for credit-builder loans)
    • Your average age of accounts decreases because you’ve added a brand-new account

    This dip is usually small (5–15 points) and recovers within a few months as you build payment history. But if you’re applying for a mortgage or auto loan in the next 3–6 months, the timing could be inconvenient.

    Mitigation: If you have a major credit application coming up soon, either start the credit-builder loan after that application or talk to a credit professional about timing.

    Risk 4: The provider doesn’t report to all three bureaus

    We’ve covered this, but it’s a risk worth restating. If you complete a 12-month loan and discover at the end that one bureau never received the reports, you’ve built credit at two bureaus but not the third — and you can’t retroactively fix it.

    Mitigation: Confirm all-bureau reporting in writing before you sign up. If a provider won’t confirm it, choose a different provider.

    Risk 5: You need the money before the term ends

    Because the savings are locked until the loan is paid in full, you don’t have access to that money if an emergency hits mid-term. If you were counting on those funds being available, this can create a real problem.

    Mitigation: Don’t think of the credit-builder loan savings as an emergency fund during the term — it’s not accessible. Keep a separate small emergency fund (even $200–$500) in a regular savings account that you can reach if needed.

    Risk 6: Some providers have early closure penalties or restrictions

    If you need to close the loan early — because your situation changed, you’re moving, or you simply want out — some providers charge an early closure fee or have restrictions on how and when you can close. Read the terms before committing.

    Mitigation: Confirm the early closure policy before you sign up. Most reputable providers allow early payoff without penalty, but not all do.

    Common Mistakes to Avoid

    In our experience working with clients on credit building, a handful of mistakes come up repeatedly. Here are the ones to watch for.

    Mistake 1: Choosing a loan payment you can’t actually afford

    It’s tempting to pick a larger loan amount because you’ll get more savings at the end. But if the monthly payment is a stretch, you’re setting yourSelf up for a late payment that will cost you far more in credit damage than the extra savings are worth.

    Fix: Choose the smallest loan amount and longest term that still gives you meaningful payment history. A $500 loan at 24 months with a $22 monthly payment builds the same payment-history benefit as a $1,000 loan at 12 months with an $87 payment — but the smaller payment is far easier to sustain.

    Mistake 2: Not setting up autopay

    Manual payments rely on memory, and memory fails. One forgotten payment can undo months of progress.

    Fix: Set up autopay on day one. If your provider doesn’t offer autopay, set a recurring calendar alert for five days before each due date.

    Mistake 3: Not verifying all-three-bureau reporting

    We’ve seen clients complete an entire loan term only to find out the provider only reported to one bureau. They built credit at one bureau and have nothing to show at the other two.

    Fix: Before you sign up, find explicit confirmation (on the provider’s website, in their FAQ, or by calling and asking) that they report to Equifax, Experian, and TransUnion. If it’s not clear, choose a different provider.

    Mistake 4: Opening a credit-builder loan when your real problem is high utilization

    If your credit cards are maxed out, your utilization is suppressing your score by up to 30% of the total calculation. A credit-builder loan won’t touch that. You could complete a 12-month loan, pay on time every month, and see only a small score improvement because your utilization is still dragging you down.

    Fix: If high utilization is your main issue, prioritize paying down card balances first. A credit-builder loan can be a useful addition, but it’s not the primary fix for utilization.

    Mistake 5: Closing the loan early without understanding the impact

    Some people get impatient or need the money and close the loan a few months in. This gives you only a few months of payment history — far less impactful than a full 12–24 months — and may trigger early closure fees.

    Fix: Commit to the full term before you start. If you think you might need the money sooner, don’t lock it up in a credit-builder loan.

    Mistake 6: Not addressing errors or inaccurate negative marks first

    If your credit report has errors — accounts that aren’t yours, payments marked late that were actually on time, outdated information that should have aged off — a credit-builder loan builds positive history on top of a flawed foundation. The errors continue to hold your score down.

    Fix: Pull your reports and review them for accuracy before starting a credit-builder loan. Dispute any errors, or work with a professional credit repair firm that can help.

    Mistake 7: Treating the loan as your only credit-building tool

    A credit-builder loan is excellent for payment history, but it leaves utilization untouched. If you stop there, you’re leaving score points on the table.

    Fix: Plan to add a revolving credit account (secured card or unsecured card, depending on where your score is) at some point during or after the loan term. The combination covers more of the scoring factors and tends to produce better results than either tool alone.

    Mistake 8: Not having a plan for the savings when the loan ends

    When that lump sum lands in your account at the end of the term, it’s easy to spend it on something non-essential — and lose the savings habit you built over 12–24 months.

    Fix: Decide before the loan ends what the savings will go toward. An emergency fund, a secured card deposit, a specific financial goal — having a plan keeps the money working for you.

    Frequently Asked Questions

    1. Does a credit builder loan actually work?

    Yes — for people with no credit or thin credit, a credit-builder loan reliably builds a positive payment history on your credit report, which is the single most important factor in your credit score (35% of your FICO score). Research from the CFPB found that participants without existing debt saw average score gains of around 60 points, and most participants with no prior score became scoreable. The gains are largest for people starting from zero and more modest for people rebuilding with existing debt. The key condition: you must make every payment on time for the full term. For more detail, see our section on .

    2. How does a credit builder loan work if I don’t get the money upfront?

    That’s the unusual mechanic. The lender places the loan amount in a locked savings account in your name. You make monthly payments toward that amount, and the lender reports each on-time payment to the credit bureaus. When the loan is paid in full, the savings account unlocks and the money is released to you — minus any interest or fees. You’re essentially paying yourSelf while building a credit record, with the lender acting as the structured middleman who reports your payments. See for the full breakdown.

    3. What’s the difference between a credit builder loan and a secured credit card?

    A credit-builder loan is an installment loan — you make fixed monthly payments toward a locked savings account, and the lender reports those payments. It builds payment history and adds to your credit mix, but it doesn’t affect your credit utilization. A secured credit card is a revolving account — you put down a refundable deposit that becomes your credit limit, you use the card for purchases, and you pay it off each month. It builds payment history AND affects your utilization (keeping your balance low relative to your limit helps your score). The secured card gives you a usable credit line; the credit-builder loan doesn’t. See our for the full side-by-side.

    4. How much does a credit builder loan cost?

    The cost depends on the provider. A low-cost CDFI credit builder loan might cost you $15–$30 in fees and interest over a 12-month term. A fintech provider like Self or Credit Strong might cost $70–$150 over the same term. The monthly payment on a typical $500–$1,000 loan with a 12-month term ranges from about $25 to $90. See for specific examples.

    5. Can I get a credit builder loan with no credit check?

    Yes — most credit-builder loan providers do not require a credit check for approval, because the structure of the loan means the lender isn’t taking on credit risk (they hold the full amount in reserve). Approval is typically based on identity verification and your ability to make the monthly payments. This is one of the main reasons credit-builder loans are accessible to people who can’t qualify for other credit products.

    6. What happens if I miss a payment on a credit builder loan?

    A missed payment is the biggest risk of a credit-builder loan. If the lender reports it as 30 days late to the credit bureaus, that negative mark stays on your credit report for up to seven years and can cause a significant score drop — potentially undoing months of progress. Some providers have grace periods before reporting, and some may offer forbearance if you contact them proactively before the due date. Read the provider’s late payment policy before signing up, and set up autopay to eliminate the risk of forgetting. See our section on for more.

    7. How long does it take for a credit builder loan to improve my score?

    You can expect to see the loan appear on your credit report within 30–60 days of opening it, and you’ll start building payment history from your first on-time payment. Meaningful score improvement typically becomes visible after 3–6 months of on-time payments, with more substantial gains after 12 months. For people starting with no credit score, becoming scoreable usually takes about 6 months of reported payments (the minimum history most scoring models need to generate a score). The full benefit accrues over the entire loan term.

    8. What’s the best credit builder loan?

    There’s no single “best” credit-builder loan — the right choice depends on your priorities. If cost is your main concern, a CDFI credit builder loan from a community credit union or nonprofit lender is usually the most affordable option. If convenience and nationwide availability matter most, Self and Credit Strong are reputable fintech options with app-based management. The universal requirement, regardless of provider, is that they report to all three major credit bureaus. See our section on for the full criteria.

    Ready to Take the Next Step?

    A credit-builder loan is a solid, proven tool for establishing or rebuilding your credit — but it works best as part of a broader plan that also addresses any errors on your credit report, manages your credit utilization, and builds positive habits across all of your financial accounts.

    If you’re not sure where you stand right now, that’s the natural starting point. Before you open any new account — credit-builder loan, secured card, or anything else — it helps to know what’s actually on your credit report, what’s helping you, what’s holding you back, and what specific steps will move the needle for your situation.

    That’s exactly what we help with at credit-repair.com. We offer a free credit audit that reviews your reports from all three major bureaus, identifies any errors or inaccurate negative marks that may be unfairly dragging down your score, and gives you a clear, honest picture of where you stand and what your options are.

    We’re a San Diego-based, attorney-backed credit repair firm operating in full compliance with the Fair Credit Reporting Act (FCRA). We don’t make empty promises or sell quick fixes — we help you understand your credit, dispute what’s inaccurate, and build a plan that combines the right tools for your specific situation. Whether that includes a credit-builder loan, a secured card, professional help removing errors, or a combination of all three, we’ll give you a straight answer about what makes sense for you.

    Get your free credit audit at credit-repair.com →

    Your credit score is one of the most important numbers in your financial life. It affects your interest rates, your insurance premiums, your housing options, even your job prospects in some cases. Building it the right way — patiently, honestly, with the right tools and the right guidance — is one of the highest-return investments you can make. We’re here to help you do it.

    {/* Internal link placeholders to update when publishing:

    • Learn more about credit repair
    • Learn about credit monitoring
    • Learn about disputing credit report errors
    • Talk to a credit advisor
    • */}
  • Experian Boost Review: Can It Really Raise Your Score?

    Experian Boost Review: Can It Really Raise Your Score?

    See also: how to find and fix credit report errors across all three bureaus, compare FICO vs VantageScore to understand which models Boost affects, see what each score range means, and discover five free credit repair steps you can take on your own.

    You’ve seen the commercials. A friendly spokesperson promises that linking your utility and phone bills to your Experian account can “instantly” raise your credit score. No new credit cards. No hard inquiries. No cost. It sounds almost too good to be true — and like most things in credit, the reality is more complicated than the marketing.Experian Boost is a real, free feature offered by Experian, one of the three major credit reporting agencies in the United States. It can, in many cases, add points to a credit score within minutes. But the score it boosts is not the score most lenders use, and that distinction matters — a lot. If you’re applying for a mortgage, an auto loan, or a credit card, your “boosted” Experian score may be invisible to the lender reviewing your application.This review breaks down what Experian Boost actually does, how it works, what it counts, who benefits, who doesn’t, and whether it’s worth your time. We’ll be honest about the limitations, because we believe you deserve a clear picture before you hand over access to your bank account data. At , our job isn’t to sell you a quick fix — it’s to help you build credit that actually holds up when a lender pulls your report.

    What Is Experian Boost and How Does It Work?

    Experian Boost is a free opt-in feature launched by Experian in 2019. Its premise is simple: many people pay recurring monthly bills on time for years — utilities, phone service, streaming subscriptions — yet those on-time payments never appear on their credit reports and never help their credit scores. Experian Boost aims to change that by giving you credit for payments that traditionally aren’t reported to the credit bureaus.

    Here’s how the mechanics work:

    • You create a free Experian account. This gives you access to your Experian credit report and a VantageScore 3.0 credit score (more on that distinction shortly).
    • You connect your bank account(s). Experian uses a data aggregation service (originally powered by Finicity, now part of Mastercard) to scan your connected checking, savings, or money market accounts for qualifying transactions.
    • Experian identifies eligible payments. The service looks for payments to utility companies, telecom providers (phone, internet), streaming services, and — in a more recent expansion — certain rent payments.
    • You choose which payments to add. You have control over which accounts and which payment categories are included. Nothing gets added without your confirmation.
    • Experian recalculates your score. The eligible on-time payment history is fed into your Experian credit file, and your VantageScore 3.0 is recalculated — often within seconds or minutes.

    The entire process is designed to be frictionless. You link a bank account, confirm a few selections, and watch your score update. Experian reports that the average user sees an increase of around 13 points, though — and this is important — results vary widely and some users see no increase at all.

    The underlying logic

    The idea behind Experian Boost aligns with a broader trend in credit scoring: the recognition that traditional credit reports capture only a narrow slice of a person’s financial behavior. If you’ve never had a credit card, a car loan, or a mortgage, you might have a thin credit file — meaning there isn’t enough data for a scoring model to assess your reliability. Yet you might have paid your electric bill, cell phone bill, and Netflix subscription on time every month for a decade. Experian Boost argues that those payments demonstrate financial responsibility and should count.

    That’s a reasonable argument. The problem isn’t the logic — it’s the scope. Experian Boost only affects your Experian credit file and only the VantageScore model. And that’s where the conversation gets more nuanced.

    The Big Caveat: It Only Boosts Your Experian VantageScore

    This is the single most important thing to understand about Experian Boost, and we want to be completely upfront about it: Experian Boost only affects your Experian credit report and only your VantageScore — not your FICO score, not your Equifax or TransUnion reports, and not the scores most lenders actually use when making lending decisions.

    Let’s unpack what that means.

    VantageScore vs. FICO: The two scoring models

    There are two dominant credit scoring models in the United States:

    • FICO (created by the Fair Isaac Corporation) — the older, more widely adopted model. FICO scores are used in the overwhelming majority of lending decisions, particularly for mortgages, auto loans, and credit cards. There are multiple FICO versions (FICO 8, FICO 9, FICO 2, FICO 4, FICO 5, etc.), and different lenders use different versions.
    • VantageScore (created jointly by the three major credit bureaus — Equifax, Experian, and TransUnion) — a newer model designed as an alternative to FICO. VantageScore 3.0 and 4.0 are the current versions. VantageScore tends to be more forgiving of thin credit files and incorporates some alternative data, which is why Experian Boost works with it.

    Here’s the critical difference for this discussion: Experian Boost’s added payment history is only factored into your VantageScore, not your FICO score. FICO’s scoring models do not currently incorporate utility, phone, or streaming payment data added through Experian Boost. So if a lender pulls your FICO 8 score (the most common version), your Boost-eligible payments are invisible.

    Why this matters for mortgages

    If you’re considering Experian Boost because you’re planning to apply for a mortgage, you need to know this: mortgage lenders overwhelmingly use FICO scores — specifically FICO 2, FICO 4, and FICO 5 (the older “classic” FICO models tailored for mortgage lending), pulled from all three bureaus. These scores do not reflect Experian Boost data. When a mortgage lender pulls your credit, they will see:

    They typically use the middle score of the three (or the lower of the two if only two scores are available). None of these scores are affected by Experian Boost. So if you boosted your Experian VantageScore from 680 to 700, your mortgage lender won’t see that 700 — they’ll see your FICO scores, which remain unchanged.

    Why this matters for auto loans and credit cards

    Most auto lenders and credit card issuers also rely on FICO scores — typically FICO 8 or FICO Auto/Bankcard scores. While a small number of lenders use VantageScore (and would therefore see your boosted score), the majority do not. Some lenders that do use VantageScore include certain fintech lenders, some credit unions, and a growing (but still minority) number of card issuers.

    The bottom line on this caveat

    This doesn’t mean Experian Boost is useless. It means you need to calibrate your expectations. If you’re applying for credit with a lender that explicitly uses VantageScore and pulls from Experian, your Boost could help. If you’re applying with the vast majority of lenders — who use FICO — your Boost won’t be a factor.

    We’ll discuss who tends to benefit most in a later section. For now, the takeaway is: Experian Boost raises a real score, but it’s often not the score that matters most.

    How Much Can Experian Boost Actually Help?

    Experian’s own marketing states that the average user sees an increase of approximately 13 points on their Experian VantageScore 3.0. That’s a meaningful number for some people and a negligible one for others, depending on where you start and what you’re trying to accomplish.

    When the boost is small

    For many users — especially those who already have an established credit history with multiple accounts — the increase is modest, often in the range of 3 to 10 points. If your score is already in the 700s or higher, a few extra points rarely changes your lending outcomes. You’re already in prime territory, and a 7-point bump from 742 to 749 doesn’t move you across a meaningful threshold.

    When the boost is larger

    For users with thin credit files — people who have few or no traditional credit accounts — the boost can be more substantial. Experian has reported that some users see increases of 20 points or more. In rare cases, people with no scorable credit history at all (meaning they previously couldn’t generate a VantageScore) become “scoreable” for the first time after adding Boost-eligible payments. For someone who was previously invisible to the credit system, that’s genuinely significant.

    When the boost is zero

    It’s also entirely possible to see no increase at all. This happens when:

    • Your connected bank accounts don’t show qualifying payments (more on eligibility below).
    • Your existing credit history is already strong enough that adding a few utility payments doesn’t change the score.
    • Your payments are too recent or too infrequent to generate meaningful history.
    • The scoring model determines that your overall payment behavior is already well-represented by your existing accounts.

    Experian is transparent about this possibility, though it doesn’t lead with it in its marketing. The truth is that Boost is not guaranteed to help everyone, and for a significant percentage of users, the impact is either negligible or zero.

    A realistic range

    Based on user reports and Experian’s own disclosures, here’s a rough breakdown of what to expect:

    Starting Credit Situation Typical Boost Impact
    No score / unscorable thin file May become scoreable; potentially 20+ points
    Thin file, low score (500s–600s) 10–20 points possible
    Established file, mid score (600s–700s) 3–13 points
    Thick file, high score (700s+) 0–5 points, often none

    These are estimates, not promises. Your individual result depends on your unique credit profile and what payments Experian finds in your connected accounts.

    What Bills Does Experian Boost Count?

    One of the most common questions we hear is: “Does Experian Boost count my [specific bill]?” The answer depends on the category of the payment and whether Experian’s scanning system can identify it in your bank transactions. Let’s go through the eligible categories.

    Utility bills

    This is the core of what Experian Boost was built around. Eligible utilities include:

    • Electric payments
    • Gas payments
    • Water and sewer payments
    • Trash and recycling services

    If you pay these bills from a connected bank account and the payment can be identified as going to a utility provider, they’re generally eligible. Payments made through third-party services (like your bank’s bill pay system) may or may not be identified correctly — it depends on how the transaction appears in your bank data.

    Telecom bills

    Your phone and internet payments count:

    • Mobile phone bills (postpaid plans — prepaid plans may not always be identified)
    • Landline phone bills
    • Internet service bills
    • Cable TV bills (in some cases)

    Streaming services

    Experian added streaming service payments as an eligible category after launch. Qualifying services include:

    • Netflix
    • Hulu
    • Disney+
    • HBO Max / Max
    • Amazon Prime Video
    • Spotify
    • And several others

    The list of recognized streaming providers has expanded over time. If you pay for a streaming service through a bundled plan (like a phone carrier that includes Netflix), the transaction may not be separately identifiable and might not count.

    Rent payments

    More recently, Experian expanded Boost to include rent payments in some cases. This works through partnerships with rent reporting services and property management platforms. If your landlord or property manager uses a participating platform and your rent payments flow through your connected bank account in an identifiable way, those payments may be eligible.

    However, rent reporting through Boost is more limited than the utility/telecom/streaming categories. Not all landlords participate, and the identification of rent transactions can be inconsistent. If rent reporting is your primary goal, you may get better results through a dedicated rent-reporting service (more on that in the comparison section below).

    What does NOT count

    Several common payment types are not eligible for Experian Boost:

    • Insurance premiums (auto, health, life, renters, etc.)
    • Groceries and retail purchases
    • Subscription boxes (unless they fall under a recognized streaming category)
    • Gym memberships
    • Childcare or tuition payments
    • Tax payments
    • Medical bills
    • Loan payments to non-reporting lenders (e.g., some Buy-Now-Pay-Later services, private loans)
    • Cash payments or money transfers (Venmo, Zelle, Cash App to individuals)
    • Mortgage payments (your mortgage is already on your credit report as a tradeline — it doesn’t need Boost)

    A note on transaction identification

    Experian Boost’s ability to count a payment depends entirely on whether the transaction in your bank account can be automatically identified as a payment to an eligible provider. If your bank labels a transaction clearly (e.g., “PG&E PAYMENT” or “NETFLIX.COM”), it will likely be recognized. If the label is vague (e.g., “ACH DEBIT 8847291”), it may not be. This is a limitation of the data aggregation approach — Experian is reading your bank transactions, not receiving direct reports from the billers themselves.

    Who Benefits Most From Experian Boost?

    Experian Boost isn’t equally useful for everyone. Based on how the feature works and the population it was designed to serve, certain people stand to gain more than others.

    1. People with thin credit files

    If you have few or no traditional credit accounts — no credit cards, no loans, no mortgage — you likely have a thin credit file. This means there isn’t enough data in your credit report for scoring models to generate a reliable score, or the score you do get is low simply because there’s not enough positive history to offset any minor negative items.

    For this group, Experian Boost can be genuinely helpful. Adding a year of on-time utility and phone payments to your Experian file can provide the scoring model with additional positive payment history, which may push your VantageScore up meaningfully or make you scoreable for the first time.

    2. People with no credit score at all

    If you’ve never had a credit account, you may be credit invisible — meaning no credit score can be generated for you at all. This is common among young adults, recent immigrants, and people who have historically operated on a cash-only basis. Experian Boost can, in some cases, generate a VantageScore for someone who previously had none. That score, even if modest, can be a stepping stone to qualifying for your first credit card or a secured loan, which in turn builds the traditional credit history that matters most.

    3. People applying with VantageScore-using lenders

    If you know — or can find out — that the specific lender you’re applying with uses VantageScore and pulls from Experian, then Experian Boost directly benefits you. This is a smaller group of lenders, but it includes some online lenders, fintechs, and credit unions. If you’re in this category, Boost is working in your favor at the exact moment you need it.

    4. People rebuilding after a setback

    If you’re recovering from a financial setback — a period of missed payments, a collection, a bankruptcy — and you’re in the early stages of rebuilding, every positive data point helps. Experian Boost can add a layer of recent on-time payment history to your Experian file that complements your rebuilding efforts. It won’t erase the negative items, but it can help dilute their impact in the VantageScore model.

    5. People who want a quick, free confidence boost

    Let’s be honest about the psychological dimension. For some people, seeing their score go up — even a score that most lenders don’t use — is motivating. It feels like progress, and that feeling can sustain the habits (paying on time, monitoring credit) that lead to real, long-term improvement. If that’s you, there’s nothing wrong with using Boost as a motivational tool, as long as you understand its limitations.

    Who Won’t Benefit From Experian Boost?

    Just as important as knowing who benefits is knowing who doesn’t. If you fall into any of these categories, Experian Boost is unlikely to move the needle for you in any practically meaningful way.

    1. People applying for a mortgage

    As we covered earlier, mortgage lenders use FICO scores — specifically the older classic FICO models (FICO 2, 4, and 5) — not VantageScore. Your Experian Boost data does not appear in these scores. If you’re preparing to buy a home or refinance, Boost will not help you qualify or get a better rate. Your time is better spent on the factors that actually move your FICO scores: paying down balances, disputing errors, and ensuring your credit reports across all three bureaus are accurate.

    2. People with thick, established credit files

    If you have multiple credit cards, an auto loan, a mortgage, and years of on-time payment history, your credit file is already rich with positive data. Adding a few utility payments through Boost is like pouring a cup of water into a full bathtub — it doesn’t change the level. Your score is already well-supported by your existing tradelines, and the incremental data from Boost is statistically insignificant.

    3. People whose scores are already high

    If your VantageScore is already in the 740+ range, you’re in prime territory. A few extra points from Boost won’t change your lending outcomes — you already qualify for the best rates most lenders offer. The effort of connecting your bank accounts and granting data access isn’t worth the negligible (or zero) return.

    4. People who don’t pay eligible bills from connected accounts

    If you pay your utilities in cash, by money order, through a service that doesn’t create identifiable bank transactions, or if you split bills with a roommate who handles the actual payment, Experian Boost won’t find qualifying transactions in your bank account. The feature only works if the eligible payments flow through a connected account in a recognizable way.

    5. People who are uncomfortable sharing bank data

    This isn’t about whether Boost “works” — it’s about whether it’s right for you. Experian Boost requires you to grant access to your bank account transaction data through a third-party aggregation service. If you’re not comfortable with that level of data sharing — and many people aren’t — then Boost isn’t for you, regardless of its potential benefits. We discuss the data privacy considerations in the cons section below.

    Pros of Experian Boost

    Despite its limitations, Experian Boost has real advantages. Here’s what it does well:

    • It’s free. There’s no cost to use Experian Boost. You don’t need a paid subscription to Experian’s credit monitoring service to access it. You create a free Experian account, connect your bank, and opt in.
    • It’s fast. The connection and scoring process typically takes minutes. You can see your updated VantageScore the same day you set it up.
    • It only adds positive history. Experian Boost is designed to add only on-time payments to your credit file. It does not report late or missed utility payments. (Note: if you stop paying a utility and the account goes to collections, that collection can still appear on your credit report through normal reporting channels — Boost itself won’t add the negative item, but the underlying biller’s collection actions still can.)
    • It’s opt-in and controllable. You choose which bank accounts to connect and which payment categories to include. You can disconnect at any time, and the added history is removed when you opt out.
    • No hard inquiry. Using Experian Boost does not generate a hard inquiry on your credit report. Your score isn’t dinged for signing up.
    • It can help thin-file consumers. For people with limited credit history, it provides a way to build some positive payment data without taking on new debt.
    • It raises awareness about alternative credit data. Even if Boost itself is limited in scope, it has helped drive a broader conversation about incorporating utility and rent payments into credit scoring — a conversation that benefits consumers generally.

    Experian Boost review showing how the service affects credit scores

    Cons of Experian Boost

    The limitations are significant, and we want you to understand them fully before you decide whether to use the feature.

    1. Lender irrelevance for mortgages and most major lending

    This is the biggest drawback and bears repeating: the score Experian Boost raises (Experian VantageScore 3.0) is not the score used by most lenders, especially mortgage lenders. If you’re using Boost specifically to improve your chances at a mortgage, auto loan, or mainstream credit card approval, the impact will likely be zero at the moment of decision. You may feel good seeing a higher number in your Experian dashboard, but the lender’s underwriting system is looking at a different number entirely.

    2. Only Experian — not Equifax or TransUnion

    Experian Boost only affects your Experian credit file. Your Equifax and TransUnion reports are unchanged. Since many lenders pull credit reports from two or all three bureaus (and use the middle or lowest score), boosting only your Experian file often doesn’t change the score the lender actually uses. Even if a lender uses VantageScore, if they pull from TransUnion or Equifax, your Boost data won’t be there.

    3. Data privacy considerations

    To use Experian Boost, you must connect your bank account(s) through a third-party data aggregation service. This means:

    • A company you may not be familiar with (the aggregation provider) receives access to your bank transaction data.
    • Experian scans your transactions to identify eligible payments.
    • You’re granting ongoing access — the service continues to monitor for new eligible payments over time.

    Experian states that it uses bank-level encryption and that your data is used in accordance with its privacy policy. The aggregation provider is a regulated entity. But the reality is that you’re adding another party to the chain of entities with access to your financial transaction data, and you’re doing it for a benefit that may be marginal. For privacy-conscious consumers, that trade-off may not be worth it.

    We encourage you to read Experian’s privacy policy and the aggregation provider’s policy before connecting your accounts. Understand what data is accessed, how it’s stored, how long it’s retained, and whether it’s shared with any third parties. Informed consent matters.

    4. Only VantageScore, not FICO

    As discussed, FICO is the dominant scoring model. Boost does not affect any FICO score. This means the score you see increase in your Experian dashboard may create a false sense of progress if you’re tracking your credit improvement against the scores that lenders actually use.

    5. Potentially misleading score improvements

    There’s a subtle risk here: if you see your Experian VantageScore jump 15 points after enabling Boost, you might assume your credit has improved broadly. But if a lender pulls your FICO 8 score and it hasn’t moved, the “improvement” was illusory from the lender’s perspective. This can lead to misplaced confidence — applying for credit you don’t actually qualify for, or relaxing your credit-building efforts because you think you’ve made more progress than you have.

    6. Inconsistent transaction identification

    Because Boost relies on reading your bank transactions and pattern-matching them to known billers, the identification process isn’t perfect. Some eligible payments may not be recognized, especially if your bank’s transaction descriptions are vague or if you pay through intermediary services. You might expect a boost and get nothing, simply because the system couldn’t identify your payments.

    7. It doesn’t address the root causes of a low score

    If your credit score is low because of errors on your credit report, high credit utilization, collections, late payments, or other negative items, Experian Boost doesn’t fix any of those things. It adds a thin layer of positive data on top of existing problems. The underlying issues remain. This is the most important limitation from our perspective as a credit repair firm: Boost is a supplement, not a solution.

    Pros and Cons Summary

    Pros Cons
    Completely free Only boosts Experian VantageScore, not FICO
    Fast — results in minutes Not seen by most lenders (mortgages, auto, cards)
    No hard inquiry Only affects Experian, not Equifax or TransUnion
    Only adds positive payment history Requires sharing bank transaction data
    Controllable and opt-out anytime Transaction identification can be inconsistent
    Helpful for thin/no credit files May create false confidence about real progress
    Raises awareness of alternative credit data Doesn’t address root causes of a low score

    Experian Boost vs. Rent Reporting vs. Traditional Credit Building

    Experian Boost is one of several approaches to building or improving your credit. Understanding how it compares to alternatives helps you choose the right strategy — or combination of strategies — for your situation.

    Experian Boost

    • What it does: Adds utility, telecom, streaming, and some rent payments to your Experian file, boosting your VantageScore.
    • Cost: Free.
    • Score affected: Experian VantageScore 3.0 only.
    • Lender visibility: Limited — most lenders use FICO, not VantageScore.
    • Bureau coverage: Experian only.
    • Best for: Thin-file or no-score consumers looking for a quick, free way to generate some positive payment data.

    Rent Reporting Services

    Dedicated rent reporting services (such as Boom, RentTrack, Esusu, and others) report your rent payments directly to one or more of the three credit bureaus. Some report to all three; others report to only one or two.

    • What they do: Report your on-time rent payments as tradelines on your credit report, similar to how a loan appears.
    • Cost: Varies — some are free, some charge a monthly fee or a one-time setup fee. Some landlords cover the cost.
    • Score affected: Depends on the service and which bureaus they report to. Some report to FICO-scorable files (if they report as a traditional tradeline), which can be more impactful than Boost.
    • Lender visibility: Better than Boost if the service reports to all three bureaus and the data appears in FICO-scored files.
    • Best for: Renters who want their largest monthly payment to count toward their credit profile, especially those building credit for a future mortgage.

    The key advantage of rent reporting over Experian Boost is bureau coverage and scoring model impact. If a rent reporting service reports to all three bureaus and the data is incorporated into FICO-scoreable tradelines, it can actually move the scores lenders use — unlike Boost, which is VantageScore-only and Experian-only.

    Traditional Credit Building

    This is the bedrock approach, and it’s what we recommend to most of our clients at credit-repair.com. Traditional credit building involves:

    • Opening a secured credit card (if you can’t qualify for an unsecured card) and using it responsibly — small purchases, paid in full each month.
    • Becoming an authorized user on a trusted family member’s well-managed credit card account.
    • Taking out a credit-builder loan (offered by many credit unions and community banks), which holds the loan proceeds in a savings account while you make payments that are reported to all three bureaus.
    • Paying down existing credit card balances to lower your credit utilization ratio — often the fastest way to raise a FICO score.
    • Disputing and removing inaccurate negative items from your credit reports across all three bureaus — errors, outdated information, duplicate accounts, and items that should have fallen off.
    • What it does: Builds genuine credit history that appears on all three bureau reports and is scored by both FICO and VantageScore.
    • Cost: Varies — secured cards require a deposit (refundable), credit-builder loans involve small interest, and professional credit repair services have their own fee structures.
    • Score affected: Both FICO and VantageScore, across all three bureaus.
    • Lender visibility: Full — this is the credit history lenders actually see and use.
    • Best for: Everyone serious about building credit that matters. This is the foundation; Boost and rent reporting are supplements.

    Which should you use?

    There’s no rule saying you can only pick one. A smart credit-building strategy might include all three:

    • Start with traditional credit building — open a secured card or credit-builder loan, keep utilization low, and make every payment on time.
    • Add rent reporting if you’re a renter, to get your largest monthly payment working for you across all three bureaus.
    • Add Experian Boost as a free supplement, understanding that it only helps your Experian VantageScore.

    The important thing is to prioritize correctly. If you have limited time and resources, traditional credit building and credit report repair should come first. They address the scores lenders actually use and the root causes of credit problems. Boost is a nice-to-have, not a must-have.

    How to Use Experian Boost (If You Want To)

    If you’ve read through the pros and cons and decided Experian Boost is worth trying — maybe you have a thin file, or you’re curious to see if it helps your VantageScore — here’s how to set it up.

    Step 1: Create a free Experian account

    Go to and sign up for a free account. You do not need to subscribe to Experian’s paid credit monitoring service to use Boost. The free account gives you access to your Experian credit report and VantageScore, plus the Boost feature.

    Step 2: Navigate to Experian Boost

    Once logged in, look for the Experian Boost option in your dashboard. It’s typically prominently featured, since Experian promotes it as a key free benefit.

    Step 3: Connect your bank account

    You’ll be prompted to connect the bank account(s) where you pay your eligible bills. The connection is made through a secure data aggregation service. You’ll log in to your bank through the aggregator’s interface (not directly through Experian), grant permission for transaction data to be shared, and return to Experian.

    Before you do this: Take a moment to review Experian’s privacy policy and the aggregation provider’s policy. Make sure you understand what data is being accessed and how it’s used. If you’re not comfortable, don’t proceed — and that’s a perfectly valid decision.

    Step 4: Review identified payments

    Experian scans your connected account(s) for eligible payments and presents them to you. You’ll see a list of recognized utility, telecom, streaming, and (if applicable) rent payments. Review the list for accuracy.

    Step 5: Select which payments to add

    You choose which categories and which specific payments to include. You don’t have to add everything — if there’s a payment you’d rather not include for any reason, you can exclude it.

    Step 6: Confirm and see your new score

    Once you confirm your selections, Experian adds the eligible payment history to your Experian credit file and recalculates your VantageScore. You’ll see your updated score within seconds or minutes.

    Step 7: Monitor and manage

    After setup, Experian Boost continues to scan your connected accounts for new eligible payments over time, adding them as they occur. You can log in to your Experian account at any time to:

    • See your current boosted score.
    • Add or remove connected bank accounts.
    • Change which payment categories are included.
    • Disconnect entirely (which removes the Boost-added history from your file).

    A few practical tips

    • Connect the account where you actually pay bills. If you pay utilities from a checking account but keep savings in a different bank, connect the checking account.
    • Make sure your transactions are identifiable. If your bank’s transaction descriptions are clear (showing the biller’s name), Boost will work better. If they’re cryptic, recognition may suffer.
    • Don’t expect miracles. Check your score, note any change, and keep your expectations grounded. If you see a bump, great. If not, you haven’t lost anything but a few minutes.
    • Remember what you’re looking at. The score in your Experian dashboard is your Experian VantageScore — not your FICO score. Don’t assume a lender will see the same number.

    Should You Bother? Our Honest Verdict

    We’ve covered a lot of ground, so let’s bring it together into a clear, honest assessment.

    Experian Boost is a legitimate, free tool that can help certain people in certain situations. It is not a scam, and it is not useless. But it is also not the credit-building breakthrough its marketing sometimes implies. Here’s our balanced take:

    Use it if:

    • You have a thin credit file or no credit score, and you want to generate some positive payment data quickly and for free.
    • You’re curious about your VantageScore and want to see if your utility and streaming payments can nudge it up.
    • You’re applying with a specific lender you’ve confirmed uses VantageScore and pulls from Experian.
    • You’re comfortable connecting your bank account and sharing transaction data with a third-party aggregation service.
    • You understand that the score it raises isn’t the one most lenders use, and you’re okay with that.

    Skip it (or don’t prioritize it) if:

    • You’re applying for a mortgage — it won’t help, and your time is better spent on FICO-moving actions.
    • You have a thick, established credit file — the incremental benefit is negligible.
    • Your FICO scores are already strong — Boost won’t change your lending outcomes.
    • You’re uncomfortable sharing bank transaction data — the privacy trade-off isn’t worth a potentially zero benefit.
    • You’re looking for a substitute for real credit repair — Boost doesn’t fix errors, remove negative items, or address utilization. Those are the factors that actually move the scores lenders use.

    Our overall verdict

    Experian Boost is a low-risk, low-reward tool that’s worth trying if you fit the profile of someone it tends to help — but it should never be your primary credit-building strategy. Think of it as a complement to, not a replacement for, the fundamentals: accurate credit reports across all three bureaus, low credit utilization, a mix of account types, and a long history of on-time payments.

    If your credit score is holding you back from your goals — buying a home, financing a car, getting approved for a better credit card — the path to real improvement runs through your FICO scores and your reports at all three bureaus. That’s where our work at credit-repair.com focuses, and that’s where we’d encourage you to focus too.

    Common Myths About Experian Boost

    Let’s clear up some of the most common misconceptions we encounter.

    Myth 1: “Experian Boost raises your credit score with all lenders.”

    False. Experian Boost only raises your Experian VantageScore 3.0. It does not affect your FICO scores (any version), and it does not affect your Equifax or TransUnion reports. Most lenders — especially mortgage lenders — use FICO scores, not VantageScore. Your boosted score is real, but it’s not the score most lenders see.

    Myth 2: “Experian Boost can help you get a mortgage.”

    False, in practical terms. Mortgage lenders use classic FICO scores (FICO 2, 4, and 5) from all three bureaus. Experian Boost data does not flow into these scores. If you’re counting on Boost to help you qualify for a mortgage or get a better rate, you’ll be disappointed. Focus on paying down debt, disputing errors, and building genuine credit history instead.

    Myth 3: “Experian Boost is a scam.”

    False. Experian Boost is a legitimate, free feature offered by Experian. It does what it says it does — adds eligible payment history to your Experian file and recalculates your VantageScore. The issue isn’t deception; it’s that the score it affects has limited relevance to most lending decisions. There’s a difference between “it doesn’t do what the marketing implies” and “it’s a scam.” Boost is the former, not the latter.

    Myth 4: “Experian Boost can hurt your credit score.”

    Mostly false, with a caveat. Boost is designed to add only positive (on-time) payment history. It does not report late or missed utility payments. However, if you have an underlying utility account that goes to collections, that collection can be reported to the credit bureaus through normal channels — but that’s the collection agency reporting it, not Experian Boost. Boost itself doesn’t add negative data. Additionally, connecting your bank account and using Boost does not generate a hard inquiry, so there’s no score impact from the setup process.

    Myth 5: “If you disconnect, the boost is permanent.”

    False. If you disconnect your bank account or opt out of Experian Boost, the payment history added through Boost is removed from your Experian file. Your VantageScore will revert to what it was before Boost (or to whatever it would be based on your current credit file without the Boost data). The benefit is only present while Boost is active.

    Myth 6: “Experian Boost works the same as adding a tradeline.”

    False. A tradeline (like a credit card or loan) appears on your credit report as an account with a balance, limit, payment history, and status. It’s reported to the bureaus by the lender and scored by both FICO and VantageScore. Experian Boost, by contrast, adds payment history data to your Experian file without creating a traditional tradeline, and it’s only scored by VantageScore. The two are fundamentally different mechanisms with different levels of lender visibility.

    Myth 7: “Experian Boost counts all your bills.”

    False. Only specific categories are eligible: utilities (electric, gas, water, trash), telecom (phone, internet, cable), streaming services, and some rent payments. Insurance, groceries, gym memberships, subscriptions boxes, medical bills, tuition, taxes, and many other common payments do not count. Even within eligible categories, the payment must be identifiable in your bank transaction data.

    Frequently Asked Questions

    1. Does Experian Boost work for mortgage approvals?

    No, not in any practically meaningful way. Mortgage lenders use FICO scores (specifically FICO 2, FICO 4, and FICO 5) from all three credit bureaus. Experian Boost only affects your Experian VantageScore 3.0, which is not the score mortgage lenders use. If you’re preparing for a mortgage, focus on the factors that actually move your FICO scores: paying down credit card balances, disputing inaccurate items on your credit reports, and ensuring all your accounts are current. A across all three bureaus is a far better use of your time than Boost if a mortgage is your goal.

    2. Is Experian Boost really free?

    Yes. Experian Boost is a free feature available with a free Experian account. You don’t need to subscribe to Experian’s paid credit monitoring or identity theft protection services to use it. Experian offers those paid services alongside Boost, but Boost itself has no cost. Just be aware that Experian may market its paid products to you while you’re using the free feature.

    3. Can Experian Boost lower your credit score?

    No, not directly. Boost is designed to add only positive payment history. It doesn’t report late or missed payments on your utilities or streaming services. The setup process doesn’t generate a hard inquiry, so there’s no initial score dip. However, if an underlying utility account goes to collections, that collection can appear on your credit report through normal reporting — but that’s the collection agency’s action, not Boost’s. Also, if you disconnect from Boost, the added history is removed and your score may drop back to its pre-Boost level.

    4. How many points does Experian Boost add?

    It varies widely. Experian reports an average increase of about 13 points on the Experian VantageScore 3.0. But “average” obscures the range: some users see 20+ points (especially those with thin files), some see 3–10 points, and some see zero. Your result depends on your existing credit profile, how many eligible payments Experian finds, and how the VantageScore model weights the new data. There’s no guarantee of any specific increase.

    5. Does Experian Boost affect Equifax and TransUnion?

    No. Experian Boost only modifies your Experian credit file. Your Equifax and TransUnion reports are completely unaffected. Since many lenders pull reports from two or all three bureaus and use the middle or lowest score, boosting only Experian often doesn’t change the score a lender actually uses — even if that lender uses VantageScore.

    6. What bills count toward Experian Boost?

    Eligible categories include electric, gas, water, and trash utilities; mobile phone, landline, internet, and cable telecom services; streaming services like Netflix, Hulu, Disney+, HBO Max, and Spotify; and some rent payments (through participating platforms). Payments must be identifiable in your connected bank account transactions. Insurance, groceries, gym memberships, medical bills, tuition, taxes, and many other common payments do not count.

    7. Is it safe to connect my bank account to Experian Boost?

    It’s reasonably safe, but it does involve data sharing you should be aware of. Experian uses a third-party data aggregation service (the same type of technology used by budgeting apps like Mint or YNAB) to access your bank transaction data. The connection uses bank-level encryption, and the aggregation provider is a regulated entity. However, you are granting access to your transaction data to an additional party, and that access remains in place until you disconnect. We recommend reading Experian’s privacy policy and the aggregation provider’s policy before connecting, so you understand exactly what’s accessed, how it’s stored, and how it’s used. If you’re not comfortable with that level of data sharing, it’s perfectly fine to skip Boost.

    8. Should I use Experian Boost while also working with a credit repair company?

    You can, but keep your priorities straight. Experian Boost is a free, low-risk supplement that won’t interfere with credit repair efforts. It won’t conflict with disputes, doesn’t add hard inquiries, and doesn’t affect your FICO scores (which is where credit repair typically focuses). If you want to enable Boost for the possible VantageScore benefit while also pursuing professional credit repair, there’s no harm in doing both. Just remember that the real score gains — the ones that change your lending outcomes — come from the credit repair work (fixing errors, removing inaccurate negatives, optimizing utilization), not from Boost. Treat Boost as a bonus, not as the main event.

    The Bottom Line: Real Score Gains Come From Real Credit Repair

    Experian Boost has its place. For the right person — someone with a thin file, no score, or a specific VantageScore-using lender — it’s a free, quick, low-risk way to add a few points or become scoreable for the first time. We don’t discourage anyone in that situation from trying it.

    But we’d be doing you a disservice if we left it there without the full context. The credit score that matters most in your financial life — the one that determines whether you get the mortgage, the auto loan, the apartment, the better interest rate — is almost always a FICO score, and it reflects the data on all three of your credit reports, not just Experian’s. Experian Boost doesn’t touch that score or those reports. It operates in a parallel lane that most lenders don’t look at.

    Real, lasting credit improvement comes from:

    • Accurate credit reports. Studies have found that a significant percentage of credit reports contain errors — some minor, some serious enough to drag down a score by dozens of points. Disputing and removing inaccurate negative items across all three bureaus (Experian, Equifax, and TransUnion) is one of the most effective ways to raise the scores lenders actually use.
    • Lower credit utilization. If you’re carrying high balances on your credit cards relative to your limits, paying those down can produce rapid FICO score improvements — often more meaningful and more broadly visible than anything Experian Boost can do.
    • A history of on-time payments on real tradelines. Credit cards, installment loans, and other reported accounts form the backbone of your credit profile. Their payment history is scored by both FICO and VantageScore and appears at all three bureaus.
    • Time and patience. Negative items age off your report (most after seven years), and the older your positive history, the stronger your score. There are no shortcuts around the passage of time.
    • Professional guidance when you need it. If your credit reports have errors, collections, outdated items, or other negative marks you’re not sure how to address, working with a reputable, FCRA-compliant credit repair firm can help you navigate the dispute process effectively and make sure your rights under federal law are exercised fully.

    We can help

    At , we offer a free credit audit across all three major bureaus. We’ll review your Experian, Equifax, and TransUnion reports, identify inaccuracies and outdated items, and give you a clear picture of what’s actually affecting your FICO scores — the scores lenders use.

    Our approach is attorney-backed and fully FCRA-compliant. We don’t make empty promises or offer quick fixes. We dispute inaccuracies, negotiate with creditors, and build a customized repair plan tailored to your goals — whether that’s buying a home, financing a car, or simply getting your financial house in order. And because we believe credit repair should also be credit education, we equip you with the knowledge to keep your credit strong long after our work together is done.

    Experian Boost might give you a few points on a score most lenders don’t use. A real credit audit can find and fix the errors holding back the scores they do. If you’re serious about improving your credit — not just the number in one dashboard, but the numbers that actually open doors — we’d be honored to help.

    Get your free credit audit at credit-repair.com →

    Disclaimer: This article is for educational purposes and does not constitute legal or financial advice. Experian Boost is a product of Experian and is not affiliated with credit-repair.com. VantageScore is a registered trademark of VantageScore Solutions, LLC. FICO is a registered trademark of the Fair Isaac Corporation. Individual credit results vary based on your unique credit profile and the specific factors affecting your scores.

    Related reading:

  • How to Ask for a Credit Limit Increase (Without Hurting Your Score)

    How to Ask for a Credit Limit Increase (Without Hurting Your Score)

    Related guides: understand the difference between hard vs soft inquiries so you know what a limit request triggers, learn how to remove hard inquiries if you get too many, see why your credit utilization ratio is the number that benefits most, and follow the full 7-step guide to improving your score.

    What Is a Credit Limit Increase — and Why It Can Help Your Score

    A credit limit increase is exactly what it sounds like: your card issuer raises the maximum balance you’re allowed to carry on your credit card. If you had a $5,000 limit and your bank bumps it to $7,500, you now have access to an additional $2,500 of available credit.That sounds simple enough. But what actually matters for your credit score is not the limit itself — it’s what the limit does to your credit utilization ratio.

    The Utilization Lever: The Fastest Score Boost Available

    Your credit utilization ratio is the percentage of your available revolving credit that you’re currently using. It’s one of the most influential factors in your FICO and VantageScore calculations — utilization is roughly 30% of your FICO score, making it the second most important factor after payment history.

    Here’s the math:

    • Before increase: You have a $5,000 limit and a $1,500 balance. Utilization = $1,500 ÷ $5,000 = 30%
    • After increase: Your limit rises to $7,500. Same $1,500 balance. Utilization = $1,500 ÷ $7,500 = 20%

    You didn’t pay down a single dollar, but your utilization dropped from 30% to 20% — and that can move your score noticeably within a billing cycle or two.

    The general rule: Keep utilization below 30% to avoid score damage. Below 10% is ideal for maximizing your score. The lower, the better — but you don’t need to hit 0%.

    Why a Limit Increase Is a Shortcut to Lower Utilization

    You have two ways to lower your utilization:

    • Pay down your balance — effective, but requires cash you may not have right now.
    • Raise your credit limit — free, instant once approved, and doesn’t require paying down a dime (though you absolutely should keep paying down debt).

    For someone carrying a balance they can’t immediately eliminate, a credit limit increase is the fastest lever available to improve utilization and, by extension, their score. No new account needed, no credit mix disruption, no inquiry if done as a soft pull.

    Other Benefits Beyond Utilization

    A higher limit also:

    • Improves your emergency flexibility. If an unexpected expense hits — a medical bill, a car repair — you have more room to absorb it without maxing out a card.
    • Helps with larger planned purchases. Buying furniture, booking travel, or covering a business expense without crossing 30% utilization keeps your score protected during the billing cycle.
    • Signals trust from your issuer. A higher limit is a vote of confidence from your bank. It can make future credit applications easier because other lenders see that your current creditor trusts you with more.

    But — and this is the part most guides gloss over — the benefit only holds if your spending stays the same. We’ll come back to that in detail. First, the question everyone asks first.

    Will It Hurt Your Score?

    This is the single most common question, and the honest answer is: it depends on whether your issuer runs a hard pull or a soft pull when reviewing your request.

    Hard Pull vs. Soft Pull: The Core Distinction

    Hard Inquiry (Hard Pull) Soft Inquiry (Soft Pull)
    Visible to lenders? Yes — shows on your credit report for 2 years No — only you can see it
    Affects your score? Yes — typically 1–5 points, fades in 6–12 months No effect at all
    Triggered by? New credit applications, some limit increase requests Account reviews, pre-approvals, your own credit checks
    Why it matters here A hard pull can temporarily lower your score A soft pull is invisible to your score

    A hard pull tells the credit bureaus a lender is evaluating you for new or expanded credit. Multiple hard pulls in a short window can signal risk-seeking behavior and compound the score impact. A soft pull is an internal review — your issuer checks your existing account standing, and it leaves no trace visible to other lenders.

    The Critical Move: Ask Before You Request

    Before you submit any credit limit increase request, find out whether your issuer will run a hard or soft inquiry. This single question can save you from an unnecessary score dip.

    How to find out:

    • Check your issuer’s policy online. Many banks publish their hard-pull vs. soft-pull policy for limit increases in their help center or terms.
    • Call customer service and ask directly. A straightforward question — “If I request a credit limit increase, will it result in a hard inquiry on my credit report?” — usually gets a straight answer.
    • Look at your online account. Some issuers show a pre-qualified increase offer with language like “this won’t affect your credit score,” which signals a soft pull.

    If your issuer runs a hard pull and your score is already in delicate shape, consider waiting until you’ve built a stronger profile — or request an increase from an issuer that uses soft pulls first.

    Does a Credit Limit Increase Hurt Your Score? The Full Picture

    Assuming a soft pull, the request itself does not hurt your score. And because the increase lowers your utilization, it typically helps your score — sometimes within the same billing cycle once the new limit reports to the bureaus.

    Assuming a hard pull, you may see a small dip (1–5 points) from the inquiry. That dip usually fades within 6–12 months. The utilization improvement from the higher limit, however, continues to help you as long as you keep balances low. In most cases, the net effect over a few months is positive — but the short-term dip is real and worth planning around if you’re applying for a mortgage or auto loan in the next 60 days.

    Bottom line: A soft-pull increase is essentially free score upside. A hard-pull increase is a small short-term cost for a longer-term utilization benefit — worth it unless you have a major credit application imminent.

    Automatic vs. Request-Initiated Increases

    Not every credit limit increase comes from you asking. There are two paths, and it helps to understand both.

    Automatic Credit Limit Increases

    Many issuers periodically review accounts and grant increases on their own — no request from you required. This is especially common:

    • After 6–12 months of on-time payments on a new account
    • When your income or credit profile improves and the issuer’s internal models flag you as eligible
    • On cards designed for credit building, where automatic increases are part of the product’s progression

    Automatic increases are virtually always soft pulls — the issuer is reviewing an existing relationship, not evaluating you for new credit. They’re the safest form of increase because there’s no inquiry and no action required from you.

    How to encourage automatic increases

    You can nudge this process along without ever making a request:

    • Pay on time, every time. Payment history is the single biggest signal issuers use.
    • Use the card regularly. A dormant card gives the issuer little reason to extend more credit. Modest, consistent usage — paid off monthly — shows active, responsible use.
    • Keep utilization low. Issuers see your balance-to-limit ratio. A card consistently near its max signals risk, not readiness for more credit.
    • Update your income when it rises. Many issuers let you update your income in the app or online portal. A higher income on file improves the case for an automatic bump.

    Request-Initiated (Customer-Initiated) Increases

    This is the path where you actively ask for more credit — through your online account, the mobile app, or by calling customer service. Request-initiated increases are where the hard-pull vs. soft-pull question becomes critical, because the issuer’s policy varies and you’re the one triggering the review.

    When to choose which path

    Situation Recommended Path
    You’re in no rush and your profile is strengthening Wait for an automatic increase — zero risk, zero effort
    You need the increase soon (utilization, planned purchase) Request it — but confirm soft-pull policy first
    Your issuer is known for soft-pull requests Request freely when your account is in good standing
    Your issuer runs hard pulls on requests Weigh the short-term dip against the utilization benefit
    You’re applying for a mortgage in the next 60 days Hold off on any request that triggers a hard pull

    Both paths achieve the same result — a higher limit and lower utilization. The difference is control: automatic increases happen on the issuer’s timeline, request-initiated ones happen on yours.

    When to Ask for a Credit Limit Increase

    Timing matters. Asking too early or at the wrong moment gets you a denial, and denials can sting — not because they directly hurt your score (they don’t, the inquiry does that), but because they waste a hard pull if your issuer runs one. Here’s when the conditions are right.

    Your account has been open at least 6 months

    Most issuers want to see a track record before extending more credit. Six months of active use and on-time payments is the practical minimum for a request-initiated increase to have a real chance. Some issuers prefer 12 months, especially on newer relationships.

    If your card is brand new, focus on building the payment history first. Automatic increases often arrive around the 6–12 month mark anyway.

    Your payment history is clean

    A single recent late payment can sink an increase request. Issuers want to see consistent on-time payments — ideally 6+ consecutive months without a single late or missed payment. If you’ve had a slip-up, give it six months of flawless history before asking.

    Your utilization is already reasonably low

    This is counterintuitive but important: issuers look at your current utilization when deciding whether to extend more credit. If you’re maxed out or hovering above 50%, the issuer sees you as already stretched. They may deny the increase or grant only a small one.

    Target utilization before you ask: 30% or lower. Below 10% is even better. This signals that you’re managing the credit you already have responsibly — which makes the issuer comfortable giving you more.

    Your income has increased

    If you’ve gotten a raise, changed jobs for higher pay, or added a side income, this strengthens your case. Higher income improves your debt-to-income ratio from the issuer’s perspective and gives them a concrete reason to extend more credit.

    Most online increase request forms ask for your current annual income. Be honest — and be accurate. We’ll cover what counts as income and what to say in a later section.

    You have few recent hard inquiries

    If your credit report shows multiple hard inquiries in the last 6 months, issuers may read that as credit-seeking behavior and get cautious. A clean inquiry history (zero or one recent hard pull) gives you the best shot.

    Your credit score has improved since you opened the card

    If you’ve moved from a 660 to a 720 since account opening, that’s a strong signal to the issuer that your creditworthiness has grown. Many issuers monitor your score and may even send you a pre-qualified increase offer when you cross certain thresholds.

    The Quick Checklist

    Before you request an increase, confirm:

    • Account open 6+ months
    • 6+ consecutive on-time payments
    • No recent late payments
    • Current utilization under 30% (ideally under 10%)
    • Income is current and accurate with the issuer
    • Few or no hard inquiries in the last 6 months
    • No major credit applications (mortgage, auto loan) in the next 60 days

    If you can check most of these boxes, you’re in good shape to ask.

    How to Prepare Before You Ask

    Preparation is where you either set yourself up for a “yes” or a polite denial. The work you do in the week before your request can be the difference.

    1. Pay Down Your Balance First

    This is the highest-leverage move. Even a partial paydown before you request an increase:

    • Lowers your utilization at the moment the issuer reviews your account
    • Shows recent responsible behavior
    • Improves the debt-to-income picture if you’re carrying the balance into the next statement

    You don’t need to pay the card to zero — but bringing a 45% utilization down to 20% before you ask meaningfully improves your odds.

    2. Update Your Income and Employment Information

    Most issuers let you update your income in the online account or app. If you’ve had a raise or a new job since you last updated it, do this before requesting the increase. A higher income on file is a direct, concrete reason for the issuer to extend more credit.

    Be accurate. Include all income you’re allowed to count — we’ll detail this in the next section. Do not inflate. Issuers can verify income in some cases, and misrepresenting income on a credit application can have serious consequences.

    3. Check Your Credit Report for Errors

    Pull your credit report from all three bureaus (Equifax, Experian, TransUnion) at AnnualCreditReport.com — you’re entitled to free reports weekly under federal law. Look for:

    • Accounts you don’t recognize (possible fraud or mixed file)
    • Late payments that are actually on time
    • Balances reported incorrectly
    • Closed accounts showing as open

    Errors can suppress your score and make issuers nervous. If you find any, dispute them before requesting an increase. This is also where a credit repair firm — like ours — can help: we audit all three bureaus, identify inaccuracies, and dispute them through the proper FCRA channels.

    Internal link placeholder:

    4. Know Your Current Limit and Balance

    It sounds obvious, but have the exact numbers in front of you when you call or fill out the online form. Issuers sometimes ask what limit you’re hoping for, and a realistic request — based on your current limit, balance, and income — reads as informed and reasonable.

    5. Confirm Your Issuer’s Hard-Pull Policy

    We covered this above, but it’s worth repeating as a preparation step: before you click “request increase” or call, confirm whether your issuer runs a hard or soft inquiry. This is the single piece of information that determines whether the request carries any score risk.

    Preparation Checklist

    • Balance paid down to under 30% utilization (ideally under 10%)
    • Income updated in your online account
    • Credit reports reviewed for errors
    • Current limit, balance, and target increase number written down
    • Issuer’s hard-pull vs. soft-pull policy confirmed

    How to Ask for a Credit Limit Increase

    You have three main channels: online, through the mobile app, or by phone. Each has trade-offs.

    Option 1: Online Account (Fastest, Most Common)

    Log in to your card issuer’s website and navigate to your card’s account services or manage card section. Look for an option like “Request Credit Limit Increase” or “Increase Credit Line.”

    What you’ll typically need to provide:

    • Current annual income (household income if allowed)
    • Employment status (employed, self-employed, retired, etc.)
    • Monthly housing payment (rent or mortgage)
    • Sometimes: reason for the increase (optional in most cases)

    The online form usually returns a decision instantly or within a few business days. Some issuers do a soft pull on the spot; others follow up with a more detailed review.

    Option 2: Mobile App (Convenient, Same Process)

    Most major issuers offer the same increase request flow in their mobile app as on the website. The app route is functionally identical — same questions, same decision timeline. Use it if that’s where you manage your cards.

    Option 3: Phone Call (Most Flexible)

    Calling customer service — the number on the back of your card — gives you a conversation with a real human. This is the best option if:

    • Your situation is nuanced (recent income change, self-employment, recent move)
    • You want to ask about the hard-pull policy before submitting
    • You’ve been denied online and want to request a reconsideration
    • You prefer to explain your request in words rather than forms

    What to say on the call

    Here’s a straightforward script you can adapt:

    “Hi, I’d like to request a credit limit increase on my [card name] card. Before we proceed, can you tell me whether this will result in a hard inquiry on my credit report?”

    If the answer is “yes, hard pull” and you’re not comfortable with that, you can decline to proceed and end the call. No inquiry happens until you submit.

    If the answer is “no, soft pull” or you’re fine with the hard pull, continue:

    “My account has been open for [X] months, I’ve made all on-time payments, and my income is now [annual income]. My current limit is [current limit], and I’d like to request an increase to [target limit].”

    Keep it factual. The representative isn’t making a personal judgment — they’re entering your information into a decision system. Honest, clean data is what helps you.

    What Happens After You Submit

    • Instant approval: You’ll see the new limit immediately. It may take one billing cycle to report to the bureaus.
    • Pending review: The issuer needs a few business days to evaluate. You’ll get a letter or email with the decision.
    • Denial: You’ll receive a reason — we’ll cover what to do next in a later section.

    Which Channel Should You Use?

    Channel Speed Best For
    Online account Instant to a few days Straightforward requests, clean profiles
    Mobile app Same as online Convenience, same process
    Phone call A few minutes on the line Nuanced situations, asking about hard-pull policy, reconsideration

    For most people with a straightforward profile, the online or app route is fine. If you want to confirm the hard-pull policy before risking an inquiry, call first.

    What to Say When Asked About Income and Employment

    The income question is where people get the most nervous — and where mistakes happen. Here’s how to handle it correctly.

    What You Can Include as Income

    Under the Credit CARD Act, issuers can ask for your gross income — your income before taxes. For most applicants, this includes:

    • Wages, salary, and tips from your primary job
    • Self-employment income (net business income, after business expenses but before personal taxes)
    • Side income — freelance, gig work, part-time jobs
    • Investment income — dividends, interest, rental income
    • Retirement income — pensions, Social Security, distributions from retirement accounts
    • Alimony, child support, separate maintenance (only if you want it considered — you’re not required to disclose these)

    If you’re 21 or older, you can also include household income — income from your spouse or partner that you have reasonable access to for paying the card. If you’re under 21, you can generally only count your own income.

    What You Cannot Include

    • Income you don’t actually have access to — don’t count a roommate’s income unless there’s a genuine shared-finances arrangement
    • Projected or speculative income — future raises, hypothetical bonuses, income you haven’t earned yet
    • Inflated numbers — this is the big one. Overstating income on a credit application is considered misrepresentation and can lead to account closure, and in serious cases, legal consequences

    How to Report Employment Status

    Be honest and specific:

    • Employed full-time — standard salaried or hourly work
    • Self-employed — you run your own business or work as an independent contractor
    • Part-time — if you work part-time, say so; the income number matters more than the label
    • Retired — include retirement income (pensions, Social Security, distributions)
    • Unemployed — if you have no income, be honest. You may be declined, but misrepresenting employment creates bigger problems
    • Student — if you’re 21+, you can include household income if applicable

    If Your Income Has Recently Changed

    If you’ve recently gotten a raise, changed jobs, or started a side business, update your income with the issuer before requesting the increase. Most online portals have an “update income” option in account settings. The updated figure is what the issuer will use when evaluating your request.

    If your income has gone down — a job loss, a business downturn — be thoughtful. Requesting an increase with reduced income is likely to fail and may flag your account for a limit decrease or account review. In that situation, focus on paying down balances and waiting for automatic increases rather than requesting one.

    The Bottom Line on Income

    Be accurate, be inclusive of what you’re allowed to count, and update it before you ask. The income figure is one of the few inputs you fully control — make sure it’s current and honest.

    How Much of an Increase Should You Request?

    This is a judgment call, and there’s no perfect formula — but there are sensible guidelines.

    The General Range

    Most people request an increase of 10% to 25% above their current limit. Some issuers allow you to request more, but large jumps draw more scrutiny and may trigger a manual review or a hard pull where a smaller request might have been a soft pull.

    Examples:

    • Current limit $5,000 → request $5,500 to $6,250 (10–25%)
    • Current limit $10,000 → request $11,000 to $12,500 (10–25%)
    • Current limit $2,000 → request $2,500 to $3,000 (25–50% — smaller limits have more flexibility)

    For lower-limit cards, issuers are often more generous with the percentage because the absolute dollar amounts are small.

    How to Decide Your Number

    Consider:

    • What utilization would you be at after the increase? If you carry a $1,000 balance and want to be at 10% utilization, you need a $10,000 limit. Work backward from your target utilization.
    • What does your income support? A general guideline: total credit limits across all cards shouldn’t exceed a reasonable fraction of your income. If you make $50,000 and already have $40,000 in credit limits, asking for another $10,000 may raise eyebrows.
    • What’s realistic for your account age? A 6-month-old card with a $1,500 limit is more likely to get a $500 increase than a $3,000 increase. Match your request to the maturity of the relationship.

    Should You Request a Specific Amount or Let the Issuer Decide?

    Some online forms require a specific number. Others ask whether you’d accept “an increase up to $X” or “whatever the system determines.” When in doubt:

    • Request a specific, modest number — it shows you’ve thought about it
    • Be willing to accept less — if the issuer comes back with a smaller increase, take it. A small increase still helps utilization
    • Don’t lowball yourself — requesting a $200 increase on a $5,000 limit when you could reasonably ask for $1,000 leaves utilization gains on the table

    What If You Get More Than You Asked For?

    Occasionally, an issuer grants a larger increase than requested — especially if your profile has improved significantly since account opening. If this happens, treat it the same as any increase: keep your spending steady, let utilization drop, and let the score benefit compound.

    Does Requesting a Credit Limit Increase Trigger a Hard Pull?

    We’ve touched on this throughout, but it deserves a dedicated section because it’s the most-asked question and the source of most anxiety.

    The Short Answer

    It depends on the issuer and, sometimes, on the specifics of your request. There is no universal rule. Some issuers always use a soft pull for customer-initiated increases. Some always use a hard pull. Some switch based on the size of the request, your account history, or their internal policies at that moment.

    General Patterns by Issuer

    We can share general patterns based on widespread customer experience — but policies change, and your specific request may be handled differently. Always confirm with your issuer before submitting.

    Issuer Typical Behavior for Limit Increase Requests
    Capital One Usually a soft pull for online requests; some cases may trigger a hard pull
    Chase Often a hard pull, though some account reviews are soft
    American Express Frequently a soft pull for existing customers; may be hard if additional review needed
    Discover Typically a soft pull; some requests trigger a hard pull depending on account history
    Bank of America Often a hard pull for customer-initiated requests
    Citi Mixed — some requests soft, some hard
    Wells Fargo Often a hard pull for requests

    Important: These are general patterns, not guarantees. Issuers update their policies, and your specific account situation can lead to a different outcome. The only way to know for certain is to ask your issuer directly before submitting the request.

    How to Protect Yourself

    • Call before you submit. Ask: “Will requesting a credit limit increase result in a hard inquiry on my credit report?” Get the answer, then decide.
    • Start with issuers that use soft pulls. If you have multiple cards, request increases from soft-pull issuers first — that’s free score upside with no inquiry risk.
    • Space out hard-pull requests. If you do accept a hard pull, avoid other credit applications for 6 months afterward to let the inquiry’s impact fade.
    • Don’t request increases from multiple issuers in the same week. Even soft pulls cluster on your report (visible only to you), and a burst of activity can look odd. One request at a time, with a few weeks between, is the safer rhythm.

    What If You Already Triggered a Hard Pull?

    If you requested an increase and got hit with a hard inquiry you weren’t expecting:

    • The inquiry stays on your report for 2 years but only affects your FICO score for 12 months
    • The impact is typically 1–5 points and fades over 6–12 months
    • The utilization benefit from the increase (if approved) usually outweighs the inquiry cost within a few billing cycles
    • If you were denied, you can ask the issuer to reconsider — and you can ask for the reason in writing, which you’re entitled to under the FCRA

    A single unexpected hard pull is not catastrophic. Learn which issuers run them, adjust your strategy, and move forward.

    How to ask for a credit limit increase without hurting your credit score

    What to Do If You’re Denied

    Denials happen, and they’re not the end of the road. Here’s how to respond constructively.

    1. Ask for the Reason

    Under the Equal Credit Opportunity Act (ECOA), if you’re denied credit — including a limit increase — you have the right to know why. The issuer must provide a specific reason within 30 days. Common reasons include:

    • Insufficient income — your income on file doesn’t support the increase
    • Recent late payment — a late payment within the last 6–12 months
    • High utilization on this or other accounts — you appear overextended
    • Short account history — the account hasn’t been open long enough
    • Too many recent inquiries — your credit report shows credit-seeking behavior
    • Low credit score — your score is below the issuer’s threshold for the increase

    2. Address the Specific Reason

    Once you know why, you can act:

    Denial Reason What to Do
    Insufficient income Update your income if it has risen; otherwise wait until it does
    Recent late payment Build 6+ months of on-time history before re-requesting
    High utilization Pay down balances across all cards before re-applying
    Short account history Wait 3–6 more months before asking again
    Too many recent inquiries Wait 6 months for inquiries to age before requesting
    Low credit score Focus on score-building — payment history, utilization, dispute errors

    3. Request a Reconsideration

    If you believe the denial was based on outdated or incorrect information — say, your income on file is old or the issuer didn’t account for a recent pay increase — you can call and request a reconsideration. This is a manual review where a representative looks at your case in more detail.

    Be polite, be specific, and have your facts ready:

    “I was denied a credit limit increase, and I’d like to request a reconsideration. My income on file may be outdated — my current annual income is [amount], and I’ve had [X] consecutive on-time payments since my last late payment in [month].”

    Reconsiderations don’t always work, but they cost nothing to request and sometimes flip a denial to an approval.

    4. Wait Before Re-Requesting

    If you’re denied and reconsideration doesn’t help, wait at least 3–6 months before requesting again. Repeated requests in a short window look desperate and can trigger multiple hard pulls (if your issuer runs them). Use the waiting period to strengthen your profile: pay down balances, build history, update income.

    5. Consider a Different Issuer

    If your current issuer is consistently stingy and you have a strong profile, a new card with a different issuer — with a higher starting limit — may be more productive than repeated increase requests. But only pursue this if you’re not planning major credit applications soon, since a new card adds a hard pull and lowers your average account age.

    Internal link placeholder:

    6. If Inaccurate Credit Report Information Caused the Denial

    If the denial was driven by errors on your credit report — accounts that aren’t yours, late payments that were actually on time, balances reported incorrectly — you have rights under the Fair Credit Reporting Act (FCRA). You can dispute the inaccuracies directly with the credit bureaus, and the disputed information must be verified or removed within 30–45 days.

    This is one of the core services we provide. If you suspect credit report errors are holding back your limit increase requests (or any other credit opportunity), a professional credit audit can identify and dispute those inaccuracies through the proper legal channels.

    Internal link placeholder:

    The Spending-Creep Trap: Don’t Spend More Just Because You Can

    This is the section that most credit guides skip — and it’s the one that matters most for your long-term financial health.

    The Trap Explained

    Here’s what happens to a lot of people after a limit increase:

    • They had a $5,000 limit and carried a $1,500 balance (30% utilization).
    • They get an increase to $8,000. Utilization drops to ~19% — score starts to rise.
    • A few weeks later, they notice the extra room. They book a trip. They make a larger purchase than usual. They stop watching the balance as closely because “there’s more headroom.”
    • Six months later, the balance is $3,000. Utilization is back to 37.5% — higher than before the increase.
    • Their score is lower than it was before they asked.

    The limit increase that was supposed to help their score actively hurt it — not because the increase was bad, but because the spending behavior changed.

    Why This Happens

    Psychologists call this credit limit inflation bias — when your available credit rises, your mental “comfortable balance” rises with it. The $1,500 that used to feel like “a lot” now feels manageable because there’s $6,500 of headroom above it.

    This isn’t a character flaw. It’s a documented behavioral pattern, and the credit system is built around it. Issuers increase limits partly because they know a meaningful percentage of customers will spend more. That’s how they earn interest.

    How to Avoid the Trap

    The fix is simple in principle, harder in practice: treat the new limit as if it doesn’t exist for spending purposes.

    Practical tactics:

    • Set a personal spending cap well below your new limit — for example, keep your balance under 10% of the new limit regardless of headroom.
    • Keep paying in full each month if you weren’t carrying a balance before. The increase is for utilization and emergencies, not for routine spending.
    • Automate your payments so you never drift into carrying a larger balance out of convenience.
    • Set balance alerts. Most issuers let you set a notification when your balance crosses a threshold you define. Set it at 20% or 30% of your limit.
    • Review your spending monthly. A quick check — “Am I spending more than I was before the increase?” — catches creep early.

    What the Increase Is Actually For

    A credit limit increase is a utilization tool and an emergency buffer. It is not:

    • A license to spend more
    • A signal that you can afford more
    • Free money

    Your income and your budget determine what you can afford — your credit limit doesn’t change either of those. The increase simply lets the same spending represent a smaller fraction of your available credit, which helps your score.

    The rule that makes or breaks this strategy: Your spending stays the same. Your limit goes up. Your utilization drops. Your score rises. If your spending goes up with your limit, the whole strategy collapses.

    Common Mistakes to Avoid

    Over years of helping clients repair and build their credit, we see the same mistakes repeat. Here are the most common ones — and how to steer clear.

    1. Requesting an Increase With a High Balance

    If your utilization is above 50% when you ask, most issuers will deny you. Pay down first, ask second.

    2. Requesting From Multiple Issuers in the Same Week

    Even if all the pulls are soft, a burst of activity in a short window can look like credit-seeking. Space requests 30+ days apart.

    3. Not Confirming the Hard-Pull Policy

    This is the most avoidable mistake. A two-minute call to ask “will this be a hard inquiry?” saves you from an unexpected score dip. Always check.

    4. Overstating Income

    Inflating your income to qualify for a larger increase is misrepresentation. It can lead to account closure, repayment demands, and in serious cases, fraud investigation. Be accurate, be inclusive of what you’re allowed to count, and never inflate.

    5. Requesting Too Soon After a Late Payment

    If you’ve had a late payment in the last 3–6 months, wait until you’ve rebuilt a clean payment history. Issuers weight recent payment behavior heavily.

    6. Requesting Too Soon After Opening the Account

    A brand-new card hasn’t earned the issuer’s trust yet. Wait at least 6 months — ideally 12 — before requesting an increase.

    7. Spending Up to the New Limit

    The spending-creep trap covered above. A limit increase is a utilization tool, not a spending license.

    8. Ignoring a Denial Reason

    If you’re denied and don’t find out why, you’ll repeat the same request and get the same answer. Always ask for the reason and address it before re-requesting.

    9. Chasing Limit Increases Instead of Pay Down Debt

    A higher limit helps utilization, but paying down debt helps utilization and saves you interest and improves your debt-to-income ratio. Don’t use limit increases as a substitute for paying down what you owe.

    10. Forgetting That Utilization Has No Memory

    Here’s a quirk of the credit scoring system: utilization has no memory. If you’re at 40% this month and pay down to 8% next month, your score reflects 8% — there’s no penalty for the prior 40%. This means you can time your paydowns to statement closing dates for maximum score benefit, and you don’t need to stress about a temporary utilization spike from a planned purchase. Pay it down before the statement closes, and your score never sees it.

    Frequently Asked Questions

    How often can I request a credit limit increase?

    Most issuers allow you to request an increase every 6 months per account. Some permit requests every 3 months. Requesting more frequently than the issuer allows typically results in an automatic denial — and if the issuer runs hard pulls, that’s an unnecessary inquiry. Stick to the 6-month cadence unless your issuer explicitly allows more frequent requests.

    Does an automatic credit limit increase affect my credit score?

    An automatic increase is almost always a soft pull, so the request itself has no score impact. The higher limit lowers your utilization, which typically helps your score once the new limit reports to the bureaus (usually within one to two billing cycles).

    Can I request a credit limit increase on a secured card?

    Yes, and it’s often a smart move. Many secured cards allow increases after 6–12 months of responsible use. In some cases, a sufficient payment history and score improvement can even trigger a transition to an unsecured card, where your deposit is refunded and the card continues as a standard credit account. Check with your secured card issuer on their specific upgrade path.

    Will a credit limit increase help if I’m carrying a balance?

    Yes — and this is actually where it helps most. If you’re carrying a balance and can’t pay it down immediately, a higher limit lowers your utilization without requiring a paydown. That said, the increase is not a substitute for eventually paying off the balance. Use the score boost as breathing room while you work a paydown plan.

    Can I be denied a credit limit increase even with good credit?

    Yes. A strong credit score helps, but issuers also consider your income, account history with them specifically, overall debt load, and recent credit activity. A 760 score with a brand-new account, a recent hard pull, or inconsistent income on file can still result in a denial. The score is one input, not the whole decision.

    Does requesting a credit limit increase hurt my score if I’m denied?

    If the request triggered a hard pull, you’ll see a small, temporary score dip regardless of whether you were approved or denied. If it was a soft pull, there’s no score impact either way — denial included. The denial itself does not appear as a separate negative mark on your credit report.

    What’s the fastest way to raise my credit score using a limit increase?

    Request a soft-pull increase from an issuer that uses soft inquiries, keep your spending exactly the same, and let the new lower utilization report at the next statement closing. Many people see a score bump within 30–45 days of the new limit reporting. For the fastest possible impact, pair the increase with a paydown before the statement closes — that puts you in the strongest utilization position when the bureaus receive the update.

    Should I close a card after getting a limit increase on another card?

    Generally, no. Closing a card reduces your total available credit, which raises your overall utilization — the opposite of what you want. Even if you don’t use a card, keeping it open preserves the credit line and the account age, both of which support your score. If the card has an annual fee you can’t justify, consider asking the issuer for a product change to a no-fee version instead of closing it.

    Ready to Take the Next Step?

    A credit limit increase, done right, is one of the simplest and most effective tools for improving your credit score — no new accounts, no credit mix disruption, and often no hard inquiry at all. The strategy comes down to a few principles:

    • Time it right — 6+ months of history, clean payments, low utilization, updated income
    • Confirm the inquiry type — soft pull is free, hard pull is a small short-term cost
    • Ask for a reasonable amount — 10–25% above your current limit
    • Keep spending steady — the increase helps your score only if utilization actually drops
    • Handle denials constructively — find out why, address it, and re-request when the time is right

    But a limit increase is just one piece of a larger credit health picture. If your credit report has errors dragging your score down — accounts that aren’t yours, late payments that were actually on time, balances reported incorrectly — no amount of limit optimization will get you where you deserve to be. That’s where a professional, FCRA-compliant credit audit comes in.

    At credit-repair.com, we help individuals and families take control of their financial future through honest, results-driven credit repair. Our process includes:

    • A comprehensive audit of all three credit bureaus — Equifax, Experian, and TransUnion
    • Disputing inaccuracies through the proper FCRA channels
    • Negotiating with creditors and working to remove negative marks
    • Customized repair plans tailored to your specific goals
    • Attorney-backed, legally compliant processes — no shortcuts, no empty promises
    • Client education so you understand your credit and how to keep it strong long after the work is done

    We’re based in San Diego and serve clients nationwide. We don’t just fix your credit — we equip you with the knowledge and tools to keep it strong for life.

    Get your free credit audit today at . No hidden fees, no pressure, no quick-fix claims — just a clear, honest look at what’s on your report and a plan to improve it.

    Your credit future is worth protecting. Let’s take the first step together.

    This article is for educational purposes and does not constitute legal or financial advice. Your individual credit situation is unique — for personalized guidance, request a free credit audit and speak with our team.

  • Credit Repair Letters: What to Send and When

    Credit Repair Letters: What to Send and When

    Dive deeper into the letters that work: get the full explanation and free template for the 609 dispute letter, learn how to write a goodwill letter to remove late payments, download a cease and desist letter template to stop collector contact, and see exactly how to file a credit dispute with the bureaus.

    If your credit report has errors dragging down your score, written correspondence is the most powerful — and most legally protected — tool you have. Credit repair letters are the formal, documented way to challenge inaccurate information, request verification of debts, negotiate with creditors, and exercise your rights under federal law. But sending the wrong letter at the wrong time, or sending the right letter the wrong way, can stall your progress or even get your dispute flagged as frivolous.This master guide walks you through every type of credit repair letter, when to use each one, what to include, and a ready-to-adapt template for each. Whether you are handling the process yourself or working with an attorney-backed credit repair firm, understanding these letters puts you in control of your financial future.

    What Are Credit Repair Letters?

    Credit repair letters are formal written communications sent to credit bureaus, creditors, debt collectors, and other entities to challenge, verify, negotiate, or request information about items appearing on your credit report. They are the backbone of credit repair correspondence — the documented, legally recognized way to address errors and negative marks.

    Unlike a phone call (which leaves no paper trail) or an online dispute form (which often limits what you can say and how much evidence you can attach), a written letter creates a permanent record. That record matters because federal law gives you specific rights that are enforced through documented communication. If a bureau or furnisher fails to respond within the legally required timeframe, your letter is the proof you need to escalate the matter — to a regulator, an attorney, or a court.

    Credit repair letters serve several core purposes:

    • Disputing inaccurate information — telling a bureau or furnisher that something on your report is wrong and asking them to investigate
    • Requesting debt validation — asking a debt collector to prove a debt is yours and the amount is correct
    • Negotiating removals — asking a creditor to remove a negative mark in exchange for payment (pay-for-delete) or out of goodwill
    • Exercising disclosure rights — requesting the source documentation behind a reported item (609 requests)
    • Stopping harassment — telling a debt collector to stop contacting you (cease and desist)
    • Demanding verification details — asking a bureau how they verified an item you already disputed (method of verification)

    Each letter type has a specific legal basis, a specific recipient, and a specific timing window. Sending the right one at the right moment is what separates effective credit repair from wasted effort.

    Internal link placeholder: Learn more about and the full dispute lifecycle.

    Types of Credit Repair Letters and When to Use Each

    There are eight primary credit repair letters. Each has a distinct purpose, recipient, and timing. Below, we cover what each one is, when to use it, what to include, and a template you can adapt.

    1. Dispute Letter to a Credit Bureau

    What it is

    A dispute letter to a credit bureau is your formal request that Equifax, Experian, or TransUnion investigate and correct or remove inaccurate, incomplete, or unverifiable information on your credit report. This is the most common credit repair letter and the starting point for most disputes.

    When to use it

    Send this letter when you have reviewed your credit report and found an item that is:

    • Factually inaccurate — e.g., a late payment that was actually paid on time, an account that is not yours, a balance that is wrong
    • Incomplete — e.g., a settled account still showing a balance, a missing “closed” status
    • Outdated — e.g., a bankruptcy older than 10 years, a collection older than 7 years
    • Unverifiable — e.g., an account from a creditor that has gone out of business and cannot confirm the information

    You can dispute with one bureau, two, or all three. If the same error appears on all three reports, send a separate letter to each bureau — they do not share dispute information with each other (unless you file an “indirect” dispute through a bureau that then forwards it, but direct disputes give you more control).

    What to include

    • Your full identifying information — name, address, date of birth, Social Security number (for matching purposes)
    • A clear statement that you are disputing specific information
    • Each item you are disputing, identified clearly (account name, account number, the specific issue)
    • The reason for your dispute — be specific (“I have never been late on this account” is better than “this is wrong”)
    • Any supporting documentation — bank statements, payment records, settlement letters, identity theft reports
    • Your requested outcome — correction or deletion
    • Your signature and the date

    Template

    [Your Full Name]
    [Your Address]
    [City, State ZIP]
    [Date of Birth]
    [Social Security Number]
    [Phone Number]
    [Email]
    
    [Date]
    
    [Credit Bureau Name — Equifax, Experian, or TransUnion]
    [Bureau Address]
    [City, State ZIP]
    
    RE: Dispute of Inaccurate Information on My Credit Report
    
    Dear Sir or Madam,
    
    I am writing to dispute the following information that appears on my
    consumer credit report. I believe this information is inaccurate, incomplete,
    or unverifiable, and I am requesting a reinvestigation under the Fair Credit
    Reporting Act, 15 U.S.C. § 1681i.
    
    Item 1:
      Creditor:       [Creditor Name]
      Account Number: [Account Number]
      Issue:          [Describe the error — e.g., "Shows a late payment in
                      March 2024; the account was paid on time."]
      Requested Action: [Delete / Correct to show paid on time]
    
    Item 2:
      Creditor:       [Creditor Name]
      Account Number: [Account Number]
      Issue:          [Describe the error]
      Requested Action: [Delete / Correct]
    
    [Repeat for each disputed item.]
    
    I have enclosed the following supporting documents:
      - [Document 1 — e.g., bank statement showing on-time payment]
      - [Document 2 — e.g., settlement letter]
    
    Please investigate and correct or delete this information within the 30-day
    period required by the FCRA. If the information cannot be verified, it must
    be deleted. Please send me an updated copy of my credit report reflecting
    the results of your investigation, as required by 15 U.S.C. § 1681j.
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]
    
    Enclosures: [List of documents]

    Tip: Send one item per letter when possible. Bureaus are more likely to flag multi-item disputes as “frivolous.” See below.

    2. Dispute Letter to a Furnisher

    What it is

    A dispute letter to a furnisher is sent directly to the creditor or company that reported the information to the bureaus — not to the bureau itself. Under FCRA § 1681s-2(b), furnishers are required to investigate disputes sent directly to them about information they reported.

    When to use it

    Send this when:

    • You have already disputed with the bureau and the item came back “verified,” but you still believe it is wrong
    • You want to address the issue at the source rather than going through the bureau
    • You have documentation that the furnisher specifically will recognize (e.g., a settlement agreement with that creditor)
    • You are dealing with a furnisher that is more likely to correct its own records than to respond to a bureau inquiry

    You can send a furnisher dispute at the same time as a bureau dispute, but be aware that if the bureau contacts the furnisher as part of its investigation, the furnisher may treat the direct dispute and the bureau-initiated one together.

    What to include

    • Your account number with the furnisher
    • A clear identification of the specific information you are disputing
    • The reason for the dispute
    • Supporting documentation
    • A request to correct the information both in their own records and with all three credit bureaus
    • Your signature and date

    Template

    [Your Full Name]
    [Your Address]
    [City, State ZIP]
    [Account Number with Furnisher]
    [Phone Number]
    [Email]
    
    [Date]
    
    [Furnisher Name — e.g., Bank, Creditor, Collection Agency]
    [Furnisher Address]
    [City, State ZIP]
    
    RE: Direct Dispute of Information Reported to Credit Bureaus
    
    Dear Sir or Madam,
    
    I am writing to dispute information that your company has reported about me
    to the credit reporting agencies (Equifax, Experian, and TransUnion). Under
    the Fair Credit Reporting Act, 15 U.S.C. § 1681s-2(b), you are required to
    investigate this dispute and report your findings to me and to the credit
    bureaus.
    
    Information I am disputing:
      Account Number: [Account Number]
      Specific Item:  [e.g., "Late payment reported for June 2024"]
      Reason:         [e.g., "I paid this account on or before the due date.
                      I have enclosed my bank statement showing the payment was
                      processed on [date]."]
      Requested Action: [Correct to show paid on time / Delete the late
                        payment notation / Delete the account entirely]
    
    Please complete your investigation within 30 days and notify me of the
    results. If you determine the information is inaccurate, please correct it
    in your own records and update or delete it with all three credit bureaus
    to which you reported it.
    
    I have enclosed the following supporting documents:
      - [Document 1]
      - [Document 2]
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]
    
    Enclosures: [List of documents]

    3. Debt Validation Letter

    What it is

    A debt validation letter is sent to a debt collector to demand proof that a debt is legitimately yours and that the amount they are trying to collect is correct. This is an FDCPA right (§ 1692g), not an FCRA right.

    When to use it

    Send this letter within 30 days of receiving the first collection notice from a debt collector. The initial communication from a collector must include a validation notice telling you that you have 30 days to dispute the debt. If you send the validation letter within that window:

    • The collector must cease collection activities until they validate the debt
    • They must provide: the amount of the debt, the name of the original creditor, and verification that the debt is yours

    If you send it after the 30-day window, the collector is not legally required to stop collecting, but many will still respond — and you still have a right to request verification at any time. The 30-day window just gives you the strongest enforcement rights.

    Use this letter when:

    • A collector contacts you about a debt you do not recognize
    • A collector contacts you about a debt you believe is the wrong amount
    • A collection appears on your credit report and you want to confirm it is valid before taking action
    • You suspect the debt is past the statute of limitations or has been re-aged

    What to include

    • The collector’s account or reference number
    • A statement that you are disputing the debt and requesting validation
    • A request for: the original creditor’s name, the amount owed, proof that they are authorized to collect, and a copy of the original agreement
    • A request that they cease collection activities until validation is provided
    • Your signature and date

    Template

    [Your Full Name]
    [Your Address]
    [City, State ZIP]
    [Phone Number]
    
    [Date]
    
    [Collection Agency Name]
    [Collection Agency Address]
    [City, State ZIP]
    
    RE: Request for Debt Validation
    Account/Reference Number: [Number]
    
    Dear Sir or Madam,
    
    I received a communication from your office regarding the above-referenced
    account. I am disputing this debt and requesting validation as is my right
    under the Fair Debt Collection Practices Act, 15 U.S.C. § 1692g.
    
    I request that you provide the following:
      1. The amount of the debt, including an accounting of how it was
         calculated
      2. The name and address of the original creditor
      3. Proof that your agency is licensed and authorized to collect this
         debt in my state
      4. A copy of the original signed agreement or contract establishing
         the debt
      5. Proof that the debt is within the applicable statute of limitations
    
    Please note that under 15 U.S.C. § 1692g(b), you must cease collection of
    this debt, and of any disputed portion thereof, until you have obtained
    verification of the debt and mailed a copy of such verification to me.
    
    Until you provide this validation, I request that you:
      - Cease all collection activities
      - Do not report this debt to any credit bureau
      - Do not contact me by telephone
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]

    Note: If the collector cannot validate the debt, they must stop collecting and, under the FCRA, should not be reporting it. A failure to validate is grounds for a bureau dispute to have the collection removed.

    4. Goodwill Letter

    What it is

    A goodwill letter is a request to a creditor to remove a negative mark from your credit report as a gesture of goodwill — not because the information is inaccurate (it usually is accurate), but because you have an otherwise strong payment history and the negative item was the result of a one-time mistake or hardship.

    When to use it

    Send this when:

    • You have an otherwise excellent payment history with the creditor
    • The negative item (usually a single late payment) was caused by a documented hardship — medical emergency, job loss, natural disaster, family emergency
    • The negative item is recent enough to still hurt your score but old enough that you have demonstrated a return to good behavior
    • You have already brought the account current (if applicable)

    Goodwill letters are not legally obligated to work. The creditor is not required to remove accurate information. But many creditors — especially for long-time customers with strong histories — will make the adjustment as a courtesy. The key is showing genuine hardship, ownership of the mistake, and a pattern of otherwise responsible behavior.

    Goodwill letters work best for:

    • A single late payment on an otherwise perfect account
    • A late payment caused by autopay failure or a bank error you cannot fully document
    • A negative mark that is several months to a year old and you have since been on-time

    They generally do not work for:

    • Multiple late payments
    • Accounts that are currently delinquent
    • Recent charge-offs or collections (consider pay-for-delete instead)
    • Accounts that were never brought current

    What to include

    • An acknowledgment of the late payment and ownership of what happened
    • A brief, honest explanation of the circumstances (do not over-explain)
    • Evidence of your otherwise strong payment history (mention how long you have been a customer, how many on-time payments you have)
    • What you have done to prevent it happening again (autopay, budgeting, etc.)
    • A polite, specific request to remove the negative mark as a goodwill adjustment
    • Your signature and date

    Template

    [Your Full Name]
    [Your Address]
    [City, State ZIP]
    [Account Number]
    [Phone Number]
    [Email]
    
    [Date]
    
    [Creditor Name]
    [Creditor Address]
    [City, State ZIP]
    
    RE: Goodwill Request — Account [Account Number]
    
    Dear [Customer Relations Manager or "Sir or Madam"],
    
    I am writing to respectfully request a goodwill adjustment to my credit
    report for my account with [Creditor Name].
    
    I have been a customer since [year] and, with one exception, have maintained
    a consistent on-time payment history. In [month and year], I missed a payment
    due to [brief explanation — e.g., "an unexpected medical emergency that
    required me to be hospitalized for two weeks"]. I take full responsibility
    for this missed payment and regret that it occurred.
    
    Since that time, I have brought the account current and have made every
    payment on time for the past [number] months. I have also enrolled in
    automatic payments to ensure this does not happen again.
    
    Because this single late payment does not reflect my overall payment
    history or my commitment to my financial obligations, I am requesting that
    [creditor name] remove the late-payment notation from [month/year] from my
    account as a goodwill gesture. I am not disputing the accuracy of the
    reporting — I am simply asking for a one-time courtesy based on my
    long-standing relationship with your company.
    
    Thank you for considering my request. I value my relationship with
    [creditor name] and intend to remain a customer for years to come.
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]

    Tip: Send goodwill letters to the creditor’s customer relations or executive resolution office, not the general payment address. Search for the creditor’s goodwill or executive contacts online, or call and ask where to send a goodwill request.

    5. Pay-for-Delete Letter

    What it is

    A pay-for-delete letter is a negotiation offer to a debt collector or creditor: you agree to pay some or all of a debt, and in exchange, they agree to remove the negative item from your credit report. It is a written version of a “settlement with deletion” agreement.

    When to use it

    Send this when:

    • You have a collection or charge-off that is legitimate and that you are willing to pay
    • The account is recent enough to be hurting your score significantly
    • You want the negative mark gone, not just marked “paid” (a paid collection still hurts your score)
    • You have confirmed the debt is valid (either through validation or your own records)

    Pay-for-delete works best with collection agencies and debt buyers, less often with original creditors. Collection agencies often have more flexibility because they purchased the debt for pennies on the dollar and a clean removal is an easy concession for them to make.

    What to include

    • Your account or reference number
    • An acknowledgment that you are offering to settle the debt
    • The specific amount you are offering (full, partial, or percentage)
    • The specific condition: full deletion of the account from all three credit bureaus upon receipt of payment
    • A request for written agreement before you send payment
    • A deadline for their response
    • Your signature and date

    Critical: Get the agreement in writing first

    Never send money based on a verbal pay-for-delete promise. Always get the collector’s written agreement — on their letterhead — stating that upon receipt of your payment, they will request deletion from all three bureaus. Without written agreement, they can take your payment and leave the collection on your report, simply updating it to “paid.”

    Template

    [Your Full Name]
    [Your Address]
    [City, State ZIP]
    [Account/Reference Number]
    [Phone Number]
    
    [Date]
    
    [Collection Agency or Creditor Name]
    [Address]
    [City, State ZIP]
    
    RE: Pay-for-Delete Offer — Account [Account Number]
    
    Dear Sir or Madam,
    
    I am writing regarding the above-referenced account, which your office
    reports I owe in the amount of $[amount].
    
    I am willing to pay this debt in full [or: "I am offering to settle this
    account for $[settlement amount], which represents [percentage]% of the
    balance"] under the following condition:
    
      Upon receipt of my payment, [agency name] agrees to:
        1. Consider this account paid in full [or: settled in full]
        2. Request deletion of this account from my credit reports with
           Equifax, Experian, and TransUnion
        3. Not sell, transfer, or assign any remaining balance to another
           collection agency
        4. Not report this account to any credit bureau in the future
    
    I am not acknowledging that this debt is valid or that I owe it. I am
    making this offer solely to resolve the matter and have the item removed
    from my credit reports.
    
    If you agree to these terms, please send me a written agreement on your
    company letterhead, signed by an authorized representative, stating the
    above terms. Upon receipt of that signed agreement, I will submit payment
    within [number] business days.
    
    Please respond within 15 days of the date of this letter. If I do not
    receive a response by [date], I will consider this offer withdrawn.
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]

    Note: Not all agencies will agree to pay-for-delete, and some creditors have internal policies against it. If they refuse, you still have options: pay the debt (it will show as “paid,” which is better than unpaid) and then dispute the paid collection, or pursue a goodwill removal after the fact.

    6. Cease and Desist Letter

    What it is

    A cease and desist letter tells a debt collector to stop contacting you. Under the FDCPA (§ 1692c), once a collector receives a written cease communication request, they must stop contacting you — with two narrow exceptions: they can contact you once more to tell you they are stopping, or to inform you of a specific action they intend to take (like filing a lawsuit).

    When to use it

    Send this when:

    • A debt collector is calling repeatedly, at all hours, or at work after you asked them to stop
    • You have already validated the debt and do not owe it, or it is past the statute of limitations
    • You want all communication to be in writing only (a variation: “cease telephone contact only”)
    • You are being harassed and want to create a paper trail for an FDCPA complaint or lawsuit

    Important caveats

    A cease and desist does not:

    • Erase the debt — the collector can still report it to the bureaus or sue you
    • Stop the original creditor (the FDCPA covers third-party collectors, not always original creditors)
    • Prevent a lawsuit — in fact, if the collector can no longer call you, their only remaining option to collect may be legal action

    If the debt is within the statute of limitations, a cease and desist could prompt a lawsuit. If it is outside the statute, the collector has little leverage, and the letter is safer to send. Know your state’s statute of limitations before sending.

    What to include

    • The collector’s account or reference number
    • A clear, unambiguous statement to cease all communication (or cease telephone communication only)
    • A reference to the FDCPA
    • A statement that you will document and report any further contact
    • Your signature and date

    Template (full cease)

    [Your Full Name]
    [Your Address]
    [City, State ZIP]
    [Account/Reference Number]
    
    [Date]
    
    [Collection Agency Name]
    [Address]
    [City, State ZIP]
    
    RE: Cease and Desist All Communication
    
    Dear Sir or Madam,
    
    Pursuant to the Fair Debt Collection Practices Act, 15 U.S.C. § 1692c(c),
    I am hereby requesting that you cease all communication with me regarding
    the above-referenced account and any other alleged debt you claim I owe.
    
    This means you may not contact me by telephone, mail, email, text message,
    or any other means, except as specifically permitted by 15 U.S.C.
    § 1692c(c) — to advise me that your further collection efforts are
    terminating, or to notify me that you may invoke a specified remedy.
    
    If you continue to contact me after receiving this letter, I will document
    each contact and file a complaint with the Consumer Financial Protection
    Bureau, the Federal Trade Commission, and my state Attorney General. I
    may also pursue legal action under 15 U.S.C. § 1692k.
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]

    Template (telephone-only cease)

    RE: Cease Telephone Communication
    
    Dear Sir or Madam,
    
    Pursuant to the Fair Debt Collection Practices Act, 15 U.S.C. § 1692c(c),
    I am requesting that you cease all telephone communication with me
    regarding the above-referenced account. You may continue to communicate
    with me by mail only.
    
    Do not call my home, my place of employment, or any other telephone number.
    Any further telephone contact will be documented and reported to the
    Consumer Financial Protection Bureau.
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]

    7. 609 Disclosure Request

    What it is

    A 609 disclosure request (sometimes called a “609 letter”) is a letter invoking your right under FCRA § 1681j to receive a disclosure of all information in your credit file. The “609” refers to the section of the FCRA that grants you the right to obtain the information in your file — including the source documentation behind reported items.

    When to use it

    Some consumers and credit repair advocates use 609 letters to request the underlying documentation (original signed agreements, account applications, billing statements) that a bureau used to verify an account. The reasoning: if the bureau cannot produce the source documents, the item is “unverifiable” and must be removed.

    The legal strength of a 609 request for source documentation is debated — the FCRA does not explicitly require bureaus to provide copies of original signed agreements on request. However, requesting the full file disclosure and the sources of information can support later disputes and method-of-verification requests.

    Use this letter when:

    • You want a complete copy of everything in your file (not just the consumer report summary)
    • You are preparing to dispute an item and want to see what source documentation the bureau has
    • You want to confirm the sources of information the bureau is relying on
    • You are building a case for a method-of-verification request

    What to include

    • A request for all information in your file under FCRA § 1681j
    • A request for the source(s) of each reported item
    • A request for any documentation the bureau has on file for specific accounts
    • Your identifying information for matching
    • Your signature and date

    Template

    [Your Full Name]
    [Your Address]
    [City, State ZIP]
    [Date of Birth]
    [Social Security Number]
    
    [Date]
    
    [Credit Bureau Name]
    [Bureau Address]
    [City, State ZIP]
    
    RE: Request for Full File Disclosure Under FCRA § 1681j
    
    Dear Sir or Madam,
    
    Pursuant to 15 U.S.C. § 1681j and § 1681g, I am requesting a complete
    disclosure of all information in my consumer credit file. This includes
    all information you have collected and reported about me, whether or not
    it appears on my standard consumer report.
    
    Specifically, I am requesting:
      1. All information in my consumer file, including items not shown on
         the standard consumer report
      2. The source(s) of all information reported about me, as required by
         15 U.S.C. § 1681g(a)(2)
      3. For the following accounts, any documentation in your possession
         supporting the reporting of these items:
           - [Creditor Name], Account [Number]
           - [Creditor Name], Account [Number]
      4. The date each item was first reported and the date it was last
         updated
    
    If any of the requested information is not available or cannot be
    provided, please state so in your response and explain the reason.
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]

    Important context: A 609 letter is not a magic deletion tool. Some online services market 609 letters as a guaranteed way to remove accurate items, but the FCRA does not require bureaus to delete accurate, verifiable information simply because you requested source documents. A 609 request is best used as a supporting step — to gather information for stronger disputes and method-of-verification requests. See our section on below.

    8. Method-of-Verification Letter

    What it is

    A method-of-verification letter is sent to a credit bureau after you have disputed an item and the bureau has responded that the item was “verified” or “remains.” Under FCRA § 1681i(a)(6)(B)(iii), the bureau must provide you, upon request, a description of the procedure used to determine the accuracy and completeness of the information — including the business name, address, and telephone number of any furnisher they contacted.

    When to use it

    Send this letter:

    • Within the response window after a bureau tells you a disputed item was verified
    • When you want to know exactly how the bureau verified the item (did they just e-verify with the furnisher, or did they investigate your documentation?)
    • When you believe the bureau did a superficial verification and you want to push further
    • As a stepping stone to a stronger second dispute or a complaint

    The method-of-verification request forces the bureau to explain its process. If they cannot describe a meaningful investigation, that failure can support:

    • A complaint to the CFPB
    • A second dispute with new information
    • A claim under the FCRA for failure to conduct a reasonable investigation

    What to include

    • A reference to the original dispute (date, items disputed, bureau’s response)
    • A request for the description of the procedure used to verify the information
    • A request for the furnisher’s contact information
    • A statement that you want to review the verification method because you continue to believe the information is inaccurate
    • Your signature and date

    Template

    [Your Full Name]
    [Your Address]
    [City, State ZIP]
    [Date of Birth]
    [Social Security Number]
    
    [Date]
    
    [Credit Bureau Name]
    [Bureau Address]
    [City, State ZIP]
    
    RE: Request for Description of Reinvestigation Procedure
    Original Dispute Date: [Date]
    Items Disputed: [Creditor / Account Number]
    
    Dear Sir or Madam,
    
    On [date], I disputed the above-referenced item(s) on my credit report.
    By letter dated [date], your agency responded that the item(s) had been
    "verified" or "reviewed" and would remain on my report.
    
    Pursuant to 15 U.S.C. § 1681i(a)(6)(B)(iii), I am requesting a
    description of the procedure used to determine the accuracy and
    completeness of the information I disputed.
    
    Specifically, I am requesting:
      1. A description of the reinvestigation procedure your agency followed
      2. The business name, address, and telephone number of any furnisher
         contacted during the reinvestigation
      3. A summary of what the furnisher provided to verify the information
      4. Confirmation of whether my enclosed supporting documentation was
         reviewed as part of the reinvestigation
    
    I continue to believe the information is inaccurate, and I intend to use
    the information you provide to determine my next steps, which may include
    a complaint to the Consumer Financial Protection Bureau and/or additional
    disputes.
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]

    Strategy: Once you receive the method-of-verification response, you can often send a second dispute that includes the new information — “The bureau only performed an electronic verification with the furnisher and did not review my documentation. I am re-disputing because the verification was not a reasonable investigation.” This approach, supported by an attorney, can be effective.

    Credit repair letters for disputing credit report errors

    Best Practices for All Credit Repair Letters

    Regardless of which letter you are sending, these practices will make your correspondence more effective and protect your rights:

    1. Send via Certified Mail with Return Receipt

    This is the single most important practice. Certified mail with return receipt gives you:

    • Proof of mailing — the date you sent the letter
    • Proof of delivery — the signed green card (or electronic equivalent) showing the recipient received it
    • A timestamp that starts the legal clock (the FCRA’s 30-day investigation period, the FDCPA’s validation window, etc.)

    Without proof of mailing and delivery, a bureau or collector can claim they never received your letter, and you have no way to prove otherwise. Certified mail costs a few dollars per letter and is worth every penny.

    2. Keep Copies of Everything

    Keep a complete file for each letter you send:

    • A copy of the letter itself
    • The certified mail receipt (with the tracking number)
    • The return receipt (the signed green card)
    • Copies of any supporting documents you enclosed
    • The recipient’s response when it arrives

    Organize by recipient (bureau, furnisher, collector) and by date. If you ever need to escalate — to the CFPB, an attorney, or a court — this file is your evidence.

    3. Be Specific

    Vague letters get vague results. Instead of “this account is wrong,” say:

    “Account [number] with [creditor] shows a late payment in March 2024. I paid this account on March 12, 2024, as shown in the enclosed bank statement. The late payment notation is inaccurate and I request it be corrected or deleted.”

    Specific, factual, supported. The more precise you are, the harder it is for the recipient to dismiss your dispute as frivolous.

    4. One Item Per Letter (When Possible)

    When disputing multiple items, send a separate letter for each. This prevents the bureau from treating a multi-item letter as a “blanket dispute” and flagging it as frivolous. It also means each dispute has its own 30-day clock and its own clear paper trail.

    If you have many items (5+), it may be practical to send 2-3 per letter, but avoid sending a letter with 10+ disputed items — bureaus are known to reject these as “frivolous or irrelevant” under FCRA § 1681i(a)(3).

    5. Keep a Log

    Maintain a simple log — a spreadsheet or notebook — tracking every letter you send:

    Date Sent Recipient Letter Type Account/Item Certified Mail # Response Due Response Received Outcome
    8/25/26 Experian Dispute Acct 1234 7012 3456 7890 9/24/26 — —

    This log is your master record. When you have letters going to three bureaus, two furnishers, and a collection agency all at once, a log keeps you from losing track.

    6. Do Not Use Threatening or Aggressive Language

    You can be firm and assertive without being hostile. Threatening letters do not improve outcomes and can make the recipient less cooperative. State your rights, state your request, cite the law, and keep the tone professional.

    7. Do Not Admit to the Debt Unnecessarily

    In pay-for-delete and validation letters, be careful with language. Phrases like “I owe this debt” or “I will pay what I owe” can be used against you later. Use language like “the account you reference” or “I am not acknowledging the validity of this debt” when appropriate.

    The Timeline and Follow-Up Process

    Credit repair is a process, not a single event. Here is what to expect and when:

    The Standard FCRA Dispute Timeline

    Day Event
    Day 0 You mail your dispute letter (certified mail)
    Day 1-5 Bureau receives the letter (track via certified mail)
    Day 5-30 Bureau conducts its reinvestigation, contacts the furnisher
    Day 30 (or 45) Bureau must complete the investigation and notify you of results
    Day 30-45 You receive written results + updated credit report (if changed)
    Day 45-60 If no response, follow up with a second letter noting the FCRA violation

    The 45-day extension: If you send additional information during the 30-day investigation window, the bureau gets an extra 15 days (45 total). Do not send follow-up information mid-investigation unless necessary — it extends the timeline.

    The FDCPA Validation Timeline

    Day Event
    Day 0 Collector’s initial communication + validation notice
    Day 1-30 You have 30 days to send a validation letter
    Day 30+ Collector must cease collection activities until validation is provided
    No fixed deadline Collector must validate “within a reasonable time” — generally 30-60 days is the practical expectation

    Unlike the FCRA, the FDCPA does not specify an exact deadline for the collector to validate. But they must stop collecting until they do. If they resume collection without validating, that is an FDCPA violation.

    Follow-Up Rules

    • If no response by the deadline: Send a follow-up letter noting that the legal deadline has passed and the item must be deleted (for FCRA disputes) or collection must cease (for FDCPA validation). Cite the specific section of the law.
    • If the response is unfavorable: Request method of verification (for bureau disputes), send a furnisher dispute (if you only disputed with the bureau), or prepare a complaint to the CFPB.
    • If the item is updated but not removed: Review the update. Sometimes a correction (e.g., a balance updated to zero) is a partial win. Decide whether to push for full deletion with a follow-up dispute or accept the correction.
    • Wait between disputes: Do not re-dispute the same item every week. Re-dispute only when you have new information or a new basis for the dispute. Repeated disputes of the same item, with no new information, can be flagged as frivolous.

    What to Do With Responses

    Every response you receive tells you something. Here is how to handle each type:

    “Item Deleted”

    This is the best outcome. Verify that the deletion appears on your updated report (the bureau must send you one). Check all three bureaus if the error appeared on all three — a deletion from one bureau does not automatically remove it from the others. If it still appears on another bureau’s report, send a dispute to that bureau referencing the deletion.

    “Item Updated/Corrected”

    A partial win. Review the updated report to confirm the correction was made accurately. If the correction is incomplete or introduces a new error, send a follow-up dispute specifying the remaining issue.

    “Item Verified — Remains”

    This is not the end. Your options:

    • Request method of verification (see ) to learn how the bureau verified it.
    • Send a furnisher dispute directly to the creditor (see ).
    • Send a second bureau dispute with new information or documentation — ideally informed by the method-of-verification response.
    • File a CFPB complaint if you believe the investigation was not reasonable.
    • Consult an attorney — an FCRA claim for failure to conduct a reasonable investigation may be viable, and attorney-backed credit repair firms handle this escalation.

    “Frivolous” Rejection

    Bureaus can reject a dispute as “frivolous or irrelevant” under FCRA § 1681i(a)(3). If this happens:

    • Review the bureau’s reasoning — they must tell you why they deemed it frivolous and what information would make it non-frivolous
    • Provide the requested information and re-dispute
    • Avoid blanket disputes (disputing everything at once) and avoid re-disputing the same item repeatedly without new information
    • Consider working with a credit repair professional — they can frame disputes in a way that reduces frivolous rejections

    No Response

    If you receive no response by the legal deadline:

    • Send a follow-up letter noting the deadline has passed and demanding deletion (FCRA) or cessation of collection (FDCPA)
    • File a CFPB complaint
    • Keep your certified mail receipts as proof

    Common Mistakes to Avoid

    1. Frivolous Disputes

    Disputing everything on your report, especially accurate items, gets flagged. Bureaus are not required to investigate disputes they reasonably determine to be frivolous. Focus on items that are genuinely inaccurate, incomplete, outdated, or unverifiable.

    2. Blanket Disputes

    Sending one letter disputing 15 items at once is a red flag. It signals to the bureau that you are not engaging with each item individually and are likely using a “shotgun” approach. Send separate letters for each item, or at most 2-3 closely related items per letter.

    3. Sending Too Many Letters at Once

    If you mail 20 dispute letters in one week, you will have a hard time tracking responses, following up on deadlines, and managing the process. More importantly, it looks like a mass-dispute operation rather than a genuine consumer exercising specific rights. Stagger your disputes — send a few, wait for responses, follow up, then send the next batch.

    4. Not Following Up

    The biggest mistake consumers make is sending a letter, getting no response, and doing nothing. The law is on your side only if you enforce it. If a bureau misses the 30-day deadline, that failure is grounds for deletion — but you have to ask. Send the follow-up. File the CFPB complaint. Keep the pressure on.

    5. Using Online Dispute Forms Exclusively

    Online dispute portals are convenient but limited. They often restrict how much you can write, limit the types of documents you can upload, and do not create the same kind of paper trail as a certified letter. For complex disputes, a written letter with supporting documentation is stronger.

    6. Admitting to Debts You Do Not Owe

    In phone calls and letters, do not say “I’ll pay this” or “I know I owe it” unless you actually do and intend to pay. Admissions can reset the statute of limitations in some states and can be used against you in collection actions.

    7. Not Keeping Records

    If you cannot prove you sent the letter, prove the recipient received it, and prove you did not get a timely response, your rights are much harder to enforce. Certified mail + return receipt + a file for every letter is non-negotiable.

    8. Falling for Quick-Fix Promises

    Anyone who promises to remove accurate, verifiable negative information in 30 days is not being honest. The FCRA does not work that way. Credit repair takes time — typically 3-6 months for meaningful progress, sometimes longer depending on the complexity of your file.

    Beware “Guaranteed Deletion” Letter Services

    The credit repair space attracts scammers and over-promisers. Here is what to watch for:

    Red Flags

    • “Guaranteed removal” — No one can guarantee removal of accurate, verifiable information. The FCRA does not allow it, and no letter can force it.
    • “We’ll remove anything in 30 days” — Legitimate disputes take 30-45 days just for the investigation, and not all disputes succeed.
    • “100% legal loophole” letters — The “609 loophole,” the “identity theft loophole for items you did create,” and similar gimmicks are marketing, not legal strategy. Some are based on real legal provisions (609 is a real section), but they are not magic deletion tools.
    • Upfront fees for “guaranteed” results — The Credit Repair Organizations Act (CROA) makes it illegal for credit repair companies to charge you before they perform services. If a company demands full payment upfront, that is a violation.
    • “We dispute everything” — A company that disputes every item on your report, regardless of accuracy, is setting you up for frivolous-dispute rejections and wasted time.
    • No physical address or attorney affiliation — Legitimate credit repair firms have a real office and, ideally, attorney oversight. Fly-by-night operations hide behind websites.

    What Legitimate Credit Repair Looks Like

    A reputable, FCRA-compliant, attorney-backed credit repair firm will:

    • Review your three-bureau credit reports with you
    • Identify items that are genuinely disputable (inaccurate, incomplete, outdated, unverifiable)
    • Send targeted, specific dispute letters — one item per letter, with supporting documentation
    • Handle furnisher disputes, validation requests, method-of-verification follow-ups, and goodwill/pay-for-delete negotiations as appropriate
    • Track deadlines and follow up when bureaus or collectors do not respond
    • Educate you on maintaining good credit long-term — because the best credit repair is preventing future negative items
    • Be transparent about pricing, timeline, and realistic outcomes
    • Never guarantee specific deletions or promise a particular score increase

    Internal link placeholder: Read more about and the warning signs to watch for.

    Frequently Asked Questions

    1. Do credit repair letters really work?

    Yes — for inaccurate, incomplete, outdated, or unverifiable information. The FCRA gives you the right to dispute, and bureaus must investigate and remove items they cannot verify. Credit repair letters do not work for accurate, verifiable, within-time-limit negative items that the furnisher can confirm — but they can work for goodwill removals and pay-for-delete negotiations in those cases.

    2. How long does it take to see results?

    The FCRA gives bureaus 30 days (up to 45 with additional information) to investigate. You typically see results within 45-60 days of mailing a dispute letter. Full credit repair — addressing multiple items across three bureaus — usually takes 3-6 months, sometimes longer for complex files.

    3. Can I dispute online instead of by mail?

    You can, but written letters sent by certified mail create a stronger paper trail and allow you to include detailed documentation. Online dispute portals are convenient but often limit what you can submit. For complex or important disputes, written letters are recommended.

    4. Do I need to send the same dispute to all three bureaus?

    Yes, if the error appears on all three reports. Bureaus do not automatically share dispute information with each other (unless you use an indirect dispute process). Send a separate letter to each bureau that is reporting the inaccurate item.

    5. What if the bureau says my dispute is frivolous?

    The bureau must tell you why it deemed the dispute frivolous and what information would make it non-frivolous. Provide that information and re-dispute. Avoid blanket disputes, limit disputes to genuinely questionable items, and include specific supporting documentation. If the bureau continues to reject valid disputes, file a CFPB complaint and consider attorney involvement.

    6. Is a 609 letter a guaranteed way to remove items?

    No. A 609 letter invokes your right to disclosure of information in your file, which is a real and useful right. But it is not a guaranteed deletion tool. Some online services market 609 letters as a magic loophole; the FCRA does not require bureaus to delete accurate, verifiable information because you requested source documents. Use 609 requests as a supporting step, not a standalone solution.

    7. Should I use a credit repair company or do it myself?

    You can do credit repair yourself — the letters in this guide are designed for self-use. But many people benefit from professional help because: the process is time-consuming, tracking multiple disputes across three bureaus is complex, and attorney-backed firms can escalate to legal action when bureaus or collectors violate the law. If your file is complex, if you have tried self-repair without success, or if you suspect FCRA/FDCPA violations, professional help is worth considering.

    8. Can I send a goodwill letter for a late payment that is my fault?

    Yes — that is exactly what goodwill letters are for. The late payment is accurate (so you cannot dispute it as an error), but you are asking the creditor to remove it as a courtesy based on your otherwise strong history and the specific circumstances. Goodwill letters are most effective for a single, isolated late payment with a clear explanation and evidence of a return to good behavior.

    Take the Next Step

    Credit repair letters are powerful tools, but they are only as effective as the strategy behind them. Knowing which letter to send, when to send it, how to document it, and what to do with the response is what turns a stack of correspondence into real credit improvement.

    If you are ready to address the errors and negative marks on your credit report — and you want the process handled correctly, with FCRA-compliant correspondence, attorney oversight, and a team that tracks every deadline and follows up on every response — we can help.

    offers a free credit audit across all three major bureaus. We will review your reports, identify the items that are genuinely disputable, and build a customized correspondence plan — from dispute letters to validation requests to goodwill and pay-for-delete negotiations — handled on your behalf with attorney backing.

    No guarantees of specific deletions. No quick-fix promises. Just honest, transparent, legally compliant credit repair designed to produce measurable, lasting progress — and the education you need to keep your credit strong long after the process is complete.

    and take the first step toward the credit score you deserve.

    This article is for educational purposes and does not constitute legal advice. Your individual situation may vary. For specific legal questions about your rights under the FCRA or FDCPA, consult a qualified attorney.

  • How to Remove Hard Inquiries From Your Credit Report

    How to Remove Hard Inquiries From Your Credit Report

    Also worth reading: understand the full difference between hard vs soft inquiries, learn how to find all other credit report errors worth disputing, see all the credit repair letters at your disposal, and get expert help from our New York credit repair team.

    If you’ve recently pulled your credit report and spotted a handful of hard inquiries you don’t remember authorizing, you’re probably feeling a mix of frustration and worry. Will those pulls drag down your score? Can you get them removed? Should you pay someone to “fix” it?You’re in the right place. This guide walks you through exactly what a hard inquiry is, how much it actually hurts your credit, the honest truth about which inquiries can be removed (and which can’t), and the step-by-step process for disputing unauthorized hard inquiries under the Fair Credit Reporting Act (FCRA). We’ll also give you a ready-to-use dispute letter template and show you how to lock down your credit so this doesn’t happen again.No quick-fix promises. No guarantees. Just clear, legally grounded steps you can take today.

    What Is a Hard Inquiry?

    A hard inquiry (also called a hard pull) happens when a lender or creditor checks your credit report to make a lending decision about you. It’s the credit check that occurs when you apply for a credit card, a mortgage, an auto loan, a personal loan, a student loan refinance, an apartment rental, or sometimes even a new cell phone plan or utility account.

    The key word is decision. A hard pull is tied to an active application for new credit or a service that effectively extends credit. The lender wants to see your full credit picture — your payment history, your current debts, your credit utilization, and your recent applications — to decide whether to approve you and at what interest rate.

    Here’s what happens behind the scenes when a hard inquiry is generated:

    • You submit an application (or in some cases, a lender submits one on your behalf with your permission).
    • The lender contacts one or more of the three major credit bureaus — Equifax, Experian, or TransUnion — and requests your credit report.
    • The bureau logs the request on your report as a hard inquiry, including the date, the lender’s name, and which bureau was contacted.
    • Your score may dip slightly (more on that below).
    • The inquiry stays on your report for up to 24 months, though its effect on your score typically fades after about 12 months.

    A hard inquiry is different from the credit checks that happen when you check your own credit, when a lender sends you a pre-approved offer, or when an existing creditor monitors your account. Those are called soft inquiries, and they don’t affect your score at all.

    It’s also important to understand that a hard inquiry is recorded per bureau. If a lender only pulls your Equifax report, the hard inquiry shows up on your Equifax report — not on your Experian or TransUnion reports. This is why you might see different numbers of hard inquiries across your three bureau reports. Some lenders pull from all three (common with mortgages), while others pull from just one or two.

    Why Lenders Make Hard Inquiries

    Lenders use hard inquiries to assess risk. When you apply for credit, they need to know:

    • Are you already carrying too much debt?
    • Have you been applying for a lot of credit recently (which could signal financial distress)?
    • Do you have a history of managing credit responsibly?
    • What interest rate and credit limit are appropriate for your risk profile?

    Each hard inquiry is essentially a snapshot of a moment when you asked someone to lend you money (or extend a credit-like service). That’s why the credit scoring models treat them as a minor risk signal — a burst of recent inquiries can suggest you’re about to take on new debt that hasn’t shown up on your report yet.

    Hard Inquiry vs. Soft Inquiry: What’s the Difference?

    The distinction between hard and soft inquiries is one of the most commonly misunderstood parts of the credit system. Here’s a clear breakdown.

    Feature Hard Inquiry Soft Inquiry
    Who initiates it A lender or creditor, with your permission You, an existing creditor, or a lender doing a pre-screen
    Why it happens You applied for credit or a credit-like service Account monitoring, pre-approval offers, your own credit check
    Visible to lenders? Yes — appears on the version of your report lenders see No — only visible to you on your consumer report
    Affects your credit score? Yes — typically a small, temporary dip No impact whatsoever
    How long it stays Up to 24 months on your report; score impact fades around 12 months Varies, but no score impact so it doesn’t matter much

    Examples of Hard Inquiries

    • Applying for a new credit card
    • Applying for a mortgage or refinancing your home
    • Applying for an auto loan or refinancing your car
    • Requesting a credit limit increase (sometimes — depends on the issuer)
    • Applying for a personal loan or debt consolidation loan
    • Applying for an apartment rental (when the landlord runs a credit check)
    • Opening a new utility or cell phone account (sometimes — depends on the provider)
    • Applying for a business credit card or business loan (if it requires a personal credit check)

    Examples of Soft Inquiries

    • Checking your own credit report or score (through AnnualCreditReport.com, your bank’s free credit monitoring, a credit karma-type service, etc.)
    • Receiving a pre-approved credit card offer in the mail (the lender did a “pre-screen” pull)
    • An existing creditor doing a periodic account review
    • An employer running a background check that includes a credit report (with your permission)
    • A landlord or insurance company checking your credit for a quote (sometimes — depends on the type)
    • Credit monitoring services you’ve enrolled in pulling your report on a recurring basis

    The rule of thumb: If you actively applied for something that involves borrowing money or a credit-like service, it’s probably a hard inquiry. If you didn’t apply for anything, it’s probably a soft inquiry.

    One common point of confusion: checking your own credit never creates a hard inquiry. You can pull your own credit report as many times as you want — from all three bureaus, through any service — and it will never affect your score. This is one of the most persistent credit myths, and it prevents people from monitoring their reports as often as they should. Don’t let it stop you.

    When a Hard Inquiry Is Legitimate

    A hard inquiry is legitimate when you knowingly applied for credit (or a credit-like service) and gave the lender permission to pull your credit report. This is the most common scenario, and it covers the vast majority of hard inquiries on most people’s reports.

    Here are some signs that a hard inquiry is legitimate:

    • You remember applying. You filled out an application — online, in person, or over the phone — within a few weeks of the inquiry date on your report.
    • You received a decision. You got an approval, a denial, or a counter-offer from the lender around the same time.
    • You authorized the pull. You signed a consent form, clicked “I agree” on an online application, or verbally authorized a credit check.
    • The lender name matches. The company listed on the inquiry is one you recognize, even if it’s a parent company or a subsidiary (for example, Synchrony Bank might show up as the issuer behind a store credit card you applied for).

    Common Legitimate Hard Inquiry Scenarios

    Store credit cards. You’re at the checkout counter, the cashier offers you 20% off your purchase if you open a store card, and you say yes. That’s a hard inquiry — even if you were approved instantly and the discount felt like a perk.

    Rate shopping. You’re buying a car and you let the dealership shop your application to multiple lenders to find the best rate. Each of those lenders may generate a hard inquiry. (The good news: the scoring models count multiple auto loan inquiries within a short window as a single inquiry — more on this in the .)

    Credit limit increases. Some credit card issuers do a hard pull when you request a credit limit increase, while others only do a soft pull. It varies by issuer, so it’s worth checking before you request one. (Many issuers will tell you upfront whether it’ll be a hard or soft pull.)

    Apartment applications. When you apply to rent an apartment, the property management company or landlord may run a credit check. This is typically a hard inquiry, though some use soft-pull screening services.

    Utility and telecom accounts. Opening a new electricity, gas, water, or cell phone account sometimes triggers a hard inquiry. The utility company wants to assess whether you’re likely to pay your bill, and they may treat it like a small credit decision.

    If a hard inquiry falls into any of these categories and you genuinely authorized it, it’s legitimate. It will stay on your report for up to 24 months, and there is no legal way to remove it early. We’ll talk more about why in the and the .

    When a Hard Inquiry Is Unauthorized

    An unauthorized hard inquiry is one that appeared on your credit report without your knowledge or permission. This is a serious matter — it means someone accessed your credit information without a legitimate application from you, and under the FCRA, you have the right to have it removed.

    Unauthorized hard inquiries typically happen in one of three ways:

    1. Identity Theft

    This is the most concerning scenario. Someone has stolen your personal information — your name, Social Security number, date of birth, address — and used it to apply for credit in your name. The lender pulls your credit report as part of the fraudulent application, and the hard inquiry lands on your report.

    Signs that an inquiry might be the result of identity theft:

    • You don’t recognize the lender at all.
    • The inquiry date corresponds to a period when you know you didn’t apply for anything.
    • You start seeing accounts on your report that you never opened.
    • You receive bills, collection notices, or calls about accounts you don’t recognize.
    • You get a notice that you were approved (or denied) for credit you never sought.

    If you suspect identity theft, time is of the essence. The faster you act, the more you can contain the damage. We’ll walk you through the identity-theft-specific removal process (including filing a report and invoking FCRA Section 605B, which lets you block identity-theft-related information from your report) in the .

    2. No-Permission Pulls

    Sometimes a lender or service provider pulls your credit without your explicit permission. This can happen when:

    • A salesperson at a car dealership runs your credit “to see what you qualify for” before you’ve formally applied or agreed to a credit check.
    • A lender pulls your credit for a pre-qualification that you thought was a soft pull but turned out to be a hard pull.
    • A company you’re doing business with runs a credit check for a purpose you didn’t authorize (for example, an existing creditor doing a hard pull when their policy only allows soft pulls for account reviews).
    • A mortgage broker or loan officer pulls your credit to “have it ready” before you’ve committed to an application.

    If you didn’t explicitly authorize the credit check — whether through a signed application, a click-through consent, or a clear verbal agreement — the inquiry may be unauthorized. You have the right to dispute it.

    3. Clerical or System Errors

    Less commonly, a hard inquiry can appear on your report due to a clerical error — a lender accidentally pulls the wrong person’s credit because of a similar name, a mixed file at the credit bureau, or a data-entry mistake. These are rare but they do happen, and they’re also disputable.

    How to Spot an Unauthorized Inquiry

    The only reliable way to catch unauthorized inquiries is to review your credit reports from all three bureaus regularly. You’re entitled to a free copy of each report once per week through AnnualCreditReport.com — that’s 52 free reports per bureau per year, thanks to a permanent change made during the pandemic. There’s no reason not to check.

    When you review your reports, look at the inquiries section (sometimes called “requests for your credit file” or “inquiries shared with others”). This is where hard inquiries are listed. Check:

    • The name of the lender — do you recognize it?
    • The date of the inquiry — does it line up with an application you remember?
    • The type of inquiry — is it coded as a hard inquiry (visible to lenders) or a soft inquiry?

    If anything looks unfamiliar, flag it. One unfamiliar inquiry might be a clerical error; multiple unfamiliar inquiries in a short period could signal identity theft. Either way, you have options.

    How Much Does a Hard Inquiry Hurt Your Credit Score?

    Let’s talk numbers — with the caveat that credit scoring models (FICO and VantageScore) are proprietary, so the exact impact varies by individual. But here’s what we know from the scoring companies’ published guidance and years of industry observation.

    The Short Answer

    A single hard inquiry typically lowers your credit score by 1 to 5 points. For most people, it’s on the lower end of that range. If you have a strong, established credit history with a long track record of on-time payments, a single hard inquiry might not move your score at all — or it might drop by a point or two, then bounce back within a few months.

    If your credit history is thin (you’re new to credit, you have few accounts, or your file is otherwise limited), the same inquiry might cause a slightly larger dip because there’s less positive history to offset it.

    The Recovery Timeline

    Here’s the good news: the impact of a hard inquiry is temporary and small compared to other credit events.

    • The score dip happens immediately when the inquiry is recorded.
    • The impact begins to fade after a few months as the scoring model sees that no new delinquency or default followed the application.
    • After about 12 months, hard inquiries have essentially no effect on your FICO score. (FICO has stated publicly that inquiries older than 12 months don’t affect your score, even though they remain visible on your report.)
    • The inquiry falls off your report entirely at 24 months. After that, it’s gone — no trace, no residual impact.

    So even if a hard inquiry causes a small score drop today, it’s a self-correcting situation. You don’t need to do anything except continue managing your credit responsibly, and time will take care of it.

    When Inquiries Matter More

    The scoring models are smart enough to distinguish between someone who’s shopping for a single loan (rate shopping) and someone who’s rapidly accumulating new credit obligations. Here’s when inquiries can have a bigger cumulative effect:

    • Six or more hard inquiries in a short period (a few months) can signal risk and may cause a more noticeable score drop — potentially 10 to 20 points or more, depending on your overall profile.
    • Inquiries combined with other negative factors (late payments, high utilization, collections) compound the damage because they paint a picture of financial distress.
    • Multiple new accounts opened in a short window (which follow hard inquiries) can lower your average age of accounts, which also hurts your score.

    But in isolation, a hard inquiry or two is one of the smaller factors in your credit score. Payment history (35% of your FICO score) and amounts owed (30%) dwarf the impact of inquiries (about 10%). If you’re paying your bills on time and keeping your credit card balances low, a few hard inquiries won’t derail your credit health.

    VantageScore vs. FICO

    Both major scoring models treat hard inquiries similarly — small, temporary impact — but VantageScore tends to be slightly more sensitive to recent inquiries than FICO. If you’re tracking your score through a free service that uses VantageScore (like Credit Karma), you might see slightly larger swings from inquiries than you would on a FICO score pulled by a lender. Don’t panic — it’s just a difference in how the models weigh the same data.

    The Bottom Line on Score Impact

    If you’re worried about a hard inquiry hurting your score:

    • One inquiry: minimal impact, usually 1–5 points, recovers within months.
    • A few inquiries from rate shopping: counted as one by the scoring models (see the ).
    • Many inquiries in a short period: can signal risk and have a larger cumulative effect.
    • Any inquiry older than 12 months: no FICO score impact.
    • Any inquiry older than 24 months: gone from your report entirely.

    The best thing you can do is not obsess over individual inquiries. Focus on the big factors — on-time payments and low utilization — and let the inquiries age off naturally.

    Can You Remove Legitimate Hard Inquiries?

    Here’s where we have to be completely honest with you, because the internet is full of companies that will tell you otherwise.

    You cannot remove a legitimate hard inquiry from your credit report before it falls off naturally at 24 months. Period.

    If you authorized the credit check — you applied for the card, the loan, the apartment, the utility account — the inquiry is accurate, it’s verifiable, and the credit bureaus are legally permitted to report it. Disputing it as “unauthorized” when you did authorize it won’t work (and could potentially flag your account as one that files frivolous disputes, which makes future legitimate disputes harder).

    Why “Inquiry Removal Services” Are Almost Always Scams

    You’ve probably seen the ads: “We remove hard inquiries from your credit report — guaranteed!” or “Boost your score 50 points in 30 days by deleting inquiries!”

    Here’s what those services typically do, and why it doesn’t work:

    • They bombard the credit bureaus with dispute letters claiming every inquiry is unauthorized, even the legitimate ones. The bureaus investigate, verify the inquiries with the lenders, and confirm them. Your disputes are denied.
    • They exploit the 30-day investigation window. Under the FCRA, if a bureau can’t verify a disputed item within 30 days, it must temporarily remove it. Some services hope that a lender won’t respond in time, causing the inquiry to be deleted. But if the lender later verifies it (which they almost always do for legitimate inquiries), it goes right back on your report. You’ve gained nothing — and you may have wasted a legitimate dispute opportunity.
    • They charge you recurring monthly fees for “ongoing monitoring and dispute management” while accomplishing little to nothing. Some clients pay for months or years with no meaningful improvement.
    • They may advise you to lie on dispute letters — to claim you never applied for credit when you did. This is fraud. It can expose you to legal liability and undermines your credibility with the bureaus for any future, legitimate disputes.

    The Honest Truth

    Legitimate hard inquiries are a fact of life when you use credit. They’re a small, temporary factor in your score, and they go away on their own. The only honest way to “remove” them is to wait.

    What you can do — and what we help our clients with — is:

    • Remove unauthorized inquiries through the formal dispute process (which we cover in detail below).
    • Protect your credit going forward by freezing or locking your report so no new unauthorized pulls can happen.
    • Focus on the factors that actually move your score — payment history, utilization, credit age, credit mix — rather than chasing inquiry removal.
    • Get a professional audit of your three-bureau reports to identify any inquiries (or other items) that are genuinely inaccurate, unverifiable, or the result of identity theft. That’s where real, legal, lasting removals happen.

    If a company promises to remove legitimate inquiries, run. If they guarantee a specific score increase, run faster. The FCRA gives you the right to dispute inaccurate, incomplete, or unverifiable information — not information that’s accurate and verified, just because you’d prefer it wasn’t there.

    How to Remove Unauthorized Hard Inquiries

    Now for the part you came here for. If you’ve identified hard inquiries on your report that you did not authorize, you have a clear, legal path to have them removed. The FCRA gives you the right to dispute any information on your credit report that you believe is inaccurate, incomplete, or unverifiable — and unauthorized inquiries fall squarely into that category.

    There are three main avenues for removing unauthorized hard inquiries, and we recommend pursuing them in this order. In many cases, you’ll want to pursue more than one simultaneously, especially if identity theft is involved.

    Method 1: Dispute Directly With the Credit Bureau

    Your first step is to dispute the unauthorized inquiry directly with the credit bureau (or bureaus) that’s reporting it. Remember, inquiries are reported per bureau — so if an unauthorized inquiry appears on your Equifax report but not your Experian or TransUnion reports, you only need to dispute it with Equifax. If it appears on all three, you dispute with all three.

    How to file a bureau dispute:

    • Gather your evidence. Before you file, collect anything that supports your claim that the inquiry is unauthorized:
    • A copy of your credit report showing the inquiry (with the lender name and date).
    • Any correspondence you’ve had with the lender (if you contacted them and they couldn’t verify your application).
    • An identity theft report, if applicable (see Method 3).
    • A simple written statement explaining that you did not apply for credit with this lender and did not authorize the inquiry.
    • File the dispute. You can file online, by phone, or by mail. We recommend mail for the strongest paper trail, but online is faster. Each bureau has a dispute portal:
    • Equifax: equifax.com/disputes
    • Experian: experian.com/disputes
    • TransUnion: transunion.com/disputes
    • Or use the AnnualCreditReport.com portal if you pulled your report from there.

    If you file by mail, include:

    • A copy of your credit report with the disputed inquiry highlighted.
    • A clear dispute letter (use our ).
    • Copies (not originals) of any supporting documents.
    • A copy of your driver’s license or state ID and a recent utility bill to verify your identity.
    • The bureau has 30 days to investigate. Under the FCRA, the credit bureau must investigate your dispute within 30 days (sometimes 45 days if you submit additional information during the investigation). They’ll contact the lender (the “furnisher” of the inquiry) and ask them to verify it.
    • The bureau must notify you of the results. Within 5 days of completing the investigation, the bureau must send you the results in writing. If the inquiry is verified as accurate, it stays. If the lender can’t verify it, or doesn’t respond within the window, the bureau must delete it from your report.
    • If it’s removed, you’ll get an updated report. The bureau will send you a free, updated copy of your credit report so you can confirm the deletion.

    What if the bureau verifies it but you still believe it’s unauthorized? You have options:

    • File a statement of dispute (a 100-word explanation that gets added to your credit report so future lenders can see your side).
    • Dispute directly with the furnisher (Method 2).
    • If identity theft is involved, invoke FCRA Section 605B (Method 3), which gives you stronger protections than a standard dispute.

    Method 2: Dispute Directly With the Furnisher

    Under FCRA Section 623, you also have the right to dispute information directly with the company that furnished it to the credit bureau — in this case, the lender who made the hard inquiry. This is sometimes called a “direct dispute” or “furnisher dispute.”

    This can be effective because the furnisher (not the bureau) is the one who actually has (or should have) records of your application. If they can’t produce evidence that you applied — a signed application, an electronic consent record, a recorded phone call — they’re required to notify the bureau to delete the inquiry.

    How to file a furnisher dispute:

    • Find the lender’s contact information. Your credit report should list an address for the company that made the inquiry. If not, look up their customer service or fraud department contact info online. Ask specifically for the fraud department or credit reporting disputes department — these are the teams that handle unauthorized inquiry claims.
    • Send a written dispute. Use a letter (our works for this too, with minor adjustments) that states:
    • You did not apply for credit with them.
    • You did not authorize a credit check.
    • You’re requesting that they investigate and, if they can’t verify your authorization, notify all three credit bureaus to delete the inquiry.
    • You want a written response within 30 days.
    • Send it via certified mail with return receipt. This gives you proof of delivery and creates a legal record. If the furnisher doesn’t respond, that documentation supports further action.
    • The furnisher has 30 days to investigate. Under FCRA Section 623(b), they must review your dispute, contact the credit bureau if appropriate, and report back to you. If they can’t verify that you authorized the inquiry, they must notify the bureau(s) to remove it.
    • If they confirm it was authorized but you disagree, ask them for proof — a copy of your application, your signed consent, the IP address and timestamp of an online application, etc. If they can’t produce it, escalate. If they produce something that looks fraudulent (a signature that isn’t yours, an address you’ve never lived at), you’re likely dealing with identity theft — move to Method 3.

    Pro tip: Filing disputes with both the bureau and the furnisher simultaneously can increase your chances of a quick removal. If either one can’t verify the inquiry, it has to come off.

    Method 3: File an Identity Theft Report and Block Under FCRA Section 605B

    If the unauthorized inquiry is the result of identity theft — someone used your personal information to apply for credit in your name — you have a powerful tool that goes beyond a standard dispute: FCRA Section 605B, also known as the identity theft block.

    This provision requires credit bureaus to block the reporting of any information on your credit report that results from identity theft, within 4 business days of receiving your request, as long as you provide the required documentation. This is stronger than a standard dispute because the bureau must block the information quickly — they can’t wait for a 30-day investigation — and the block is permanent unless the bureau later determines that the information didn’t result from identity theft and notifies you.

    How to use FCRA Section 605B:

    • File an identity theft report with the FTC. Go to IdentityTheft.gov and file a report. The FTC will create an Identity Theft Report (sometimes called an “FTC Affidavit”) that you can use as proof of identity theft. This is free, takes about 20–30 minutes, and walks you through the process step by step.
    • File a police report (recommended). Take your FTC Identity Theft Report to your local police department and file a report. This creates an additional official record. Get a copy of the police report — you’ll need it.
    • Contact the lender’s fraud department. Notify the lender that the application was fraudulent and that you’ve filed an identity theft report. Ask them to close any fraudulent accounts and stop reporting the inquiry. Provide them with a copy of your FTC report and police report.
    • Send a Section 605B block request to each credit bureau. Write to each bureau that’s reporting the inquiry and include:
    • A clear statement that you’re requesting a block under FCRA Section 605B.
    • A copy of your FTC Identity Theft Report.
    • A copy of your police report (if you filed one).
    • A copy of your credit report with the identity-theft-related inquiry highlighted.
    • A statement of the facts — what happened, when you discovered it, and why you believe the inquiry resulted from identity theft.
    • Your identity verification (copy of driver’s license, utility bill, Social Security card).
    • The bureau must block the information within 4 business days. They can only refuse if they determine the information didn’t result from identity theft or if you’ve previously admitted to committing fraud. If they block it, the inquiry (and any related fraudulent accounts) must be suppressed from your report.
    • The bureau must notify you. Within 5 business days of blocking the information, the bureau must send you confirmation and a copy of your updated report.
    • Place a fraud alert or credit freeze. Once you’ve been a victim of identity theft, you should immediately place a fraud alert (7-year extended fraud alerts are available for confirmed identity theft victims) or a credit freeze on all three bureaus to prevent future unauthorized applications. See the for details.

    Why Section 605B is powerful: Standard disputes rely on the furnisher failing to verify the inquiry within 30 days. Section 605B shifts the burden — the bureau must block the information quickly based on your identity theft documentation, and the furnisher has to actively prove the information didn’t result from identity theft to have it restored. For genuine identity theft cases, this is the most reliable, fastest removal path.

    How to remove hard inquiries from your credit report

    Sample Inquiry Dispute Letter

    Here’s a template you can adapt for disputing an unauthorized hard inquiry with either a credit bureau or a furnisher. Fill in the bracketed information with your details. Send via certified mail with return receipt so you have proof of delivery.

    [Your Name] [Your Address] [City, State ZIP Code] [Your Phone Number] [Your Email] [Date] [Credit Bureau or Lender Name] [Department — e.g., Dispute Department / Fraud Department] [Their Address] [City, State ZIP Code] RE: Dispute of Unauthorized Hard Inquiry on Credit Report To Whom It May Concern: I am writing to dispute a hard inquiry that appears on my credit report and that I did not authorize. The details of the inquiry are as follows: Lender/Creditor Name: [Name of lender as it appears on your report] Date of Inquiry: [Date as it appears on your report] Credit Bureau: [Equifax / Experian / TransUnion] Account/Reference #: [If any — otherwise write “N/A”] I did not apply for credit with the above-named lender, and I did not authorize anyone to pull my credit report on the date listed. I have no recollection of, or connection to, this inquiry. [If identity theft is suspected, add: I believe this inquiry is the result of identity theft, and I have filed a report with the Federal Trade Commission. A copy is enclosed. I am requesting a block of this information under FCRA Section 605B.] Under the Fair Credit Reporting Act (15 U.S.C. § 1681), I have the right to dispute inaccurate or incomplete information on my credit report. I am requesting that you investigate this inquiry and, if it cannot be verified as authorized, remove it from my credit report immediately. Please provide me with: 1. Written confirmation of the results of your investigation. 2. An updated copy of my credit report reflecting the removal, if applicable. 3. The name, address, and phone number of any furnisher you contacted during the investigation. If the inquiry is verified, please provide me with the specific documentation that establishes my authorization — including a copy of any application, signed consent, or electronic authorization record bearing my signature, IP address, or other identifying information. Enclosed are the following supporting documents: – Copy of my credit report with the disputed inquiry highlighted – Copy of my driver’s license (identity verification) – Copy of a recent utility bill (address verification) – [If applicable: Copy of FTC Identity Theft Report] – [If applicable: Copy of police report] Please process this dispute within the timeframe required by the FCRA (30 days for standard disputes; 4 business days for identity theft blocks under Section 605B) and notify me of the outcome in writing. Thank you for your prompt attention to this matter. Sincerely, [Your Signature] [Your Printed Name] Enclosures: [List the number of enclosures]

    A few notes on using this letter:

    • Send it to the right place. If you’re disputing with a bureau, send it to that bureau’s dispute mailing address (check their website for the current address). If you’re disputing with a furnisher, send it to their fraud or credit reporting disputes department.
    • Keep copies of everything. Print two copies of the letter — sign both, keep one for your records, and send the other. Keep your certified mail receipt and return receipt in a file.
    • Be truthful. Only claim an inquiry is unauthorized if you genuinely did not authorize it. Filing false disputes is fraud and can damage your ability to pursue legitimate disputes in the future.
    • Customize as needed. If you’re disputing multiple inquiries, list them all in one letter. If you have additional evidence (emails with the lender, a fraud alert confirmation, etc.), mention and enclose it.

    How to Freeze or Lock Your Credit

    Once you’ve dealt with existing unauthorized inquiries, your next priority is preventing future ones. The single most effective tool for this is a credit freeze (also called a security freeze). A close alternative is a credit lock, which offers similar protection through a different legal mechanism.

    Credit Freeze vs. Credit Lock

    Feature Credit Freeze Credit Lock
    Legal protection Mandated by federal law (Free Credit Freeze Act, part of the Economic Growth Act of 2018) A contractual arrangement with the bureau (not federally mandated)
    Cost Free by law Usually free, but some bureaus offer paid lock-plus-monitoring packages
    How to place it Through each bureau’s website or by mail/phone Through each bureau’s website or mobile app
    Speed to lift Must be lifted within 1 hour of online/phone request Typically instant via app or website
    Fraud alert vs. freeze A freeze blocks all access; a fraud alert adds a verification step but doesn’t block Same

    A credit freeze is the gold standard for preventing unauthorized hard inquiries. When your credit is frozen, lenders cannot pull your credit report at all — which means no one can open new credit in your name, because lenders won’t approve an application without seeing a credit report. Even if an identity thief has your Social Security number and date of birth, they can’t generate a hard inquiry or open an account because the freeze blocks the pull.

    A credit lock offers the same practical protection but is faster to toggle on and off (instant via app) and may come with additional monitoring features. The tradeoff is that it’s not backed by the same federal legal framework as a freeze. For most people, either is fine — and some choose to use both for layered protection.

    How to Place a Credit Freeze

    You must place a freeze separately with each of the three major bureaus. A freeze at Equifax does not freeze your Experian or TransUnion reports. Here’s how:

    • Equifax: Visit equifax.com, search for “security freeze,” and follow the prompts to create an account and place the freeze. You can also call 1-800-349-9960 or mail a request.
    • Experian: Visit experian.com, search for “security freeze,” and follow the prompts. Or call 1-888-397-3742 or mail a request.
    • TransUnion: Visit transunion.com, search for “credit freeze,” and follow the prompts. Or call 1-888-909-8872 or mail a request.

    When you place a freeze, each bureau will give you a PIN or password that you’ll use to temporarily lift the freeze when you need to apply for credit. Keep these in a safe place. If you lose a PIN, you can recover it, but it’s a hassle.

    How to Lift a Freeze When You Need Credit

    When you’re ready to apply for a credit card, loan, apartment, or anything else that requires a credit check, you’ll need to temporarily lift the freeze at the bureau(s) the lender will pull from. (If you don’t know which bureau the lender uses, lift it at all three.)

    You can request:

    • A temporary lift for a specific time period (e.g., 7 days), after which the freeze automatically goes back into effect.
    • A specific lift for a specific lender, allowing only that lender to access your report.
    • A permanent removal of the freeze (not recommended unless you have a specific reason).

    By law, the bureau must lift the freeze within 1 hour of your online or phone request. This makes it practical to freeze your credit full-time and just lift it for the brief window when you’re actively applying.

    Fraud Alerts: A Lighter Alternative

    If a full freeze feels too restrictive, you can place a fraud alert instead. A fraud alert doesn’t block access to your credit report — instead, it tells lenders to take extra steps to verify your identity before extending credit. The lender must make a “reasonable effort” to contact you (by phone, email, or text) to confirm that you’re the one applying.

    Types of fraud alerts:

    • Initial fraud alert: Lasts 1 year. Available to anyone.
    • Active-duty military alert: Lasts 1 year. For active-duty service members.
    • Extended fraud alert: Lasts 7 years. Available to confirmed identity theft victims (requires an FTC Identity Theft Report or police report).

    You only need to place a fraud alert with one bureau — they’re required to notify the other two. But for a freeze, you must contact all three separately.

    Our Recommendation

    For maximum protection: place a credit freeze at all three bureaus and only lift it when you’re actively applying for credit. This is free, fast, and stops virtually all unauthorized hard inquiries and fraudulent account openings. Pair it with ongoing credit monitoring (many banks and services offer this for free) so you’re alerted if anything changes on your report.

    If you’ve been a victim of identity theft: place an extended fraud alert (7 years) and a credit freeze at all three bureaus. Use both. The freeze blocks access; the alert adds a verification layer for any legitimate application you make. This is the strongest protection available.

    The Rate-Shopping Window Explained

    One of the most common (and understandable) fears people have about hard inquiries is that rate shopping — letting multiple lenders pull your credit to find the best rate on a mortgage or auto loan — will tank their score. Here’s the reassuring truth: the credit scoring models are designed to encourage rate shopping, not penalize it.

    How the Deduplication Window Works

    Both FICO and VantageScore apply a deduplication rule to inquiries of the same type (mortgage, auto, student loan) made within a specific time window. Instead of counting each inquiry separately, they count all inquiries within the window as a single inquiry for scoring purposes.

    Here are the specifics:

    FICO:

    • Window: 45 days (for FICO 8, 9, and 10; older versions used 14 days).
    • Applies to: Mortgage, auto, and student loan inquiries.
    • Effect: All inquiries of the same type within the 45-day window count as one inquiry for scoring. Your score only sees one inquiry, not five or ten.
    • Note: Credit card inquiries are NOT deduplicated. Each credit card application is counted separately.

    VantageScore:

    • Window: 14 days (VantageScore 3.0 and 4.0).
    • Applies to: Mortgage, auto, student loan, and personal loan inquiries.
    • Effect: Same — all inquiries of the same type within the window count as one.

    What This Means for You

    If you’re buying a car and you let the dealership shop your application to five different lenders over a weekend, your FICO score treats those five auto-loan inquiries as one inquiry. You don’t get penalized five times for shopping around. The scoring models want you to find the best rate — that’s good for you and good for the lending market.

    Similarly, if you’re getting a mortgage and you apply with three different lenders over two weeks to compare offers, those three mortgage inquiries count as one.

    Best Practices for Rate Shopping

    • Do all your shopping within a short window. Aim to concentrate your applications within 14 days (to be safe across all scoring models). If you stretch it out over months, the deduplication may not apply.
    • Know which type you’re applying for. The deduplication applies to mortgage, auto, and student loan inquiries (plus personal loans for VantageScore). It does NOT apply to credit card applications. If you apply for three credit cards in a week, that’s three separate hard inquiries.
    • Don’t avoid shopping for the best rate out of fear. A single inquiry (which is what your score sees after deduplication) is a minimal, temporary factor. Saving 0.5% on a mortgage or 2% on an auto loan is worth far more over the life of the loan than a 2–3 point temporary score dip.
    • Check your credit before you start shopping. Pull your reports from all three bureaus so you know where you stand. If there are errors or unauthorized inquiries, clean those up first so lenders see your best, most accurate profile.
    • Understand that all inquiries still show on your report. Even though they count as one for scoring, each individual inquiry remains visible on your credit report for 24 months. A lender who manually reviews your report will see all of them — but they’ll also see that they’re all the same type (e.g., auto loan) and clustered in a short window, which is normal rate-shopping behavior.

    A Note on “Pre-Qualification” and “Pre-Approval”

    Many lenders offer “pre-qualification” or “pre-approval” tools that let you check your potential rates without a hard inquiry. These typically use a soft pull — no score impact. Take advantage of these when they’re available. They give you a sense of what you might qualify for without generating a hard inquiry. When you’re ready to formally apply (with a hard pull), you’ll already have a shortlist of lenders with competitive offers.

    How Many Hard Inquiries Is Too Many?

    There’s no magic number that triggers an automatic score drop or a lender rejection. But there are guidelines that can help you understand how lenders and scoring models view your inquiry history.

    The Scoring Model Perspective

    FICO and VantageScore look at inquiries as one factor among many. Here’s a rough framework:

    • 0–2 hard inquiries in the past 12 months: Considered normal and low-risk by most lenders. Minimal to no score impact.
    • 3–5 hard inquiries in the past 12 months: Slightly elevated. May cause a small cumulative score dip. Some lenders may ask questions, but it’s rarely a dealbreaker.
    • 6+ hard inquiries in the past 12 months: Starts to look like risk-seeking behavior. Lenders may see this as a sign that you’re rapidly accumulating credit, possibly due to financial distress. Score impact can be more noticeable. Some lenders may decline new applications or offer less favorable terms.
    • 10+ hard inquiries in the past 12 months: This will raise red flags with most lenders. It suggests either financial distress, potential fraud, or very aggressive credit-seeking behavior. You may be denied for new credit regardless of your overall score.

    Remember: inquiries older than 12 months don’t affect your FICO score at all, even though they’re still visible on your report. So the “too many” calculation is really about the past 12 months.

    The Lender Perspective

    Different lenders have different tolerance levels for inquiries:

    • Mortgage lenders tend to be the most sensitive. They may scrutinize any inquiries in the past 6 months and ask you to explain each one. If they see inquiries for new credit that isn’t yet showing as an account on your report, they may want to know whether you’ve taken on new debt that could affect your debt-to-income ratio.
    • Auto lenders are moderately sensitive but understand rate shopping. If your auto inquiries are clustered (deduplication window), they won’t hold it against you.
    • Credit card issuers vary widely. Some are inquiry-sensitive and may decline you if you’ve opened too many cards recently (this is sometimes called “velocity” — too many new accounts in a short period). Others are more lenient if your overall credit profile is strong.
    • Personal loan lenders often look at the total number of inquiries but weigh it alongside other factors like income and debt-to-income ratio.

    Context Matters More Than Raw Numbers

    A high number of inquiries isn’t automatically bad if there’s a clear, reasonable explanation:

    • Rate shopping for a single loan: Multiple auto or mortgage inquiries in a short window = one inquiry for scoring. Lenders understand this.
    • Building credit after a thin file: A few credit card applications over several months as someone establishes credit is normal and expected.
    • A single burst of applications followed by a quiet period: Often happens when someone is setting up their financial life (new apartment, utilities, a car, a credit card). Explainable.
    • A sustained pattern of new applications over many months: This is what raises concerns. It suggests ongoing credit-seeking behavior rather than a one-time event.

    What to Do If You Have “Too Many” Inquiries

    • Stop applying for new credit for a while. Let the inquiries age. After 12 months, they stop affecting your FICO score.
    • Focus on the factors that matter more. Pay every bill on time. Keep your credit card balances below 30% of your limits (ideally below 10%). Let your accounts age.
    • Review your reports for unauthorized inquiries. If some of those inquiries weren’t authorized by you, dispute them using the process above.
    • Be prepared to explain. If a lender asks about your inquiries, have a clear, honest explanation ready. Rate shopping, a period of establishing credit, a life event — context helps.
    • Wait it out. Time is your friend. Inquiries fall off at 24 months and stop affecting your score at 12. If you’re patient and practice good credit habits, your score will recover and grow.

    Common Mistakes and Scams

    As you work on cleaning up your credit report, it’s important to avoid the traps that waste your time, money, and credibility. Here are the most common mistakes and scams we see, and how to steer clear of them.

    Mistake 1: Disputing Legitimate Inquiries

    We covered this above, but it bears repeating: disputing a hard inquiry that you authorized will not work, and it can hurt you. The lender will verify it, the bureau will confirm it, and your dispute will be denied. If you file multiple frivolous disputes, the bureaus can flag your account — which makes it harder to get legitimate disputes taken seriously in the future.

    Only dispute inquiries you genuinely did not authorize. If you’re unsure whether you authorized an inquiry, contact the lender first and ask for proof of your application. If they can’t provide it, then dispute.

    Mistake 2: Paying for “Inquiry Removal” Services

    Any company that promises to remove legitimate hard inquiries is either lying to you or planning to file fraudulent disputes on your behalf. Neither is good. You’re paying for something that can’t be done legally, and if they file false disputes, the fallout lands on you, not them.

    Legitimate credit repair companies (including ours) help you remove inaccurate, unverifiable, or identity-theft-related items — not accurate ones. If a company’s pitch sounds too good to be true (“Remove ALL inquiries! Guaranteed score boost!”), it is.

    Mistake 3: Ignoring Unauthorized Inquiries

    On the flip side, some people notice an unfamiliar inquiry, shrug it off as “probably nothing,” and move on. This is a mistake. An unauthorized inquiry could be the first sign of identity theft. If someone has your information and is applying for credit in your name, the sooner you act, the more you can limit the damage.

    If you see an inquiry you don’t recognize:

    • Contact the lender and ask for proof of authorization.
    • If they can’t provide it, dispute with the bureau and the furnisher.
    • If identity theft is suspected, file an FTC report and invoke Section 605B.
    • Place a fraud alert or credit freeze immediately.

    Mistake 4: Not Checking All Three Bureaus

    Inquiries are reported per bureau. An unauthorized inquiry might appear on your Equifax report but not your Experian or TransUnion reports — or it might appear on all three. If you only check one bureau’s report, you might miss unauthorized inquiries on the others.

    Pull your reports from all three bureaus (free through AnnualCreditReport.com) and review the inquiry section on each one. If you find an unauthorized inquiry on one, check whether it’s also on the others before you start disputing.

    Mistake 5: Not Keeping Records of Disputes

    Credit repair is a paper-trail-intensive process. If you dispute by phone or online without saving confirmation numbers, correspondence, and results, you have no way to prove what you filed and when. If a dispute is ignored or incorrectly processed, you need documentation to escalate.

    Best practice: File disputes by mail with certified mail return receipts. Keep copies of every letter, every enclosures list, every receipt, and every response in a single file (physical or digital). If you file online, screenshot every confirmation page and save dispute reference numbers.

    Scam 1: “Guaranteed” Credit Repair

    No legitimate credit repair company can guarantee specific results — not a specific score increase, not the removal of specific items, not a timeline. The FCRA process depends on investigations, furnisher responses, and bureau decisions that no one can control. Any “guarantee” is a marketing lie.

    Scam 2: Upfront Fees for Credit Repair

    Under the Credit Repair Organizations Act (CROA), credit repair companies cannot legally charge you upfront fees before they perform any services. They can only charge you after services are rendered. If a company demands payment before doing any work, walk away — it’s illegal.

    Scam 3: “New Credit Identity” or CPN Scams

    Some scams offer to sell you a “Credit Privacy Number” (CPN) or a “new credit identity” that you can use instead of your Social Security number on credit applications. This is fraud. Using a CPN on a credit application is a federal crime, and the CPNs sold by these scammers are often stolen Social Security numbers (including those of children and deceased individuals). Never use a CPN. If you see this pitch, report it to the FTC.

    Scam 4: Imposter Credit Repair Sites

    Be cautious of websites and social media ads claiming to be affiliated with legitimate credit repair companies, the credit bureaus, or government agencies. Always verify you’re on the official website (check the URL) before entering personal information. When in doubt, go directly to the source — Equifax.com, Experian.com, TransUnion.com, AnnualCreditReport.com, identitytheft.gov, FTC complaintassistant.gov.

    Scam 5: “We Can Remove Anything” Scams

    Some services claim they can remove bankruptcies, late payments, collections, judgments, and inquiries — anything negative — from your credit report. The truth: you can only dispute and remove information that is inaccurate, incomplete, unverifiable, or the result of identity theft. Accurate, verified negative information stays on your report for the legally specified time (7–10 years for most items; 24 months for inquiries). Anyone who says otherwise is lying.

    How to Protect Yourself

    • Work with FCRA-compliant, attorney-backed credit repair professionals who are transparent about what can and cannot be removed.
    • Check reviews and complaints with the Better Business Bureau and your state’s attorney general’s office.
    • Read contracts carefully — understand what you’re paying for, how much, and when.
    • Never pay upfront for credit repair services (it’s illegal under CROA).
    • Never use a CPN or agree to misrepresent your identity on credit applications.
    • File disputes yourself if you’re comfortable — you don’t need to pay anyone to file a dispute. The FCRA gives you the right to do it for free.

    FAQ

    Can I remove a hard inquiry if I was approved but changed my mind?

    No. If you authorized the credit check as part of a legitimate application — even if you were approved and decided not to use the credit, or you closed the account immediately — the inquiry is accurate and will remain on your report for up to 24 months. Changing your mind after the fact doesn’t make the inquiry unauthorized.

    How long do hard inquiries stay on my credit report?

    Hard inquiries remain on your credit report for 24 months from the date of the inquiry. However, they only affect your FICO score for the first 12 months. After that, they’re visible but have no scoring impact. After 24 months, they’re automatically removed.

    Do hard inquiries affect all three credit scores the same way?

    Not necessarily. Since inquiries are recorded per bureau, and different lenders pull from different bureaus, you may have different numbers of inquiries on each report. Your FICO score is also calculated separately for each bureau (based on the data that bureau holds), so the score impact may differ slightly across bureaus. The general magnitude (1–5 points per inquiry) is similar, though.

    What’s the difference between a fraud alert and a credit freeze?

    A fraud alert tells lenders to verify your identity before extending credit, but it doesn’t block access to your credit report. A credit freeze completely blocks lenders from accessing your credit report, which prevents new accounts from being opened in your name. A freeze is stronger protection. You can use both simultaneously. Fraud alerts last 1 year (or 7 years for extended alerts available to identity theft victims); freezes last until you lift them.

    Can I dispute a hard inquiry online, or do I have to mail a letter?

    You can dispute online, by phone, or by mail. Online is fastest, but mailing a letter via certified mail gives you the strongest paper trail — proof of exactly what you sent and when it was received. If your dispute is straightforward (e.g., an inquiry from a lender you’ve never heard of), online may be fine. If your case is complex or involves identity theft, mail is preferable.

    Will disputing a hard inquiry lower my credit score?

    No. Filing a dispute does not affect your credit score. The dispute process is between you, the bureau, and the furnisher — it’s not reported to lenders and doesn’t appear on the version of your report that lenders see. If the dispute results in the inquiry being removed, your score may actually improve (or at least stop being held back by that inquiry).

    How many points will my score go up if an unauthorized inquiry is removed?

    It depends on your overall credit profile. If the unauthorized inquiry was recent and your file is thin, removing it might give you a few points back (roughly the same 1–5 points it cost you when it was added). If you have a long, strong credit history, the effect may be minimal. The bigger benefit of removing unauthorized inquiries is preventing them from accumulating — especially if identity theft is ongoing.

    Can a credit repair company remove hard inquiries faster than I can on my own?

    No. The FCRA dispute process is the same whether you file it yourself or a credit repair company files it on your behalf. The timelines (30 days for standard disputes, 4 business days for identity theft blocks) are set by law and apply equally to everyone. A reputable credit repair company can save you time and hassle by handling the paperwork, tracking deadlines, and following up — but they can’t make the process faster than the law allows, and they can’t remove legitimate inquiries that you could not remove yourself.

    Free Credit Audit

    If you’ve read this far, you’re clearly taking your credit health seriously — and that’s the right mindset. Here’s our invitation to you.

    At credit-repair.com, we offer a free, no-obligation credit audit across all three major bureaus — Equifax, Experian, and TransUnion. Here’s what that includes:

    • A full review of your three-bureau credit reports, including every hard inquiry, account, public record, and collection item.
    • Identification of any unauthorized hard inquiries and other inaccurate, incomplete, or unverifiable information that may be dragging down your score.
    • A personalized assessment of your credit situation, including which items can potentially be disputed and removed through the FCRA process.
    • A clear, honest explanation of what can and can’t be done — no guarantees, no quick-fix promises, just a straightforward plan based on your actual reports.
    • Attorney-backed guidance on identity-thebt scenarios, Section 605B blocks, and the most effective dispute strategy for your situation.

    We’re a San Diego-based, FCRA-compliant credit repair firm that works with clients nationwide. Our approach is built on transparency, legal compliance, and measurable progress — not empty promises. We don’t just help you remove what shouldn’t be there; we educate and equip you to keep your credit strong for the long term.

    Ready to find out what’s really on your report?

    Visit to request your free credit audit today. We’ll review your reports, flag any unauthorized inquiries or other disputable items, and walk you through your options — clearly, honestly, and with no pressure.

    Your credit future starts with knowing exactly where you stand. Let’s find out together.

    This article is for educational purposes and does not constitute legal advice. The FCRA dispute process is available to you at no cost — you do not need to pay anyone to file a dispute on your behalf. If you choose to work with a credit repair company, ensure they are FCRA-compliant and do not charge upfront fees before services are rendered, as required by the Credit Repair Organizations Act (CROA).

  • Statute of Limitations on Debt: How Old Debts Become Time-Barred

    Statute of Limitations on Debt: How Old Debts Become Time-Barred

    You pick up the phone, and a voice on the other end tells you that you owe money on a credit card you stopped paying on years ago — maybe a decade ago. They say they’ll sue you, garnish your wages, and report you to the credit bureaus unless you pay up today. Your stomach drops. Your mind races. You don’t even remember the account.

    Take a breath. Before you agree to anything, read this.

    There’s a legal time limit on how long a creditor or debt collector can sue you for an unpaid debt. It’s called the statute of limitations on debt, and once that clock runs out, the debt becomes what the law calls time-barred. That doesn’t mean the debt disappears, and it doesn’t mean it leaves your credit report — but it does mean you have powerful legal rights that most collectors won’t volunteer to tell you about.

    This guide walks you through everything you need to know: what the statute of limitations is, how it’s different from the seven-year credit reporting clock (people confuse these constantly, and that confusion costs them), what can restart the clock, what “time-barred” actually means, what to do if a collector calls or sues you on an old debt, and how to protect yourself from “zombie debt” that keeps rising from the grave.

    We’re a San Diego-based, attorney-backed credit repair firm, and we’ve spent years helping people across the country understand and exercise their rights under federal credit laws like the Fair Credit Reporting Act (FCRA) and the Fair Debt Collection Practices Act (FDCPA). This article is educational — it is not legal advice. State laws vary significantly, and if you’re dealing with a lawsuit or a particularly aggressive collector, having attorneys in your corner makes a real difference. We’ll explain why throughout.

    What Is the Statute of Limitations on Debt?

    The statute of limitations on debt (often abbreviated as SOL) is a state law that sets a time limit on how long a creditor or debt collector has to file a lawsuit against you to collect an unpaid debt. Think of it as a legal expiration date on their right to drag you into court over that specific obligation.

    Here’s the key idea: the statute of limitations is about suing you — not about whether you still owe the money. A debt doesn’t vanish when the SOL runs out. You may still technically owe it, and a collector may still try to collect it through letters and phone calls (within the limits of the FDCPA). What changes is that they lose their most powerful enforcement tool: the courts. They can’t get a judgment against you, which means they can’t garnish your wages, lien your property, or levy your bank account through that debt — unless you let them.

    That last part is critical, and we’ll return to it. Many people accidentally reset the statute of limitations clock by doing something seemingly innocent, like making a small “good faith” payment or even just acknowledging the debt on a recorded call. More on that below.

    Why does the SOL exist?

    Statutes of limitations exist for a practical reason: evidence disappears, memories fade, and records get lost over time. It’s fundamentally unfair to drag someone into court over a 15-year-old credit card charge when neither side can reliably prove what happened. The SOL forces creditors to act within a reasonable window or lose their judicial remedies. Every state has its own version, and they vary by the type of debt (more on that in the table below).

    A quick note on terminology

    You’ll see a few terms in this article that are worth defining up front:

    • Statute of limitations (SOL) — the lawsuit deadline, set by state law.
    • Time-barred debt — a debt past its statute of limitations. Collectors generally can’t sue you on it.
    • Zombie debt — very old, often uncollectible or already-paid debt that gets resold to aggressive collectors who try to revive it.
    • Charge-off — when a creditor writes a debt off their books as a loss, typically after ~180 days of non-payment. This is an accounting event, not a legal one, and it’s not the same as the SOL expiring.

    With those definitions in hand, let’s tackle the single most common — and most costly — point of confusion around all of this.

    The Critical Distinction: SOL vs. the 7-Year Credit Reporting Clock

    If you remember only one thing from this article, let it be this: the statute of limitations and the seven-year credit reporting period are two completely separate clocks, and they run on different timelines. People mix them up all the time, and collectors sometimes count on that confusion.

    Here’s the simple version:

    Clock What It Governs Typical Length Set By
    Statute of Limitations (SOL) How long a collector can sue you 3–6 years (varies by state and debt type) State law
    FCRA 7-Year Reporting Period How long the debt can appear on your credit report ~7 years from the first delinquency Federal law (FCRA)

    Two clocks. Two different lengths. Two different legal frameworks. One governs lawsuits, the other governs your credit report. They are not synchronized, and a debt can be in very different stages on each.

    How this plays out in real life

    Imagine a credit card you stopped paying in January 2020. Let’s say you live in a state with a 4-year SOL for open-ended accounts (which is what most credit cards are). Here’s how the two clocks would run:

    • SOL clock: Runs out in January 2024. After that, a collector generally can’t sue you on this debt.
    • Reporting clock: The first missed payment was January 2020. The creditor likely charged it off around July 2020. The 7-year reporting period runs from the first delinquency, so the debt can stay on your credit report until roughly January 2027.

    That means there’s a three-year window where the debt is time-barred (no lawsuit possible) but still showing up on your credit report (hurting your score). People in this window often think, “Well, it’s past the SOL, so it must be off my credit report too.” No. It’s still there, dragging down your score, until the 7-year period expires or you successfully dispute it.

    Conversely, some debts fall off your credit report but are still within the SOL and legally sue-able. This happens when the reporting period is shorter than your state’s SOL, or when a debt has been re-aged or re-reported in ways that need to be challenged.

    Why collectors love this confusion

    When a collector calls about a debt that’s time-barred but still on your credit report, they may pressure you to pay by saying, “This will stay on your credit for years unless you pay it.” That’s technically true — payment won’t remove it faster — but they’re banking on you not knowing that the debt is already past the SOL and that they can’t actually sue you. They want you to act out of fear of a lawsuit that, legally, they can no longer file.

    This is why understanding both clocks is so powerful. When you know where each one stands, you can make informed decisions instead of being bullied into payments that may actually hurt you (by restarting the SOL — see below).

    The bottom line on the two clocks

    • SOL = lawsuit window. Set by your state. Typically 3–6 years. Once it’s up, they generally can’t sue.
    • FCRA 7-year reporting = credit report window. Set by federal law. Runs from the first delinquency that led to the charge-off. Once it’s up, the debt must come off your report.
    • They are separate. A debt can be time-barred and still on your report, or off your report and still sue-able.
    • Knowing both positions tells you your real options. This is exactly the kind of thing a credit repair professional (with attorneys in the background) can help you map out.

    Typical Statute of Limitations Ranges by State

    The statute of limitations on debt is set by state law, not federal law, which means it varies depending on where you live (or, in some cases, where the creditor is headquartered — read your original contract’s choice-of-law clause). Most states group debts into a few legal categories, each with its own deadline.

    Debt types and what they mean

    Debt Type What It Covers Typical SOL Range
    Oral contract A spoken agreement to repay money (no written document) 3–6 years
    Written contract A signed written agreement to repay (e.g., a personal loan, medical debt in some states) 3–6 years (some states up to 10+)
    Promissory note A written promise to pay a specific sum, often with interest (e.g., student loans, some auto loans) 3–6 years (some states up to 15)
    Open-ended account Revolving credit with a balance that changes over time — credit cards, store cards, lines of credit 3–6 years

    A few important caveats:

    • These are general ranges, not exact numbers. State laws change, courts interpret them differently, and some states have quirky rules. Always confirm the current SOL for your specific state and debt type before relying on it. We’ll show you how below.
    • Credit cards are the trickiest. Courts disagree on whether a credit card is an “open-ended account” or a “written contract,” and that distinction can change the SOL by years in some states.
    • Some debts have much longer SOLs. Federal student loans, for example, generally have no statute of limitations — the government can pursue them indefinitely. Some states have long SOLs for child support, tax debts, and judgments (a court judgment itself can often be renewed for 10–20 years).
    • Where you live may not be the only factor. Many credit card agreements include a “choice of law” clause saying which state’s laws apply to disputes. This can sometimes be used to shorten or lengthen the SOL — another reason this gets complicated fast.

    A general snapshot (not a substitute for checking your state)

    As of recent years, the general landscape looks something like this — but please treat this as a starting point, not legal authority:

    • Shorter SOL states (often 3 years for many debt types): States like North Carolina, South Carolina, Maryland, and New Hampshire tend to have shorter windows.
    • Middle-range states (4–6 years): The majority of states fall here, including California (typically 4 years for written contracts and open-ended accounts), Texas (4 years), and Florida (typically 4–5 years).
    • Longer SOL states (6+ years, some up to 10 or 15): States like New York (typically 6 years), Illinois (typically 5–10 years depending on type), and Ohio (typically 6–15 years depending on type) tend toward longer windows. A handful of states have 10-year or even 15-year SOLs for written contracts.

    Again — state laws change, and court interpretations shift. The only way to be confident about your SOL is to check the current statute for your state or, better, work with someone who does this for a living and has attorneys reviewing the details. We’ll cover how to check in a later section.

    Why the category matters so much

    If you’re being sued on an old credit card debt, whether that debt is treated as an “open-ended account” (shorter SOL) or a “written contract” (sometimes longer SOL) can be the difference between winning and losing the case. This is a genuinely technical legal question, and it’s one of the biggest reasons people benefit from having attorney-backed help — not just a DIY dispute, but someone who knows how your state’s courts have ruled on this exact question.

    How the SOL Clock Starts

    A question we hear all the time: “When does the clock actually start running?” The answer is more nuanced than you’d expect, and it matters a lot.

    The general rule: last activity

    In most states, the statute of limitations clock starts running from the date of your last payment — or more precisely, from the date of “last activity” on the account. “Last activity” usually means your most recent payment, but in some states it can also be the date of your last charge, the date of the last written acknowledgment of the debt, or the date the account was charged off.

    Here’s a concrete example. Say you made your last payment on a credit card on March 15, 2021, and you never touched the account again. In a state with a 4-year SOL for open-ended accounts, the clock would start on or around March 15, 2021, and the SOL would expire on or around March 15, 2025. After that date, a collector generally cannot sue you on that debt.

    Variations by state

    Some states start the clock differently:

    • From the date of breach (when you first failed to make a required payment) — this is the most common approach.
    • From the date of charge-off — less common, but some states use this.
    • From the date of the last payment — also common, and often the same as the breach date if you simply stopped paying.
    • From the date the creditor accelerated the debt (declared the full balance immediately due) — in some contract-based debts.

    These differences can shift the SOL date by months, which is sometimes the entire ballgame. If the SOL expires in April but the collector sues you in February, the suit is valid; if they wait until May, it’s not. Every month matters.

    Why this is a frequent battleground

    Collectors sometimes argue that the clock started later than you think — for example, by claiming you made a payment or acknowledged the debt at a date that resets the timeline (more on that next). This is one of the most common ways old-debt lawsuits get fought: not over whether you owe the money, but over when the clock started and whether it has run out.

    Good record-keeping on your end matters here. If you can produce bank statements showing your last payment was in March 2021 and nothing since, that’s strong evidence. If you can’t, the collector may try to fill the gap with their own (sometimes shaky) records.

    What Can Restart the Statute of Limitations

    This is where a lot of people get burned. In many states, certain actions on your part can restart the statute of limitations clock from zero, effectively giving the collector a fresh window to sue you. This is called “reviving” or “tolling” the debt, and the rules vary — you guessed it — by state.

    The actions that can restart the SOL typically fall into a few categories:

    1. Making a payment

    In many states, making any payment on an old debt — even a tiny one — can restart the SOL. A collector calls, pressures you, and you think, “I’ll just send $20 to get them off my back.” That $20 can reset the clock entirely, giving the collector a brand-new multi-year window to sue you. This is one of the most common traps we see.

    It doesn’t matter whether the payment was voluntary, coerced, or even a settlement offer. In many jurisdictions, any payment is enough to revive the debt. Some states require the payment to be accompanied by a written acknowledgment, but many don’t.

    2. Making a written acknowledgment of the debt

    In some states, signing a written acknowledgment that you owe the debt can restart the SOL. This might include:

    • Signing a payment agreement or new contract with the collector.
    • Sending a letter that says, “I acknowledge I owe this debt and I intend to pay.”
    • Signing a settlement offer in writing.

    The exact rule varies. Some states require the acknowledgment to be in writing and signed; some require it to be a clear admission of the debt; some are more lenient. But the general principle is the same: if you formally admit the debt is yours and valid, you may reset the clock.

    3. Making a settlement offer

    In some states, offering to settle the debt — even if the offer is rejected — can be treated as an acknowledgment that revives the SOL. This is less universal than the payment rule, but it’s real in several jurisdictions.

    4. A partial payment agreement

    Entering into a written payment plan or agreeing to make partial payments can restart the clock in many states, for the same reasons a payment does.

    What generally does NOT restart the clock

    • Merely discussing the debt on the phone. A verbal acknowledgment usually isn’t enough to revive a debt in most states (though a few are stricter). That said, collectors record these calls and will try to get you to say things they can use — so silence is safer.
    • Disputing the debt. Sending a validation dispute letter (which we’ll cover) does not restart the SOL because you’re not acknowledging the debt; you’re challenging it.
    • A collector reporting the debt. Their actions don’t restart the clock — only yours do.

    The safe move

    If a collector contacts you about an old debt, do not make any payment, do not acknowledge the debt in writing, and do not agree to a settlement — until you know whether the debt is time-barred. This is the single most important protective step you can take. A few minutes of caution can save you years of legal exposure.

    Here’s the trap collectors often set: they call about a debt that’s two months from being time-barred. They’re friendly, they offer you a “deal,” they say a small payment will show good faith. You send $50. The clock resets. Now they have another 3–6 years to sue you, and you’ve just handed them that power. Don’t do it.

    What “Time-Barred” Means and Your Rights

    When a debt passes its statute of limitations, it becomes time-barred. That’s a legal term with real teeth. Here’s what it means for you.

    What time-barred does NOT mean

    Let’s clear up the biggest misconception first. A time-barred debt:

    • Does not disappear. You may still technically owe the money.
    • Does not automatically come off your credit report. That’s the separate 7-year FCRA clock.
    • Does not prevent collectors from contacting you. They can still call and write (within FDCPA limits).
    • Does not prevent them from asking you to pay voluntarily. You can choose to pay a time-barred debt if you want to.

    What time-barred DOES mean

    A time-barred debt gives you strong legal protections:

    • Collectors generally cannot sue you. Filing a lawsuit on a time-barred debt is, in most courts, a violation of the Fair Debt Collection Practices Act (FDCPA). The FDCPA prohibits collectors from using false or deceptive means to collect, and courts have repeatedly held that suing on a debt you legally can’t enforce is deceptive and abusive.
    • Collectors cannot threaten to sue you on a time-barred debt. Even the threat of a lawsuit on time-barred debt is an FDCPA violation. If a collector says, “We’ll take you to court if you don’t pay,” on a debt that’s past the SOL, that’s illegal — and you may have a claim against them.
    • If they do sue you, you have an absolute defense. You can raise the expired SOL as an affirmative defense and ask the court to dismiss the case. But — and this is critical — you have to actually raise the defense. If you ignore the lawsuit, the collector can get a default judgment against you, even on a time-barred debt. More on this in the lawsuit section.

    The FDCPA’s role

    The Fair Debt Collection Practices Act (FDCPA) is a federal law that governs how third-party debt collectors can operate. (It generally doesn’t apply to original creditors, only to third-party collectors and debt buyers.) Among its many protections, the FDCPA:

    • Prohibits collectors from suing or threatening to sue on time-barred debts.
    • Requires collectors to send you a validation notice within 5 days of first contact.
    • Gives you the right to dispute the debt and demand validation within 30 days.
    • Prohibits harassment, false statements, and unfair practices.
    • Limits when and how collectors can contact you.

    The FDCPA is a powerful tool, but it only works if you know your rights and assert them. Collectors violate it every day, betting that consumers don’t know the rules. Knowing that a time-barred debt is legally unenforceable — and that threatening to sue on one is illegal — flips the power dynamic.

    A note on state laws

    Many states have their own debt collection laws that go beyond the FDCPA, sometimes covering original creditors (which the FDCPA doesn’t) or adding additional protections. California’s Rosenthal Act, for example, extends FDCPA-like rules to original creditors. If your state has stronger consumer protection laws, you may have even more leverage than the federal floor provides. This is where attorney-backed guidance really pays off — knowing both the federal framework and your state’s specific overlays.

    How to Respond if a Collector Calls on an Old Debt

    A collector calls about an old debt. What do you actually do, step by step? Here’s the playbook.

    1. Don’t panic, and don’t say much

    Your first goal on the call is to gather information without giving any. Collectors record calls. Everything you say can and will be used against you. Do not acknowledge the debt. Do not agree to pay anything. Do not confirm personal details beyond your identity (and even that, cautiously).

    2. Ask for the details

    Get the basics, writing them down if you can:

    • The name of the collection agency and the original creditor.
    • The account number and the amount they claim you owe.
    • The date of your last payment (ask them what they have on file — this helps you figure out the SOL).
    • Their mailing address (you’ll need this for the validation letter).

    3. Say as little as possible

    A good script: “I’m not discussing any debt today. Please send me the validation notice in writing. I’ll review it and respond.” Then end the call. You are not obligated to talk to them, and silence is your safest position until you know the SOL status.

    4. Send a validation letter within 30 days

    Under the FDCPA, collectors must send you a validation notice within 5 days of first contacting you. Once you receive it, you have 30 days to dispute the debt and demand validation. If you do, the collector must stop collection activities until they provide proof that you owe the debt and that the amount is correct.

    This is one of the most underused consumer protections out there. A validation letter:

    • Forces the collector to prove the debt is yours.
    • Forces them to prove the amount is correct.
    • Stops collection activity while they gather the proof.
    • Sometimes causes them to drop the matter entirely (especially if the debt has been sold multiple times and the records are thin).

    Your validation letter should be simple and should not acknowledge the debt. Something like: “I am disputing this debt and requesting validation. Please provide the original creditor’s name, the account number, the amount owed, and proof that I am responsible for this debt.” Send it by certified mail with a return receipt so you have proof they received it.

    5. Check the SOL

    Once you have the details — especially the date of your last payment — figure out whether the debt is past your state’s statute of limitations. If it is, you have much more leverage. You can:

    • Send a cease-and-desist letter demanding they stop contacting you (the FDCPA requires them to comply, with limited exceptions).
    • Use the time-barred status as leverage if they’re threatening to sue (which would be an FDCPA violation).
    • Decide whether to pay, settle, or simply let it age off your report.

    6. Don’t pay anything until you’ve done all of the above

    The temptation to “just make it go away” with a quick payment is exactly what collectors prey on. Any payment can restart the SOL. Don’t send a dime until you know where you stand and have a clear strategy.

    A warning about “settlement” offers

    Collectors love to offer “settlements” on old debts — “Pay 40% and we’ll consider it settled.” These offers can be legitimate, but they can also be traps:

    • Paying may restart the SOL on the remaining balance (though settled debts are usually considered closed — read the terms carefully).
    • A settlement may be reported as “settled for less than full balance,” which is still a negative mark on your credit report.
    • If the debt is time-barred, you may be paying money you’re not legally required to pay.

    If you’re considering a settlement, do it strategically, in writing, and ideally with professional guidance.

    Zombie Debt: Old Debts Resold and Re-Aged

    There’s a special category of old debt that deserves its own discussion: zombie debt. These are debts that should be dead — they’re past the SOL, they’re already been paid, they were discharged in bankruptcy, they were never yours in the first place — but they keep coming back, sold and resold to increasingly aggressive collectors who try to revive them.

    How zombie debt happens

    When you stop paying a debt, the original creditor may sell it to a debt buyer at pennies on the dollar. That debt buyer may try to collect for a while, then sell it again to another buyer for even less. Each sale adds a layer of separation from the original records. By the time a debt has been sold three or four times, the documentation is often a mess — missing signatures, incomplete account histories, wrong amounts.

    Some debt buyers specialize in buying these near-worthless, out-of-statute debts for fractions of a cent on the dollar, then aggressively pursuing consumers who don’t know their rights. Their business model relies on a small percentage of people either paying out of fear or accidentally restarting the SOL.

    The re-aging problem

    One of the most abusive practices in the zombie debt world is re-aging — when a collector reports an old debt to the credit bureaus with a newer date, making it look fresh. This is illegal under the FCRA. The reporting clock starts from the date of first delinquency with the original creditor, and no amount of reselling or re-reporting can legally reset it.

    But it happens. A debt buyer picks up a 2018 charge-off and reports it to the bureaus with a 2024 date of last activity. Suddenly, a debt that should fall off your report in 2025 looks like it’ll stay until 2031. This is a serious violation, and it’s exactly the kind of thing that FCRA disputes and attorney-backed credit repair are designed to catch and correct.

    How to fight zombie debt

    If you suspect a debt on your report is zombie debt — re-aged, out of statute, or not yours — here’s the approach:

    • Dispute it with the credit bureaus. Under the FCRA, you have the right to dispute any inaccurate information on your credit report. The bureau must investigate within 30 days (generally) and remove unverifiable information. Cite the correct date of first delinquency if you know it.
    • Send a validation letter to the collector. Force them to prove the debt is yours, the amount is correct, and the dates are accurate. Many zombie debt buyers can’t produce adequate documentation and will drop the claim.
    • Document everything. Keep records of when the debt was first delinquent, when it was charged off, and any communications from collectors. This paper trail is your evidence.
    • Consider legal action. If a collector is reporting re-aged debt or threatening to sue on a time-barred debt, they may be violating the FDCPA or FCRA — and you may have grounds to sue them. Consumer protection attorneys often take these cases on contingency.

    Zombie debt is scary precisely because it exploits people’s lack of knowledge. The moment you understand your rights, the threat shrinks dramatically. A debt that’s past the SOL and misreported on your credit report is not a problem to fear — it’s a problem to fix, and you have the law on your side.

    How to Handle a Lawsuit on an Old Debt

    If you actually get served with a lawsuit on an old debt, the stakes are higher — but you still have strong defenses. Here’s what to do.

    1. Do not ignore it

    The worst thing you can do is nothing. If you ignore a lawsuit, the collector can get a default judgment against you — even if the debt is time-barred. A default judgment is what the court enters when you don’t respond. It basically says, “The plaintiff wins by default because the defendant didn’t show up.” At that point, the SOL defense is lost, and the collector can pursue wage garnishment, bank levies, and property liens.

    This is the biggest trap with old-debt lawsuits. Collectors file them on time-barred debts hoping you won’t respond. Many people don’t, either out of fear, confusion, or the mistaken belief that the SOL protects them automatically. It doesn’t. You have to raise the SOL defense.

    2. Check the SOL immediately

    Look at the date of your last payment on the debt and your state’s SOL. If the debt is time-barred, you have an affirmative defense. Calculate the date carefully — this is not the moment to guess.

    3. File a response and raise the SOL defense

    You typically have a limited window (often 20–30 days, varies by state) to file a written response to the lawsuit. In your response, you raise affirmative defenses, one of which is that the debt is past the statute of limitations. This forces the collector to prove the debt is still within the SOL — and if it’s not, the case should be dismissed.

    4. Demand proof of the debt

    In addition to the SOL defense, demand that the collector produce documentation proving:

    • The debt is actually yours.
    • The amount is correct.
    • They have the legal right to collect it (chain of assignment if it’s been sold).
    • The date of your last payment (which establishes the SOL timeline).

    Debt buyers, especially those dealing in old debts, often have thin documentation. If they can’t prove the debt, they can’t win — even if the SOL hasn’t expired.

    5. Consider counterclaims

    If the collector has violated the FDCPA (by suing or threatening to sue on a time-barred debt, for example), you may have counterclaims. You could potentially recover damages, attorney’s fees, and costs. This is where having an attorney becomes especially valuable — they can evaluate whether the collector’s conduct gives you leverage to flip the case.

    6. Get help if you need it

    Defending a lawsuit is technical. Deadlines are strict, court procedures are formal, and the consequences of a mistake are serious. If you’re sued on an old debt, this is the moment where professional help earns its keep. An attorney (or an attorney-backed credit repair firm like ours) can:

    • Evaluate whether the debt is actually time-barred.
    • Prepare and file your response.
    • Raise the SOL defense properly.
    • Challenge the collector’s documentation.
    • Identify FDCPA or FCRA violations that give you leverage.
    • Negotiate a settlement or dismissal from a position of strength.

    You don’t have to face this alone, and you shouldn’t. The good news is that old-debt lawsuits are very winnable when the SOL defense is properly raised.

    What Happens If You Pay an Old Debt

    This is one of the most important sections in this article, because well-meaning people sabotage themselves here all the time. Here’s what can happen when you pay an old debt — and why “doing the right thing” can sometimes backfire.

    Paying can restart the SOL

    As we covered, making a payment on an old debt can restart the statute of limitations in many states. If the debt was three months from being time-barred and you make a payment, you may have just given the collector another 3–6 years to sue you. This is true even if you only paid a small amount, and even if the payment was coerced by collector pressure.

    Paying can update the report date

    Paying an old debt can also update the date of last activity on your credit report. While the FCRA’s 7-year reporting clock is supposed to run from the original date of first delinquency, a payment can cause the account to be re-reported with a more recent activity date, which may make the negative mark look fresher than it is and potentially extend how long it appears to affect your score. This is a gray area and a source of real consumer harm, and it’s something to be very careful about.

    Paying a collection account doesn’t remove it

    A common misconception: “If I pay the collection, it’ll come off my credit report.” No. Paying a collection generally updates it to “paid” or “paid, settled” status, but the negative mark remains on your report for the remainder of the 7-year reporting period. A paid collection can still drag down your score, just slightly less than an unpaid one. Newer credit scoring models (FICO 9, VantageScore 3.0+) ignore paid collections, but many lenders still use older models that don’t.

    When paying an old debt might make sense

    None of this means you should never pay an old debt. There are situations where it’s the right move:

    • The debt is recent and within the SOL. If you’re still in the lawsuit window and you can afford to pay or settle, doing so may be smarter than risking a judgment.
    • You’re applying for a mortgage. Many mortgage lenders require that collection accounts be paid or settled before closing, regardless of age. Paying may be necessary to get the loan.
    • You want peace of mind. Some people simply don’t want old debts hanging over them, and paying — even a time-barred debt — is worth it to them for the mental relief. That’s a valid choice, as long as it’s informed.
    • You’ve negotiated a favorable settlement. If a collector will take a small fraction of the balance in exchange for closing the account, and you’ve confirmed in writing that the payment won’t restart the SOL on any remaining balance, it can be a good deal.

    The key: decide strategically, not reactively

    The danger isn’t paying an old debt — it’s paying it reactively, under collector pressure, without understanding the consequences. The right approach is to first understand where the debt stands on both clocks (SOL and reporting), then decide based on your goals and the full picture. That’s exactly what a thoughtful, attorney-backed credit repair process helps you do.

    How to Check Your State’s Statute of Limitations

    So how do you actually find out your state’s SOL for a specific debt? Here’s the practical approach.

    1. Identify the type of debt

    First, figure out what kind of debt you’re dealing with — credit card (usually open-ended), personal loan (usually written contract), medical debt (varies), auto loan (varies), etc. The category determines which SOL applies.

    2. Find your last payment date

    Pull your old bank statements, credit reports, or account records to find the date of your last payment. This is the starting point for the SOL clock in most states. If you’re not sure, the date of first delinquency on your credit report is a good proxy.

    3. Look up your state’s SOL

    You can find your state’s statute of limitations through:

    • Your state’s consumer protection agency or attorney general’s website (many publish SOL summaries).
    • Reputable consumer law resources (Nolo, the CFPB, and similar).
    • A consumer protection attorney in your state.
    • An attorney-backed credit repair firm (like us) that can research and confirm it for you.

    4. Calculate carefully

    Add your state’s SOL to your last-payment date. If the result is in the past, the debt is likely time-barred. If it’s in the future, you’re still within the SOL window and need to be more careful.

    5. Confirm with a professional

    SOL calculations have a lot of moving parts — choice-of-law clauses, tolling rules, restart events, debt-type classifications. If the debt is large or you’re facing a lawsuit, confirm your calculation with someone who does this professionally. A small mistake can be expensive.

    Common Mistakes to Avoid

    We’ve covered a lot of ground. Let’s consolidate the most common mistakes people make with old debts — mistakes that can restart clocks, extend negative reporting, or cost real money.

    Mistake 1: Acknowledging the debt on a collector’s call

    The collector is recording. You’re not. Anything you say — “I know I owe it but I can’t pay right now,” “I’ll try to send something next month,” “I think I made a payment last year” — can be used to restart the SOL or establish a timeline. Say as little as possible. Dispute in writing.

    Mistake 2: Making a “good faith” payment

    A $20 payment to get a collector off your back can reset the SOL for years. Never make a payment on an old debt without first confirming the SOL status and understanding the consequences.

    Mistake 3: Ignoring a lawsuit

    A time-barred debt doesn’t protect you if you don’t show up to court and raise the defense. Always respond to a lawsuit. Default judgments are how collectors win cases they should lose.

    Mistake 4: Confusing the SOL with the 7-year reporting clock

    They’re separate. A debt can be off your report and still sue-able, or time-barred and still on your report. Know where both clocks stand.

    Mistake 5: Assuming paying will fix your credit

    Paying an old collection updates it to “paid” but doesn’t remove it from your report. Understand what payment will and won’t do before you send money.

    Mistake 6: Trusting a collector’s timeline

    Collectors have every incentive to make a debt seem newer than it is. Verify dates independently through your own records and credit reports.

    Mistake 7: Not disputing re-aged debts

    If an old debt shows up on your report with a newer date, that’s likely an FCRA violation. Dispute it. Don’t let zombie debt sit on your report unchallenged.

    Mistake 8: Going it alone on a lawsuit

    If you’re sued, the procedural rules are unforgiving. Get professional help. Attorney-backed guidance can be the difference between winning and a default judgment.

    Frequently Asked Questions

    Can a collector still contact me about a time-barred debt?

    Yes. A time-barred debt doesn’t vanish — the collector can still attempt to collect it through calls and letters, as long as they don’t threaten to sue or actually sue (both of which are FDCPA violations on time-barred debt). You can send a cease-and-desist letter demanding they stop contacting you, and under the FDCPA they generally must comply (with limited exceptions, like notifying you of specific actions). If they continue to harass you after receiving the letter, you may have an FDCPA claim.

    Does the statute of limitations apply to all types of debt?

    No. Most consumer debts (credit cards, personal loans, medical bills, auto loans) have an SOL. But some debts are special cases:

    • Federal student loans generally have no SOL — the government can pursue them indefinitely.
    • Federal tax debt generally has a 10-year collection statute, but it can be extended in various ways.
    • Child support often has no SOL or a very long one.
    • Court judgments can often be renewed for 10–20 years depending on the state.
    • Some state tax debts have their own long collection windows.

    If you’re dealing with one of these special categories, the general SOL rules in this article may not apply — get specific guidance.

    Can a debt collector sue me after the SOL has expired?

    They can file the lawsuit (courts don’t automatically screen for SOL), but if you raise the SOL as a defense, the case should be dismissed. Suing or threatening to sue on a time-barred debt is an FDCPA violation. The key is that you must respond and raise the defense — ignoring the lawsuit leads to a default judgment that bypasses the SOL entirely.

    Will paying an old debt improve my credit score?

    Not immediately, and maybe not much. Paying a collection updates it to “paid” status, which is better than “unpaid” but doesn’t remove the negative mark from your report. The collection still shows for the remainder of the 7-year reporting period. Newer scoring models (FICO 9, VantageScore 3.0+) ignore paid collections, but many lenders use older models (FICO 8) that don’t. If your goal is credit score improvement, there are often more effective strategies than simply paying an old collection — which is where a thoughtful credit repair process comes in.

    How do I know if a debt has been re-aged illegally?

    Re-aging means a collector reports an old debt to the credit bureaus with a newer date than the actual date of first delinquency. Signs of re-aging:

    • A debt you recognize as old suddenly shows a recent “date of last activity” on your credit report.
    • A debt that should be approaching the 7-year reporting limit appears to have a fresh reporting date.
    • A collection account shows up that you’ve never seen before, for a very old debt.

    If you see any of these, pull your credit reports from all three bureaus, compare the dates, and dispute the inaccurate information. Re-aging is an FCRA violation, and you have the right to have it corrected.

    What’s the difference between the FDCPA and the FCRA?

    They’re two separate federal laws that protect consumers in different ways:

    • FDCPA (Fair Debt Collection Practices Act) governs how debt collectors can behave — who they can contact, when, what they can say, and what they can’t do (like suing on time-barred debt, harassing you, or making false statements).
    • FCRA (Fair Credit Reporting Act) governs how credit bureaus and creditors report and handle your credit information — accuracy, dispute rights, how long items can stay on your report, and your right to see and correct your report.

    Both are relevant to old debts: the FDCPA protects you from abusive collection tactics, and the FCRA protects you from inaccurate credit reporting. A good credit repair strategy uses both.

    Should I ever pay a time-barred debt?

    It depends on your goals. If you’re applying for a mortgage and the lender requires it, yes. If you want peace of mind and can afford it, maybe. If the debt is time-barred, off your credit report soon, and the collector is just fishing — probably not. The key is to decide strategically, in writing, with full knowledge of the consequences — not reactively under collector pressure.

    Can a creditor restart the SOL without my action?

    Generally no — only your actions (payment, written acknowledgment, settlement offer) restart the clock in most states. A creditor simply reporting the debt, selling it, or contacting you does not restart the SOL. This is an important protection: the clock keeps running regardless of what the creditor does. But be aware that some states have tolling rules that can pause the clock in specific situations (e.g., if you leave the state or file for bankruptcy). These are less common but worth confirming.

    Get Attorney-Backed Guidance on Your Old Debts

    Understanding the statute of limitations on debt is one thing. Navigating it — with collectors calling, lawsuits threatening, and your credit on the line — is another. That’s where we come in.

    We’re a San Diego-based credit repair firm dedicated to helping individuals and families take control of their financial future. Our approach is attorney-backed and fully compliant with federal credit laws like the FCRA and FDCPA. We don’t just send form letters — we work alongside experienced attorneys to make sure every step of the process is ethical, accurate, and effective.

    Here’s what that means for you when you’re dealing with old debts:

    • A real audit of your credit situation, across all three major bureaus, to identify what’s actually on your report and whether dates, amounts, or reporting statuses are accurate.
    • Clear guidance on your state’s statute of limitations, including whether specific debts are time-barred and what that means for your options.
    • Strategic disputes under the FCRA to challenge re-aged debts, inaccurate dates, and unverifiable accounts.
    • FDCPA-aware handling of collector communications, including validation requests and cease-and-desist letters when appropriate.
    • A customized plan tailored to your goals — whether that’s buying a house, cleaning up old mistakes, or just getting creditors off your back.
    • Education and empowerment so you understand not just what we’re doing, but why — and how to keep your credit strong long after the work is done.

    We believe in transparency. No hidden fees, no misleading claims, no unnecessary services. We won’t tell you old debts magically disappear, because they don’t. We won’t promise a perfect credit score overnight, because that’s not how the law works. What we will do is give you an honest assessment of where you stand, a clear plan for moving forward, and the legal backing to make it stick.

    If you’re dealing with old debts, collector calls, or an old-debt lawsuit — or if you just want to understand what’s really on your credit report and what your options are — start with a free credit audit at . We’ll review your situation, map out where each of your debts stands on both the SOL and reporting clocks, and give you a straightforward plan for next steps.

    You don’t have to figure this out alone. And you shouldn’t — not when the law gives you this many tools to protect yourself.

    This article is educational and does not constitute legal advice. Statutes of limitations vary by state and by debt type, and state laws change over time. If you are facing a lawsuit or dealing with aggressive collection activity, consult with a qualified attorney or an attorney-backed credit repair firm to understand your specific rights and options.

    Ready to take the next step? Get your free credit audit at — attorney-backed guidance on old debts, credit reporting errors, and everything in between.


  • Debt Management Plans: How Nonprofit Credit Counseling Works

    Debt Management Plans: How Nonprofit Credit Counseling Works

    Related topics: understand how a DMP affects your credit utilization ratio, get 9 credit repair tips you can use on your own, see how long credit repair takes so you can plan realistically, or request a free consultation to explore professional options.

    If you’re juggling multiple credit card bills, watching interest pile up faster than you can pay down balances, and fielding calls from creditors you’d rather not answer, you’re not alone — and you’re not out of options. Millions of Americans reach a point where minimum payments are no longer enough, and the treadmill of high-interest debt starts to feel impossible to step off.That’s where a debt management plan (DMP) comes in.

    A DMP is a structured repayment program coordinated through a nonprofit credit counseling agency that negotiates with your creditors on your behalf — often securing lower interest rates, waived fees, and a single, predictable monthly payment. It’s not a loan. It’s not debt settlement. It’s not bankruptcy. It’s a proven, legally sound path back to financial stability that has helped people pay off billions in unsecured debt over the past several decades.

    This guide walks you through everything you need to know: what a DMP is, how it works, what it does to your credit, how it compares to debt settlement and bankruptcy, how to find a legitimate nonprofit agency, and how a DMP can actually work alongside professional credit repair to rebuild your financial life from the ground up.

    We’ll keep it straightforward, because that’s how this should be. No quick-fix promises. No scare tactics. Just honest, step-by-step information you can use.

    What Is a Debt Management Plan (DMP)?

    A debt management plan (DMP) is a structured repayment program offered by nonprofit credit counseling agencies to help consumers pay off unsecured debt — primarily credit cards, personal loans, medical bills, and similar obligations — over a set period, usually three to five years.

    Here’s the key distinction that trips a lot of people up: a DMP is not a loan. You’re not borrowing money to pay off other debts. Instead, a certified credit counselor reviews your full financial picture, helps you build a workable budget, and then — if a DMP makes sense for your situation — negotiates with your creditors to secure more favorable repayment terms.

    Those terms typically include:

    • Reduced interest rates — often dramatically lower than what you’re currently paying, sometimes dropping from 25%+ APR down to single digits
    • Waived or reduced fees — late fees, over-limit fees, and penalty charges that have been piling up
    • A single consolidated monthly payment — you pay the counseling agency once, and they disburse funds to each of your creditors
    • A clear payoff timeline — typically 36 to 60 months, with a defined end date

    The DMP itself is a voluntary agreement. Your creditors aren’t legally forced to participate, but most major credit card issuers work with NFCC-approved counseling agencies on standardized terms. Why? Because they’d rather get repaid (even at a lower interest rate) than risk you defaulting entirely or filing for bankruptcy.

    The counseling agency doesn’t lend you money, doesn’t buy your debt, and doesn’t take ownership of your accounts. They act as an intermediary — a trusted coordinator between you and your creditors — while you do the work of making consistent payments and rebuilding your financial footing.

    It’s worth noting what a DMP is not: it’s not debt settlement (where you pay a lump sum for less than you owe), it’s not a consolidation loan (where you take on new debt to pay old debt), and it’s not bankruptcy (a legal proceeding that discharges or restructures debt through the courts). We’ll get into those distinctions in detail shortly, because understanding the difference matters — a lot.

    How a DMP Differs from Debt Settlement and Consolidation

    People use “debt relief,” “debt consolidation,” and “debt management” almost interchangeably, but they’re three very different things with very different consequences for your credit, your taxes, and your legal standing.

    Let’s break each one down clearly.

    Debt Management Plan (DMP)

    • Who runs it: A nonprofit credit counseling agency
    • What it does: Negotiates lower interest and waived fees; you repay 100% of what you owe over 3–5 years
    • Effect on credit: Generally neutral to mildly positive over time; the DMP itself doesn’t appear on your credit report
    • Cost: Low setup fee (usually capped around $25–$50) and small monthly fee (typically $10–$25), often waivable based on hardship
    • Tax impact: None — you’re paying the full balance, so no forgiven debt to report as income

    Debt Settlement

    • Who runs it: For-profit companies (often heavily marketed online and on TV)
    • What it does: You stop paying creditors, save money in a third-party account, and the company attempts to negotiate lump-sum settlements for less than you owe
    • Effect on credit: Severely damaging — you’ll rack up late payments, charge-offs, and possibly collections while the settlement is being negotiated
    • Cost: Often 15–25% of the enrolled debt, charged on the amount “saved”
    • Tax impact: Forgiven debt over $600 is generally reported to the IRS as taxable income
    • Risk: Creditors can sue you during the process, and there’s no guarantee they’ll agree to settle

    Debt Consolidation Loan

    • What it does: You take out a new loan (personal loan, balance transfer card, or home equity loan) to pay off multiple debts, leaving you with one monthly payment
    • Effect on credit: Mixed — a hard inquiry and new account ding your score initially, but lower credit utilization can help over time
    • Cost: Depends on your credit score and the loan’s APR; if your credit is already damaged, you may not qualify for a rate that actually helps
    • Risk: You’re moving debt around, not eliminating it — and if you run the credit cards back up after paying them off, you’ll be in worse shape than before

    The Bottom Line

    A DMP is the only option where you repay what you owe in full, work with a nonprofit (not a for-profit company incentivized by fees), and avoid the credit damage of settlement or the legal weight of bankruptcy. It’s also the option most grounded in financial education — the counseling agency’s job isn’t just to manage your payments, but to help you understand how you got here and how to stay out.


    What Happens in a Credit Counseling Session

    Before anyone puts you on a DMP, you’ll have a credit counseling session — and this first conversation is one of the most valuable parts of the entire process. It’s typically free, takes about 45 to 60 minutes, and can be done over the phone, online, or in person at a local agency office.

    Here’s what to expect.

    1. A Full Financial Review

    Your counselor will ask about your income, your monthly expenses, all of your debts (balances, interest rates, minimum payments), and any assets you have. Be honest. The more accurate your numbers, the better the advice. This isn’t a test you can fail — it’s a diagnostic, like a doctor asking where it hurts before recommending treatment.

    2. A Budget Built Together

    Using your income and expenses, the counselor helps you construct a realistic monthly budget. This isn’t about guilt-tripping you for your coffee habit — it’s about seeing clearly where your money goes and identifying what’s sustainable. Often, people discover they have more room than they thought, or that certain expenses can be trimmed without gutting their quality of life.

    3. A Review of All Your Options

    A good counselor won’t push you into a DMP. They’ll explain every viable path:

    • A DMP, if your debt is primarily unsecured and your income can support the monthly payment
    • Self-directed repayment, if a revised budget frees up enough to tackle debts more aggressively on your own
    • Referral to a bankruptcy attorney, if your debt load is truly unmanageable relative to your income
    • Referral to legal aid or other resources, if you’re dealing with specific issues like medical debt or predatory lending

    4. A Recommendation (Not a Sales Pitch)

    If a DMP makes sense, the counselor will explain the proposed terms: estimated monthly payment, projected payoff timeline, which creditors are likely to participate, and what fees the agency charges. You’ll get this in writing. You’re under no obligation to enroll on the spot — take the paperwork, think it over, ask questions.

    If a DMP doesn’t make sense — say, your debt is too low, your income is too inconsistent, or most of your debt is secured (like a car loan or mortgage) — the counselor will tell you that too. A legitimate nonprofit agency has no incentive to enroll you in a program that won’t help.

    This initial session, by itself, is often worth the time even if you never enroll in a DMP. Many people walk away with a clearer budget, a better understanding of their options, and a concrete action plan — all at no cost.

    How a DMP Actually Works, Step by Step

    If you decide to enroll after your counseling session, here’s what happens — and in what order.

    Step 1: You Submit a Proposal to Creditors

    Your counselor drafts a proposal for each of your creditors. This document outlines your financial situation, the proposed monthly payment, the requested interest rate, and the requested fee waivers. The proposal is sent to each creditor through the counseling agency, often through pre-existing relationships the agency has with major lenders.

    Most major credit card issuers — banks like Chase, Citi, Bank of America, Capital One, Discover, and others — have established creditor guidelines for DMPs. These guidelines set standard terms (e.g., interest rate reduced to 6–9%, late fees waived, account closed to new charges). Because the agency is NFCC-approved and operating under these established guidelines, approval is often quick — typically within a few days to a couple of weeks.

    Step 2: Creditors Accept (or Counter)

    Most creditors accept DMP proposals as submitted. Occasionally, a creditor may counter with slightly different terms — a higher interest rate, for example, or a requirement that you make one or two on-time payments directly before the plan kicks in. Your counselor communicates these counteroffers back to you, and the plan is adjusted accordingly.

    A small number of creditors — some store cards, certain subprime lenders, and a few credit unions — may decline to participate. Your counselor will let you know which accounts are and aren’t included, and you can continue paying those directly.

    Step 3: You Make One Monthly Payment to the Agency

    Once the plan is in place, you make one monthly payment to the counseling agency. This payment is typically auto-drafted from your checking account on a date you choose (often aligned with your payday). The amount stays the same every month — no surprises, no escalating minimums.

    Step 4: The Agency Disburses Funds to Your Creditors

    The agency takes your single payment and distributes it across all participating creditors according to the agreed-upon terms. This happens behind the scenes — you don’t have to manage multiple payments, track due dates, or worry about one creditor getting paid while another slips through the cracks.

    You’ll receive regular statements showing exactly how much went to each creditor, the remaining balance, and your projected payoff date. Transparency is a hallmark of legitimate nonprofit counseling.

    Step 5: You Complete the Plan and Graduate

    Most DMPs run 36 to 60 months. If you make every payment on time, you’ll graduate debt-free from all enrolled accounts on the projected date. Many agencies celebrate graduations — it’s a genuine milestone, and the counseling community takes it seriously.

    After graduation, you’ll have zero balances on your enrolled cards, a rebuilt payment history, and (usually) a meaningfully improved credit score. Your counselor will often do a final session to review your post-DMP budget and help you plan for the next phase — whether that’s saving, investing, or responsibly re-establishing credit.

    Typical DMP Terms: What You Can Expect

    Every DMP is tailored to your specific debts and income, but most share a common structure. Here’s what the typical terms look like in practice.

    Duration

    • Standard range: 36 to 60 months (3 to 5 years)
    • Maximum: Most agencies cap plans at 60 months; some may extend slightly under special circumstances, but creditor guidelines generally set the ceiling
    • Minimum: If your debts could be paid off in under 36 months with a revised budget, a counselor may recommend self-directed repayment instead of a DMP

    Interest Rates

    • Pre-DMP average credit card APR: Often 20–29% (and higher for subprime cards)
    • Typical DMP negotiated APR: 6–12%, depending on the creditor and their specific guidelines
    • Some creditors offer rates as low as 0–2% on DMPs, though this is less common
    • The interest reduction is the single biggest financial benefit of a DMP — it means far more of each payment goes to principal rather than getting eaten by finance charges

    Fees

    • Setup fee: Typically $10–$35, sometimes waived entirely
    • Monthly maintenance fee: Usually $10–$25 per month, deducted from your monthly payment
    • Fee waivers: Most agencies waive or reduce fees for clients facing genuine hardship (unemployment, medical issues, etc.)
    • No upfront fees: Legitimate nonprofit agencies do not charge large upfront fees before services are rendered — this is both an ethical standard and a legal requirement under federal telemarketing rules

    Accounts Included

    • Included: Unsecured debts — credit cards, store cards, personal loans, medical bills, collection accounts (in some cases)
    • Not included: Secured debts (auto loans, mortgages), student loans (handled through separate federal programs), and certain specialized debts
    • Account closure: All credit card accounts enrolled in the DMP are closed to new charges. You keep the accounts (which helps your credit age), but you can’t use the cards during the plan.

    Payment Amount

    Your monthly payment is calculated based on what you can afford after essential expenses — not on a one-size-fits-all formula. The counselor works backward from your income and budget to arrive at a sustainable figure, then confirms that figure will retire all enrolled debts within the 60-month window.

    If the math doesn’t work — if your income can’t support a payment that would pay off your debts within five years even at reduced interest — the counselor will tell you. A DMP isn’t the right fit for everyone, and a good agency would rather refer you to bankruptcy counseling than set you up for a plan you can’t complete.

    How a DMP Affects Your Credit

    This is the question people ask most often, and it deserves a thorough, honest answer — because the reality is more nuanced than the marketing from either DMP promoters or DMP skeptics would suggest.

    The DMP Itself Doesn’t Appear on Your Credit Report

    Let’s start with the most important fact: a debt management plan is not a separate entry on your credit report. The three major bureaus — Equifax, Experian, and TransUnion — do not list “enrolled in a DMP” as a standalone item. There’s no public record, no notation that screams “this person is in credit counseling” to anyone who pulls your report.

    What Does Appear: Account Closures and Notations

    Here’s where the nuance comes in. When you enroll a credit card in a DMP:

    • The account is closed — typically by the creditor, sometimes at your request. A closed account shows on your report with a status like “closed by credit grantor” or simply “closed.” This can cause a small, temporary dip in your score because it reduces your available credit and can slightly affect your credit utilization ratio (if you have other open accounts).
    • A “credit counseling” notation may appear — some creditors add a comment to the account on your credit report indicating it’s being paid through a counseling agency, often phrased as “account managed by credit counseling” or “paid through partial payment plan.” This notation is informational; it doesn’t carry a point value.

    FICO Ignores DMP Notations

    Here’s the part most people don’t know: FICO scoring models ignore “credit counseling” or “partial payment plan” notations entirely. According to FICO’s own published guidance, comments indicating enrollment in a DMP are not factored into the score calculation. Your FICO score is driven by payment history, amounts owed, length of credit history, credit mix, and new credit — not by whether a creditor added a counseling comment.

    So while a lender reading your report manually can see the notation (if one was added), it does not mechanically lower your FICO score.

    The Real Credit Impact: Mostly Positive Over Time

    Here’s what actually moves your score during a DMP:

    • Positive: Consistent, on-time payments to all enrolled creditors (reported monthly by each creditor, just as before) steadily build your payment history — the single biggest factor in your FICO score (35%).
    • Positive: As balances decline month over month, your credit utilization improves — the second-biggest factor (30%).
    • Slightly negative (temporary): Account closures reduce your total available credit, which can cause a brief dip. This is usually minor and recovers within months as balances drop.
    • Negative (avoidable): Missing a DMP payment can result in a creditor dropping you from the plan, which may lead to late fees and negative reporting. Consistency is everything.

    Most people who complete a DMP see their credit score improve meaningfully from where it started — often by 50 to 100 points or more — because they’ve built 3–5 years of clean payment history and eliminated high balances.

    Can You Get New Credit During a DMP?

    Generally, no — and that’s by design. Most creditors won’t approve new credit while you’re on a DMP, and the plan’s structure assumes you’re not taking on new debt. Some agencies allow a narrow exception for emergency situations (e.g., you need to replace a broken-down car), but you should discuss this with your counselor before applying for anything.


    Pros of a Debt Management Plan

    Let’s be clear-eyed about what a DMP does well — and what it doesn’t. Here are the genuine advantages.

    1. Significantly Lower Interest Rates

    This is the headline benefit. Dropping from a 24% APR to an 8% APR on a $15,000 balance means thousands of dollars saved over the life of the plan — and a payoff timeline that shrinks from “decades of minimum payments” to “under five years.”

    2. One Predictable Monthly Payment

    Instead of tracking five or six due dates and minimum amounts (all of which change as balances shift), you make one payment, on one date, for one amount that stays constant. This eliminates a huge amount of mental overhead and significantly reduces the risk of missed payments.

    3. Waived Late Fees and Penalty Charges

    If you’ve been paying late (or not at all), late fees can add $35+ per month per account. A DMP typically halts those fees immediately upon enrollment, stopping the bleeding.

    4. A Clear Finish Line

    Knowing that you’ll be debt-free from your enrolled accounts on, say, March 2029 is profoundly motivating. A DMP gives you a date to circle on the calendar — something minimum payments never do.

    5. Nonprofit, Regulated, and Transparent

    Unlike for-profit debt settlement companies, NFCC-approved agencies operate under strict standards, are audited, and are accountable to accrediting bodies. Your monthly statements show exactly where every dollar goes.

    6. Financial Education and Ongoing Support

    A DMP isn’t just a payment mechanism — it comes with budgeting help, financial workshops, one-on-one counseling, and resources designed to keep you from ending up back in the same place. The goal is long-term financial health, not just a temporary fix.

    7. No Tax Consequences on Forgiven Debt

    Because you’re repaying 100% of what you owe (just at better terms), there’s no “forgiven debt” to report as income to the IRS. Debt settlement, by contrast, can generate a 1099-C form and a surprise tax bill.

    8. Creditors Often Stop Collection Calls

    Once creditors receive the DMP proposal and accept it, collection calls typically cease. You’re in a structured repayment agreement, and the creditor has no reason to keep pursuing you.

    9. Works Alongside Credit Repair

    A DMP handles the debt side of your financial picture. Professional credit repair handles the report side — disputing inaccuracies, addressing outdated information, and ensuring your credit file accurately reflects your history. The two together can accelerate your financial recovery significantly. We’ll cover this in detail later.

    Debt management plans and nonprofit credit counseling explained

    Cons of a Debt Management Plan

    A DMP isn’t right for every situation, and no one should enroll without understanding the tradeoffs.

    1. You Must Close Your Credit Cards

    Every credit card enrolled in the DMP is closed to new charges. For people who rely on cards for daily expenses or emergencies, this can feel like losing a financial safety net. It’s necessary — you can’t keep using the cards you’re paying off through a structured plan — but it’s a real adjustment.

    2. You’re on a Strict Budget

    A DMP payment is a non-negotiable monthly obligation. If your income is irregular or you’re living paycheck to paycheck with no buffer, a fixed monthly payment can create pressure. You need to be confident the payment is sustainable before enrolling.

    3. Not All Creditors Participate

    While most major banks and card issuers work with DMPs, some creditors — certain store cards, credit union loans, subprime lenders, and a few specialty accounts — may decline. You’d need to continue paying those separately, which can complicate your monthly finances.

    4. No New Credit During the Plan

    You generally cannot open new credit cards or take out loans while on a DMP. If you have a legitimate need (like financing a necessary vehicle), you’ll need to work through your counselor, and approval is not guaranteed.

    5. One Missed Payment Can Cause Problems

    If you miss a DMP payment, a creditor may drop you from the plan — reverting your interest rate to the original (much higher) APR and potentially reinstating fees. Most agencies have a grace period and will work with you, but repeated misses can collapse the plan.

    6. It Takes Years

    A DMP is not a quick solution. It’s a 3–5 year commitment. If you’re looking for immediate relief from debt, this isn’t it — and honestly, nothing legitimate is. Anyone promising fast debt elimination is either lying or selling you something that will damage your credit.

    7. It Doesn’t Address Secured Debt or Student Loans

    A DMP only covers unsecured debt. If your primary financial burden is a mortgage, car loan, or student debt, a DMP won’t help with those — though your counselor can advise on other strategies.

    8. You May Need to Pause Financial Goals

    During a DMP, you’re focused on debt elimination. Saving for a home down payment, investing, or other financial goals may need to wait — though your budget may include modest savings, and your counselor will help you balance priorities.

    Who a DMP Is Right For

    A DMP isn’t universal, but for a specific profile of borrower, it can be genuinely life-changing. You’re likely a good candidate for a debt management plan if:

    • Your debt is primarily unsecured — credit cards, personal loans, medical bills, and similar obligations that aren’t backed by collateral
    • Your total unsecured debt is manageable relative to your income — generally, if you could pay it off in 5 years at reduced interest rates, a DMP makes sense
    • You have steady income — the monthly payment needs to be sustainable for 3–5 years
    • Your credit card interest rates are high — if you’re paying 18%+ APR and only making minimum payments, the math strongly favors a DMP
    • You’re current or slightly behind on payments — a DMP works best before accounts go to collections or charge off
    • You want to avoid bankruptcy — for ethical, personal, or financial reasons
    • You’re committed to changing your financial habits — a DMP is a tool, not a cure. It works best for people who are ready to engage with budgeting, financial education, and long-term change
    • You’ve been turned down for consolidation loans — if your credit has already slipped and you can’t qualify for a balance transfer or personal loan at a better rate, a DMP may be your best alternative

    When a DMP Probably Isn’t Right

    • Your debt is mostly secured (mortgage, auto)
    • Your income is too low or too irregular to sustain a monthly payment
    • Your total unsecured debt is so high that even at reduced rates, you couldn’t pay it off in 5 years — in that case, bankruptcy may be the more honest option
    • Your debt is very small (under ~$3,000) — a stricter budget and the avalanche or snowball method might handle it without a formal plan
    • You’re not willing to close your credit cards

    A credit counselor will help you assess this honestly. That free initial session exists precisely to determine whether a DMP fits your situation — or whether a different path serves you better.

    How to Find a Legitimate Nonprofit Credit Counseling Agency

    This is critical. The debt relief space has more than its share of bad actors, and enrolling with the wrong organization can cost you money, time, and credit damage. Here’s how to find a legitimate nonprofit agency.

    1. Look for NFCC Membership

    The National Foundation for Credit Counseling (NFCC) is the oldest and largest nonprofit credit counseling network in the United States. NFCC member agencies must meet rigorous standards:

    • Nonprofit status (501(c)(3))
    • Independent third-party accreditation
    • Certified counselors who pass comprehensive exams
    • Transparent fee structures
    • Regular audits

    You can search for NFCC member agencies directly at the NFCC website (nfcc.org). This is the single most reliable starting point.

    2. Check for COA Accreditation

    The Council on Accreditation (COA) independently accredits credit counseling agencies. COA accreditation means the agency has undergone a thorough review of its practices, finances, counselor qualifications, and client outcomes. Many (not all) NFCC members carry COA accreditation; the two together are a strong signal of legitimacy.

    3. Verify Nonprofit Status

    A legitimate credit counseling agency should be a registered 501(c)(3) nonprofit. You can verify this through the IRS Tax Exempt Organization Search. If an organization is for-profit but calls itself “counseling,” that’s a red flag — not necessarily proof of wrongdoing, but reason to scrutinize further.

    4. Confirm No Upfront Fees

    Federal law (the FTC’s Telemarketing Sales Rule, amended by the Credit CARD Act and related regulations) prohibits debt relief companies from charging upfront fees before services are delivered. A legitimate agency charges only modest fees — and only after you’re enrolled and services are underway. If someone asks for hundreds of dollars before reviewing your situation, walk away.

    5. Check for Complaints

    Search the Consumer Financial Protection Bureau (CFPB) complaint database and the Better Business Bureau (BBB) for the agency’s name. A few complaints over years of operation is normal; a pattern of complaints about hidden fees, broken promises, or poor communication is a serious warning.

    6. Evaluate Their Communication

    A good agency will:

    • Spend real time understanding your situation before recommending anything
    • Provide all terms in writing
    • Answer your questions clearly, without pressure
    • Give you time to decide
    • Offer the counseling session for free
    • Be reachable by phone, email, or in person

    If you feel rushed, pressured, or “sold to,” trust that instinct. Legitimate counseling feels like a consultation — not a sales call.

    7. Look for Local Presence

    Many NFCC member agencies have local offices where you can meet face-to-face. While phone and online counseling are fully functional, a physical presence in your community is a positive signal — it suggests stability and accountability.

    Red Flags of Scam “Counseling” Services

    The debt relief industry attracts predators because desperate people are vulnerable. Here’s what should make you stop and reconsider — immediately.

    1. “We Can Reduce Your Debt by 50%!”

    No legitimate counselor promises a specific reduction percentage before reviewing your finances. DMPs reduce your interest rate and fees, not your principal. Anyone promising to slash what you owe by half is describing debt settlement — and likely overstating what they can achieve.

    2. Large Upfront Fees

    Any company demanding a significant payment before providing services is violating federal law. Period. Legitimate agencies charge modest fees, disclosed upfront, collected after enrollment.

    3. “Stop Paying Your Creditors”

    This is the hallmark of debt settlement, not debt management. If a company tells you to stop paying your creditors and instead send money to them (or to a “savings account” they control), you’re being set up for settlement — which means months of missed payments, tanking credit, collection calls, and potential lawsuits. A DMP does the opposite: you continue paying your creditors, through the agency, every month.

    4. No Mention of Budgeting or Financial Education

    If the conversation is entirely about their program and never about your budget, your income, your expenses, or your financial habits, that’s a sales pitch — not counseling. Real credit counseling starts with your full financial picture.

    5. “We’ll Remove the DMP From Your Credit Report”

    This is nonsensical — the DMP itself isn’t on your credit report as a standalone item. Anyone claiming they can “clean up” DMP-related notations is either misunderstanding how credit reporting works or selling you a credit repair scam alongside the counseling.

    6. Pressure to Enroll Immediately

    A legitimate counselor will give you written materials, answer your questions, and encourage you to take time deciding. High-pressure tactics — “this offer expires today,” “credors won’t wait,” “enroll now or lose this chance” — are designed to override your judgment. Walk away.

    7. No Clear Fee Disclosure

    If fees are vague, described as “contribution,” or not put in writing, that’s a problem. Legitimate agencies are transparent about every dollar.

    8. They’re Not Nonprofit

    Many for-profit companies use “credit counseling” in their marketing to borrow the credibility of the nonprofit sector. Ask directly: “Are you a 501(c)(3) nonprofit?” If the answer is no or evasive, keep looking.

    9. No NFCC Membership or COA Accreditation

    While there may be legitimate agencies outside these networks, the absence of both is a reason to investigate further. NFCC membership is the most meaningful credential in this industry.

    10. Unrealistic Timeline Promises

    “We’ll have you debt-free in 12 months.” For most people with substantial unsecured debt, a 12-month payoff isn’t realistic without either a windfall or a settlement — and settlement comes with the damage described above. Real DMPs run 3–5 years. Anyone promising dramatically faster results is selling something else.

    DMP vs. Debt Settlement vs. Bankruptcy

    When you’re overwhelmed by debt, these are the three main structured options (beyond self-directed repayment or a consolidation loan, which we covered earlier). Here’s a clear comparison.

    Feature Debt Management Plan (DMP) Debt Settlement Bankruptcy (Chapter 7) Bankruptcy (Chapter 13)
    Who runs it Nonprofit credit counseling agency For-profit debt settlement company Federal bankruptcy court Federal bankruptcy court
    What happens to debt Repaid in full at reduced interest/fees Settled for less than owed (lump sum) Discharged (eliminated) Repaid over 3–5 years under court plan
    Effect on credit Neutral to positive over time Severely negative (late pays, charge-offs) Severely negative; stays on report 10 years Negative; stays on report 7 years
    Typical timeline 3–5 years 2–4 years (if successful) 3–6 months (filing to discharge) 3–5 years
    Costs ~$10–$25/month + small setup fee 15–25% of enrolled debt $1,500–$3,500 (attorney + filing fees) $2,000–$4,000 (attorney + filing fees)
    Tax impact None Forgiven debt may be taxed as income Generally no tax on discharged debt Generally no tax on discharged debt
    Creditor participation Voluntary but common Voluntary and uncertain Mandatory (court-ordered) Mandatory (court-ordered)
    Legal protection None None (creditors can sue) Automatic stay (halts collections) Automatic stay (halts collections)
    Risk of creditor lawsuits Low (you’re paying) High (you stop paying) None (automatic stay) None (automatic stay)
    Best for People with steady income, primarily unsecured debt, who want to repay fully and avoid credit damage People with lump-sum funds available and debts already significantly delinquent People with no realistic ability to repay and limited assets People with steady income who need legal restructuring and have assets to protect

    Which One Is Right for You?

    There’s no universal answer — that’s the point. The right choice depends on your debt load, income, assets, goals, and personal values. This is exactly why a free credit counseling session is so valuable: a certified counselor will assess your situation and recommend the most appropriate path, even if that path is bankruptcy (which they can’t file for you, but can refer you to an attorney for).

    If you’re also working with a credit repair firm — like a San Diego-based, attorney-backed team that audits your reports across all three bureaus — that’s a complementary process. Credit repair addresses what’s on your report; a DMP addresses how you’re paying down what you owe. Together, they can rebuild both your credit score and your actual financial position.

    Common Mistakes People Make with DMPs

    A DMP is a powerful tool, but like any tool, it can be misused. Here are the most common mistakes people make — and how to avoid them.

    1. Enrolling Without Understanding the Commitment

    A DMP is a 3–5 year contractual relationship with real consequences if you stop paying. Some people enroll in a moment of financial panic without fully grasping the monthly obligation. Fix: Take the counseling session seriously, ask every question you have, and make sure the monthly payment is truly sustainable before signing.

    2. Choosing a For-Profit “Counseling” Company

    We’ve covered this above, but it bears repeating: many companies use “credit counseling” language while operating as for-profit debt settlement operations. Enrolling with the wrong company can mean months of stopped payments, ruined credit, and lost money. Fix: Verify NFCC membership and nonprofit status before engaging.

    3. Not Disclosing All Debts

    Some people leave certain debts off their DMP enrollment — perhaps because they want to keep a specific card, or because they’re embarrassed about a particular account. This undermines the plan’s effectiveness and can create financial gaps. Fix: Be fully transparent with your counselor. They’re there to help, not judge.

    4. Missing Payments

    A single missed DMP payment can cause a creditor to drop out of the plan, reverting your interest rate and reinstating fees. Multiple misses can collapse the plan entirely. Fix: Set up auto-draft if possible. If you anticipate a problem (job loss, medical emergency), contact your counselor before the payment is due — agencies have hardship options, but only if you communicate early.

    5. Taking on New Debt During the Plan

    The whole point of a DMP is to get out of debt. Taking on new obligations — a car loan, a store card, a “buy now, pay later” arrangement — undermines the plan and can violate its terms. Fix: If you have a genuine emergency need (like a car to get to work), talk to your counselor first. They can help you explore options within the plan’s framework.

    6. Not Following Through on Financial Education

    A DMP that’s just a payment mechanism misses its full value. The budgeting skills, financial literacy, and behavioral changes are what keep you out of debt after graduation. Fix: Engage with the workshops, resources, and counseling sessions your agency offers. Treat the educational component as the real product — because it is.

    7. Stopping the Plan Without a Strategy

    Some people drop out of a DMP partway through — maybe their financial situation improves and they want to pay directly, or maybe they hit a rough patch and stop paying entirely. Dropping out without a plan can leave you in a worse position than you started. Fix: If you need to leave the plan, talk to your counselor about an exit strategy. If your situation has improved, you may be able to pay off remaining balances directly at the reduced rates already negotiated. If your situation has worsened, they can help you explore other options.

    8. Ignoring Your Credit Reports During the Plan

    Your DMP payments should be reported monthly by each creditor. If a creditor fails to report (or reports incorrectly), you could be making payments that don’t show up on your credit file. Fix: Pull your reports from all three bureaus at least annually during the DMP (you’re entitled to free weekly reports from AnnualCreditReport.com). If something’s wrong, address it — either with the creditor directly or through a credit repair process.


    How a DMP and Credit Repair Work Together

    This is where many people miss an opportunity. A debt management plan and professional credit repair address two different sides of your financial life — and pursuing both simultaneously can accelerate your recovery more than either one alone.

    What a DMP Does

    A DMP manages your debt. It reduces your interest, structures your payments, and gets you to zero balances on enrolled accounts. It’s about your money — what you owe and how you’re paying it.

    What Credit Repair Does

    Credit repair addresses your credit report. A reputable, FCRA-compliant, attorney-backed credit repair firm audits your reports across all three major bureaus, identifies inaccuracies (accounts that don’t belong, outdated information, incorrectly reported statuses, duplicate entries, unauthorized inquiries), and disputes them. If the bureaus and creditors can’t verify or substantiate the disputed items, they must remove or correct them. It’s about your file — what’s being reported about you.

    Why Both Together Is Powerful

    Imagine this scenario:

    • You enroll in a DMP and begin paying down $20,000 in credit card debt at reduced interest. Over 4 years, you retire that debt completely.
    • Meanwhile, your credit repair team audits your reports and finds: a collection account from 2022 that was actually paid but never updated; a late payment from 2023 that was reported in error; an address you never lived at; two inquiries you never authorized.
    • Those inaccuracies get disputed and removed. Your report now reflects your actual history accurately.
    • As your DMP payments build a clean, on-time payment history and your balances drop, your credit utilization improves dramatically.
    • By the time you graduate from the DMP, your reports are accurate and your credit behavior is strong. Your score has likely climbed significantly, and you’re positioned to qualify for favorable rates on whatever you need next — a mortgage, a car loan, a business credit line.

    This is the combined power: credit repair ensures your report tells the truth, while a DMP ensures your financial reality is the truth. Together, they build a foundation that’s both accurate and strong.

    Important Caveats

    • Not the same service. A DMP is administered by a nonprofit counseling agency. Credit repair is provided by a separate firm (and should be FCRA-compliant and, ideally, attorney-backed). They don’t overlap, and no single organization should be selling you both.
    • A DMP is not a credit repair strategy. Enrolling in a DMP won’t remove accurate negative items from your report. It will build positive history going forward, but it doesn’t fix what’s already there. That’s what credit repair does.
    • Credit repair doesn’t eliminate debt. Disputing and removing inaccuracies can improve your score, but it doesn’t reduce what you actually owe. That’s what a DMP does.
    • Timing matters. If you’re considering both, start with a credit counseling session (free) and a credit audit (often free as an initial consultation) to understand your full picture before committing to either.

    If you’re working with a credit repair firm that’s transparent, attorney-backed, and focused on education — not just disputes — they can often help you think through whether a DMP fits your situation, even though they don’t administer one themselves. The best firms think about your whole financial health, not just the report.

    Frequently Asked Questions

    1. Will a DMP show up on my credit report?

    No — not as a standalone item. The three major credit bureaus do not list “enrolled in a debt management plan” as a separate entry. What may appear is a notation on individual accounts (e.g., “account managed by credit counseling”) and the fact that your enrolled accounts are closed. FICO scoring models ignore the counseling notation entirely, so it does not directly affect your score.

    2. Can I keep one credit card off the DMP for emergencies?

    Generally, no. Most DMPs require you to enroll all of your unsecured credit card accounts. If you keep a card open with a balance, the creditor may decline to participate in the DMP for your other accounts. Some agencies may allow you to keep one card with a zero balance for emergencies, but this varies — ask your counselor directly.

    3. What happens if I miss a DMP payment?

    Most agencies have a short grace period (often 1–2 days) and will work with you if you communicate in advance. But a significant missed payment can cause a creditor to drop you from the plan, reverting your interest rate to the original APR and reinstating fees. If you anticipate a problem, call your counselor immediately — hardship options may be available.

    4. How much does a DMP cost?

    Legitimate nonprofit agencies charge a modest setup fee (typically $10–$35, sometimes waived) and a monthly maintenance fee (typically $10–$25, often waivable for hardship). These fees are regulated and disclosed upfront. If you’re being quoted hundreds of dollars in fees, you’re not dealing with a legitimate nonprofit DMP.

    5. Can I pay off the DMP early?

    Yes. There’s no prepayment penalty. If your financial situation improves and you can pay off remaining balances faster, you’re free to do so. Some people receive bonuses, tax refunds, or other windfalls and use them to accelerate their DMP payoff.

    6. Will my creditors definitely accept the DMP proposal?

    Most major creditors accept DMP proposals from NFCC-approved agencies, because these agencies operate under established creditor guidelines. However, participation is voluntary, and some creditors (certain store cards, credit unions, subprime lenders) may decline or counter-offer. Your counselor will tell you which accounts are confirmed and which aren’t.

    7. Can I do a DMP if I’m already behind on payments?

    Yes — in fact, being behind is one of the most common reasons people seek out a DMP. However, if your accounts have already charged off (typically 180 days delinquent) and gone to collections, those accounts may not be eligible for a DMP. The earlier you engage with credit counseling, the more options you’ll have.

    8. What’s the difference between a DMP and working with a credit repair company?

    A DMP, administered by a nonprofit credit counseling agency, manages how you repay your unsecured debts — negotiating lower interest and fees and coordinating your payments. A credit repair company audits your credit reports and disputes inaccurate, outdated, or unverifiable information with the bureaus and creditors. They’re complementary processes that address different sides of your financial picture. A reputable credit repair firm won’t run a DMP, and a DMP agency won’t do credit repair disputes — but both can refer you to the other if needed.

    Next Steps: A Free Credit Audit Can Help You Decide

    If you’ve read this far, you’re serious about understanding your options — and that’s the right place to start. Whether a DMP is right for you, or whether your situation calls for a different approach, begins with knowing exactly where you stand.

    At credit-repair.com, we offer a free credit audit that reviews your reports across all three major bureaus — Equifax, Experian, and TransUnion — to identify inaccuracies, outdated items, and errors that may be dragging down your score. We’re a San Diego-based, attorney-backed credit repair firm operating in full compliance with the Fair Credit Reporting Act (FCRA), and we work with clients nationwide.

    Here’s what a free audit includes:

    • A comprehensive review of all three credit reports
    • Identification of inaccuracies, outdated information, and unverifiable items
    • A clear, honest assessment of what can be disputed and what can’t
    • A discussion of whether credit repair makes sense for your situation — and if a DMP or other debt strategy might also help
    • No obligation, no pressure, and no hidden fees — ever

    How Credit Repair and a DMP Fit Together

    If your audit reveals report inaccuracies alongside significant unsecured debt, you may benefit from pursuing both:

    • Credit repair to ensure your reports accurately reflect your history (removing errors that aren’t yours, correcting misreported statuses, addressing outdated items)
    • A DMP (through an NFCC-approved nonprofit agency we can refer you to) to structure your debt repayment at reduced interest and fees

    These two processes address different problems — your report and your debt — and together, they can help you rebuild both your credit score and your actual financial position. We don’t run DMPs ourselves (that’s the job of nonprofit counseling agencies), but we can help you understand whether one fits your situation and point you toward legitimate, accredited agencies.

    Why Work With Us

    • Attorney-backed — every step of our process is reviewed for legal compliance
    • FCRA-compliant — we operate strictly within federal credit law
    • Transparent pricing — no hidden fees, no misleading claims, no unnecessary services
    • Educational approach — we don’t just dispute items; we help you understand your credit, your rights, and how to maintain strong credit for the long term
    • Nationwide service — wherever you are, we can help

    Get Started

    Visit to request your free credit audit, or reach out to our team directly. We’ll review your reports, explain what we find in plain language, and help you map out a path forward — whether that includes credit repair, a DMP, a combination of both, or a referral to another resource that fits your situation better.

    Your financial future isn’t something to leave to chance — or to quick-fix promises. It deserves honest assessment, legal compliance, and a partner who’s in it for the long haul. That’s what we do.

    Disclaimer: This article is for educational purposes only and does not constitute financial or legal advice. A debt management plan is administered by nonprofit credit counseling agencies, not by credit-repair.com. We do not provide DMPs, but we can help you understand whether one may fit your situation and refer you to accredited nonprofit agencies. Credit repair services are provided by credit-repair.com in compliance with the Fair Credit Reporting Act (FCRA) and applicable federal and state laws. Individual results vary; we do not guarantee specific outcomes or promise the removal of any particular item from your credit report.


  • Cease and Desist Letter for Debt Collectors (with Template)

    Cease and Desist Letter for Debt Collectors (with Template)

    If debt collectors are calling you five, ten, twenty times a day — at work, on your cell, on your family’s phone — you are not powerless. Federal law gives you a written tool that forces them to stop. It is called a cease and desist letter, and under the Fair Debt Collection Practices Act (FDCPA), once a collector receives it, they are legally required to halt nearly all communication with you.

    That sounds simple, and in many ways it is. But a cease and desist letter is also one of the most misunderstood tools in the credit repair world. People assume it erases the debt. It does not. People assume it stops lawsuits. It does not. People assume once they send it, the whole problem goes away. It does not — and in some cases, sending one without thinking through the consequences can actually accelerate a lawsuit.

    This guide walks you through everything you need to know: what the letter does, what it does not do, when to send one (and when to think twice), two ready-to-use templates, how to send it so it actually holds up, and what to do if the collector ignores it. We have spent years helping people across the country navigate exactly this situation, and we want you to have the same clear, honest information we give our own clients — no hype, no quick-fix promises, just the law and how to use it.

    What Is a Cease and Desist Letter?

    A cease and desist letter is a written notice from you to a debt collector demanding that they stop contacting you about a specific debt. It is not a court order. It is not a lawsuit. It is a letter — but it is a letter that carries the force of federal law behind it.

    Under the FDCPA, a debt collector is someone whose primary business is collecting debts owed to others — this includes collection agencies, debt buyers, and third-party collectors. It generally does not include the original creditor (like the bank that issued your credit card) collecting its own debt in its own name. That distinction matters, and we will come back to it.

    When you send a cease and desist letter, you are exercising a specific legal right: the right to tell a third-party debt collector, in writing, that they may no longer communicate with you. The law says that once they receive your letter, they must stop — with very limited exceptions. If they do not stop, they are violating federal law, and you may have grounds to sue them or file a complaint.

    A cease and desist letter is sometimes confused with a debt validation letter (also called a dispute letter), which is a separate request demanding the collector prove the debt is yours and the amount is correct. The two serve different purposes and can be used together or separately. We cover how they interact .

    Key takeaway: A cease and desist letter is a written demand that a debt collector stop contacting you. It is enforceable under federal law, and it is one of the most direct tools you have for stopping collection harassment.


    Your FDCPA Right to Demand a Collector Stop Contacting You

    The legal foundation for a cease and desist letter is found in 15 U.S.C. § 1692c(c), part of the Fair Debt Collection Practices Act. The FDCPA was passed by Congress in 1977 to eliminate abusive, deceptive, and unfair debt collection practices. Before the FDCPA, collectors could — and did — call at all hours, threaten arrest, contact employers, and use intimidation freely. The law changed that.

    Here is what the statute says, in plain terms: if you notify a debt collector in writing that you refuse to pay the debt or that you wish the collector to cease further communication, the collector must stop communicating with you — with three exceptions:

    • To advise you that further efforts to collect the debt are terminated. The collector can send one final letter saying “we are giving up on collecting this.”
    • To notify you that a specific remedy (like referring the debt to an attorney or reporting it to a credit bureau) may be invoked. The collector can tell you they are escalating — for example, handing the file to a lawyer or flagging your credit report.
    • To notify you that a specific remedy is about to be invoked. A follow-up saying “we have now done the thing we warned you about.”

    That is it. Beyond those three narrow notifications, the collector must go silent. No more calls. No more letters. No more texts. No more emails. No more showing up at your door.

    Who the FDCPA Covers

    The FDCPA applies to third-party debt collectors — collection agencies, debt buyers who purchased a defaulted account, and attorneys who regularly collect debts. It does not generally apply to:

    • Original creditors collecting their own debts in their own name (like a bank calling about its own credit card)
    • In-house collection departments of the original creditor, as long as they use the creditor’s name
    • Government employees collecting government debts

    Some states have their own laws that extend similar protections to original creditors. For example, California’s Rosenthal Fair Debt Collection Practices Act extends most FDCPA protections to original creditors. If you are dealing with an original creditor rather than a third-party collector, check your state’s law — a cease and desist letter may still carry weight, just under a different legal basis.

    The Difference Between “Refuse to Pay” and “Cease Communication”

    The FDCPA gives you two ways to trigger the cease-contact requirement, and they sound similar but have slightly different implications:

    • “I refuse to pay the debt” — This tells the collector you have no intention of paying. This is the strongest form. It signals to the collector that further collection attempts are likely futile, which may push them toward either closing the file or escalating to a lawsuit.
    • “I wish you to cease further communication” — This tells the collector to stop contacting you, but does not make a statement about whether you will pay. It is a narrower request. Some attorneys prefer this phrasing because it stops contact without explicitly daring the collector to sue.

    Both are legally valid. The templates in this guide use the “cease communication” phrasing as the default, because it is the most broadly useful. If you want the strongest possible version, you can add “I also refuse to pay this debt” — but understand that this increases the likelihood the collector will either sell the debt, close the file, or sue.

    Key takeaway: Your right to demand a collector stop contacting you comes from federal law (15 U.S.C. § 1692c(c)). The collector can only contact you after receiving your letter to say they are stopping collection, or to notify you of a specific action like referring the debt to an attorney or suing you.


    When to Send a Cease and Desist Letter

    A cease and desist letter is a powerful tool, but it is not always the right first move. Here are the situations where sending one makes the most sense, and a few where you should think carefully before sending.

    Good Reasons to Send a Cease and Desist Letter

    1. 1. The collector is harassing you.

    The FDCPA already prohibits harassment — repeated calls, calls before 8 a.m. or after 9 p.m., threats, obscene language, and calling you at work after you have told them not to. But enforcement is reactive: the law does not physically prevent the calls, it just gives you a remedy after the fact. If a collector is calling you repeatedly, ignoring your requests to stop, or contacting family members and your workplace, a cease and desist letter puts a hard line in the sand. Once they receive it, continued contact is a clear, documented violation.

    1. 2. You have already validated or disputed the debt and it is resolved (or not yours).

    If you sent a debt validation letter and the collector failed to validate, or the debt turned out to be the result of identity theft, or you already settled or paid it, there is no reason for continued contact. A cease and desist letter closes the door. (See for how to sequence these.)

    1. 3. You want all communication in writing.

    If you are fine with the collector communicating with you, but you do not want phone calls — you want everything in writing so you have a paper trail — that is a limited cease rather than a full cease. We cover this in detail . A limited cease is often the better first step because it keeps the channel open while protecting you from phone harassment.

    1. 4. You are being contacted about a time-barred debt.

    A time-barred debt is one where the statute of limitations has expired — meaning the collector can no longer sue you to collect it. The exact time limit varies by state and by the type of debt (oral, written, open-ended), but typically ranges from three to six years. If a collector is contacting you about an old debt that is past the statute of limitations, a cease and desist letter is an appropriate response. Just be careful: making a partial payment or even acknowledging the debt in some states can restart the clock. If you are not sure whether the debt is time-barred, talk to an attorney before sending anything.

    1. 5. The debt is outside the credit reporting window.

    Most negative items can only stay on your credit report for seven years (ten years for Chapter 7 bankruptcy). If a collector is pursuing you for a debt that is so old it can no longer be reported, a cease and desist letter can stop the contact. Be aware that the reporting window and the statute of limitations are two different clocks — a debt can be unreportable but still within the statute of limitations, or vice versa.

    When to Think Twice Before Sending

    You are within the statute of limitations and the collector has not sued yet.

    If the debt is still legally collectible (within the statute of limitations), sending a full cease and desist letter removes the collector’s ability to contact you — which means their main remaining options are to sell the debt, close the file, or sue. Some collectors, particularly debt buyers who purchased the account for pennies on the dollar, will choose to sue rather than walk away, because a lawsuit is cheap to file and often goes uncontested. If the debt is large enough to be worth their while and you have assets or wages they could go after, think carefully. A limited cease (no phone calls, written contact only) may be the safer middle ground — it stops the harassment while keeping the door open for a negotiated settlement or payment plan.

    You have not validated the debt yet.

    If you are not sure the debt is yours, or the amount is wrong, your first letter should be a validation dispute under 15 U.S.C. § 1692g, not a cease and desist. A validation dispute forces the collector to pause collection and prove the debt. Sending a cease and desist first cuts off communication, but it does not resolve the underlying question of whether you actually owe what they say you owe.

    The original creditor is contacting you (not a third-party collector).

    As noted above, the FDCPA generally does not cover original creditors collecting their own debts. A cease and desist letter to an original creditor is not backed by the same federal enforcement mechanism. It may still be worth sending — some creditors will respect it as a matter of policy — but your legal recourse if they ignore it is different and often depends on state law.

    Key takeaway: Send a cease and desist letter when you are being harassed, when you have already resolved or validated the debt, when the debt is time-barred, or when you simply want all communication in writing. Think twice if the debt is still within the statute of limitations and you have not yet validated it — a limited cease or a validation dispute may be the better first step.


    What a Cease and Desist Letter Does — and Does Not Do

    Understanding what a cease and desist letter does not do is just as important as understanding what it does. Here is the honest breakdown.

    What It Does

    • Stops the collector from contacting you. Once the letter is received, the collector must stop calling, texting, emailing, and mailing you — except for the three narrow notifications allowed by the FDCPA (cessation of efforts, notification of a specific remedy, or notification that a remedy is being invoked).
    • Creates a documented legal boundary. The letter and its proof of delivery create a clear record that you invoked your FDCPA right. If the collector continues to contact you, each contact is a potential statutory violation worth up to $1,000 per violation plus actual damages and attorney fees under 15 U.S.C. § 1692k.
    • Gives you leverage. If the collector violates the cease and desist, you have a strong basis for an FDCPA lawsuit or a CFPB complaint. Many collectors will back off entirely once they receive a properly worded letter with proof of delivery, because they know the cost of a violation.
    • Reduces stress and harassment. For people who have been living under a barrage of collection calls, the simple act of forcing the phone to go quiet can be a profound relief. That matters — chronic financial stress takes a real toll.

    What It Does Not Do

    • It does not erase the debt. The debt still exists. You still legally owe it (assuming it is valid and within the statute of limitations). The collector simply cannot contact you about it anymore.
    • It does not stop a lawsuit. The collector can still sue you to collect the debt. In fact, as we discuss in the next section, sending a cease and desist letter can sometimes increase the likelihood of a lawsuit, because the collector’s other options (continued contact, settlement offers, payment plans) are cut off.
    • It does not remove the item from your credit report. If the collection account is being reported to the credit bureaus, a cease and desist letter does not make it go away. The account will continue to be reported according to the credit reporting time limits (typically seven years from the original delinquency). To address the credit reporting, you need a separate process — dispute with the bureaus, negotiate a pay-for-delete, or work with a credit repair professional.
    • It does not prevent the collector from selling the debt. The collector may simply sell your account to another debt buyer, who becomes a new “debt collector” under the FDCPA. Your cease and desist letter applies to the collector you sent it to — not automatically to every future buyer. You may need to send a new letter to each new collector who contacts you. (Some attorneys argue that a cease and desist transfers with the debt, but the safest approach is to send a new one if a new collector appears.)
    • It does not apply to the original creditor. As discussed, the FDCPA’s cease-contact right applies to third-party debt collectors, not original creditors collecting in their own name (unless your state law says otherwise).

    Key takeaway: A cease and desist letter stops contact. It does not erase the debt, stop lawsuits, remove credit report entries, prevent the debt from being sold, or bind the original creditor. It is a communication tool, not a debt-elimination tool.


    The Risk: A Collector May Escalate to a Lawsuit

    This is the part many guides skip or gloss over. We are not going to do that, because being honest about the risk is the only way to make a good decision.

    When you send a full cease and desist letter, you are cutting off the collector’s primary tool for recovering the debt: communication. Without the ability to call or write, the collector has three main options:

    • Sell the debt to another buyer. This is common. The debt gets passed down the chain, often for less and less money, to successive buyers. Each new buyer may contact you, and you may need to send a new cease and desist. Eventually, the debt may end up with a buyer who is willing to just write it off — or one who decides to sue.
    • Close the file and walk away. Some collectors will simply give up, especially if the debt is small, old, or hard to collect. This is the outcome many people hope for when they send a cease and desist, and it does happen — but it is not guaranteed, and it is more likely with smaller or older debts.
    • Refer the debt to an attorney and sue you. This is the risk. A lawsuit is relatively cheap for a collector to file, and if you do not respond, they get a default judgment — which can lead to wage garnishment, bank account levies, or property liens depending on your state. If the debt is large, you have a verifiable income or assets, and the debt is within the statute of limitations, the risk of a lawsuit after a cease and desist is real.

    How to Assess Your Risk

    Before sending a full cease and desist, ask yourself:

    • Is the debt within the statute of limitations in my state? If yes, the collector can legally sue. If no, they cannot win a lawsuit (though they can still file one — you would raise the statute of limitations as a defense). Check your state’s statute of limitations for the type of debt involved.
    • How large is the debt? Collectors are more likely to sue over larger debts (many set an internal threshold, often around $1,000–$5,000, above which litigation becomes worthwhile). Small debts are more likely to be sold or written off.
    • Do I have wages or assets they could collect against? If you have a steady job (subject to garnishment) or money in a bank account, you are a more attractive litigation target. If you are judgment-proof — no assets, no garnishable income, retired on protected benefits — a lawsuit is less likely and less threatening.
    • Has the collector already threatened legal action or sent a letter from a law firm? If so, they may already be on the litigation path. A cease and desist at that point will not stop the lawsuit; it just stops the pre-suit contact.

    The Limited Cease as a Risk-Reducing Alternative

    If you are concerned about triggering a lawsuit, consider a limited cease instead. A limited cease tells the collector to stop calling you (or stop all phone contact) but allows written communication to continue. This stops the harassment while keeping the door open for the collector to send you a settlement offer or payment plan — options that disappear with a full cease. We cover the limited cease in the .

    Key takeaway: Sending a full cease and desist letter can, in some cases, push a collector toward suing you — because you have removed their ability to collect through contact. Assess the size of the debt, the statute of limitations, and your exposure to garnishment before sending. A limited cease is often a safer first step.


    Full Cease vs. Limited Cease: Which Is Right for You?

    The FDCPA does not require you to demand a total stop to all communication. You can demand a limited stop — for example, no phone calls, but written contact is okay. This is called a limited cease and desist, and it is one of the most underused tools in the credit repair toolkit.

    Full Cease and Desist

    A full cease and desist demands that the collector stop all communication with you, subject only to the three statutory exceptions (cessation notice, remedy notification, remedy invocation). After receiving a full cease, the collector cannot call, write, text, or email you about the debt.

    When a full cease makes sense:

    • The debt is time-barred (past the statute of limitations).
    • The debt is not yours (identity theft, mixed file, etc.) and you have already disputed it.
    • The collector is harassing you and you have no intention of paying or negotiating.
    • The debt is small and unlikely to be worth a lawsuit.
    • You are judgment-proof and a lawsuit would not produce anything for the collector.
    • You have already resolved the debt (paid, settled, discharged in bankruptcy) and the collector is still contacting you.

    The tradeoff: You cut off all communication, which means no settlement offers, no payment plans, and no opportunity to negotiate a pay-for-delete or a reduced payoff. You also increase the risk that the collector will sell the debt or sue.

    Limited Cease and Desist

    A limited cease and desist restricts the method of contact but does not cut off all communication. The most common form is a “no phone calls” letter: you tell the collector they may not contact you by phone, but they may still write to you.

    The FDCPA does not explicitly codify the “limited cease” by name, but it is widely accepted as a lawful exercise of your right to control how a collector contacts you. Under § 1692c(a), a collector must stop calling you if you tell them to stop calling at a particular number, and must stop contacting you at work if you tell them your employer prohibits it. A limited cease letter formalizes this in writing and broadens it: “Do not contact me by telephone. All future communication must be in writing.”

    When a limited cease makes sense:

    • The debt is within the statute of limitations and you want to avoid pushing the collector toward a lawsuit.
    • You are open to a settlement or payment plan but do not want to deal with phone calls.
    • You want a paper trail of everything the collector says, which written communication provides and phone calls do not.
    • You are still validating or disputing the debt and want to keep the channel open.
    • You want to negotiate but from a calmer, more controlled position — on paper, not under pressure on the phone.

    The tradeoff: The collector can still send you letters, which may include settlement offers, balance statements, or notices of escalation. You will still receive mail about the debt. Some people find this preferable to calls; others want total silence.

    A Quick Comparison

    Full Cease Limited Cease
    Phone calls Stopped Stopped
    Letters/mail Stopped Allowed
    Texts/emails Stopped Stopped (or per your terms)
    Settlement offers No longer sent Still sent
    Lawsuit risk Potentially higher Generally lower
    Negotiation possible No Yes
    Paper trail Minimal (you set the boundary) Strong (collector writes to you)
    Best for Time-barred debts, harassment, debts you will not pay Debts you may negotiate, within SOL, want to keep options open

    Key takeaway: A full cease stops all contact but raises lawsuit risk and closes the door on negotiation. A limited cease stops phone calls but keeps written communication open, preserving your options and reducing escalation risk. For many people, the limited cease is the better first step.


    What the Letter Must Include

    A cease and desist letter does not need to be written by a lawyer or use magic legal language. The FDCPA says you need to notify the collector “in writing” — that is the core requirement. But to make the letter effective, enforceable, and useful if you later need to prove a violation, it should include certain elements.

    Essential Elements

    • Your name and current address. This identifies you and connects you to the account. If the collector has your address on file, use that address — it helps them match the letter to your account. If you have moved, include both your current address and the address they have on file.
    • The collector’s name and address. Address the letter to the specific collection agency or debt buyer. If you know the individual collector’s name, include it; otherwise, address it to the agency generally.
    • The account or reference number. Include any account number, file number, or reference number the collector has used in their correspondence with you. This is critical — it ties your letter to the specific debt in their system. If you do not have the number, describe the debt (original creditor, approximate amount, date) as specifically as you can.
    • A clear statement demanding they cease communication. Use explicit language: “I am writing to demand that you cease all communication with me regarding the above-referenced debt, pursuant to 15 U.S.C. § 1692c(c).” For a limited cease, specify the method: “I demand that you cease all telephone communication with me. You may contact me in writing only.”
    • Citation of the FDCPA. Referencing the FDCPA and the specific section (§ 1692c(c) for a full cease) signals that you know your rights and are invoking them deliberately. It also makes the letter harder for the collector to dismiss.
    • The date. Date the letter. The date matters because the collector’s obligation to stop contact begins when they receive the letter, but the date on the letter helps establish your timeline.
    • Your signature. Sign the letter by hand if you are mailing a printed copy. If you are sending it electronically (some collectors accept email), a typed signature is acceptable, but a handwritten signature on a mailed letter is the gold standard for proof.
    • A statement that you dispute the debt (if you do). If you believe the debt is not yours or the amount is wrong, say so: “I dispute this debt in its entirety and request validation pursuant to 15 U.S.C. § 1692g.” This triggers a separate right — the collector must pause collection and send you validation. (See .)
    • A statement that all calls are inconvenient. Under § 1692c(a)(1), a collector may not contact you at a time or place they know or should know is inconvenient. Stating “All telephone contact is inconvenient” strengthens a no-calls demand, especially for a limited cease.
    • A statement prohibiting workplace contact. If you do not want the collector contacting you at work, say: “My employer prohibits personal calls. Do not contact me at my place of employment.” Under § 1692c(a)(3), once the collector knows your employer prohibits it, they must stop.
    • A reminder of the consequences of violation. A line like “Be advised that any further communication except as permitted by 15 U.S.C. § 1692c(c) will be documented and may form the basis of an FDCPA claim” is not required, but it signals that you are serious and aware of your remedies.
    • A request for written confirmation. You can ask the collector to confirm in writing that they have received your cease and desist and will comply. They are not required to send confirmation, but some will.

    What to Leave Out

    • Do not acknowledge the debt. If you are not sure the debt is yours, do not write “I owe this debt but I want you to stop calling.” A written acknowledgment can, in some states, restart the statute of limitations. If you are disputing, say you dispute. If you are not disputing but just want contact to stop, simply demand cessation without discussing the merits.
    • Do not make threats. Do not threaten the collector with violence, legal action you have no intention of taking, or anything else. A calm, factual letter is far more effective than an angry one.
    • Do not provide unnecessary personal information. Do not include your Social Security number, date of birth, or bank account information. The collector should already have enough to identify your account. Providing extra personal information can work against you.

    Key takeaway: Your letter needs your name and address, the collector’s name and address, the account/reference number, a clear demand to cease communication, the FDCPA citation, the date, and your signature. Do not acknowledge the debt, make threats, or over-share personal information.


    Full Cease and Desist Letter Template

    Below is a complete, ready-to-use template for a full cease and desist letter. Replace every bracketed field with your own information. Send it by certified mail with return receipt (see ).

    [Your Full Name]
    [Your Current Address]
    [Your City, State, ZIP]
    [Your Phone Number — optional]
    
    [Date]
    
    [Collector/Agency Name]
    [Collector's Address]
    [Collector's City, State, ZIP]
    
    RE: Account No. [Account/Reference Number]
        Original Creditor: [Original Creditor Name, if known]
        Amount Claimed: [$Amount, if known]
    
    To Whom It May Concern:
    
    I am writing in response to your collection efforts regarding the
    above-referenced account. Pursuant to 15 U.S.C. § 1692c(c) of the Fair
    Debt Collection Practices Act (FDCPA), I hereby demand that you CEASE
    AND DESIST all communication with me regarding this debt.
    
    This cease and desist demand applies to all forms of communication,
    including but not limited to telephone calls, text messages, emails,
    postal mail, and personal contact at my home or place of employment.
    
    As provided by 15 U.S.C. § 1692c(c), you may contact me only to:
      (1) advise me that you are ceasing further efforts to collect this
          debt;
      (2) notify me that you may invoke a specified remedy (such as
          referring this debt to an attorney or reporting it to a credit
          bureau); or
      (3) notify me that you are invoking a specified remedy.
    
    Be advised that any communication from you beyond these three
    permitted purposes will be documented and may form the basis of a
    complaint to the Consumer Financial Protection Bureau (CFPB), the
    Federal Trade Commission (FTC), and/or a civil action under 15 U.S.C.
    § 1692k, which provides for statutory damages, actual damages, and
    attorney's fees.
    
    Furthermore, pursuant to 15 U.S.C. § 1692c(a), please be advised that:
      - All telephone contact with me is inconvenient at all times and at
        all locations.
      - My employer prohibits personal calls. Do not contact me at my
        place of employment.
    
    [Optional — include if applicable: I also dispute this debt in its
    entirety and request validation pursuant to 15 U.S.C. § 1692g. Until
    you provide adequate validation, you may not continue collection
    activity.]
    
    [Optional — include if you refuse to pay: I refuse to pay this debt.]
    
    This is my formal written notice to cease communication. I expect your
    immediate compliance.
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]

    How to use this template:

    • Copy the text above into a word processor or text editor.
    • Replace every bracketed [ ] field with your information. Remove fields you do not have (e.g., if you do not know the original creditor, delete that line).
    • Keep or remove the optional paragraphs based on your situation.
    • Print the letter. Sign it by hand.
    • Make a photocopy for your records.
    • Send the original by certified mail with return receipt requested to the collector’s address.
    • Keep the return receipt (the green card) with your copy of the letter — this is your proof of delivery.

    Note: This template is provided for educational purposes and is not a substitute for legal advice. If your situation is complex — large debt, impending lawsuit, multiple collectors — consider consulting an attorney who handles FDCPA matters. Many consumer law attorneys offer free consultations and work on contingency.

    Limited Cease and Desist Letter Template

    Below is a template for a limited cease and desist letter — one that stops phone calls but permits written communication. Use this if you want to stop harassment while keeping the door open for settlement offers or negotiation.

    [Your Full Name]
    [Your Current Address]
    [Your City, State, ZIP]
    
    [Date]
    
    [Collector/Agency Name]
    [Collector's Address]
    [Collector's City, State, ZIP]
    
    RE: Account No. [Account/Reference Number]
        Original Creditor: [Original Creditor Name, if known]
        Amount Claimed: [$Amount, if known]
    
    To Whom It May Concern:
    
    I am writing regarding your collection efforts on the above-referenced
    account. Pursuant to 15 U.S.C. § 1692c(a) of the Fair Debt Collection
    Practices Act (FDCPA), I hereby demand that you CEASE all telephone
    communication with me regarding this debt.
    
    Specifically:
      - You may not call me at [your home phone number].
      - You may not call me at [your cell phone number].
      - You may not call me at [your work phone number].
      - You may not call any of my family members, neighbors, or
        references.
      - My employer prohibits personal calls. Do not contact me at my
        place of employment under any circumstances.
    
    All telephone contact is inconvenient at all times and at all
    locations, as provided by 15 U.S.C. § 1692c(a)(1).
    
    I am willing to communicate with you in writing only. You may send
    correspondence to the address listed at the top of this letter. I
    will respond in writing as appropriate.
    
    [Optional — include if applicable: I dispute this debt and request
    validation pursuant to 15 U.S.C. § 1692g. Until you provide adequate
    validation, you may not continue collection activity.]
    
    [Optional — include if you want to signal openness to settlement:
    I am open to discussing a written settlement or payment arrangement,
    provided all negotiation is conducted in writing.]
    
    If you continue to contact me by telephone after receiving this
    letter, I will document each call and may file a complaint with the
    Consumer Financial Protection Bureau (CFPB) and/or pursue a civil
    action under 15 U.S.C. § 1692k for violation of the FDCPA.
    
    I expect your immediate compliance with this written demand.
    
    Sincerely,
    
    [Your Signature]
    [Your Printed Name]

    How to use this template:

    • Copy the text, fill in the bracketed fields, and remove any that do not apply.
    • List every phone number you want them to stop calling.
    • Keep or remove the optional paragraphs.
    • Print, sign by hand, photocopy, and send by certified mail with return receipt requested.
    • Keep the return receipt with your copy.

    Tip: If you include the “open to settlement” optional paragraph, you signal to the collector that you are not just hiding — you are willing to resolve the debt, but on paper, not under phone pressure. This can keep the collector in a negotiation posture rather than a litigation posture.

    Cease and desist letter for debt collectors and FDCPA collection rights

    How to Send It So It Actually Holds Up

    A cease and desist letter is only as strong as your ability to prove the collector received it. If you send it by regular first-class mail and the collector says “we never got it,” you have no proof and no leverage. Here is how to send it so it holds up.

    Use Certified Mail With Return Receipt

    Send the letter by U.S. Postal Service Certified Mail with Return Receipt Requested (the green card). This gives you two things:

    • A tracking number that shows the letter was mailed and is in the postal system.
    • A return receipt — a postcard signed by the recipient (or their agent) confirming delivery, with the date of delivery.

    When the return receipt comes back in the mail, keep it. Staple or paperclip it to your copy of the letter. Store both somewhere safe. This is your proof that the collector received your cease and desist on a specific date. From that date forward, any contact from the collector (beyond the three statutory exceptions) is a documented violation.

    Keep a Complete File

    Your cease and desist file should contain:

    • A copy of the letter you sent (the signed version, not just the blank template).
    • The certified mail receipt (the stub with the tracking number).
    • The return receipt (the signed green card showing delivery).
    • The original collection notices you received from the collector — the first letter they are required to send within five days of initial contact under § 1692g, plus any subsequent letters.
    • A log of all calls you received from the collector before and after sending the letter — date, time, number, what was said, and any voicemail messages (save them).
    • Any correspondence from the collector after the cease and desist.

    If you ever need to file a CFPB complaint, an FTC complaint, or an FDCPA lawsuit, this file is your evidence.

    Alternative Delivery Methods

    • Email or online portal: Some collectors accept cease and desist letters by email or through an online dispute portal. If you use this method, save the sent email (with full headers) and any reply. Email delivery is harder to prove than certified mail, so if the stakes are high, use certified mail instead or in addition.
    • Fax: Rarely used today, but if the collector provides a fax number, a fax with a confirmation page provides proof of transmission. Again, certified mail is stronger.
    • Process server: For a cease and desist that may precede litigation, some attorneys use a process server. This is overkill for most consumer cease and desist letters but is an option in high-stakes situations.

    When Does the Collector’s Obligation Begin?

    The collector must stop contacting you once they receive your letter — not the day you mail it. Certified mail typically arrives in 1–3 business days, but allow up to a week. If the collector contacts you between the day you mail the letter and the day they receive it, that contact is generally not a violation (they have not received the letter yet). After the return receipt date, any non-permitted contact is a violation.

    One Letter Per Collector

    Send a separate cease and desist letter to each collector who contacts you. If the debt is sold to a new buyer, send a new letter to the new buyer. Keep a file for each.

    Key takeaway: Send by certified mail with return receipt, keep a complete paper file (letter copy, receipts, call log, collector correspondence), and send a new letter to each new collector. Your proof of delivery is what makes the letter enforceable.


    What Happens After You Send a Cease and Desist Letter

    Once the collector receives your cease and desist letter, several things can happen. Here is what to expect, what is normal, and what is a red flag.

    What Should Happen

    • The collector stops contacting you. This is the primary outcome and the legal requirement. Within a reasonable time after receiving your letter, the collector should cease all phone calls, letters, texts, and emails, except for the three permitted notifications under § 1692c(c).
    • You may receive one final communication. The collector may send one letter confirming that they are ceasing collection efforts, or notifying you that they are invoking a specific remedy — referring the debt to an attorney, suing you, or reporting it to a credit bureau. This is permitted and is not a violation.
    • The collector may close the file. If the collector decides the debt is not worth pursuing without the ability to contact you, they may close the file. This is more likely with smaller or older debts.
    • The collector may sell the debt. The collector may sell your account to another debt buyer. If the new buyer contacts you, you will need to send a new cease and desist letter to them. The original cease and desist does not automatically bind the new buyer (though some attorneys argue it should transfer with the debt — the safest approach is to send a new letter).
    • The collector may sue you. If the debt is within the statute of limitations and the collector decides litigation is worth the cost, they may file a lawsuit. If they do, you will receive a summons and complaint (formal court documents), which is not an FDCPA communication — it is a legal action. You must respond to a lawsuit; ignoring it leads to a default judgment. If you are sued, contact an attorney immediately.

    What Is Not Supposed to Happen

    • Continued calls or letters about the debt (beyond the permitted notifications). If the collector keeps calling or sending collection letters after receiving your cease and desist, each contact is a potential FDCPA violation.
    • Contact with third parties about your debt (family, neighbors, employer) except to get location information, and only if you have not already provided it.
    • Threats or intimidation. The FDCPA prohibits threats of violence, threats of arrest, and false statements about the legal status of the debt.
    • Continued credit reporting without addressing your dispute. If you disputed the debt and the collector continues to report it as undisputed, that may be a separate FDCPA and FCRA issue.

    Timeline

    There is no fixed statutory deadline for the collector to stop contact after receiving your letter — the law says they must cease, and “cease” means stop. In practice, most collectors stop within a few days to a couple of weeks of receiving the letter, as their systems update. If you receive contact more than 30 days after the return receipt date (and it is not one of the three permitted notifications), it is a clear violation worth documenting and pursuing.

    Key takeaway: After receiving your letter, the collector should stop contacting you (except for permitted notifications), may close the file or sell the debt, and may sue if the debt is within the statute of limitations. Continued collection contact beyond the permitted exceptions is an FDCPA violation — document it.


    What to Do If They Keep Calling

    If a debt collector continues to contact you after receiving your cease and desist letter, they are violating the FDCPA. Here is how to respond, step by step.

    Step 1: Document Every Contact

    Every call, text, email, or letter you receive after the collector’s receipt of your cease and desist is evidence. For each contact, record:

    • Date and time of the contact.
    • Method (phone call, text, letter, email, in-person).
    • Phone number or address the contact came from.
    • Who you spoke with (collector’s name, if given).
    • What was said (as close to verbatim as possible).
    • Any voicemail messages — do not delete them; save the audio.
    • Any caller ID screenshots or text message screenshots.

    Keep this log in a notebook, a spreadsheet, or a dedicated folder on your phone or computer. The more detailed and contemporaneous (written at the time of the contact) your records are, the stronger your evidence.

    Step 2: Save All Communication

    • Voicemails: Save the audio files. Many phones allow you to save voicemails as audio files or forward them to email. If you cannot save them digitally, record them with another device.
    • Texts and emails: Screenshot them and save the screenshots. Do not delete the originals.
    • Letters: Keep the originals, including the envelopes (the postmark can be important evidence). Do not write on the original — make a copy if you need to annotate.

    Step 3: File a Complaint With the CFPB

    The Consumer Financial Protection Bureau (CFPB) accepts complaints about debt collectors online at consumerfinance.gov/complaint. The process is free and straightforward:

    • Go to the CFPB complaint portal.
    • Select “Debt collection” as the category.
    • Describe the violation, including dates and what happened.
    • Attach copies of your cease and desist letter, the return receipt, and your contact log.
    • The CFPB will forward your complaint to the collector and require them to respond.

    The CFPB does not resolve individual disputes or award damages, but a CFPB complaint creates a public record, pressures the collector to respond, and can trigger regulatory scrutiny. Many collectors will resolve the issue quickly once a CFPB complaint is filed.

    Step 4: File a Complaint With Your State Attorney General

    Many state attorneys general have consumer protection divisions that handle debt collection complaints. Some states (like California, New York, and Florida) have their own debt collection laws that provide additional protections and remedies. Filing with your state AG is free and can be done through your state’s AG website.

    Step 5: Consult a Consumer Law Attorney

    If the collector continues to contact you after a cease and desist, you may have a claim under 15 U.S.C. § 1692k, which provides for:

    • Statutory damages up to $1,000 per violation (not per call — the cap is generally $1,000 for the overall pattern of violations for a given debt, though some courts interpret this differently).
    • Actual damages — compensation for any documented harm, such as emotional distress, lost wages, or medical costs related to the harassment.
    • Attorney’s fees and costs — the FDCPA requires the collector to pay your attorney’s fees if you win, which is why many consumer law attorneys take FDCPA cases on contingency (no upfront cost to you).

    A consumer law attorney can evaluate your case, send a follow-up letter, negotiate a settlement, or file a lawsuit. Many offer free consultations. You can find one through the National Association of Consumer Advocates (NACA) at consumeradvocates.org.

    Step 6: Consider an FDCPA Lawsuit

    If the violations are clear and well-documented, an FDCPA lawsuit can be an effective way to stop the harassment and recover damages. The statute of limitations for an FDCPA claim is one year from the date of the violation, so do not wait too long. A lawsuit also creates a strong public record and can deter the collector from violating again — against you or anyone else.

    Key takeaway: If a collector ignores your cease and desist, document every contact, save all evidence, file a CFPB complaint, file a complaint with your state AG, and consult a consumer law attorney. Many attorneys take FDCPA cases on contingency because the law requires the collector to pay your attorney’s fees if you win.


    How a Cease and Desist Letter Interacts With Validation Disputes

    A cease and desist letter and a debt validation letter (dispute letter) are two different tools that serve two different purposes. Understanding how they interact helps you use them in the right order.

    What a Validation Dispute Does

    Under 15 U.S.C. § 1692g, within five days of a debt collector’s first communication with you, they must send you a written notice containing:

    • The amount of the debt.
    • The name of the original creditor.
    • A statement that you have 30 days to dispute the debt.
    • A statement that if you dispute in writing within 30 days, the collector must obtain verification of the debt and mail it to you.
    • A statement that if you request the name and address of the original creditor within 30 days, the collector must provide it.

    If you send a validation dispute within the 30-day window, the collector must cease collection until they send you validation. “Cease collection” means no calls, no letters, no lawsuits, no credit reporting — until they validate. This is a powerful pause button.

    The Key Difference

    • A validation dispute forces the collector to prove the debt. It pauses collection temporarily. It does not permanently stop contact — once the collector validates, they can resume collection.
    • A cease and desist letter permanently stops contact (with the three exceptions). It does not require the collector to prove anything. It just shuts down communication.

    Which Should You Send First?

    If you are not sure the debt is yours or the amount is correct: Send a validation dispute first, within the 30-day window. This forces the collector to prove the debt and pauses collection while they do. If they fail to validate, they must stop collecting — and you may have grounds to dispute the credit reporting as well. If they do validate and the debt is legitimate, you can then decide whether to send a cease and desist, negotiate a settlement, or pay it.

    If you know the debt is yours and you just want the calls to stop: Send a cease and desist (or limited cease). You do not need to dispute a debt you acknowledge.

    If you are not sure AND you want to stop harassment: You can combine both in a single letter — dispute the debt and demand validation under § 1692g, and simultaneously demand cessation of telephone contact under § 1692c(a). This is a common and effective approach. The full cease template above includes an optional paragraph for disputing the debt; use it if it fits your situation.

    If the 30-day validation window has passed: You can still send a validation dispute, but the collector is not legally required to pause collection. They may still choose to validate. You can also still send a cease and desist at any time — there is no deadline for demanding that contact stop.

    A Note on Timing

    If you send a cease and desist letter before sending a validation dispute, you cut off the collector’s ability to send you the validation they would be required to provide. This can create a confusing situation. The safest sequence is usually: dispute first (if you are disputing), then cease and desist after you have the collector’s response (or non-response). But if the harassment is severe and you need the calls to stop immediately, a combined letter or a limited cease (no calls, written contact okay) lets you dispute while still protecting yourself from phone harassment.

    Key takeaway: A validation dispute forces the collector to prove the debt and pauses collection. A cease and desist stops contact permanently but does not require proof. If you are unsure about the debt, dispute first. If you just want contact to stop, cease and desist. You can combine both in one letter.


    Common Mistakes to Avoid

    Over the years, we have seen people make the same handful of mistakes with cease and desist letters. Here are the most common ones — and how to avoid them.

    1. Not Sending It by Certified Mail

    The single most common mistake. If you send a cease and desist by regular mail, the collector can simply say “we never received it” — and you have no way to prove otherwise. Certified mail with return receipt costs a few dollars and is the difference between an enforceable letter and a piece of paper.

    2. Acknowledging the Debt in the Letter

    Writing “I know I owe this debt but I want you to stop calling” may feel honest, but it can work against you. In some states, a written acknowledgment of a debt can restart the statute of limitations — turning a time-barred debt into a collectible one. If you are disputing, say you dispute. If you are not disputing, simply demand cessation without discussing the debt’s validity.

    3. Sending a Full Cease When a Limited Cease Would Do

    A full cease and desist is a nuclear option. It stops all communication, but it also stops settlement offers, payment plan options, and negotiation opportunities — and it can push the collector toward a lawsuit. If the debt is within the statute of limitations and you might be willing to negotiate, a limited cease (no calls, written contact okay) is often the smarter first move.

    4. Not Keeping a Copy and Proof of Delivery

    If you ever need to prove a violation — to the CFPB, your state AG, or a court — you need the letter, the certified mail receipt, and the return receipt. If you do not keep these, you have no evidence. Make a file the day you send the letter and keep everything in it.

    5. Ignoring a Lawsuit

    A cease and desist letter does not stop a collector from suing you. If you receive a summons and complaint, you must respond — usually within 20–30 days depending on your state. Ignoring a lawsuit leads to a default judgment, which can result in wage garnishment, bank levies, and property liens. If you are sued, contact an attorney immediately, regardless of whether you sent a cease and desist.

    6. Sending the Letter to the Wrong Party

    If the original creditor (not a third-party collector) is contacting you, the FDCPA’s cease and desist right does not apply the same way. Make sure you are sending the letter to a third-party debt collector covered by the FDCPA. If the original creditor is the one calling, check your state’s law — many states have parallel protections.

    7. Not Sending a New Letter When the Debt Is Sold

    If the collector sells your debt to a new buyer, your original cease and desist letter applies to the original collector — not automatically to the new one. When a new collector contacts you, send a new cease and desist (or validation dispute) to them. Keep a separate file for each collector.

    8. Giving Up Personal Information Unnecessarily

    Do not include your Social Security number, date of birth, or bank account information in a cease and desist letter. The collector should already have enough to identify your account (account number, original creditor, amount). Providing extra personal information can be used against you and serves no purpose in the letter.

    9. Making Threats You Cannot Back Up

    “Do this or I will sue you” is only effective if you actually intend and are able to sue. If you are not prepared to file an FDCPA lawsuit, do not threaten one. Instead, state that violations “may form the basis of a complaint or claim” — which is true and does not overcommit you. Let the law and your documentation do the work.

    10. Expecting the Debt to Disappear

    A cease and desist letter stops contact. It does not erase the debt, remove it from your credit report, or prevent a lawsuit. If you send a cease and desist expecting the whole problem to vanish, you may be surprised when the debt shows up on a new collector’s call list, or a lawsuit arrives. Use the letter for what it is — a communication tool — and pair it with a broader credit repair strategy.

    Key takeaway: Avoid the most common mistakes — send by certified mail, do not acknowledge the debt, keep copies and proof of delivery, do not ignore lawsuits, send new letters to new collectors, and do not expect the letter to erase the debt. Use the cease and desist as one tool within a larger plan.


    Frequently Asked Questions

    1. Does a cease and desist letter erase my debt?

    No. A cease and desist letter stops the debt collector from contacting you. It does not eliminate the debt, remove it from your credit report, or prevent the collector from suing you (if the debt is within the statute of limitations). The debt still legally exists. If you want to address the debt itself, you need a separate strategy — validation dispute, settlement, pay-for-delete, or bankruptcy, depending on your situation.

    2. Can a debt collector still sue me after I send a cease and desist letter?

    Yes. The FDCPA’s cease and desist right stops communication, not legal action. A collector can still file a lawsuit to collect the debt, as long as the debt is within the statute of limitations. In fact, some collectors are more likely to sue after receiving a full cease and desist, because their other options (calls, letters, settlement offers) are cut off. If you receive a summons, respond to it — do not ignore it. Consult an attorney if you are sued.

    3. Does a cease and desist letter remove the collection from my credit report?

    No. A cease and desist letter has no effect on credit reporting. If the collection account is being reported to the credit bureaus, it will continue to be reported for up to seven years from the date of the original delinquency, regardless of whether you sent a cease and desist. To address the credit reporting, you need to dispute the item with the credit bureaus, negotiate a pay-for-delete with the collector, or work with a credit repair professional.

    4. What is the difference between a full cease and desist and a limited cease and desist?

    A full cease and desist demands that the collector stop all communication (except for three narrow statutory notifications). A limited cease and desist restricts only certain types of contact — most commonly, it demands that the collector stop calling but permits written communication. A limited cease is often a better first step because it stops phone harassment while keeping the door open for settlement offers and negotiation, and it generally carries a lower risk of triggering a lawsuit.

    5. How long does a debt collector have to stop calling after receiving my cease and desist letter?

    There is no specific number of days written into the FDCPA. The law says the collector must cease communication, which means stop. In practice, most collectors stop within a few days to two weeks of receiving the letter, as their internal systems update. If you receive contact more than 30 days after the return receipt date (and it is not one of the three permitted notifications), it is a clear violation worth documenting and pursuing through a CFPB complaint or an attorney.

    6. What if the debt collector sells my debt to another company?

    Your cease and desist letter applies to the collector you sent it to. When a new debt buyer purchases the account and contacts you, they are a new “debt collector” under the FDCPA, and you should send a new cease and desist (or validation dispute) to them. Some attorneys argue that a cease and desist transfers with the debt, but the safest approach is to send a new letter to each new collector. Keep a separate file for each.

    7. Can I send a cease and desist letter by email?

    You can, but email is harder to prove than certified mail. The FDCPA requires “written” notice — email can qualify as written, but if the collector claims they did not receive it, you have less proof than you would with a certified mail return receipt. If you send by email, save the sent message with full headers and any reply. For maximum enforceability, use certified mail with return receipt, or send by both email and certified mail.

    8. Do I need a lawyer to send a cease and desist letter?

    No. You can send a cease and desist letter yourself using the templates in this guide. The FDCPA does not require the letter to be written by an attorney. However, if your situation is complex — large debt, impending lawsuit, multiple collectors, identity theft — consulting a consumer law attorney is wise. Many offer free consultations and take FDCPA cases on contingency. An attorney can also handle communications on your behalf, which provides an additional layer of protection: once a collector knows you are represented by counsel, they must generally communicate only through your attorney.

    Take the Next Step Toward Cleaner Credit

    A cease and desist letter is a powerful tool for stopping collection harassment, but it is just one piece of a larger credit repair picture. The debt still exists. The credit report may still show negative items. And the collector may still sue — or sell the debt to someone who will.

    If you are dealing with collection calls, disputes, negative credit items, or just want a clear picture of where your credit stands, we can help. At credit-repair.com, we offer a free credit audit that reviews your three-bureau credit reports, identifies inaccuracies and negative items, and maps out a personalized repair plan — all in plain language, with no pressure and no hidden fees.

    We are a San Diego-based, attorney-backed credit repair firm that operates in full compliance with the FCRA and FDCPA. We do not make empty promises or sell quick fixes. We educate you, advocate for you, and equip you with the tools to keep your credit strong for the long term — not just for the next few months.

    Get your free credit audit at credit-repair.com →

    You do not have to navigate this alone. Let us take a look at your credit picture and give you an honest, no-obligation assessment of what we can do together.

    Disclaimer: This article is provided for educational purposes only and does not constitute legal advice. The templates are general samples and may not fit every situation. If you are facing a lawsuit, dealing with identity theft, or have a complex credit situation, consult a qualified attorney in your jurisdiction. The FDCPA provides a one-year statute of limitations for filing claims, so do not delay if you believe your rights have been violated.

    Related articles:

    • [Internal link placeholder: What Is the FDCPA and How Does It Protect You?]
    • [Internal link placeholder: Debt Validation Letter — Template and Guide]
    • [Internal link placeholder: Statute of Limitations on Debt by State]
    • [Internal link placeholder: How to Remove Collection Accounts From Your Credit Report]
    • [Internal link placeholder: What to Do If a Debt Collector Sues You]
    • [Internal link placeholder: FDCPA Violations — How to Document and Report Them]
  • Credit Repair Denver, Colorado

    Credit Repair Denver, Colorado

    Ready-to-paste deliverable for the Denver city page on . Paste into WordPress (Elementor/Rank Math). Do not publish from here — this is copy only.

    SEO Metadata (set in Rank Math)

    SEO Title (59 chars): Credit Repair Denver, CO | Attorney-Backed Credit Solutions

    Meta Description (148 chars): Struggling with credit in Denver? Our attorney-backed, FCRA-compliant team disputes report errors and helps you rebuild. Start with a free review.

    Canonical URL: https://credit-repair.com/credit-repair-denver/

    IMPORTANT: The current canonical is broken and points to https://credit-repair.com/credit-repair-denver/ (typo). Update it in Rank Math → Advanced → Canonical URL to the correct URL above.

    Target Keyword / Phrase: credit repair Denver

    Secondary Keywords: Denver credit repair services, credit repair Denver Colorado, fix credit Denver, FCRA-compliant credit repair

    Suggested URL slug: credit-repair-denver (already correct — keep it)

    Page Content

    Credit Repair Denver, Colorado

    Credit Repair Denver, Colorado — We’re Here to Help You Rebuild

    Living with a low credit score is stressful. High interest rates, denied loan applications, rejected rentals, and the worry that one mistake will follow you for years — it adds up, and it can feel like the system is stacked against you.

    Here’s the good news: even small improvements to your score can open real doors — lower monthly payments, better loan terms, and a wider range of financial opportunities. You don’t have to figure it out alone, and you don’t have to do it all at once.

    If you’re in Denver dealing with missed payments, mounting debt, or errors on your credit report, our team is ready to work alongside you. We help you correct inaccurate reporting, dispute items that shouldn’t be there, and build a clear, realistic plan toward a stronger credit profile — no jargon, no false promises.

    Who Benefits from Credit Repair in Denver?

    Credit challenges affect renters, homeowners, small business owners, and families alike. If any of the following sounds familiar, we can help:

    Denied a loan, credit card, or apartment because of a low score — we’ll help you address what’s holding you back.

    Stuck paying high interest rates from past credit issues — improving your score can ease that monthly strain.

    Errors or outdated information on your report — we dispute and correct them with all three bureaus.

    Trying to rent or qualify for a mortgage in the Denver market — we’ll help you clean up your report so you can move forward.

    Missed payments or collection accounts in your history — we’ll walk you through strategies to recover and rebuild.

    Victim of identity theft — we’ll help remove fraudulent accounts and protect your credit going forward.

    Simply want better financial options — better cards, easier approvals, stronger terms. We’re here to help you get there.

    You’re not alone, and you don’t have to fix it alone either. Everyone deserves the opportunity to rebuild, and we’re here to help make that happen.

    Why Denver Residents Trust Us

    Attorney-backed expertise — our work is backed by experienced attorneys and built on a deep understanding of federal credit law. Your disputes are handled with legal rigor, not guesswork.

    Clear, honest communication — no hidden fees, no confusing fine print, no empty promises. We explain every step in plain language so you always know where things stand.

    Plans built around you — your financial situation is unique, so your credit repair plan is too. We tailor every strategy to your goals, timeline, and credit history.

    Ongoing guidance and support — we don’t disappear after the first dispute. From regular progress updates to prompt answers, we stay with you throughout the process.

    Serving Denver with integrity — we’re proud to serve Denver clients with the same honest, FCRA-compliant approach we bring to every city. We understand the local housing market and the cost-of-living pressures Denver residents face — and the role credit plays in getting ahead here.

    Credit repair Denver Colorado services and credit improvement

    Your Path to Stronger Credit: How Our Process Works

    Step 1 — Start With a Free Credit Review

    We begin with a no-cost, in-depth review of your reports from all three major bureaus — Equifax, Experian, and TransUnion. We look for errors, outdated accounts, duplicates, and anything else dragging your score down, then build a personalized plan.

    Step 2 — Dispute Inaccurate Negative Items

    Once we’ve identified the problems, we file formal disputes with the credit bureaus to challenge inaccurate, unverifiable, outdated, or unfair information. The bureaus generally have 30 days to investigate each dispute, and we follow up relentlessly to make sure your report reflects only what’s accurate.

    Step 3 — Build Strong Financial Habits

    Credit repair is only part of the picture. We also help you build the knowledge and habits that keep your score climbing — from credit utilization to payment management — so your progress lasts well beyond the disputes.

    Step 4 — Stay Informed With Regular Updates

    You’ll never be left guessing. We provide ongoing progress updates and stay available to answer your questions. Most clients begin to see initial changes within 30–90 days, though more complex files can take several months. Results vary, and we’ll always be honest with you about what to expect.

    Common Credit Issues We Address

    Late payments and delinquencies — a single late mark can weigh down your score. We help you address delinquencies and rebuild step by step.

    Collections and charge-offs — unpaid debts in collections can block new credit. We work with creditors and bureaus to dispute, negotiate, or reduce their impact where the law allows.

    Inaccurate or outdated information — wrong addresses, duplicate accounts, outdated balances, or incorrect details don’t belong on your report. We identify and dispute them.

    Bankruptcies and foreclosures — recovery is absolutely possible. We help you lay the groundwork for a stronger profile and guide you along the way.

    Identity theft — if accounts were opened in your name without permission, we take quick action to remove fraudulent items and safeguard your credit.

    No matter what’s bringing your score down, we’re ready to help you turn things around.

    Start Rebuilding Your Credit Today

    Ready to take charge of your credit and your financial future? Whether you’re dealing with negative marks or simply want a higher score, our attorney-backed team is here to help — one clear, honest step at a time.

    Call: +1 800-603-8045 Email: Request your free credit review today. Your fresh start begins with one conversation. Let’s take that first step together.

    Frequently Asked Questions

    What is credit repair, and how does it work?

    Credit repair is the process of reviewing your reports from the three major bureaus — Equifax, Experian, and TransUnion — and disputing inaccurate, outdated, or unverifiable information that may be hurting your score: wrong late payments, accounts that don’t belong to you, duplicate entries, or outdated negative items. Under the Fair Credit Reporting Act (FCRA), you have the legal right to dispute any information you believe is incorrect. We handle that process for you, from identifying issues to filing and following up on disputes.

    Yes. The FCRA gives you the right to dispute inaccurate information, and the Credit Repair Organizations Act (CROA) sets strict rules for legitimate credit repair companies — a written contract, a three-day cancellation right, and no fees charged before services are delivered. We operate in full compliance with both laws and work alongside experienced attorneys to keep every step ethical and accountable.

    How long does credit repair take?

    There’s no one-size-fits-all answer. Credit bureaus typically have 30 days to investigate each dispute, so many clients begin to see initial changes within 30–90 days. More complex files — multiple disputes, identity theft, older negative items — can take several months. We’ll give you an honest estimate based on your report and keep you updated throughout. Real, lasting credit improvement takes time, and we never promise overnight results.

    Can you guarantee a specific credit score increase?

    No — and you should be cautious of any company that does. No legitimate credit repair service can guarantee a specific score increase or the removal of specific items, because outcomes depend on your unique credit history and how the bureaus respond. What we offer is a thorough, FCRA-compliant process, honest communication, and a personalized plan focused on the issues most likely to move your score in the right direction.

    How do I get started with credit repair in Denver?

    It starts with a free credit review. We’ll pull and examine your reports from all three bureaus, identify what’s hurting your score, and walk you through a clear plan — with no obligation. Call +1 800-603-8045 or email to request your free review today.

    Request a free credit review