
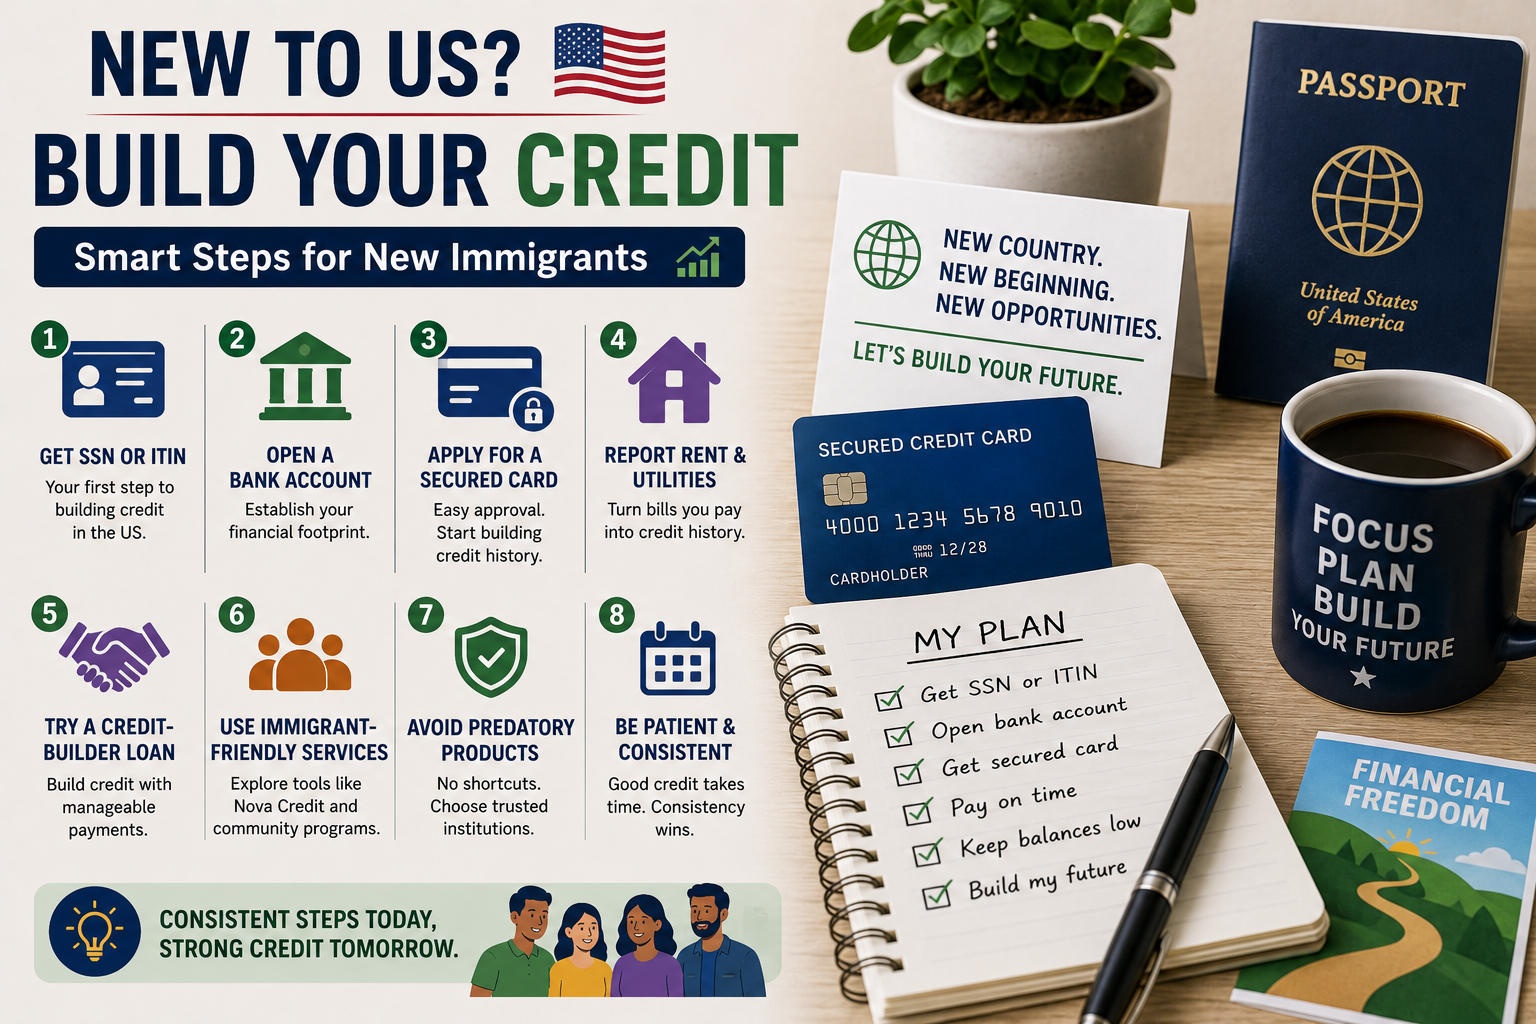
If you’re new to the United States, one of the most disorienting financial realities is that your credit history — even an excellent one — from your home country almost never transfers over. The US credit system is largely self-contained, and starting from zero here is a normal, expected part of the process, not a reflection of anything about your actual financial reliability. Here’s a practical, realistic path through it.
Why Foreign Credit History Doesn’t Transfer
US credit bureaus (Equifax, Experian, TransUnion) only track data reported by US-based lenders and furnishers. Credit history built in another country — even decades of it — simply isn’t in their system, because foreign financial institutions generally don’t report to US bureaus. A small number of specialized services have emerged attempting to bridge this gap for people relocating from specific countries, but they’re limited in scope and not universally recognized by US lenders, so it’s realistic to expect you’re building a file from scratch regardless of your financial history elsewhere.
Step 1: Get an SSN or ITIN
Before you can build a US credit file, you generally need either:
– A **Social Security Number (SSN)**, if you’re authorized to work in the US.
– An **Individual Taxpayer Identification Number (ITIN)**, available to those who don’t qualify for an SSN but need to file taxes or, in some cases, apply for certain credit products.
Some credit-building products (a small number of secured cards and specific immigrant-focused lenders) accept ITIN applicants, which is worth knowing if you don’t yet have work authorization but want to start building credit.
Step 2: Open a US Bank Account First
This is a foundational step that isn’t credit-building directly, but it’s usually a prerequisite for what comes next, and it also starts establishing a US financial footprint that some newer credit products consider during underwriting. Most major banks have accounts specifically designed to be accessible to new arrivals, sometimes with reduced documentation requirements compared to standard account opening.
Step 3: Apply for a Secured Credit Card
This is the most reliable and widely accessible starting point, largely because approval is based on your cash deposit rather than US credit history or, in many cases, even a long US income history. Look specifically for:
– **Cards that accept ITIN applicants**, if you don’t have an SSN.
– **Cards from banks with immigrant-focused programs** — several major banks have specific secured card products marketed toward new arrivals, sometimes with more accessible underwriting than their standard secured card offerings.
– **Confirmed reporting to all three bureaus**, as always.
Step 4: Look Into Alternative Data and Specialized Immigrant Credit Services
A growing category of services specifically addresses the “no US credit history” problem for immigrants:
– **Nova Credit and similar services** attempt to translate credit history from certain specific countries (the list of supported countries is limited but has been expanding) into a form some US lenders will consider, though this isn’t universally accepted and works only for immigrants from supported countries.
– **Rent and utility reporting services**, as covered in our credit-from-scratch guide, are particularly useful here since many new arrivals are reliably paying rent and utilities but not seeing that reflected anywhere on a credit file.
Step 5: Consider a Credit-Builder Loan Through a Community-Focused Institution
Community development financial institutions (CDFIs) and many credit unions specifically serve immigrant communities and often have credit-builder loan products designed for exactly this situation, sometimes with more flexible documentation requirements and staff experienced in helping new-to-country members navigate the process. These are worth researching in your specific area, since availability and terms vary by institution.
Step 6: Be Cautious With Employer- or Community-Based Informal Lending
In some immigrant communities, informal lending circles (sometimes called by various cultural names — tandas, susu, hui, and others depending on the community) are a longstanding and often effective way to save and access funds collectively. These are valuable financial tools, but it’s worth understanding they generally don’t report to US credit bureaus, so while they may serve real financial purposes, they won’t substitute for building an actual US credit file if that’s part of your goal (for future mortgage qualification, for example).
Step 7: Understand How US Employment History Affects Credit Applications
Beyond credit history specifically, many credit and loan applications ask about employment history and time at your current address, both of which are naturally limited for recent arrivals. A few practical notes:
– **Some lenders have specific accommodations for recent immigrants**, recognizing that standard “2 years at current job” thresholds don’t fit new arrivals — worth asking directly rather than assuming disqualification.
– **Building a consistent employment record, even across different employers**, generally satisfies most underwriting requirements better than gaps, so continuity matters more than tenure at a single employer in the early years.
Step 8: Avoid Predatory Products Targeting New Immigrants
Unfortunately, new arrivals are sometimes specifically targeted by less scrupulous lenders and “credit repair” operations that overstate what they can do, or by exploitative rent-to-own and high-interest installment lenders. Red flags to watch for:
– Any company implying they can “transfer” or “restore” your foreign credit history in a way that sounds too easy or complete.
– High-pressure sales tactics specifically targeting language barriers or unfamiliarity with US financial norms.
– Requests for large upfront fees before any service is rendered (illegal for credit repair companies specifically under CROA, and a red flag in lending contexts generally).
Community organizations, immigrant resource centers, and many credit unions offer free or low-cost financial counseling specifically for new arrivals, and are often a safer and more knowledgeable starting point than a cold-outreach product or service.
Realistic Timeline
– **First few months**: SSN/ITIN obtained, bank account opened, secured card and/or credit-builder loan application submitted.
– **6 months**: enough reporting history for most models to generate an initial score, assuming consistent on-time payments.
– **12-24 months**: with continued responsible use, a genuinely solid US credit foundation, often sufficient to qualify for unsecured products, better rental terms without requiring extra deposits, and eventually more substantial financing like an auto loan or, further down the line, a mortgage.
The Bottom Line
Starting a US credit file as a new immigrant is a genuine reset, regardless of your financial history elsewhere, and there’s no way around that structurally — US credit bureaus simply don’t have access to foreign financial data. The most reliable path is the same fundamental toolkit used by anyone building credit from scratch (secured cards, credit-builder loans, alternative data reporting), layered with an awareness of ITIN-accepting products if you don’t yet have an SSN, and a healthy skepticism toward any service overpromising a shortcut around the fact that this genuinely does take consistent time and responsible use to build.