
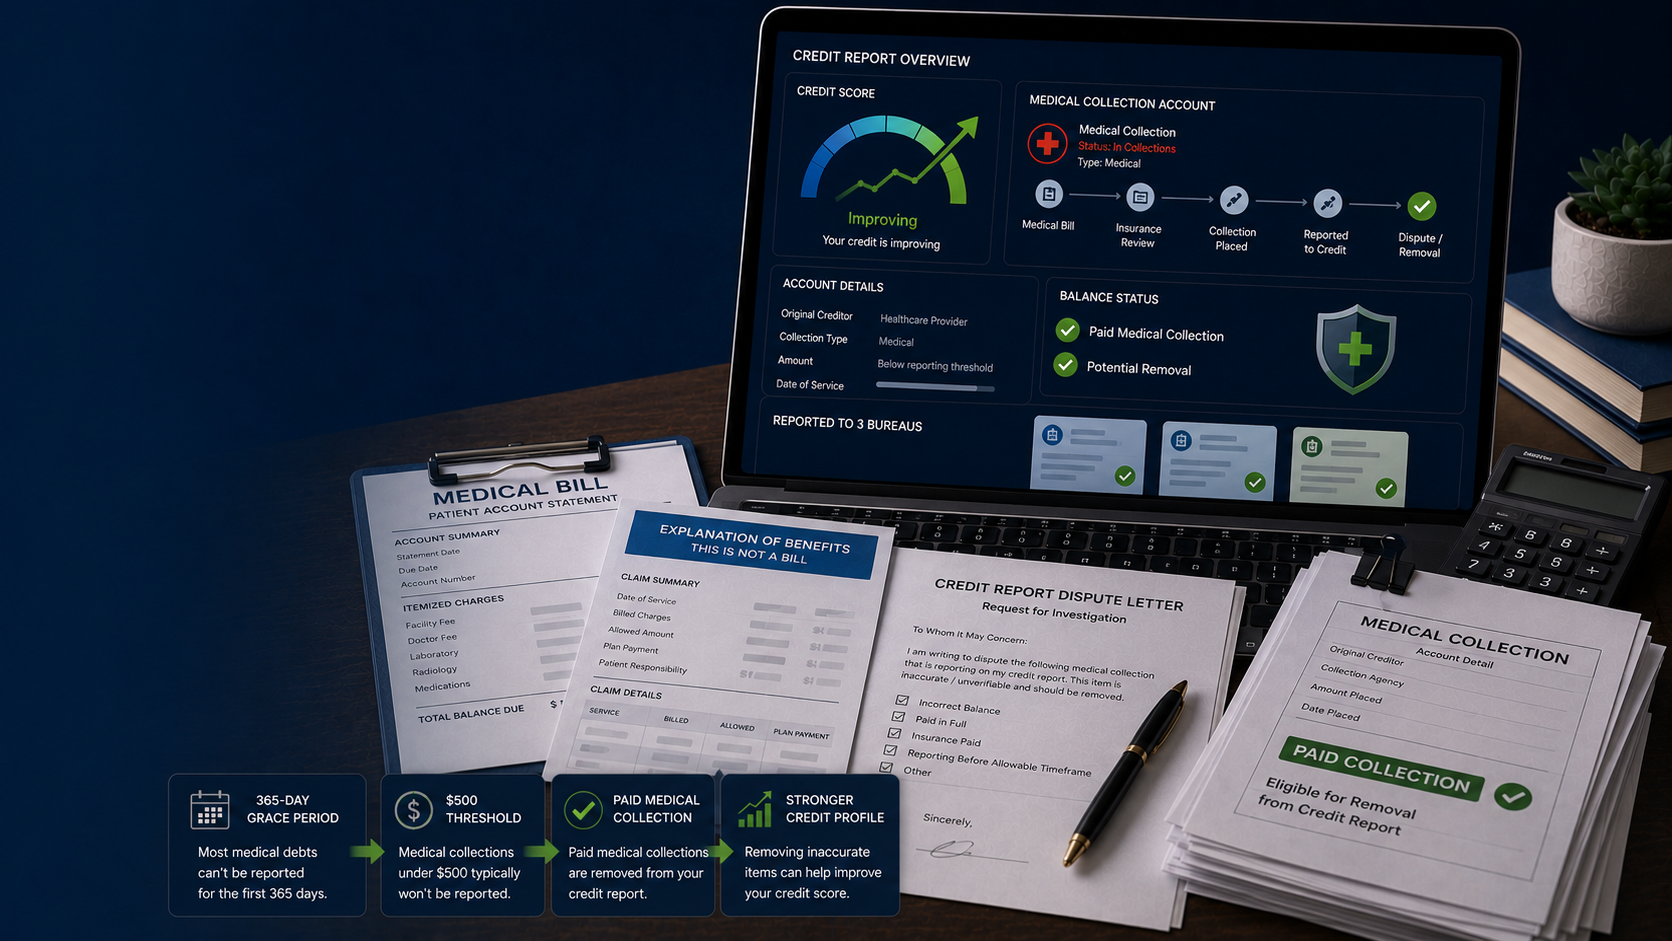
Medical bills on your credit report are now subject to new rules designed to protect consumers and reduce their impact on credit scores. As of July 1, 2022, paid medical collections are no longer included on credit reports, and as of March 1, 2023, medical collections under $500 are also excluded. Furthermore, starting in 2026, medical collections will only appear on credit reports after a full year of non-payment, providing a 12-month grace period before reporting. These changes aim to prevent medical debt from unfairly damaging consumers' financial standing.
For years, medical debt was treated almost identically to credit card debt or unpaid loans on your credit file. A single unpaid bill sent to collections could drag your score down by 100 points or more, follow you for seven years, and block you from a mortgage, a car loan, or even an apartment lease. That system was unfair on its face — medical debt is rarely a sign of financial irresponsibility. People don’t choose to get sick. They don’t comparison-shop while being wheeled into surgery. And bills often arrive months later, riddled with codes no one outside a billing department can decipher.
The good news is that the landscape has shifted — significantly. Over the past few years, the major credit bureaus and federal regulators have introduced rules that give you more breathing room, remove certain medical collections entirely, and create a grace period before a bill can ever touch your credit. These changes have already helped millions of people, but most consumers still don’t know the rules exist, let alone how to use them.
This guide walks through everything you need to know about medical bills on your credit report: how they get there, what the current rules are, how long they stay, how to check for them, how to dispute inaccurate ones, how to negotiate the underlying bills, and what to do if a collection is already on your file. Whether you’re staring down a fresh bill or cleaning up past damage, you’ll find a clear, step-by-step path here.
How Medical Bills End Up on Your Credit Report
Understanding the journey a medical bill takes — from a provider’s office to your credit file — is the first step to protecting yourself. Most people assume that a missed payment shows up on their credit the way a missed credit card payment does: almost immediately, automatically, and without warning. That’s not how medical debt works at all.
Here’s the actual path a medical bill travels before it ever touches your credit report.
Step 1: You Receive Care and Are Billed
You visit a doctor, urgent care, emergency room, or hospital. You may pay a copay at the time of service, but the bulk of the bill is usually submitted to your insurance first. Once insurance processes the claim — which can take 30 to 90 days — the provider bills you for your share: deductibles, coinsurance, out-of-network charges, or anything insurance denied.
This is where the timeline starts. Importantly, medical providers do not report directly to the credit bureaus. A hospital, a physician’s practice, or a lab cannot place a bill on your credit report themselves. They report to collections agencies, and those agencies are the ones that report to the bureaus.
Step 2: The Bill Becomes Past Due
Once you receive a bill, it’s past due according to the provider’s terms — typically 30 days from the statement date. However, “past due” at this stage still has nothing to do with your credit. The provider will send reminders, call you, and possibly offer payment plans. Most providers wait 90 to 180 days (and sometimes longer) before sending a bill to collections. This window is your opportunity to act, and we’ll cover exactly what to do in the sections ahead.
Step 3: The Account Is Sent to an External Collection Agency
If the bill remains unpaid after the provider’s internal collection efforts, they typically do one of two things:
- Assign the debt to a third-party collection agency (the provider still owns it and takes a percentage of what’s recovered).
- Sell the debt to a collection agency outright (the agency owns it and keeps everything they collect).
This is the moment the debt enters the collections ecosystem — but it still isn’t on your credit report yet.
Step 4: The Collection Agency Reports to the Credit Bureaus
Once a collection agency has the account, they can report it to Equifax, Experian, and TransUnion. This is when the medical collection appears on your credit report and begins affecting your score.
The Major Recent Changes That Help You
Medical debt is no longer treated exactly like other collection accounts. The three major credit bureaus — Equifax, Experian, and TransUnion — have voluntarily changed how medical collections are reported, and federal regulators have pushed further.
The Current Rules (as of 2026)
Here’s where things stand:
- Paid medical collections are removed. As of July 2022, paid medical collection accounts are no longer allowed to appear on your credit report. If you pay a medical collection, it must be removed — not just marked as paid, but deleted entirely. If a paid medical collection is still showing, dispute it with the bureaus and cite the rule; it will be removed.
- Unpaid medical collections have a 1-year waiting period. As of July 2023, medical collection accounts do not appear on your credit report until one year (365 days) after the original delinquency. This gives you a full year to work with the provider, set up a payment plan, dispute the bill, or resolve insurance issues before it ever touches your credit. Before this change, the waiting period was 6 months.
- Medical collections under $500 are excluded. As of April 2023, medical collection accounts with an original balance of less than $500 are excluded from credit reports entirely. If a small medical bill was sent to collections, it should not appear on your report at all.
- The major bureaus have removed most older medical collections. Equifax, Experian, and TransUnion have collectively removed billions in medical debt from consumer reports as part of these reforms. If you had medical collections that are now covered by the new rules, they may already be gone.
What This Means for You
If you have medical collections:
- Check if it should even be there. If it’s under $500, if it’s paid, or if it’s been less than a year since the delinquency, it should not be on your report. Dispute it.
- If it’s unpaid and over $500 and over a year old, consider paying it. Because paid medical collections must be removed, paying a medical collection is the most straightforward path to deletion — more reliable than pay-for-delete negotiations. Contact the provider or the collection agency, set up payment (or a payment plan), and once it’s paid, the entry should come off. If it doesn’t within 30–60 days, dispute it with the bureaus citing the paid-medical-removal rule.
- Dispute medical billing errors. Medical bills are notoriously error-prone. If the amount is wrong, if insurance should have covered it, or if the billing is duplicated, dispute it — both with the provider and, if it’s on your credit report, with the bureaus.
- Negotiate with the provider. Many hospitals and providers offer financial assistance programs, charity care, or discounts for uninsured patients. If you qualify, the bill may be reduced or eliminated — and if it’s already in collections, a resolved bill can be pulled back.
- Don’t ignore medical bills hoping they’ll go away. The 1-year grace period is a window to resolve them — not a reason to do nothing. Once the year passes and the collection appears, it will hurt your score like any other collection until it’s paid or falls off after 7 years.
A Note on Accuracy
The rules above are the current federal and industry standards as of 2026. Credit reporting rules do evolve — the CFPB has continued to push for further medical debt reporting restrictions. Always check your current reports to see what’s actually showing, and dispute anything that doesn’t match the rules in effect.
How Long Medical Collections Stay on Your Credit Report
The seven-year rule is one of the most misunderstood parts of credit reporting. People hear “seven years” and assume there’s nothing they can do but wait. That’s only partly true — and for medical collections specifically, the waiting period is often much shorter.
The Seven-Year Baseline
Under the Fair Credit Reporting Act (FCRA), most negative information — including collections — can remain on your credit report for up to seven years from the date of the original delinquency. For medical collections, the seven-year clock starts from the date the account was first reported as delinquent by the original provider, not the date it was sent to collections.
This means a medical collection that was sent to collections in, say, June 2024, would be eligible to fall off your report in June 2031 — seven years later.
But Medical Collections Often Don’t Last Seven Years
Here’s where the new rules change the math:
- If you pay the collection, it should be removed entirely — not just marked as “paid,” but removed. You don’t wait seven years.
- If the original balance was under $500 and it’s unpaid, it shouldn’t be on your report at all.
- If the collection is less than a year old and unpaid, it shouldn’t be on your report yet (the grace period).
- If the collection is inaccurate, unverifiable, or outdated, you can dispute it and have it removed.
In practice, the only medical collections that stay on a report for the full seven years are unpaid collections with an original balance of $500 or more that are more than a year old and are accurately reported. Even then, there are strategies — which we’ll cover in the section on dealing with existing collections — that can shorten that timeline.
What About Bankruptcies Involving Medical Debt?
If medical debt was included in a Chapter 7 bankruptcy, the bankruptcy itself remains on your report for up to 10 years from the filing date. The individual medical accounts included in the bankruptcy should show as “discharged in bankruptcy” with a zero balance and should not be reported as separate collections. If a medical account that was discharged in bankruptcy is still showing as an active collection, that’s a dispute candidate.
How to Tell When a Collection Should Fall Off
Your credit report should include the “date of first delinquency” or a similar date that tells you when the seven-year clock started. If you’re not sure whether a collection is too old to be on your report, look for that date. If seven years have passed (minus any period the account was in active dispute or litigation, in some cases), the entry should be removed automatically. If it’s still there, dispute it as obsolete.
How to Check if Medical Bills Are on Your Credit Report
You can’t fix what you can’t see. Checking your credit report for medical collections is straightforward and free, but you need to know where to look and what to look for.
Step 1: Get Your Free Reports from All Three Bureaus
Under federal law (the FCRA), you’re entitled to a free copy of your credit report from each of the three major bureaus — Equifax, Experian, and TransUnion — every 12 months. The official site is AnnualCreditReport.com. This is the only federally authorized source; other sites that offer “free” reports often come with strings attached, like paid subscription enrollment.
In recent years, the three bureaus have made reports available weekly through the same site at no cost — a temporary policy that has been extended multiple times. Even if weekly access changes, your annual right remains.
Pull all three reports, not just one. Medical collections may appear on one bureau’s report and not the others, because not all collection agencies report to all three. If you only pull one, you might miss something.
Step 2: Look in the “Collections” Section
Each report has a section dedicated to collection accounts. Scan it for:
- Account names that include words like “recovery,” “resolution,” “collections,” “financial services,” or “associates”
- The original creditor field — for medical debt, this often lists a hospital, physician group, lab, or imaging center, or it may simply say “medical” or “healthcare”
- Account types labeled as “medical” or “healthcare collection”
If the original creditor field is blank or unclear, the collection may still be medical. Some collectors don’t disclose the original creditor, which is itself a potential issue you can raise in a dispute.
Step 3: Cross-Reference With Your Own Records
Once you’ve identified potential medical collections, match them against your own records — Explanation of Benefits (EOB) statements from your insurance, bills from providers, and any collection letters you’ve received. Confirm:
- Is this a bill you actually owe?
- Was the amount correctly reported?
- Is the date of first delinquency accurate?
- Did insurance already pay this, or should it have?
- Is this a duplicate of another collection on the same report or a different bureau’s report?
Duplicate medical collections — where the same debt appears twice, often because it was transferred between collection agencies — are common and disputable.
Step 4: Check Your Credit Score Impact
After reviewing your reports, check your credit score to understand the impact. Many credit card issuers and banks now offer free FICO or VantageScore access to their customers. You can also use free services like Credit Karma or Experian’s free credit monitoring. Keep in mind that the scores these services show may differ from the scores a lender sees, but they’re useful for tracking movement over time.
If you find a medical collection on your report that shouldn’t be there — because it’s paid, under $500, within the grace period, or just plain wrong — the next step is to dispute it. That’s where the real cleanup work begins.
How to Dispute Inaccurate Medical Collections
Disputing an inaccurate medical collection is one of the most effective ways to improve your credit, and it’s a right guaranteed to you under the FCRA. The process is designed to be something you can do yourself, though many people choose to work with a professional — especially when multiple collections or complex billing errors are involved.
Grounds for Disputing a Medical Collection
You can dispute a medical collection on any of these grounds:
- The debt is not yours — wrong person, mixed file, identity theft, or a billing error attributed to you.
- The amount is wrong — the balance is higher than what you actually owe, includes unauthorized fees, or doesn’t reflect payments or insurance adjustments.
- The collection is a duplicate — the same debt appears more than once, on the same report or across bureaus.
- The collection is already paid — and should have been removed under the paid-removal rule.
- The original balance was under $500 — and it shouldn’t appear at all.
- The collection is within the 365-day grace period — and shouldn’t be reported yet.
- The collection is obsolete — more than seven years have passed since the date of first delinquency.
- The collection is unverifiable — the furnisher cannot or will not confirm the details when the bureau investigates.
- The original creditor information is missing or inaccurate.
How to File a Dispute
You can dispute with the credit bureau, the collection agency (the furnisher), or both. Disputing with both is often the most thorough approach.
For the credit bureaus, submit your dispute online or by mail. Include:
- A copy of your credit report with the disputed item highlighted
- A clear explanation of exactly what is wrong
- Copies of supporting documents
- A specific request for what you want corrected or removed
What to Include in a Dispute Letter
A strong dispute letter includes:
- Your full name, current address, and date of birth
- Any previous addresses that may be on file (helps the bureau locate your report)
- The account name and number as it appears on the report
- The specific reason for the dispute
- Copies (not originals) of supporting documents
- A clear request: remove, correct, or verify
- Your signature and the date
What If the Dispute Comes Back “Verified”?
If the bureau responds that the collection was verified and will remain, that’s not the end of the road. You can:
- Request a description of the reinvestigation procedure — the bureau must tell you how they verified the information.
- Dispute again with additional evidence if you have new documentation.
- Dispute directly with the furnisher if you haven’t already.
- Request a statement of dispute be added to your report — a brief note that appears on your file explaining that you dispute the accuracy of the information.
- File a complaint with the CFPB or your state attorney general if you believe the bureau or furnisher violated the FCRA.
- Work with a professional — an attorney-backed credit repair firm can often resolve disputes that have stalled at the consumer level, especially when the issue involves FCRA violations or complex billing errors.
A Note on “Frivolous” Disputes
Bureaus can reject disputes they consider “frivolous” — for example, if you dispute the same account repeatedly without new information, or if your dispute is vague. To avoid this, be specific, provide documentation, and only dispute when you have a legitimate reason.
How to Negotiate Medical Bills Before They Damage Your Credit
Prevention is always cheaper than cleanup. If you’re facing a medical bill you can’t pay in full, there are more options than most people realize — and many of them can reduce the amount you owe or eliminate it entirely. Here’s how to approach medical bills strategically.
Step 1: Request an Itemized Bill
Never pay a medical bill based on a summary statement. Always request a fully itemized bill from the provider. This document lists every service, supply, medication, and charge — and it’s where errors hide.
Common errors on medical bills include:
- Duplicate charges for the same procedure or supply
- Charges for services you didn’t receive (e.g., medications you weren’t given, procedures that weren’t performed)
- Upcoding — billing for a more expensive service than the one you actually received
- Separate charges for items that should be bundled (e.g., charging individually for surgical tools when they’re included in the procedure code)
- Facility fees and observation charges that don’t match the level of care you received
If you don’t recognize a charge, ask. If the provider can’t explain it, it shouldn’t be on your bill.
Step 2: Check for Coding and Insurance Errors
Medical billing uses standardized codes (CPT, HCPCS, ICD-10) for every service. A single wrong code can cause an insurance claim to be denied, leaving you with a bill you shouldn’t owe. Common coding issues include:
- A procedure coded as out-of-network when the provider was in-network
- A diagnosis code that doesn’t match the procedure code (which triggers automatic denials)
- A service coded as “self-pay” when you have insurance
- Pre-authorization requirements that weren’t communicated
If you suspect a coding error, ask the provider’s billing office to review the claim. You can also request that the claim be resubmitted to insurance with corrected codes. Many “denied” claims are approved on resubmission.
Step 3: Apply for Charity Care or Financial Assistance
This is the most underused tool in the medical billing world. Nonprofit hospitals are required by federal law (Section 501(r) of the Internal Revenue Code) to have financial assistance policies — often called charity care — that provide free or discounted care to patients who meet income thresholds.
Eligibility varies by hospital, but many policies offer:
- Full write-offs for patients below a certain income level (often 200% of the federal poverty level or below)
- Significant discounts (50–80%) for patients in the next income tier
- Sliding-scale discounts based on income and family size
For-profit hospitals and physician practices aren’t subject to the same legal requirement, but many still offer financial assistance programs. Always ask. You may be eligible for a substantial reduction or a complete write-off based on your income, even if you’re employed and insured.
To apply, contact the hospital’s billing or financial counseling department and ask for the financial assistance application. You’ll typically need to provide proof of income (tax returns, pay stubs), household size, and information about your assets and expenses.
Important: Under the law, nonprofit hospitals must make their financial assistance policies publicly available and must not engage in extraordinary collection actions (including reporting to credit bureaus) before making reasonable efforts to determine whether you qualify for financial assistance. If a nonprofit hospital sent your bill to collections without offering or processing your financial assistance application, that may be a violation worth raising.
Step 4: Use the No Surprises Act
The No Surprises Act, which took effect in 2022, protects you from certain types of surprise medical bills — particularly balance billing from out-of-network providers at in-network facilities.
Under the law:
- Emergency services cannot be balance-billed. If you receive emergency care from an out-of-network provider or facility, you cannot be charged more than your in-network cost-sharing amount.
- Non-emergency services at in-network facilities cannot be balance-billed by out-of-network providers (like anesthesiologists, radiologists, or pathologists) without your consent. You must be given a plain-language notice and consent to out-of-network care in advance.
- Air ambulance services are also protected from balance billing.
If you receive a balance bill that you believe violates the No Surprises Act, you have the right to dispute it through the federal independent dispute resolution process. You can also file a complaint with the CFPB or your state insurance department.
Step 5: Negotiate a Settlement or Payment Plan
If you’ve verified the bill is accurate, insurance has processed correctly, and you don’t qualify for financial assistance, you can still negotiate:
- Ask for a self-pay discount. Providers often have a lower rate for uninsured or self-pay patients. If you’re insured but facing a high out-of-network bill, ask if the self-pay rate is lower than your coinsurance amount — sometimes it is.
- Offer a lump-sum settlement. Collection agencies and providers may accept 40–70% of the balance as full payment if you can pay it in a single payment. Get any settlement agreement in writing before paying.
- Set up an interest-free payment plan. Many providers offer payment plans with no interest. Even small monthly payments ($25–$50) can keep an account out of collections while you work on a longer-term solution. Get the payment plan terms in writing and confirm that the provider will not send the account to collections as long as you’re making the agreed payments.
- Ask about “prompt pay” discounts. Some providers offer a discount (often 10–20%) if you pay within a certain timeframe.
A Warning About Medical Credit Cards
Some providers offer specialized medical credit cards (like CareCredit) to finance bills. These can be useful in narrow circumstances, but they often come with deferred interest promotions — if you don’t pay the full balance within the promotional period, you can be hit with retroactive interest at high rates. Read the terms carefully, and don’t sign up for a medical credit card under pressure in a billing office. Treat it as a last resort, not a first option.
What to Do Before a Bill Goes to Collections
The period between receiving a bill and it being sent to collections is your best window for protecting your credit. Here’s how to use it.
Don’t Ignore the Bill
The single most common mistake people make with medical bills is ignoring them. A bill you don’t understand feels easier to set aside than to confront — but every day you wait, the clock toward collections is ticking. Open every bill and EOB, even if you don’t think you owe anything. Insurance adjustments and corrections often arrive weeks after the original bill.
Call the Provider’s Billing Office
As soon as you receive a bill you can’t pay or don’t understand, call the provider’s billing office. Be polite but persistent. Ask for:
- An itemized bill if you haven’t received one
- An explanation of any charge you don’t understand
- A review of how insurance processed the claim
- A resubmission to insurance if you suspect a coding or processing error
- Information about financial assistance or charity care
- A payment plan if you’ll owe the balance
Document every call: the date, the name of the person you spoke with, and what was agreed. If the representative promises something (an extended due date, a payment plan, a financial assistance application), ask for it in writing.
Keep the Line Open
If you can’t pay the full amount, making even small payments can sometimes keep an account out of collections — but only if the provider has agreed to accept those payments. Some providers will still send an account to collections even if partial payments are being made, unless there’s a formal payment plan in place. This is why getting any payment arrangement in writing matters so much.
Submit Financial Assistance Applications Early
If you think you might qualify for charity care, apply as soon as you receive the bill — not after the account has gone to collections. Some hospitals will only consider financial assistance for a limited time after billing, and applying early can stop the collections process entirely.
Watch for the Transition to Collections
If you receive a letter from a collection agency, that’s your signal that the account has been transferred. At that point:
- The 365-day credit reporting grace period begins (if it hasn’t already).
- You should request debt validation from the collector in writing within 30 days (this forces them to prove the debt is yours and the amount is correct).
- You can still negotiate directly with the collector — often more aggressively than with the original provider, since collectors buy debt for pennies on the dollar.
Dealing with Medical Collections Already on Your Report
If you already have medical collections showing on your credit report, don’t panic. The first step is to determine whether each collection is actually allowed to be there under the current rules.
Start With the Easy Wins
- Paid collection? Dispute it. Paid medical collections should be removed.
- Under $500? Dispute it. Unpaid medical collections with an original balance under $500 should not appear.
- Less than 365 days old? Dispute it. It should not yet be reporting.
- Inaccurate? Dispute it with documentation.
- Duplicate? Dispute the duplicate entry.
- Too old? Check the date of first delinquency and dispute obsolete reporting.
For Legitimate, Older Medical Collections
If the collection is accurate, unpaid, $500 or more, and more than a year old, you have fewer options — but you still have choices.
First, determine whether you can afford to pay it. Because paid medical collections should be removed under the current bureau policies, payment may be the most direct route to deletion.
If you cannot pay the full amount, negotiate. Ask whether the provider or collector will accept a reduced settlement or payment plan. Get the agreement in writing before making a payment.
If the account is close to the seven-year reporting limit, waiting may be another option. But remember that the credit-reporting clock and the statute of limitations for a lawsuit are two different clocks. One does not automatically determine the other.
Can Credit Repair Help?
Yes — particularly when you have multiple collections, inconsistent reporting across bureaus, complicated insurance issues, or disputes that have already been verified and rejected.
A legitimate credit repair firm can:
- Review all three of your credit reports for medical collections
- Identify accounts that appear to violate current reporting rules
- Prepare and submit targeted disputes with supporting documentation
- Follow up when bureaus or furnishers fail to correct inaccurate information
- Help you understand whether paying, negotiating, or disputing is the best option for each account
No legitimate credit repair firm can guarantee specific results or promise to remove accurate, verifiable information — but a good one can significantly shorten the timeline and reduce the effort of cleaning up your report.
Common Mistakes That Make Medical Debt Worse
In our work with clients across the country, we see the same handful of mistakes over and over. Recognizing them can save you months of credit damage and thousands of dollars.
Mistake 1: Ignoring Bills You Don’t Understand
A bill you don’t understand isn’t a bill you don’t owe — but it’s also not a bill you should pay without question. Ignoring it is the worst response. Open it, request an itemized version, and start asking questions. The billing office would rather hear from you than send the account to collections.
Mistake 2: Paying a Bill Without Reviewing It
Paying a bill without checking for errors, confirming insurance processed it correctly, and asking about financial assistance is like paying a restaurant check without looking at the itemized receipt — except the amounts are much larger and the errors are much more common. Always review before you pay.
Mistake 3: Not Asking for Charity Care
This is the single biggest missed opportunity. Patients routinely assume they don’t qualify for financial assistance because they’re employed or insured. In reality, many hospital assistance programs cover families well into the middle class. Always ask. The worst they can say is no.
Mistake 4: Assuming a Collection Is Accurate
Collection agencies make mistakes. Debts are assigned or sold with incomplete information. Balances are inflated with fees that aren’t always lawful. Original creditor information is missing. If a collection shows up on your report, don’t assume it’s correct — verify it.
Mistake 5: Disputing Without Documentation
A bare dispute (“this isn’t mine”) with no supporting evidence is easy for a bureau to reject as frivolous. A documented dispute (“this debt was paid on Sat, 05 Sep 2026 17:14:59 +0000; attached is the receipt; under the bureaus’ paid medical collection removal policy it should be deleted”) is much harder to ignore. Always include copies of supporting documents.
Mistake 6: Giving a Collector Bank Access
Once a collection agency has your bank account number and authorization to withdraw, you’ve lost control of the payment schedule. Some collectors withdraw more than agreed, withdraw early, or continue withdrawing after the debt is settled. Pay by money order, certified check, or a one-time card transaction. Never sign up for recurring ACH payments with a collector.
Mistake 7: Waiting Too Long to Act
The 365-day grace period is generous, but it’s not infinite. The earlier you act — requesting itemized bills, applying for financial assistance, negotiating payment plans, disputing errors — the more options you have. Once a collection is on your report, cleanup is still possible but more work.
Mistake 8: Believing Quick-Fix Promises
Any company that promises to “remove all negative items in 30 days” or “legally wipe your credit clean” is not being honest with you. Legitimate credit repair takes time, works within the framework of the FCRA, and cannot guarantee removal of accurate, verifiable information. The credit system rewards patience and persistence, not magic.
Frequently Asked Questions
1. Do medical bills show up on your credit report immediately?
No. Medical bills do not appear on your credit report when you receive them or even when they’re past due. A bill must first be sent to a collection agency, and then the collection agency must report it to the credit bureaus. Under the current rules, unpaid medical collections cannot appear on your report until at least 365 days after the bill is sent to collections. Paid medical collections should not appear at all, and unpaid collections with an original balance under $500 should not appear either.
2. How much does a medical collection hurt your credit score?
The impact varies depending on your overall credit profile, but a single medical collection can lower your score by 50 to 100 points or more, especially if your credit was otherwise good. The impact is largest when the collection first appears and diminishes as it ages. Newer credit scoring models (like FICO 9 and VantageScore 4.0) treat medical collections less harshly than older models, and some disregard paid medical collections entirely — but many lenders still use older scoring models where medical collections carry full weight.
3. If I pay a medical collection, will my credit score go up?
Under the current rules, paying a medical collection should result in it being removed from your credit report, which can produce a meaningful score increase — sometimes 50 points or more, depending on what else is on your report. If you pay a medical collection and it’s still showing on your report after 30–45 days, dispute it with the bureau citing the paid-removal policy.
4. Can I dispute a medical collection if I think the bill is wrong?
Yes. You can dispute a medical collection on the grounds that the underlying bill is inaccurate — for example, if the amount includes charges for services you didn’t receive, if insurance should have paid it, or if it was already settled. Include any supporting documentation you have (EOBs, receipts, correspondence with the provider). The bureau must investigate and remove the collection if the furnisher cannot verify it.
5. What is the $500 medical collection rule?
As of July 2023, unpaid medical collections with an original balance under $500 should not appear on your credit report. The threshold is based on the original balance when the debt was sent to collections — not the current balance, which may have grown with fees or interest. If you see an unpaid medical collection under $500 on your report, it may be there in error and is a strong dispute candidate.
6. Will medical debt ever be completely removed from credit reports?
The CFPB finalized a rule in 2025 that would ban medical debt from credit reports entirely, but the rule has faced legal challenges and its enforcement status is uncertain as of 2026. The voluntary credit bureau changes — paid removal, the $500 threshold, and the 365-day grace period — remain in effect regardless. The trend is clearly toward reducing or eliminating medical debt’s role in credit reporting, but you should not rely on a full ban being in place today. Take action under the current rules, and a full ban — if it comes — will be a bonus.
7. Can a medical collection be removed before seven years?
Yes — and it often is. Paid medical collections should be removed immediately. Collections under $500 should not appear at all. Collections within the grace period should not appear yet. Inaccurate or unverifiable collections can be removed through disputes. Pay-for-delete agreements and goodwill removals can shorten the timeline for legitimate collections. The only medical collections that typically remain for the full seven years are accurate, unpaid collections of $500 or more that are more than a year old.
8. Should I use a medical credit card to pay my bills?
Medical credit cards can be a last-resort option, but they carry significant risks — particularly deferred interest promotions that can result in retroactive interest charges if you don’t pay the full balance within the promotional period. Read the terms carefully, don’t sign up under pressure in a billing office, and explore financial assistance, payment plans, and settlement options first. A medical credit card should never be your first move.
Take the Next Step Toward a Cleaner Credit Report
Medical debt doesn’t have to follow you for years. The rules have changed in your favor — paid collections come off, small debts shouldn’t appear, and you have a full year to resolve bills before they touch your credit. But knowing the rules and using them effectively are two different things.
If you’re dealing with medical collections on your credit report, or you want to understand exactly what’s on your file and what can be done about it, we can help. At credit-repair.com, we offer a free credit audit that pulls and reviews all three of your credit reports, identifies medical collections and other negative items, and walks you through exactly what can be disputed, negotiated, or removed — all within the framework of the FCRA and other consumer protection laws.
Our approach is attorney-backed, transparent, and built on the belief that you deserve a financial partner, not a one-time service. We don’t make empty promises or offer quick fixes. What we do is methodical, legal, and effective: we audit your reports, identify what’s hurting your score, and work with you to build a plan that produces measurable progress.
Get your free credit audit at credit-repair.com →
Your credit report shouldn’t be punished for getting sick. Let’s take a look together and see what we can clean up.
This article is for informational purposes only and does not constitute legal advice. Credit outcomes vary based on individual circumstances. We operate in full compliance with the Fair Credit Reporting Act (FCRA) and all applicable federal and state consumer protection laws.