
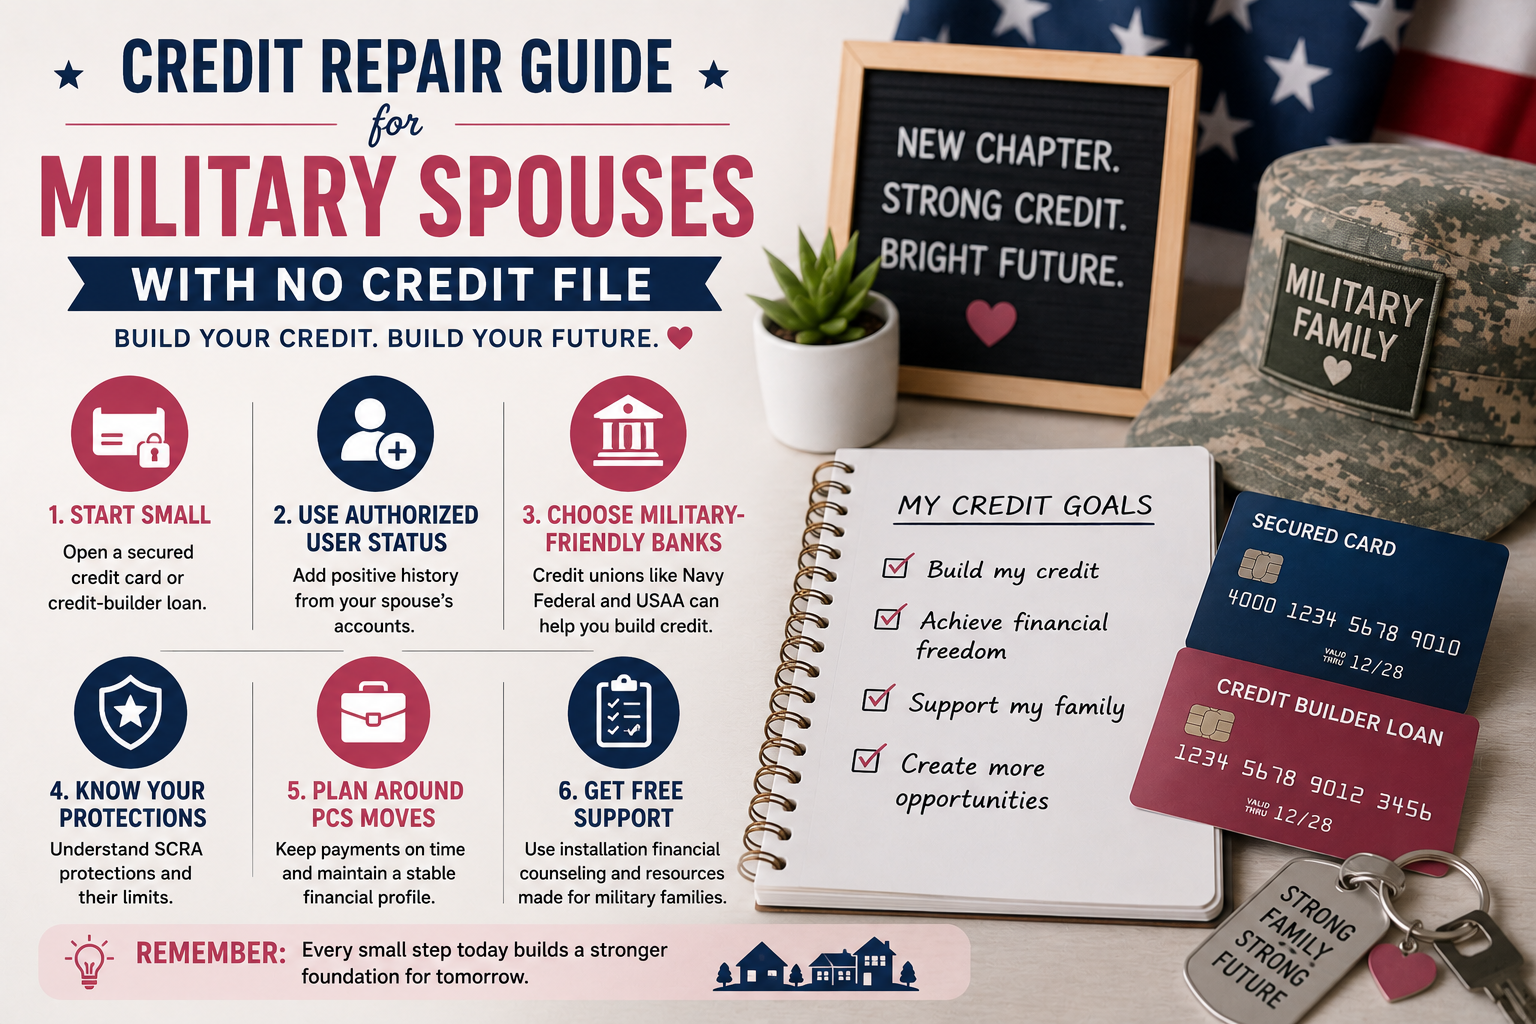
Military spouses face a specific, well-documented credit problem: frequent relocation, employment gaps tied to permanent-change-of-station (PCS) moves, and — for many — a credit history that never got the chance to establish itself because life circumstances kept interrupting the process. None of this is really “credit repair” in the traditional sense of fixing errors or negative marks; it’s about building a file that’s been structurally hard to establish. Here’s a practical path forward.
Military spouses frequently face challenges in establishing an independent credit file due to the unique demands of military life, including frequent relocations every 2-3 years and employment gaps often caused by permanent-change-of-station (PCS) moves and state-by-state licensing delays. These circumstances can prevent the consistent employment and financial stability lenders typically seek, leading many military spouses to become "credit invisible" or rely solely on their service member spouse's credit. To overcome this, military spouses can strategically build credit by using secured credit cards, becoming an authorized user on a spouse's well-established account, or securing credit-builder loans from military-focused financial institutions such as Navy Federal or USAA.
Why Military Spouses Are Disproportionately Credit Invisible
A few compounding factors specific to military spouse life make this a genuinely common issue, not an individual failing:
– **Frequent moves (often every 2-3 years)** disrupt employment continuity, which affects income stability that lenders like to see, and can also make it harder to maintain long-standing local financial relationships (like with a hometown credit union) that sometimes offer more favorable terms to established customers.
– **Employment gaps** are common and often necessary given relocation timing, licensing transfer delays (particularly for licensed professions like teaching, nursing, or cosmetology, where state-by-state relicensing can take months), and childcare availability that varies dramatically by duty station.
– **Reliance on a spouse’s credit** during periods of un- or under-employment is common, which can leave the non-military spouse with a thin or nonexistent independent credit file, especially if most household credit was established under the service member’s name before marriage.
Step 1: Establish Your Own Credit Identity, Even If Your Spouse Has Strong Credit
If your household’s credit is largely built under your service member spouse’s name, prioritize establishing something in your own name, even modestly:
– **A secured credit card** used lightly and paid in full monthly is the most reliable, widely available starting point regardless of your current employment status, since approval is based on your deposit rather than income.
– **Becoming an authorized user on your spouse’s well-established accounts** can add years of positive history to your own file relatively quickly, assuming the card issuer reports authorized user activity (worth confirming, since not all do) — this is often one of the fastest ways for a military spouse to build a real credit history if the service member has strong existing credit.
– **A credit-builder loan** through a military-focused credit union (Navy Federal, USAA, and others serve this market specifically and often have relevant products) adds installment credit history alongside revolving credit.
Step 2: Use Military-Specific Financial Institutions Strategically
Credit unions and banks that specifically serve military families often have more flexibility and relevant product offerings for exactly this situation:
– They’re generally more familiar with PCS-related employment gaps and less likely to view them as a red flag the way a conventional lender unfamiliar with military life might.
– Many offer specific credit-builder products, often with lower minimums and more accessible approval criteria.
– Membership eligibility typically extends to spouses and dependents, not just the service member, so these institutions are directly available to you.
Step 3: Understand the Servicemembers Civil Relief Act (SCRA) — and Its Limits for Spouses
The SCRA provides certain protections to active-duty service members regarding interest rate caps and other financial protections, but it’s worth understanding that **these protections generally apply to the service member specifically**, not automatically to the spouse’s independently-held accounts, unless the spouse is a joint holder on a covered obligation. If you’re navigating financial hardship tied to a PCS move or deployment, it’s worth confirming exactly which accounts and which of you the SCRA protections actually cover, rather than assuming blanket coverage.
Step 4: Navigate Employment Gaps Strategically for Credit Applications
Employment gaps are a normal and expected part of military spouse life, but they can complicate income verification for credit and loan applications. A few practical approaches:
– **Document any freelance, remote, or portable income** consistently, even if modest — remote and portable careers have become more common and more accepted by lenders as verifiable income sources.
– **Time larger credit applications (a car loan, a mortgage) around periods of established employment** where possible, rather than immediately after a PCS move when your income history at a new position is thin.
– **Use household income when applying jointly** with your service member spouse for products where joint income qualification makes sense, rather than trying to qualify solely on your own often-interrupted income history.
Step 5: Protect Your Address and Identity During Frequent Moves
Frequent relocation creates practical credit-file hygiene issues worth staying on top of:
– **Update your address with the credit bureaus and all creditors promptly** after each move — mail-related identity verification issues and missed statements (which can lead to accidentally missed payments) are a real and preventable risk during PCS transitions.
– **Consider a permanent mailing address** (a family member’s address, a P.O. box you maintain regardless of duty station) for critical financial mail, to reduce the risk of missing something important during the chaos of a move.
– **Monitor your credit report more frequently than average** during and immediately after moves, since this is a higher-risk window for both administrative errors and identity theft (moving-related mail is a known vector for mail theft and identity fraud).
Step 6: Take Advantage of Free Military Financial Counseling
Every branch offers free financial counseling through installation-based Personal Financial Management Programs, generally available to spouses and dependents, not just service members. These counselors can provide personalized guidance on credit building, budgeting through PCS transitions, and navigating the specific financial disruptions of military life — and unlike many private financial advisors, this service is free and specifically trained around military-family financial patterns.
Realistic Expectations Given the PCS Cycle
Credit building doesn’t pause for a move, but it’s worth planning around your PCS timeline realistically:
– **Before a move**: ensure autopay is set up on any credit accounts so payments continue reliably even amid moving chaos, and update your address proactively rather than after mail starts bouncing.
– **During the transition period**: this is often when employment and income are most disrupted; lean on any established credit (secured cards, authorized user status) that doesn’t depend on your current employment status.
– **After settling at a new duty station**: this is typically the best window to pursue new employment-dependent credit products, once you have a documented income history at the new location.
The Bottom Line
Building credit as a military spouse isn’t fundamentally different in mechanics from building credit anywhere else — it’s the same combination of secured products, authorized user status, and consistent on-time payments — but the PCS cycle and associated employment disruption make consistency harder to maintain without deliberate planning. Leaning on military-specific financial institutions, keeping address and autopay information current through moves, and using authorized user status on a spouse’s established accounts are the most practical, military-life-specific accelerators available, on top of the standard credit-building fundamentals that apply to everyone.