
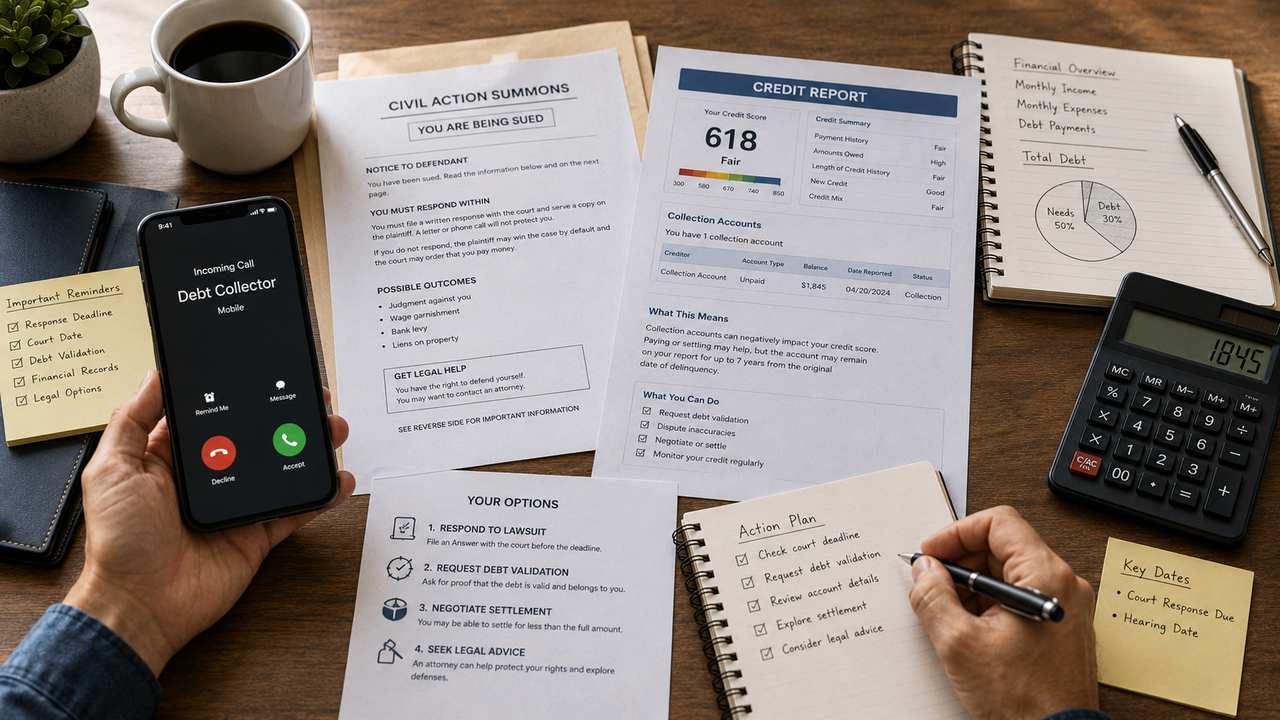
If Midland Credit Management (MCM) is suing you, it is crucial not to ignore the lawsuit, as this can lead to a default judgment against you. MCM is a debt buyer that purchases delinquent accounts, and their lawsuits require a formal response within a specific deadline to protect your rights. Your options include confirming the lawsuit's legitimacy, carefully reviewing documents, exploring potential defenses, and considering consultation with a consumer law attorney. Engaging with the legal process, such as filing a formal answer or exploring settlement options, is essential to avoid automatic adverse outcomes.
First: Do Not Ignore This
Before anything else, understand this clearly: ignoring a lawsuit is the single worst thing you can do, regardless of whether you believe the debt is accurate, too old, or improperly pursued. Every lawsuit comes with a specific deadline to file a formal response (called an “Answer” in most courts), typically ranging from 14 to 30 days depending on your state and the type of court. If you don’t respond by that deadline, the court can enter a default judgment against you — meaning you automatically lose the case without ever presenting any defense, even a legitimate one like an expired statute of limitations or inadequate proof of the debt. A default judgment can lead to wage garnishment, bank account levies, or property liens, depending on your state’s laws, and it’s considerably harder to undo after the fact than it is to prevent by responding on time.
Who Is Midland Credit Management, and Why Are They Suing You?
Midland Credit Management (MCM) is a large debt buyer, a subsidiary of publicly traded Encore Capital Group (NASDAQ: ECPG), headquartered in San Diego, California. Unlike a traditional collection agency hired by your original bank, MCM (often through its affiliate Midland Funding LLC, which frequently holds legal ownership of the purchased accounts) buys charged-off debt outright, typically credit card debt, for a small fraction of the original balance. When informal collection efforts — calls, letters, settlement offers — don’t result in payment, MCM sometimes escalates to filing a lawsuit to obtain a court judgment, which gives them additional legal tools (like wage garnishment or bank levies, depending on your state) to collect.
If you’re being sued, it almost always means an old, unpaid credit card or similar account was charged off by your original bank, sold to MCM (or Midland Funding), and MCM has now decided that litigation is the most effective way to pursue collection on that specific account.
Step One: Confirm the Lawsuit Is Legitimate
Before anything else, verify that what you’ve received is a genuine court filing, not a scam. Legitimate lawsuits are filed with an actual court, will reference a specific case number, and can be verified by contacting the clerk of the court listed on the documents directly (using contact information you look up independently, not from the paperwork itself, as an added precaution). If you have any doubt about legitimacy, this verification step takes only a few minutes and provides real peace of mind either way.
Step Two: Read the Documents Carefully and Note the Deadline
Court documents can be dense and intimidating, but the most important details to identify immediately are: the specific deadline to respond, which court the case was filed in, the case number, and the exact amount MCM is claiming you owe. Mark the response deadline prominently — this is the single most time-sensitive piece of information in the entire process.
Step Three: Determine Whether You Have a Response Strategy
You generally have a few broad paths once served: filing a formal Answer contesting the lawsuit (in whole or in part), attempting to settle with MCM before the case proceeds further, or, in rare cases, allowing a judgment if you have no viable defense and no ability to negotiate (though even in this scenario, responding is still generally preferable to a default judgment, since it may allow you to negotiate a structured payment arrangement as part of the judgment rather than facing more aggressive collection tools).
Filing a Formal Answer
An Answer is your formal written response to the lawsuit, addressing each claim MCM has made. This doesn’t need to be a lengthy legal document — many court systems provide simplified Answer forms, and some consumer advocacy organizations offer templates specifically designed for responding to debt collection lawsuits. Filing an Answer, even a relatively simple one, prevents a default judgment and forces MCM to actually prove their case in court, which shifts real leverage back toward you, since debt buyers sometimes struggle to produce complete documentation for older, resold accounts.
Common Defenses Worth Considering
- The statute of limitations has expired. Every state has a legal time limit (commonly 3-10 years, depending on the state and debt type) within which a creditor can sue you to collect. If MCM filed suit after this window closed, this is a strong, often case-ending defense — but it must generally be raised affirmatively in your Answer, since courts don’t always apply it automatically on your behalf.
- MCM can’t adequately prove ownership of the debt. Debt buyers must be able to demonstrate a clear chain of ownership from the original creditor to themselves, along with accurate documentation of the amount owed. For older debt that’s been resold multiple times, this documentation is sometimes incomplete or missing, which can be a genuine, successful defense if the plaintiff can’t meet their burden of proof.
- The amount claimed is inaccurate. If MCM’s claimed balance includes improper fees, incorrect interest calculations, or simply doesn’t match your own records, this is worth raising specifically.
- You’ve already paid or settled this debt. If you have documentation showing prior resolution, this is a straightforward and often decisive defense.
- The debt isn’t yours. Whether due to identity theft or a data-matching error, this is worth raising if applicable, along with any supporting documentation.
Step Four: Consider Consulting a Consumer Law Attorney
Given what’s potentially at stake — a court judgment, wage garnishment, and lasting damage to your credit and finances — consulting an attorney, even for a single initial conversation, is genuinely worth considering. Many consumer law attorneys who handle debt defense cases offer free or low-cost initial consultations, and some even work on a contingency or fee-shifting basis in cases involving FDCPA violations, since that law allows for recovery of attorney’s fees if a violation is successfully proven. An attorney can help you identify which specific defenses genuinely apply to your situation, draft a proper Answer, and potentially negotiate a more favorable settlement than you might secure on your own, given their familiarity with how MCM and similar debt buyers typically approach litigation and settlement.
Step Five: Explore Settlement, Even After Being Sued
Being sued doesn’t mean settlement is off the table — in fact, many debt buyer lawsuits, including those filed by MCM, are resolved through a negotiated settlement rather than proceeding to a full trial. Since MCM purchased the debt at a steep discount, there’s often genuine room to negotiate a reduced lump-sum payment or structured payment plan, even after litigation has begun, sometimes resulting in the lawsuit being dismissed as part of the settlement agreement.
If you pursue this route, get any settlement agreement in writing before making a payment, and specifically confirm what happens to the lawsuit itself — ideally, a dismissal with prejudice (meaning it can’t be refiled later) as part of the agreement, rather than simply an informal understanding that they won’t pursue it further.
What Happens If You Don’t Respond and a Default Judgment Is Entered?
If you miss the response deadline and a default judgment is entered against you, MCM gains access to additional legal collection tools that vary by state but commonly include:
- Wage garnishment, where a portion of your paycheck is legally redirected to satisfy the judgment, subject to state and federal limits on how much can be garnished.
- Bank account levies, where funds in your bank account can be seized to satisfy the judgment, though certain funds (like Social Security income, in many states) are often protected from this.
- Property liens, particularly relevant if you own real estate, which can complicate selling or refinancing the property until the judgment is resolved.
It’s sometimes possible to have a default judgment vacated (undone) after the fact, particularly if you can show you weren’t properly served or had a legitimate reason for missing the deadline, but this is a more difficult and uncertain process than simply responding on time in the first place — which is exactly why acting quickly upon being served matters so much.
Understanding MCM’s Documentation Requirements in Court
Because MCM is a debt buyer rather than the original creditor, they’re generally required to prove, to the court’s satisfaction, a complete chain connecting the original account to their current ownership, along with accurate records of the amount owed. This typically requires records like the original account agreement, a bill of sale or assignment document showing the debt was properly transferred to Midland Funding or MCM, and account statements showing the balance history. In practice, this documentation is sometimes incomplete, especially for older debt that’s changed hands more than once before reaching MCM — which is exactly why a well-prepared response that specifically challenges MCM to produce this documentation, rather than simply asserting the debt isn’t yours in general terms, is often the more effective legal strategy.
What to Expect at Each Stage of the Process
After filing your Answer, the case typically proceeds to a discovery phase, where both sides can request documentation from each other — this is your opportunity to formally request MCM produce their complete chain-of-ownership documentation.
Settlement discussions often occur throughout this process, sometimes initiated by MCM, sometimes by you or your attorney, and many cases resolve at this stage without ever reaching trial.
If the case does proceed to trial (relatively uncommon for smaller consumer debt amounts, though not impossible, particularly in small claims court), you or your attorney would present your defense, and MCM would need to prove their case with adequate documentation and testimony.
Frequently Asked Questions
How much time do I actually have to respond to a lawsuit from Midland Credit Management?
This varies by state and court, but commonly ranges from 14 to 30 days from when you were served. The exact deadline should be specified in the court documents themselves — confirm this immediately upon receiving the paperwork.
Can I represent myself in court against MCM without an attorney?
Yes, this is legally permitted (called appearing “pro se”), and many people do successfully respond to and even win debt collection lawsuits without an attorney, particularly with the help of self-help resources many courts provide specifically for this type of case. That said, given what’s potentially at stake, at least a brief consultation with an attorney is worth considering if it’s accessible to you.
Will settling with MCM after being sued still show up as a lawsuit on my record?
The underlying court case is a matter of public record regardless of the outcome, though a settled or dismissed case is generally viewed far more favorably than an unpaid judgment, both practically and in terms of your credit report, which would reflect the resolved status rather than an open judgment.
Can MCM garnish my wages immediately after filing the lawsuit?
No — garnishment generally can’t occur until after a court judgment has been entered against you, which requires either a default (from not responding) or an actual court ruling in MCM’s favor after the case proceeds.
Is it worth negotiating with MCM before my response deadline, or should I file an Answer first?
Both are worth pursuing simultaneously if possible — filing your Answer protects you from a default judgment regardless of how settlement discussions proceed, so it’s generally not advisable to rely solely on settlement negotiations without also meeting your formal response deadline, since a settlement isn’t guaranteed to be finalized before that deadline passes.
What if I can prove the statute of limitations has expired — do I still need to respond to the lawsuit?
Yes, absolutely — an expired statute of limitations is a defense you generally need to raise affirmatively in your Answer; it doesn’t automatically dismiss the case on its own, and failing to respond and raise this defense properly could still result in a default judgment despite having a technically valid defense available.
A Sample Structure for Your Answer
While you should always check your specific court’s required format (many courts provide official fillable Answer forms specifically for debt collection cases, which is generally preferable to a freeform document), a basic Answer typically includes:
- Case caption information — the court name, case number, and the names of both parties, copied exactly from the summons or complaint you received.
- A response to each numbered allegation in MCM’s complaint — for each numbered paragraph they’ve filed, you’ll typically respond with “admit,” “deny,” or “without sufficient knowledge to admit or deny” as appropriate.
- Any affirmative defenses, listed specifically — this is where you’d state, for example, “Plaintiff’s claim is barred by the applicable statute of limitations” or “Plaintiff has failed to establish ownership of the alleged debt,” if these apply to your situation.
- Your signature and the date, along with proper filing according to your specific court’s rules (which may include filing fees, though fee waivers are often available for those who qualify based on income).
Many state court websites and legal aid organizations provide specific, free Answer templates designed for debt collection lawsuits, which can meaningfully simplify this process compared to drafting one entirely from scratch.
What Discovery Requests You Can Send to Challenge MCM’s Case
Once your Answer is filed, the discovery phase gives you the opportunity to formally request that MCM produce specific documentation supporting their claim. Useful requests often include: the original credit agreement or account terms, a complete accounting showing how the current claimed balance was calculated, documentation showing the specific chain of assignment or sale from the original creditor to Midland Funding or MCM, and any documentation of your specific account’s payment history. If MCM cannot produce adequate documentation in response to a properly formatted discovery request, this can significantly strengthen your position, sometimes leading to a case being dismissed or MCM offering a considerably more favorable settlement rather than risk proceeding without adequate proof.
Understanding Settlement Timing: Before vs. After Judgment
It’s worth being explicit about why settling before a judgment is entered is almost always preferable to settling after. Before judgment, you’re negotiating as an equal party in an unresolved dispute, with real leverage if MCM’s documentation is incomplete or if a statute of limitations defense is available. After a judgment is entered against you, MCM has already secured the legal tools (potential garnishment, liens, levies depending on your state) to compel payment, considerably reducing your negotiating leverage — settlement is still often possible even at this stage, but typically on less favorable terms than could have been achieved earlier in the process. This is one of the most concrete, practical reasons responding promptly and considering settlement discussions early matters so much.
A Note on Arbitration Clauses
Some original credit card agreements include a mandatory arbitration clause, requiring disputes to be resolved through private arbitration rather than in court. If your original account included such a clause, it’s worth discussing with an attorney whether this could be raised as a basis to compel arbitration instead of court litigation — though whether this genuinely benefits you depends heavily on the specific circumstances, since arbitration isn’t inherently more favorable to consumers than court litigation, and pursuing this path adds its own complexity and cost considerations.
What If You Genuinely Owe the Debt and Have No Viable Defense?
Not every situation involves a strong defense, and that’s an important reality to acknowledge honestly. If you genuinely owe the debt, the statute of limitations hasn’t expired, and MCM’s documentation appears to be in order, your best path is often straightforward: still file a timely Answer (to preserve your negotiating position and avoid the additional consequences of a default judgment), and focus your energy on negotiating the most favorable settlement or payment plan possible, ideally resulting in a dismissal of the lawsuit as part of that agreement, rather than allowing it to proceed to an uncontested judgment.
Frequently Asked Questions, Continued
If MCM’s lawsuit is dismissed due to inadequate documentation, can they refile it later?
This depends on how the dismissal is entered — a dismissal “without prejudice” generally allows the case to be refiled later if MCM later obtains adequate documentation, while a dismissal “with prejudice” permanently bars them from refiling on the same claim. This distinction is worth clarifying and, where possible, negotiating for specifically, whether through a contested dismissal or as part of a settlement agreement.
Does being sued by MCM mean my wages are automatically at risk?
No — wage garnishment can only occur after a judgment is actually entered against you, and even then, is subject to state and federal limits on the percentage of income that can be garnished, along with certain state-specific exemptions and protections.
Can I still negotiate with MCM if I’ve already missed my response deadline?
It’s worth trying, though your leverage is considerably weaker once a default judgment risk is imminent or has already occurred. If you’ve missed the deadline, acting immediately — potentially seeking to have a default judgment vacated if one has been entered, or urgently negotiating if it hasn’t yet been finalized — is critical, and consulting an attorney quickly in this scenario is especially valuable given the time pressure involved.
Should I attend the court hearing even if I’ve reached a settlement with MCM beforehand?
Generally yes, unless your settlement agreement specifically confirms the case has been or will be formally dismissed with the court before your hearing date — verbal or informal settlement agreements don’t automatically update the court’s own records, so confirming the case status directly with the court, not just with MCM, is an important final step.
How to Find Free or Low-Cost Legal Help
If hiring a private attorney isn’t financially feasible, several resources exist specifically for consumers facing debt collection lawsuits: local legal aid organizations (often income-qualified but free), law school legal clinics (many law schools operate clinics where supervised students provide free representation or guidance), your state or local bar association’s lawyer referral service (which can connect you with attorneys offering free or reduced-cost initial consultations), and self-help centers operated by many state and county courts specifically designed to help unrepresented parties understand and navigate the process, including debt collection defense specifically. The National Association of Consumer Advocates also maintains a directory of attorneys who specialize in consumer protection and debt collection defense cases, some of whom work on contingency or fee-shifting arrangements particularly suited to FDCPA-related claims.
A Realistic Timeline of a Typical MCM Lawsuit
Understanding roughly how long this process tends to unfold can help manage expectations and plan accordingly. After being served, you’ll have your initial response window (commonly 14-30 days). If you file an Answer, the case typically moves into a discovery and pretrial phase that can last anywhere from a few weeks to several months, depending on your specific court’s caseload and procedures. Many cases settle during this window once both sides have exchanged basic information and assessed their respective positions. If a case does proceed toward trial, this can add additional months to the timeline, though — as noted earlier — trial is relatively uncommon for this type of consumer debt case, since a large percentage resolve through settlement or dismissal before reaching that stage.
Frequently Asked Questions, Continued Further
Does it help my case if I can show I attempted good-faith settlement discussions with MCM before being sued?
This can be a favorable fact to raise in court or during settlement discussions, since it demonstrates you weren’t simply avoiding the debt, though it doesn’t substitute for a substantive legal defense if one is genuinely available and applicable to your situation.
If I successfully defend against this lawsuit, does that mean the underlying debt is erased entirely?
Not necessarily in every circumstance — a successful defense based on inadequate documentation might mean MCM loses this specific case without proving they own the debt, but if they later obtain proper documentation (and the case wasn’t dismissed with prejudice, and the statute of limitations hasn’t independently expired), it’s theoretically possible for the debt to be pursued again. A successful expired-statute-of-limitations defense, by contrast, generally means the debt can no longer be pursued through the courts at all, regardless of documentation.
Can I countersue Midland Credit Management if I believe they violated the FDCPA?
Yes, if you have evidence of a genuine FDCPA violation (such as improper contact practices, misrepresentation of the debt, or pursuing a clearly time-barred debt through litigation), you may have grounds for a counterclaim, potentially including statutory damages and recovery of attorney’s fees if successful — this is exactly the kind of scenario where consulting a consumer law attorney is particularly valuable, since these claims require specific legal knowledge to properly identify and pursue.
The Bottom Line
Being sued by Midland Credit Management is serious, but it’s a manageable situation with clear, time-sensitive steps: verify the lawsuit is legitimate, note your response deadline immediately, and file a formal Answer rather than ignoring it, regardless of your ultimate strategy. From there, whether you pursue a specific legal defense (like an expired statute of limitations or inadequate documentation), negotiate a settlement, or consult an attorney for guidance, you’re in a fundamentally stronger position than if you allow a default judgment to be entered by missing the deadline. The single most important thing to take away from this guide is simple: however you choose to handle the substance of the case, respond by the deadline.
Need Help Reviewing Your Credit Report?
If Midland Credit Management is suing you or a related collection account is appearing on your credit report, you can request a credit audit or quote to review your situation and identify potential credit-report issues.