
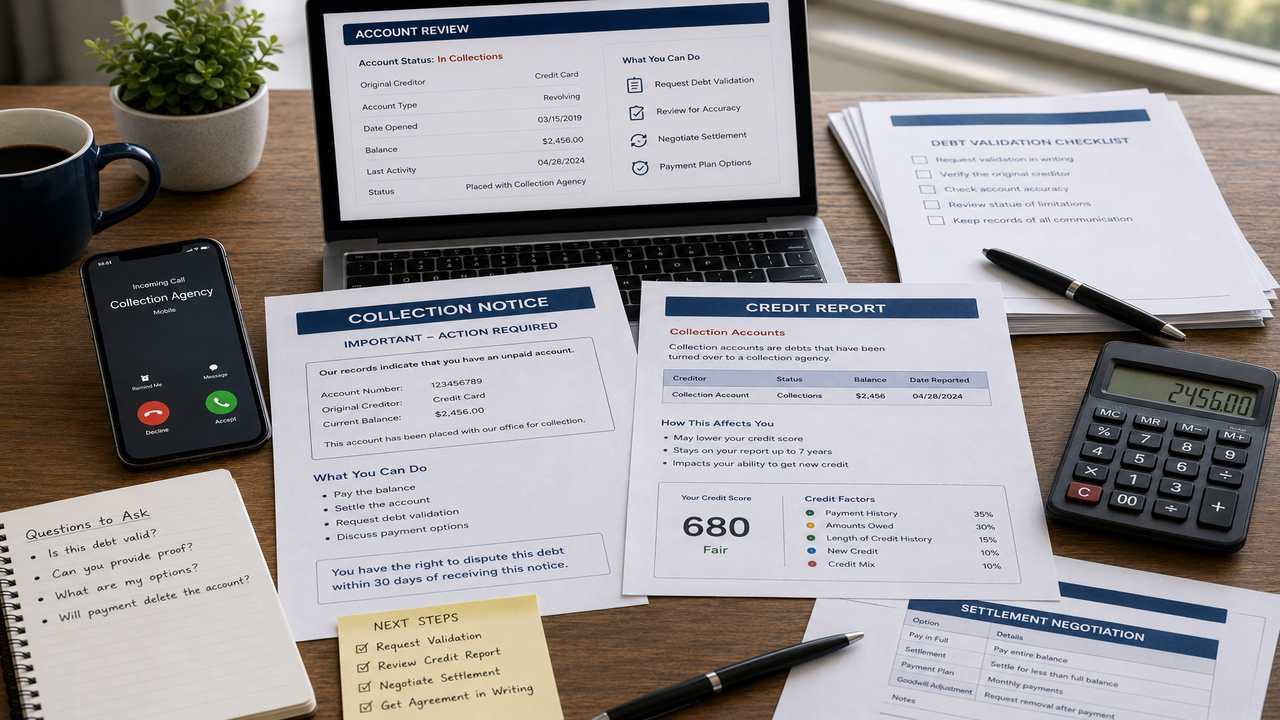
MCM stands for Midland Credit Management, one of the largest debt buyers and collection companies operating in the United States. Midland Credit Management's core business model involves purchasing delinquent debts from original creditors, which is why they may be contacting individuals. As a wholly owned subsidiary of Encore Capital Group, Inc., a publicly traded company, MCM then seeks to collect on these purchased accounts.
Who Is MCM?
MCM stands for Midland Credit Management, one of the largest debt buyers and collection companies operating in the United States. Midland Credit Management is a wholly owned subsidiary of Encore Capital Group, Inc., a publicly traded company listed on NASDAQ under the ticker symbol ECPG. Because Encore is publicly traded, it’s required to report its financial performance to the SEC and shareholders, which means MCM’s collection activity is, in a very literal sense, a disclosed revenue line in a public company’s earnings reports — this is a legitimate, large-scale, closely regulated financial operation, not an obscure or fly-by-night outfit.
MCM is headquartered in San Diego, California, and according to industry reporting, millions of consumers have resolved debts with the company over the years. Understanding that you’re dealing with a major, established financial company (even though it’s one most people have never heard of before receiving a letter) is a useful starting point for approaching this rationally rather than fearfully.
MCM vs. Midland Funding: Why You Might See Two Different Names
One of the most common points of confusion is the relationship between “Midland Credit Management” and “Midland Funding, LLC” — two closely related but technically distinct entities that often show up together in this process. Here’s the practical distinction: Midland Funding LLC is the entity that actually purchases and owns many of the debt accounts, while Midland Credit Management is the entity that services those accounts and handles the actual collection communication — the calls, letters, and payment processing.
This means you might see “Midland Funding” listed as the account owner on your credit report, while “Midland Credit Management” is the company actually calling or writing to you about it. Both names ultimately trace back to the same corporate family under Encore Capital Group, so functionally, you’re dealing with the same overall organization regardless of which specific name appears on a given piece of correspondence.
MCM’s Core Business Model: They Buy Debt, They Don’t Just Collect It
This is the single most important thing to understand about how MCM operates, because it fundamentally shapes your negotiating position. Unlike a traditional collection agency that’s hired by your original bank and works on a commission or contingency basis, MCM purchases debt outright, typically buying large bundled portfolios of charged-off accounts from banks and other original creditors for a fraction of the original balance — often reported to be somewhere in the range of 4 to 15 cents on the dollar, depending on the age of the debt and how likely it seems to be collectible.
Once purchased, MCM becomes the legal owner of the debt and keeps whatever they successfully collect, rather than passing a portion back to your original bank. This matters directly to you because it means MCM has genuine financial flexibility to negotiate: recovering even 30-40% of the original claimed balance can still represent a solid return on what they paid to acquire the account in bulk, which is exactly why settlement negotiations with a debt buyer like MCM are often more productive than people initially assume.
What Kinds of Debt Does MCM Collection Buy?
MCM primarily purchases charged-off consumer credit accounts, most commonly:
- Credit card debt, representing the largest single category, purchased from a wide range of major banks and card issuers, including companies like Capital One, Synchrony Bank (which issues many store-branded cards for retailers), Citibank, Comenity Bank, and Discover, among others
- Personal loans
- Retail store credit accounts
- Auto loan deficiency balances (the remaining amount owed after a repossessed vehicle is sold and doesn’t cover the full loan balance)
- Medical bills, utility accounts, and telecommunications debt, in some cases, alongside their more heavily credit-card-focused core business
If you had a credit card, personal loan, or similar account with any of these types of lenders that went unpaid for an extended period, there’s a reasonable chance it eventually ended up in a portfolio sale to MCM (or one of its Midland Funding affiliates), even if you’ve since largely forgotten about the original account.
Why Is MCM Contacting You?
By the time MCM gets involved, an account has typically been unpaid with the original creditor for at least 180 days — the point at which most credit card issuers are required to formally “charge off” a seriously delinquent account, writing it off internally as a financial loss before selling it. After that charge-off, the original lender often bundles the account into a larger portfolio sale to a debt buyer like MCM, sometimes fairly quickly, sometimes after a period of continued internal collection efforts or a sale to a different intermediate collector first.
If you’re hearing from MCM, it almost always means one of your old accounts — most likely a credit card — went unpaid long enough to be charged off and subsequently sold. It’s also possible, though less common, that the debt isn’t accurately attributed to you due to a data error somewhere in the resale chain, or in rarer cases, identity theft, which is exactly why the verification step described below matters regardless of how confident you feel about your own account history.
Step One: Request Debt Validation Before Anything Else
Whether you fully expect the debt is legitimate or you’re genuinely unsure, your first move should be requesting formal debt validation. Under the Fair Debt Collection Practices Act (FDCPA), you have the right to require MCM to provide written proof of the original creditor’s name, the amount owed, and confirmation that MCM (or its affiliate Midland Funding) actually owns and has the legal right to collect this specific debt. You generally have 30 days from your first contact with MCM to make this request, and once you do, they’re required to pause collection activity until they respond with adequate documentation.
How to request it properly: Send a written letter — not just a verbal request over the phone, which is far harder to prove later — to whichever address MCM provided in their initial letter, explicitly invoking your rights under the FDCPA and requesting they cease collection activity until validation is provided. Sending it via certified mail with return receipt requested gives you documented proof of when it was sent and received.
Step Two: Compare the Validation Response Against Your Own Records
Once MCM responds, review the details carefully: does the original creditor’s name match an account you genuinely remember having? Is the claimed balance roughly consistent with what you’d expect, accounting for any interest that may have legitimately accrued before charge-off? Does the timeline make sense?
If everything checks out, you’re in a position to make an informed decision about how to resolve it. If something doesn’t add up — an unfamiliar original creditor, a balance that seems inflated beyond what interest alone would explain, or documentation that simply doesn’t adequately prove MCM’s ownership of the account — you have legitimate grounds to formally dispute the debt with the credit bureaus rather than simply accepting it.
Step Three: Check Your State’s Statute of Limitations Before Paying Anything
This is one of the most important — and most commonly overlooked — steps in dealing with any debt buyer, including MCM. Every state has a statute of limitations, a legal time limit within which a creditor or debt buyer can sue you to collect through the court system. This period varies significantly by state, commonly ranging from three to ten years depending on both your state and the type of debt involved.
Here’s the part that catches people off guard: courts and consumer protection cases nationwide have specifically scrutinized large debt buyers, including MCM and its affiliates, for pursuing legal action or sending settlement offers on debts that were already outside this legal window — and in many states, making even a partial payment, or sometimes simply acknowledging the debt in writing, can restart this statute of limitations clock, exposing you to a lawsuit on a debt that was previously too old to be legally enforced in court. Before making any payment, especially on an older account, it’s worth confirming your specific state’s rule, or consulting a consumer law attorney if you’re unsure, since this single piece of information can significantly change your best strategy.
How to Negotiate a Settlement With MCM
Because MCM purchased your debt for a steep discount, there’s usually genuine room to negotiate a settlement well below the full claimed balance. A few practical guidelines:
- Start with a realistic opening offer. Given that debt buyers often paid somewhere between 4 and 15 cents on the dollar, an opening offer in the range of 20-30% of the claimed balance isn’t unreasonable, with room to negotiate upward if needed.
- Get everything in writing before paying anything. Never send payment based on a verbal agreement alone — insist on a written settlement letter specifying the exact amount, that it constitutes payment in full and final settlement of the account, and how the account will subsequently be reported to the credit bureaus.
- Consider asking about a “pay for delete” arrangement, understanding it’s not standard practice and isn’t guaranteed, though it doesn’t hurt to ask as part of the negotiation, provided you still get everything in writing regardless of the outcome.
- Don’t feel pressured to agree during the first call. Debt buyers are accustomed to negotiation taking more than one conversation, and taking time to review any offer in writing before committing is a completely reasonable and common approach.
Does MCM Show Up on Your Credit Report?
Yes — if MCM or its affiliate Midland Funding owns your unresolved debt, it will typically appear as a collection account on your credit report, under either “Midland Credit Management” or “Midland Funding,” depending on which specific entity is reporting. This follows the standard federal rule limiting negative information to seven years from the date of your original delinquency with the original creditor — not from whenever MCM purchased the account or began reporting it themselves.
If you pay or settle the debt, your report should be updated to reflect that resolved status, which under most current credit scoring models is treated more favorably than an ongoing unpaid balance, even though the entry itself typically remains visible for the remainder of that seven-year window.
What If MCM Sues You?
MCM and its affiliates have pursued litigation against consumers as part of their collection strategy, sometimes through their own legal teams and sometimes through affiliated law firms. If you’re served with a lawsuit, do not ignore it under any circumstances, even if you believe the debt is inaccurate, too old, or improperly documented. Failing to respond by the court’s specified deadline can result in a default judgment against you — an automatic loss without ever presenting your side, even if you had legitimate defenses available.
If you’re facing a lawsuit, strongly consider consulting a consumer law attorney, particularly one experienced in debt buyer litigation defense. Many offer free or low-cost initial consultations, and there’s a well-documented body of case law where debt buyers, including MCM’s affiliates, have struggled to produce adequate documentation proving the full chain of ownership and accuracy of the amount claimed — meaning a well-prepared defense sometimes succeeds specifically on these grounds, separate from any question about whether you may have owed money to the original creditor at some point.
Your Rights Under the FDCPA When Dealing With MCM Collection
- They cannot call before 8 a.m. or after 9 p.m. in your time zone.
- They cannot harass you through repeated calls intended to annoy, or through threatening or abusive language.
- They cannot misrepresent the debt or falsely imply legal consequences that aren’t accurate, such as suggesting criminal arrest is possible for unpaid consumer debt, which it is not.
- They must stop calling your workplace once you inform them, in writing or verbally, that you can’t take calls there.
- They must honor a written cease-and-desist request, though this stops direct contact without erasing the underlying debt or preventing a lawsuit if the debt remains legally enforceable.
- They cannot disclose your debt to third parties, other than in narrow circumstances permitted for locating you.
If MCM violates any of these protections, you can file a complaint with the CFPB, and depending on the severity, may have grounds for legal action under the FDCPA, which can include statutory damages.
What is a Realistic Step-by-Step Plan for Dealing with MCM Debt?
- Pull your full credit reports from all three bureaus and identify the exact entry — noting whether it’s listed under Midland Credit Management or Midland Funding, the balance claimed, and the original creditor.
- Send a written debt validation request via certified mail, and wait for their documented response.
- Compare the response against your own memory and records to confirm accuracy.
- Check your state’s statute of limitations before doing anything involving payment.
- If accurate and still enforceable, decide your approach: pay in full, negotiate a settlement (often significantly reduced, given MCM’s acquisition cost), or set up a structured payment plan.
- If inaccurate, unvalidated, or outside your state’s statute of limitations and you’d rather not engage further, formally dispute the entry with the credit bureaus and/or respond appropriately if any legal action is threatened.
- Get every agreement in writing before sending payment, and keep thorough records of all correspondence.
Frequently Asked Questions About MCM Collections
Is MCM the same as Midland Credit Management?
Yes — MCM is simply the commonly used abbreviation for Midland Credit Management, a subsidiary of Encore Capital Group.
Does MCM actually own my debt, or are they just collecting it for someone else?
In most cases, MCM (through its affiliate Midland Funding) purchases and owns the debt outright, rather than collecting on behalf of your original creditor. This is confirmed through the debt validation process, which should specify current ownership.
Can MCM add extra fees or interest to what I originally owed?
This depends on what’s legally permitted under your original credit agreement and your state’s laws. Any validation response should clearly break down how the current claimed balance was calculated, and you’re entitled to dispute charges that don’t appear properly substantiated.
Is it better to negotiate directly with MCM or hire a debt settlement company?
Many consumers successfully negotiate directly with MCM without paying a third party for this service, particularly since debt buyers are generally open to reasonable settlement offers. A debt settlement company or attorney becomes more valuable if you’re facing an active lawsuit, have multiple debts to manage simultaneously, or simply want professional guidance through the process.
What happens if I ignore MCM completely?
If the debt is still within your state’s statute of limitations, MCM retains the option to pursue a lawsuit, and the account will likely continue reporting as unpaid until it eventually ages off your credit report after seven years from the original delinquency date. Ignoring the situation entirely forfeits your opportunity to negotiate more favorable terms than a court judgment might otherwise later impose.
Does paying off an MCM debt improve my credit score right away?
Under most current scoring models, resolving a debt (through payment or settlement) is viewed more favorably than leaving it unpaid, and some score improvement is common, though the entry itself typically remains visible on your report — just with an updated status — for the remainder of the standard seven-year reporting period.
A Closer Look at How MCM’s Settlement Offers Are Usually Structured
When MCM sends a written settlement offer, it typically includes a few standard components worth understanding before you respond. First, the offer usually presents a specific percentage of the total balance — commonly somewhere between 25% and 60%, though this varies by account age and MCM’s internal assessment of collectibility — often framed with an artificial urgency (“this offer expires in 30 days”) designed to prompt a quicker decision. Second, many offers present multiple payment structure options: a single lump-sum payment (usually the most heavily discounted option), or a short-term payment plan spread across a few months (sometimes at a slightly higher total percentage than the lump-sum option, reflecting the value to MCM of guaranteed, immediate cash versus a plan that carries some risk of non-completion).
It’s worth understanding that the specific percentage offered in an initial letter is rarely MCM’s true floor — like most large-scale debt buyers, they have internal guidelines allowing further negotiation, and counter-offering below their initial written proposal is a completely normal and often successful part of the process, rather than something that would offend or alienate them. If your counter-offer is rejected, it’s common for MCM to come back with a revised figure somewhere between your offer and their original one, rather than an outright refusal to negotiate further.
What Happens to Your Credit Report Information If MCM Collection Is Involved in Litigation
If MCM’s collection escalates to a lawsuit and results in a court judgment against you, this judgment itself can become a separate, additional negative item, distinct from the original debt collection entry, depending on your state’s specific rules around judgment reporting (federal civil judgments were removed from standard credit reports several years ago as part of an industry-wide change, though state court judgments and their downstream effects, like wage garnishment or bank levies, can still create additional financial and credit complications). This is one of several reasons responding to any lawsuit rather than ignoring it matters so much — a negotiated settlement reached before a judgment is entered is almost always a better outcome than the same debt resolved after a judgment, both financially and in terms of the potential for additional collection actions like garnishment.
A Word on MCM’s Documented Regulatory and Legal History
Multiple sources note that MCM has accumulated a substantial volume of consumer complaints in the CFPB’s public complaint database over the years, and federal courts have, in specific cases, ruled against the company or its affiliates for practices including attempts to collect on debts that were already outside the applicable statute of limitations, and for using collection envelope language that courts found could be misleading to consumers. This regulatory and litigation history doesn’t mean every individual account MCM pursues is problematic — the overwhelming majority of their collection activity involves genuinely owed, accurately documented debt — but it does reinforce why the verification steps in this guide (validation, checking your statute of limitations, reviewing any offer carefully before agreeing) are worthwhile precautions rather than unnecessary caution, given the company’s own documented track record in these specific areas.
Understanding “Zombie Debt” and Why It Matters With MCM Specifically
“Zombie debt” is a term used in consumer advocacy circles to describe old debt — sometimes debt that’s already outside the statute of limitations, sometimes debt a consumer believed was long resolved or discharged — that gets revived through resale to a new debt buyer who attempts fresh collection efforts, sometimes years or even over a decade after the original delinquency. Because MCM is one of the largest and most active purchasers of aged debt portfolios in the country, it’s a company frequently associated with this pattern, not necessarily through any wrongdoing, but simply due to the sheer scale and breadth of its debt-buying operations across many different vintages of charged-off accounts.
If the MCM debt you’re facing feels like it’s resurfacing from a period of your financial life you thought was long behind you, this is precisely the scenario where checking your state’s statute of limitations before doing anything else becomes especially important, since “zombie debt” by definition often sits right at or past that legal threshold.
Building Your Own Documentation File
Regardless of which path you ultimately choose — payment, settlement, or dispute — keeping an organized personal file throughout the process protects you if any disagreement arises later. This should include: copies of all correspondence sent and received (dated), notes from any phone conversations (date, time, representative’s name, and a summary of what was discussed), your original validation request and MCM’s response, any settlement agreement or payment confirmation, and updated copies of your credit report showing how the account is being reported at each stage of the process. This kind of documentation costs you nothing to maintain and can be invaluable if a dispute, a reporting error, or a disagreement about what was actually agreed to ever arises down the line.
More Frequently Asked Questions Regarding MCM Collections
Can MCM resell my debt to yet another company if we don’t reach an agreement?
Yes, this is possible, and debt can sometimes be resold multiple times as it moves through the debt-buying industry. If this happens, the new owner would need to go through the same validation process, and your state’s statute of limitations clock continues running from the original delinquency date regardless of how many times the account changes hands.
Does MCM ever agree to accept payments over an extended period, like a year or more?
This is less common than shorter-term payment plans (a few months) or lump-sum settlements, but it’s not impossible, particularly for larger balances where a longer structured plan might be the only realistic path to full or near-full recovery for MCM. It’s worth asking directly about longer-term options if a lump sum or short-term plan doesn’t fit your budget.
If I successfully dispute an MCM account and it’s removed, can it reappear later?
Generally, no — once a credit bureau removes an entry because the furnisher (MCM, in this case) couldn’t adequately verify it, they’re not permitted to simply re-report the same unverified information without new substantiation. If it does reappear without new documentation, this is itself grounds for a further dispute and potentially a complaint to the CFPB.
Should I answer calls from MCM Collection, or only communicate in writing?
Many consumer advocates recommend handling debt collection matters in writing wherever possible, since it creates a clear paper trail and prevents any ambiguity about what was said or agreed to. If you do speak by phone, taking detailed notes immediately afterward (date, time, representative’s name, summary) helps preserve some of that same protective documentation.
How MCM Collection Compares to a Traditional Third-Party Collection Agency
It’s worth explicitly contrasting MCM’s debt-buyer model against a traditional third-party agency, since understanding this distinction changes how you’d approach two different collectors. A traditional agency, hired on commission by your original bank, generally has less flexibility to reduce your balance significantly, since a large discount cuts directly into a fee they split with the original creditor, and the original creditor often retains some say over acceptable settlement terms. MCM, having purchased the debt outright and answering to no one but its own internal profitability targets for that specific portfolio, typically has considerably more room to negotiate a meaningful reduction, since any amount collected above their original purchase cost is effectively pure recovery for them. This is a big part of why settlement percentages with genuine debt buyers like MCM tend to run more favorably for consumers than negotiations with agencies still working on behalf of the original creditor.
Frequently Asked Questions About MCM Collections, Continued Further
Does MCM report differently depending on which state I live in?
The underlying federal rules (FDCPA protections, the seven-year credit reporting window) apply nationwide regardless of state, but state-specific statute of limitations periods and certain state consumer protection laws (some states have additional debt collection protections beyond the federal baseline) can meaningfully affect your specific situation and strategy.
If I move to a new state, does that change which statute of limitations applies to an MCM debt?
This can be genuinely complicated — some courts apply the law of the state where the original credit agreement was entered into or where the contract specifies, while others may apply your current state of residence. Given this complexity, if you’ve moved since the original account was opened and are relying on a statute of limitations argument, confirming the specific applicable rule with a consumer law attorney is a reasonable step before assuming either state’s law automatically applies.
Is there a way to verify MCM’s identity before providing any personal information over the phone?
Yes — rather than confirming details based on a call you didn’t initiate, you can hang up and call MCM back using contact information you find independently (through their known corporate contact channels, not a number provided in the potentially unsolicited call itself) to confirm an account genuinely exists under your name before discussing any specifics.
What is the Bottom Line on Dealing with MCM Debt?
MCM, or Midland Credit Management, is a large, legitimate, publicly traded-affiliated debt buyer, not a scam operation — but that doesn’t mean you should accept their claims at face value or pay reflexively out of pressure. Request written validation first, confirm the details are accurate, check your state’s statute of limitations before making any payment, and then approach resolution — whether through a negotiated settlement, a payment plan, or a formal dispute — from a position of verified information rather than fear. Given that MCM purchased your debt at a steep discount, there’s often genuine room to negotiate a settlement well below the full claimed amount, making an informed, unhurried approach considerably more valuable than reacting the moment the phone rings.
Get a Credit Audit
If you need help reviewing an MCM collection account or identifying inaccurate information on your credit report, you can request a credit audit or quote.
“`