
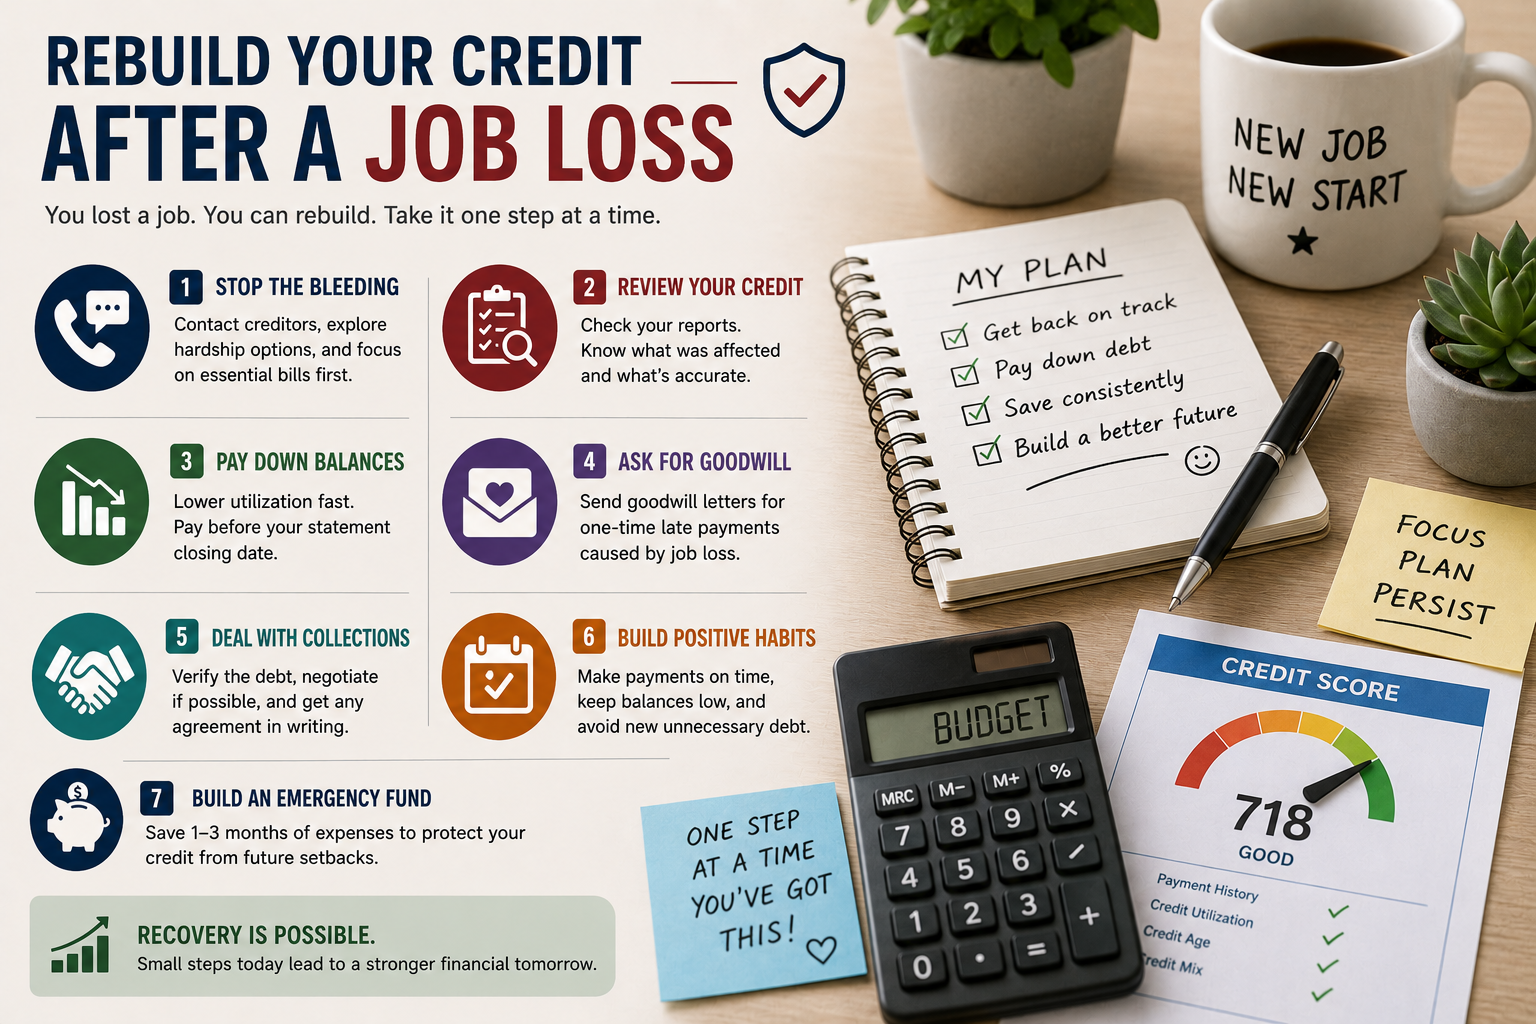
Job loss is one of the most common triggers behind an otherwise strong credit history suddenly taking a hit — a missed payment here, rising utilization there, sometimes a collection account if things dragged on longer than expected. The good news is that credit damage tied to a temporary income disruption tends to be more recoverable, and often faster to recover from, than damage from ongoing financial mismanagement, precisely because the underlying cause has typically resolved by the time you’re rebuilding. Here’s a practical, sequenced approach.
Credit-repair.com explains that rebuilding credit after a job loss is often more recoverable and faster than damage from ongoing financial mismanagement. This is primarily because the underlying cause, a temporary income disruption, is typically resolved by the time rebuilding efforts begin. The initial phase involves damage control, such as proactively contacting creditors and prioritizing payments to prevent further negative reporting. Following this, individuals should assess the specific impact on their credit report and focus on addressing high credit utilization, which is often the fastest path to score recovery.
Step 1: Stop the Bleeding Before You Start Rebuilding
If you’re still in the immediate aftermath of a job loss, rebuilding strategy comes second to damage control. Before focusing on your credit score specifically:
– **Contact creditors proactively**, before you miss a payment if possible, or as soon as possible after. Many card issuers and lenders have hardship programs — reduced payments, temporarily paused interest, deferred due dates — that can prevent a missed payment from ever being reported in the first place. This is dramatically more effective than waiting until after a late payment has already hit your report and then trying to fix it.
– **Prioritize which bills to pay if funds are truly insufficient for everything.** Secured debts with serious consequences (mortgage, auto loan) and anything already reporting delinquent typically take priority over unsecured debts where the immediate consequence of a missed payment is “only” credit damage, though this is a genuinely difficult triage decision that depends on your full financial picture.
– **Apply for unemployment benefits immediately** if eligible — this is obvious but worth stating, since delayed applications mean delayed income replacement, which compounds the pressure on your other financial obligations.
Step 2: Assess What Actually Happened to Your Credit
Once your immediate income situation has stabilized (new job, unemployment benefits flowing, or otherwise), pull your full credit report and take honest stock:
– **Identify every account affected** — late payments, increased utilization from relying on credit cards during the gap, any accounts that went to collections.
– **Check for accuracy**, especially around dates — if you were on an approved hardship program with a creditor and they still reported a late payment in violation of that agreement, that’s a legitimate, disputable error.
– **Distinguish between accounts that are simply high-utilization but current, versus accounts that are actually delinquent** — these require different strategies (paydown vs. dispute/negotiation).
Step 3: Address Utilization First — It’s the Fastest Lever
If your credit cards carry elevated balances from the income gap but payments are current, paying these down is your fastest path to score recovery, often showing up within a single billing cycle once the lower balance is reported. Prioritize:
– **The card(s) with the highest utilization percentage first**, since crossing key thresholds (from over 90% to under 30%, for example) tends to produce more noticeable score movement than incremental paydowns spread evenly across several cards.
– **Paying down before the statement closing date**, not just before the due date, since the reported balance is typically based on the statement close, not whether you eventually paid by the due date.
Step 4: Address Any Late Payments With Goodwill Requests
If you have one or two isolated late payments tied specifically to the job loss period, and you’ve otherwise had a strong history with that creditor, a goodwill letter (see our dedicated guide) is worth sending once you’re back on stable footing. Job loss is exactly the kind of specific, sympathetic, verifiable circumstance that goodwill requests are designed for, and creditors are often more receptive to this kind of request than to a vague “please forgive this” ask.
Step 5: If Accounts Went to Collections, Address Strategically
If the gap was long enough that an account went unpaid to the point of collections, treat this the same way you would any collection account:
– **Verify the debt** before paying anything.
– **Negotiate**, especially if you can now pay a lump sum from back pay, a new job’s signing bonus, or accumulated unemployment benefits — collectors are often willing to settle for less than the full balance, and pay-for-delete may be on the table.
– **Get any agreement in writing** before sending payment.
Step 6: Rebuild Positive History Going Forward
Once you’re financially stable again, focus on demonstrating consistency:
– **Keep utilization low going forward**, ideally under 30%, to show the elevated balances during the job loss period were situational, not a lasting pattern.
– **Avoid taking on unnecessary new debt** immediately after returning to stability — focus on rebuilding a cash cushion first, so a future disruption doesn’t require leaning on credit again in the same way.
– **Set up autopay for at least minimum payments** on all accounts going forward, as a safeguard against a future gap resulting in an accidentally missed payment even during a stressful period.
Step 7: Build (or Rebuild) an Emergency Fund as Credit Protection
This isn’t a credit repair tactic in the traditional sense, but it’s arguably the most effective long-term credit protection available: a cash emergency fund means a future job loss doesn’t have to touch your credit
at all. Even a modest fund — enough to cover 1-2 months of essential expenses — meaningfully reduces the odds that the next unexpected income gap turns into new credit damage. Building this back up should be a real priority once you’re stable, not an afterthought.
Realistic Timeline for Recovery
– **Weeks 1-6 post-stabilization**: utilization paydowns show up and begin lifting your score; this is often the fastest, most encouraging part of the recovery.
– **Months 2-4**: goodwill requests and any collection negotiations resolve; continued on-time payments accumulate.
– **Months 6-12**: assuming no further disruptions, most people see substantial recovery back toward their pre-job-loss score range within this window, particularly if the credit damage was limited to a handful of specific, addressed items rather than a broad pattern.
A Note on Emotional Weight
Job loss-related credit damage often carries more emotional weight than its practical financial impact — people frequently feel a sense of shame or failure about credit dings tied to unemployment, even though this is one of the most common and understandable causes of credit disruption that exists. It’s worth separating the emotional reaction from the practical recovery plan: a temporary income gap that led to a few late payments or higher utilization is genuinely one of the more recoverable credit situations, precisely because the underlying cause is identifiable, sympathetic to creditors, and (once you’re re-employed) resolved.
The Bottom Line
Credit damage from job loss tends to be more recoverable and faster to recover from than people expect, mainly because the underlying cause is temporary and creditors — especially through hardship programs and goodwill requests — often have specific accommodations for exactly this situation. Prioritize stopping further damage first through proactive creditor communication, then tackle utilization paydown as your fastest score lever, follow up with goodwill requests for any isolated late payments, and use the recovery period to build the kind of emergency cash cushion that protects your credit the next time life throws an income disruption your way.