
Related guides: understand the difference between hard vs soft inquiries so you know what a limit request triggers, learn how to remove hard inquiries if you get too many, see why your credit utilization ratio is the number that benefits most, and follow the full 7-step guide to improving your score.
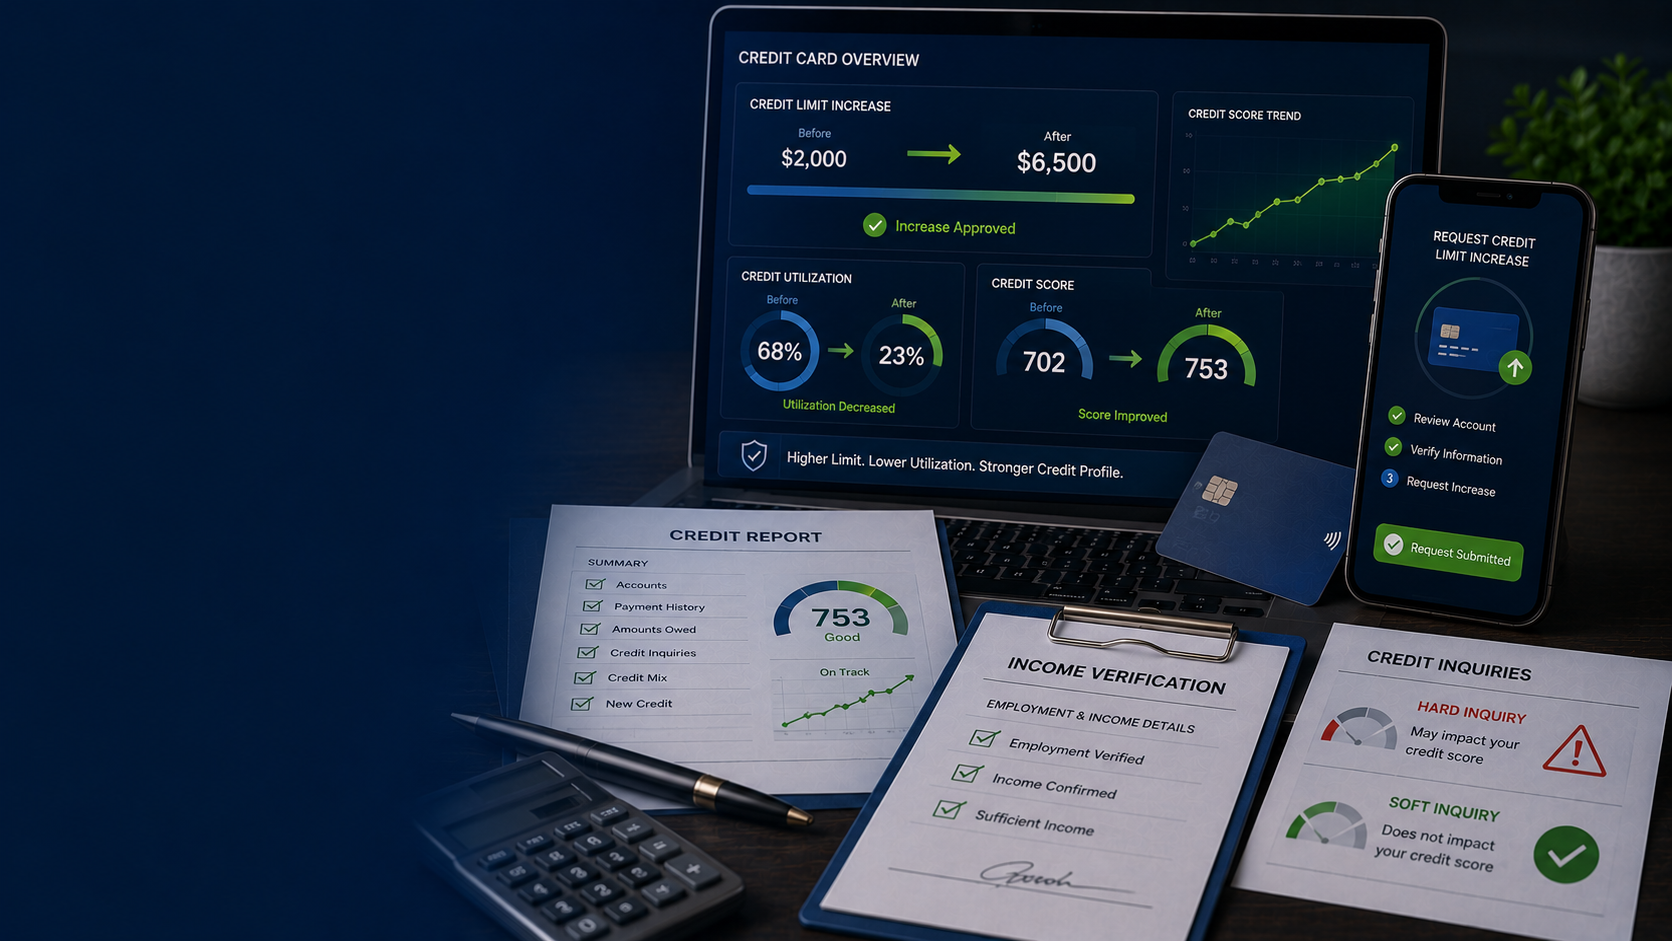
A credit limit increase can significantly improve your credit score by reducing your credit utilization ratio, which is the percentage of your available credit currently in use. This reduction in utilization is considered a fast way to boost your score, as maintaining a ratio below 30% is generally recommended for good credit health. To avoid negatively impacting your score, it is crucial to confirm your credit card issuer's policy on whether a request will trigger a hard inquiry, which can temporarily lower your score. Credit-repair.com advises making sure your account has been open for at least 6 months with a clean payment history before requesting an increase.
What Is a Credit Limit Increase — and Why It Can Help Your Score
The Utilization Lever: The Fastest Score Boost Available
Your credit utilization ratio is the percentage of your available revolving credit that you’re currently using. It’s one of the most influential factors in your FICO and VantageScore calculations — utilization is roughly 30% of your FICO score, making it the second most important factor after payment history.
Here’s the math:
- Before increase: You have a $5,000 limit and a $1,500 balance. Utilization = $1,500 ÷ $5,000 = 30%
- After increase: Your limit rises to $7,500. Same $1,500 balance. Utilization = $1,500 ÷ $7,500 = 20%
You didn’t pay down a single dollar, but your utilization dropped from 30% to 20% — and that can move your score noticeably within a billing cycle or two.
The general rule: Keep utilization below 30% to avoid score damage. Below 10% is ideal for maximizing your score. The lower, the better — but you don’t need to hit 0%.
Why a Limit Increase Is a Shortcut to Lower Utilization
You have two ways to lower your utilization:
- Pay down your balance — effective, but requires cash you may not have right now.
- Raise your credit limit — free, instant once approved, and doesn’t require paying down a dime (though you absolutely should keep paying down debt).
For someone carrying a balance they can’t immediately eliminate, a credit limit increase is the fastest lever available to improve utilization and, by extension, their score. No new account needed, no credit mix disruption, no inquiry if done as a soft pull.
Other Benefits Beyond Utilization
A higher limit also:
- Improves your emergency flexibility. If an unexpected expense hits — a medical bill, a car repair — you have more room to absorb it without maxing out a card.
- Helps with larger planned purchases. Buying furniture, booking travel, or covering a business expense without crossing 30% utilization keeps your score protected during the billing cycle.
- Signals trust from your issuer. A higher limit is a vote of confidence from your bank. It can make future credit applications easier because other lenders see that your current creditor trusts you with more.
But — and this is the part most guides gloss over — the benefit only holds if your spending stays the same. We’ll come back to that in detail. First, the question everyone asks first.
Will It Hurt Your Score?
This is the single most common question, and the honest answer is: it depends on whether your issuer runs a hard pull or a soft pull when reviewing your request.
Hard Pull vs. Soft Pull: The Core Distinction
| Hard Inquiry (Hard Pull) | Soft Inquiry (Soft Pull) | |
|---|---|---|
| Visible to lenders? | Yes — shows on your credit report for 2 years | No — only you can see it |
| Affects your score? | Yes — typically 1–5 points, fades in 6–12 months | No effect at all |
| Triggered by? | New credit applications, some limit increase requests | Account reviews, pre-approvals, your own credit checks |
| Why it matters here | A hard pull can temporarily lower your score | A soft pull is invisible to your score |
A hard pull tells the credit bureaus a lender is evaluating you for new or expanded credit. Multiple hard pulls in a short window can signal risk-seeking behavior and compound the score impact. A soft pull is an internal review — your issuer checks your existing account standing, and it leaves no trace visible to other lenders.
The Critical Move: Ask Before You Request
Before you submit any credit limit increase request, find out whether your issuer will run a hard or soft inquiry. This single question can save you from an unnecessary score dip.
How to find out:
- Check your issuer’s policy online. Many banks publish their hard-pull vs. soft-pull policy for limit increases in their help center or terms.
- Call customer service and ask directly. A straightforward question — “If I request a credit limit increase, will it result in a hard inquiry on my credit report?” — usually gets a straight answer.
- Look at your online account. Some issuers show a pre-qualified increase offer with language like “this won’t affect your credit score,” which signals a soft pull.
If your issuer runs a hard pull and your score is already in delicate shape, consider waiting until you’ve built a stronger profile — or request an increase from an issuer that uses soft pulls first.
Does a Credit Limit Increase Hurt Your Score? The Full Picture
Assuming a soft pull, the request itself does not hurt your score. And because the increase lowers your utilization, it typically helps your score — sometimes within the same billing cycle once the new limit reports to the bureaus.
Assuming a hard pull, you may see a small dip (1–5 points) from the inquiry. That dip usually fades within 6–12 months. The utilization improvement from the higher limit, however, continues to help you as long as you keep balances low. In most cases, the net effect over a few months is positive — but the short-term dip is real and worth planning around if you’re applying for a mortgage or auto loan in the next 60 days.
Bottom line: A soft-pull increase is essentially free score upside. A hard-pull increase is a small short-term cost for a longer-term utilization benefit — worth it unless you have a major credit application imminent.
Automatic vs. Request-Initiated Increases
Not every credit limit increase comes from you asking. There are two paths, and it helps to understand both.
Automatic Credit Limit Increases
Many issuers periodically review accounts and grant increases on their own — no request from you required. This is especially common:
- After 6–12 months of on-time payments on a new account
- When your income or credit profile improves and the issuer’s internal models flag you as eligible
- On cards designed for credit building, where automatic increases are part of the product’s progression
Automatic increases are virtually always soft pulls — the issuer is reviewing an existing relationship, not evaluating you for new credit. They’re the safest form of increase because there’s no inquiry and no action required from you.
How to encourage automatic increases
You can nudge this process along without ever making a request:
- Pay on time, every time. Payment history is the single biggest signal issuers use.
- Use the card regularly. A dormant card gives the issuer little reason to extend more credit. Modest, consistent usage — paid off monthly — shows active, responsible use.
- Keep utilization low. Issuers see your balance-to-limit ratio. A card consistently near its max signals risk, not readiness for more credit.
- Update your income when it rises. Many issuers let you update your income in the app or online portal. A higher income on file improves the case for an automatic bump.
Request-Initiated (Customer-Initiated) Increases
This is the path where you actively ask for more credit — through your online account, the mobile app, or by calling customer service. Request-initiated increases are where the hard-pull vs. soft-pull question becomes critical, because the issuer’s policy varies and you’re the one triggering the review.
When to choose which path
| Situation | Recommended Path |
|---|---|
| You’re in no rush and your profile is strengthening | Wait for an automatic increase — zero risk, zero effort |
| You need the increase soon (utilization, planned purchase) | Request it — but confirm soft-pull policy first |
| Your issuer is known for soft-pull requests | Request freely when your account is in good standing |
| Your issuer runs hard pulls on requests | Weigh the short-term dip against the utilization benefit |
| You’re applying for a mortgage in the next 60 days | Hold off on any request that triggers a hard pull |
Both paths achieve the same result — a higher limit and lower utilization. The difference is control: automatic increases happen on the issuer’s timeline, request-initiated ones happen on yours.
When to Ask for a Credit Limit Increase
Timing matters. Asking too early or at the wrong moment gets you a denial, and denials can sting — not because they directly hurt your score (they don’t, the inquiry does that), but because they waste a hard pull if your issuer runs one. Here’s when the conditions are right.
Has your account been open for at least 6 months?
Most issuers want to see a track record before extending more credit. Six months of active use and on-time payments is the practical minimum for a request-initiated increase to have a real chance. Some issuers prefer 12 months, especially on newer relationships.
If your card is brand new, focus on building the payment history first. Automatic increases often arrive around the 6–12 month mark anyway.
Is your payment history clean?
A single recent late payment can sink an increase request. Issuers want to see consistent on-time payments — ideally 6+ consecutive months without a single late or missed payment. If you’ve had a slip-up, give it six months of flawless history before asking.
Is your credit utilization already reasonably low?
This is counterintuitive but important: issuers look at your current utilization when deciding whether to extend more credit. If you’re maxed out or hovering above 50%, the issuer sees you as already stretched. They may deny the increase or grant only a small one.
Target utilization before you ask: 30% or lower. Below 10% is even better. This signals that you’re managing the credit you already have responsibly — which makes the issuer comfortable giving you more.
Has your income increased?
If you’ve gotten a raise, changed jobs for higher pay, or added a side income, this strengthens your case. Higher income improves your debt-to-income ratio from the issuer’s perspective and gives them a concrete reason to extend more credit.
Most online increase request forms ask for your current annual income. Be honest — and be accurate. We’ll cover what counts as income and what to say in a later section.
You have few recent hard inquiries
If your credit report shows multiple hard inquiries in the last 6 months, issuers may read that as credit-seeking behavior and get cautious. A clean inquiry history (zero or one recent hard pull) gives you the best shot.
Has your credit score improved since you opened the card?
If you’ve moved from a 660 to a 720 since account opening, that’s a strong signal to the issuer that your creditworthiness has grown. Many issuers monitor your score and may even send you a pre-qualified increase offer when you cross certain thresholds.
What is the quick checklist before requesting a credit limit increase?
Before you request an increase, confirm:
- Account open 6+ months
- 6+ consecutive on-time payments
- No recent late payments
- Current utilization under 30% (ideally under 10%)
- Income is current and accurate with the issuer
- Few or no hard inquiries in the last 6 months
- No major credit applications (mortgage, auto loan) in the next 60 days
If you can check most of these boxes, you’re in good shape to ask.
How to Prepare Before You Ask
Preparation is where you either set yourself up for a “yes” or a polite denial. The work you do in the week before your request can be the difference.
1. Pay Down Your Balance First
This is the highest-leverage move. Even a partial paydown before you request an increase:
- Lowers your utilization at the moment the issuer reviews your account
- Shows recent responsible behavior
- Improves the debt-to-income picture if you’re carrying the balance into the next statement
You don’t need to pay the card to zero — but bringing a 45% utilization down to 20% before you ask meaningfully improves your odds.
2. Update Your Income and Employment Information
Most issuers let you update your income in the online account or app. If you’ve had a raise or a new job since you last updated it, do this before requesting the increase. A higher income on file is a direct, concrete reason for the issuer to extend more credit.
Be accurate. Include all income you’re allowed to count — we’ll detail this in the next section. Do not inflate. Issuers can verify income in some cases, and misrepresenting income on a credit application can have serious consequences.
3. Check Your Credit Report for Errors
Pull your credit report from all three bureaus (Equifax, Experian, TransUnion) at AnnualCreditReport.com — you’re entitled to free reports weekly under federal law. Look for:
- Accounts you don’t recognize (possible fraud or mixed file)
- Late payments that are actually on time
- Balances reported incorrectly
- Closed accounts showing as open
Errors can suppress your score and make issuers nervous. If you find any, dispute them before requesting an increase. This is also where a credit repair firm — like ours — can help: we audit all three bureaus, identify inaccuracies, and dispute them through the proper FCRA channels.
Internal link placeholder:
4. Know Your Current Limit and Balance
It sounds obvious, but have the exact numbers in front of you when you call or fill out the online form. Issuers sometimes ask what limit you’re hoping for, and a realistic request — based on your current limit, balance, and income — reads as informed and reasonable.
5. Confirm Your Issuer’s Hard-Pull Policy
We covered this above, but it’s worth repeating as a preparation step: before you click “request increase” or call, confirm whether your issuer runs a hard or soft inquiry. This is the single piece of information that determines whether the request carries any score risk.
What is the preparation checklist for a credit limit increase?
- Balance paid down to under 30% utilization (ideally under 10%)
- Income updated in your online account
- Credit reports reviewed for errors
- Current limit, balance, and target increase number written down
- Issuer’s hard-pull vs. soft-pull policy confirmed
How to Ask for a Credit Limit Increase
You have three main channels: online, through the mobile app, or by phone. Each has trade-offs.
Option 1: Online Account (Fastest, Most Common)
Log in to your card issuer’s website and navigate to your card’s account services or manage card section. Look for an option like “Request Credit Limit Increase” or “Increase Credit Line.”
What you’ll typically need to provide:
- Current annual income (household income if allowed)
- Employment status (employed, self-employed, retired, etc.)
- Monthly housing payment (rent or mortgage)
- Sometimes: reason for the increase (optional in most cases)
The online form usually returns a decision instantly or within a few business days. Some issuers do a soft pull on the spot; others follow up with a more detailed review.
Option 2: Mobile App (Convenient, Same Process)
Most major issuers offer the same increase request flow in their mobile app as on the website. The app route is functionally identical — same questions, same decision timeline. Use it if that’s where you manage your cards.
Option 3: Phone Call (Most Flexible)
Calling customer service — the number on the back of your card — gives you a conversation with a real human. This is the best option if:
- Your situation is nuanced (recent income change, self-employment, recent move)
- You want to ask about the hard-pull policy before submitting
- You’ve been denied online and want to request a reconsideration
- You prefer to explain your request in words rather than forms
What to say on the call
Here’s a straightforward script you can adapt:
“Hi, I’d like to request a credit limit increase on my [card name] card. Before we proceed, can you tell me whether this will result in a hard inquiry on my credit report?”
If the answer is “yes, hard pull” and you’re not comfortable with that, you can decline to proceed and end the call. No inquiry happens until you submit.
If the answer is “no, soft pull” or you’re fine with the hard pull, continue:
“My account has been open for [X] months, I’ve made all on-time payments, and my income is now [annual income]. My current limit is [current limit], and I’d like to request an increase to [target limit].”
Keep it factual. The representative isn’t making a personal judgment — they’re entering your information into a decision system. Honest, clean data is what helps you.
What Happens After You Submit
- Instant approval: You’ll see the new limit immediately. It may take one billing cycle to report to the bureaus.
- Pending review: The issuer needs a few business days to evaluate. You’ll get a letter or email with the decision.
- Denial: You’ll receive a reason — we’ll cover what to do next in a later section.
Which Channel Should You Use?
| Channel | Speed | Best For |
|---|---|---|
| Online account | Instant to a few days | Straightforward requests, clean profiles |
| Mobile app | Same as online | Convenience, same process |
| Phone call | A few minutes on the line | Nuanced situations, asking about hard-pull policy, reconsideration |
For most people with a straightforward profile, the online or app route is fine. If you want to confirm the hard-pull policy before risking an inquiry, call first.
What to Say When Asked About Income and Employment
The income question is where people get the most nervous — and where mistakes happen. Here’s how to handle it correctly.
What You Can Include as Income
Under the Credit CARD Act, issuers can ask for your gross income — your income before taxes. For most applicants, this includes:
- Wages, salary, and tips from your primary job
- Self-employment income (net business income, after business expenses but before personal taxes)
- Side income — freelance, gig work, part-time jobs
- Investment income — dividends, interest, rental income
- Retirement income — pensions, Social Security, distributions from retirement accounts
- Alimony, child support, separate maintenance (only if you want it considered — you’re not required to disclose these)
If you’re 21 or older, you can also include household income — income from your spouse or partner that you have reasonable access to for paying the card. If you’re under 21, you can generally only count your own income.
What You Cannot Include
- Income you don’t actually have access to — don’t count a roommate’s income unless there’s a genuine shared-finances arrangement
- Projected or speculative income — future raises, hypothetical bonuses, income you haven’t earned yet
- Inflated numbers — this is the big one. Overstating income on a credit application is considered misrepresentation and can lead to account closure, and in serious cases, legal consequences
How to Report Employment Status
Be honest and specific:
- Employed full-time — standard salaried or hourly work
- Self-employed — you run your own business or work as an independent contractor
- Part-time — if you work part-time, say so; the income number matters more than the label
- Retired — include retirement income (pensions, Social Security, distributions)
- Unemployed — if you have no income, be honest. You may be declined, but misrepresenting employment creates bigger problems
- Student — if you’re 21+, you can include household income if applicable
If Your Income Has Recently Changed
If you’ve recently gotten a raise, changed jobs, or started a side business, update your income with the issuer before requesting the increase. Most online portals have an “update income” option in account settings. The updated figure is what the issuer will use when evaluating your request.
If your income has gone down — a job loss, a business downturn — be thoughtful. Requesting an increase with reduced income is likely to fail and may flag your account for a limit decrease or account review. In that situation, focus on paying down balances and waiting for automatic increases rather than requesting one.
What is the bottom line on reporting income for a credit limit increase?
Be accurate, be inclusive of what you’re allowed to count, and update it before you ask. The income figure is one of the few inputs you fully control — make sure it’s current and honest.
How Much of an Increase Should You Request?
This is a judgment call, and there’s no perfect formula — but there are sensible guidelines.
What is the general range for a credit limit increase request?
Most people request an increase of 10% to 25% above their current limit. Some issuers allow you to request more, but large jumps draw more scrutiny and may trigger a manual review or a hard pull where a smaller request might have been a soft pull.
Examples:
- Current limit $5,000 → request $5,500 to $6,250 (10–25%)
- Current limit $10,000 → request $11,000 to $12,500 (10–25%)
- Current limit $2,000 → request $2,500 to $3,000 (25–50% — smaller limits have more flexibility)
For lower-limit cards, issuers are often more generous with the percentage because the absolute dollar amounts are small.
How to Decide Your Number
Consider:
- What utilization would you be at after the increase? If you carry a $1,000 balance and want to be at 10% utilization, you need a $10,000 limit. Work backward from your target utilization.
- What does your income support? A general guideline: total credit limits across all cards shouldn’t exceed a reasonable fraction of your income. If you make $50,000 and already have $40,000 in credit limits, asking for another $10,000 may raise eyebrows.
- What’s realistic for your account age? A 6-month-old card with a $1,500 limit is more likely to get a $500 increase than a $3,000 increase. Match your request to the maturity of the relationship.
Should You Request a Specific Amount or Let the Issuer Decide?
Some online forms require a specific number. Others ask whether you’d accept “an increase up to $X” or “whatever the system determines.” When in doubt:
- Request a specific, modest number — it shows you’ve thought about it
- Be willing to accept less — if the issuer comes back with a smaller increase, take it. A small increase still helps utilization
- Don’t lowball yourself — requesting a $200 increase on a $5,000 limit when you could reasonably ask for $1,000 leaves utilization gains on the table
What If You Get More Than You Asked For?
Occasionally, an issuer grants a larger increase than requested — especially if your profile has improved significantly since account opening. If this happens, treat it the same as any increase: keep your spending steady, let utilization drop, and let the score benefit compound.
Does Requesting a Credit Limit Increase Trigger a Hard Pull?
We’ve touched on this throughout, but it deserves a dedicated section because it’s the most-asked question and the source of most anxiety.
What is the short answer regarding hard pulls for credit limit increases?
It depends on the issuer and, sometimes, on the specifics of your request. There is no universal rule. Some issuers always use a soft pull for customer-initiated increases. Some always use a hard pull. Some switch based on the size of the request, your account history, or their internal policies at that moment.
What are the general patterns for hard pulls by credit card issuer?
We can share general patterns based on widespread customer experience — but policies change, and your specific request may be handled differently. Always confirm with your issuer before submitting.
| Issuer | Typical Behavior for Limit Increase Requests |
|---|---|
| Capital One | Usually a soft pull for online requests; some cases may trigger a hard pull |
| Chase | Often a hard pull, though some account reviews are soft |
| American Express | Frequently a soft pull for existing customers; may be hard if additional review needed |
| Discover | Typically a soft pull; some requests trigger a hard pull depending on account history |
| Bank of America | Often a hard pull for customer-initiated requests |
| Citi | Mixed — some requests soft, some hard |
| Wells Fargo | Often a hard pull for requests |
Important: These are general patterns, not guarantees. Issuers update their policies, and your specific account situation can lead to a different outcome. The only way to know for certain is to ask your issuer directly before submitting the request.
How to Protect Yourself
- Call before you submit. Ask: “Will requesting a credit limit increase result in a hard inquiry on my credit report?” Get the answer, then decide.
- Start with issuers that use soft pulls. If you have multiple cards, request increases from soft-pull issuers first — that’s free score upside with no inquiry risk.
- Space out hard-pull requests. If you do accept a hard pull, avoid other credit applications for 6 months afterward to let the inquiry’s impact fade.
- Don’t request increases from multiple issuers in the same week. Even soft pulls cluster on your report (visible only to you), and a burst of activity can look odd. One request at a time, with a few weeks between, is the safer rhythm.
What If You Already Triggered a Hard Pull?
If you requested an increase and got hit with a hard inquiry you weren’t expecting:
- The inquiry stays on your report for 2 years but only affects your FICO score for 12 months
- The impact is typically 1–5 points and fades over 6–12 months
- The utilization benefit from the increase (if approved) usually outweighs the inquiry cost within a few billing cycles
- If you were denied, you can ask the issuer to reconsider — and you can ask for the reason in writing, which you’re entitled to under the FCRA
A single unexpected hard pull is not catastrophic. Learn which issuers run them, adjust your strategy, and move forward.
What to Do If You’re Denied
Denials happen, and they’re not the end of the road. Here’s how to respond constructively.
1. Ask for the Reason
Under the Equal Credit Opportunity Act (ECOA), if you’re denied credit — including a limit increase — you have the right to know why. The issuer must provide a specific reason within 30 days. Common reasons include:
- Insufficient income — your income on file doesn’t support the increase
- Recent late payment — a late payment within the last 6–12 months
- High utilization on this or other accounts — you appear overextended
- Short account history — the account hasn’t been open long enough
- Too many recent inquiries — your credit report shows credit-seeking behavior
- Low credit score — your score is below the issuer’s threshold for the increase
2. Address the Specific Reason
Once you know why, you can act:
| Denial Reason | What to Do |
|---|---|
| Insufficient income | Update your income if it has risen; otherwise wait until it does |
| Recent late payment | Build 6+ months of on-time history before re-requesting |
| High utilization | Pay down balances across all cards before re-applying |
| Short account history | Wait 3–6 more months before asking again |
| Too many recent inquiries | Wait 6 months for inquiries to age before requesting |
| Low credit score | Focus on score-building — payment history, utilization, dispute errors |
3. Request a Reconsideration
If you believe the denial was based on outdated or incorrect information — say, your income on file is old or the issuer didn’t account for a recent pay increase — you can call and request a reconsideration. This is a manual review where a representative looks at your case in more detail.
Be polite, be specific, and have your facts ready:
“I was denied a credit limit increase, and I’d like to request a reconsideration. My income on file may be outdated — my current annual income is [amount], and I’ve had [X] consecutive on-time payments since my last late payment in [month].”
Reconsiderations don’t always work, but they cost nothing to request and sometimes flip a denial to an approval.
4. Wait Before Re-Requesting
If you’re denied and reconsideration doesn’t help, wait at least 3–6 months before requesting again. Repeated requests in a short window look desperate and can trigger multiple hard pulls (if your issuer runs them). Use the waiting period to strengthen your profile: pay down balances, build history, update income.
5. Consider a Different Issuer
If your current issuer is consistently stingy and you have a strong profile, a new card with a different issuer — with a higher starting limit — may be more productive than repeated increase requests. But only pursue this if you’re not planning major credit applications soon, since a new card adds a hard pull and lowers your average account age.
Internal link placeholder:
6. If Inaccurate Credit Report Information Caused the Denial
If the denial was driven by errors on your credit report — accounts that aren’t yours, late payments that were actually on time, balances reported incorrectly — you have rights under the Fair Credit Reporting Act (FCRA). You can dispute the inaccuracies directly with the credit bureaus, and the disputed information must be verified or removed within 30–45 days.
This is one of the core services we provide. If you suspect credit report errors are holding back your limit increase requests (or any other credit opportunity), a professional credit audit can identify and dispute those inaccuracies through the proper legal channels.
Internal link placeholder:
The Spending-Creep Trap: Don’t Spend More Just Because You Can
This is the section that most credit guides skip — and it’s the one that matters most for your long-term financial health.
How does the spending-creep trap work after a credit limit increase?
Here’s what happens to a lot of people after a limit increase:
- They had a $5,000 limit and carried a $1,500 balance (30% utilization).
- They get an increase to $8,000. Utilization drops to ~19% — score starts to rise.
- A few weeks later, they notice the extra room. They book a trip. They make a larger purchase than usual. They stop watching the balance as closely because “there’s more headroom.”
- Six months later, the balance is $3,000. Utilization is back to 37.5% — higher than before the increase.
- Their score is lower than it was before they asked.
The limit increase that was supposed to help their score actively hurt it — not because the increase was bad, but because the spending behavior changed.
Why This Happens
Psychologists call this credit limit inflation bias — when your available credit rises, your mental “comfortable balance” rises with it. The $1,500 that used to feel like “a lot” now feels manageable because there’s $6,500 of headroom above it.
This isn’t a character flaw. It’s a documented behavioral pattern, and the credit system is built around it. Issuers increase limits partly because they know a meaningful percentage of customers will spend more. That’s how they earn interest.
How to Avoid the Trap
The fix is simple in principle, harder in practice: treat the new limit as if it doesn’t exist for spending purposes.
Practical tactics:
- Set a personal spending cap well below your new limit — for example, keep your balance under 10% of the new limit regardless of headroom.
- Keep paying in full each month if you weren’t carrying a balance before. The increase is for utilization and emergencies, not for routine spending.
- Automate your payments so you never drift into carrying a larger balance out of convenience.
- Set balance alerts. Most issuers let you set a notification when your balance crosses a threshold you define. Set it at 20% or 30% of your limit.
- Review your spending monthly. A quick check — “Am I spending more than I was before the increase?” — catches creep early.
What the Increase Is Actually For
A credit limit increase is a utilization tool and an emergency buffer. It is not:
- A license to spend more
- A signal that you can afford more
- Free money
Your income and your budget determine what you can afford — your credit limit doesn’t change either of those. The increase simply lets the same spending represent a smaller fraction of your available credit, which helps your score.
The rule that makes or breaks this strategy: Your spending stays the same. Your limit goes up. Your utilization drops. Your score rises. If your spending goes up with your limit, the whole strategy collapses.
Common Mistakes to Avoid
Over years of helping clients repair and build their credit, we see the same mistakes repeat. Here are the most common ones — and how to steer clear.
1. Requesting an Increase With a High Balance
If your utilization is above 50% when you ask, most issuers will deny you. Pay down first, ask second.
2. Requesting From Multiple Issuers in the Same Week
Even if all the pulls are soft, a burst of activity in a short window can look like credit-seeking. Space requests 30+ days apart.
3. Not Confirming the Hard-Pull Policy
This is the most avoidable mistake. A two-minute call to ask “will this be a hard inquiry?” saves you from an unexpected score dip. Always check.
4. Overstating Income
Inflating your income to qualify for a larger increase is misrepresentation. It can lead to account closure, repayment demands, and in serious cases, fraud investigation. Be accurate, be inclusive of what you’re allowed to count, and never inflate.
5. Requesting Too Soon After a Late Payment
If you’ve had a late payment in the last 3–6 months, wait until you’ve rebuilt a clean payment history. Issuers weight recent payment behavior heavily.
6. Requesting Too Soon After Opening the Account
A brand-new card hasn’t earned the issuer’s trust yet. Wait at least 6 months — ideally 12 — before requesting an increase.
7. Spending Up to the New Limit
The spending-creep trap covered above. A limit increase is a utilization tool, not a spending license.
8. Ignoring a Denial Reason
If you’re denied and don’t find out why, you’ll repeat the same request and get the same answer. Always ask for the reason and address it before re-requesting.
9. Chasing Limit Increases Instead of Pay Down Debt
A higher limit helps utilization, but paying down debt helps utilization and saves you interest and improves your debt-to-income ratio. Don’t use limit increases as a substitute for paying down what you owe.
10. Forgetting That Utilization Has No Memory
Here’s a quirk of the credit scoring system: utilization has no memory. If you’re at 40% this month and pay down to 8% next month, your score reflects 8% — there’s no penalty for the prior 40%. This means you can time your paydowns to statement closing dates for maximum score benefit, and you don’t need to stress about a temporary utilization spike from a planned purchase. Pay it down before the statement closes, and your score never sees it.
Frequently Asked Questions
How often can I request a credit limit increase?
Most issuers allow you to request an increase every 6 months per account. Some permit requests every 3 months. Requesting more frequently than the issuer allows typically results in an automatic denial — and if the issuer runs hard pulls, that’s an unnecessary inquiry. Stick to the 6-month cadence unless your issuer explicitly allows more frequent requests.
Does an automatic credit limit increase affect my credit score?
An automatic increase is almost always a soft pull, so the request itself has no score impact. The higher limit lowers your utilization, which typically helps your score once the new limit reports to the bureaus (usually within one to two billing cycles).
Can I request a credit limit increase on a secured card?
Yes, and it’s often a smart move. Many secured cards allow increases after 6–12 months of responsible use. In some cases, a sufficient payment history and score improvement can even trigger a transition to an unsecured card, where your deposit is refunded and the card continues as a standard credit account. Check with your secured card issuer on their specific upgrade path.
Will a credit limit increase help if I’m carrying a balance?
Yes — and this is actually where it helps most. If you’re carrying a balance and can’t pay it down immediately, a higher limit lowers your utilization without requiring a paydown. That said, the increase is not a substitute for eventually paying off the balance. Use the score boost as breathing room while you work a paydown plan.
Can I be denied a credit limit increase even with good credit?
Yes. A strong credit score helps, but issuers also consider your income, account history with them specifically, overall debt load, and recent credit activity. A 760 score with a brand-new account, a recent hard pull, or inconsistent income on file can still result in a denial. The score is one input, not the whole decision.
Does requesting a credit limit increase hurt my score if I’m denied?
If the request triggered a hard pull, you’ll see a small, temporary score dip regardless of whether you were approved or denied. If it was a soft pull, there’s no score impact either way — denial included. The denial itself does not appear as a separate negative mark on your credit report.
What’s the fastest way to raise my credit score using a limit increase?
Request a soft-pull increase from an issuer that uses soft inquiries, keep your spending exactly the same, and let the new lower utilization report at the next statement closing. Many people see a score bump within 30–45 days of the new limit reporting. For the fastest possible impact, pair the increase with a paydown before the statement closes — that puts you in the strongest utilization position when the bureaus receive the update.
Should I close a card after getting a limit increase on another card?
Generally, no. Closing a card reduces your total available credit, which raises your overall utilization — the opposite of what you want. Even if you don’t use a card, keeping it open preserves the credit line and the account age, both of which support your score. If the card has an annual fee you can’t justify, consider asking the issuer for a product change to a no-fee version instead of closing it.
Are you ready to take the next step in credit repair?
A credit limit increase, done right, is one of the simplest and most effective tools for improving your credit score — no new accounts, no credit mix disruption, and often no hard inquiry at all. The strategy comes down to a few principles:
- Time it right — 6+ months of history, clean payments, low utilization, updated income
- Confirm the inquiry type — soft pull is free, hard pull is a small short-term cost
- Ask for a reasonable amount — 10–25% above your current limit
- Keep spending steady — the increase helps your score only if utilization actually drops
- Handle denials constructively — find out why, address it, and re-request when the time is right
But a limit increase is just one piece of a larger credit health picture. If your credit report has errors dragging your score down — accounts that aren’t yours, late payments that were actually on time, balances reported incorrectly — no amount of limit optimization will get you where you deserve to be. That’s where a professional, FCRA-compliant credit audit comes in.
At credit-repair.com, we help individuals and families take control of their financial future through honest, results-driven credit repair. Our process includes:
- A comprehensive audit of all three credit bureaus — Equifax, Experian, and TransUnion
- Disputing inaccuracies through the proper FCRA channels
- Negotiating with creditors and working to remove negative marks
- Customized repair plans tailored to your specific goals
- Attorney-backed, legally compliant processes — no shortcuts, no empty promises
- Client education so you understand your credit and how to keep it strong long after the work is done
We’re based in San Diego and serve clients nationwide. We don’t just fix your credit — we equip you with the knowledge and tools to keep it strong for life.
Get your free credit audit today at . No hidden fees, no pressure, no quick-fix claims — just a clear, honest look at what’s on your report and a plan to improve it.
Your credit future is worth protecting. Let’s take the first step together.
This article is for educational purposes and does not constitute legal or financial advice. Your individual credit situation is unique — for personalized guidance, request a free credit audit and speak with our team.
