
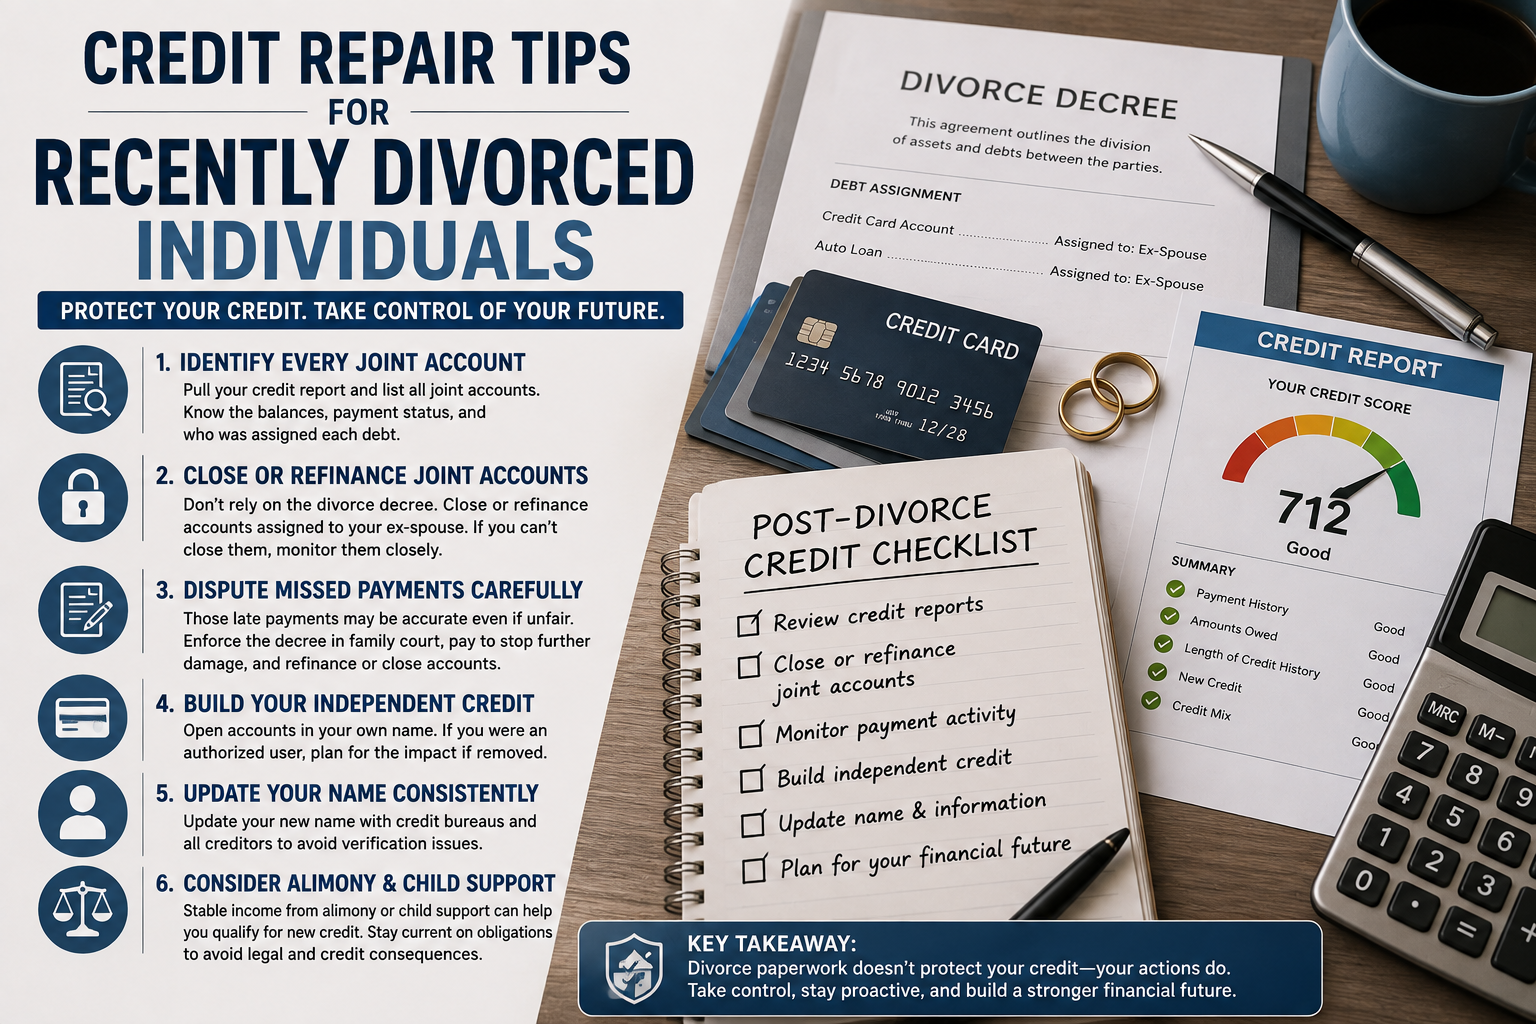
Divorce creates a specific, often confusing category of credit problems, because a divorce decree — the legal document dividing responsibility for debts — has essentially no power over your actual credit report. Understanding this disconnect is the foundation for fixing credit issues that emerge during or after a divorce.
The Core Problem: Divorce Decrees Don’t Bind Creditors
If your divorce settlement assigns a joint credit card debt to your ex-spouse, that assignment is a legal agreement between the two of you, enforceable in family court. But the original creditor was never a party to that agreement — they only know about the account terms you originally signed, which almost always list both spouses as jointly and individually liable if it was a joint account.
This means: if your ex-spouse was assigned a joint debt in the divorce and stops paying it, **the creditor can still come after you**, and that missed payment will still show up on your credit report, regardless of what the decree says. Your only recourse for the decree not being honored is back in family court against your ex — the creditor and credit bureau are entirely unaffected by that legal proceeding.
Step 1: Identify Every Joint Account
Before anything else, pull your credit report and identify every account where you’re listed as a joint holder or co-signer, not just an authorized user (a distinction that matters — authorized users generally aren’t legally liable for the debt, while joint holders and co-signers are).
For each joint account:
– Note the current balance and payment status.
– Determine whether it was assigned to you or your ex-spouse in the divorce settlement.
– Confirm who’s actually been making payments since the divorce, regardless of what was assigned.
Step 2: Actually Close or Refinance Joint Accounts You Don’t Control
This is the single most important practical step, and it’s the one people skip most often because it requires action, not just paperwork. If an account was assigned to your ex-spouse but remains open with both names on it:
– **Request the account be closed** and any remaining balance refinanced solely in your ex-spouse’s name, if that was the agreed division.
– **If refinancing isn’t possible**, at minimum, monitor the account closely, since you remain liable regardless of the decree.
– **For accounts assigned to you**, consider removing your ex-spouse if the creditor allows it, both to simplify your file and to avoid disputes over an account they no longer have interest in.
Waiting passively for the divorce decree to “handle” this is one of the most common and damaging mistakes — the decree only creates an obligation between you and your ex-spouse; it does nothing with the creditor unless you take separate action to actually restructure the account.
Step 3: Dispute Any Post-Divorce Missed Payments Carefully
If your ex-spouse missed a payment on an account assigned to them, and it’s now showing on your credit report, you generally cannot dispute this as “inaccurate” in the FCRA sense — if you were legally a joint account holder when the payment was missed, the reporting is technically accurate, even though it feels deeply unfair given the divorce agreement.
Your options in this situation:
– **Pursue enforcement in family court** against your ex-spouse for violating the decree — this doesn’t fix your credit report directly, but can result in the court ordering compensation or specific compliance.
– **Consider paying the missed payment yourself** to stop further damage, then pursuing reimbursement from your ex-spouse separately, if the ongoing credit damage is a bigger concern than the immediate cash outlay.
– **If the account can be refinanced or closed going forward**, prioritize that immediately to prevent recurring damage, even if you can’t undo what’s already been reported.
Step 4: Build Independent Credit If You Relied on Joint Accounts
Many people, especially those who weren’t the primary account holder on shared credit during the marriage, find themselves with a thinner independent credit file than expected post-divorce. If this applies to you:
– Open **individual accounts in your own name** — a card or credit-builder loan solely under your name and Social Security number, separate from anything connected to your ex-spouse.
– If you were mostly an authorized user on your ex-spouse’s accounts (rather than a joint holder), understand that being removed as an authorized user can actually reduce your available history, since authorized user history typically stops counting once removed — this is worth factoring into your planning before a divorce is finalized, if you have advance notice.
Step 5: Address Name Changes Carefully
If you’re changing your name post-divorce, make sure this is updated consistently across your credit accounts and with the bureaus, since a name mismatch can occasionally cause identity verification issues or slow down dispute processing. This is a minor administrative step but worth doing early to avoid downstream friction.
Step 6: Consider the Alimony/Child Support Interaction
If you’re receiving alimony or child support, be aware:
– Consistent, documented alimony or child support income can generally be counted toward qualifying for new credit, which is useful if you’re
trying to build independent credit post-divorce and have limited individual income otherwise.
– If you’re paying alimony or child support and fall behind, this can result in its own collection or, in some states, judgment-related consequences, separate from any joint-debt credit issues.
Special Consideration: Community Property States
If you were divorced in a community property state (Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, Wisconsin), debts incurred during the marriage may be treated as jointly owned regardless of whose name is technically on the account, which can complicate the picture further — even an account solely in your ex-spouse’s name might have been treated as shared marital debt during the divorce proceedings. This is worth discussing directly with a family law attorney if you’re unsure how your state’s rules affected your specific settlement.
A Realistic Timeline for Untangling Joint Credit
– **Immediately post-divorce**: identify all joint accounts and prioritize closing or refinancing those not aligned with your intended financial independence.
– **First 3-6 months**: monitor closely for any missed payments on accounts still technically joint, and address quickly if they occur.
– **6-12 months**: as accounts are successfully separated and any new individual accounts season, your independent credit profile should start reflecting your own behavior more clearly, separate from your ex-spouse’s.
The Bottom Line
The single biggest mistake in post-divorce credit management is assuming the divorce decree itself protects your credit report — it doesn’t, and creditors will continue to hold both parties liable on joint accounts regardless of what a family court ordered. The real fix is taking active steps to close, refinance, or separate joint accounts as quickly as possible after the divorce, rather than relying on the paperwork to do that work automatically, and building independent credit history in parallel if your financial identity was previously intertwined with your former spouse’s.