
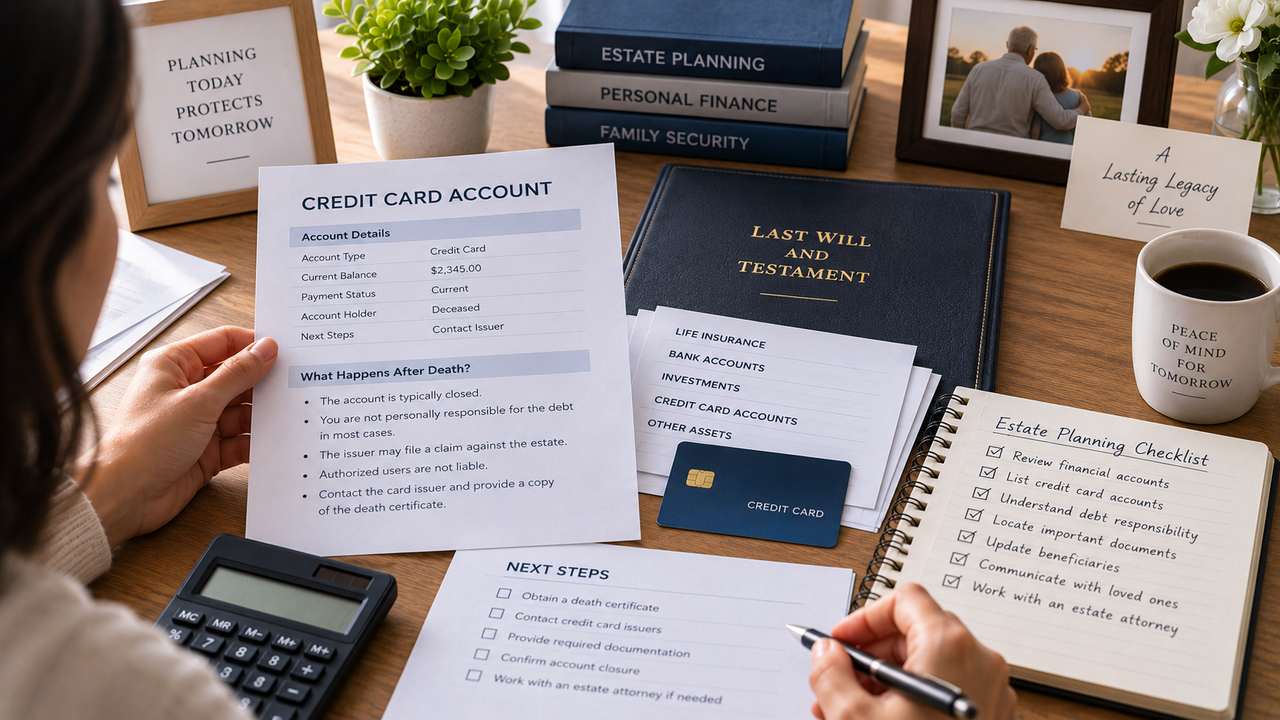
In the United States, credit card debt does not automatically transfer to surviving family members upon a person's death. Instead, the deceased individual's credit card debt becomes the responsibility of their estate, which is the collection of their assets and liabilities. This principle generally protects spouses, children, and other family members from inheriting unsecured debt. However, exceptions exist for joint account holders, cosigners, or individuals living in community property states, where family members may be held responsible.
The Core Principle: Your Debt Doesn’t Automatically Transfer to Your Family
In the United States, credit card debt (and most other unsecured debt) does not automatically become the responsibility of your spouse, children, or other family members simply because you’ve passed away. Your debts become the responsibility of your estate — the collection of assets and liabilities you leave behind — not of your surviving relatives personally, with a few specific and important exceptions covered below.
How the Estate Settlement Process Handles Debt
When someone dies, their estate typically goes through a legal process called probate (though smaller estates in many states qualify for a simplified process, and some assets bypass probate entirely). As part of this process, the estate’s executor or administrator is responsible for identifying debts, notifying creditors, and paying valid debts using the estate’s available assets, in a specific order of priority determined by state law, before any remaining assets are distributed to heirs.
If the estate has sufficient assets to cover the debt, credit card companies get paid from those assets. If the estate’s assets are insufficient to cover all debts, creditors generally must accept whatever partial payment the estate can provide (following the priority order), and any remaining unpaid balance is typically simply written off by the creditor — not passed on to surviving family members to pay out of their own personal funds.
The Key Exceptions Where Family Members CAN Be Held Responsible
Joint Account Holders
If someone was a joint account holder on the credit card (not simply an authorized user), they remain fully, personally liable for the debt, exactly as they were before the death — this liability doesn’t change or transfer through the estate process, since a joint account holder was always independently responsible for the full balance, regardless of who passed away.
Cosigners
Similarly, if someone cosigned the credit card account, they remain personally responsible for the debt after the primary cardholder’s death, since a cosigner’s liability was never contingent on the primary borrower’s continued survival.
Community Property States
In community property states (including states like California, Texas, and several others), debt incurred during a marriage can sometimes be considered a shared marital obligation, potentially making a surviving spouse responsible for debt even on an account that was solely in the deceased spouse’s name, depending on the specific state’s laws and when and how the debt was incurred. This varies meaningfully by state, so if you’re in a community property state, understanding your specific state’s rule is worth doing directly, ideally with an estate attorney’s guidance.
Authorized Users Are Generally NOT Liable
It’s worth explicitly noting what does NOT create liability: being an authorized user on the deceased’s credit card does not make you personally responsible for the debt, since an authorized user was never legally obligated for the balance in the first place, even while the primary cardholder was alive.
What Debt Collectors Can and Cannot Do When Contacting Family After a Death
Debt collectors are permitted to contact family members specifically to identify the appropriate estate representative to handle the debt, but they cannot mislead family members into believing they’re personally obligated to pay a debt that isn’t legally theirs to pay (unless one of the exceptions above genuinely applies). Some family members, out of grief, a sense of obligation, or simple confusion about the law, end up paying debts they were never actually legally required to pay — understanding your actual legal position protects you from this, whether you’re the one navigating a family member’s estate or being contacted directly by a collector.
If you believe a collector is using misleading or inappropriate tactics, you can learn more about your rights in our guide to collection agency harassment and your rights under the FDCPA.
For additional consumer information about debt collection practices, visit the Consumer Financial Protection Bureau’s FDCPA resource.
What Happens If the Deceased Had Life Insurance?
Life insurance proceeds generally pass directly to the named beneficiary, outside of the probate process, and are generally not considered part of the estate available to creditors (with some limited exceptions depending on state law and how the policy is structured) — meaning life insurance proceeds paid to a named beneficiary are typically protected from the deceased’s creditors, providing financial support to survivors without being absorbed into estate debt repayment.
Steps for an Executor or Family Member Handling This Situation
- Notify credit card companies and other creditors promptly once you’re managing the estate, providing a death certificate as required.
- Do not pay any debt from your own personal funds unless you’ve confirmed you’re actually personally liable (as a joint holder, cosigner, or under applicable community property rules) — paying out of a sense of obligation when you’re not legally required to is a common, avoidable mistake.
- Let the estate’s assets, through the proper probate or estate settlement process, handle valid debts in the legally required priority order, rather than making informal payments outside this structured process.
- Consult an estate attorney if the situation is complex, particularly if you’re unsure whether you personally have any liability, or if debt collectors are pressuring you in ways that don’t align with your understanding of your actual legal position.
What Happens to the Deceased’s Credit Score and Report?
The deceased’s credit file is typically updated to reflect their death (sometimes reported by the Social Security Administration to the credit bureaus, or by the estate representative directly), and their credit report generally becomes inactive rather than continuing to be actively monitored or updated in the way a living person’s would be. This is also part of why proactively notifying credit bureaus of a death is an important estate-settlement step — it helps prevent identity theft targeting a deceased person’s identity, an unfortunately real and specific category of fraud.
For more information about protecting a person’s credit information and identity, see our guide to identity theft protection.
Frequently Asked Questions
Can debt collectors contact me about a deceased family member’s debt if I have no legal responsibility for it?
Yes, but only for the limited purpose of identifying the appropriate estate representative — they cannot pressure you into personally paying a debt you’re not legally responsible for, and if this happens, it’s worth documenting and potentially reporting as an FDCPA violation.
Does credit card debt ever just “disappear” entirely if the estate has no assets?
Effectively, yes, in the sense that if the estate genuinely has no assets to pay creditors, unsecured debt like credit card balances is typically written off by the creditor as uncollectible, with no legal mechanism to pursue family members who aren’t otherwise personally liable.
If I’m an authorized user on my deceased parent’s card, do I need to do anything specific?
You should stop using the card once you’re aware of the death (continuing to use it could raise legitimate questions, even though you weren’t liable for pre-existing balances), and the account will typically be closed as part of the estate settlement process.
Does this apply the same way to federal versus private student loans if a family member co-signed?
Federal student loans have some specific death discharge provisions (federal Direct Loans are generally discharged upon the borrower’s death), while private student loans vary considerably by lender — some do discharge upon death, others may still hold a cosigner responsible, making this worth checking with the specific loan servicer if it’s relevant to your situation.
Is it worth getting life insurance specifically to cover potential debt for my family’s protection?
This is a legitimate estate-planning consideration for some people, particularly those in community property states or with joint debts, since it can provide funds to help settle debts (or simply provide general financial support) without depleting other estate assets your heirs might otherwise receive — though this is a personal financial planning decision worth discussing with a financial advisor given your specific situation.
A Walkthrough of the Estate Debt Priority Order
Understanding roughly how creditors get paid from an estate’s assets helps explain why some debts get fully covered while others don’t, even from the same estate. While specific priority orders vary by state, a common general pattern looks something like this: funeral and burial expenses, and the costs of administering the estate itself, are typically paid first. Then, secured debts (like a mortgage or car loan, where the debt is tied to specific collateral) are addressed, often through the collateral itself rather than other estate assets. Taxes owed (federal and state) generally take priority over general unsecured debt. Only after these higher-priority categories are addressed does unsecured debt — credit cards, medical bills, personal loans — get paid from whatever assets remain, and if nothing remains at that point, these creditors typically receive nothing and cannot pursue payment from family members who aren’t otherwise personally liable.
This priority structure is exactly why it’s possible for an estate to have some assets (enough to cover funeral costs and outstanding taxes, for example) while still leaving credit card debt completely unpaid and ultimately written off, without this being any kind of unusual or improper outcome — it’s simply how the legally mandated priority order works.
What “Insolvent Estate” Means and Why It Matters
An estate is considered “insolvent” when its debts exceed its available assets. This is actually a fairly common situation, particularly for someone who didn’t accumulate substantial assets during their lifetime, or whose major assets (like a home) pass outside probate through other mechanisms (joint ownership with survivorship rights, for instance) and therefore aren’t available to satisfy the deceased’s individual debts. An insolvent estate doesn’t create any personal liability for family members beyond the specific exceptions already discussed — it simply means creditors, including credit card companies, absorb the loss on whatever portion of the debt the estate’s limited assets can’t cover.
A Practical Note for Someone Currently Grieving and Facing These Questions
It’s worth acknowledging directly: figuring out debt and estate obligations while actively grieving a loss is genuinely difficult, and debt collectors reaching out during this period — however legally limited their actual authority might be — can feel like an additional, unwelcome burden at an already overwhelming time. It’s completely reasonable to take time, consult with an estate attorney if the situation feels complex or if you’re facing pressure that doesn’t align with your understanding of the law, and not feel obligated to resolve every detail immediately under pressure from a collector’s timeline rather than your own.
More FAQs: State Laws, Claim Deadlines, and Debt Repayment
Does it matter which state the deceased lived in versus which state their family members live in?
Generally, the deceased’s state of residence and where their estate is being probated governs the estate settlement process and applicable debt rules, though if a surviving spouse has independent liability under community property rules, their own state of residence at the relevant time the debt was incurred can also be relevant — this cross-state complexity is exactly the kind of detail worth an estate attorney’s specific guidance if it applies to your situation.
Can a credit card company file a claim against the estate even years after the death, or is there a deadline?
Most states impose a specific claims period (often several months to a year) during which creditors must formally file claims against an estate, after which they’re generally barred from pursuing payment — this is one of the protective functions of the formal probate process, providing eventual finality for the estate rather than indefinite ongoing creditor claims.
If I paid off a deceased family member’s credit card debt out of my own funds before realizing I wasn’t legally obligated to, can I get that money back?
This is a difficult, fact-specific situation worth discussing with an attorney — depending on the circumstances and how the payment was made, there may be limited options for recovery, though this varies considerably and isn’t guaranteed, which is exactly why understanding your actual legal obligations before making any payment is so important.
What Happens to Ongoing Subscriptions and Recurring Charges Linked to the Card
A practical detail often overlooked: any subscriptions or recurring charges linked to the deceased’s card will typically continue attempting to bill until the account is formally closed, potentially resulting in declined charge notices or service interruptions. Part of the estate settlement process should include identifying and canceling these recurring charges directly with each service provider, separate from the broader debt settlement process, since simply closing the credit card account doesn’t automatically notify every merchant with a saved payment method.
How to Handle Multiple Cards Across Multiple Institutions
If the deceased held several credit cards across different banks, each issuer needs to be separately notified and each account separately addressed through the estate process — there’s no centralized, single notification that automatically closes every account at once. Keeping an organized list of every known account, along with the relevant contact information for each issuer’s estate or deceased-accounts department (most major issuers have a dedicated team for this), helps streamline what can otherwise become a scattered, time-consuming process during an already difficult period.
Additional FAQs: Executor Notifications and Post-Death Fraud
Does the executor need to personally contact each credit card company, or can this be handled through a single unified process?
Generally, each creditor needs to be individually notified, though some estate attorneys and services specialize in streamlining this notification process across multiple accounts on the executor’s behalf, which can be worth considering for an estate with numerous accounts.
If a deceased person’s card was used fraudulently after their death, who is responsible for resolving that?
The estate representative should report this to the card issuer the same way any fraud would be reported, and standard fraud liability protections generally still apply, protecting the estate from being held responsible for charges made without authorization after the cardholder’s death.
Key Takeaways: Credit Card Debt and Family Liability After Death
Credit card debt generally dies with the estate’s ability to pay it, not with surviving family members personally, except in specific situations — joint account holders, cosigners, and in some cases spouses in community property states. Authorized users are never personally liable.
If you’re navigating a family member’s estate, understanding this distinction protects you from paying debts you’re not legally obligated to cover, and if you’re managing your own estate planning, understanding these rules can inform decisions about joint accounts, cosigning, and life insurance as you think about what you’ll ultimately leave behind for your family to navigate.
Need Help Understanding Your Credit Report?
Understanding how credit accounts, debt, collections, and reporting work can help you make more informed financial decisions. If you are concerned about inaccurate information or negative accounts appearing on a credit report, a professional review may help identify potential issues.