
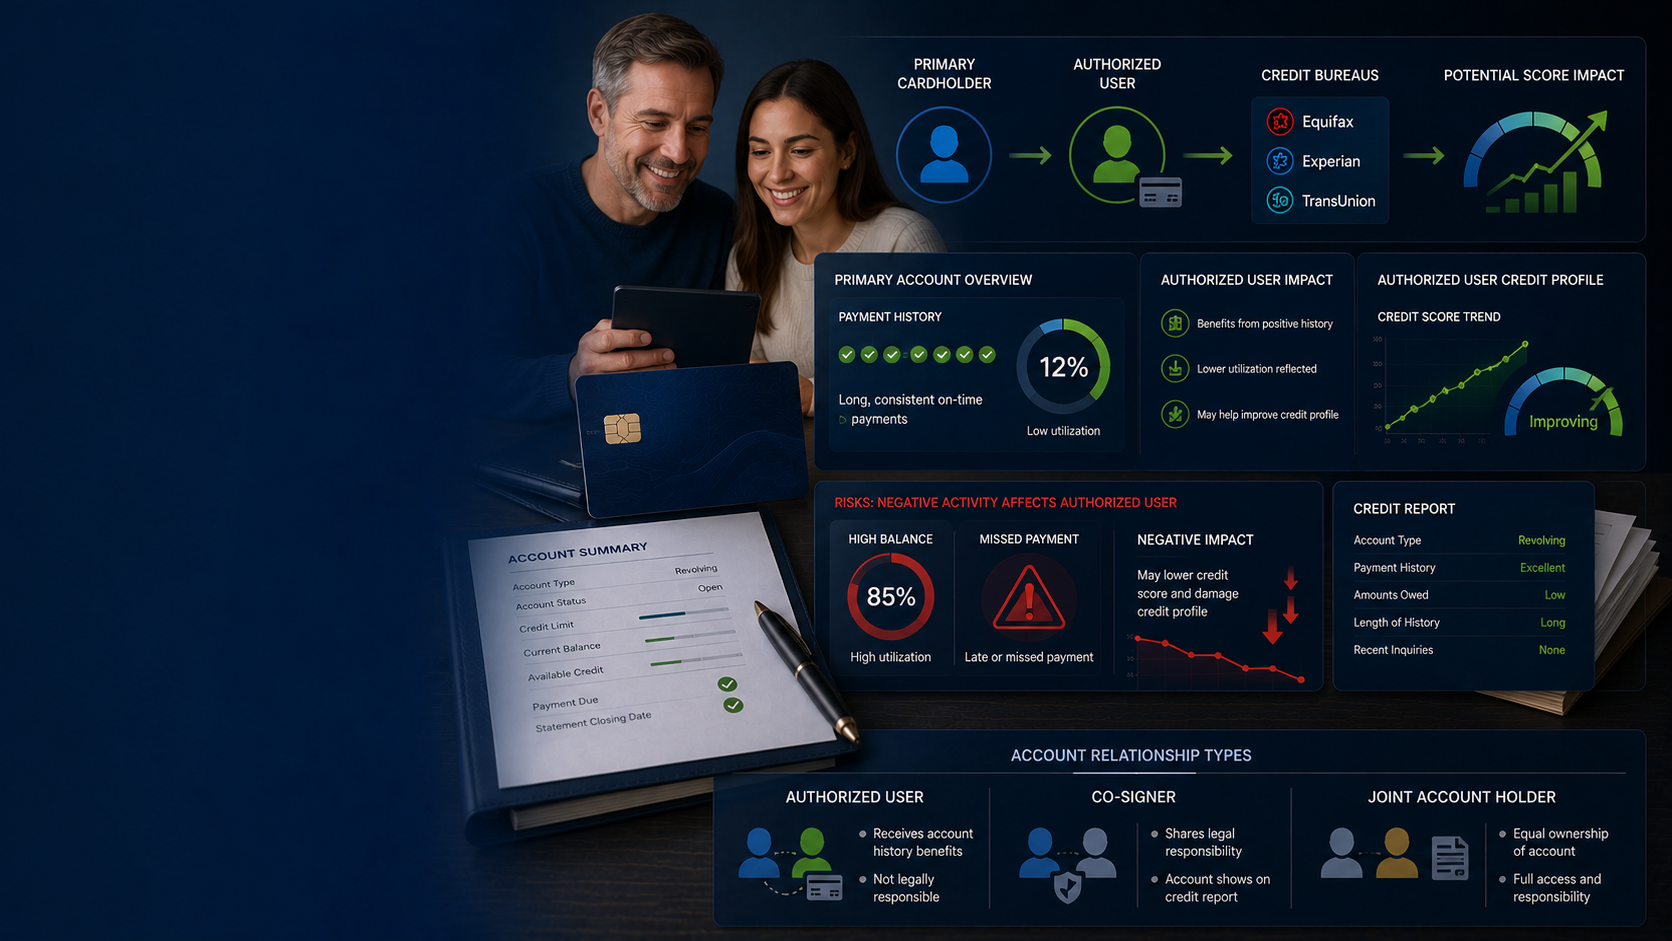
How being an authorized user affects your credit score
If you’ve ever been added to someone else’s credit card — maybe a parent pulled you onto their oldest card to help you start building credit, or a spouse added you for convenience — you’ve been an authorized user. It’s one of the oldest and most misunderstood tools in the credit-building playbook. Done well, it can meaningfully strengthen a thin credit file. Done carelessly, it can drag down your score or saddle someone you love with debt they didn’t expect to be responsible for.

Quick Answer

Being an authorized user on a credit card allows the primary account's payment history and credit limit to appear on the authorized user's credit report, potentially helping to build or improve their credit score. This strategy is most effective when the primary account has a long, spotless payment history and low credit utilization, and crucially, when the card issuer reports authorized user activity to the major credit bureaus. However, an authorized user's credit score can be negatively impacted if the primary cardholder makes late payments or maintains high credit utilization, as these negative factors will also be reflected on the authorized user's credit file. The impact of authorized user status is also influenced by specific scoring models like FICO Score 8 and VantageScore 3.0, and its effectiveness is continually evolving with changes in how credit bureaus and lenders process this data, with stricter abuse detection anticipated by 2026.

Table of Contents

This guide breaks down what actually happens to your credit score when you become an authorized user, which cards report that history, how the scoring models treat it differently, the real risks on both sides of the relationship, and how to add or remove an authorized user the right way. We’ll also be honest about where this strategy stops working — including the murky world of paid “tradelines” — so you can make a clear-eyed decision.

What Is an Authorized User?

An authorized user (often abbreviated AU) is someone who is permitted to use another person’s credit card account but is not legally responsible for paying the debt. The primary cardholder — the person who opened the account and signed the credit agreement — remains fully on the hook for every charge made on the card, including charges made by the authorized user.

Here’s what being an authorized user does and does not give you:

  • You can make purchases with a card issued in your name on the primary account.
  • You can build credit history — if the card issuer reports authorized user activity to the credit bureaus.
  • You cannot be held legally responsible for the balance.
  • You cannot change the account terms, request credit limit increases, or close the account.
  • You cannot remove the primary cardholder or other authorized users.

This is a one-way street of permission and liability. The primary cardholder extends a privilege and bears all the legal risk. You, as the authorized user, get the convenience of using the card and — critically — the potential benefit of the account’s history landing on your credit report.

The arrangement is common between family members: a parent adds a teenager or young adult child to a long-standing card; a spouse adds a partner who is rebuilding credit after a divorce or bankruptcy; sometimes a trusted friend sponsors someone working to recover from past credit mistakes. It is one of the few ways a person with no credit history at all can begin to establish one without opening their own account and risking a hard inquiry or a denial.

Why the strategy exists at all

Credit scoring models reward two things above almost everything else: a long history of on-time payments and low credit utilization. For someone with a thin file — a young adult, a recent immigrant, someone who has avoided credit for years — those two ingredients are exactly what they lack. You can’t build payment history without an account, and you can’t get an account without some history. Authorized user status is the most common workaround: it lets you “inherit” the positive history of an established account without having to qualify for it yourself.

This is why the strategy is sometimes called piggybacking — you ride on the back of someone else’s good credit. When it’s done between family members with honest intentions, it’s a legitimate and widely recommended credit-building tool. When it’s commercialized and sold to strangers (more on that below), it enters a gray area that the credit bureaus and scoring models have spent years trying to police.


Authorized User vs. Co-Signer vs. Joint Account Holder

People often use these three terms interchangeably, but they are legally and financially distinct — and the differences matter a lot for your credit and your liability.

Authorized user

As described above, an authorized user has no legal responsibility for the debt. Your name appears on a card tied to the primary account, and the account may show up on your credit report, but the creditor cannot come after you for the balance. If the primary cardholder stops paying, your credit may suffer (if the account is reporting on your file), but you won’t be sued or sent to collections for that debt.

Co-signer

co-signer is someone who signs the credit agreement alongside the primary borrower and agrees to be fully responsible for the debt if the primary borrower fails to pay. Co-signers are common on loans for young borrowers, people with limited credit, or people rebuilding credit — auto loans, private student loans, and sometimes credit cards.

The key difference from an authorized user: a co-signer is legally on the hook. If the primary borrower defaults, the lender can pursue the co-signer for the full balance, report the default on the co-signer’s credit, and take the co-signer to court. The loan appears on both parties’ credit reports from the start, and both are equally exposed to the consequences of missed payments.

Joint account holder

joint account holder (or joint applicant) co-owns the account with equal rights and equal responsibility. Both parties applied for the account together, both can use it, both can make changes to it, and both are fully liable for the balance. Joint accounts are more common on credit cards from credit unions and some smaller issuers; the major national banks have largely moved away from offering them.

Feature Authorized User Co-Signer Joint Account Holder
Can use the card Yes No (usually) Yes
Legally responsible for debt No Yes (if primary defaults) Yes (always)
Account reports on their credit Sometimes (issuer-dependent) Yes Yes
Can request changes to account No No Yes
Can close the account No No Yes (usually)
Risk to their credit if payments are late Possible (if reporting) Yes Yes
Risk of being sued for the debt No Yes Yes

The practical takeaway: if someone asks you to “help them build credit” and you’re trying to decide which role to take, understand what you’re signing up for. Being an authorized user is low-risk for the person being added. Co-signing or opening a joint account is high-risk for the person doing the helping — you’re putting your own credit and your own assets on the line.

How Being an Authorized User Affects Your Credit

When everything lines up correctly, being an authorized user can help your credit score in several specific ways. But “when everything lines up correctly” is doing a lot of work in that sentence — so let’s unpack what actually happens under the hood.

The mechanism: account history lands on your file

When you’re added as an authorized user to a credit card, the card issuer has the option to report the account to the three major credit bureaus — EquifaxExperian, and TransUnion — under your name as well as the primary cardholder’s name. If the issuer does report it, the entire history of that account (not just the period after you were added) typically appears on your credit report as if you had been associated with the account all along.

That means if the primary cardholder opened the card ten years ago, has never missed a payment, and keeps the balance low, your credit report may suddenly show a ten-year-old account in perfect standing — even if you were added last week and have never made a single charge.

This matters because credit scoring models weight several factors that this account can influence:

  • Payment history (the single biggest factor in most scoring models, roughly 35% under FICO 8). An account with years of on-time payments boosts this category.
  • Length of credit history (about 15% under FICO 8). An old account raises your average age of accounts, which is one of the hardest metrics to improve quickly on your own.
  • Credit utilization (about 30% under FICO 8). A card with a high credit limit and a low balance improves your overall utilization ratio.
  • Credit mix (about 10% under FICO 8). An additional revolving account can modestly help if your file is thin on revolving credit.

What shows up on your report

When an authorized user account reports on your credit file, it typically displays:

  • The account type (revolving credit card)
  • The date opened (the original opening date, not the date you were added)
  • The credit limit and current balance
  • The payment history for the life of the account
  • Your relationship to the account (authorized user)
  • The account status (open, current, etc.)

The reporting relationship is usually clearly marked as “authorized user,” which is important because it tells anyone reading the report (including scoring models) that you are not the primary account holder.

When it helps most

Authorized user status helps most for people with:

  • A thin credit file — few or no open accounts, short or nonexistent credit history
  • No credit score at all — a completely “unscorable” file because there isn’t enough data
  • A damaged score being rebuilt — where adding a clean, old positive account can help offset past negatives
  • Limited revolving credit — where adding one more healthy revolving account improves utilization and credit mix

For someone who already has a thick file, multiple established cards, and a strong score (say, 760+), adding an authorized user account typically produces a much smaller — sometimes imperceptible — change. The marginal value of one more good account diminishes as your file gets richer.

When it does not help

Being an authorized user does not help your credit when:

  • The issuer does not report authorized user accounts to the bureaus (see the next section).
  • The primary account has late payments, high utilization, or other negative marks — those can hurt you, not help you.
  • You already have stronger accounts of your own and the new AU account doesn’t add anything.
  • The scoring model being used to evaluate you strips out or downweights authorized user accounts (more on this below).


The Catch: Not Every Issuer Reports Authorized Users

Here’s the part that trips people up: not all credit card issuers report authorized user accounts to all three credit bureaus. If the issuer doesn’t report the AU relationship, then as far as your credit report is concerned, being an authorized user changes nothing. You can use the card, but it won’t help your credit at all.

Which issuers report, and to whom?

Reporting practices vary by issuer and can change over time. As a general rule:

  • Most major national issuers (American Express, Bank of America, Capital One, Chase, Citi, Discover, Wells Fargo, and others) do report authorized users to all three bureaus — but there are caveats.
  • Some issuers require the authorized user to have a Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN) on file before they’ll report. Without one, the account may not land on the AU’s credit file.
  • A few issuers report to only one or two bureaus rather than all three.
  • Store cards and co-branded cards sometimes have different reporting practices than the issuer’s general-purpose cards.

Because these practices shift, the most reliable approach is to call the issuer directly and ask: “Do you report authorized users to all three credit bureaus — EquifaxExperian, and TransUnion? Do you require a Social Security Number for the authorized user to be reported?” Get the answer in writing if you can (some issuers will note it in chat transcripts), and confirm before you rely on the arrangement for credit-building.

The scoring model wrinkle

Even when the issuer does report the AU account, the scoring model that eventually evaluates your credit file has to actually consider it. The two major scoring model families handle authorized users differently:

FICO 8 and later — FICO has stated that its models are designed to prevent “abuse” of authorized user status, a response to the paid tradeline industry (more on that below). In practice, FICO 8 does still consider authorized user accounts for most consumers, but it applies logic meant to isolate suspicious patterns — for example, a sudden spike in newly added AU accounts on a single primary card may be treated differently than a long-standing family arrangement. For ordinary consumers being added to a family member’s card, FICO 8 generally counts the AU history.

VantageScore 3.0 and 4.0 — VantageScore has historically taken a more skeptical view of authorized user accounts. Earlier versions of VantageScore stripped out AU accounts entirely in some cases. VantageScore 3.0 and 4.0 do consider authorized user tradelines, but the models have been tuned to reduce the weight of AU-only history relative to primary accounts. If a lender pulls a VantageScore to evaluate you, the AU account may help less than it would under FICO 8.

FICO 9, FICO 10, and FICO 10T — These newer models continue to consider authorized user accounts but include refinements to the abuse-detection logic. FICO 10T, which uses trended data (looking at your balances over time rather than a single snapshot), may weight the primary cardholder’s utilization patterns differently when they appear on your file as an AU.

Industry-specific scores — Auto-enhanced and bankcard-enhanced FICO scores may treat AU accounts somewhat differently from the base scores used for most general lending decisions.

The practical implication: the same authorized user account can help your score a lot under one model and barely move it under another. Since you don’t control which model a lender uses, the best you can do is make sure the account is reporting to all three bureaus and is in good standing — then let the models do what they do.

What you should verify

Before you count on authorized user status to build credit, confirm three things:

  • The issuer reports AU accounts to all three bureaus. Call and ask.
  • The issuer has the AU’s identifying information (SSN or ITIN, date of birth, legal name) so the bureaus can match the account to the AU’s file.
  • The account is in good standing — no late payments, low utilization, not in dispute or hardship status.

If any of those three are missing, the strategy may quietly do nothing — or worse, do something harmful.

How Much Does It Actually Help?

Let’s be honest about the upside, because there’s a lot of hype online that suggests becoming an authorized user is a magic credit-score boost. It isn’t. It’s a useful tool in the right circumstances, and a near-irrelevant one in the wrong circumstances.

For a thin or new credit file: meaningful

If you have no credit history at all — no cards, no loans, no score — being added as an authorized user to a single old, clean, low-utilization account can be enough to generate a FICO score where none existed before. We’ve seen cases where a previously “unscorable” consumer becomes scorable within one or two billing cycles of being added to the right card.

For someone with one or two young accounts and a short history, adding a ten-year-old AU account can raise their average age of accounts significantly, which can nudge the score up by a meaningful number of points — sometimes 20 to 50 points depending on the rest of the file. This is the sweet spot for the strategy.

For a damaged file being rebuilt: modest and conditional

If you have negative marks (late payments, collections, charge-offs), a positive AU account can help, but it won’t erase the damage. Payment history dominates the scoring models, and a single clean AU account can’t outweigh a recent 90-day late payment or an active collection. The AU account helps by adding positive history and improving utilization, which can support gradual recovery — but the timeline is driven by when the negative items age off your report (typically seven years for most late payments and collections).

For an established, strong file: minimal

If you already have several cards in good standing, a long average age of accounts, and a score in the mid-700s or above, adding one more authorized user account will usually produce a change so small it’s within the normal month-to-month fluctuation of your score. There’s no harm in it, but there’s also little reason to expect a meaningful bump.

For someone with no credit accounts but a long AU history: model-dependent

Some people have only authorized user accounts on their file — no primary accounts of their own. Whether this produces a usable score depends on the model. FICO 8 can generate a score from AU-only history in some cases, but the score may be weaker and less predictive than one built on primary accounts. VantageScore may handle AU-only files differently. Lenders that manually review the report will see that the history is all “authorized user” and may discount it.

The honest summary

  • Best case (thin file, great primary card): can take you from no score to a solid score, or from a limited score to a meaningfully better one.
  • Typical case (average file, decent primary card): a modest bump, maybe 10–30 points.
  • Worst case (thick file, or a primary card with problems): little to no help, or actual harm.

No one can guarantee a specific point increase, and you should be skeptical of anyone — including a credit repair company — who promises one. The outcome depends on the totality of your credit file, the specific account you’re attached to, and the scoring model the lender uses.

Choosing the Right Primary Cardholder

If you’re the one being added, the quality of the primary account matters more than almost anything else. A great authorized user arrangement can help you; a bad one can hurt you. Here’s what to look for in the account you’re attaching yourself to.

1. Long account history

Older is better. An account opened 10, 15, or 20 years ago contributes a long payment history and raises your average age of accounts. A brand-new account — even a perfectly managed one — adds almost nothing to your length of history and may actually lower your average age briefly. If you have a choice between being added to a card your parent opened in 2008 and a card your sibling opened last year, pick the 2008 card.

2. Spotless payment history

This is non-negotiable. A single 30-day late payment on the primary account can show up on your credit report as an authorized user and damage your score. Look for an account that has never been late — not once, not for a month, not during a hardship. If the primary cardholder has had any payment issues on that card, even years ago, consider a different account.

3. Low credit utilization

Utilization — the ratio of the current balance to the credit limit — is one of the most powerful levers in credit scoring. The primary card should ideally report a balance below 10% of its limit, and certainly below 30%. A card with a $10,000 limit that routinely reports a $4,000 balance (40% utilization) can hurt your score, not help it, even if it’s never been late.

Be aware that utilization is typically reported based on the statement balance — the balance on the day the statement closes — not the balance you carry month to month. A cardholder who pays in full every month but has high statement balances can still report high utilization. Ask the primary cardholder about their typical statement balance relative to the limit.

4. High credit limit (for utilization spillover)

A card with a high limit helps your overall utilization across all your accounts. If you have a $500 limit card of your own with a $200 balance (40% utilization on that card), and you’re added to a $20,000 limit AU card with a $500 balance, your total utilization drops from 40% to about 3.4% — a significant improvement.

5. Stability

Avoid accounts that are in active hardship programs, frequently disputed, or at risk of closure. An account that gets closed while you’re an authorized user loses its ongoing contribution to your file (though the history may remain for up to 10 years on FICO scores). An account that gets sent to collections is far worse.

6. An issuer that reports AUs

As discussed above, confirm the issuer reports authorized users to all three bureaus. There’s no point in being added to a perfect account if it never shows up on your credit report.

Quick checklist for the ideal AU card

  • Opened at least 5–10 years ago (older is better)
  • Never a late payment
  • Statement balance usually under 10% of the limit
  • High credit limit
  • Stable, active, not at risk of closure
  • Issuer reports AUs to all three bureaus

If the primary cardholder ticks all those boxes, you’ve found a strong candidate. If they tick only some, weigh the trade-offs — and remember that a single late payment or sustained high utilization can flip a “helpful” AU card into a “harmful” one overnight.
How being an authorized user affects your credit score

Risks to the Authorized User

Being added to someone else’s card is not risk-free for you, even though you’re not legally responsible for the debt. The risks are all about what lands on your credit report.

1. Their late payments become your late payments

If the primary cardholder misses a payment on the account — 30 days late, 60 days late, 90 days late — that late payment can be reported on your credit file as an authorized user. A 90-day late mark is one of the most damaging single items that can appear on a credit report, and it can tank your score by 100 points or more depending on your starting point. You didn’t make the late payment. You may not have even known about it. But it shows up on your report nonetheless.

This is the single biggest risk of being an authorized user, and it’s why you should only be added to an account you trust completely — one where the primary cardholder has a long, clean payment record and the financial discipline to keep it that way.

2. High utilization on the card hurts your score

Even if the primary cardholder never misses a payment, if they run the balance up near the limit, your utilization — as reflected on your credit report — goes up with it. A sudden spike in utilization (say, from 10% to 85% because of a large purchase or an emergency expense) can cause an immediate score drop, sometimes 30–60 points, until the balance is paid down.

3. Account closure removes the benefit

If the primary cardholder closes the account, or if the issuer closes it (for inactivity, default, fraud, or any other reason), the account may stop contributing to your active credit picture. The closed account’s history may remain on your report for up to 10 years (under FICO scoring), which softens the blow — but your “open revolving accounts” count drops, and if this was your oldest or only account, the impact can be noticeable.

4. Disputed or charged-off accounts are catastrophic

If the account goes into default, gets charged off, or is sent to collections, those severe negative marks can appear on your credit report as an authorized user. A charge-off is nearly as damaging as a 90-day late payment and stays on your report for seven years.

5. You have no control

As an authorized user, you cannot log in and pay the bill (unless the primary cardholder gives you access), you cannot request a credit limit increase, you cannot dispute inaccuracies on the account as the primary party, and you cannot close the account. You are entirely dependent on the primary cardholder to keep the account in good standing. If your relationship with the primary cardholder deteriorates — a divorce, a family estrangement, a falling-out — you may find it difficult to get yourself removed quickly.

How to protect yourself

  • Only join accounts you trust. The primary cardholder should have a years-long clean payment record.
  • Monitor your credit. Pull your reports from all three bureaus at AnnualCreditReport.com at least once a year, and consider a free credit monitoring service so you’ll see changes quickly.
  • Ask to be removed immediately if the account goes sideways. The faster you’re removed, the faster the account stops updating on your file. (More on removal below.)
  • Remember that removal stops future reporting but doesn’t erase past negatives. If a late payment already hit your file as an AU, removing yourself prevents new ones but doesn’t delete the old one. You may need to dispute it (with help from a credit repair professional if necessary) on the basis that you were not the responsible party.

Risks to the Primary Cardholder

The risks run the other direction too — and they’re more severe, because the primary cardholder is the one with legal liability.

1. You are responsible for every charge the AU makes

This is the core risk and the one most often underestimated. If the authorized user runs up $15,000 in charges on your card, you owe the $15,000. The card issuer will come after you, not the AU, for payment. If you don’t pay, your credit is the one that gets destroyed — not theirs. You could sue the AU in small claims court to recover the money, but that’s a long, uncertain, relationship-destroying process.

This is why the most common advice is: if you add an authorized user, don’t give them the physical card. Many issuers let you add an AU for credit-reporting purposes without ever issuing a card in their name. The AU gets the credit-building benefit, and you get zero risk of them making charges you didn’t authorize.

2. AU charges can push up your utilization

Even if the AU is responsible and only uses the card for agreed-upon expenses, their charges still count toward your balance and your utilization. If you keep a tight utilization strategy (paying down balances before the statement closes to report a low number), AU charges can disrupt that if you’re not coordinating closely.

3. Your credit is exposed if you add the wrong person

If the AU has a history of financial irresponsibility — and you give them a card — you’re handing a loaded financial instrument to someone who may not use it wisely. The AU’s past credit problems don’t directly affect your credit (their negatives don’t migrate to your file), but their future behavior on your card absolutely does.

4. Relationship risk

Mixing family or friendship with shared credit can strain even strong relationships. Disagreements about what was “agreed,” what charges were authorized, and who was supposed to pay can turn into lasting rifts. Set clear expectations in advance — ideally in writing — about whether the AU will use the card, for what, and how repayment will work.

How to protect yourself as the primary cardholder

  • Add the AU for credit-building only — don’t issue a card. This is the safest arrangement and is available from most major issuers.
  • If you do issue a card, set spending limits. Some issuers let you set a per-card spending limit for authorized users. Use it.
  • Monitor the account. Set up alerts for every transaction. Review the statement every month.
  • Have a clear agreement. If the AU will use the card, agree in advance on what’s allowed and how and when they’ll reimburse you. Put it in writing.
  • Be ready to remove the AU and destroy the card. If the arrangement isn’t working, act quickly. You can remove an AU at any time, and the sooner you do, the sooner you stop the bleeding.

How to Add or Remove an Authorized User

The mechanics of adding and removing an authorized user are straightforward, but there are some details worth getting right.

Adding an authorized user

  • Log in to your online account or call the issuer’s customer service line. Most issuers have an “Add an Authorized User” option in the account management section.
  • Provide the AU’s information. You’ll typically need their full legal name, date of birth, and Social Security Number (or ITIN). Some issuers allow you to add an AU without an SSN, but as discussed, providing one improves the likelihood that the account will report on the AU’s credit file.
  • Decide whether to issue a card. You can usually choose to have a physical card mailed in the AU’s name, or to add them without issuing a card. For pure credit-building purposes, adding without a card is the safest option.
  • Set spending limits if available. If the issuer supports per-AU spending limits and you’re issuing a card, set one that reflects your comfort level.
  • Confirm reporting. Within one to two billing cycles, check the AU’s credit report (via AnnualCreditReport.com or a monitoring service) to confirm the account is appearing on their file at all three bureaus. If it isn’t, call the issuer to verify their reporting settings.

Removing an authorized user

Removing an AU is just as easy — sometimes easier:

  • Log in or call. Most issuers let you remove an AU online; some require a phone call.
  • Request removal. You’ll need the AU’s name. Some issuers may ask for a reason, but you’re not obligated to provide a detailed one.
  • Destroy the AU’s card if one was issued. Cutting it up is the simplest approach. The issuer may also deactivate the card on their end.
  • Confirm the removal stops reporting. After removal, the account should stop updating on the AU’s credit file. The historical entries (positive or negative) that already reported while the AU was on the account generally remain on the AU’s report — removal doesn’t retroactively erase them.

If you’re the AU and want to be removed

As the authorized user, you generally cannot remove yourself from an account through the issuer — only the primary cardholder can remove you. However, you have another option: you can dispute the account directly with the credit bureaus. File a dispute with EquifaxExperian, and TransUnion stating that you are an authorized user, not a responsible party, and that you want the account removed from your credit report. The bureaus will typically remove authorized user accounts at the consumer’s request, since you have no legal obligation on the account.

This is a useful escape hatch if the primary cardholder is unresponsive, unreachable, or uncooperative — for example, in a difficult divorce or family estrangement.

A note on timing

If the account has already damaged your credit as an AU (late payments, high utilization), removing yourself or being removed stops future reporting but doesn’t fix the past. For that, you may need to dispute the negative items with the bureaus, arguing that as an authorized user you were not the responsible party. This is one of the situations where working with a reputable, FCRA-compliant credit repair firm can help — the dispute process has specific legal requirements, and doing it wrong can waste time or even backfire.


Does Being an Authorized User Still Work in 2026?

Yes — with caveats. Authorized user status remains a legitimate and widely used credit-building tool in 2026. The major issuers still report AU accounts (though always confirm with your specific issuer), FICO and VantageScore models still consider them, and lenders still recognize AU history on consumer credit reports.

But the landscape has evolved in ways worth understanding:

Stricter abuse detection in scoring models

FICO has been refining its authorized user handling since FICO 8, which introduced logic to detect and limit “piggybacking” abuse — specifically, the practice of selling authorized user slots on strong accounts to strangers. FICO 10 and FICO 10T continue this trend. The models are designed to let legitimate family AU relationships count while limiting the impact of suspicious, commercially motivated AU additions. For ordinary consumers being added to a family member’s long-held card, the models generally still give full credit. But the models are less generous with patterns that look like tradeline brokering.

Trended data changes the utilization picture

FICO 10T, which has been gaining adoption among lenders, uses trended data — it looks at your balance and payment patterns over time, not just a single snapshot. This means that if the primary cardholder has a history of running up high balances and paying them down (even if they’re never late), that pattern may be visible to the model and could reduce the benefit of the AU account. Under trended-data scoring, the ideal AU card is one with consistently low balances, not one that swings between high and zero.

Bureau-level AU handling

The credit bureaus themselves have tightened some of their processes around AU reporting over the years, partly in response to regulatory scrutiny and partly to combat tradeline brokering. This has not stopped legitimate family AU reporting, but it has made it slightly more important to ensure the AU’s identifying information is accurate and complete when they’re added.

Lender discretion

Even when an AU account helps your credit score, some lenders — particularly mortgage lenders — may look at your credit report manually and treat AU accounts differently. A mortgage underwriter might ask you to provide a letter explaining your relationship to the primary cardholder, or might discount AU accounts when calculating your effective credit history. This doesn’t make AU status useless, but it means that for major lending decisions (like a home purchase), the AU benefit may be less than your credit score alone suggests.

The bottom line for 2026

Authorized user status still works as a credit-building tool. It is most effective for thin files, still useful for average files, and least useful for thick files or for scoring models that downweight AU history. It is not a shortcut to an 800 credit score, and anyone who tells you it is — is selling you something. Use it as one tool in a broader credit-building strategy that includes opening and responsibly managing your own accounts over time.

Piggybacking and Paid Tradelines: The Scammy Side

This is the part of the authorized user conversation that gets shady, and we want to be direct about it because we’ve seen too many clients get burned.

What is “piggybacking” in the commercial sense?

In its innocent form, “piggybacking” just means being added as an authorized user to a family member’s card to build credit — exactly what we’ve been describing throughout this article. That’s legitimate.

In its commercial form, “piggybacking” refers to a for-profit industry where brokers sell authorized user slots on strangers’ credit card accounts. The arrangement works like this:

  • A person with a strong, old credit card agrees to sell authorized user slots on their account.
  • A broker connects that cardholder with buyers who want a credit boost.
  • The buyer is added as an authorized user (usually without ever receiving a card).
  • The account’s positive history reports on the buyer’s credit file.
  • After a billing cycle or two, the buyer is removed, and the slot is sold to the next customer.

Why it’s problematic

  • It may violate the cardholder’s agreement with the issuer. Most issuers prohibit using their cards for commercial arrangements like this. If caught, the cardholder’s account can be closed — which damages both the cardholder and every AU currently on the account.
  • It’s designed to game the credit scoring models. FICO has explicitly built abuse-detection logic to limit the effectiveness of this practice. A sudden burst of AU additions on a single account, especially with no apparent family relationship, can trigger the model to discount or ignore those AU tradelines.
  • The boost is temporary. Because the AU is removed after a short period, the benefit disappears as soon as the account stops reporting — unless the buyer is simultaneously building their own primary credit, the score will drift back down.
  • It’s expensive. Brokers typically charge hundreds to thousands of dollars per tradeline, for a benefit that may last only a billing cycle or two.
  • There are scams. Some tradeline brokers take payment and never add the buyer to any account. Others use stolen or synthetic identities to create the “primary” accounts being sold — which means the AU history on your report is tied to a fraudulent account that can collapse at any time, potentially dragging your score down or flagging you for fraud.

What we recommend

Don’t buy tradelines. If you want the benefit of authorized user status, do it the legitimate way:

  • Ask a trusted family member with a strong, old, clean credit card to add you as an authorized user. Most people are surprised at how willing a parent or spouse is to help when they understand it doesn’t put them at risk (as long as they don’t issue you a card).
  • Make sure the issuer reports AU accounts.
  • In parallel, start building your own primary credit — a secured card, a credit-builder loan, a student card, or a starter card from a bank you already have a relationship with. Your own accounts are the foundation; the AU account is a supplement, not a substitute.

If you’ve already bought tradelines and you’re worried about what’s on your credit report, pull your reports from all three bureaus and review them carefully. If you see accounts you don’t recognize, or accounts that look like they may be tied to a broker, consider working with an FCRA-compliant credit repair firm to dispute and remove them. Cleaning up the aftermath of a tradeline scheme can take time, but it’s absolutely possible.

A clear warning

Be especially skeptical of any company that guarantees a specific score increase from adding tradelines, that requires large upfront payments, or that pressures you to act quickly. These are classic signs of a credit repair scam. Under the federal Credit Repair Organizations Act (CROA), a legitimate credit repair company cannot charge you in advance for work that hasn’t been done, and cannot make guaranteed claims about outcomes.


Common Mistakes to Avoid

Over years of working with clients on credit repair and credit building, we see the same handful of authorized user mistakes over and over. Here are the most common — and how to avoid them.

1. Being added to the wrong account

Not all accounts are created equal. Being added to a card that’s two years old, carries a 60% utilization, and had a late payment last year will hurt you, not help you. Before you’re added, evaluate the account against the checklist in the “Choosing the Right Primary Cardholder” section above.

2. Not confirming the issuer reports AUs

This is the most common reason the strategy “doesn’t work.” You get added, you wait, you check your credit, and nothing has changed. Nine times out of ten, the issuer doesn’t report authorized users (or doesn’t report without an SSN on file). Confirm before you commit.

3. Being added to too many accounts at once

Adding multiple AU accounts in a short window can look suspicious to the scoring models — especially if the accounts have no apparent relationship to you. If you’re going to use the strategy, add one strong account and let it season. Adding three or four at once is more likely to trigger abuse-detection logic than to triple your benefit.

4. Issuing a card when you don’t need to

If the goal is credit building, the primary cardholder doesn’t need to give you a physical card. Not issuing a card eliminates essentially all the risk to the primary cardholder while preserving the credit-reporting benefit for you. If you do need a card for convenience (a spouse, a business partner), set spending limits and clear expectations.

5. Ignoring the account after you’re added

Credit reports aren’t set-and-forget. Once you’re an AU, the account affects your credit every month it reports. If the primary cardholder runs up the balance, misses a payment, or closes the account, your score can move — and not in a good direction. Monitor your credit and stay in communication with the primary cardholder.

6. Staying on an account that’s gone bad

If the primary cardholder starts missing payments or maxing out the card, remove yourself (by dispute with the bureaus if necessary) as soon as possible. Every month the account reports negatively is another month of damage. Don’t wait and hope it gets better.

7. Relying on AU status alone

Authorized user history is a supplement, not a foundation. If your entire credit file is AU accounts, your score is fragile — it depends entirely on someone else’s behavior, and lenders may discount it. Build your own primary accounts alongside the AU arrangement so that, over time, your credit stands on its own.

8. Buying tradelines

As discussed above, this is expensive, temporary, potentially fraudulent, and increasingly ineffective as scoring models get better at detecting it. Use the legitimate family version instead.

9. Forgetting to remove an AU after a relationship ends

If you go through a divorce, a breakup, or a family estrangement and you were the primary cardholder, remove the AU promptly. If you were the AU, get yourself removed (by dispute if necessary). Lingering AU connections after a relationship ends can lead to surprises — sometimes years later — when the primary cardholder’s behavior on the account shifts.

10. Expecting a guaranteed point increase

No legitimate credit professional can guarantee a specific score increase from an authorized user arrangement. The outcome depends on your full file, the specific account, and the scoring model. If someone promises you “50 points in 30 days” from becoming an AU, walk away.

Frequently Asked Questions

1. Does being an authorized user help your credit score?

It can, under the right conditions. If the card issuer reports authorized user accounts to the credit bureaus, and the primary account is in good standing (long history, no late payments, low utilization), the account’s positive history can appear on your credit report and improve your score. It helps most for people with thin or no credit history, and less for people who already have strong, established files. It does not help at all if the issuer doesn’t report AU accounts, or if the primary account has negative marks.

2. Will my credit be affected if the primary cardholder misses a payment?

Yes, potentially. If the issuer reports authorized user accounts, a late payment on the primary account can show up on your credit report as an authorized user and damage your score. This is the biggest risk of being an AU. If this happens, you can dispute the late payment with the credit bureaus (arguing that you were not the responsible party) or ask the primary cardholder to remove you from the account to stop future negative reporting.

3. Can I remove myself as an authorized user?

You generally can’t remove yourself through the card issuer directly — only the primary cardholder can do that. However, you can file a dispute with each of the three credit bureaus (EquifaxExperianTransUnion) requesting that the authorized user account be removed from your credit report. Because you have no legal responsibility for the debt, the bureaus will typically honor this request. This is a useful option if the primary cardholder is unavailable or uncooperative.

4. Do all credit card companies report authorized users to the credit bureaus?

No. Most major issuers do report authorized users, but practices vary — some issuers require a Social Security Number for the AU before reporting, some report to only one or two bureaus, and some don’t report AU accounts at all. Before relying on the strategy, call the issuer and ask specifically whether they report authorized users to all three bureaus and what information they require.

5. Does being an authorized user hurt your credit?

It can, if the primary account has problems. Late payments, high utilization, charge-offs, or collections on the primary account can appear on your credit report as an AU and lower your score. The strategy only helps when the primary account is in excellent standing. Being added to a problem account is worse than not being added at all.

6. How long does it take for an authorized user to show up on your credit report?

If the issuer reports AU accounts, you can usually expect the account to appear on your credit file within one to two billing cycles — typically 30 to 60 days after you’re added. If it hasn’t appeared after 60 days, confirm with the issuer that they’re reporting and that they have your correct identifying information (name, date of birth, SSN or ITIN).

7. Is buying authorized user tradelines safe or effective?

We don’t recommend it. Paid tradelines — where brokers sell AU slots on strangers’ credit cards — are expensive, the benefit is temporary, the practice may violate the cardholder’s agreement with the issuer, and the scoring models have built-in logic to detect and limit their effectiveness. Some tradeline operations are outright scams, and some involve fraudulent “primary” accounts that can collapse and damage your credit. The legitimate alternative is being added to a family member’s card, which is free, safe, and recognized by the scoring models.

8. What’s the difference between an authorized user and a co-signer?

An authorized user has no legal responsibility for the debt — they can use the card and may build credit from the account’s history, but the creditor cannot pursue them for the balance. A co-signer has full legal responsibility — if the primary borrower defaults, the co-signer can be pursued for the full balance, and the debt appears on the co-signer’s credit report with all the risk that entails. Co-signing is far riskier than adding an authorized user.

Ready to Take Control of Your Credit?

Being an authorized user is one useful tool in a broader credit-building strategy — but it’s not the whole strategy, and it works best when it’s part of a clear, compliant plan tailored to your specific situation.

If your credit report has errors, outdated negative items, or accounts that don’t belong there, those problems can undermine even the best authorized user arrangement. That’s where we come in.

At credit-repair.com, we help individuals and families across the country take control of their financial future through honest, attorney-backed, FCRA-compliant credit repair. We start with a free credit audit — a thorough review of your reports from all three major bureaus — to identify inaccuracies, disputable negative items, and opportunities to strengthen your file. From there, we build a customized plan tailored to your goals, with transparent pricing and no hidden fees.

No quick fixes. No empty promises. Just a clear path forward, guided by people who know the system and care about your outcome.

[Get your free credit audit at credit-repair.com →] (link placeholder to audit signup page)

Have questions about authorized users, credit building, or anything else on your credit report? We’re here to help you understand your options — no pressure, no obligation, just straightforward answers from a team that’s on your side.

Leave a Reply

Your email address will not be published. Required fields are marked *