
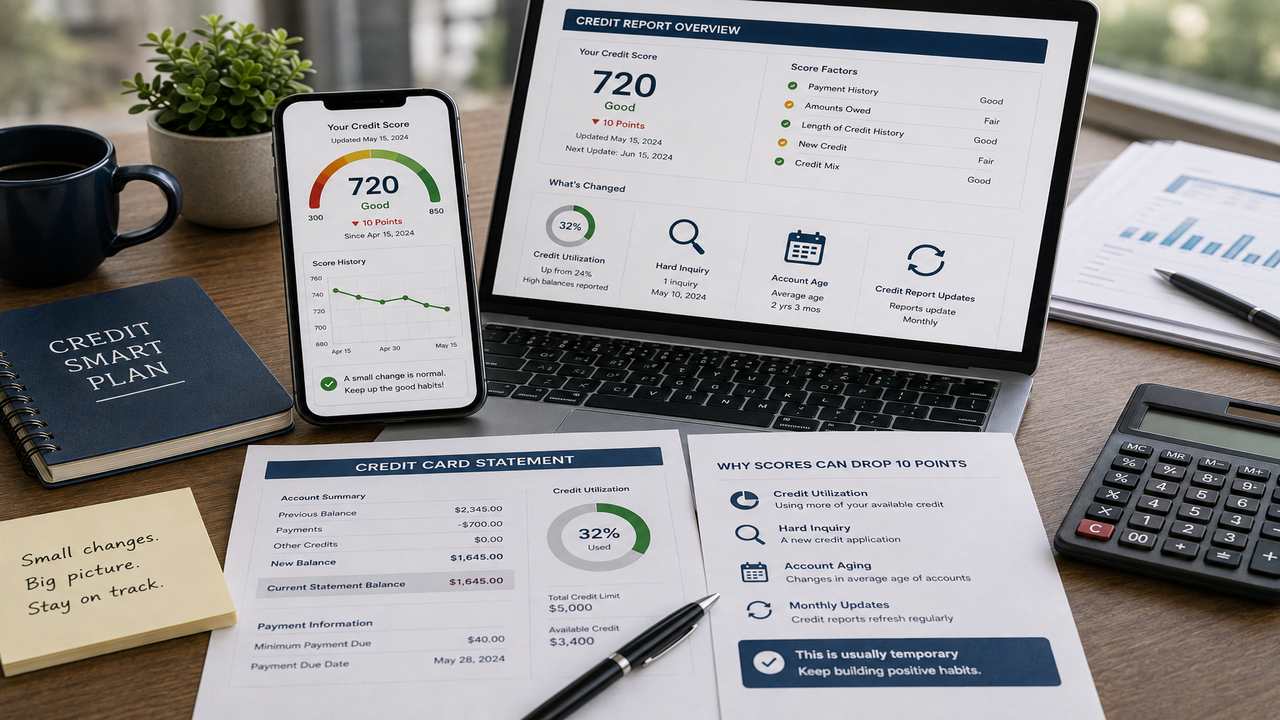
This guide walks through the specific causes behind a small score movement like this, how it differs from a larger drop, and when — if ever — it’s worth taking action.
Why 10 Points Is Genuinely a Small Move
Before diving into causes, it’s worth putting this in context. Credit scores routinely fluctuate by five to fifteen points from month to month as part of completely normal account activity — a slightly different reported balance, the natural aging of an account, or a small shift in how the scoring algorithm weighs your current file. A 10-point move sits squarely within this normal range of month-to-month variation, and by itself, it isn’t a signal that anything is meaningfully wrong with your credit management.
This is different from a 50-, 75-, or 100-point drop, which almost always indicates something more specific and worth investigating in detail — a missed payment, a new collection, or a significant utilization spike. A 10-point change is more often the accumulation of very minor factors, or a single mild one, rather than anything dramatic.
Common Causes of a Small, 10-Point Drop
A Modest Increase in Reported Utilization
Perhaps the single most common cause at this scale. If your card’s reported balance ticked up slightly from one statement to the next — even by a relatively small amount — your utilization ratio shifts accordingly, and a modest utilization increase produces a modest score effect. This is especially likely if the increase pushed your utilization across one of the general benchmark thresholds scoring models are believed to weigh somewhat more heavily around, such as moving from under 10% to somewhere in the 10-29% range, or from under 30% into the 30-49% range.
A Single New Hard Inquiry
While a new inquiry can sometimes cause a larger drop, especially on a thin credit file, for someone with a longer, more established credit history, a single new inquiry often produces an effect in this smaller range, since the scoring model has more existing data to weigh it against.
Normal Account Aging Effects
As your accounts age each month, the average age of your credit history shifts slightly, and if you have a mix of newer and older accounts, small month-to-month shifts in this average can contribute modestly to score movement, independent of anything specific you did.
A Minor Change in Your Number of Open Accounts
Opening a new account, even one you plan to manage perfectly, can temporarily lower your average account age and add a new hard inquiry, both modest factors that combine to produce a small overall dip even before that new account has a chance to demonstrate a positive payment history over time.
An Authorized-User Account’s Minor Change
If you’re an authorized user on someone else’s card, even a modest change on their end — a slightly higher balance one month, for instance — can produce a small ripple effect on your own score, since that account’s data flows into your file as well.
Scoring Model or Bureau Data Timing Differences
Sometimes what looks like a “drop” is actually a difference in timing between when different creditors report to different bureaus, or a difference between which specific scoring model version a particular app or lender is showing you. If you’re comparing scores from two different sources, a small discrepancy might not represent an actual change in your underlying file at all, but rather a difference in which data each source is pulling from and when.
How to Quickly Check Whether Anything Actually Changed
Look at your utilization first. This is the fastest and most common explanation to check — compare your current reported balances and limits against last month’s, on each individual card, not just your overall total.
Check for any new inquiries. Review the “hard inquiries” section of your credit report for anything in the past month you might not immediately connect to the score change.
Confirm no payments were missed or reported late. Even though a missed payment usually causes a larger drop than 10 points, it’s worth ruling out, especially if you have a shorter credit history where the impact of a single new negative item might be smaller relative to what a longer-established file would experience.
Check whether any account was closed, including one you closed yourself or one an issuer closed for inactivity, which reduces your total available credit and can modestly raise your utilization ratio.
When You Genuinely Don’t Need to Take Any Action
If your review above doesn’t turn up anything beyond routine utilization fluctuation, a single expected hard inquiry from something you applied for, or simple month-to-month variation with no clear single cause, there’s genuinely nothing that needs fixing. This is one of the more common and least alarming score movements you’ll experience, and it typically self-corrects, or simply becomes irrelevant as your file continues to build positive history over subsequent months.
When a Small Drop Is Actually Worth a Closer Look
If it’s part of a consistent, ongoing downward trend rather than an isolated single-month dip — several consecutive months of small declines can add up to something more meaningful and worth investigating for an underlying cause you might have missed, like a gradually increasing balance across several cards.
If you genuinely can’t identify any cause after reviewing your full report, particularly if you haven’t applied for anything, your balances look normal, and no accounts have changed — this is a reasonable trigger to check for a potential reporting error or, in rare cases, unauthorized account activity you haven’t otherwise noticed.
If it coincides with an important, time-sensitive application, such as a mortgage pre-approval you’re actively pursuing — even a small drop is worth understanding in that specific context, simply because you want full clarity on your file at a moment when precision matters more than usual.
A Practical Habit: Don’t Chase Every Small Fluctuation
One of the more counterproductive habits people develop with free credit monitoring apps is checking their score daily or even weekly and reacting emotionally to every small movement. Scores are dynamic, recalculating regularly as new data comes in, and normal daily life — spending on a credit card, a bill getting paid, a statement closing — will naturally produce small fluctuations that don’t reflect any meaningful change in your actual creditworthiness. A more useful habit is checking in on a monthly or quarterly basis, focusing on the overall trend over several months rather than any single data point, and reserving genuine investigation for either a larger, unexplained drop or a persistent multi-month downward trend.
What a 10-Point Drop Typically Does NOT Mean
It doesn’t mean you’re at meaningfully higher risk of loan denial, since a 10-point difference rarely crosses a lender’s specific approval threshold or interest-rate-tier boundary on its own, though it’s worth noting that being right at the edge of a tier boundary is one of the few scenarios where even a small difference could matter practically.
It doesn’t mean something is fundamentally wrong with your credit habits. As covered throughout this guide, this scale of movement is well within the range of completely normal, expected monthly variation.
It doesn’t require you to take on debt or change your spending to “fix” it, since in the vast majority of cases there’s nothing broken that needs fixing — the fluctuation is simply how the scoring system naturally responds to routine account activity.
Frequently Asked Questions
Should I be more worried about a 10-point drop if my score is already excellent (800+)?
Not particularly — in fact, scores at the very top of the range can sometimes show slightly more relative movement from small changes, simply because there’s more room within the highest tiers for minor factors to shift the number around, without any real change in your underlying creditworthiness or lending risk.
Can a 10-point drop happen with no changes to my credit report at all?
It’s uncommon but not impossible, particularly if you’re comparing scores calculated by different scoring models or pulled at slightly different times relative to when various creditors report their monthly updates — in these cases the “drop” may partly reflect differences in measurement rather than an actual change in the underlying data.
How quickly does a 10-point drop typically recover?
Usually within one to two billing cycles if it’s tied to a temporary utilization increase, and often faster than that if it was simply a timing artifact rather than a genuine account change. A hard inquiry’s small effect fades gradually over several months and disappears from scoring entirely after 12 months.
Is it worth disputing anything for just a 10-point difference?
Only if you find a genuine inaccuracy while reviewing your report — the size of the score impact shouldn’t be the deciding factor in whether to dispute an error; accuracy on your report matters regardless of how many points are currently at stake, since an uncorrected error could compound or resurface in a more consequential way later.
Does closing an unused credit card that I never use cause this kind of small drop?
Yes, this is a very plausible and common cause — closing a card, even one you rarely use, reduces your total available credit, which increases your overall utilization ratio proportionally, even without any change to your actual spending.
Comparing Score Drops by Severity
| Drop size | Typical cause(s) | Action needed? |
|---|---|---|
| 1-15 points | Routine utilization shift, single inquiry, normal monthly variation | Usually none |
| 15-30 points | New inquiry on a thinner file, moderate utilization jump, single late payment on a strong file | Review report, monitor next cycle |
| 30-60 points | Missed payment, new collection, significant utilization spike, closed major account | Investigate specific cause and address it |
| 60-100+ points | Charge-off, bankruptcy filing, multiple missed payments, identity theft | Immediate investigation, likely dispute or hardship action needed |
This table is illustrative rather than a precise formula — actual point impacts vary by scoring model, your existing file thickness, and the specific combination of factors at play — but it’s a useful mental framework for calibrating how seriously to treat any given drop.
Why File Thickness Changes How Much Any Single Factor Moves Your Score
One of the more counterintuitive aspects of credit scoring is that the same event can produce very different point impacts depending on how much existing history you have. Someone with a thin file — a year or two of credit history and only one or two accounts — will typically see larger swings from any single new event (an inquiry, a new account, a modest utilization change) because that new data represents a much larger proportion of their total available information. Someone with a thick file — a decade or more of history across several account types — has enough existing data that any single new event gets “diluted” across a much larger overall picture, typically producing smaller point movements for the same type of event.
This is part of why a 10-point drop is more likely to represent something genuinely minor for someone with an established, longer credit history, while the same numerical drop might represent a comparatively more significant proportional event for someone still early in building their file. If you’re relatively new to credit, it’s worth keeping this in mind — the same explanations apply, but the relative significance of a 10-point move for you might be slightly different than it would be for someone with 15 years of credit history.
A Look at How Monitoring Tools Can Create Confusion
Many people track their credit through more than one free source: their bank’s app, a card issuer’s provided score, and perhaps a dedicated credit monitoring service. It’s extremely common for these different sources to show slightly different scores at any given time, and slightly different month-to-month changes, for a few structural reasons:
They may pull from different bureaus. One service might show your Experian-based score while another shows TransUnion, and since not every creditor reports identically or simultaneously to every bureau, the underlying data can differ.
They may use different scoring models. A VantageScore 3.0 score and a FICO 8 score, even calculated from identical underlying data, can produce different numbers and react somewhat differently to the same changes, since the two models weight certain factors differently.
They update on different schedules. Some services refresh weekly, others monthly, and the specific day of the month a given app checks in relative to when your creditors report their monthly updates can create the appearance of a “sudden” change that’s really just catching up to information that changed gradually or was already reflected elsewhere.
If you’re seeing conflicting information about a small score change across different apps, it’s more productive to focus on your actual credit report details (which are consistent, factual data) rather than trying to reconcile exactly why two different scoring apps show slightly different numbers or timing.
A Broader Perspective on What Actually Matters for Your Financial Life
It’s worth zooming out from any single month’s score movement to what actually determines your access to good credit terms over time: a consistent, multi-year pattern of on-time payments, reasonably low utilization, and a mix of account types managed responsibly. Lenders evaluating a mortgage, auto loan, or major credit line application are looking at this broader pattern, not obsessing over whether your score was 3 points higher or lower in any particular month along the way. Building genuinely good financial habits — the kind that show up consistently in your credit report over years — matters enormously more than reacting to or trying to optimize away every small, routine fluctuation your score naturally goes through as part of ordinary account activity.
Frequently Asked Questions, Continued
Does my score drop by a predictable amount every time I apply for something?
No — the exact point impact of any single hard inquiry varies based on your overall file, how many other recent inquiries you have, and which specific scoring model is being used to calculate the score you’re viewing. There’s no single fixed number that applies universally to every person and every application.
If I see a 10-point drop right after paying off a loan in full, is that expected?
Yes, this is a known and reasonably common pattern. Paying off and closing an installment loan (like a car loan reaching its final payment) can modestly reduce your credit mix diversity and, if it was an older account, eventually affect your average account age once it fully drops off your report — both minor factors that can produce a small score dip even though paying off debt is, in every practical sense, a positive financial achievement.
Will a small score drop like this affect my credit card’s advertised interest rate on an existing account?
Generally no — a modest score change on an existing account doesn’t typically trigger an automatic interest rate change on that specific account (rates are usually governed by your account agreement and broader market rate changes, not minute-to-minute score fluctuations), though a larger, more sustained decline could factor into a card issuer’s periodic account reviews.
Is there a way to prevent this type of small monthly fluctuation entirely?
Not entirely, since some fluctuation is a structural feature of how scoring models work with dynamically updating credit report data, not a flaw to be eliminated. You can minimize the more controllable contributors — keeping utilization consistently low and stable, spacing out credit applications, and maintaining long-term account relationships — but some degree of natural month-to-month variation is a normal and expected part of having an active credit file.
A Step-by-Step Diagnostic Process
If you want to be thorough rather than just accepting “it’s probably nothing,” here’s a simple process to work through in about ten minutes:
Step one: Pull your current full credit report, not just the score, from whichever bureau your monitoring service is showing you.
Free reports are available from all three bureaus at AnnualCreditReport.com.
Step two: List your open accounts and their current reported balances and limits.
Calculate your overall utilization percentage and compare it mentally to what you’d estimate it was last month based on your typical spending pattern.
Step three: Check the hard inquiries section for anything within the last month you might have forgotten about.
Sometimes even a phone carrier upgrade, a new insurance policy, or a rental application triggers one without you necessarily connecting it immediately to “applying for credit.”
Step four: Review the payment status of every account to confirm everything shows current and on-time.
Rule out a late payment as the cause.
Step five: Check for any new accounts, closed accounts, or newly appearing collection entries you don’t immediately recognize.
Step six: If everything checks out normal, conclude confidently that this is routine fluctuation and move on without further concern.
If something looks genuinely unfamiliar — an account you don’t recognize, an inquiry from a company you’ve never interacted with — treat that specific item as a possible identity theft indicator and consider a fraud alert or credit freeze as a precaution, even though the score drop itself is small.
Understanding Your Personal Baseline Range
Everyone’s credit file has a certain amount of natural “bounce” around a central trend, and getting familiar with your own typical range makes future fluctuations far less anxiety-inducing. If you check your score consistently for a few months and notice it typically moves within a 15-20 point band during ordinary financial activity, then a future 10-point dip immediately reads as unremarkable, comfortably within your established normal range, rather than as an unknown, alarming event each time it happens. This kind of personal calibration is one of the most underrated tools for maintaining a healthy, non-anxious relationship with credit monitoring over the long run.
What Credit Bureaus and Scoring Companies Say About Normal Variation
Both FICO and VantageScore, along with all three major credit bureaus, publicly acknowledge that scores naturally fluctuate as part of normal, ongoing credit report updates, and none of them position small movements as inherently meaningful signals requiring consumer action. This industry-wide acknowledgment reflects the underlying mathematical reality of how these models work: they’re recalculated fresh each time new data is available, based on a snapshot of your file at that moment, and any change to that underlying data — even a small, routine one — will produce some corresponding change in the calculated output. This is simply how a dynamic, continuously updated scoring system is designed to function, not a flaw or a cause for concern at this scale.
Frequently Asked Questions, Continued Further
Does my score typically fluctuate more right after I pay off my full statement balance?
It can, in either direction depending on timing — paying off your full balance generally lowers your reported utilization once your next statement closes with the reduced balance, which would be a positive contributor rather than a cause for a drop. If you see a drop right after paying off a balance, it’s more likely coincidental with some other factor (a new inquiry, another account’s balance shift) happening around the same time, rather than caused by the payoff itself.
Can weather or economic news affect my personal credit score?
No — your individual credit score is calculated entirely from your own personal credit report data. Broader economic conditions, interest rate changes, or news events have no direct mechanical effect on your individual score calculation, though they can indirectly affect things like available credit offers or interest rates lenders choose to offer, which is a separate matter from your score itself.
Is a 10-point drop more concerning right before a big purchase like a car?
Timing matters more for practical reasons than for the size of the drop itself — if you’re actively planning a major purchase requiring financing, it’s worth doing the quick diagnostic check above simply for peace of mind and to rule out anything that might affect your application, even though a 10-point difference is unlikely to change your approval odds or rate tier in most cases.
The Bottom Line
A 10-point credit score drop is one of the least concerning score movements you’re likely to encounter, almost always attributable to routine causes like a modest utilization shift, a single hard inquiry, or normal account aging. In the vast majority of cases, no action is needed — the fluctuation naturally resolves as your account activity continues. The one habit worth building is checking your full credit report periodically, so that if something more significant ever does happen, you’re already familiar with what a normal, unremarkable fluctuation looks like and can recognize a genuine issue when it appears by contrast.
Need Help Reviewing Your Credit?
If you’re concerned about an unexpected credit score change and want to review your credit reports for inaccurate or negative information, you can request a credit audit or quote.