
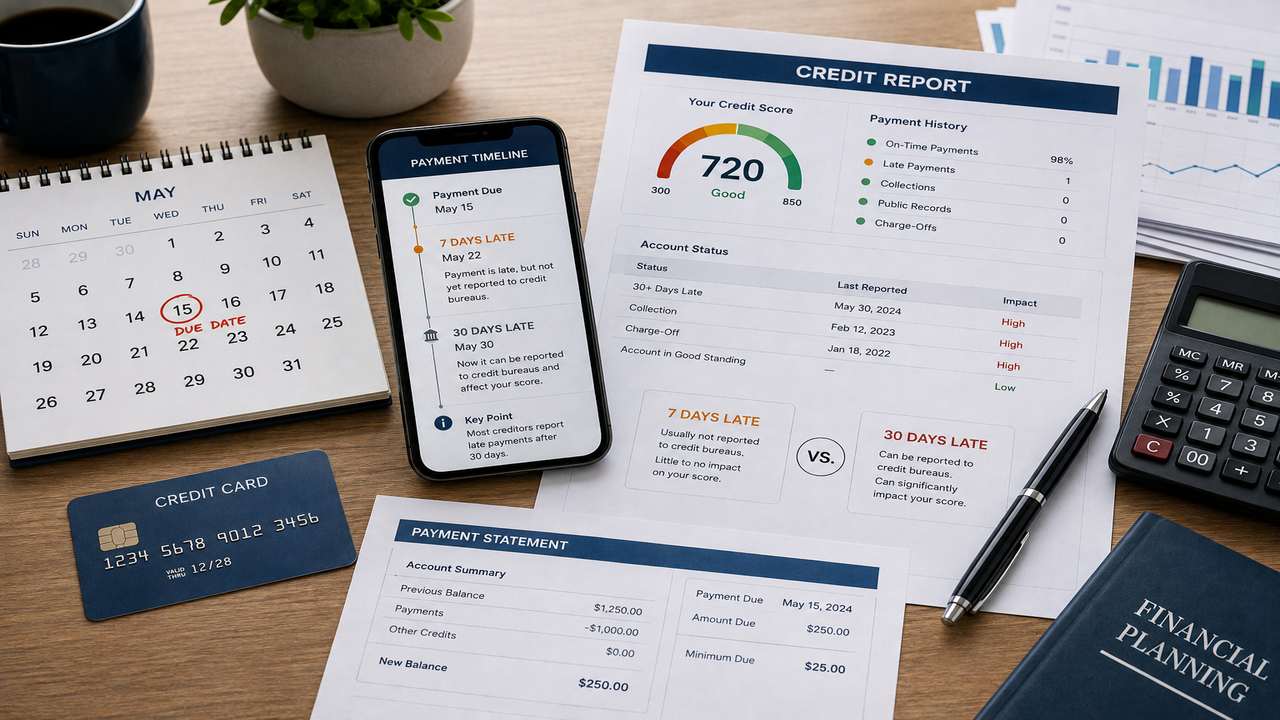
This guide explains exactly how late payment reporting works, why the 30-day mark is the real threshold that matters, what does happen during that first week even if your score is unaffected, and the specific situations where a short delay can still cause a problem.
The 30-Day Rule: Why It’s the Number That Actually Matters
Credit card companies, mortgage servicers, auto lenders, and virtually all other creditors that report to the major credit bureaus (Equifax, Experian, and TransUnion) follow a standard convention: a payment isn’t reported as “late” to the bureaus until it’s at least 30 days past the due date. This isn’t just an industry courtesy — it’s baked into how the reporting fields in the credit bureau data systems (following the Metro 2 reporting format used industry-wide) are structured, with late payment statuses defined in 30-day increments: 30, 60, 90, 120+ days past due.
This means a payment made 7 days late, while genuinely late from your creditor’s internal perspective, falls well short of the threshold that triggers a report to the credit bureaus. In the vast majority of cases, a payment made within that first 30-day window — even if it’s technically past the stated due date — will not appear on your credit report as a late payment at all, and will have zero effect on your credit score.
What Actually Happens During Those First 7 Days, Even If Your Score Is Safe
Even though your score is very likely unaffected, a payment that’s a week late isn’t consequence-free. Here’s what’s actually happening behind the scenes with most creditors during that window:
A late fee is typically charged, often in the range of $25 to $40 for credit cards, though this varies by issuer and is subject to certain regulatory caps under the CARD Act for credit cards specifically. Other loan types (mortgages, auto loans, personal loans) have their own late fee structures defined in your original loan agreement.
Your interest rate could be affected on some credit cards. Many credit card agreements include an “penalty APR” clause that can be triggered once a payment is 60 days late (again, past the 30-day reporting threshold, but worth knowing the escalation path), so a single 7-day late payment alone typically won’t trigger this, but it’s a reminder of what’s at stake if a short delay turns into a longer one.
Your grace period for new purchases may be affected. If you’re carrying a balance and miss your due date, even briefly, some card issuers will begin charging interest on new purchases immediately rather than extending the usual grace period, until you’ve paid your balance in full again.
Internal account flags may be set. Even if nothing reaches the credit bureaus, your creditor’s internal system now shows a late payment on your account history with them specifically, which they can reference for their own purposes — such as evaluating you for a credit limit increase, a retention offer, or future account decisions — even though this internal note isn’t visible to other lenders or reflected in your credit score.
When a 7-Day Late Payment CAN Still Cause a Problem
While the 30-day reporting threshold covers the vast majority of situations, there are a few specific scenarios where a short delay can still matter:
If it happens repeatedly
A pattern of consistently paying a few days late, even if each individual instance stays under the 30-day reporting threshold, can eventually lead a creditor to take other actions — closing your account for risk management reasons, declining to extend a credit limit increase, or, in some subscription or utility contexts, canceling the service — even without any single late payment ever reaching your credit report.
If your specific due date and the 30-day window overlap in an unusual way
In rare cases involving certain loan servicers or unusual billing cycles, the exact timing of when a “30 days late” status gets calculated and reported can vary slightly. If you’re right at the edge of that window due to a payment processing delay, a mailed check, or a bank transfer that took longer than expected, it’s worth confirming directly with your creditor exactly when your account will be considered officially delinquent for reporting purposes, rather than assuming the standard convention applies exactly.
If it’s a rent payment, and your landlord uses rent-reporting
Some landlords and property managers use services that report rent payments to the credit bureaus, and these services don’t always follow the same 30-day convention as traditional lenders — some report payment timeliness on a more granular basis. If your lease specifies rent reporting, it’s worth checking the specific service’s policy on late payment reporting thresholds.
If your account was already delinquent from a previous missed payment
If a 7-day-late payment is actually the second consecutive missed payment on an account where the first one was never fully caught up, the cumulative delinquency could already be approaching or past the 30-day mark from the original missed due date, in which case the “7 days late” framing understates how far behind the account actually is.
Certain non-traditional or specialty lenders may report differently
Some smaller lenders, certain buy-now-pay-later services, or specialty financing products don’t always follow the standard Metro 2 reporting conventions used by major banks and credit unions, and some report payment status on a more frequent or different schedule. If you’re using a newer or less traditional lending product, it’s worth directly confirming their specific reporting practices rather than assuming the standard 30-day rule applies.
What to Do If You’re About to Be a Few Days Late
Contact your creditor before the due date if you already know you’ll be late. Many creditors, especially for a customer with an otherwise good payment history, will work with you — extending the due date slightly, waiving the late fee, or at minimum confirming exactly when a payment would need to post to avoid any issue.
Make the payment as soon as possible, even if it’s already past the due date. The sooner you pay, the sooner any grace period effects or reporting risk resolve, and this also minimizes any additional late fees or interest that might accrue with additional delay.
Set up autopay for at least the minimum payment going forward, even if you prefer to manually pay in full each month. This creates a safety net so that a forgotten manual payment doesn’t accidentally cross the 30-day threshold due to being overlooked for weeks rather than days.
Double check whether your specific creditor’s grace period differs from the standard. While 30 days is the near-universal convention for credit bureau reporting, individual account-level grace periods (for late fees, interest, or promotional rate forfeiture) can be shorter, and it’s worth knowing your specific account’s terms, usually found in your cardholder agreement or loan documents.
If You Discover a 7-Day-Late Payment Was Incorrectly Reported
Although rare, reporting errors do happen — a creditor’s system glitch, a misapplied payment, or an administrative mistake can occasionally result in a payment being reported as late to the credit bureaus even when it was actually made within the standard grace window. If you find what you believe is an inaccurately reported late payment on your credit report:
Gather your proof first
Bank statements, payment confirmations, or screenshots showing the exact date and time your payment was made or posted are essential for a successful dispute.
Contact the creditor directly before filing a formal dispute
Many disputes can be resolved faster by calling the creditor’s customer service line directly, explaining the discrepancy, and asking them to correct their reporting to the bureaus — this is often faster than the formal bureau dispute process, though it doesn’t replace your right to file a formal dispute if the creditor doesn’t cooperate.
File a formal dispute with the credit bureau if needed
If the creditor won’t correct an error you can document, file a dispute directly with whichever bureau (or bureaus) shows the incorrect information, including your supporting documentation. Under the FCRA, the bureau is required to investigate, typically within 30 days.
How to Think About the Distinction Between “Late” and “Reported Late”
It’s worth internalizing this distinction clearly, since it resolves a lot of unnecessary anxiety: being “late” in the everyday sense — missing your stated due date by any amount of time — has real consequences (fees, interest, and potentially account-level flags with that specific creditor), but it is meaningfully different from being “reported late” to the credit bureaus, which is the thing that actually affects your credit score and appears on your report for other lenders to see. A short delay puts you in the first category without typically crossing into the second, but treating the two as identical leads either to unnecessary panic over a minor delay, or, in the opposite direction, to complacency about repeatedly paying just a few days late without recognizing the compounding fee costs and creditor-relationship risk that come with it, even absent any credit score impact.
Frequently Asked Questions
Will a 7-day late payment show up if I check my credit report immediately?
No, assuming your creditor follows the standard 30-day reporting convention, a payment made within that window — even after the due date — won’t generate a late payment entry on your report at all, regardless of when you check.
Does this apply to mortgages the same way it applies to credit cards?
Generally yes, mortgage servicers also follow the standard 30-day reporting convention for credit bureau purposes, though mortgage late fees and specific account-level consequences (which can include escalating notices well before the 30-day mark) are governed by your specific loan agreement and can differ from credit card terms.
If I’m late by 7 days every single month, will that eventually catch up with my score?
Not through credit bureau reporting directly, as long as each individual instance stays under 30 days. However, a consistent pattern like this carries real risk of other consequences — a creditor closing your account, declining future credit limit increases, or in some cases reporting the account differently if they determine the pattern represents a heightened risk, so it’s worth addressing the underlying cause of consistently paying late even if your score isn’t directly affected yet.
What’s the safest number of days to consider a hard deadline?
Given the standard is 30 days, but grace periods, fees, and account-specific terms all vary, a reasonable personal rule of thumb is to treat any missed due date as requiring payment within a few days at most, both to avoid unnecessary fees and interest, and to build in a safety margin against any variation in how a specific creditor calculates and reports delinquency.
Can a 7-day late payment affect a mortgage application I’m currently in the middle of?
If it doesn’t get reported to the credit bureaus, it generally won’t show up on a credit report pulled during underwriting. However, some mortgage lenders request recent bank statements as part of underwriting, and a pattern of late payments or overdrafts visible in those statements (separate from your credit report) could still raise questions during the underwriting process, even without a formal late payment report.
How Different Types of Accounts Handle a Short Delay
| Account type | Credit bureau reporting threshold | Late fee risk in first 7 days | Other early consequences |
|---|---|---|---|
| Credit card | 30 days (standard) | High — often charged after just 1 day late | Grace period on new purchases may be lost |
| Mortgage | 30 days (standard) | Varies by servicer, often after a short window (commonly 10-15 days per loan terms) | Servicer may send early notices well before 30 days |
| Auto loan | 30 days (standard) | Varies by lender, sometimes after just a few days | Some loans allow repossession proceedings to begin surprisingly early per contract terms, even without credit reporting yet |
| Personal loan | 30 days (standard) | Varies by lender agreement | Some online lenders use non-standard reporting schedules — worth confirming directly |
| Rent (if reported) | Varies by rent-reporting service | Governed by lease terms and state/local law | Some services report more granularly than the standard 30-day convention |
| Student loans (federal) | 90 days for federal loans specifically | Grace period varies by loan type | Federal loans have a notably longer reporting grace period than most other credit types |
This table highlights something important: federal student loans are a notable exception to the general 30-day rule, with a longer 90-day window before being reported as delinquent to the credit bureaus. This doesn’t mean a short delay on a federal student loan is risk-free — interest continues accruing and other consequences can apply — but it does mean the credit-reporting risk specifically is even more limited than with most other account types.
Understanding What “Day One” of Lateness Actually Means
A subtle point that trips people up: your due date itself is not a late day. If your payment is due on the 15th, a payment made on the 15th is on time, and a payment made on the 16th is one day late — not the “first day of your grace period” in some interpretations, but genuinely one day past due from your creditor’s perspective, even though (as covered above) it won’t be reported to the credit bureaus until it reaches 30 days past that due date. Some people mistakenly believe there’s an automatic few-day cushion built into every due date; while some individual account terms do include an explicit grace period for fees specifically (common with mortgages, for example, which often have a 10-to-15-day grace period before a late fee is charged, separate from the 30-day credit bureau threshold), this isn’t universal, and it’s worth checking your specific account terms rather than assuming a cushion exists.
A Practical Autopay Setup Guide to Prevent This Entirely
Given how much of the risk here comes down to timing rather than an inability to pay, setting up a reliable autopay system is one of the highest-value, lowest-effort things you can do. A few specifics worth getting right:
- Choose “pay in full” rather than “minimum payment only” if your cash flow reliably supports it. This avoids carrying a balance and paying interest, while still providing the safety net against a missed due date.
- If your income is variable, consider autopay for the minimum payment only, with manual additional payments when you have extra funds. This ensures you never technically miss a due date (avoiding the fee and reporting risk entirely) while giving you flexibility on the rest.
- Verify your payment method on file is current, especially before it expires. An expired card or a closed bank account linked to autopay is one of the most common reasons a payment silently fails despite autopay being “set up,” precisely the kind of surprise that can turn into an unintentional multi-week delay if you’re not checking your statements regularly.
- Set a backup calendar reminder a few days before each due date anyway. Autopay failures do happen — due to a bank processing delay, an issuer’s system error, or an account status change — and a simple manual check a few days early catches this before it becomes a genuine problem.
- Consider aligning due dates across multiple accounts to a schedule that matches your pay cycle. Many creditors will let you request a specific due date; aligning several bills to fall shortly after payday reduces the chance of a payment failing due to insufficient funds at the moment it’s scheduled.
What a Short Late Payment Does to Your Relationship With a Creditor, Beyond the Score
Even when your credit score is completely unaffected, it’s worth remembering that your creditor’s internal records are a separate thing entirely, and they do track your payment behavior over time for their own purposes. A card issuer deciding whether to offer you a credit limit increase, a lower interest rate, or a retention bonus when you consider closing an account will often reference their own internal history with you — which does include every late payment, regardless of whether it was ever reported to the bureaus. This is a good reason to treat on-time payment as a broader habit worth maintaining consistently, not simply a box to check only when the credit-bureau reporting threshold is at stake.
Frequently Asked Questions, Continued
Does a 7-day late payment affect my ability to get a new credit card while it’s outstanding?
If it isn’t reported to the credit bureaus (the typical case), it won’t appear on the credit report a new card issuer would review, so it generally wouldn’t affect a new application. If the payment is still outstanding at the time you apply, though, it’s better practice to resolve it first regardless, both for the late fee and to keep your account in good standing with your existing creditor.
If I pay 7 days late but the creditor charges a late fee, does that fee itself ever get reported to credit bureaus?
No, fees themselves aren’t reported as a line item to credit bureaus. What matters for reporting purposes is your payment status (on time vs. a specific number of days past due), not fees assessed on the account.
Can a creditor choose to report a late payment sooner than 30 days if they want to?
While the 30-day convention is a strong industry norm tied to the standardized Metro 2 reporting format, technically nothing legally requires every creditor to use exactly that threshold. In practice, virtually all major banks, credit unions, and mainstream lenders follow it, but it’s worth being aware that a small number of alternative or non-traditional lenders could theoretically report differently, which is why checking your specific creditor’s stated policy is a reasonable extra precaution if you’re ever genuinely unsure.
Is there a difference between “late” and “past due” on my account statement?
These terms are often used interchangeably by creditors and generally mean the same thing: a payment hasn’t been received by the stated due date. Neither term on its own indicates whether the account has crossed the 30-day credit-bureau reporting threshold — you’d need to check the specific number of days past due to know that.
Why This Reporting Standard Exists in the First Place
It’s worth understanding the reasoning behind the 30-day convention, since it isn’t arbitrary. Credit reporting exists to help lenders assess long-term repayment reliability, not to penalize every minor timing slip a person makes in daily financial life. Bills get missed for all kinds of ordinary reasons — a bank holiday delaying a transfer, a forgotten due date during a busy week, a temporary mail delay for a paper check — that have little to do with someone’s actual ability or willingness to repay debt. A reporting standard that flagged every single-day delay would generate enormous noise in the credit system and would punish minor administrative slip-ups as harshly as genuine payment difficulty, making credit scores far less useful as a signal of real risk.
The 30-day threshold represents an industry-wide judgment that a delay of less than a month is common enough, and generally recoverable enough, that it doesn’t yet indicate meaningful credit risk on its own. Once a payment crosses that threshold, it starts to represent a more genuine signal — the person either can’t currently pay, is actively avoiding payment, or has lost track of the obligation entirely — which is the kind of information a future lender genuinely benefits from knowing about.
A Note on Buy Now, Pay Later Services
Buy Now, Pay Later (BNPL) services like Klarna, Afterpay, and Affirm have grown enormously in recent years, and their credit reporting practices are still evolving and vary significantly between providers. Some BNPL providers don’t report to the major credit bureaus at all under normal circumstances, only doing so if an account becomes seriously delinquent or is sent to collections. Others have begun reporting more routinely, including for on-time payments, as the industry moves toward more standardized practices. If you use these services regularly, it’s worth checking the specific provider’s current reporting policy directly, since the general 30-day guidance for traditional credit doesn’t necessarily map cleanly onto every BNPL provider’s practices, and this is an area where policies have been changing faster than most other parts of consumer credit reporting.
Frequently Asked Questions, Continued Further
Does my bank see a late payment on my checking account the same way a credit late payment works?
No — an overdraft or low balance on a checking account is an entirely separate matter from credit reporting and doesn’t follow the same 30-day convention. Overdrafts are typically tracked through a different system (sometimes ChexSystems, used for banking history rather than credit history) and can affect your ability to open new bank accounts, separate from your credit score.
If I’m 7 days late on one card but current on all my others, does that isolated instance affect my overall creditworthiness in any lender’s eyes?
Since it’s very unlikely to be reported to the credit bureaus, it generally won’t be visible to other lenders reviewing your credit report. The one exception is if that specific creditor is later asked directly by another party (which is uncommon) or if you disclose it yourself during an application process that asks about your payment history in detail.
Can I ask my creditor to simply not report this if it does end up crossing 30 days?
In rare cases, particularly for a longtime customer with an excellent payment history and a clearly explainable one-time circumstance (a documented medical emergency, for example), some creditors will agree to a “goodwill” non-reporting or later removal of an isolated late payment, though this is entirely at their discretion and not something you’re legally entitled to request.
The Bottom Line
A payment that’s seven days late almost always falls safely under the 30-day threshold that triggers credit bureau reporting, meaning your credit score is very unlikely to be directly affected. That said, late fees, potential interest rate consequences, and the risk of an escalating pattern with your creditor are all real considerations even when your score is untouched. The safest approach is simple: treat every due date as a genuine deadline, set up autopay as a backstop, and if you do end up a few days late, pay as soon as possible and don’t hesitate to contact your creditor proactively if you know a delay is coming.
Get a Credit Audit
If you’re dealing with a late payment or want to review your credit reports for inaccurate or negative information, you can request a credit audit or quote.