
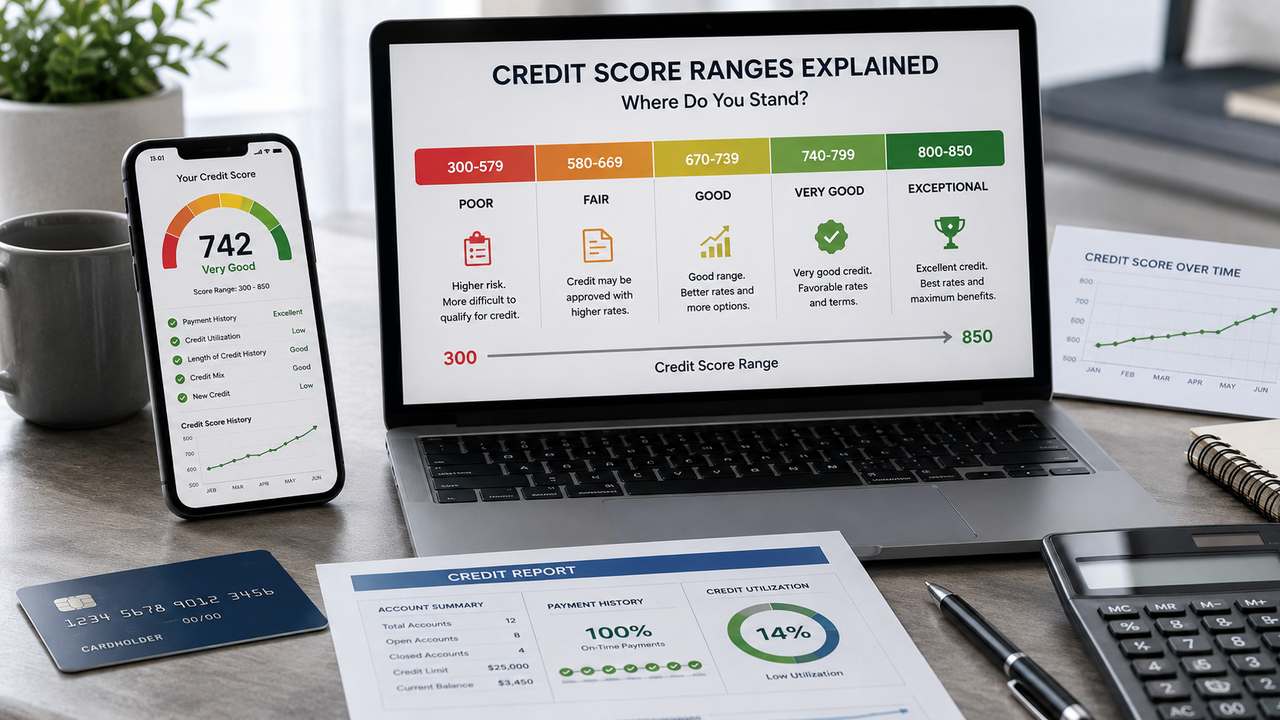
That knowledge gap is costly. A score in the fair credit range instead of the good credit range can add tens of thousands of dollars in extra interest over the life of a mortgage. A score in the poor credit range can keep you from being approved at all. The good news is that credit scores are not fixed stars. They move in response to how you manage credit, and understanding the ranges is the first step to moving yours in the right direction.
This guide breaks down the credit score ranges for both major scoring models in the United States — FICO and VantageScore — explains what each tier means for your wallet, and gives you a practical, tier-by-tier plan for climbing higher. We keep things honest: no “secret tricks,” no overnight-fix promises. What you will get instead is the transparent, legally grounded guidance we give every client at our San Diego-based, FCRA-compliant, attorney-backed credit repair firm.
What Credit Score Ranges Are
A credit score range is the spread of possible numerical values a scoring model can assign to a consumer, divided into named bands or credit score tiers. Each tier corresponds to a level of credit risk: the higher the score, the lower the perceived risk to a lender, and the better the terms you are likely to be offered.
Think of a credit score range as a ladder. The bottom rung represents the highest risk and the worst borrowing terms; the top rung represents the lowest risk and the best terms. Most consumers land somewhere in the middle, which is why the “good” and “fair” tiers get so much attention — they are where the majority of Americans live, and they are also where the most dramatic improvement is usually possible.
Why do ranges matter? Because lenders rarely quote a single interest rate to everyone. They price risk. A borrower in the excellent credit range might qualify for a 6.5% APR on a personal loan, while a borrower in the fair range might be quoted 15% or higher for the exact same loan from the exact same lender. Over a five-year repayment, that gap can mean thousands of dollars.
Ranges also matter because they set the mental benchmarks consumers use when setting goals. “I want to hit 700” is a common target because 700 sits solidly in the good tier for most models and unlocks meaningfully better offers. “I just need to get above 620” is another common goal because 620 is the rough threshold many mortgage lenders use for conventional loan eligibility. Knowing the ranges helps you set a goal that is tied to a real-world outcome, not just an arbitrary number.
The Basic Structure of a Credit Score Range
Both major U.S. scoring models use a 300 to 850 scale for their general-purpose scores. That means the lowest possible score is 300 and the highest is 850. Within that span, each model defines its own tier cut-offs:
- Poor (or Very Poor / Deep Subprime)
- Fair (or Subprime)
- Good (or Prime)
- Very Good (or Superprime, in VantageScore terminology)
- Exceptional (or Excellent)
The exact numerical boundaries differ slightly between FICO and VantageScore, which is why we cover each separately below. Some industry-specific scores (auto, bankcard) use different scales, which we address in the industry-specific section.
Why Two Models Exist
The credit scoring industry is dominated by two competitors. FICO (developed by the Fair Isaac Corporation) is the older and more widely used model, especially in mortgage lending. VantageScore (developed jointly by the three major credit bureaus — Equifax, Experian, and TransUnion) is newer and is often the score you see in free credit-monitoring apps and on credit card statements.
Because the two models weigh factors slightly differently and sometimes use different tier boundaries, a consumer can have a FICO score of 712 (good) and a VantageScore of 698 (also good, but on a different boundary). Both are “real” scores; neither is more correct than the other. What matters is knowing which model a given lender uses — and understanding the ranges for both.
The Two Main Scoring Models: FICO and VantageScore
Before we get into the tier-by-tier breakdown, it helps to understand how each model is built. The ranges are only meaningful once you know what moves the number inside them.
FICO: The Mortgage Standard
FICO is the scoring model you will encounter most often in high-stakes lending. When you apply for a conventional mortgage, a FHA loan, an auto loan, or a new credit card, there is a strong chance the lender is pulling a FICO score — often a specific FICO variant tailored to that product.
FICO’s base scoring factors (roughly weighted):
- Payment history — 35%: whether you have paid past credit accounts on time. This is the single biggest lever.
- Amounts owed — 30%: how much of your available credit you are using, especially revolving credit. This is your credit utilization ratio.
- Length of credit history — 15%: how long your accounts have been open, including the age of your oldest account and the average age of all accounts.
- Credit mix — 10%: the variety of account types you manage (revolving, installment, mortgage).
- New credit — 10%: how many recent inquiries and new accounts you have. Too many in a short window signals risk.
FICO updates its models periodically (FICO 8, FICO 9, and the newer FICO 10/T are all in circulation), but the 300–850 scale and the five-tier structure have remained stable across recent generations.
VantageScore: The Bureau-Built Alternative
VantageScore was created by the three credit bureaus to compete with FICO and to produce a score even when a consumer has a thinner credit file. The current generation in wide use is VantageScore 4.0, which also uses the 300–850 scale.
VantageScore’s scoring factors (roughly weighted):
- Payment history — ~40%: the dominant factor, similar to FICO.
- Credit utilization and balances — ~20%: how much you owe relative to your limits.
- Credit mix and experience — ~20%: the variety of account types and how long you have managed them.
- Credit age — ~15%: the age of your accounts.
- Recent credit behavior — ~5%: inquiries and new accounts.
VantageScore tends to be more forgiving of thin credit files and can produce a score with fewer accounts than FICO requires. It also treats certain negative items (like paid collections and medical collections) more leniently in its newer generations, which can push a consumer up a tier relative to their FICO score.
Which Score Will a Lender See?
There is no universal answer. A mortgage lender will typically pull a tri-merge of FICO scores — one from each bureau, using a FICO model specifically designed for mortgage risk (often FICO 2, FICO 4, or FICO 5, depending on the bureau). An auto lender might pull an auto-enhanced FICO that weights your past auto-loan behavior more heavily. A credit card issuer might use FICO 8 or FICO Bankcard. A free credit app is probably showing you a VantageScore.
This is why your “score” can differ by 20, 40, or even 60 points depending on who is looking. The ranges below give you the framework to interpret any of them.
FICO
Score Ranges: A Detailed Breakdown
FICO’s base scores (FICO 8 and FICO 9 are the most common) use the following tier boundaries. These are the ranges most lenders and consumers reference when they talk about “your FICO score.”
| FICO Tier | Score Range | Share of U.S. Consumers (approx.) |
|---|---|---|
| Exceptional | 800–850 | ~21% |
| Very Good | 740–799 | ~25% |
| Good | 670–739 | ~21% |
| Fair | 580–669 | ~18% |
| Poor | 300–579 | ~15% |
Exceptional (800–850)
An exceptional FICO score tells a lender you are an extremely low risk. You have a long, spotless payment history, low utilization, a mature credit mix, and no recent negative marks. At this level, you are effectively at the front of the line for the best offers a lender has. Denial is almost unheard of for new credit unless there is an income or fraud issue. Interest rates are typically the lowest the lender publishes.
Very Good (740–799)
A very good FICO score still puts you in the top tier for most practical purposes. The difference between 740 and 800 is usually invisible at the cash register — both qualify you for the best advertised mortgage rates and top-tier credit card offers. The main benefit of climbing from very good to exceptional is psychological and marginal: a little more cushion if a negative event (a late payment, a new hard inquiry) ever lands on your file.
Good (670–739)
A good FICO score means you are a solid, acceptable risk. You will be approved for most credit cards and auto loans, and you will generally qualify for conventional mortgage financing (most conventional mortgage programs use a 620–640 floor, so 670 clears it comfortably). Your interest rates, however, will be noticeably higher than what an exceptional borrower pays. This is the tier where many consumers first notice that “good” is not quite “great” when the monthly payment is calculated.
Fair (580–669)
A fair FICO score is the tier where borrowing starts to get uncomfortable. You may still qualify for credit, but the terms tighten: higher APRs, lower credit limits, and more denials. A 580 score is the minimum for an FHA mortgage with the standard 3.5% down payment, so consumers in the lower half of this tier often rely on government-backed loan programs rather than conventional financing. Credit card offers in this tier tend to come with annual fees, high APRs, and smaller credit lines — and secured cards become a realistic rebuilding tool.
Poor (300–579)
A poor FICO score reflects significant credit risk in the eyes of a lender. This tier is commonly associated with recent late payments, accounts in collections, high utilization, charged-off accounts, or a combination of these. Traditional unsecured credit is very difficult to obtain at this level. Consumers in the poor range are often limited to secured credit cards, credit-builder loans, or subprime auto financing with very high rates. The encouraging news: this is also the tier where disciplined, structured repair produces the fastest absolute point gains, because removing even one or two negative marks can move a score up by dozens of points.
VantageScore Ranges: A Detailed Breakdown
VantageScore 3.0 and 4.0 use the same 300–850 scale as FICO but draw the tier boundaries at slightly different points. The names also differ: VantageScore uses “Superprime” instead of “Exceptional,” for example.
| VantageScore Tier | Score Range | Share of U.S. Consumers (approx.) |
|---|---|---|
| Superprime | 781–850 | ~45% |
| Prime | 661–780 | ~22% |
| Near Prime | 601–660 | ~13% |
| Subprime | 500–600 | ~13% |
| Deep Subprime | 300–499 | ~7% |
Superprime (781–850)
A superprime VantageScore is the top tier and signals very low risk. Consumers here enjoy the best rates and the broadest approval odds across product types. Because VantageScore’s superprime band starts lower than FICO’s exceptional band (781 vs. 800), a consumer can be “superprime” by VantageScore standards while sitting in FICO’s “very good” tier. This is a common source of confusion when comparing scores across models.
Prime (661–780)
A prime VantageScore is a healthy, lender-friendly score. Consumers in this band are generally approved for credit cards, auto loans, and mortgages, and qualify for competitive — though not always the absolute lowest — interest rates. The 661 lower boundary is meaningfully lower than FICO’s 670 “good” boundary, which is why a VantageScore often looks a few points more favorable than a FICO score for the same consumer.
Near Prime (601–660)
A near prime VantageScore corresponds roughly to the upper half of FICO’s fair tier. Borrowers here may qualify for credit but typically at higher rates and with smaller limits. This is a transitional band — consumers in near prime are usually only a few good habits (and a few months) away from crossing into prime, where terms improve noticeably.
Subprime (500–600)
A subprime VantageScore maps to the lower half of FICO’s fair tier and the upper portion of FICO’s poor tier. Borrowers in this band face real headwinds: higher APRs, more denials, and a heavier reliance on secured products and government-backed loan programs. Like FICO’s poor tier, this is a band where structured repair work can produce meaningful gains.
Deep Subprime (300–499)
A deep subprime VantageScore reflects the highest perceived risk. Borrowers in this band typically have multiple serious negative items — recent late payments, collections, charge-offs, public records, or a combination. Traditional credit is largely unavailable, and the path forward usually starts with secured credit products and a deliberate, multi-month rebuilding plan.
FICO vs. VantageScore Ranges: Side-by-Side Comparison
Because the two models use the same 300–850 scale but draw boundaries differently, it is easy to misread your standing if you do not know which score you are looking at. The table below places the two sets of tiers side by side so you can compare directly.
| Risk Level | FICO Tier | FICO Range | VantageScore Tier | VantageScore Range |
|---|---|---|---|---|
| Lowest risk | Exceptional | 800–850 | Superprime | 781–850 |
| Low risk | Very Good | 740–799 | Superprime | 781–850 |
| Moderate-low risk | Good | 670–739 | Prime | 661–780 |
| Moderate risk | Fair | 580–669 | Near Prime | 601–660 |
| Higher risk | Fair / Poor (border) | 580–669 | Subprime | 500–600 |
| Highest risk | Poor | 300–579 | Deep Subprime | 300–499 |
A Few Patterns Are Worth Noting
- VantageScore’s top tier starts earlier. A 785 is superprime under VantageScore but only “very good” under FICO. If a free app shows you a 790 VantageScore, do not assume your FICO is also in the exceptional band — it may sit at 760.
- VantageScore draws the prime line lower than FICO draws the good line. A 665 is prime under VantageScore but only fair under FICO. This is a frequent reason consumers feel “better” looking at their VantageScore than their FICO.
- The lower boundary differs. FICO’s poor tier starts at 579 and below; VantageScore’s deep subprime starts at 499 and below. A consumer at 540 is “poor” under FICO but “subprime” (one tier higher) under VantageScore.
The practical takeaway: when a lender tells you their minimum score requirement, always ask which model and which generation they use. A “620 minimum” almost always refers to a FICO score in mortgage lending; a “660 minimum” on a credit card pre-qualification tool may well reference VantageScore.
What Each Tier Means for Borrowing, Rates, and Approvals
Knowing the range is only half the picture. The other half is understanding what each tier actually buys you in the real world — what lenders will approve, what rates they will quote, and what you will pay over time. Below we translate each tier into concrete borrowing outcomes.
Exceptional / Superprime (Top Tier)
- Mortgages: You qualify for the lowest advertised rates. On a conventional 30-year mortgage, the difference between a top-tier rate and a good-tier rate can be 0.25% to 0.75%. On a $400,000 loan, that is roughly $60–$180 per month — and $20,000–$65,000 over the life of the loan.
- Auto loans: You qualify for the manufacturer’s advertised promotional APRs, often 0%–3.99% for well-qualified buyers.
- Credit cards: You receive pre-qualified offers for premium rewards cards, low ongoing APRs, large credit limits, and sign-up bonuses.
- Approvals: Near-certain for any standard product, assuming income supports the debt.
Very Good (FICO) / Upper Superprime (VantageScore)
- Mortgages: You still qualify for the best or near-best rates. The practical difference from exceptional is minimal.
- Auto loans: You qualify for top-tier promotional rates.
- Credit cards: Premium cards remain well within reach.
- Approvals: Very high. Denial is rare and usually tied to income or a recent negative item rather than the score itself.
Good / Prime
- Mortgages: You qualify for conventional financing. Rates run a quarter to half a point above the best available.
- Auto loans: You are approved, but the lowest promotional APRs may be just out of reach. Expect rates a point or two above top-tier offers.
- Credit cards: You qualify for most mid-tier rewards cards. The most competitive premium cards may be borderline depending on the issuer.
- Approvals: High, but you may face smaller credit limits and slightly more scrutiny on income and debt-to-income ratio.
Fair / Near Prime
- Mortgages: Conventional loans become difficult. FHA loans (minimum 580 FICO for 3.5% down) are the typical path. You may face higher mortgage insurance costs.
- Auto loans: You are approved, but rates climb sharply — often 8% to 15% or higher depending on the lender and the vehicle.
- Credit cards: Unsecured cards are available but come with higher APRs, lower limits, and possible annual fees. Secured cards are a strong rebuilding option.
- Approvals: Mixed. You will be approved by some lenders and declined by others, especially for premium products.
Poor / Subprime / Deep Subprime
- Mortgages: Traditional conventional and FHA financing is generally out of reach until the score improves. Specialized programs (manual underwriting, certain non-prime lenders) may exist but at significantly higher rates.
- Auto loans: Subprime auto financing is available but rates can exceed 20%. Down payments are usually required.
- Credit cards: Unsecured cards are largely unavailable. Secured credit cards and credit-builder loans are the primary tools for rebuilding.
- Approvals: Limited. Expect denials on most standard credit products and a reliance on secured or alternative lenders.
How to Move Up from One Tier to the Next
This is where most consumers want the “secret.” There is no secret — but there is a reliable, repeatable process. The same factors that pull a score down are the levers that push it up. Below is tier-by-tier, actionable guidance for climbing the ladder.
From Poor to Fair
If you are in the poor credit range (FICO 300–579, VantageScore 300–600), your score is being held down by specific, identifiable items — not by some abstract “bad luck.” The priority is removing or neutralizing those items.
- Pull all three bureau reports. You are entitled to a free report from each bureau every week at AnnualCreditReport.com. Pull Equifax, Experian, and TransUnion so you can see the full picture.
- Audit for errors. According to a Federal Trade Commission study, roughly one in five consumers has an error on at least one credit report serious enough to affect their score. Look for accounts that are not yours, incorrect late-payment notations, outdated balances, and duplicate entries. Every error you successfully dispute is a potential score gain.
- Dispute inaccurate negative marks under the FCRA. The Fair Credit Reporting Act gives you the right to dispute any item you believe is inaccurate, incomplete, or unverifiable. The bureaus must investigate within 30 days (45 in some cases) and remove anything they cannot verify. This is the legal backbone of credit repair.
- Address legitimate negative items. For accurate negative marks, explore options: pay-for-delete agreements with creditors on smaller collections, goodwill letters asking a long-standing creditor to remove a one-time late payment, and negotiated settlements on charged-off accounts.
- Open a secured credit card. A secured card (with a $200–$500 deposit) reports to the bureaus just like an unsecured card. Using it for a small recurring charge and paying it in full each month establishes a fresh positive payment record.
- Consider a credit-builder loan. These small installment loans hold the borrowed funds in a savings account while you make payments, building both payment history and an installment account in your credit mix.
The combination of removing negative items and adding positive payment history is the fastest reliable path out of the poor tier. Many of our clients see meaningful movement within 60–90 days of starting structured repair work, though individual results vary and no specific outcome can be guaranteed.
From Fair to Good
Once you are in the fair credit range, the heavy negative items are usually fewer, and the levers shift toward utilization and consistency.
- Drive down credit card balances. Utilization is recalculated every time a new balance is reported — usually monthly. Paying a card from 80% utilized to under 30% can produce a noticeable score increase the next cycle.
- Aim for under 10% utilization on each card. The biggest utilization gains come from getting each individual card below 10%, not just the aggregate. If one card is maxed and others are at zero, that one card still drags the score.
- Never miss a payment. At this tier, a single 30-day late mark can undo months of progress. Set auto-pay for at least the minimum on every account.
- Avoid new hard inquiries unless necessary. Each hard inquiry can cost a few points. In the fair tier, you want every point working in your favor.
- Keep old accounts open. Closing an older card shortens your average account age and reduces your total available credit — both of which can lower your score.
From Good to Very Good
Moving from good to very good is a matter of refinement. The big levers have already been pulled; now you are optimizing.
- Maintain long-term low utilization. Keep your reported balances consistently under 10%.
- Let your accounts age. Time is a scoring factor you cannot rush, but you can protect it by avoiding unnecessary new accounts and keeping your oldest cards open and lightly used.
- Diversify your credit mix thoughtfully. If you only have revolving credit, a well-managed installment loan (auto, personal, or mortgage) can add points over time. Do not take on debt you do not need just for the mix — but if you are already financing a car, that installment account is helping.
- Pay down installment loans. For installment loans, paying down the principal reduces the “original loan amount vs. current balance” ratio, which VantageScore and newer FICO models reward.
From Very Good to Exceptional
The jump from very good to exceptional is the slowest and least urgent. The practical benefits are marginal — you already qualify for top-tier offers. The remaining gains come from patience: continued perfect payments, aging accounts, and avoiding any new negative marks. Most consumers who reach exceptional do so by simply maintaining very good habits for several more years.
How Long It Takes to Climb Between Tiers
There is no universal timeline, because every credit file is different. But general patterns hold, and setting realistic expectations helps you stay motivated.
Poor to Fair: 2–6 months
This is often the fastest tier-to-tier climb, especially if your poor score is driven by a small number of correctable items. Successful disputes, pay-for-delete agreements, and the establishment of a single new positive account (a secured card) can move a score from the 500s to the low 600s within a few reporting cycles. If the file has extensive, recent negative items (a recent bankruptcy, multiple fresh collections), the climb takes longer — often 12–24 months.
Fair to Good: 6–18 months
This climb is steadier. It usually involves paying down balances to consistently low utilization and accumulating 6–12 months of flawless payment history. If a single significant negative item (like a 30-day late from a year ago) is still aging, expect the climb to accelerate once that item crosses the 12- or 24-month mark.
Good to Very Good: 12–24 months
This is a patience tier. You are optimizing, not rescuing. Continued low utilization, no new negatives, and the slow aging of your accounts produce gradual upward movement. Most consumers reach very good by simply maintaining good habits for another year or two.
Very Good to Exceptional: 2–5 years
This is the slowest transition and is largely a function of account age and the total absence of negative marks. Consumers who reach exceptional typically have 7–10+ years of credit history and zero recent derogatory items. There is no shortcut — only consistency.
Special Case: Bankruptcy
A Chapter 7 bankruptcy stays on your report for 10 years; a Chapter 13 for 7 years. The score impact is most severe in the first two years, after which it gradually lessens. Many consumers see their scores recover into the fair and then good range within 3–5 years post-discharge, provided they establish new positive credit and avoid new negative marks. This is a marathon, not a sprint, and it is one of the situations where professional, FCRA-compliant guidance is most valuable.
What Pulls You Down a Tier
Understanding the downward forces is just as important as knowing the upward ones. Here are the most common reasons consumers drop from one tier to the next.
Late Payments
A single 30-day late payment can drop a good score by 60–80 points, especially if your history was previously spotless. The higher your score, the bigger the drop from a first late. A 60- or 90-day late is more severe and lingers longer in the scoring models.
High Credit Utilization
Utilization is the second-biggest factor, and it is dynamic — it updates with each monthly balance report. Maxing out a card (or coming close) can drop a score 20–40 points in a single cycle, even with no late payments. The good news: bringing the balance back down restores the score just as quickly.
Collections and Charge-Offs
An account sent to collections or charged off by the original creditor is a serious negative mark. Even a small medical bill sent to collections can cost 50–100 points depending on your starting score. Newer scoring models (FICO 9, VantageScore 4.0) discount paid collections and smaller medical collections, but older models still in wide use (FICO 8) do not.
New Hard Inquiries in Clusters
A single hard inquiry typically costs 1–5 points and fades in 12 months. But a cluster of inquiries in a short window — say, applying for four credit cards in two months — signals risk and can compound the score impact, especially for thinner files.
Closing Old Accounts
Closing an older card does not immediately remove it from your report (it continues to age for up to 10 years), but it does reduce your total available credit immediately, which can spike your utilization ratio and lower your score.
Applying for Too Much New Credit
A burst of new accounts lowers your average account age and adds inquiries, both of which can pull a score down temporarily. The effect is usually modest and recovers within 6–12 months, but it can be enough to nudge you across a tier boundary at exactly the wrong moment — like right before a mortgage application.
Public Records
A civil judgment or tax lien (when still reportable — standards have tightened in recent years) is a serious negative mark. Bankruptcies, as noted above, are the most impactful and longest-lasting.
Industry-Specific Scores: Auto-Enhanced and Bankcard Scores
The 300–850 ranges we have covered apply to general-purpose credit scores. But many lenders use industry-specific scores that are tuned for the product they are underwriting. These scores have their own ranges — sometimes the same 300–850, sometimes different.
FICO Auto Scores
FICO Auto Scores are used by many auto lenders. They weigh your past auto-loan and auto-lease history more heavily than a base FICO score would. If you have always paid your car loan on time but had some credit card stumbles, your Auto Score may be higher than your base score.
- Range: 250–900 (wider than the base 300–850 range)
- Use case: Auto loan origination and refinancing
- What it means for ranges: The tiers are roughly shifted. A “good” Auto Score might sit around 660–720, slightly different from the base FICO good tier. Always ask the dealer which score they are pulling.
FICO Bankcard Scores
FICO Bankcard Scores are used by credit card issuers. They weigh your history with revolving credit more heavily.
- Range: 250–900
- Use case: Credit card underwriting and limit assignment
- What it means for ranges: As with Auto Scores, the tier boundaries are shifted relative to the base score. A Bankcard Score of 680 may correspond to a slightly different risk band than a base FICO of 680.
VantageScore Industry Scores
VantageScore also offers industry-specific variants for auto and credit card lending, though these are less commonly discussed than FICO’s. The same principle applies: the score is tuned for the product, and the tier boundaries may not line up exactly with the general-purpose VantageScore ranges.
Mortgage Scores
Mortgage lending deserves special mention. Most conventional and FHA lenders pull a tri-merge of older FICO models — typically FICO Score 2 (Experian), FICO Score 4 (TransUnion), and FICO Score 5 (Equifax). These older models use the 300–850 scale but can produce scores somewhat different from FICO 8 or 9, particularly because they treat certain credit mix and utilization factors differently.
If you are planning a major purchase — a home, a car, a balance-transfer credit card — it is worth asking the prospective lender which specific score they will pull. That way you can focus your preparation on the model that actually matters for that decision.
Common Myths About Credit Score Ranges
A surprising amount of bad advice circulates about credit scores. Here are the myths we hear most often, and the reality behind each.
Myth 1: “Checking my credit score lowers it.”
False. Checking your own score or pulling your own report is a soft inquiry, which has zero impact on your score. Only hard inquiries — those initiated by a lender evaluating you for new credit — can affect your score, and even then only slightly.
Myth 2: “Closing a paid-off card helps my score.”
Usually false. Closing a card reduces your total available credit, which can raise your utilization ratio and lower your score. It also eventually shortens your account-age history. In most cases, it is better to keep a paid-off card open and use it occasionally for a small charge you pay in full.
Myth 3: “Carrying a small balance builds credit faster.”
False. You do not need to carry a balance or pay interest to build credit. The scoring models reward on-time payments and low utilization — both of which are achieved by paying your statement balance in full each month. Carrying a balance only costs you interest and, if the balance is high relative to your limit, can actually hurt your score.
Myth 4: “My income is part of my credit score.”
False. Credit scoring models do not consider income, salary, or net worth. Lenders consider income separately, as part of their underwriting (debt-to-income ratio, ability to repay). Your score reflects how you have managed credit, not how much money you make.
Myth 5: “Negative items fall off after seven years — automatically.”
Mostly true, with caveats. Most negative items (late payments, collections, charge-offs) fall off after seven years; Chapter 7 bankruptcies after ten. But they do not always disappear on schedule — a creditor may re-report, or a collection may be re-aged if mishandled. It is worth checking your reports periodically to confirm old items have been removed.
Myth 6: “Paying off a collection instantly removes it from my report.”
Usually false. Paying or settling a collection updates the balance to zero, but the collection record typically remains on your report for up to seven years from the original delinquency date. The newer scoring models (FICO 9, VantageScore 4.0) ignore paid collections, so paying can help your score under those models — but the item may still be visible on your report. A pay-for-delete agreement, where the collector agrees to remove the item in exchange for payment, is the way to actually clear the item from the report.
Myth 7: “Credit repair is illegal.”
False. Credit repair is a legal, regulated activity under the Credit Repair Organizations Act (CROA), which sets rules for how credit repair companies must operate. Legitimate, FCRA-compliant credit repair — disputing inaccurate, incomplete, or unverifiable items — is your right under federal law. What is illegal is a company promising guaranteed results or asking you to misrepresent information to the bureaus.
Myth 8: “A higher salary moves you into a higher tier.”
False, for the same reason as Myth 4. Tiers are determined by your credit behavior, not your income. A high earner with missed payments can sit in the poor tier; a modest earner with long, flawless credit history can sit in the exceptional tier.
Frequently Asked Questions
1. What is the difference between a credit score and a credit report?
Your credit report is a detailed record of your credit history — every account, its status, your payment history, balances, inquiries, and public records. Your credit score is a three-digit number calculated from the information in your report. The report is the underlying data; the score is a summary of the risk that data represents. You can have different scores from different models, all calculated from the same underlying report.
2. Which credit score range matters most?
The one your prospective lender uses. For mortgages, that is almost always a FICO score (and often an older FICO model). For many credit cards and free monitoring apps, it is a VantageScore. For auto loans, it may be a FICO Auto Score. Knowing the product you are shopping for tells you which score to focus on.
3. Can I have a score above 850?
On the standard base FICO and VantageScore scales, no — 850 is the ceiling. Some industry-specific scores (FICO Auto, FICO Bankcard) go up to 900, but those are different scales used only for specific products. For general-purpose credit, 850 is the maximum.
4. How often does my credit score change?
Potentially every time a new piece of information is reported to the bureaus — which for most active accounts means once a month. If you pay down a credit card balance, your score can move the next time that card reports. If a late payment lands, your score can drop the next reporting cycle. Scores are dynamic, not static.
5. Does the credit score range I am in affect my insurance rates?
In many states, yes. Insurers in many jurisdictions use a credit-based insurance score — derived from credit report data but calculated with a different model — to help set auto and home insurance premiums. A lower score can mean higher premiums in states where the practice is permitted. Several states (California, Hawaii, Massachusetts, and others) restrict or prohibit the practice for certain insurance types.
6. What is a “good” credit score for a mortgage?
For a conventional mortgage, most lenders look for a FICO score of at least 620, though some programs accept lower. For an FHA loan, the minimum is 580 for the standard 3.5% down payment (or 500 with a 10% down payment in some cases). To get the best advertised mortgage rates, you generally need a FICO score of 740 or higher.
7. Will disputing an error on my report hurt my score?
No. Filing a dispute does not affect your score. While an item is under investigation, it remains on your report. If the bureau verifies the item, it stays and your score is unchanged. If the bureau cannot verify it and removes it, your score may go up. There is no downside to disputing items you genuinely believe are inaccurate.
8. How long do hard inquiries stay on my report?
Hard inquiries remain on your report for two years, but their scoring impact fades after about 12 months. Most consumers see the point impact disappear entirely within a year. Rate-shopping for a single product (a mortgage or auto loan) within a focused window — typically 14–45 days depending on the model — is usually treated as a single inquiry for scoring purposes, so shopping around does not multiply the impact.
Take the Next Step With a Free Credit Audit
Knowing the credit score ranges is the first step. Knowing where you stand — and exactly what is holding your score where it is — is the step that actually changes things.
At our San Diego-based, FCRA-compliant, attorney-backed credit repair firm, we start every relationship with a free, no-obligation three-bureau credit audit. We pull your reports from Equifax, Experian, and TransUnion, walk you through every item line by line, identify inaccuracies and negative marks that may be dragging your score down, and give you a clear, honest picture of where you stand and what is possible.
You do not have to figure this out alone, and you do not have to settle for a score that is costing you money every month in higher interest rates. Whether you are working toward a mortgage, refinancing a car, or simply want to stop overpaying for credit, the path starts with knowing your numbers.
Schedule your free credit audit at credit-repair.com — no pressure, no quick-fix promises, just a transparent, legally grounded plan for moving your score where it needs to be.
Disclaimer: This article is provided for educational purposes only and is not legal or financial advice. Individual credit outcomes vary based on the specifics of each credit file. No specific score improvement or timeline is guaranteed. Our services operate in full compliance with the Fair Credit Reporting Act (FCRA) and the Credit Repair Organizations Act (CROA).