
That’s exactly what this guide is about. We’ll walk through the average credit score in America right now, how it’s shifted over the past decade, how it breaks down by age and state, and — most importantly — what those numbers actually mean for your borrowing power, your monthly costs, and your financial future. We’ll also get honest about why the “average” is useful context but not the whole story, especially when credit reports contain errors that quietly drag scores down.
No hype. No “raise your score 100 points overnight” promises. Just a clear, trustworthy picture of where things stand and what you can realistically do about it.
The Current Average Credit Score in America
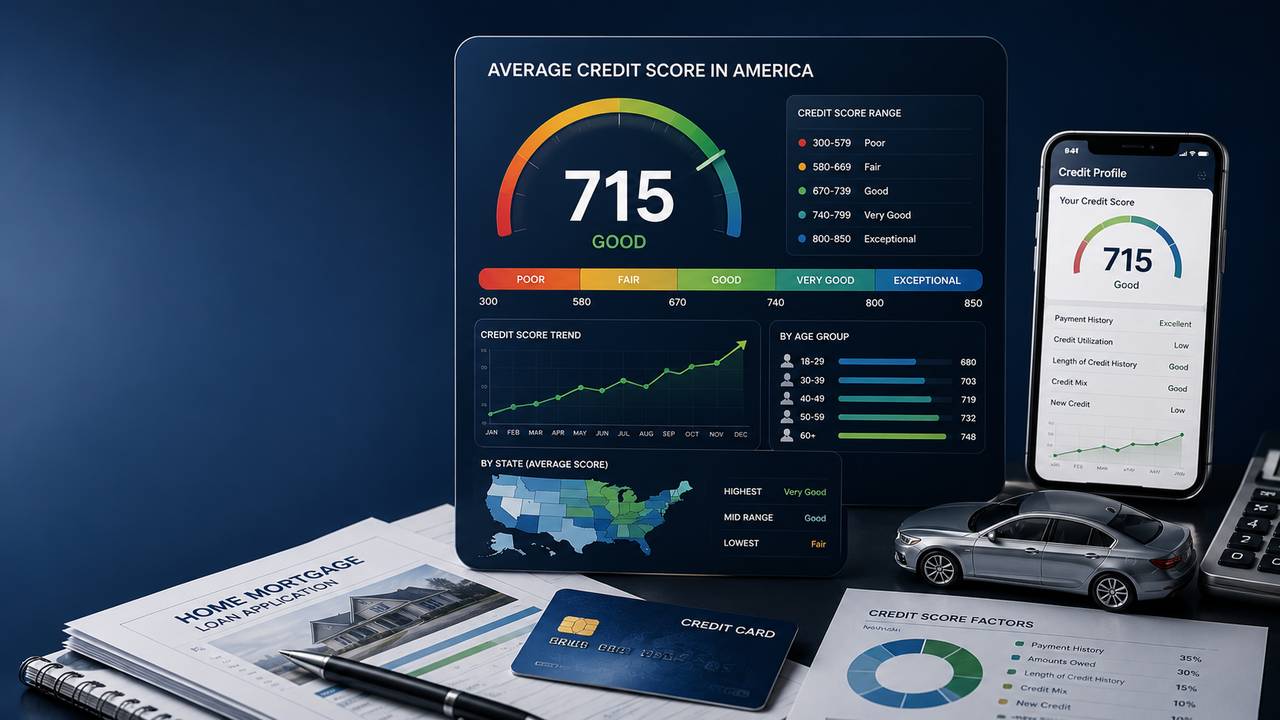
As of recent data, the average FICO score in the United States sits around 715 to 718. We say “around” deliberately, because the number shifts slightly from quarter to quarter and depends on which scoring model and which bureau’s data you’re looking at. FICO and VantageScore use slightly different scales and pull from slightly different data, so you’ll see figures hovering anywhere in that 715–718 band depending on the source.
Here’s the important framing: that average lands squarely in the “good” credit range. FICO’s official score ranges look like this:
| Score Range | Rating |
|---|---|
| 300–579 | Poor |
| 580–669 | Fair |
| 670–739 | Good |
| 740–799 | Very Good |
| 800–850 | Exceptional |
So the average American, statistically speaking, has good credit — not great, not poor. They can qualify for most loans and credit cards, but they’re not getting the very best rates lenders reserve for the 740+ and 800+ crowds. That’s a meaningful distinction we’ll come back to, because the difference between “good” and “very good” can translate into thousands of dollars over the life of a loan.
A Quick Note on Where These Numbers Come From
FICO scores are calculated using data from the three major credit bureaus — Equifax, Experian, and TransUnion. The average we’re referencing comes from FICO’s periodic publications based on millions of consumer credit files. VantageScore, the competing model created jointly by the three bureaus, tends to report a similar average (usually within a few points). When you see a headline like “the average credit score hit 715,” it’s almost always FICO data.
Your own score will vary a bit depending on which bureau’s data was used and which scoring model the lender pulls. It’s completely normal to see a 10- or 20-point swing between, say, your Experian FICO 8 and your TransUnion FICO 8. That’s not a glitch — it’s because not every creditor reports to every bureau, and reporting timing can differ. We’ll dig into this more in the FAQ.
How the Average Has Trended Up Over the Past Decade
Here’s something that might surprise you: the average credit score in America has been climbing steadily for years. A decade ago, the national average FICO score was sitting closer to 695. Today it’s around 715–718. That’s roughly a 20-point gain over ten years — not a dramatic leap, but a clear, sustained upward drift.
What’s Driving the Rise?
Several factors have pushed scores upward:
- Greater access to credit information. Free credit score services, credit-monitoring apps, and lender-provided scores on monthly statements have made consumers far more aware of their credit than they were a generation ago. Awareness drives behavior.
- The pandemic effect. During 2020 and 2021, stimulus checks, paused student loan payments, reduced spending on travel and dining, and forbearance programs gave many households room to pay down debt. Average scores jumped noticeably during this period — one of the few silver linings of a difficult time.
- Improved consumer protections. Changes like the removal of certain tax liens and civil judgments from credit reports, and agreements to wait longer before reporting medical collections, removed negative marks from many files.
- A shift toward longer credit histories. As the population ages and older adults maintain accounts longer, average credit history length — a factor in scoring — has nudged upward.
- Better financial education. Schools, employers, and nonprofits have invested more in financial literacy, and a lot of that education focuses on the mechanics of credit building.
But the Average Doesn’t Tell the Whole Story
Here’s the honest caveat: a rising average doesn’t mean everyone’s doing better. The distribution matters. What’s really happened is that a lot of people moved from “fair” into “good,” and a meaningful chunk moved from “good” into “very good.” But a significant portion of the population — roughly 1 in 6 Americans — still has a score below 580. The average can go up while a lot of people stay stuck, and that’s exactly what’s happened.
We’ll come back to this point throughout the article, because it’s the core reason we encourage people to look beyond the headline number. Your goal isn’t to match the average. Your goal is to understand your own file, fix what’s holding it back, and build from there.
Average Credit Score by Age Group
This is where the data gets genuinely interesting, because credit scores follow a remarkably predictable pattern: they rise with age. That’s not because older people are somehow “better” with money. It’s because the scoring model rewards things that accumulate over time — longer credit histories, more accounts paid on time, and lower credit utilization as people pay down debt and earn more.
Here’s a breakdown of average credit scores by age group based on recent FICO data:
| Age Group | Generation | Average FICO Score | Range | Rating |
|---|---|---|---|---|
| 18–25 | Gen Z | ~679 | Fair to Good | |
| 26–41 | Millennials | ~690 | Good | |
| 42–57 | Gen X | ~709 | Good | |
| 58–76 | Boomers | ~745 | Very Good | |
| 77+ | Silent Generation | ~760 | Very Good |
Why Younger Americans Score Lower
If you’re in your twenties or early thirties and your score feels lower than you’d like, there’s a structural reason for that. Credit scoring models favor history.
The length of your credit history accounts for about 15% of your FICO score, and the age of your oldest account, your newest account, and the average across all accounts all factor in. A 23-year-old simply hasn’t had time to build a 15-year track record.
Younger consumers also tend to have:
- Thinner credit files — fewer accounts means less data for the scoring model to work with, and one missed payment can swing the score more dramatically.
- Higher credit utilization — younger people often have lower credit limits, so even modest balances use up a bigger percentage of available credit.
- Student loan debt — which, while not inherently bad for credit, adds to overall debt load and can hurt if payments are missed.
- Newer accounts — every time you open a new card or loan, it temporarily lowers the average age of your accounts.
Why Older Americans Score Higher
Boomers and the Silent Generation tend to score well because they’ve had decades to:
- Build long, clean payment histories (payment history is 35% of your score — the single biggest factor).
- Pay down mortgages and other installment loans.
- Accumulate multiple accounts in good standing.
- Establish high credit limits with low balances, which means low utilization.
This isn’t about moral virtue or financial wisdom. It’s about the math of the scoring model. Time is a legitimate credit-building tool, and older adults have more of it working in their favor.
The Takeaway for Every Age
If you’re young, don’t panic. Your score has more upward potential than any other group’s, and small habits — paying on time, keeping balances low, avoiding unnecessary new accounts — compound quickly. If you’re middle-aged and feeling stuck, that’s often the signal of a specific issue dragging your score down (a collection, a high-utilization card, an error on your report). And if you’re older, your job is mostly preservation: keep accounts open, keep utilization low, and watch for errors that can quietly chip away at hard-earned scores.
Average Credit Score by State
Credit scores also vary geographically, and the patterns reveal something important: scores correlate heavily with local economic conditions — income levels, cost of living, housing markets, and access to traditional banking. States with higher median incomes and stronger job markets tend to have higher average scores, while states with more economic hardship tend to sit lower.
The General Picture
Based on recent data from Experian and FICO, here’s how the country shakes out:
Higher-average states (typically in the 730–740+ range) tend to include:
- Minnesota
- Vermont
- New Hampshire
- Massachusetts
- Washington
- North Dakota
- South Dakota
Lower-average states (typically in the 680–695 range) tend to include:
- Mississippi
- Louisiana
- Alabama
- Texas
- Georgia
- Nevada
- Oklahoma
Most states cluster somewhere in the 700–720 band, which lines up with the national average.
Why the Regional Spread?
A few structural factors explain most of the variation:
- Income and employment. States with higher median incomes tend to have lower credit utilization, fewer missed payments, and better access to financial tools. It’s not that wealthy people are more responsible — it’s that they have more margin.
- Cost of living versus wages. In states where housing and basics eat up a larger share of income, people are more likely to carry higher balances and occasionally miss payments. That directly lowers scores.
- Medical debt. States with higher uninsured rates tend to have more medical collections on credit reports, which can significantly drag down averages. (Recent rule changes have removed many medical collections from credit reports, but the legacy effect persists.)
- Access to credit. “Credit deserts” — areas with few traditional banks and credit unions — push people toward higher-cost alternative financial services that don’t build credit the same way.
- Cultural and educational factors. Regions with stronger financial education infrastructure tend to see better credit outcomes over time.
What This Means for You
Your state’s average is interesting context, but it doesn’t determine your score. We’ve worked with clients in so-called “low-average” states who have 800+ scores, and clients in “high-average” states who are fighting to break 600. Your score is about your file, not your zip code. That said, if you live somewhere with thinner financial infrastructure, it’s worth being proactive about building credit deliberately — we’ll cover how in a later section.
What “Average” Means for Your Borrowing Power
Here’s where the rubber meets the road. A credit score isn’t a trophy — it’s a key that unlocks (or restricts) access to financing, and the terms you get can vary enormously based on where you land on the scale. Let’s get concrete about what average credit score actually buys you.
Credit Cards
- Below 580: You’ll mostly qualify for secured cards (which require a cash deposit) or subprime cards with high fees and low limits. Rewards and cash-back cards are generally out of reach.
- 580–669 (Fair): You can get unsecured cards, but APRs will be high (often 25–30%+) and limits modest. Some entry-level rewards cards become available at the top of this range.
- 670–739 (Good — the average zone): Most mainstream cards open up, including many rewards and cash-back cards. APRs are still on the higher side, and premium travel cards may require 700+.
- 740–799 (Very Good): You’ll qualify for most cards, including premium travel and rewards cards, with better APRs and higher limits.
- 800+ (Exceptional): You get the best offers lenders have — lowest APRs, highest limits, premium card approvals, and often pre-approved offers with generous sign-up bonuses.
Mortgages
This is where the score really hits your wallet. Conventional mortgage rates are tiered, and even small differences compound over a 30-year loan. As a rough framework:
- 760+ unlocks the best available rates.
- 700–759 gets very competitive rates, typically within 0.25% of the top tier.
- 680–699 sees a noticeable bump in rate.
- 620–679 may still qualify for conventional loans (FHA loans go lower), but rates and mortgage insurance costs climb.
- Below 620 generally means non-prime or FHA territory, with higher costs.
To put that in real terms: on a $350,000 30-year mortgage, the difference between a rate available at 760+ and a rate available at 660 can add up to tens of thousands of dollars in additional interest over the life of the loan. That’s not a hypothetical — it’s the actual cost of a lower score.
Auto Loans
Auto lenders also tier their rates, and the spread is significant:
- 750+ typically gets the advertised promotional rates (sometimes 0% financing offers on new cars).
- 700–749 gets competitive rates, usually within 1–2 percentage points of the best.
- 600–699 sees rates climbing — often 2–5 points higher than the best offers.
- Below 600 can mean rates of 15%+ or difficulty qualifying without a co-signer.
On a $30,000 car loan over 60 months, the difference between a 5% APR and a 15% APR is roughly $8,500 in extra interest. That’s real money that comes straight out of your monthly budget.
Insurance, Rentals, and Employment
Credit scores also influence things beyond borrowing:
- Auto and home insurance — in most states, insurers use credit-based insurance scores to set premiums. Lower scores can mean higher premiums.
- Rentals — landlords routinely check credit. A lower score may require a larger deposit or a co-signer, or get your application passed over entirely.
- Employment — certain employers (especially in finance and government) check credit reports as part of background checks. They don’t see your score, but they see the underlying report.
- Utility and cell phone accounts — lower scores may trigger security deposit requirements.
The Bottom Line on Borrowing Power
If you’re sitting at the national average of around 715, you’re in decent shape. You can get a mortgage, qualify for good cards, and access most mainstream financial products. But you’re not getting the best terms — those are reserved for 740 and above. Moving from 715 to 760 can be one of the highest-ROI financial moves you make, because it compounds across every loan and card you open for years to come.
Why Comparing Yourself to the Average Is Useful — But Not the Whole Story
We give you all these averages because context matters. Knowing the national average, your age group’s average, and your state’s average gives you a rough sense of where you stand. But we want to be clear: the average is a starting point, not a finish line.
Averages Hide the Distribution
The average might be 715, but that doesn’t mean most people are clustered right around 715. The actual distribution is wide — there are millions of Americans at 550 and millions at 800. The average just tells you where the center of mass is, not where you personally need to be. Two people with very different files can both be “above average” or “below average” for entirely different reasons.
Averages Don’t Account for Your Specific Goals
If your goal is to buy a house in the next year, the relevant threshold isn’t the national average — it’s whatever score your target lender requires for the rate you can afford. If you’re trying to refinance credit card debt, the relevant number is whatever the consolidation lender wants. Your goal should be tied to your specific milestone, not a national statistic.
Averages Mask Individual Errors
This is the big one, and it’s core to our work at credit-repair.com. The average is calculated across millions of credit files, including ones with errors. If a meaningful percentage of those files contain inaccuracies — a duplicate account, a misreported late payment, a collection that shouldn’t be there — then the average is being pulled down by problems that are fixable. Your score might be lower than it should be not because of anything you did, but because of something someone else reported incorrectly. We’ll dig into this more in a dedicated section below.
Averages Don’t Reflect Your Trajectory
A 680 score that’s been climbing steadily for two years is in a very different place than a 680 that just dropped from 720. The direction matters as much as the number. Lenders sometimes look at trends, and more importantly, you should look at trends — a dropping score is a signal to investigate, even if the number still looks “okay.”
How to Use the Average Well
Here’s the healthy way to use these numbers:
- As a sanity check. If you’re 100 points below your age group’s average, it’s worth understanding why. That gap usually points to something specific.
- As a goal-setting reference. If you’re at 660 and your age group averages 705, that gives you a concrete, realistic target.
- As motivation, not shame. Being below average doesn’t mean you’ve failed. It means there’s room to improve, and often that improvement is very achievable.
How to Improve From Below Average to Above Average
This is the section most people come for. The good news: credit scores are not fixed. They update as new information flows into your credit report, which means the habits you build today start moving the needle within weeks, not decades. Here’s a practical, grounded approach — no magic, just the mechanics of how scoring actually works.
1. Pay Every Bill on Time, Every Time
Payment history is 35% of your FICO score — the single largest factor. One late payment (30+ days past due) can drop a good score by 80 to 100 points, and it stays on your report for up to seven years. The flip side: a long, clean payment history is the most powerful score-builder there is.
Practical steps:
- Set up automatic payments for at least the minimum on every account.
- Use payment reminders or calendar alerts for anything that can’t be auto-paid.
- If you miss a payment, catch it up within 30 days — many creditors don’t report until you’re 30 days late.
- If you have a good history with a creditor and slip up once, call and ask for a goodwill removal. Many will remove a first-time late payment as a courtesy.
2. Lower Your Credit Utilization
Credit utilization — how much of your available credit you’re using — is about 30% of your score, making it the second-biggest factor and the fastest one to move. The scoring model looks at utilization both per-card and overall.
The targets:
- Below 30% is the widely cited threshold, but lower is better.
- Below 10% is where you see the biggest score benefit.
- 0% isn’t ideal — a small balance that you pay off monthly shows active use.
Practical steps:
- Pay down balances, and pay them before the statement closing date (that’s when balances get reported to the bureaus, not when your bill is due).
- Ask for credit limit increases — more available credit with the same balance lowers your utilization. (Just don’t use the new limit as a license to spend.)
- If you have a big purchase coming up, consider paying it off immediately rather than carrying the balance.
- Spread balances across multiple cards rather than maxing one out — per-card utilization matters too.
3. Don’t Open Unnecessary New Accounts
Every new credit application triggers a hard inquiry, which can ding your score 5–10 points. New accounts also lower the average age of your credit history. This isn’t a reason to never open new credit — strategic new accounts can help over time — but avoid opening several cards in a short window, especially if you’re planning to apply for a mortgage or auto loan soon.
4. Keep Old Accounts Open
The age of your accounts matters. Closing your oldest card shortens your credit history and reduces your total available credit, both of which can lower your score. If a card has no annual fee, keep it open and use it for a small recurring charge (like a streaming subscription) to keep it active.
5. Build a Credit Mix
About 10% of your score comes from having a mix of credit types — revolving (cards) and installment (loans). If you only have credit cards, adding an installment loan (a personal loan, a credit-builder loan, or even a car loan you were planning anyway) can give your score a small lift over time. Don’t take on debt just for the sake of mix, but if you’re going to borrow anyway, it helps.
6. Deal With Collections and Charge-Offs
If you have accounts in collections, they’re dragging your score down significantly. Options:
- Validate the debt. Collectors must prove the debt is yours and the amount is correct. If they can’t, you can dispute it.
- Negotiate a pay-for-delete. Some collectors will remove the item from your report in exchange for payment (get any agreement in writing).
- Pay in full vs. settle. Paid collections still hurt your score but less than unpaid. Newer FICO models (FICO 9, VantageScore 3 and 4) ignore paid collections entirely, though many lenders still use FICO 8, which counts them.
7. Dispute Inaccuracies on Your Report
This is where the biggest, fastest gains often hide. If your report contains errors — and a lot of them do — those errors may be the single thing holding your score down. We’ll cover this in depth in the next section.
What Below-Average Scores Actually Cost You
A below-average credit score isn’t just a number you see on an app. It can translate directly into higher borrowing costs, fewer choices, and larger deposits.
Credit Card Costs
Below-average scores can mean higher APRs, lower credit limits, fewer rewards options, and fewer balance-transfer opportunities. Even when you’re approved, the difference between a low APR and a high APR can become expensive if you carry a balance.
Mortgage Costs
Mortgage rates are particularly sensitive to credit score tiers because the loan amounts are large and the repayment period is long. A lower score can mean a higher interest rate and potentially higher mortgage insurance costs.
Auto Loan Costs
Auto lenders also tier their rates, and the spread is significant:
- 750+ typically gets the advertised promotional rates (sometimes 0% financing offers on new cars).
- 700–749 gets competitive rates, usually within 1–2 percentage points of the best.
- 600–699 sees rates climbing — often 2–5 points higher than the best offers.
- Below 600 can mean rates of 15%+ or difficulty qualifying without a co-signer.
On a $30,000 car loan over 60 months, the difference between a 5% APR and a 15% APR is roughly $8,500 in extra interest. That’s real money that comes straight out of your monthly budget.
Insurance, Rentals, and Other Costs
Lower credit can also affect insurance premiums, rental approvals, security deposits, utility accounts, and other financial opportunities.
How Averages Hide Credit Report Errors Pulling Scores Down
This is the section we care about most, and it’s the heart of why we do what we do at credit-repair.com.
Here’s a fact that doesn’t get enough attention: a meaningful percentage of credit reports contain errors. Various studies and Federal Trade Commission reports over the years have found that roughly 1 in 5 consumers have a material error on at least one of their credit reports — meaning an inaccuracy significant enough to affect their score or their ability to get credit.
That means millions of Americans are walking around with scores lower than they deserve because of something they didn’t do. And here’s the kicker: those errors get averaged into the national “average credit score.” The headline number you see is being pulled down by fixable problems across millions of files.
Common Types of Credit Report Errors
Errors come in several flavors:
- Identity errors — accounts that belong to someone with a similar name or Social Security number showing up on your report.
- Account status errors — payments reported as late when they were on time, accounts marked as open when they’re closed (or vice versa), or accounts showing as active that you never opened.
- Data errors — incorrect credit limits (which can artificially inflate your utilization), wrong balances, or duplicated accounts that make it look like you have more debt than you do.
- Outdated information — negative items that should have aged off after seven years still lingering on your report.
- Mixed files — a more serious form of identity error where two consumers’ credit histories get merged, which can drag in someone else’s collections, late payments, or bankruptcies.
- Re-aging errors — a collection or negative account whose “date of last activity” gets incorrectly updated, making it look newer than it is and resetting the seven-year clock.
- Furnisher errors — a creditor reporting information incorrectly to the bureaus, whether by mistake or because of sloppy record-keeping.
Why This Matters for the Average
When these errors pull individual scores down, they also pull the national average down. If we could wave a wand and correct every error tomorrow, the average credit score in America would almost certainly jump. That’s not a number we can quantify precisely, but given that 1 in 5 reports have material errors and many of those errors are score-lowering, the effect is real.
This is why we say the average is “useful but not the whole story.” It includes people whose scores are artificially depressed by someone else’s mistake. Your job isn’t to beat the average — it’s to make sure your score is based on accurate information. If you’re below average and you don’t know why, an error is one of the first things to rule out.
Your Rights Under the FCRA
The Fair Credit Reporting Act (FCRA) is the federal law that gives you the right to an accurate credit report. Under the FCRA:
- You have the right to see your reports from all three bureaus — free, once a year, at AnnualCreditReport.com (and currently, you can access them weekly at no cost).
- You have the right to dispute any information you believe is inaccurate.
- The bureaus are required to investigate your dispute, usually within 30 days.
- If information can’t be verified, it must be corrected or removed.
- You have the right to add a statement to your report if a dispute isn’t resolved in your favor.
This is where attorney-backed credit repair becomes valuable. While you can dispute errors on your own, the process can be slow, frustrating, and repetitive — especially when creditors and bureaus push back. Having legal professionals who understand the FCRA, the Fair Debt Collection Practices Act (FDCPA), and the nuances of how furnishers and bureaus are required to respond can make a real difference in outcomes. It’s not about doing something you can’t do yourself — it’s about having experienced advocates who know the system and don’t get deterred by the first “verified” response.
How to Check for Errors Yourself
If you haven’t reviewed your three-bureau credit report recently, that’s the place to start:
- Pull your reports from all three bureaus (Equifax, Experian, TransUnion) via AnnualCreditReport.com.
- Review each one carefully. Don’t assume they’re identical — they often aren’t. Look for accounts you don’t recognize, late payments you don’t remember, balances that look wrong, and any personal information errors.
- Dispute inaccuracies in writing with the bureau reporting the error. Be specific: include the account name, the error, and why it’s wrong. Attach supporting documentation if you have it.
- Follow up. If the bureau says the item is “verified” but you know it’s wrong, you can dispute again with additional documentation, file a complaint with the Consumer Financial Protection Bureau (CFPB), or get professional help.
- Repeat periodically. Errors can reappear or new ones can surface. An annual review at minimum is wise; more frequent monitoring catches problems sooner.
The Bottom Line on Errors
If your score is lower than you’d expect — especially if you’ve been responsible with credit and can’t point to a reason — an error is a likely culprit. Don’t accept a low score as a verdict until you’ve confirmed your report is accurate. This is the single highest-leverage thing many people can do for their credit, because correcting an error can produce a faster, bigger jump than any behavioral change.
Frequently Asked Questions
1. What is the average credit score in America in 2026?
The average FICO score in the U.S. is currently around 715 to 718, depending on the quarter and data source. It’s been hovering in that band for a couple of years after rising steadily through the 2010s and early 2020s. VantageScore reports a similar national average. The number fluctuates slightly as new data comes in, which is why you’ll see slightly different figures from different sources — they’re all pointing at roughly the same reality.
2. Is a 700 credit score good?
Yes. A 700 lands in the “good” range (670–739). You’ll qualify for most credit cards, many mortgages, and most auto loans. You’re right around the national average. That said, you’re not yet in the “very good” tier (740+) where the best rates live, so there’s meaningful room to improve — and the financial payoff of moving from 700 to 760 can be substantial, especially on mortgages and auto loans.
3. What credit score do I need to buy a house?
It depends on the loan type:
- Conventional loans: typically 620+, though some lenders want 660+.
- FHA loans: as low as 580 with 3.5% down (some lenders accept 500–579 with 10% down).
- VA loans: no official minimum, but most lenders want 580–620+.
- USDA loans: typically 640+.
But qualifying and getting a good rate are different things. For the best conventional mortgage rates, you generally want 760 or higher. If you’re below that, improving your score before applying can save you a lot over the life of the loan.
4. How fast can I raise my credit score?
It depends on what’s holding it down:
- High utilization — paying down balances can produce a noticeable jump within 30–60 days, because utilization updates when bureaus receive new balance information (usually monthly).
- A recent late payment — its impact fades over time, but a goodwill removal can help immediately if the creditor agrees.
- An error or unauthorized account — disputing and removing it can produce a jump within 30–45 days, once the bureau completes its investigation.
- Thin credit file — building new positive history takes 6–12 months to show meaningful movement.
Realistic expectation: most people can move 20–60 points in a few months with focused effort. Bigger gains (100+ points) usually take longer and depend on what’s on the report. Be wary of anyone promising fast, huge gains.
5. Does checking my own credit score lower it?
No. When you check your own score or pull your own report, it’s a “soft inquiry,” which has no effect on your score. Only “hard inquiries” — when a lender pulls your credit as part of an application — can affect your score, and even then, a single hard inquiry typically drops your score by only a few points and fades within a year. Checking your own credit is free, safe, and something you should do regularly.
6. Why are my three credit scores different?
Because your three credit reports aren’t identical. Not every creditor reports to all three bureaus, and even when they do, the timing of updates can differ. Since your FICO score is calculated from whatever data is in that specific bureau’s file, the scores will vary. A 10–30 point difference between bureaus is normal. If the difference is much larger, it’s a sign that something is being reported to one bureau but not the others — or that there’s an error on one report. Worth investigating.
7. How long do negative items stay on my credit report?
Here are the standard timeframes under the FCRA:
- Late payments: 7 years from the missed payment date.
- Collections: 7 years from the original delinquency date.
- Charge-offs: 7 years from the date of the first missed payment.
- Chapter 7 bankruptcy: 10 years.
- Chapter 13 bankruptcy: 7 years.
- Civil judgments: no longer reported (removed in 2017–2018 reforms).
- Paid tax liens: no longer reported (removed in 2018 reforms).
- Hard inquiries: 2 years (impact fades after about 12 months).
Positive information stays much longer — often 10 years or more — which is why keeping old accounts in good standing helps your score long-term.
8. Can credit repair actually remove accurate negative items?
Only inaccurate, unverifiable, or outdated items can be removed through disputes — and that’s what legitimate credit repair focuses on. If a negative item is accurate, verified, and within the reporting window, it generally can’t be removed through the dispute process. What legitimate credit repair can do is make sure everything on your report meets that standard — accurate, verified, and within the time limit — and push back when it doesn’t. Be very cautious of anyone who promises to remove accurate negative items; that’s a red flag. The FCRA-compliant approach is about accuracy and verification, not erasure.
Ready to See Where You Stand?
Here’s our honest take: the average credit score in America is useful context, but your score is what actually shapes your financial life — and your score is based on your specific credit file, not a national statistic. The most important question isn’t “how do I compare to the average?” It’s “is my credit report accurate, and is there anything on it holding me back that shouldn’t be?”
That’s where we come in. At credit-repair.com, we offer a free credit audit across all three major bureaus — Equifax, Experian, and TransUnion. We’ll review your reports for inaccuracies, identify items that may be pulling your score down, and walk you through what we find in plain language. No pressure, no quick-fix promises, no hidden fees. Just a clear picture of where you stand and what, if anything, is worth addressing.
We’re a San Diego-based credit repair firm that operates in full compliance with the FCRA and works alongside experienced attorneys to make sure every step of the process is ethical, accurate, and effective. We serve clients in cities nationwide, and our approach is built on transparency and client education — because we don’t just want to help you fix your credit, we want to equip you with the knowledge to keep it strong for life.
Start your free credit audit at credit-repair.com →
Whether you’re above average and looking to optimize, below average and not sure why, or somewhere in between and just want a second set of eyes on your report — we’re here to help. Your credit score isn’t a verdict. It’s a snapshot, and snapshots change.