
While you wait, take action now: learn exactly how to file a credit dispute and what happens at each stage, use the fastest methods to build positive credit history in parallel, see our step-by-step credit repair process to know exactly what a professional does for you, and get 9 credit repair tips you can use today while the dispute process runs.
If you’re working on your credit, one question probably comes up pretty quickly: how long does credit repair take? There isn’t a set answer. It really depends on what’s hurting your credit and how much needs to be fixed.
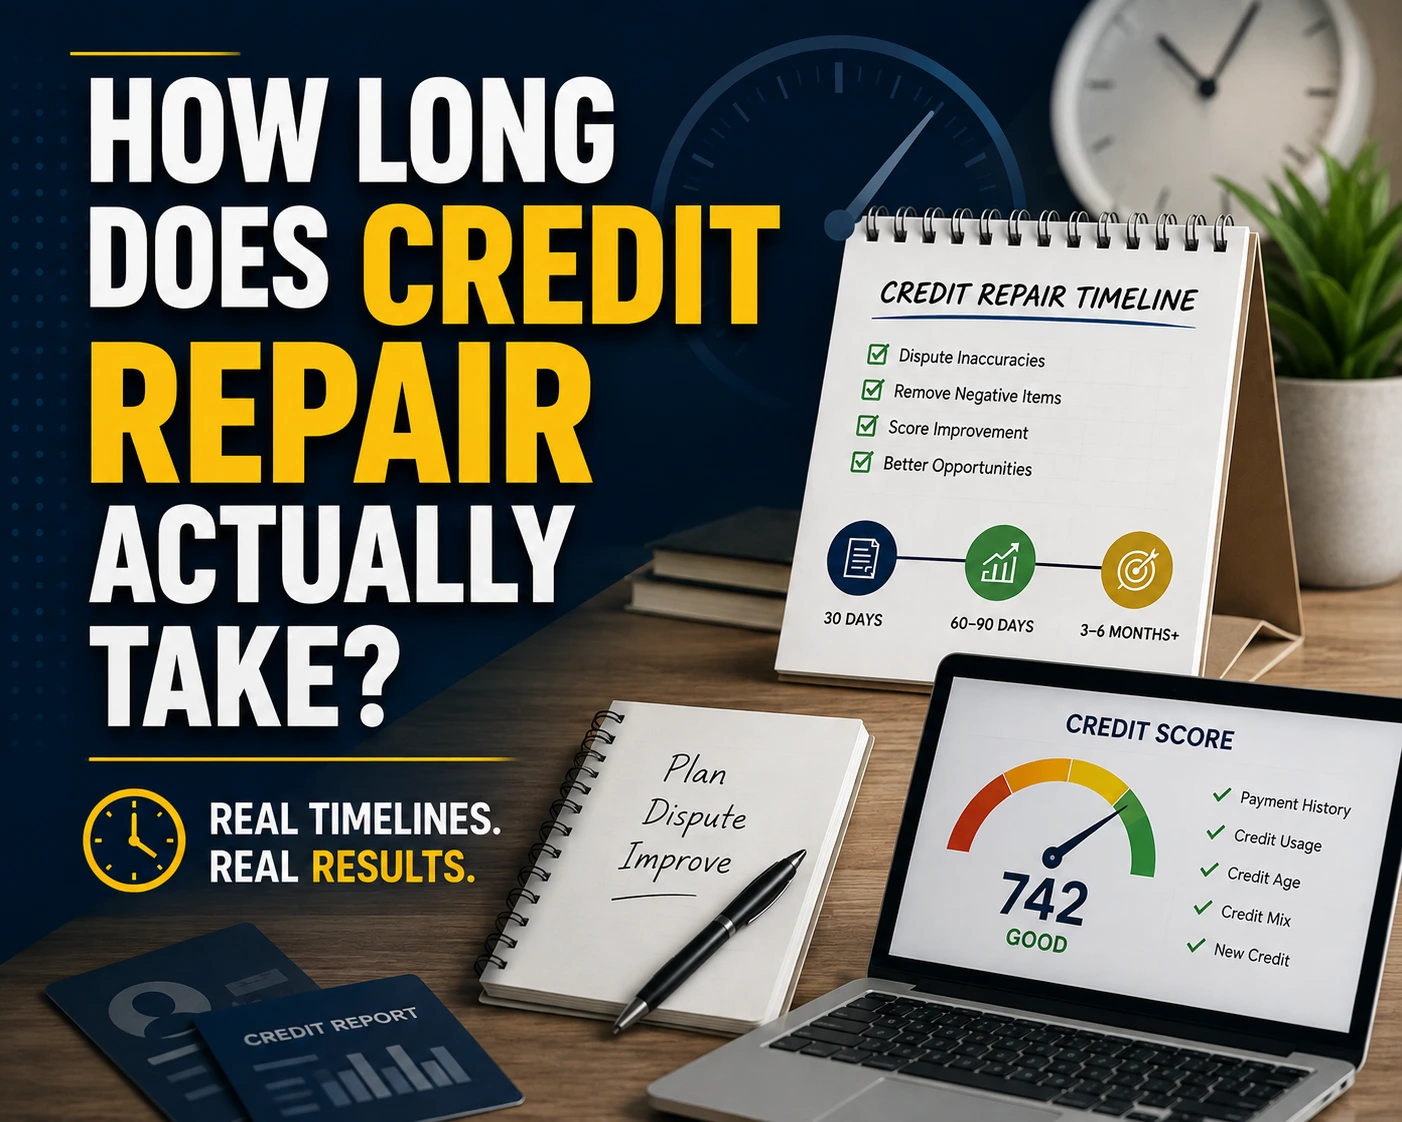
Some credit report errors can be investigated and corrected within about 30 days. Improving a credit score after high balances, missed payments, or other legitimate negative information can take several months or longer. The key is understanding the difference between correcting credit report errors and rebuilding your credit history.
How Long Does Credit Repair Take?
For many people, credit repair is a process that takes a few months to see noticeable progress, while more serious credit problems can take much longer.
If you are disputing inaccurate information, the process can move relatively quickly. Credit reporting companies generally have 30 days to investigate a dispute. In certain situations, the investigation can take up to 45 days.
But correcting an error does not automatically mean your entire credit score will increase dramatically. Your score is based on multiple factors, including payment history, amounts owed, length of credit history, new credit, and credit mix.
If your credit report is accurate but your score is low because of high balances or a history of missed payments, the timeline is different. You are rebuilding your credit rather than simply correcting an error.
How Long Does It Take to Repair Credit Score?
If you are wondering how long does it take to repair credit score, a realistic starting point is around three to six months for noticeable improvement, assuming you are consistently taking positive steps.
FICO notes that people may begin seeing small score changes within three to six months, although significant improvements can take longer depending on the situation.
Your timeline could be shorter if your main problem is high credit card utilization and you reduce your balances. It could be much longer if your report contains multiple late payments, collections, charge-offs, or other serious negative information.
That is why a promise such as “we will increase your score by 100 points in 30 days” should be treated with caution.
Read More: Can You Fix Your Own Credit for Free?
Credit Repair Timeline: What to Expect
The timeline usually depends on the type of problem you are trying to address.
1. Reviewing Your Credit Reports: A Few Days
The first step is getting copies of your credit reports from the major credit reporting companies and reviewing them carefully.
Look for incorrect personal information, accounts you do not recognize, duplicate accounts, inaccurate balances, incorrect payment history, and other information that does not belong on your report.
This step can be completed fairly quickly, but finding every potential error may take more time.
2. Disputing Credit Report Errors: About 30–45 Days
If you find inaccurate information, you can dispute it with the credit reporting company and the company that furnished the information.
Generally, a credit reporting company must investigate a dispute within 30 days. Some disputes can take up to 45 days, depending on the circumstances.
If the information is found to be inaccurate, it should be corrected or removed. You should then review your updated report to make sure the change was properly reflected.
3. Lowering Credit Card Balances: Potentially a Few Months
High credit card utilization can affect your credit scores. Paying down revolving balances can help your score once the lower balances are reported.
The exact improvement varies from person to person. Someone who is using most of their available credit may see a more noticeable change after reducing their balances, while someone with other major negative factors may need more time.
The important part is consistency. Paying balances down once is helpful, but maintaining responsible credit use is what supports long-term improvement.
4. Rebuilding After Late Payments: Several Months or Longer
Late payments can be more difficult because accurate negative information generally cannot simply be removed.
If a late payment is accurate, a legitimate credit repair company cannot legally erase it just because you want it gone. The FTC warns that companies cannot remove accurate and current negative information from your credit report.
Instead, the focus should be on establishing a new pattern of on-time payments. As more positive payment history is reported, your overall credit profile can gradually improve.
5. Recovering From Collections or Charge-Offs: Longer-Term
Collections, charge-offs, and other serious negative accounts can make credit recovery more complicated.
If the information is inaccurate, incomplete, duplicated, or does not belong to you, disputing it may lead to a correction. If the information is accurate, however, it generally cannot be legally removed simply because it hurts your score.
Most accurate negative information can remain on a credit report for up to seven years, although the impact on your credit score can change over time.
What Can Make Credit Repair Faster or Slower?
The biggest factor is what needs to be repaired. Someone with one inaccurate collection account may have a much shorter timeline than someone with several years of missed payments and high balances.
Your timeline can also depend on:
- How many errors are on your credit reports
- How quickly disputes are submitted
- How quickly furnishers respond
- Your current credit utilization
- The number and age of negative accounts
- Your payment history
- How consistently you make payments going forward
- How often your creditors report updated information
This is why there is no universal answer to how long credit repair takes.
Can Credit Repair Raise Your Score in 30 Days?
It is possible to see a score change within 30 days in some situations, but that does not mean your credit has been fully repaired.
For example, correcting a significant reporting error or lowering a high credit card balance may produce a relatively quick change. But rebuilding a damaged credit history generally requires more time.
Be especially careful with companies that guarantee a specific score increase within a specific number of days. Legitimate credit repair cannot guarantee that an inaccurate item will be removed or that your score will increase by a certain number of points.
The FTC specifically warns consumers about credit repair companies that make promises to remove accurate negative information or guarantee results.
Read More: How much does credit repair cost
How to Speed Up the Credit Repair Process
You cannot control every part of the process, but you can avoid unnecessary delays. Start by reviewing all three credit reports and identifying the problems that are actually affecting your profile. Dispute legitimate inaccuracies with the appropriate credit reporting companies and furnishers, and keep copies of your documentation.
At the same time, focus on the factors you can control. Pay every bill on time, reduce credit card balances, avoid unnecessary new applications, and monitor your reports regularly.
The goal should not be to find a shortcut. It should be to correct genuine errors and build stronger credit habits that continue helping you after the initial repair process is finished.
Is Credit Repair Worth It?
Credit repair can be useful when your credit reports contain legitimate errors that need to be challenged. However, you do not necessarily need to hire a credit repair company to dispute inaccurate information.
You have the legal right to dispute inaccurate information yourself, generally at no cost. The CFPB also notes that consumers can dispute inaccuracies directly with credit reporting companies and furnishers.
If you decide to work with a credit repair company, look for transparency about what it can actually do. Avoid any company that asks you to dispute information you know is accurate, tells you to create a new credit identity, or promises to permanently erase accurate negative information.
Read More: How does credit repair work
How Long Does Credit Repair Actually Take?
So, how long does credit repair take? For simple credit report errors, you may see results in roughly 30 to 45 days. For broader credit improvement, expect a longer process, often several months or more.
The fastest approach is not chasing quick fixes. Review your reports, dispute legitimate errors, pay your bills on time, manage your balances, and give your credit history time to improve.
Ready to take the first step? Start by reviewing your credit reports and identifying exactly what is holding your credit back.
